目录
Post-Close Summary
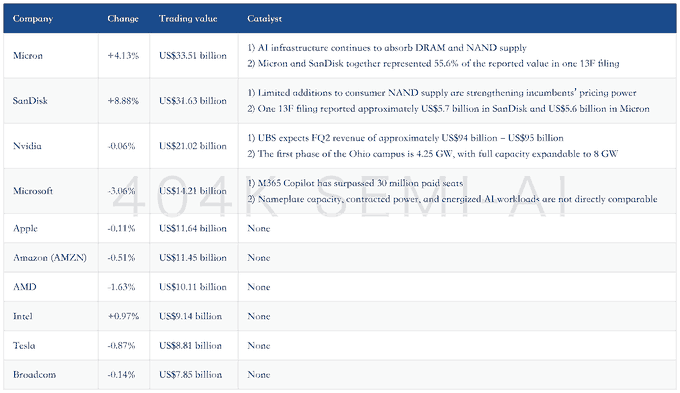
Top 10 U.S. Stocks by Trading Value
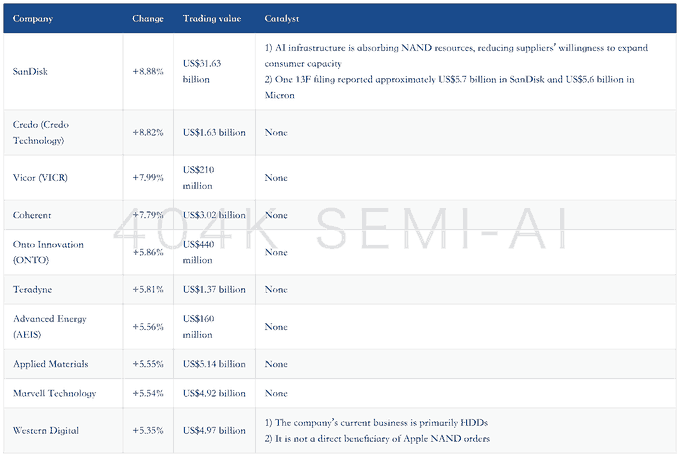
Top U.S. Stock Gainers
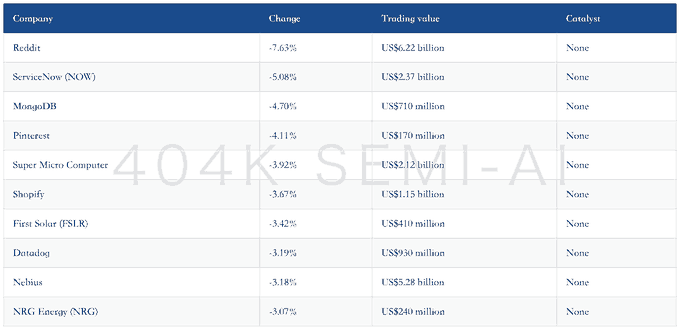
Top U.S. Stock Decliners
The Full AI/Semiconductor Value Chain
AI Models, CSPs, and Data Center Expansion
GPU/CPU/ASIC, Memory, and Advanced Packaging
Semiconductor Equipment, Testing, and Optical Communications
Internet / Platforms
Software/SaaS
Consumer Electronics/Smart Vehicles
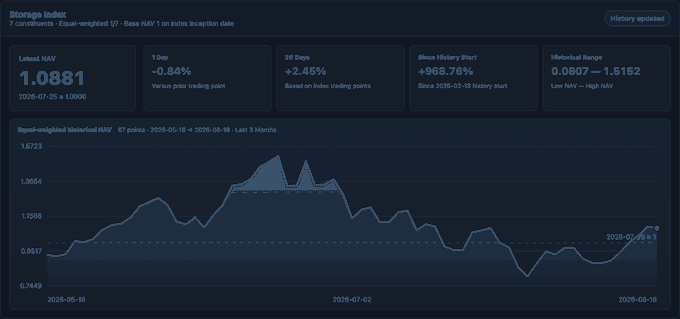
Huang’s Select Portfolio
Memory Index Performance
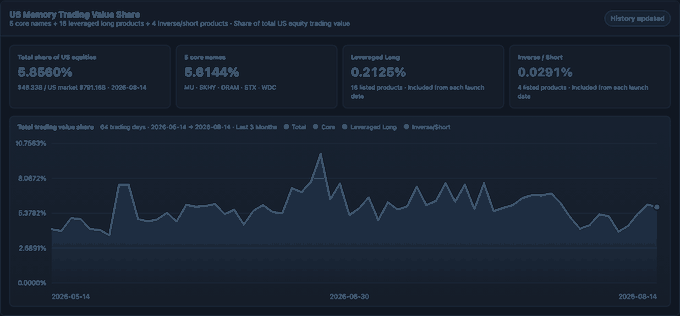
Memory Stocks’ Share of U.S. Equity Trading Value
Huang’s Select Portfolio
Memory Index Performance
Memory Stocks’ Share of U.S. Equity Trading Value
Overview
404K SEMI-AI | 2026-08-18
Post-Close Summary
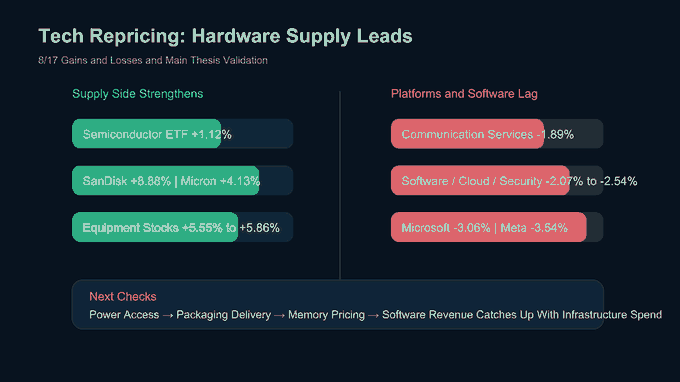
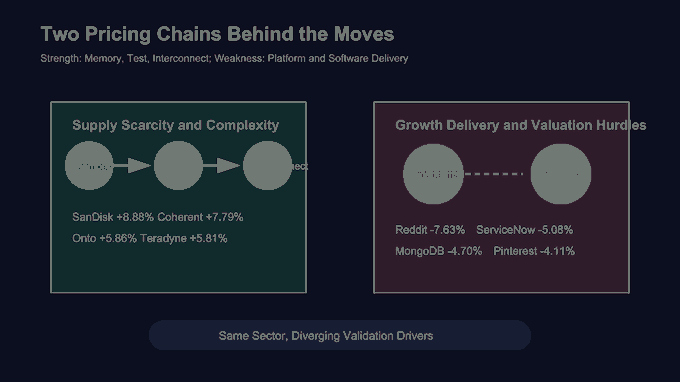
U.S. equities retreated on August 17: the S&P; 500 fell 0.48%, the Nasdaq 100 declined 0.19%, and the equal-weighted S&P; 500 dropped 0.81%. Technology bucked the market with a 0.12% gain, while the semiconductor ETF rose 1.12%. Communication services fell 1.89%; software, cloud computing, and cybersecurity ETFs declined 2.07%, 2.11%, and 2.54%, respectively, on the latest available trading day. Capital is not leaving technology; it is repricing hardware supply relative to platforms and software.
The sharpest divergence was in memory and semiconductor equipment. SanDisk rose 8.88%, Micron 4.13%, and Western Digital 5.35%; Applied Materials, Teradyne, and Onto Innovation gained 5.55%, 5.81%, and 5.86%, respectively. Microsoft, Meta, and Oracle fell 3.06%, 3.54%, and 2.57%. Investors are increasingly willing to pay for already-constrained memory, testing, and interconnect capacity, while demanding clearer returns from cloud platforms that still require sustained investment.
Fundamentals point in the same direction. OpenAI’s Ohio campus combines approximately 8 GW of IT capacity, a 20-year lease, and Nvidia credit support in a single transaction. UBS’s optical roadmap extends from NPO in 2026–2027 to CPO across 2026–2029. The next tests are whether power can be connected, packaging capacity can be delivered, memory pricing can hold, and software revenue can catch up with infrastructure spending.
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
The Full AI/Semiconductor Value Chain
AI Models, CSPs, and Data Center Expansion
Anthropic
1) Annualized revenue reached US$65 billion as of the end of July, more than 7 times its year-end 2025 run rate. Revenue exceeded US$11.5 billion in the latest full quarter, versus US$787 million a year earlier, with positive adjusted operating profit.
2) The company forecasts 2028 revenue of US$190 billion–US$200 billion, but compute-financing liabilities and differences in how companies calculate run rates increase valuation uncertainty.
“Its revenue run rate surpassed US$47 billion in May. OpenAI recently exceeded US$40 billion, although the two companies may calculate this metric differently.”
OpenAI
The PORTS-Pike campus in Ohio has secured approximately 8 GW of IT capacity, including 4.25 GW in the first phase; the first 800 MW is expected to enter service in 2028. Under a 20-year lease, SB Energy will build, own, and operate the site. Nvidia is investing US$1.5 billion and providing up to US$105 billion of asset-level credit support for the first phase. Demand is strong, but reletting, asset-sale, and residual-value support risks following a tenant exit require continued scrutiny.
“SB Energy will build, own, and operate the data center under a 20-year lease with OpenAI, delivering capacity in stages.”
Enterprise AI Adoption
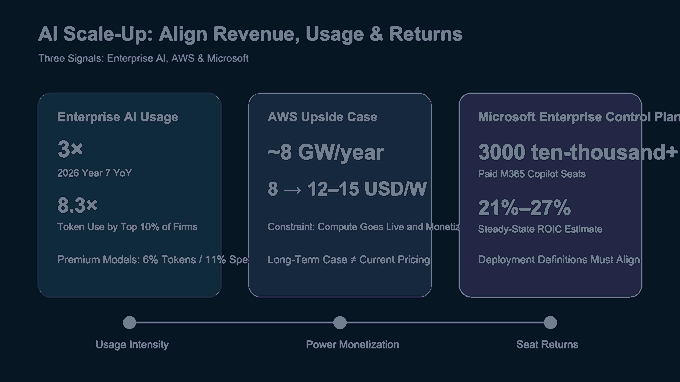
AI-related revenue in July 2026 was 3 times the year-earlier level, with an annualized run rate above US$210 billion. The top 10% of enterprises using OpenAI products consume 8.3 times as many tokens as the average enterprise. Fable 5 accounts for only 6% of enterprise tokens but 11% of spending, indicating a divergence between revenue growth and pricing elasticity for premium models.
Amazon
The AWS upside case assumes approximately 8 GW of annual capacity additions and an increase in power monetization from roughly US$8 per watt to US$12–US$15 per watt, implying annual revenue of approximately US$1 trillion around 2034–2036. A greater mix of internally designed chips could lift revenue per unit of power, but the binding constraint remains whether usable compute capacity can come online and be monetized on schedule.
Microsoft
1) M365 Copilot has surpassed 30 million paid seats, while steady-state returns on invested capital for AI infrastructure are estimated at 21%–27%.
2) One external comparison converts global data center capacity into an implied number of AI chips and then compares it with 2.2 million installed accelerators. However, nameplate capacity, contracted power, energized load, and AI capacity are not equivalent metrics. Deployment speed warrants monitoring, but mismatched datasets should not be used to manufacture a precisely quantified shortfall.
“The figure of 2.2 million installed chips may indicate a slower-than-expected deployment ramp. But if the power and chip datasets differ in scope, ownership, or operating status, the purported ‘gap’ is largely an assumption-driven construct.”
Google
1) A regulatory filing showed that Berkshire Hathaway increased its Google stake by 83% in the second quarter to nearly 106 million shares, worth approximately US$37.8 billion, including the US$10 billion AI infrastructure investment announced in June.
2) JPMorgan said Google is advancing outsourced design work for TPU v10 and may shift some back-end design volume to Alchip and Global Unichip, potentially reshuffling value allocation across the custom-ASIC supply chain.
Meta
Meta fell 3.54% and is down 11.90% over 20 days, with a stock-level RPS20 of just 4.5. The market still recognizes its user engagement and AI monetization potential, but now demands clearer evidence that platform remediation, capital investment, and compute-capacity sales can translate into incremental EPS. Its 18 times forward P/E also remains below the S&P; 500’s 21 times.
Nebius
1) Six quarters after relisting, quarterly revenue reached US$577 million; at the same stage of development, IREN reported US$34 million in quarterly revenue.
2) Pricing on its first short-term contract reached US$40 million–US$50 million per MW, well above the US$9 million–US$10 million per MW average for neocloud providers. The premium reflects scarce capacity but could decline as supply comes online.
CoreWeave
The shares rose 0.70%, gaining 20.20% over 5 days and 45.09% over 20 days, with a stock-level RPS20 of 96.2. 13F filings also showed that two AI infrastructure portfolios hold CoreWeave. The next tests are whether backlog converts into revenue from energized capacity and whether contract duration and customer quality adequately cover financing costs.
Data Center Power Contracts
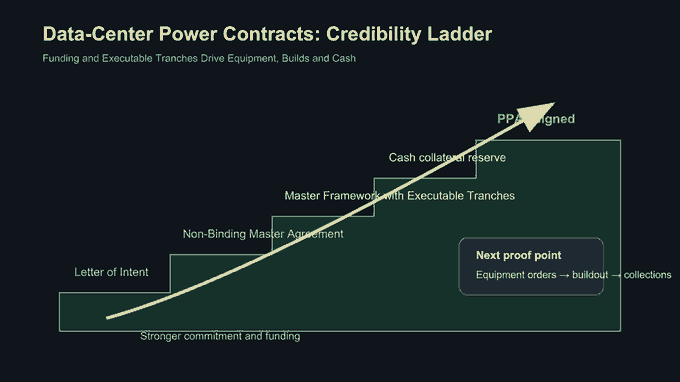
Bernstein ranks project credibility across 5 levels: signed PPAs, cash-secured reservations, master frameworks with executed tranches, non-binding master agreements, and letters of intent. Capacity announcements drive equipment, construction, and power revenue only when backed by committed funding and executable tranches. Equipment orders—and subsequent cash collection—are the next validation points.
“Bernstein compiled binding and non-binding transactions from several power companies to assess how much of the reported demand is supported by actual orders and funding rather than remaining at the framework-announcement stage.”
GPU/CPU/ASIC, Memory, and Advanced Packaging
Nvidia
1) UBS expects FQ2 revenue of approximately US$94 billion–US$95 billion and FQ3 guidance of approximately US$107 billion–US$108 billion, with actual revenue potentially exceeding US$110 billion.
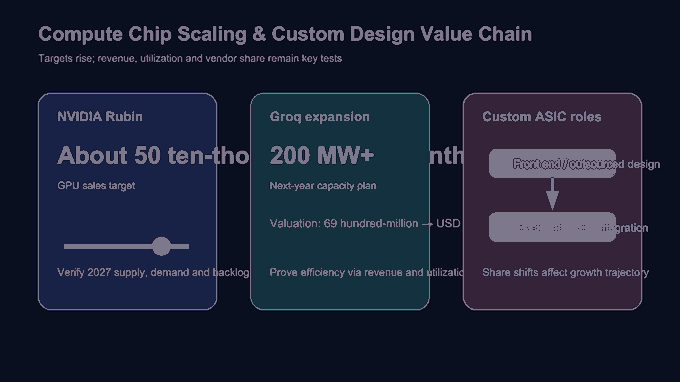
2) Rubin’s monthly sales target is moving toward approximately 500,000 GPUs, while the Ohio campus adds land, power, and buildings to the delivery chain. After earnings, investors should focus on 2027 supply and demand, backlog, and the limits of credit support.
“Because many of the debates around AI infrastructure spending, returns on investment, and credit risk are outside Nvidia’s control, we believe the numbers matter more than the narrative.”
Groq
The company raised US$350 million at a US$3.5 billion valuation, approximately half its US$6.9 billion valuation last September. Nvidia participated in the financing, and Groq plans to expand capacity to more than 200 MW by next year. The funding and expansion targets are clear, but the valuation reset shows that inference-chip companies must still prove commercialization efficiency through revenue and utilization.
Broadcom and Marvell Technology
JPMorgan said Alchip remains the sole back-end design supplier for TRN4 and continues to lead compute back-end, I/O die, and integration work. Google’s outsourced TPU v10 design program could shift volume toward pure-play design-service providers. Marvell Technology rose 5.54%, but market expectations for custom silicon in FY2027–FY2028 already incorporate the ramp of next-generation Trainium; changes in supplier share would directly affect the growth trajectory.
Micron
Micron rose 4.13%, gaining 17.51% over 5 days and 16.90% over 20 days. Bank of America reiterated its Buy rating and US$1,550 price target. Its bull case assumes a 30.7% revenue CAGR from FY2026 to FY2030, an 80% gross margin, and FY2030 EPS of US$236.16. Because an 80% gross margin is far above normalized levels, these figures should be viewed as an upside scenario in which the economics of the memory industry change fundamentally.
SK Hynix
One profitability analysis reported US$50 billion in trailing-12-month net income and a 37.3% profit margin, and stated that HBM4 has entered mass production. The company’s ADR rose 3.04% and gained 26.68% over 5 days. Sustainability depends on HBM4 mass-production yields, advanced-stacking supply, and cloud-provider demand—not on permanently extrapolating the current margin.
SanDisk and Western Digital
SanDisk rose 8.88% on US$31.63 billion of trading value and gained 28.46% over 20 days; Western Digital rose 5.35% on US$4.97 billion of trading value. AI inference is increasing demand for enterprise NAND and high-capacity storage, while suppliers have less incentive to expand low-margin consumer NAND. Western Digital’s current business is primarily HDDs, so potential Apple NAND orders should not be attributed directly to the company.
DDR5 Pricing
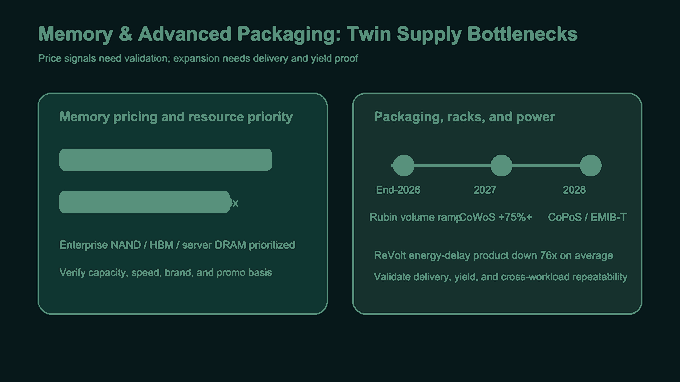
German DDR5 prices are reportedly close to 5 times their level a year ago, while the limited-time promotional price of a Corsair 32GB kit on Amazon is approximately 4 times its year-earlier level. These price signals support the near-term tightness thesis, but differences in capacity, frequency, brand, and promotional methodology must be reconciled before retail samples can be extrapolated to industry-wide average selling prices.
Advanced Packaging and Power Delivery
1) Vera Rubin racks are expected to begin scaling in late 2026 and could exceed 50,000 systems in 2027. CoWoS capacity is expected to grow more than 75% year over year in 2027, followed by CoPoS and EMIB-T in 2028.
2) ReVolt dynamically adjusts operating units using an LSTM-based power-delivery-network surrogate model, reducing the energy-delay product by an average of 76 times versus two baseline approaches. Packaging delivery, yields, and reproducibility across workloads still require validation.
“Because the current requirements of different chiplets vary throughout computation, supply voltage fluctuates across both space and time. This can cause voltage violations, impair system performance, and ultimately reduce the inference accuracy of machine-learning models.”
Semiconductor Equipment, Testing, and Optical Communications
Applied Materials
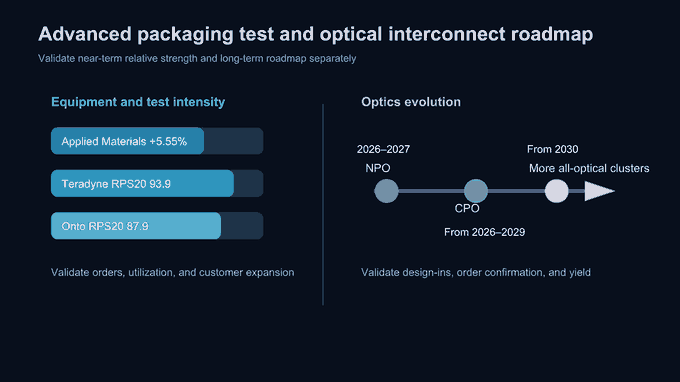
Applied Materials rose 5.55% on trading value of $5.14 billion; it gained 2.53% over 5 days and 1.83% over 20 days, with a stock-level RPS20 of 31.1. The strong one-day move has not changed its relatively weak medium-term strength. The next checkpoints are whether customers’ new cleanroom capacity converts into equipment orders and the visibility of wafer-fab equipment spending in 2027.
Teradyne
Teradyne rose 5.81%, gaining 21.37% over 5 days and 32.77% over 20 days, with a stock-level RPS20 of 93.9. Relative strength in semiconductor testing is well above the broader equipment sector, indicating that the market is pricing in demand for testing more complex chips and packages. The thesis would be invalidated if orders and utilization fail to keep pace with the share-price trajectory.
Onto Innovation
Onto Innovation rose 5.86%, gaining 20.53% over 5 days and 26.07% over 20 days, with a stock-level RPS20 of 87.9. Advanced-packaging process control and metrology should benefit from greater packaging-layer complexity, but the thesis must be validated through revenue, backlog, and the pace of customer capacity expansion—not merely inferred from correlated moves across equipment stocks.
Optical Roadmap
UBS expects NPO adoption at 200G per lane in 2026–2027, followed by CPO switches at 400G per lane beginning in 2026–2029, a gradual transition toward on-chip photonics, and potentially broader adoption of all-optical AI clusters from 2030. Given the long timeframe, confirmed orders and yields matter more than thematic exposure.
“The expected roadmap is NPO adoption at 200G/lane in 2026–27, followed by CPO switches at 400G/lane beginning in 2026–29.”
Lumentum
Lumentum rose 4.62%, gaining 19.10% over 5 days and 26.56% over 20 days, with a stock-level RPS20 of 89.4. One 13F filing showed that a portfolio exited an approximately $188 million Lumentum position in the second quarter. The shares subsequently rose 7.9%, however, while the latest quarter delivered revenue above $1 billion for the first time and a non-GAAP operating margin of 36.6%—evidence against the exit thesis.
Coherent and Credo
Coherent rose 7.79% and Credo gained 8.82%; over 20 days, they advanced 23.06% and 33.36%, respectively. Credo’s stock-level RPS20 reached 94.7. Simultaneous strength in optical components and high-speed electrical connectivity is consistent with rising networking content per rack. However, NPO, CPO, and electrical connectivity are not mutually exclusive alternatives, and customer design wins must be tracked separately for each.
Nokia
Nokia rose 0.19%, gaining 18.07% over 5 days and 6.94% over 20 days. One 13F filing showed share counts in Nokia, Ciena, Coherent, Semtech, and 11 other stocks all rising by approximately 1.73%, suggesting a proportional allocation rather than active company-specific additions. If these holdings continue to move in tandem, the filing should not be used to reinforce a stock-specific thesis.
Internet / Platforms
Google
Google fell 0.62% and declined 2.34% over 20 days. Citizens reiterated its Outperform rating and $515 price target, arguing that YouTube’s scale, discovery engine, and partner ecosystem continue to reinforce its position in television and content platforms. Meanwhile, changes in the division of backend design responsibilities for TPU v10 are a reminder that investors should assess platform value separately from supply-chain value.
“The analyst believes YouTube’s scale, discovery engine, and partner flywheel are reinforcing its position as a television and content platform.”
Meta
Meta fell 3.54% and declined 11.90% over 20 days. Its forward P/E is 18x, below the S&P; 500’s 21x. User engagement provides the foundation for monetizing AI recommendations and compute, but the valuation discount suggests that the market is more concerned about platform remediation, investment efficiency, and potential penalties than user scale. Execution remains to be confirmed.
“Meta does need to fix its platform, but a $1.4 trillion fine will not materialize and may not even reach 10% of that amount.”
Shopify
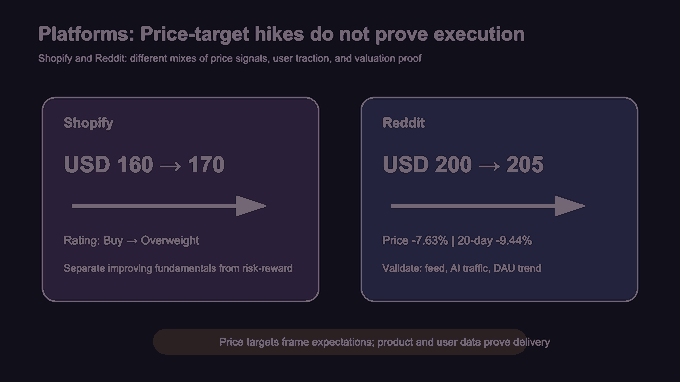
Shopify fell 3.67% but remained up 19.42% over 20 days. Phillip Securities raised its price target from $160 to $170 while downgrading the rating from Buy to Accumulate: its GMV and growth outlook improved, but the share-price rally compressed the risk-reward. The opposing directions of the target-price and rating changes underscore the need to assess fundamentals separately from valuation.
“The analyst sees resilient growth and stronger GMV performance but downgraded Shopify because of its recent share-price performance.”
Reddit
Reddit fell 7.63% on trading value of $6.22 billion and declined 9.44% over 20 days. Raymond James maintained its Strong Buy rating and raised its price target from $200 to $205. Feed improvements and potential traffic from its AI chatbot support the bull case, while mixed daily active user trends are the principal counterpoint. The immediate checkpoint is whether product changes can stabilize user growth.
“The analyst sees mixed DAU trends, but feed improvements, eventual traffic from the AI chatbot, and valuation offer an attractive risk-reward.”
Uber
Uber fell 1.26% but gained 3.91% over 20 days. The company is partnering with Zipline to launch autonomous drone delivery, with initial deployments planned for later this year and a target of 1 million deliveries per day by the end of 2029. The investment case centers on delivery speed and service radius; the near-term checkpoint is whether the first cities launch on schedule.
“Uber is partnering with Zipline to provide autonomous drone delivery to Uber Eats customers across the US, with initial deployments beginning later this year.”
Amazon
Amazon fell 0.51%, declining 6.03% over 5 days but gaining 4.53% over 20 days. AWS’s long-term revenue ceiling depends on power capacity, revenue per watt, and the efficiency of its in-house chips. At the platform level, however, investors must also assess whether e-commerce cash flow can continue funding infrastructure investment; the current business should not be valued solely against a long-term $1 trillion revenue scenario.
Apple
Apple fell 0.11% and declined 6.43% over 20 days. On-device AI requires simultaneous increases in base storage, unified memory, and RAM, while upstream suppliers are prioritizing resources for HBM, server DRAM, and enterprise NAND. Apple can absorb costs through gross margin, device pricing, configurations, and promotions; the key is whether price per GB and capacity upgrades can both remain controlled.
AppLovin
AppLovin fell 1.10% and declined 26.52% over 20 days, with a stock-level RPS20 of just 1.5. Normalizing gaming growth is pressuring the advertising platform’s high-growth narrative. The next question is whether expansion among non-gaming customers and returns on ad spend can offset base effects. A short-term valuation decline is no substitute for business validation, which still requires confirmation in reported results.
Snap
Snap fell 4.25% but gained 13.60% over 20 days. More than 3,000 lawsuits and the risk of product restrictions are reducing visibility, requiring the platform to re-establish its operating boundaries through user engagement, advertising conversion, and legal developments. The combination of a 20-day rebound and a one-day decline indicates that expectations remain unstable; progress must be assessed quarter by quarter.
Netflix
Netflix fell 2.74% but gained 12.46% over 20 days, with a stock-level RPS20 of 62.9. The streaming platform retains medium-term relative strength but cannot decouple when risk appetite deteriorates. The outlook ultimately depends on subscribers, advertising, content returns, and cash flow; share-price data cannot substitute for operating validation.
Pinterest
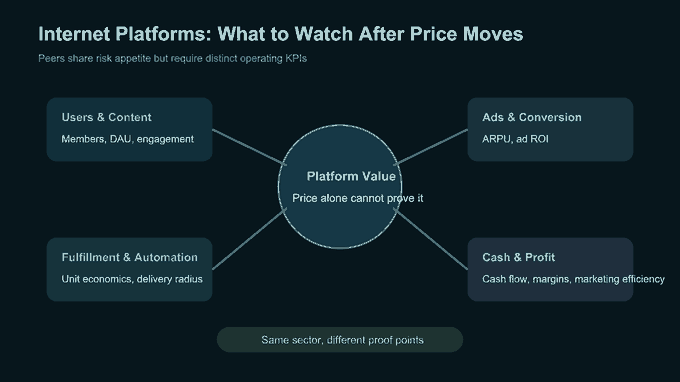
Pinterest fell 4.11% on trading value of $170 million but gained 1.14% over 20 days. The shares were relatively weak during the platform-sector pullback, but this alone does not establish a change in advertising demand or users. Daily active users, revenue per user, shopping conversion, and cash flow are needed to confirm the fundamental trend.
DoorDash
DoorDash fell 1.98% but gained 12.54% over 20 days, with a stock-level RPS20 of 63.6. Its medium-term platform strength remains intact, but Uber’s introduction of drone delivery into local services could create new variables for delivery radius and fulfillment costs. Any competitive shift must still be validated through unit economics, automation investment, and customer retention.
Airbnb
Airbnb fell 2.59% but gained 23.70% over 20 days, with a stock-level RPS20 of 83.3, placing it among the stronger internet platforms. Share-price strength cannot replace evidence from bookings and margins. Relative strength must still be tested against demand resilience, bookings, margins, marketing efficiency, and cash flow.
The Trade Desk
The Trade Desk fell 5.23% and declined 28.11% over 20 days, with a stock-level RPS20 of 0.8. The programmatic advertising platform is caught in simultaneous software and internet-sector de-risking, and its relative strength has already fallen behind. Customer budgets, retention, and returns on ad spend are needed to explain the outlook; share-price changes should not be attributed directly to any single product.
Alibaba
Alibaba reportedly plans to sell approximately $2 billion of non-core gaming assets. The portfolio adjustment could release capital and sharpen the company’s focus on its core businesses, but any improvement in capital returns will depend on the transaction price, use of proceeds, and profit trends in core e-commerce and cloud operations. The impact should not be upgraded before transaction details are finalized; the next checkpoint is how the cash is used.
Open-Weight Platforms
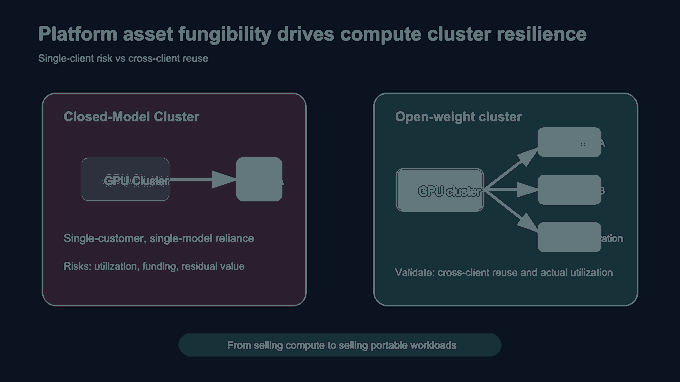
GPU clusters serving a single closed model carry single-customer risk, while clusters serving open-weight models can be reused more readily across customers and models. A platform’s ability to improve asset fungibility affects utilization, financing, and residual value. It is also a critical test of whether cloud platforms can evolve from “selling compute” to “selling portable workloads”; utilization still needs to be monitored.
“The same cluster serving open-weight models is a general-purpose asset that can be deployed interchangeably across customers and models.”
Software/SaaS
Microsoft
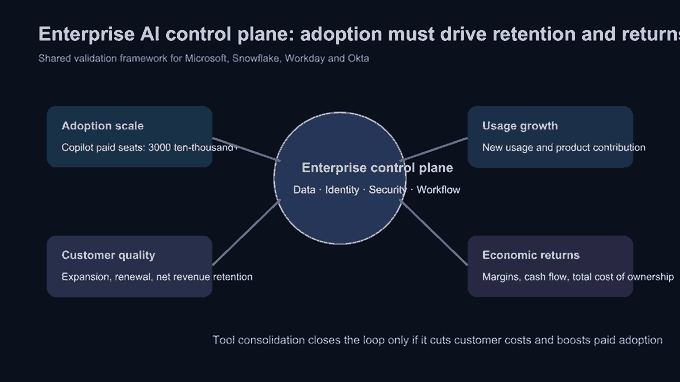
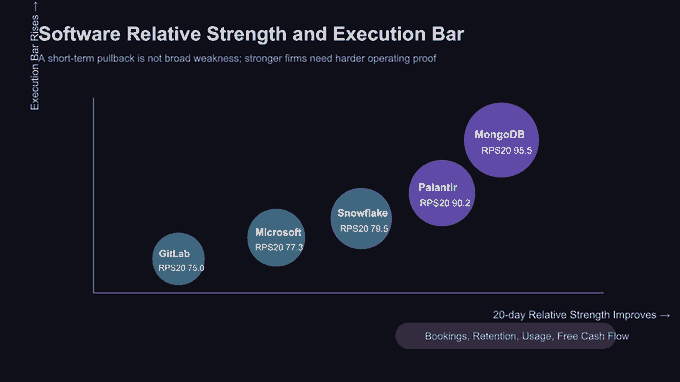
Microsoft fell 3.06%, but remained up 19.38% over 20 days, with an RPS20 of 77.3. M365 Copilot has surpassed 30 million paid seats, while data, identity, security, governance, and workflows form the enterprise control plane. The next test is whether seat expansion can drive revenue per user, rather than merely increasing product activations.
“With an enterprise control plane spanning data, identity, security, governance, and workflows, M365 Copilot has surpassed 30 million paid seats, while steady-state returns on invested capital for AI infrastructure are estimated at 21% to 27%.”
Snowflake
Snowflake rose 0.36%, bringing its 20-day gain to 20.33% and its RPS20 to 79.5. Channel demand remains stable, with approximately 90% of partners meeting targets. CoCo and AI are expected to contribute approximately 7 percentage points of growth in 2026. Competition from Databricks and a high valuation leave little room for error; incremental consumption and net revenue retention are the key validation metrics.
Workday
Subscription growth could slow to approximately 12%. Acquisition speculation provides valuation support, but the probability of a transaction is considered low. Without a deal, slowing growth would again become the primary valuation driver. Usage-based billing, customer expansion, and renewals matter more than treating a potential buyer as evidence of improving fundamentals; cash flow and renewal rates remain key disconfirming indicators.
“Subscription growth could slow to approximately 12%; acquisition speculation provides support, but the probability of a transaction is considered low.”
Okta
Identity security is benefiting from demand for AUTH0 and platform consolidation, although channel improvement remains uneven. Enterprise security budgets are still split among hardware refreshes, services, and implementation, so new tools must demonstrate lower total cost of ownership. Key indicators include customer expansion, remaining performance obligations, and margins, with channel feedback cross-checked against reported bookings.
CrowdStrike
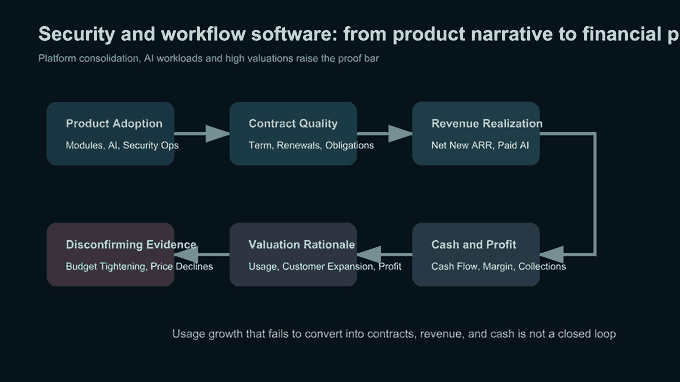
CrowdStrike fell 1.41%, declining 5.00% over five days but remaining up 7.76% over 20 days. Platform offerings such as Flex can broaden module adoption, but when software budgets tighten, customers focus more closely on actual consolidated spending. The key test is whether growth in module count translates into net new annual recurring revenue.
“Identity, SIEM, platform consolidation, and AI security remain tailwinds, but channel improvement is uneven, while a substantial share of cybersecurity budgets continues to flow toward hardware refreshes, services, and implementation.”
Palo Alto Networks
Palo Alto Networks fell 2.21%, but remained up 7.77% over 20 days. XSiam and Prisma AIRS bring security operations and AI security onto a single platform, but orders and contract duration must still demonstrate that consolidation lowers customer costs. Initial annual guidance will determine whether positive channel feedback converts into results.
Datadog
Datadog fell 3.19%, declining 5.16% over five days and 6.03% over 20 days. AI agents are increasing demand for observability, but declining model prices could also reshape customer usage and revenue mix. The market now requires evidence that growth in AI workloads can offset lower unit pricing, rather than relying solely on higher invocation volumes.
Monday.com
Weakness among lower-end customers is weighing on growth quality. As software demand shifts from point solutions toward consolidated platforms, small and midsize customers are becoming more sensitive to seat pricing and implementation returns. Key indicators are whether enterprise-customer mix, net revenue retention, and sales efficiency can offset lower-end weakness. Customer-acquisition costs, collection speed, and churn also require close scrutiny.
ServiceNow
ServiceNow fell 5.08% on turnover of $2.37 billion, declining 7.64% over five days but remaining up 12.42% over 20 days. The combination of a sharp one-day pullback and continued medium-term strength indicates that expectations for workflow AI remain high. Contract value, renewals, paid AI-product adoption, cash flow, and profitability will provide the next confirmation.
“Which companies can translate advantages in compute, storage, networking, power, and software into verifiable revenue and profits—and which highly valued assets face execution, competitive, governance, or policy risks?”
MongoDB
MongoDB fell 4.70% on turnover of $710 million, but remained up 35.67% over 20 days, with an RPS20 of 95.5. The database layer remains one of the strongest areas in software, but high relative strength raises the execution bar. Atlas consumption, customer expansion, and margins must now justify the valuation.
Salesforce
Monetization of enterprise-software AI depends on whether existing customer data and workflows are genuinely incorporated into paid products, not on the number of new features released. Salesforce fell 2.67%, but remained up 9.89% over 20 days. Current price action merely signals lower risk appetite across the sector and cannot substitute for order evidence; renewals and contract duration are the next hard metrics.
Cloudflare
Cloudflare fell 2.78%, but remained up 12.70% over 20 days and 46.10% over 60 days. Edge cloud and AI networking retain medium-term strength, but valuation tolerance depends jointly on large-customer growth, migration of developer workloads, and margins. Investors should also monitor whether spending grows faster than revenue and verify the quality of cash collections.
Palantir
Palantir fell 0.86%, but remained up 27.96% over 20 days, with an RPS20 of 90.2. The AI data platform continues to show relative strength, with the market focused on whether commercial demand can convert into sustainable contracts. The key tests are U.S. commercial revenue, customer count, contract duration, and cash collections—not headlines around isolated large deals.
GitLab
GitLab fell 4.93%, but remained up 18.93% over 20 days, with an RPS20 of 75.0. Its DevSecOps platform benefits from the proliferation of coding agents, but also faces competition as model providers move directly into developer workflows. Key indicators include seat expansion, usage-based revenue, margins, cash collections, and developer retention.
Software Sector
The software ETF fell 2.07% on the latest available trading day, but remained up 12.16% over 20 days, with an RPS20 of 92.6. The sector has not weakened across the board; rather, highly valued companies have become more sensitive to guidance and monetization evidence. Stock selection should prioritize orders, retention, usage, and free cash flow over AI product announcements alone.
“Software and internet companies must use AI monetization, platform consolidation, and product improvements to meet already elevated expectations.”
Consumer Electronics/Smart Vehicles
Apple
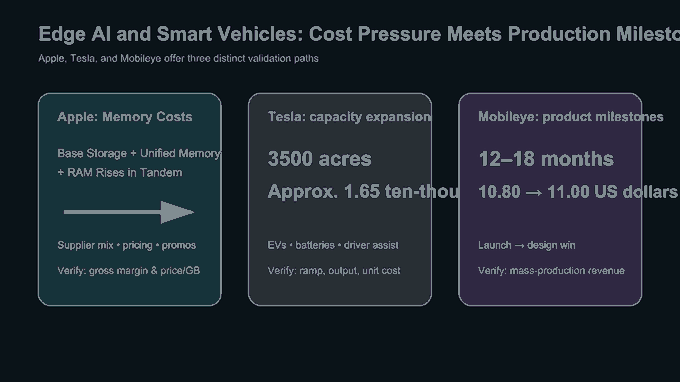
On-device AI is simultaneously increasing baseline storage requirements for the iPhone and unified-memory and RAM requirements for the Mac, while upstream suppliers prioritize HBM, server DRAM, and enterprise NAND. Apple fell 0.11% and was down 6.43% over 20 days. Its ability to defend gross margin depends on balancing supplier mix, capacity upgrades, pricing, and promotions.
“Apple faces the dual pressure of higher capacity and rising prices per GB, which could ultimately result in lower gross margins, higher device prices, configuration changes, fewer promotions, or reduced procurement flexibility.”
Tesla
1) Tesla fell 0.87% and was down 8.19% over 20 days, with an RPS20 of 8.3.
2) The Texas Gigafactory campus could expand to 3,500 acres, with approximately 16,500 employees building production lines for electric vehicles, batteries, driver assistance, AI, and robotics. This expansion must be validated through production-line commissioning, output, and unit costs.
“16,500 employees are focused on producing electric vehicles, batteries, and driver-assistance technology, while building new production lines and facilities for other products that the CEO says will determine the company’s future in AI, robotics, and autonomous vehicles.”
Mobileye
Mobileye rose 3.48%. Berenberg upgraded the stock from Hold to Buy and raised its price target from $10.80 to $11.00, arguing that product launches over the next 12 to 18 months are not fully priced in. Near-term validation depends on meeting product milestones; over the longer term, design wins must convert into mass-production revenue.
“The analyst believes the sell-off in Mobileye has mispriced its medium-term growth outlook and expects products to launch within 12 to 18 months.”
Uber and Zipline
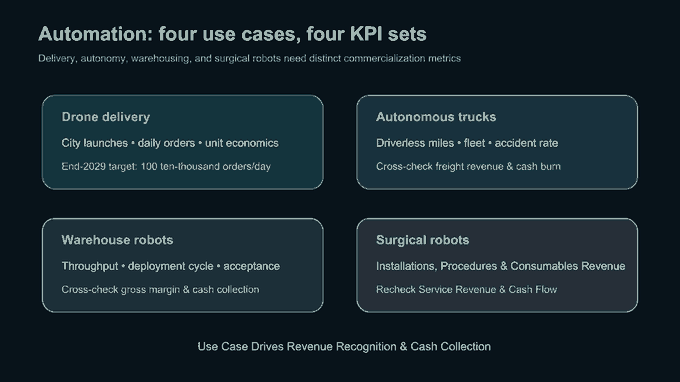
The first autonomous drone deliveries are scheduled to begin later this year, with a long-term target of 1 million deliveries per day by the end of 2029. The commercial value lies in shorter delivery times, broader service radii, and lower marginal fulfillment costs. Risks include regulation, urban coverage, weather, and unit economics, while execution must be validated city by city.
Aurora
Aurora fell 0.29%, but remained up 14.45% over 20 days, with an RPS20 of 69.7. Autonomous trucking retains medium-term relative strength. The next indicators are driverless miles, fleet size, freight revenue, accident rates, cash burn, and cost per mile. Share-price performance cannot substitute for commercialization progress.
Aptiv
Aptiv rose 0.97%, but remained down 12.69% over 20 days, with an RPS20 of only 3.8. The automotive-electronics and intelligent-driving supply chain remains relatively weak. The key question is whether rising content value from advanced driver assistance can offset pressure from traditional vehicle volumes and pricing. Orders, output, pricing, and margins must recover together to confirm a turnaround.
Symbotic
Symbotic fell 0.82%, but remained up 3.72% over 20 days. Warehouse robotics is an automation use case that can be directly validated through throughput, deployment timelines, and customer returns. Project acceptance, revenue recognition, gross margin, and cash collections matter more than generalized enthusiasm for humanoid robots, while deployment timelines also determine cash efficiency.
Intuitive Surgical
Intuitive Surgical fell 1.06%, but remained up 10.52% over 20 days, with an RPS20 of 58.3. The surgical-robotics business model depends on installed systems, consumables, and procedure volumes, offering a clearer validation path than general-purpose robotics. The next confirmation must come from installations, procedure volumes, consumables-revenue growth, cash flow, and service revenue per system.
“China accounted for 97% of global humanoid-robot shipments in the first half of this year, with AgiBot surpassing Unitree Robotics for the first time at a 44% global share.”
Humanoid Robotics Industry
First-half shipments were concentrated among Chinese manufacturers, led by AgiBot with a 44% global share. Market share reflects production ramp-up, not end-market profitability. The next tests are genuine customers, repeat purchases, unit costs, stable operating hours, after-sales expenses, and improvements in the cash-conversion cycle. Shipment volume should not be treated as a substitute for a closed commercial loop.
Rockwell Automation
Rockwell Automation fell 1.06% and was down 3.08% over 20 days, with an RPS20 of 18.2. Industrial automation depends on manufacturing capital expenditure and project returns, which do not move in lockstep with improvements in model capabilities. Orders, backlog, and end-market inventory matter more than assuming all robotics demand will grow simultaneously.
Qualcomm
Qualcomm fell 2.18% and was down 4.78% over 20 days. Quarterly results met expectations, but smartphone weakness reduced margin guidance. On-device AI must translate into higher chip content value or replacement demand to offset pressure on total handset volumes. Key indicators are premium Android design wins, the automotive pipeline, IoT revenue, and stabilization in gross margin.
NXP Semiconductors
NXP Semiconductors fell 0.85% and was down 12.90% over 20 days, with an RPS20 of 2.3. Automotive and industrial semiconductors remain in a low-relative-strength regime. The recovery thesis requires confirmation from inventory digestion, improving orders, capacity utilization, and distributor inventories. One-day price movements cannot define a cyclical inflection, while distributor inventory turnover must also improve.
STMicroelectronics
STMicroelectronics rose 2.76%, but remained down 9.70% over 20 days, with an RPS20 of 6.8. AI data centers and optical connectivity could provide incremental growth, but automotive and industrial demand will continue to determine margin leverage. Product mix, capacity utilization, and gross-margin guidance must improve together, alongside sustained improvement in order visibility.
onsemi
onsemi rose 0.87%, but remained down 3.83% over 20 days. Growth in AI data-center revenue is viewed as a potential contributor in 2027, while the Fab Right plan targets improvements in costs and gross margin. An earnings-per-share inflection requires data-center orders and a recovery in the traditional automotive business to materialize together; otherwise, the inflection will be delayed further.
Smart-Vehicle Supply Chain
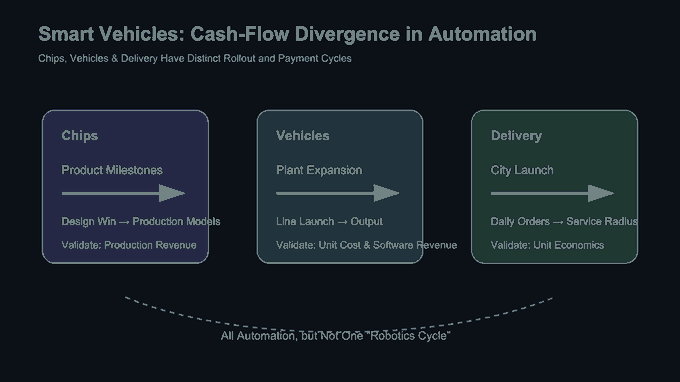
Mobileye’s price-target increase, Tesla’s campus expansion, and autonomous drone delivery all point toward the deployment of automation, but each requires different validation: chips through production vehicle programs, automakers through production lines and software revenue, and delivery through daily order volumes and unit economics. Combining them into a single “robotics cycle” would obscure differences in cash-flow timing.
“The long-term objective is not only to accelerate deliveries, but also to extend service to more distant areas that conventional delivery methods cannot economically reach.”
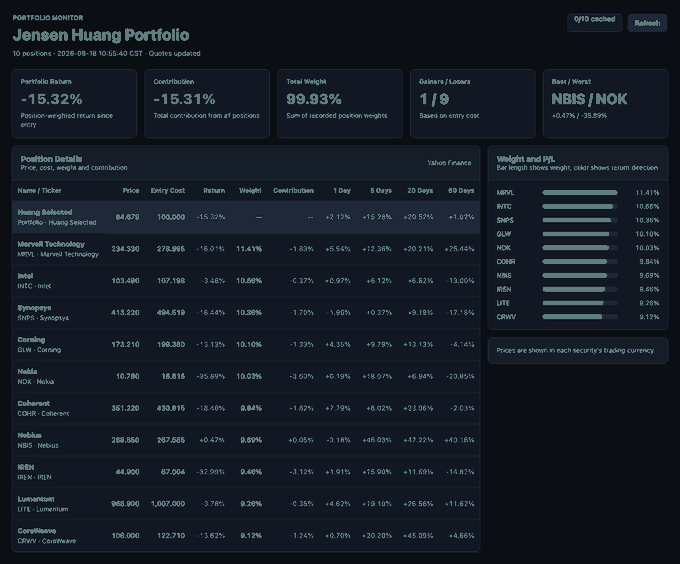
Huang’s Select Portfolio
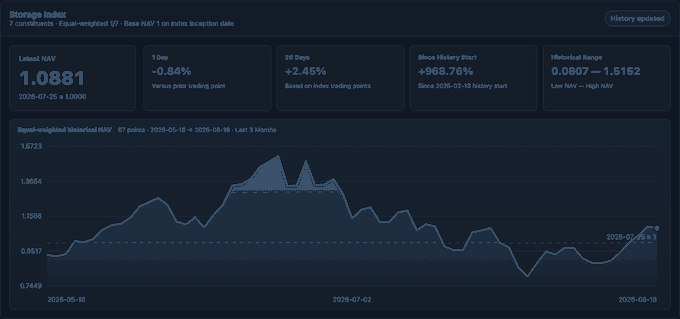
Memory Index Performance
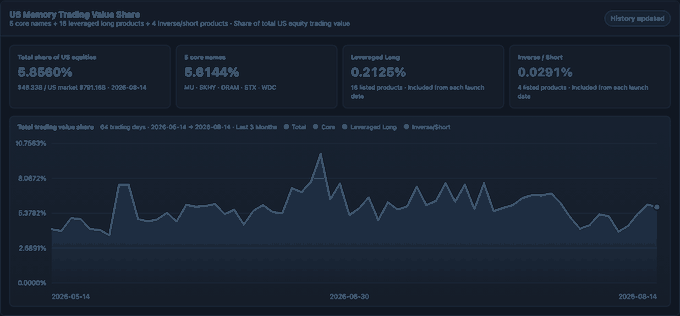
Memory Stocks’ Share of U.S. Equity Trading Value
Huang’s Select Portfolio
Memory Index Performance
Memory Stocks’ Share of U.S. Equity Trading Value