
目录
After-Hours Summary
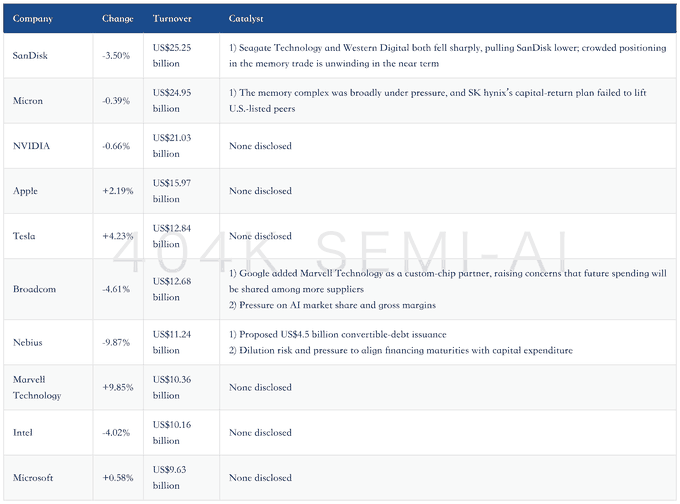
Top 10 U.S. Stocks by Turnover
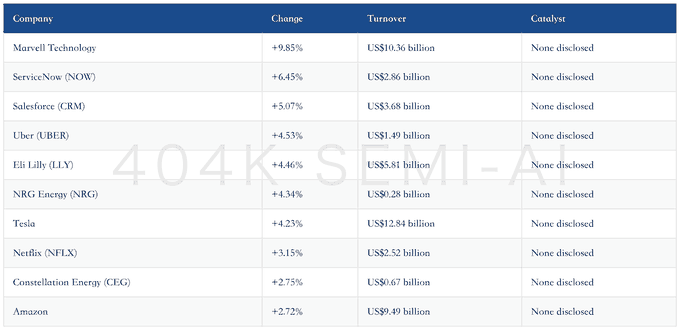
Top U.S. Stock Gainers
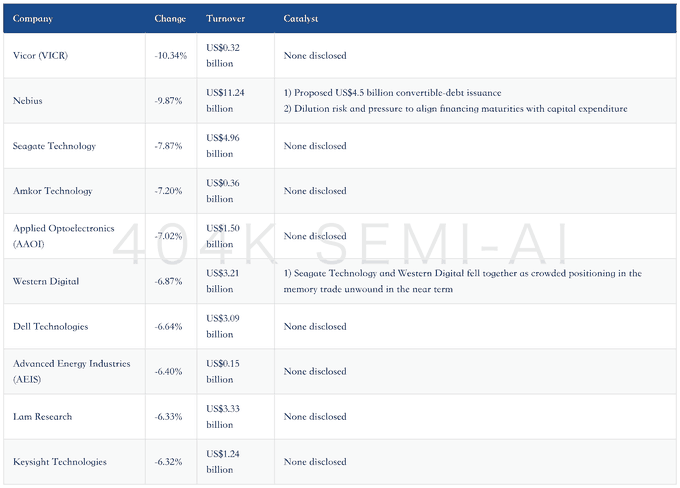
Top U.S. Stock Decliners
Full AI and Semiconductor Supply Chain
AI Models, Applications, and Capital Expenditure
CSP/Cloud Capital Expenditure and AI Cloud
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundries, Semiconductor Equipment, and Advanced Packaging
Optical Communications, High-Speed Interconnects, and Power
Internet/Platforms
Software/SaaS
Consumer Electronics/Smart Vehicles
Jensen Huang’s Top Picks Portfolio
Memory Index Performance
Memory Stocks’ Share of U.S. Equity Trading Value
Overview
404K SEMI-AI | 2026-08-20
After-Hours Summary
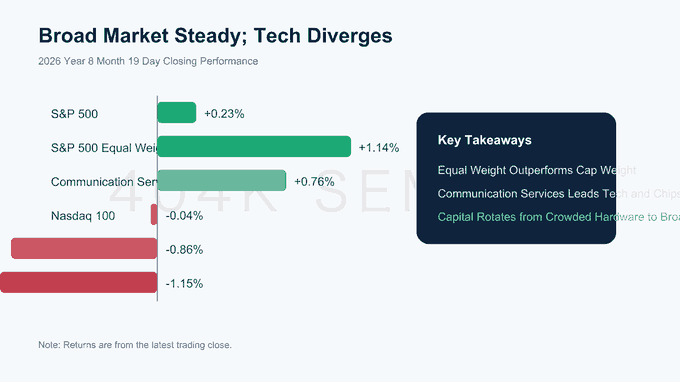
Major U.S. indices held near flat, but capital rotated sharply out of crowded hardware trades. The S&P; 500 rose 0.23%, the Nasdaq 100 fell 0.04%, and the equal-weighted S&P; 500 gained 1.14%; technology declined 0.86%, while communication services advanced 0.76%. The indices looked calm, but breadth was expanding beneath the surface.
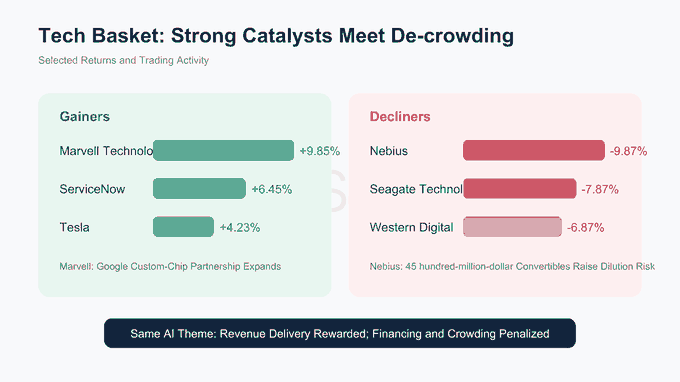
The semiconductor ETF fell 1.15%, with its 20-day RPS dropping to 0; cloud computing and software posted 20-day RPS readings of 100 and 96.3, respectively. Marvell Technology surged 9.85% on its Google partnership, while Nebius fell 9.87% on convertible-debt financing. Multiple memory, equipment, and optical-communications stocks also weakened as investors began differentiating among revenue conversion, financing costs, and supply constraints.
AI demand has not lost momentum. OpenAI’s revenue run rate has risen 35% quarter to date, while its enterprise revenue run rate is up 50%. The larger shift is in funding sources and order allocation: cloud providers are increasing debt financing, Google is expanding its custom-chip work to Marvell Technology, and supply-chain opportunities continue to broaden into memory, packaging, networking, and power.
Top 10 U.S. Stocks by Turnover
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI and Semiconductor Supply Chain
AI Models, Applications, and Capital Expenditure
OpenAI
1) Revenue run rate has increased 35% quarter to date, while enterprise revenue run rate has risen 50%. AI coding and workplace products have reached 20 million weekly active users; Codex previously reported 15 million users, with another update due within days.
2) “Private Secure Processing” keeps zero-data-retention deployments within customer-controlled infrastructure, while a hosted encryption solution is scheduled for a phased September launch. Revenue and enterprise capabilities continue to accelerate, but the operating loss widened to US$12.3 billion in Q2 2026. Whether usage can cover inference costs remains a key test.
“OpenAI’s total ARR has grown 35% quarter to date, B2B ARR has increased more than 50% quarter to date, and average weekly users of agent products have risen more than 3.5x quarter to date.”
Anthropic
1) Q2 2026 revenue more than doubled to US$11.6 billion, with a modest adjusted operating profit. Another data set puts Q2 operating profit at US$559 million, but ARR may be shifting from gross to net presentation, requiring a consistent basis for period-to-period comparisons.
2) Amazon Bedrock accounted for most agentic Token usage, and cloud channels are expected to contribute the majority of incremental ARR in Q4. Demand remains strong, although growth may naturally moderate once enterprise budgets are committed.
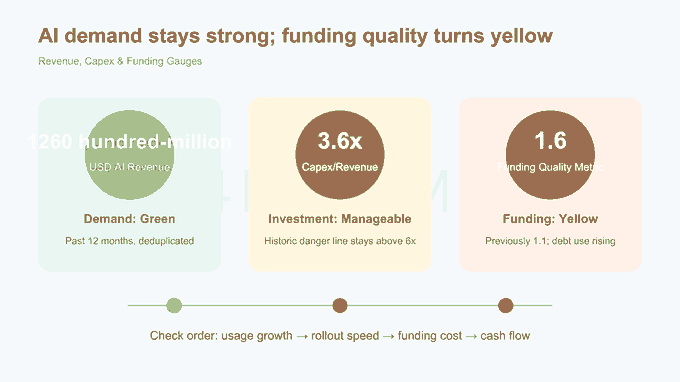
AI Revenue and Capital Expenditure: As of July 2026, deduplicated AI revenue over the preceding 12 months totaled US$126 billion, including US$43 billion in Q2 2026; full-year revenue is projected at US$190 billion to US$200 billion. The capital-expenditure-to-revenue ratio is 3.6x, or 4.8x after discounting certain expenditures, still below the historical danger threshold of consistently above 6x. Token prices fell 67% while revenue grew 84%, indicating that expanding usage is driving demand. The slope of usage growth is therefore the most important subsequent falsification indicator.
Stripe and OpenRouter: Stripe has agreed to acquire OpenRouter, which processes more than 10 trillion Tokens per day across over 400 models. The acquisition shows that model routing is evolving from a developer tool into payments and enterprise infrastructure. Token consumption has compounded at 9% per week since the beginning of the year, but free routing lasts only through the end of 2026; post-monetization request retention and unit gross margins will matter more.
CSP/Cloud Capital Expenditure and AI Cloud
Google
1) The 2026 capital-expenditure plan is US$195 billion to US$205 billion. Google Cloud grew 82%, and backlog reached US$514 billion.
2) On July 29, Google signed a custom-chip agreement with Marvell Technology covering inference accelerators, storage, networking, memory interfaces, and near-memory computing. Broadcom remains involved in the core TPU, while the supplier base is expanding around inference and peripheral functions. Capital expenditure continues to rise, but a 1-year construction delay reduces a data center’s lifecycle value by 5.5%, making deployment speed more important than the headline budget.
Microsoft: Actual capital expenditure rose 69% year over year, with an estimated two-thirds allocated to AI. Approximately US$25 billion of 2026 capital expenditure reflects the incremental cost of higher component prices alone. Cloud demand has not weakened, but rising prices for memory, storage devices, and other components are consuming more of the budget. The key question is how much deployable capacity each dollar of spending will ultimately deliver.
Meta: The 2026 capital-expenditure plan is US$130 billion to US$145 billion. Revenue grew 28% year over year, providing cash-flow support for investment, but data-center permitting, community acceptance, and grid access are extending project timelines. Converting capital expenditure into revenue depends not only on procurement volumes but also on when facilities actually come online.
“Delays have the greatest negative impact on the lifecycle value of AI data centers: a 1.5-year delay reduces value by 8.9%.”
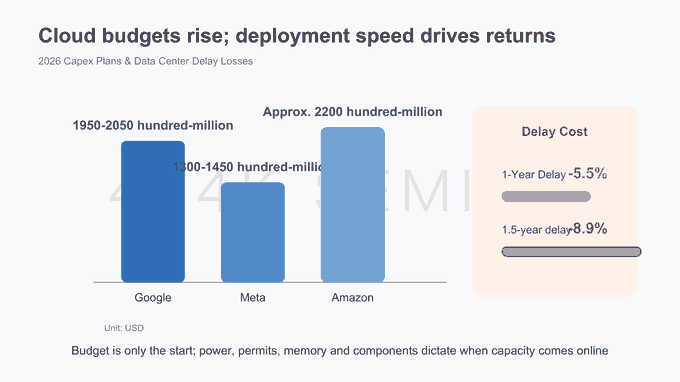
Amazon: 2026 capital expenditure is approximately US$220 billion, while Bedrock is directing Anthropic’s agentic Token usage onto AWS. Amazon rose 2.72% and has gained 8.84% over 20 days, but the investment case still depends on whether cloud channels can convert model usage into high-margin revenue—not simply on the scale of the budget.
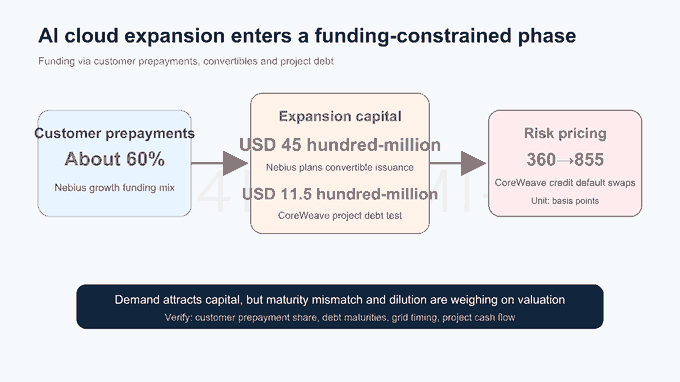
Nebius: Shares fell 9.87%. The company plans to issue US$4.5 billion of convertible senior notes, comprising US$2.75 billion due in 2030 and US$1.75 billion due in 2034. Following a US$4.3 billion financing in March, Nebius said it had sufficient funding to support US$16 billion to US$20 billion of capital expenditure, with approximately 60% of growth funding sourced from customer prepayments and 40% from equity and debt. Expansion demand is strong, but dilution and maturity matching are weighing on the share price.
CoreWeave: Goldman Sachs is testing demand for approximately US$1.15 billion of high-yield bonds to finance a data center leased to CoreWeave; the transaction is structured around a long-term lease rather than conventional corporate debt. Another US$10.6 billion of principal matures over the next 2 years, the company lost US$600 million last quarter, and its 5-year credit-default swap spread has widened from approximately 360 basis points to approximately 855 basis points. Compute demand continues to attract capital, but financing costs have become the dividing line between viable and uneconomic corporate and project returns.
“Despite the higher yields, investors continue to finance CoreWeave’s multibillion-dollar projects because demand for AI compute is driving extensive data-center expansion.”
GPU/CPU/ASIC
NVIDIA
1) Shares fell 0.66%. NVIDIA will provide up to US$105 billion of credit support for a 20-year lease involving OpenAI. The project totals 8 IT-GW, with the first 800 MW scheduled to enter service in 2028; the chip supplier is assuming risk increasingly similar to that of a financing intermediary.
2) NVIDIA is also matching GPU customers with Nordic data-center operators, using available power, land, and a PUE of approximately 1.15 to accelerate deployment. Its moat is expanding from chips into capital and infrastructure, but guarantee losses, grid-connection progress, and the residual value of older GPUs require continued monitoring.
Advanced Micro Devices
1) Shares fell 3.71%. Helios sample racks have been delivered and customers are running code, reducing proof-of-concept risk. The next step is converting samples into scaled rack deployments.
2) The partnerships with OpenAI and Meta each involve 6 GW of GPU orders and warrants, with potential dilution of approximately 10% for each individual customer. The orders lock in demand, but low exercise prices transfer part of the upside to customers; scaled manufacturing and gross margins are critical.
“We have demonstrated that we can build racks. The question now is whether we can execute the substantial, concrete work required to manufacture these racks at the scale we have discussed.”
Broadcom: Shares fell 4.61%. Its long-term TPU agreement with Google remains in force and extends through 2031. Marvell Technology is an additional, complementary supplier covering inference, networking, and storage—not a replacement. The market is concerned that future spending will be divided among more vendors, but current evidence does not support the view that Broadcom is being displaced. The key variables are next-generation TPU share, pricing power, and AI gross margins.
