404K Tech Morning Brief 2026-07-03 — AI Infrastructure Pullback, Memory Pricing Power, Software Relative Strength
目录
After-Hours Summary
U.S. Stocks Making New Highs
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry
Semiconductor Equipment/Test
Optical Communications/Optical Chain
High-Speed Interconnect/Connectors/Thermal and Power
Internet/Platforms
Software/SaaS
Consumer Electronics/Smart Vehicles
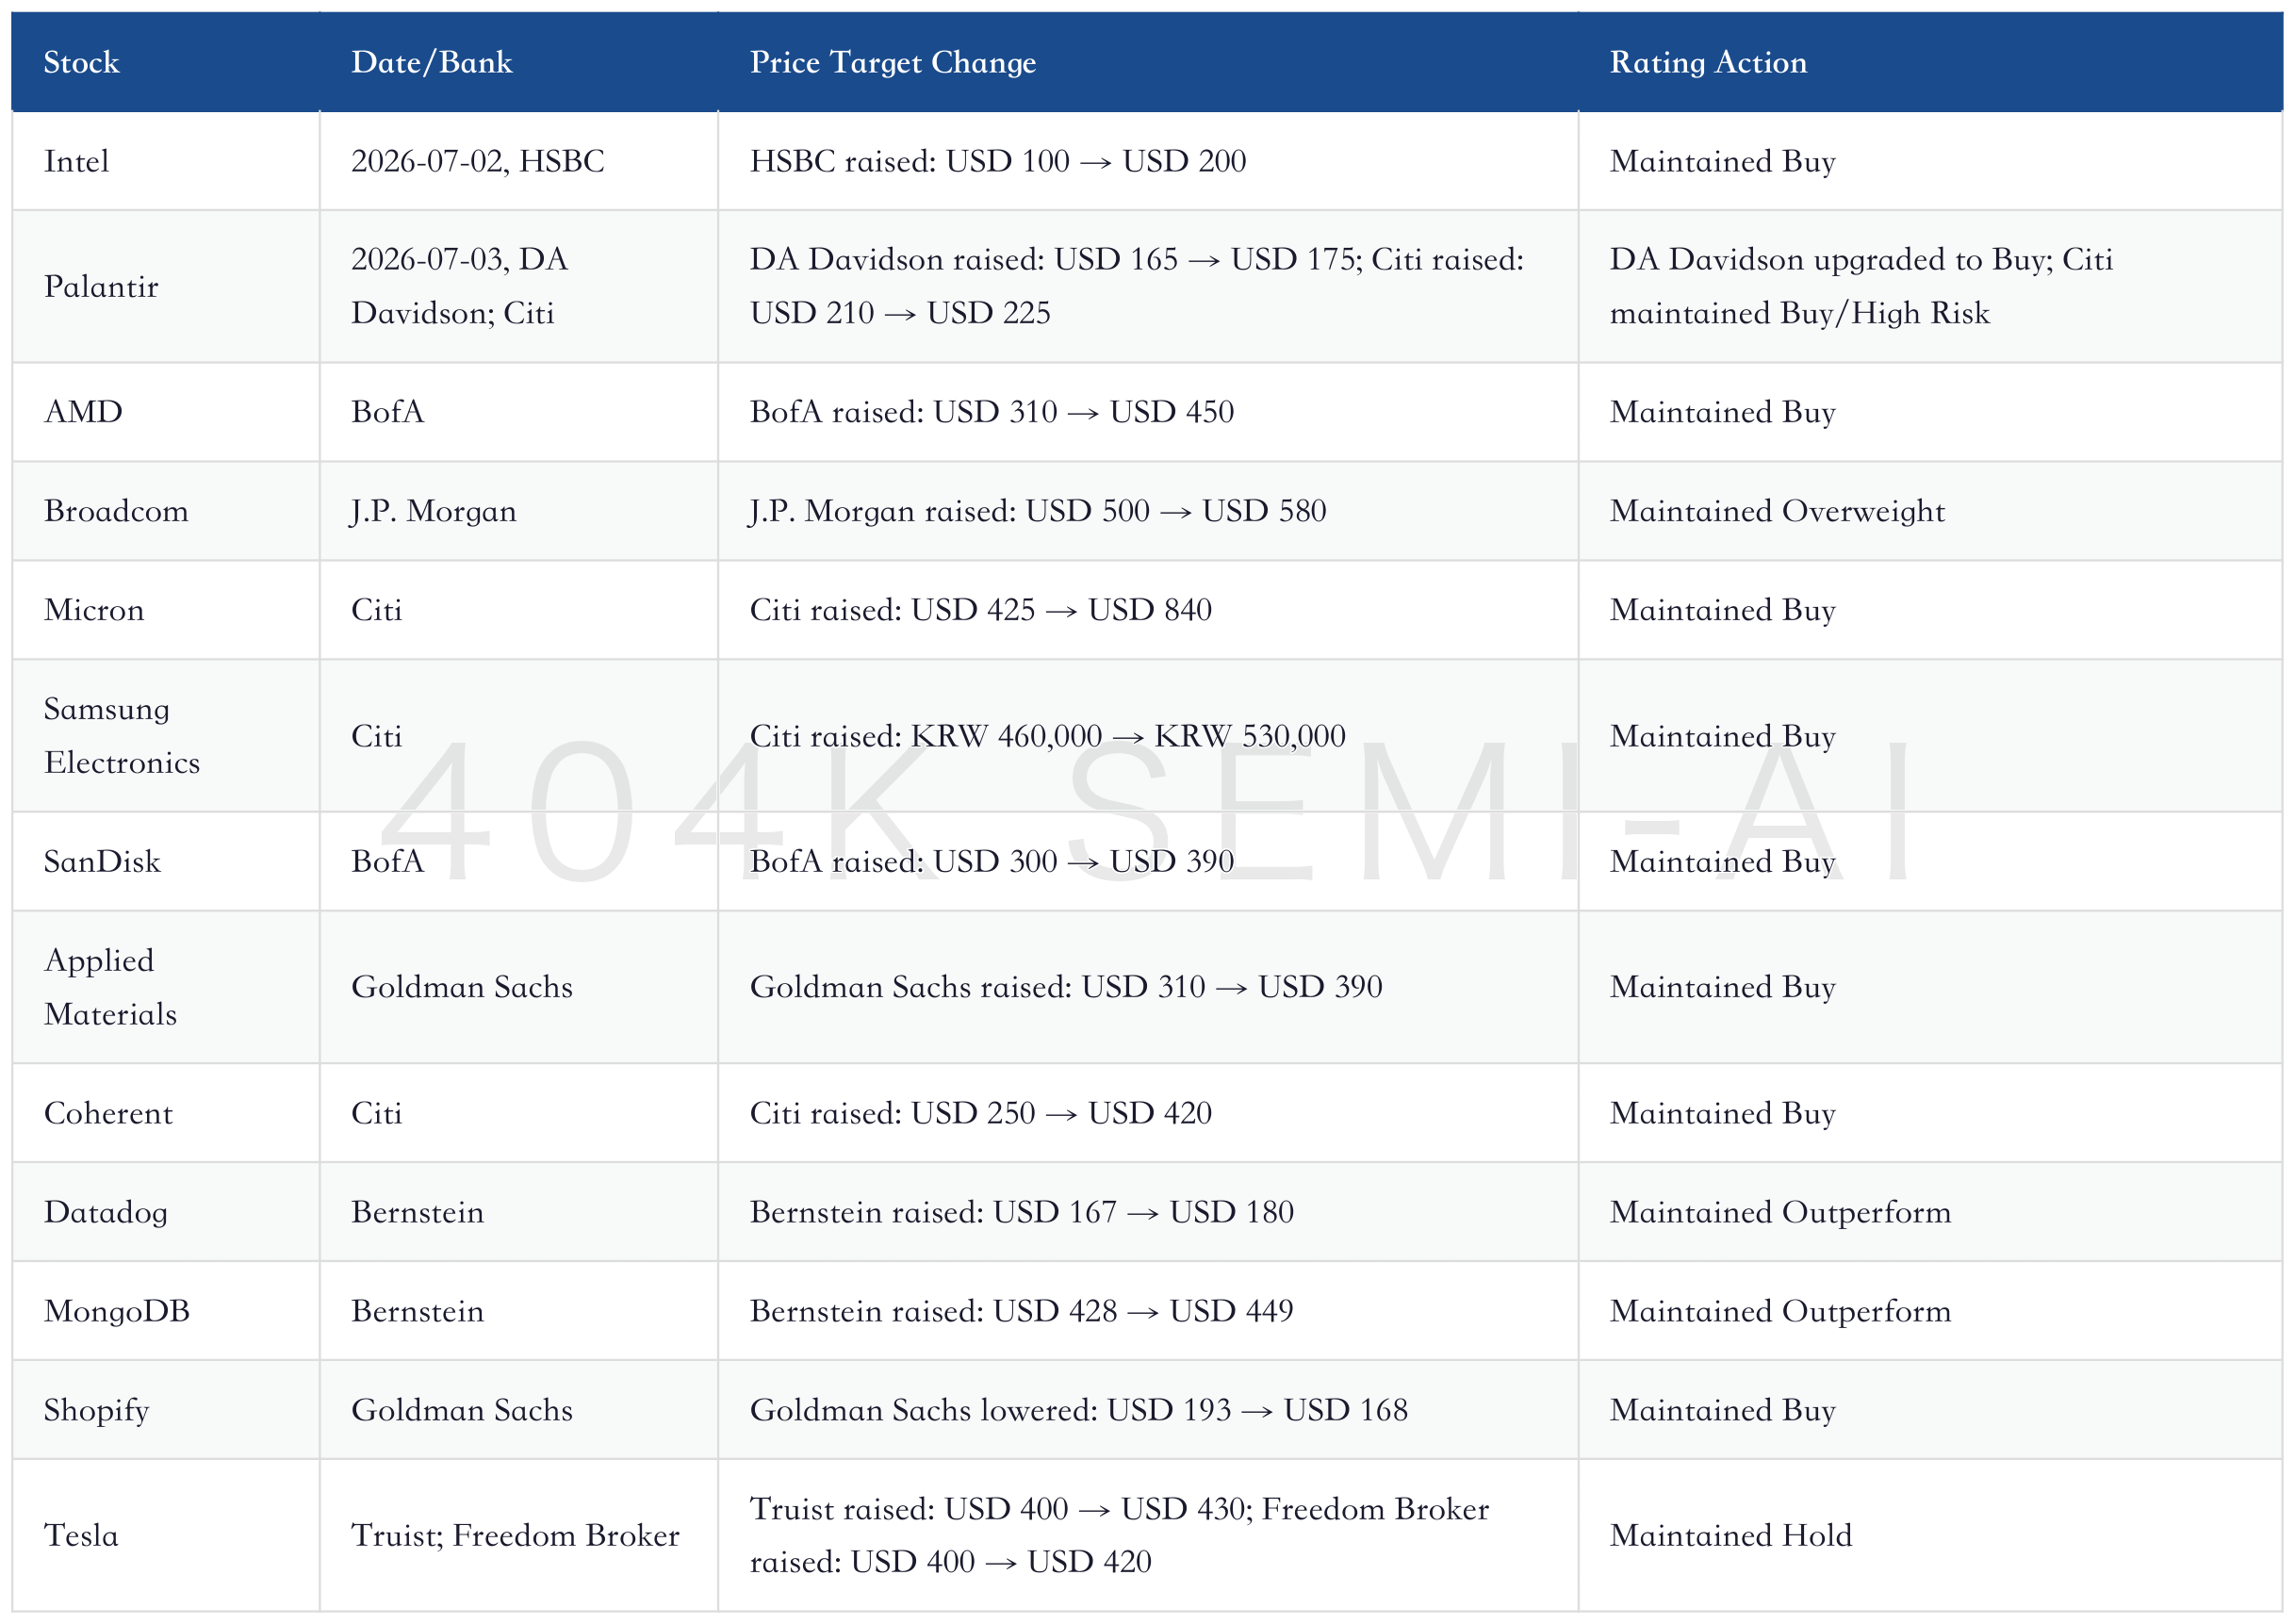
Investment Bank Price-Target Changes Over the Past 12 Hours
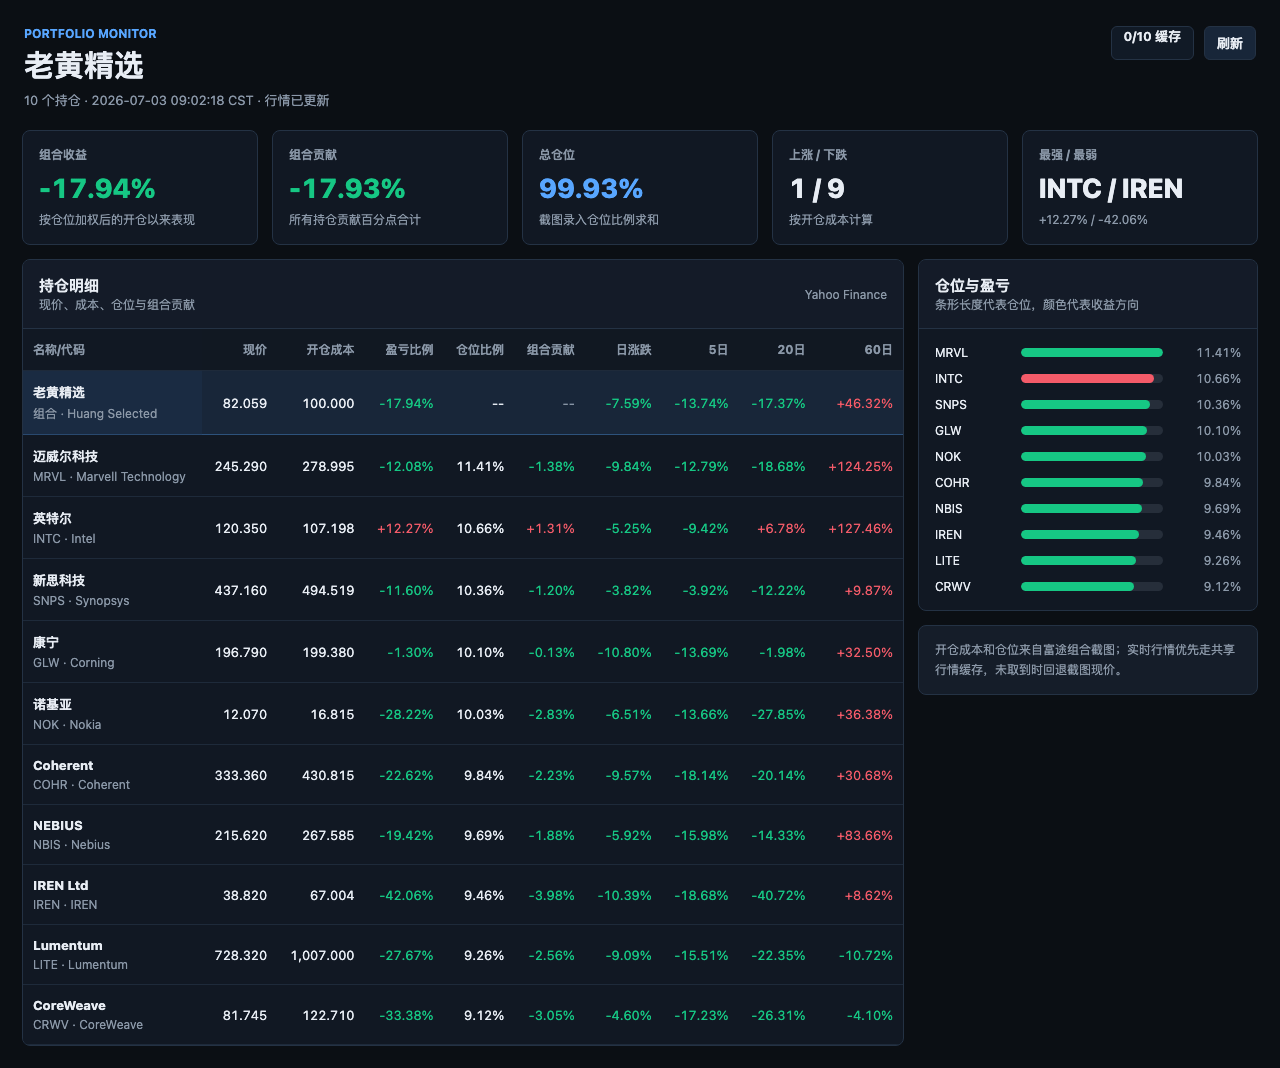
Huang’s Select Portfolio
The AI trade last night shifted from “what can still go up” to “who is paying for compute.” Semiconductors and the memory chain sold off sharply, but investment-bank and supply-chain data still point to no cooling in demand for server CPUs, HBM, NAND, optical interconnects, AI cloud, and enterprise AI software.
After-Hours Summary
U.S. equities showed a clear structural split after hours. The S&P; 500 fell 0.18%, the Nasdaq 100 fell 1.69%, the Dow rose 1.00%, the equal-weight S&P; 500 rose 0.70%, and the small-cap Russell 2000 fell 0.58%. Technology retreated from leadership, while capital tilted more toward healthcare, financials, staples, and utilities, indicating that the AI trade has entered a short-term phase of profit-taking and valuation reassessment.
Semiconductors saw the heaviest drawdown, with SMH down 4.36%, SOXX down 5.57%, the AI & Big Data ETF down 2.80%, and the technology ETF down 2.71%. Software, by contrast, held relative strength: IGV rose 0.25%, with a five-day gain of 10.39% and RPS5 at 100.0. The market message is straightforward: capital has not left AI; it is rotating from crowded hardware trades toward software and platforms with nearer-term earnings and lighter cash-flow intensity.
At the single-stock level, pressure was concentrated in memory, optical communications, equipment, and the AI server chain. SanDisk fell 13.26%, SK Hynix fell 14.57%, Seagate fell 10.38%, Western Digital fell 9.79%, Applied Materials fell 7.21%, Teradyne fell 13.02%, and Coherent fell 9.59%. This was not a collapse in demand data. Rather, debates over Meta selling compute externally, AI cloud utilization, and upstream pricing power all emerged at the same time, prompting the market to cut high-beta names first.
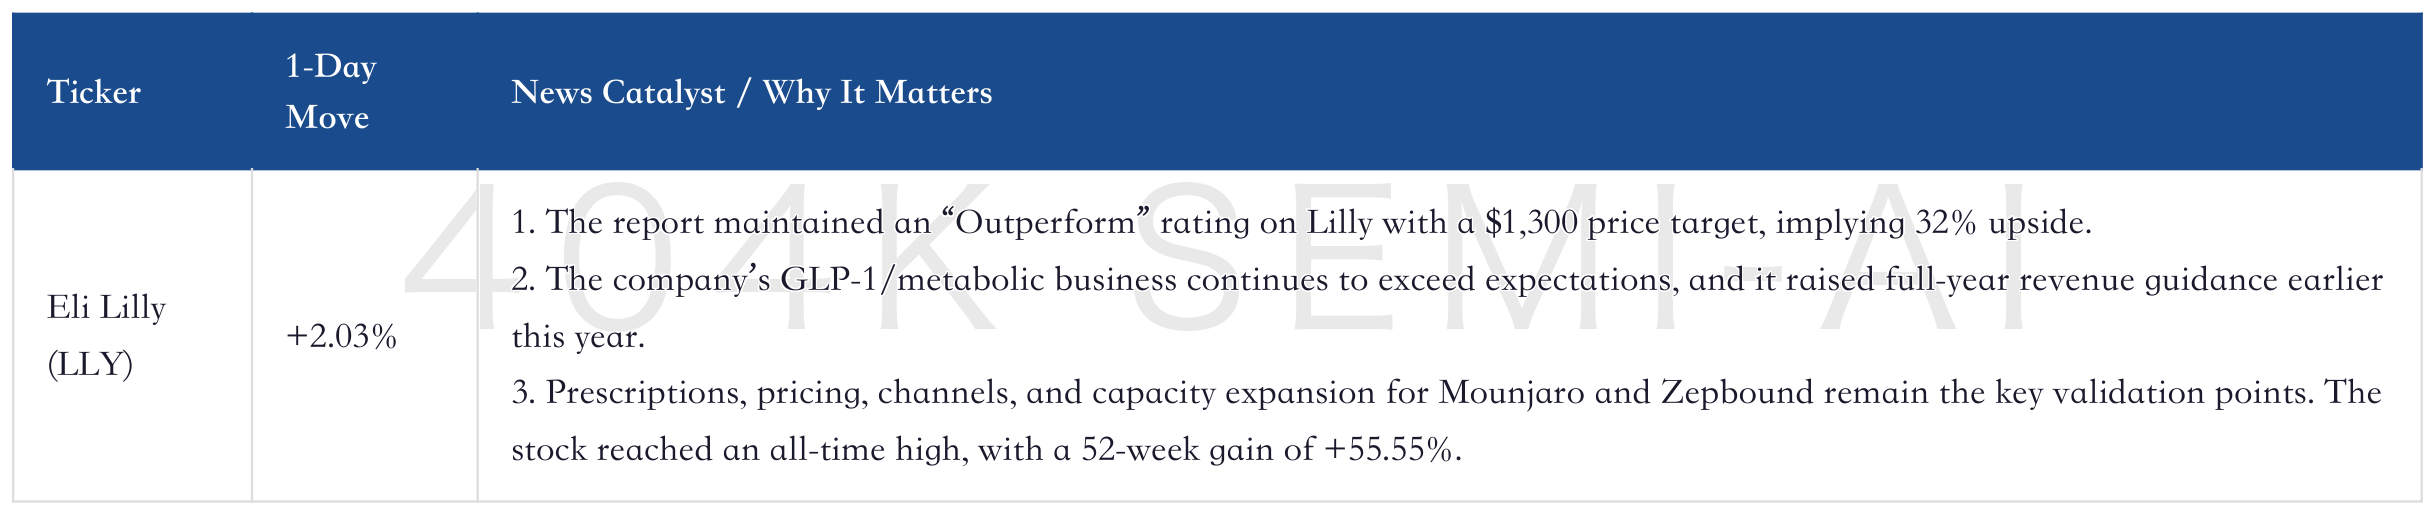
U.S. Stocks Making New Highs
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
OpenAI and Anthropic
1. Compute demand from frontier model companies continues to push upstream capex higher. Reports suggest OpenAI and Anthropic together may need more than 100GW of compute by 2030.
2. Anthropic has begun early work on developing its own AI chip and has discussed potential manufacturing with Samsung Electronics, considering a 2nm process and advanced packaging.
3. The investment implication is that large-model companies are moving from buying GPUs toward custom ASICs, and future orders will be redistributed among Nvidia, Broadcom, Samsung Electronics, TSMC, and cloud providers.
“Anthropic has begun preliminary work on developing its own AI chip. The company reportedly discussed potential manufacturing with Samsung Electronics. Anthropic is evaluating the chip’s capability, performance, and server integration.”
Meta
1. Meta fell 4.90% last night, but BofA still reiterated a Buy rating and an $835 price target, citing stronger AI models, progress on MTIA processors, and the path to AI monetization.
2. The market is concerned that Meta’s shift toward AI cloud could pressure neocloud valuations, but multiple clues point to continued tightness in Meta’s compute supply. Bernstein estimates Meta has roughly a 20GW global footprint, with another roughly 14GW coming online over the next few years.
3. The near-term risk is that Zuckerberg said AI agent development over the past four months has not accelerated as expected, indicating a timing gap between capex intensity and application monetization.
“AI agent development over the last four months has not accelerated in the way we expected”
Microsoft
1. Microsoft rose 1.62%, showing more resilience than the AI hardware chain, mainly because the market is more willing to assign valuation to enterprise AI deployment and cloud revenue certainty.
2. The company plans to invest $2.5 billion and allocate 6,000 industry and engineering experts to establish Frontier Company, helping customers deploy AI systems that deliver measurable business outcomes.
3. This type of business does not directly increase GPU order numbers, but it can validate whether enterprises are willing to keep paying for AI applications, serving as an ex-post demand anchor for hardware capex.
Palantir
1. DA Davidson upgraded Palantir to Buy and raised its price target from $165 to $175; a separate Citi report set a $225 target.
2. Q1 revenue growth was 85%, FY26 revenue guidance was raised by 10 percentage points, U.S. commercial revenue grew 133% year over year, and U.S. government business accelerated by 18 percentage points.
3. The debate is valuation. The FY28 target price implies roughly 65x EV/FCF, but if enterprises are unwilling to bind themselves to a single model, the AI orchestration layer still has real budget behind it.
“Strong Q1 Execution and Upsized FY26 Outlook Reinforces AI Thesis”
CSP/Cloud Capital Expenditure
Google
1. Google fell 0.79%. Wells Fargo cut its price target from $435 to $416 but maintained an Overweight rating, as search and cloud growth were stronger than expected, while higher AI investment reduced long-term forecasts.
2. Investment-bank materials continue to frame external TPU sales, cloud orders, and search AI monetization as the main themes; another report raised its price target to $447.
3. The investment implication is that the debate on Google is not about demand, but whether AI capex can convert into search, cloud, and TPU revenue rather than only pressuring margins.
Amazon
1. Amazon rose 0.41%. Wells Fargo raised its price target to $313 and maintained an Overweight rating, with the core thesis being that AWS is benefiting from AI demand, compute expansion, and improved pricing power.
2. The materials also noted that Amazon may reduce its reliance on external chips for consumer electronics devices and redirect more capex toward AI infrastructure.
3. This is pressure for consumer-chip suppliers such as MediaTek, while signaling budget reallocation toward AWS in-house chips, Trainium, and the data-center investment chain.
Apple
1. Apple rose 4.84%, supported by expectations for at least five new iPhone models in 2H26 and 1H27.
2. Goldman Sachs maintained a Buy rating and a 12-month price target of $266, expecting iPhone revenue to grow 5% year over year in FY2025E and accelerate to 7% in FY2026E.
3. The risk is that AI-enhanced Siri will not launch until 2026. Hardware upgrades in memory, chips, and cameras will need to wait for software experience delivery before replacement-cycle elasticity can be validated.
AI Cloud/Data-Center Operators
Oracle and Crusoe
1. Crusoe is in talks to raise roughly $3 billion, potentially at a valuation close to $30 billion, nearly twice its prior valuation.
2. The company provides AI compute to Meta and Oracle. The upward valuation reset shows that capital markets remain willing to pay for AI data-center outsourcing.
3. For Oracle, OCI is not only a cloud-service growth driver; it is also a valuation variable tied to AI facilities, long-term leases, and financing capacity.
CoreWeave
1. CoreWeave was pressured by the narrative around Meta selling compute externally, but Rosenblatt reiterated a Buy rating and a $250 price target, viewing the pullback as a repricing opportunity under GPU shortages and contractual constraints.
2. Nvidia previously had an unsold-capacity agreement through 2032 worth $6.3 billion, along with another $3.5 billion of guarantees related to data-center leases.
3. The risk is revenue quality and utilization. If customers bring their own GPUs into a colo model, AI cloud revenue per MW and capital returns will be lower than the pure GPU service-provider narrative implies.
“AI Compute Partnership”
Nebius and IREN
1. Nebius’s AI cloud platform is close to full utilization. Reports said Q2 sales were constrained by capacity rather than demand, with customers expanding from AI-native startups to large enterprises.
2. IREN appointed a product executive with experience at Oracle Cloud and in multi-cloud environments to advance GPU, managed services, and platform products, while emphasizing its 5GW secured grid-connected power portfolio.
3. The investment implication is that new cloud valuations are shifting from “who has GPUs” to “who has power, land, productization capability, and long-term customers.”
GPU/CPU/ASIC
Nvidia
1. Nvidia fell 1.36%, but the key development is business-model expansion: the company is reportedly providing financial backstops to smaller GPU cloud providers in exchange for a share of cloud revenue and guarantees to rent unused GPU capacity.
2. This can help customers finance GPU purchases and data centers, while also extending Nvidia from one-time hardware sales into recurring AI cloud revenue.
3. The risk is circular transactions and cloud revenue quality. The key follow-up is whether this capacity is absorbed by real end customers, rather than supported only by upstream credit.
Intel
1. Intel fell 5.10%, but HSBC raised its price target from $100 to $200 and maintained a Buy rating, citing stronger server CPU shipments, growing demand for Intel Foundry, and increased customer commitments in 2H26.
2. The company also raised suggested prices for Core Ultra 200S Plus. Core Ultra 7 270K Plus rose from $299 to $339-349, while Core Ultra 5 250K Plus rose from $199 to $219-229.
3. The investment implication is that the CPU cycle is recovering, but if retail pricing follows, Intel’s price-performance positioning relative to AMD will be reassessed.
“HSBC doubles Intel price target”
Broadcom
1. Broadcom fell 2.51%. J.P. Morgan reiterated Overweight and raised its price target from $500 to $580, with the main thesis being accelerating AI ASIC/XPU compute and networking orders.
2. F2Q26 revenue was $22.187 billion, up 48% year over year; AI semiconductor revenue was $10.8 billion, up roughly 143% year over year; AI semiconductor bookings exceeded $30 billion.
3. Management still describes FY27 AI revenue as exceeding $100 billion, while J.P. Morgan maintains its view of more than $150 billion. The debate is whether power, facilities, and GW-scale customer commitments can be delivered.
“AI bookings eclipsed $30B against $10.8B shipped”
AMD
1. AMD fell 4.26%. BofA reiterated Buy and raised its price target from $310 to $450, arguing that agentic AI expands the CPU/GPU TAM.
2. 1Q26 revenue was $10.253 billion, up 37.8% year over year; data-center revenue was $5.775 billion, up 57.2%; server CPU revenue was $3.293 billion, up 54.9%.
3. BofA estimates that each incremental 1GW customer opportunity corresponds to $15-20 billion of incremental opportunity. The risk is that customer share from OpenAI, Meta, and others still needs to be allocated among Nvidia, Broadcom, Cerebras, and other suppliers.
“every GW is $15-$20bn in incremental opportunity”
HBM/DRAM/NAND/SSD/HDD
Micron
1. Micron fell 5.60%, but Citi raised its price target from $425 to $840, judging that HBM prices could still rise in 2027.
2. Citi expects DRAM ASP to rise 200% year over year in 2026 and NAND ASP to rise 186% year over year; Micron 2027E EPS was raised from $94.55 to $104.56.
3. The risk is that high prices start to suppress downstream configurations. The report noted that Cisco has cut 50% of DRAM content in more than 20 projects.
“DRAM ASPs will increase 200% YoY in 2026, and NAND ASPs will increase 186% YoY in 2026”
Samsung Electronics and SK Hynix
1. Samsung Electronics fell 9.06% and SK Hynix fell 14.57%, but Citi raised its Samsung price target from KRW 460,000 to KRW 530,000 and lifted its 2026 operating-profit estimate by 20%.
2. Citi expects Samsung’s 2026Q2 DRAM and NAND ASPs to rise 44% and 57% quarter over quarter, respectively, with server DRAM blended ASP up 363% year over year and SSD pricing up 330% year over year.
3. SK Hynix reportedly removed some LTA price caps and extended agreements from one year to three to five years. Pricing power is strengthening, but customer prepayments and long-term contract structures will also amplify cyclical backlash.
SanDisk
1. SanDisk fell 13.26%. BofA reiterated Buy and raised its price target from $300 to $390, with the main theme being NAND’s rising strategic role in AI inference.
2. The report forecasts FY2027E revenue of $13.6277 billion and EPS of $27.31, with NAND prices potentially rising 20%-30% quarter over quarter in 4Q and another 30%+ in 1Q.
3. The key change is that large context windows and dedicated storage tiers are raising the value of eSSD. Risks include NAND capacity expansion, Chinese supply, and slow rollout of AI consumer applications.
“NAND could be up +20-30% q/q in 4Q followed by another 30%+ increase in 1Q”
Seagate and Western Digital
1. Seagate fell 10.38% and Western Digital fell 9.79%, with HDD/NAND stocks following the high-beta memory pullback.
2. The move did not change the logic that data-center enterprise drives and high-capacity storage are benefiting from AI inference, cold data, and expanding training datasets.
3. The near-term focus is whether cloud customers reduce configurations as memory, SSD, and HDD prices all rise at the same time. If storage consumes more downstream budget, server BOM allocation will face new constraints.
Foundry
TSMC
1. TSMC ADR fell 2.27%, but long-term commitments to U.S. manufacturing continue to advance; Taiwan regulators approved a $20 billion capital injection by TSMC into Arizona Corporation.
2. The funding will be used for U.S. 12-inch wafer fabs and advanced packaging facilities, bringing total funds flowing to the U.S. to $44 billion, part of the $165 billion commitment.
3. The investment implication is that U.S. manufacturing in the AI era is moving from symbolic expansion toward a logic manufacturing plus advanced packaging ecosystem, while core R&D; and leading-edge processes remain in Taiwan.
Samsung Foundry
1. Anthropic’s talks with Samsung on manufacturing its self-developed AI chip have shifted market focus from Samsung’s HBM share to whether its 2nm process and advanced packaging can win frontier-model customers.
2. Other reports suggest Samsung Foundry has entered a customer-allocated capacity state in some processes and has begun screening new orders.
3. For TSMC, this confirms tight supply. For Samsung, it is another test of yield, packaging, and customer trust.
Semiconductor Equipment/Test
Applied Materials
1. Applied Materials fell 7.21%. Goldman Sachs maintained Buy and raised its price target from $310 to $390.
2. FY1Q revenue was $7.012 billion, above consensus of $6.890 billion; the midpoint of FY2Q revenue guidance was $7.65 billion, above consensus of $7.076 billion.
3. The company guided for semiconductor equipment business growth of more than 20% in 2026, with roughly 55% exposure to deposition and etch, benefiting from GAA logic, stacked memory, and advanced packaging.
“semiconductor equipment business to grow over 20% in 2026”
Lam Research, KLA, Teradyne
1. Lam Research fell 10.19%, KLA fell 11.39%, and Teradyne fell 13.02%, as the equipment/test chain was sold as high-beta AI capex exposure.
2. Applied Materials’ strong guidance has positive spillover for etch, deposition, and process control, but the market is also worried about China WFE, U.S. export controls, and the pace of memory capex.
3. The next focus is whether DRAM/HBM/NAND capacity expansion continues to push orders higher, rather than only looking at a one-day semiconductor ETF pullback.
Optical Communications/Optical Chain
Coherent
1. Coherent fell 9.59%. Citi maintained Buy and raised its price target from $250 to $420, centered on high-growth businesses such as AI transceivers, CPO, and OCS.
2. FY2026E/FY2027E/FY2028E sales forecasts were raised by 2%/14%/13%, respectively. AI transceiver sales are expected to reach $3.2 billion in FY2026E and $5.6 billion in FY2027E.
3. Risks include EML supply-demand, 6-inch fab expansion, SiPho 1.6T, and CPO customer qualification, but optical modules remain the key outlet for AI capex spreading from GPUs to networking.
“Coherent’s AI transceiver sales to reach $3.2B (+99% YoY) and $5.6B (+72% YoY)”
Arista
1. Arista fell 3.98%. J.P. Morgan maintained Overweight with a December 2026 price target of $200, based on 2027E EPS of $4.75 and roughly 42x P/E.
2. The 7060XE7 series 1.6T switches expand the company from AI scale-out networking into scale-up rack-level networking. The first 64-port 1.6T air-cooled systems are expected to ship in 4Q26.
3. The AI scale-up networking market is expected to grow from $16.7 billion in 2026 to $78.5 billion in 2030. LPO’s roughly 60% reduction in interconnect power consumption is a customer TCO lever.
Nokia, Corning, Ciena
1. Nokia materials point to AI infrastructure buildout supporting optical and IP networks, while Corning and Ciena continue to be validated around fiber, optical-network orders, supply chain, and margins.
2. During last night’s optical communications pullback, the market first treated these companies as part of the “crowded AI hardware” trade rather than distinguishing them by order visibility.
3. The next focus is whether 1.6T, CPO, fiber cabling, and data-center interconnects continue to win budgets from CSPs and neoclouds.
High-Speed Interconnect/Connectors/Thermal and Power
Credo and Astera Labs
1. Credo fell 6.57% and Astera Labs fell 4.73%, but both companies remain on the core demand path as AI networking upgrades from copper cables and retimers to optical interconnects.
2. Credo’s earlier report tied its AEC leadership to emerging optical interconnect opportunities, while Astera materials emphasized opportunities in Scorpio X, memory expansion, and inference workloads.
3. The near-term pullback comes from cooling semiconductor valuations overall. The real validation points are 1.6T/800G rack deployments, customer concentration, and gross margin.
Vertiv, Eaton, GE Vernova
1. Vertiv fell 3.49%, Eaton fell 3.61%, and GE Vernova fell 0.32%, with the data-center power and thermal chain pulling back less than semiconductors.
2. GE Vernova’s power business accounted for 51.3% of 2025 revenue, and electrification accounted for 25.0%. AI data-center expansion is pushing power demand into a seller’s market.
3. If AI cloud valuation shifts from GPUs to power and delivery capability, electrical equipment, liquid cooling, power distribution, and on-site power will remain ways for capital to defensively express AI capex exposure.
Internet/Platforms
AppLovin
1. AppLovin sits on the expansion path for mobile performance advertising and e-commerce advertising; Morgan Stanley rates it Overweight with a USD 720 price target.
2. The report says AppLovin’s real conversion rate remains very low; every 10bp improvement in conversion could drive roughly 17 percentage points of net revenue growth. Another survey shows Axon penetration among Shopify stores is only about 0.34%.
3. The debate is whether e-commerce advertising can scale. Continued budget increases from major brands would lift valuation, while overly high CPP would limit scalability.
"each additional 10bps would drive 17 points of Cloudflare revenue growth"
Shopify
1. Shopify benefits from agentic commerce rather than being directly bypassed by LLMs; Goldman Sachs maintains Buy and lowers its price target from USD 193 to USD 168.
2. The report’s anchor point is that orders from AI search have increased 15x since January 2025, and LLMs do not bypass Shopify checkout, so GMV still flows through the Shopify ecosystem.
3. The investment implication is that if agentic shopping becomes a new entry point, Shopify’s value lies in merchants, payments, and unified commerce protocols, not merely website-building tools.
"orders from AI search grow 15x since January 2025"
Google/Waymo and Uber
1. Morgan Stanley believes Waymo’s commercialization expansion and safety data are ahead of expectations, but Uber is still not a simple disruption target.
2. Waymo weekly rides have reached 500,000; the report expects this to reach 1 million rides per week in 2026. However, Uber’s U.S. ride-hailing volume is about 51 million rides per week, still roughly 50x Waymo’s level.
3. The investment implication is that autonomous driving will re-rate Google’s option value, while also forcing Uber to prove that its multi-supplier AV strategy works.
Netflix
1. Goldman Sachs maintains Buy on Netflix with a USD 120 price target. Q1 results were solid, but full-year guidance was not raised.
2. Q2 revenue forecast was lowered to USD 12.577 billion, and operating profit was lowered to USD 4.106 billion. Management attributed the pressure to the content slate, pricing adjustments, and ad-tech investment.
3. The platform implication is that video platforms still have growth curves in advertising, live streaming, gaming, and podcasts, but the market will focus on whether revenue growth and margin expansion move in tandem.
Reddit and Social Platforms
1. Morgan Stanley data show Reddit rose 24% in one week on Shopify integration, while AppLovin rose 27%, indicating that AI/e-commerce connectivity is becoming a re-rating signal for platform stocks.
2. AMZN/Google/META trade at 29x/26x/19x 2026 EPS, respectively, with Meta still at a discount to its own two-year average.
3. The investment implication is that platform stocks do not face a uniform AI risk. Ad conversion, merchant transactions, and agentic entry points will drive valuation dispersion.
Software/SaaS
Datadog
1. Datadog’s share-price performance has been relatively stable; Bernstein maintains Outperform and raises its price target from USD 167 to USD 180.
2. Q1 revenue was USD 1.0064 billion, up 32% YoY and about 5% above consensus; AI-native customers added around USD 15 million in revenue QoQ and contributed nearly USD 200 million in ARR.
3. The risk is that OpenAI may reduce Datadog usage, but 22 AI-native customers have ARR above USD 1 million, and almost all use more than 10 products, indicating platform penetration rather than single-point demand.
"Born-in-AI added around +$15MM revenue QoQ"
MongoDB
1. Bernstein maintains Outperform on MongoDB and raises its price target from USD 428 to USD 449.
2. 1Q27 revenue was USD 688 million, up 25% YoY. Atlas cloud revenue grew 29.4% YoY and accounted for 75% of total revenue; management raised FY27 revenue guidance to USD 2.920-2.960 billion.
3. AI contribution remains small but is accelerating. The report argues MongoDB’s positioning is “the database used by AI,” rather than trying to become an AI platform.
"MongoDB is targeting being the database used by AI rather than trying to be an AI platform"
Cloudflare
1. Citi maintains Buy/High Risk on Cloudflare with a USD 265 price target. The main thesis is that Investor Day may lean more optimistic on revenue.
2. Internal AI usage at the company has increased 600% over the past three months, but AI, Workers, and free-to-paid conversion will pressure gross margin; 2026E/2027E gross margins are both 72.4%.
3. The key debate is whether AI traffic is a high-quality growth headwind or a cost-pressure issue under a high valuation.
"internal AI usage +600% L3M"
Adobe
1. HSBC upgraded Adobe to Buy with a USD 308 price target, arguing that the market is overestimating AI competitive risk.
2. 2QFY26 revenue grew 12.7% YoY, FY26 revenue guidance implies +11.8%, and AI-first revenue tripled YoY but accounted for only about 2% of 2QFY26 revenue.
3. This suggests AI is more of an embedded enhancement than an immediate replacement for creative-software revenue. The next test is whether generative features can convert into ARPU.
Snowflake and Data Cloud
1. Snowflake did not have new standalone hard data, but multiple software reports used it as a comparison benchmark for AI data platforms.
2. The MongoDB report said Snowflake’s stronger beat-and-raise raised market expectations for data infrastructure.
3. The investment implication is that data cloud and database companies need to provide three types of evidence: AI usage, customer expansion, and margins. Simply talking about AI is no longer enough.
Consumer Electronics/Smart Vehicles
Apple
1. Apple’s near-term trading anchor has shifted from the AI narrative back to the iPhone 17 supply chain and ASP. Goldman Sachs expects the iPhone 17 lineup to include base, Air, Pro, and Pro Max models, with preorders on September 12 and launch on September 19.
2. On specs, the base model screen increases from 6.1 inches to 6.3 inches, A19/A19 Pro use 3nm, RAM rises to 12GB from 8GB in the iPhone 16 series, and the front camera increases from 12MP to 24MP.
3. The Pro may remove the 128GB starting capacity, supporting ASP. The risk is that AI-enhanced Siri is delayed to 2026, meaning hardware upgrades and AI experience may not be fully synchronized.
"forecast iPhone revenue to grow +5% yoy in F2025E before accelerating to +7% yoy growth in F2026E"
Tesla
1. Tesla fell 7.57% even though Q2 deliveries were 480,126 vehicles, above the 406,024-vehicle expectation; production was 451,758 vehicles, and energy-storage deployment was 13.5GWh.
2. Goldman Sachs had previously raised its Q2 delivery forecast from 405,000 to 420,000, but maintained Neutral and a USD 375 price target.
3. The market is concerned that the delivery beat came from pulled-forward demand. The next question is whether FSD, Robotaxi, Model Y L, and energy storage can support margins.
4. Tesla Model Y L: 1. Reports say Tesla launched a larger Model Y L in the U.S., debuting the Limited Edition Premium AWD Launch Series at USD 61,990.
5. The package includes one year of FSD, one year of Supercharging, and one year of Premium Connectivity. UAE version deliveries start in November 2026.
6. The investment implication is that Tesla continues to use lineup extension and software-package bundling to stimulate demand, but whether this can lift gross margin still depends on real orders and price discounts.
"2Q26 vehicle deliveries are likely tracking ahead of consensus"
Qualcomm and MediaTek
1. Qualcomm fell 2.76% last night, as handset SoCs and edge AI remain weighed down by end-demand pressure; at its prior Investor Day, Qualcomm positioned its data-center revenue target as a potential catalyst.
2. MediaTek faces risk from Amazon consumer devices reducing external chip usage, but the bigger 2027 focus is potential customer opportunities in custom AI ASICs.
3. The consumer chip chain is diverging: mainstream handsets and IoT are under pressure, while cloud-customer ASICs and high-end edge-AI handsets still offer incremental growth.
Xiaomi and Smart-Hardware Chain
1. Xiaomi-related materials mainly focus on premium EVs, AI glasses, and ecosystem expansion, but ordinary Chinese NEV sales do not enter this report’s main thread.
2. The investable implication is that consumer electronics companies are connecting AI glasses, smartphones, cars, and home devices into ecosystems, rather than relying only on a single smartphone cycle.
3. Follow-up validation points are premium vehicle order quality, AI-glasses retention, and supply-chain gross margin, rather than short-term launch-event enthusiasm.
Investment Bank Price-Target Changes Over the Past 12 Hours
Huang’s Select Portfolio
404K Tech Morning Brief 2026-07-03 — AI Infrastructure Pullback, Memory Pricing Power, Software Relative Strength
目录
After-Hours Summary
U.S. Stocks Making New Highs
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry
Semiconductor Equipment/Test
Optical Communications/Optical Chain
High-Speed Interconnect/Connectors/Thermal and Power
Internet/Platforms
Software/SaaS
Consumer Electronics/Smart Vehicles
Investment Bank Price-Target Changes Over the Past 12 Hours
Huang’s Select Portfolio
The AI trade last night shifted from “what can still go up” to “who is paying for compute.” Semiconductors and the memory chain sold off sharply, but investment-bank and supply-chain data still point to no cooling in demand for server CPUs, HBM, NAND, optical interconnects, AI cloud, and enterprise AI software.
After-Hours Summary
U.S. equities showed a clear structural split after hours. The S&P; 500 fell 0.18%, the Nasdaq 100 fell 1.69%, the Dow rose 1.00%, the equal-weight S&P; 500 rose 0.70%, and the small-cap Russell 2000 fell 0.58%. Technology retreated from leadership, while capital tilted more toward healthcare, financials, staples, and utilities, indicating that the AI trade has entered a short-term phase of profit-taking and valuation reassessment.
Semiconductors saw the heaviest drawdown, with SMH down 4.36%, SOXX down 5.57%, the AI & Big Data ETF down 2.80%, and the technology ETF down 2.71%. Software, by contrast, held relative strength: IGV rose 0.25%, with a five-day gain of 10.39% and RPS5 at 100.0. The market message is straightforward: capital has not left AI; it is rotating from crowded hardware trades toward software and platforms with nearer-term earnings and lighter cash-flow intensity.
At the single-stock level, pressure was concentrated in memory, optical communications, equipment, and the AI server chain. SanDisk fell 13.26%, SK Hynix fell 14.57%, Seagate fell 10.38%, Western Digital fell 9.79%, Applied Materials fell 7.21%, Teradyne fell 13.02%, and Coherent fell 9.59%. This was not a collapse in demand data. Rather, debates over Meta selling compute externally, AI cloud utilization, and upstream pricing power all emerged at the same time, prompting the market to cut high-beta names first.
U.S. Stocks Making New Highs
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
OpenAI and Anthropic
1. Compute demand from frontier model companies continues to push upstream capex higher. Reports suggest OpenAI and Anthropic together may need more than 100GW of compute by 2030.
2. Anthropic has begun early work on developing its own AI chip and has discussed potential manufacturing with Samsung Electronics, considering a 2nm process and advanced packaging.
3. The investment implication is that large-model companies are moving from buying GPUs toward custom ASICs, and future orders will be redistributed among Nvidia, Broadcom, Samsung Electronics, TSMC, and cloud providers.
“Anthropic has begun preliminary work on developing its own AI chip. The company reportedly discussed potential manufacturing with Samsung Electronics. Anthropic is evaluating the chip’s capability, performance, and server integration.”
Meta
1. Meta fell 4.90% last night, but BofA still reiterated a Buy rating and an $835 price target, citing stronger AI models, progress on MTIA processors, and the path to AI monetization.
2. The market is concerned that Meta’s shift toward AI cloud could pressure neocloud valuations, but multiple clues point to continued tightness in Meta’s compute supply. Bernstein estimates Meta has roughly a 20GW global footprint, with another roughly 14GW coming online over the next few years.
3. The near-term risk is that Zuckerberg said AI agent development over the past four months has not accelerated as expected, indicating a timing gap between capex intensity and application monetization.
“AI agent development over the last four months has not accelerated in the way we expected”
Microsoft
1. Microsoft rose 1.62%, showing more resilience than the AI hardware chain, mainly because the market is more willing to assign valuation to enterprise AI deployment and cloud revenue certainty.
2. The company plans to invest $2.5 billion and allocate 6,000 industry and engineering experts to establish Frontier Company, helping customers deploy AI systems that deliver measurable business outcomes.
3. This type of business does not directly increase GPU order numbers, but it can validate whether enterprises are willing to keep paying for AI applications, serving as an ex-post demand anchor for hardware capex.
Palantir
1. DA Davidson upgraded Palantir to Buy and raised its price target from $165 to $175; a separate Citi report set a $225 target.
2. Q1 revenue growth was 85%, FY26 revenue guidance was raised by 10 percentage points, U.S. commercial revenue grew 133% year over year, and U.S. government business accelerated by 18 percentage points.
3. The debate is valuation. The FY28 target price implies roughly 65x EV/FCF, but if enterprises are unwilling to bind themselves to a single model, the AI orchestration layer still has real budget behind it.
“Strong Q1 Execution and Upsized FY26 Outlook Reinforces AI Thesis”
CSP/Cloud Capital Expenditure
Google
1. Google fell 0.79%. Wells Fargo cut its price target from $435 to $416 but maintained an Overweight rating, as search and cloud growth were stronger than expected, while higher AI investment reduced long-term forecasts.
2. Investment-bank materials continue to frame external TPU sales, cloud orders, and search AI monetization as the main themes; another report raised its price target to $447.
3. The investment implication is that the debate on Google is not about demand, but whether AI capex can convert into search, cloud, and TPU revenue rather than only pressuring margins.
Amazon
1. Amazon rose 0.41%. Wells Fargo raised its price target to $313 and maintained an Overweight rating, with the core thesis being that AWS is benefiting from AI demand, compute expansion, and improved pricing power.
2. The materials also noted that Amazon may reduce its reliance on external chips for consumer electronics devices and redirect more capex toward AI infrastructure.
3. This is pressure for consumer-chip suppliers such as MediaTek, while signaling budget reallocation toward AWS in-house chips, Trainium, and the data-center investment chain.
Apple
1. Apple rose 4.84%, supported by expectations for at least five new iPhone models in 2H26 and 1H27.
2. Goldman Sachs maintained a Buy rating and a 12-month price target of $266, expecting iPhone revenue to grow 5% year over year in FY2025E and accelerate to 7% in FY2026E.
3. The risk is that AI-enhanced Siri will not launch until 2026. Hardware upgrades in memory, chips, and cameras will need to wait for software experience delivery before replacement-cycle elasticity can be validated.
AI Cloud/Data-Center Operators
Oracle and Crusoe
1. Crusoe is in talks to raise roughly $3 billion, potentially at a valuation close to $30 billion, nearly twice its prior valuation.
2. The company provides AI compute to Meta and Oracle. The upward valuation reset shows that capital markets remain willing to pay for AI data-center outsourcing.
3. For Oracle, OCI is not only a cloud-service growth driver; it is also a valuation variable tied to AI facilities, long-term leases, and financing capacity.
CoreWeave
1. CoreWeave was pressured by the narrative around Meta selling compute externally, but Rosenblatt reiterated a Buy rating and a $250 price target, viewing the pullback as a repricing opportunity under GPU shortages and contractual constraints.
2. Nvidia previously had an unsold-capacity agreement through 2032 worth $6.3 billion, along with another $3.5 billion of guarantees related to data-center leases.
3. The risk is revenue quality and utilization. If customers bring their own GPUs into a colo model, AI cloud revenue per MW and capital returns will be lower than the pure GPU service-provider narrative implies.
“AI Compute Partnership”
Nebius and IREN
1. Nebius’s AI cloud platform is close to full utilization. Reports said Q2 sales were constrained by capacity rather than demand, with customers expanding from AI-native startups to large enterprises.
2. IREN appointed a product executive with experience at Oracle Cloud and in multi-cloud environments to advance GPU, managed services, and platform products, while emphasizing its 5GW secured grid-connected power portfolio.
3. The investment implication is that new cloud valuations are shifting from “who has GPUs” to “who has power, land, productization capability, and long-term customers.”
GPU/CPU/ASIC
Nvidia
1. Nvidia fell 1.36%, but the key development is business-model expansion: the company is reportedly providing financial backstops to smaller GPU cloud providers in exchange for a share of cloud revenue and guarantees to rent unused GPU capacity.
2. This can help customers finance GPU purchases and data centers, while also extending Nvidia from one-time hardware sales into recurring AI cloud revenue.
3. The risk is circular transactions and cloud revenue quality. The key follow-up is whether this capacity is absorbed by real end customers, rather than supported only by upstream credit.
Intel
1. Intel fell 5.10%, but HSBC raised its price target from $100 to $200 and maintained a Buy rating, citing stronger server CPU shipments, growing demand for Intel Foundry, and increased customer commitments in 2H26.
2. The company also raised suggested prices for Core Ultra 200S Plus. Core Ultra 7 270K Plus rose from $299 to $339-349, while Core Ultra 5 250K Plus rose from $199 to $219-229.
3. The investment implication is that the CPU cycle is recovering, but if retail pricing follows, Intel’s price-performance positioning relative to AMD will be reassessed.
“HSBC doubles Intel price target”
Broadcom
1. Broadcom fell 2.51%. J.P. Morgan reiterated Overweight and raised its price target from $500 to $580, with the main thesis being accelerating AI ASIC/XPU compute and networking orders.
2. F2Q26 revenue was $22.187 billion, up 48% year over year; AI semiconductor revenue was $10.8 billion, up roughly 143% year over year; AI semiconductor bookings exceeded $30 billion.
3. Management still describes FY27 AI revenue as exceeding $100 billion, while J.P. Morgan maintains its view of more than $150 billion. The debate is whether power, facilities, and GW-scale customer commitments can be delivered.
“AI bookings eclipsed $30B against $10.8B shipped”
AMD
1. AMD fell 4.26%. BofA reiterated Buy and raised its price target from $310 to $450, arguing that agentic AI expands the CPU/GPU TAM.
2. 1Q26 revenue was $10.253 billion, up 37.8% year over year; data-center revenue was $5.775 billion, up 57.2%; server CPU revenue was $3.293 billion, up 54.9%.
3. BofA estimates that each incremental 1GW customer opportunity corresponds to $15-20 billion of incremental opportunity. The risk is that customer share from OpenAI, Meta, and others still needs to be allocated among Nvidia, Broadcom, Cerebras, and other suppliers.
“every GW is $15-$20bn in incremental opportunity”
HBM/DRAM/NAND/SSD/HDD
Micron
1. Micron fell 5.60%, but Citi raised its price target from $425 to $840, judging that HBM prices could still rise in 2027.
2. Citi expects DRAM ASP to rise 200% year over year in 2026 and NAND ASP to rise 186% year over year; Micron 2027E EPS was raised from $94.55 to $104.56.
3. The risk is that high prices start to suppress downstream configurations. The report noted that Cisco has cut 50% of DRAM content in more than 20 projects.
“DRAM ASPs will increase 200% YoY in 2026, and NAND ASPs will increase 186% YoY in 2026”
Samsung Electronics and SK Hynix
1. Samsung Electronics fell 9.06% and SK Hynix fell 14.57%, but Citi raised its Samsung price target from KRW 460,000 to KRW 530,000 and lifted its 2026 operating-profit estimate by 20%.
2. Citi expects Samsung’s 2026Q2 DRAM and NAND ASPs to rise 44% and 57% quarter over quarter, respectively, with server DRAM blended ASP up 363% year over year and SSD pricing up 330% year over year.
3. SK Hynix reportedly removed some LTA price caps and extended agreements from one year to three to five years. Pricing power is strengthening, but customer prepayments and long-term contract structures will also amplify cyclical backlash.
SanDisk
1. SanDisk fell 13.26%. BofA reiterated Buy and raised its price target from $300 to $390, with the main theme being NAND’s rising strategic role in AI inference.
2. The report forecasts FY2027E revenue of $13.6277 billion and EPS of $27.31, with NAND prices potentially rising 20%-30% quarter over quarter in 4Q and another 30%+ in 1Q.
3. The key change is that large context windows and dedicated storage tiers are raising the value of eSSD. Risks include NAND capacity expansion, Chinese supply, and slow rollout of AI consumer applications.
“NAND could be up +20-30% q/q in 4Q followed by another 30%+ increase in 1Q”
Seagate and Western Digital
1. Seagate fell 10.38% and Western Digital fell 9.79%, with HDD/NAND stocks following the high-beta memory pullback.
2. The move did not change the logic that data-center enterprise drives and high-capacity storage are benefiting from AI inference, cold data, and expanding training datasets.
3. The near-term focus is whether cloud customers reduce configurations as memory, SSD, and HDD prices all rise at the same time. If storage consumes more downstream budget, server BOM allocation will face new constraints.
Foundry
TSMC
1. TSMC ADR fell 2.27%, but long-term commitments to U.S. manufacturing continue to advance; Taiwan regulators approved a $20 billion capital injection by TSMC into Arizona Corporation.
2. The funding will be used for U.S. 12-inch wafer fabs and advanced packaging facilities, bringing total funds flowing to the U.S. to $44 billion, part of the $165 billion commitment.
3. The investment implication is that U.S. manufacturing in the AI era is moving from symbolic expansion toward a logic manufacturing plus advanced packaging ecosystem, while core R&D; and leading-edge processes remain in Taiwan.
Samsung Foundry
1. Anthropic’s talks with Samsung on manufacturing its self-developed AI chip have shifted market focus from Samsung’s HBM share to whether its 2nm process and advanced packaging can win frontier-model customers.
2. Other reports suggest Samsung Foundry has entered a customer-allocated capacity state in some processes and has begun screening new orders.
3. For TSMC, this confirms tight supply. For Samsung, it is another test of yield, packaging, and customer trust.
Semiconductor Equipment/Test
Applied Materials
1. Applied Materials fell 7.21%. Goldman Sachs maintained Buy and raised its price target from $310 to $390.
2. FY1Q revenue was $7.012 billion, above consensus of $6.890 billion; the midpoint of FY2Q revenue guidance was $7.65 billion, above consensus of $7.076 billion.
3. The company guided for semiconductor equipment business growth of more than 20% in 2026, with roughly 55% exposure to deposition and etch, benefiting from GAA logic, stacked memory, and advanced packaging.
“semiconductor equipment business to grow over 20% in 2026”
Lam Research, KLA, Teradyne
1. Lam Research fell 10.19%, KLA fell 11.39%, and Teradyne fell 13.02%, as the equipment/test chain was sold as high-beta AI capex exposure.
2. Applied Materials’ strong guidance has positive spillover for etch, deposition, and process control, but the market is also worried about China WFE, U.S. export controls, and the pace of memory capex.
3. The next focus is whether DRAM/HBM/NAND capacity expansion continues to push orders higher, rather than only looking at a one-day semiconductor ETF pullback.
Optical Communications/Optical Chain
Coherent
1. Coherent fell 9.59%. Citi maintained Buy and raised its price target from $250 to $420, centered on high-growth businesses such as AI transceivers, CPO, and OCS.
2. FY2026E/FY2027E/FY2028E sales forecasts were raised by 2%/14%/13%, respectively. AI transceiver sales are expected to reach $3.2 billion in FY2026E and $5.6 billion in FY2027E.
3. Risks include EML supply-demand, 6-inch fab expansion, SiPho 1.6T, and CPO customer qualification, but optical modules remain the key outlet for AI capex spreading from GPUs to networking.
“Coherent’s AI transceiver sales to reach $3.2B (+99% YoY) and $5.6B (+72% YoY)”
Arista
1. Arista fell 3.98%. J.P. Morgan maintained Overweight with a December 2026 price target of $200, based on 2027E EPS of $4.75 and roughly 42x P/E.
2. The 7060XE7 series 1.6T switches expand the company from AI scale-out networking into scale-up rack-level networking. The first 64-port 1.6T air-cooled systems are expected to ship in 4Q26.
3. The AI scale-up networking market is expected to grow from $16.7 billion in 2026 to $78.5 billion in 2030. LPO’s roughly 60% reduction in interconnect power consumption is a customer TCO lever.
Nokia, Corning, Ciena
1. Nokia materials point to AI infrastructure buildout supporting optical and IP networks, while Corning and Ciena continue to be validated around fiber, optical-network orders, supply chain, and margins.
2. During last night’s optical communications pullback, the market first treated these companies as part of the “crowded AI hardware” trade rather than distinguishing them by order visibility.
3. The next focus is whether 1.6T, CPO, fiber cabling, and data-center interconnects continue to win budgets from CSPs and neoclouds.
High-Speed Interconnect/Connectors/Thermal and Power
Credo and Astera Labs
1. Credo fell 6.57% and Astera Labs fell 4.73%, but both companies remain on the core demand path as AI networking upgrades from copper cables and retimers to optical interconnects.
2. Credo’s earlier report tied its AEC leadership to emerging optical interconnect opportunities, while Astera materials emphasized opportunities in Scorpio X, memory expansion, and inference workloads.
3. The near-term pullback comes from cooling semiconductor valuations overall. The real validation points are 1.6T/800G rack deployments, customer concentration, and gross margin.
Vertiv, Eaton, GE Vernova
1. Vertiv fell 3.49%, Eaton fell 3.61%, and GE Vernova fell 0.32%, with the data-center power and thermal chain pulling back less than semiconductors.
2. GE Vernova’s power business accounted for 51.3% of 2025 revenue, and electrification accounted for 25.0%. AI data-center expansion is pushing power demand into a seller’s market.
3. If AI cloud valuation shifts from GPUs to power and delivery capability, electrical equipment, liquid cooling, power distribution, and on-site power will remain ways for capital to defensively express AI capex exposure.
Internet/Platforms
AppLovin
1. AppLovin sits on the expansion path for mobile performance advertising and e-commerce advertising; Morgan Stanley rates it Overweight with a USD 720 price target.
2. The report says AppLovin’s real conversion rate remains very low; every 10bp improvement in conversion could drive roughly 17 percentage points of net revenue growth. Another survey shows Axon penetration among Shopify stores is only about 0.34%.
3. The debate is whether e-commerce advertising can scale. Continued budget increases from major brands would lift valuation, while overly high CPP would limit scalability.
“each additional 10bps would drive 17 points of Cloudflare revenue growth”
Shopify
1. Shopify benefits from agentic commerce rather than being directly bypassed by LLMs; Goldman Sachs maintains Buy and lowers its price target from USD 193 to USD 168.
2. The report’s anchor point is that orders from AI search have increased 15x since January 2025, and LLMs do not bypass Shopify checkout, so GMV still flows through the Shopify ecosystem.
3. The investment implication is that if agentic shopping becomes a new entry point, Shopify’s value lies in merchants, payments, and unified commerce protocols, not merely website-building tools.
“orders from AI search grow 15x since January 2025”
Google/Waymo and Uber
1. Morgan Stanley believes Waymo’s commercialization expansion and safety data are ahead of expectations, but Uber is still not a simple disruption target.
2. Waymo weekly rides have reached 500,000; the report expects this to reach 1 million rides per week in 2026. However, Uber’s U.S. ride-hailing volume is about 51 million rides per week, still roughly 50x Waymo’s level.
3. The investment implication is that autonomous driving will re-rate Google’s option value, while also forcing Uber to prove that its multi-supplier AV strategy works.
Netflix
1. Goldman Sachs maintains Buy on Netflix with a USD 120 price target. Q1 results were solid, but full-year guidance was not raised.
2. Q2 revenue forecast was lowered to USD 12.577 billion, and operating profit was lowered to USD 4.106 billion. Management attributed the pressure to the content slate, pricing adjustments, and ad-tech investment.
3. The platform implication is that video platforms still have growth curves in advertising, live streaming, gaming, and podcasts, but the market will focus on whether revenue growth and margin expansion move in tandem.
Reddit and Social Platforms
1. Morgan Stanley data show Reddit rose 24% in one week on Shopify integration, while AppLovin rose 27%, indicating that AI/e-commerce connectivity is becoming a re-rating signal for platform stocks.
2. AMZN/Google/META trade at 29x/26x/19x 2026 EPS, respectively, with Meta still at a discount to its own two-year average.
3. The investment implication is that platform stocks do not face a uniform AI risk. Ad conversion, merchant transactions, and agentic entry points will drive valuation dispersion.
Software/SaaS
Datadog
1. Datadog’s share-price performance has been relatively stable; Bernstein maintains Outperform and raises its price target from USD 167 to USD 180.
2. Q1 revenue was USD 1.0064 billion, up 32% YoY and about 5% above consensus; AI-native customers added around USD 15 million in revenue QoQ and contributed nearly USD 200 million in ARR.
3. The risk is that OpenAI may reduce Datadog usage, but 22 AI-native customers have ARR above USD 1 million, and almost all use more than 10 products, indicating platform penetration rather than single-point demand.
“Born-in-AI added around +$15MM revenue QoQ”
MongoDB
1. Bernstein maintains Outperform on MongoDB and raises its price target from USD 428 to USD 449.
2. 1Q27 revenue was USD 688 million, up 25% YoY. Atlas cloud revenue grew 29.4% YoY and accounted for 75% of total revenue; management raised FY27 revenue guidance to USD 2.920-2.960 billion.
3. AI contribution remains small but is accelerating. The report argues MongoDB’s positioning is “the database used by AI,” rather than trying to become an AI platform.
“MongoDB is targeting being the database used by AI rather than trying to be an AI platform”
Cloudflare
1. Citi maintains Buy/High Risk on Cloudflare with a USD 265 price target. The main thesis is that Investor Day may lean more optimistic on revenue.
2. Internal AI usage at the company has increased 600% over the past three months, but AI, Workers, and free-to-paid conversion will pressure gross margin; 2026E/2027E gross margins are both 72.4%.
3. The key debate is whether AI traffic is a high-quality growth headwind or a cost-pressure issue under a high valuation.
“internal AI usage +600% L3M”
Adobe
1. HSBC upgraded Adobe to Buy with a USD 308 price target, arguing that the market is overestimating AI competitive risk.
2. 2QFY26 revenue grew 12.7% YoY, FY26 revenue guidance implies +11.8%, and AI-first revenue tripled YoY but accounted for only about 2% of 2QFY26 revenue.
3. This suggests AI is more of an embedded enhancement than an immediate replacement for creative-software revenue. The next test is whether generative features can convert into ARPU.
Snowflake and Data Cloud
1. Snowflake did not have new standalone hard data, but multiple software reports used it as a comparison benchmark for AI data platforms.
2. The MongoDB report said Snowflake’s stronger beat-and-raise raised market expectations for data infrastructure.
3. The investment implication is that data cloud and database companies need to provide three types of evidence: AI usage, customer expansion, and margins. Simply talking about AI is no longer enough.
Consumer Electronics/Smart Vehicles
Apple
1. Apple’s near-term trading anchor has shifted from the AI narrative back to the iPhone 17 supply chain and ASP. Goldman Sachs expects the iPhone 17 lineup to include base, Air, Pro, and Pro Max models, with preorders on September 12 and launch on September 19.
2. On specs, the base model screen increases from 6.1 inches to 6.3 inches, A19/A19 Pro use 3nm, RAM rises to 12GB from 8GB in the iPhone 16 series, and the front camera increases from 12MP to 24MP.
3. The Pro may remove the 128GB starting capacity, supporting ASP. The risk is that AI-enhanced Siri is delayed to 2026, meaning hardware upgrades and AI experience may not be fully synchronized.
“forecast iPhone revenue to grow +5% yoy in F2025E before accelerating to +7% yoy growth in F2026E”
Tesla
1. Tesla fell 7.57% even though Q2 deliveries were 480,126 vehicles, above the 406,024-vehicle expectation; production was 451,758 vehicles, and energy-storage deployment was 13.5GWh.
2. Goldman Sachs had previously raised its Q2 delivery forecast from 405,000 to 420,000, but maintained Neutral and a USD 375 price target.
3. The market is concerned that the delivery beat came from pulled-forward demand. The next question is whether FSD, Robotaxi, Model Y L, and energy storage can support margins.
4. Tesla Model Y L: 1. Reports say Tesla launched a larger Model Y L in the U.S., debuting the Limited Edition Premium AWD Launch Series at USD 61,990.
5. The package includes one year of FSD, one year of Supercharging, and one year of Premium Connectivity. UAE version deliveries start in November 2026.
6. The investment implication is that Tesla continues to use lineup extension and software-package bundling to stimulate demand, but whether this can lift gross margin still depends on real orders and price discounts.
“2Q26 vehicle deliveries are likely tracking ahead of consensus”
Qualcomm and MediaTek
1. Qualcomm fell 2.76% last night, as handset SoCs and edge AI remain weighed down by end-demand pressure; at its prior Investor Day, Qualcomm positioned its data-center revenue target as a potential catalyst.
2. MediaTek faces risk from Amazon consumer devices reducing external chip usage, but the bigger 2027 focus is potential customer opportunities in custom AI ASICs.
3. The consumer chip chain is diverging: mainstream handsets and IoT are under pressure, while cloud-customer ASICs and high-end edge-AI handsets still offer incremental growth.
Xiaomi and Smart-Hardware Chain
1. Xiaomi-related materials mainly focus on premium EVs, AI glasses, and ecosystem expansion, but ordinary Chinese NEV sales do not enter this report’s main thread.
2. The investable implication is that consumer electronics companies are connecting AI glasses, smartphones, cars, and home devices into ecosystems, rather than relying only on a single smartphone cycle.
3. Follow-up validation points are premium vehicle order quality, AI-glasses retention, and supply-chain gross margin, rather than short-term launch-event enthusiasm.
Investment Bank Price-Target Changes Over the Past 12 Hours
Huang’s Select Portfolio