
404K SEMI-AI Tech Morning Brief 2026-07-08 — Semis Cool, Memory Monetizes, AI Capex Keeps Spilling Over
目录
After-Hours Summary
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models/Applications and Capex
CSP/Cloud Capex
AI Cloud/Data Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry, Equipment, and Advanced Packaging
Optical Communications/High-Speed Interconnect/Power
MLCC/Passive Components, Power Semiconductors, and Server Chain
Space/Satellites and Robotics/Autonomous Driving
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Investment-Bank Target-Price Changes Over the Past 12 Hours
Lao Huang’s Selected Portfolio
Lao Huang’s Selected Portfolio
U.S. tech stocks diverged sharply after hours. Semiconductors and high-beta AI infrastructure names remained under pressure, but cloud capex, long-term memory contracts, AI cloud orders, power, and optical interconnects continue to provide hard support for the supply chain. The most important shift today: the market is moving from “only watching GPU and HBM shortages” toward validating cash flow, financing capacity, data-center power, and optical communications supply.
After-Hours Summary
The U.S. tech complex saw a clear de-crowding. The S&P; 500 fell 0.51%, the Nasdaq 100 fell 1.82%, and the tech ETF fell 2.39%.
The semiconductor ETF fell 3.69%, while the equal-weight semiconductor reference fell 5.13%. This was not a single negative catalyst, but a collective deleveraging across the strongest prior winners: memory, semiconductor equipment, interconnects, AI cloud, and small-cap compute names.
By style, software and cloud computing were relatively resilient. The cloud computing ETF rose 1.05%, the software ETF fell 0.70%, and communication services rose 0.73%.
Semiconductors, robotics and AI, and AI and big data fell 3.69%, 4.34%, and 2.76%, respectively. The market is not rejecting AI capex, but it is starting to require every layer of the chain to prove orders, cash flow, and funding sources.
At the single-stock level, NVIDIA, Meta, Amazon, and Microsoft remained relatively resilient; Intel, AMD, Micron, Western Digital, SanDisk, and the semiconductor equipment chain fell more sharply. The AI trade has entered its next phase: upstream demand remains intact, but equities are first digesting “peak rate of change” and financing pressure.
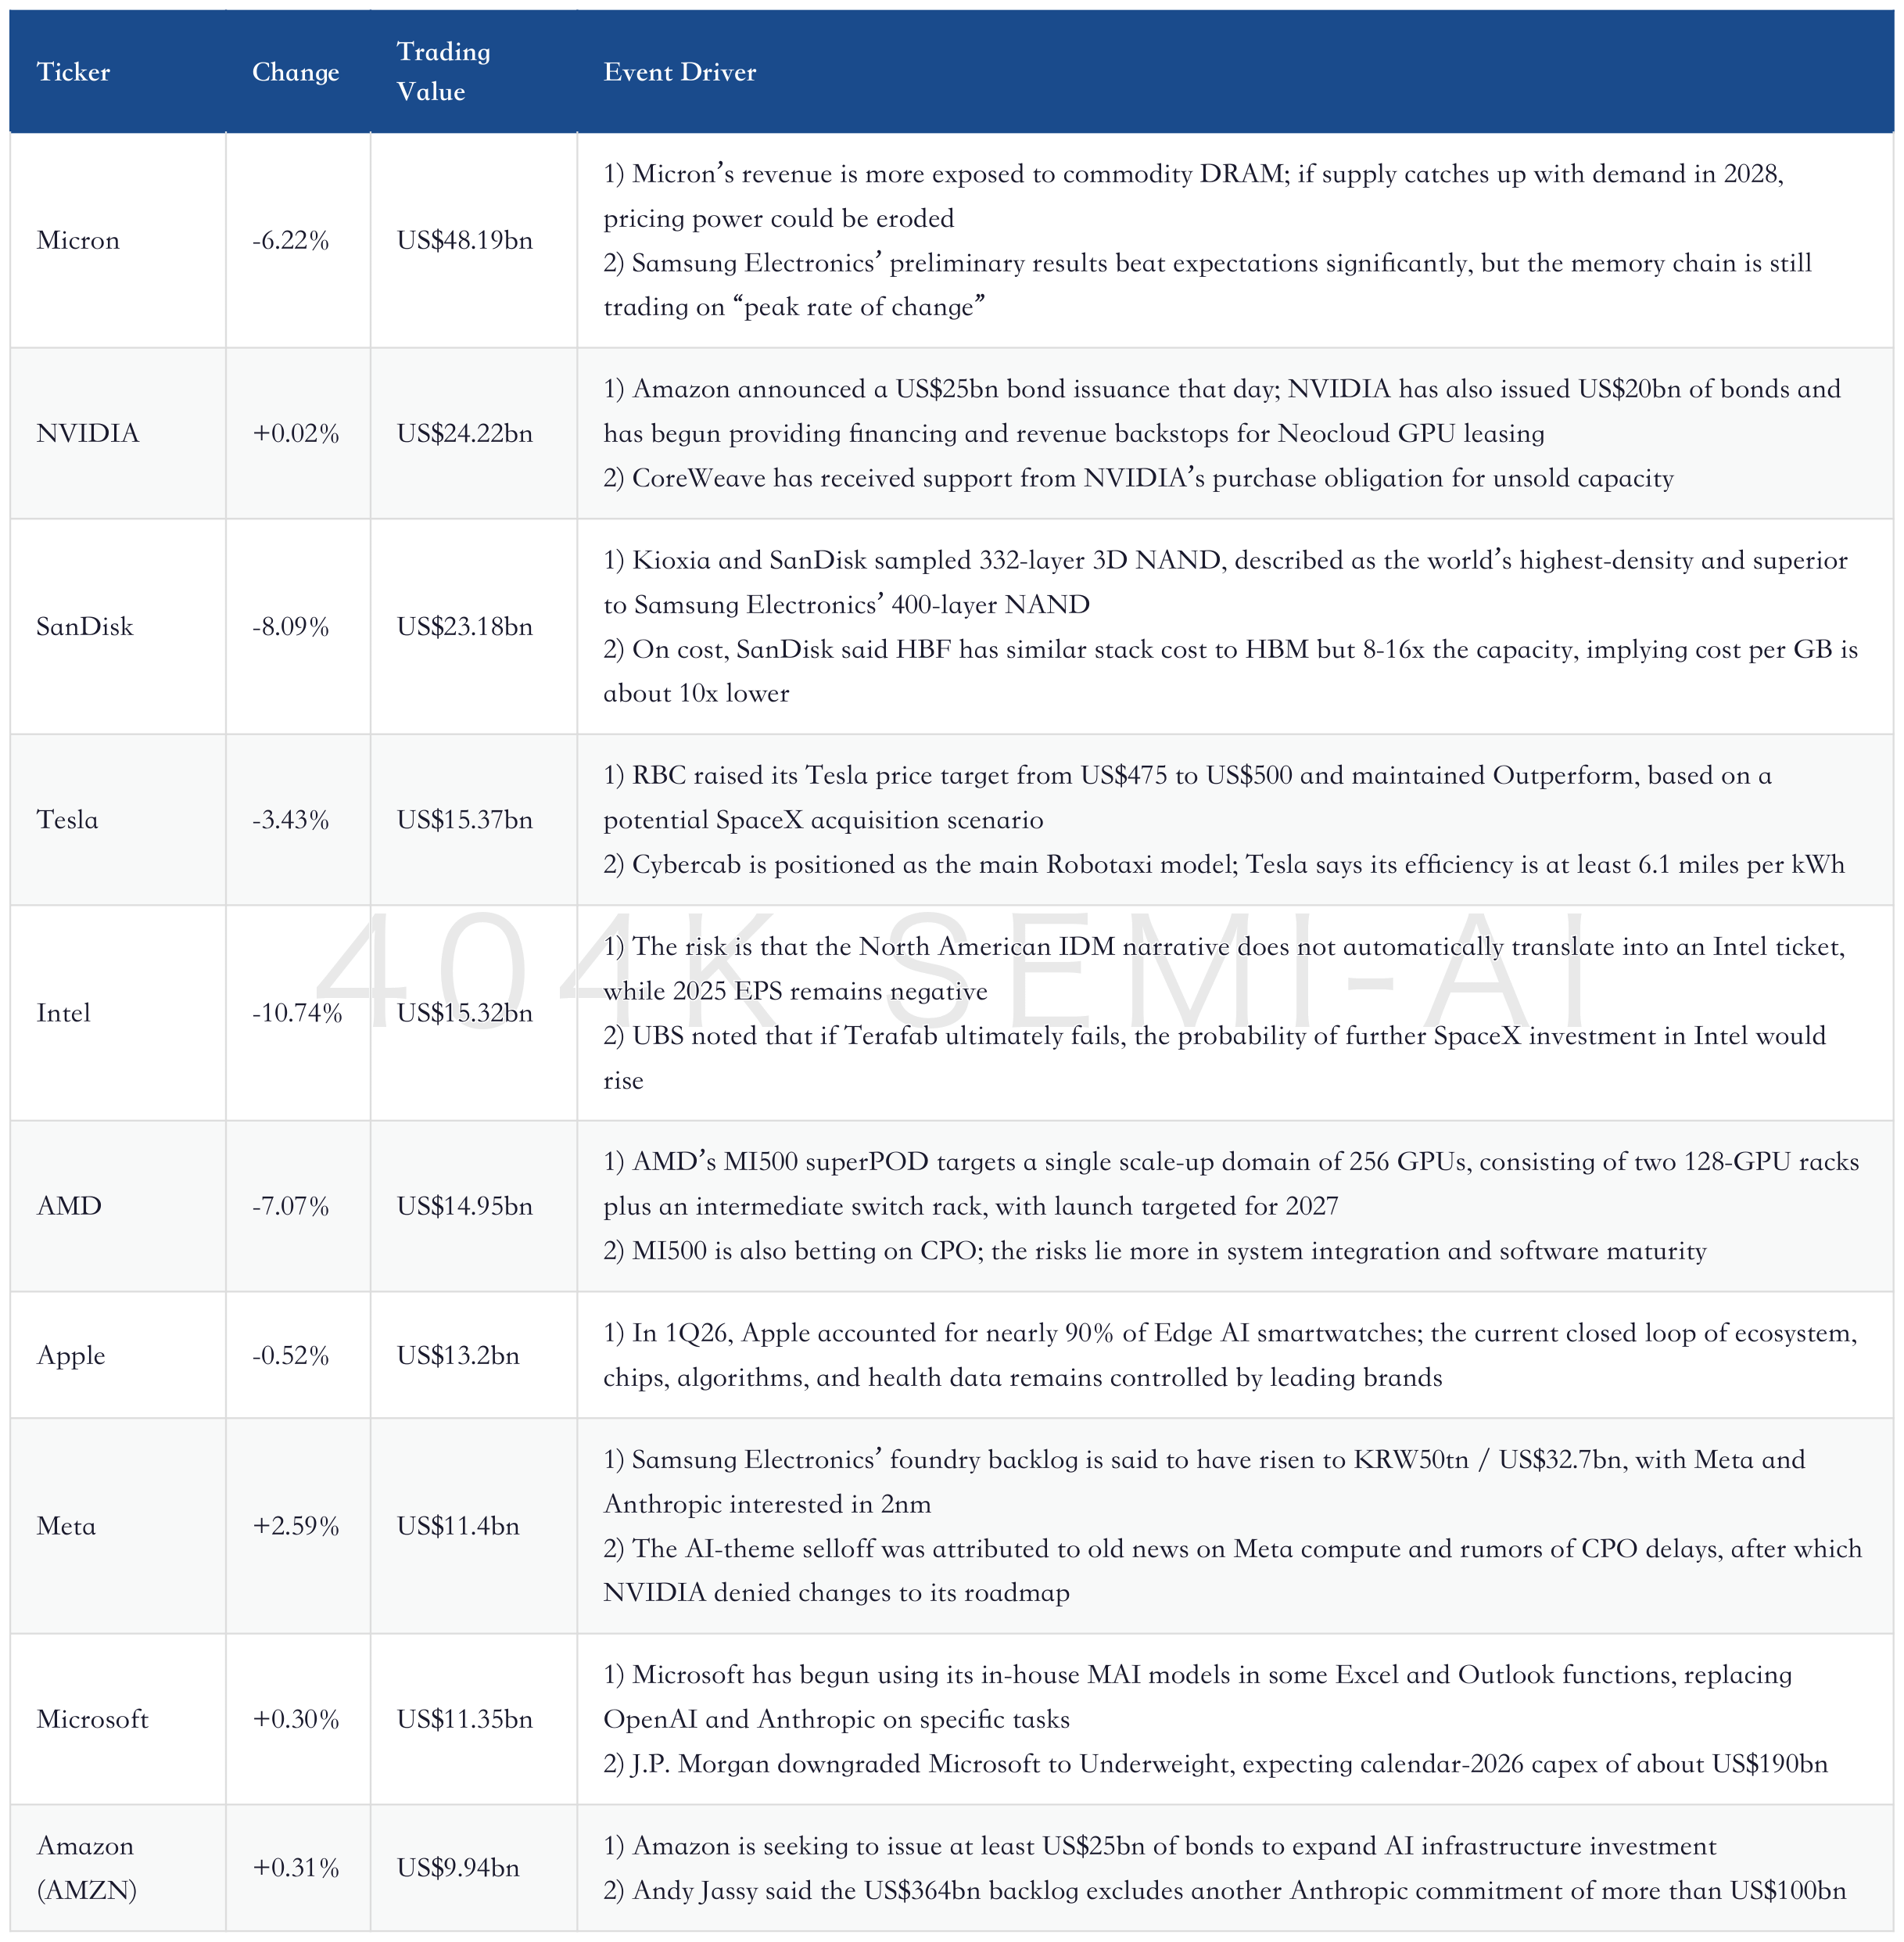
Top 10 U.S. Stocks by Trading Value
The most heavily traded names remained concentrated in memory, AI infrastructure, and large-cap tech.
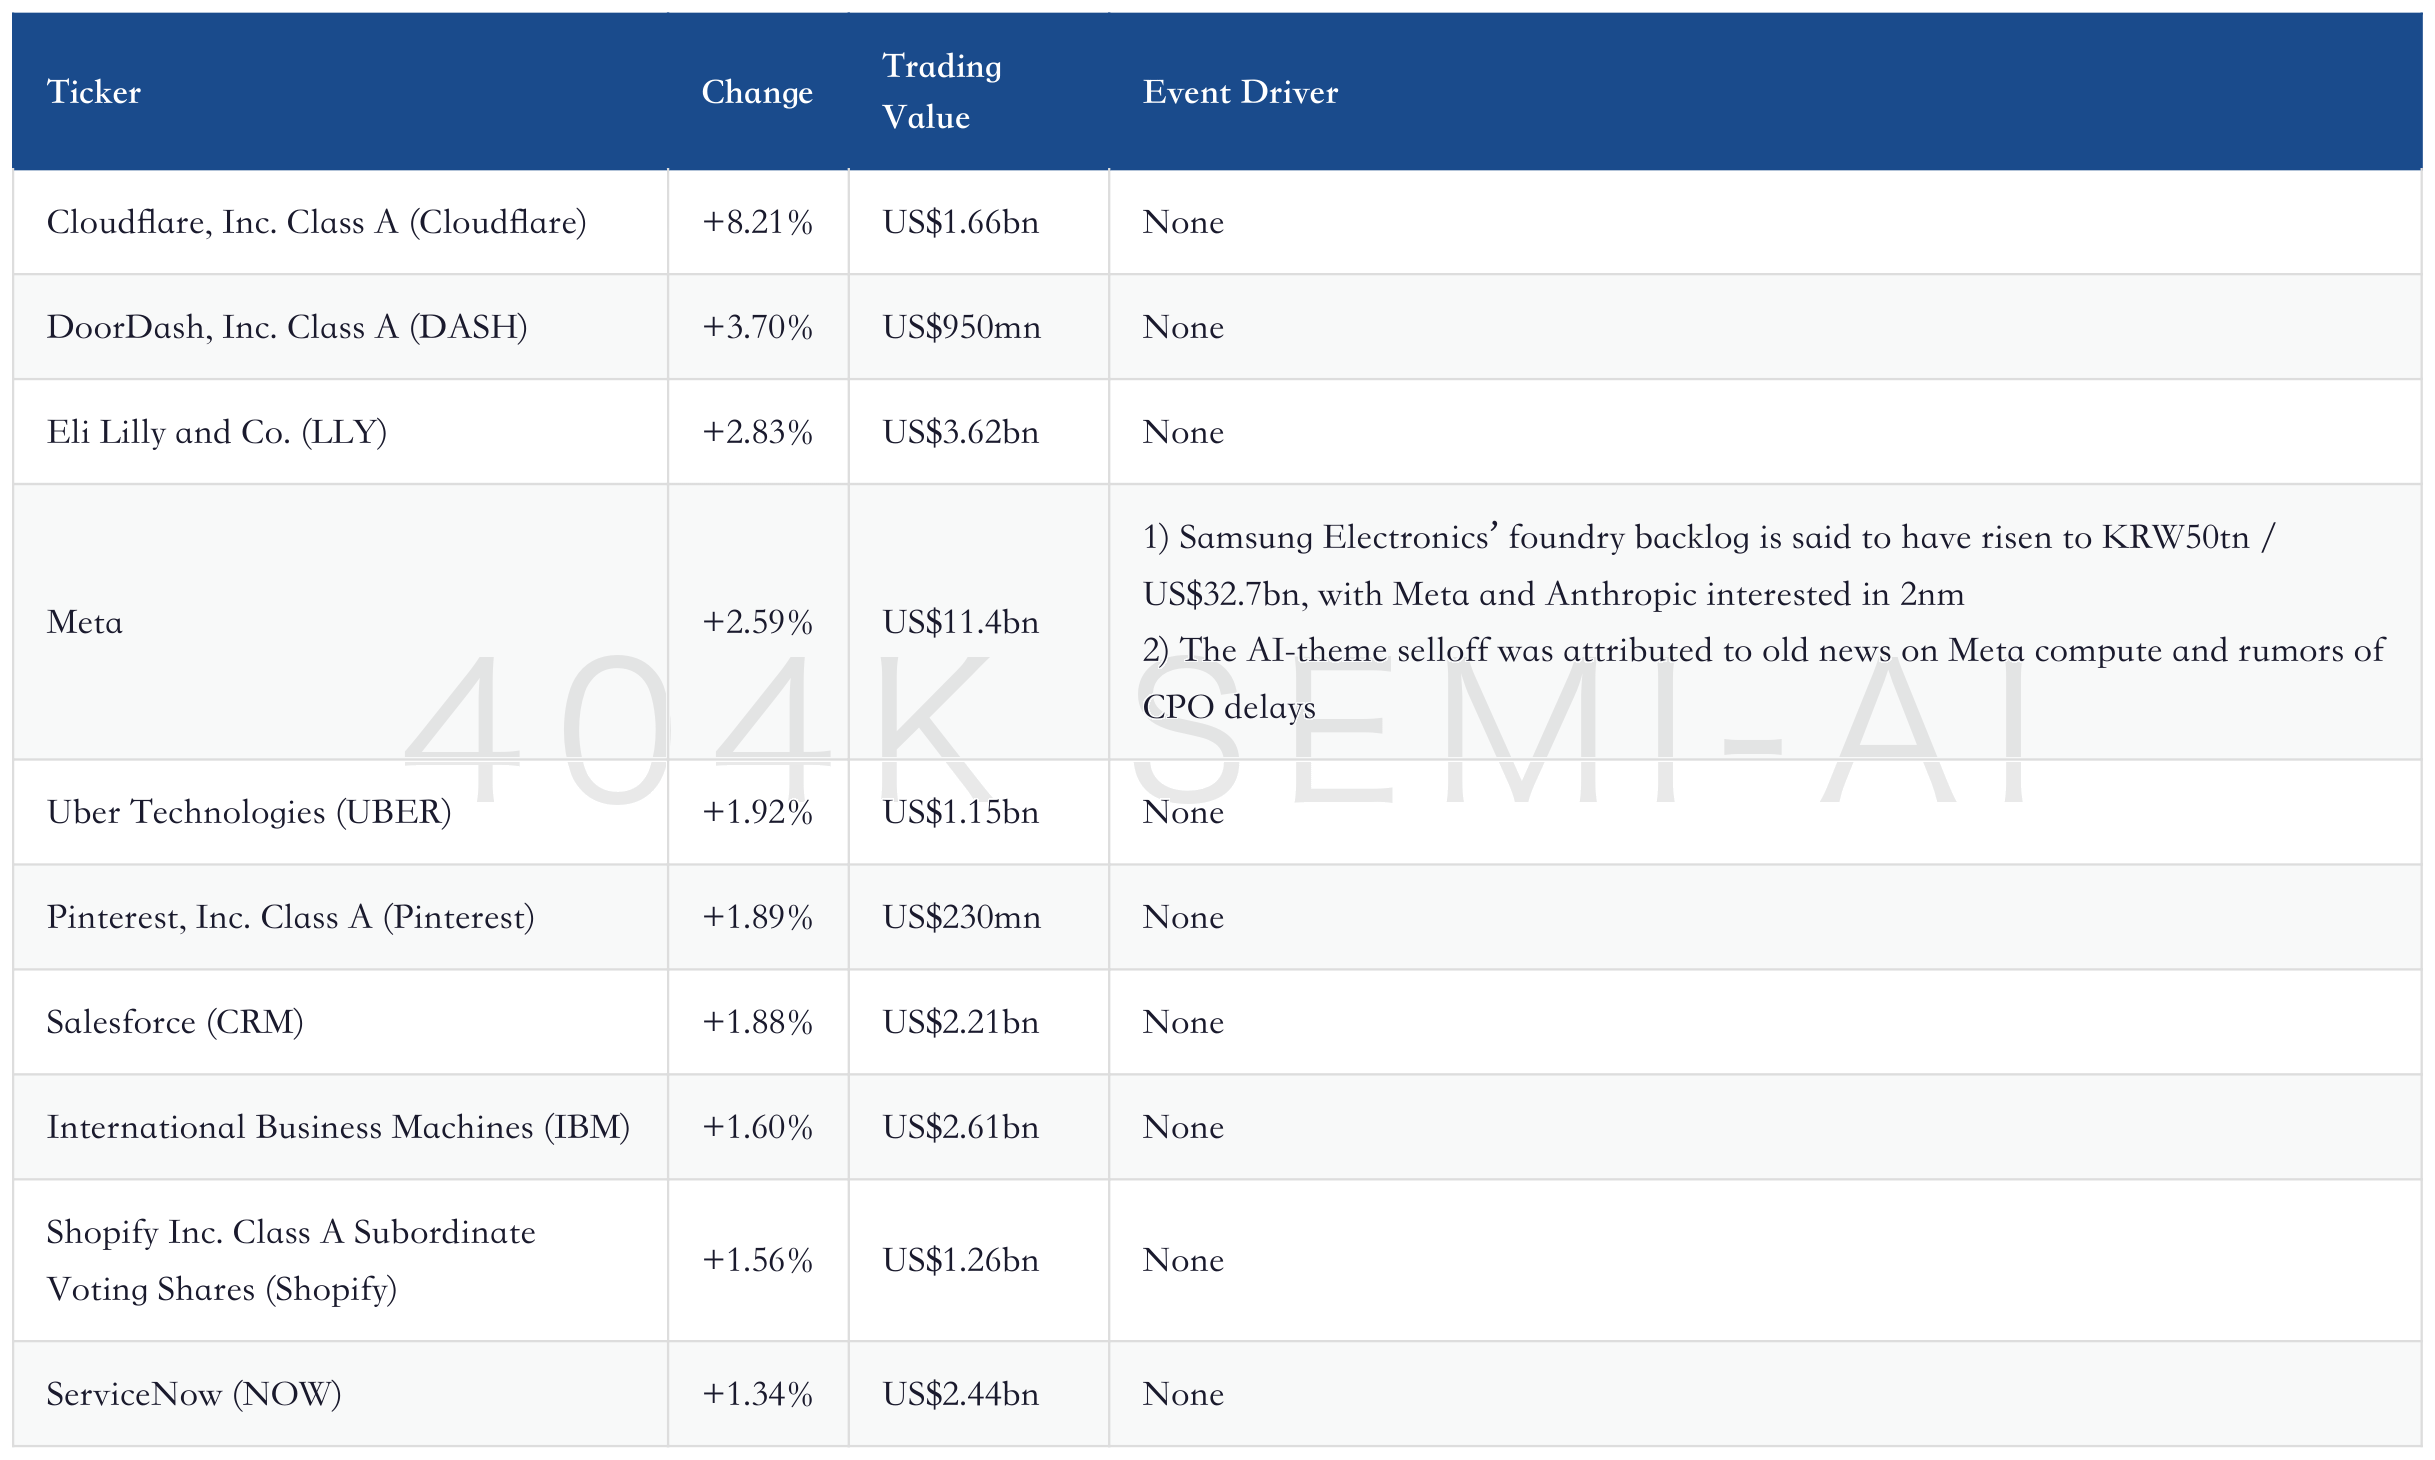
Top U.S. Stock Gainers
The gainers list shows software, platforms, and defensive tech assets were relatively resilient.
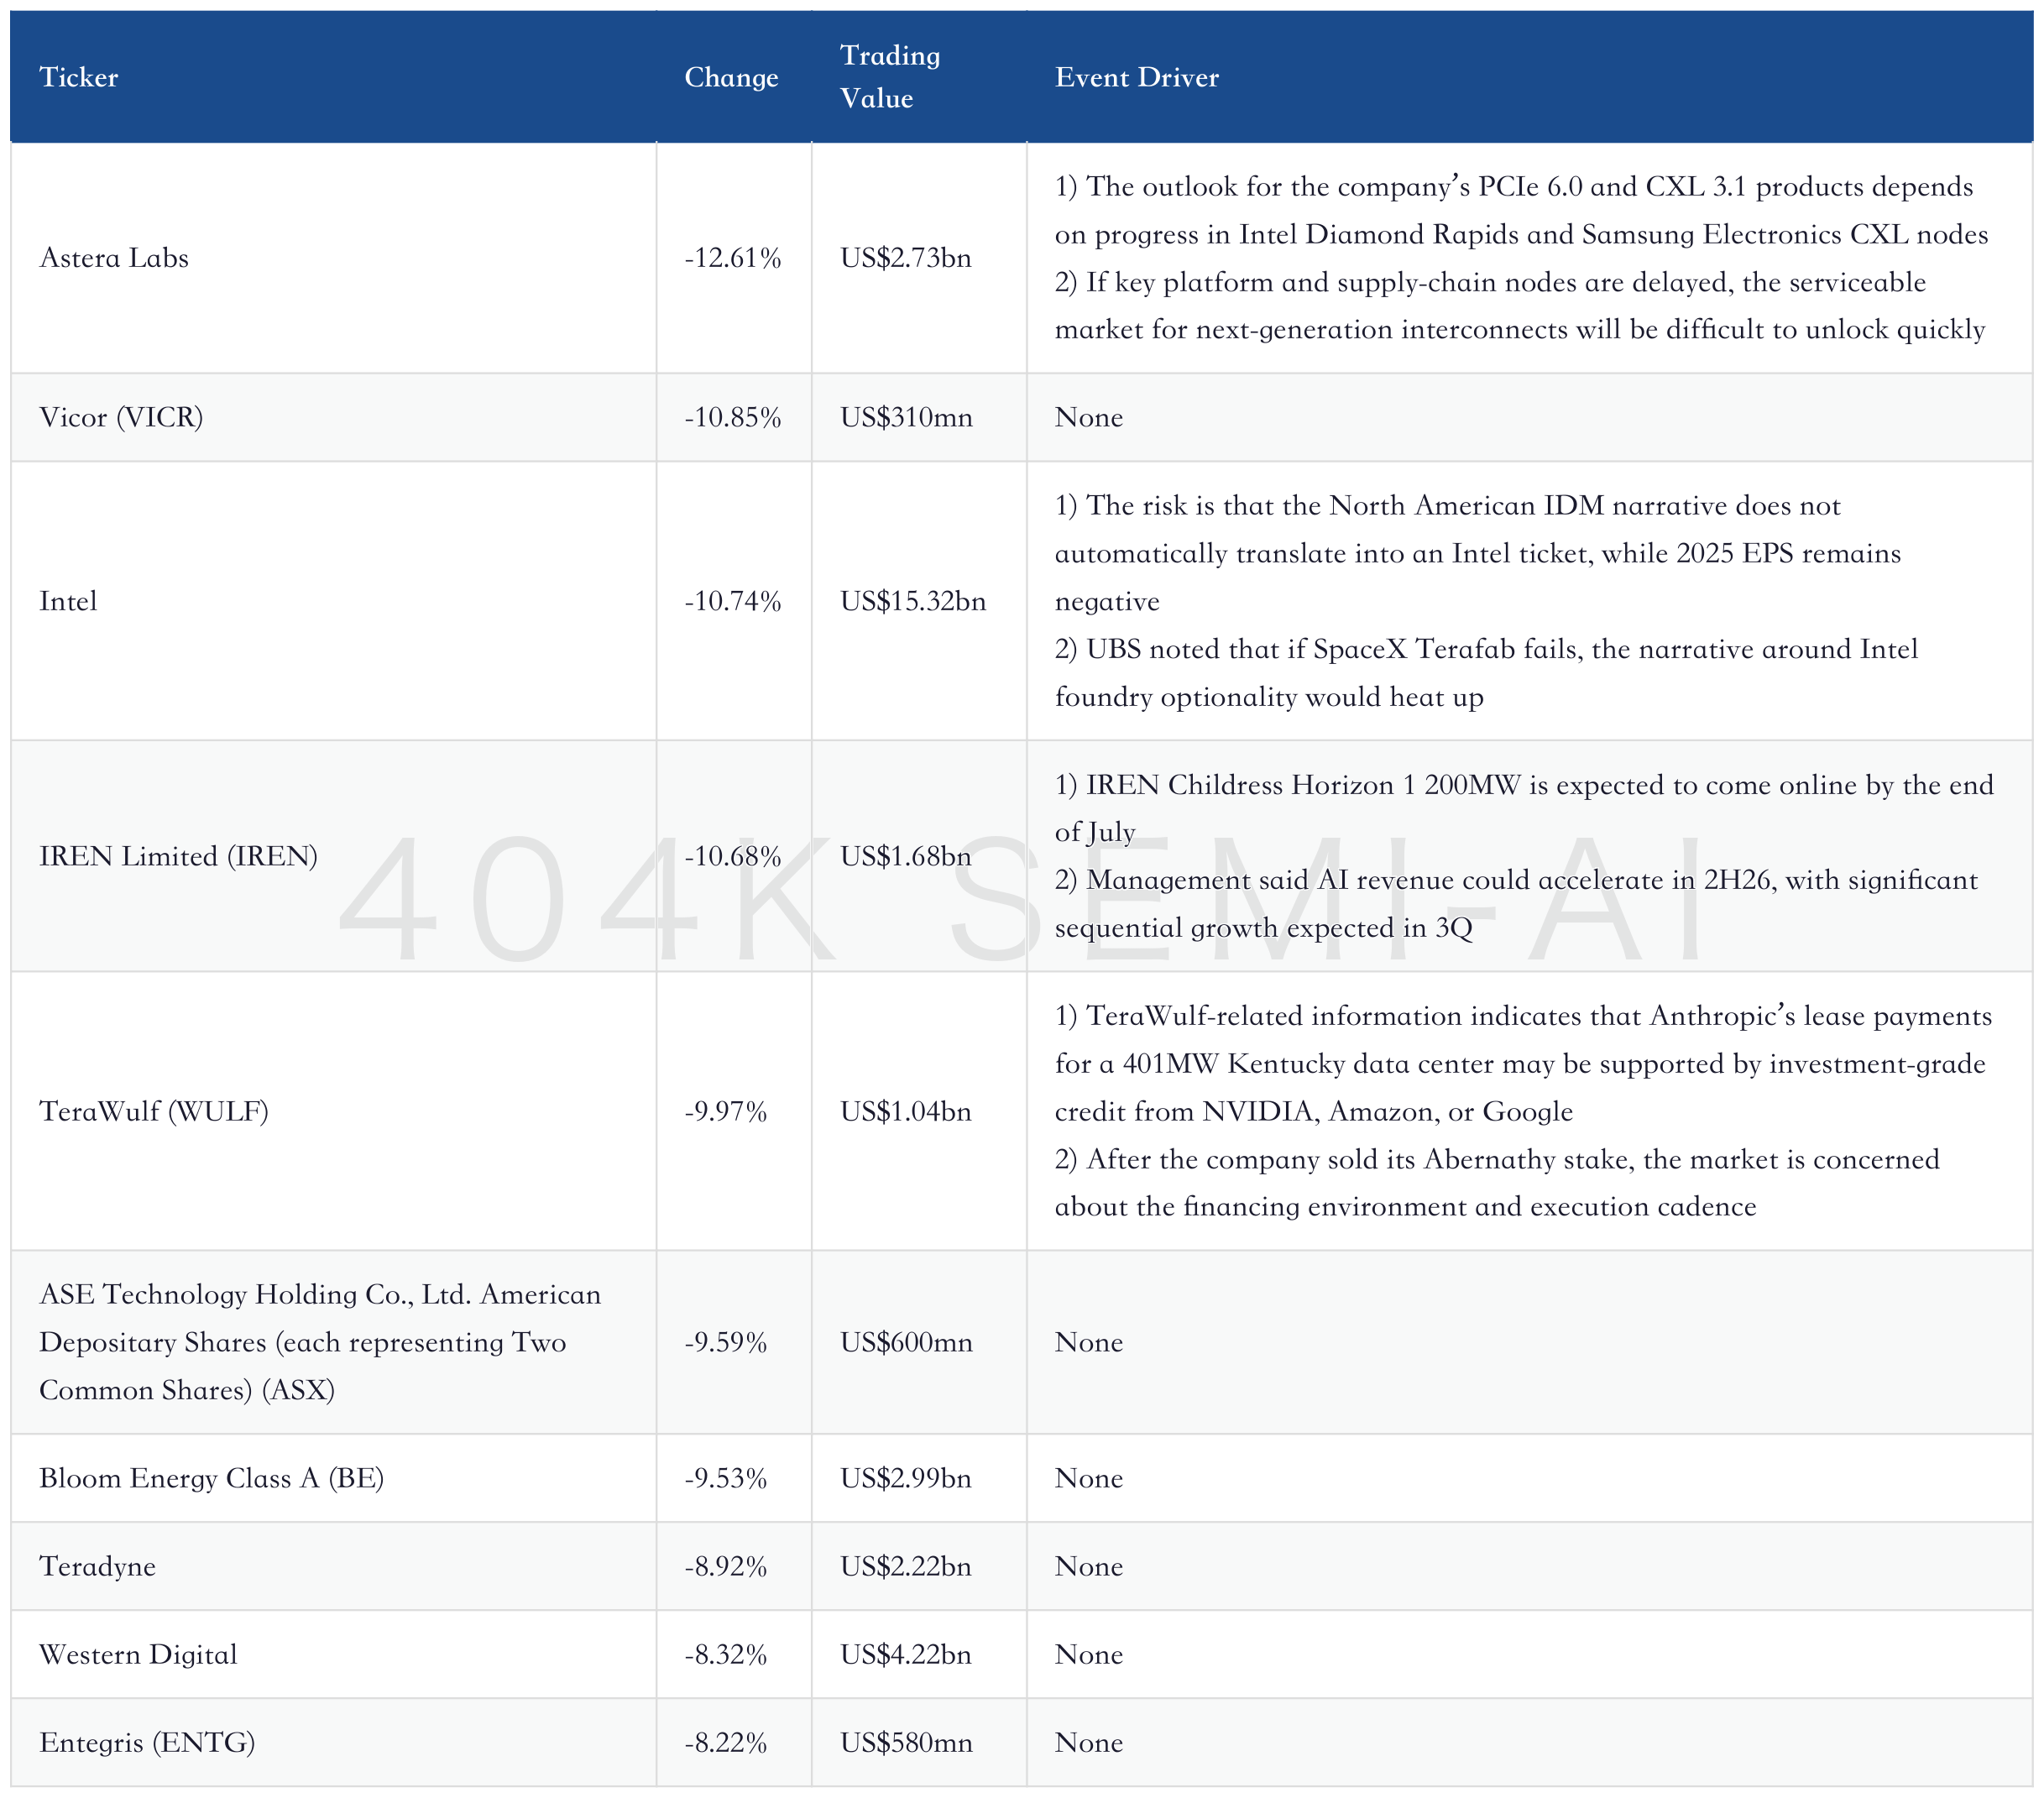
Top U.S. Stock Decliners
The decliners list was concentrated in interconnects, power, equipment, and the memory chain.
Full AI/Semiconductor Value Chain
AI Models/Applications and Capex
AI Application Deployment: The bottleneck in enterprise AI is shifting from model capability to deployment engineering. Over the next 12 months, five AI companies have committed $9.75 billion to front-end deployment engineering.
OpenAI and Anthropic raised $4.0 billion and $1.5 billion, respectively, from external PE investors, while another $750 million from Google Cloud flowed to systems integrators. The investment implication is that AI revenue realization depends on whether model companies can sell engineers, cloud resources, and customer workflows as one package.
"The FDE model has gone from a Palantir signature to an industry default."
Anthropic/OpenAI: Anthropic reportedly has a 41.0% share of paid enterprise AI customers in the U.S., above OpenAI’s 39.5%.
Google, xAI, and DeepSeek still have meaningfully lower shares. The model layer has not stopped expanding, but platforms are placing more emphasis on cost, distribution, and in-house control.
Claude access extensions, OpenAI and Anthropic fundraising, and Microsoft’s partial replacement of third-party models are all part of the same thread.
Zhipu/MiniMax: J.P. Morgan raised its December 2026 target price for Zhipu from HK$1,800 to HK$2,000 and maintained Overweight, arguing that after open weights expand distribution, the company can still monetize through official APIs, licensing, and workflow products.
MiniMax’s target price was cut from HK$400 to HK$300, with Neutral maintained, as revenue forecasts were lowered by 2%-8%. The debate centers on model capability, the premium for official services, and financing pressure.
"Open-weight commercialization is therefore becoming a winner-takes-more framework."
Microsoft: Microsoft has begun using its in-house MAI models in some Excel and Outlook features, processing a large volume of prompts weekly and replacing part of the workload previously handled by OpenAI and Anthropic.
J.P. Morgan downgraded Microsoft to Underweight, forecasting calendar-2026 capex of about $190 billion, further increases in 2027, and about $9 billion of refinancing needs in fiscal 2027. From an investment perspective, model internalization can reduce costs, but cloud capex will pressure cash flow first.
CSP/Cloud Capex
Capex of the Three Major Cloud Providers: BofA raised its capex forecasts for Google, Meta, and Amazon over the next three years.
Combined capex for the three companies is expected to reach $705 billion in 2027.
Combined capex is forecast to rise further to $816 billion in 2028.
Market estimates show hyperscaler capex totaling about $700 billion in 2026. Demand forecasts are still being revised upward, but the market is starting to ask whether these expenditures will be funded by debt, equity, or free cash flow.
"Collective capex between the three CSPs alone now estimated at $705 billion in 2027 and $816 billion in 2028 per BofA."
Amazon: Amazon plans to issue at least $25 billion of bonds to fund AI infrastructure expansion.
Its 2026 capex may exceed $200 billion.
Andy Jassy said the $364 billion backlog does not include another Anthropic commitment of more than $100 billion. Debt financing shifts the AI demand story from orders into credit markets, with interest costs and data center ramp timing the next variables to watch.
Meta: Meta released Muse Image and launched it in the Meta AI app, replacing third-party models with its own proprietary image technology.
The market is more focused on compute-asset leasing: Morgan Stanley estimates that if Meta subleases 250MW of contracted neocloud capacity at $40 per watt, it could add about $3 of EPS upside in 2028.
If expanded to 1,000MW, that would imply about $12 of incremental EPS.
Google: Google’s standalone capex pace is described as $350 billion, above the combined $256 billion capex of a group of companies in 2024.
J.P. Morgan maintained Overweight on Google, citing among other reasons an $85 billion equity issuance that eases debt-financing pressure. Cloud capex remains a source of orders for the AI chain, but financial structure has already become a valuation variable.
AI Cloud/Data Center Operators
CoreWeave: CoreWeave’s backlog reached $99.4 billion.
This is up sharply from $25.9 billion a year earlier.
First-quarter 2026 revenue was $2.1 billion, up 112% year on year, with an adjusted EBITDA margin of 56%.
Announced deals in 2026 total $63.9 billion, with customers including OpenAI, Meta, Microsoft, Nvidia, Anthropic, and Jane Street.
The question is no longer whether demand exists, but whether cost of capital, GPU depreciation, and customer concentration can match it.
Nebius: Nebius’s first-quarter 2026 AI cloud revenue grew 841% year on year, with an adjusted EBITDA margin of 45%.
The company guided for ARR of $7 billion to $9 billion by year-end 2026.
The company acquired Eigen AI for about $640 million.
Eigen AI’s quantization technology can compress a model that previously required four GPUs to run on two.
It can also double the speed of a model running on one card. Competition among new clouds is shifting from “how many cards can you buy” to “how many tokens can each card produce.”
"The neocloud contest is not about the number of GPUs, but the number of tokens generated by each GPU."
IREN/TeraWulf: IREN’s 200MW Childress Horizon 1 is expected to come online by the end of July. AI revenue could accelerate in the second half of 2026, with clear sequential growth expected in the third quarter.
Lease payments for TeraWulf’s 401MW Anthropic Kentucky project may require investment-grade credit support from Nvidia, Amazon, or Google. After the company sold its Abernathy stake, the market became concerned about financing and execution timing.
GPU/CPU/ASIC
Nvidia: Nvidia’s share price rose 0.73% against the broader trend, but market focus shifted to the engineering difficulty of Kyber/Rubin Ultra racks.
Kyber plans include NVL72, NVL144, and NVL576.
NVL144 has 144 GPUs in a single rack, with power entering the 600kW class.
The midplane has about 78 layers and is close to 1 square meter.
Perplexity adopted Nvidia’s Vera CPU for AI infrastructure; Nvidia expects Vera CPU sales to exceed $20 billion this fiscal year. CPU, GPU, interconnect, and full rack systems are becoming a single order.
"The AI chip race is no longer just about GPUs."
AMD: Advanced Micro Devices fell 6.51%, but the MI500 superPOD still targets 256 GPUs in a single scale-up domain, using two 128-GPU racks plus an intermediate switch rack, with launch targeted for 2027.
MI500 is also betting on CPO. The risks are more about system integration and software maturity than optics itself. AMD’s validation point is not single-card performance, but whether it can deliver racks, interconnect, and software together in 2027.
Broadcom/Apple ASIC: Broadcom and Apple’s custom ASIC supply has been extended to 2031. Apple accounts for about 20% of Broadcom’s revenue, and the Baltra project reinforces the importance of external ASIC design services.
Chip collaboration threads between OpenAI and Broadcom, Anthropic and Samsung Electronics, and DeepSeek and Chinese suppliers show that AI companies’ in-house ASIC efforts will not disappear; however, the economics still depend on model margins and deployment scale.
Intel: Intel fell 9.65%, with the market becoming more selective on the North American IDM and Intel Foundry narrative.
Patent information shows Intel’s new XBM memory architecture patent, which attempts to bypass HBM’s expensive silicon interposer by using UCIe links and built-in repair to ease AI memory bottlenecks. Without clear customers and a production timeline, this remains a technology option, not revenue realization.
HBM/DRAM/NAND/SSD/HDD
Samsung Electronics: Samsung Electronics’ preliminary second-quarter 2026 revenue was KRW 171 trillion.
Up 129.3% year on year and about 28% quarter on quarter.
Operating profit was KRW 89.4 trillion, up about 1,810% year on year and 56% quarter on quarter, but the share price still closed down about 7%.
Mirae Asset maintained Buy with a target price of KRW 550,000.
It estimates DRAM operating margin at 82% and NAND at 69.5%.
It expects third-quarter 2026 revenue of KRW 201 trillion and operating profit of KRW 120 trillion. The market is trading the idea that “the rate of change peaks after blowout earnings.”
SK Hynix: SK Hynix is described as the HBM leader.
Its shares are 56.4% in HBM, 29% in DRAM, and 18.5% in NAND.
First-quarter 2026 revenue rose 198% year on year, operating profit rose 405%, and margin was 72%.
Its U.S. listing size is about $28.0 billion-$29.4 billion, with some cornerstone investors interested in buying up to $7 billion.
Funds will mainly be used for AI memory fabs and EUV equipment. The near-term decline reflects a crowded trade, not the disappearance of HBM orders.
Micron/SanDisk/Western Digital/Seagate Technology: The memory chain saw a concentrated pullback. Among the top 10 by turnover, Micron fell 6.22%, SanDisk fell 8.09%, and Western Digital fell 8.32%.
Bernstein said about 35% of memory bits, or about 160 billion GB, in fiscal 2027-2029 have been locked in by long-term agreements.
The floor price is $0.26/GB, only 10% below the June-quarter 2026 spot ASP of $0.29. The market is selling the cycle in the short term, while long-term contracts are lifting the floor.
Memory Prices: Jefferies expects memory prices to rise 40%-50% quarter on quarter in the third quarter of 2026.
Another 30%-40% increase in the fourth quarter.
A further 40%-45% year-on-year increase in 2027.
Bernstein expects DRAM ASP to approach $2.23/GB by the end of 2027.
ADATA said third-quarter DRAM contract prices may rise 20%-30%.
NAND contract prices may rise 35%-40%. If downstream end devices cannot fully pass this through, upstream memory profits will squeeze smartphone, PC, and server BOMs.
Foundry, Equipment, and Advanced Packaging
TSMC: TSMC’s moat is being reinterpreted as its EDA/IP ecosystem, not just PPA, EUV, or yield. Its certified Silicon IP library grew from 3,000 items in 2010 to 93,000 in 2025, a 31-fold increase.
Pre-verified SerDes, HBM, PCIe, UCIe, memory, and chiplet interface blocks reduce tape-out risk and also raise the migration cost for flagship ASICs moving to Samsung Electronics or Intel Foundry.
"TSMC’s moat is bigger than PPA, EUV, or yield."
Semiconductor Equipment/WFE: Every additional $100 billion of AI data center investment translates into about $8 billion of WFE spending.
Ex-China WFE is expected to rise 36%/33% in 2026/2027.
Memory WFE is expected to rise 48%/26%.
Assumptions related to SpaceX’s Terafab are more aggressive.
AI-related investment could exceed $1.1 trillion over the next five years.
About $225 billion of that would go into semiconductor capex.
This corresponds to more than $135 billion of WFE demand. The risk for the equipment chain is that valuation leads first, while order realization depends on actual capacity buildout.
ASE Technology Holding/Advanced Packaging Equipment: ASE Technology’s target price was raised to NT$805.
LEAP revenue is expected to be $3.6 billion/$6.4 billion in 2026/2027.
PSK Holdings has a target price of KRW 220,000 and a Buy rating. Its Fluxless Reflow market share exceeds 90%, driven by both CoWoS and HBM TSV. Advanced packaging remains the capacity valve for AI chip volume growth.
Optical Communications/High-Speed Interconnect/Power
Optical Communications Chain: InP is a key material for high-speed optical communications in AI data centers. Global effective capacity is about 600,000-750,000 wafers.
Corresponding demand is about 2.6 million-3.0 million wafers.
The price of 2-inch InP substrates rose from about $800 per piece in 2025 to a higher range in April 2026.
The April price was $2,300-$2,500 per piece.
Sumitomo Electric raised its investment plan to JPY 18 billion, targeting 3.1x capacity by 2028.
"When we move to 400G, we can no longer fully connect a rack with copper."
Marvell Technology/Copper Wall: Marvell Technology’s CEO emphasized at COMPUTEX 2026 that every doubling of bandwidth halves the transmission distance of copper cables; after moving to 400G, copper can no longer fully connect a rack.
Each time the “copper wall” moves one step, the number of connections increases by at least one order of magnitude, requiring large-scale expansion of the optical communications supply chain. The investment implication is that optical modules, lasers, CPO, silicon photonics, and fiber cables will benefit from cluster scale rather than single-port speed.
Lumentum/Coherent/Furukawa: Needham estimates that pump-laser manufacturing volumes will reach 4x over the next one to two years, with demand expanding from subsea cable amplifiers to DCI.
High-quality pump lasers are mainly controlled by Lumentum, Coherent, Furukawa, and 3SP/O-Cloudflare. Even when the material is GaAs, power and reliability requirements still make scaled production difficult.
Power/BBU/800VDC: UBS raised its global Data Center Equipment growth forecasts to +25% in 2026 and +20% in 2027.
Hyperscaler capex is expected to exceed $1 trillion by 2027.
Citi initiated coverage of Simplo with Buy and a target price of NT$800.
BBU content value rises from about $15,000-$16,000 per GB300 cabinet.
It can exceed $33,000 for Rubin Ultra.
BBU penetration is expected to exceed 85% in 2027.
MLCC/Passive Components, Power Semiconductors, and Server Chain
Yageo/MLCC: On July 7, foreign investors net bought 7,286 lots of Yageo, while the three major institutional investor groups net bought 4,611 lots combined.
The share price closed at NT$905, giving back more than 20% from its intrawweek high.
Another report said Yageo’s general-purpose MLCC price-hike cycle has arrived, with more capacity shifting to the AI industry, and gave a new target price of NT$1,490. In trading terms, the short-term move has cooled; at the industry level, AI server MLCCs are still seeing price increases and capacity migration.
Samsung Electro-Mechanics/Murata/TDK: Samsung Electro-Mechanics’ report focuses on strong ASP growth for AI MLCCs in 2027, FC-BGA shortages, and new demand for silicon capacitors; TDK is maintained at Buy, with AI server-related sales growth viewed as a potential catalyst.
Murata was upgraded to Buy, with the core thesis that AI servers will accelerate MLCC profit growth. The business issue for passive components is straightforward: the higher the power per rack, the more on-board capacitors and high-reliability power-management components are needed.
onsemi/Power Semiconductors: onsemi signed agreements to sell its Tarlac facility in the Philippines and Mountain Top facility in Pennsylvania, part of its Fab Right strategy.
The company expects to save about $35 million annually starting in 2027, with full realization in 2028. Power semiconductors are not currently the hottest part of the AI chain, but asset-light capacity helps defend margins.
Penguin Solutions: Fiscal 3Q26 net sales were $478.7 million, up 48% YoY.
Non-GAAP EPS was $0.84, above expectations of $0.56.
Integrated Memory revenue was $275.1 million, up 111% YoY.
Full-year net sales growth guidance was raised from 12%±5% to 22%±2%.
Non-GAAP EPS guidance was raised to $2.60. In the AI infrastructure chain, companies delivering actual results are starting to look more convincing than narrative-driven companies.
Space/Satellites and Robotics/Autonomous Driving
SpaceX/Starlink: Goldman Sachs initiated coverage of SpaceX at Buy, with a 12-month price target of $205.
Citi initiated coverage at Buy, with a base-case price target of $200 and a long-term bull-case framework pointing above $900.
SpaceX applied for a third-generation constellation of 100,000 ultra-low-Earth-orbit satellites.
Orbital altitudes are 323-327.5 km and 473-477.5 km. The space AI narrative is large, but it needs to be validated step by step through high-frequency Starship launches, regulatory approvals, satellite deployment, and financing capacity.
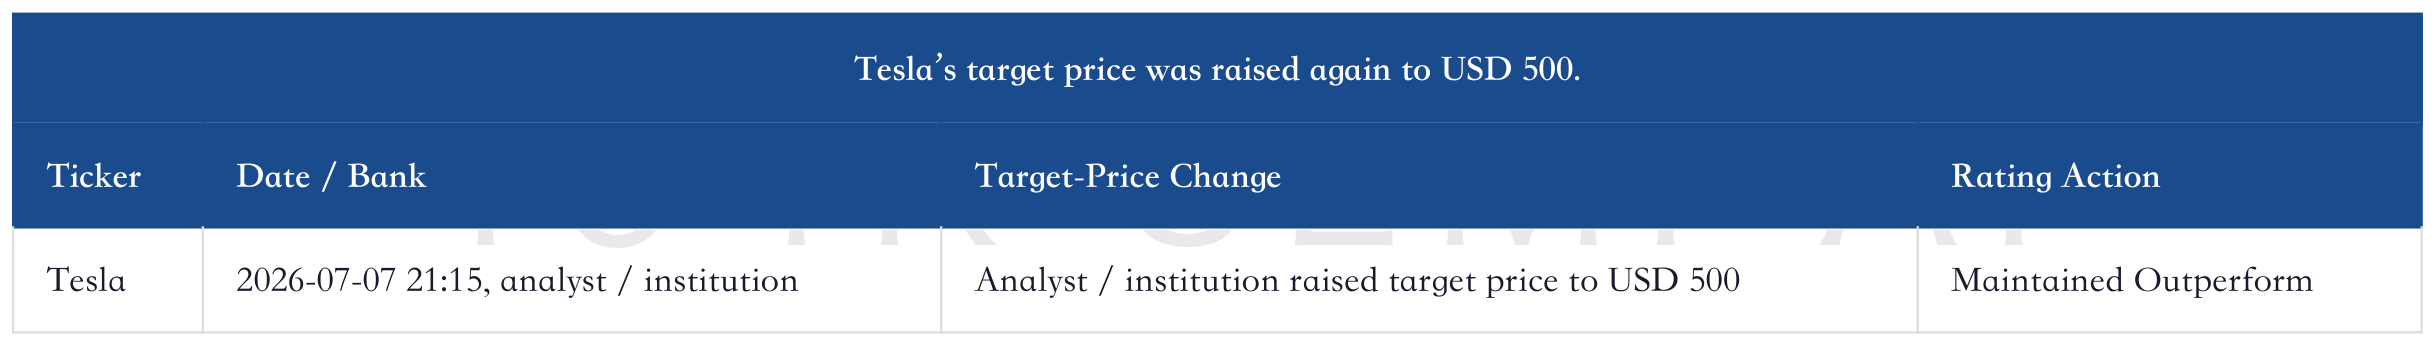
Tesla Robotaxi/Cybercab: RBC raised its Tesla price target from $475 to $500 and maintained Outperform, based on a potential SpaceX acquisition scenario.
Tesla said Cybercab will serve as the main Robotaxi model, removing the steering wheel, pedals, and traditional controls, with efficiency of at least 6.1 miles per kWh.
The RIM process reduces the traditional paint cycle from several hours to several minutes and cuts greenhouse-gas emissions from related components by 35%.
Internet/Platforms
Meta: Meta shares rose 2.30%, with Muse Image acting as a short-term catalyst, but the larger investment question is whether compute assets can become a new revenue line.
Reportedly, Meta is still advancing expensive new data-center plans and has signed major compute deals with CoreWeave, Google, Oracle, and others. If Meta leases out older GPU capacity, this looks more like compute tiering than a cooling of AI demand.
"Meta leases out just 250MW... $3 in EPS upside."
Amazon: Amazon shares rose 0.62%, but the real incremental information is bond financing and backlog.
The company plans to issue at least $25 billion of bonds, with AI infrastructure capex expected to exceed $200 billion.
The $364 billion backlog excludes more than $100 billion of Anthropic commitments, indicating that signed demand is still expanding. The follow-up risks are debt costs, data-center delivery, and AWS margins.
Google: Google shares rose 0.16%, and the capex path continues to move higher.
Market estimates suggest the company’s spending pace could reach $350 billion, above the combined $256 billion spent by a group of companies in 2024.
Google also invested in Proxima Fusion, indicating that long-term power supply for data centers has entered the strategic investment scope. The investment implication is that search and advertising are not today’s main line; cloud and energy are the core of AI pricing.
Shopify/Figma: BofA initiated coverage of Figma at Buy with a $30 price target, arguing that AI is more likely to be a tailwind than a headwind, with valuation based on 8x expected 2027 EV/Sales.
BofA resumed coverage of Shopify at Buy with a $150 price target, citing its checkout, payments, and back-end infrastructure as a potential core foundation for AI agent commerce.
Uber/DoorDash/Pinterest: On the gainers list, DoorDash rose 3.70%, Uber rose 1.92%, and Pinterest rose 1.89%, but there were no new earnings, order, or rating actions that directly mapped to the moves.
The common implication for these platform stocks is that when capital pulls back from high-beta semiconductors, it looks for platform assets with clearer cash flow and lighter AI capex burdens.
Software/SaaS
Cloudflare: Cloudflare rose 8.21%, topping the gainers list. Within software, it is more like a cross-over asset across edge cloud, cybersecurity, and AI traffic distribution.
J.P. Morgan’s China AI report places Cloudflare, OpenRouter, Fireworks AI, and others into the model distribution chain, suggesting that after models become open source, the real monetization may sit in routing, caching, inference platforms, and developer entry points.
DigitalOcean: DigitalOcean expects a record 2Q26, with RPO above $800 million and up more than 10x YoY.
New RPO added in 2Q exceeded $550 million.
RPO duration rose from 1.6 years to more than 3 years, and revenue growth was about 29%.
The company added 20MW of data-center capacity to roughly 155MW. If smaller cloud vendors can secure long-term AI workload contracts, their valuation framework can shift from ordinary cloud hosting toward AI infrastructure.
"DOCN... revenue growth accelerated to 29%, above consensus 25%."
Palantir: Palantir’s FDE model is moving from a company-specific feature to the default industry playbook, with five AI companies spending $9.75 billion over 12 months on forward-deployed engineering.
The company also announced that Mexico’s GNP Seguros expanded its enterprise agreement, using Foundry and AIP across health, life, auto, and property-casualty insurance, covering claims fraud detection, risk monitoring, and underwriting.
ServiceNow/Salesforce/MongoDB/Datadog: ServiceNow rose 1.34%, Salesforce rose 1.88%, and MongoDB and Datadog were included in the software rotation as part of the AI application foundation and observability chain.
Market performance shows that when semiconductors fall, software sees clearer fund inflows; but software stocks still need to prove that AI features can drive seats, usage, or net retention.
Adobe/Figma: Adobe was initiated at Underperform with a $190 price target, while Figma was initiated at Buy with a $30 price target.
This comparison shows that generative AI is competitive pressure for legacy creative tools, while it may be a new usage entry point for collaborative design platforms. From an investment perspective, the focus should be hybrid monetization, usage-based pricing, and enterprise adoption, not just “AI feature launches.”
Samsara: Samsara Agent Studio is based on 25 trillion real-world data points captured in 2025 and includes more than 15 prebuilt safety and maintenance templates.
Samsara Network covers 99% of major U.S. roads and tens of thousands of work sites. Its AI value is not in chat, but in closing real operational loops across fleets, job sites, and equipment maintenance.
Consumer Electronics / Smart Vehicles
Apple / Edge AI Watches: In Q1 2026, global shipments of smartwatches supporting Edge AI rose 70% YoY. Edge AI now accounts for 25% of smartwatch shipments, with Apple’s share close to 90%.
Health and fitness monitoring is the main driver. Low-power neural accelerators make on-device processing feasible without sacrificing battery life. Apple’s advantage lies in its closed loop across hardware, chips, algorithms, and health data.
BOE A: Citi downgraded BOE A from Buy to Neutral, but raised its target price from RMB 5.0 to RMB 8.7, arguing that LCD improvement and glass-substrate expectations are already fairly reflected in valuation.
On glass substrates, the company completed mainland China’s first pilot line in 2024 and delivered second-generation samples in 2025. However, a mass-production investment decision is not expected to be clarified until mid-2027, and meaningful net-profit contribution is unlikely before 2029.
Tesla: Over the past six weeks, Tesla has announced more than USD 9 billion of Megapack projects.
These projects total more than 43GWh and can support 5.9 million households.
The order from Esyasoft is worth up to USD 3 billion and exceeds 15GWh, covering the UK, Western Europe, the GCC, and India.
The energy-storage business is evolving from an appendage to auto valuation into part of the power chain for grids and data centers.
Tesla Cybercab: 1) Cybercab is designed as a compact two-seater because more than 85% of ride-hailing trips carry one to two passengers.
The RIM process compresses manufacturing cycle time from several hours to several minutes and eliminates VOC emissions. The validation points for Robotaxi are not slogans, but per-vehicle cost, energy consumption, regulation, and fleet utilization.
Humanoid Robots / Industrial Automation: Morgan Stanley expects the humanoid robot market to reach approximately USD 7.5 trillion by 2050.
Industry commercial revenue is approximately USD 3 billion in 2025.
Cost is expected to fall from approximately USD 200,000 in 2024 to USD 150,000 in 2028.
In high-income countries, cost is expected to be around USD 50,000 by 2050.
In regions dominated by China’s supply chain, cost could be as low as USD 15,000.
The more certain near-term beneficiaries are edge-computing chips, bearings, motors, and precision reducers.
Japan Factory Automation: Morgan Stanley MUFG is positive on Japan’s FA industry and expects WFE to grow 31% YoY in 2026 and 28% YoY in 2027.
Keyence is rated Overweight with a JPY 95,000 target price, while FANUC and SMC are rated Equal-weight. AI capex is transmitting into fab automation, but profit elasticity varies by company depending on product mix and fixed costs.
Investment-Bank Target-Price Changes Over the Past 12 Hours
Lao Huang’s Selected Portfolio
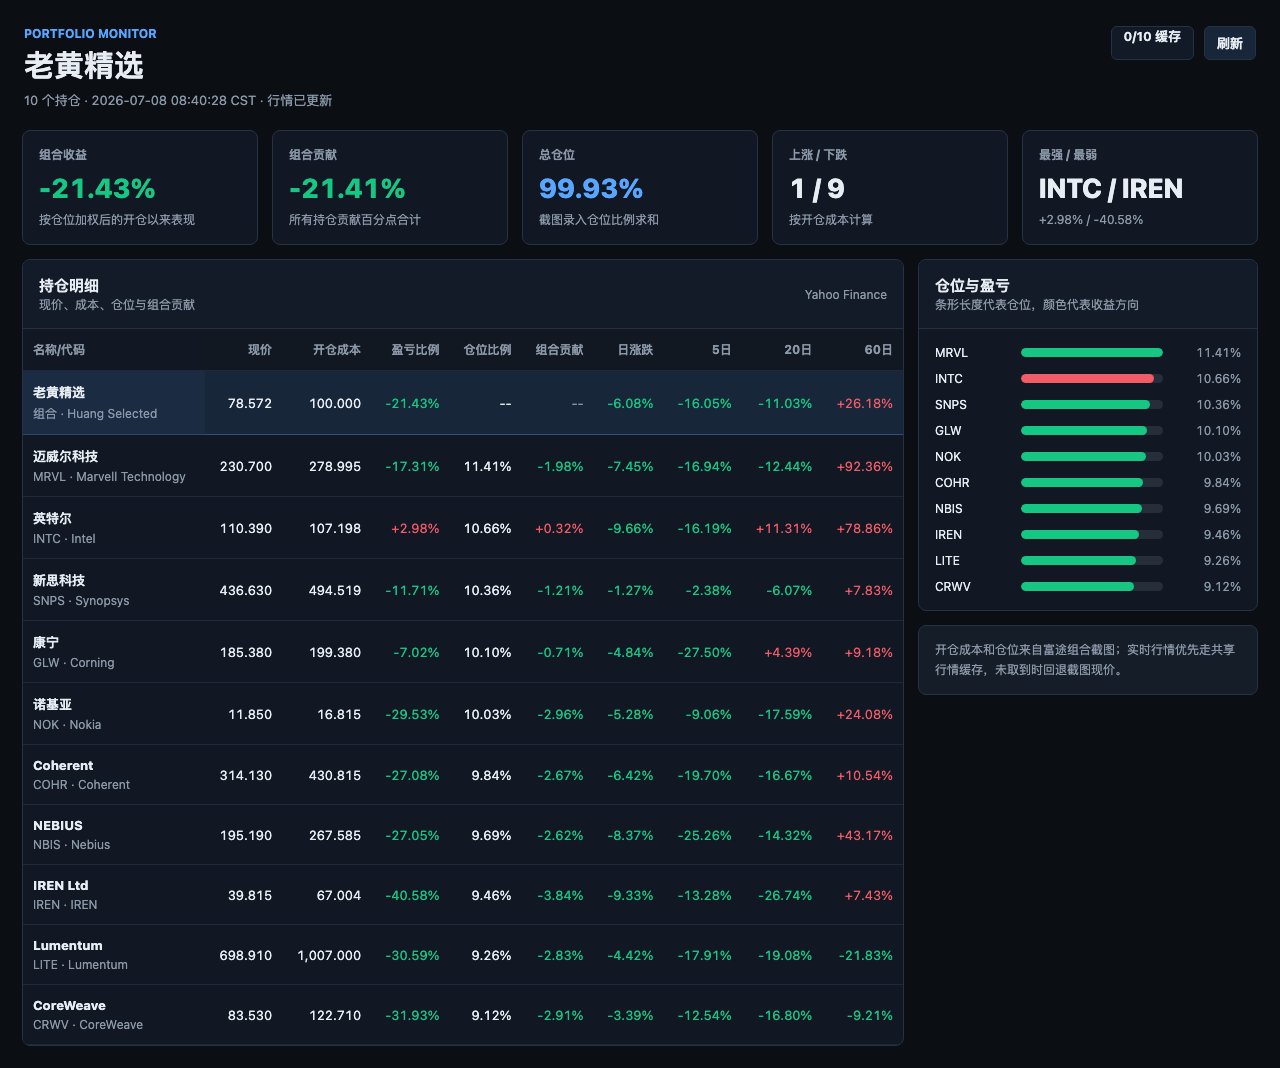
Lao Huang’s Selected Portfolio
404K SEMI-AI Tech Morning Brief 2026-07-08 — Semis Cool, Memory Monetizes, AI Capex Keeps Spilling Over
目录
After-Hours Summary
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models/Applications and Capex
CSP/Cloud Capex
AI Cloud/Data Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry, Equipment, and Advanced Packaging
Optical Communications/High-Speed Interconnect/Power
MLCC/Passive Components, Power Semiconductors, and Server Chain
Space/Satellites and Robotics/Autonomous Driving
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Investment-Bank Target-Price Changes Over the Past 12 Hours
Lao Huang’s Selected Portfolio
Lao Huang’s Selected Portfolio
U.S. tech stocks diverged sharply after hours. Semiconductors and high-beta AI infrastructure names remained under pressure, but cloud capex, long-term memory contracts, AI cloud orders, power, and optical interconnects continue to provide hard support for the supply chain. The most important shift today: the market is moving from “only watching GPU and HBM shortages” toward validating cash flow, financing capacity, data-center power, and optical communications supply.
After-Hours Summary
The U.S. tech complex saw a clear de-crowding. The S&P; 500 fell 0.51%, the Nasdaq 100 fell 1.82%, and the tech ETF fell 2.39%.
The semiconductor ETF fell 3.69%, while the equal-weight semiconductor reference fell 5.13%. This was not a single negative catalyst, but a collective deleveraging across the strongest prior winners: memory, semiconductor equipment, interconnects, AI cloud, and small-cap compute names.
By style, software and cloud computing were relatively resilient. The cloud computing ETF rose 1.05%, the software ETF fell 0.70%, and communication services rose 0.73%.
Semiconductors, robotics and AI, and AI and big data fell 3.69%, 4.34%, and 2.76%, respectively. The market is not rejecting AI capex, but it is starting to require every layer of the chain to prove orders, cash flow, and funding sources.
At the single-stock level, NVIDIA, Meta, Amazon, and Microsoft remained relatively resilient; Intel, AMD, Micron, Western Digital, SanDisk, and the semiconductor equipment chain fell more sharply. The AI trade has entered its next phase: upstream demand remains intact, but equities are first digesting “peak rate of change” and financing pressure.
Top 10 U.S. Stocks by Trading Value
The most heavily traded names remained concentrated in memory, AI infrastructure, and large-cap tech.
Top U.S. Stock Gainers
The gainers list shows software, platforms, and defensive tech assets were relatively resilient.
Top U.S. Stock Decliners
The decliners list was concentrated in interconnects, power, equipment, and the memory chain.
Full AI/Semiconductor Value Chain
AI Models/Applications and Capex
AI Application Deployment: The bottleneck in enterprise AI is shifting from model capability to deployment engineering. Over the next 12 months, five AI companies have committed $9.75 billion to front-end deployment engineering.
OpenAI and Anthropic raised $4.0 billion and $1.5 billion, respectively, from external PE investors, while another $750 million from Google Cloud flowed to systems integrators. The investment implication is that AI revenue realization depends on whether model companies can sell engineers, cloud resources, and customer workflows as one package.
“The FDE model has gone from a Palantir signature to an industry default.”
Anthropic/OpenAI: Anthropic reportedly has a 41.0% share of paid enterprise AI customers in the U.S., above OpenAI’s 39.5%.
Google, xAI, and DeepSeek still have meaningfully lower shares. The model layer has not stopped expanding, but platforms are placing more emphasis on cost, distribution, and in-house control.
Claude access extensions, OpenAI and Anthropic fundraising, and Microsoft’s partial replacement of third-party models are all part of the same thread.
Zhipu/MiniMax: J.P. Morgan raised its December 2026 target price for Zhipu from HK$1,800 to HK$2,000 and maintained Overweight, arguing that after open weights expand distribution, the company can still monetize through official APIs, licensing, and workflow products.
MiniMax’s target price was cut from HK$400 to HK$300, with Neutral maintained, as revenue forecasts were lowered by 2%-8%. The debate centers on model capability, the premium for official services, and financing pressure.
“Open-weight commercialization is therefore becoming a winner-takes-more framework.”
Microsoft: Microsoft has begun using its in-house MAI models in some Excel and Outlook features, processing a large volume of prompts weekly and replacing part of the workload previously handled by OpenAI and Anthropic.
J.P. Morgan downgraded Microsoft to Underweight, forecasting calendar-2026 capex of about $190 billion, further increases in 2027, and about $9 billion of refinancing needs in fiscal 2027. From an investment perspective, model internalization can reduce costs, but cloud capex will pressure cash flow first.
CSP/Cloud Capex
Capex of the Three Major Cloud Providers: BofA raised its capex forecasts for Google, Meta, and Amazon over the next three years.
Combined capex for the three companies is expected to reach $705 billion in 2027.
Combined capex is forecast to rise further to $816 billion in 2028.
Market estimates show hyperscaler capex totaling about $700 billion in 2026. Demand forecasts are still being revised upward, but the market is starting to ask whether these expenditures will be funded by debt, equity, or free cash flow.
“Collective capex between the three CSPs alone now estimated at $705 billion in 2027 and $816 billion in 2028 per BofA.”
Amazon: Amazon plans to issue at least $25 billion of bonds to fund AI infrastructure expansion.
Its 2026 capex may exceed $200 billion.
Andy Jassy said the $364 billion backlog does not include another Anthropic commitment of more than $100 billion. Debt financing shifts the AI demand story from orders into credit markets, with interest costs and data center ramp timing the next variables to watch.
Meta: Meta released Muse Image and launched it in the Meta AI app, replacing third-party models with its own proprietary image technology.
The market is more focused on compute-asset leasing: Morgan Stanley estimates that if Meta subleases 250MW of contracted neocloud capacity at $40 per watt, it could add about $3 of EPS upside in 2028.
If expanded to 1,000MW, that would imply about $12 of incremental EPS.
Google: Google’s standalone capex pace is described as $350 billion, above the combined $256 billion capex of a group of companies in 2024.
J.P. Morgan maintained Overweight on Google, citing among other reasons an $85 billion equity issuance that eases debt-financing pressure. Cloud capex remains a source of orders for the AI chain, but financial structure has already become a valuation variable.
AI Cloud/Data Center Operators
CoreWeave: CoreWeave’s backlog reached $99.4 billion.
This is up sharply from $25.9 billion a year earlier.
First-quarter 2026 revenue was $2.1 billion, up 112% year on year, with an adjusted EBITDA margin of 56%.
Announced deals in 2026 total $63.9 billion, with customers including OpenAI, Meta, Microsoft, Nvidia, Anthropic, and Jane Street.
The question is no longer whether demand exists, but whether cost of capital, GPU depreciation, and customer concentration can match it.
Nebius: Nebius’s first-quarter 2026 AI cloud revenue grew 841% year on year, with an adjusted EBITDA margin of 45%.
The company guided for ARR of $7 billion to $9 billion by year-end 2026.
The company acquired Eigen AI for about $640 million.
Eigen AI’s quantization technology can compress a model that previously required four GPUs to run on two.
It can also double the speed of a model running on one card. Competition among new clouds is shifting from “how many cards can you buy” to “how many tokens can each card produce.”
“The neocloud contest is not about the number of GPUs, but the number of tokens generated by each GPU.”
IREN/TeraWulf: IREN’s 200MW Childress Horizon 1 is expected to come online by the end of July. AI revenue could accelerate in the second half of 2026, with clear sequential growth expected in the third quarter.
Lease payments for TeraWulf’s 401MW Anthropic Kentucky project may require investment-grade credit support from Nvidia, Amazon, or Google. After the company sold its Abernathy stake, the market became concerned about financing and execution timing.
GPU/CPU/ASIC
Nvidia: Nvidia’s share price rose 0.73% against the broader trend, but market focus shifted to the engineering difficulty of Kyber/Rubin Ultra racks.
Kyber plans include NVL72, NVL144, and NVL576.
NVL144 has 144 GPUs in a single rack, with power entering the 600kW class.
The midplane has about 78 layers and is close to 1 square meter.
Perplexity adopted Nvidia’s Vera CPU for AI infrastructure; Nvidia expects Vera CPU sales to exceed $20 billion this fiscal year. CPU, GPU, interconnect, and full rack systems are becoming a single order.
“The AI chip race is no longer just about GPUs.”
AMD: Advanced Micro Devices fell 6.51%, but the MI500 superPOD still targets 256 GPUs in a single scale-up domain, using two 128-GPU racks plus an intermediate switch rack, with launch targeted for 2027.
MI500 is also betting on CPO. The risks are more about system integration and software maturity than optics itself. AMD’s validation point is not single-card performance, but whether it can deliver racks, interconnect, and software together in 2027.
Broadcom/Apple ASIC: Broadcom and Apple’s custom ASIC supply has been extended to 2031. Apple accounts for about 20% of Broadcom’s revenue, and the Baltra project reinforces the importance of external ASIC design services.
Chip collaboration threads between OpenAI and Broadcom, Anthropic and Samsung Electronics, and DeepSeek and Chinese suppliers show that AI companies’ in-house ASIC efforts will not disappear; however, the economics still depend on model margins and deployment scale.
Intel: Intel fell 9.65%, with the market becoming more selective on the North American IDM and Intel Foundry narrative.
Patent information shows Intel’s new XBM memory architecture patent, which attempts to bypass HBM’s expensive silicon interposer by using UCIe links and built-in repair to ease AI memory bottlenecks. Without clear customers and a production timeline, this remains a technology option, not revenue realization.
HBM/DRAM/NAND/SSD/HDD
Samsung Electronics: Samsung Electronics’ preliminary second-quarter 2026 revenue was KRW 171 trillion.
Up 129.3% year on year and about 28% quarter on quarter.
Operating profit was KRW 89.4 trillion, up about 1,810% year on year and 56% quarter on quarter, but the share price still closed down about 7%.
Mirae Asset maintained Buy with a target price of KRW 550,000.
It estimates DRAM operating margin at 82% and NAND at 69.5%.
It expects third-quarter 2026 revenue of KRW 201 trillion and operating profit of KRW 120 trillion. The market is trading the idea that “the rate of change peaks after blowout earnings.”
SK Hynix: SK Hynix is described as the HBM leader.
Its shares are 56.4% in HBM, 29% in DRAM, and 18.5% in NAND.
First-quarter 2026 revenue rose 198% year on year, operating profit rose 405%, and margin was 72%.
Its U.S. listing size is about $28.0 billion-$29.4 billion, with some cornerstone investors interested in buying up to $7 billion.
Funds will mainly be used for AI memory fabs and EUV equipment. The near-term decline reflects a crowded trade, not the disappearance of HBM orders.
Micron/SanDisk/Western Digital/Seagate Technology: The memory chain saw a concentrated pullback. Among the top 10 by turnover, Micron fell 6.22%, SanDisk fell 8.09%, and Western Digital fell 8.32%.
Bernstein said about 35% of memory bits, or about 160 billion GB, in fiscal 2027-2029 have been locked in by long-term agreements.
The floor price is $0.26/GB, only 10% below the June-quarter 2026 spot ASP of $0.29. The market is selling the cycle in the short term, while long-term contracts are lifting the floor.
Memory Prices: Jefferies expects memory prices to rise 40%-50% quarter on quarter in the third quarter of 2026.
Another 30%-40% increase in the fourth quarter.
A further 40%-45% year-on-year increase in 2027.
Bernstein expects DRAM ASP to approach $2.23/GB by the end of 2027.
ADATA said third-quarter DRAM contract prices may rise 20%-30%.
NAND contract prices may rise 35%-40%. If downstream end devices cannot fully pass this through, upstream memory profits will squeeze smartphone, PC, and server BOMs.
Foundry, Equipment, and Advanced Packaging
TSMC: TSMC’s moat is being reinterpreted as its EDA/IP ecosystem, not just PPA, EUV, or yield. Its certified Silicon IP library grew from 3,000 items in 2010 to 93,000 in 2025, a 31-fold increase.
Pre-verified SerDes, HBM, PCIe, UCIe, memory, and chiplet interface blocks reduce tape-out risk and also raise the migration cost for flagship ASICs moving to Samsung Electronics or Intel Foundry.
“TSMC’s moat is bigger than PPA, EUV, or yield.”
Semiconductor Equipment/WFE: Every additional $100 billion of AI data center investment translates into about $8 billion of WFE spending.
Ex-China WFE is expected to rise 36%/33% in 2026/2027.
Memory WFE is expected to rise 48%/26%.
Assumptions related to SpaceX’s Terafab are more aggressive.
AI-related investment could exceed $1.1 trillion over the next five years.
About $225 billion of that would go into semiconductor capex.
This corresponds to more than $135 billion of WFE demand. The risk for the equipment chain is that valuation leads first, while order realization depends on actual capacity buildout.
ASE Technology Holding/Advanced Packaging Equipment: ASE Technology’s target price was raised to NT$805.
LEAP revenue is expected to be $3.6 billion/$6.4 billion in 2026/2027.
PSK Holdings has a target price of KRW 220,000 and a Buy rating. Its Fluxless Reflow market share exceeds 90%, driven by both CoWoS and HBM TSV. Advanced packaging remains the capacity valve for AI chip volume growth.
Optical Communications/High-Speed Interconnect/Power
Optical Communications Chain: InP is a key material for high-speed optical communications in AI data centers. Global effective capacity is about 600,000-750,000 wafers.
Corresponding demand is about 2.6 million-3.0 million wafers.
The price of 2-inch InP substrates rose from about $800 per piece in 2025 to a higher range in April 2026.
The April price was $2,300-$2,500 per piece.
Sumitomo Electric raised its investment plan to JPY 18 billion, targeting 3.1x capacity by 2028.
“When we move to 400G, we can no longer fully connect a rack with copper.”
Marvell Technology/Copper Wall: Marvell Technology’s CEO emphasized at COMPUTEX 2026 that every doubling of bandwidth halves the transmission distance of copper cables; after moving to 400G, copper can no longer fully connect a rack.
Each time the “copper wall” moves one step, the number of connections increases by at least one order of magnitude, requiring large-scale expansion of the optical communications supply chain. The investment implication is that optical modules, lasers, CPO, silicon photonics, and fiber cables will benefit from cluster scale rather than single-port speed.
Lumentum/Coherent/Furukawa: Needham estimates that pump-laser manufacturing volumes will reach 4x over the next one to two years, with demand expanding from subsea cable amplifiers to DCI.
High-quality pump lasers are mainly controlled by Lumentum, Coherent, Furukawa, and 3SP/O-Cloudflare. Even when the material is GaAs, power and reliability requirements still make scaled production difficult.
Power/BBU/800VDC: UBS raised its global Data Center Equipment growth forecasts to +25% in 2026 and +20% in 2027.
Hyperscaler capex is expected to exceed $1 trillion by 2027.
Citi initiated coverage of Simplo with Buy and a target price of NT$800.
BBU content value rises from about $15,000-$16,000 per GB300 cabinet.
It can exceed $33,000 for Rubin Ultra.
BBU penetration is expected to exceed 85% in 2027.
MLCC/Passive Components, Power Semiconductors, and Server Chain
Yageo/MLCC: On July 7, foreign investors net bought 7,286 lots of Yageo, while the three major institutional investor groups net bought 4,611 lots combined.
The share price closed at NT$905, giving back more than 20% from its intrawweek high.
Another report said Yageo’s general-purpose MLCC price-hike cycle has arrived, with more capacity shifting to the AI industry, and gave a new target price of NT$1,490. In trading terms, the short-term move has cooled; at the industry level, AI server MLCCs are still seeing price increases and capacity migration.
Samsung Electro-Mechanics/Murata/TDK: Samsung Electro-Mechanics’ report focuses on strong ASP growth for AI MLCCs in 2027, FC-BGA shortages, and new demand for silicon capacitors; TDK is maintained at Buy, with AI server-related sales growth viewed as a potential catalyst.
Murata was upgraded to Buy, with the core thesis that AI servers will accelerate MLCC profit growth. The business issue for passive components is straightforward: the higher the power per rack, the more on-board capacitors and high-reliability power-management components are needed.
onsemi/Power Semiconductors: onsemi signed agreements to sell its Tarlac facility in the Philippines and Mountain Top facility in Pennsylvania, part of its Fab Right strategy.
The company expects to save about $35 million annually starting in 2027, with full realization in 2028. Power semiconductors are not currently the hottest part of the AI chain, but asset-light capacity helps defend margins.
Penguin Solutions: Fiscal 3Q26 net sales were $478.7 million, up 48% YoY.
Non-GAAP EPS was $0.84, above expectations of $0.56.
Integrated Memory revenue was $275.1 million, up 111% YoY.
Full-year net sales growth guidance was raised from 12%±5% to 22%±2%.
Non-GAAP EPS guidance was raised to $2.60. In the AI infrastructure chain, companies delivering actual results are starting to look more convincing than narrative-driven companies.
Space/Satellites and Robotics/Autonomous Driving
SpaceX/Starlink: Goldman Sachs initiated coverage of SpaceX at Buy, with a 12-month price target of $205.
Citi initiated coverage at Buy, with a base-case price target of $200 and a long-term bull-case framework pointing above $900.
SpaceX applied for a third-generation constellation of 100,000 ultra-low-Earth-orbit satellites.
Orbital altitudes are 323-327.5 km and 473-477.5 km. The space AI narrative is large, but it needs to be validated step by step through high-frequency Starship launches, regulatory approvals, satellite deployment, and financing capacity.
Tesla Robotaxi/Cybercab: RBC raised its Tesla price target from $475 to $500 and maintained Outperform, based on a potential SpaceX acquisition scenario.
Tesla said Cybercab will serve as the main Robotaxi model, removing the steering wheel, pedals, and traditional controls, with efficiency of at least 6.1 miles per kWh.
The RIM process reduces the traditional paint cycle from several hours to several minutes and cuts greenhouse-gas emissions from related components by 35%.
Internet/Platforms
Meta: Meta shares rose 2.30%, with Muse Image acting as a short-term catalyst, but the larger investment question is whether compute assets can become a new revenue line.
Reportedly, Meta is still advancing expensive new data-center plans and has signed major compute deals with CoreWeave, Google, Oracle, and others. If Meta leases out older GPU capacity, this looks more like compute tiering than a cooling of AI demand.
“Meta leases out just 250MW... $3 in EPS upside.”
Amazon: Amazon shares rose 0.62%, but the real incremental information is bond financing and backlog.
The company plans to issue at least $25 billion of bonds, with AI infrastructure capex expected to exceed $200 billion.
The $364 billion backlog excludes more than $100 billion of Anthropic commitments, indicating that signed demand is still expanding. The follow-up risks are debt costs, data-center delivery, and AWS margins.
Google: Google shares rose 0.16%, and the capex path continues to move higher.
Market estimates suggest the company’s spending pace could reach $350 billion, above the combined $256 billion spent by a group of companies in 2024.
Google also invested in Proxima Fusion, indicating that long-term power supply for data centers has entered the strategic investment scope. The investment implication is that search and advertising are not today’s main line; cloud and energy are the core of AI pricing.
Shopify/Figma: BofA initiated coverage of Figma at Buy with a $30 price target, arguing that AI is more likely to be a tailwind than a headwind, with valuation based on 8x expected 2027 EV/Sales.
BofA resumed coverage of Shopify at Buy with a $150 price target, citing its checkout, payments, and back-end infrastructure as a potential core foundation for AI agent commerce.
Uber/DoorDash/Pinterest: On the gainers list, DoorDash rose 3.70%, Uber rose 1.92%, and Pinterest rose 1.89%, but there were no new earnings, order, or rating actions that directly mapped to the moves.
The common implication for these platform stocks is that when capital pulls back from high-beta semiconductors, it looks for platform assets with clearer cash flow and lighter AI capex burdens.
Software/SaaS
Cloudflare: Cloudflare rose 8.21%, topping the gainers list. Within software, it is more like a cross-over asset across edge cloud, cybersecurity, and AI traffic distribution.
J.P. Morgan’s China AI report places Cloudflare, OpenRouter, Fireworks AI, and others into the model distribution chain, suggesting that after models become open source, the real monetization may sit in routing, caching, inference platforms, and developer entry points.
DigitalOcean: DigitalOcean expects a record 2Q26, with RPO above $800 million and up more than 10x YoY.
New RPO added in 2Q exceeded $550 million.
RPO duration rose from 1.6 years to more than 3 years, and revenue growth was about 29%.
The company added 20MW of data-center capacity to roughly 155MW. If smaller cloud vendors can secure long-term AI workload contracts, their valuation framework can shift from ordinary cloud hosting toward AI infrastructure.
“DOCN... revenue growth accelerated to 29%, above consensus 25%.”
Palantir: Palantir’s FDE model is moving from a company-specific feature to the default industry playbook, with five AI companies spending $9.75 billion over 12 months on forward-deployed engineering.
The company also announced that Mexico’s GNP Seguros expanded its enterprise agreement, using Foundry and AIP across health, life, auto, and property-casualty insurance, covering claims fraud detection, risk monitoring, and underwriting.
ServiceNow/Salesforce/MongoDB/Datadog: ServiceNow rose 1.34%, Salesforce rose 1.88%, and MongoDB and Datadog were included in the software rotation as part of the AI application foundation and observability chain.
Market performance shows that when semiconductors fall, software sees clearer fund inflows; but software stocks still need to prove that AI features can drive seats, usage, or net retention.
Adobe/Figma: Adobe was initiated at Underperform with a $190 price target, while Figma was initiated at Buy with a $30 price target.
This comparison shows that generative AI is competitive pressure for legacy creative tools, while it may be a new usage entry point for collaborative design platforms. From an investment perspective, the focus should be hybrid monetization, usage-based pricing, and enterprise adoption, not just “AI feature launches.”
Samsara: Samsara Agent Studio is based on 25 trillion real-world data points captured in 2025 and includes more than 15 prebuilt safety and maintenance templates.
Samsara Network covers 99% of major U.S. roads and tens of thousands of work sites. Its AI value is not in chat, but in closing real operational loops across fleets, job sites, and equipment maintenance.
Consumer Electronics / Smart Vehicles
Apple / Edge AI Watches: In Q1 2026, global shipments of smartwatches supporting Edge AI rose 70% YoY. Edge AI now accounts for 25% of smartwatch shipments, with Apple’s share close to 90%.
Health and fitness monitoring is the main driver. Low-power neural accelerators make on-device processing feasible without sacrificing battery life. Apple’s advantage lies in its closed loop across hardware, chips, algorithms, and health data.
BOE A: Citi downgraded BOE A from Buy to Neutral, but raised its target price from RMB 5.0 to RMB 8.7, arguing that LCD improvement and glass-substrate expectations are already fairly reflected in valuation.
On glass substrates, the company completed mainland China’s first pilot line in 2024 and delivered second-generation samples in 2025. However, a mass-production investment decision is not expected to be clarified until mid-2027, and meaningful net-profit contribution is unlikely before 2029.
Tesla: Over the past six weeks, Tesla has announced more than USD 9 billion of Megapack projects.
These projects total more than 43GWh and can support 5.9 million households.
The order from Esyasoft is worth up to USD 3 billion and exceeds 15GWh, covering the UK, Western Europe, the GCC, and India.
The energy-storage business is evolving from an appendage to auto valuation into part of the power chain for grids and data centers.
Tesla Cybercab: 1) Cybercab is designed as a compact two-seater because more than 85% of ride-hailing trips carry one to two passengers.
The RIM process compresses manufacturing cycle time from several hours to several minutes and eliminates VOC emissions. The validation points for Robotaxi are not slogans, but per-vehicle cost, energy consumption, regulation, and fleet utilization.
Humanoid Robots / Industrial Automation: Morgan Stanley expects the humanoid robot market to reach approximately USD 7.5 trillion by 2050.
Industry commercial revenue is approximately USD 3 billion in 2025.
Cost is expected to fall from approximately USD 200,000 in 2024 to USD 150,000 in 2028.
In high-income countries, cost is expected to be around USD 50,000 by 2050.
In regions dominated by China’s supply chain, cost could be as low as USD 15,000.
The more certain near-term beneficiaries are edge-computing chips, bearings, motors, and precision reducers.
Japan Factory Automation: Morgan Stanley MUFG is positive on Japan’s FA industry and expects WFE to grow 31% YoY in 2026 and 28% YoY in 2027.
Keyence is rated Overweight with a JPY 95,000 target price, while FANUC and SMC are rated Equal-weight. AI capex is transmitting into fab automation, but profit elasticity varies by company depending on product mix and fixed costs.
Investment-Bank Target-Price Changes Over the Past 12 Hours
Lao Huang’s Selected Portfolio
Lao Huang’s Selected Portfolio