
目录
Market Close Recap
Top 10 US Stocks by Turnover
Top US Stock Gainers
Top US Stock Decliners
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
CSP/Cloud Capital Expenditure and AI Data Centers
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry, Equipment, and Materials
Optical Communications, High-Speed Interconnects, and Power
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Huang’s Select Portfolio
Storage Index Performance
U.S.-Listed Memory Stocks’ Share of Trading Value
Overview
404K SEMI-AI | 2026-08-26
Market Close Recap
US equity risk appetite continued to tilt toward growth. The S&P; 500 ETF rose 0.32%, the Nasdaq 100 ETF gained 0.73%, the equal-weight S&P; 500 ETF added just 0.11%, and the small-cap ETF advanced 0.42%. The clear outperformance of market-cap-weighted indices suggests investors favored mega-cap technology and high-beta hardware rather than a broad-based rally.
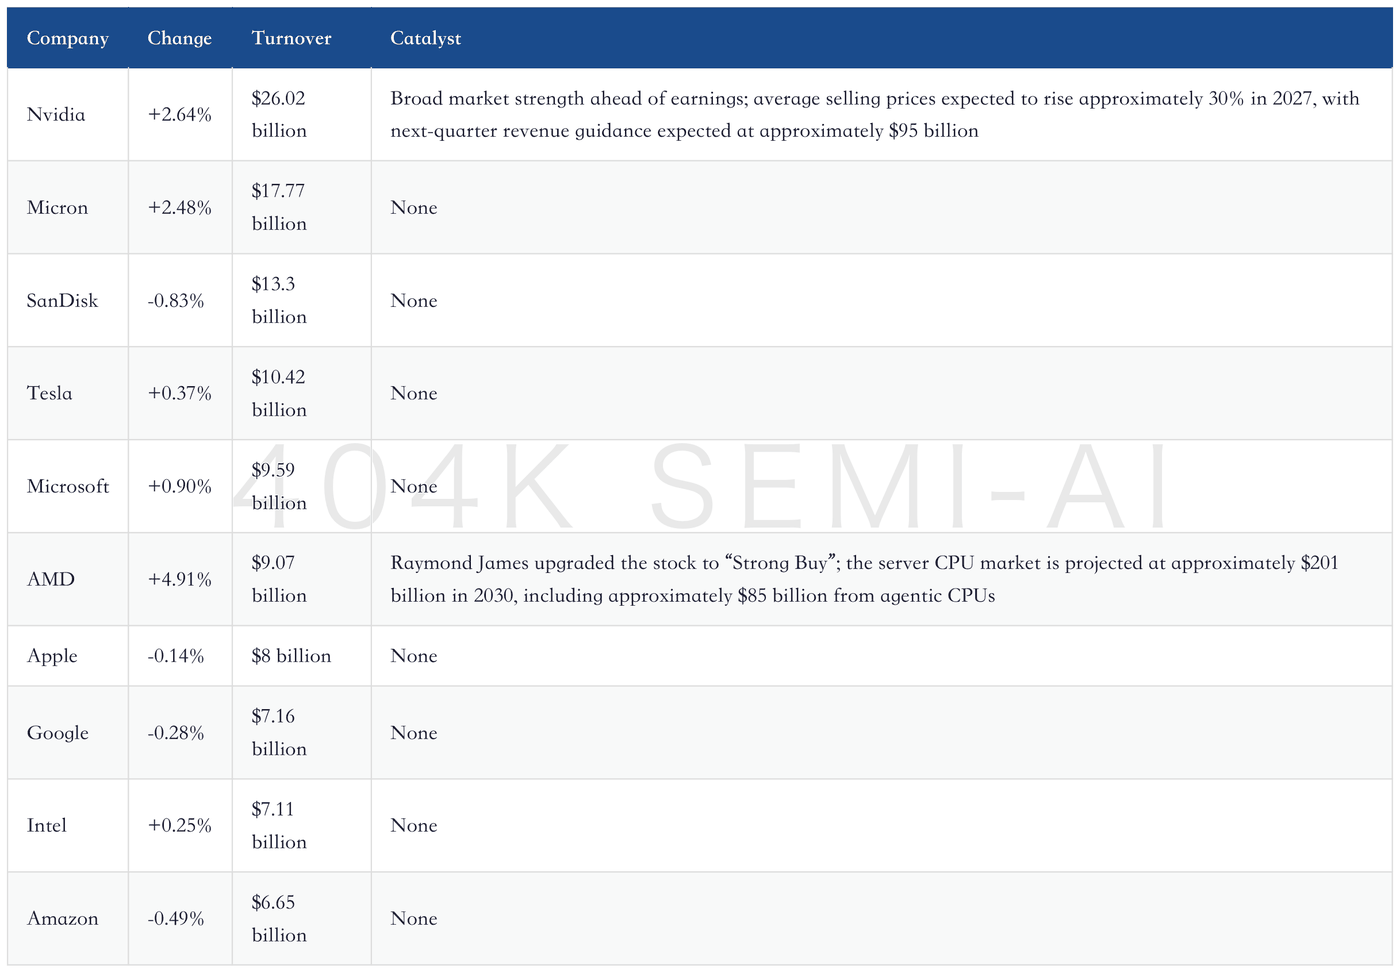
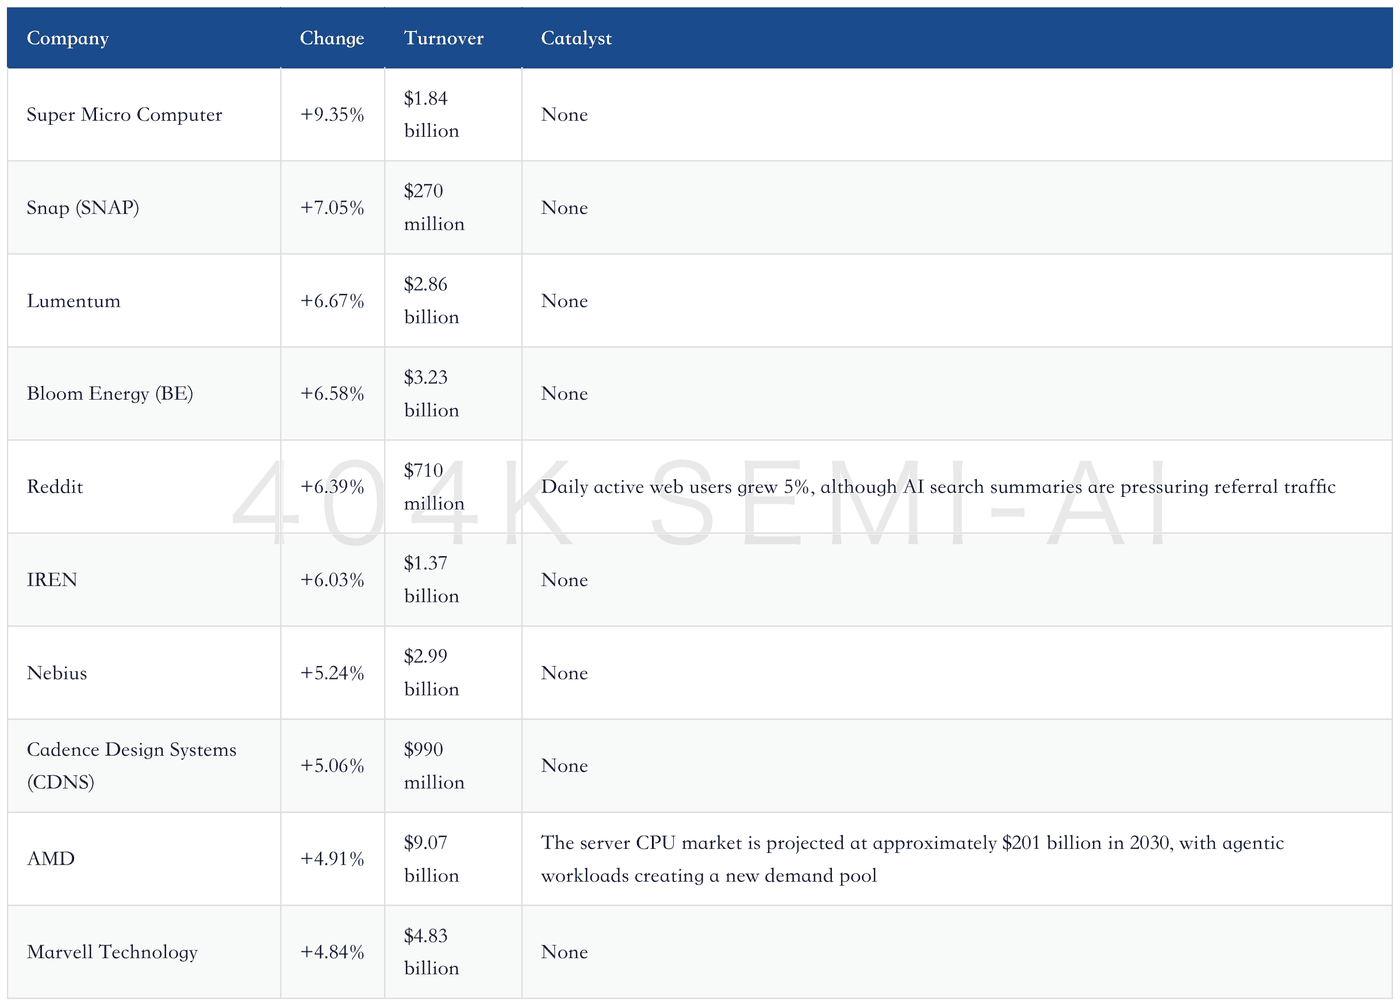
Technology and communication services led the market: the technology-sector ETF rose 0.98%, the communication-services ETF gained 1.22%, and the semiconductor ETF advanced 1.65%. Nvidia climbed 2.64% ahead of earnings, while AMD rose 4.91%; memory, optical communications, and AI data-center operators were also broadly stronger. The market’s focus has shifted from whether AI demand exists to how orders will be reallocated across GPUs, custom silicon, memory, networking, and power.
The most important development came from custom inference silicon. Jalapeño, jointly developed by OpenAI and Broadcom, has brought performance per watt, low latency, and flexible scheduling to the forefront. However, independent validation, long-context performance, and volume production in 2027 remain critical hurdles. Nvidia retains advantages in rack-scale networking, software ecosystem, and supply capability, but competition is increasingly centered on how many tokens each megawatt can generate.
Top 10 US Stocks by Turnover
Top US Stock Gainers
Top US Stock Decliners
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
OpenAI
1) Jalapeño was jointly developed with Broadcom, progressing from team formation to production tape-out in approximately 16 months. A0 outperformed Blackwell on performance per watt across several inference workloads, but the data were largely company-provided; comprehensive testing on InferenceX, AgentX, and multi-turn long-context workloads remains outstanding.
2) B0 uses TSMC’s N3P process. Each compute die delivers 13.4 PFLOPs at 700W, with performance per watt expected to improve by approximately 25% versus A0. Volume production is scheduled to ramp in 2027, with output concentrated in Q4.
3) The departure of the company’s infrastructure chief, projected spending of approximately $750 billion through 2030, and a 10 GW leasing plan have further elevated execution risk.
“OpenAI is currently constrained by data-center power, not budget or facility footprint.”
Anthropic
1) Market indicators suggest that Anthropic and OpenAI could together account for approximately 50% of incremental compute capacity in 2027. Both companies, however, remain heavily dependent on external financing, so compute concentration also amplifies capital-expenditure sustainability risk.
2) Claude has introduced unified memory across Chat and Cowork, with users deciding what to retain. The product proposition is shifting from one-off answers to persistent working context; enterprise adoption will depend on retention, paid usage, and security boundaries rather than the feature launch itself.
“Give Cowork a task, and it will begin with what Claude already knows from your chats.”
AI compute concentration: New power capacity and chip efficiency are rising simultaneously. Industry estimates put incremental global compute capacity at approximately 30 GW, 50 GW, and 70 GW in 2026, 2027, and 2028, respectively, while next-generation GB300, TPUV7, and TRAINIUM3 systems could deliver 3–5x the performance per watt of their predecessors. US data-center capacity under construction already exceeds 66 GW. Deployment wattage alone understates the effective compute delivered by newer systems, but demand concentration will also transmit financing and utilization risks rapidly across the hardware supply chain.
Microsoft: MAI-IMAGE26PREVIEW ranked No. 1 in image-editing benchmarks and No. 2 in text-to-image generation, with five No. 1 finishes across 19 categories. The model is live on Microsoft’s own experience platform and available in private preview through its cloud development platform. The incremental opportunity comes from distributing an internally developed model through Microsoft products; the next test is whether usage, enterprise deployment, and compute costs can create a closed revenue loop.
“Microsoft highlighted stronger text rendering, better portraits and 3D imagery, and more refined commercial and photorealistic output.”
CSP/Cloud Capital Expenditure and AI Data Centers
Google: The assumed TPU price has risen to approximately $27 billion/GW, with related cloud revenue estimated at approximately $84 billion in 2027 and $108 billion in 2028. Higher pricing increases revenue sensitivity but also raises customer expectations for inference costs and utilization. Google fell 0.28% on the day. The market is not rejecting the demand outlook, but it is increasingly asking how much billable compute each $1 of capital expenditure can generate.
Amazon: Combined demand for Trainium 2 and TRAINIUM3 is approaching 2.7 million chips, underscoring the importance of internally developed silicon in controlling cloud inference costs. The tradeoff is that data-center investment is consuming cash; if compute procurement outpaces cloud-revenue realization, free cash flow will come under pressure first. Amazon fell 0.49% on the day. Key indicators are chip deployment, cloud-revenue growth, and capital-expenditure intensity.
Meta: The Hatch agent may charge up to $199.99 per month, while Watermelon is scheduled for an October launch. In external compute sales, each 0.5 GW of capacity could generate approximately $11 billion in annualized revenue and $1.44–$2.16 in incremental EPS, although expanding supply would compress pricing premiums. The more durable validation point is whether agents, subscriptions, WhatsApp, and cloud interfaces can generate high-margin revenue.
Nebius: Goldman Sachs said Q2 deals were priced above $20 million/MW, with near-term capacity negotiations rising to $40,000,000–$50,000,000/MW. The company raised its long-term target from 4 GW to 5 GW, with more than $9 billion in upfront funding through 2026 and approximately $40 billion in committed backlog. Pricing power and the financing structure support expansion; risks include short-duration contracts, competition, and the pace at which capacity becomes operational.
AM Intelligence: The company ordered 9,000 Nvidia Vera Rubin NVL72 systems for delivery in Q1 2027, with the initial phase supporting 30 MW. The order is part of an approximately $8 billion, 1 GW compute-services plan spanning 4 countries. The large order validates rack-scale demand, although actual revenue recognition still depends on delivery, grid connection, and customer onboarding.
GPU/CPU/ASIC
Nvidia
1) Shares rose 2.64%. Ahead of earnings, the market expects average selling prices to increase approximately 30% in 2027 and next-quarter revenue guidance of approximately $95 billion, potentially rising to between $105 billion and $107 billion in the following quarter.
2) BlueField-4 and DOCA form a new intra-rack networking layer. Each Vera Rubin tray requires 7Tb/s, using four 1.6T outputs and 800G inputs, making networking an integral component of total system throughput rather than a supporting accessory.
3) Approximately $230 billion in potential backstop obligations includes $105 billion of data-center leases and up to $125 billion in residual-value guarantees. Growth quality must therefore be assessed across revenue, gross margin, and contingent obligations.
AMD: Raymond James upgraded the stock to “Strong Buy,” estimating that the server CPU market will reach approximately $201 billion in 2030, including approximately $85 billion from agentic CPUs and approximately $83 billion from AI front-end CPUs. UBS separately estimates that revenue could reach approximately $227 billion in 2030, with a 45% EBIT margin. The thesis is that agents require orchestration, retrieval, database, and security workloads, but AMD’s ability to capture share still depends on EPYC and Helios execution.
Broadcom
1) OpenAI defined Jalapeño’s architecture, while Broadcom provided design services. Custom inference silicon places Broadcom at the intersection of chips, SerDes, and rack interconnects.
2) The company disclosed that deployment by one AI customer will increase from 1.5 GW this year to 6.5 GW next year and could reach 17 GW within 3 years. The contract confirms robust demand, but the revenue trajectory will depend on delivery timing, customer concentration, and data-center power availability.
“This sacrifices some theoretical peak efficiency so the system can flexibly accommodate a changing real-world workload mix without subsequently rebalancing the hardware.”
Intel: HSBC included foundry services in its sum-of-the-parts valuation for the first time, arguing that tight advanced-packaging and wafer capacity will push some customers toward EMIB and 18A. The bank also raised its server CPU shipment-growth forecasts for 2026 and 2027 to 25% and 30%, respectively. Better-than-expected 18A yields are encouraging, but the real tests remain external customers, volume shipments, and narrowing foundry losses.
Cerebras: Its division of labor with OpenAI is becoming clearer: Jalapeño will serve internal infrastructure, while Cerebras handles ultra-low-latency inference. The existing agreement includes a firm 750 MW obligation and an additional 1.25 GW option, providing near-term demand visibility. If Jalapeño continues improving throughput and cost, however, it could affect option exercise and the structure of future procurement.
Semtech: Q2 revenue was $342 million, with EPS of $0.71. Q3 guidance calls for revenue of $410 million, EPS of $1.05, and a 58.3% gross margin, or 63.9% excluding the business held for sale. Portfolio streamlining is improving both growth and margins; the key question is whether the higher-margin mix can be sustained, rather than whether reported metrics benefit from a one-off classification change.
HBM/DRAM/NAND/SSD/HDD
Memory pricing and cloud spending: Combined DRAM and NAND pricing rose approximately 20% in Q3, while sequential growth is expected to slow to 5%–10% in Q4. Capital expenditure by major cloud providers is projected to grow 98% year over year in 2026 and another 50% in 2027, while DRAM and NAND’s share could rise from 47% to 68%. Prices are still increasing, but at a slower rate; higher costs may drive chip price increases or reduce memory content per accelerator.
Samsung Electronics
1) LPDDR is beginning to incorporate near-memory computing, extending memory from passive capacity into part of the inference-compute stack.
2) Jalapeño’s HBM4 bandwidth is 15.4TB/s. The supplier’s identity remains speculative and does not confirm an exclusive order.
3) In foundry, Groq 3 uses the SF4X 4 nm process. Monthly wafer starts are expected to increase from 10,000 to more than 15,000 in 2027, with reported 4 nm yields above 80%; however, the next-generation order has not yet been finalized.
SanDisk: The company must fulfill $11.4 billion of flash-memory orders over the next 12 months, versus $20.2 billion of flash sales in the most recent fiscal year. These orders were signed before prices increased, locking in customer pricing. The company also has $48.4 billion of longer-term commitments and signed an additional $31.3 billion of orders after year-end. The backlog secures shipments but limits near-term upside from higher prices; margin sensitivity will depend on contract repricing and the cost curve.
