404K SEMI-AI Tech Morning Brief 2026-07-10 — Meta Compute Expansion, Storage Chain Re-Rating, Semiconductor Equipment Capacity Buildout
目录
Post-Market Summary
U.S. Stocks at New Highs
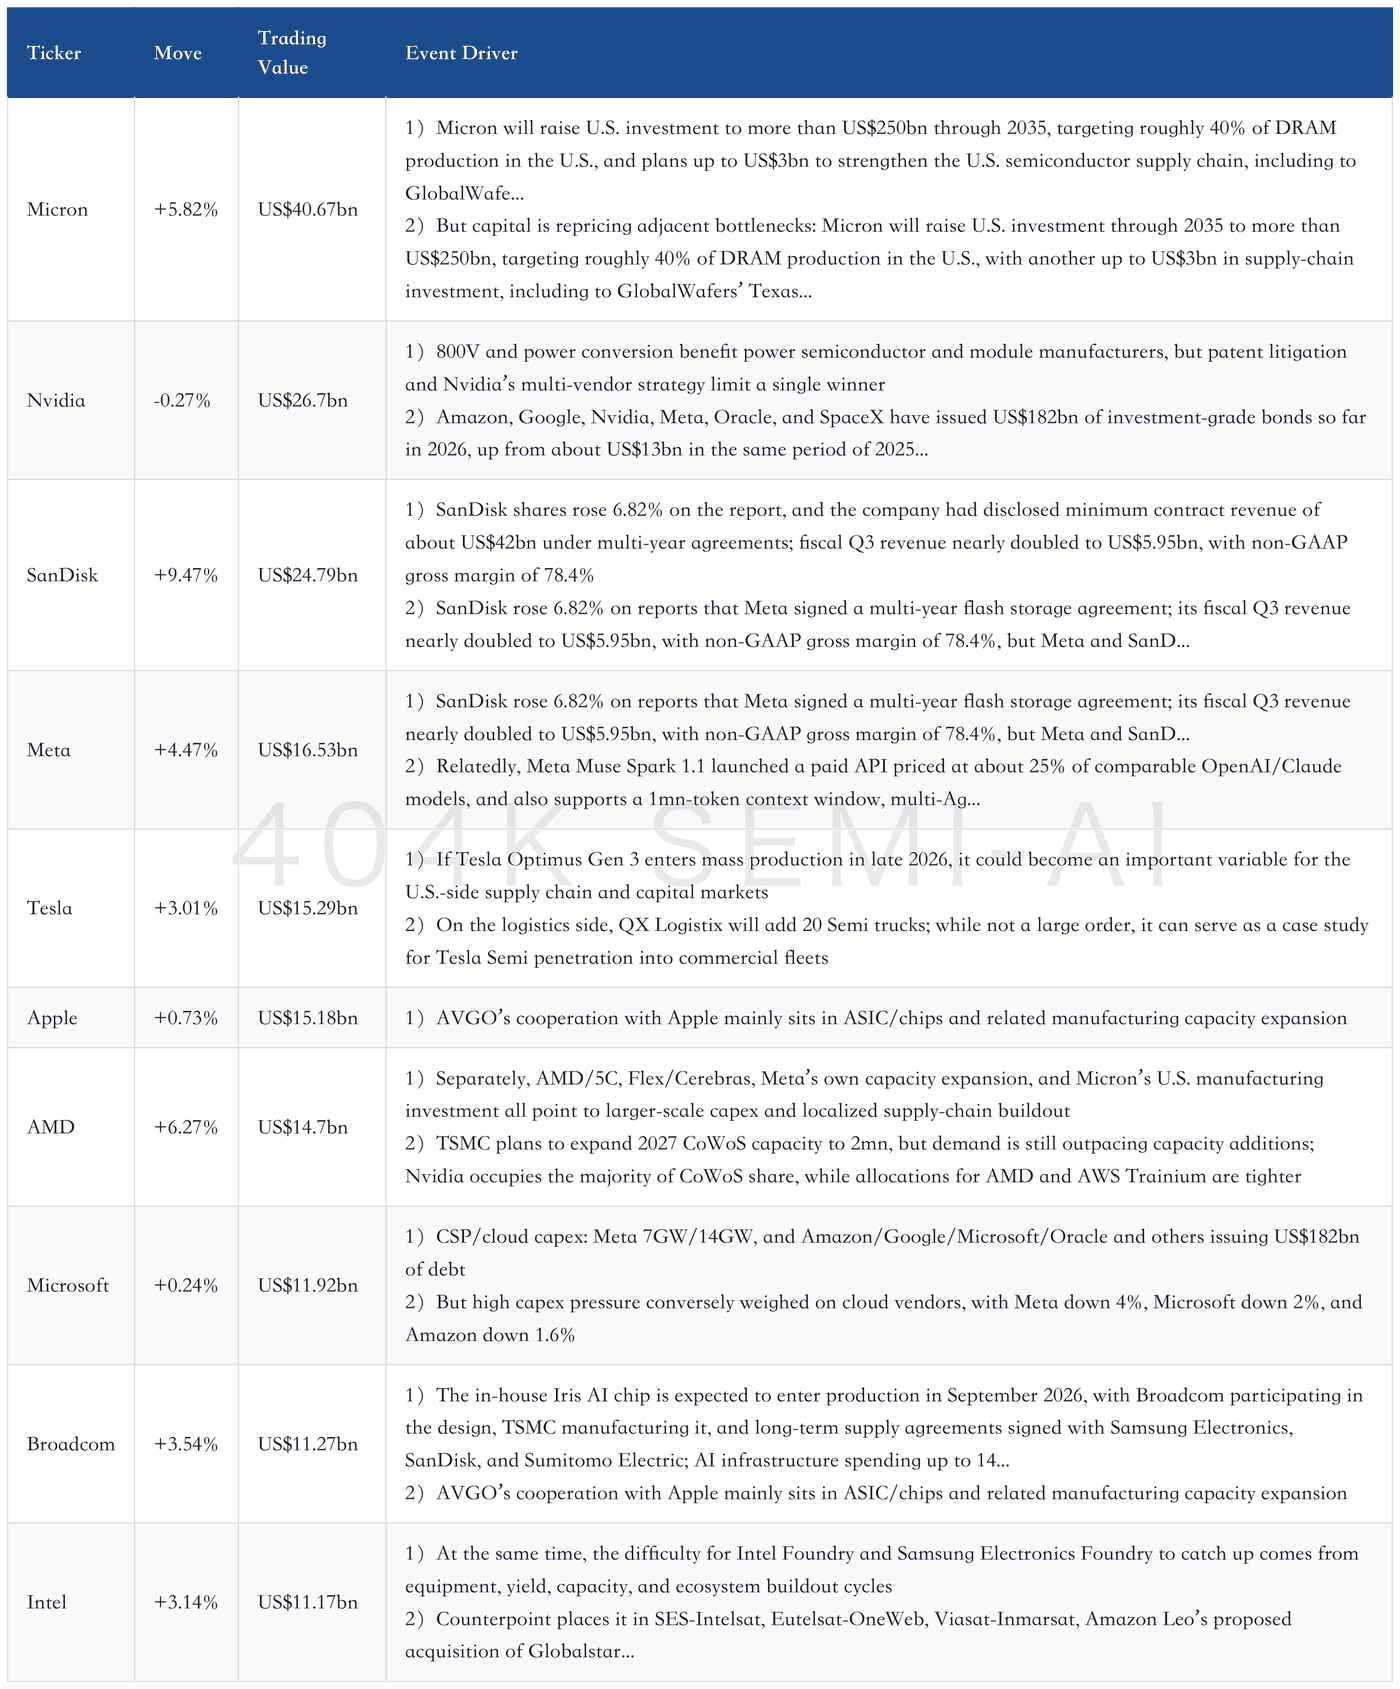
Top 10 U.S. Stocks by Trading Value
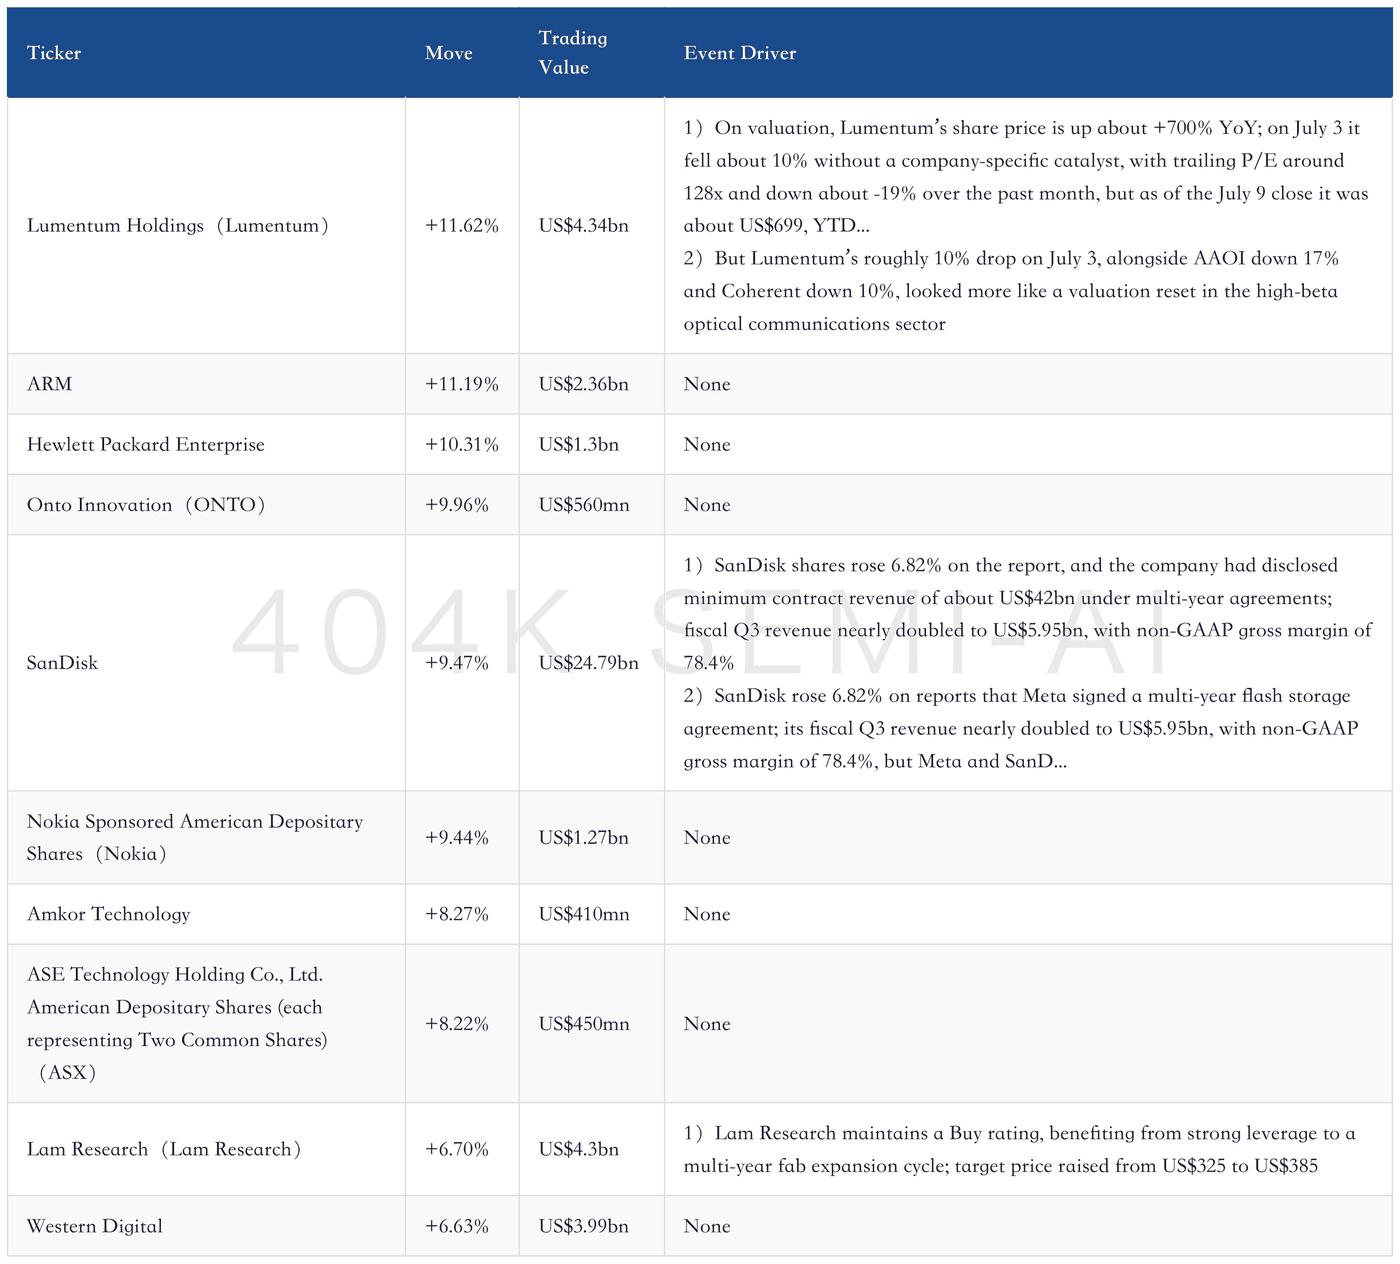
U.S. Stock Gainers
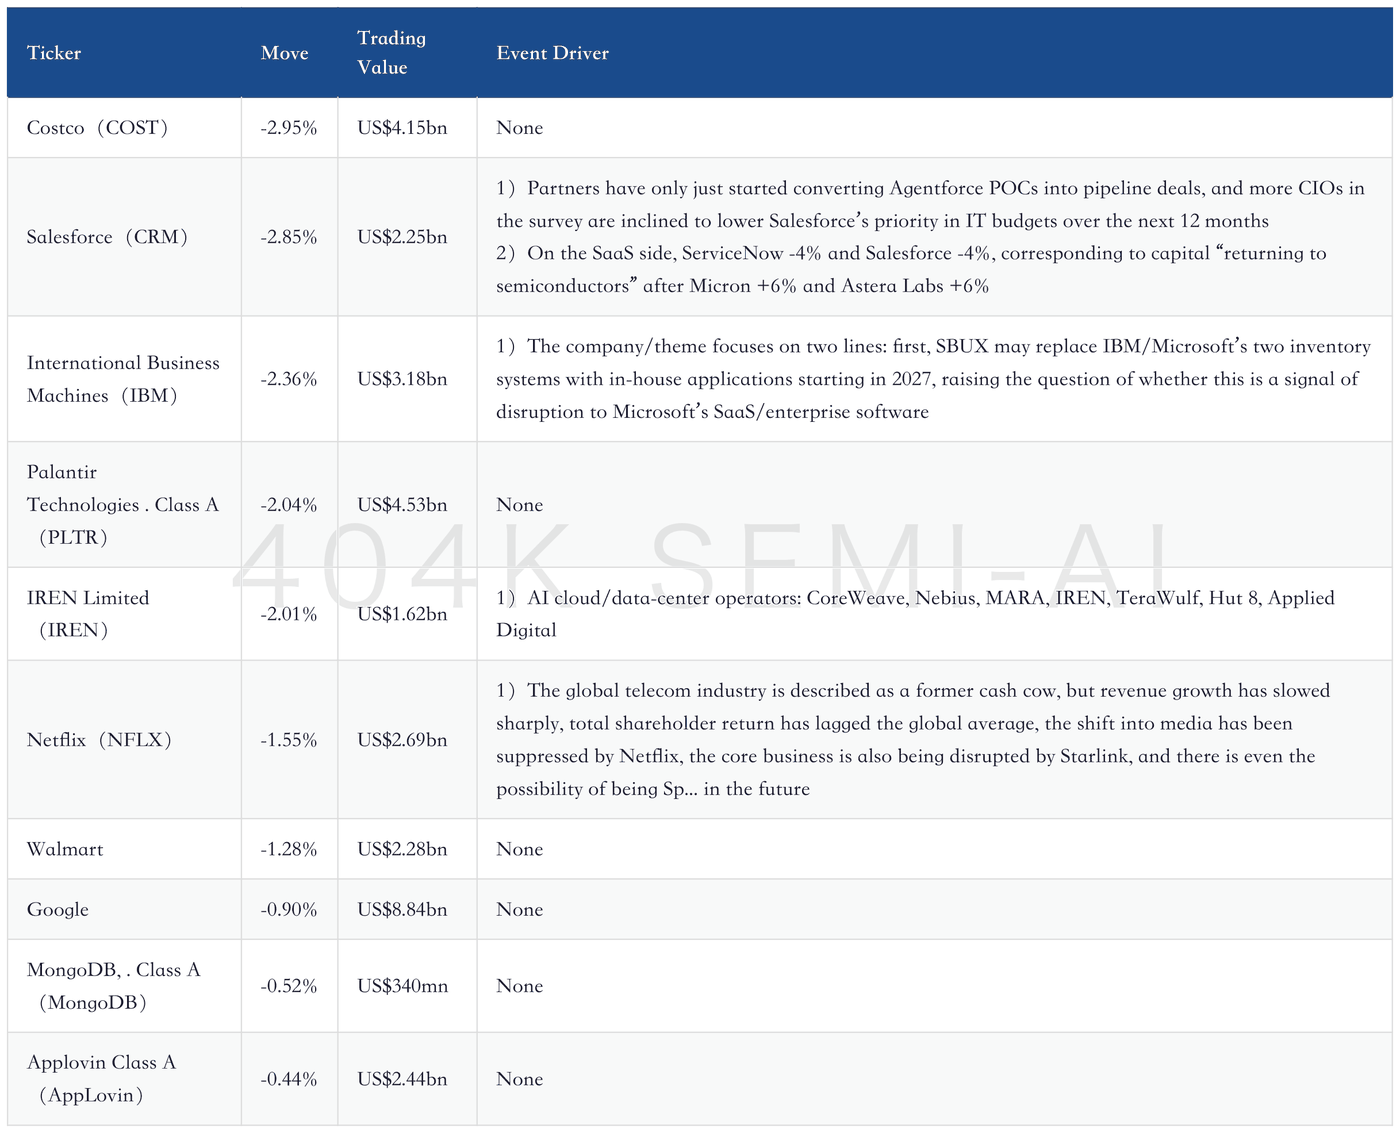
U.S. Stock Decliners
AI/Semiconductor Full Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Wafer Foundry and Advanced Packaging
Semiconductor Equipment/Testing
PCB/Substrates/Optical Communications/Power
Internet / Platforms
Software / SaaS
Consumer Electronics / Smart Vehicles
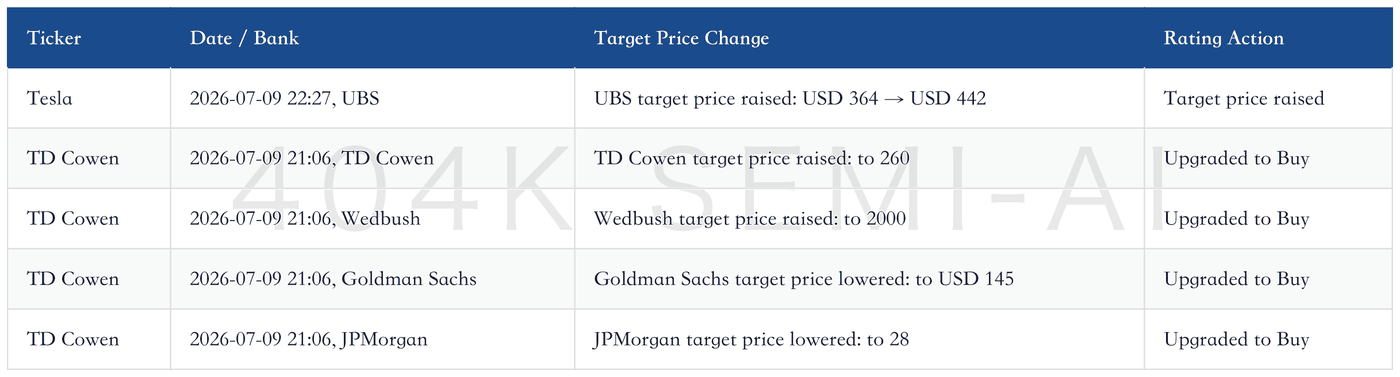
Investment Bank Target Price Changes in the Past 12 Hours
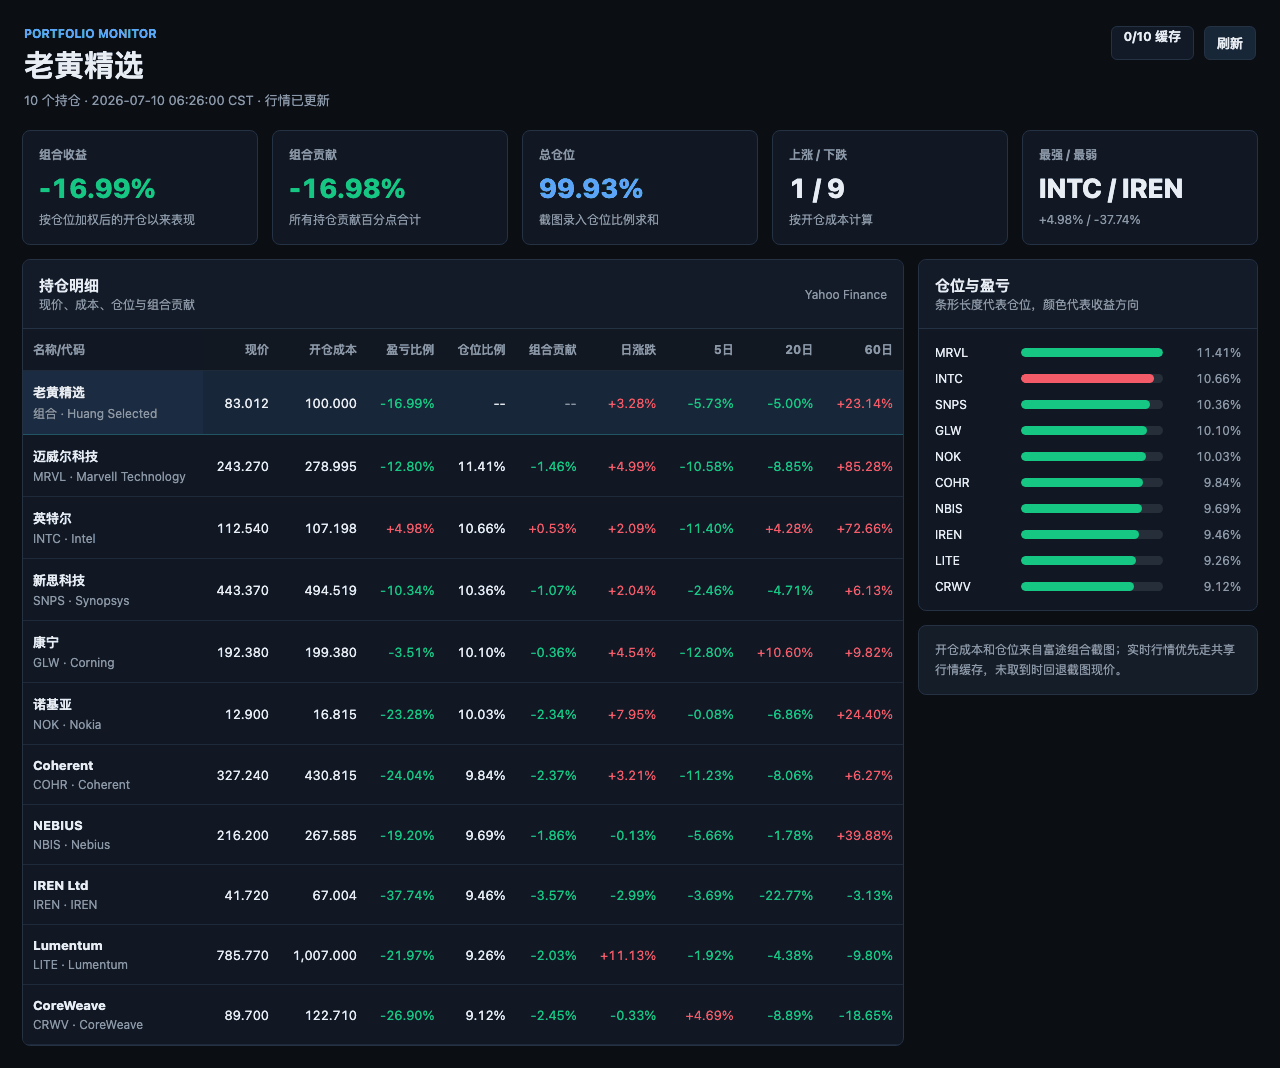
Jensen Huang Select Portfolio
The marginal change in the AI trade is shifting from “who has the strongest model” to “who can absorb the power, storage, packaging, networking, and cash flow requirements.” Last night, semiconductors, cloud computing, and optical communications all strengthened, while software/SaaS diverged. The market is starting to price AI capex as a longer supply chain.
Post-Market Summary
U.S. equities continued to lean toward technology growth at the 2026-07-09 close. The S&P; 500 rose 0.81%, the Nasdaq 100 rose 1.66%, and the Russell 2000 rose 1.32%; the technology ETF rose 2.18%, the semiconductor ETF rose 2.78%, and the equal-weight semiconductor reference rose 3.50%. The key driver was AI capex pulling capital back into semiconductors, memory, equipment, and data-center infrastructure.
By theme, the cloud computing ETF rose 2.16%, cybersecurity rose 2.84%, software rose 1.29%, and AI & big data rose 2.01%. The robotics and AI ETF rose 1.78%, but its 20-day RPS remains lagging, indicating that capital is still prioritizing “AI infrastructure picks-and-shovels” while staying selective on longer-dated robotics applications. The VIX fell 6.51%, leaving room for a rebound in high-beta technology stocks.
At the single-stock level, the semiconductor chain outperformed the M7. Micron rose 4.36%, SanDisk rose 6.24%, Western Digital rose 4.91%, Broadcom rose 3.20%, Advanced Micro Devices rose 5.62%, and ARM rose 9.68%. Cloud vendors diverged: Meta rose 4.50%, Amazon rose 1.40%, Microsoft rose only 0.12%, and Google fell 0.84%; the market is willing to pay for compute and supply-chain bottlenecks, but is still scrutinizing the pace of returns on cloud capex.
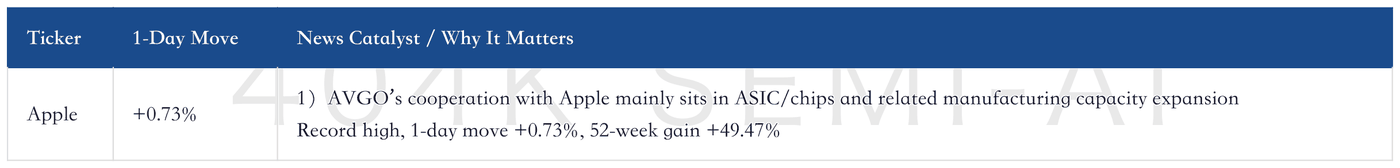
U.S. Stocks at New Highs
Top 10 U.S. Stocks by Trading Value
U.S. Stock Gainers
U.S. Stock Decliners
AI/Semiconductor Full Value Chain
AI Models/Applications and Capital Expenditure
OpenAI
1. OpenAI’s incremental value lies in the application entry point, not in a single model’s parameter count. ChatGPT Work has been rolled out to 100% of Pro users, and nearly 100% of internal employees use it regularly; GPT-5.6 Sol is described as covering coding, complex context, strategy tasks, and website building.
2. The GPT-Live API has begun recruiting design partners, indicating that real-time interactive AI is moving from demos into the developer ecosystem. The validation points are public pricing, SDKs, customer cases, and call volume; social-media benchmarks have limited reference value.
"ChatGPT Work is now rolled out to 100% of our Pro users."
Claude
Claude-related signals more clearly reflect its competitive model positioning. Multiple reports compare Claude with GPT-5.6, Grok 4.5, and Meta Muse Spark within the same framework, emphasizing that frontier-model competition continues to intensify. The supply-chain implication is that training and inference demand remains strong, but the current materials do not provide cloud-contract or GPU-procurement figures, so orders cannot be directly extrapolated.
Meta Model API
1. Meta launched Muse Spark 1.1, a paid developer model. API pricing is roughly 25% of comparable models from OpenAI and Claude, and it supports a 1 million-token context window, multi-agent orchestration, tool use, and multimodal understanding.
2. A low-price strategy will pressure model-pricing expectations, but if it expands developer usage, it could instead increase demand for inference, storage, networking, and power.
"API pricing is roughly 25% of the cost advertised by other top models."
Frontier-Model Competition
GPT-5.6, Grok 4.5, Meta Muse Spark, and Chinese models all appear in the materials at the same time. The market focus has shifted from “who is ahead” to “who has the lowest unit task cost and who can absorb workflows.” This will push revenue validation away from model launch events and toward API usage, enterprise seats, agent success rates, and cloud inference costs.
Enterprise AI Budgets
Citi’s CIO survey shows that expected global IT budget growth over the next 12 months rose from 2.6% to 3.3%. AI accounts for about 6.5% of IT budgets, and CIOs expect AI spending to increase by about 10% over the next 12 months. 69% of AI funding still comes from incremental budgets, but traditional BI, consulting, front-office, and back-office projects have already begun to be crowded out.
"Overall forward IT budget growth expectations rose to +3.3% from +2.6%."
CSP/Cloud Capital Expenditure
Meta
1. Meta was last night’s main AI infrastructure theme. Multiple materials point to compute-infrastructure plans of 7GW in 2026 and 14GW in 2027. Its in-house Iris AI chip is expected to enter production in September 2026, with Broadcom participating in design and TSMC manufacturing it.
2. Meta also signed long-term agreements with Samsung Electronics, SanDisk, and Sumitomo Electric covering memory, flash storage, and optical-fiber equipment. The risk is that if 14GW is realized, financing, depreciation, and free-cash-flow pressure will rise in parallel.
"Meta plans 7 GW of AI computing capacity in 2026 and 14 GW in 2027."
Amazon, Google, Microsoft, Oracle
Large technology companies are using debt to extend the runway for AI infrastructure. Amazon, Google, Nvidia, Meta, Oracle, and SpaceX have issued $182 billion of investment-grade bonds so far in 2026, up 1,300% from about $13 billion in the same period of 2025. This shows that AI capex has moved from a cash-flow issue to a credit-market issue.
Google
Google’s main thread is TPU and cloud workloads. Reports say Claude has proven the feasibility of training models on TPUs, and TPUs continue to gain share beyond Google’s internal workloads. However, Google’s share price fell 0.84% that day, as the market still applies a discount to advertising, AI disclosure, and cloud capital returns. The next points to watch are Google Cloud growth and external TPU customers.
Microsoft
Microsoft’s near-term issue is that incremental AI budgets are beginning to squeeze traditional software seats. In the CIO survey, Microsoft was the vendor most likely to see increased AI spending, with 50 votes; but it was also included in discussions about systems that could be replaced by enterprises’ in-house development. Azure and Copilot need to use RPO, cloud growth, and customer renewals to prove that AI can drive net incremental budgets.
Apple
Apple’s new high comes from expectations around on-device AI and chip partnerships. Market reports say PrismML can compress Alibaba’s 27 billion-parameter Qwen 3.6 model from 54GB to below 4GB and run it locally on the iPhone 17 Pro. At the same time, Apple’s cooperation with Broadcom has been extended to 2031, with plans to produce more than 15 billion U.S.-made chips. If on-device AI is validated, it would change assumptions about cloud inference growth.
AI Cloud/Data-Center Operators
CoreWeave, Nebius, IREN
New cloud deals are recovering from fears of “compute oversupply.” Meta is exploring compute leasing while also planning to push deployment scale to 14GW, weakening the oversupply narrative. CoreWeave’s contracted backlog is cited in the materials at $99 billion, while Nebius has more than $50 billion of agreements with customers including Meta and Microsoft. Near term, watch leasing prices and customer concentration.
TeraWulf, Applied Digital, Galaxy Digital, Cipher Mining
This group of compute and power assets is meaningful only when customers, capacity, power, and financing are disclosed together. The current materials place them on the neocloud rebound list, but hard evidence remains concentrated in Meta capex, CoreWeave/Nebius contracts, and IREN trading sentiment. Next, watch MW/GW deployment, lease-contract duration, and electricity prices.
GPU/CPU/ASIC
Nvidia
1. Nvidia fell 0.66% in the near term, but the AI GPU demand narrative has not weakened. TD Cowen maintained Buy with a $275 target price, and Citi maintained Buy with a $300 target price. Wells Fargo estimates potential H200 sales into China of about 200,000 units, worth $6 billion-$8 billion.
2. Rubin/Vera signals continue to strengthen. Reports say Vera CPU has a revenue opportunity of about $20 billion by the end of this fiscal year; Vera delivers a 50% IPC improvement over Grace, and sustained per-core performance for agent tasks is 1.8x that of x86.
"Rubin Ultra roadmap and Computex NVLink domains are fully intact."
Broadcom
Broadcom rose 3.20%, benefiting from Meta Iris, custom ASICs, and cooperation with Apple. Iris is designed with Broadcom participation and manufactured by TSMC; the Apple partnership has been extended to 2031 and involves the manufacture of more than 15 billion U.S. chips. The debate around Broadcom is whether ASIC growth can continue to offset cyclical volatility in general semiconductors. Next, watch customer concentration and the cadence of TPU/AI XPU.
AMD
Advanced Micro Devices rose 5.62%, as the market bought back into the MI450/MI455, Venice CPU, and CoWoS supply story. The materials clarify that 240,000 CoWoS units in 2027 cannot be directly equated with GPU shipments. MI455 targets about 1 million units, Meta’s customized half-size MI450 version targets 500,000 units, and Venice CPU has potential volume of 5.7 million-6.0 million units in 2027. The bottlenecks are packaging, HBM, and substrates.
ARM
ARM rose 9.68%, among the strongest gainers. The materials do not provide new earnings or target prices, but frontier models, Vera CPU, agentic AI, and on-device inference all reinforce the long-term narrative for CPU IP. Near term, investors should be alert to high valuation elasticity and slow earnings confirmation. The real validation points are data-center CPU share, royalty rates, and adoption of in-house chips by large customers.
Cerebras
Cerebras and Flex expanded their California manufacturing partnership, targeting an approximately 7x increase in CS-3 AI system output by 2026, with new production lines, testing infrastructure, and high-skill jobs. This reflects the broadening demand from model developers, cloud providers, and enterprises for different forms of AI systems.
HBM/DRAM/NAND/SSD/HDD
Micron
1. Micron rose 4.36% and ranked first by trading value. The company increased its planned U.S. investment through 2035 to more than $250 billion, targeting about 40% of DRAM production in the United States. It also announced up to $3 billion of supply-chain investment, including $500 million to support GlobalWafers’ Texas 300mm silicon-wafer plant, with a 10-year supply agreement.
2. Memory sales reached $74.6 billion, up 31.7% sequentially, including $48.0 billion of DRAM and $25.8 billion of NAND. UBS expects DDR contract prices to rise 32%/18% in Q3/Q4 2026, and NAND to rise 30%/12%.
"DRAM market remaining structurally undersupplied through at least Q2 2028."
SK Hynix
SK Hynix’s U.S. ADR was priced at $149, with demand close to $200 billion; the top 25 accounts received about 67% of the allocation. The materials cite two HBM share figures, 58% and 64%, but both point to the same conclusion: overseas capital wants direct exposure to HBM assets. The risk is that amid a strong cycle, both valuation and supply expansion are accelerating.
SanDisk
SanDisk rose 6.24%, ranking higher among gainers. Reports indicate Meta signed a multi-year flash-storage agreement with SanDisk. SanDisk had previously disclosed a multi-year agreement with minimum contracted revenue of about $42 billion; fiscal Q3 revenue nearly doubled to $5.95 billion, and non-GAAP gross margin reached 78.4%. Meta and SanDisk have not confirmed the financial terms. Next, watch contract disclosure and NAND pricing.
"Customer affordability and sustainability of AI-related capital expenditure are still the key risks."
Samsung Electronics
Samsung Electronics’ main thread is DRAM, HBM, and the domestic supply chain. According to reports, the U.S. Commerce Secretary urged Samsung Electronics and SK Hynix to expand U.S. memory capacity. Samsung Electronics also expanded annual support by about 1,000 graphics wafers and is sharing process data with materials, components, and equipment partners. If HBM and advanced DRAM demand remains strong, Samsung Electronics’ key variables are yield and customer qualification.
Western Digital, Seagate Technology
Western Digital rose 4.91%, and Seagate Technology rose 3.50%. HDDs and enterprise drives continue to be supported by AI data-center storage demand. The current materials do not provide new orders or target prices, but the gains come from the same logic: training data, model checkpoints, inference logs, and cold-data storage are all amplifying enterprise-drive demand. The risk is that NAND and HDD cycles may be out of sync.
Wafer Foundry and Advanced Packaging
TSMC
TSMC ADR rose 0.11%, but the industry information was stronger. Reports say CoWoS capacity is planned to expand to 2 million units in 2027, while demand is still growing faster than capacity expansion. Nvidia occupies the majority of CoWoS share, and allocation for AMD and AWS Trainium is tighter. Another equipment framework mentions TSMC capex reaching $100 billion in 2028. The validation points are monthly CoWoS capacity, advanced-node price increases, and customer queues.
Samsung Foundry, Intel Foundry
The difficulty of Samsung Electronics and Intel catching up in foundry is being discussed within the cycles of equipment, yield, capacity, and ecosystem. The signal that Samsung Electronics is raising prices by 15% for 4/5nm and automotive 8nm indicates advanced-node pricing power is shifting toward suppliers. Intel rose 2.17%, but entering foundry season still requires monitoring customers, yield, and advanced-node wafer starts, not just CPU sentiment.
ASE Technology Holding, Amkor, Advanced Packaging and Testing
OSAT stocks followed the heating-up of advanced packaging. Amkor rose 7.85%, and ASE Technology Holding ADR rose 8.31%. ASE-related materials mention earnings continuing to beat expectations, TSMC advancing CoWoS plans, and CPU-driven upside in FOCoS. The business issue for the OSAT chain is straightforward: the larger AI chips become and the more complex packaging gets, the firms with capacity and yield can raise prices.
Semiconductor Equipment/Testing
Applied Materials
Applied Materials rose 3.80%. Deutsche Bank raised its WFE forecasts to $145 billion in 2026, $193 billion in 2027, and $220 billion in 2028. Applied Materials remains its top pick, with the target price raised from $550 to $680; Mizuho also raised its target price from $540 to $650. Its key variables are the durability of DRAM, foundry, and advanced-packaging capital expenditure.
"WFE forecast is $145 billion in 2026, $193 billion in 2027, and $220 billion in 2028."
Lam Research
Lam Research rose 6.56%. Deutsche Bank maintained Buy and raised its target price from $325 to $385; Mizuho raised its target price from $380 to $400. Under the GAA transition, Lam estimates that every additional 100,000 wafers per month of wafer-start capacity adds about $1 billion to its serviceable market, with clearer leverage in etch, deposition, and cleaning.
KLA
KLA rose 4.15%. Morgan Stanley upgraded it to Buy, and TD Cowen raised its target price to $260. Deutsche Bank still rates it Hold, raising its target price from $175 to $220, because process control has less leverage to capacity-driven expansion than Applied Materials and Lam Research. The debate is whether WFE upside can benefit inspection/metrology to the same degree.
ASML
ASML rose 2.01%. Reports say EUV revenue over the past three quarters was EUR2.1 billion, EUR3.6 billion, and EUR4.1 billion. TD Cowen’s framework also gives EUV shipments of 88 units in 2027 and 110 units in 2028. Advanced nodes, HBM, and ASIC are all pushing lithography demand higher, but ASML remains affected in the near term by delivery cadence and 2027 order visibility.
Advantest, Onto Innovation, FormFactor
The test and metrology chain strengthened in tandem. Advantest ADR rose 5.38%, Onto rose 8.77%, and FormFactor rose 7.03%. The materials mention that silicon photonics, HBM, CPU, and advanced packaging have different testing requirements, and testing could become the next-stage bottleneck. The validation points for this line are order visibility and gross margin; one-day gains only indicate trading sentiment.
PCB/Substrates/Optical Communications/Power
ABF/PCB/CCL
The logic for AI board-material price increases continues to strengthen. Goldman Sachs said ABF supply and demand should remain favorable for at least the next 18-24 months, and AI IC substrate TAM is expected to grow at a 66% CAGR from 2025 to 2028. The materials also say Low-DK Gen2 glass-fiber cloth will face a 60%+ supply gap in 2H 2026, T-glass a 50%+ gap extending into 2028, and IC substrates a 40%+ gap in 2027.
"IC Substrates: Fully Sold Out Through 2027."
Lumentum, Coherent, AAOI
The rally in optical communications is driven by AI data centers shifting from copper cables to fiber. Lumentum rose 10.59%; fiscal 2026 Q3 revenue was $808.4 million, with components revenue up 77% to $533.3 million and systems revenue up 121% to $275.1 million. Current-quarter revenue guidance is $960 million to $1.0 billion. Management said the main constraint is on the supply side.
Nokia
Nokia ADR rose 9.44%. According to reports, Nokia is expanding photonics capacity in Pennsylvania by 10x, with part of the capacity to come online before Q3 2026. New AI and cloud orders reached EUR 1.0 billion, and optical business growth guidance is 18%-20%. The bottleneck is in packaging and testing, indicating that optical networking equipment is also starting to benefit from AI cluster interconnect demand.
Corning, Sumitomo Electric, Furukawa Electric, Fujikura
Meta’s long-term agreements have pushed fiber-optic cables back to the forefront. Sumitomo Electric was specifically named as signing a long-term fiber supply agreement. Corning rose 4.70% in the U.S. technology equity pool. Japanese fiber-optic cable names remain supported by AI data centers and cross-campus clusters. Key tracking points are fiber preforms, optical cable lead times, and data center interconnect orders.
Power Semiconductors and Power Supplies
AI rack power is turning 800V HVDC, GaN/SiC, and power modules into critical links. A Rubin-generation Kyber rack can reach 1MW per cabinet, while 800V can reduce copper usage by up to 45%. Navitas demonstrated a 20kW power board that can step 800V down to 6V in one stage, with peak efficiency of 97.5%. Wolfspeed has sued Navitas; the risk is patents, while the opportunity is high-voltage step-down conversion.
"Navitas’ 20kW power board can step 800V down to 6V in one stage, with peak efficiency of 97.5%."
Internet / Platforms
Meta
Meta rose 4.50%. It is both a platform stock and an AI infrastructure buyer. The paid Muse Spark 1.1 API pushes AI monetization toward developers, while 7GW/14GW pulls the supply chain toward storage, fiber, and ASICs. The market is simultaneously rewarding AI offense and questioning financing pressure. Next, watch ad growth, API revenue, and capex guidance.
"AI infrastructure spending this year could reach up to $145 billion."
Amazon
Amazon rose 1.40%. In the CIO survey, Amazon was the second-largest beneficiary supplier from increased AI spending, receiving 12 votes. AWS is also linked to Trainium and cloud inference demand. The risk is that after hyperscalers stop buybacks and shift toward buying chips, near-term margins and free cash flow are compressed. AWS revenue acceleration is needed to prove the return on investment.
Google
Google fell 0.84%, with advertising, externalization of TPUs, and model competition all weighing on valuation. AI advertising disclosures have expanded to Search, YouTube, and Discover, indicating rising regulatory and user-transparency costs. If TPUs continue to win training workloads from external frontier labs, that would improve returns on cloud capex.
Apple
Apple rose 0.83%, reaching an all-time high. On-device AI compression technology and the Broadcom partnership point to two lines of development: local models may reduce dependence on cloud inference, while on-device AI still requires ASICs, advanced process nodes, and storage upgrades. If DRAM/NAND price increases continue, high-end iPhone BOM and pricing strategy will become core variables for the consumer electronics sector.
Tesla
Tesla rose 3.21%. UBS raised its price target from $364 to $442, citing the long-term potential of physical AI and robotics. Robotaxi materials said deployments have already occurred in three states and could reach 12 states by year-end, with costs potentially 10x lower than Uber. These remain long-duration narratives; near-term validation depends on regulation, city expansion, and unit economics.
"Robotaxis deployed in 3 states, and will reach 12 by EOY."
Uber
Uber was framed in the Robotaxi report as a potential displacement target. Uber handles about 14 million rides per day in the U.S. and generates $24 billion in annual revenue. If autonomous driving reduces costs to around 10%, the TAM could be reopened. The risk for Uber is that the market begins valuing it with a lower long-term take rate and higher competitive intensity.
Netflix, Traditional Telecom Operators
Netflix fell 1.55%, but the material was used more to explain pressure on traditional telecom operators. Telecom industry revenue growth is slowing, streaming media is being pressured by Netflix, and satellite internet is bringing new competition. The investment implication is that content platforms still have an advantage in user time spent, while traditional telecom and satellite networks are entering a more complex capex race.
Alibaba, Qwen On-Device Spillover
Alibaba’s Qwen 3.6 was cited by PrismML as an example of on-device compression, with a 27 billion-parameter model compressed from 54GB to below 4GB and running on an iPhone 17 Pro. Alibaba itself is not expanded upon within the main U.S.-listed platform theme, but this line shows that Chinese open-source models will affect the on-device AI cost curve for overseas platforms.
Software / SaaS
ServiceNow
ServiceNow rose 1.13%, but fund flows within software were divergent. Goldman Sachs lowered ServiceNow to $145 in its price-target read-throughs, while another investment bank preview said 2Q26 re-rating depends on whether AI contribution can improve the growth algorithm. The market needs to see GenAI’s contribution to net new ARR, RPO, and renewal rates.
"Key metrics to watch: ARR growth, RPO, retention, free cash flow, margins, and valuation discipline."
Salesforce
Salesforce fell 2.45%. The decliners-list event showed that partners are only just beginning to turn Agentforce POCs into pipeline deals. In the CIO survey, IBM, ServiceNow, Dell Technologies, and Cisco were all listed as suppliers that could be cut to fund AI investment. Salesforce needs to prove that Agentforce can move from demos to contracts.
Snowflake, MongoDB, Datadog
Data platforms and observability remain supported by AI workloads. Snowflake rose 2.09% and is up 11.32% over 20 days. Datadog rose 3.04% and is up 18.34% over 20 days. MongoDB fell 0.52%. Enterprise AI first requires data warehouses, governance, monitoring, and cost control. Earnings validation will depend on consumption revenue, RPO, and cloud workload intensity.
Cloudflare, Cybersecurity
The cybersecurity ETF rose 2.84% and is up 11.86% over 20 days, with a high RPS20 ranking. Citi’s CIO survey shows IT security as the No. 2 priority. AI security beneficiaries include CrowdStrike, Palo Alto, Microsoft, as well as Cloudflare, Akamai, and Fastly, which have WAF, DDoS, bot, and API security capabilities. Security is a necessary cost of AI deployment.
"Cybersecurity remains the strongest theme."
Palantir, AppLovin, Reddit
AI application stocks did not strengthen in sync. Palantir fell 2.42%, and AppLovin fell 0.15%. This indicates that capital is currently more willing to buy semiconductors and data center infrastructure, while becoming more selective on AI application stocks. Application stocks will need validation from paid conversion, customer expansion, and margins. The pricing power of the “AI label” is weakening.
DigitalOcean, Core AI Workloads
The material mentioned DigitalOcean’s focus on inference and agentic workloads, along with its AI platform, data center capacity expansion, and rising enterprise usage. The opportunity for small and mid-sized clouds and developer clouds lies in cheap and easy-to-use inference deployment close to developers. The risk is competition with hyperscalers, CoreWeave, and open-source inference stacks.
Consumer Electronics / Smart Vehicles
Apple Supply Chain
Memory price increases have already passed through to consumer electronics. According to reports, the iPhone 18 Pro Max 1TB BOM could rise by as much as USD 300 due to higher DRAM and NAND prices, with the memory cost for the 12GB configuration tripling. If Apple passes on costs through tiered pricing, high-end handset ASP can hold; if demand weakens, supply-chain margins will be squeezed.
Qualcomm, On-Device AI
Qualcomm rose 2.52%, with edge AI and mobile SoCs still supported by the narrative. Compressed on-device large models, local inference on smartphones, and AI PCs all require stronger NPU/CPU/GPU combinations. There are no new orders in the near-term materials; follow-up indicators are adoption in Android flagship phones, AI PC shipments, and disclosures on data-center AI accelerators.
Tesla Robotics
Tesla’s long-term incremental opportunity is expanding from autos to robotics. Supply-chain sources indicate that if Optimus Gen 3 enters mass production by the end of 2026, it could become a variable for the U.S.-side supply chain. Separately, 1X released a video of humanoid robot hands, while China ships roughly 90% of global humanoid robots. The investment implication is that hardware, actuators, sensors, batteries, and edge inference chips will attract attention first.
"China is shipping ~90% of the world's humanoid robots."
Mobileye, Aurora, Aptiv
Smart-driving materials are centered on Robotaxi, with no new earnings or target prices provided for these companies. The sector needs to return to verifiable numbers: number of commercialized cities, orders per vehicle per day, intervention rate, and insurance and maintenance costs. Without these metrics, autonomous driving remains a theme with high valuation elasticity but slow cash-flow validation.
SpaceX / Starlink
The space value chain has two clues: first, SpaceX launched 1,589 Starlink satellites in 1H26, potentially exceeding the full-year record for 2025; second, Raymond James initiated coverage with a Strong Buy rating and USD 800 target price, implying 440% upside. The company is not listed; this is used here to illustrate the financing intensity behind satellite internet and AI infrastructure.
Rocket Lab and Satellite Services
The Rocket Lab theme is “following in SpaceX’s footsteps,” but current materials do not add new hard financial figures to the core thesis. The key issues for the satellite sector remain launch cadence, backlog, satellite-manufacturing gross margin, and the mix of government versus commercial customers. If Starlink deployment continues to accelerate, small-launch and satellite-service chains will benefit from sentiment spillover.
Investment Bank Target Price Changes in the Past 12 Hours
Jensen Huang Select Portfolio
404K SEMI-AI Tech Morning Brief 2026-07-10 — Meta Compute Expansion, Storage Chain Re-Rating, Semiconductor Equipment Capacity Buildout
目录
Post-Market Summary
U.S. Stocks at New Highs
Top 10 U.S. Stocks by Trading Value
U.S. Stock Gainers
U.S. Stock Decliners
AI/Semiconductor Full Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Wafer Foundry and Advanced Packaging
Semiconductor Equipment/Testing
PCB/Substrates/Optical Communications/Power
Internet / Platforms
Software / SaaS
Consumer Electronics / Smart Vehicles
Investment Bank Target Price Changes in the Past 12 Hours
Jensen Huang Select Portfolio
The marginal change in the AI trade is shifting from “who has the strongest model” to “who can absorb the power, storage, packaging, networking, and cash flow requirements.” Last night, semiconductors, cloud computing, and optical communications all strengthened, while software/SaaS diverged. The market is starting to price AI capex as a longer supply chain.
Post-Market Summary
U.S. equities continued to lean toward technology growth at the 2026-07-09 close. The S&P; 500 rose 0.81%, the Nasdaq 100 rose 1.66%, and the Russell 2000 rose 1.32%; the technology ETF rose 2.18%, the semiconductor ETF rose 2.78%, and the equal-weight semiconductor reference rose 3.50%. The key driver was AI capex pulling capital back into semiconductors, memory, equipment, and data-center infrastructure.
By theme, the cloud computing ETF rose 2.16%, cybersecurity rose 2.84%, software rose 1.29%, and AI & big data rose 2.01%. The robotics and AI ETF rose 1.78%, but its 20-day RPS remains lagging, indicating that capital is still prioritizing “AI infrastructure picks-and-shovels” while staying selective on longer-dated robotics applications. The VIX fell 6.51%, leaving room for a rebound in high-beta technology stocks.
At the single-stock level, the semiconductor chain outperformed the M7. Micron rose 4.36%, SanDisk rose 6.24%, Western Digital rose 4.91%, Broadcom rose 3.20%, Advanced Micro Devices rose 5.62%, and ARM rose 9.68%. Cloud vendors diverged: Meta rose 4.50%, Amazon rose 1.40%, Microsoft rose only 0.12%, and Google fell 0.84%; the market is willing to pay for compute and supply-chain bottlenecks, but is still scrutinizing the pace of returns on cloud capex.
U.S. Stocks at New Highs
Top 10 U.S. Stocks by Trading Value
U.S. Stock Gainers
U.S. Stock Decliners
AI/Semiconductor Full Value Chain
AI Models/Applications and Capital Expenditure
OpenAI
1. OpenAI’s incremental value lies in the application entry point, not in a single model’s parameter count. ChatGPT Work has been rolled out to 100% of Pro users, and nearly 100% of internal employees use it regularly; GPT-5.6 Sol is described as covering coding, complex context, strategy tasks, and website building.
2. The GPT-Live API has begun recruiting design partners, indicating that real-time interactive AI is moving from demos into the developer ecosystem. The validation points are public pricing, SDKs, customer cases, and call volume; social-media benchmarks have limited reference value.
“ChatGPT Work is now rolled out to 100% of our Pro users.”
Claude
Claude-related signals more clearly reflect its competitive model positioning. Multiple reports compare Claude with GPT-5.6, Grok 4.5, and Meta Muse Spark within the same framework, emphasizing that frontier-model competition continues to intensify. The supply-chain implication is that training and inference demand remains strong, but the current materials do not provide cloud-contract or GPU-procurement figures, so orders cannot be directly extrapolated.
Meta Model API
1. Meta launched Muse Spark 1.1, a paid developer model. API pricing is roughly 25% of comparable models from OpenAI and Claude, and it supports a 1 million-token context window, multi-agent orchestration, tool use, and multimodal understanding.
2. A low-price strategy will pressure model-pricing expectations, but if it expands developer usage, it could instead increase demand for inference, storage, networking, and power.
“API pricing is roughly 25% of the cost advertised by other top models.”
Frontier-Model Competition
GPT-5.6, Grok 4.5, Meta Muse Spark, and Chinese models all appear in the materials at the same time. The market focus has shifted from “who is ahead” to “who has the lowest unit task cost and who can absorb workflows.” This will push revenue validation away from model launch events and toward API usage, enterprise seats, agent success rates, and cloud inference costs.
Enterprise AI Budgets
Citi’s CIO survey shows that expected global IT budget growth over the next 12 months rose from 2.6% to 3.3%. AI accounts for about 6.5% of IT budgets, and CIOs expect AI spending to increase by about 10% over the next 12 months. 69% of AI funding still comes from incremental budgets, but traditional BI, consulting, front-office, and back-office projects have already begun to be crowded out.
“Overall forward IT budget growth expectations rose to +3.3% from +2.6%.”
CSP/Cloud Capital Expenditure
Meta
1. Meta was last night’s main AI infrastructure theme. Multiple materials point to compute-infrastructure plans of 7GW in 2026 and 14GW in 2027. Its in-house Iris AI chip is expected to enter production in September 2026, with Broadcom participating in design and TSMC manufacturing it.
2. Meta also signed long-term agreements with Samsung Electronics, SanDisk, and Sumitomo Electric covering memory, flash storage, and optical-fiber equipment. The risk is that if 14GW is realized, financing, depreciation, and free-cash-flow pressure will rise in parallel.
“Meta plans 7 GW of AI computing capacity in 2026 and 14 GW in 2027.”
Amazon, Google, Microsoft, Oracle
Large technology companies are using debt to extend the runway for AI infrastructure. Amazon, Google, Nvidia, Meta, Oracle, and SpaceX have issued $182 billion of investment-grade bonds so far in 2026, up 1,300% from about $13 billion in the same period of 2025. This shows that AI capex has moved from a cash-flow issue to a credit-market issue.
Google
Google’s main thread is TPU and cloud workloads. Reports say Claude has proven the feasibility of training models on TPUs, and TPUs continue to gain share beyond Google’s internal workloads. However, Google’s share price fell 0.84% that day, as the market still applies a discount to advertising, AI disclosure, and cloud capital returns. The next points to watch are Google Cloud growth and external TPU customers.
Microsoft
Microsoft’s near-term issue is that incremental AI budgets are beginning to squeeze traditional software seats. In the CIO survey, Microsoft was the vendor most likely to see increased AI spending, with 50 votes; but it was also included in discussions about systems that could be replaced by enterprises’ in-house development. Azure and Copilot need to use RPO, cloud growth, and customer renewals to prove that AI can drive net incremental budgets.
Apple
Apple’s new high comes from expectations around on-device AI and chip partnerships. Market reports say PrismML can compress Alibaba’s 27 billion-parameter Qwen 3.6 model from 54GB to below 4GB and run it locally on the iPhone 17 Pro. At the same time, Apple’s cooperation with Broadcom has been extended to 2031, with plans to produce more than 15 billion U.S.-made chips. If on-device AI is validated, it would change assumptions about cloud inference growth.
AI Cloud/Data-Center Operators
CoreWeave, Nebius, IREN
New cloud deals are recovering from fears of “compute oversupply.” Meta is exploring compute leasing while also planning to push deployment scale to 14GW, weakening the oversupply narrative. CoreWeave’s contracted backlog is cited in the materials at $99 billion, while Nebius has more than $50 billion of agreements with customers including Meta and Microsoft. Near term, watch leasing prices and customer concentration.
TeraWulf, Applied Digital, Galaxy Digital, Cipher Mining
This group of compute and power assets is meaningful only when customers, capacity, power, and financing are disclosed together. The current materials place them on the neocloud rebound list, but hard evidence remains concentrated in Meta capex, CoreWeave/Nebius contracts, and IREN trading sentiment. Next, watch MW/GW deployment, lease-contract duration, and electricity prices.
GPU/CPU/ASIC
Nvidia
1. Nvidia fell 0.66% in the near term, but the AI GPU demand narrative has not weakened. TD Cowen maintained Buy with a $275 target price, and Citi maintained Buy with a $300 target price. Wells Fargo estimates potential H200 sales into China of about 200,000 units, worth $6 billion-$8 billion.
2. Rubin/Vera signals continue to strengthen. Reports say Vera CPU has a revenue opportunity of about $20 billion by the end of this fiscal year; Vera delivers a 50% IPC improvement over Grace, and sustained per-core performance for agent tasks is 1.8x that of x86.
“Rubin Ultra roadmap and Computex NVLink domains are fully intact.”
Broadcom
Broadcom rose 3.20%, benefiting from Meta Iris, custom ASICs, and cooperation with Apple. Iris is designed with Broadcom participation and manufactured by TSMC; the Apple partnership has been extended to 2031 and involves the manufacture of more than 15 billion U.S. chips. The debate around Broadcom is whether ASIC growth can continue to offset cyclical volatility in general semiconductors. Next, watch customer concentration and the cadence of TPU/AI XPU.
AMD
Advanced Micro Devices rose 5.62%, as the market bought back into the MI450/MI455, Venice CPU, and CoWoS supply story. The materials clarify that 240,000 CoWoS units in 2027 cannot be directly equated with GPU shipments. MI455 targets about 1 million units, Meta’s customized half-size MI450 version targets 500,000 units, and Venice CPU has potential volume of 5.7 million-6.0 million units in 2027. The bottlenecks are packaging, HBM, and substrates.
ARM
ARM rose 9.68%, among the strongest gainers. The materials do not provide new earnings or target prices, but frontier models, Vera CPU, agentic AI, and on-device inference all reinforce the long-term narrative for CPU IP. Near term, investors should be alert to high valuation elasticity and slow earnings confirmation. The real validation points are data-center CPU share, royalty rates, and adoption of in-house chips by large customers.
Cerebras
Cerebras and Flex expanded their California manufacturing partnership, targeting an approximately 7x increase in CS-3 AI system output by 2026, with new production lines, testing infrastructure, and high-skill jobs. This reflects the broadening demand from model developers, cloud providers, and enterprises for different forms of AI systems.
HBM/DRAM/NAND/SSD/HDD
Micron
1. Micron rose 4.36% and ranked first by trading value. The company increased its planned U.S. investment through 2035 to more than $250 billion, targeting about 40% of DRAM production in the United States. It also announced up to $3 billion of supply-chain investment, including $500 million to support GlobalWafers’ Texas 300mm silicon-wafer plant, with a 10-year supply agreement.
2. Memory sales reached $74.6 billion, up 31.7% sequentially, including $48.0 billion of DRAM and $25.8 billion of NAND. UBS expects DDR contract prices to rise 32%/18% in Q3/Q4 2026, and NAND to rise 30%/12%.
“DRAM market remaining structurally undersupplied through at least Q2 2028.”
SK Hynix
SK Hynix’s U.S. ADR was priced at $149, with demand close to $200 billion; the top 25 accounts received about 67% of the allocation. The materials cite two HBM share figures, 58% and 64%, but both point to the same conclusion: overseas capital wants direct exposure to HBM assets. The risk is that amid a strong cycle, both valuation and supply expansion are accelerating.
SanDisk
SanDisk rose 6.24%, ranking higher among gainers. Reports indicate Meta signed a multi-year flash-storage agreement with SanDisk. SanDisk had previously disclosed a multi-year agreement with minimum contracted revenue of about $42 billion; fiscal Q3 revenue nearly doubled to $5.95 billion, and non-GAAP gross margin reached 78.4%. Meta and SanDisk have not confirmed the financial terms. Next, watch contract disclosure and NAND pricing.
“Customer affordability and sustainability of AI-related capital expenditure are still the key risks.”
Samsung Electronics
Samsung Electronics’ main thread is DRAM, HBM, and the domestic supply chain. According to reports, the U.S. Commerce Secretary urged Samsung Electronics and SK Hynix to expand U.S. memory capacity. Samsung Electronics also expanded annual support by about 1,000 graphics wafers and is sharing process data with materials, components, and equipment partners. If HBM and advanced DRAM demand remains strong, Samsung Electronics’ key variables are yield and customer qualification.
Western Digital, Seagate Technology
Western Digital rose 4.91%, and Seagate Technology rose 3.50%. HDDs and enterprise drives continue to be supported by AI data-center storage demand. The current materials do not provide new orders or target prices, but the gains come from the same logic: training data, model checkpoints, inference logs, and cold-data storage are all amplifying enterprise-drive demand. The risk is that NAND and HDD cycles may be out of sync.
Wafer Foundry and Advanced Packaging
TSMC
TSMC ADR rose 0.11%, but the industry information was stronger. Reports say CoWoS capacity is planned to expand to 2 million units in 2027, while demand is still growing faster than capacity expansion. Nvidia occupies the majority of CoWoS share, and allocation for AMD and AWS Trainium is tighter. Another equipment framework mentions TSMC capex reaching $100 billion in 2028. The validation points are monthly CoWoS capacity, advanced-node price increases, and customer queues.
Samsung Foundry, Intel Foundry
The difficulty of Samsung Electronics and Intel catching up in foundry is being discussed within the cycles of equipment, yield, capacity, and ecosystem. The signal that Samsung Electronics is raising prices by 15% for 4/5nm and automotive 8nm indicates advanced-node pricing power is shifting toward suppliers. Intel rose 2.17%, but entering foundry season still requires monitoring customers, yield, and advanced-node wafer starts, not just CPU sentiment.
ASE Technology Holding, Amkor, Advanced Packaging and Testing
OSAT stocks followed the heating-up of advanced packaging. Amkor rose 7.85%, and ASE Technology Holding ADR rose 8.31%. ASE-related materials mention earnings continuing to beat expectations, TSMC advancing CoWoS plans, and CPU-driven upside in FOCoS. The business issue for the OSAT chain is straightforward: the larger AI chips become and the more complex packaging gets, the firms with capacity and yield can raise prices.
Semiconductor Equipment/Testing
Applied Materials
Applied Materials rose 3.80%. Deutsche Bank raised its WFE forecasts to $145 billion in 2026, $193 billion in 2027, and $220 billion in 2028. Applied Materials remains its top pick, with the target price raised from $550 to $680; Mizuho also raised its target price from $540 to $650. Its key variables are the durability of DRAM, foundry, and advanced-packaging capital expenditure.
“WFE forecast is $145 billion in 2026, $193 billion in 2027, and $220 billion in 2028.”
Lam Research
Lam Research rose 6.56%. Deutsche Bank maintained Buy and raised its target price from $325 to $385; Mizuho raised its target price from $380 to $400. Under the GAA transition, Lam estimates that every additional 100,000 wafers per month of wafer-start capacity adds about $1 billion to its serviceable market, with clearer leverage in etch, deposition, and cleaning.
KLA
KLA rose 4.15%. Morgan Stanley upgraded it to Buy, and TD Cowen raised its target price to $260. Deutsche Bank still rates it Hold, raising its target price from $175 to $220, because process control has less leverage to capacity-driven expansion than Applied Materials and Lam Research. The debate is whether WFE upside can benefit inspection/metrology to the same degree.
ASML
ASML rose 2.01%. Reports say EUV revenue over the past three quarters was EUR2.1 billion, EUR3.6 billion, and EUR4.1 billion. TD Cowen’s framework also gives EUV shipments of 88 units in 2027 and 110 units in 2028. Advanced nodes, HBM, and ASIC are all pushing lithography demand higher, but ASML remains affected in the near term by delivery cadence and 2027 order visibility.
Advantest, Onto Innovation, FormFactor
The test and metrology chain strengthened in tandem. Advantest ADR rose 5.38%, Onto rose 8.77%, and FormFactor rose 7.03%. The materials mention that silicon photonics, HBM, CPU, and advanced packaging have different testing requirements, and testing could become the next-stage bottleneck. The validation points for this line are order visibility and gross margin; one-day gains only indicate trading sentiment.
PCB/Substrates/Optical Communications/Power
ABF/PCB/CCL
The logic for AI board-material price increases continues to strengthen. Goldman Sachs said ABF supply and demand should remain favorable for at least the next 18-24 months, and AI IC substrate TAM is expected to grow at a 66% CAGR from 2025 to 2028. The materials also say Low-DK Gen2 glass-fiber cloth will face a 60%+ supply gap in 2H 2026, T-glass a 50%+ gap extending into 2028, and IC substrates a 40%+ gap in 2027.
“IC Substrates: Fully Sold Out Through 2027.”
Lumentum, Coherent, AAOI
The rally in optical communications is driven by AI data centers shifting from copper cables to fiber. Lumentum rose 10.59%; fiscal 2026 Q3 revenue was $808.4 million, with components revenue up 77% to $533.3 million and systems revenue up 121% to $275.1 million. Current-quarter revenue guidance is $960 million to $1.0 billion. Management said the main constraint is on the supply side.
Nokia
Nokia ADR rose 9.44%. According to reports, Nokia is expanding photonics capacity in Pennsylvania by 10x, with part of the capacity to come online before Q3 2026. New AI and cloud orders reached EUR 1.0 billion, and optical business growth guidance is 18%-20%. The bottleneck is in packaging and testing, indicating that optical networking equipment is also starting to benefit from AI cluster interconnect demand.
Corning, Sumitomo Electric, Furukawa Electric, Fujikura
Meta’s long-term agreements have pushed fiber-optic cables back to the forefront. Sumitomo Electric was specifically named as signing a long-term fiber supply agreement. Corning rose 4.70% in the U.S. technology equity pool. Japanese fiber-optic cable names remain supported by AI data centers and cross-campus clusters. Key tracking points are fiber preforms, optical cable lead times, and data center interconnect orders.
Power Semiconductors and Power Supplies
AI rack power is turning 800V HVDC, GaN/SiC, and power modules into critical links. A Rubin-generation Kyber rack can reach 1MW per cabinet, while 800V can reduce copper usage by up to 45%. Navitas demonstrated a 20kW power board that can step 800V down to 6V in one stage, with peak efficiency of 97.5%. Wolfspeed has sued Navitas; the risk is patents, while the opportunity is high-voltage step-down conversion.
“Navitas’ 20kW power board can step 800V down to 6V in one stage, with peak efficiency of 97.5%.”
Internet / Platforms
Meta
Meta rose 4.50%. It is both a platform stock and an AI infrastructure buyer. The paid Muse Spark 1.1 API pushes AI monetization toward developers, while 7GW/14GW pulls the supply chain toward storage, fiber, and ASICs. The market is simultaneously rewarding AI offense and questioning financing pressure. Next, watch ad growth, API revenue, and capex guidance.
“AI infrastructure spending this year could reach up to $145 billion.”
Amazon
Amazon rose 1.40%. In the CIO survey, Amazon was the second-largest beneficiary supplier from increased AI spending, receiving 12 votes. AWS is also linked to Trainium and cloud inference demand. The risk is that after hyperscalers stop buybacks and shift toward buying chips, near-term margins and free cash flow are compressed. AWS revenue acceleration is needed to prove the return on investment.
Google
Google fell 0.84%, with advertising, externalization of TPUs, and model competition all weighing on valuation. AI advertising disclosures have expanded to Search, YouTube, and Discover, indicating rising regulatory and user-transparency costs. If TPUs continue to win training workloads from external frontier labs, that would improve returns on cloud capex.
Apple
Apple rose 0.83%, reaching an all-time high. On-device AI compression technology and the Broadcom partnership point to two lines of development: local models may reduce dependence on cloud inference, while on-device AI still requires ASICs, advanced process nodes, and storage upgrades. If DRAM/NAND price increases continue, high-end iPhone BOM and pricing strategy will become core variables for the consumer electronics sector.
Tesla
Tesla rose 3.21%. UBS raised its price target from $364 to $442, citing the long-term potential of physical AI and robotics. Robotaxi materials said deployments have already occurred in three states and could reach 12 states by year-end, with costs potentially 10x lower than Uber. These remain long-duration narratives; near-term validation depends on regulation, city expansion, and unit economics.
“Robotaxis deployed in 3 states, and will reach 12 by EOY.”
Uber
Uber was framed in the Robotaxi report as a potential displacement target. Uber handles about 14 million rides per day in the U.S. and generates $24 billion in annual revenue. If autonomous driving reduces costs to around 10%, the TAM could be reopened. The risk for Uber is that the market begins valuing it with a lower long-term take rate and higher competitive intensity.
Netflix, Traditional Telecom Operators
Netflix fell 1.55%, but the material was used more to explain pressure on traditional telecom operators. Telecom industry revenue growth is slowing, streaming media is being pressured by Netflix, and satellite internet is bringing new competition. The investment implication is that content platforms still have an advantage in user time spent, while traditional telecom and satellite networks are entering a more complex capex race.
Alibaba, Qwen On-Device Spillover
Alibaba’s Qwen 3.6 was cited by PrismML as an example of on-device compression, with a 27 billion-parameter model compressed from 54GB to below 4GB and running on an iPhone 17 Pro. Alibaba itself is not expanded upon within the main U.S.-listed platform theme, but this line shows that Chinese open-source models will affect the on-device AI cost curve for overseas platforms.
Software / SaaS
ServiceNow
ServiceNow rose 1.13%, but fund flows within software were divergent. Goldman Sachs lowered ServiceNow to $145 in its price-target read-throughs, while another investment bank preview said 2Q26 re-rating depends on whether AI contribution can improve the growth algorithm. The market needs to see GenAI’s contribution to net new ARR, RPO, and renewal rates.
“Key metrics to watch: ARR growth, RPO, retention, free cash flow, margins, and valuation discipline.”
Salesforce
Salesforce fell 2.45%. The decliners-list event showed that partners are only just beginning to turn Agentforce POCs into pipeline deals. In the CIO survey, IBM, ServiceNow, Dell Technologies, and Cisco were all listed as suppliers that could be cut to fund AI investment. Salesforce needs to prove that Agentforce can move from demos to contracts.
Snowflake, MongoDB, Datadog
Data platforms and observability remain supported by AI workloads. Snowflake rose 2.09% and is up 11.32% over 20 days. Datadog rose 3.04% and is up 18.34% over 20 days. MongoDB fell 0.52%. Enterprise AI first requires data warehouses, governance, monitoring, and cost control. Earnings validation will depend on consumption revenue, RPO, and cloud workload intensity.
Cloudflare, Cybersecurity
The cybersecurity ETF rose 2.84% and is up 11.86% over 20 days, with a high RPS20 ranking. Citi’s CIO survey shows IT security as the No. 2 priority. AI security beneficiaries include CrowdStrike, Palo Alto, Microsoft, as well as Cloudflare, Akamai, and Fastly, which have WAF, DDoS, bot, and API security capabilities. Security is a necessary cost of AI deployment.
“Cybersecurity remains the strongest theme.”
Palantir, AppLovin, Reddit
AI application stocks did not strengthen in sync. Palantir fell 2.42%, and AppLovin fell 0.15%. This indicates that capital is currently more willing to buy semiconductors and data center infrastructure, while becoming more selective on AI application stocks. Application stocks will need validation from paid conversion, customer expansion, and margins. The pricing power of the “AI label” is weakening.
DigitalOcean, Core AI Workloads
The material mentioned DigitalOcean’s focus on inference and agentic workloads, along with its AI platform, data center capacity expansion, and rising enterprise usage. The opportunity for small and mid-sized clouds and developer clouds lies in cheap and easy-to-use inference deployment close to developers. The risk is competition with hyperscalers, CoreWeave, and open-source inference stacks.
Consumer Electronics / Smart Vehicles
Apple Supply Chain
Memory price increases have already passed through to consumer electronics. According to reports, the iPhone 18 Pro Max 1TB BOM could rise by as much as USD 300 due to higher DRAM and NAND prices, with the memory cost for the 12GB configuration tripling. If Apple passes on costs through tiered pricing, high-end handset ASP can hold; if demand weakens, supply-chain margins will be squeezed.
Qualcomm, On-Device AI
Qualcomm rose 2.52%, with edge AI and mobile SoCs still supported by the narrative. Compressed on-device large models, local inference on smartphones, and AI PCs all require stronger NPU/CPU/GPU combinations. There are no new orders in the near-term materials; follow-up indicators are adoption in Android flagship phones, AI PC shipments, and disclosures on data-center AI accelerators.
Tesla Robotics
Tesla’s long-term incremental opportunity is expanding from autos to robotics. Supply-chain sources indicate that if Optimus Gen 3 enters mass production by the end of 2026, it could become a variable for the U.S.-side supply chain. Separately, 1X released a video of humanoid robot hands, while China ships roughly 90% of global humanoid robots. The investment implication is that hardware, actuators, sensors, batteries, and edge inference chips will attract attention first.
“China is shipping ~90% of the world’s humanoid robots.”
Mobileye, Aurora, Aptiv
Smart-driving materials are centered on Robotaxi, with no new earnings or target prices provided for these companies. The sector needs to return to verifiable numbers: number of commercialized cities, orders per vehicle per day, intervention rate, and insurance and maintenance costs. Without these metrics, autonomous driving remains a theme with high valuation elasticity but slow cash-flow validation.
SpaceX / Starlink
The space value chain has two clues: first, SpaceX launched 1,589 Starlink satellites in 1H26, potentially exceeding the full-year record for 2025; second, Raymond James initiated coverage with a Strong Buy rating and USD 800 target price, implying 440% upside. The company is not listed; this is used here to illustrate the financing intensity behind satellite internet and AI infrastructure.
Rocket Lab and Satellite Services
The Rocket Lab theme is “following in SpaceX’s footsteps,” but current materials do not add new hard financial figures to the core thesis. The key issues for the satellite sector remain launch cadence, backlog, satellite-manufacturing gross margin, and the mix of government versus commercial customers. If Starlink deployment continues to accelerate, small-launch and satellite-service chains will benefit from sentiment spillover.
Investment Bank Target Price Changes in the Past 12 Hours
Jensen Huang Select Portfolio