
目录
After-Hours Summary
U.S. Stocks at New Highs
Three U.S. Stock Rankings
Full AI and Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
CSP and Cloud Capital Expenditure; AI Clouds
GPUs, CPUs, ASICs, and High-Speed Interconnects
Memory, Wafers, Packaging, and PCBs
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Jensen Huang’s Curated Portfolio
Memory Index Performance
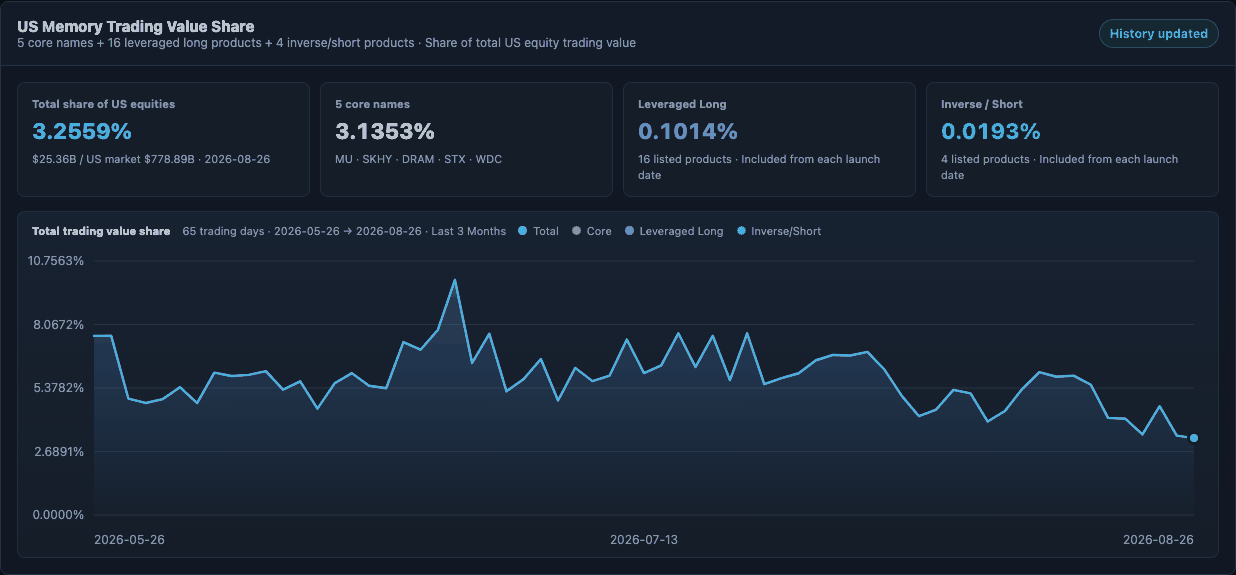
Memory’s Share of US Equity Trading Turnover
Overview
404K SEMI-AI | 2026-08-28
After-Hours Summary
The S&P; 500 rose 0.51%, the Nasdaq 100 gained 1.10%, and the equal-weighted S&P; 500 fell 0.32%, as megacap technology stocks continued to drive the broader market. Technology ETFs rose 2.77% and semiconductor ETFs gained 2.33%, while communication-services ETFs declined 0.72%. The clearest market signal was the return of capital to technology following Nvidia’s earnings.
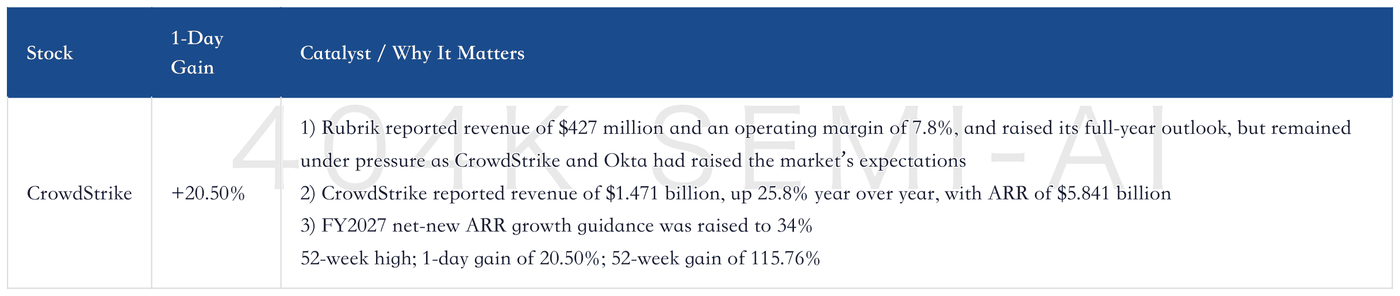
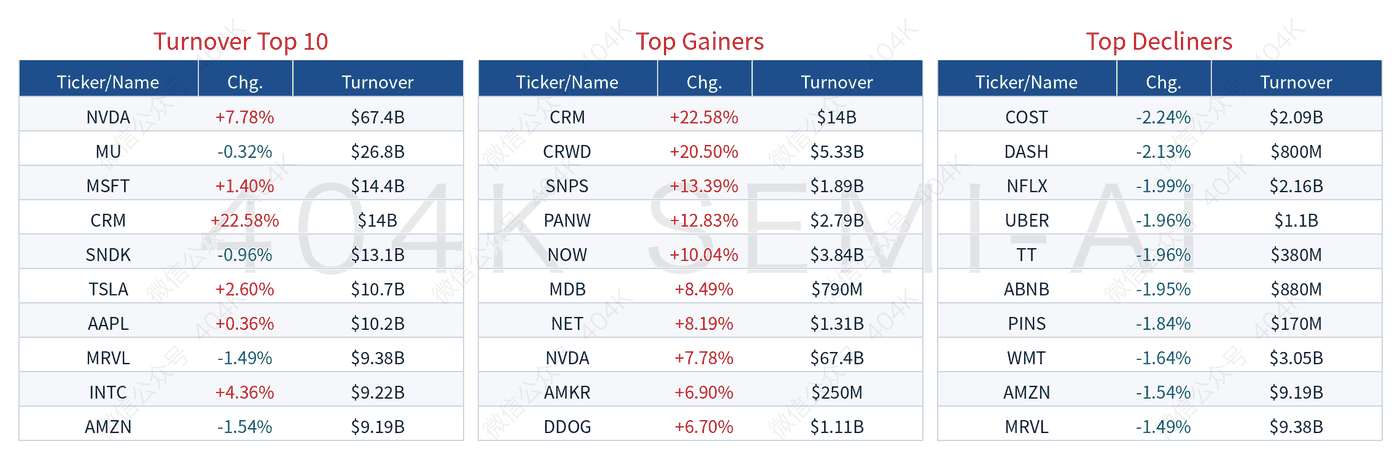
Single-stock dispersion was even more pronounced than the index moves. Nvidia rose 7.78%, Salesforce gained 22.58%, and CrowdStrike climbed 20.50%; Amazon, Meta, Google, and Netflix fell 1.54%, 0.80%, 0.36%, and 1.99%, respectively. Investors are again willing to pay for AI demand and software bookings, but remain selective on internet platforms and capital-intensive businesses.
Nvidia raised its FY2028 revenue-growth outlook to approximately 70%, temporarily easing concerns about demand and shifting the hurdle to execution. Procurement commitments, HBM, wafers, packaging, power, and customer financing are all scaling simultaneously. On the software side, cRPO, ARR, renewals, and margins must demonstrate that AI can generate real revenue rather than merely support a product narrative.
U.S. Stocks at New Highs
Three U.S. Stock Rankings
Full AI and Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
OpenAI
1) Its revenue run rate has increased from $13 billion last August to more than $40 billion, indicating that paid demand continues to expand.
2) Codex is testing a persistent-work mode that can create follow-up tasks across sessions, although there are no plans for an immediate release. The next tests are whether growth can remain strong against a higher base and whether long-running Agent tasks materially increase inference calls.
“OpenAI and Anthropic are growing as fast as, or faster than, virtually any companies of comparable scale in history.”
Anthropic
1) Its revenue run rate reportedly reached $65 billion at the end of July; the combined OpenAI and Anthropic run rate increased from $30 billion to $105 billion between the start of 2026 and August.
2) Its Vera Rubin lease with Nscale runs for 6 years, extending the contract duration from 4 years in the Hopper era.
3) Model Hardware Standard enables Claude to operate physical devices through a shared driver layer, expanding the commercial opportunity from software into laboratory hardware.
Frontier-model revenue: The generative-AI industry reached a deduplicated annualized run rate of approximately $175 billion in June 2026, with OpenAI and Anthropic accounting for most of the total. Further rapid growth may depend on coding Agents crossing a capability threshold, while the risk is that coding demand plateaus over the coming months. Quarterly revenue growth is a better test of paid utility than any single benchmark.
“Revenue—and the investment it supports—also feeds the compute flywheel: better AI generates more revenue, more revenue funds more compute, and more compute produces better AI.”
Agent applications: Agents turn a single task into many inference calls, shifting the relevant cost metric from cost per token to total cost per completed task. Even small changes in browsing order or memory can alter a shopping Agent’s preferences, requiring platforms to manage outcome stability, inference costs, and auditability simultaneously.
Inference architecture: Prefill is primarily compute-bound, while decode depends more heavily on memory bandwidth and the KV cache. Running a 70-billion-parameter FP16 model on an H100 requires reading approximately 140GB of weights per token; a 128K context can generate around 40GB of KV data. The bottleneck has not disappeared—it has shifted from weight movement to long contexts, batching, memory, and networking.
“The fact that AI inference was never a single workload has finally been etched into the hardware itself.”
CSP and Cloud Capital Expenditure; AI Clouds
Microsoft: New Azure AI backlog was slightly above $50 billion, all from customers other than OpenAI and Anthropic, indicating that enterprises and other model providers are also expanding capacity. Demand will continue to exceed supply this year; FY2027 capital expenditure is expected to grow year over year, with first-quarter capital expenditure exceeding $50 billion. M365 Copilot has more than 30 million paid seats.
Amazon
1) AWS has received its first Vera CPU server and Vera Rubin GPU. Vera features 88 custom cores and memory bandwidth of up to 1.2TB/s.
2) Annapurna Labs will be the first to work with NVHBM, while TRAINIUM4 will support NVLink Fusion. The relationship between proprietary XPUs and Nvidia’s rack-scale platform is shifting from substitution toward hybrid deployment.
IREN: Contracted ARR tied to 2026 capacity has reached $4 billion, of which approximately $1 billion is already operational, leaving capacity effectively sold out. Recent 3-year contracts generate more than $20 million per megawatt, with negotiated prices approaching $25 million and payback periods of approximately 2 years. Customer prepayments cover 45% to 55% of GPU capital expenditure, making the financing structure critical to the equity dilution required for expansion.
CoreWeave: Second-quarter revenue rose 115% year over year to $2.6 billion, but the company posted a quarterly loss of $626 million, incurred $985 million of interest expense in the first half, and carried $35.6 billion of debt. A 25% increase in service pricing can improve unit revenue, but also exposes the margin pressure embedded in legacy pricing. The real test is whether growth can outpace interest and refinancing costs.
“The key issue to validate is earnings quality: operating cash flow fell sequentially from $50.3 billion to $24.1 billion, accounts receivable rose to $63.1 billion, and DSO lengthened from 45 days to 60 days.”
Nebius: The company has contracted more than 2 GW of power, but only approximately 170 MW of early revenue-generating capacity, leaving a substantial gap between contracted power and actual deployment. Emerging cloud providers must control substations, power distribution, construction schedules, and their balance sheets—not merely secure GPUs. Key metrics are revenue per megawatt and the conversion rate from contract signing to energization.
Oracle: GPU utilization is close to 97.5%, demonstrating that operational capacity can be converted rapidly into revenue. Relative to Nebius and CoreWeave, Oracle benefits from high utilization and a mature balance sheet. The risk remains that grid connections, transformers, and power-distribution timelines delay new capacity, making GPU purchase volumes an insufficient standalone indicator.
AI data-center supply: North American demand is expected to reach approximately 35 GW in 2027, versus only 16.5 to 23.4 GW of deliverable supply, implying a gap of approximately 1.8 to 2.1 times. Grid interconnection waits can reach 4 to 5 years, while lead times for high-voltage transformers exceed 160 weeks. Power constraints accounted for 60% to 70% of megawatt-weighted delays over the past 12 months, and capital alone cannot compress these timelines quickly.
GPUs, CPUs, ASICs, and High-Speed Interconnects
Nvidia
1) Quarterly revenue reached $96.2 billion, up 106% year over year, including data-center revenue of $89.0 billion. The company’s FY2028 revenue-growth outlook is approximately 70%.
2) Purchase and supply commitments rose to $279.0 billion, primarily to secure HBM, while gross-margin guidance declined to 74.0%.
3) Relative to standard HBM4E, NVHBM can increase bandwidth by up to 30%, reduce power consumption by 15%, and free up as much as 25% of the XPU compute-die area. Demand has been validated; inventory, cash collection, and guarantee exposure are now the key quality metrics.
“Gross margin is expected to decline from 75% this quarter to 74% in F3Q, potentially bottom at 71% to 72% in F4Q, and stabilize at 72% to 73% in FY28, reflecting pricing pressure from HBM and other memory.”
Marvell Technology: Second-quarter revenue was $2.74 billion, up 37% year over year, including data-center revenue of $2.17 billion, up 46%. Third-quarter revenue guidance of $3.15 billion exceeded the $3.03 billion consensus. Adjusted gross margin was 58.9%, down 50 basis points year over year, indicating that AI bookings remain strong while product mix and costs continue to constrain margins.
Groq: Nvidia’s approximately $17 billion non-exclusive licensing transaction with Groq pairs GPUs for prefill with SRAM-based LPUs for decode. An LPX rack contains 256 LP30 chips, 128GB of SRAM, and 12TB of DDR5. The vendor claims throughput per megawatt can reach up to 35 times that of GB200 under specific conditions, although GPUs retain an advantage for large batches and workloads with looser latency requirements.
AMD: Cerebras, Nvidia, and Groq are all pursuing workload-specific disaggregation of inference. AMD’s Venice server CPU provides a test of CPU-side growth, while the GPU-side test is task-level cost when operating alongside specialized SRAM architectures. If unified engines prove more effective in scheduling and fault recovery, the benefits of heterogeneous architectures may be lower than currently expected.
Lumentum: Management reported a substantial increase in backlog and set a target for earnings power of more than $40 per share in FY2028, versus $8.67 in FY2026 and the current sell-side estimate of approximately $33. OCS revenue is expected to exceed $100 million next quarter, while the NPO timeline has moved forward to late 2027 or early 2028. Laser qualification and lead times for substrates and equipment remain the key volume-production constraints.
Arista: AI back-end networks, campuses, and core data centers are jointly driving networking demand, with scale-across already accounting for approximately one-third of AI revenue. Investors must distinguish between cross-rack networking and within-rack scale-up, which have different chip, optical-interconnect, and software economics. The next test is whether scale-up can reach meaningful scale in 2027.
Memory, Wafers, Packaging, and PCBs
SK hynix
1) HBM is expected to account for more than 50% of revenue in 2027, 2028, and beyond—a higher share than at Micron and Samsung Electronics.
2) The company has broken ground on a $4 billion packaging facility in Indiana, with mass production of next-generation HBM planned for the second half of 2029; wafers will continue to be produced in South Korea.
3) Management expects strong demand to persist through the end of 2030, although additional investment will depend on incentives, operating conditions, and customer collaboration.
HBM industry: Bank of America expects the market to grow from approximately $77 billion in 2026 to approximately $280 billion in 2030, representing a compound annual growth rate of roughly 38%. HBM4E’s wafer-displacement ratio versus conventional DRAM could rise to 4 times. Value is being created simultaneously through bandwidth, logic base dies, and stacking yields, further crowding out conventional DRAM supply.
Kioxia: The company plans to build a new memory facility in Iwate Prefecture, targeting mass production in FY2029. Together with its Mie Prefecture facility, total investment over the next 6 years will reach ¥5 trillion. The order and expansion trajectory is clear, but new capacity remains years from operation; returns will depend on NAND pricing, demand for high-speed AI storage, and actual utilization.
TSMC: Advanced-packaging projects generated virtually no business from 2011 until around 2020; AI demand finally made heterogeneous integration a critical capacity requirement. TSMC rose 2.30%, as advanced packaging shifted from a long-term R&D; project into a mass-production bottleneck for GPUs, HBM, and networking chips. The next tests are CoWoS capacity expansion and yields on new architectures.
PCB materials: At 10GHz, PTFE has a dielectric constant of approximately 2.1 and dielectric loss of approximately 0.0003, enabling longer high-speed copper interconnects. However, drilling, hole-wall quality, dimensional stability, and repeated lamination have yet to achieve stable mass production. Rubin Ultra may use a hybrid structure combining a PTFE core with M9 prepreg, or may shift to M10, which remains at an early sampling stage.
“The key issue is not whether PTFE can deliver low loss, but whether it can be processed into qualified PCBs consistently, repeatedly, and at scale.”
Memory hierarchy: Rubin uses 288GB of HBM4 for training, prefill, and large batches; LP30 uses 500MB of SRAM for low-latency decode; and Crescent Island emphasizes capacity economics with up to 480GB of LPDDR. Value is spreading beyond the standalone GPU into memory tiers, packaging, rack-level networking, and scheduling software.
Internet/Platforms
Meta
1) Hatch Agent reportedly runs continuously in the background and connects to email, calendars, and consumer apps; pricing as high as $200 per month was considered.
2) Meta’s annual spending on Anthropic may at one point have reached $10 billion and remains several hundred million dollars per month. External procurement is proceeding alongside in-house initiatives such as Muse Code and Watermelon. Shares fell 0.80% as the market continues to assess product execution and the returns on heavy spending.
“Overall market volume was quite light, making it difficult to read too much into the price action.”
Netflix: One model generates “Because You Watched” recommendation copy, while another scores it, with humans reviewing drift weekly. During a 5-week test, members shifted slightly toward unwatched content and more often ended browsing by starting playback. Shares fell 1.99%; the key metric is whether better recommendation explanations consistently improve viewing conversion.
“A judge running in production has a lifecycle and must be maintained like any other model.”
Google: Shares fell 0.36% but gained 2.13% over 20 days. TPU 8i represents an inference architecture optimized for Google’s own workloads. The platform’s value depends on whether its models, chips, and cloud services can jointly reduce per-task costs; if customers increasingly favor multi-vendor deployments, the lock-in power of a single architecture will decline.
Amazon: Shares fell 1.54% but gained 8.83% over 20 days. AWS’s adoption of Vera Rubin and integration of TRAINIUM4 with NVLink Fusion indicate that proprietary chips and Nvidia’s platform will coexist over the long term. Near-term momentum in the internet business remains weak, while cloud capacity delivery will depend on power availability, utilization, and customer contracts.
Shopify: Shares rose 2.69% and gained 26.09% over 20 days, making Shopify one of the few platform stocks maintaining strong momentum. The rally did not extend to most advertising and local-services platforms, suggesting investors still favor companies with clearer growth trajectories. Sustainability must next be validated by GMV, merchant services, and margins.
Reddit: Shares fell 0.91% and declined 13.53% over 20 days, with the near-term recovery clearly lagging Shopify and leading software names. Both AI data licensing and advertising must demonstrate growth quality. Without new operating data, relative price performance signals market disagreement but cannot substitute for revenue and user metrics.
Uber: Shares fell 1.96% but gained 9.35% over 20 days. Avride has completed 100,000 autonomous trips through Uber in Dallas, still with safety operators onboard, and targets fully driverless operations in the first half of 2027. Whether the platform can convert autonomy into lower fulfillment costs will depend on fleet scale, intervention rates, and commercial miles.
“A safety operator remains in the seat in this footage, but fully driverless operations are expected in the first half of 2027.”
DoorDash: Shares fell 2.13% but gained 17.39% over 20 days. Medium-term strength alongside a daily pullback shows that local-services platforms did not participate in the broad AI and software rally. Attention should return to order frequency, per-order fulfillment profit, and automation investment rather than inferring demand changes from one day’s share-price move.
Airbnb: Shares fell 1.95% but gained 21.25% over 20 days, broadly mirroring DoorDash. Travel platforms faced near-term pressure from sector rotation, but the 20-day trend remains strong. Booking growth, average nightly rates, and margins are the relevant testable variables; current data are insufficient to interpret the pullback as fundamental deterioration.
Pinterest: Shares fell 1.84% and declined 6.34% over 20 days, underperforming among advertising platforms. Research on agentic shopping shows that small changes in page-view order and memory can materially alter AI preferences. Platforms will need both to compete for user attention and to accommodate machine agents whose purchasing paths cannot be predicted reliably.
“Even small differences—page-view order and memory—change AI preferences in unpredictable ways.”
Snap: Shares fell 1.66% but gained 13.65% over 20 days. Near-term performance has been stronger than Pinterest and Trade Desk, although there is no new operating anchor. A recovery must still be demonstrated through advertising pricing, user engagement, and augmented-reality monetization, rather than platform-sector rotation alone.
AppLovin: Shares rose 1.47% but declined 22.59% over 20 days, marking a one-day rebound within a still-weak medium-term trend. The advertising-algorithm company must reverse that trend through improved advertiser returns and renewed platform-revenue growth. If AI tools only improve bidding efficiency without expanding budgets, valuation recovery will remain constrained.
Trade Desk: Shares rose 2.99% but declined 26.59% over 20 days, the clearest oversold rebound among internet platforms. Whether programmatic-advertising demand has bottomed still requires validation from subsequent revenue and customer retention; the daily gain does not erase the stock’s relative weakness over the past 20 days.
Spotify: Advertising showed no signs of accelerating in the second half, leaving the platform still needing to demonstrate that user scale can translate into greater ad monetization. As capital rotates from internet stocks toward software and Nvidia, companies lacking an advertising inflection are more vulnerable. The next key indicator is ad growth, not any single product launch.
“Meta is using Anthropic models to help support and test its forthcoming personal AI agent, Hatch, while developing competing products internally.”
Agentic Shopping: Research shows that differences in page order and memory are sufficient to produce unpredictable agent choices, potentially undermining traditional human-oriented attribution and marketing methods. Platforms will need machine-readable product information, authorization controls, and outcome audits; commercial value will depend on converting unstable choices into controllable conversions.
Software/SaaS
Salesforce
1) Revenue was $11.345 billion, up 10.8% year over year; excluding Informatica, organic growth was approximately 6.4% to 7%. cRPO reached $33.5 billion, up 14% in constant currency.
2) Agentforce ARR exceeded $1.5 billion, up 240% year over year, with renewals and expansions accounting for roughly half of AI bookings.
3) Claudeforce offers 37 prebuilt sales skills, with public beta planned for September. As Claude takes over the interaction layer, Salesforce must defend revenue through data, permissions, workflows, and headless APIs.
“The core improvement in CRM came from high-quality bookings rather than current-period revenue: revenue reached $11.345 billion, up 10.8% year over year, but organic growth excluding Informatica was only approximately 6.4% to 7%.”
CrowdStrike: Revenue was $1.471 billion, up 25.8% year over year; ARR reached $5.841 billion, with net new ARR of $332 million. Fiscal 2027 guidance for net new ARR growth was raised to 34%. Flex ARR reached $2.29 billion, up 101% year over year, and AIDR nearly doubled quarter over quarter, although endpoint security still accounted for approximately 90% of the growth improvement.
“AI is initially supporting bookings indirectly through identity modernization and platform consolidation, with material revenue potentially emerging only after FY28. Counterevidence includes DBNRR of just 107%, a mature core access-management market, and competition from Microsoft’s bundling.”
Okta
1) Revenue was $805 million, up 10.6% year over year; cRPO grew 14.1%, and adjusted operating margin was 28.1%.
2) New products contributed approximately 30% of bookings, while deals incorporating new products were approximately 40% larger. One customer expanded from roughly 50 Claude Agents to 1,500 within several weeks.
3) Jefferies raised its price target to $200, but direct AI revenue remains small. The key test is whether cRPO can continue to accelerate.
SentinelOne: Second-quarter revenue was $292 million, up 21% year over year; ARR reached $1.22 billion, up 22%, with 1,715 customers generating more than $100,000 in ARR. Adjusted operating margin increased from 2% to 10%, but free cash flow remained negative at $13.2 million. Growth and cash-flow improvement must progress together.
“This appears more like a disappointment in expectations and positioning than a material fundamental problem.”
Elastic: Shares rose approximately 17% after hours after revenue of $478 million and EPS of $0.70 both exceeded expectations. Elastic Cloud and sales-led subscriptions stabilized, while full-year operating-margin guidance increased to 19.4%. Cloud stabilization was the principal driver; the next test is whether cRPO and renewals can sustain the improvement, rather than a one-time margin increase.
Workday: EPS of $2.75 and an operating margin of 31.1% exceeded expectations, while AI contributed more than 25% of new contract value. However, subscriptions, cRPO, and remaining performance obligations were relatively flat. Remaining performance obligations totaled $27.4 billion, below expectations of approximately $28.5 billion. AI-driven pipeline is emerging, but revenue conversion remains slow.
Autodesk: Quarterly operating margin reached 41.0%, but third-quarter EPS guidance was weak. The increase in full-year revenue guidance includes the consolidation of MaintainX, while organic billings showed no clear inflection. Margins are outperforming revenue; investors must distinguish acquisition contributions from demand in the legacy business.
Rubrik: Revenue reached $427 million and operating margin was 7.8%, with the company also raising its full-year outlook. However, the shares remained constrained by the higher expectations established by CrowdStrike and Okta. The divergence between fundamentals and price reaction shows that the benchmark for software earnings has shifted from consensus expectations to the strongest peer performance.
MongoDB: Atlas has grown at least 29% for 4 consecutive quarters, with net ARR expansion of approximately 121%, as the database layer continues to benefit from increasing AI workloads. Shares rose 8.49% and gained 35.20% over 20 days. The next question is whether AI projects drive higher consumption rather than merely adding trial accounts.
Snowflake: Shares rose 4.36% and gained 10.40% over 20 days, as institutions raised forecasts on accelerating AI usage. The key test for the data cloud is whether usage translates into faster product-revenue growth while preserving gross margin. If model calls generate only short-term compute consumption, sustainability will require confirmation over additional quarters.
“Software valuations now depend not only on quarterly results, but also on bearish positioning, whether AI generates incremental revenue, the competitive and cooperative dynamics between model providers and application platforms, and whether full-year guidance increases are sufficient relative to quarterly beats.”
Veeva: Revenue growth accelerated to 17.6%, and full-year guidance was raised by 1.2%. Vault CRM added several large pharmaceutical customers in the second quarter, with 12 of the top 20 pharmaceutical companies now committed to adoption. Falcon is beginning to deploy agents in drug discovery and clinical workflows, while the horizontal CRM platform Aspen remains in early development.
ServiceNow: Shares rose 10.04% and gained 25.77% over 20 days, placing ServiceNow among the stronger names in the software recovery. Salesforce says its IT service-management offering already has 450 customers and is competing for some ServiceNow accounts. Competition will ultimately center on workflow depth, incremental AI revenue, and renewals—not which company launches more agents.
Palo Alto Networks: Shares rose 12.83% and gained 17.55% over 20 days, joining CrowdStrike’s strength in a broader cybersecurity rally. Without new operating data, sustainability still depends on platform consolidation, retention, and AI-security revenue. The sharp gain raises the expectations bar for the next earnings report.
Cloudflare: Shares rose 8.19% and gained 8.77% over 20 days as investors renewed their focus on the edge-cloud and AI-networking thesis. The commercial test is whether AI inference, networking, and security traffic can translate into faster revenue growth. A one-day sector-wide rally cannot substitute for customer expansion and margin improvement.
Datadog: Shares rose 6.70% but declined 9.54% over 20 days, leaving the near-term recovery insufficient to reverse medium-term weakness. Rising AI workloads support observability demand, but investors must still assess whether log, metrics, and tracing consumption recover in parallel and whether cloud-cost optimization re-emerges.
“The software sector is recovering from extreme pessimism, while partnerships between model providers and enterprise-software platforms have eased concerns about AI-driven disintermediation.”
Consumer Electronics / Smart Vehicles
Apple: Shares rose 0.36% but fell 5.65% over 20 days, as on-device AI and consumer electronics failed to participate in the sharp rally in GPUs and enterprise software. Higher memory prices and premium-component costs could still squeeze the hardware mix. The next catalysts are product demand, memory configurations, and gross margin—not treating a broader market rebound as evidence of a replacement-cycle recovery.
“Recent memory-spec reductions have been concentrated in PCs, smartphones, and lower-end GPUs/ASICs.”
Tesla: Shares rose 2.60% and gained 14.88% over 20 days, maintaining relative strength within autonomous driving. With no new product or delivery catalyst that day, the price action reflects investor preference rather than fundamental validation. The next proof points remain commercial autonomous-driving mileage, intervention rates, and robotics progress.
Avride
1) Its sidewalk robots have completed more than 600,000 deliveries, with 99% requiring no human assistance. The company plans to double its fleet to 1,000 units this fall and expand into 25 US campuses.
2) It has completed 100,000 autonomous trips in Dallas through Uber and plans to achieve fully driverless operations in 1H27. Scaling is clear; unit economics and the removal of safety operators are the next tests.
“This is a volume product: walking speed, in-compartment food delivery, Uber Eats, and university campuses.”
Unity Software: A potential world-model launch raised disintermediation concerns, with investors worried that content-generation and simulation tools could weaken the traditional game-engine gateway, although mid-quarter channel checks remain strong. Key proof points include developer retention, advertising monetization, and whether new tools continue to operate within Unity Software workflows.
Duolingo: User growth continues to lead, while monetization still lags. Unless AI features in its education app improve paid conversion and bookings, usage growth will be difficult to translate fully into profits. The next metrics to watch are daily active users, CURR, and bookings—not merely the rollout of AI features.
“Edge-computing revenue was $7.2 billion, up 27% year over year, with limited impact on the current profit structure.”
Qualcomm: Shares rose 0.65% and gained 8.69% over 20 days, showing relative resilience among consumer and edge-AI chips. On-device inference can increase semiconductor content value, but smartphone demand and customer inventories still determine the revenue trajectory. The next indicators are AI-smartphone penetration, average selling prices, and the share of non-handset revenue.
NXP Semiconductors: Shares rose 1.21% but fell 7.87% over 20 days, as automotive and industrial chips continued to lag the AI data-center supply chain. Rising semiconductor content in smart vehicles must offset vehicle-demand weakness and the inventory cycle. Key metrics are automotive revenue, channel inventory, and power-management orders.
onsemi: Shares rose 2.16% but fell 10.68% over 20 days; the one-day rebound has not reversed the medium-term weakness. Power semiconductors are sensitive to EV production, silicon content per vehicle, and pricing. If vehicle demand slows, AI data-center power opportunities are unlikely to fill the automotive shortfall immediately.
STMicroelectronics: Shares rose 3.38% but fell 3.24% over 20 days, outperforming most automotive and analog-chip names. A recovery in automotive MCUs and power devices still requires confirmation through orders and inventory digestion. For now, the move looks more like a sector rebound than evidence of stronger end demand.
Mobileye: Shares rose 0.82% and gained 8.99% over 20 days, outperforming Aurora and Aptiv among autonomous-driving chip names. Production vehicle programs, system shipments, and commercial autonomous-driving progress are the true revenue anchors. Without new orders, relative share-price strength does not imply higher customer production schedules.
“Many people do not realize this, but Avride is Nebius’s autonomous-driving company.”
Aurora: Shares fell 1.22% and declined 8.81% over 20 days, as autonomous trucking remained under pressure. The next metrics are driverless operating mileage, fleet utilization, and safety validation. If operations still require costly safety and remote support, scaling may not improve cash flow in parallel.
Aptiv: Shares fell 1.79% and declined 21.78% over 20 days, making it one of the weakest names in the smart-vehicle group. In-vehicle electronics demand, automaker production schedules, and product mix jointly determine margins. Without new orders or guidance, investors still need fundamental data to confirm an inflection point.
Symbotic: Shares rose 1.31% but fell 4.19% over 20 days, marking a modest recovery in warehouse robotics. Project-based revenue is sensitive to customer acceptance and deployment schedules. The next metrics are backlog conversion, the number of systems brought online, and gross margin—not a direct extrapolation from AI-robotics enthusiasm to current-period revenue.
Intuitive Surgical: Shares fell 0.90% but gained 3.99% over 20 days, as surgical robotics diverged from industrial automation and autonomous-driving names. System installations are only the starting point; procedure volumes and consumables revenue determine long-term returns. AI capabilities must translate into clinical efficiency and higher utilization.
Rockwell Automation: Shares rose 0.29% but fell 8.07% over 20 days, as industrial automation failed to participate in the rebound in AI software and GPUs. Enterprise agents are beginning to control laboratory equipment, but factory-scale deployment must still overcome safety, determinism, and equipment-compatibility hurdles. The next indicators are orders, backlog, and the automation investment cycle.
“Inference has not simply shifted from the GPU market to the ASIC market. It is evolving toward stage-specific allocation of compute and memory, subsequently reintegrated through racks, fabric, and software into heterogeneous systems.”
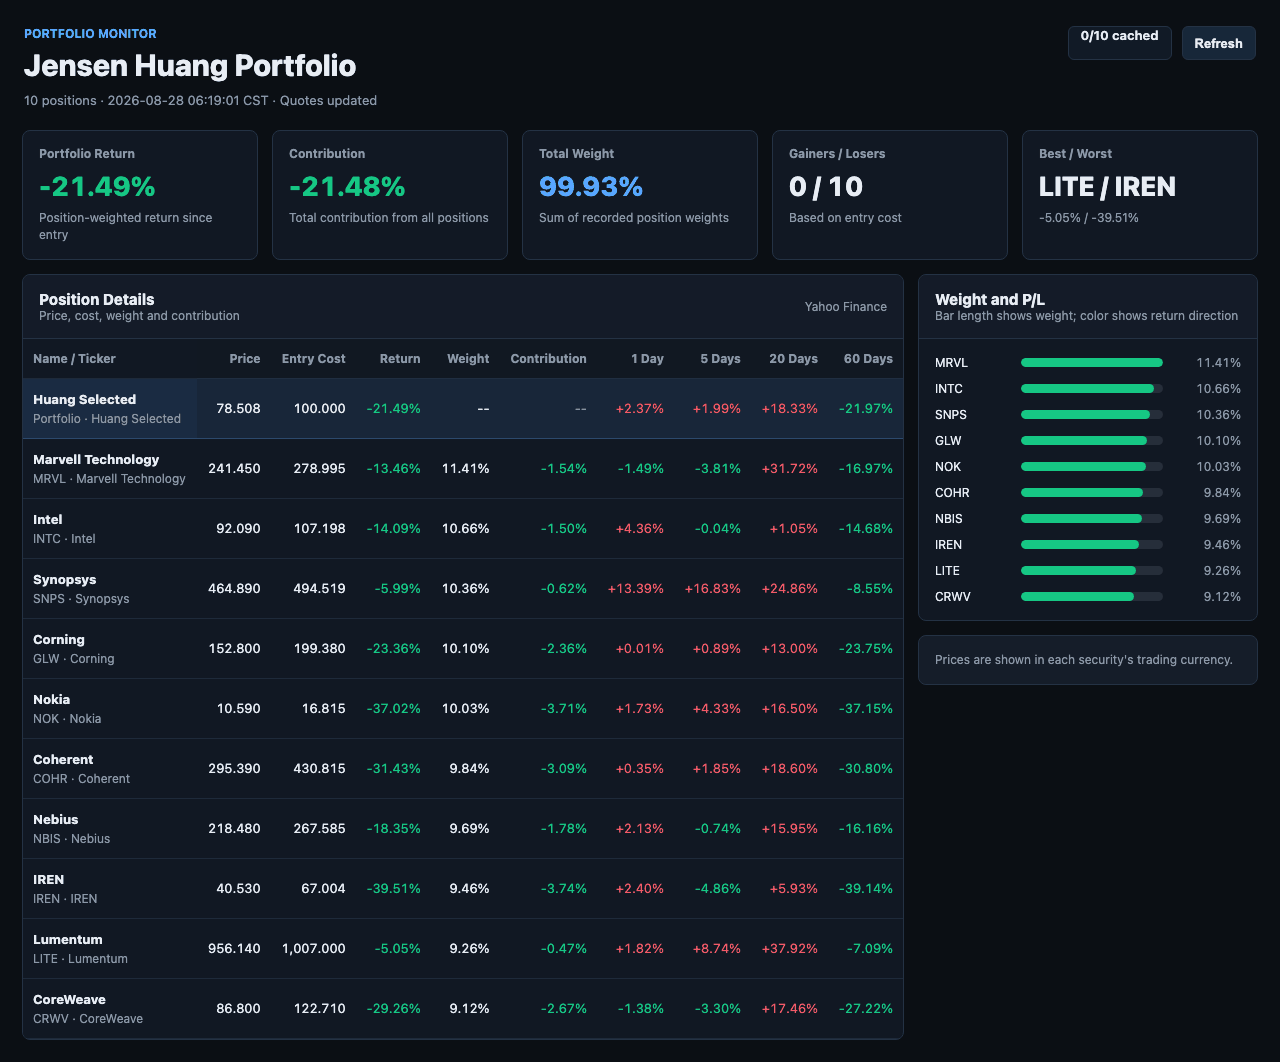
Jensen Huang’s Curated Portfolio
Memory Index Performance
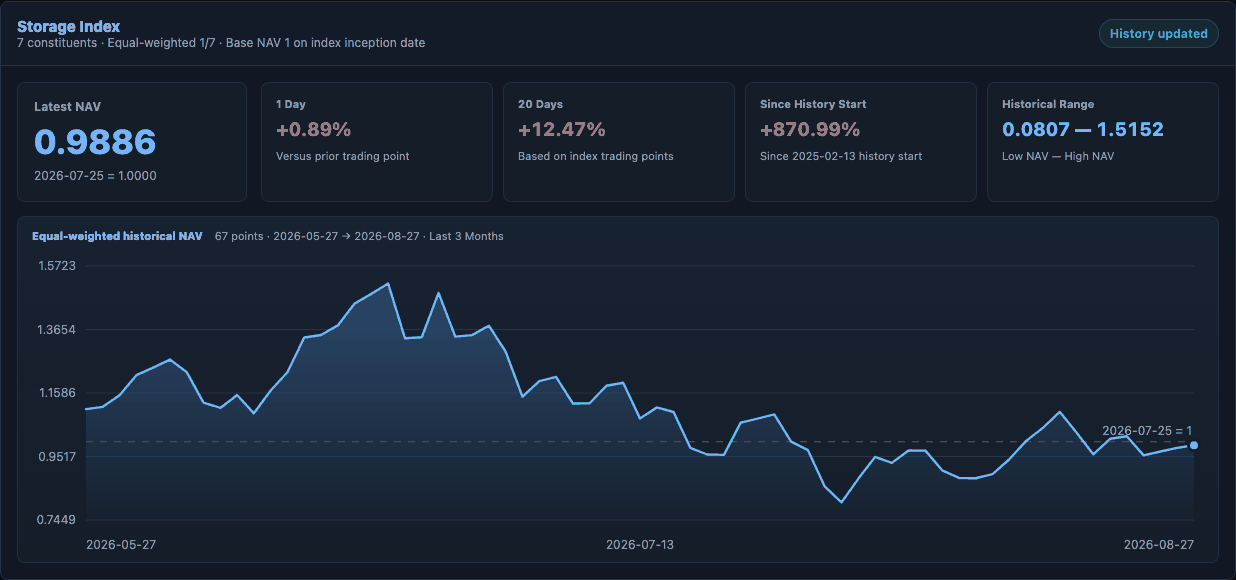
Memory’s Share of US Equity Trading Turnover
Related Reading
Rubin Ultra HBM Capacity Cut to 192GB: Supply and Power Constraints Drive Roadmap Downgrade