404K SEMI-AI Tech Morning Brief 2026-07-09 - AI Infrastructure Diffusion, Memory Price Increases, Cloud and Power Repricing
目录
After-Hours Summary
U.S. Stocks at New Highs
Top 10 U.S. Stocks by Turnover
U.S. Stock Gainers
U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models/Applications and Capex
CSP/Cloud Capex
AI Cloud/Data Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry
Semiconductor Equipment/Test
High-Speed Interconnect / Optical Communications / Cooling and Power
Internet / Platforms
Software / SaaS
Consumer Electronics / Smart Vehicles
Investment Bank Target Price Changes Over the Past 12 Hours
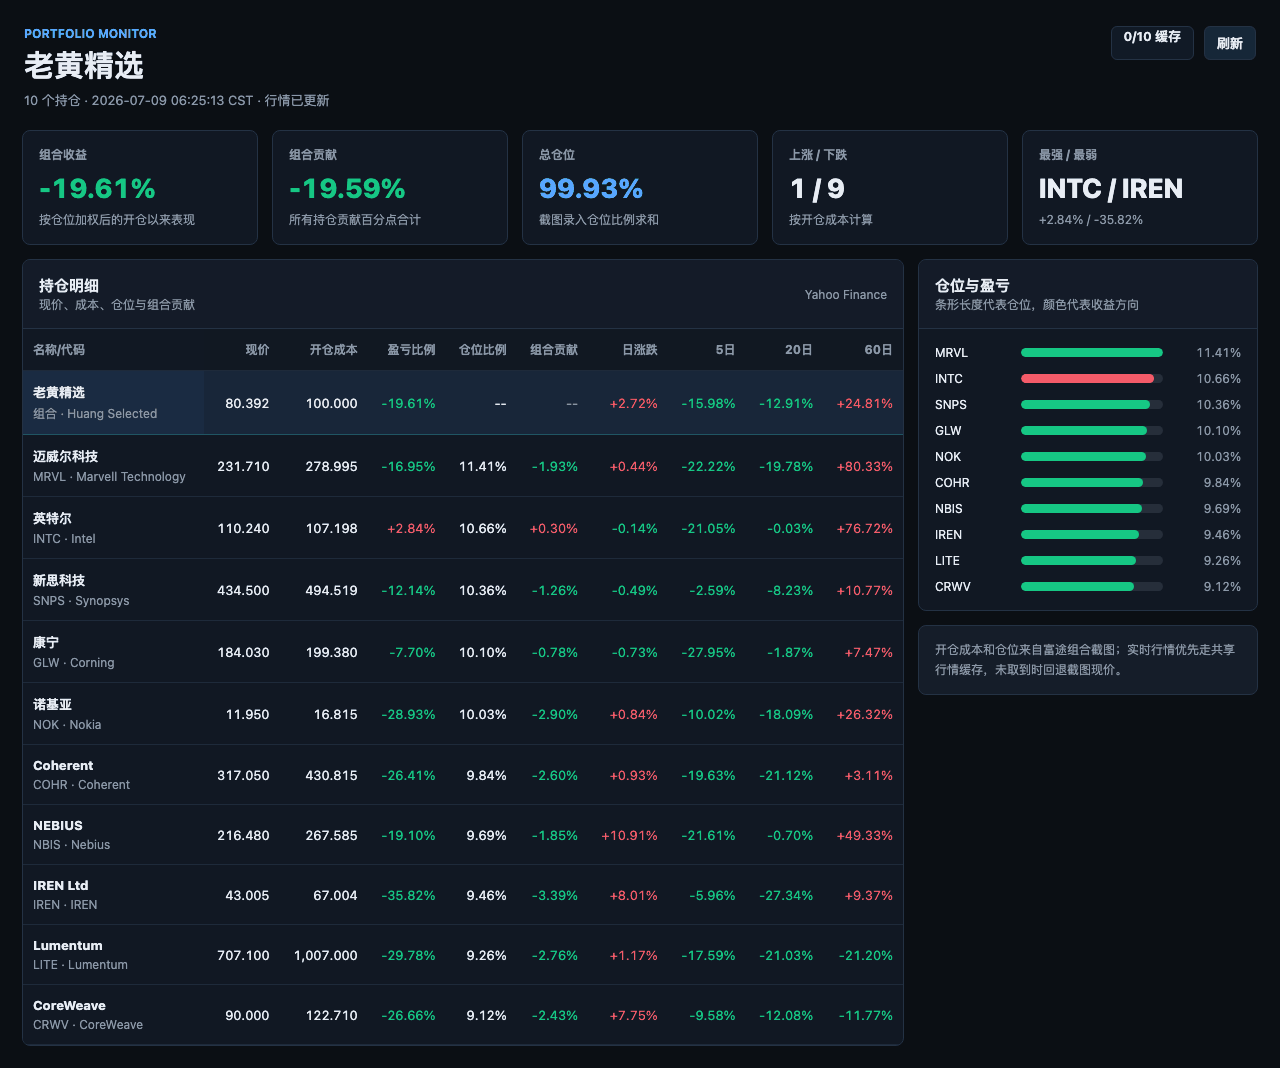
Huang’s Selected Portfolio
The AI infrastructure trade is spreading from GPUs to memory, networking, equipment, silicon photonics, power, and AI cloud operators; after-hours U.S. tech remains stronger than the broader market, but dispersion across software and platform stocks is becoming more pronounced.
After-Hours Summary
The latest U.S. market close was 2026-07-08. Index performance continued to diverge: the S&P; 500 fell 0.36%, Nasdaq 100 rose 0.28%, Dow Jones fell 1.07%, equal-weight S&P; 500 fell 1.18%, and Russell 2000 fell 0.91%. The technology ETF rose 1.24%, the semiconductor ETF rose 1.85%, and the equal-weight semiconductor reference rose 1.87%, indicating capital is still buying the AI hardware chain, while market breadth has not improved in tandem.
By theme, the AI and big data ETF rose 0.79%, the cloud computing ETF fell 0.12%, the software ETF fell 1.75%, and the cybersecurity ETF fell 0.60%. On the day, capital was more willing to pay for companies with capacity, orders, pricing power, and network bottlenecks, and less willing to assign high valuations to pure software names that still need to prove AI revenue elasticity.
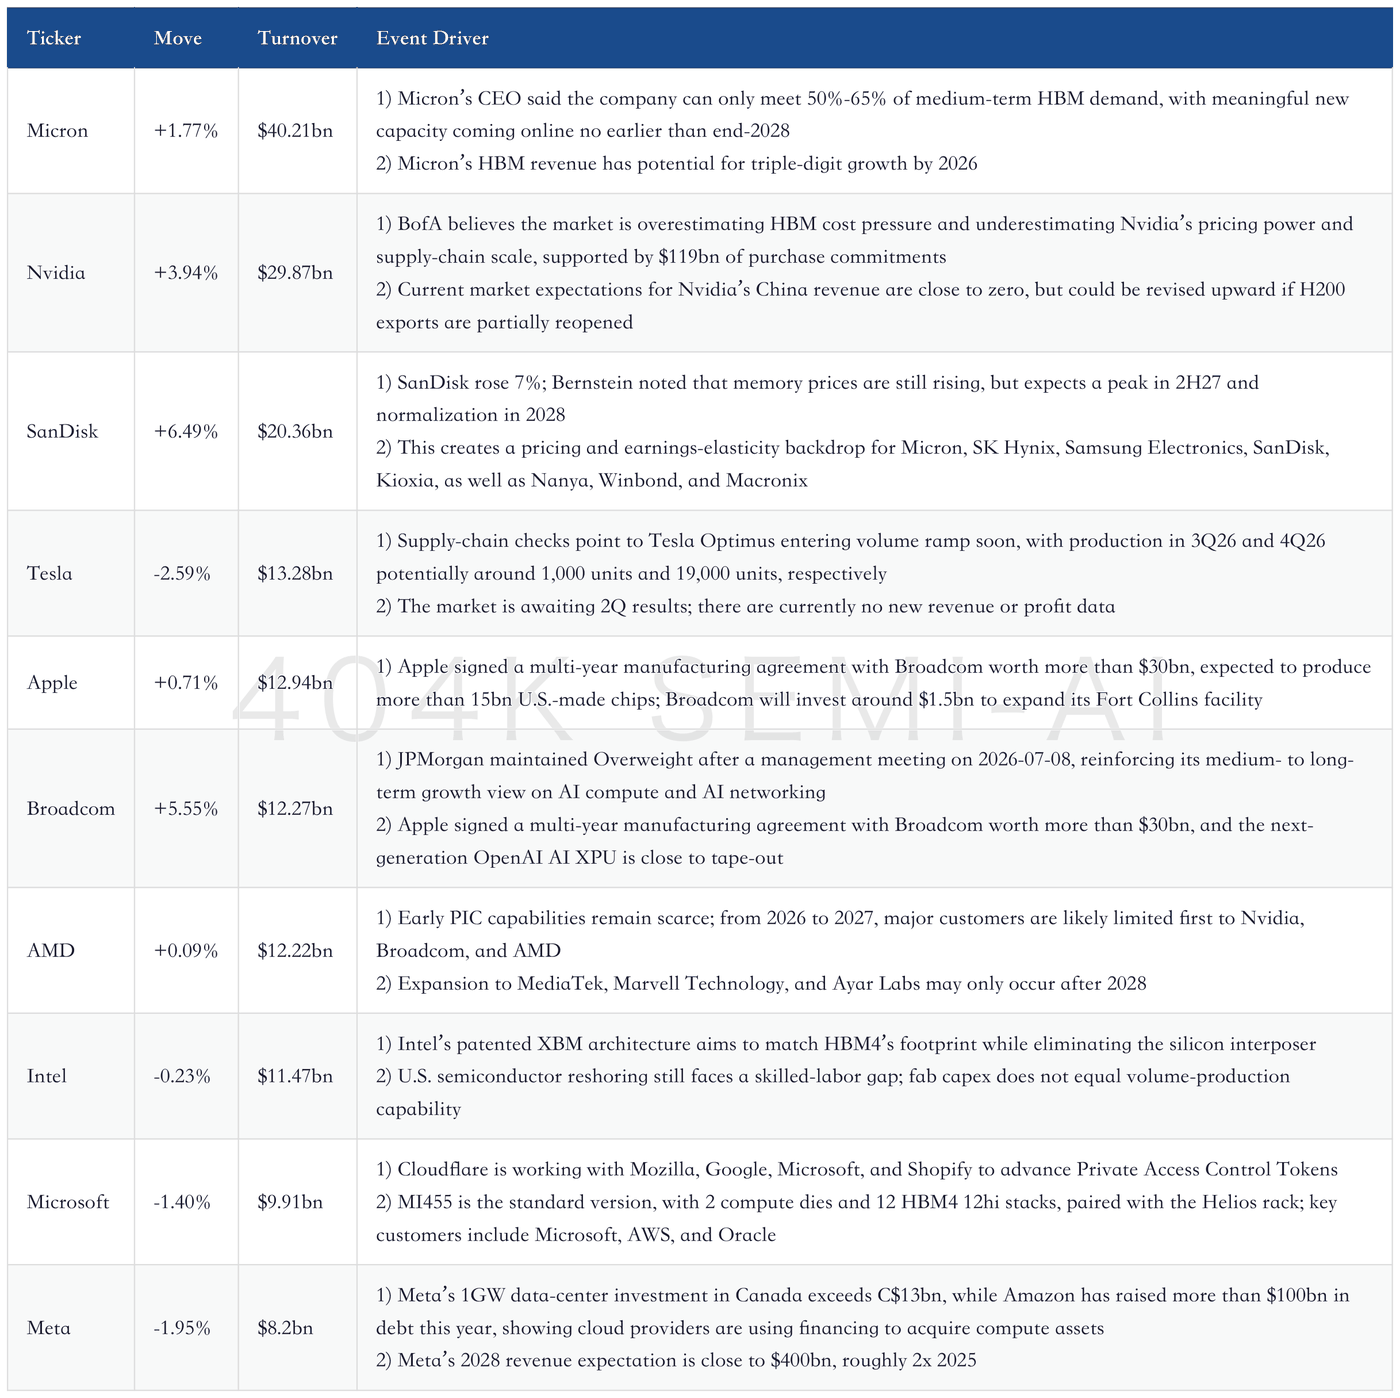
At the single-stock level, Nvidia rose 3.55%, Broadcom rose 4.78%, Arista rose 8.85%, SanDisk rose 6.82%, Western Digital rose 3.36%, and Seagate Technology rose 3.33%. By contrast, Microsoft fell 1.53%, Google fell 1.42%, Meta fell 1.93%, and Tesla fell 2.37%. The market signal was direct: AI capex is still accelerating, but profits, cash flow, and financing pressure are prompting renewed scrutiny of platform stocks.
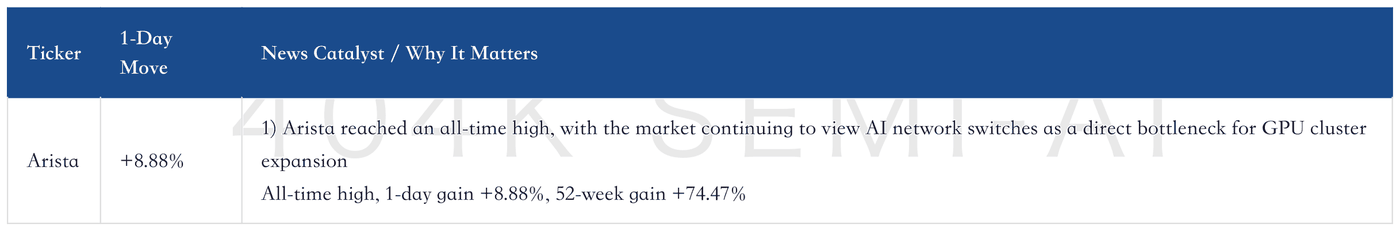
U.S. Stocks at New Highs
Top 10 U.S. Stocks by Turnover
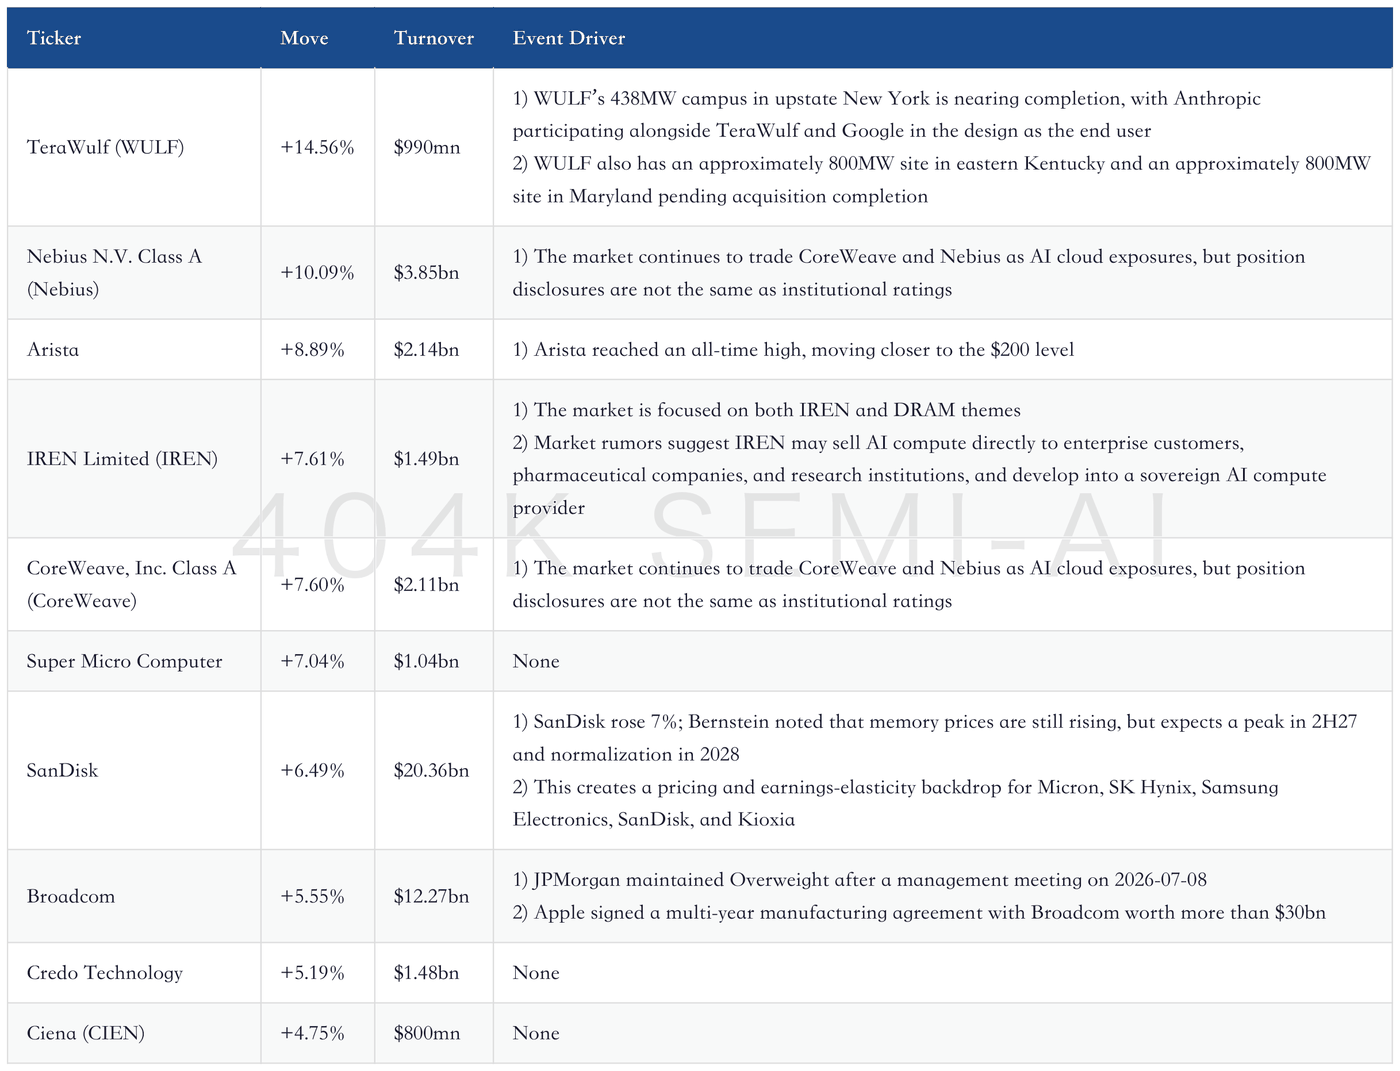
U.S. Stock Gainers
U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models/Applications and Capex
OpenAI
1) OpenAI Deployment Company agreed to acquire applied AI company Northslope, its second enterprise AI acquisition after Tomoro; the team will expand to several hundred forward deployed engineers.
2) Cloudflare and OpenAI launched a search crawling and indexing pilot, using signals such as content freshness, traffic quality, and page changes to improve ChatGPT answers. The investment implication is that model companies are starting to fill gaps in enterprise delivery and network data entry points, rather than competing only on parameters.
"Cloudflare and OpenAI launched a research pilot using Cloudflare signals such as content freshness, traffic quality and page changes to improve OpenAI search crawling and indexing."
Anthropic/Claude
1) Multiple reports indicate Claude’s processed tokens could nearly double to triple by year-end, while indirect channels such as AWS Bedrock and Azure Foundry may contribute 15%-20% of ARR, versus only 5%-10% one quarter ago.
2) Claude Code usage data shows roughly 95% of token consumption comes from cache hits, reducing token bills by about 84%. This suggests AI application adoption will grow, but unit revenue and compute elasticity for model service providers may not rise linearly.
Grok/xAI
1) Grok 4.5 has been described by multiple users as approaching leading models in coding and knowledge work, and has entered Cursor.
2) There is also information suggesting xAI may reclaim some compute for prioritized internal use, but no confirmed agreement scale. The investment implication is that model iteration continues to stimulate inference demand; what truly needs tracking is cloud resource scheduling and cost curves.
AI Application Costs
Claude Code, GPT-Live, Alexa Moonraker, and agentic advertising platforms collectively show that AI applications are entering multi-scenario deployment. Internal documents for Amazon Alexa Moonraker estimate 2026 GPU costs above US$100 million, making it the highest-cost new Alexa+ project. Whether these costs can convert into advertising, subscription, or enterprise workflow revenue is the validation point for platform-stock valuations.
CSP/Cloud Capex
Google
1) BofA raised Google’s 2026/2027 capex estimates to US$195 billion/US$290 billion, while Barclays inferred from the sustainability report that Google’s 2025 total electricity consumption rose 37% YoY to more than 43TWh, with data centers accounting for over 97%.
2) Google’s PUE remained at 1.09, while compute per unit of energy has improved more than 3x over the past five years. The investment implication is that Google’s bottleneck is shifting from whether it buys compute to power, water, grid connection, and compute per unit of energy.
"Electricity use jumped 37% y/y, while PUE remained flat at an industry-leading 1.09."
Meta
1) BofA raised Meta’s 2026/2027 capex estimates to US$145 billion/US$185 billion; Meta is building a 1GW AI data center in Alberta, Canada, with investment exceeding CAD13 billion, about 3,000 workers at peak construction, and more than 300 long-term operating jobs.
2) The market is concerned about Meta Compute overbuild on one hand, while on the other it continues to see the company self-fund generation and grid infrastructure. The next question is whether advertising, recommendations, and enterprise AI products can absorb this compute.
"Meta is breaking ground on a new 1GW AI-optimized data center, with more than CAD13 billion in investment."
Amazon
1) BofA says AWS’s 2026 cloud capex remains at US$159 billion, while 2027 was raised to US$230 billion; Barclays estimates Amazon’s 2025 data-center electricity consumption at about 90TWh, with deployed IT compute capacity of about 13GW.
2) Amazon added about 3.9GW of compute capacity in 2025 and plans to double again by 2027. The company has raised more than US$100 billion of debt during the year, and AI financing plus cash-flow pressure will become core issues in earnings season.
Microsoft
1) Microsoft continues to appear on the key customer lists for MI455/Helios, as well as Cloudflare’s PACT partner list.
2) Current information does not provide a new cloud capex target or order number for Microsoft, so it is treated here as a participant in CSP, enterprise AI software, and AI traffic-identification infrastructure. Follow-up validation points are Azure AI revenue, capex, and depreciation pressure.
Apple/Broadcom
Apple and Broadcom signed a multiyear manufacturing agreement worth more than US$30 billion, expected to produce more than 15 billion US-made chips, while Broadcom will invest about US$1.5 billion to expand its Fort Collins facility. The agreement is not large for Apple’s income statement, but it is a substantive order anchor for Broadcom’s RF, custom-chip, and US-manufacturing narratives.
AI Cloud/Data Center Operators
TeraWulf
1) TeraWulf signed a 401MW lease with Anthropic, implying about US$800 million of average annual NOI over the next 20 years; its 438MW campus in upstate New York is near completion, with Anthropic and Google jointly involved in design.
2) The company still has an approximately 800MW site in eastern Kentucky and an approximately 800MW site in Maryland that has not yet completed acquisition. Behind the 14.56% share-price gain, the market is buying power, land, and delivery credibility, not simply reported GW figures.
"We expect compute demand between OpenAI and Anthropic to exceed 100GW by the end of 2030, requiring more than 90GW of Cloudflare compute additions."
Nebius
Nebius rose 10.09%. Another report says 58MW of IT capacity under the Mega DC framework will come online in 3Q26, with Nebius providing the compute layer. This item does not disclose revenue or order value, but it gives a clear delivery milestone; future AI cloud valuation depends on capacity coming online on schedule, utilization, and customer contracts, not just share-price beta.
CoreWeave
CoreWeave rose 7.60%. Its CTO said in an interview that the real concern is not power generation, but everything required to connect power lines into data centers, including electricians and construction resources for advanced cooling loops. The investment implication is that AI cloud competition is shifting from GPU rental pricing to power access, construction, cooling, and customer lock-in.
IREN
IREN rose 7.61%. The market is focused on the possibility that it may sell AI compute directly to enterprise customers, pharmaceutical companies, and research institutions, and evolve into a sovereign AI compute provider. Current information is closer to industry rumor; for now, treat it as a clue for AI cloud beta, requiring follow-up validation through customer orders, financing, and power capacity.
GPU/CPU/ASIC
Nvidia
1) Nvidia rose 3.55%. BofA maintained Buy and a US$350 price target, arguing the market overestimates HBM cost pressure and underestimates pricing power. From Blackwell to Vera Rubin, HBM cost per rack rises only about US$200,000-US$300,000, but rack ASP is expected to increase from US$3 million-US$4 million to US$6 million-US$7 million, with gross margin still in the mid-70% range.
2) Limited approval for China H200 shipments could bring fewer than 200,000 units, corresponding to US$4 billion-US$6 billion of revenue at a US$20,000-US$30,000 ASP, but inference will still prioritize domestic Chinese chips.
3) The company also emphasized Vera CPU’s single-thread performance in Agentic AI. The logic is that faster agent loops can reduce GPU waiting time and increase revenue-generating time.
"Gross margins are expected to safely remain in the mid-70% range."
Broadcom
1) Broadcom rose 4.78%. After a management meeting on 2026-07-08, JPMorgan maintained Overweight. The report said Google’s TPU v9 roadmap is progressing on schedule, with volume expected in 2028; OpenAI’s first-generation custom XPU, Jalapeno, took only nine months from initial design to tape-out, and the next-generation OpenAI chip is expected to tape out soon.
2) Tomahawk 6 is already effectively sold out, and 400G-per-lane SerDes can drive copper cables longer than 1 meter. The debate on Broadcom is whether cloud in-house silicon will compress ASIC outsourcing, but multi-chip XPUs, SerDes, and advanced packaging raise the barrier to in-house design.
"XPU/GPU unit shipments could approach a 50/50 mix next year."
AMD
AMD rose 0.17%. TSMC’s early customer list for COUPE/PIC includes Nvidia, Broadcom, and AMD, with major customers in 2026-2027 initially limited to these three. Other inference-chip information points to MI455, Helios racks, and HBM4 configurations, indicating AMD’s opportunity lies in AI GPUs, CPUs, and system-level racks rather than single-chip parameters.
Intel
Intel fell 0.10%. One clue is the XBM patent architecture, which aims to match HBM4 area while eliminating the silicon interposer; another is the labor bottleneck in US semiconductor reshoring, with a skilled-labor shortfall of up to 157,000 by 2030. Intel’s investment implication still has two layers: on the product side, CPU/AI memory architecture; on the foundry side, US manufacturing ramp and yield.
ARM/Qualcomm
ARM fell 0.48%, while Qualcomm rose 2.10%. Agentic AI is again raising the importance of CPUs, edge AI, and low-latency loops, but current information lacks new ARM/Qualcomm financial figures. Qualcomm has a clue from Arete raising its price target from US$200 to US$314, which can serve as a watchpoint for more optimistic pricing of edge AI and data centers.
HBM/DRAM/NAND/SSD/HDD
Micron
1) Micron rose 0.70%. Goldman Sachs and Bernstein reports show DRAM like-for-like prices are expected to rise 250%-300% in 2026, with mix-inclusive ASP up 300%-350%; NAND like-for-like prices are expected to rise 200%-250%.
2) BofA named Micron its preferred memory pick and reiterated a US$1,550 price target, saying memory now accounts for 35%-40% of cloud AI capex, 2-3x historical levels.
3) Micron raised current-fiscal-year capex guidance from US$25 billion to about US$27 billion, with next year potentially exceeding the US$40 billion-US$45 billion range. The downside case is memory prices peaking, LTA execution, and new capacity in 2028.
"Memory now represents 35-40% of cloud AI capex."
Samsung Electronics
Samsung Electronics’ preliminary 2Q26 revenue was KRW171 trillion, with operating profit of KRW89.4 trillion, up 19x YoY, mainly driven by AI server DRAM/HBM. Counterpoint also estimates Samsung Electronics’ memory business operating margin was about 80% in 2Q. The risk is that Korean indices are too concentrated in Samsung Electronics and SK Hynix, so deleveraging would amplify share-price volatility.
SK Hynix
BNK maintained Hold on SK Hynix with a KRW1.85 million target price, citing US CSP 2026 capex consensus growth of +83% YoY and +23% in 2027; however, after incorporating memory/CPU price increases and Agentic AI spec upgrades, at least another 30%-40%+ growth in equipment investment is required. Bulls focus on the HBM bottleneck, while bears focus on capex execution difficulty.
SanDisk
SanDisk rose 6.82%; both the new-high list and turnover list show memory has the strongest beta. The company announced it has begun sampling BiCS10 1Tb TLC 3D NAND to support data-intensive workloads. Bernstein notes memory prices are still rising, but expects them to peak in 2H27 and normalize in 2028, meaning the price-hike trade needs close monitoring for inflection points.
Seagate Technology/Western Digital
Seagate Technology rose 3.33%, and Western Digital rose 3.36%. Demand from enterprise SSDs, nearline HDDs, and the AI inference data layer jointly strengthens the memory spillover logic; supply-chain information also mentions that 16TB to 30TB+ enterprise SSDs will drive shortages of dedicated DRAM cache. The investment implication is that HDD/NAND companies continue to benefit from AI data growth, but a weakening price cycle would hit valuation first.
Kioxia
Morgan Stanley listed Kioxia as its top Japanese semiconductor pick, with a JPY110,000 target price and Overweight rating, arguing AI inference is driving NAND demand, while low inventories and restrained NAND WFE investment make supply difficult to increase quickly. This clue forms the same NAND re-rating chain as SanDisk, Western Digital, and enterprise SSD price increases.
Foundry
TSMC
1) TSMC ADR rose 1.02%. Multiple previews expect 2Q26 gross margin of 68.4%, above the 65.5%-67.5% guidance range, with 3Q gross margin expected at 69.9%.
2) Silicon photonics/CPO is the new variable: PIC monthly capacity is expected to rise from about 500 wafers to 10,000 wafers in 2Q26, 15,000 in 4Q26, and at least 25,000 by 2028; the COUPE roadmap includes 1.6T OSFP optical engines in 2025, 6.4T CoWoS CPO in 2026, and subsequent processor-level 12.8T.
3) Early customers are prioritized as Nvidia, Broadcom, and AMD. The investment implication is that advanced-packaging capacity allocation is extending into the optical interconnect layer.
"PIC wafer capacity rises from roughly 500 wafers per month to 10,000 in 2026Q2, 15,000 in Q4 and at least 25,000 by 2028."
Rapidus
Rapidus’s president stated that semiconductor foundry pricing will be lower than TSMC’s. This information only confirms the pricing policy, with no yield, customer, capacity, or mass-production timeline. The investment implication is that Japan’s advanced foundry effort wants to use lower pricing to reduce customers’ trial barriers, but what truly matters in advanced foundry is yield, EDA/IP, advanced-packaging coordination, and delivery stability.
Intel Foundry/Samsung Foundry
The migration to GAA simultaneously pushes TSMC, Samsung Foundry, and Intel Foundry toward selective etching, advanced packaging, and yield challenges. New US fabs also face a skilled-labor shortfall of up to 157,000. The main foundry theme is not “subsidies mean mass production,” but customer onboarding, process yield, and workforce organization capability.
Semiconductor Equipment/Test
ASML
ASML rose 1.22%. The preview report raised its 2026/2027 EUV shipment forecasts to 66/95 units, with 109 units expected in 2028; demand is coming from both memory and logic. The risk is that 2027 capex could be constrained by EUV supply, making equipment order conversion more important than AI capex slogans.
Applied Materials / Lam Research / Tokyo Electron
GAA makes selective etching a required capability for leading-edge nodes. The report says every leading-edge chip manufactured from 2nm onward is tied to Lam Research, Applied Materials, and Tokyo Electron, because GAA channel release requires selective etching of germanium-rich fill layers while keeping the silicon wafer intact. The validation points for equipment stocks are advanced-node ramps, order continuity, and gross margin.
"Every leading-edge chip made from 2nm onward depends on selective etching, specifically the channel release step."
KLA / Teradyne / Advantest
KLA rose 2.35%, Teradyne rose 2.26%, and Advantest ADR rose 0.11%. Current information does not include new company-level orders, but rising complexity in AI accelerators, HBM, advanced packaging, and wafer testing continues to support demand for inspection, metrology, and test equipment. In the absence of new target prices, the focus is on the diffusion chain of the equipment cycle.
High-Speed Interconnect / Optical Communications / Cooling and Power
Arista
Arista rose 8.85% to a record high. As AI clusters scale, network switches are shifting from connectivity components to a key determinant of GPU utilization. Marvell Technology’s report also emphasized that in clusters with tens of thousands of GPUs, a single dropped packet can stall multiple GPUs. The investment implication is that the networking layer is now capturing a second layer of GPU capex budgets.
Marvell Technology
1) Marvell demonstrated Teralynx switch fabric support for Ultra Ethernet capabilities, including packet trimming, Auto Load Balancing, and Ultra Ethernet Transport.
2) Another silicon photonics report noted that PFLink supports UCIe-A, with bandwidth of 14.4Tbps, reach of more than 50 meters, and estimated energy efficiency of 2.8pJ/bit. The key question for Marvell is whether it can integrate SerDes, optics, packaging, and software into an AI interconnect platform.
"Ethernet is no longer just a connectivity layer; a single dropped packet can stall multiple GPUs."
Credo / Ciena / Optical Chain
Credo rose 5.19%, and Ciena rose 4.75%. The market table did not provide an event driver, so this should not be read into as an order story. Industry-chain reports indicate that optical cables and optical components will remain severely constrained through the end of 2027, while CPO switch deployments are expected to rise from 5,000 units in 2025 to 200,000 units in 2030. The next focus is customer orders and 800G/1.6T volume ramp.
Data-Center Power / Liquid Cooling
Barclays’ AI energy report identifies power, water, and cooling as the bottlenecks. Amazon’s direct-to-chip liquid cooling can reduce mechanical cooling energy consumption by up to 50% during peak cooling periods, while IRHX can cut water use by about 9% versus traditional evaporative air-cooling designs. PJM’s 2027/28 capacity auction still shows a shortage of roughly 6.5GW-6.6GW, so grid access will continue to affect data-center delivery.
Internet / Platforms
Alibaba
Morgan Stanley previewed Alibaba’s 1QF27 results, maintaining Overweight and Top Pick, but cut its target price from $190 to $180. The report forecasts group revenue of RMB269.045bn, up 8.6% YoY; Cloud Intelligence revenue of RMB48.427bn, up 45% YoY; and adjusted EBITA of RMB5.327bn, up 80.3% YoY, with an 11.0% margin. The investment implication is that Alibaba’s valuation repair depends on cloud acceleration and e-commerce profit coming in better than feared, not simply on China tech sentiment.
Amazon Advertising and Alexa
AWS and Warner Bros. Discovery launched an agent-based AI advertising platform aimed at automating ad workflows; Alexa Moonraker may generate more than $100mn of GPU costs in 2026. The debate on Amazon is clear: advertising and AWS AI can create revenue, but debt financing, depreciation, and application-layer ROI will weigh on free cash flow.
Meta Platforms
Meta is trading on two issues at once: a 1GW Canadian data center and long-term AI capex, and expectations for revenue approaching $400bn in 2028. The stock fell 1.93% in the near term, indicating market concern that capex will crowd out buybacks and cash flow. Over the medium term, the question is whether recommendation systems, ad efficiency, AI products, and external compute monetization can cover the capital spending.
Google / Waymo
Google fell 1.42%. Waymo is expanding its fully autonomous ride-hailing service to Las Vegas and plans to enter Denver, San Diego, and Tampa; meanwhile, Google’s power usage and data-center PUE data indicate that AI cloud expansion remains intense. The investment implication for Google is that AI, cloud, and autonomous driving are all consuming capital. The validation points are compute efficiency per unit and commercialization revenue.
Apple
Apple rose 0.88%. Its more than $30bn multi-year manufacturing agreement with Broadcom is more of a supply-chain and U.S. manufacturing commitment, at roughly $6bn per year, which is not large relative to Apple’s annual revenue of more than $400bn. What really affects Apple’s valuation is on-device AI, iPhone pricing, services revenue, and regulatory pressure. The Broadcom agreement mainly provides certainty for the RF and custom-chip supply chain.
Netflix / Streaming
Netflix fell 0.76%, with no new financial data in the current information set. Within the market tape, it sits on the weaker side of M7/internet platforms and does not fall into the AI capex main line. Without advertising, content-cost, or subscriber data, it should not be forcibly grouped with the AI hardware chain.
Uber / Local Services Platforms
Waymo’s city expansion and reports that Uber removed Waymo in Austin bring autonomous-driving platform partnerships back into focus. Current information does not include Uber revenue or order figures, so the only conclusion is that bargaining power between autonomous-driving suppliers and distribution platforms is changing.
Software / SaaS
Cloudflare
Cloudflare and OpenAI launched a research pilot on search crawling and indexing, while Cloudflare is also advancing PACT with Mozilla, Google, Microsoft, and Shopify to identify human or authorized agent traffic without relying on CAPTCHA, mandatory login, or intrusive tracking. The investment implication is that in the AI agent era, internet entry points, security, and traffic management will become new software-company budget items.
Snowflake
Snowflake is discussed in the context of Anthropic’s indirect-channel growth: platforms such as AWS Bedrock and Azure Foundry contribute 15%-20% of Anthropic ARR. For data-cloud companies, more model calls mean greater need for data governance, permissions, and workflow connectivity; however, current information does not include new Snowflake guidance or target prices.
Datadog
Market information says Datadog is less than 5% away from another record high and ranks among the top 20 S&P; 500 performers year to date. The information did not disclose financial figures, but the logic is that observability, cloud, and security operations become more valuable as AI applications expand. The next focus is AI operations, log-volume growth, and net retention.
Palo Alto Networks / CrowdStrike
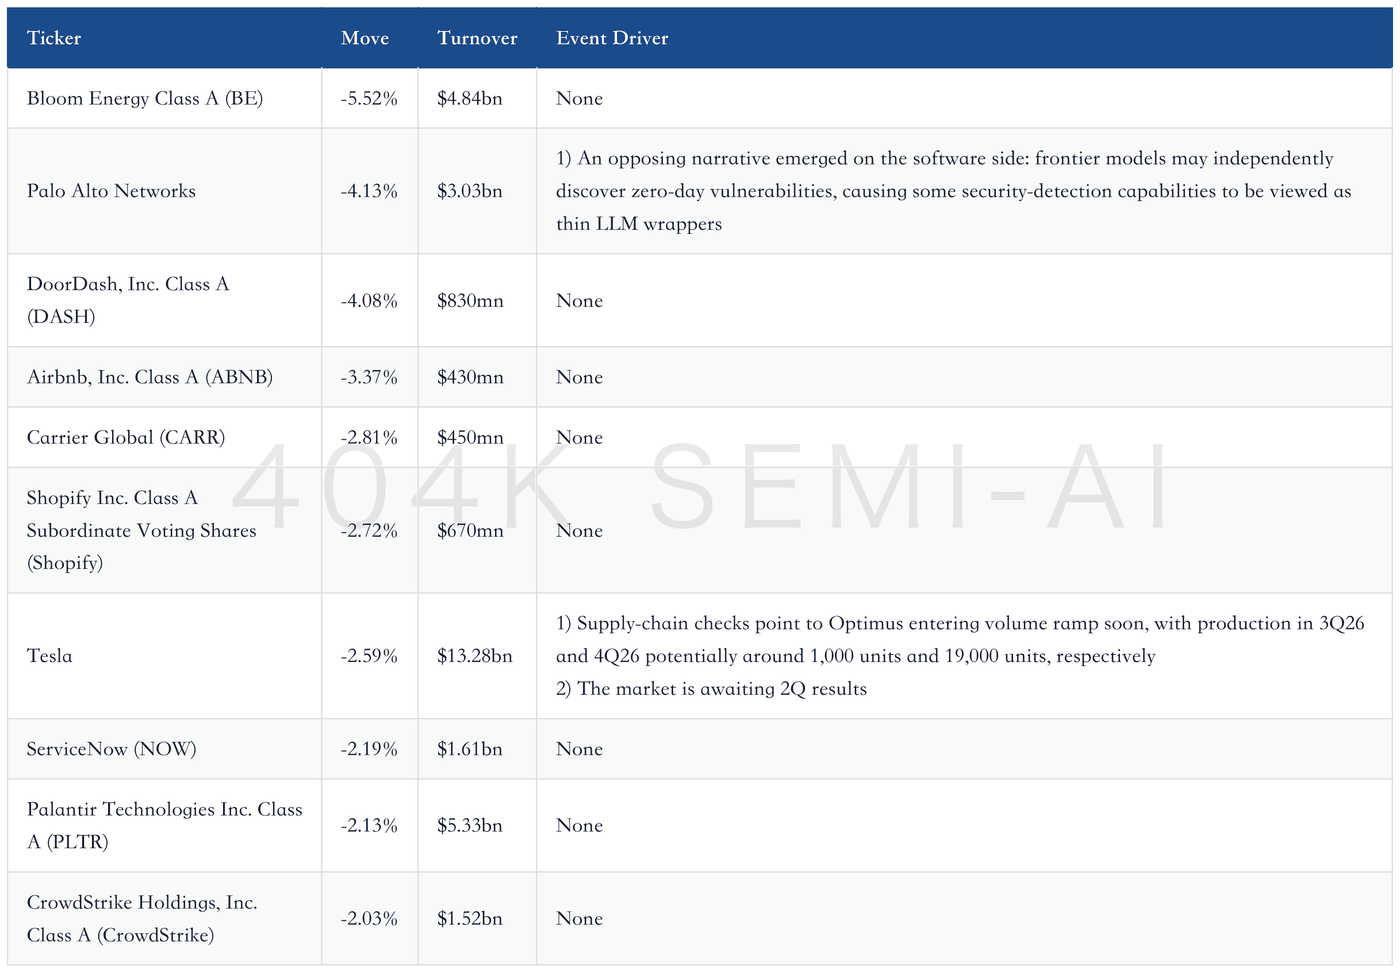
Palo Alto fell 4.13%, and CrowdStrike fell 2.03%. The market is concerned that frontier models can independently discover zero-day vulnerabilities, turning some detection capabilities into thin LLM wrappers. This logic has not yet been financially validated, but it explains why the cybersecurity ETF fell 0.60% and the software ETF fell 1.75%: AI is both a source of demand for software and a potential substitution pressure.
ServiceNow / Salesforce
ServiceNow fell 2.19%, and Salesforce fell 1.73%. Current information does not include new order or earnings figures. The real question for the software sector is whether AI features can lift paid seats, workflows, and CRM monetization, rather than merely increasing R&D; costs. Before numerical validation, they should be placed within the context of software valuation divergence.
GitLab / Vercel / Shopify
The developer ecosystem report mentioned Vercel Ship and Cloudflare, DOCN, Shopify, Okta, and CRM-related names, but the main line remains AI development tools and agentic workflows. Cloudflare and Shopify’s participation in PACT shows that software infrastructure will first enter through identity, traffic, and developer experience, rather than immediately showing up as a revenue surge.
Consumer Electronics / Smart Vehicles
Tesla
Tesla fell 2.37%. Supply-chain checks suggest Optimus may ramp in Q3 and Q4 2026, with production of roughly 1,000 units and 19,000 units, respectively. Another data point only noted that the share price held $400 and that investors are waiting for Q2 results, with no new revenue or profit figures. The investment implication is that the robotics narrative needs validation on volume, cost, and customers, not just videos and expectations.
Waymo / Autonomous Driving
Waymo is expanding its fully autonomous ride-hailing service to Las Vegas and plans to enter Denver, San Diego, and Tampa. Robotaxi materials also noted a modest near-term downgrade to Waymo expectations, while the long-term trajectory remains broadly optimistic. Key follow-ups are the pace of city expansion, regulatory approvals, unit economics, and platform partnerships.
Mobileye / Aurora / Aptiv
The list did not provide new orders, earnings, or target prices for Mobileye, Aurora, or Aptiv, so we will not force the discussion. Within autonomous driving, we retain only the Waymo and Tesla threads, which have event anchors with clear time windows.
Apple Edge AI
Apple’s manufacturing agreement with Broadcom affects the consumer electronics supply chain across RF, wireless connectivity, and custom chips. Edge AI remains a medium-term focus for Apple, but the current information does not include new numbers for iPhone shipments, AI feature adoption, or services revenue, so the supply-chain agreement cannot be framed as demand confirmation.
Nintendo / Sony / Consumer Hardware
The Japan semiconductor and consumer electronics report is constructive on Sony, with a JPY 4,700 target price, an Overweight rating, and FY26 operating profit forecast at JPY 1.7 trillion. It also flags that memory costs will pressure margins for some hardware products. The main consumer electronics theme is not a broad demand recovery, but pressure on hardware BOMs from rising AI memory prices.
Rocket Lab
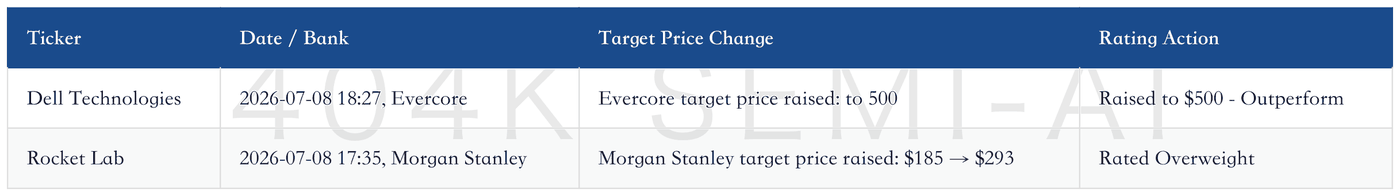
Rocket Lab belongs in the space / satellite theme. Morgan Stanley reiterated Overweight and raised its bull-case scenario from $185 to $293, citing the Iridium acquisition, upside in launch and connectivity businesses, and the company’s move toward a more vertically integrated space platform. Additional information noted that the CEO plans to sell 5 million shares, worth roughly $465 million, while retaining about 90% of his stake. Near term, this creates a trust discount; longer term, the focus is Neutron and Iridium integration.
Starlink
Starlink Business Aviation raised package pricing by 100%, with equipment prices increasing from $145,000 per aircraft to $200,000, and delivery times typically at 2-12 weeks. The investment implication is that satellite communications pricing power remains strong, but private-market valuation cannot be directly mixed with public-company target prices.
Investment Bank Target Price Changes Over the Past 12 Hours
Huang’s Selected Portfolio
404K SEMI-AI Tech Morning Brief 2026-07-09 - AI Infrastructure Diffusion, Memory Price Increases, Cloud and Power Repricing
目录
After-Hours Summary
U.S. Stocks at New Highs
Top 10 U.S. Stocks by Turnover
U.S. Stock Gainers
U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models/Applications and Capex
CSP/Cloud Capex
AI Cloud/Data Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry
Semiconductor Equipment/Test
High-Speed Interconnect / Optical Communications / Cooling and Power
Internet / Platforms
Software / SaaS
Consumer Electronics / Smart Vehicles
Investment Bank Target Price Changes Over the Past 12 Hours
Huang’s Selected Portfolio
The AI infrastructure trade is spreading from GPUs to memory, networking, equipment, silicon photonics, power, and AI cloud operators; after-hours U.S. tech remains stronger than the broader market, but dispersion across software and platform stocks is becoming more pronounced.
After-Hours Summary
The latest U.S. market close was 2026-07-08. Index performance continued to diverge: the S&P; 500 fell 0.36%, Nasdaq 100 rose 0.28%, Dow Jones fell 1.07%, equal-weight S&P; 500 fell 1.18%, and Russell 2000 fell 0.91%. The technology ETF rose 1.24%, the semiconductor ETF rose 1.85%, and the equal-weight semiconductor reference rose 1.87%, indicating capital is still buying the AI hardware chain, while market breadth has not improved in tandem.
By theme, the AI and big data ETF rose 0.79%, the cloud computing ETF fell 0.12%, the software ETF fell 1.75%, and the cybersecurity ETF fell 0.60%. On the day, capital was more willing to pay for companies with capacity, orders, pricing power, and network bottlenecks, and less willing to assign high valuations to pure software names that still need to prove AI revenue elasticity.
At the single-stock level, Nvidia rose 3.55%, Broadcom rose 4.78%, Arista rose 8.85%, SanDisk rose 6.82%, Western Digital rose 3.36%, and Seagate Technology rose 3.33%. By contrast, Microsoft fell 1.53%, Google fell 1.42%, Meta fell 1.93%, and Tesla fell 2.37%. The market signal was direct: AI capex is still accelerating, but profits, cash flow, and financing pressure are prompting renewed scrutiny of platform stocks.
U.S. Stocks at New Highs
Top 10 U.S. Stocks by Turnover
U.S. Stock Gainers
U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models/Applications and Capex
OpenAI
1) OpenAI Deployment Company agreed to acquire applied AI company Northslope, its second enterprise AI acquisition after Tomoro; the team will expand to several hundred forward deployed engineers.
2) Cloudflare and OpenAI launched a search crawling and indexing pilot, using signals such as content freshness, traffic quality, and page changes to improve ChatGPT answers. The investment implication is that model companies are starting to fill gaps in enterprise delivery and network data entry points, rather than competing only on parameters.
“Cloudflare and OpenAI launched a research pilot using Cloudflare signals such as content freshness, traffic quality and page changes to improve OpenAI search crawling and indexing.”
Anthropic/Claude
1) Multiple reports indicate Claude’s processed tokens could nearly double to triple by year-end, while indirect channels such as AWS Bedrock and Azure Foundry may contribute 15%-20% of ARR, versus only 5%-10% one quarter ago.
2) Claude Code usage data shows roughly 95% of token consumption comes from cache hits, reducing token bills by about 84%. This suggests AI application adoption will grow, but unit revenue and compute elasticity for model service providers may not rise linearly.
Grok/xAI
1) Grok 4.5 has been described by multiple users as approaching leading models in coding and knowledge work, and has entered Cursor.
2) There is also information suggesting xAI may reclaim some compute for prioritized internal use, but no confirmed agreement scale. The investment implication is that model iteration continues to stimulate inference demand; what truly needs tracking is cloud resource scheduling and cost curves.
AI Application Costs
Claude Code, GPT-Live, Alexa Moonraker, and agentic advertising platforms collectively show that AI applications are entering multi-scenario deployment. Internal documents for Amazon Alexa Moonraker estimate 2026 GPU costs above US$100 million, making it the highest-cost new Alexa+ project. Whether these costs can convert into advertising, subscription, or enterprise workflow revenue is the validation point for platform-stock valuations.
CSP/Cloud Capex
Google
1) BofA raised Google’s 2026/2027 capex estimates to US$195 billion/US$290 billion, while Barclays inferred from the sustainability report that Google’s 2025 total electricity consumption rose 37% YoY to more than 43TWh, with data centers accounting for over 97%.
2) Google’s PUE remained at 1.09, while compute per unit of energy has improved more than 3x over the past five years. The investment implication is that Google’s bottleneck is shifting from whether it buys compute to power, water, grid connection, and compute per unit of energy.
“Electricity use jumped 37% y/y, while PUE remained flat at an industry-leading 1.09.”
Meta
1) BofA raised Meta’s 2026/2027 capex estimates to US$145 billion/US$185 billion; Meta is building a 1GW AI data center in Alberta, Canada, with investment exceeding CAD13 billion, about 3,000 workers at peak construction, and more than 300 long-term operating jobs.
2) The market is concerned about Meta Compute overbuild on one hand, while on the other it continues to see the company self-fund generation and grid infrastructure. The next question is whether advertising, recommendations, and enterprise AI products can absorb this compute.
“Meta is breaking ground on a new 1GW AI-optimized data center, with more than CAD13 billion in investment.”
Amazon
1) BofA says AWS’s 2026 cloud capex remains at US$159 billion, while 2027 was raised to US$230 billion; Barclays estimates Amazon’s 2025 data-center electricity consumption at about 90TWh, with deployed IT compute capacity of about 13GW.
2) Amazon added about 3.9GW of compute capacity in 2025 and plans to double again by 2027. The company has raised more than US$100 billion of debt during the year, and AI financing plus cash-flow pressure will become core issues in earnings season.
Microsoft
1) Microsoft continues to appear on the key customer lists for MI455/Helios, as well as Cloudflare’s PACT partner list.
2) Current information does not provide a new cloud capex target or order number for Microsoft, so it is treated here as a participant in CSP, enterprise AI software, and AI traffic-identification infrastructure. Follow-up validation points are Azure AI revenue, capex, and depreciation pressure.
Apple/Broadcom
Apple and Broadcom signed a multiyear manufacturing agreement worth more than US$30 billion, expected to produce more than 15 billion US-made chips, while Broadcom will invest about US$1.5 billion to expand its Fort Collins facility. The agreement is not large for Apple’s income statement, but it is a substantive order anchor for Broadcom’s RF, custom-chip, and US-manufacturing narratives.
AI Cloud/Data Center Operators
TeraWulf
1) TeraWulf signed a 401MW lease with Anthropic, implying about US$800 million of average annual NOI over the next 20 years; its 438MW campus in upstate New York is near completion, with Anthropic and Google jointly involved in design.
2) The company still has an approximately 800MW site in eastern Kentucky and an approximately 800MW site in Maryland that has not yet completed acquisition. Behind the 14.56% share-price gain, the market is buying power, land, and delivery credibility, not simply reported GW figures.
“We expect compute demand between OpenAI and Anthropic to exceed 100GW by the end of 2030, requiring more than 90GW of Cloudflare compute additions.”
Nebius
Nebius rose 10.09%. Another report says 58MW of IT capacity under the Mega DC framework will come online in 3Q26, with Nebius providing the compute layer. This item does not disclose revenue or order value, but it gives a clear delivery milestone; future AI cloud valuation depends on capacity coming online on schedule, utilization, and customer contracts, not just share-price beta.
CoreWeave
CoreWeave rose 7.60%. Its CTO said in an interview that the real concern is not power generation, but everything required to connect power lines into data centers, including electricians and construction resources for advanced cooling loops. The investment implication is that AI cloud competition is shifting from GPU rental pricing to power access, construction, cooling, and customer lock-in.
IREN
IREN rose 7.61%. The market is focused on the possibility that it may sell AI compute directly to enterprise customers, pharmaceutical companies, and research institutions, and evolve into a sovereign AI compute provider. Current information is closer to industry rumor; for now, treat it as a clue for AI cloud beta, requiring follow-up validation through customer orders, financing, and power capacity.
GPU/CPU/ASIC
Nvidia
1) Nvidia rose 3.55%. BofA maintained Buy and a US$350 price target, arguing the market overestimates HBM cost pressure and underestimates pricing power. From Blackwell to Vera Rubin, HBM cost per rack rises only about US$200,000-US$300,000, but rack ASP is expected to increase from US$3 million-US$4 million to US$6 million-US$7 million, with gross margin still in the mid-70% range.
2) Limited approval for China H200 shipments could bring fewer than 200,000 units, corresponding to US$4 billion-US$6 billion of revenue at a US$20,000-US$30,000 ASP, but inference will still prioritize domestic Chinese chips.
3) The company also emphasized Vera CPU’s single-thread performance in Agentic AI. The logic is that faster agent loops can reduce GPU waiting time and increase revenue-generating time.
“Gross margins are expected to safely remain in the mid-70% range.”
Broadcom
1) Broadcom rose 4.78%. After a management meeting on 2026-07-08, JPMorgan maintained Overweight. The report said Google’s TPU v9 roadmap is progressing on schedule, with volume expected in 2028; OpenAI’s first-generation custom XPU, Jalapeno, took only nine months from initial design to tape-out, and the next-generation OpenAI chip is expected to tape out soon.
2) Tomahawk 6 is already effectively sold out, and 400G-per-lane SerDes can drive copper cables longer than 1 meter. The debate on Broadcom is whether cloud in-house silicon will compress ASIC outsourcing, but multi-chip XPUs, SerDes, and advanced packaging raise the barrier to in-house design.
“XPU/GPU unit shipments could approach a 50/50 mix next year.”
AMD
AMD rose 0.17%. TSMC’s early customer list for COUPE/PIC includes Nvidia, Broadcom, and AMD, with major customers in 2026-2027 initially limited to these three. Other inference-chip information points to MI455, Helios racks, and HBM4 configurations, indicating AMD’s opportunity lies in AI GPUs, CPUs, and system-level racks rather than single-chip parameters.
Intel
Intel fell 0.10%. One clue is the XBM patent architecture, which aims to match HBM4 area while eliminating the silicon interposer; another is the labor bottleneck in US semiconductor reshoring, with a skilled-labor shortfall of up to 157,000 by 2030. Intel’s investment implication still has two layers: on the product side, CPU/AI memory architecture; on the foundry side, US manufacturing ramp and yield.
ARM/Qualcomm
ARM fell 0.48%, while Qualcomm rose 2.10%. Agentic AI is again raising the importance of CPUs, edge AI, and low-latency loops, but current information lacks new ARM/Qualcomm financial figures. Qualcomm has a clue from Arete raising its price target from US$200 to US$314, which can serve as a watchpoint for more optimistic pricing of edge AI and data centers.
HBM/DRAM/NAND/SSD/HDD
Micron
1) Micron rose 0.70%. Goldman Sachs and Bernstein reports show DRAM like-for-like prices are expected to rise 250%-300% in 2026, with mix-inclusive ASP up 300%-350%; NAND like-for-like prices are expected to rise 200%-250%.
2) BofA named Micron its preferred memory pick and reiterated a US$1,550 price target, saying memory now accounts for 35%-40% of cloud AI capex, 2-3x historical levels.
3) Micron raised current-fiscal-year capex guidance from US$25 billion to about US$27 billion, with next year potentially exceeding the US$40 billion-US$45 billion range. The downside case is memory prices peaking, LTA execution, and new capacity in 2028.
“Memory now represents 35-40% of cloud AI capex.”
Samsung Electronics
Samsung Electronics’ preliminary 2Q26 revenue was KRW171 trillion, with operating profit of KRW89.4 trillion, up 19x YoY, mainly driven by AI server DRAM/HBM. Counterpoint also estimates Samsung Electronics’ memory business operating margin was about 80% in 2Q. The risk is that Korean indices are too concentrated in Samsung Electronics and SK Hynix, so deleveraging would amplify share-price volatility.
SK Hynix
BNK maintained Hold on SK Hynix with a KRW1.85 million target price, citing US CSP 2026 capex consensus growth of +83% YoY and +23% in 2027; however, after incorporating memory/CPU price increases and Agentic AI spec upgrades, at least another 30%-40%+ growth in equipment investment is required. Bulls focus on the HBM bottleneck, while bears focus on capex execution difficulty.
SanDisk
SanDisk rose 6.82%; both the new-high list and turnover list show memory has the strongest beta. The company announced it has begun sampling BiCS10 1Tb TLC 3D NAND to support data-intensive workloads. Bernstein notes memory prices are still rising, but expects them to peak in 2H27 and normalize in 2028, meaning the price-hike trade needs close monitoring for inflection points.
Seagate Technology/Western Digital
Seagate Technology rose 3.33%, and Western Digital rose 3.36%. Demand from enterprise SSDs, nearline HDDs, and the AI inference data layer jointly strengthens the memory spillover logic; supply-chain information also mentions that 16TB to 30TB+ enterprise SSDs will drive shortages of dedicated DRAM cache. The investment implication is that HDD/NAND companies continue to benefit from AI data growth, but a weakening price cycle would hit valuation first.
Kioxia
Morgan Stanley listed Kioxia as its top Japanese semiconductor pick, with a JPY110,000 target price and Overweight rating, arguing AI inference is driving NAND demand, while low inventories and restrained NAND WFE investment make supply difficult to increase quickly. This clue forms the same NAND re-rating chain as SanDisk, Western Digital, and enterprise SSD price increases.
Foundry
TSMC
1) TSMC ADR rose 1.02%. Multiple previews expect 2Q26 gross margin of 68.4%, above the 65.5%-67.5% guidance range, with 3Q gross margin expected at 69.9%.
2) Silicon photonics/CPO is the new variable: PIC monthly capacity is expected to rise from about 500 wafers to 10,000 wafers in 2Q26, 15,000 in 4Q26, and at least 25,000 by 2028; the COUPE roadmap includes 1.6T OSFP optical engines in 2025, 6.4T CoWoS CPO in 2026, and subsequent processor-level 12.8T.
3) Early customers are prioritized as Nvidia, Broadcom, and AMD. The investment implication is that advanced-packaging capacity allocation is extending into the optical interconnect layer.
“PIC wafer capacity rises from roughly 500 wafers per month to 10,000 in 2026Q2, 15,000 in Q4 and at least 25,000 by 2028.”
Rapidus
Rapidus’s president stated that semiconductor foundry pricing will be lower than TSMC’s. This information only confirms the pricing policy, with no yield, customer, capacity, or mass-production timeline. The investment implication is that Japan’s advanced foundry effort wants to use lower pricing to reduce customers’ trial barriers, but what truly matters in advanced foundry is yield, EDA/IP, advanced-packaging coordination, and delivery stability.
Intel Foundry/Samsung Foundry
The migration to GAA simultaneously pushes TSMC, Samsung Foundry, and Intel Foundry toward selective etching, advanced packaging, and yield challenges. New US fabs also face a skilled-labor shortfall of up to 157,000. The main foundry theme is not “subsidies mean mass production,” but customer onboarding, process yield, and workforce organization capability.
Semiconductor Equipment/Test
ASML
ASML rose 1.22%. The preview report raised its 2026/2027 EUV shipment forecasts to 66/95 units, with 109 units expected in 2028; demand is coming from both memory and logic. The risk is that 2027 capex could be constrained by EUV supply, making equipment order conversion more important than AI capex slogans.
Applied Materials / Lam Research / Tokyo Electron
GAA makes selective etching a required capability for leading-edge nodes. The report says every leading-edge chip manufactured from 2nm onward is tied to Lam Research, Applied Materials, and Tokyo Electron, because GAA channel release requires selective etching of germanium-rich fill layers while keeping the silicon wafer intact. The validation points for equipment stocks are advanced-node ramps, order continuity, and gross margin.
“Every leading-edge chip made from 2nm onward depends on selective etching, specifically the channel release step.”
KLA / Teradyne / Advantest
KLA rose 2.35%, Teradyne rose 2.26%, and Advantest ADR rose 0.11%. Current information does not include new company-level orders, but rising complexity in AI accelerators, HBM, advanced packaging, and wafer testing continues to support demand for inspection, metrology, and test equipment. In the absence of new target prices, the focus is on the diffusion chain of the equipment cycle.
High-Speed Interconnect / Optical Communications / Cooling and Power
Arista
Arista rose 8.85% to a record high. As AI clusters scale, network switches are shifting from connectivity components to a key determinant of GPU utilization. Marvell Technology’s report also emphasized that in clusters with tens of thousands of GPUs, a single dropped packet can stall multiple GPUs. The investment implication is that the networking layer is now capturing a second layer of GPU capex budgets.
Marvell Technology
1) Marvell demonstrated Teralynx switch fabric support for Ultra Ethernet capabilities, including packet trimming, Auto Load Balancing, and Ultra Ethernet Transport.
2) Another silicon photonics report noted that PFLink supports UCIe-A, with bandwidth of 14.4Tbps, reach of more than 50 meters, and estimated energy efficiency of 2.8pJ/bit. The key question for Marvell is whether it can integrate SerDes, optics, packaging, and software into an AI interconnect platform.
“Ethernet is no longer just a connectivity layer; a single dropped packet can stall multiple GPUs.”
Credo / Ciena / Optical Chain
Credo rose 5.19%, and Ciena rose 4.75%. The market table did not provide an event driver, so this should not be read into as an order story. Industry-chain reports indicate that optical cables and optical components will remain severely constrained through the end of 2027, while CPO switch deployments are expected to rise from 5,000 units in 2025 to 200,000 units in 2030. The next focus is customer orders and 800G/1.6T volume ramp.
Data-Center Power / Liquid Cooling
Barclays’ AI energy report identifies power, water, and cooling as the bottlenecks. Amazon’s direct-to-chip liquid cooling can reduce mechanical cooling energy consumption by up to 50% during peak cooling periods, while IRHX can cut water use by about 9% versus traditional evaporative air-cooling designs. PJM’s 2027/28 capacity auction still shows a shortage of roughly 6.5GW-6.6GW, so grid access will continue to affect data-center delivery.
Internet / Platforms
Alibaba
Morgan Stanley previewed Alibaba’s 1QF27 results, maintaining Overweight and Top Pick, but cut its target price from $190 to $180. The report forecasts group revenue of RMB269.045bn, up 8.6% YoY; Cloud Intelligence revenue of RMB48.427bn, up 45% YoY; and adjusted EBITA of RMB5.327bn, up 80.3% YoY, with an 11.0% margin. The investment implication is that Alibaba’s valuation repair depends on cloud acceleration and e-commerce profit coming in better than feared, not simply on China tech sentiment.
Amazon Advertising and Alexa
AWS and Warner Bros. Discovery launched an agent-based AI advertising platform aimed at automating ad workflows; Alexa Moonraker may generate more than $100mn of GPU costs in 2026. The debate on Amazon is clear: advertising and AWS AI can create revenue, but debt financing, depreciation, and application-layer ROI will weigh on free cash flow.
Meta Platforms
Meta is trading on two issues at once: a 1GW Canadian data center and long-term AI capex, and expectations for revenue approaching $400bn in 2028. The stock fell 1.93% in the near term, indicating market concern that capex will crowd out buybacks and cash flow. Over the medium term, the question is whether recommendation systems, ad efficiency, AI products, and external compute monetization can cover the capital spending.
Google / Waymo
Google fell 1.42%. Waymo is expanding its fully autonomous ride-hailing service to Las Vegas and plans to enter Denver, San Diego, and Tampa; meanwhile, Google’s power usage and data-center PUE data indicate that AI cloud expansion remains intense. The investment implication for Google is that AI, cloud, and autonomous driving are all consuming capital. The validation points are compute efficiency per unit and commercialization revenue.
Apple
Apple rose 0.88%. Its more than $30bn multi-year manufacturing agreement with Broadcom is more of a supply-chain and U.S. manufacturing commitment, at roughly $6bn per year, which is not large relative to Apple’s annual revenue of more than $400bn. What really affects Apple’s valuation is on-device AI, iPhone pricing, services revenue, and regulatory pressure. The Broadcom agreement mainly provides certainty for the RF and custom-chip supply chain.
Netflix / Streaming
Netflix fell 0.76%, with no new financial data in the current information set. Within the market tape, it sits on the weaker side of M7/internet platforms and does not fall into the AI capex main line. Without advertising, content-cost, or subscriber data, it should not be forcibly grouped with the AI hardware chain.
Uber / Local Services Platforms
Waymo’s city expansion and reports that Uber removed Waymo in Austin bring autonomous-driving platform partnerships back into focus. Current information does not include Uber revenue or order figures, so the only conclusion is that bargaining power between autonomous-driving suppliers and distribution platforms is changing.
Software / SaaS
Cloudflare
Cloudflare and OpenAI launched a research pilot on search crawling and indexing, while Cloudflare is also advancing PACT with Mozilla, Google, Microsoft, and Shopify to identify human or authorized agent traffic without relying on CAPTCHA, mandatory login, or intrusive tracking. The investment implication is that in the AI agent era, internet entry points, security, and traffic management will become new software-company budget items.
Snowflake
Snowflake is discussed in the context of Anthropic’s indirect-channel growth: platforms such as AWS Bedrock and Azure Foundry contribute 15%-20% of Anthropic ARR. For data-cloud companies, more model calls mean greater need for data governance, permissions, and workflow connectivity; however, current information does not include new Snowflake guidance or target prices.
Datadog
Market information says Datadog is less than 5% away from another record high and ranks among the top 20 S&P; 500 performers year to date. The information did not disclose financial figures, but the logic is that observability, cloud, and security operations become more valuable as AI applications expand. The next focus is AI operations, log-volume growth, and net retention.
Palo Alto Networks / CrowdStrike
Palo Alto fell 4.13%, and CrowdStrike fell 2.03%. The market is concerned that frontier models can independently discover zero-day vulnerabilities, turning some detection capabilities into thin LLM wrappers. This logic has not yet been financially validated, but it explains why the cybersecurity ETF fell 0.60% and the software ETF fell 1.75%: AI is both a source of demand for software and a potential substitution pressure.
ServiceNow / Salesforce
ServiceNow fell 2.19%, and Salesforce fell 1.73%. Current information does not include new order or earnings figures. The real question for the software sector is whether AI features can lift paid seats, workflows, and CRM monetization, rather than merely increasing R&D; costs. Before numerical validation, they should be placed within the context of software valuation divergence.
GitLab / Vercel / Shopify
The developer ecosystem report mentioned Vercel Ship and Cloudflare, DOCN, Shopify, Okta, and CRM-related names, but the main line remains AI development tools and agentic workflows. Cloudflare and Shopify’s participation in PACT shows that software infrastructure will first enter through identity, traffic, and developer experience, rather than immediately showing up as a revenue surge.
Consumer Electronics / Smart Vehicles
Tesla
Tesla fell 2.37%. Supply-chain checks suggest Optimus may ramp in Q3 and Q4 2026, with production of roughly 1,000 units and 19,000 units, respectively. Another data point only noted that the share price held $400 and that investors are waiting for Q2 results, with no new revenue or profit figures. The investment implication is that the robotics narrative needs validation on volume, cost, and customers, not just videos and expectations.
Waymo / Autonomous Driving
Waymo is expanding its fully autonomous ride-hailing service to Las Vegas and plans to enter Denver, San Diego, and Tampa. Robotaxi materials also noted a modest near-term downgrade to Waymo expectations, while the long-term trajectory remains broadly optimistic. Key follow-ups are the pace of city expansion, regulatory approvals, unit economics, and platform partnerships.
Mobileye / Aurora / Aptiv
The list did not provide new orders, earnings, or target prices for Mobileye, Aurora, or Aptiv, so we will not force the discussion. Within autonomous driving, we retain only the Waymo and Tesla threads, which have event anchors with clear time windows.
Apple Edge AI
Apple’s manufacturing agreement with Broadcom affects the consumer electronics supply chain across RF, wireless connectivity, and custom chips. Edge AI remains a medium-term focus for Apple, but the current information does not include new numbers for iPhone shipments, AI feature adoption, or services revenue, so the supply-chain agreement cannot be framed as demand confirmation.
Nintendo / Sony / Consumer Hardware
The Japan semiconductor and consumer electronics report is constructive on Sony, with a JPY 4,700 target price, an Overweight rating, and FY26 operating profit forecast at JPY 1.7 trillion. It also flags that memory costs will pressure margins for some hardware products. The main consumer electronics theme is not a broad demand recovery, but pressure on hardware BOMs from rising AI memory prices.
Rocket Lab
Rocket Lab belongs in the space / satellite theme. Morgan Stanley reiterated Overweight and raised its bull-case scenario from $185 to $293, citing the Iridium acquisition, upside in launch and connectivity businesses, and the company’s move toward a more vertically integrated space platform. Additional information noted that the CEO plans to sell 5 million shares, worth roughly $465 million, while retaining about 90% of his stake. Near term, this creates a trust discount; longer term, the focus is Neutron and Iridium integration.
Starlink
Starlink Business Aviation raised package pricing by 100%, with equipment prices increasing from $145,000 per aircraft to $200,000, and delivery times typically at 2-12 weeks. The investment implication is that satellite communications pricing power remains strong, but private-market valuation cannot be directly mixed with public-company target prices.
Investment Bank Target Price Changes Over the Past 12 Hours
Huang’s Selected Portfolio