404K SEMI-AI Tech Morning Brief 2026-07-07 — Memory Price Increases, AI Data Centers Heat Up, Optical Interconnect Divergence
目录
After-Hours Summary
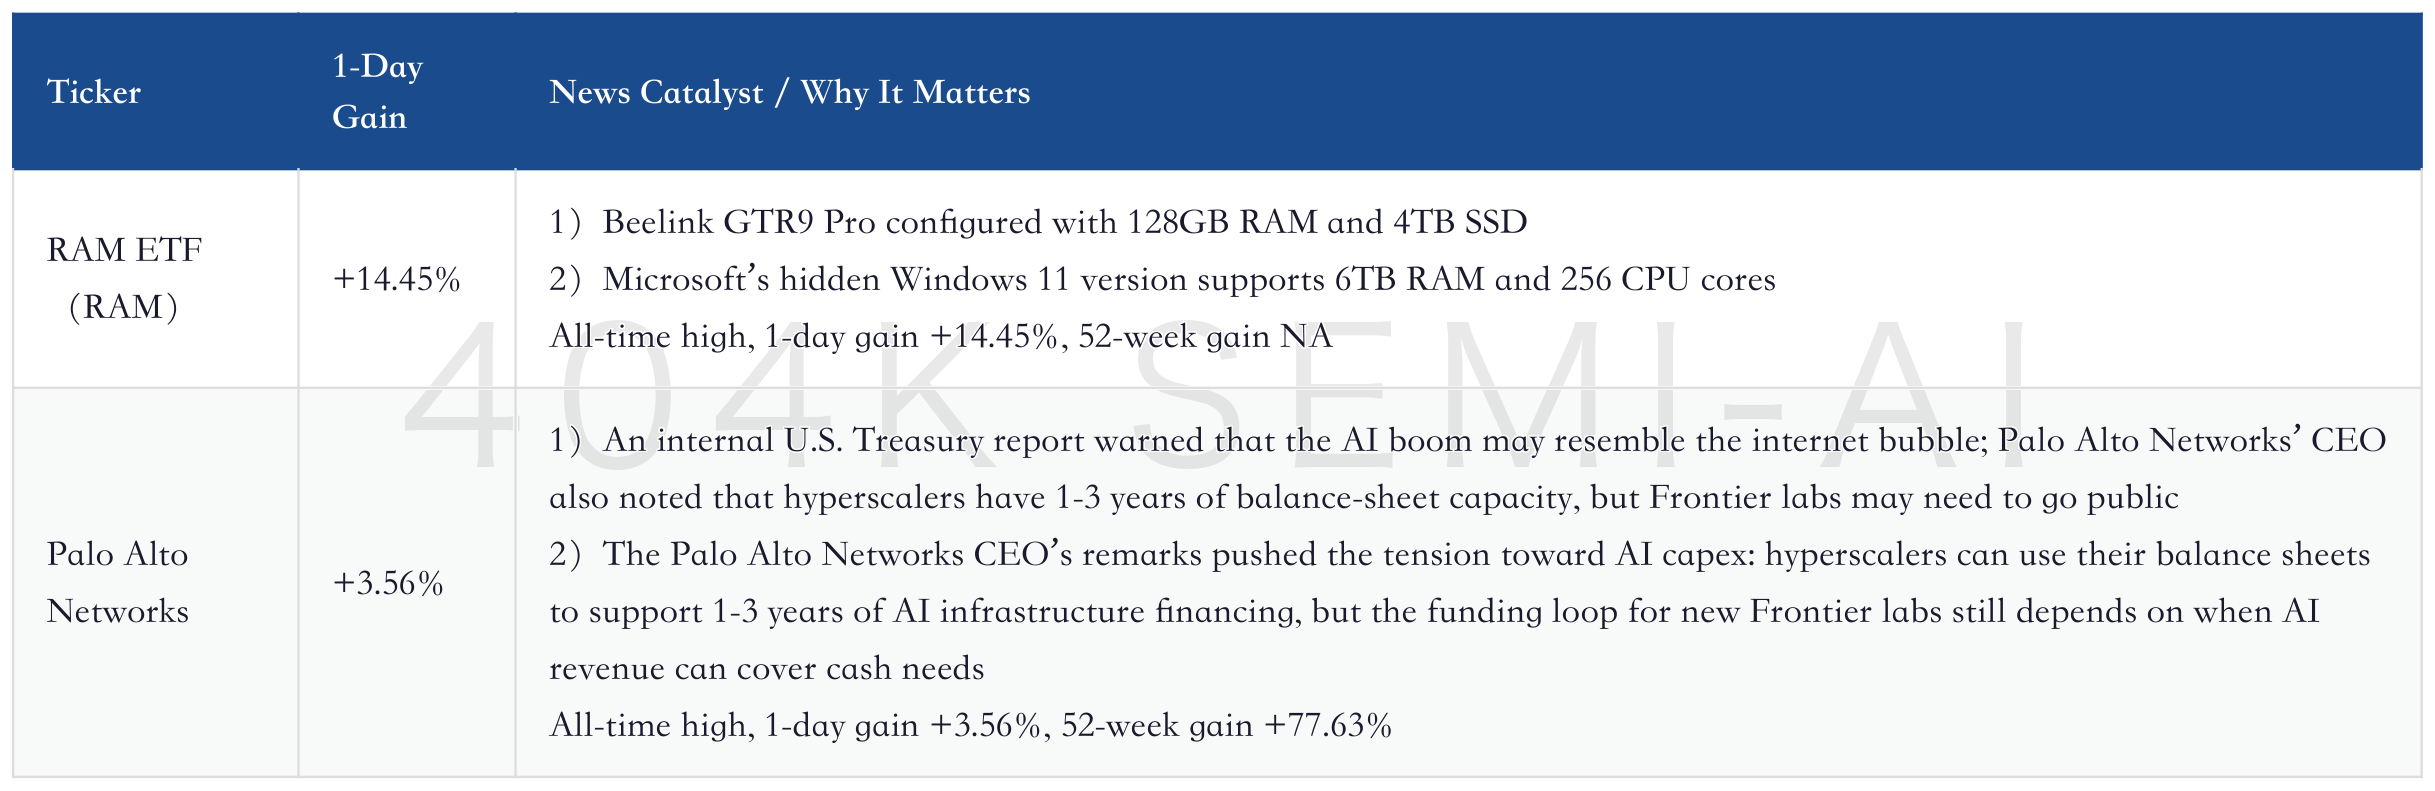
U.S. Stock New Highs
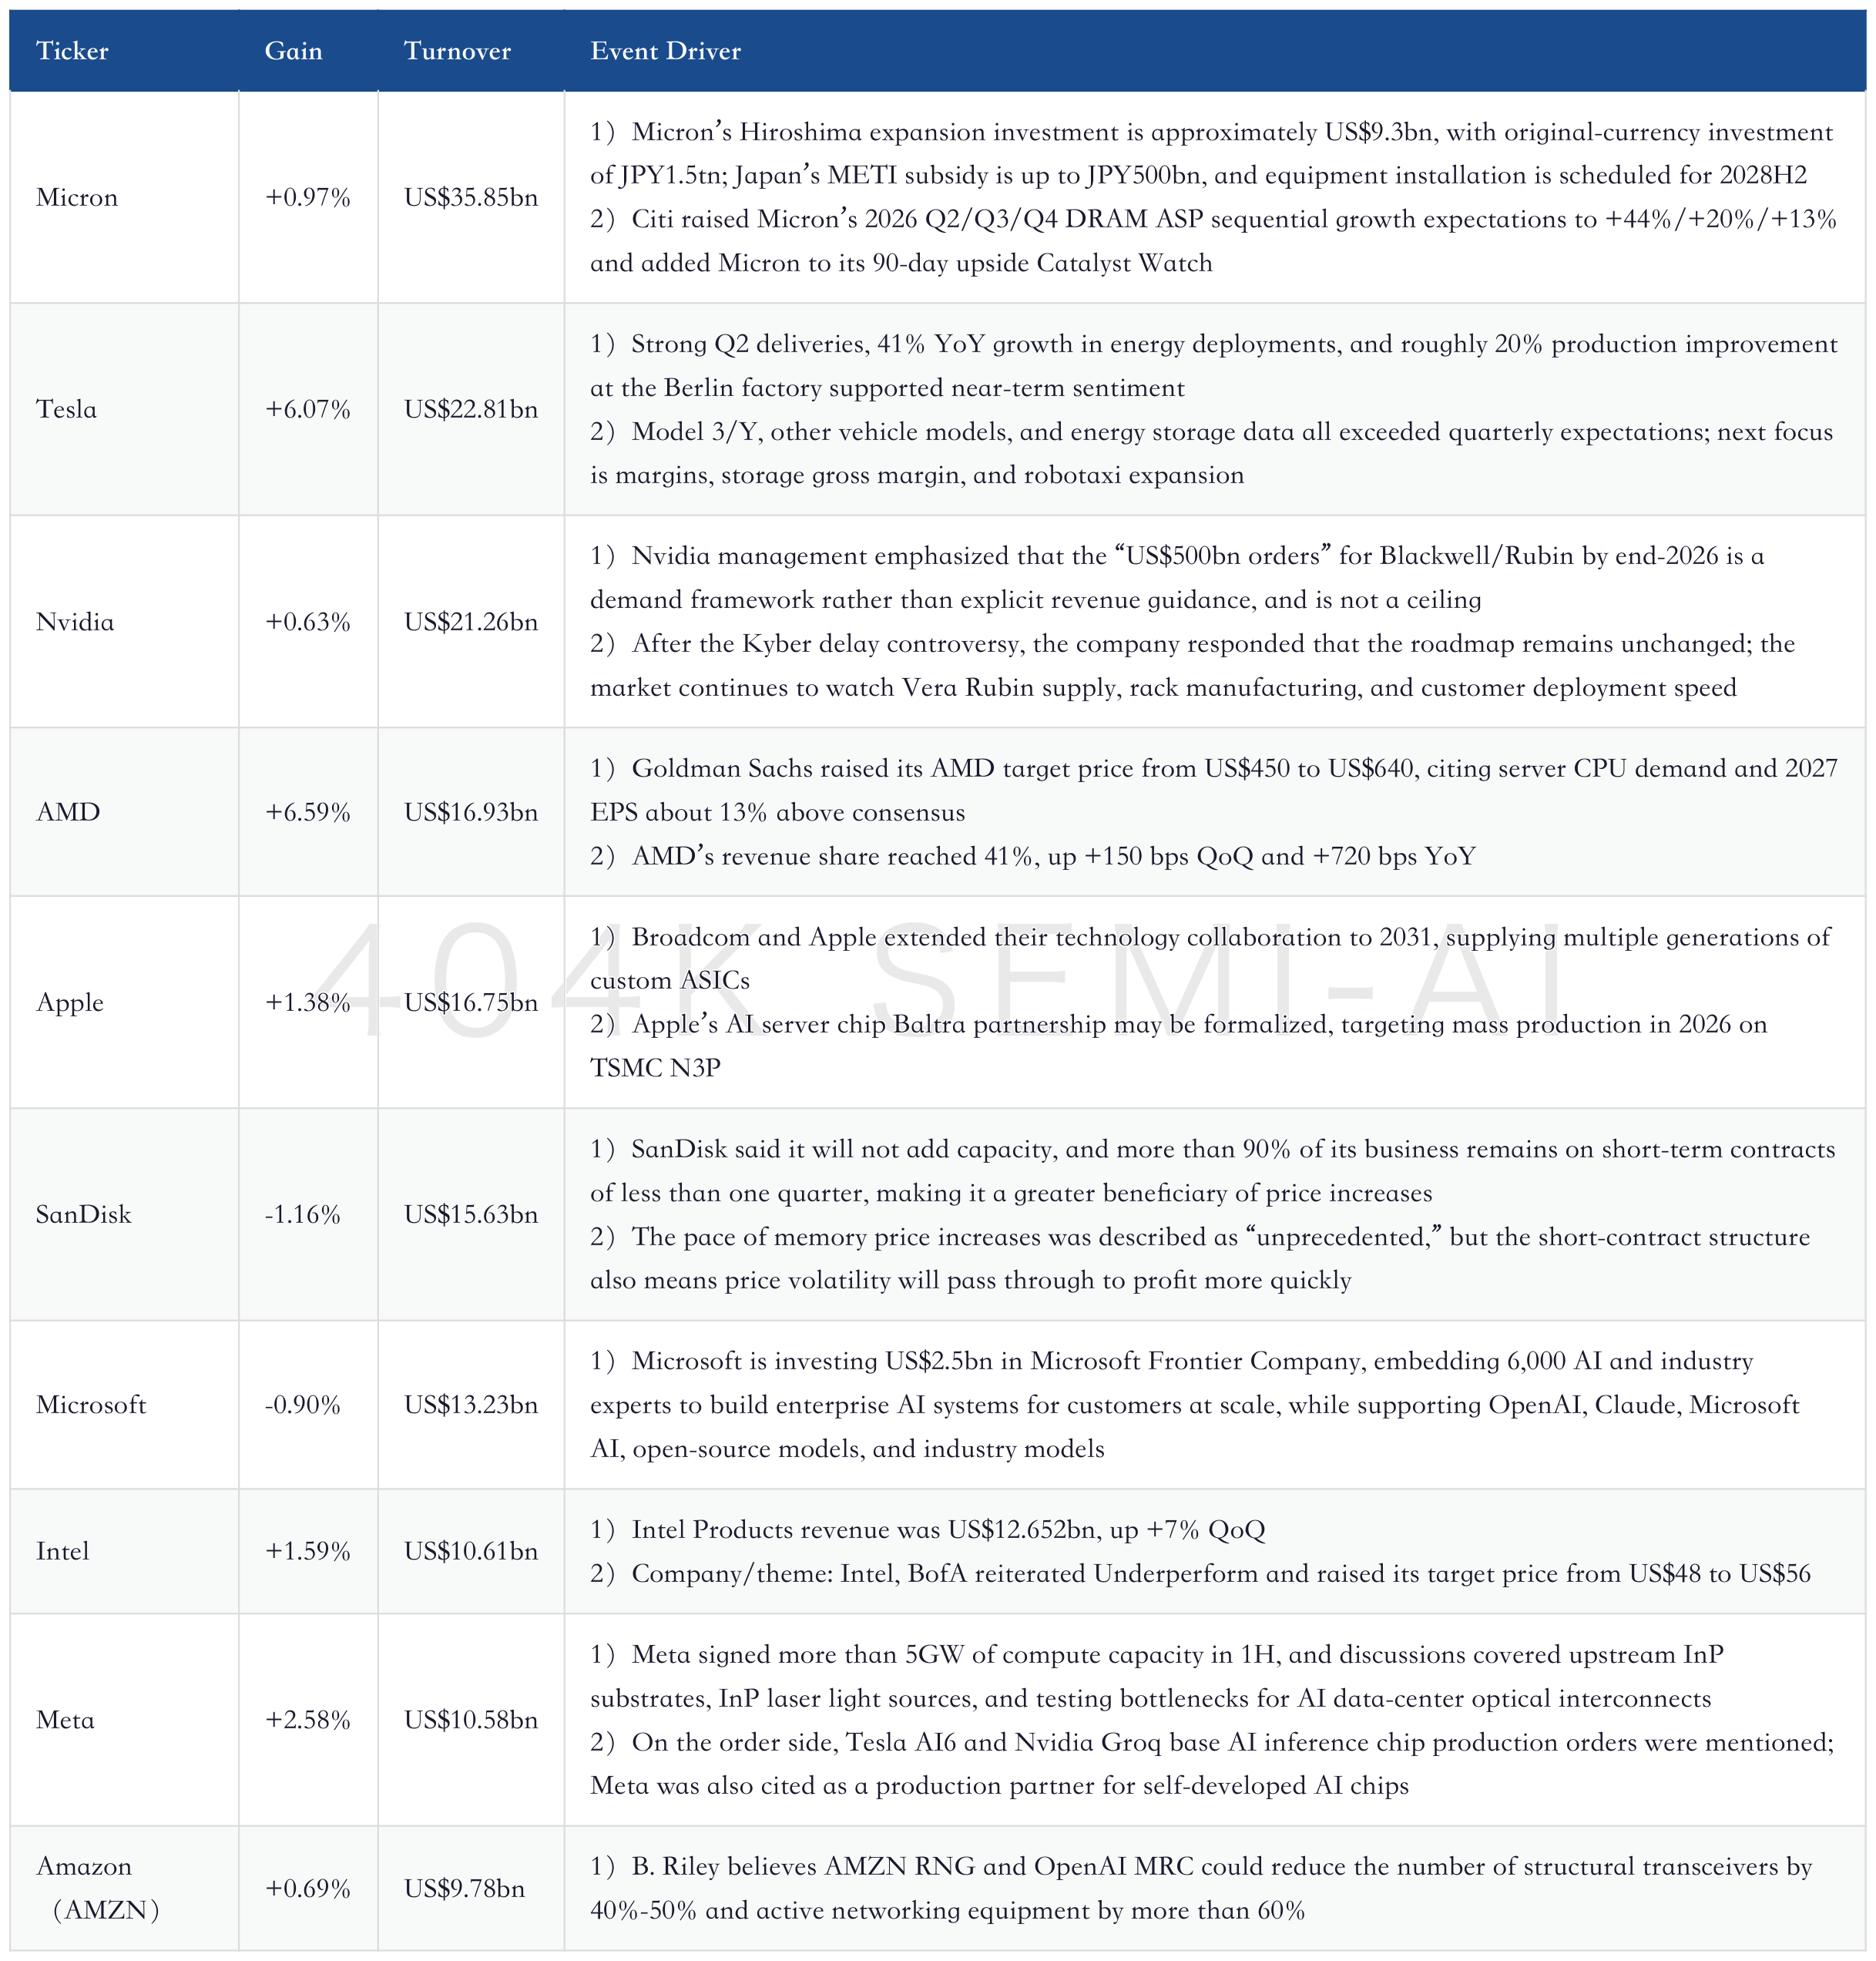
Top 10 U.S. Stocks by Turnover
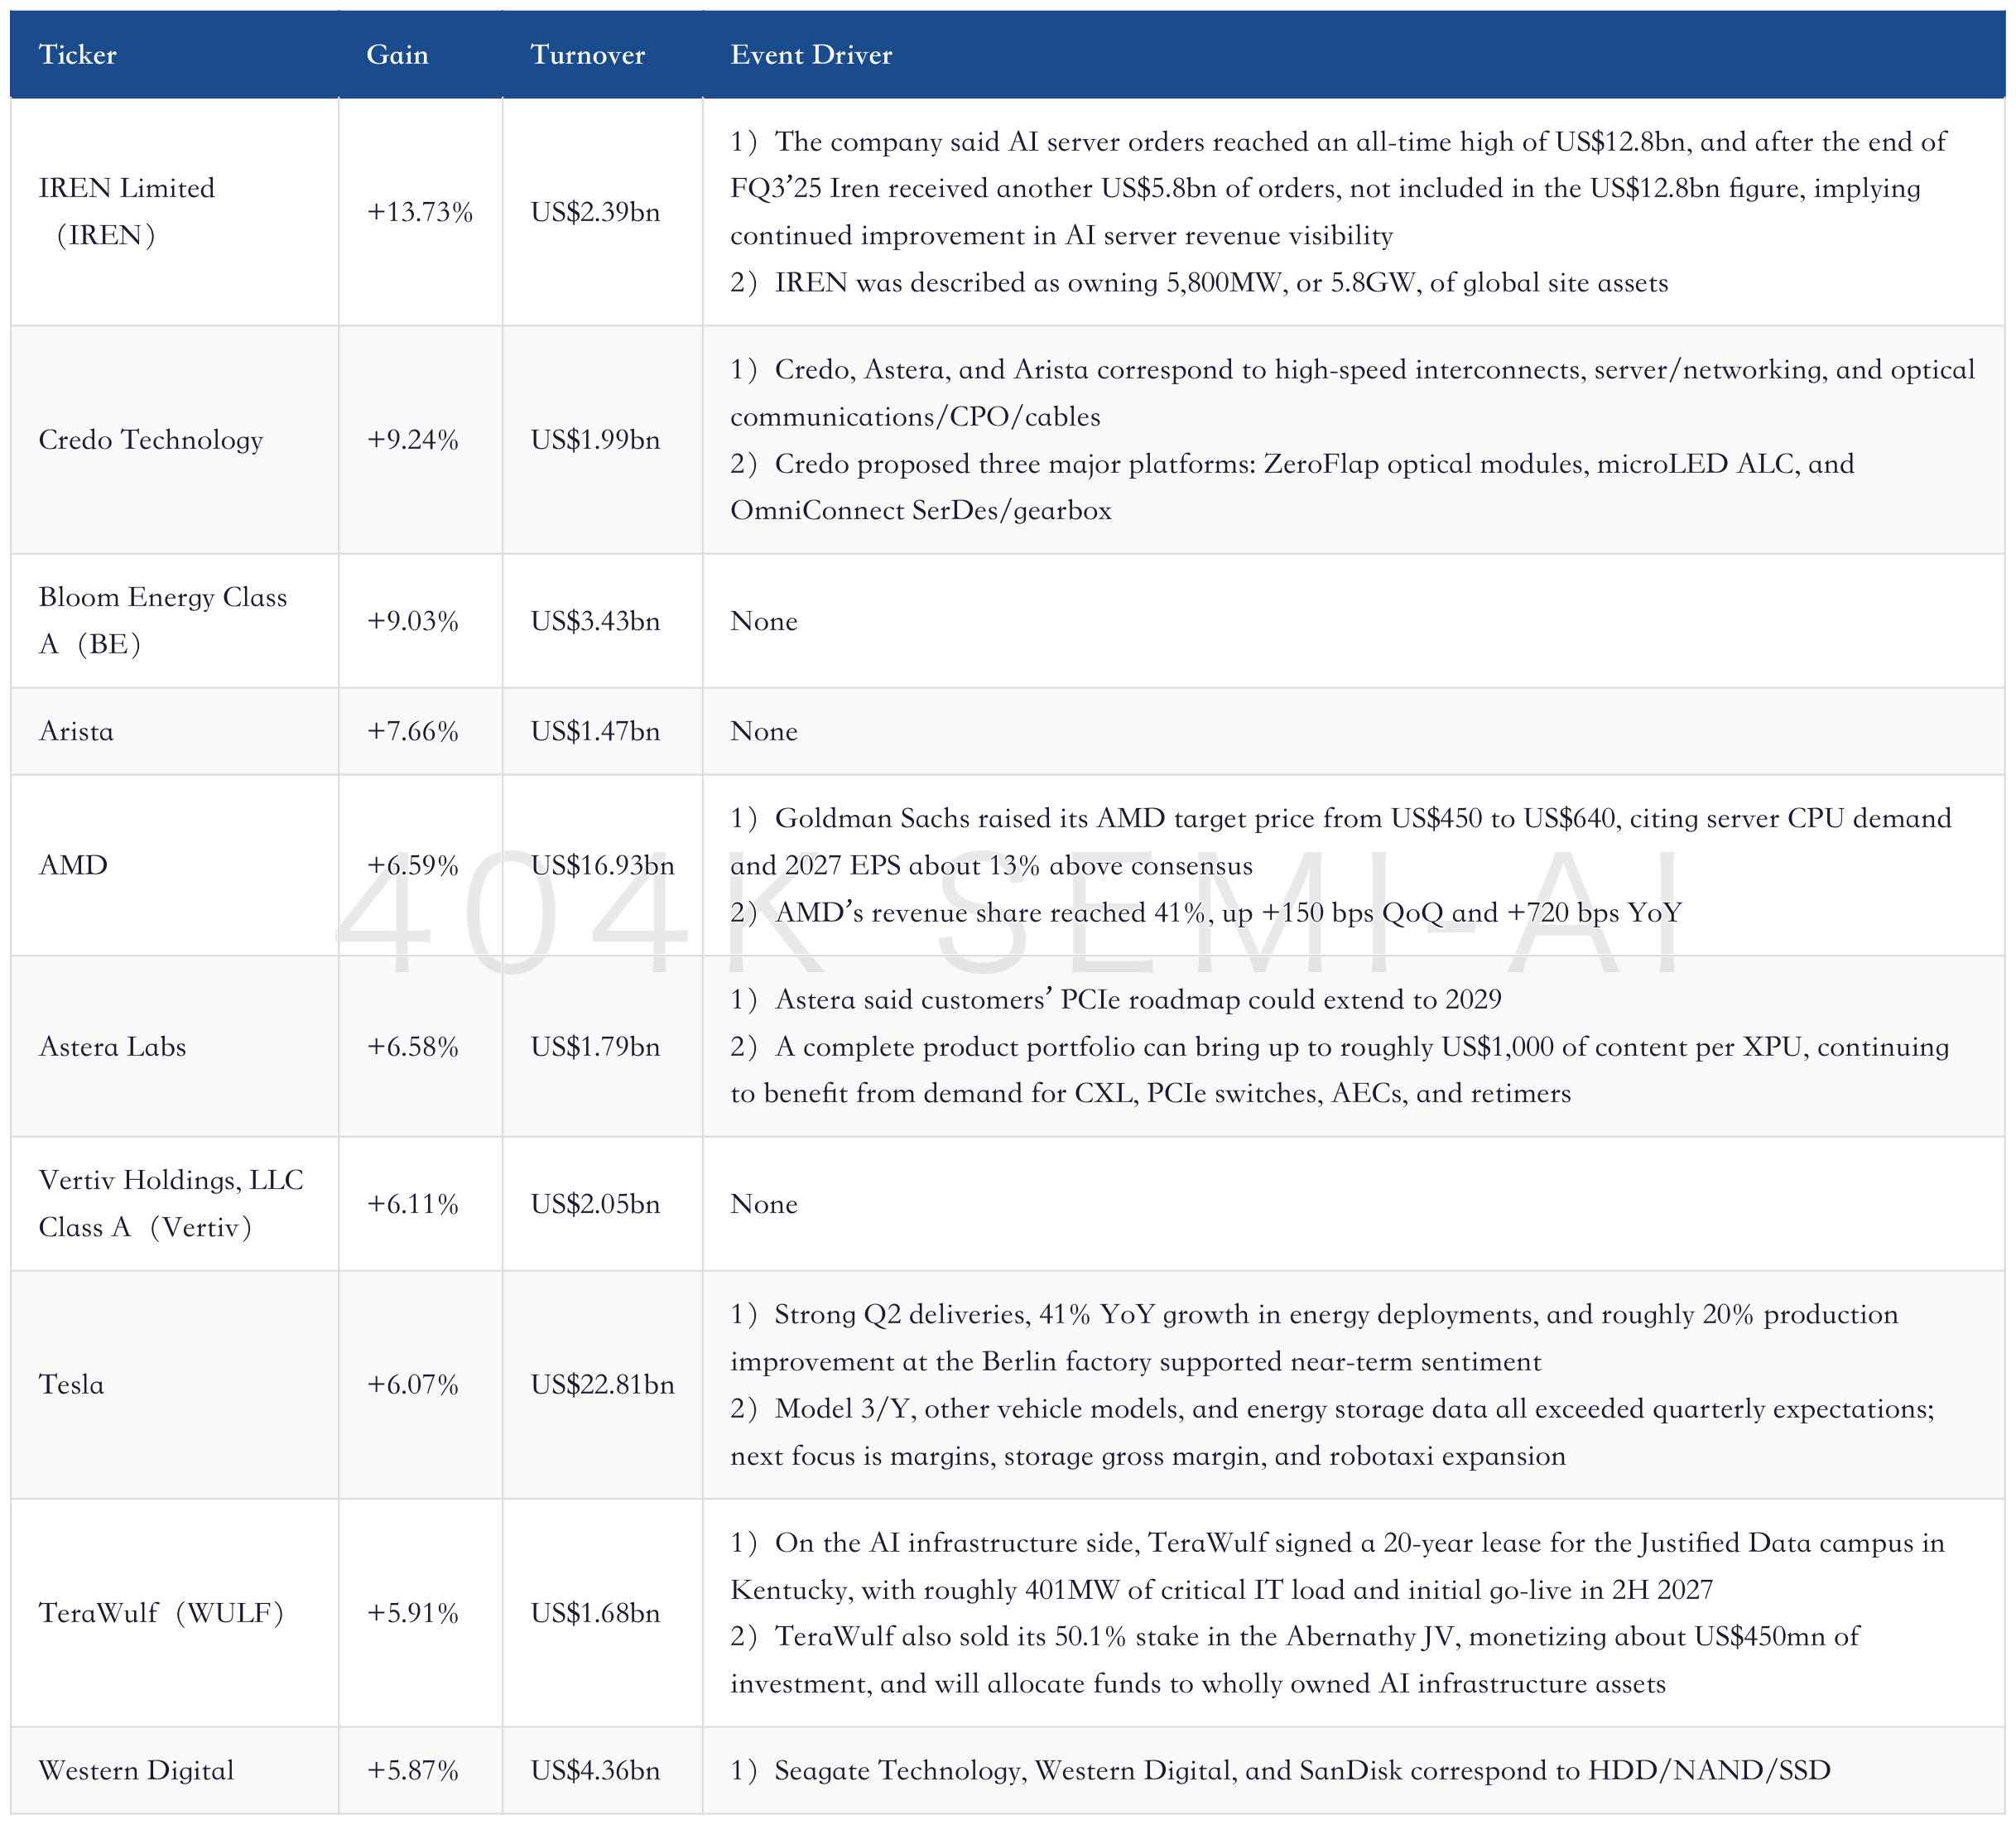
U.S. Stock Gainers
U.S. Stock Decliners
AI/Semiconductor Full Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry
Semiconductor Equipment/Testing
Advanced Packaging/OSAT
MLCC/Passive Components
Optical Communications/Optical Chain
High-Speed Interconnect/Connectors/Thermal and Power
Robotics / Intelligent Driving
Space / Satellites
Internet / Platforms
Software / SaaS
Consumer Electronics / Smart Vehicles
Investment Bank Target Price Changes in the Past 12 Hours
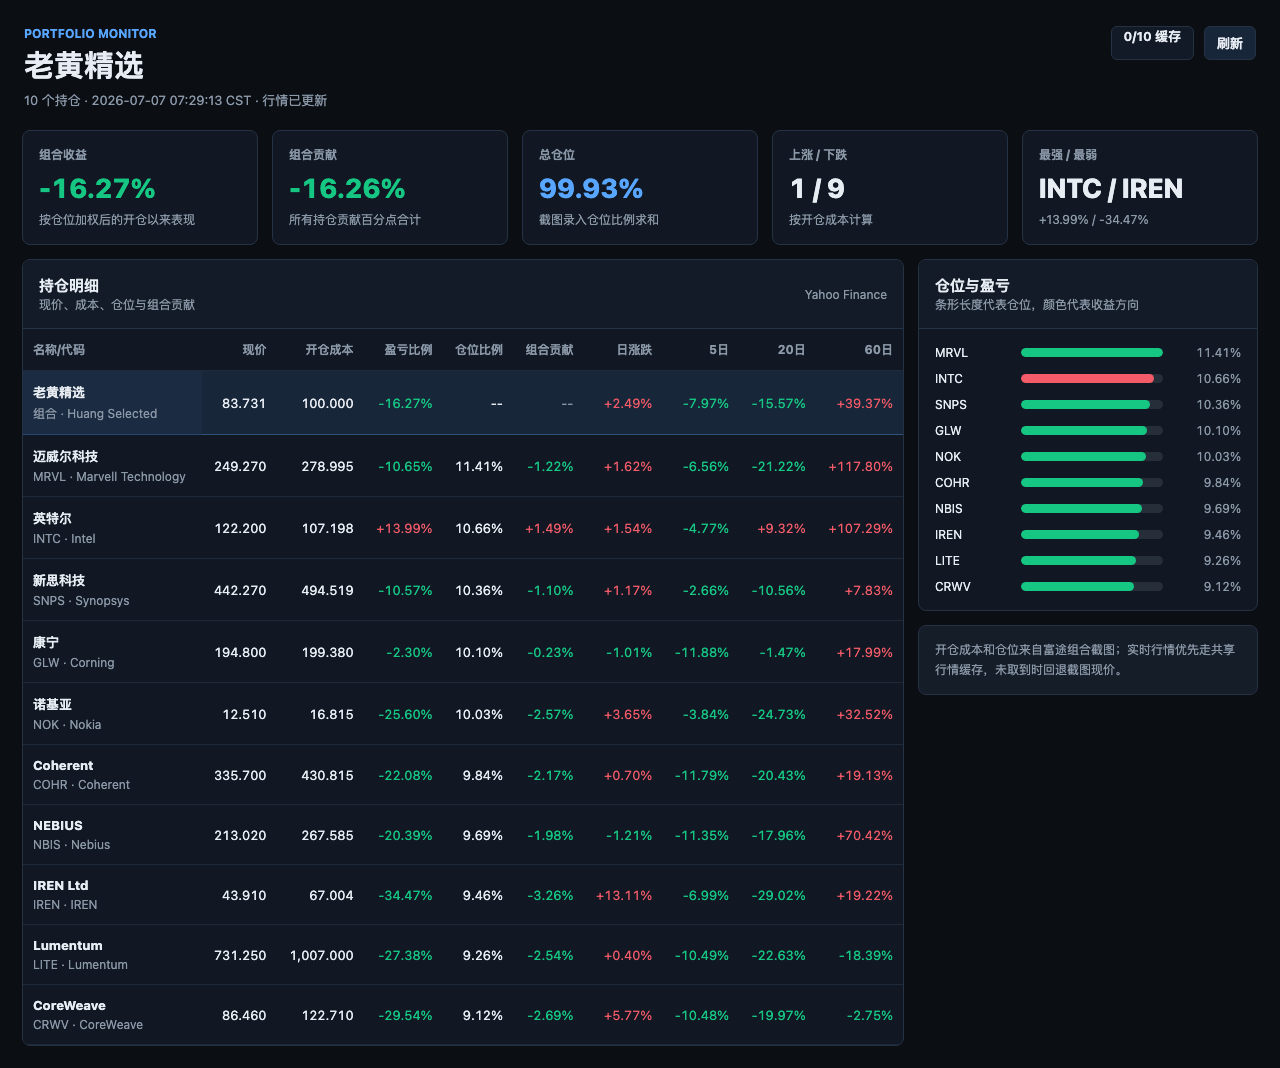
Huang’s Select Portfolio
AI infrastructure trades continue to spread across memory, equipment, data-center power, and interconnects. After-hours technology and semiconductors led gains, with capital most concentrated in memory, AI cloud, and networking adjacencies. But CPO, Kyber, power, and software efficiency are also reminding the market that strong demand does not mean every link in the chain can monetize linearly.
After-Hours Summary
U.S. equities closed on 2026-07-06 with a tilt toward technology growth. The S&P; 500 rose 0.88%, the Nasdaq 100 rose 1.43%, the Dow rose 0.40%, and the Russell 2000 rose 0.44%; the technology ETF rose 1.79%, the semiconductor ETF rose 2.15%, the AI & big data ETF rose 3.48%, and the cloud computing ETF rose 2.00%. The equal-weight index rose only 0.04%, with gains concentrated in a small number of core technology-chain stocks.
Thematic strength looked more like “AI hardware repair + software rebound.” The cybersecurity ETF rose 2.47% over 1 day and 8.84% over 5 days, while the software ETF rose 1.30% over 1 day and 7.47% over 5 days; semiconductors were up 43.06% over 60 days and 62.07% year to date.
Data-center adjacencies and the semiconductor chain absorbed capital. Advanced Micro Devices rose 6.48%, TSMC ADR rose 4.25%, Broadcom rose 3.81%, and Micron rose 1.18%; Credo rose 9.54% and Arista rose 8.64%.
U.S. Stock New Highs
Top 10 U.S. Stocks by Turnover
U.S. Stock Gainers
U.S. Stock Decliners
AI/Semiconductor Full Value Chain
AI Models/Applications and Capital Expenditure
OpenAI/Claude
1. Model revenue growth is still underpinning compute demand. In June, LLM token volume on OpenRouter rose 70% MoM and 20x YoY, while spending rose 70% MoM and 16x YoY. The U.S. share of model volume fell to 35%, but it still captured more than 85% of spending.
2. The divergence between paid models and low-cost open-source models is critical: low-cost models expand usage, while high-performance closed-source models still control paid revenue. This determines whether frontier labs can continue absorbing GPU, memory, and data center contracts.
"Token volume: +70% MoM, 20x YoY; spending: +70% MoM, 16x YoY; pricing: slightly up MoM, still -5% YoY"
AI Application Costs/Local Models
The AI trade is starting to shift from “model capability” to “whether cash flow can cover inference costs.” Palo Alto Networks’ CEO believes hyperscalers can use their balance sheets to support AI infrastructure financing for 1-3 years; Tencent’s Hy3 has 295bn MoE parameters, 21bn active parameters, and a 256K context window, showing that local and edge inference will continue to push down unit costs.
CSP/Cloud Capital Expenditure
Big Four Cloud Providers
2026 hyperscaler capex has repeatedly been cited at roughly $725bn, including about $200bn for Amazon, $190bn for Microsoft, $190bn for Google, and $145bn for Meta. Rising storage costs, tight GPU/ASIC supply, and power-grid interconnection are jointly pushing budgets higher. Late-July earnings calls will be the window to verify whether capex is revised up again.
"Demand has not disappeared; capacity is the bottleneck"
Microsoft/Google/Amazon/Meta
Microsoft invested $2.5bn in Frontier Company and embedded 6,000 AI and industry specialists into customer teams; Google’s upwardly revised TPU supply chain supports Broadcom; Amazon RNG and OpenAI MRC are viewed as potentially reducing active transceiver demand by 40%-50%; Meta has signed multiple compute-capacity agreements on top of its $125bn-$145bn 2026 budget.
Apple/Broadcom
Apple and Broadcom extended their technology collaboration to 2031, with Broadcom to develop and supply custom ASICs for multiple generations of Apple products. The agreement extends Apple supply-chain visibility from WiFi/RF into longer-cycle custom chips.
AI Cloud/Data Center Operators
TeraWulf
1. TeraWulf signed a 20-year lease with a large AI customer for the Justified Data campus in Kentucky, representing about $19bn of contracted revenue and roughly 401MW of critical IT load. Initial capacity is expected to come online in 2H27, with full capacity in early 2028.
2. The company also sold a 50.1% stake in the Abernathy JV, realizing about $450mn to fund wholly owned AI infrastructure assets. For the market, this transaction validates the pricing power of power access and deliverable campuses.
"The lease represents about $19bn of contracted revenue over the initial term. The campus will support about 401MW of critical IT load."
Galaxy Digital/CoreWeave
Galaxy Digital completed Phase I of the Helios AI data center for CoreWeave, delivering 200MW of total power and 133MW of critical IT load. CoreWeave has committed to 526MW across Phases I-III; the Helios campus is approved for 1.63GW and can expand to 3.6GW. Scarce assets in AI cloud are expanding from GPU quotas to power, land, and delivery timelines.
IREN
IREN was among the top gainers. The core catalyst is an RFP for roughly 1.4GW of Australian AI data center capacity, with IREN listed as one of the bidders. A decision is expected in about six weeks and may involve awards to multiple suppliers. The company is described as having 5.8GW of global site assets; the market is now buying the question of whether available power pipelines can translate into contracted revenue.
CoreWeave/Nebius
AI labs’ short-term demand for large-scale compute is creating a market priced at 3-4x normal rates. Whether pricing power can persist depends on power, hardware access rights, and operating-software capabilities.
GPU/CPU/ASIC
NVIDIA
1. NVIDIA rose 0.34%. The move was not strong, but it remains the anchor of the AI supply chain. Management emphasized that “$500bn of orders” for Blackwell/Rubin by the end of 2026 is a demand framework, not revenue guidance.
2. After the Kyber delay controversy, the company responded that the “roadmap remains unchanged.” The market needs to verify Vera Rubin supply, rack manufacturing, and customer deployment speed.
"customers' biggest anxiety...procure enough NVIDIA product generally, and Vera Rubin specifically"
AMD
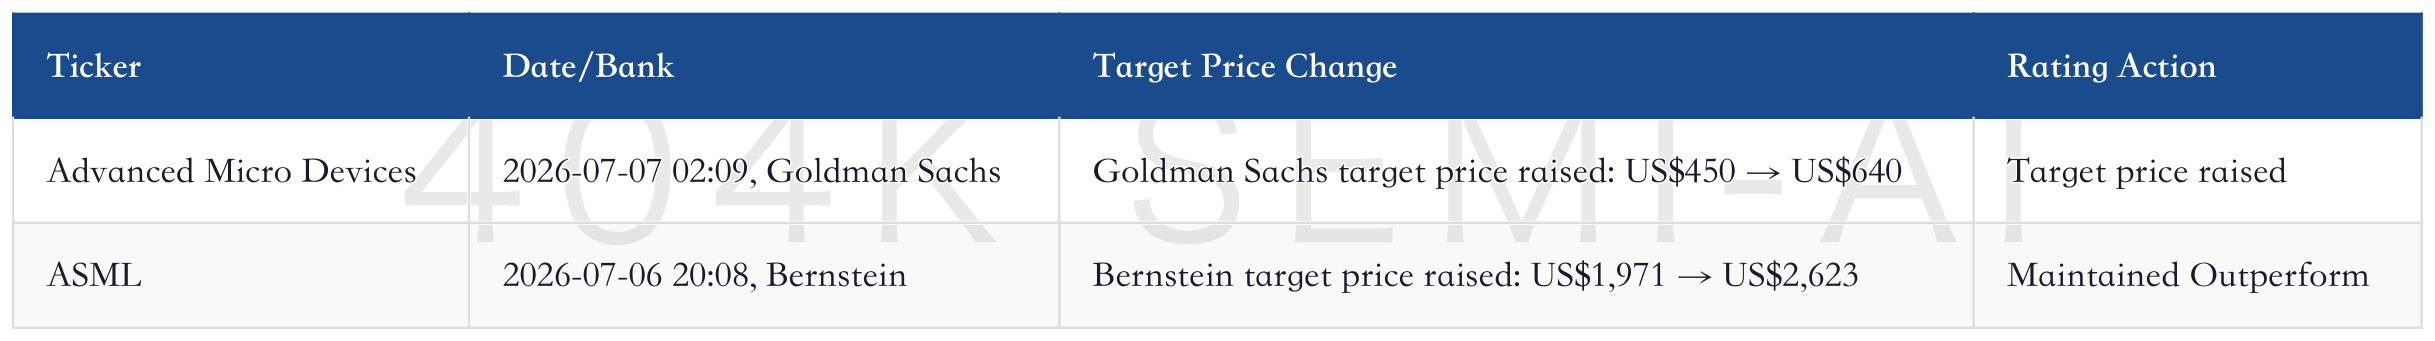
1. Advanced Micro Devices rose 6.48%. Goldman Sachs raised its price target from $450 to $640 and said it remains one of its preferred long-term semiconductor longs. Goldman expects server CPU demand to drive quarterly earnings above expectations, with 2027 EPS 13% above consensus.
2. AMD’s trading logic has shifted from “NVIDIA substitute” to “CPU share + MI roadmap + Kyber delay window.” If NVIDIA rack momentum slows, MI450/Helios and server CPUs will gain more negotiating room.
"Goldman Sachs raised its Advanced Micro Devices price target from 450 to 640"
Intel
1. Intel rose 1.68%, with the widest market disagreement. HSBC maintained Buy and raised its price target from $100 to $200, citing server CPU demand driven by agentic AI and inclusion of Foundry in SOTP valuation. Its 2027 DCAI revenue forecast is $33bn, 20% above consensus.
2. BofA and Jefferies are more cautious, noting that external customers for 18A/14A, Foundry yields, and the AI accelerator roadmap remain unproven. Intel is better tracked through DCAI supply, external foundry customers, and EMIB packaging orders, rather than only through CPU demand recovery.
Broadcom
Broadcom rose 3.81%, with AI ASICs and the Apple collaboration both supporting valuation. The Apple agreement was extended to 2031, improving visibility for a low-teens revenue customer and potentially formalizing cooperation on Apple’s Baltra AI server chip.
Qualcomm
Qualcomm rose 6.10%. A leaked iPhone 18 Pro BOM shows U.S. models still using the full Qualcomm suite, which may create upside to revenue previously modeled on a “zero relationship” basis. Reports of negotiations to acquire Modular for about $4bn point to the AI data center software stack.
HBM/DRAM/NAND/SSD/HDD
Micron
1. Micron closed up 1.18% with high trading value, as capital continues to trade DRAM/HBM supply constraints. Citi raised its Micron DRAM ASP growth assumptions for 2Q/3Q/4Q 2026 to +44%/+20%/+13% QoQ and added Micron to its 90-day upside Catalyst Watch.
2. Micron’s Hiroshima expansion investment is about $9.3bn, with original-currency investment of JPY1.5tn and up to JPY500bn of subsidies from Japan’s METI. Equipment installation is scheduled for 2H28. The expansion is large, but offers limited help for the current 2026-2027 shortage.
Samsung Electronics
Samsung Electronics’ memory line remains the anchor of profit elasticity. Meritz expects 2Q26 operating profit of KRW90.1tn, sales of KRW182.1tn, and an operating margin of 49.5%, raising its target price from KRW420,000 to KRW500,000. DRAM BG/ASP are +12%/+50%, and NAND BG/ASP are +3%/+63%. The risk is that terminal businesses such as MX/VD are squeezed by chip price increases, so profit is not benefiting across all segments.
SK Hynix
Both signals from SK Hynix point to expansion financing: first, a planned U.S. ADS issuance described as 177.9mn ADS, equivalent to 17.79mn ordinary shares, with potential proceeds of about $28bn; second, about $8bn of ASML EUV orders, roughly 20 tools, for delivery before December 2027. In the short term, HBM is in shortage; in the medium term, capital and equipment delivery will determine capacity release.
SanDisk/Western Digital/Seagate Technology
SanDisk fell 0.21%, Western Digital rose 6.90%, and Seagate Technology rose 6.08%. SanDisk said it is not adding capacity, and more than 90% of its business remains on short contracts of less than one quarter. TD Cowen also prefers both NAND and HDD because near-term supply additions are limited.
Foundry
TSMC
TSMC ADR rose 4.25%, with upward revisions for both advanced nodes and silicon-photonics PIC. Citi expects combined N2/A16/N3 capacity to reach 350,000-400,000 wafers per month by the end of 2028. Supply-chain sources say TSMC’s PIC capacity will expand from 10,000 wafers per month in 2026 to 15,000 wafers per month in 4Q26, and at least 25,000 wafers per month in 2028. The key question for foundry is not whether demand exists, but whether advanced capacity, packaging, and testing can all keep up.
Samsung Electronics Foundry
Samsung Electronics Foundry is showing signs of profit recovery. SK Securities said Samsung Electronics’ foundry division was profitable on a monthly basis in June 2026, for the first time since 2023, partly because HBM4 base die ramped on the 4nm process and 4nm yield rose to about 80%. But in 1Q26, global foundry share was 72.3% for TSMC and 6.5% for Samsung Electronics, leaving a still-large gap.
Intel Foundry
The bull-bear debate on Intel Foundry is centered on 14A and external customers. HSBC raised its Foundry revenue forecast to $23.5bn in 2026 and $27.5bn in 2027. BofA argues that unless external business can reach at least above $10bn, EPS accretion will be limited. Investors need to see real customers, not only the scarcity value of manufacturing assets.
Semiconductor Equipment/Testing
ASML
ASML rose 3.15%. Bernstein raised its price target from $1,971 to $2,623 and maintained Outperform. It expects 2030 revenue of EUR80bn, a 20% CAGR, and EUV shipments of 91 units in 2027, 113 units in 2028, and 125 units in 2030. SK Hynix’s roughly $8bn EUV order reinforces the main theme that memory is pulling equipment first.
"AI-driven WFE spending remains strong, with visibility now extending into 2028."
Applied Materials/Lam Research/KLA
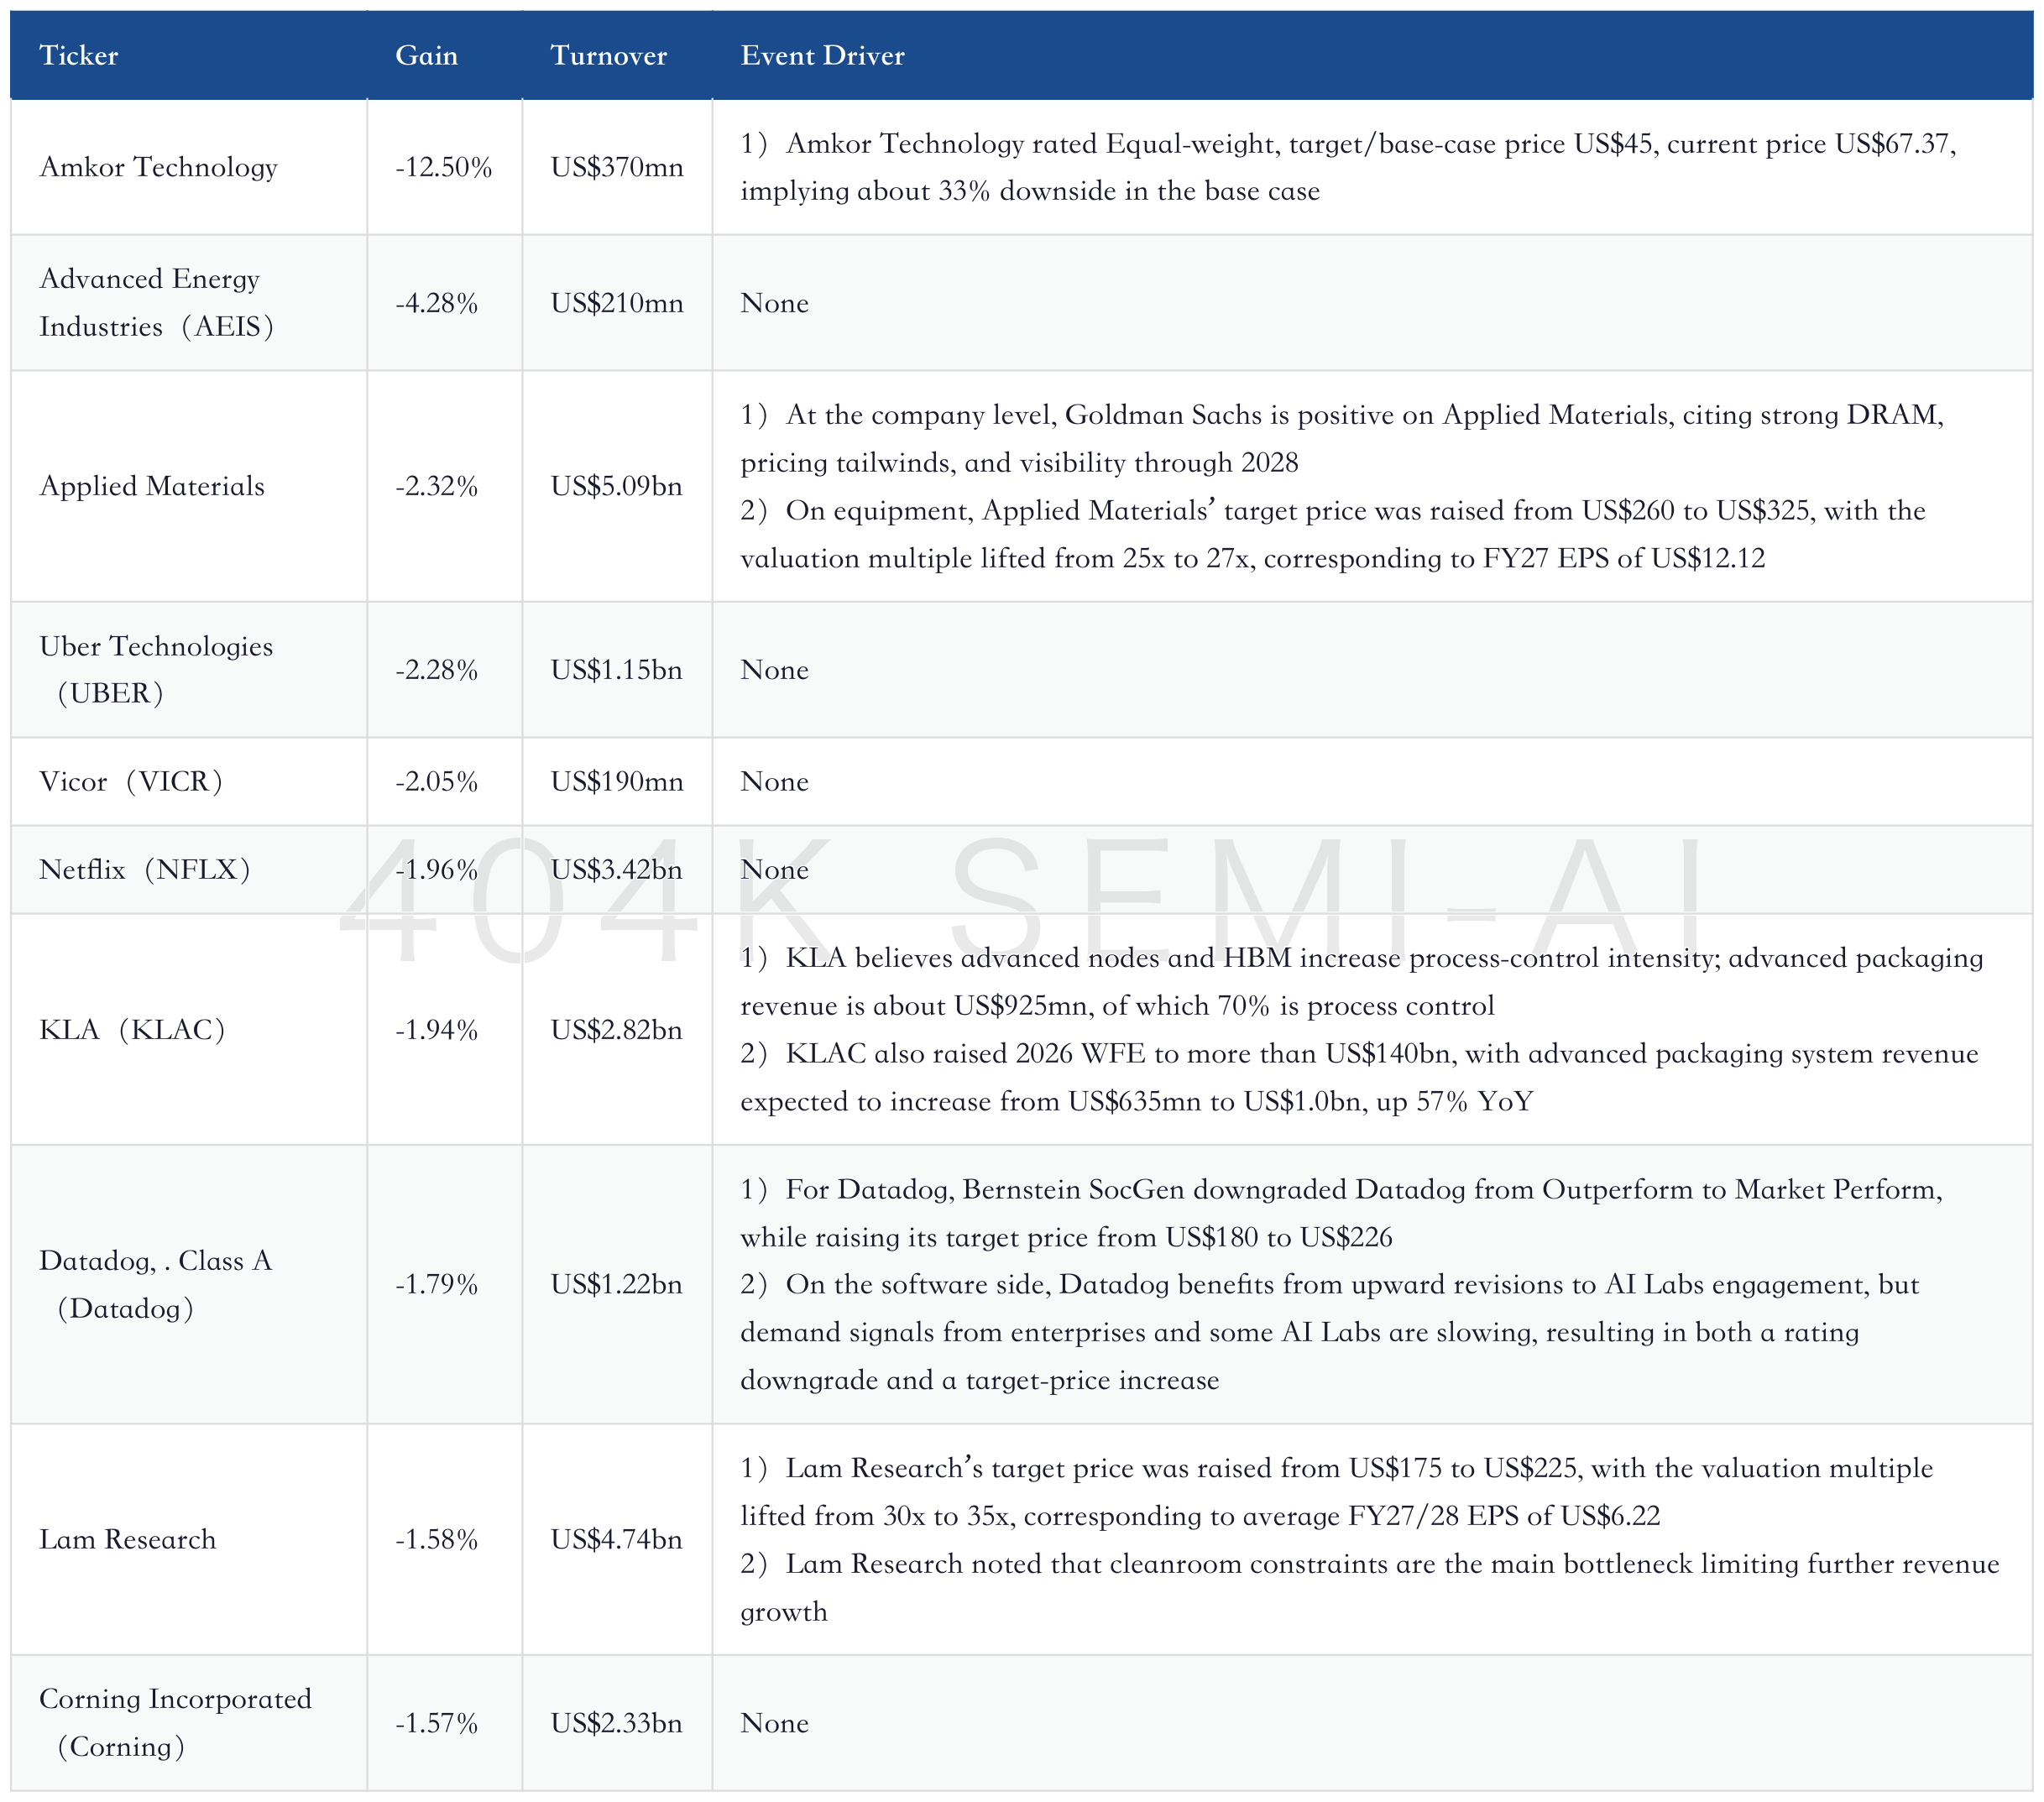
Applied Materials fell 1.40%, but Goldman still favors strong DRAM, pricing tailwinds, and visibility through 2028. In the equipment table, Applied Materials’ target price was raised from $260 to $325. Lam Research’s target price was raised from $175 to $225 on NAND, DRAM/HBM, advanced packaging, and dry EUV patterning. KLA is more mixed in the near term because of a DRAM-heavy WFE mix and valuation constraints.
Teradyne/Advantest
Teradyne rose 3.19%, and Advantest ADR rose 5.38%. Test equipment benefits from rising test intensity for GPUs, ASICs, DRAM, and HBM, though the larger contribution from GPU testing may come after CY27. KLA noted about $925mn of advanced-packaging revenue, of which 70% is process control, showing that testing and process control are benefiting from rising advanced-packaging complexity.
Advanced Packaging/OSAT
Advanced Packaging Chain/Amkor
The AI supply bottleneck has expanded from CoWoS to HBM, EMIB, hybrid bonding, and CPO testing. KLA’s advanced-packaging revenue is about $925mn, of which 70% is process control. Amkor fell 12.50%, reflecting the market’s greater focus on the OSAT profit path.
MLCC/Passive Components
Murata/Samsung Electro-Mechanics/Taiyo Yuden/Yageo
High-end MLCC shortages are starting to be amplified by AI servers. Goldman said Yageo and Japanese and Korean suppliers are shifting capacity from commodity MLCCs to high-margin AI-grade MLCCs. It expects 14% of global MLCC capacity to be used for AI in 2026, rising to 32% by 2028. Murata, Samsung Electro-Mechanics, and Taiyo Yuden had late-June BB ratios of 1.30, 1.31, and 1.25, respectively, indicating orders are already clearly exceeding capacity.
Optical Communications/Optical Chain
CPO/Optical Module Chain
Morgan Stanley expects CPO switch shipments to increase from 23,000 units in 2026 and 59,000 units in 2027 to 200,000 units in 2030, a 144% CAGR for 2024-2030. Insertion 2 wafer-level testing has already been shortened from a full day per wafer to six hours, with a target of reducing it to 3-4 hours over the next 6-12 months. The near-term debate is whether Kyber/CPO delays will pressure demand; current evidence looks more like the window is shifting toward 800G/1.6T pluggables, AEC, and DSP.
"CPO switch shipments...23k units in 2026...200k units by 2030"
AAOI/Credo/Astera
Credo rose 9.54%, Astera rose 6.54%, while AAOI faced pressure from architecture changes. B. Riley’s negative view on AAOI is that Amazon RNG and OpenAI MRC are structurally flattening networks, reducing active transceiver demand by 40%-50%. Credo and Astera’s relative advantage lies in SerDes, gearbox, AEC, PCIe/CXL, and other interconnect content that can more easily migrate as rack architectures change.
Coherent/Ciena/Corning
Scale-across networks connect multiple data centers into a single cluster, driving content for ZR/ZR+ coherent pluggables and Optical Line Systems. Related estimates put pure scale-across content at about $3bn in 2026, rising to about $14bn in 2028.
High-Speed Interconnect/Connectors/Thermal and Power
Arista/Credo/Astera
Arista rose 8.64%, Credo rose 9.54%, and Astera rose 6.54%, showing that capital is betting network and interconnect will monetize faster than standalone CPO. Astera said customer PCIe roadmaps may extend to 2029, and its full product portfolio can provide up to about $1,000 of content per XPU.
Vertiv / Eaton / Power Chain
Vertiv rose 5.97%, Eaton rose 3.74%, and power and thermal management continued to benefit from AI data-center constraints. Bernstein’s teardown of a 1GW data center shows GB200/NVL72 racks at roughly $3.4 million, plus about $2.5 million of physical infrastructure per rack, for a total of roughly $5.9 million per rack. Power and thermal management are not the largest cost items, but they are the easiest links to block deployment.
Robotics / Intelligent Driving
Tesla
Tesla rose 6.66%. The near-term catalyst came from Q2 deliveries beating expectations, energy deployments growing 41% YoY, and roughly 20% production improvement at the Berlin plant. What really needs to be tracked is whether margins, storage gross margin, and robotaxi expansion can materialize.
Space / Satellites
Space Data Centers
Bernstein believes thermal management for 20-100kW-class in-orbit computing satellites is technically “plausible / doable,” but the economics remain constrained by launch costs. A 20kW satellite’s five-year electricity consumption corresponds to about $44,000-$219,000 in ground-based power costs, while current launch cost is about $1.7 million. For the solution to be viable, launch costs need to fall from several thousand dollars per kilogram to several hundred dollars, and power density needs to rise to 60-100kW/ton.
Internet / Platforms
Meta
Meta rose 2.87%. The main thread is its AI infrastructure commitment beyond the advertising platform. The company’s 2026 capex budget has been repeatedly cited at roughly $145 billion, and on top of that it has signed a $27 billion five-year agreement with Nebius, a $21 billion expansion agreement with CoreWeave, and an approximately 1.6GW capacity agreement with Crusoe. Meta’s question is not whether it is willing to invest, but whether the spending can translate into recommendation systems, model capability, and advertising returns.
Google
Google rose 1.82%, with progress appearing simultaneously in TPUs, Gemini, and Maps monetization. Upward revisions in Google’s TPU supply chain support Broadcom’s ASIC revenue. TurboQuant reduces KV cache memory requirements by as much as 5/6 and can accelerate GPU inference by up to 8x. Reports say Google Maps may use Gemini as an entry point for restaurant discovery and ordering, potentially affecting local-services platforms such as DoorDash and Uber Eats.
Amazon
Amazon rose 0.55%, with AWS AI infrastructure still the main thread. AWS has raised Q3 2026 ASIC server shipments by 20%-30% versus the original plan. Trainium 2 is sold out, Trainium 3 is almost fully reserved, Trainium 4 already has reservations, and Trainium 5 has started development. The negative variable is that the RNG network architecture may reduce the use of active optical transceivers. Self-developed chips benefiting does not mean all optical-module suppliers benefit.
Apple
Apple rose 1.29%. Its multi-year ASIC agreement with Broadcom was the hard news of the day. The two parties extended their long-term technology partnership to 2031, with Broadcom developing and supplying custom ASICs for future generations of Apple products. Reports say the foldable iPhone will be priced at roughly $2,300-$2,500, with first shipments of 7 million-8 million units in the second half, but this is more of a consumer-electronics demand anchor and should not be mixed with AI server orders.
Reddit
Reddit’s AI data-licensing logic continues to improve. After upgrading its LLM-based system, the company captures about 25,000 net new spam posts and comments per day, blocks about 23 million spam-content views, and reverses nearly 2 million inauthentic votes. Improved content quality strengthens the basis for licensing negotiations with model companies such as Google and OpenAI.
Netflix / Uber / DoorDash
Netflix fell 2.14%, Uber fell 2.28%, and DoorDash was affected by Google Maps’ potential ordering feature. The marginal change for platform stocks comes from traffic entry points and AI search rewrites; customer acquisition costs and commission rates will both be revisited.
Software / SaaS
Microsoft
Microsoft fell 0.89%, with enterprise AI investment coexisting with contraction in the gaming business. The company is investing $2.5 billion to build Frontier Company, embedding 6,000 AI and industry experts to serve customers. On the other side, Xbox has reportedly seen layoffs, studio adjustments, and commentary about relatively low margins. For Microsoft, AI cloud and enterprise software are areas of increased investment, while gaming content is an area for cost reduction.
Snowflake
Snowflake rose 0.75%. The core is enterprise data governance and the AI layer. A Benchmark-related report said Snowflake is building AI around governed enterprise data, expanding the use of Claude within Cortex AI, and reducing the need to move sensitive data into standalone systems. The investment implication is that enterprise AI budgets are more likely to flow to platforms where “data stays where it is, and models are invoked through the governance layer.”
Datadog
Datadog fell 1.92%. Bernstein SocGen downgraded the rating from Outperform to Market Perform, but raised the target price from $180 to $226, reflecting the divergence: AI Labs engagement and product demand were revised upward, while signals from enterprises and some AI Labs slowed and weighed on the rating. Software stocks can no longer be assessed only by AI engagement; renewals, seats, and platform gross margin also matter.
Palo Alto Networks / CrowdStrike
Palo Alto Networks reached an all-time high, and CrowdStrike rose 2.78%. Cybersecurity led five-day gains for a direct reason: AI expands the attack surface and also increases the automation value of security platforms. PANW’s CEO’s comments on AI capex financing also serve as a reminder that rising security demand and AI infrastructure bubble risk may coexist.
Salesforce / SAP
Salesforce fell 0.07%. Signals that smaller companies are using Claude-like tools to replace traditional enterprise applications suggest a risk that seat-based software budgets may be compressed. On SAP’s side, automotive SCM software spending is expected to grow at a roughly 14% CAGR through 2030, and supply-chain control towers remain an incremental direction for enterprise software.
Consumer Electronics / Smart Vehicles
Tesla / Autonomous Driving
Tesla’s near-term fundamentals come from deliveries and energy storage, while the long term still depends on autonomous driving and real-world AI. Q2 deliveries beat expectations, energy deployments grew 41% YoY, and Berlin plant output improved by roughly 20%. If robotaxi expands to more cities, the validation point will shift from shipment volume to unit economics and regulatory cadence.
Qualcomm / Apple Baseband
The leaked iPhone 18 Pro BOM shows U.S. models still using Qualcomm’s SDX80M modem, SDR875 transceiver, PMX75, QET7100A, and mmWave AiP, while international models use Apple’s C2 modem. If teardown in September confirms this, U.S. mmWave iPhones will become upside outside Qualcomm’s model, easing the revenue pressure from Apple’s in-house modem.
Investment Bank Target Price Changes in the Past 12 Hours
Huang’s Select Portfolio
404K SEMI-AI Tech Morning Brief 2026-07-07 — Memory Price Increases, AI Data Centers Heat Up, Optical Interconnect Divergence
目录
After-Hours Summary
U.S. Stock New Highs
Top 10 U.S. Stocks by Turnover
U.S. Stock Gainers
U.S. Stock Decliners
AI/Semiconductor Full Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry
Semiconductor Equipment/Testing
Advanced Packaging/OSAT
MLCC/Passive Components
Optical Communications/Optical Chain
High-Speed Interconnect/Connectors/Thermal and Power
Robotics / Intelligent Driving
Space / Satellites
Internet / Platforms
Software / SaaS
Consumer Electronics / Smart Vehicles
Investment Bank Target Price Changes in the Past 12 Hours
Huang’s Select Portfolio
AI infrastructure trades continue to spread across memory, equipment, data-center power, and interconnects. After-hours technology and semiconductors led gains, with capital most concentrated in memory, AI cloud, and networking adjacencies. But CPO, Kyber, power, and software efficiency are also reminding the market that strong demand does not mean every link in the chain can monetize linearly.
After-Hours Summary
U.S. equities closed on 2026-07-06 with a tilt toward technology growth. The S&P; 500 rose 0.88%, the Nasdaq 100 rose 1.43%, the Dow rose 0.40%, and the Russell 2000 rose 0.44%; the technology ETF rose 1.79%, the semiconductor ETF rose 2.15%, the AI & big data ETF rose 3.48%, and the cloud computing ETF rose 2.00%. The equal-weight index rose only 0.04%, with gains concentrated in a small number of core technology-chain stocks.
Thematic strength looked more like “AI hardware repair + software rebound.” The cybersecurity ETF rose 2.47% over 1 day and 8.84% over 5 days, while the software ETF rose 1.30% over 1 day and 7.47% over 5 days; semiconductors were up 43.06% over 60 days and 62.07% year to date.
Data-center adjacencies and the semiconductor chain absorbed capital. Advanced Micro Devices rose 6.48%, TSMC ADR rose 4.25%, Broadcom rose 3.81%, and Micron rose 1.18%; Credo rose 9.54% and Arista rose 8.64%.
U.S. Stock New Highs
Top 10 U.S. Stocks by Turnover
U.S. Stock Gainers
U.S. Stock Decliners
AI/Semiconductor Full Value Chain
AI Models/Applications and Capital Expenditure
OpenAI/Claude
1. Model revenue growth is still underpinning compute demand. In June, LLM token volume on OpenRouter rose 70% MoM and 20x YoY, while spending rose 70% MoM and 16x YoY. The U.S. share of model volume fell to 35%, but it still captured more than 85% of spending.
2. The divergence between paid models and low-cost open-source models is critical: low-cost models expand usage, while high-performance closed-source models still control paid revenue. This determines whether frontier labs can continue absorbing GPU, memory, and data center contracts.
“Token volume: +70% MoM, 20x YoY; spending: +70% MoM, 16x YoY; pricing: slightly up MoM, still -5% YoY”
AI Application Costs/Local Models
The AI trade is starting to shift from “model capability” to “whether cash flow can cover inference costs.” Palo Alto Networks’ CEO believes hyperscalers can use their balance sheets to support AI infrastructure financing for 1-3 years; Tencent’s Hy3 has 295bn MoE parameters, 21bn active parameters, and a 256K context window, showing that local and edge inference will continue to push down unit costs.
CSP/Cloud Capital Expenditure
Big Four Cloud Providers
2026 hyperscaler capex has repeatedly been cited at roughly $725bn, including about $200bn for Amazon, $190bn for Microsoft, $190bn for Google, and $145bn for Meta. Rising storage costs, tight GPU/ASIC supply, and power-grid interconnection are jointly pushing budgets higher. Late-July earnings calls will be the window to verify whether capex is revised up again.
“Demand has not disappeared; capacity is the bottleneck”
Microsoft/Google/Amazon/Meta
Microsoft invested $2.5bn in Frontier Company and embedded 6,000 AI and industry specialists into customer teams; Google’s upwardly revised TPU supply chain supports Broadcom; Amazon RNG and OpenAI MRC are viewed as potentially reducing active transceiver demand by 40%-50%; Meta has signed multiple compute-capacity agreements on top of its $125bn-$145bn 2026 budget.
Apple/Broadcom
Apple and Broadcom extended their technology collaboration to 2031, with Broadcom to develop and supply custom ASICs for multiple generations of Apple products. The agreement extends Apple supply-chain visibility from WiFi/RF into longer-cycle custom chips.
AI Cloud/Data Center Operators
TeraWulf
1. TeraWulf signed a 20-year lease with a large AI customer for the Justified Data campus in Kentucky, representing about $19bn of contracted revenue and roughly 401MW of critical IT load. Initial capacity is expected to come online in 2H27, with full capacity in early 2028.
2. The company also sold a 50.1% stake in the Abernathy JV, realizing about $450mn to fund wholly owned AI infrastructure assets. For the market, this transaction validates the pricing power of power access and deliverable campuses.
“The lease represents about $19bn of contracted revenue over the initial term. The campus will support about 401MW of critical IT load.”
Galaxy Digital/CoreWeave
Galaxy Digital completed Phase I of the Helios AI data center for CoreWeave, delivering 200MW of total power and 133MW of critical IT load. CoreWeave has committed to 526MW across Phases I-III; the Helios campus is approved for 1.63GW and can expand to 3.6GW. Scarce assets in AI cloud are expanding from GPU quotas to power, land, and delivery timelines.
IREN
IREN was among the top gainers. The core catalyst is an RFP for roughly 1.4GW of Australian AI data center capacity, with IREN listed as one of the bidders. A decision is expected in about six weeks and may involve awards to multiple suppliers. The company is described as having 5.8GW of global site assets; the market is now buying the question of whether available power pipelines can translate into contracted revenue.
CoreWeave/Nebius
AI labs’ short-term demand for large-scale compute is creating a market priced at 3-4x normal rates. Whether pricing power can persist depends on power, hardware access rights, and operating-software capabilities.
GPU/CPU/ASIC
NVIDIA
1. NVIDIA rose 0.34%. The move was not strong, but it remains the anchor of the AI supply chain. Management emphasized that “$500bn of orders” for Blackwell/Rubin by the end of 2026 is a demand framework, not revenue guidance.
2. After the Kyber delay controversy, the company responded that the “roadmap remains unchanged.” The market needs to verify Vera Rubin supply, rack manufacturing, and customer deployment speed.
“customers’ biggest anxiety...procure enough NVIDIA product generally, and Vera Rubin specifically”
AMD
1. Advanced Micro Devices rose 6.48%. Goldman Sachs raised its price target from $450 to $640 and said it remains one of its preferred long-term semiconductor longs. Goldman expects server CPU demand to drive quarterly earnings above expectations, with 2027 EPS 13% above consensus.
2. AMD’s trading logic has shifted from “NVIDIA substitute” to “CPU share + MI roadmap + Kyber delay window.” If NVIDIA rack momentum slows, MI450/Helios and server CPUs will gain more negotiating room.
“Goldman Sachs raised its Advanced Micro Devices price target from 450 to 640”
Intel
1. Intel rose 1.68%, with the widest market disagreement. HSBC maintained Buy and raised its price target from $100 to $200, citing server CPU demand driven by agentic AI and inclusion of Foundry in SOTP valuation. Its 2027 DCAI revenue forecast is $33bn, 20% above consensus.
2. BofA and Jefferies are more cautious, noting that external customers for 18A/14A, Foundry yields, and the AI accelerator roadmap remain unproven. Intel is better tracked through DCAI supply, external foundry customers, and EMIB packaging orders, rather than only through CPU demand recovery.
Broadcom
Broadcom rose 3.81%, with AI ASICs and the Apple collaboration both supporting valuation. The Apple agreement was extended to 2031, improving visibility for a low-teens revenue customer and potentially formalizing cooperation on Apple’s Baltra AI server chip.
Qualcomm
Qualcomm rose 6.10%. A leaked iPhone 18 Pro BOM shows U.S. models still using the full Qualcomm suite, which may create upside to revenue previously modeled on a “zero relationship” basis. Reports of negotiations to acquire Modular for about $4bn point to the AI data center software stack.
HBM/DRAM/NAND/SSD/HDD
Micron
1. Micron closed up 1.18% with high trading value, as capital continues to trade DRAM/HBM supply constraints. Citi raised its Micron DRAM ASP growth assumptions for 2Q/3Q/4Q 2026 to +44%/+20%/+13% QoQ and added Micron to its 90-day upside Catalyst Watch.
2. Micron’s Hiroshima expansion investment is about $9.3bn, with original-currency investment of JPY1.5tn and up to JPY500bn of subsidies from Japan’s METI. Equipment installation is scheduled for 2H28. The expansion is large, but offers limited help for the current 2026-2027 shortage.
Samsung Electronics
Samsung Electronics’ memory line remains the anchor of profit elasticity. Meritz expects 2Q26 operating profit of KRW90.1tn, sales of KRW182.1tn, and an operating margin of 49.5%, raising its target price from KRW420,000 to KRW500,000. DRAM BG/ASP are +12%/+50%, and NAND BG/ASP are +3%/+63%. The risk is that terminal businesses such as MX/VD are squeezed by chip price increases, so profit is not benefiting across all segments.
SK Hynix
Both signals from SK Hynix point to expansion financing: first, a planned U.S. ADS issuance described as 177.9mn ADS, equivalent to 17.79mn ordinary shares, with potential proceeds of about $28bn; second, about $8bn of ASML EUV orders, roughly 20 tools, for delivery before December 2027. In the short term, HBM is in shortage; in the medium term, capital and equipment delivery will determine capacity release.
SanDisk/Western Digital/Seagate Technology
SanDisk fell 0.21%, Western Digital rose 6.90%, and Seagate Technology rose 6.08%. SanDisk said it is not adding capacity, and more than 90% of its business remains on short contracts of less than one quarter. TD Cowen also prefers both NAND and HDD because near-term supply additions are limited.
Foundry
TSMC
TSMC ADR rose 4.25%, with upward revisions for both advanced nodes and silicon-photonics PIC. Citi expects combined N2/A16/N3 capacity to reach 350,000-400,000 wafers per month by the end of 2028. Supply-chain sources say TSMC’s PIC capacity will expand from 10,000 wafers per month in 2026 to 15,000 wafers per month in 4Q26, and at least 25,000 wafers per month in 2028. The key question for foundry is not whether demand exists, but whether advanced capacity, packaging, and testing can all keep up.
Samsung Electronics Foundry
Samsung Electronics Foundry is showing signs of profit recovery. SK Securities said Samsung Electronics’ foundry division was profitable on a monthly basis in June 2026, for the first time since 2023, partly because HBM4 base die ramped on the 4nm process and 4nm yield rose to about 80%. But in 1Q26, global foundry share was 72.3% for TSMC and 6.5% for Samsung Electronics, leaving a still-large gap.
Intel Foundry
The bull-bear debate on Intel Foundry is centered on 14A and external customers. HSBC raised its Foundry revenue forecast to $23.5bn in 2026 and $27.5bn in 2027. BofA argues that unless external business can reach at least above $10bn, EPS accretion will be limited. Investors need to see real customers, not only the scarcity value of manufacturing assets.
Semiconductor Equipment/Testing
ASML
ASML rose 3.15%. Bernstein raised its price target from $1,971 to $2,623 and maintained Outperform. It expects 2030 revenue of EUR80bn, a 20% CAGR, and EUV shipments of 91 units in 2027, 113 units in 2028, and 125 units in 2030. SK Hynix’s roughly $8bn EUV order reinforces the main theme that memory is pulling equipment first.
“AI-driven WFE spending remains strong, with visibility now extending into 2028.”
Applied Materials/Lam Research/KLA
Applied Materials fell 1.40%, but Goldman still favors strong DRAM, pricing tailwinds, and visibility through 2028. In the equipment table, Applied Materials’ target price was raised from $260 to $325. Lam Research’s target price was raised from $175 to $225 on NAND, DRAM/HBM, advanced packaging, and dry EUV patterning. KLA is more mixed in the near term because of a DRAM-heavy WFE mix and valuation constraints.
Teradyne/Advantest
Teradyne rose 3.19%, and Advantest ADR rose 5.38%. Test equipment benefits from rising test intensity for GPUs, ASICs, DRAM, and HBM, though the larger contribution from GPU testing may come after CY27. KLA noted about $925mn of advanced-packaging revenue, of which 70% is process control, showing that testing and process control are benefiting from rising advanced-packaging complexity.
Advanced Packaging/OSAT
Advanced Packaging Chain/Amkor
The AI supply bottleneck has expanded from CoWoS to HBM, EMIB, hybrid bonding, and CPO testing. KLA’s advanced-packaging revenue is about $925mn, of which 70% is process control. Amkor fell 12.50%, reflecting the market’s greater focus on the OSAT profit path.
MLCC/Passive Components
Murata/Samsung Electro-Mechanics/Taiyo Yuden/Yageo
High-end MLCC shortages are starting to be amplified by AI servers. Goldman said Yageo and Japanese and Korean suppliers are shifting capacity from commodity MLCCs to high-margin AI-grade MLCCs. It expects 14% of global MLCC capacity to be used for AI in 2026, rising to 32% by 2028. Murata, Samsung Electro-Mechanics, and Taiyo Yuden had late-June BB ratios of 1.30, 1.31, and 1.25, respectively, indicating orders are already clearly exceeding capacity.
Optical Communications/Optical Chain
CPO/Optical Module Chain
Morgan Stanley expects CPO switch shipments to increase from 23,000 units in 2026 and 59,000 units in 2027 to 200,000 units in 2030, a 144% CAGR for 2024-2030. Insertion 2 wafer-level testing has already been shortened from a full day per wafer to six hours, with a target of reducing it to 3-4 hours over the next 6-12 months. The near-term debate is whether Kyber/CPO delays will pressure demand; current evidence looks more like the window is shifting toward 800G/1.6T pluggables, AEC, and DSP.
“CPO switch shipments...23k units in 2026...200k units by 2030”
AAOI/Credo/Astera
Credo rose 9.54%, Astera rose 6.54%, while AAOI faced pressure from architecture changes. B. Riley’s negative view on AAOI is that Amazon RNG and OpenAI MRC are structurally flattening networks, reducing active transceiver demand by 40%-50%. Credo and Astera’s relative advantage lies in SerDes, gearbox, AEC, PCIe/CXL, and other interconnect content that can more easily migrate as rack architectures change.
Coherent/Ciena/Corning
Scale-across networks connect multiple data centers into a single cluster, driving content for ZR/ZR+ coherent pluggables and Optical Line Systems. Related estimates put pure scale-across content at about $3bn in 2026, rising to about $14bn in 2028.
High-Speed Interconnect/Connectors/Thermal and Power
Arista/Credo/Astera
Arista rose 8.64%, Credo rose 9.54%, and Astera rose 6.54%, showing that capital is betting network and interconnect will monetize faster than standalone CPO. Astera said customer PCIe roadmaps may extend to 2029, and its full product portfolio can provide up to about $1,000 of content per XPU.
Vertiv / Eaton / Power Chain
Vertiv rose 5.97%, Eaton rose 3.74%, and power and thermal management continued to benefit from AI data-center constraints. Bernstein’s teardown of a 1GW data center shows GB200/NVL72 racks at roughly $3.4 million, plus about $2.5 million of physical infrastructure per rack, for a total of roughly $5.9 million per rack. Power and thermal management are not the largest cost items, but they are the easiest links to block deployment.
Robotics / Intelligent Driving
Tesla
Tesla rose 6.66%. The near-term catalyst came from Q2 deliveries beating expectations, energy deployments growing 41% YoY, and roughly 20% production improvement at the Berlin plant. What really needs to be tracked is whether margins, storage gross margin, and robotaxi expansion can materialize.
Space / Satellites
Space Data Centers
Bernstein believes thermal management for 20-100kW-class in-orbit computing satellites is technically “plausible / doable,” but the economics remain constrained by launch costs. A 20kW satellite’s five-year electricity consumption corresponds to about $44,000-$219,000 in ground-based power costs, while current launch cost is about $1.7 million. For the solution to be viable, launch costs need to fall from several thousand dollars per kilogram to several hundred dollars, and power density needs to rise to 60-100kW/ton.
Internet / Platforms
Meta
Meta rose 2.87%. The main thread is its AI infrastructure commitment beyond the advertising platform. The company’s 2026 capex budget has been repeatedly cited at roughly $145 billion, and on top of that it has signed a $27 billion five-year agreement with Nebius, a $21 billion expansion agreement with CoreWeave, and an approximately 1.6GW capacity agreement with Crusoe. Meta’s question is not whether it is willing to invest, but whether the spending can translate into recommendation systems, model capability, and advertising returns.
Google
Google rose 1.82%, with progress appearing simultaneously in TPUs, Gemini, and Maps monetization. Upward revisions in Google’s TPU supply chain support Broadcom’s ASIC revenue. TurboQuant reduces KV cache memory requirements by as much as 5/6 and can accelerate GPU inference by up to 8x. Reports say Google Maps may use Gemini as an entry point for restaurant discovery and ordering, potentially affecting local-services platforms such as DoorDash and Uber Eats.
Amazon
Amazon rose 0.55%, with AWS AI infrastructure still the main thread. AWS has raised Q3 2026 ASIC server shipments by 20%-30% versus the original plan. Trainium 2 is sold out, Trainium 3 is almost fully reserved, Trainium 4 already has reservations, and Trainium 5 has started development. The negative variable is that the RNG network architecture may reduce the use of active optical transceivers. Self-developed chips benefiting does not mean all optical-module suppliers benefit.
Apple
Apple rose 1.29%. Its multi-year ASIC agreement with Broadcom was the hard news of the day. The two parties extended their long-term technology partnership to 2031, with Broadcom developing and supplying custom ASICs for future generations of Apple products. Reports say the foldable iPhone will be priced at roughly $2,300-$2,500, with first shipments of 7 million-8 million units in the second half, but this is more of a consumer-electronics demand anchor and should not be mixed with AI server orders.
Reddit
Reddit’s AI data-licensing logic continues to improve. After upgrading its LLM-based system, the company captures about 25,000 net new spam posts and comments per day, blocks about 23 million spam-content views, and reverses nearly 2 million inauthentic votes. Improved content quality strengthens the basis for licensing negotiations with model companies such as Google and OpenAI.
Netflix / Uber / DoorDash
Netflix fell 2.14%, Uber fell 2.28%, and DoorDash was affected by Google Maps’ potential ordering feature. The marginal change for platform stocks comes from traffic entry points and AI search rewrites; customer acquisition costs and commission rates will both be revisited.
Software / SaaS
Microsoft
Microsoft fell 0.89%, with enterprise AI investment coexisting with contraction in the gaming business. The company is investing $2.5 billion to build Frontier Company, embedding 6,000 AI and industry experts to serve customers. On the other side, Xbox has reportedly seen layoffs, studio adjustments, and commentary about relatively low margins. For Microsoft, AI cloud and enterprise software are areas of increased investment, while gaming content is an area for cost reduction.
Snowflake
Snowflake rose 0.75%. The core is enterprise data governance and the AI layer. A Benchmark-related report said Snowflake is building AI around governed enterprise data, expanding the use of Claude within Cortex AI, and reducing the need to move sensitive data into standalone systems. The investment implication is that enterprise AI budgets are more likely to flow to platforms where “data stays where it is, and models are invoked through the governance layer.”
Datadog
Datadog fell 1.92%. Bernstein SocGen downgraded the rating from Outperform to Market Perform, but raised the target price from $180 to $226, reflecting the divergence: AI Labs engagement and product demand were revised upward, while signals from enterprises and some AI Labs slowed and weighed on the rating. Software stocks can no longer be assessed only by AI engagement; renewals, seats, and platform gross margin also matter.
Palo Alto Networks / CrowdStrike
Palo Alto Networks reached an all-time high, and CrowdStrike rose 2.78%. Cybersecurity led five-day gains for a direct reason: AI expands the attack surface and also increases the automation value of security platforms. PANW’s CEO’s comments on AI capex financing also serve as a reminder that rising security demand and AI infrastructure bubble risk may coexist.
Salesforce / SAP
Salesforce fell 0.07%. Signals that smaller companies are using Claude-like tools to replace traditional enterprise applications suggest a risk that seat-based software budgets may be compressed. On SAP’s side, automotive SCM software spending is expected to grow at a roughly 14% CAGR through 2030, and supply-chain control towers remain an incremental direction for enterprise software.
Consumer Electronics / Smart Vehicles
Tesla / Autonomous Driving
Tesla’s near-term fundamentals come from deliveries and energy storage, while the long term still depends on autonomous driving and real-world AI. Q2 deliveries beat expectations, energy deployments grew 41% YoY, and Berlin plant output improved by roughly 20%. If robotaxi expands to more cities, the validation point will shift from shipment volume to unit economics and regulatory cadence.
Qualcomm / Apple Baseband
The leaked iPhone 18 Pro BOM shows U.S. models still using Qualcomm’s SDX80M modem, SDR875 transceiver, PMX75, QET7100A, and mmWave AiP, while international models use Apple’s C2 modem. If teardown in September confirms this, U.S. mmWave iPhones will become upside outside Qualcomm’s model, easing the revenue pressure from Apple’s in-house modem.
Investment Bank Target Price Changes in the Past 12 Hours
Huang’s Select Portfolio