
404K SEMI-AI Storage Weekly — July 24, 2026: Long-Term Contracts Raise the Floor, Inference Expands into NAND, and Equipment Revenue Still Lags
目录
TL;DR
Overall View This Week
Developments This Week
Weekly Performance of Memory-Related Securities
DRAM/HBM: Supply Control, Long-Term Agreements, and Customer Qualification
LPDDR/SoCAMM: Spillover from AI CPUs and Rack-Level Memory
NAND/eSSD/SSD: Inference, RAG, and Enterprise SSD Upside
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
Equipment, Testing, and Materials: Second-Order Beneficiaries of Memory Capex
Downstream Costs and Demand Destruction: Servers, Networking Equipment, Smartphones, PCs, and EVs
Investment Ranking, Risks, and Falsification
What to Watch Next Week
The memory upcycle remains intact, but share prices have begun discounting supply constraints further into the future. Winners will be determined not only by price increases, but also by contract quality, customer qualification, and whether cost pressure forces downstream customers to reduce specifications.
TL;DR
DRAM/HBM still offers the highest visibility, but long-term contracts cannot eliminate cyclicality. Korean HBM exports grew approximately 39% quarter on quarter in the second quarter, with June up 46% from March. Samsung Electronics’ export regression estimate significantly exceeded prior expectations, while SK hynix was broadly in line. Locked-in orders and capacity raise the earnings floor, but customers may still walk away if prices fall below breach-of-contract costs. Long-term agreements therefore should not be treated as fixed-price bonds.
AI inference is broadening memory demand from “the fastest HBM” to “more DRAM and cheaper NAND.” Research assumptions for Vera Rubin’s NAND configuration per GPU have risen from 4TB to 20–21TB, while rack-level CPU memory could increase to roughly three times current levels. KV cache compression reduces capacity requirements per task, but longer contexts, larger models, and greater concurrency will refill the freed capacity. Net demand still needs to be validated against actual configurations.
NAND/eSSD offers the greatest upside sensitivity in this cycle—and is also the most vulnerable to a supply response. Enterprise SSD pricing and revenue have shown strong operating leverage, benefiting Sandisk, Kioxia, and Samsung Electronics as AI storage tiers expand. The downside is that rising Yangtze Memory Technologies market share, new fab ramps, and QLC expansion could replenish supply more quickly. Investors should track contract prices, the enterprise product mix, and wafer starts rather than spot-market sentiment alone.
The HDD thesis is closer to a cash-flow trade and should not simply replicate the NAND price-increase narrative. Growth in AI data lakes and nearline capacity supports orders and backlogs at Seagate Technology and Western Digital, but this week’s materials provided no new exabyte shipment, build-to-order, or free-cash-flow guidance. Demand for upstream glass substrates is strong, yet suppliers have not proactively raised prices despite shortages, showing that robust industry conditions do not confer equal pricing power across every segment.
The direction for equipment, testing, and materials is positive, but the timing of revenue realization varies. Long-term AI data-center wafer demand is pulling through DRAM, HBM, NAND, and logic equipment simultaneously. New memory-test equipment orders from Micron provide near-term validation. Hybrid bonding has a clearer adoption path in logic, while conventional thermocompression bonding may remain viable longer in HBM. Investors should first watch mass-production orders, transaction prices, and customer qualification.
Downstream cost pass-through has become the main counterargument to this upcycle. Research estimates suggest the investment index for a Vera Rubin data center could rise from 1.0 to 1.3, or remain around 1.25 after configuration optimization. Competitive pressure may keep AI cloud providers investing, but smartphones, PCs, networking equipment, and automotive customers are likely to reduce specifications, delay procurement, or shift toward general-purpose components sooner.
Memory equities have moved from “supply-demand confirmation” into a phase where execution and crowded positioning coexist. Micron, Sandisk, Western Digital, and Seagate Technology all posted double-digit gains this week, while memory ETFs rose even more. The ranking remains: customer lock-in for high-end DRAM/HBM first, pricing leverage for NAND/eSSD second, and HDD orders and cash flow third. From a trading perspective, valuations should incorporate discounts for crowded positioning and interest-rate volatility.
Overall View This Week
This memory upcycle remains supported by fundamentals, but the easiest phase for generating returns is changing. The first half of the cycle was driven by spot-price increases. The second half depends on which suppliers can convert higher prices into long-term contracts, contracts into shipments, and shipments into cash flow. Price increases alone, without committed customer volumes and supply constraints, are unlikely to sustain valuations.
HBM and high-end DRAM benefit from superior visibility. AI accelerator upgrades continue to increase capacity requirements, while the complexity of HBM4 manufacturing consumes more effective wafer capacity. To secure supply, customers are willing to make prepayments, fund equipment, or sign multiyear agreements. This gives suppliers greater demand visibility and enables more disciplined capital-expenditure planning.
NAND and enterprise SSDs offer greater earnings sensitivity. Inference requires storage for model weights, vector databases, checkpoints, training and inference data, as well as a lower-cost capacity tier for the expanding KV cache. Relying solely on HBM is prohibitively expensive. As hot and cold data are tiered, NAND’s cost-per-bit advantage is beginning to translate into incremental demand.
HDDs benefit from a duopoly market structure and strong cash-flow characteristics. Large-capacity data lakes still require nearline HDDs, while build-to-order production can reduce inventory volatility. However, this week provided no new exabyte shipment, backlog, or free-cash-flow figures. We can therefore maintain the directional thesis but cannot place HDD’s earnings trajectory on the same footing as NAND spot-price increases.
The entry points for these three asset categories are not the same.
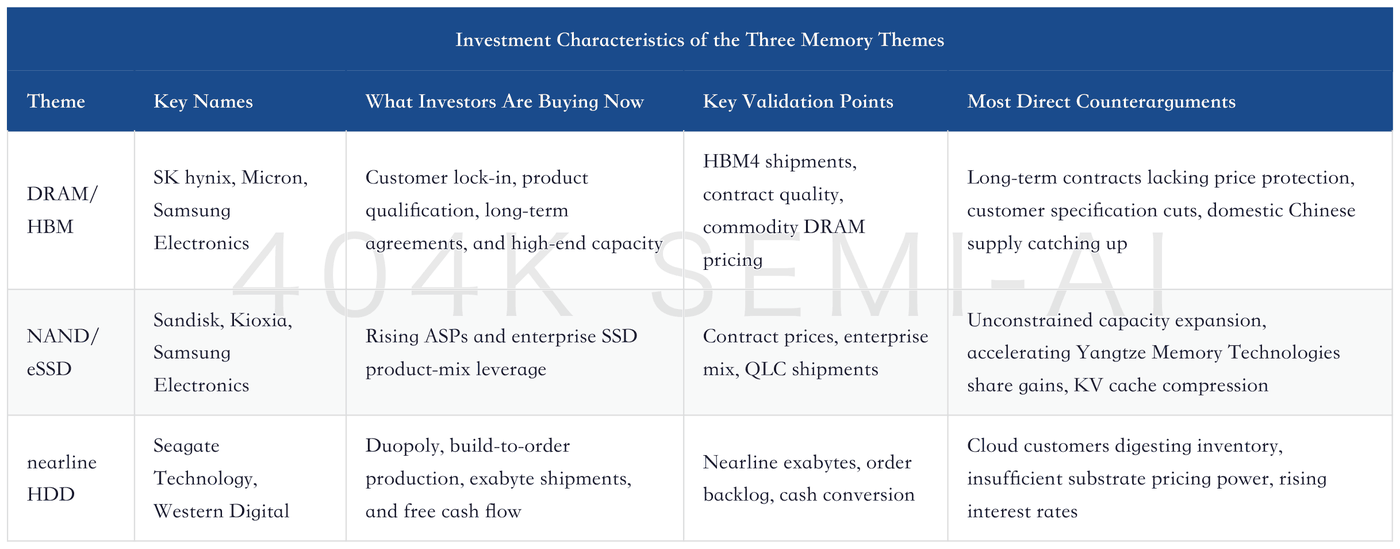
The most important development this week is that the market has begun pricing both “prolonged shortages” and “declining downstream affordability.” Both can be true simultaneously. Tight supply improves memory suppliers’ profits; when prices rise too rapidly, server and device customers optimize configurations. Investors should ask not only how long prices can continue rising, but also how much bit demand is lost with each successive increase.
Developments This Week
July 20: Supply visibility continued to strengthen, while long-term contract quality became the focus of debate. Korea’s June export data confirmed strong second-quarter HBM demand, with Samsung Electronics showing particularly notable incremental growth. At the same time, multiple research reports examined long-term agreements in greater detail: hyperscale cloud customers have stronger credit quality and greater ability to fulfill contracts, while consumer-electronics customer orders offer weaker protection. If prices fall sharply, customers will still compare breach-of-contract costs with spot-procurement costs.
Demand boundaries also expanded further that day. Kimi K3’s 2.8 trillion parameters and 1 million-token context window reinforced the view that efficiency gains will be reabsorbed by model scaling. Higher configurations for Vera CPUs, LPDDR5X, and enterprise storage mean that commodity DRAM, low-power DRAM, and NAND are no longer merely passive beneficiaries of HBM-related capacity displacement; they are becoming integral components of AI racks.
July 21: The cyclical upturn remained intact, but momentum and valuation pressure began to emerge. Industry pricing remained strong, but some research expects the rate of change in memory pricing to peak in the fourth quarter of 2026, while DRAM and NAND inventories increased in the second quarter. Earnings upgrades still outnumber downgrades, but have retreated from their peak. Industry conditions and share prices may continue higher, yet the risk-reward is no longer determined solely by shortages.
Equipment divergence became clearer on the same day. Hybrid bonding has a relatively clear adoption path in logic chips, while HBM remains subject to disruption from extended thermocompression bonding lifecycles, relaxed package-height standards, and customer qualification timelines. AI supernodes are expanding demand beyond accelerators to CPUs, memory pools, packaging, and networking, broadening the equipment opportunity. However, the order of revenue realization will not be uniform.
July 22: Supply constraints spread upstream into materials, but pricing power still needs to be confirmed segment by segment. The shortage of electronic-grade glass-fiber cloth could persist through the end of 2027, supporting copper-clad laminate pricing and profitability. This indicates that the migration of AI and non-AI capacity is changing upstream material allocation. However, materials price increases are primarily driven by servers and high-speed interconnects and cannot be directly equated with further tightening in memory-chip supply.
Evidence throughout the week sequentially pointed to higher AI configurations, greater wafer consumption by high-end memory, tightening commodity-memory supply, more long-term agreements, and the beginning of downstream configuration optimization. This chain remains intact. What would materially change the weekly view is earlier-than-expected capacity additions, customer resistance to higher prices, or inference architectures that significantly reduce external-storage requirements.
Weekly Performance of Memory-Related Securities
The measurement window for U.S. equities and ETFs is July 17–23, 2026. Available Korean and Japanese market data has expired; accordingly, these are marked as unavailable rather than replaced with data from an earlier week.
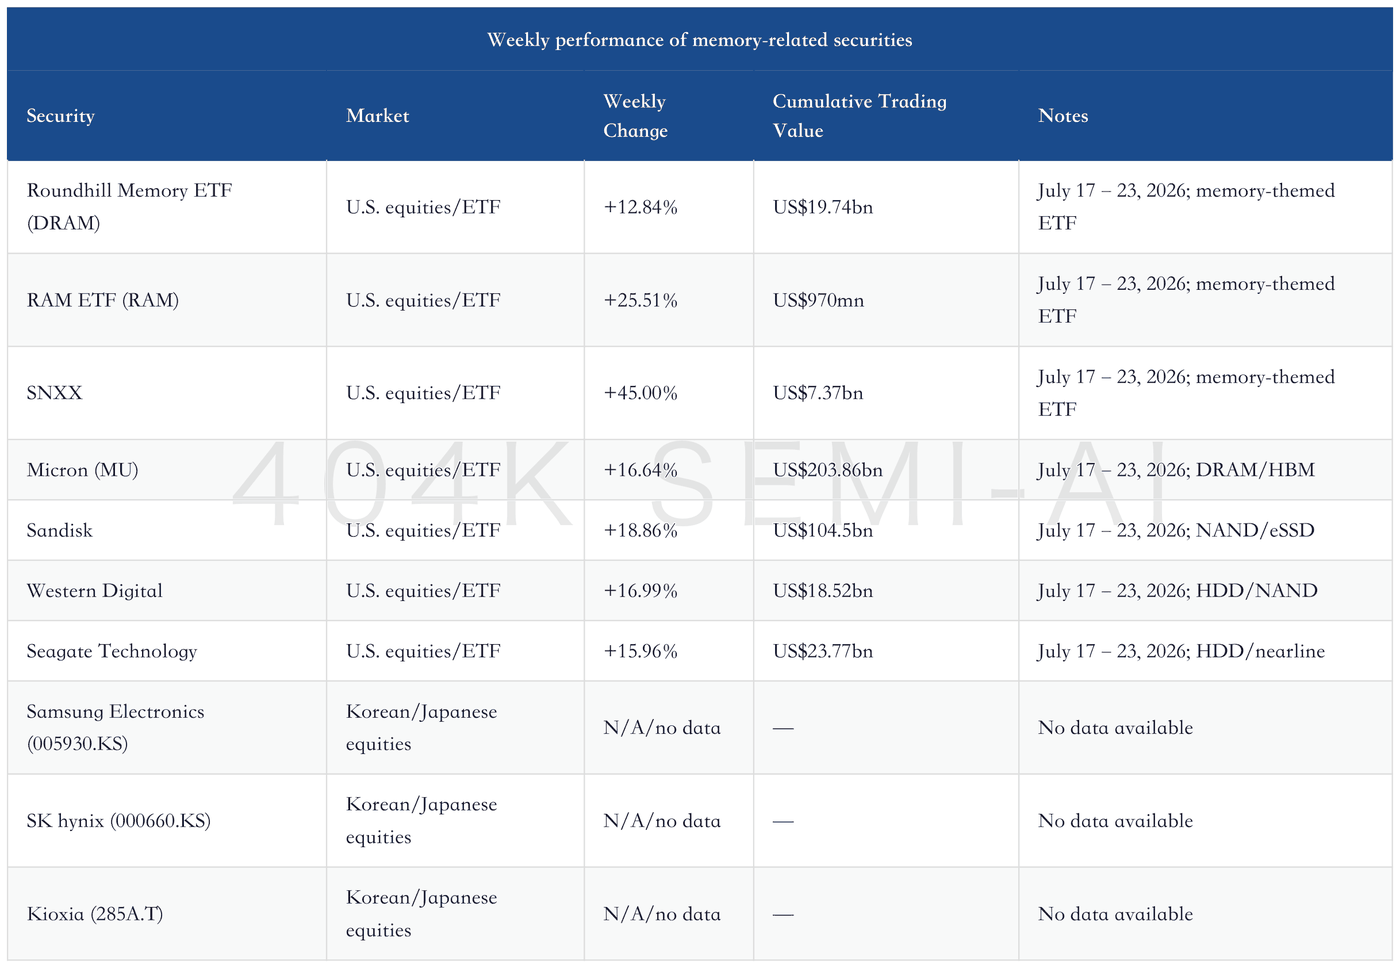
The table shows that capital has rotated from a single market leader into the broader memory basket. ETFs outperformed most individual stocks, which typically indicates rising trading momentum and should not be interpreted directly as a ranking of fundamental strength. Micron’s trading value was substantially higher than that of other individual stocks, also suggesting that positive news is being priced in more quickly.
Qualified data for Korean and Japanese equities is unavailable for the week, so this table cannot be used to assess the relative performance of Samsung Electronics, SK hynix, and Kioxia. Industry analysis should remain anchored in orders, pricing, customer qualifications, and cash flow.
DRAM/HBM: Supply Control, Long-Term Agreements, and Customer Qualification
HBM demand is not merely a forward-looking narrative. This week’s export data provided further physical confirmation. Samsung Electronics’ incremental growth was materially stronger than the market had previously estimated, while SK hynix was broadly in line with expectations.
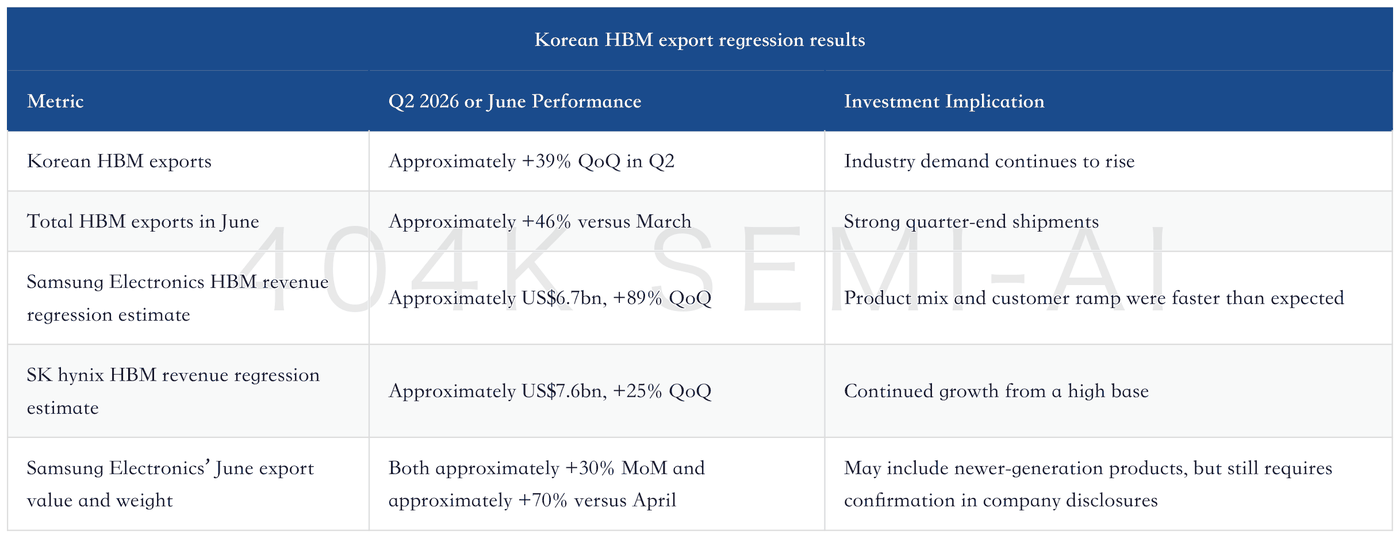
Export regression has limitations. Packaging outside Korea and domestic consumption are not fully captured, and monthly data cannot substitute for company confirmation. The data demonstrates strong shipments, but cannot independently prove that HBM4 has completed all customer qualifications. Nor should Samsung Electronics’ regression estimate be treated directly as reported revenue.
Supply constraints remain more severe than for conventional DRAM. HBM uses TSVs, stacking, and more complex back-end processes, resulting in higher effective wafer consumption than conventional DRAM of equivalent capacity. HBM4 further increases complexity, meaning higher nominal wafer starts may not translate proportionally into qualified finished products. As premium products absorb advanced-node capacity, server DDR5 and low-power DRAM should also receive pricing support.
