
404K SEMI-AI Semiconductor Equipment Weekly — ASML Capacity Expansion Shifts the Bottleneck to Deliveries, While Thermocompression Bonding Converts Packaging Demand into Orders
目录
TL;DR
Overall Assessment This Week
Front-End Wafer-Fabrication Equipment
Metrology, Inspection, and Test
Advanced-Packaging Equipment and Critical Materials
Company, Order, and Capital-Expenditure Validation
Divergences, Counter-Evidence, and Key Indicators for Next Week
ASML raised both its 2026 guidance and its 2027–2028 capacity targets, while ASMPT’s thermocompression bonding orders translated advanced-packaging demand into equipment purchases. The next question is whether orders can convert into capacity, pricing, and margins.
TL;DR
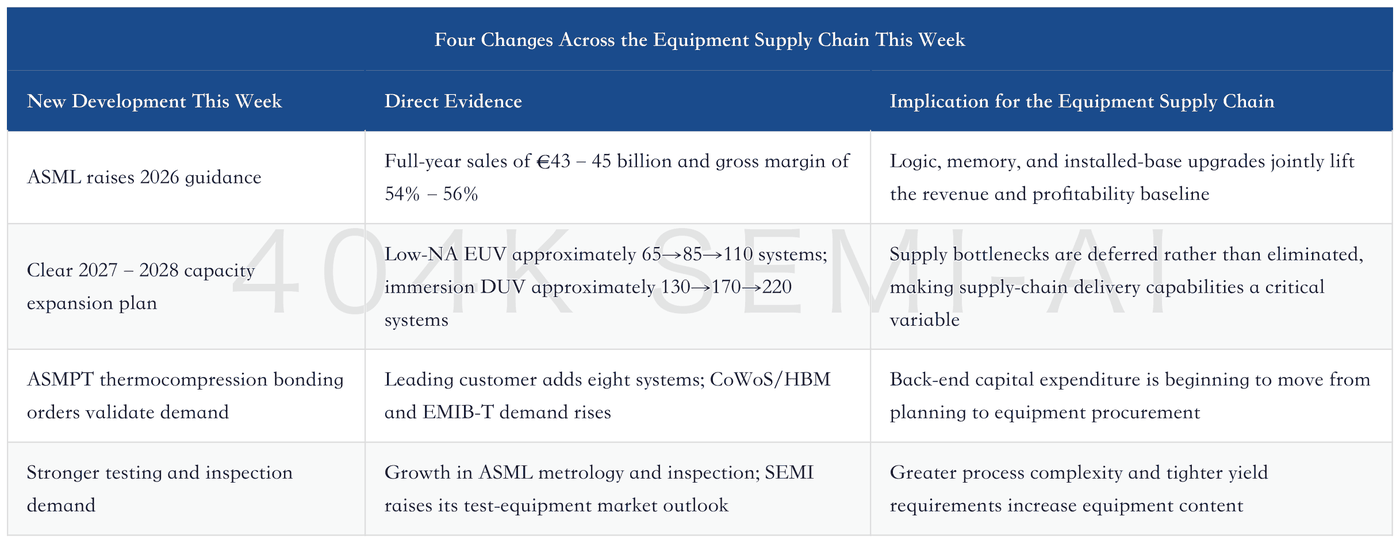
ASML reported second-quarter sales of €9.326 billion and a 54.0% gross margin. It guided to third-quarter sales of €11.0–12.0 billion and a 55%–57% gross margin, while raising its 2026 sales guidance to €43–45 billion and gross-margin guidance to 54%–56%. This is no longer merely a quarterly beat: stronger logic, memory, and installed-base upgrades have prompted the company to raise the midpoint of both full-year revenue and profitability expectations.
The key question for lithography equipment has shifted from “Is demand strong?” to “Can systems be delivered on time?” ASML plans to increase annual low-NA EUV capacity from approximately 65 systems in 2026 to around 85 in 2027 and 110 in 2028. Immersion DUV capacity is set to rise from approximately 130 systems to around 170 and 220, respectively. EUV orders already nearly cover required 2027 capacity, while substantial orders have also been secured for 2028, providing tangible order support for supply expansion over the next two years.
The most easily overlooked areas this week were not EUV, but DUV, metrology and inspection, and installed-base upgrades. ASML expects combined DUV, metrology, and inspection revenue to grow approximately 25% in 2026, with installed-base management revenue rising more than 30%. Bernstein raised its 2028 DUV revenue forecast from €17 billion to €21 billion. As advanced logic and DRAM become more complex, process control, upgrades, and mature-layer equipment outside the exposure step are increasingly important rather than peripheral.
Advanced-packaging equipment is beginning to move from thematic trading to validation through orders and capacity. JPMorgan expects ASMPT’s addressable thermocompression bonding market to continue expanding on CoWoS, HBM, capacity additions by Chinese OSATs, and the ramp of Intel’s EMIB-T. It forecasts ASMPT’s EPS to grow 97%, 54%, and 23% in 2026–2028, respectively. Goldman Sachs confirmed that a leading integrated device manufacturer placed a repeat order for eight thermocompression bonding systems, while cautioning that the valuation already reflects a meaningful portion of the optimistic outlook.
Back-end growth is not limited to bonding. Equipment installation is under way at TSMC’s first two advanced-packaging plants in Chiayi, with mass production targeted for 2027. SEMI expects test-equipment sales to rise 31.0% to $15.3 billion in 2026 and assembly and packaging-equipment sales to increase 9.6% to $6.7 billion. As glass substrates, panel-level packaging, and higher-density interconnects advance, nondestructive inspection, metrology, and reliability testing will become new yield bottlenecks.
The largest disagreement concerns the pace of execution. Planned 2027 low-NA EUV capacity of approximately 85 systems remains below some prior market expectations of 90–100. Although Intel has deployed high-NA systems in mass production, TSMC continues to emphasize technology maturity and manufacturing costs. ASMPT has also yet to see a broad smartphone and PC recovery in mainstream packaging demand. The equipment upcycle can continue, but share prices will trade first on gaps in capacity, pricing, valuation, and customer returns on capital.
Overall Assessment This Week
The central development in semiconductor equipment this week was not another set of bullish forecasts, but the first simultaneous visibility across orders, capacity, and margins. ASML disclosed exceptionally strong first-half orders, with nearly all required EUV orders for 2027 already secured and substantial orders in hand for 2028. At the same time, it guided to a third-quarter gross-margin midpoint of 56%, materially above previous market expectations. The combination of long-dated orders, expanding capacity, and rising margins suggests that customers are no longer merely requesting quotes or reserving slots; they are making firmer equipment commitments for logic and memory expansion over the next two years.
The second change is the continued broadening of the equipment upcycle. EUV lithography remains the scarcest equipment category for leading-edge processes, but this week’s new information also brought DUV, metrology and inspection, installed-base upgrades, and advanced-packaging equipment to the forefront. ASML expects to ship approximately 65 low-NA EUV and 130 immersion DUV systems in 2026, with capacity for the latter also set to expand by roughly 30% annually over the following two years. Metrology and inspection are benefiting from more complex nodes and higher customer adoption, while installed-base management is being driven by capacity upgrades and a larger installed base. The equipment cycle is no longer determined solely by new fabs: upgrades to existing systems, yield control, and increasing process-layer counts are also contributing revenue.
The third change is the emergence of a verifiable handoff from front-end to back-end equipment. Advanced logic, HBM, and high-end DRAM first drive demand for lithography, deposition, etch, and process control, before CoWoS, EMIB, and HBM stacking transmit that demand to thermocompression bonding, testing, and inspection. ASMPT’s repeat order for eight systems and the start of equipment installation at TSMC’s Chiayi packaging plants are harder evidence than general claims of an “advanced-packaging boom.” The key question is no longer the direction of demand, but which equipment categories will convert first into deliveries, revenue, and margins.
Market prices did not strengthen in tandem with fundamentals this week. Major US-listed equipment stocks declined despite ASML’s strong results, while memory, server, and equipment names also experienced profit-taking. This divergence looks more like position and valuation digestion than a sudden deterioration in orders, but it reminds investors that the equipment industry has moved from debating whether an upcycle exists to assessing whether optimistic expectations can be delivered quarter by quarter. Future analysis must consider orders, deliveries, and margins together rather than focusing solely on aggregate capital expenditure.
Front-End Wafer-Fabrication Equipment
ASML’s second-quarter results demonstrated delivery capability first and foremost, rather than merely confirming that demand exists. The company reported sales of €9.326 billion, up approximately 6% sequentially, a 54.0% gross margin, and net income of €2.918 billion. Installed-base management revenue reached €2.762 billion, around €300 million above the company’s prior expectations, primarily because of customer demand for productivity upgrades. Third-quarter guidance implies a sales midpoint of €11.5 billion and a gross-margin midpoint of 56%, indicating that higher volumes and a better product mix will continue to reinforce one another in the second half.
Demand is coming simultaneously from logic and memory. ASML expects advanced-foundry logic revenue to grow approximately 25% in 2026 and memory revenue to rise around 75%. Logic demand is not limited to the 2nm ramp: it also includes capacity expansion at 3nm, 4nm, and 5nm for AI accelerators and supporting chips, as well as initial planning for 1.4nm. Memory demand includes new DDR and HBM capacity, together with additional EUV and advanced immersion layers resulting from migrations to the 1b and 1c nodes. In other words, demand is not a wager on a single customer or node; both leading-edge capacity expansion and greater process complexity are increasing lithography intensity.
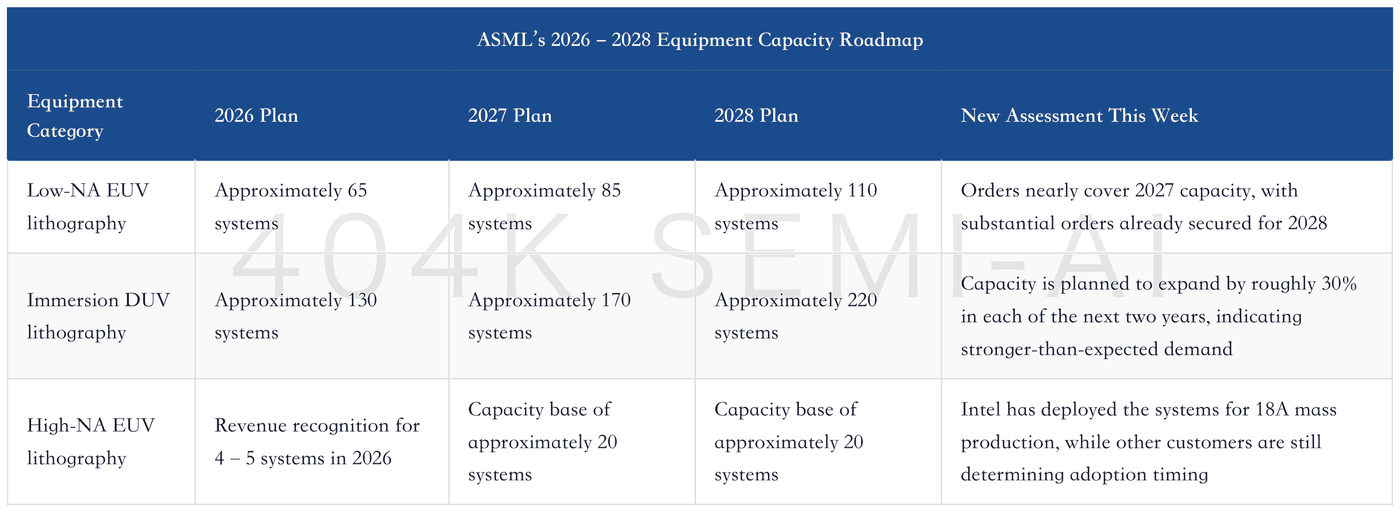
DUV represents the largest expectations gap this week. The market had focused on whether EUV capacity could exceed 90 systems, while underestimating the large number of DUV layers still required for advanced chips. ASML expects revenue from non-EUV systems to grow approximately 25% in 2026, including around 130 immersion systems. Bernstein consequently raised its 2028 DUV revenue forecast from €17 billion to €21 billion. Greater EUV adoption in advanced logic and DRAM does not mean DUV is being displaced; it often comes with more supporting layers, mature-node layers, and metrology steps. The plan for approximately 220 immersion systems in 2028 indicates that rising equipment intensity is spreading from the most advanced exposure steps across the broader process flow.
Installed-base upgrades turn one-off equipment sales into a longer revenue tail. ASML expects installed-base management revenue to grow more than 30% in 2026. Customers are willing to pay for software-led productivity upgrades because they can increase wafer output per hour with minimal downtime. Service revenue also rises as the EUV installed base expands. Bernstein estimates that the 3800E performance-enhancement package can increase throughput from 220 to 230 wafers per hour, while future system pricing may also adjust in line with productivity gains. The interaction of new systems, upgrades, services, and pricing provides the complete rationale for a structurally higher gross-margin baseline.
The front-end equipment bottleneck has not disappeared; it is simply propagating beyond ASML’s own capacity into the supply chain. The company says its 2027–2028 expansion can be completed within its existing production footprint, with the new campus primarily supporting longer-term demand. However, light sources, optics, precision mechanics, installation teams, and customer fab infrastructure must all expand in parallel. If any link lags, orders will not disappear, but revenue recognition may be delayed. The next priority is therefore not to keep raising long-term system forecasts, but to verify whether supplier lead times, customer prepayments, equipment installation, and cleanroom readiness remain synchronized.
Metrology, Inspection, and Test
The metrology and inspection upcycle is driven by greater process complexity, rather than simply tracking wafer starts. ASML explicitly stated that customers are using more process control at advanced nodes, while adoption of its optical metrology and e-beam inspection products is increasing. The company expects combined revenue from deep ultraviolet, metrology, and inspection to grow by approximately 25% in 2026. As 2nm production, 1.4nm planning, DRAM 1b/1c, and more complex packaging advance concurrently, defect tolerance will decline, increasing both the number of metrology steps and sampling density. Revenue elasticity for process-control equipment could therefore exceed growth in wafer volumes themselves.
Applied Materials’ structural assessment this week points in the same direction: DRAM wafer-fab equipment growth is expected to exceed NAND growth by more than 2x, while advanced-node logic will account for well over 50% of foundry and logic equipment demand. More importantly, DRAM could subsequently undergo broader EUV adoption, more advanced peripheral logic, CMOS-bonded arrays, vertical-transistor 4F² architectures, and ultimately 3D DRAM. Each structural transition will increase the complexity of deposition, etching, bonding, metrology, and defect control. However, no mass-production timetable, equipment intensity, or orders have yet been disclosed. This therefore serves only as directional evidence of rising equipment content and cannot be directly extrapolated to individual-company revenue.
Test-equipment growth is beginning to outpace assembly and packaging equipment. SEMI expects test-equipment sales to grow 31.0% to $15.3 billion in 2026, following 55.3% growth in 2025, and potentially reach $20.8 billion by 2028. Over the same period, assembly and packaging equipment sales are expected to grow 9.6% to $6.7 billion. The divergence indicates that the challenge for high-performance computing chips, HBM, and heterogeneous integration is shifting from whether they can be packaged to whether they can operate reliably under high power, high bandwidth, and dense interconnects. Demand for wafer-level testing, final testing, burn-in testing, probe cards, and system-level testing will not move in lockstep. Investors will need to assess test duration, parallelism, and yield separately rather than applying a single back-end growth rate to all companies.
Glass substrates provide an earlier-stage case study. Tomocube launched the HT-T1D tool for glass substrates, highlighting rapid, nondestructive detection of microcracks, voids, and warpage. If glass-core and panel-level packaging are to enter mass production, inspection throughput and defect-recognition capabilities will directly determine their economics. This equipment category is currently very small, but it demonstrates how innovation in advanced-packaging materials creates new metrology categories. The more relevant issues to monitor next week are customer qualification, inspection throughput, minimum detectable defect size, and deployment on production lines—not merely the launch of a new tool.
A common feature of metrology, inspection, and test is that revenue recognition often lags process selection but may precede large-scale capacity ramp-ups. Front-end customers first increase process control, after which packaging houses add reliability and final-test capacity; only equipment orders can confirm whether process complexity is translating into actual spending. The key metrics for this section should therefore be customer adoption rates, metrology steps per wafer, test time per chip, equipment utilization, and service revenue—not a single market-size forecast.
Advanced-Packaging Equipment and Critical Materials
This week, ASMPT advanced the thermocompression-bonding thesis from addressable market to customer orders. The company disclosed that a leading integrated device manufacturer placed a follow-on order for eight thermocompression-bonding systems for data-center processors. JPMorgan believes incremental demand will come not only from HBM, but also from CoWoS logic-die-to-substrate bonding, future fluxless thermocompression bonding of logic dies to wafers, and Intel’s EMIB-T capacity expansion. As products such as Trainium, NVIDIA’s next-generation platform, and Google Tensor Processing Units adopt more complex chiplet integration, the addressable process steps for thermocompression bonding could expand from die-to-substrate applications to a broader range of die-to-wafer use cases.
JPMorgan expects CoWoS shipments to grow 92% in 2027 and 39% in 2028, with more incremental capacity coming from outsourced semiconductor assembly and test providers. It estimates ASMPT’s share of the overall thermocompression-bonding market at 30%–40%, and its potential share at major Korean memory customers at 30%–35%. Thermocompression-bonding equipment already accounts for approximately 50% of ASMPT’s advanced-packaging portfolio, allowing market expansion to flow relatively directly into its Semiconductor Solutions business. JPMorgan forecasts revenue growth of 25% in 2026 and 29% in 2027 for the segment. These figures are more meaningful than discussing advanced-packaging market size alone because they jointly address the product, customer, and revenue-conversion pathways.
Changes in the HBM roadmap have not weakened thermocompression bonding for now; instead, they have extended its effective window. Twelve-layer stacks may remain prevalent longer than previously expected. If HBM4E also remains predominantly 12-layer, and industry limits on stack height are relaxed, the risk of thermocompression bonding being rapidly displaced by hybrid bonding over the next two to three years will decline. On the other hand, competition in HBM thermocompression bonding remains intense: capacity expansion by Korean equipment vendors, customers’ in-house development, and advances in hybrid bonding could all compress market share. The most reasonable conclusion is not that thermocompression bonding will prevail over the long term, but that its 2026–2028 order window is longer than the market previously estimated—sufficient to support improvements in ASMPT’s margins and revenue.
Goldman Sachs and JPMorgan differ primarily on the magnitude of execution rather than the direction of demand. Goldman adjusted its ASMPT net-income forecasts for 2026–2028 by 0%, 16%, and 22%, respectively, expects a three-year net-income CAGR of approximately 36%, and notes that both thermocompression bonding and surface-mount equipment for AI-server printed circuit boards should benefit. JPMorgan, meanwhile, forecasts EPS growth of 97%, 54%, and 23% from 2026 through 2028 and is more constructive on the medium-term contributions from Chinese OSAT providers and Intel’s EMIB-T. Both acknowledge that an improved thermocompression-bonding product mix supports gross margins, although Goldman cautions that the current share price already reflects a substantial portion of the growth. From an investment perspective, upward revisions to the addressable market should be separated from further valuation expansion.
