404K SEMI-AI Morning Tech Brief 2026-07-01 — Memory LTAs, Advanced Packaging, Power and Interconnects
目录
Post-Close Summary
U.S. Stock New Highs
AI/Semiconductor Full Value Chain
AI Models/Applications and Capex
CSP/Cloud Capex
AI Cloud/Data Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry, Advanced Packaging, and Equipment
MLCC, Optical Communications, and Power Infrastructure
Robotics/Autonomous Driving
Internet/Platforms
Software/SaaS
Consumer Electronics/Smart Vehicles
Investment Bank Target-Price Changes Over the Past 12 Hours
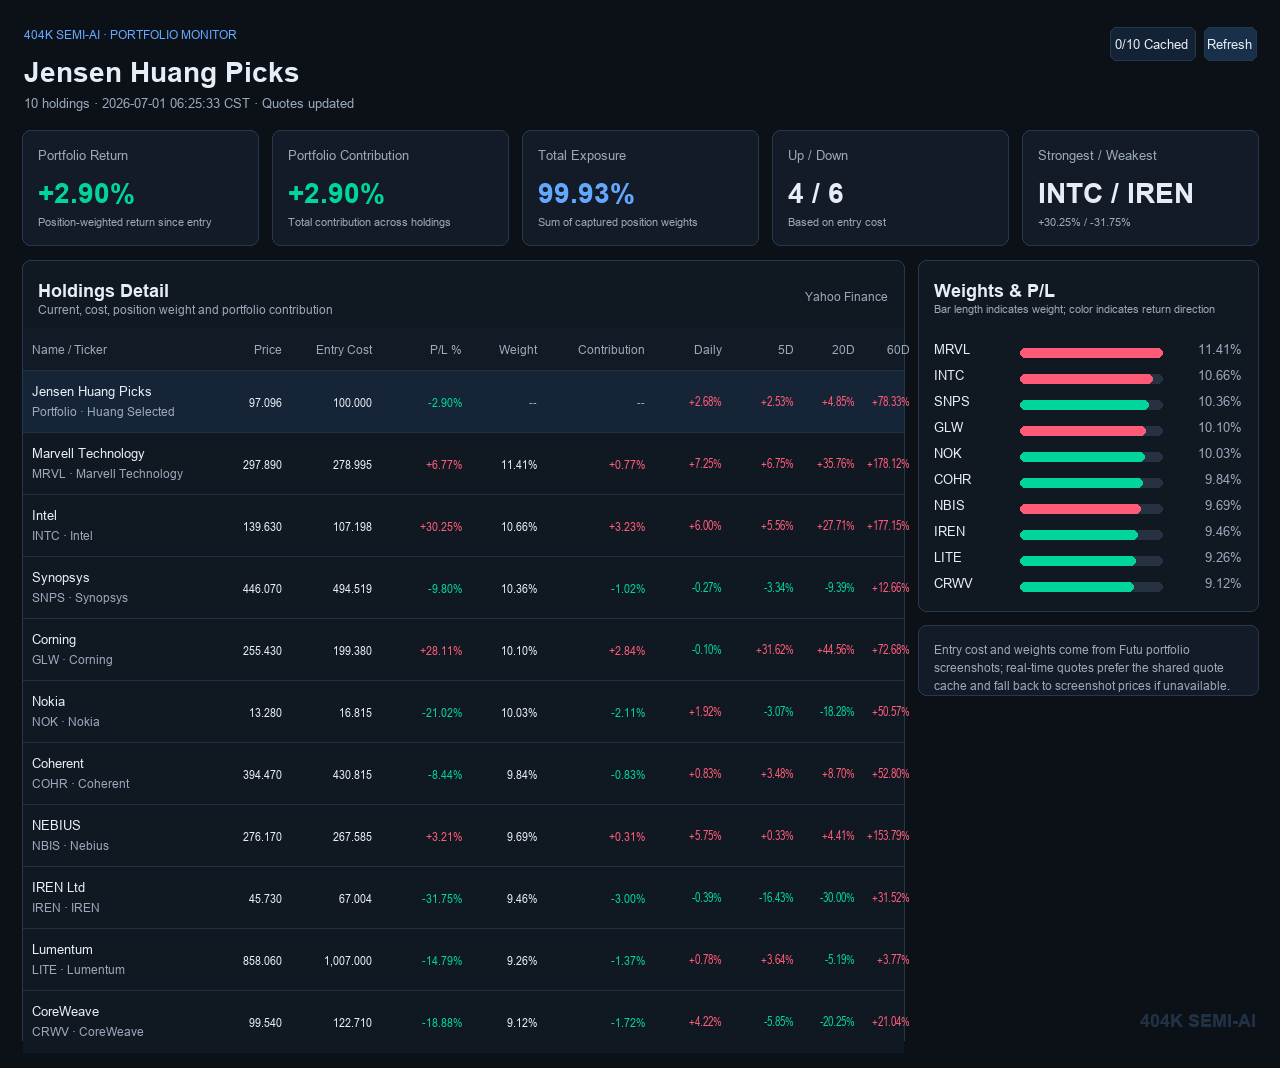
Jensen Huang Picks Portfolio
The AI hardware trade continues to broaden from the GPU main line into memory, packaging, power, and optical interconnects. After the close, semiconductor ETFs and equipment names led, while software and communication services remained weak. Capital is more willing to buy supply bottlenecks than a broad technology valuation repair.
Post-Close Summary
On June 30, U.S. tech leadership rotated back to the hardware chain. SPY rose 0.76%, QQQ rose 1.65%, and RSP fell 0.13%, showing that index gains were still driven by large-cap growth and semiconductors. At the sector level, XLK rose 2.77%, SMH rose 3.75%, and SOXX rose 4.26%, with semiconductor strength clearly ahead of software, cloud computing, and communication services.
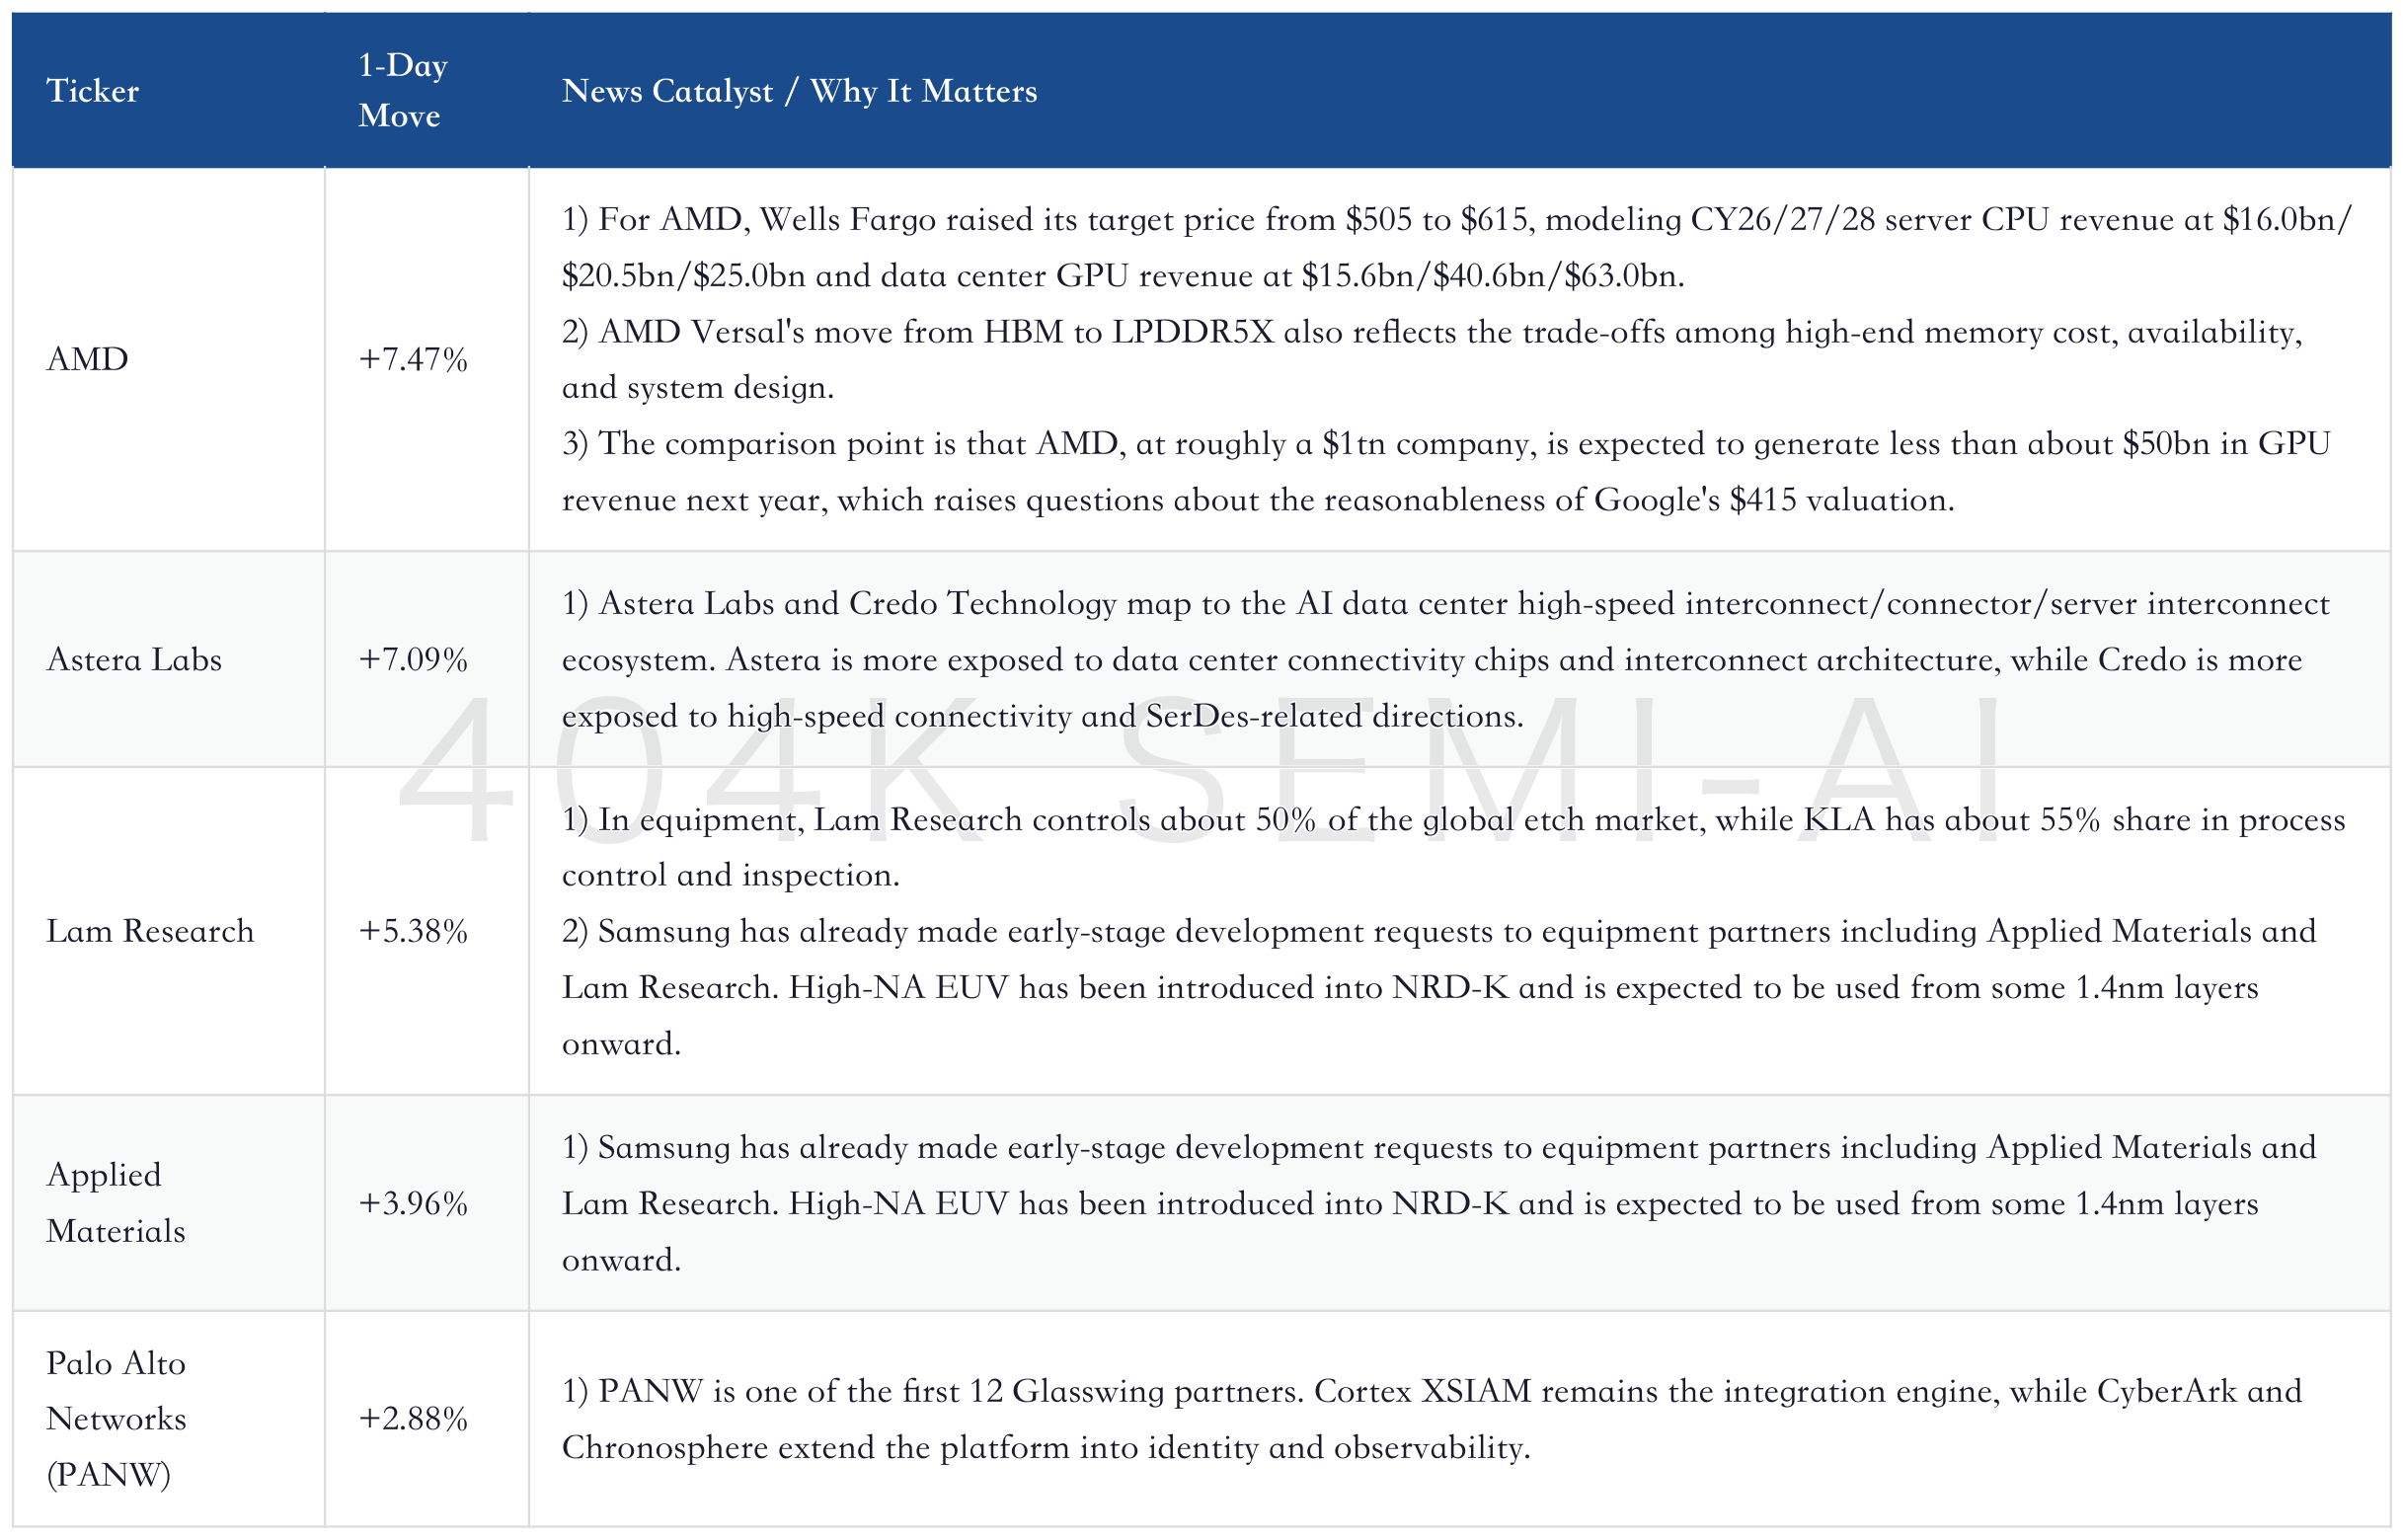
At the stock level, AMD rose 7.53%, Intel rose 5.52%, TSMC rose 4.94%, ASML rose 5.65%, Applied Materials rose 4.48%, Lam Research rose 6.06%, Credo rose 10.69%, and Astera Labs rose 6.37%. The marginal change in the AI trade is that capital is continuing to spill outward along the chain of "GPU demand validation -> memory price increases -> advanced packaging -> power and optical interconnects."
Software remains more mixed. IGV rose 0.79%, SKYY rose 1.25%, and AIQ rose 2.16%, all lagging semiconductors; communication services ETF XLC fell 0.70%. This shows that the market is placing more near-term weight on orders, capacity, price increases, and supply constraints. Pure application and advertising names need a stronger revenue slope to take over leadership.
U.S. Stock New Highs
AI/Semiconductor Full Value Chain
AI Models/Applications and Capex
OpenAI
1) Inference economics continue to improve. OpenAI's inference cost fell by more than 50% in the latest cycle, with Q1 gross margin at 39% and a year-end target of 52%.
2) The investment implication is that model cost reductions have not depressed compute demand. Instead, they allow more enterprise workflows to shift into real-time inference, keeping usage hours for cloud, GPUs, memory, and networking on an upward path.
"OpenAI inference cost more than halved, Q1 gross margin 39%, year-end target 52%."
Anthropic
Claude Sonnet 5 has entered long-context and enterprise coding use cases. Pricing for a 1mn-token context is $2 input and $10 output before August 31, then returns to $3 input and $15 output afterward. Enterprise customers buy capability first and negotiate cost later, which is more favorable in the near term for high-end inference throughput and reserved cloud capacity.
Enterprise AI Usage
Token consumption among large internet and cloud customers is still climbing. Meta's token usage reached 60tn over the past 30 days, with the single largest user at 280bn. Developers' monthly AI tool spend is concentrated in the $150-250 range, and more than 70% of Anthropic and OpenAI ARR comes from code-related use cases. This shows that coding, agents, and enterprise workflows remain the clearest paid entry points.
Etched
Etched has raised $800mn and has more than $1bn of customer contracts, with the first racks planned for delivery in the summer. It is betting on a dedicated Transformer inference chip. The commercial validation point is not benchmark scores, but how many tokens can be produced per unit of power. If delivery goes smoothly, it will further reinforce the long-term pressure from inference-specific ASICs on traditional GPU share.
"Whoever produces the most tokens will win the AI economy."
Local AI Models
Rampart's WebGPU model is 14.7MB, with 98.4% recall for privacy detection and millisecond-level latency. This shows that lightweight models can already handle some edge-side and in-browser tasks. However, the workloads that truly affect cloud capex remain training, long context, multimodality, and enterprise agent tasks, so this will not replace the data center main line in the near term.
CSP/Cloud Capex
Amazon
AWS Bedrock ARR has reached $25bn-$30bn, with margins above 50%. AWS also plans to expand its frontline engineering team by $1bn in scale to embed model capabilities into enterprise customer processes. The validation point for cloud capex is shifting from "whether there are GPUs" to "whether customers can turn models into billable business."
Google
The TPU supply chain continues to expand. MediaTek participates in about 50% of TPU v9 share; v9 is priced at about 3x v8 and is configured with 1GB SRAM. The market's real focus is whether Google can translate TPU cost advantages into cloud AI service gross margin, rather than treating in-house chips only as Nvidia substitutes.
Meta
MTIA 500 specifications point to higher power and higher memory bandwidth, with single-card TDP around 1.7kW, HBM bandwidth of 27.6TB/s, and memory capacity of 384-512GB. Meta's in-house chips continue to pull demand for Broadcom, TSMC, and advanced packaging, while also exposing CPO, power delivery, and thermal constraints earlier.
Microsoft
Microsoft's AI infrastructure bottleneck has extended from GPU procurement to power and campus supply. The Pecos project has on-site energy supply funded by Microsoft, with the logic of shortening the time spent waiting for grid interconnection. The future revenue validation point remains whether Azure AI consumption can cover higher unit MW investment.
Oracle
Oracle previously disclosed a $638bn order backlog, of which about $344bn is expected to convert into revenue over the next three years. The FY2030 revenue CAGR target is 31%. After the share-price pullback, the market debate is not whether demand exists, but whether customer concentration, financing cadence, and data center delivery can be realized in sync.
"Oracle backlog was $638bn, with $344bn expected over the next three years."
AI Cloud/Data Center Operators
Nebius
Nebius's AI cloud revenue grew 841% YoY in Q1, while total revenue was $399mn, up 684% YoY. Full-year revenue guidance is $3.0bn-$3.4bn, with an ARR target of $7.0bn-$9.0bn. It has already secured a $27bn contract from Meta and a $19.4bn contract from Microsoft. The question now shifts to whether 3.5GW of contracted power can become billable compute on schedule.
Bloom Energy
Bloom and Brookfield expanded their AI power partnership from $5bn to $25bn. The core selling point is faster access to on-site data center power. The investment implication for AI data centers is direct: when grid interconnection, transformer, and gas turbine lead times lengthen, companies that can shorten the time to energization will receive a valuation premium.
Digital Realty
Digital Realty's JV asset transaction size was $7.8bn, with a capitalization rate above 6.5% and stabilization in 2027-2028. Data center asset value is about $27mn/MW, while construction cost is about $12mn/MW. A 2.3x cost recovery ratio reflects AI leasing demand repricing mature campuses.
AI Capacity Constraints
AI-ready centralized energized capacity is estimated at 12-15GW, while 2026 U.S. accelerator batch design load is about 10/15/20GW. Transformer lead times are 3-4 years, gas turbines are 3-6+ years, and transmission projects may require 7-15 years. Getting GPUs in hand is no longer the only bottleneck.
"GPU allocation ranks fourteenth."
GPU/CPU/ASIC
Nvidia
1) Nvidia rose 2.63%, with the market continuing to trade lower Blackwell inference costs and upward revisions to second-half data center revenue.
2) DeepSeek V4 token cost on Blackwell has fallen about 5x in one month, while single-GPU throughput has improved by as much as 20x.
3) If inference costs continue to fall, customer budgets will not fall linearly. They may instead shift toward higher-frequency calls and longer context.
AMD
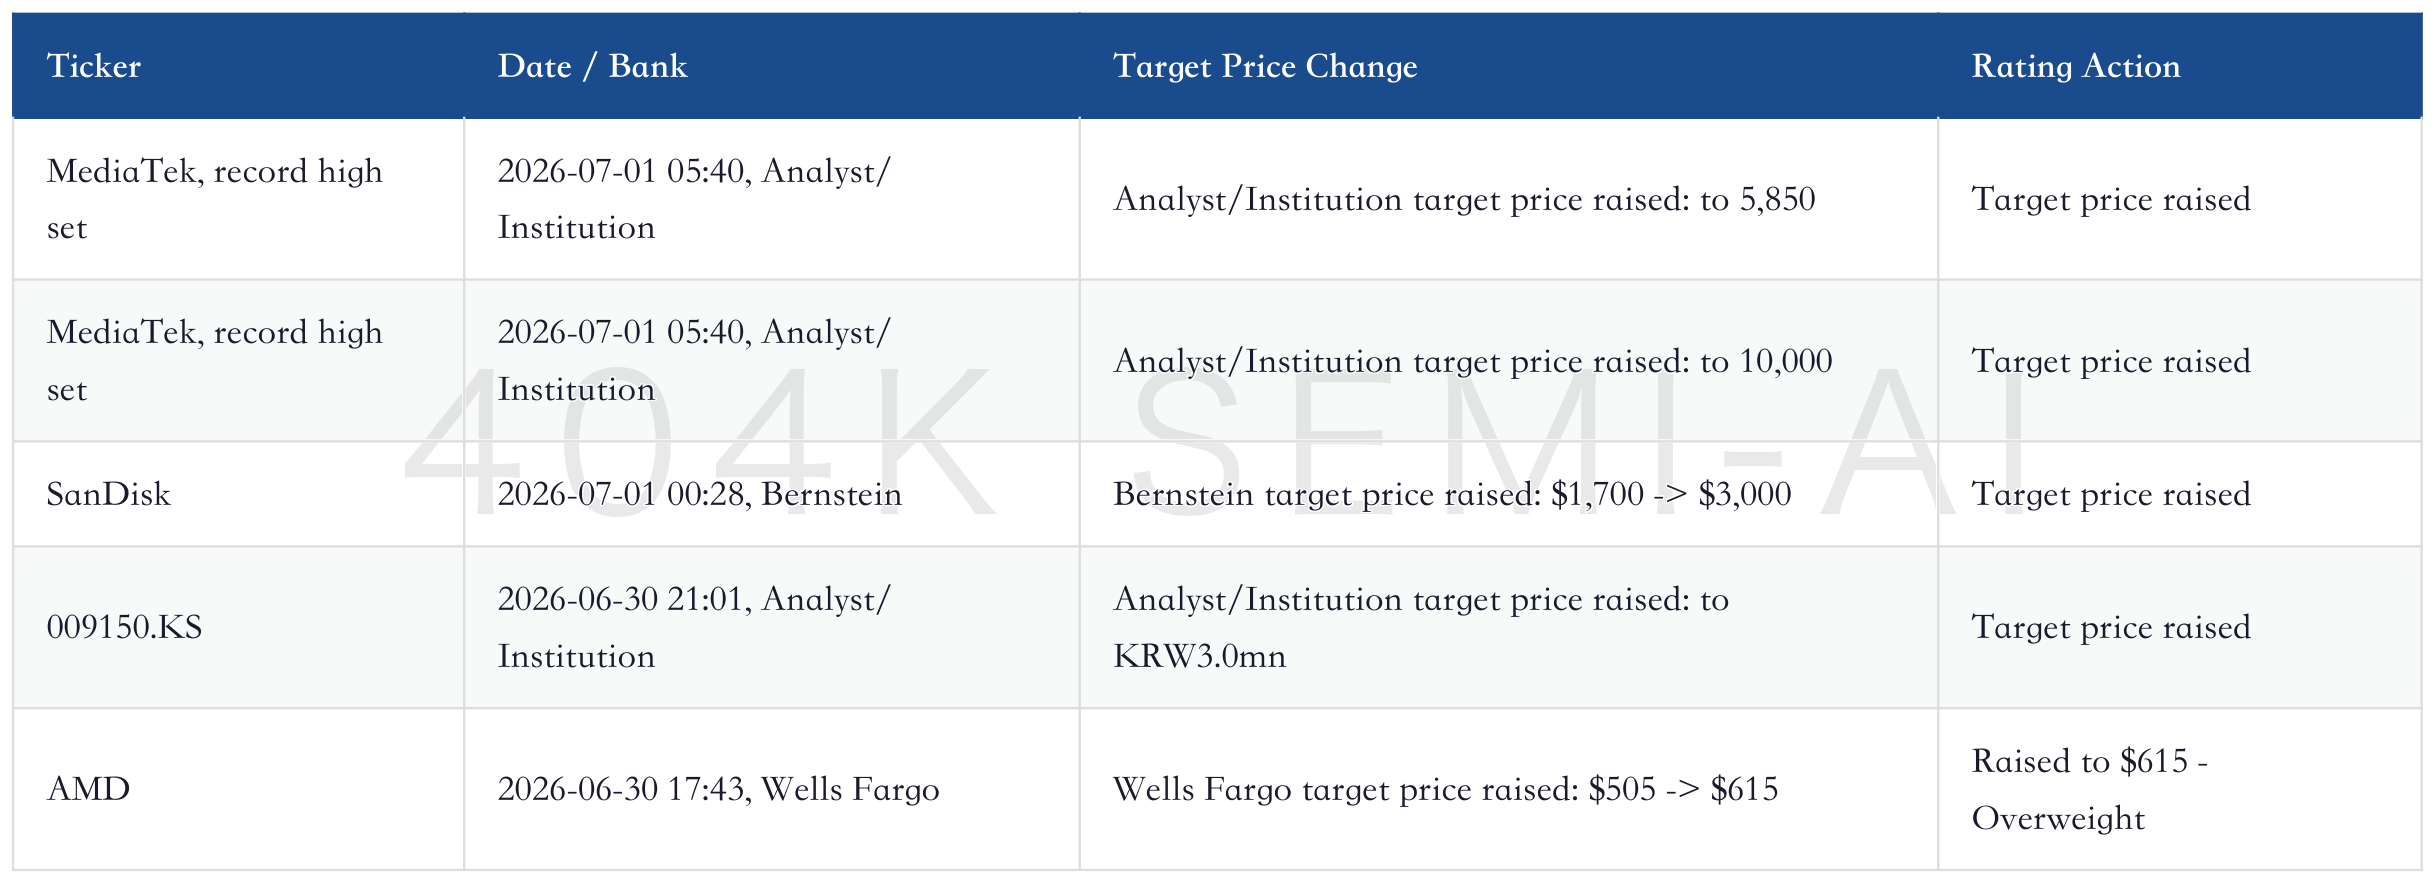
1) AMD rose 7.53%, and Wells Fargo raised its target price from $505 to $615 while maintaining Overweight.
2) Wells Fargo models CY26/27/28 server CPU revenue at $16.0bn/$20.5bn/$25.0bn and data center GPU revenue at $15.6bn/$40.6bn/$63.0bn.
3) Versal's move from HBM to LPDDR5X shows that memory cost and supply availability have already started to affect system design.
"CY26/27/28 server CPU revenue was modeled at $16.0bn/$20.5bn/$25.0bn, data center GPU at $15.6bn/$40.6bn/$63.0bn."
Broadcom
Jefferies maintains Buy on Broadcom with a $550 target price, and places C28 EPS potential in the $30-40 range. TPU 8i is expected to ramp in 3Q26, and the Google partnership can extend to 2031. The investment focus is whether ASIC revenue can expand from a single customer to more CSPs, not near-term gross-margin volatility.
MediaTek
Macquarie raised its MediaTek target price from NT$5,850 to NT$10,000 and maintained Outperform. The core change comes from the TPU roadmap: v9 is priced at about 3x v8, and MediaTek participates in about 50% share. If v10 continues to ramp later, the company could be rerated from a handset SoC cyclical name into an AI ASIC supply-chain name.
Qualcomm
Qualcomm's FY2029 non-handset revenue target is $40bn, including a data center target above $15bn and an automotive revenue target of $10bn. Current automotive annualized revenue is about $5bn, up 38% YoY. The Meta CPU agreement and the $4bn Modular acquisition have prompted the market to reassess Qualcomm's option value in edge AI, automotive, and server CPUs.
Cerebras
Cerebras capacity has been reserved by OpenAI, and some users are seeking low-latency inference at 1,000-2,000 tokens per second. Its advantage is in real-time output and low-latency experiences for large models. The risks are customer concentration, capacity lock-in, and whether the software ecosystem can support more enterprise workloads.
HBM/DRAM/NAND/SSD/HDD
Micron Technology
Micron rose 0.42%, with the memory main line still driven by data center demand and price-increase expectations. DBS raised its target price from $1,200 to $1,400. The company's Q3 data center revenue grew 653%, with DRAM, HBM, and enterprise SSDs all benefiting from AI server procurement.
SanDisk
SanDisk rose 10.23%, and Bernstein raised its target price from $1,700 to $3,000. The memory trade is spreading from DRAM to NAND and enterprise SSDs. The investment implication is that once AI training data, inference logs, and cold-storage demand rise, HDDs, NAND, and the controller chain are no longer just a PC-cycle recovery trade.
"SanDisk target was raised from $1,700 to $3,000."
Samsung Electronics
Samsung's HBM process is still working through yield loss after layer-count increases. Moving from 8-high to 12-high stacks may reduce yield by 10-20 percentage points, while 16-high yield is in the 40%-60% range. A new patent uses dummy dies to improve structural stability, with the goal of preparing for HBM5 stacks above 16-high.
SK Hynix
SK Hynix remains the leader in HBM share, with industry estimates placing its HBM share above 50%. If 2027 HBM contract prices continue to rise, Hynix will benefit first. The risk is that after Samsung and Micron improve yield, customer bargaining power rises again.
Enterprise SSDs and HDDs
Enterprise SSD total capacity is expected to reach 509.33EB in 2026, up 94% YoY. Data center nearline HDD capacity is expected to reach 1,841EB in 2026, up 30.1% YoY. This data shows that AI storage demand is not a single HBM trade. Training data, inference caches, and archives are all extending the storage upcycle.
DRAM Pricing
Q3 PC DRAM prices are expected to rise 15%-20%, while server DRAM is expected to rise 13%-18%. SLC NAND prices rose 28%-31% in June and may rise another 60%-70% in Q3. Price increases can lift profit sensitivity, but they will also pass through the BOM into AI modules, servers, and end devices.
Foundry, Advanced Packaging, and Equipment
TSMC
Nomura expects TSMC's 2026/2027 USD revenue to grow 37%/30%, with capex of $75bn/$85bn, respectively. CoWoS capacity is expected to rise from 1.1mn pieces in 2026 to 2.0mn pieces in 2027, with TPU, GPU, and ASIC orders all competing for advanced-packaging share.
"CoWoS capacity was modeled at 1,100kpcs in 2026 and 2,000kpcs in 2027."
Applied Materials
Applied Materials rose 4.48%, and Susquehanna raised its target price from $575 to $900 while maintaining Positive. Samsung has already made early-stage development requests to equipment partners including Applied Materials and Lam Research. High-NA EUV has been introduced into NRD-K and is expected to be used from some 1.4nm layers onward.
Lam Research
Lam Research rose 6.06% and has about 50% global share in etch, benefiting from GAA, HBM, advanced packaging, and more complex process steps. As AI chips move toward higher bandwidth and higher-density packaging, etch and deposition steps increase, and equipment revenue sensitivity will be higher than traditional wafer shipments.
KLA
KLA fell 8.04%, but still has about 55% share in process control and inspection, making it a key link in advanced-node yield ramps. Short-term share-price reaction cannot replace fundamental judgment. The real validation point is whether 2nm, High-NA, and advanced-packaging inspection orders can continue.
ASML
ASML rose 5.65%, with High-NA EUV already entering Samsung's NRD-K node development. The risk for the equipment chain is not disappearing demand, but customer capex cadence and the mass-production timing of advanced nodes. If 1.4nm layers adopt High-NA, follow-on order visibility will continue to rise.
AEHR
AEHR's new orders reached $37.2mn, up 500% YoY, with book-to-bill above 3.5x. Reliability-testing demand for CPO, silicon photonics, and AI optical networking is rising. Test equipment is rotating from the automotive silicon carbide cycle into the optical interconnect and advanced-packaging cycle.
MLCC, Optical Communications, and Power Infrastructure
Samsung Electro-Mechanics
Hana Securities raised its Samsung Electro-Mechanics target price to KRW3.0mn and maintained Buy. The company secured about KRW454bn of high-end MLCC long-term agreements, with customer demand coming from AI servers, ASICs, and automotive electronics. High-capacity MLCC lead times have reached 20-24 weeks, while automotive-grade and leaded products are at 26-30 weeks.
Murata Manufacturing / Taiyo Yuden
High-end MLCC quotations continue to rise, with key raw material BaTiO3 and capacity utilization becoming sources of profit sensitivity. AI servers, 800G/1.6T optical modules, and high-power automotive electronics all require higher-reliability capacitors, and Japanese vendors' pricing power is likely to be stronger than in ordinary consumer electronics cycles.
Optical Communications Chain
800G copper connection distance is about 2 meters, 1.6T is about 1 meter, and 3.2T is even shorter. This turns CPO, silicon photonics, and optical modules from "optional upgrades" into necessary components for large-scale clusters. Valuation divergence among Lumentum, Coherent, and AAOI centers on EML supply, customer validation, and data center revenue mix.
Sivers
Sivers secured $61mn of funding to expand InP laser and optical-amplifier capacity. EML supply is believed to remain 40%-60% short in 2027, and lead times for upstream lasers and optical components will directly affect the ramp of 1.6T/3.2T networks.
POET
POET plans to begin volume shipments of optical engines in 2H26, with a year-end 2027 monthly capacity target of 1mn units and more than 10 active customers. If customer validation lands, the company has a chance to exceed $100mn in annual revenue. In the near term, however, yield, packaging capacity, and customer concentration remain the key watch points.
Power Chain
AI-ready data center capex has already exceeded $17mn-$20mn/MW, and annual gas turbine market capacity has been revised up from 90-100GW to 110-120GW. The logic of power equipment, on-site generation, and high-voltage distribution is to translate model demand into deliverable data hall capacity.
Robotics/Autonomous Driving
Ambarella
Ambarella received a $120 target price from Rosenblatt, and the shares previously rose about 30% in a single day. The company's Edge AI SoC ASP has risen from $8 to $15, third-generation chip ASP can exceed $100, and the target gross margin is 59%-62%. Robotics design projects have reached 15, with the key question being the pace of mass production.
Agility Robotics
Agility has deployed into customer scenarios including GXO, Schaeffler, Toyota Motor, MercadoLibre, and Amazon, with planned capacity above 10,000 units per year. Each humanoid robot may use 20-40 reducers. If annual output reaches 100,000 units, reducer demand could correspond to a $1.6bn market.
Harmonic Drive
Harmonic Drive's FY3/26 sales are expected to be JPY59.6bn, up 7% in yen terms. FY3/27 guidance is JPY68.0bn, up 14.2% in yen terms, with operating profit expected to grow 141%. North American reducer orders rose 31.3% and Japan rose 26.9%, showing that robotics capex has already started to pass through to precision components.
Internet/Platforms
Google Search and YouTube
Advertising expert checks show Google Search growth at 4.9%, above the 4.0% expectation, and YouTube growth at 12.9%, above the 11.5% expectation. Search budget expectations were raised from 4.0% to 4.6%, and YouTube from 10.7% to 12.0%, indicating that the AI search impact has not yet clearly appeared in ad budgets.
"Google Search growth was 4.9 versus 4.0 expected, YouTube was 12.9 versus 11.5 expected."
AppLovin
AppLovin advertising growth reached 36.5%, above the 28.4% expectation, while non-gaming ROAS improved 12.5% QoQ. The expected 2026 budget share was raised from 27.5% to 30.0%, and the market continues to treat AppLovin as a representative of mobile advertising efficiency improvement and AI ad-delivery model optimization.
The Trade Desk
The Trade Desk growth was 6.1%, 190bp below expectation, and 2026 growth expectations were lowered from 8.5% to 7.0%. The investment implication for programmatic advertising is clear: if retail media, CTV, and the open internet cannot improve growth in sync, valuation will be hard to support with the AI label alone.
Pinterest
Pinterest growth was 5.0%, while 2026 growth expectations were lowered from 5.9% to 5.5%, and CPM rose 3%. Its advantages remain commercial intent and visual search, but advertiser budgets are shifting toward platforms that can directly prove ROAS. Near-term revenue sensitivity is weaker than AppLovin's.
Amazon Advertising and Cloud Synergy
Amazon shares fell 0.90% that day, but AWS Bedrock ARR and the advertising business remain two entry points for a company rerating. E-commerce traffic drives conversion, while cloud AI drives enterprise monetization. What the market truly needs to validate is whether AI tools can bring higher cloud consumption, rather than only increasing capex.
Meta Advertising and In-House Chips
Meta rose 0.12%. The advertising side is stable, while in-house MTIA puts the company into the ASIC and HBM demand chains. If MTIA 500 advances as planned, Meta's value drivers will expand from advertising recovery to AI infrastructure efficiency. The core validation points are inference cost and recommendation-system conversion rates.
Shopify
The AI trade for platform e-commerce is more tool-oriented, with focus on merchant customer acquisition, customer service, and conversion, not the model itself. If ad prices keep rising, small and medium merchants will be more willing to buy plugins and payment services that directly reduce customer acquisition costs. These platforms need to prove that AI is not a cost item through GMV and take rate.
Internet Platform Style
The communication services ETF fell 0.70%, and no unified theme has formed inside internet platforms. Advertising, cloud, and AI chips pull valuation in different directions within the same company. The market assigns higher weight to the higher-certainty hardware chain, while patience for platform applications depends on whether Q2 results can deliver revenue acceleration.
Software/SaaS
Palo Alto Networks
Palo Alto Networks rose 2.88% and made a stage high. It is one of the first 12 Glasswing partners, Cortex XSIAM remains the platform integration engine, and CyberArk and Chronosphere connect identity and observability into security operations. The main line for security software is platformization, not the stacking of point AI features.
"Cortex XSIAM remains the integration engine, with CyberArk and Chronosphere extending the platform to identity and observability."
CrowdStrike
JPMorgan maintains Overweight on CrowdStrike, seeing it as uniquely positioned across three AI security alliances. Endpoint, identity, cloud workload, and data security are converging into a unified platform. Customers' willingness to pay depends on reducing alert noise and shortening response time.
Tenable
JPMorgan raised its Tenable target price from $35 to $40 and maintained Overweight. 2026-2028 revenue forecasts are $1.077bn, $1.168bn, and $1.263bn, respectively. Tenable One already accounted for 41% of 1Q26 new business, about 30% of customers have migrated, and ASP uplift ranges from 6% to 60%.
Qualys
JPMorgan raised its Qualys target price from $87 to $139 and upgraded the rating to Neutral. The company has a 47% EBITDA margin, Rule of 40 at 57%, and free-cash-flow margin of 45%. The valuation repair comes from profit quality, but revenue reacceleration still needs a clearer product cycle.
Security Software Budgets
Security software remains a priority destination for enterprise AI budget spillover, because once models connect to enterprise data, identity, observability, endpoint, and data protection all rise together. The investment implication is that platform vendors can raise prices more easily than point tools, but customers will require automated response and lower false positives to prove ROI.
Rampart
Rampart uses a 14.7MB WebGPU model to complete privacy detection inside the browser, with 98.4% recall. These local small models will not weaken the cloud AI main line, but they will allow software companies to move some inference onto endpoints, lowering latency and reducing sensitive data egress.
AI Coding Tools
Developers pay $150-250 per month for AI coding tools, and more than 70% of Anthropic and OpenAI ARR comes from coding use cases. The real business question for software companies is whether they can turn "assisted coding" into team-level workflows, rather than only selling individual subscriptions.
Software Style
IGV rose only 0.79%, and SKYY rose 1.25%, clearly lagging semiconductors. The market is setting a higher bar for software: it needs to see revenue reacceleration, margins not being consumed by AI inference cost, and customer renewals not being squeezed by budget reallocation.
Consumer Electronics/Smart Vehicles
Apple
Apple rose 2.70%, still supported in the short term by the large-cap growth style. The key variables for the consumer electronics chain are not one-day share moves, but whether edge AI features can drive replacement demand, storage-capacity upgrades, and service monetization. If DRAM, NAND, and high-end MLCC prices continue to rise, terminal gross margins will come under pressure.
Qualcomm Automotive and Edge AI
Qualcomm automotive annualized revenue is about $5bn, up 38% YoY, and the automotive design pipeline has reached $65bn. The company has set a FY2029 non-handset revenue target of $40bn. Automotive, edge AI, and data centers will jointly determine whether valuation can break away from the handset cycle.
Cellular IoT Modules
Q1 cellular IoT module shipments fell 17% YoY, ending 12 quarters of growth. AI embedded modules account for about 6% of cellular IoT modules and are expected to grow 19% in 2025. Memory price increases are pushing up BOM, and low-end IoT devices will accept AI features more slowly than high-end automotive and industrial scenarios.
Tesla
Tesla rose 2.13%, with robotics and autonomous driving still the most important long-term options in valuation. In the short term, regulatory milestones, FSD usage data, and the pace from robot prototypes to mass production need to be tracked. If progress remains at the demonstration stage, supply-chain orders will be hard to transmit continuously to reducers, sensors, and edge AI chips.
Mobileye
Mobileye has recently rebounded with the robotics and autonomous-driving chain, as the market refocuses on revenue sensitivity in vision perception and autonomous-driving SoCs. Its risks are automaker insourcing and price pressure. The validation point is whether high-level driver-assistance penetration can turn into stable design wins and software revenue.
Aurora / Symbotic / Rockwell Automation
Autonomous trucks, warehouse automation, and industrial automation all belong to the robotics capex spillover direction. The market is more willing to buy companies with customer deployments and order visibility. For concept names, revenue recognition, gross margin, and delivery cycles matter more than demonstration videos.
Precision Reducer Chain
If humanoid robots reach annual production of 100,000 units, reducer demand could reach $1.6bn. Similar products in China are priced at about 40%-60% of Harmonic Drive's level, with performance at about 70%-85%. This means overseas high-end vendors still have a quality premium, but price declines will compress medium- to long-term gross margins.
Consumer Electronics Cost Pass-Through
Simultaneous price increases in PC DRAM, server DRAM, SLC NAND, and high-end MLCC will pressure BOM for smartphones, PCs, IoT, and automotive terminals. If downstream brands lack pricing power from new features, inventory turnover and promotion intensity will become risk indicators before unit sales improve.
Investment Bank Target-Price Changes Over the Past 12 Hours
Jensen Huang Picks Portfolio
404K SEMI-AI Morning Tech Brief 2026-07-01 — Memory LTAs, Advanced Packaging, Power and Interconnects
目录
Post-Close Summary
U.S. Stock New Highs
AI/Semiconductor Full Value Chain
AI Models/Applications and Capex
CSP/Cloud Capex
AI Cloud/Data Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry, Advanced Packaging, and Equipment
MLCC, Optical Communications, and Power Infrastructure
Robotics/Autonomous Driving
Internet/Platforms
Software/SaaS
Consumer Electronics/Smart Vehicles
Investment Bank Target-Price Changes Over the Past 12 Hours
Jensen Huang Picks Portfolio
The AI hardware trade continues to broaden from the GPU main line into memory, packaging, power, and optical interconnects. After the close, semiconductor ETFs and equipment names led, while software and communication services remained weak. Capital is more willing to buy supply bottlenecks than a broad technology valuation repair.
Post-Close Summary
On June 30, U.S. tech leadership rotated back to the hardware chain. SPY rose 0.76%, QQQ rose 1.65%, and RSP fell 0.13%, showing that index gains were still driven by large-cap growth and semiconductors. At the sector level, XLK rose 2.77%, SMH rose 3.75%, and SOXX rose 4.26%, with semiconductor strength clearly ahead of software, cloud computing, and communication services.
At the stock level, AMD rose 7.53%, Intel rose 5.52%, TSMC rose 4.94%, ASML rose 5.65%, Applied Materials rose 4.48%, Lam Research rose 6.06%, Credo rose 10.69%, and Astera Labs rose 6.37%. The marginal change in the AI trade is that capital is continuing to spill outward along the chain of “GPU demand validation -> memory price increases -> advanced packaging -> power and optical interconnects.”
Software remains more mixed. IGV rose 0.79%, SKYY rose 1.25%, and AIQ rose 2.16%, all lagging semiconductors; communication services ETF XLC fell 0.70%. This shows that the market is placing more near-term weight on orders, capacity, price increases, and supply constraints. Pure application and advertising names need a stronger revenue slope to take over leadership.
U.S. Stock New Highs
AI/Semiconductor Full Value Chain
AI Models/Applications and Capex
OpenAI
1) Inference economics continue to improve. OpenAI’s inference cost fell by more than 50% in the latest cycle, with Q1 gross margin at 39% and a year-end target of 52%.
2) The investment implication is that model cost reductions have not depressed compute demand. Instead, they allow more enterprise workflows to shift into real-time inference, keeping usage hours for cloud, GPUs, memory, and networking on an upward path.
“OpenAI inference cost more than halved, Q1 gross margin 39%, year-end target 52%.”
Anthropic
Claude Sonnet 5 has entered long-context and enterprise coding use cases. Pricing for a 1mn-token context is $2 input and $10 output before August 31, then returns to $3 input and $15 output afterward. Enterprise customers buy capability first and negotiate cost later, which is more favorable in the near term for high-end inference throughput and reserved cloud capacity.
Enterprise AI Usage
Token consumption among large internet and cloud customers is still climbing. Meta’s token usage reached 60tn over the past 30 days, with the single largest user at 280bn. Developers’ monthly AI tool spend is concentrated in the $150-250 range, and more than 70% of Anthropic and OpenAI ARR comes from code-related use cases. This shows that coding, agents, and enterprise workflows remain the clearest paid entry points.
Etched
Etched has raised $800mn and has more than $1bn of customer contracts, with the first racks planned for delivery in the summer. It is betting on a dedicated Transformer inference chip. The commercial validation point is not benchmark scores, but how many tokens can be produced per unit of power. If delivery goes smoothly, it will further reinforce the long-term pressure from inference-specific ASICs on traditional GPU share.
“Whoever produces the most tokens will win the AI economy.”
Local AI Models
Rampart’s WebGPU model is 14.7MB, with 98.4% recall for privacy detection and millisecond-level latency. This shows that lightweight models can already handle some edge-side and in-browser tasks. However, the workloads that truly affect cloud capex remain training, long context, multimodality, and enterprise agent tasks, so this will not replace the data center main line in the near term.
CSP/Cloud Capex
Amazon
AWS Bedrock ARR has reached $25bn-$30bn, with margins above 50%. AWS also plans to expand its frontline engineering team by $1bn in scale to embed model capabilities into enterprise customer processes. The validation point for cloud capex is shifting from “whether there are GPUs” to “whether customers can turn models into billable business.”
Google
The TPU supply chain continues to expand. MediaTek participates in about 50% of TPU v9 share; v9 is priced at about 3x v8 and is configured with 1GB SRAM. The market’s real focus is whether Google can translate TPU cost advantages into cloud AI service gross margin, rather than treating in-house chips only as Nvidia substitutes.
Meta
MTIA 500 specifications point to higher power and higher memory bandwidth, with single-card TDP around 1.7kW, HBM bandwidth of 27.6TB/s, and memory capacity of 384-512GB. Meta’s in-house chips continue to pull demand for Broadcom, TSMC, and advanced packaging, while also exposing CPO, power delivery, and thermal constraints earlier.
Microsoft
Microsoft’s AI infrastructure bottleneck has extended from GPU procurement to power and campus supply. The Pecos project has on-site energy supply funded by Microsoft, with the logic of shortening the time spent waiting for grid interconnection. The future revenue validation point remains whether Azure AI consumption can cover higher unit MW investment.
Oracle
Oracle previously disclosed a $638bn order backlog, of which about $344bn is expected to convert into revenue over the next three years. The FY2030 revenue CAGR target is 31%. After the share-price pullback, the market debate is not whether demand exists, but whether customer concentration, financing cadence, and data center delivery can be realized in sync.
“Oracle backlog was $638bn, with $344bn expected over the next three years.”
AI Cloud/Data Center Operators
Nebius
Nebius’s AI cloud revenue grew 841% YoY in Q1, while total revenue was $399mn, up 684% YoY. Full-year revenue guidance is $3.0bn-$3.4bn, with an ARR target of $7.0bn-$9.0bn. It has already secured a $27bn contract from Meta and a $19.4bn contract from Microsoft. The question now shifts to whether 3.5GW of contracted power can become billable compute on schedule.
Bloom Energy
Bloom and Brookfield expanded their AI power partnership from $5bn to $25bn. The core selling point is faster access to on-site data center power. The investment implication for AI data centers is direct: when grid interconnection, transformer, and gas turbine lead times lengthen, companies that can shorten the time to energization will receive a valuation premium.
Digital Realty
Digital Realty’s JV asset transaction size was $7.8bn, with a capitalization rate above 6.5% and stabilization in 2027-2028. Data center asset value is about $27mn/MW, while construction cost is about $12mn/MW. A 2.3x cost recovery ratio reflects AI leasing demand repricing mature campuses.
AI Capacity Constraints
AI-ready centralized energized capacity is estimated at 12-15GW, while 2026 U.S. accelerator batch design load is about 10/15/20GW. Transformer lead times are 3-4 years, gas turbines are 3-6+ years, and transmission projects may require 7-15 years. Getting GPUs in hand is no longer the only bottleneck.
“GPU allocation ranks fourteenth.”
GPU/CPU/ASIC
Nvidia
1) Nvidia rose 2.63%, with the market continuing to trade lower Blackwell inference costs and upward revisions to second-half data center revenue.
2) DeepSeek V4 token cost on Blackwell has fallen about 5x in one month, while single-GPU throughput has improved by as much as 20x.
3) If inference costs continue to fall, customer budgets will not fall linearly. They may instead shift toward higher-frequency calls and longer context.
AMD
1) AMD rose 7.53%, and Wells Fargo raised its target price from $505 to $615 while maintaining Overweight.
2) Wells Fargo models CY26/27/28 server CPU revenue at $16.0bn/$20.5bn/$25.0bn and data center GPU revenue at $15.6bn/$40.6bn/$63.0bn.
3) Versal’s move from HBM to LPDDR5X shows that memory cost and supply availability have already started to affect system design.
“CY26/27/28 server CPU revenue was modeled at $16.0bn/$20.5bn/$25.0bn, data center GPU at $15.6bn/$40.6bn/$63.0bn.”
Broadcom
Jefferies maintains Buy on Broadcom with a $550 target price, and places C28 EPS potential in the $30-40 range. TPU 8i is expected to ramp in 3Q26, and the Google partnership can extend to 2031. The investment focus is whether ASIC revenue can expand from a single customer to more CSPs, not near-term gross-margin volatility.
MediaTek
Macquarie raised its MediaTek target price from NT$5,850 to NT$10,000 and maintained Outperform. The core change comes from the TPU roadmap: v9 is priced at about 3x v8, and MediaTek participates in about 50% share. If v10 continues to ramp later, the company could be rerated from a handset SoC cyclical name into an AI ASIC supply-chain name.
Qualcomm
Qualcomm’s FY2029 non-handset revenue target is $40bn, including a data center target above $15bn and an automotive revenue target of $10bn. Current automotive annualized revenue is about $5bn, up 38% YoY. The Meta CPU agreement and the $4bn Modular acquisition have prompted the market to reassess Qualcomm’s option value in edge AI, automotive, and server CPUs.
Cerebras
Cerebras capacity has been reserved by OpenAI, and some users are seeking low-latency inference at 1,000-2,000 tokens per second. Its advantage is in real-time output and low-latency experiences for large models. The risks are customer concentration, capacity lock-in, and whether the software ecosystem can support more enterprise workloads.
HBM/DRAM/NAND/SSD/HDD
Micron Technology
Micron rose 0.42%, with the memory main line still driven by data center demand and price-increase expectations. DBS raised its target price from $1,200 to $1,400. The company’s Q3 data center revenue grew 653%, with DRAM, HBM, and enterprise SSDs all benefiting from AI server procurement.
SanDisk
SanDisk rose 10.23%, and Bernstein raised its target price from $1,700 to $3,000. The memory trade is spreading from DRAM to NAND and enterprise SSDs. The investment implication is that once AI training data, inference logs, and cold-storage demand rise, HDDs, NAND, and the controller chain are no longer just a PC-cycle recovery trade.
“SanDisk target was raised from $1,700 to $3,000.”
Samsung Electronics
Samsung’s HBM process is still working through yield loss after layer-count increases. Moving from 8-high to 12-high stacks may reduce yield by 10-20 percentage points, while 16-high yield is in the 40%-60% range. A new patent uses dummy dies to improve structural stability, with the goal of preparing for HBM5 stacks above 16-high.
SK Hynix
SK Hynix remains the leader in HBM share, with industry estimates placing its HBM share above 50%. If 2027 HBM contract prices continue to rise, Hynix will benefit first. The risk is that after Samsung and Micron improve yield, customer bargaining power rises again.
Enterprise SSDs and HDDs
Enterprise SSD total capacity is expected to reach 509.33EB in 2026, up 94% YoY. Data center nearline HDD capacity is expected to reach 1,841EB in 2026, up 30.1% YoY. This data shows that AI storage demand is not a single HBM trade. Training data, inference caches, and archives are all extending the storage upcycle.
DRAM Pricing
Q3 PC DRAM prices are expected to rise 15%-20%, while server DRAM is expected to rise 13%-18%. SLC NAND prices rose 28%-31% in June and may rise another 60%-70% in Q3. Price increases can lift profit sensitivity, but they will also pass through the BOM into AI modules, servers, and end devices.
Foundry, Advanced Packaging, and Equipment
TSMC
Nomura expects TSMC’s 2026/2027 USD revenue to grow 37%/30%, with capex of $75bn/$85bn, respectively. CoWoS capacity is expected to rise from 1.1mn pieces in 2026 to 2.0mn pieces in 2027, with TPU, GPU, and ASIC orders all competing for advanced-packaging share.
“CoWoS capacity was modeled at 1,100kpcs in 2026 and 2,000kpcs in 2027.”
Applied Materials
Applied Materials rose 4.48%, and Susquehanna raised its target price from $575 to $900 while maintaining Positive. Samsung has already made early-stage development requests to equipment partners including Applied Materials and Lam Research. High-NA EUV has been introduced into NRD-K and is expected to be used from some 1.4nm layers onward.
Lam Research
Lam Research rose 6.06% and has about 50% global share in etch, benefiting from GAA, HBM, advanced packaging, and more complex process steps. As AI chips move toward higher bandwidth and higher-density packaging, etch and deposition steps increase, and equipment revenue sensitivity will be higher than traditional wafer shipments.
KLA
KLA fell 8.04%, but still has about 55% share in process control and inspection, making it a key link in advanced-node yield ramps. Short-term share-price reaction cannot replace fundamental judgment. The real validation point is whether 2nm, High-NA, and advanced-packaging inspection orders can continue.
ASML
ASML rose 5.65%, with High-NA EUV already entering Samsung’s NRD-K node development. The risk for the equipment chain is not disappearing demand, but customer capex cadence and the mass-production timing of advanced nodes. If 1.4nm layers adopt High-NA, follow-on order visibility will continue to rise.
AEHR
AEHR’s new orders reached $37.2mn, up 500% YoY, with book-to-bill above 3.5x. Reliability-testing demand for CPO, silicon photonics, and AI optical networking is rising. Test equipment is rotating from the automotive silicon carbide cycle into the optical interconnect and advanced-packaging cycle.
MLCC, Optical Communications, and Power Infrastructure
Samsung Electro-Mechanics
Hana Securities raised its Samsung Electro-Mechanics target price to KRW3.0mn and maintained Buy. The company secured about KRW454bn of high-end MLCC long-term agreements, with customer demand coming from AI servers, ASICs, and automotive electronics. High-capacity MLCC lead times have reached 20-24 weeks, while automotive-grade and leaded products are at 26-30 weeks.
Murata Manufacturing / Taiyo Yuden
High-end MLCC quotations continue to rise, with key raw material BaTiO3 and capacity utilization becoming sources of profit sensitivity. AI servers, 800G/1.6T optical modules, and high-power automotive electronics all require higher-reliability capacitors, and Japanese vendors’ pricing power is likely to be stronger than in ordinary consumer electronics cycles.
Optical Communications Chain
800G copper connection distance is about 2 meters, 1.6T is about 1 meter, and 3.2T is even shorter. This turns CPO, silicon photonics, and optical modules from “optional upgrades” into necessary components for large-scale clusters. Valuation divergence among Lumentum, Coherent, and AAOI centers on EML supply, customer validation, and data center revenue mix.
Sivers
Sivers secured $61mn of funding to expand InP laser and optical-amplifier capacity. EML supply is believed to remain 40%-60% short in 2027, and lead times for upstream lasers and optical components will directly affect the ramp of 1.6T/3.2T networks.
POET
POET plans to begin volume shipments of optical engines in 2H26, with a year-end 2027 monthly capacity target of 1mn units and more than 10 active customers. If customer validation lands, the company has a chance to exceed $100mn in annual revenue. In the near term, however, yield, packaging capacity, and customer concentration remain the key watch points.
Power Chain
AI-ready data center capex has already exceeded $17mn-$20mn/MW, and annual gas turbine market capacity has been revised up from 90-100GW to 110-120GW. The logic of power equipment, on-site generation, and high-voltage distribution is to translate model demand into deliverable data hall capacity.
Robotics/Autonomous Driving
Ambarella
Ambarella received a $120 target price from Rosenblatt, and the shares previously rose about 30% in a single day. The company’s Edge AI SoC ASP has risen from $8 to $15, third-generation chip ASP can exceed $100, and the target gross margin is 59%-62%. Robotics design projects have reached 15, with the key question being the pace of mass production.
Agility Robotics
Agility has deployed into customer scenarios including GXO, Schaeffler, Toyota Motor, MercadoLibre, and Amazon, with planned capacity above 10,000 units per year. Each humanoid robot may use 20-40 reducers. If annual output reaches 100,000 units, reducer demand could correspond to a $1.6bn market.
Harmonic Drive
Harmonic Drive’s FY3/26 sales are expected to be JPY59.6bn, up 7% in yen terms. FY3/27 guidance is JPY68.0bn, up 14.2% in yen terms, with operating profit expected to grow 141%. North American reducer orders rose 31.3% and Japan rose 26.9%, showing that robotics capex has already started to pass through to precision components.
Internet/Platforms
Google Search and YouTube
Advertising expert checks show Google Search growth at 4.9%, above the 4.0% expectation, and YouTube growth at 12.9%, above the 11.5% expectation. Search budget expectations were raised from 4.0% to 4.6%, and YouTube from 10.7% to 12.0%, indicating that the AI search impact has not yet clearly appeared in ad budgets.
“Google Search growth was 4.9 versus 4.0 expected, YouTube was 12.9 versus 11.5 expected.”
AppLovin
AppLovin advertising growth reached 36.5%, above the 28.4% expectation, while non-gaming ROAS improved 12.5% QoQ. The expected 2026 budget share was raised from 27.5% to 30.0%, and the market continues to treat AppLovin as a representative of mobile advertising efficiency improvement and AI ad-delivery model optimization.
The Trade Desk
The Trade Desk growth was 6.1%, 190bp below expectation, and 2026 growth expectations were lowered from 8.5% to 7.0%. The investment implication for programmatic advertising is clear: if retail media, CTV, and the open internet cannot improve growth in sync, valuation will be hard to support with the AI label alone.
Pinterest
Pinterest growth was 5.0%, while 2026 growth expectations were lowered from 5.9% to 5.5%, and CPM rose 3%. Its advantages remain commercial intent and visual search, but advertiser budgets are shifting toward platforms that can directly prove ROAS. Near-term revenue sensitivity is weaker than AppLovin’s.
Amazon Advertising and Cloud Synergy
Amazon shares fell 0.90% that day, but AWS Bedrock ARR and the advertising business remain two entry points for a company rerating. E-commerce traffic drives conversion, while cloud AI drives enterprise monetization. What the market truly needs to validate is whether AI tools can bring higher cloud consumption, rather than only increasing capex.
Meta Advertising and In-House Chips
Meta rose 0.12%. The advertising side is stable, while in-house MTIA puts the company into the ASIC and HBM demand chains. If MTIA 500 advances as planned, Meta’s value drivers will expand from advertising recovery to AI infrastructure efficiency. The core validation points are inference cost and recommendation-system conversion rates.
Shopify
The AI trade for platform e-commerce is more tool-oriented, with focus on merchant customer acquisition, customer service, and conversion, not the model itself. If ad prices keep rising, small and medium merchants will be more willing to buy plugins and payment services that directly reduce customer acquisition costs. These platforms need to prove that AI is not a cost item through GMV and take rate.
Internet Platform Style
The communication services ETF fell 0.70%, and no unified theme has formed inside internet platforms. Advertising, cloud, and AI chips pull valuation in different directions within the same company. The market assigns higher weight to the higher-certainty hardware chain, while patience for platform applications depends on whether Q2 results can deliver revenue acceleration.
Software/SaaS
Palo Alto Networks
Palo Alto Networks rose 2.88% and made a stage high. It is one of the first 12 Glasswing partners, Cortex XSIAM remains the platform integration engine, and CyberArk and Chronosphere connect identity and observability into security operations. The main line for security software is platformization, not the stacking of point AI features.
“Cortex XSIAM remains the integration engine, with CyberArk and Chronosphere extending the platform to identity and observability.”
CrowdStrike
JPMorgan maintains Overweight on CrowdStrike, seeing it as uniquely positioned across three AI security alliances. Endpoint, identity, cloud workload, and data security are converging into a unified platform. Customers’ willingness to pay depends on reducing alert noise and shortening response time.
Tenable
JPMorgan raised its Tenable target price from $35 to $40 and maintained Overweight. 2026-2028 revenue forecasts are $1.077bn, $1.168bn, and $1.263bn, respectively. Tenable One already accounted for 41% of 1Q26 new business, about 30% of customers have migrated, and ASP uplift ranges from 6% to 60%.
Qualys
JPMorgan raised its Qualys target price from $87 to $139 and upgraded the rating to Neutral. The company has a 47% EBITDA margin, Rule of 40 at 57%, and free-cash-flow margin of 45%. The valuation repair comes from profit quality, but revenue reacceleration still needs a clearer product cycle.
Security Software Budgets
Security software remains a priority destination for enterprise AI budget spillover, because once models connect to enterprise data, identity, observability, endpoint, and data protection all rise together. The investment implication is that platform vendors can raise prices more easily than point tools, but customers will require automated response and lower false positives to prove ROI.
Rampart
Rampart uses a 14.7MB WebGPU model to complete privacy detection inside the browser, with 98.4% recall. These local small models will not weaken the cloud AI main line, but they will allow software companies to move some inference onto endpoints, lowering latency and reducing sensitive data egress.
AI Coding Tools
Developers pay $150-250 per month for AI coding tools, and more than 70% of Anthropic and OpenAI ARR comes from coding use cases. The real business question for software companies is whether they can turn “assisted coding” into team-level workflows, rather than only selling individual subscriptions.
Software Style
IGV rose only 0.79%, and SKYY rose 1.25%, clearly lagging semiconductors. The market is setting a higher bar for software: it needs to see revenue reacceleration, margins not being consumed by AI inference cost, and customer renewals not being squeezed by budget reallocation.
Consumer Electronics/Smart Vehicles
Apple
Apple rose 2.70%, still supported in the short term by the large-cap growth style. The key variables for the consumer electronics chain are not one-day share moves, but whether edge AI features can drive replacement demand, storage-capacity upgrades, and service monetization. If DRAM, NAND, and high-end MLCC prices continue to rise, terminal gross margins will come under pressure.
Qualcomm Automotive and Edge AI
Qualcomm automotive annualized revenue is about $5bn, up 38% YoY, and the automotive design pipeline has reached $65bn. The company has set a FY2029 non-handset revenue target of $40bn. Automotive, edge AI, and data centers will jointly determine whether valuation can break away from the handset cycle.
Cellular IoT Modules
Q1 cellular IoT module shipments fell 17% YoY, ending 12 quarters of growth. AI embedded modules account for about 6% of cellular IoT modules and are expected to grow 19% in 2025. Memory price increases are pushing up BOM, and low-end IoT devices will accept AI features more slowly than high-end automotive and industrial scenarios.
Tesla
Tesla rose 2.13%, with robotics and autonomous driving still the most important long-term options in valuation. In the short term, regulatory milestones, FSD usage data, and the pace from robot prototypes to mass production need to be tracked. If progress remains at the demonstration stage, supply-chain orders will be hard to transmit continuously to reducers, sensors, and edge AI chips.
Mobileye
Mobileye has recently rebounded with the robotics and autonomous-driving chain, as the market refocuses on revenue sensitivity in vision perception and autonomous-driving SoCs. Its risks are automaker insourcing and price pressure. The validation point is whether high-level driver-assistance penetration can turn into stable design wins and software revenue.
Aurora / Symbotic / Rockwell Automation
Autonomous trucks, warehouse automation, and industrial automation all belong to the robotics capex spillover direction. The market is more willing to buy companies with customer deployments and order visibility. For concept names, revenue recognition, gross margin, and delivery cycles matter more than demonstration videos.
Precision Reducer Chain
If humanoid robots reach annual production of 100,000 units, reducer demand could reach $1.6bn. Similar products in China are priced at about 40%-60% of Harmonic Drive’s level, with performance at about 70%-85%. This means overseas high-end vendors still have a quality premium, but price declines will compress medium- to long-term gross margins.
Consumer Electronics Cost Pass-Through
Simultaneous price increases in PC DRAM, server DRAM, SLC NAND, and high-end MLCC will pressure BOM for smartphones, PCs, IoT, and automotive terminals. If downstream brands lack pricing power from new features, inventory turnover and promotion intensity will become risk indicators before unit sales improve.
Investment Bank Target-Price Changes Over the Past 12 Hours
Jensen Huang Picks Portfolio