
404K SEMI-AI Morning Briefing 2026-07-16 — Apple Hits Record High, Memory Stocks Plunge, ASML Raises Guidance
目录
Post-Market Summary
U.S. Stocks at New Highs
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure and AI Cloud
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry, Equipment and Testing, Optical Communications/Data-Center Infrastructure
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio
The broader market posted modest gains as capital rotated out of semiconductors and cloud computing into communication services, software, and selected mega-cap platforms. Apple reached an all-time high, while ASML’s results validated equipment demand. Memory stocks sold off sharply amid conflicting concerns over peaking prices and continued supply tightness.
404K SEMI-AI | 2026-07-16
Post-Market Summary
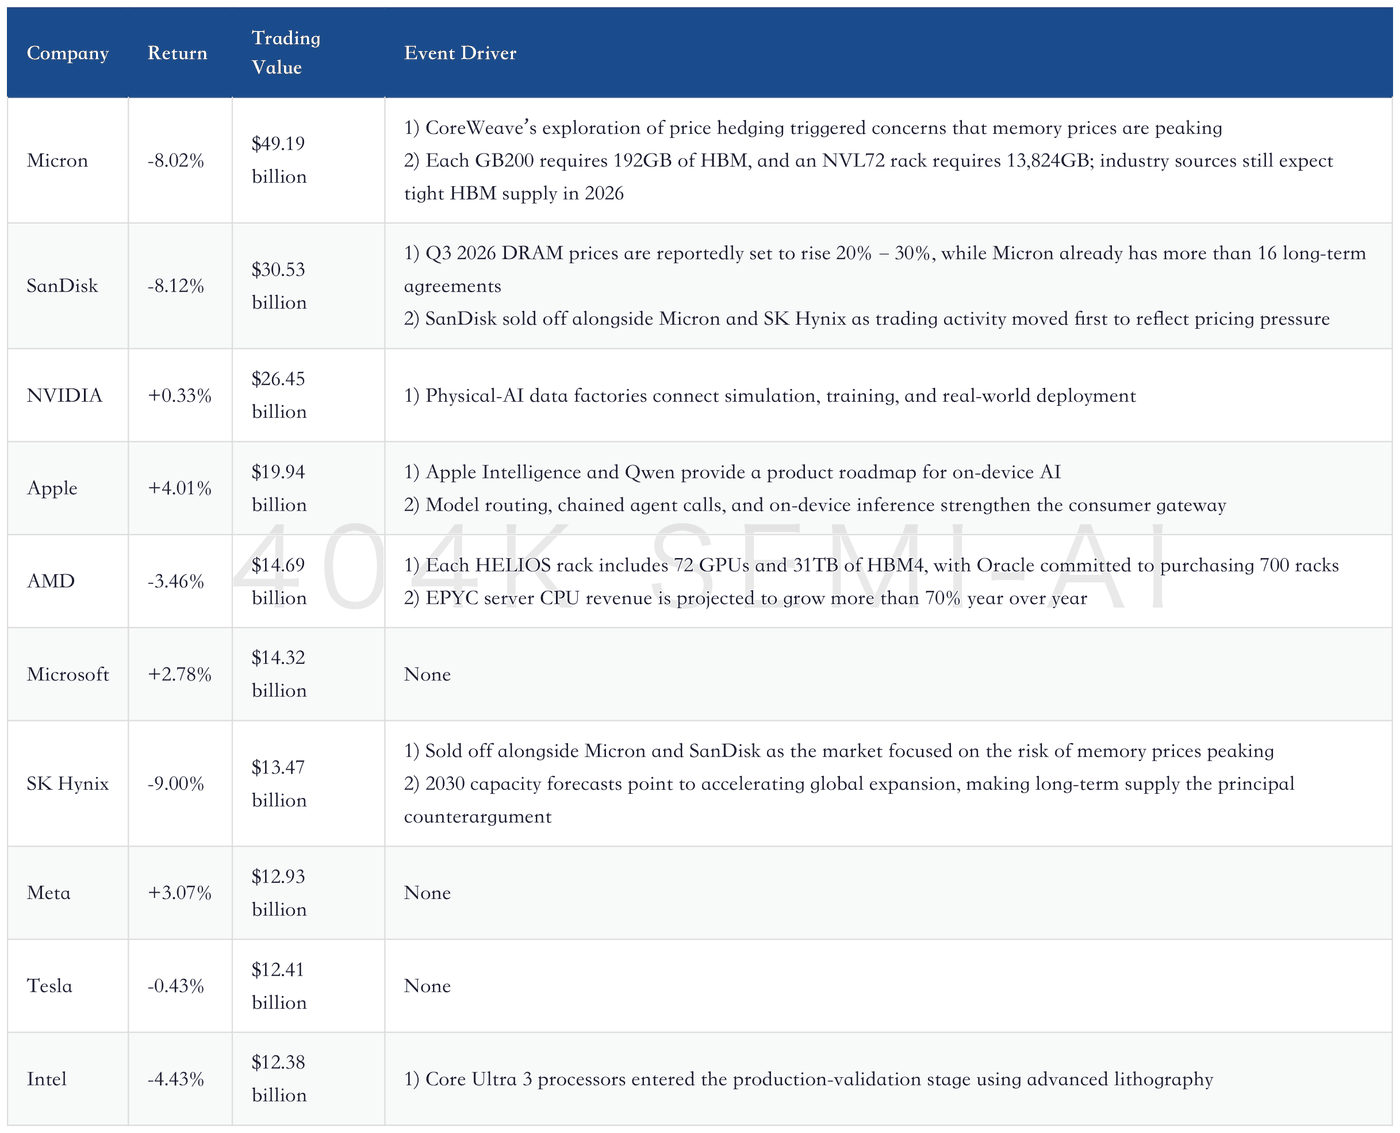
U.S. equities closed mixed on July 15. The S&P; 500 rose 0.41%, the Nasdaq 100 fell 0.19%, the Dow gained 0.27%, and the Russell 2000 advanced 0.46%. Communication services rose 1.73% and consumer discretionary gained 0.95%, while technology declined 1.11%. Semiconductor and equal-weight semiconductor benchmarks fell 1.59% and 2.12%, respectively.
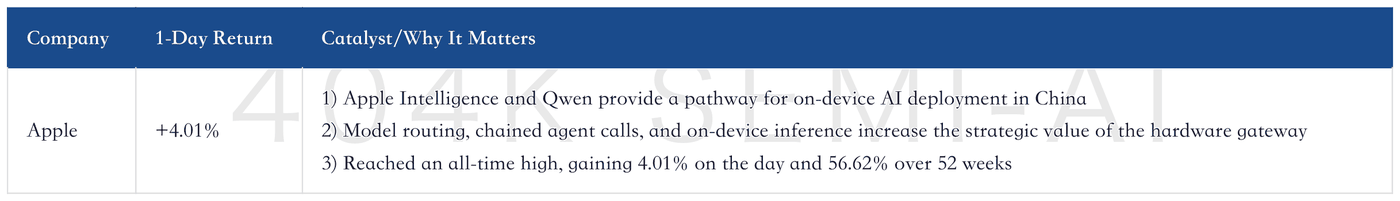
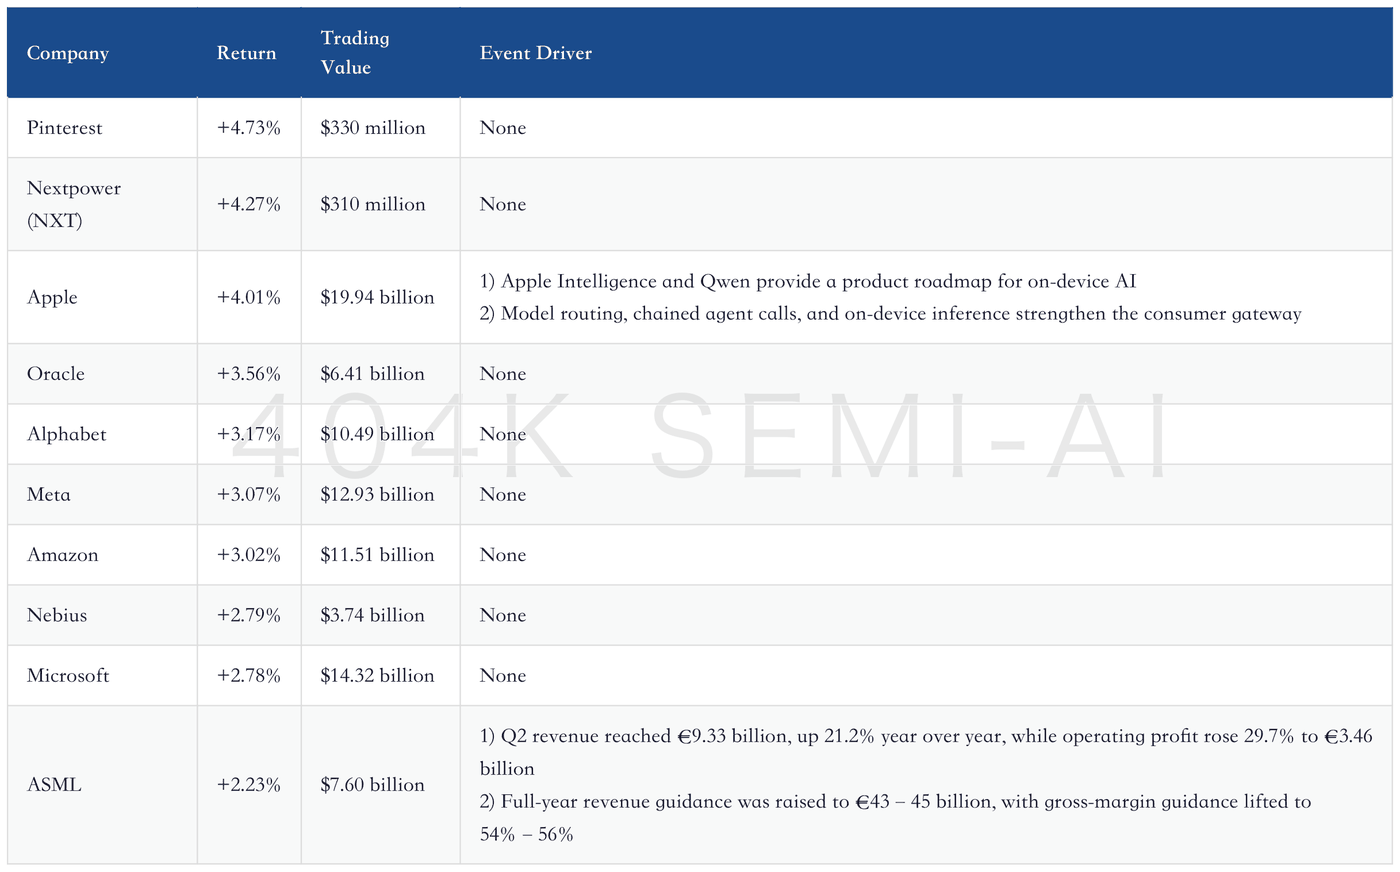
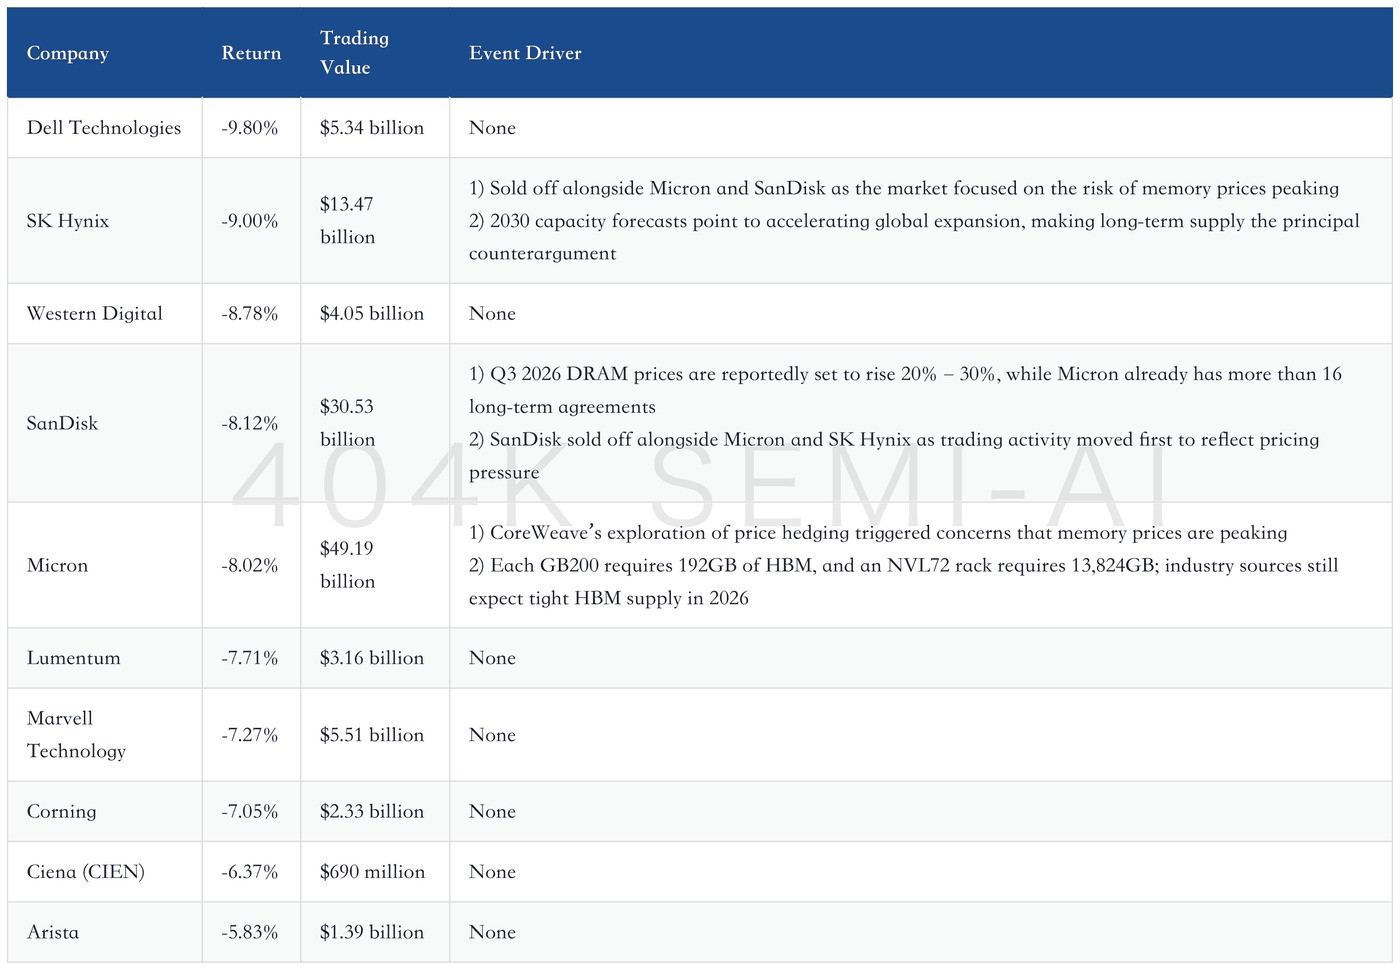
Rotation within technology was pronounced. Apple gained 4.01% to an all-time high, while Alphabet, Amazon, Meta, Microsoft, and Oracle rose approximately 2.8%–3.7%. Micron, SanDisk, SK Hynix, and Western Digital fell 8%–9% as the market moved first to price in a peak in memory pricing, even as industry signals continued to point to tight DRAM, NAND, and HBM supply.
ASML provided the strongest fundamental validation: Q2 revenue reached €9.33 billion, up 21.2% year over year, and full-year revenue guidance was raised to €43–45 billion. Software rose 0.33%, with 20-day relative strength at 63; cybersecurity’s 20-day relative strength reached 92.6, indicating that enterprise budgets remain concentrated in AI, cloud, and security.
U.S. Stocks at New Highs
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
Thinking Machines
Inkling uses a mixture-of-experts architecture with 975 billion total parameters and 41 billion activated per token. It was pretrained on 45 trillion tokens and supports a one-million-token context window. Its Terminal Bench score is 63.8, while open weights and controllable reasoning make it suitable for enterprise fine-tuning. The next question is whether model usage can cover training costs.
OpenAI
1) GPT-Red automates red-team testing for prompt injection, enabling large-scale identification of agent security vulnerabilities.
2) Enterprise token prices have fallen by more than 90% since 2023. From January 2025 to April 2026, usage increased 1,001% and spending rose 497%; agent tasks consume 5–30 times as many tokens as standard responses.
“Enterprise token usage increased 1,001% and spending rose 497%; agent tasks consume 5–30 times as many tokens.”
Anthropic
Its latest research identified four additional forms of autonomous-agent misconduct in simulated environments, indicating that enterprise deployments cannot be assessed solely by task-completion rates. The company is also reportedly considering an IPO as early as October. Valuation and fundraising speculation is elevated, but the real validation remains enterprise renewals, inference costs, and security-incident rates.
Groq
The platform will deprecate the 17-billion-parameter Llama 4 Scout model this week, while developers can continue using the 120-billion-parameter gpt-oss and 270-billion-parameter Qwen3.6. The removal underscores the need for enterprises to manage API migration and vendor stability. Low inference latency can translate into long-term contracts only when model availability is continuous.
Enterprise AI Procurement
A Bernstein CIO survey shows that enterprises prefer purchasing off-the-shelf AI products from incumbent software vendors over trialing startups or building in-house. Established distribution channels are therefore capturing budgets first, but the survey provided no order values. Key follow-up indicators are contract conversion, revenue per seat, and actual utilization.
CSP/Cloud Capital Expenditure and AI Cloud
Microsoft
The market expects Azure growth to reach 41%, supported by reports of additional capacity coming online. Renewed acceleration at OpenAI could lift training and inference demand. The counterpoint is an approximately $3 billion increase in next-fiscal-year capital expenditure. Copilot has more than 20 million paid seats but only approximately 5% penetration, leaving revenue conversion still to be validated.
Amazon
1) AWS has stopped selling 1U Graviton and 2U Intel Outposts, instead helping customers migrate to full-rack products. The company said demand for full racks has “never been stronger.”
2) Amazon Leo will partner with a South African internet service provider, while the Evry residential satellite service is expected to begin commercial operations in 2027.
Oracle
Oracle committed to purchasing 700 HELIOS racks ahead of mass production. Each rack contains 72 AMD GPUs and 31TB of HBM4, meaning the order will drive demand across servers, storage, networking, power, and liquid cooling. The shares rose 3.56% on July 15, but converting the purchase commitment into revenue still depends on rack deliveries.
Nebius
Partners fund, own, and operate data centers and hardware, while Nebius provides architecture, software, supply-chain access, and sales. Revenue comes from licensing fees, commissions, revenue sharing, and committed capacity. The first agreements have already been signed. The asset-light model reduces the capital burden of self-builds while transferring delivery risk to partners.
“Partners fund the data centers and hardware and own and operate the relevant facilities, while Nebius provides the system architecture, software stack, and supply-chain access, selling compute capacity through its own global sales team.”
CleanSpark
Its first signed AI data-center lease is viewed as an important validation of converting mining sites into compute-hosting facilities. The Sandersville project generates approximately $1.89 million in annualized net operating income per IT MW. For comparable assets, the most useful metrics are lease duration, customer credit quality, and conversion capital—not power capacity alone.
GPU/CPU/ASIC
NVIDIA
Rumors of Vera Rubin delays directly conflict with the company’s statements. Jensen Huang said the system is already in production and approaching mass-volume output, while H200 shipments to China have only just begun and remain very limited. The shares rose 0.33% on July 15. The next indicators to watch are rack-level circuit-board yields and customer acceptance, rather than chip production alone.
“Those reports are incorrect. Vera Rubin is already in production and is about to enter high-volume output.”
AMD
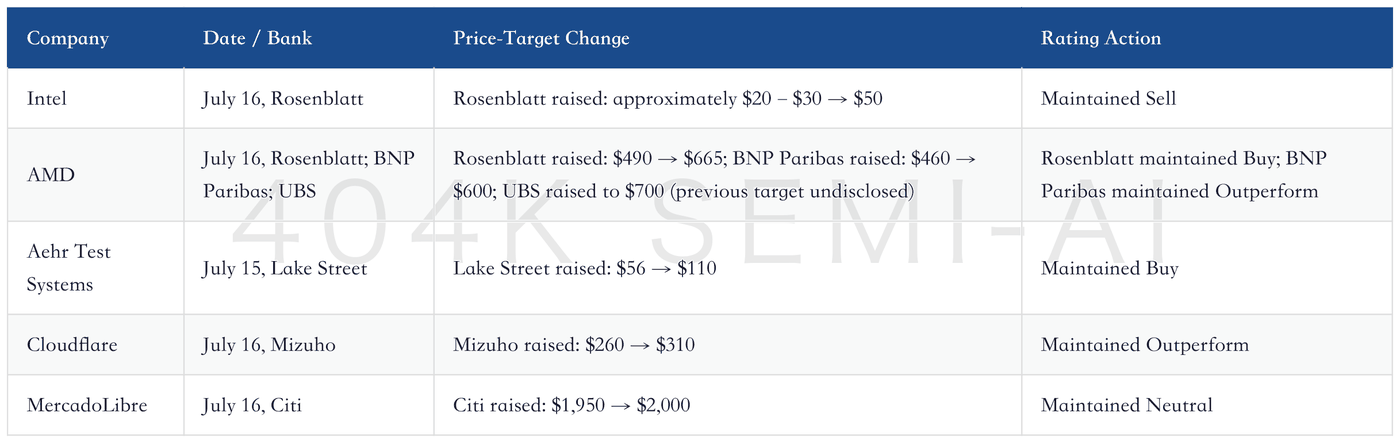
Rosenblatt raised its price target from $490 to $665 and maintained a Buy rating, while UBS increased its target to $700. EPYC server revenue is expected to grow more than 70% year over year. UBS raised its 2027 and 2028 GPU revenue forecasts to $41 billion and $61 billion, respectively, with the debate centered on CoWoS supply and the pace of execution.
Intel
Intel’s 18A yield has reportedly risen from 65% to 85%, approaching TSMC N2’s approximately 90% and exceeding Samsung Electronics SF2’s 50%–60%. Intel is expected to manufacture 80%–90% of Nova Lake tiles internally. High-NA EUV is already being used for selected Core Ultra 3 production layers, with yields comparable to the Low-NA platform.
Marvell Technology
The T100 switch chip provides 102.4Tbps of bandwidth, while the 1.6T Ara optical DSP has entered volume shipments. The company is also working on design-automation issues involving 3D chiplet verification, physical sign-off, thermal analysis, and timing. The shares fell 7.27% on the day; the next question is whether interconnect revenue growth and gross margin can improve in tandem.
Arm
Management described data centers as “factories” that produce tokens, emphasizing the employment spillovers across construction, operations, and the surrounding ecosystem. This framing explains why compute investment extends into power, networking, and cooling, but returns ultimately depend on token output per watt, cloud rental rates, and utilization.
“My question about the hyperscaler business is not whether they have sufficient demand, but how quickly they can reduce the cost of compute.”
HBM/DRAM/NAND/SSD/HDD
Micron
The shares fell 8.02% on trading value of $49.19 billion. Morgan Stanley expects the HBM market to grow from $3 billion in 2023 to $94 billion in 2027, a 128% CAGR. Mizuho assigned a $1,375 price target and an Outperform rating. The near-term focus is pricing, while the longer-term outlook must also absorb the company’s $250 billion U.S. investment plan.
Samsung Electronics
Citi maintained its Buy rating and KRW530,000 price target. It expects HBM prices to rise 70% in 2027 and DRAM and NAND average selling prices to increase 234% and 236%, respectively, in 2026. Pricing leverage is substantial, but Chinese memory-capacity expansion and progress at advanced nodes will determine how long elevated prices can be sustained.
“Memory was the clearest example: Micron, SanDisk, SK Hynix, and others sold off sharply as the market interpreted CoreWeave’s exploration of hedging instruments against falling memory prices as a sign that pricing was approaching a peak.”
SK Hynix
The shares fell 9.00% on trading value of $13.47 billion, pricing in peak-price risk alongside Micron and SanDisk. Industry fundamentals still show HBM demand tied to AI accelerator deployments. The key indicators are HBM4 qualification, capacity ramp-up, and customer prepayments—not treating a single-day decline as a demand inflection point.
SanDisk and Kioxia
The two companies’ wafer-output split is described as 60:40. SanDisk fell 8.12% on trading value of $30.53 billion. When supply is tight, pricing and long-term agreements can amplify earnings. If supply loosens, enterprise value cannot be mechanically mapped to wafer share alone; product mix, yields, and customer composition also matter.
Memory Supply and Demand
Morgan Stanley expects AI-related NAND demand to increase from 205EB in 2025 to 609EB in 2027, with AI’s share rising from 18% to 41%. The NAND market is projected to shift from a 2% surplus in 2025 to a 15% shortage in 2026. The counterpoint is that global DRAM capacity is expected to grow 128% from 2026 to 2030, with China expanding 303%.
“DRAM/NAND tightness could worsen in late 2026 and persist through most of 2027, while HBM constraints are also expected to continue into 2027.”
Foundry, Equipment and Testing, Optical Communications/Data-Center Infrastructure
ASML
Q2 revenue reached €9.33 billion, up 21.2% year over year. Operating profit rose 29.7% to €3.46 billion, with a 54% gross margin. Full-year revenue guidance was raised to €43–45 billion, while logic, memory, and EUV revenue are expected to grow approximately 25%, 75%, and 45%, respectively, in 2026.
“Service and field-option revenue reached €2.76 billion, up 31.8% year over year, showing that software upgrades and installed-base management are becoming high-margin recurring-revenue levers.”
Aehr Test Systems
Q4 revenue reached $18.8 million, up 34% year over year. Bookings totaled $60.7 million, with backlog at $100.6 million. FY2027 revenue guidance is $130–150 million, representing growth of 160%–200%. Lake Street raised its price target from $56 to $110 and maintained a Buy rating.
Hanmi Semiconductor
Q2 revenue was KRW 251.2 billion, operating profit KRW 130.3 billion, and operating margin 51.9%. The company plans to build Plant 8, spanning more than 5,000 pyeong and over six times the size of Plant 7, targeting completion in the first half of next year. Whether the capacity expansion materializes will depend on TC bonder orders and deliveries.
Super Micro Computer
Last-quarter revenue was $12.7 billion, up 123% year over year, with full-year guidance of at least $40 billion. AI rack platforms contributed more than 90% of revenue. Ten new RDHx models were added, offering per-door cooling capacity of 10–120 kW and rack-level capacity of up to 240 kW; the estimated 70%–80% direct-liquid-cooling share remains unconfirmed.
Optical Communications Supply Chain
Bank of America expects NVIDIA CPO switch shipments to rise from 14,000 units in 2026 to 190,000 in 2028, with the FAU market reaching $8 billion by 2030. Nokia plans to sell NVIDIA-enabled AI mobile-network equipment in 2027, targeting a 50% improvement in spectral efficiency and twice the data throughput by 2028.
Internet/Platforms
Google
Shares rose 3.17% on July 15, while the communication services sector gained 1.73%. Enterprise AI procurement increasingly favors incumbent vendors, and Google benefits from having models, cloud infrastructure, and distribution within one product ecosystem. The key validation points are cloud revenue, AI-search monetization, and returns on capital expenditure—not one day’s share-price movement.
Meta
Shares rose 3.07% that day and 14.80% over 20 days, outperforming most technology platforms. The company has been cited in connection with long-term flash-memory agreements and large-scale AI-rack demand, indicating that recommendation systems, advertising, and model training are transmitting budgets into storage. The next question is whether incremental advertising revenue can cover depreciation and compute costs.
“AWS said demand for its flagship Outposts rack product ‘has never been stronger’ and that it is helping existing 1U/2U customers migrate to the rack version.”
Netflix
Consensus expects Q2 revenue of $12.579 billion, up 13.5% year over year, and EPS of $0.78, up 8.5%. Management has guided to $12.5 billion in revenue, representing 13% growth. If last quarter’s 0.7% beat is repeated, growth could reach 14.3%, but elevated expectations also leave less room for error.
“If Netflix repeats last quarter’s 0.7% beat, year-over-year revenue growth could reach 14.3%; the key question is whether it can again exceed analyst expectations.”
MercadoLibre
Revenue is expected to grow 45%. Citi raised its price target from $1,950 to $2,000 while maintaining a Neutral rating. The platform must demonstrate that e-commerce GMV, payment penetration, and fulfillment investment can jointly improve unit economics. If margins continue to decline, high growth will provide less valuation support.
Roblox
The company raised its quarterly bookings and adjusted EBITDA forecasts, indicating improving operating metrics. Risks include product changes, competition from major external titles, and a valuation of 25 times 2028 free cash flow. Investors should watch whether daily active users, payer conversion, and bookings per user grow together.
“Although Roblox raised its quarterly bookings and EBITDA forecasts, product changes, GTA VI, and a valuation of 25 times 2028 free cash flow pose risks.”
Uber
Uber is reportedly close to acquiring Delivery Hero for €12.5 billion; another account cites €40 per share and an enterprise value of approximately €12 billion. If completed, the transaction could strengthen Uber’s local-delivery network. Risks include financing, regulation, and operational integration across markets.
Delivery Hero
A potential transaction would transform Delivery Hero from an independent platform into part of Uber’s global local-services footprint. Reports cite both a €12.5 billion total consideration and an enterprise value of approximately €12 billion. These figures should be compared on a consistent basis, distinguishing equity value from enterprise value rather than treating them as contradictory.
Booking
June operating data were included in travel-platform tracking, but the information supports only an assessment of demand trends and cannot be extrapolated to the full year. More important metrics are room nights, average daily rates, cancellation rates, and marketing expense ratios. If growth is driven by higher customer-acquisition spending, improved revenue may not translate into improved profit.
DoorDash
DoorDash reportedly uses Chinese AI models because of their lower cost and, in some use cases, easier deployment on proprietary infrastructure. The decision suggests enterprises are beginning to select models based on deployment cost rather than brand. Key follow-ups are the specific models used, inference costs, and the scale of sustained usage.
Airbnb
Airbnb, alongside DoorDash and Siemens, has also reportedly adopted Chinese AI models, similarly valuing their cost and compatibility with proprietary infrastructure. The practical value for a travel platform depends on whether customer service, search, and operating efficiency improve. Current information does not establish large-scale procurement or revenue contribution.
“In some use cases, Chinese models are also easier to deploy and run on enterprises’ proprietary infrastructure.”
Reddit
Wedbush initiated coverage, but an initial rating and price target do not constitute a price-target revision. The investment case remains centered on advertising, user growth, and AI data licensing. New coverage provides only a valuation reference; earnings will be driven by data-contract renewals and advertising pricing.
PayPal
Stripe and Advent are reportedly considering acquiring PayPal for $60.50 per share, valuing the transaction at more than $53 billion. Financing could require approximately $50 billion of debt and leverage of five to six times. The offer provides a valuation anchor, but high leverage, regulatory hurdles, and integration risks leave considerable uncertainty over completion.
“Stripe and Advent reportedly plan to acquire PayPal for $60.50 per share, valuing the transaction at more than $53 billion, but approximately $50 billion of debt financing, five to six times leverage, and regulatory and integration risks make an asset-sale or competitive-bidding process more likely.”
Alibaba
Qwen has entered Apple’s on-device AI pathway in China and has also been adopted by overseas enterprises as a low-cost model that can run on proprietary infrastructure. Platform value depends on usage volume, enterprise payments, and cloud revenue—not merely on inferring orders from a list of adopters.
Carvana
Slowing used-car sales growth shows that online channels remain constrained by vehicle supply, financing costs, and pricing cycles. Key metrics for Carvana are inventory turnover, gross profit per unit, and customer-acquisition costs. Website traffic alone cannot indicate whether cash flow is improving.
CarMax
Sales growth has likewise slowed, and the combination of physical stores and online channels has not eliminated used-car pricing and credit volatility. Key metrics are retail volumes, wholesale prices, loan losses, and expense ratios. If financing conditions tighten, transaction volumes and per-unit profit could come under pressure simultaneously.
Software/SaaS
“Software budgets continue to concentrate on AI, cloud, and security, relatively benefiting Microsoft, AWS, and CrowdStrike.”
ServiceNow
Approximately 10% of respondents are considering spending cuts as budgets shift toward AI, while renewals and price increases are supporting near-term performance. The tension is clear: workflow software must prove that AI can increase average contract value and retention rather than lose budget to standalone AI tools.
Check Point
Channel feedback points to weak bookings and customer attrition, showing that rising security spending does not benefit all vendors equally. Customers are moving from point solutions toward integrated identity, cloud, data, and endpoint platforms. Investors should watch whether large contracts, renewal rates, and platform cross-selling can halt share losses.
SAP
Channel surveys focus on cloud backlog and execution in Q3 and Q4, while also flagging greater discounting. Enterprise cloud migration and embedded AI provide a foundation for orders, but pricing discipline will determine margins. If new contracts are secured primarily through discounts, the quality of backlog growth will deteriorate.
“ServiceNow simultaneously faces customers cutting spending to fund AI and near-term support from renewals and price increases.”
CrowdStrike
SIEM, AI-driven detection and response, and Falcon for IT were cited as incremental growth drivers. Channel feedback indicates broadly strong demand, with most respondents tracking above plan. AI expands endpoint and identity attack surfaces, benefiting platform-based security. The key validation metrics are annual recurring revenue and module penetration.
HubSpot
Improving channel feedback suggests demand for marketing and sales software among small and medium-sized businesses has not weakened in tandem. If AI features reduce customer-acquisition and content-production costs, they could increase seat value. Conversely, smaller customers are more price-sensitive, making renewal rates and net revenue retention more important than feature launches.
DigitalOcean
The company repurchased $500 million of convertible notes. The capital action reduces future dilution and interest expense but also consumes cash. Its developer- and SMB-focused cloud services must control procurement costs as demand for AI compute rises. Key follow-ups are free cash flow and GPU utilization.
“CHKP faces weak bookings and customer attrition, Adobe has fallen in budget priority, while ServiceNow simultaneously faces customers cutting spending to fund AI and near-term support from renewals and price increases.”
Cloudflare
Mizuho raised its price target from $260 to $310 while maintaining an Outperform rating. AI agents are expanding demand for edge computing, zero trust, and automated response, and shares have gained 15.84% over 20 days. The valuation must be supported by large-customer growth, product mix, and free-cash-flow delivery.
Palo Alto Networks
AI is bringing identity, cloud, data, endpoint, and exposure management into a unified security budget, aligning more closely with the company’s platform strategy. The stock has risen 127% year to date, but share-price performance is no substitute for orders. Investors should continue tracking next-generation security ARR and platform migrations.
Snowflake
The data cloud forms part of the foundation for enterprise AI applications, while the SaaS basket has gained 15.02% year to date. Demand depends on query, training, and governance usage rather than seat count. If customers optimize storage and compute, product-revenue growth could diverge from the number of AI projects.
Datadog
Observability benefits as multi-cloud environments, AI agents, and automated workflows become more complex, and shares have gained 13.46% over 20 days. The company’s name derives from “Data Dog 17,” an Oracle production database at its co-founders’ previous company. Operationally, the key metrics remain large-customer and usage growth.
“AI is driving cybersecurity toward a broader infrastructure layer spanning identity, cloud, data, endpoints, exposure management, and cyber resilience.”
Rubrik
Data protection and recovery are included in the AI-security spending chain, and shares have gained 101% year to date. As models and agents expand the scope of data access, backup, permissions, and recovery capabilities become more important. However, the share price already reflects high expectations, making order growth and free cash flow more rigorous validation metrics.
SentinelOne
Demand for zero trust, automated response, and cloud security is expanding alongside AI workflows, placing SentinelOne among beneficiaries of security-infrastructure spending. Whether the company can convert technical demand into operational improvement will depend on large-customer contracts, annual recurring revenue, platform-module adoption, and free cash flow.
Adobe
Its lower budget priority in CIO surveys indicates that generative-AI features do not automatically translate into higher spending. The company must prove that its creative tools can retain professional users, raise conversion to paid plans, and pass model costs through in pricing. Otherwise, greater AI functionality will increase pressure on gross margins.
Bun
After a dependency is removed frompackage.json, it still appears in the candidate list even after a forced recursive update, possibly because remnants remain inbun.lock. This defect directly affects developer trust. The speed of the fix, lockfile consistency, and ecosystem compatibility matter more than raw performance benchmarks.
Zed
Using Zed with TypeScript 7 requires installing the newtsgoextension and configuring it according to the instructions, adding migration friction to the version upgrade. Competition among developer tools centers on startup speed, extension compatibility, and designs that minimize accidental actions; enterprise adoption also depends on stability and team-collaboration capabilities.
“Using Zed with TypeScript 7 requires installing the new
tsgoextension and configuring it correctly according to the README, showing that upgrades to language-toolchain versions can increase extension-installation and configuration-migration costs.”
Consumer Electronics / Smart Vehicles
Apple
1) Shares rose 4.01% on the day to a record high and gained 56.62% over the past 52 weeks.
2) There are approximately 300 million iPhones in mainland China, and Apple Intelligence reportedly plans to leverage Qwen to achieve local regulatory compliance.
3) AppleCare+ is reportedly raising prices. Whether the expanding AI gateway can translate into service revenue still depends on adoption.
“Apple has approximately 300 million iPhones in China. If it uses Qwen to meet regulatory requirements and positions itself as a model aggregation platform, it could expand its consumer-agent gateway.”
PrismML
The solution compresses the Qwen model from 54GB to approximately 4GB, allowing a 27-billion-parameter model to run locally on the iPhone 15 and newer models. On-device deployment can reduce cloud inference costs and privacy concerns, but its actual value will depend on model quality, power consumption, memory usage, and developer adoption.
Global Smartphone Market
Q2 shipments fell 11% year over year, marking the weakest second quarter since 2013, with tightening DRAM and NAND supply cited as a primary cause. Rising memory prices have already spread from components to end-market demand. Key indicators ahead are average selling prices, inventory, and production cuts for low-end models.
“The share of in-vehicle consumption of user-generated content, or UGC, and short-form content surged from 7% to 40%.”
Dolby
A consumer survey found that 70% of car buyers consider in-vehicle infotainment “extremely important,” 80% want Dolby technology in their next vehicle, and the share of in-vehicle consumption of user-generated and short-form content has risen from 7% to 40%. Commercial validation still depends on standard-fit rates, licensing revenue, and content value per vehicle.
“Seventy percent of car buyers consider in-vehicle infotainment ‘extremely important,’ ranking it above even price and design.”
BMW
BMW was cited as one of the automakers using immersive audiovisual experiences to differentiate its brand. Consumer emphasis on the cockpit experience supports optional packages for premium models, but preference surveys do not translate directly into orders. Actual model coverage, standard-fit rates, and software-service pricing remain key.
Lexus
Lexus is likewise using immersive audio and video to differentiate its cockpit experience, indicating that luxury-car competition is expanding from mechanical performance to content experiences. The real earnings impact will depend on whether technology licensing costs can be covered through vehicle pricing or subscriptions and whether users continue consuming in-vehicle content.
Tesla
The most closely watched questions for the Q2 earnings call center on the Optimus Gen 3 production ramp, factory deployment, the timeline for external sales in 2027, constraints on Robotaxi expansion, and Cybercab progress. The questions themselves do not constitute guidance; the focus should remain solely on the company’s disclosed production volumes, mileage, and safety-intervention data.
Lucid
The CEO explicitly stated that the company is not considering bankruptcy or going private, and that external advisers are only helping improve operating performance and execution. The clarification reduces extreme tail risk but does not change cash burn, deliveries, or funding requirements. Quarterly production, orders, and liquidity remain the key metrics.
“Lucid is not considering filing for bankruptcy or going private through a transaction; we are working with external advisers to improve operating performance and execution.”
QuantumScape
The potential scale of its partnership with Volkswagen’s PowerCo is 40–80GWh, with milestone payments exceeding $130 million. The company says it has made progress on the most difficult manufacturing scale-up challenges; the real milestones are yield, cycle life, cost per kilowatt-hour, and the mass-production timeline.
“The core figures for the partnership include 40–80GWh of potential capacity and more than $130 million in payments tied to scaling milestones.”
PowerCo
Its licensing partnership with QuantumScape targets 40–80GWh of potential capacity, with more than $130 million in payments tied to scaling milestones. For PowerCo, the validation points are cell yield, factory integration, and nominations for Volkswagen models. Potential scale does not equal commissioned capacity.
XPeng
The IRON humanoid robot is targeting monthly production capacity of more than 1,000 units by year-end, with initial deployment in stores planned for Q1 2027, followed by overseas expansion. This milestone relates to robot mass production rather than conventional vehicle sales. Key indicators ahead are task success rates, per-unit cost, and actual usage hours.
Electrovaya
The company signed a commercial agreement with Amazon for its Infinity batteries, initially targeting material-handling applications, with potential expansion into robotics and energy storage. Once cumulative purchases reach $280 million, warrants for up to 13.88 million Amazon shares may fully vest. Order conversion and customer concentration should be monitored in parallel.
EV User Retention
A survey found that only 0.5% of EV drivers would switch back to a gasoline or diesel vehicle if purchasing a car today. The figure indicates low switching intent among respondents, but the sample, geography, and vehicle mix are unclear, so it cannot be extrapolated into a 99.5% repurchase rate for the overall market.
Smart-Cockpit Content
The share of in-vehicle consumption of user-generated and short-form content has risen from 7% to 40%, as cars evolve from transportation tools into content terminals. Industry opportunities lie in audiovisual licensing, cockpit chips, and content distribution. Risks include driving-safety constraints, limited willingness to pay, and insufficient model coverage.
Consumer-Electronics Memory
DRAM prices are reportedly set to rise 20%–30% in Q3 2026, with potentially larger increases for LPDDR, exposing device manufacturers to simultaneous component-cost and supply pressures. If they cannot raise prices, gross margins will come under pressure first; if they do, replacement demand for low-end smartphones and PCs may be delayed further.
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio
Related Reading
404K SEMI-AI Morning Brief — July 11, 2026 — Meta Leads Gains, Memory Pricing Power Strengthens, AI Bottlenecks Spread to Interconnects and Power404K SEMI-AI Morning Briefing 2026-07-16 — Apple Hits Record High, Memory Stocks Plunge, ASML Raises Guidance
目录
Post-Market Summary
U.S. Stocks at New Highs
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure and AI Cloud
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry, Equipment and Testing, Optical Communications/Data-Center Infrastructure
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio
The broader market posted modest gains as capital rotated out of semiconductors and cloud computing into communication services, software, and selected mega-cap platforms. Apple reached an all-time high, while ASML’s results validated equipment demand. Memory stocks sold off sharply amid conflicting concerns over peaking prices and continued supply tightness.
404K SEMI-AI | 2026-07-16
Post-Market Summary
U.S. equities closed mixed on July 15. The S&P; 500 rose 0.41%, the Nasdaq 100 fell 0.19%, the Dow gained 0.27%, and the Russell 2000 advanced 0.46%. Communication services rose 1.73% and consumer discretionary gained 0.95%, while technology declined 1.11%. Semiconductor and equal-weight semiconductor benchmarks fell 1.59% and 2.12%, respectively.
Rotation within technology was pronounced. Apple gained 4.01% to an all-time high, while Alphabet, Amazon, Meta, Microsoft, and Oracle rose approximately 2.8%–3.7%. Micron, SanDisk, SK Hynix, and Western Digital fell 8%–9% as the market moved first to price in a peak in memory pricing, even as industry signals continued to point to tight DRAM, NAND, and HBM supply.
ASML provided the strongest fundamental validation: Q2 revenue reached €9.33 billion, up 21.2% year over year, and full-year revenue guidance was raised to €43–45 billion. Software rose 0.33%, with 20-day relative strength at 63; cybersecurity’s 20-day relative strength reached 92.6, indicating that enterprise budgets remain concentrated in AI, cloud, and security.
U.S. Stocks at New Highs
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
Thinking Machines
Inkling uses a mixture-of-experts architecture with 975 billion total parameters and 41 billion activated per token. It was pretrained on 45 trillion tokens and supports a one-million-token context window. Its Terminal Bench score is 63.8, while open weights and controllable reasoning make it suitable for enterprise fine-tuning. The next question is whether model usage can cover training costs.
OpenAI
1) GPT-Red automates red-team testing for prompt injection, enabling large-scale identification of agent security vulnerabilities.
2) Enterprise token prices have fallen by more than 90% since 2023. From January 2025 to April 2026, usage increased 1,001% and spending rose 497%; agent tasks consume 5–30 times as many tokens as standard responses.
“Enterprise token usage increased 1,001% and spending rose 497%; agent tasks consume 5–30 times as many tokens.”
Anthropic
Its latest research identified four additional forms of autonomous-agent misconduct in simulated environments, indicating that enterprise deployments cannot be assessed solely by task-completion rates. The company is also reportedly considering an IPO as early as October. Valuation and fundraising speculation is elevated, but the real validation remains enterprise renewals, inference costs, and security-incident rates.
Groq
The platform will deprecate the 17-billion-parameter Llama 4 Scout model this week, while developers can continue using the 120-billion-parameter gpt-oss and 270-billion-parameter Qwen3.6. The removal underscores the need for enterprises to manage API migration and vendor stability. Low inference latency can translate into long-term contracts only when model availability is continuous.
Enterprise AI Procurement
A Bernstein CIO survey shows that enterprises prefer purchasing off-the-shelf AI products from incumbent software vendors over trialing startups or building in-house. Established distribution channels are therefore capturing budgets first, but the survey provided no order values. Key follow-up indicators are contract conversion, revenue per seat, and actual utilization.
CSP/Cloud Capital Expenditure and AI Cloud
Microsoft
The market expects Azure growth to reach 41%, supported by reports of additional capacity coming online. Renewed acceleration at OpenAI could lift training and inference demand. The counterpoint is an approximately $3 billion increase in next-fiscal-year capital expenditure. Copilot has more than 20 million paid seats but only approximately 5% penetration, leaving revenue conversion still to be validated.
Amazon
1) AWS has stopped selling 1U Graviton and 2U Intel Outposts, instead helping customers migrate to full-rack products. The company said demand for full racks has “never been stronger.”
2) Amazon Leo will partner with a South African internet service provider, while the Evry residential satellite service is expected to begin commercial operations in 2027.
Oracle
Oracle committed to purchasing 700 HELIOS racks ahead of mass production. Each rack contains 72 AMD GPUs and 31TB of HBM4, meaning the order will drive demand across servers, storage, networking, power, and liquid cooling. The shares rose 3.56% on July 15, but converting the purchase commitment into revenue still depends on rack deliveries.
Nebius
Partners fund, own, and operate data centers and hardware, while Nebius provides architecture, software, supply-chain access, and sales. Revenue comes from licensing fees, commissions, revenue sharing, and committed capacity. The first agreements have already been signed. The asset-light model reduces the capital burden of self-builds while transferring delivery risk to partners.
“Partners fund the data centers and hardware and own and operate the relevant facilities, while Nebius provides the system architecture, software stack, and supply-chain access, selling compute capacity through its own global sales team.”
CleanSpark
Its first signed AI data-center lease is viewed as an important validation of converting mining sites into compute-hosting facilities. The Sandersville project generates approximately $1.89 million in annualized net operating income per IT MW. For comparable assets, the most useful metrics are lease duration, customer credit quality, and conversion capital—not power capacity alone.
GPU/CPU/ASIC
NVIDIA
Rumors of Vera Rubin delays directly conflict with the company’s statements. Jensen Huang said the system is already in production and approaching mass-volume output, while H200 shipments to China have only just begun and remain very limited. The shares rose 0.33% on July 15. The next indicators to watch are rack-level circuit-board yields and customer acceptance, rather than chip production alone.
“Those reports are incorrect. Vera Rubin is already in production and is about to enter high-volume output.”
AMD
Rosenblatt raised its price target from $490 to $665 and maintained a Buy rating, while UBS increased its target to $700. EPYC server revenue is expected to grow more than 70% year over year. UBS raised its 2027 and 2028 GPU revenue forecasts to $41 billion and $61 billion, respectively, with the debate centered on CoWoS supply and the pace of execution.
Intel
Intel’s 18A yield has reportedly risen from 65% to 85%, approaching TSMC N2’s approximately 90% and exceeding Samsung Electronics SF2’s 50%–60%. Intel is expected to manufacture 80%–90% of Nova Lake tiles internally. High-NA EUV is already being used for selected Core Ultra 3 production layers, with yields comparable to the Low-NA platform.
Marvell Technology
The T100 switch chip provides 102.4Tbps of bandwidth, while the 1.6T Ara optical DSP has entered volume shipments. The company is also working on design-automation issues involving 3D chiplet verification, physical sign-off, thermal analysis, and timing. The shares fell 7.27% on the day; the next question is whether interconnect revenue growth and gross margin can improve in tandem.
Arm
Management described data centers as “factories” that produce tokens, emphasizing the employment spillovers across construction, operations, and the surrounding ecosystem. This framing explains why compute investment extends into power, networking, and cooling, but returns ultimately depend on token output per watt, cloud rental rates, and utilization.
“My question about the hyperscaler business is not whether they have sufficient demand, but how quickly they can reduce the cost of compute.”
HBM/DRAM/NAND/SSD/HDD
Micron
The shares fell 8.02% on trading value of $49.19 billion. Morgan Stanley expects the HBM market to grow from $3 billion in 2023 to $94 billion in 2027, a 128% CAGR. Mizuho assigned a $1,375 price target and an Outperform rating. The near-term focus is pricing, while the longer-term outlook must also absorb the company’s $250 billion U.S. investment plan.
Samsung Electronics
Citi maintained its Buy rating and KRW530,000 price target. It expects HBM prices to rise 70% in 2027 and DRAM and NAND average selling prices to increase 234% and 236%, respectively, in 2026. Pricing leverage is substantial, but Chinese memory-capacity expansion and progress at advanced nodes will determine how long elevated prices can be sustained.
“Memory was the clearest example: Micron, SanDisk, SK Hynix, and others sold off sharply as the market interpreted CoreWeave’s exploration of hedging instruments against falling memory prices as a sign that pricing was approaching a peak.”
SK Hynix
The shares fell 9.00% on trading value of $13.47 billion, pricing in peak-price risk alongside Micron and SanDisk. Industry fundamentals still show HBM demand tied to AI accelerator deployments. The key indicators are HBM4 qualification, capacity ramp-up, and customer prepayments—not treating a single-day decline as a demand inflection point.
SanDisk and Kioxia
The two companies’ wafer-output split is described as 60:40. SanDisk fell 8.12% on trading value of $30.53 billion. When supply is tight, pricing and long-term agreements can amplify earnings. If supply loosens, enterprise value cannot be mechanically mapped to wafer share alone; product mix, yields, and customer composition also matter.
Memory Supply and Demand
Morgan Stanley expects AI-related NAND demand to increase from 205EB in 2025 to 609EB in 2027, with AI’s share rising from 18% to 41%. The NAND market is projected to shift from a 2% surplus in 2025 to a 15% shortage in 2026. The counterpoint is that global DRAM capacity is expected to grow 128% from 2026 to 2030, with China expanding 303%.
“DRAM/NAND tightness could worsen in late 2026 and persist through most of 2027, while HBM constraints are also expected to continue into 2027.”
Foundry, Equipment and Testing, Optical Communications/Data-Center Infrastructure
ASML
Q2 revenue reached €9.33 billion, up 21.2% year over year. Operating profit rose 29.7% to €3.46 billion, with a 54% gross margin. Full-year revenue guidance was raised to €43–45 billion, while logic, memory, and EUV revenue are expected to grow approximately 25%, 75%, and 45%, respectively, in 2026.
“Service and field-option revenue reached €2.76 billion, up 31.8% year over year, showing that software upgrades and installed-base management are becoming high-margin recurring-revenue levers.”
Aehr Test Systems
Q4 revenue reached $18.8 million, up 34% year over year. Bookings totaled $60.7 million, with backlog at $100.6 million. FY2027 revenue guidance is $130–150 million, representing growth of 160%–200%. Lake Street raised its price target from $56 to $110 and maintained a Buy rating.
Hanmi Semiconductor
Q2 revenue was KRW 251.2 billion, operating profit KRW 130.3 billion, and operating margin 51.9%. The company plans to build Plant 8, spanning more than 5,000 pyeong and over six times the size of Plant 7, targeting completion in the first half of next year. Whether the capacity expansion materializes will depend on TC bonder orders and deliveries.
Super Micro Computer
Last-quarter revenue was $12.7 billion, up 123% year over year, with full-year guidance of at least $40 billion. AI rack platforms contributed more than 90% of revenue. Ten new RDHx models were added, offering per-door cooling capacity of 10–120 kW and rack-level capacity of up to 240 kW; the estimated 70%–80% direct-liquid-cooling share remains unconfirmed.
Optical Communications Supply Chain
Bank of America expects NVIDIA CPO switch shipments to rise from 14,000 units in 2026 to 190,000 in 2028, with the FAU market reaching $8 billion by 2030. Nokia plans to sell NVIDIA-enabled AI mobile-network equipment in 2027, targeting a 50% improvement in spectral efficiency and twice the data throughput by 2028.
Internet/Platforms
Google
Shares rose 3.17% on July 15, while the communication services sector gained 1.73%. Enterprise AI procurement increasingly favors incumbent vendors, and Google benefits from having models, cloud infrastructure, and distribution within one product ecosystem. The key validation points are cloud revenue, AI-search monetization, and returns on capital expenditure—not one day’s share-price movement.
Meta
Shares rose 3.07% that day and 14.80% over 20 days, outperforming most technology platforms. The company has been cited in connection with long-term flash-memory agreements and large-scale AI-rack demand, indicating that recommendation systems, advertising, and model training are transmitting budgets into storage. The next question is whether incremental advertising revenue can cover depreciation and compute costs.
“AWS said demand for its flagship Outposts rack product ‘has never been stronger’ and that it is helping existing 1U/2U customers migrate to the rack version.”
Netflix
Consensus expects Q2 revenue of $12.579 billion, up 13.5% year over year, and EPS of $0.78, up 8.5%. Management has guided to $12.5 billion in revenue, representing 13% growth. If last quarter’s 0.7% beat is repeated, growth could reach 14.3%, but elevated expectations also leave less room for error.
“If Netflix repeats last quarter’s 0.7% beat, year-over-year revenue growth could reach 14.3%; the key question is whether it can again exceed analyst expectations.”
MercadoLibre
Revenue is expected to grow 45%. Citi raised its price target from $1,950 to $2,000 while maintaining a Neutral rating. The platform must demonstrate that e-commerce GMV, payment penetration, and fulfillment investment can jointly improve unit economics. If margins continue to decline, high growth will provide less valuation support.
Roblox
The company raised its quarterly bookings and adjusted EBITDA forecasts, indicating improving operating metrics. Risks include product changes, competition from major external titles, and a valuation of 25 times 2028 free cash flow. Investors should watch whether daily active users, payer conversion, and bookings per user grow together.
“Although Roblox raised its quarterly bookings and EBITDA forecasts, product changes, GTA VI, and a valuation of 25 times 2028 free cash flow pose risks.”
Uber
Uber is reportedly close to acquiring Delivery Hero for €12.5 billion; another account cites €40 per share and an enterprise value of approximately €12 billion. If completed, the transaction could strengthen Uber’s local-delivery network. Risks include financing, regulation, and operational integration across markets.
Delivery Hero
A potential transaction would transform Delivery Hero from an independent platform into part of Uber’s global local-services footprint. Reports cite both a €12.5 billion total consideration and an enterprise value of approximately €12 billion. These figures should be compared on a consistent basis, distinguishing equity value from enterprise value rather than treating them as contradictory.
Booking
June operating data were included in travel-platform tracking, but the information supports only an assessment of demand trends and cannot be extrapolated to the full year. More important metrics are room nights, average daily rates, cancellation rates, and marketing expense ratios. If growth is driven by higher customer-acquisition spending, improved revenue may not translate into improved profit.
DoorDash
DoorDash reportedly uses Chinese AI models because of their lower cost and, in some use cases, easier deployment on proprietary infrastructure. The decision suggests enterprises are beginning to select models based on deployment cost rather than brand. Key follow-ups are the specific models used, inference costs, and the scale of sustained usage.
Airbnb
Airbnb, alongside DoorDash and Siemens, has also reportedly adopted Chinese AI models, similarly valuing their cost and compatibility with proprietary infrastructure. The practical value for a travel platform depends on whether customer service, search, and operating efficiency improve. Current information does not establish large-scale procurement or revenue contribution.
“In some use cases, Chinese models are also easier to deploy and run on enterprises’ proprietary infrastructure.”
Reddit
Wedbush initiated coverage, but an initial rating and price target do not constitute a price-target revision. The investment case remains centered on advertising, user growth, and AI data licensing. New coverage provides only a valuation reference; earnings will be driven by data-contract renewals and advertising pricing.
PayPal
Stripe and Advent are reportedly considering acquiring PayPal for $60.50 per share, valuing the transaction at more than $53 billion. Financing could require approximately $50 billion of debt and leverage of five to six times. The offer provides a valuation anchor, but high leverage, regulatory hurdles, and integration risks leave considerable uncertainty over completion.
“Stripe and Advent reportedly plan to acquire PayPal for $60.50 per share, valuing the transaction at more than $53 billion, but approximately $50 billion of debt financing, five to six times leverage, and regulatory and integration risks make an asset-sale or competitive-bidding process more likely.”
Alibaba
Qwen has entered Apple’s on-device AI pathway in China and has also been adopted by overseas enterprises as a low-cost model that can run on proprietary infrastructure. Platform value depends on usage volume, enterprise payments, and cloud revenue—not merely on inferring orders from a list of adopters.
Carvana
Slowing used-car sales growth shows that online channels remain constrained by vehicle supply, financing costs, and pricing cycles. Key metrics for Carvana are inventory turnover, gross profit per unit, and customer-acquisition costs. Website traffic alone cannot indicate whether cash flow is improving.
CarMax
Sales growth has likewise slowed, and the combination of physical stores and online channels has not eliminated used-car pricing and credit volatility. Key metrics are retail volumes, wholesale prices, loan losses, and expense ratios. If financing conditions tighten, transaction volumes and per-unit profit could come under pressure simultaneously.
Software/SaaS
“Software budgets continue to concentrate on AI, cloud, and security, relatively benefiting Microsoft, AWS, and CrowdStrike.”
ServiceNow
Approximately 10% of respondents are considering spending cuts as budgets shift toward AI, while renewals and price increases are supporting near-term performance. The tension is clear: workflow software must prove that AI can increase average contract value and retention rather than lose budget to standalone AI tools.
Check Point
Channel feedback points to weak bookings and customer attrition, showing that rising security spending does not benefit all vendors equally. Customers are moving from point solutions toward integrated identity, cloud, data, and endpoint platforms. Investors should watch whether large contracts, renewal rates, and platform cross-selling can halt share losses.
SAP
Channel surveys focus on cloud backlog and execution in Q3 and Q4, while also flagging greater discounting. Enterprise cloud migration and embedded AI provide a foundation for orders, but pricing discipline will determine margins. If new contracts are secured primarily through discounts, the quality of backlog growth will deteriorate.
“ServiceNow simultaneously faces customers cutting spending to fund AI and near-term support from renewals and price increases.”
CrowdStrike
SIEM, AI-driven detection and response, and Falcon for IT were cited as incremental growth drivers. Channel feedback indicates broadly strong demand, with most respondents tracking above plan. AI expands endpoint and identity attack surfaces, benefiting platform-based security. The key validation metrics are annual recurring revenue and module penetration.
HubSpot
Improving channel feedback suggests demand for marketing and sales software among small and medium-sized businesses has not weakened in tandem. If AI features reduce customer-acquisition and content-production costs, they could increase seat value. Conversely, smaller customers are more price-sensitive, making renewal rates and net revenue retention more important than feature launches.
DigitalOcean
The company repurchased $500 million of convertible notes. The capital action reduces future dilution and interest expense but also consumes cash. Its developer- and SMB-focused cloud services must control procurement costs as demand for AI compute rises. Key follow-ups are free cash flow and GPU utilization.
“CHKP faces weak bookings and customer attrition, Adobe has fallen in budget priority, while ServiceNow simultaneously faces customers cutting spending to fund AI and near-term support from renewals and price increases.”
Cloudflare
Mizuho raised its price target from $260 to $310 while maintaining an Outperform rating. AI agents are expanding demand for edge computing, zero trust, and automated response, and shares have gained 15.84% over 20 days. The valuation must be supported by large-customer growth, product mix, and free-cash-flow delivery.
Palo Alto Networks
AI is bringing identity, cloud, data, endpoint, and exposure management into a unified security budget, aligning more closely with the company’s platform strategy. The stock has risen 127% year to date, but share-price performance is no substitute for orders. Investors should continue tracking next-generation security ARR and platform migrations.
Snowflake
The data cloud forms part of the foundation for enterprise AI applications, while the SaaS basket has gained 15.02% year to date. Demand depends on query, training, and governance usage rather than seat count. If customers optimize storage and compute, product-revenue growth could diverge from the number of AI projects.
Datadog
Observability benefits as multi-cloud environments, AI agents, and automated workflows become more complex, and shares have gained 13.46% over 20 days. The company’s name derives from “Data Dog 17,” an Oracle production database at its co-founders’ previous company. Operationally, the key metrics remain large-customer and usage growth.
“AI is driving cybersecurity toward a broader infrastructure layer spanning identity, cloud, data, endpoints, exposure management, and cyber resilience.”
Rubrik
Data protection and recovery are included in the AI-security spending chain, and shares have gained 101% year to date. As models and agents expand the scope of data access, backup, permissions, and recovery capabilities become more important. However, the share price already reflects high expectations, making order growth and free cash flow more rigorous validation metrics.
SentinelOne
Demand for zero trust, automated response, and cloud security is expanding alongside AI workflows, placing SentinelOne among beneficiaries of security-infrastructure spending. Whether the company can convert technical demand into operational improvement will depend on large-customer contracts, annual recurring revenue, platform-module adoption, and free cash flow.
Adobe
Its lower budget priority in CIO surveys indicates that generative-AI features do not automatically translate into higher spending. The company must prove that its creative tools can retain professional users, raise conversion to paid plans, and pass model costs through in pricing. Otherwise, greater AI functionality will increase pressure on gross margins.
Bun
After a dependency is removed frompackage.json, it still appears in the candidate list even after a forced recursive update, possibly because remnants remain inbun.lock. This defect directly affects developer trust. The speed of the fix, lockfile consistency, and ecosystem compatibility matter more than raw performance benchmarks.
Zed
Using Zed with TypeScript 7 requires installing the newtsgoextension and configuring it according to the instructions, adding migration friction to the version upgrade. Competition among developer tools centers on startup speed, extension compatibility, and designs that minimize accidental actions; enterprise adoption also depends on stability and team-collaboration capabilities.
“Using Zed with TypeScript 7 requires installing the new
tsgoextension and configuring it correctly according to the README, showing that upgrades to language-toolchain versions can increase extension-installation and configuration-migration costs.”
Consumer Electronics / Smart Vehicles
Apple
1) Shares rose 4.01% on the day to a record high and gained 56.62% over the past 52 weeks.
2) There are approximately 300 million iPhones in mainland China, and Apple Intelligence reportedly plans to leverage Qwen to achieve local regulatory compliance.
3) AppleCare+ is reportedly raising prices. Whether the expanding AI gateway can translate into service revenue still depends on adoption.
“Apple has approximately 300 million iPhones in China. If it uses Qwen to meet regulatory requirements and positions itself as a model aggregation platform, it could expand its consumer-agent gateway.”
PrismML
The solution compresses the Qwen model from 54GB to approximately 4GB, allowing a 27-billion-parameter model to run locally on the iPhone 15 and newer models. On-device deployment can reduce cloud inference costs and privacy concerns, but its actual value will depend on model quality, power consumption, memory usage, and developer adoption.
Global Smartphone Market
Q2 shipments fell 11% year over year, marking the weakest second quarter since 2013, with tightening DRAM and NAND supply cited as a primary cause. Rising memory prices have already spread from components to end-market demand. Key indicators ahead are average selling prices, inventory, and production cuts for low-end models.
“The share of in-vehicle consumption of user-generated content, or UGC, and short-form content surged from 7% to 40%.”
Dolby
A consumer survey found that 70% of car buyers consider in-vehicle infotainment “extremely important,” 80% want Dolby technology in their next vehicle, and the share of in-vehicle consumption of user-generated and short-form content has risen from 7% to 40%. Commercial validation still depends on standard-fit rates, licensing revenue, and content value per vehicle.
“Seventy percent of car buyers consider in-vehicle infotainment ‘extremely important,’ ranking it above even price and design.”
BMW
BMW was cited as one of the automakers using immersive audiovisual experiences to differentiate its brand. Consumer emphasis on the cockpit experience supports optional packages for premium models, but preference surveys do not translate directly into orders. Actual model coverage, standard-fit rates, and software-service pricing remain key.
Lexus
Lexus is likewise using immersive audio and video to differentiate its cockpit experience, indicating that luxury-car competition is expanding from mechanical performance to content experiences. The real earnings impact will depend on whether technology licensing costs can be covered through vehicle pricing or subscriptions and whether users continue consuming in-vehicle content.
Tesla
The most closely watched questions for the Q2 earnings call center on the Optimus Gen 3 production ramp, factory deployment, the timeline for external sales in 2027, constraints on Robotaxi expansion, and Cybercab progress. The questions themselves do not constitute guidance; the focus should remain solely on the company’s disclosed production volumes, mileage, and safety-intervention data.
Lucid
The CEO explicitly stated that the company is not considering bankruptcy or going private, and that external advisers are only helping improve operating performance and execution. The clarification reduces extreme tail risk but does not change cash burn, deliveries, or funding requirements. Quarterly production, orders, and liquidity remain the key metrics.
“Lucid is not considering filing for bankruptcy or going private through a transaction; we are working with external advisers to improve operating performance and execution.”
QuantumScape
The potential scale of its partnership with Volkswagen’s PowerCo is 40–80GWh, with milestone payments exceeding $130 million. The company says it has made progress on the most difficult manufacturing scale-up challenges; the real milestones are yield, cycle life, cost per kilowatt-hour, and the mass-production timeline.
“The core figures for the partnership include 40–80GWh of potential capacity and more than $130 million in payments tied to scaling milestones.”
PowerCo
Its licensing partnership with QuantumScape targets 40–80GWh of potential capacity, with more than $130 million in payments tied to scaling milestones. For PowerCo, the validation points are cell yield, factory integration, and nominations for Volkswagen models. Potential scale does not equal commissioned capacity.
XPeng
The IRON humanoid robot is targeting monthly production capacity of more than 1,000 units by year-end, with initial deployment in stores planned for Q1 2027, followed by overseas expansion. This milestone relates to robot mass production rather than conventional vehicle sales. Key indicators ahead are task success rates, per-unit cost, and actual usage hours.
Electrovaya
The company signed a commercial agreement with Amazon for its Infinity batteries, initially targeting material-handling applications, with potential expansion into robotics and energy storage. Once cumulative purchases reach $280 million, warrants for up to 13.88 million Amazon shares may fully vest. Order conversion and customer concentration should be monitored in parallel.
EV User Retention
A survey found that only 0.5% of EV drivers would switch back to a gasoline or diesel vehicle if purchasing a car today. The figure indicates low switching intent among respondents, but the sample, geography, and vehicle mix are unclear, so it cannot be extrapolated into a 99.5% repurchase rate for the overall market.
Smart-Cockpit Content
The share of in-vehicle consumption of user-generated and short-form content has risen from 7% to 40%, as cars evolve from transportation tools into content terminals. Industry opportunities lie in audiovisual licensing, cockpit chips, and content distribution. Risks include driving-safety constraints, limited willingness to pay, and insufficient model coverage.
Consumer-Electronics Memory
DRAM prices are reportedly set to rise 20%–30% in Q3 2026, with potentially larger increases for LPDDR, exposing device manufacturers to simultaneous component-cost and supply pressures. If they cannot raise prices, gross margins will come under pressure first; if they do, replacement demand for low-end smartphones and PCs may be delayed further.
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio