404K SEMI-AI Morning Brief — July 24, 2026 — Google Steps Up AI Infrastructure Spending, AMD’s Inference Platform Takes Shape, Equipment and Grid Orders Strengthen
目录
Post-Market Summary
Top 10 U.S. Stocks by Trading Value
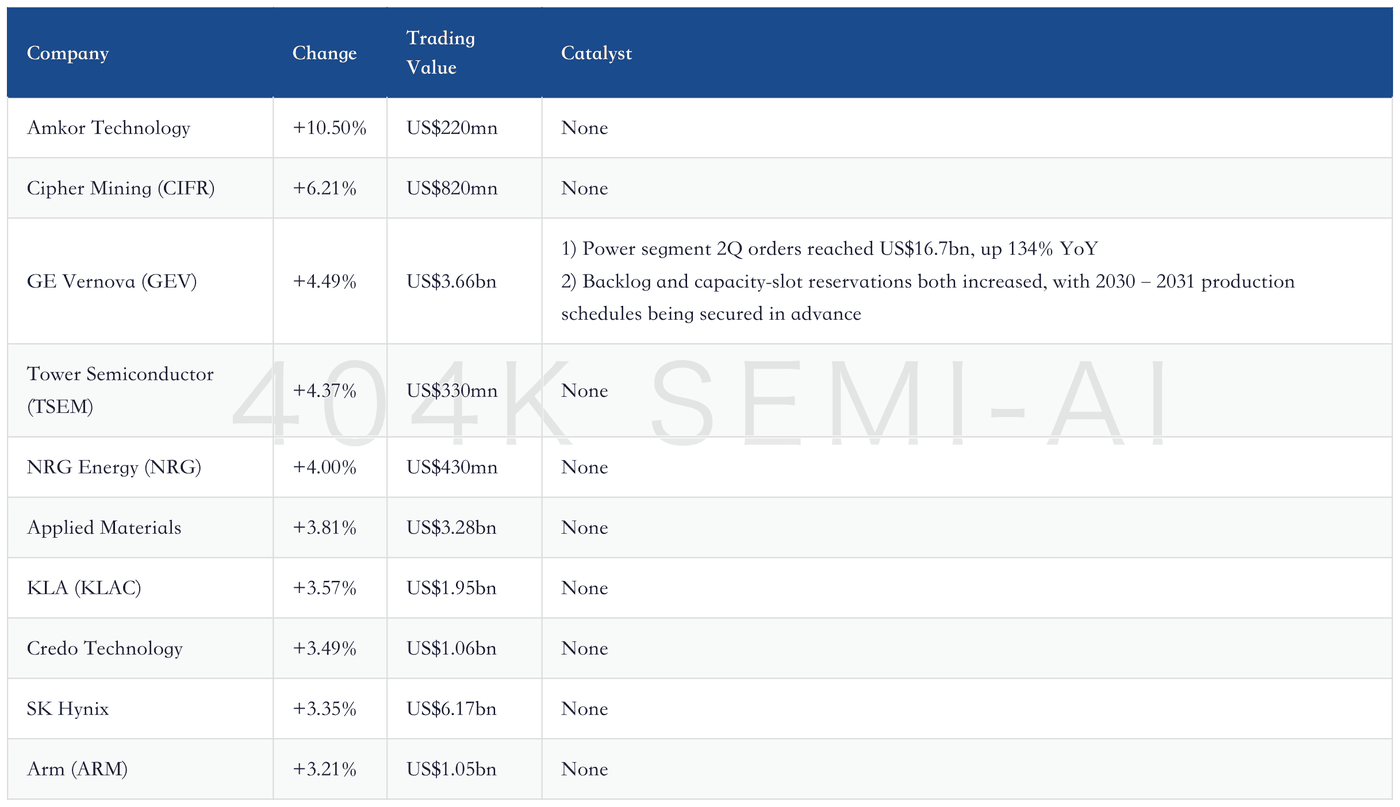
Top U.S. Stock Gainers
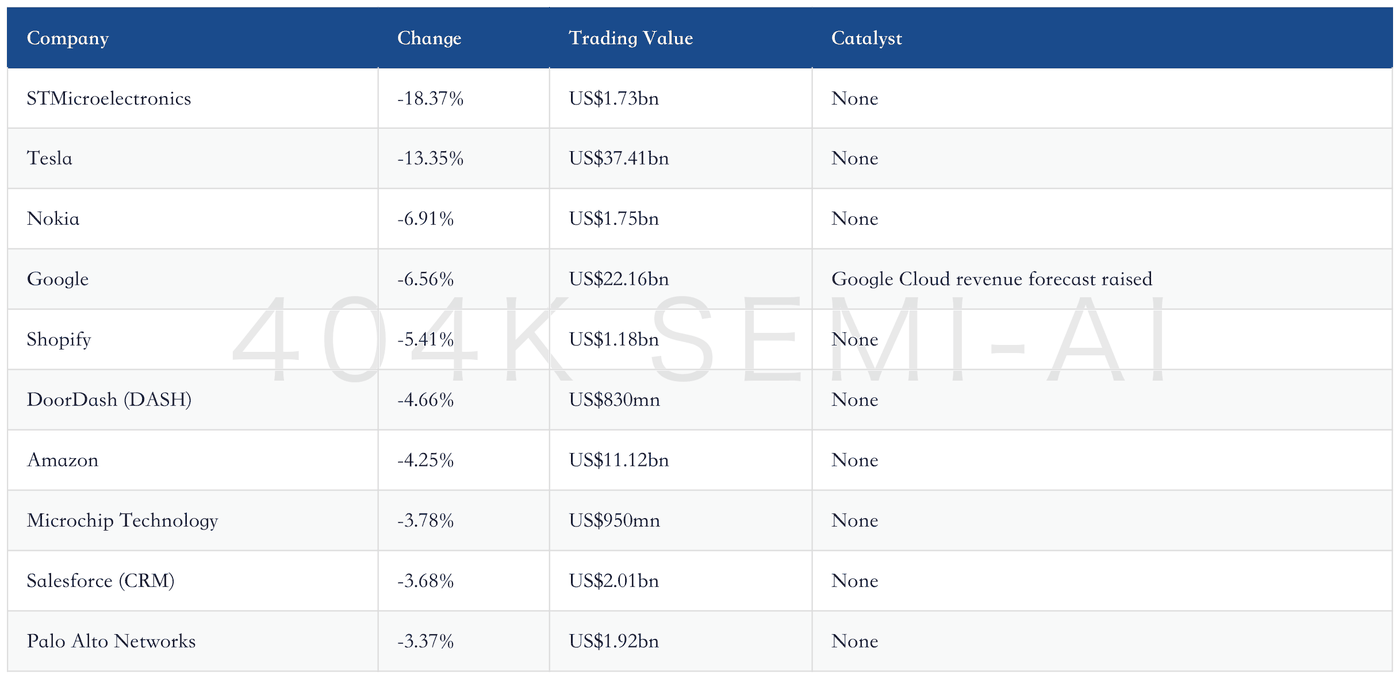
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
CSP/Cloud Capital Expenditure
GPU/CPU/ASIC
Semiconductor Equipment/Advanced Packaging
Optical Communications/High-Speed Interconnects/Grid Power Infrastructure
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Huang’s Selected Portfolio
U.S. equity risk appetite cooled, but capital has not left the AI value chain: cloud platforms are under pressure from capital expenditure and free cash flow, while semiconductor equipment, advanced packaging, and data-center power infrastructure continue to enjoy order support. Google’s earnings brought the tension between strong demand, tight supply, and higher investment to the fore, while AMD, Intel, and Nokia provided fresh validation through products and orders.
404K SEMI-AI | 2026-07-24
Post-Market Summary
U.S. equities broadly declined on July 23, with the S&P; 500, Nasdaq 100, and Dow Jones down 1.13%, 1.55%, and 1.02%, respectively, while the equal-weighted S&P; 500 fell only 0.37%. Large caps came under greater pressure, and the VIX rose 16.29% to 19.35 as the market reassessed AI capital expenditure, free cash flow, and the pace of earnings realization during reporting season.
Sector dispersion was clear: communication services and consumer discretionary fell 3.53% and 4.64%, respectively, while software and cloud computing declined 1.85% and 2.61%. The semiconductor ETF lost only 0.11%, while equal-weighted semiconductors gained 0.27%. Industrials rose 2.05%, with data-center grid infrastructure, equipment, and advanced packaging continuing to benefit from the order cycle.
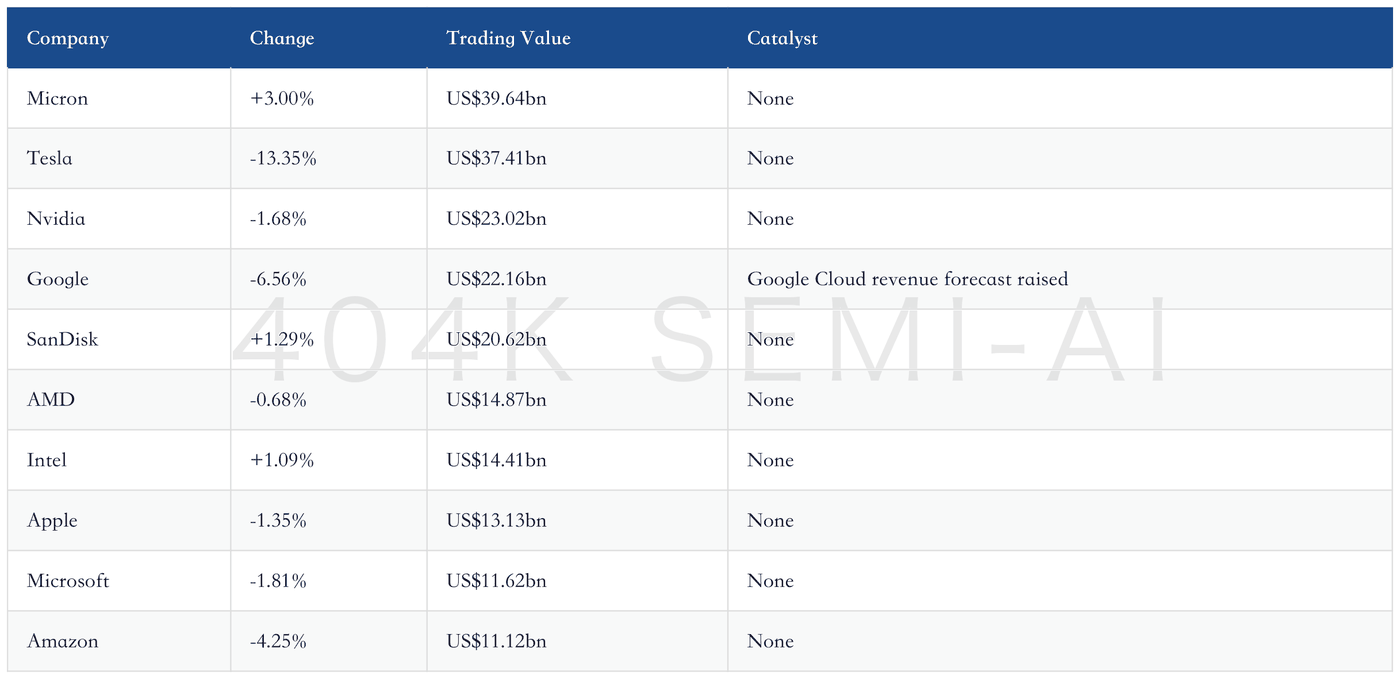
At the company level, Google fell 6.56% and Tesla declined 13.35%, indicating reduced market tolerance for revenue growth accompanied by weaker cash flow. Micron gained 3.00%, while Applied Materials, KLA, and GE Vernova ranked among the strongest performers in the large-cap technology value chain. Capital continues to favor hardware segments with visible orders, capacity, or delivery schedules.
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
Kimi K3: Open weights have not eliminated inference costs. K3 has 2.8 trillion parameters and approximately 1.4TB of weights, requiring infrastructure comparable to a 72-GPU GB200 NVL72 rack. Purchase and installation cost approximately US$3mn–4mn, continuous power consumption is around 120kW, and annual rental cost on the open market is approximately US$7mn. The key question is whether low pricing can sustainably drive token usage and cover infrastructure costs.
“Model weights may be free, but inference is not.”
Open-model economics: The article estimates that every 10% decline in token pricing increases usage by 12%–18%, causing total expenditure to rise at the current stage. Depending on the workload, hosting K3 can generate US$23–60 of revenue per GPU-hour, above the US$7.8–11.5 from directly renting compute capacity. The key variables are actual utilization, throughput, and enterprise switching costs.
Enterprise AI security: Enterprise AI deployment is more than 20 percentage points ahead of dedicated security-tool adoption, making security teams the approval gate for production deployment. Demand initially centers on data visibility, machine identity, and least-privilege access before expanding to runtime blocking. The metrics that genuinely validate incremental revenue are paid add-on purchases, renewal value, and usage—not the number of product launches.
“Security will be one of the earliest and most durable sources of incremental demand created by enterprise AI adoption.”
OpenAI: ChatGPT Health has begun rolling out to U.S. users and can connect to medical records and Apple Health data with authorization. Another infrastructure datapoint indicates that OpenAI has secured early access to AMD Helios racks and is advancing multi-path networking protocols with several chip and cloud vendors. Model products and underlying compute infrastructure are expanding into production environments in parallel.
Anthropic: AMD said Anthropic will use AMD CPUs and GPUs through cloud providers, neoclouds, and potentially self-built data centers. Google’s stake in Anthropic is reportedly worth approximately US$124bn. More importantly for the value chain, customers are beginning to diversify their compute sources. The next points to monitor are actual deployment scale and procurement cadence.
CSP/Cloud Capital Expenditure
Google
1) Second-quarter revenue reached US$119.8bn, up 24% YoY; Google Cloud revenue was US$24.77bn, up 82%, while cloud backlog rose to US$514bn.
2) 2026 capital-expenditure guidance was raised from US$180bn–190bn to US$195bn–205bn, with another significant increase expected in 2027.
3) Citi estimates that TPU sales contributed approximately US$1.2bn of revenue, but third-party compute costs and depreciation will weigh on near-term margins.
“Strong demand is forcing the company to expand capacity further; investors must continue to validate cloud revenue conversion, compute supply, and the margin impact of depreciation and third-party procurement.”
Meta: Inference, training, recommendation systems, and content creation are simultaneously driving compute demand, with some categories growing exponentially. Data-center construction cycles are measured in years: a 1GW project requires discussions approximately two years in advance, while silicon capacity cannot be added at short notice. The capital-expenditure risk is not insufficient demand, but mismatches among supply, delivery, and payback periods.
“Data centers take years to build… You should have come to talk to me two years ago.”
Amazon: The elastic network graph uses a flat topology and passive optical components, reportedly reducing router requirements by 69%, increasing throughput by up to 33%, and lowering network-equipment power consumption by 40%. Improved network efficiency benefits unit compute costs but could reduce optical-transceiver demand by 40%–50%, providing a counter-indicator that the optical communications value chain must monitor.
Oracle: Guggenheim reiterated its Buy rating and maintained a US$400 price target, citing management’s view that AI construction risk has declined materially and data-center delays are not systemic. Whether this assessment holds will depend on project delivery, customer go-lives, and the timely conversion of lease commitments into revenue—not construction plans alone.
CoreWeave and Nebius: Market estimates indicate that CoreWeave could convert approximately US$31bn of backlog over the next 18 months, including US$25bn in 2027. Nebius also has US$31bn of backlog over the same period, with approximately US$11bn expected to convert in 2027. Upside for neoclouds comes from order conversion, while the risks are financing costs and generational GPU depreciation compressing the payback window to two or three years.
GPU/CPU/ASIC
Nvidia: Japan plans to procure 27,500 Rubin GPUs for a national AI factory and physical-AI multimodal models. Nvidia’s advantages remain software compatibility and its installed base, but customers are also beginning to test AMD systems. A separate supply-chain comparison indicates that Nvidia’s HBM4 delivers 10.7Gbps per pin, above AMD’s 7.5Gbps.
Intel
1) Second-quarter revenue reached US$16.13bn, up 25% YoY, with a non-GAAP gross margin of 41.8% and adjusted EPS of US$0.42; the midpoint of third-quarter revenue guidance is US$16.3bn.
2) Xeon 6+ became the first 18A server processor, while 18A-P entered risk production; the company raised 2026 capital expenditure from US$18bn to US$20bn.
3) Improvements in yield, production cycle times, and shipment volumes are critical to sustaining growth.
“AI is driving unprecedented compute demand, and Intel is positioned to grow across CPUs, ASICs, advanced packaging, and its foundry network.”
AMD
1) MI450-powered Helios shipments are scheduled to begin at the end of the third quarter and ramp in the fourth quarter. The platform integrates 320 billion transistors, 432GB of memory, and 12 compute and I/O chiplets.
2) The Venice server CPU offers up to 256 cores and 512 threads, with system shipments beginning in the fourth quarter.
3) AMD raised its 2030 AI accelerator market forecast to US$1.4tn and expects inference to represent approximately 60% of global AI capacity. The long-term forecast still requires validation through application revenue and returns on capital.
Cerebras: Cerebras and AMD are developing a disaggregated inference system in which Helios handles prompts, long contexts, and high-throughput workloads, while the wafer-scale engine handles low-latency token generation. The companies claim the system can deliver up to five times more tokens per second per watt than Cerebras alone. Cloud services are scheduled to launch in the second half of 2026, with systems available for purchase in 2027.
Server CPU supply and demand: Industry sources indicate that AMD’s relevant capacity is sold out through the end of 2026, with lead times exceeding 30 weeks, while Intel’s actual shipments are approximately 20% below demand. Bottlenecks affect both advanced logic wafers and supporting packaging capacity. CPU demand is being driven by agent orchestration and edge inference, but upward revisions to market-size forecasts still require validation through actual server shipments.
Semiconductor Equipment/Advanced Packaging
BESI: Second-quarter revenue reached €250mn, up 69% YoY; orders totaled approximately €293mn, up 9% QoQ and around 18% above consensus. The number of hybrid-bonding customers increased from 15 at the end of 2025 to 21, with applications expanding into logic, memory, co-packaged optics, and consumer electronics. Outsourced semiconductor assembly and test providers accounted for a relatively large share of incremental orders.
“Expanding AI infrastructure investment is accelerating advanced-packaging demand, while the hybrid-bonding customer base and application scope continue to broaden.”
Japanese semiconductor equipment: Average monthly sales of Japanese semiconductor production equipment reached ¥513.6bn from April through June, up 27% YoY and 7.0% QoQ. The industry expects FY3/27 sales of ¥6.55tn, up 26%, followed by another 13% increase in FY3/28. Demand spans HBM, advanced logic, general-purpose DRAM, and NAND, with customers continuing to request earlier delivery.
“Front-end equipment has displaced previously strong back-end testing as the primary growth engine at the start of FY3/27.”
Lasertec, Ebara, Disco, and Tokyo Electron: Goldman Sachs maintained Buy ratings on all four companies, with stock selection based on whether earnings growth can exceed consensus rather than on an indiscriminate equipment-sector rally. Yen weakness explains only part of the forecast revisions; orders, market share, and product mix remain the true drivers of earnings. Export restrictions and competition from Chinese equipment vendors are the principal counterarguments.
Chiplet simulation: Finite-element simulation for 2.5D and 3D chiplets can take several days, with complex tasks distributed across hundreds of machines. Once trained, AI thermal models can return results within seconds while keeping errors below 1.7°C. The bottleneck in chiplet expansion is shifting from whether tools exist to whether multiphysics verification can be completed quickly enough.
EDA agents: Core simulation and verification engines will not disappear in the near term, but will become machine-callable modules orchestrated by agents and signed off by humans. Tape-out allows virtually no margin for error, while specifications continue to change; even 100% coverage and passing tests are insufficient to establish trust. Commercial opportunities are therefore more concentrated in trusted engines, structured data, and cross-tool collaboration.
Optical Communications/High-Speed Interconnects/Grid Power Infrastructure
Nokia: Second-quarter AI and cloud orders reached €2.8bn, nearly double the first quarter’s €1.0bn, while related sales rose 105% YoY. Comparable operating profit was €434mn, above the €382mn consensus estimate. Demand remains strong, but supply constraints are prompting customers to place longer-dated orders. Delivery and revenue recognition are the key items to monitor.
“Demand remains strong, while supply continues to be the industry’s primary constraint, prompting customers to place longer-dated orders.”
GE Vernova: Second-quarter Power segment orders reached US$16.7bn, up 134% YoY, including orders for 113 gas turbines representing 12.1GW. Equipment backlog and slot reservations totaled 116GW. The company raised its end-2026 target from 110GW to at least 125GW and plans to reach 30GW of annual capacity by 2030.
“The company does not expect orders to peak in 2026, and most 2030 production slots and more than half of 2031 slots are expected to be secured during the year.”
Hitachi Energy: GE Vernova’s Electrification segment reported second-quarter sales of US$3.637bn, orders of US$6.347bn, and backlog of US$44.6bn. First-half data-center orders exceeded US$5bn, already above the full-year 2025 level. Goldman Sachs views this as a positive read-through for Hitachi Energy, with validation dependent on the delivery of transformer, switchgear, and high-voltage direct-current orders.
Siemens Energy: Gas Services orders increased 26% over the past four quarters, while Gas & Power-related orders reached €58.4bn and backlog totaled €123bn. Goldman Sachs forecasts FY2030 EBITDA of approximately €16.734bn, above consensus for GE Vernova, yet the company still trades at an approximately 53% discount on 2028 valuation. Discount convergence depends on earnings delivery in gas services and grid operations.
Optical networking protocols: Amazon’s RNG and OpenAI’s MRC both flatten network hierarchies, with MRC splitting an 800Gbps link into eight parallel 100Gbps networks. Fewer routers and lower power consumption improve data-center unit economics but could reduce optical-module demand. Optical communications companies must therefore monitor both total bandwidth growth and declining component density per cluster.
Internet/Platforms
Google
1) Search revenue grew 17% YoY and YouTube advertising grew 13%, indicating that AI has not yet disrupted the core advertising cash flow.
2) Gemini reached 950 million monthly active users, while its model APIs process 22 billion tokens per minute; approximately 500,000 advertisers using AI Max achieved about 15% more conversions at a similar return on ad spend.
3) Free cash flow turned negative at $5.9 billion, as platform growth and capital intensity increased simultaneously.
“Our advertiser support team uses Gemini agents, which can now autonomously handle 75% of support inquiries.”
Meta: Recommendation systems, content generation, training, and inference are jointly driving infrastructure demand. The platform advantage is that AI can directly improve ad matching and content supply; the risk is that data-center deployment lags product demand. The market is more focused on whether incremental capital expenditure can translate into measurable advertising revenue and free cash flow.
“When you look across inference, training, recommendation systems, and content creation, we are seeing what can only be described as a surge in demand.”
Amazon: According to four people familiar with the matter, Prime Video’s internal Project Lighthouse will put AI at the center of its streaming transformation and showcase Amazon’s AI capabilities to more than 200 million consumers. Platform distribution provides a low-cost testing channel; the investment implications depend on whether engagement, content costs, and advertising monetization improve.
“Prime Video will become a high-impact platform for showcasing Amazon’s AI investments.”
Microsoft: The company has begun routing some first-party product traffic to its proprietary MAI models where performance in specific use cases matches or exceeds general-purpose frontier models while consuming fewer tokens. If migration expands, Microsoft could reduce external model costs and improve product gross margins; the counterevidence would be insufficient model quality and reliability.
“When our models match or exceed the performance of frontier alternatives, we are beginning to route traffic from first-party product interfaces to MAI.”
Oracle: The near-term constraint on AI data-center development is delivery, not demand. Guggenheim believes the delays do not represent a systemic risk, but the market still requires evidence of a complete cycle spanning construction, power-up, customer acceptance, and revenue recognition. With the cost of capital rising, orders or targeted capacity alone are insufficient to support platform valuations.
“Oracle’s AI buildout has been substantially de-risked, and data-center delays are not a systemic issue.”
SpaceX: Google disclosed that its SpaceX stake has a market value of approximately $94 billion, of which about $80 billion is subject to a short-term post-IPO lockup and another $14.1 billion is locked up until Q3 2027. The substantial unrealized gain increases asset value but cannot be monetized in the near term, while share-price volatility will affect related gains and losses.
Anthropic: Anthropic is reportedly considering requiring rank-and-file employees to use preset securities trading plans to sell shares after the company goes public, balancing its information-sharing culture with trading compliance. The rising value of Google’s stake strengthens the capital relationship, but platform competition will ultimately depend on model capabilities, enterprise adoption, and inference costs.
OpenAI: ChatGPT’s health features now connect to U.S. users’ medical records and Apple Health data, bringing the model into highly sensitive, high-liability use cases. The commercial opportunity lies in higher-frequency personal-data services, while the risks include authorization, data isolation, incorrect recommendations, and regulatory liability. These requirements will also increase spending on security controls.
Reddit: The market briefly worried that Google would not renew its data agreement, before management indicated otherwise. The episode shows that platform data is becoming a tradable asset for model training and search enhancement. Pricing power depends on unique content, alternative data sources, and competitive bidding by buyers, rather than traffic growth alone.
CoreWeave: Emerging cloud providers depend more heavily on direct GPU monetization, with payback periods of approximately two to three years versus three to five years for hyperscalers. Growth in committed-use contracts helps stabilize cash flow, but next-generation GPUs may erode pricing before older equipment achieves payback. Financing costs and residual asset values are the most important risks.
Nebius: Its backlog is comparable in scale to CoreWeave’s, but conversion is slower through 2027 despite a higher market valuation. Whether this divergence can persist depends on customer concentration, contract quality, power-up progress, and financing structure. Comparing sales multiples alone can overlook lease obligations and hardware depreciation.
Digital advertising: AI Max users achieved approximately 15% more conversions at a similar return on ad spend, while Google’s advertiser-support agents can automatically handle 75% of inquiries. AI’s near-term contribution to platform profits is more likely to come from higher conversions and lower service costs than from standalone fees.
Cloud-platform cash flow: Google’s free cash flow turned negative for the first time in Q2, prompting investors to prioritize capital expenditure and cash payback periods over revenue growth. Large platforms can cross-monetize through advertising, subscriptions, and cloud services, but valuations will remain under pressure if depreciation and third-party compute costs continue to outpace revenue over the long term.
Platform distribution: Google is embedding Gemini across Search, Android, productivity applications, and YouTube; Amazon is integrating AI into Prime Video; and Microsoft is shifting traffic to MAI. Platform competition is moving from model leaderboards toward “who can integrate models into existing user journeys,” with adoption, paid conversion, and unit service costs as the key validation metrics.
AI data transactions: Data licensing between content platforms and model developers remains in a repricing phase. The dispute over Reddit’s renewal shows that unique human-generated content may command higher prices, but synthetic data, the open web, and alternative partners will limit the long-term bargaining power of any single platform.
Software/SaaS
Adobe
1) Morgan Stanley downgraded the stock from Equal-weight to Underweight and cut its price target from $365 to $240.
2) Monthly active users of its free creative products increased from 50 million to 90 million, but implied FY26 organic ARR was revised down by approximately $500 million, indicating that free traffic has yet to convert consistently into paid subscriptions.
3) AI investment, delayed price increases, and CEO/CFO transitions are occurring simultaneously, creating execution risk beyond competition at the individual-product level.
“Adobe’s growth inflection will become visible only when AI usage and free traffic consistently convert into paid ARR.”
ServiceNow: Q2 EPS, revenue, and current remaining performance obligations all exceeded expectations, while gross margin fell short; Citizens maintained its Outperform rating and $157 price target. Renewal performance indicates that customers are not rapidly abandoning configuration management databases because of generative AI or low-code tools. The next question is whether AI features can increase contract value.
“Product releases cannot determine this distinction; paid usage and renewal behavior can.”
Microsoft Security: Microsoft controls the productivity interface, identity stack, and cloud infrastructure, making it best positioned to bundle AI security controls into existing contracts. Distribution advantages do not necessarily create an incremental market; if features are included at no additional charge, the economic value will mainly take the form of share shifts rather than meaningful expansion in customer budgets.
Palo Alto Networks: The platform controls security telemetry across endpoints, networks, and cloud environments, making it well suited to apply AI to alert classification, investigation, and runtime controls. The near-term value lies in expanding analyst capacity, not fully replacing security personnel. High-impact remediation will still require human approval, while renewals and higher usage are the evidence required to validate revenue.
CrowdStrike: Endpoint telemetry gives the company an advantage in training security models and identifying anomalous machine behavior. As agents proliferate, the number of endpoints and machine identities will increase in parallel. The risk is that cloud platforms bundle basic controls at no additional charge, reducing customers’ willingness to pay for standalone security products.
“At this stage, the revenue opportunity comes from improving security-team productivity, not replacing them.”
Zscaler: The access edge is a critical control point for governing model and agent access to enterprise systems. The opportunity comes from extending zero-trust policies to more machine identities and workloads. The key validation point is whether contract usage increases after production AI deployments; if default cloud permissions prove sufficient, incremental demand may fall short of expectations.
Cloudflare: Its edge network sits close to model calls and external access paths, positioning it to provide runtime detection, access control, and inference security. Its advantages are latency and distribution; the challenge is whether enterprises will pay separately for model security. Improvements at the interface layer have limited value unless they control actual execution permissions.
Data security: Models first expose the question of “what they can see,” requiring enterprises to map data visibility, inherited permissions, and potential leakage of sensitive content. Commercialization is likely to precede standalone model security because data controls already exist within customer budgets. The next indicators are add-on module adoption and renewal values.
Identity security: As agents evolve from assistants into operators, they will create large numbers of machine identities and require least-privilege access and task-level revocation rights. Growth in identity counts is a more reliable tracking metric than seat counts. If permissions remain read-only for an extended period, revenue sensitivity will be weaker than expected.
“The first security question is simple: what can the model see?”
Runtime governance: Production systems must monitor agents’ actual calls and promptly block unauthorized actions, erroneous operations, or anomalous data access. This layer is more closely tied to transactions and operational outcomes, increasing the likelihood that customers will pay for it; however, excessive false positives could slow production deployment.
SOC agents: AI can already improve alert classification, information gathering, triage, and investigation. The near-term objective is to reduce mean time to resolution and increase capacity per analyst. Investors should track actual productivity and human approval processes for high-risk incidents, rather than focusing solely on automation rates in demonstrations.
Model security tools: Standalone model evaluation, prompt-attack protection, and output controls will create new products, but the revenue pool may emerge later than those for data and identity security. Bundling by major cloud providers and integrated platforms will compress pricing, requiring specialists to demonstrate differentiation through superior detection, auditing, or cross-platform capabilities.
“There are two distinct revenue pools: AI-enabled security and securing AI itself.”
Security pricing: Per-seat pricing does not fully capture machine calls, and the industry may shift toward pricing based on usage, machine identities, or outcomes. The more closely pricing aligns with production workloads, the more clearly revenue will scale with AI adoption. Discounts and platform bundling, however, will separate technical demand from commercial value.
Security platformization: Identity, data, access, model, and runtime controls need shared policies and telemetry, while fragmentation increases the cost of transferring context. Platform vendors have an integration advantage, while specialists must demonstrate that their point-solution capabilities are sufficient to offset integration complexity.
Falsification conditions: If default cloud-platform controls prove sufficient, agents remain without elevated privileges for an extended period, open-model attack capabilities plateau, or customer renewals show no increase in pricing or usage, AI security will resemble a reallocation of existing budgets rather than a large standalone market.
“Bundling will absorb the economic value; necessary controls do not automatically create standalone revenue.”
Consumer Electronics / Smart Vehicles
Tesla
1) Second-quarter revenue was approximately $28.0 billion, up 25.5% year over year, but operating profit fell 57%, with the operating margin declining to 1.4%; the free cash flow margin was negative 3.9%.
2) Paid FSD users approached 1.5 million, up 56% year over year, while adoption among new vehicles in North America exceeded 55%; cumulative unsupervised Robotaxi mileage surpassed 380,000 miles.
3) Full-year capital expenditure is expected to exceed $25 billion, making rapid monetization of physical AI imperative.
“The next leg of share-price appreciation requires not another vision of the future, but Robotaxi and Optimus translating into actual production, revenue, and profit.”
General Motors
1) Second-quarter revenue was $48.026 billion, adjusted EBIT was $3.943 billion, and automotive free cash flow was $5.033 billion, all above expectations.
2) The company raised the midpoint of its 2026 adjusted EBIT guidance by $500 million to a range of $14 billion–$16 billion.
3) Digital subscriptions and Super Cruise are potential valuation rerating catalysts, but DRAM, raw materials, and tariffs will increase costs in 2027.
“Software and services are underappreciated growth drivers, with digital subscriptions becoming an increasingly important and less cyclical source of earnings.”
Hyundai Motor: Second-quarter revenue was KRW49.215 trillion, while operating profit fell 20.8% year over year to KRW2.851 trillion, implying a 5.8% operating margin. Goldman Sachs expects disruptions from production, FX translation, and raw materials to ease in the second half; the robotics narrative now requires evidence of actual Atlas deployment or training progress rather than a reiteration of the long-term vision.
“Unless there is tangible deployment or training progress, Hyundai Motor’s share price is still more likely to track its earnings trajectory.”
Yaskawa Electric: An ERP migration created bottlenecks in logistics processes. Inverter utilization has already exceeded 100% on a single-shift basis, servo motors are targeted to reach full production in September, and robots are expected to reach full single-shift production in October. Humanoid-robot actuators have entered customer loan testing, but mass-production processes, automated assembly, and cost remain the biggest commercialization challenges.
“The greatest challenges on the path to commercialization are likely to be mass production and cost.”
Mitsubishi Electric and Sony: The companies will establish an AI vision-sensor joint venture, scheduled to begin operations in October 2026, with ownership stakes of 60% and 40%, respectively. The sensors will run AI directly at the image-sensor level to identify the condition and position of components on production lines. The strategic rationale is clear, but specific products, orders, and earnings contributions still need to be disclosed.
“Vision sensors will use AI analysis at the image-sensor level to provide real-time detection of product and component conditions on production lines.”
Samsung Electronics: The company has applied to build an HVAC plant on approximately 10,000 pyeong of land in Gwangju, with the market estimating investment of around KRW200 billion. Following its acquisition of FläktGroup, Samsung’s business is expanding beyond residential and commercial air conditioning into central HVAC systems for factories, hospitals, and AI data centers. Construction could be delayed by site-related issues; orders and customer qualifications matter more.
Apple and Ford: Ford will reportedly use Apple software in its new autonomous-driving system. This indicates that competition in automotive software is not confined to automakers’ in-house platforms and may also be penetrated through consumer-electronics ecosystems. Key issues to watch are the scope of the partnership, the production models involved, and Apple’s access rights to vehicle data and interfaces.
Black Forest Labs and Audi: FLUX 3 has expanded from images into video, audio, and physical-action prediction. Its first robotics model, FLUX-mimic, is being developed with Mimic Robotics and tested for deployment at Audi. Whether the model can enter industrial production will depend on motion stability, closed-loop data, and on-site safety.
Boston Dynamics: Hyundai Motor’s CEO Investor Day in August may provide an update on Atlas. Goldman Sachs believes numerous public robotics milestones have already been presented, and the next step must be evidence of deployment, training, or customer use. If the project remains at the demonstration stage, the group’s valuation will depend more heavily on a recovery in automotive margins.
Super Cruise: General Motors expects to add 1 million digital subscriptions in 2026 and has confirmed more than $3 billion in revenue. Second-quarter deferred revenue was $6.3 billion, up 50% year over year, with a year-end target of $7.5 billion. Broader model coverage, conversion to paid subscriptions after free trials, and higher ARPU will determine whether the approximately 70% gross-margin target can be achieved.
FSD: Tesla has nearly 1.5 million paying customers, 45% of whom subscribe. Rising adoption indicates that autonomous driving is shifting from an optional feature to a purchase driver, but average automotive revenue per vehicle declined to $42,426, and software growth still needs to offset price cuts and high capital expenditure.
Humanoid-Robot Actuators: Yaskawa uses larger motors and lower reduction ratios, estimates external force through current signals, and collects image, torque, speed, and load data through teleoperation to train AI. Differentiation lies in compliance and the integration of motors, gearboxes, and controls, while near-term revenue still depends on mass production.
AI Vision Sensors: Industrial vision AI runs models at the image-sensor level, reducing latency and enabling real-time assessment of product quality, equipment condition, and maintenance needs. Mitsubishi Electric provides the factory-automation use cases, while Sony supplies the sensor technology; the key question is whether customers will pay for unmanned monitoring.
Automotive DRAM Costs: General Motors estimates that higher commodity and DRAM costs could create a $250 million–$500 million headwind in 2027. Vehicle intelligence is increasing memory content, but automakers’ ability to pass on costs through pricing or product mix will determine the actual impact of memory price increases on profitability.
Capital Constraints on Physical AI: Tesla, Hyundai Motor, and Yaskawa are all advancing robotics or autonomous-driving initiatives, but they are at very different stages of commercialization. Near-term validation should focus on Robotaxi mileage, paid FSD adoption, Atlas deployment, actuator loan testing, and mass-production costs. Only when these metrics translate into revenue will valuations gain a new anchor.
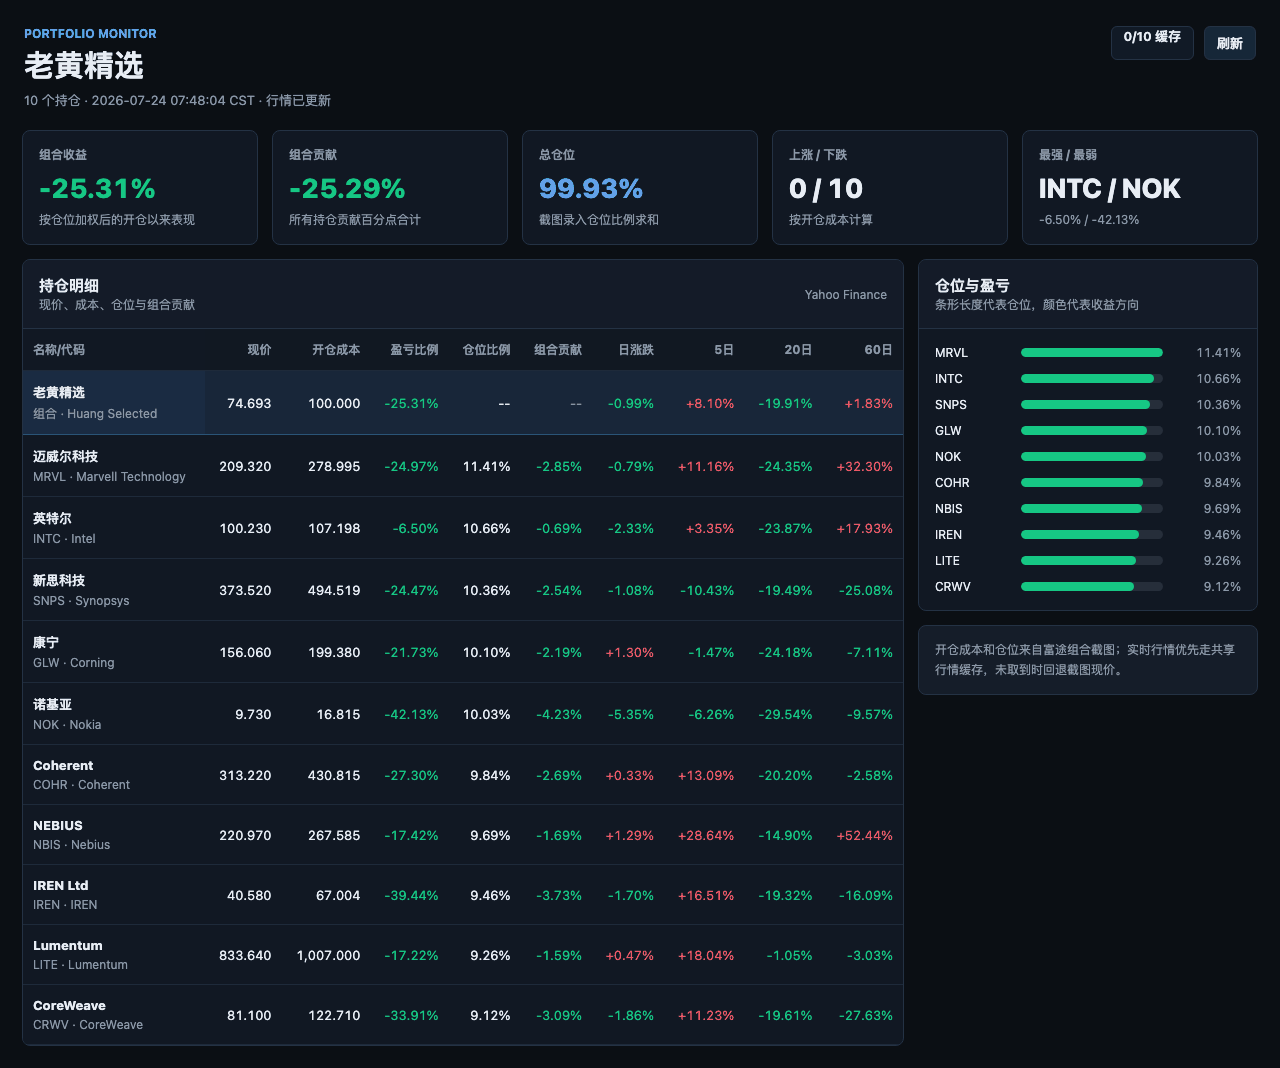
Huang’s Selected Portfolio