
404K SEMI-AI Morning Brief — July 17, 2026 — Model Catch-Up Accelerates, Compute Supply Remains Tight, Tech Momentum Pulls Back
目录
Post-Market Summary
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capex
CSP/Cloud Capex and AI Cloud
GPUs, CPUs, ASICs, and High-Speed Interconnects
HBM/DRAM/NAND/SSD/HDD, Equipment, and Optical Communications
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Investment-Bank Price-Target Changes Over the Past 12 Hours
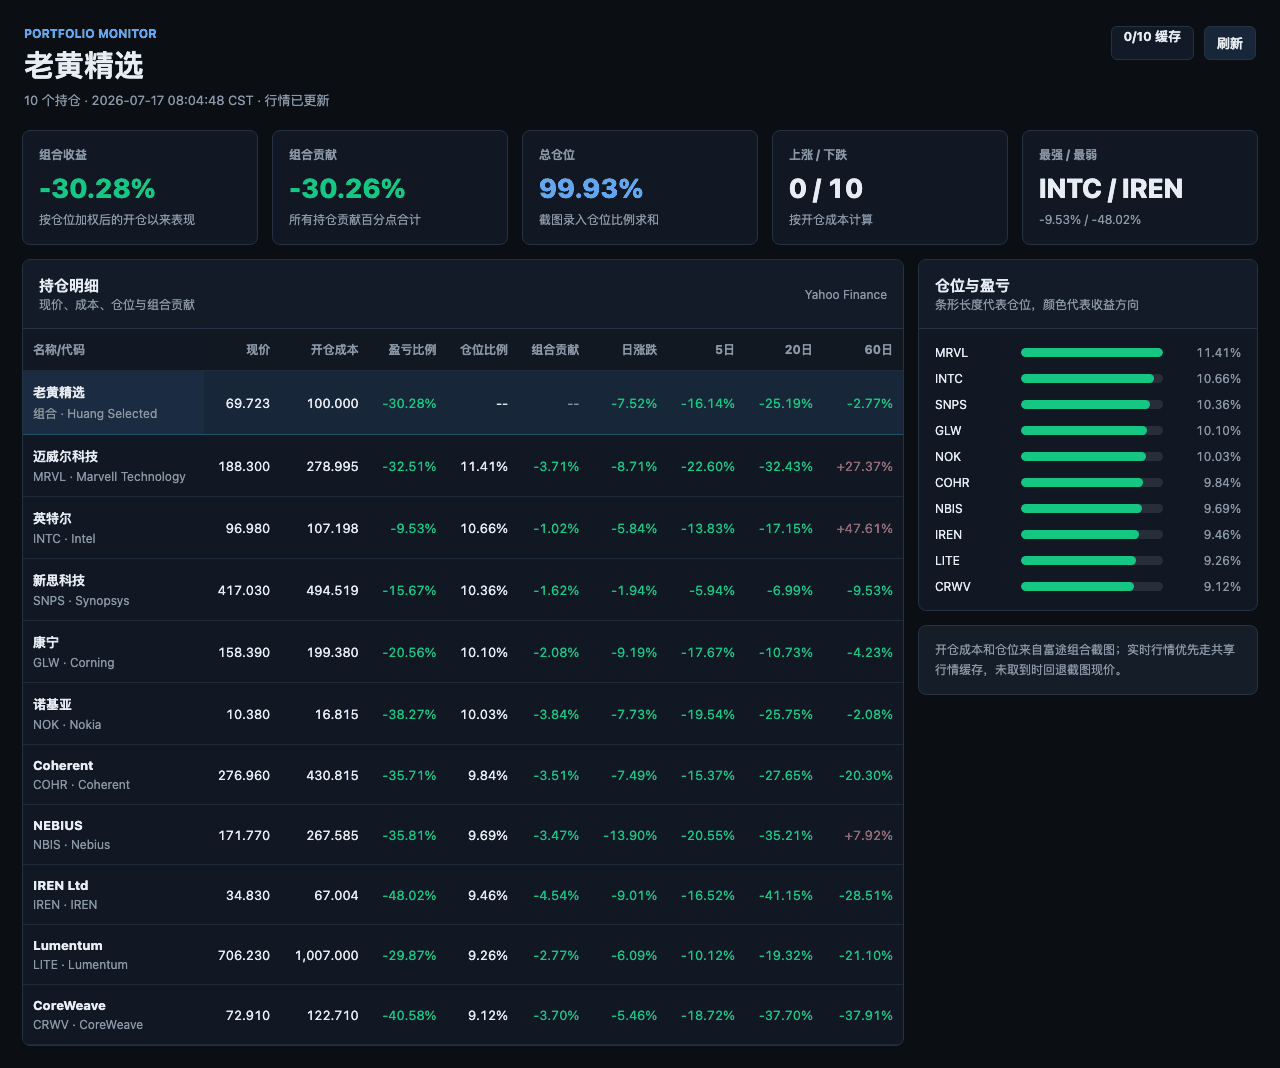
Huang’s Selected Portfolio
Demand for AI applications and infrastructure has not weakened, but the market has shifted from rewarding growth alone to scrutinizing margins, returns on capital, and supply delivery. Kimi K3, GPU rental rates, memory price increases, and EUV orders continue to provide positive evidence, while the broad sell-off in semiconductor and neocloud names reminds investors that even good businesses must be bought at the right price.
404K SEMI-AI | July 17, 2026
Post-Market Summary
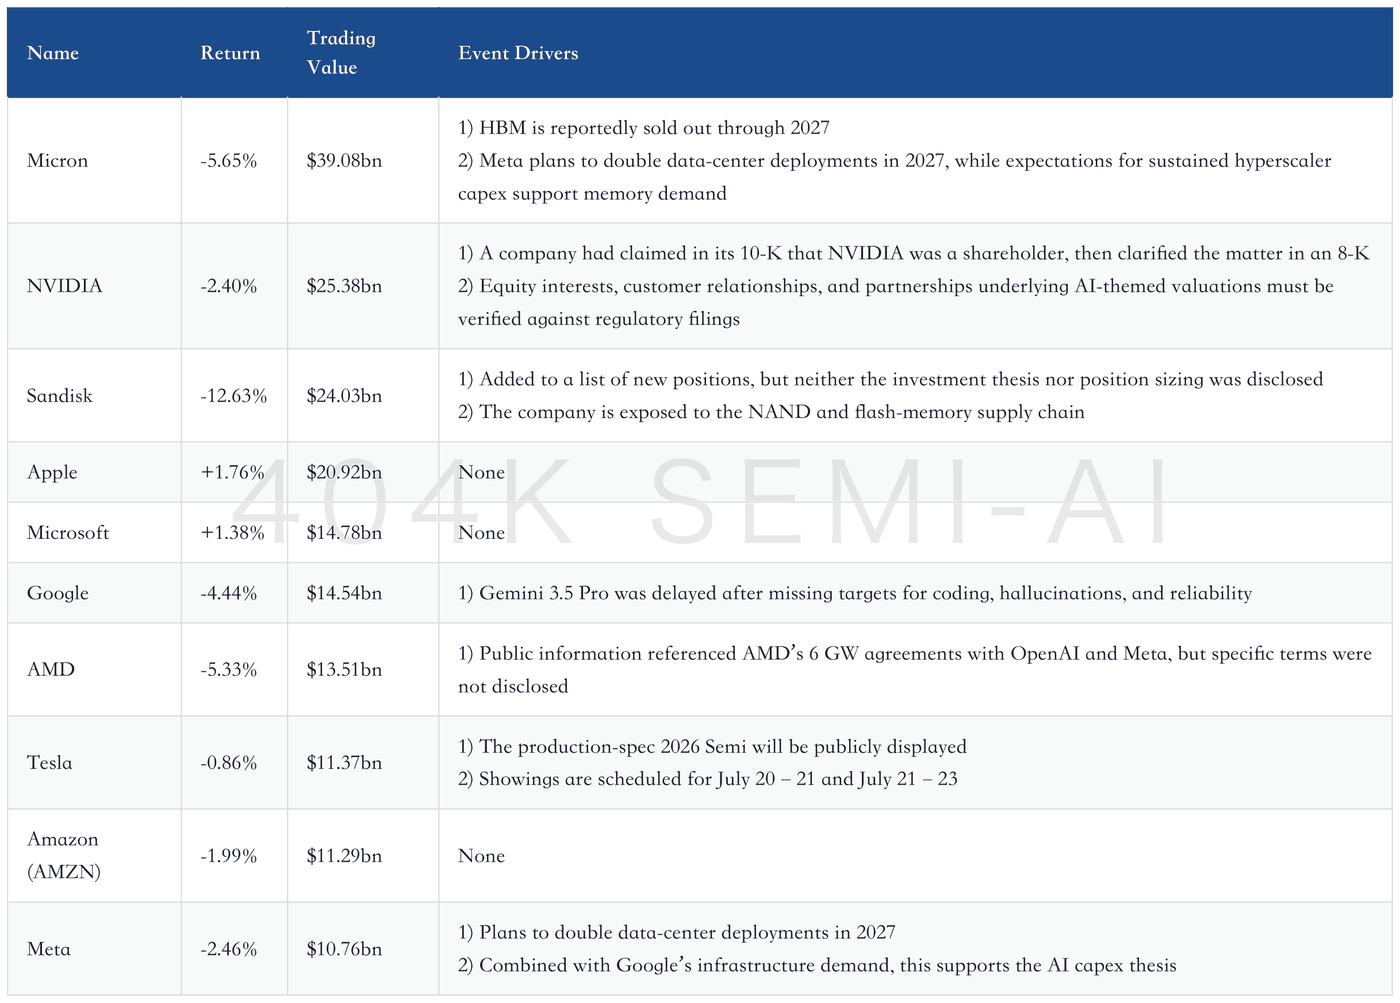
The U.S. technology trade cooled markedly. The S&P; 500 fell 0.54% and the Nasdaq 100 declined 1.71%, while the equal-weighted S&P; 500 rose 0.98%, indicating a rotation from high-beta technology into the broader market. The VIX rose 9.00%, suggesting this was not merely an adjustment in individual names but also a tightening in risk appetite.
Semiconductors were at the center of the pressure: SMH fell 3.70% and SOXX declined 4.54%. Their 20-day returns were -7.64% and -10.35%, respectively, with RPS20 readings of just 11.1 and 3.7. The software ETF fell only 0.26% and remained up 2.55% over 20 days, indicating that the day’s valuation compression was concentrated in hardware, memory, and neoclouds.
Fundamentals diverged sharply from market performance. Google Cloud backlog, GPU rental rates, DRAM contract prices, and EUV orders continue to point to robust demand, yet Micron, Sandisk, Seagate Technology, Marvell, and Nebius all sold off sharply. The focus now shifts to order conversion, capacity ramp-up, and margins; demand narratives alone are no longer sufficient.
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capex
Kimi K3: Capabilities are catching up rapidly, but deployment economics have yet to be demonstrated in parallel. The model has 2.8tn total parameters and a 1mn-token context window. It scores 57 on the Artificial Analysis Intelligence Index, 1,668 Elo on GDPval v2, and 53% on AutomationBench-AA, ranking No. 1; cost per task is $0.94, and model weights have not yet been released.
“Kimi K3 has 2.8tn parameters, an index score of 57, a GDPval v2 Elo rating of 1,668, and an AutomationBench-AA score of 53%.”
OpenAI
1) The ChatGPT custom-instruction limit increased from 1,500 to 5,000 characters, expanding capacity for personalized interactions.
2) Its research collaboration with Chip Ganassi Racing has expanded to developing track-data tools using ChatGPT and Codex, but no data on revenue or decision-making efficiency has been disclosed.
“How racing teams use AI to identify marginal differences in track data that influence outcomes and convert data into decisions more quickly.”
Anthropic: The investment implications are shifting from model capabilities toward commercialization and capital efficiency. Reports that the company is nearing profitability, together with supply-constrained GPT-5.6 compute and Codex users increasing from 5mn to 9mn in one month, support an extended inference-demand cycle. The risk is that specific profit, cash-flow, and credit terms remain undisclosed.
Enterprise AI Buyers: Procurement rules are beginning to shift from “deploy first” to “prove results first.” Vendors are moving toward usage-based pricing, while buyers allocate tasks to cheaper models and cap employee spending; only 11% of agentic-AI pilots have reached production. Utilization rates and unit costs are the next metrics to watch.
“Buyers are assigning tasks to cheaper models, limiting employee spending, and demanding evidence of results before scaling deployments.”
Healthcare AI: Verifiable efficiency metrics are emerging. UnitedHealth reduced prior-authorization processing from eight hours to less than 30 seconds; Eli Lilly is running drug-discovery workloads on an NVIDIA-powered AI supercomputer; and Sanofi and Mayo Clinic have embedded AI into sales preparation and clinical documentation, respectively.
CSP/Cloud Capex and AI Cloud
Google
1) 2026 capex guidance increased from $175–185bn to $180–190bn, with $35.7bn already spent in the first quarter.
2) Cloud backlog stands at $462bn, with more than 50% expected to convert within 24 months. Gemini 3.5 Pro missed its target for the third time, showing that strong compute demand does not eliminate product-execution risk.
“Internal compute demand is now competing with external enterprise customers for GPU time within Google’s own infrastructure.”
Meta: Its plan to double data-center deployments in 2027 provides a medium-term anchor for memory, interconnect, and power demand. Meta is also reportedly the sole buyer of active copper cables using Maxim analog chips, with three other cable vendors having completed qualification. This is a supply-chain indicator that still requires confirmation through orders and revenue recognition.
CoreWeave: B200 rental rates reached $6.83 per hour in June, up 25% from early May, while the 30-day trend points to $8.54 per hour. The company operates sizable B200 and GB200 clusters and should theoretically benefit as the rental-rate gap between new and previous-generation GPUs narrows. However, rental-rate trends, utilization, and financing costs remain critical to cash flow.
Nebius
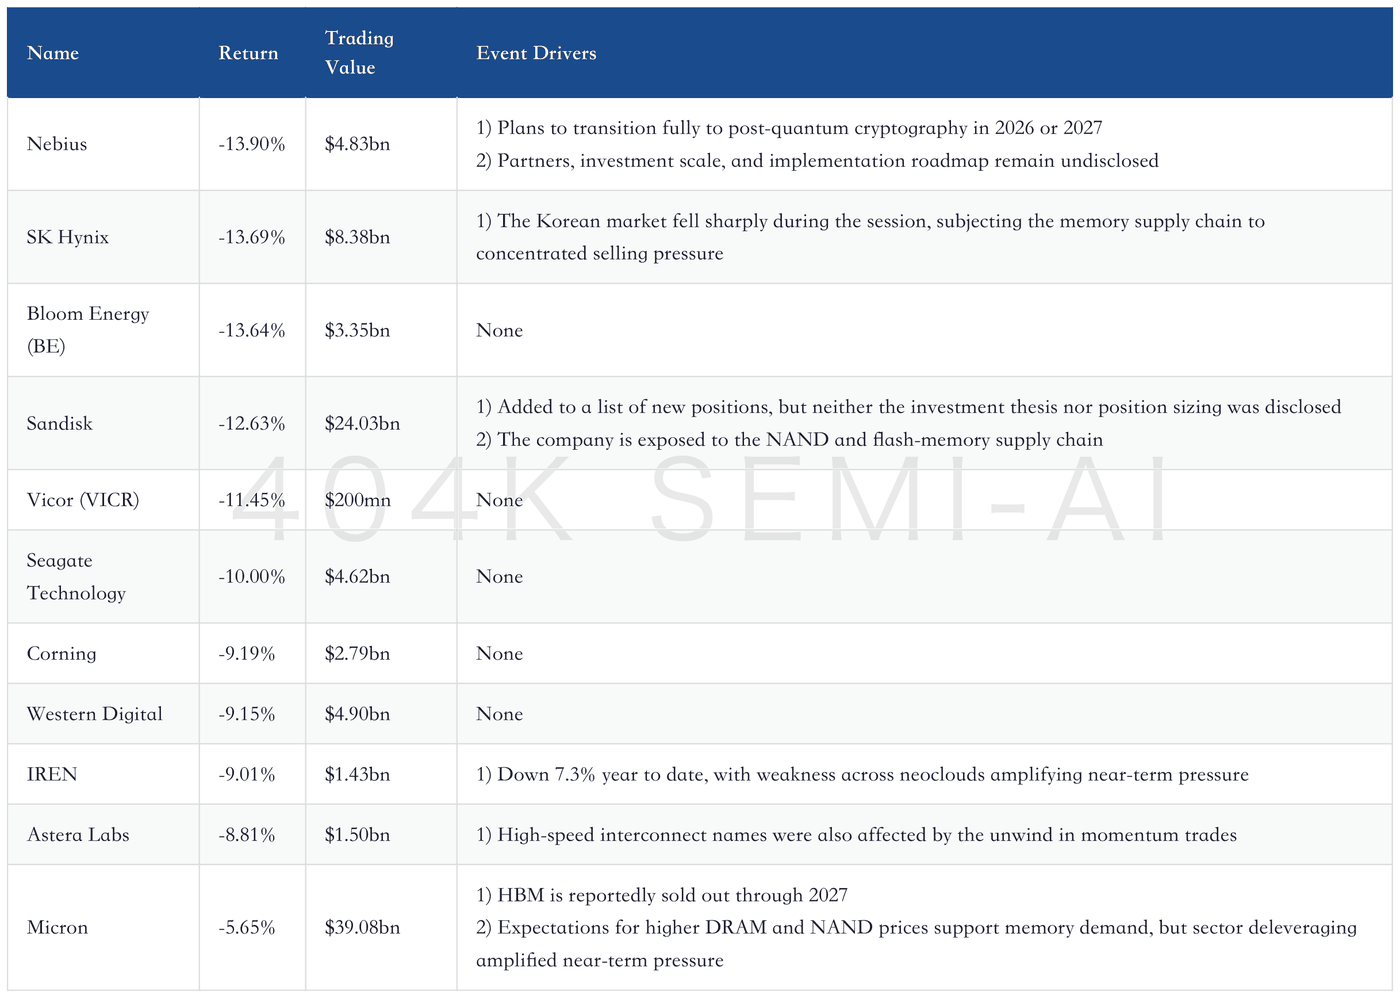
1) Like CoreWeave, Nebius benefits from B200 deployments and improving rental rates, but its 13.90% decline during the session highlights trading risk that is materially greater than the smoothness implied by industry data.
2) The company plans to transition fully to post-quantum cryptography in 2026 or 2027, but partners and investment scale remain undisclosed.
“The bear case for neocloud providers has consistently been that oversupply would destroy pricing, but this chart shows that precisely the opposite is occurring.”
CleanSpark: Its first colocation lease provides tangible evidence on asset returns. The tenant was not disclosed but is reportedly investment grade; the 20-year agreement uses a triple-net lease structure, and the author estimates a cost yield of approximately 12.8%. Project costs, rent, power capacity, and delivery timing still need to be verified.
GPUs, CPUs, ASICs, and High-Speed Interconnects
NVIDIA
1) It is working with Japan to build a national AI factory for physical AI, targeting manufacturing, logistics, transportation, healthcare, telecommunications, and power-grid optimization. Project investment, GPU configuration, and construction timelines were not disclosed.
2) The “gigawatt economics” model indicates that GPU performance must translate into effective throughput and gross profit per active MW to generate returns.
Intel
1) Expanded its multiyear partnership with Google Cloud, using Gemini Enterprise across engineering, supply chains, and chip design, while C4 and N4 instances supplement on-premises high-performance computing.
2) A High-NA process layer completed dual qualification in Oregon, and notebook chips partly patterned using a $380mn High-NA scanner have been delivered to customers.
Marvell: The new Teralynx T100 is a 3nm, 102.4T data-center switching ASIC designed to reduce power consumption, system complexity, and latency in AI training and inference. The company claims it delivers “the industry’s lowest latency,” but disclosed no latency figures, customer validation, mass-production timeline, or orders.
Maxim: Three supply-chain indicators warrant tracking: Meta’s active-copper-cable procurement, an on-board linear-equalizer platform at another major hyperscaler, and an approximately 50% share in 800G TIAs alongside design wins for 1.6T modules. All are based on industry checks and require confirmation through company disclosures on orders, customers, and revenue.
GPU Rental Market: H100 forward rental rates rose 40% in the first half of 2026, while B200 rates increased 27%. B200 performance is approximately 1.8–2.5x that of H100, versus rental rates of roughly 1.75x, resulting in more favorable per-token economics. This suggests previous-generation supply is being absorbed, but rental rates are only a real-time signal and cannot substitute for cluster utilization and cash payback.
HBM/DRAM/NAND/SSD/HDD, Equipment, and Optical Communications
Micron
1) Bank of America expects DRAM average selling prices to rise 21% quarter over quarter in the third quarter, while its survey indicates server DRAM contract prices will increase 20–30% quarter over quarter, led by high-speed LPDDR5.
2) Bank of America said urgent OEM orders confirm quarter-over-quarter price increases exceeding 20% for both commodity DRAM and NAND, while orders are also shifting from HBM3e toward higher-priced HBM4.
“NAND recovery: NAND spot prices have rebounded, driven by a 4% week-over-week increase in 1Tb wafer prices, supporting expectations for NAND ASP growth of more than 10% in 3Q.”
SK Hynix and Samsung Electronics: Memory trades experienced sharp deleveraging despite strong fundamentals. Weekly inflows into Korean ETFs reached $814mn and $1.1bn in succession, as some investors used them as substitutes for SK Hynix ADRs trading at an approximately 25% premium. However, the SK Hynix ADR fell 13.69% during the session, indicating that positioning concentration has become a risk factor.
Sandisk, Seagate Technology, and Western Digital: The three memory and storage names fell 12.63%, 10.00%, and 9.15%, respectively, although industry indicators have not weakened in parallel. Bank of America said 1Tb NAND wafer prices rose 4% week over week, supporting third-quarter NAND ASP growth above 10%; Seagate’s nearline product prices are expected to increase approximately 7% quarter over quarter.
ASML: EUV translates advanced-node demand into trackable equipment volumes. The 2026 shipment outlook is approximately 65 systems, excluding High-NA, rising to around 85 in 2027, with the required orders nearly fully booked. Upstream capacity at Carl Zeiss SMT is a leading indicator of the shipment ceiling, while 90 systems remains only a potential upside scenario.
“The company’s 2026 guidance is already close to the author’s forecast of 67 systems, while the 2027 order position is increasingly validating the ‘sold-out’ assessment.”
UMC and Tower Semiconductor: The bottleneck in optical-communications expansion is shifting from the availability of 300mm capacity to customer qualification, yields, and ramp speed. Tower Semiconductor has signed contracts corresponding to $1.3bn of silicon-photonics revenue in 2027 and received $290mn in capacity-reservation payments; additional supply could also reduce average selling prices for PIC wafers.
“Silicon can be used to manufacture modulators, waveguides, and detectors, but its indirect bandgap prevents it from generating laser light. Rising silicon-photonics penetration therefore still requires external InP continuous-wave light sources.”
Internet/Platforms
Netflix
1) Q2 revenue was $12.56 billion, up 13% YoY, with EPS of $0.80; operating margin was 33.4%, down 70 bps YoY, while free cash flow fell 33% YoY to $1.53 billion.
2) Q3 revenue guidance of $12.86 billion and EPS guidance of $0.82 were both below expectations. Growth continues, but the market is demanding stronger cash flow and guidance.
“Q2 revenue was $12.56 billion, up 13% YoY; EPS was $0.80, up 11% YoY; and operating profit was approximately $4.19–4.20 billion, up 11% YoY.”
Streaming Advertising Technology: Incremental growth in mature markets must come from advertising and new interactive formats. Advertising spend on Netflix’s platform grew 15%–30% YoY in Q2 2026, while integration between its in-house programmatic advertising system and Amazon DSP improved attribution. India and the Philippines are key execution variables for achieving the $3 billion target.
Google: Shares fell 4.44% on the day amid both model delays and higher capital expenditure. Management’s long-term investment thesis is that revolutionary technologies cannot be built solely through incremental improvements. Investors should test this thesis against cloud backlog conversion, Gemini adoption, and returns on capital.
“The central tension is the information gap between the necessity of long-term investment and the verifiability of near-term financial returns.”
Meta: Shares fell 2.46% on the day, but capital expenditure signals still point to a doubling of data-center deployments in 2027. The key issue for the platform is not merely recommendation quality and advertising effectiveness, but whether greater investment can translate into model usage, advertising monetization, and longer user engagement.
Amazon: Its DSP integration with Netflix makes measurement and attribution easier for advertisers, showing that Amazon’s platform value has expanded from media buying to streaming monetization. Advertising volume, take rates, and conversion rates were not disclosed, so only the strategic direction of the partnership can be confirmed at this stage; revenue sensitivity cannot yet be extrapolated.
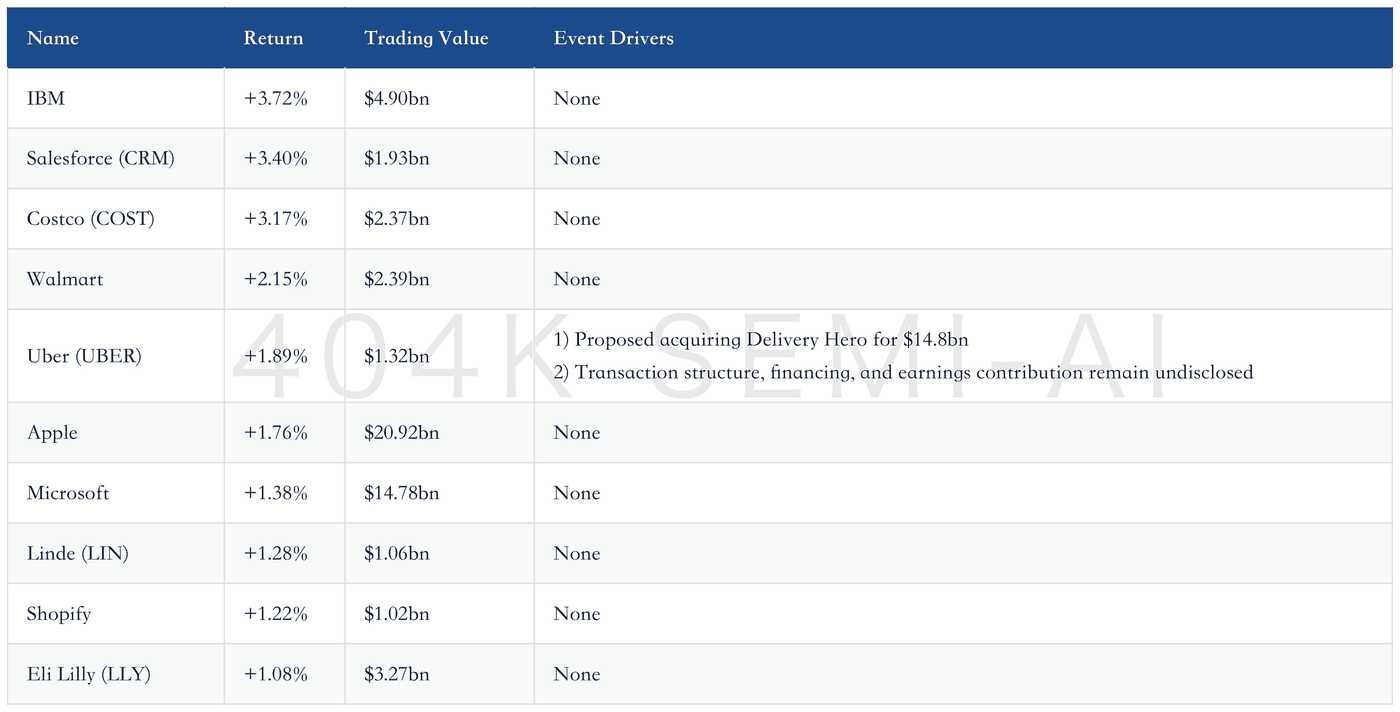
Uber: The proposed $14.8 billion acquisition of Delivery Hero shifts platform competition from drivers and users toward regional supply consolidation. Shares rose 1.89% on the day, but the transaction structure, financing, antitrust approval, and Year 3 EPS contribution are the real validation points.
“Uber’s proposed $14.8 billion acquisition, the Netskope price-target increase, and expectations of continued ARK buying constitute positive event signals, but the report lacks comprehensive fundamental validation.”
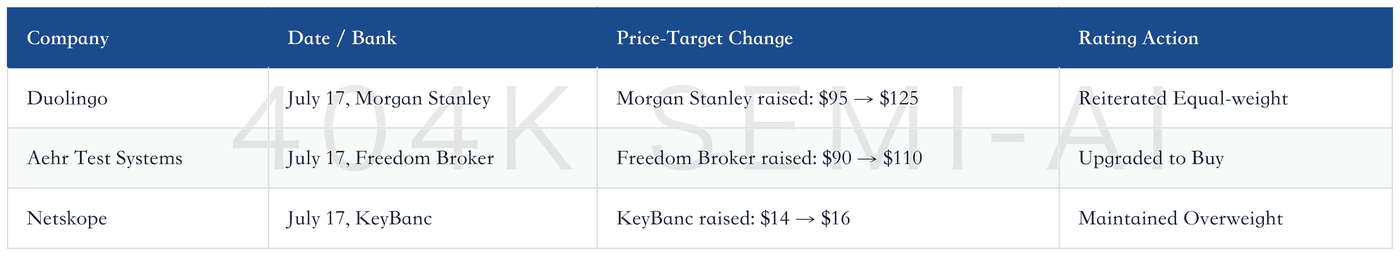
Duolingo: Morgan Stanley reiterated its “Equal-weight” rating on July 17 and raised its price target from $95 to $125. The firm remains tactically optimistic about Q2, believing momentum in users, bookings, and EBITDA is driving an inflection. The risk is that the rating remains neutral rather than positive.
Truth API: The service plans to open its proprietary content data feed to institutional clients beginning in August, demonstrating how social content can evolve from a traffic product into a data product. However, the operator, pricing, number of institutional clients, and revenue contribution were not disclosed. Whether exclusivity can generate recurring revenue will depend on subscription conversion.
X Platform: Creator rewards are beginning to provide real income, but the feed mechanism also encourages users to split long-form articles into more than ten posts and repeatedly refresh the feed. Since ordinary creators struggle to publish 20–30 high-quality standalone posts each day, the conflict between incentives and content integrity could damage the user experience.
“The rewards and feed mechanisms encourage users to split a complete long-form article into more than ten posts and compete for attention through constant posting, ultimately damaging the user experience and diluting genuinely valuable content.”
ChatGPT Work: New workflows for creating and editing documents, spreadsheets, and presentations move the platform from a conversational interface into office productivity workflows. The product direction is clear, but account availability, usage rates, export success rates, and paid conversion were not disclosed. Activity levels must confirm whether it is genuinely diverting usage from traditional office software.
Public-Market AI Platforms: Google fell 4.44% on the day, while private model companies have temporarily avoided real-time pricing pressure. This does not prove that private-company valuations are more stable; it only shows that public markets reflect product delays, capital expenditure, and monetization concerns in prices more quickly.
Platform Advertising Buyers: Growth in Netflix advertising spend and its Amazon DSP integration show that advertisers are willing to pay for better measurement and attribution. Premium CPMs are beginning to normalize, which should support broader customer coverage. If advertising revenue cannot offset content costs, however, platform margins will remain under pressure.
Model-Hosting Platforms: Enterprises unable to absorb approximately $6 million in spending to self-host GB300 systems will turn to cloud hosting. When open models are priced similarly to leading proprietary models, customers are buying more than model weights: they are also paying for support, sales coverage, stability, and the deployment ecosystem. This will concentrate value among leading cloud platforms.
“When open models are priced the same as models from leading cloud-based AI labs, why should I use an open model?”
Frontend Generation Platforms: Models capable of generating attractive websites, SVGs, and three.js worlds are more likely to spread online, but visual appeal does not imply superior underlying reasoning. From an investment perspective, customer-acquisition efficiency must be assessed separately from task success rates; otherwise, the market may mistake a one-off demonstration for general capability.
Platform Risk Appetite: High-valuation platforms are not facing a uniform deterioration in fundamentals. Instead, investors’ tolerance for weak cash flow, acquisition premiums, and capital expenditure is declining simultaneously. Long-term investment will translate back into earnings evidence only if Netflix repairs free cash flow, Uber demonstrates transaction accretion, and Google converts cloud backlog on schedule.
Software/SaaS
Netskope: KeyBanc maintained its “Overweight” rating on July 17 and raised its price target from $14 to $16, citing momentum in cloud security and AI networking platforms. Shares rose against the market on the day, but the upside implied by the price target cannot substitute for validation through bookings, net retention, and free cash flow.
“KeyBanc maintained its ‘Overweight’ rating on Netskope and raised its price target from $14 to $16, implying approximately 21% upside.”
Cloudflare: Developers used React, Hono, and Cloudflare Workers to consolidate a lightweight AI web application into one port and one Worker. After merging requests, deployment took less than 60 seconds and cost $5 per month. This demonstrates that edge platforms can lower the launch threshold for small applications, but high concurrency, databases, and enterprise security remain unvalidated.
“A React frontend, Hono routing, and Cloudflare Workers can form an integrated single-port development and single-Worker deployment solution, enabling deployment in under 60 seconds and an always-on, globally distributed service for $5 per month.”
Gemini 3.5 Pro: The release is already several months behind schedule and has missed its target for the third time. The team is improving coding performance, hallucination rates, and reliability while considering an interim Flash release. This is a negative execution signal in AI software competition; the next validation points are a new release date, developer retention, and hallucination rates.
“Google Gemini 3.5 Pro was delayed by several months because its coding capabilities and overall technical performance fell short of targets.”
ChatGPT: The custom-instruction limit was increased from 1,500 to 5,000 characters, directly expanding the long-term preferences, task constraints, and output formats users can preset. The feature expansion is clear, but supported platforms, account availability, usage frequency, and subscription conversion were not disclosed.
AI Cybersecurity: Generative AI lowers the barrier to sophisticated attacks, and the global cybersecurity market is expected to exceed $350 billion by 2030, representing a 9.1% CAGR from 2025 to 2030. Spending is growing fastest in healthcare, financial services, and insurance. The market opportunity must be validated through renewals, customer retention, and reductions in security incidents.
“Accordingly, the global cybersecurity market is expected to exceed $350 billion by 2030.”
Wiz: Google’s $32 billion acquisition of Wiz shows that cloud security has become a platform-level asset. The investment implication is that as AI workloads increase, identity, configuration, and data risks become more concentrated. However, regulatory approval, integration costs, revenue synergies, and customer overlap still require company disclosure.
Armis: ServiceNow’s $7.8 billion acquisition of Armis embeds cybersecurity capabilities into enterprise workflows. Together with the Wiz acquisition, the transaction shows that security is no longer a standalone tool but a default layer within cloud and workflow platforms. Key follow-up metrics include post-transaction product bundling, customer cross-selling, and gross margin.
ServiceNow: While expanding its security perimeter through Armis, the platform must also demonstrate whether AI monetization can exceed acquisition and R&D; costs. The relevant metrics are not the “AI narrative,” but penetration of products such as Pro Plus, seat expansion among large customers, security-product attach sales, and free cash flow.
Palo Alto Networks: The expanding attack surface and demand for agent governance make cybersecurity a necessary complement to AI investment. Shares fell 0.25% on the day but rose 26.16% over 20 days, placing relative strength among the highest in the peer group. The key question is whether platform bookings, remaining performance obligations, and margins can support the valuation.
CrowdStrike: Endpoint, cloud, and identity data have direct value for detecting AI-enabled attacks. Shares fell 1.46% on the day but remained up 19.95% over 20 days, indicating that the market continues to assign a premium to cybersecurity. Investors should focus on net new ARR, module expansion, and sales efficiency rather than industry growth alone.
Datadog: Survey results continue to support growth above 30% in 2026, but the forward spending score fell from 5.4 to 2.0, while the valuation approaches 20 times revenue and 75 times free cash flow. Business performance will depend on cloud consumption, incremental purchases by large customers, and revenue from new AI products. If spending intentions continue to cool, the high valuation will amplify expectation gaps.
“Datadog survey results continue to support growth above 30% in 2026, but the forward spending score fell from 5.4 to 2.0, while the valuation approaches 20 times revenue and 75 times free cash flow.”
Post-Quantum Cryptography Software: Nebius has provided a 2026–2027 timeframe for full migration, moving security demand from a research topic toward cloud-infrastructure implementation. However, the algorithms, key management, migration scope, and vendors have not been confirmed. At this stage, the investable signal is that demand exists—not that any specific company has already secured orders.
Aehr Test Systems: Freedom Broker upgraded the stock to “Buy” on July 17 and raised its price target from $90 to $110. The firm views FY2027 guidance as a timetable for order conversion, supported by record orders and a strong backlog. However, order value, backlog size, and the pace of revenue conversion were not disclosed.
Sparse Mixture-of-Experts Model Services: The model activates 16 of its 896 experts per inference, representing an activation rate of approximately 1.7%. Service pricing is $3/$15 per million tokens, and inference gross margins are reportedly 75%–85%. These figures suggest attractive unit economics, but the provider, pricing basis, and cost definition are unclear, preventing direct profit extrapolation.
Software Spending Selection: The software ETF fell only 0.26% on the day and rose 2.55% over 20 days, significantly outperforming semiconductors. Relative sector strength does not mean every SaaS company has pricing power. Priority should be given to whether customers are expanding purchases, whether AI features are separately monetized, and whether sales and R&D; expenses can decline in tandem.
Consumer Electronics / Smart Vehicles
Apple
1) Shares rose 1.76% on the day, making Apple one of the few technology leaders to outperform the broader decline, but the stock has already gained 11.31% over 20 days, suggesting expectations are elevated.
2) Industry sources believe the price increases already passed through have only mitigated margin erosion rather than protected margins, while further increases could again hurt demand. Jefferies also noted that Apple Intelligence lacks application data.
“The price increases Apple has already passed through cannot protect its margins; they have merely mitigated the damage. Further price increases are also highly likely.”
Tesla
1) The production-spec 2026 Semi will be showcased near Chicago on July 20–21 and exhibited in Virginia on July 21–23, marking a milestone in bringing the commercial-vehicle product closer to customers.
2) Model 3 and Model Y orders have opened in Uruguay, making it the third South American market where Teslas are available for purchase.
3) Tesla Semi: A public showcase does not mean large-scale deliveries have begun, but the “production-spec” designation at least advances the vehicle from development toward customer validation. The most useful subsequent metrics will be monthly production, signed orders, deliveries, per-vehicle cost, and charging-infrastructure investment. Until these figures are available, the exhibitions should not be treated as earnings delivery.
“Tesla plans to exhibit the vehicle at the Mid-Atlantic Clean Cities and Communities Advanced Transportation Summit and Expo in Harrisonburg, Virginia, on July 21–23.”
Intuitive Surgical: Q2 revenue was $2.89 billion, above the $2.82 billion consensus estimate and up 19% year over year. Adjusted EPS was $2.80, ahead of the $2.51 estimate and up 28% year over year, while adjusted operating profit was $1.22 billion. The earnings beat included an $0.08 benefit from tariff refunds, which should be separated from recurring growth.
“Q2 2026 highlights — Revenue: $2.89 billion versus $2.82 billion expected; up 19% year over year.”
Aina: Raised $5.5 million to develop a new AI interaction interface beyond keyboards and touchscreens. The founder has 10 years of hardware experience and previously developed the Ring AIR and the context-aware Dune keyboard. The product remains in confidential development, with its form factor, mass-production readiness, user demand, and commercialization prospects all unconfirmed.
Intel Notebook Supply Chain: Some wafers were patterned using a $380 million High-NA scanner, and the related notebook chips have begun shipping to customers. This moves advanced lithography from test chips into end products, but the chip models, notebook brands, shipment scale, and mass-production yields have not been disclosed.
Nvidia and Sega: The Tokyo event only confirmed that the two companies appeared together. Historical information also shows that Sega invested $5 million in Nvidia in the 1990s. No products, orders, revenue, or timetable for any new collaboration have been disclosed, so this remains only an event-related signal.
AeroVironment: Market reports indicate that the company may be discussing a contract with the U.S. Army. A potential contract could serve as an event-driven catalyst for unmanned systems and intelligent equipment, but the language remains tentative. The contract value, products, progress, and signing date are all undisclosed and should not be treated as an order before an official announcement.
“AVAV is reported to ‘possibly’ be discussing a contract with the Army. A potential contract could provide an event-driven catalyst, but the wording is clearly uncertain, and the original report disclosed no contract value, products, progress, or signing date.”
On-Device AI Application Ecosystem: Jefferies views Apple’s lack of application data as a key issue, implying that competition in on-device AI extends beyond model parameters to application usage, developer ecosystems, and user feedback. If price increases are not accompanied by application penetration, both margins and demand could come under pressure.
Robotic Surgery: Intuitive Surgical exceeded revenue and profit expectations, but Q2 EPS included an $0.08 benefit from refunds of previously paid tariffs. When assessing operating acceleration, this one-off benefit should be separated from adjusted growth, while da Vinci procedure volumes, installed systems, and consumables revenue should be monitored.
New AI Hardware: Aina’s $5.5 million financing demonstrates that investors remain willing to buy optionality on new forms of human-machine interaction. However, the failures of Humane and Rabbit show that novel demonstrations do not necessarily translate into high-frequency demand. Beyond the team’s track record, investors need to monitor product form factor, battery life, pricing, subscription model, and return rates.
“He has now raised $5.5 million to build a new interaction interface beyond keyboards and touchscreens.”
Commercial Vehicles and Energy Infrastructure: The Semi’s two showcases will bring the vehicle in front of fleet operators and clean-transport customers, but operating economics will still depend on vehicle price, energy consumption, payload, maintenance, and charging infrastructure. For the supply chain, exhibitions are only a customer-acquisition entry point; production cadence and repeat purchases by heavy-truck customers will ultimately determine revenue.
On-Device AI Interaction: Apple’s on-device AI and Aina’s new interface point to the same business question: whether customers will continue paying for more natural forms of interaction. Apple has a large installed device base but lacks application data, while Aina has hardware experience but no product. For Apple, watch penetration; for Aina, first assess whether the product launches on schedule.
Consumer-Electronics Pricing: Apple’s risk profile highlights a common challenge for hardware companies: when costs rise, price increases can protect revenue but may also reduce demand, while holding prices directly compresses gross margin. Investors should monitor four metrics: average selling price, unit sales, gross margin, and channel inventory. Revenue growth alone is insufficient to demonstrate successful pricing.
Consumer Electronics and Smart-Vehicle Performance: Apple rose 1.76% while Tesla fell 0.86%. Their divergent performance despite both being consumer-facing hardware companies shows that product milestones do not automatically translate into share-price catalysts. For Apple, monitor average selling price and gross margin; for the Tesla Semi, monitor orders, monthly production, and deliveries. A single exhibition cannot substitute for operating execution.
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio
Related Reading
404K SEMI-AI Morning Brief — July 11, 2026 — Meta Leads Gains, Memory Pricing Power Strengthens, AI Bottlenecks Spread to Interconnects and Power404K SEMI-AI Morning Brief — July 17, 2026 — Model Catch-Up Accelerates, Compute Supply Remains Tight, Tech Momentum Pulls Back
目录
Post-Market Summary
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capex
CSP/Cloud Capex and AI Cloud
GPUs, CPUs, ASICs, and High-Speed Interconnects
HBM/DRAM/NAND/SSD/HDD, Equipment, and Optical Communications
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio
Demand for AI applications and infrastructure has not weakened, but the market has shifted from rewarding growth alone to scrutinizing margins, returns on capital, and supply delivery. Kimi K3, GPU rental rates, memory price increases, and EUV orders continue to provide positive evidence, while the broad sell-off in semiconductor and neocloud names reminds investors that even good businesses must be bought at the right price.
404K SEMI-AI | July 17, 2026
Post-Market Summary
The U.S. technology trade cooled markedly. The S&P; 500 fell 0.54% and the Nasdaq 100 declined 1.71%, while the equal-weighted S&P; 500 rose 0.98%, indicating a rotation from high-beta technology into the broader market. The VIX rose 9.00%, suggesting this was not merely an adjustment in individual names but also a tightening in risk appetite.
Semiconductors were at the center of the pressure: SMH fell 3.70% and SOXX declined 4.54%. Their 20-day returns were -7.64% and -10.35%, respectively, with RPS20 readings of just 11.1 and 3.7. The software ETF fell only 0.26% and remained up 2.55% over 20 days, indicating that the day’s valuation compression was concentrated in hardware, memory, and neoclouds.
Fundamentals diverged sharply from market performance. Google Cloud backlog, GPU rental rates, DRAM contract prices, and EUV orders continue to point to robust demand, yet Micron, Sandisk, Seagate Technology, Marvell, and Nebius all sold off sharply. The focus now shifts to order conversion, capacity ramp-up, and margins; demand narratives alone are no longer sufficient.
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capex
Kimi K3: Capabilities are catching up rapidly, but deployment economics have yet to be demonstrated in parallel. The model has 2.8tn total parameters and a 1mn-token context window. It scores 57 on the Artificial Analysis Intelligence Index, 1,668 Elo on GDPval v2, and 53% on AutomationBench-AA, ranking No. 1; cost per task is $0.94, and model weights have not yet been released.
“Kimi K3 has 2.8tn parameters, an index score of 57, a GDPval v2 Elo rating of 1,668, and an AutomationBench-AA score of 53%.”
OpenAI
1) The ChatGPT custom-instruction limit increased from 1,500 to 5,000 characters, expanding capacity for personalized interactions.
2) Its research collaboration with Chip Ganassi Racing has expanded to developing track-data tools using ChatGPT and Codex, but no data on revenue or decision-making efficiency has been disclosed.
“How racing teams use AI to identify marginal differences in track data that influence outcomes and convert data into decisions more quickly.”
Anthropic: The investment implications are shifting from model capabilities toward commercialization and capital efficiency. Reports that the company is nearing profitability, together with supply-constrained GPT-5.6 compute and Codex users increasing from 5mn to 9mn in one month, support an extended inference-demand cycle. The risk is that specific profit, cash-flow, and credit terms remain undisclosed.
Enterprise AI Buyers: Procurement rules are beginning to shift from “deploy first” to “prove results first.” Vendors are moving toward usage-based pricing, while buyers allocate tasks to cheaper models and cap employee spending; only 11% of agentic-AI pilots have reached production. Utilization rates and unit costs are the next metrics to watch.
“Buyers are assigning tasks to cheaper models, limiting employee spending, and demanding evidence of results before scaling deployments.”
Healthcare AI: Verifiable efficiency metrics are emerging. UnitedHealth reduced prior-authorization processing from eight hours to less than 30 seconds; Eli Lilly is running drug-discovery workloads on an NVIDIA-powered AI supercomputer; and Sanofi and Mayo Clinic have embedded AI into sales preparation and clinical documentation, respectively.
CSP/Cloud Capex and AI Cloud
Google
1) 2026 capex guidance increased from $175–185bn to $180–190bn, with $35.7bn already spent in the first quarter.
2) Cloud backlog stands at $462bn, with more than 50% expected to convert within 24 months. Gemini 3.5 Pro missed its target for the third time, showing that strong compute demand does not eliminate product-execution risk.
“Internal compute demand is now competing with external enterprise customers for GPU time within Google’s own infrastructure.”
Meta: Its plan to double data-center deployments in 2027 provides a medium-term anchor for memory, interconnect, and power demand. Meta is also reportedly the sole buyer of active copper cables using Maxim analog chips, with three other cable vendors having completed qualification. This is a supply-chain indicator that still requires confirmation through orders and revenue recognition.
CoreWeave: B200 rental rates reached $6.83 per hour in June, up 25% from early May, while the 30-day trend points to $8.54 per hour. The company operates sizable B200 and GB200 clusters and should theoretically benefit as the rental-rate gap between new and previous-generation GPUs narrows. However, rental-rate trends, utilization, and financing costs remain critical to cash flow.
Nebius
1) Like CoreWeave, Nebius benefits from B200 deployments and improving rental rates, but its 13.90% decline during the session highlights trading risk that is materially greater than the smoothness implied by industry data.
2) The company plans to transition fully to post-quantum cryptography in 2026 or 2027, but partners and investment scale remain undisclosed.
“The bear case for neocloud providers has consistently been that oversupply would destroy pricing, but this chart shows that precisely the opposite is occurring.”
CleanSpark: Its first colocation lease provides tangible evidence on asset returns. The tenant was not disclosed but is reportedly investment grade; the 20-year agreement uses a triple-net lease structure, and the author estimates a cost yield of approximately 12.8%. Project costs, rent, power capacity, and delivery timing still need to be verified.
GPUs, CPUs, ASICs, and High-Speed Interconnects
NVIDIA
1) It is working with Japan to build a national AI factory for physical AI, targeting manufacturing, logistics, transportation, healthcare, telecommunications, and power-grid optimization. Project investment, GPU configuration, and construction timelines were not disclosed.
2) The “gigawatt economics” model indicates that GPU performance must translate into effective throughput and gross profit per active MW to generate returns.
Intel
1) Expanded its multiyear partnership with Google Cloud, using Gemini Enterprise across engineering, supply chains, and chip design, while C4 and N4 instances supplement on-premises high-performance computing.
2) A High-NA process layer completed dual qualification in Oregon, and notebook chips partly patterned using a $380mn High-NA scanner have been delivered to customers.
Marvell: The new Teralynx T100 is a 3nm, 102.4T data-center switching ASIC designed to reduce power consumption, system complexity, and latency in AI training and inference. The company claims it delivers “the industry’s lowest latency,” but disclosed no latency figures, customer validation, mass-production timeline, or orders.
Maxim: Three supply-chain indicators warrant tracking: Meta’s active-copper-cable procurement, an on-board linear-equalizer platform at another major hyperscaler, and an approximately 50% share in 800G TIAs alongside design wins for 1.6T modules. All are based on industry checks and require confirmation through company disclosures on orders, customers, and revenue.
GPU Rental Market: H100 forward rental rates rose 40% in the first half of 2026, while B200 rates increased 27%. B200 performance is approximately 1.8–2.5x that of H100, versus rental rates of roughly 1.75x, resulting in more favorable per-token economics. This suggests previous-generation supply is being absorbed, but rental rates are only a real-time signal and cannot substitute for cluster utilization and cash payback.
HBM/DRAM/NAND/SSD/HDD, Equipment, and Optical Communications
Micron
1) Bank of America expects DRAM average selling prices to rise 21% quarter over quarter in the third quarter, while its survey indicates server DRAM contract prices will increase 20–30% quarter over quarter, led by high-speed LPDDR5.
2) Bank of America said urgent OEM orders confirm quarter-over-quarter price increases exceeding 20% for both commodity DRAM and NAND, while orders are also shifting from HBM3e toward higher-priced HBM4.
“NAND recovery: NAND spot prices have rebounded, driven by a 4% week-over-week increase in 1Tb wafer prices, supporting expectations for NAND ASP growth of more than 10% in 3Q.”
SK Hynix and Samsung Electronics: Memory trades experienced sharp deleveraging despite strong fundamentals. Weekly inflows into Korean ETFs reached $814mn and $1.1bn in succession, as some investors used them as substitutes for SK Hynix ADRs trading at an approximately 25% premium. However, the SK Hynix ADR fell 13.69% during the session, indicating that positioning concentration has become a risk factor.
Sandisk, Seagate Technology, and Western Digital: The three memory and storage names fell 12.63%, 10.00%, and 9.15%, respectively, although industry indicators have not weakened in parallel. Bank of America said 1Tb NAND wafer prices rose 4% week over week, supporting third-quarter NAND ASP growth above 10%; Seagate’s nearline product prices are expected to increase approximately 7% quarter over quarter.
ASML: EUV translates advanced-node demand into trackable equipment volumes. The 2026 shipment outlook is approximately 65 systems, excluding High-NA, rising to around 85 in 2027, with the required orders nearly fully booked. Upstream capacity at Carl Zeiss SMT is a leading indicator of the shipment ceiling, while 90 systems remains only a potential upside scenario.
“The company’s 2026 guidance is already close to the author’s forecast of 67 systems, while the 2027 order position is increasingly validating the ‘sold-out’ assessment.”
UMC and Tower Semiconductor: The bottleneck in optical-communications expansion is shifting from the availability of 300mm capacity to customer qualification, yields, and ramp speed. Tower Semiconductor has signed contracts corresponding to $1.3bn of silicon-photonics revenue in 2027 and received $290mn in capacity-reservation payments; additional supply could also reduce average selling prices for PIC wafers.
“Silicon can be used to manufacture modulators, waveguides, and detectors, but its indirect bandgap prevents it from generating laser light. Rising silicon-photonics penetration therefore still requires external InP continuous-wave light sources.”
Internet/Platforms
Netflix
1) Q2 revenue was $12.56 billion, up 13% YoY, with EPS of $0.80; operating margin was 33.4%, down 70 bps YoY, while free cash flow fell 33% YoY to $1.53 billion.
2) Q3 revenue guidance of $12.86 billion and EPS guidance of $0.82 were both below expectations. Growth continues, but the market is demanding stronger cash flow and guidance.
“Q2 revenue was $12.56 billion, up 13% YoY; EPS was $0.80, up 11% YoY; and operating profit was approximately $4.19–4.20 billion, up 11% YoY.”
Streaming Advertising Technology: Incremental growth in mature markets must come from advertising and new interactive formats. Advertising spend on Netflix’s platform grew 15%–30% YoY in Q2 2026, while integration between its in-house programmatic advertising system and Amazon DSP improved attribution. India and the Philippines are key execution variables for achieving the $3 billion target.
Google: Shares fell 4.44% on the day amid both model delays and higher capital expenditure. Management’s long-term investment thesis is that revolutionary technologies cannot be built solely through incremental improvements. Investors should test this thesis against cloud backlog conversion, Gemini adoption, and returns on capital.
“The central tension is the information gap between the necessity of long-term investment and the verifiability of near-term financial returns.”
Meta: Shares fell 2.46% on the day, but capital expenditure signals still point to a doubling of data-center deployments in 2027. The key issue for the platform is not merely recommendation quality and advertising effectiveness, but whether greater investment can translate into model usage, advertising monetization, and longer user engagement.
Amazon: Its DSP integration with Netflix makes measurement and attribution easier for advertisers, showing that Amazon’s platform value has expanded from media buying to streaming monetization. Advertising volume, take rates, and conversion rates were not disclosed, so only the strategic direction of the partnership can be confirmed at this stage; revenue sensitivity cannot yet be extrapolated.
Uber: The proposed $14.8 billion acquisition of Delivery Hero shifts platform competition from drivers and users toward regional supply consolidation. Shares rose 1.89% on the day, but the transaction structure, financing, antitrust approval, and Year 3 EPS contribution are the real validation points.
“Uber’s proposed $14.8 billion acquisition, the Netskope price-target increase, and expectations of continued ARK buying constitute positive event signals, but the report lacks comprehensive fundamental validation.”
Duolingo: Morgan Stanley reiterated its “Equal-weight” rating on July 17 and raised its price target from $95 to $125. The firm remains tactically optimistic about Q2, believing momentum in users, bookings, and EBITDA is driving an inflection. The risk is that the rating remains neutral rather than positive.
Truth API: The service plans to open its proprietary content data feed to institutional clients beginning in August, demonstrating how social content can evolve from a traffic product into a data product. However, the operator, pricing, number of institutional clients, and revenue contribution were not disclosed. Whether exclusivity can generate recurring revenue will depend on subscription conversion.
X Platform: Creator rewards are beginning to provide real income, but the feed mechanism also encourages users to split long-form articles into more than ten posts and repeatedly refresh the feed. Since ordinary creators struggle to publish 20–30 high-quality standalone posts each day, the conflict between incentives and content integrity could damage the user experience.
“The rewards and feed mechanisms encourage users to split a complete long-form article into more than ten posts and compete for attention through constant posting, ultimately damaging the user experience and diluting genuinely valuable content.”
ChatGPT Work: New workflows for creating and editing documents, spreadsheets, and presentations move the platform from a conversational interface into office productivity workflows. The product direction is clear, but account availability, usage rates, export success rates, and paid conversion were not disclosed. Activity levels must confirm whether it is genuinely diverting usage from traditional office software.
Public-Market AI Platforms: Google fell 4.44% on the day, while private model companies have temporarily avoided real-time pricing pressure. This does not prove that private-company valuations are more stable; it only shows that public markets reflect product delays, capital expenditure, and monetization concerns in prices more quickly.
Platform Advertising Buyers: Growth in Netflix advertising spend and its Amazon DSP integration show that advertisers are willing to pay for better measurement and attribution. Premium CPMs are beginning to normalize, which should support broader customer coverage. If advertising revenue cannot offset content costs, however, platform margins will remain under pressure.
Model-Hosting Platforms: Enterprises unable to absorb approximately $6 million in spending to self-host GB300 systems will turn to cloud hosting. When open models are priced similarly to leading proprietary models, customers are buying more than model weights: they are also paying for support, sales coverage, stability, and the deployment ecosystem. This will concentrate value among leading cloud platforms.
“When open models are priced the same as models from leading cloud-based AI labs, why should I use an open model?”
Frontend Generation Platforms: Models capable of generating attractive websites, SVGs, and three.js worlds are more likely to spread online, but visual appeal does not imply superior underlying reasoning. From an investment perspective, customer-acquisition efficiency must be assessed separately from task success rates; otherwise, the market may mistake a one-off demonstration for general capability.
Platform Risk Appetite: High-valuation platforms are not facing a uniform deterioration in fundamentals. Instead, investors’ tolerance for weak cash flow, acquisition premiums, and capital expenditure is declining simultaneously. Long-term investment will translate back into earnings evidence only if Netflix repairs free cash flow, Uber demonstrates transaction accretion, and Google converts cloud backlog on schedule.
Software/SaaS
Netskope: KeyBanc maintained its “Overweight” rating on July 17 and raised its price target from $14 to $16, citing momentum in cloud security and AI networking platforms. Shares rose against the market on the day, but the upside implied by the price target cannot substitute for validation through bookings, net retention, and free cash flow.
“KeyBanc maintained its ‘Overweight’ rating on Netskope and raised its price target from $14 to $16, implying approximately 21% upside.”
Cloudflare: Developers used React, Hono, and Cloudflare Workers to consolidate a lightweight AI web application into one port and one Worker. After merging requests, deployment took less than 60 seconds and cost $5 per month. This demonstrates that edge platforms can lower the launch threshold for small applications, but high concurrency, databases, and enterprise security remain unvalidated.
“A React frontend, Hono routing, and Cloudflare Workers can form an integrated single-port development and single-Worker deployment solution, enabling deployment in under 60 seconds and an always-on, globally distributed service for $5 per month.”
Gemini 3.5 Pro: The release is already several months behind schedule and has missed its target for the third time. The team is improving coding performance, hallucination rates, and reliability while considering an interim Flash release. This is a negative execution signal in AI software competition; the next validation points are a new release date, developer retention, and hallucination rates.
“Google Gemini 3.5 Pro was delayed by several months because its coding capabilities and overall technical performance fell short of targets.”
ChatGPT: The custom-instruction limit was increased from 1,500 to 5,000 characters, directly expanding the long-term preferences, task constraints, and output formats users can preset. The feature expansion is clear, but supported platforms, account availability, usage frequency, and subscription conversion were not disclosed.
AI Cybersecurity: Generative AI lowers the barrier to sophisticated attacks, and the global cybersecurity market is expected to exceed $350 billion by 2030, representing a 9.1% CAGR from 2025 to 2030. Spending is growing fastest in healthcare, financial services, and insurance. The market opportunity must be validated through renewals, customer retention, and reductions in security incidents.
“Accordingly, the global cybersecurity market is expected to exceed $350 billion by 2030.”
Wiz: Google’s $32 billion acquisition of Wiz shows that cloud security has become a platform-level asset. The investment implication is that as AI workloads increase, identity, configuration, and data risks become more concentrated. However, regulatory approval, integration costs, revenue synergies, and customer overlap still require company disclosure.
Armis: ServiceNow’s $7.8 billion acquisition of Armis embeds cybersecurity capabilities into enterprise workflows. Together with the Wiz acquisition, the transaction shows that security is no longer a standalone tool but a default layer within cloud and workflow platforms. Key follow-up metrics include post-transaction product bundling, customer cross-selling, and gross margin.
ServiceNow: While expanding its security perimeter through Armis, the platform must also demonstrate whether AI monetization can exceed acquisition and R&D; costs. The relevant metrics are not the “AI narrative,” but penetration of products such as Pro Plus, seat expansion among large customers, security-product attach sales, and free cash flow.
Palo Alto Networks: The expanding attack surface and demand for agent governance make cybersecurity a necessary complement to AI investment. Shares fell 0.25% on the day but rose 26.16% over 20 days, placing relative strength among the highest in the peer group. The key question is whether platform bookings, remaining performance obligations, and margins can support the valuation.
CrowdStrike: Endpoint, cloud, and identity data have direct value for detecting AI-enabled attacks. Shares fell 1.46% on the day but remained up 19.95% over 20 days, indicating that the market continues to assign a premium to cybersecurity. Investors should focus on net new ARR, module expansion, and sales efficiency rather than industry growth alone.
Datadog: Survey results continue to support growth above 30% in 2026, but the forward spending score fell from 5.4 to 2.0, while the valuation approaches 20 times revenue and 75 times free cash flow. Business performance will depend on cloud consumption, incremental purchases by large customers, and revenue from new AI products. If spending intentions continue to cool, the high valuation will amplify expectation gaps.
“Datadog survey results continue to support growth above 30% in 2026, but the forward spending score fell from 5.4 to 2.0, while the valuation approaches 20 times revenue and 75 times free cash flow.”
Post-Quantum Cryptography Software: Nebius has provided a 2026–2027 timeframe for full migration, moving security demand from a research topic toward cloud-infrastructure implementation. However, the algorithms, key management, migration scope, and vendors have not been confirmed. At this stage, the investable signal is that demand exists—not that any specific company has already secured orders.
Aehr Test Systems: Freedom Broker upgraded the stock to “Buy” on July 17 and raised its price target from $90 to $110. The firm views FY2027 guidance as a timetable for order conversion, supported by record orders and a strong backlog. However, order value, backlog size, and the pace of revenue conversion were not disclosed.
Sparse Mixture-of-Experts Model Services: The model activates 16 of its 896 experts per inference, representing an activation rate of approximately 1.7%. Service pricing is $3/$15 per million tokens, and inference gross margins are reportedly 75%–85%. These figures suggest attractive unit economics, but the provider, pricing basis, and cost definition are unclear, preventing direct profit extrapolation.
Software Spending Selection: The software ETF fell only 0.26% on the day and rose 2.55% over 20 days, significantly outperforming semiconductors. Relative sector strength does not mean every SaaS company has pricing power. Priority should be given to whether customers are expanding purchases, whether AI features are separately monetized, and whether sales and R&D; expenses can decline in tandem.
Consumer Electronics / Smart Vehicles
Apple
1) Shares rose 1.76% on the day, making Apple one of the few technology leaders to outperform the broader decline, but the stock has already gained 11.31% over 20 days, suggesting expectations are elevated.
2) Industry sources believe the price increases already passed through have only mitigated margin erosion rather than protected margins, while further increases could again hurt demand. Jefferies also noted that Apple Intelligence lacks application data.
“The price increases Apple has already passed through cannot protect its margins; they have merely mitigated the damage. Further price increases are also highly likely.”
Tesla
1) The production-spec 2026 Semi will be showcased near Chicago on July 20–21 and exhibited in Virginia on July 21–23, marking a milestone in bringing the commercial-vehicle product closer to customers.
2) Model 3 and Model Y orders have opened in Uruguay, making it the third South American market where Teslas are available for purchase.
3) Tesla Semi: A public showcase does not mean large-scale deliveries have begun, but the “production-spec” designation at least advances the vehicle from development toward customer validation. The most useful subsequent metrics will be monthly production, signed orders, deliveries, per-vehicle cost, and charging-infrastructure investment. Until these figures are available, the exhibitions should not be treated as earnings delivery.
“Tesla plans to exhibit the vehicle at the Mid-Atlantic Clean Cities and Communities Advanced Transportation Summit and Expo in Harrisonburg, Virginia, on July 21–23.”
Intuitive Surgical: Q2 revenue was $2.89 billion, above the $2.82 billion consensus estimate and up 19% year over year. Adjusted EPS was $2.80, ahead of the $2.51 estimate and up 28% year over year, while adjusted operating profit was $1.22 billion. The earnings beat included an $0.08 benefit from tariff refunds, which should be separated from recurring growth.
“Q2 2026 highlights — Revenue: $2.89 billion versus $2.82 billion expected; up 19% year over year.”
Aina: Raised $5.5 million to develop a new AI interaction interface beyond keyboards and touchscreens. The founder has 10 years of hardware experience and previously developed the Ring AIR and the context-aware Dune keyboard. The product remains in confidential development, with its form factor, mass-production readiness, user demand, and commercialization prospects all unconfirmed.
Intel Notebook Supply Chain: Some wafers were patterned using a $380 million High-NA scanner, and the related notebook chips have begun shipping to customers. This moves advanced lithography from test chips into end products, but the chip models, notebook brands, shipment scale, and mass-production yields have not been disclosed.
Nvidia and Sega: The Tokyo event only confirmed that the two companies appeared together. Historical information also shows that Sega invested $5 million in Nvidia in the 1990s. No products, orders, revenue, or timetable for any new collaboration have been disclosed, so this remains only an event-related signal.
AeroVironment: Market reports indicate that the company may be discussing a contract with the U.S. Army. A potential contract could serve as an event-driven catalyst for unmanned systems and intelligent equipment, but the language remains tentative. The contract value, products, progress, and signing date are all undisclosed and should not be treated as an order before an official announcement.
“AVAV is reported to ‘possibly’ be discussing a contract with the Army. A potential contract could provide an event-driven catalyst, but the wording is clearly uncertain, and the original report disclosed no contract value, products, progress, or signing date.”
On-Device AI Application Ecosystem: Jefferies views Apple’s lack of application data as a key issue, implying that competition in on-device AI extends beyond model parameters to application usage, developer ecosystems, and user feedback. If price increases are not accompanied by application penetration, both margins and demand could come under pressure.
Robotic Surgery: Intuitive Surgical exceeded revenue and profit expectations, but Q2 EPS included an $0.08 benefit from refunds of previously paid tariffs. When assessing operating acceleration, this one-off benefit should be separated from adjusted growth, while da Vinci procedure volumes, installed systems, and consumables revenue should be monitored.
New AI Hardware: Aina’s $5.5 million financing demonstrates that investors remain willing to buy optionality on new forms of human-machine interaction. However, the failures of Humane and Rabbit show that novel demonstrations do not necessarily translate into high-frequency demand. Beyond the team’s track record, investors need to monitor product form factor, battery life, pricing, subscription model, and return rates.
“He has now raised $5.5 million to build a new interaction interface beyond keyboards and touchscreens.”
Commercial Vehicles and Energy Infrastructure: The Semi’s two showcases will bring the vehicle in front of fleet operators and clean-transport customers, but operating economics will still depend on vehicle price, energy consumption, payload, maintenance, and charging infrastructure. For the supply chain, exhibitions are only a customer-acquisition entry point; production cadence and repeat purchases by heavy-truck customers will ultimately determine revenue.
On-Device AI Interaction: Apple’s on-device AI and Aina’s new interface point to the same business question: whether customers will continue paying for more natural forms of interaction. Apple has a large installed device base but lacks application data, while Aina has hardware experience but no product. For Apple, watch penetration; for Aina, first assess whether the product launches on schedule.
Consumer-Electronics Pricing: Apple’s risk profile highlights a common challenge for hardware companies: when costs rise, price increases can protect revenue but may also reduce demand, while holding prices directly compresses gross margin. Investors should monitor four metrics: average selling price, unit sales, gross margin, and channel inventory. Revenue growth alone is insufficient to demonstrate successful pricing.
Consumer Electronics and Smart-Vehicle Performance: Apple rose 1.76% while Tesla fell 0.86%. Their divergent performance despite both being consumer-facing hardware companies shows that product milestones do not automatically translate into share-price catalysts. For Apple, monitor average selling price and gross margin; for the Tesla Semi, monitor orders, monthly production, and deliveries. A single exhibition cannot substitute for operating execution.
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio