
404K SEMI-AI Morning Brief — July 11, 2026 — Meta Leads Gains, Memory Pricing Power Strengthens, AI Bottlenecks Spread to Interconnects and Power
目录
Post-Close Summary
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundries, Equipment, and Advanced Packaging
Optical Communications, High-Speed Interconnects, and Power
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Investment Bank Target Price Changes Over the Past 12 Hours
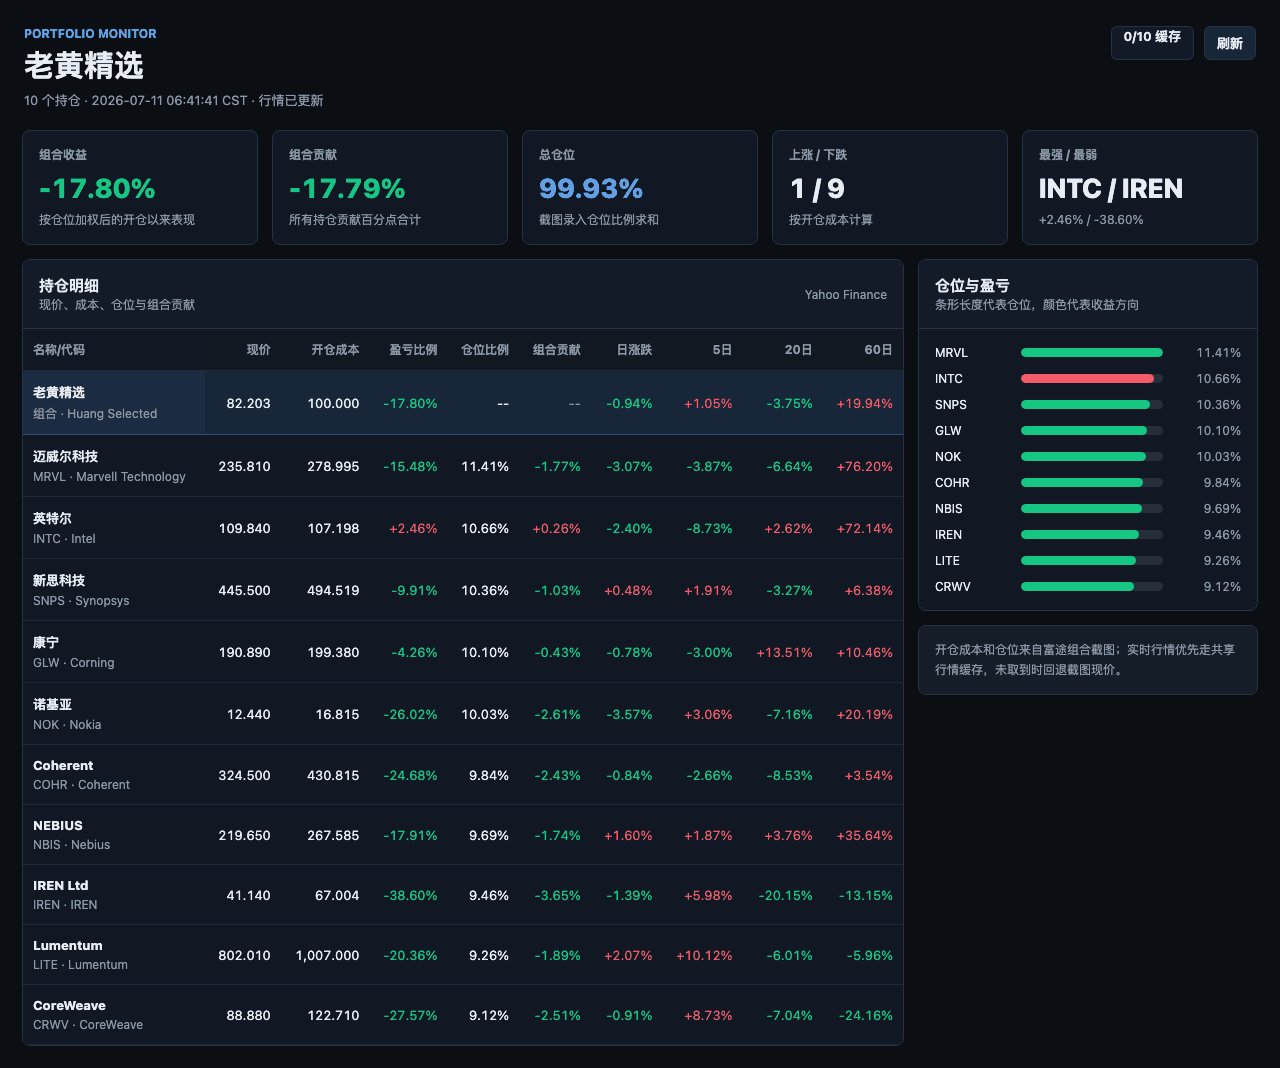
Huang’s Select Portfolio
U.S. equities edged higher, led by Meta and Nvidia, while software and cybersecurity remained under pressure. Industry developments were more concentrated: SK Hynix’s U.S. listing highlighted memory scarcity, Cerebras shifted the manufacturing bottleneck toward system assembly, and optical interconnects and power are beginning to determine whether incremental compute capacity can be delivered on schedule.
Post-Close Summary
As of the July 10 close, the S&P; 500 rose 0.45%, the Nasdaq 100 gained 0.37%, the Dow advanced 0.30%, and the Russell 2000 fell 0.42%. Technology rose 0.35% and communication services gained 1.02%; the semiconductor ETF advanced 0.54%, while the software ETF declined 1.65% and the cybersecurity ETF fell 2.52%. Capital continued to favor large AI platforms and hardware leaders.
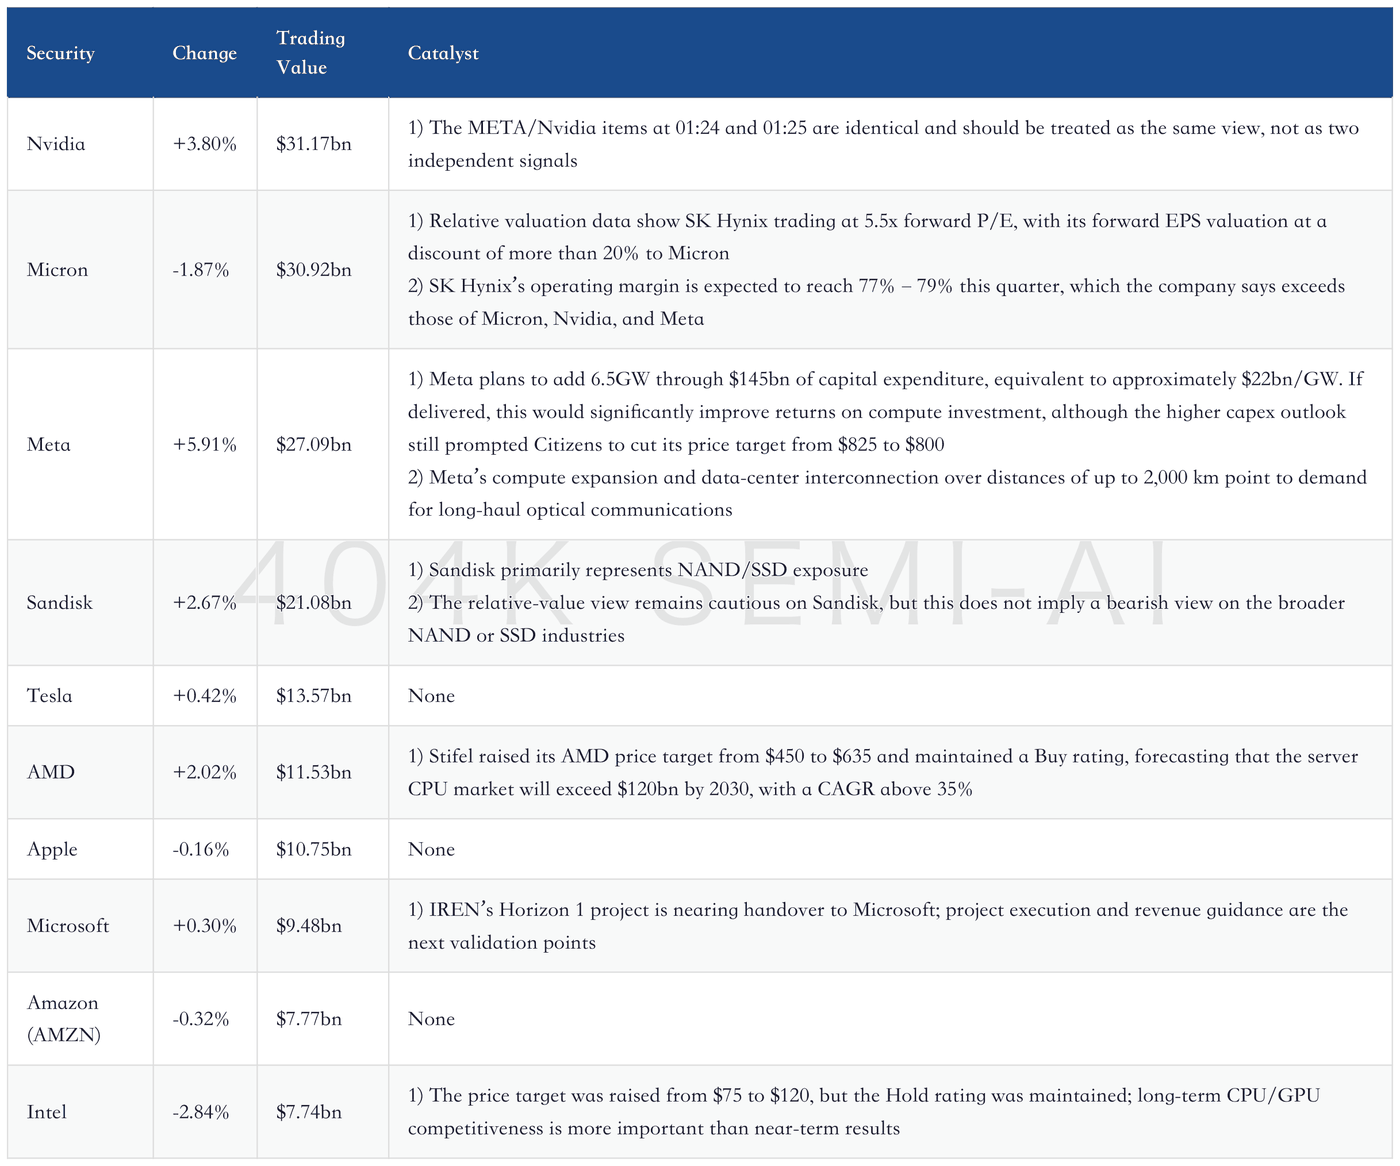
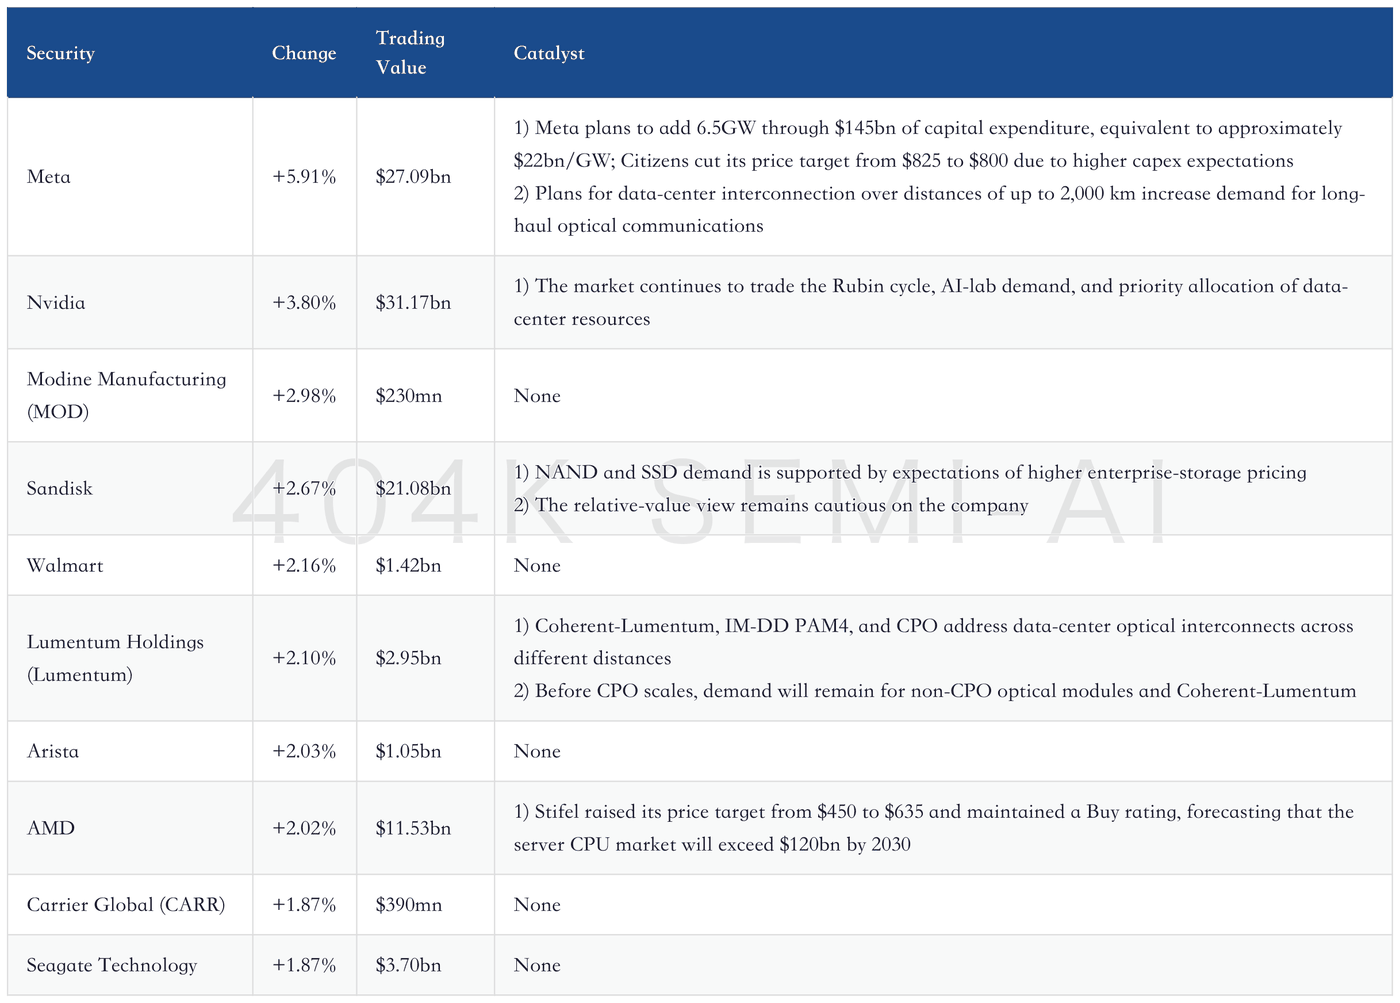
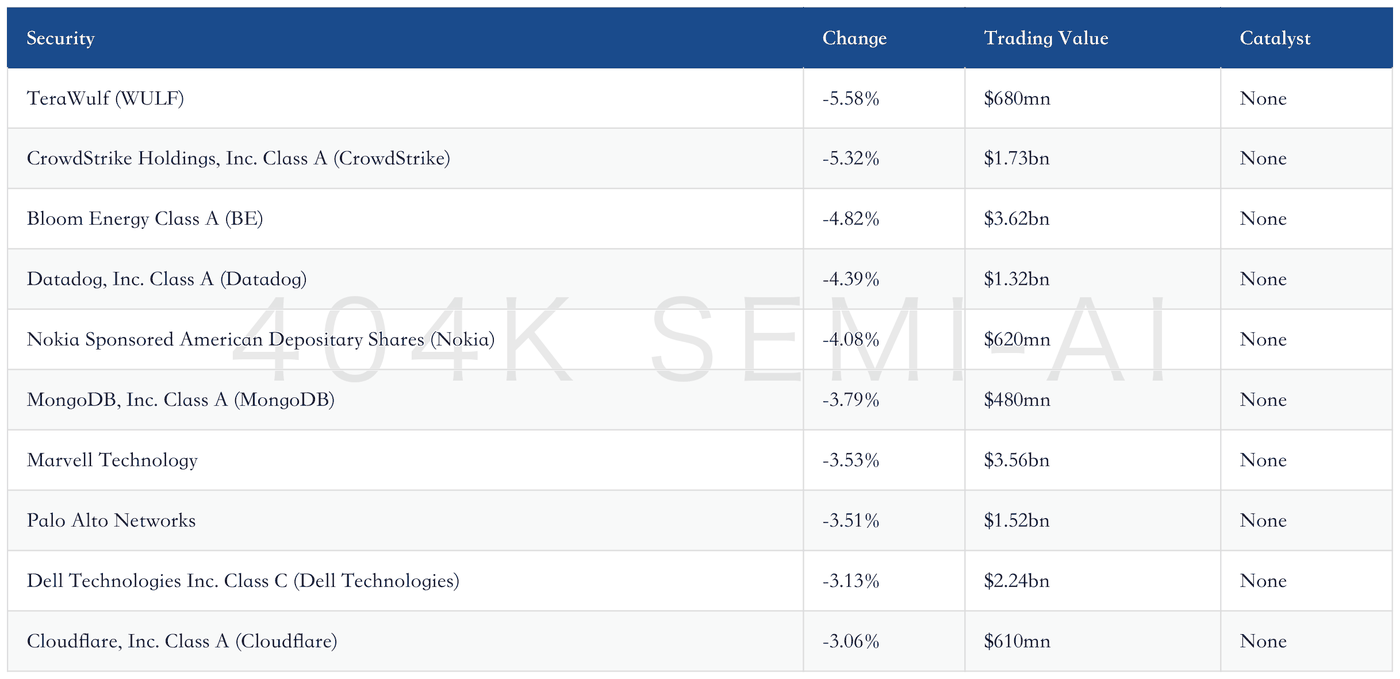
Dispersion among individual stocks was more pronounced than at the index level. Meta rose 5.94%, Nvidia gained 4.04%, and AMD advanced 2.04%; Oracle fell 2.46%, Marvell Technology declined 2.90%, MongoDB dropped 5.73%, and CrowdStrike lost 5.59%. The storage supply chain continued to outperform most software names, with Seagate Technology, Western Digital, and Sandisk up 11.64%, 18.71%, and 16.84%, respectively, over the past 20 days.
The day’s most important marginal change came from supply constraints. After pricing its ADR at $149, SK Hynix opened at approximately $170, while customer requests for memory supply reached five to six times existing plans. Compute demand is not stopping at GPUs: storage, advanced packaging, testing, optical interconnects, system assembly, cooling, and power are jointly determining project delivery timelines.
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
OpenAI
1) After integrating ChatGPT Work and Codex, traffic reached roughly twice its previous peak. The team scheduled two quota resets that day, with a larger fix planned for next week.
2) Apple has filed a lawsuit alleging that two former employees misappropriated trade secrets while helping OpenAI develop competing hardware. The case remains undecided; near-term focus should be on the product roadmap and talent-compliance costs.
“bringing ChatGPT and Codex together into a workspace where people and agents can collaborate”
Anthropic: Additional compute is translating into more generous usage quotas, with users reporting that the platform has become “noticeably more generous after gaining access to additional compute.” Demand still exceeds supply, but publicly cited ARR figures vary widely. More reliable near-term indicators are quotas, stability, paid-user retention, and inference cost per unit; revenue assessments should await standardized disclosure.
Tencent Hy3: The 295-billion-parameter MoE model activates 21 billion parameters per inference and supports a 256K context window. Pricing is US$0.14 per million input tokens and US$0.58 per million output tokens. Low pricing, sparse activation, and an open license shift competition away from parameter counts toward the capabilities, cost, and deployment convenience that customers actually value. Developer adoption and real-world task quality are the next key indicators.
“Cost-effectiveness is China’s true moat.”
CSP/Cloud Capital Expenditure
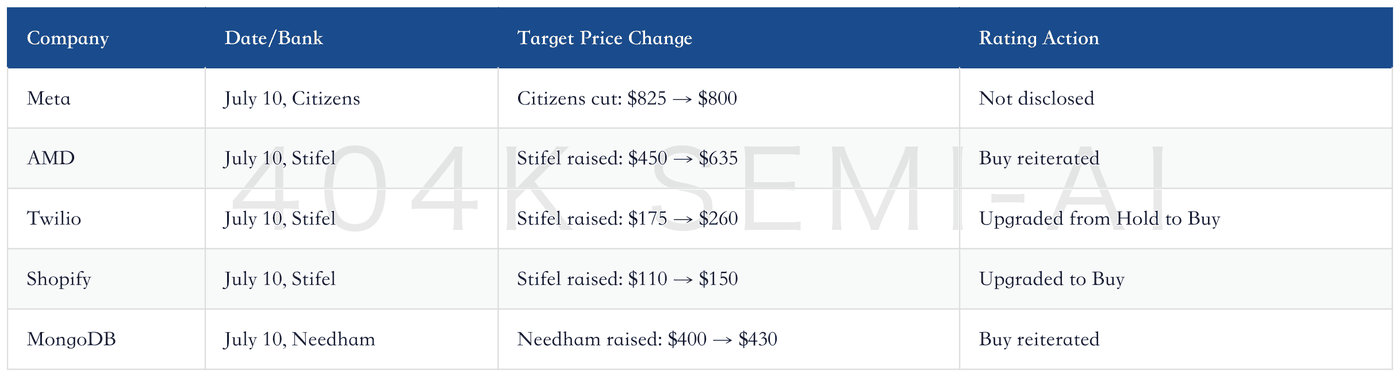
Meta: Shares rose 5.94%. Bank of America estimates approximately US$22 billion per GW based on US$145 billion of capital expenditure and 6.5GW of incremental capacity, maintaining its Buy rating and US$835 price target. Citizens lowered its target from US$825 to US$800 as investment continues to rise. The disagreement centers on unit capacity costs and the pace at which AI returns materialize.
“Meta views the API as a real business, not merely a learning exercise.”
Google: Google is moving the TPUv9 scale-up network toward 2.4T coherent-Lumentum, with Innolight supplying modules and Marvell providing custom DSPs. The solution covers distances of 2–20 kilometers, filling the gap between conventional IM-DD’s sub-2-kilometer reach and still-immature CPO. Watch for adoption at scale and optical costs.
Microsoft: FY25 electricity consumption increased 24% year over year to approximately 37TWh. The company reclaimed 690MW of stranded data-center power and extended low-power states to nearly four million unallocated servers. Compute expansion has entered a “secure power first, install equipment second” phase. Server utilization and PUE are more indicative of effective capacity than nominal GPU counts and will determine the payback period on incremental investment.
AI Cloud/Data-Center Operators
IREN: Horizon 1 is approaching handover to Microsoft, with the market citing a nine-day countdown. Reports indicate that 260MW of contracted capacity represents approximately US$14 billion in revenue, alongside a 5,500MW power pipeline. The latter is only developable resource potential and should not be treated as contracted orders. First monitor whether Microsoft’s acceptance and revenue guidance are updated concurrently, then assess project funding.
CoreWeave: After signing its first agreement with Meta in 2025, CoreWeave has expanded the relationship as capacity ramped. Meta also plans to double its compute capacity next year. Further expansion of the agreement is directionally plausible, but no incremental contract value has been disclosed. Assessment should focus on customer commitments, GPU deliveries, power access, financing costs, and utilization once capacity comes online.
WhiteFiber: First-quarter revenue was US$21.92 million, up 31% year over year, while colocation revenue rose 190.2% to US$4.77 million. The long-term target is 1.5GW. Current high growth is being driven by colocation, while the longer-term US$4 billion ARR figure remains an estimate. Key variables are NC-1 construction, financing, and the ability to deliver targeted revenue per MW.
“100% of our compute is allocated today”
GPU/CPU/ASIC
Nvidia: Shares rose 4.04%. Management said growth continued to accelerate even as quarterly revenue approached US$100 billion, with AI labs accounting for approximately 20% of total demand. Rubin Ultra remains scheduled to ship next year, while 800-volt architecture and inter-rack optical scale-up are progressing as planned. Changes to the Kyber form factor will continue to affect production scheduling for rack and interconnect suppliers.
“The memory shortage looks to last for several years”
AMD: Shares rose 2.04%. Stifel raised its price target from US$450 to US$635 and maintained its Buy rating, forecasting that the server CPU market will exceed US$120 billion by 2030, representing a CAGR of more than 35%. MI450, Helios, and a combined 6GW of commitments from OpenAI and Meta are catalysts; execution hinges on delivery and the software ecosystem.
Cerebras: The company signed a multiyear inference contract with OpenAI worth more than US$20 billion and covering 750MW. Its latest quarterly revenue reached US$193.4 million, up 94% year over year, while Flex plans to increase CS-3 capacity by approximately sevenfold. WSE-3 bypasses HBM and CoWoS but shifts the bottleneck to assembly of 23kW systems, with core gross-margin guidance reduced to 36%–38%.
HBM/DRAM/NAND/SSD/HDD
SK Hynix
1) The company issued 177.9 million ADRs at US$149 each, raising approximately US$26.51 billion. The offering was more than seven times subscribed, and the shares opened at approximately US$170.
2) Customers are requesting five to six times more supply, and management believes capacity would remain insufficient even if doubled over the next five years. Proceeds will fund the Yongin fab, P&T7; advanced packaging, and HBM expansion.
3) The risk is that high margins will ultimately induce additional supply. From 2027 to 2028, investors must assess capacity expansion alongside cloud capital expenditure.
“Demand is growing far faster than our ability to add supply.”
Nanya Technology: Second-quarter revenue was US$2.61 billion, up 68% sequentially and 684% year over year. Gross margin reached 79.5%, and ASP increased by more than 60% quarter over quarter, while bit shipments were flat sequentially. DDR4 and LPDDR4 contributed 60%–70% of revenue, indicating that traditional DRAM is also benefiting from pricing leverage as HBM crowds out leading-edge capacity.
Micron: TD Cowen reiterated its Buy rating and US$1,600 price target. Long-term strategic customer agreements are expected to cover nearly 50% of revenue, while tight supply and demand could persist beyond 2027. The company raised its US manufacturing investment target to US$250 billion. Order visibility is improving, but capital-expenditure payback, customer concentration, and a reversal in the memory cycle remain key risks to monitor.
Sandisk: Shares rose 3.32%, with trading value of US$21.08 billion. Enterprise SSD prices are expected to rise 18%–23% in the third quarter, supported by tight NAND supply. The relative-value trade remains short Sandisk and long SK Hynix, indicating that the market prefers HBM exposure and tighter supply control. Watch whether SSD pricing translates into realized earnings.
Foundries, Equipment, and Advanced Packaging
TSMC: The company plans to invest an additional US$20 billion in Arizona. AI/HPC demand is driving both advanced-node and CoWoS capacity. Constraints on capacity expansion have shifted from funding to equipment lead times, yields, power supply, and customer qualification. Whether the US fabs can achieve stable high-volume production will determine whether capital expenditure converts into revenue and will also affect localization costs and gross margins.
Samsung Electronics: The company is advancing a glass-interposer prototype, seeking to reduce silicon-interposer costs through improved flatness, lower warpage, and large-area processing. Multilayer RDL, TGV, and copper filling remain process challenges. Separately, the 4nm GAIA AI PC chip is scheduled for mass production as early as 2027. Foundry-customer trust, mass-production yields, and internal competition require monitoring; customer adoption will determine revenue.
Applied Materials: The price target was raised from US$530 to US$650. Memory expansion, advanced nodes, and packaging are jointly extending the WFE cycle, while equipment vendors benefit from procurement across multiple fabs. Risks include cleanroom expectations running ahead of demand, delayed order allocation, and customer pressure on pricing as equipment lead times lengthen. Monitor orders, revenue recognition, delivery cycles, and gross margin.
Cohu: The price target was raised from US$50 to US$70, based on the combined impact of AI-compute testing revenue and a semiconductor-cycle recovery. KYEC separately plans to invest up to US$1.4 billion in US testing facilities, although the location, timeline, and customers have not been confirmed. Monitor equipment orders, project commencement, testing revenue, and capacity utilization before assessing earnings leverage.
Optical Communications, High-Speed Interconnects, and Power
Marvell Technology: FY26 revenue was US$8.195 billion, up 42% year over year, with data centers accounting for 76% of sales. More than 50 custom AI ASIC projects are scheduled to enter production in FY2028–FY2029. The company spans copper interconnects, custom ASICs, and optics; the real risks are project-production timelines and long-dated assumptions for network TAM.
“If SerDes does not work, nothing else matters.”
Credo: Shares fell 3.03% but remained up 6.48% over five days. The company is developing both microLED and silicon photonics, while high-speed interconnect demand is supported by growth in XPU deployments. The number of transceivers per XPU could decline by 40%–50%. The key question is whether total XPU growth can offset lower content per unit and translate into orders and revenue.
Coherent: Communications revenue increased 55% year over year. Both long-haul DCI and CPO require capabilities in InP, lasers, detectors, and modules. Industry data indicate that relevant capacity remains tight, but meaningful CPO volumes may not emerge until 2029. Near-term growth depends more on pluggable coherent modules, conventional optical components, and inter-campus connectivity, while profitability hinges on InP supply.
Bloom Energy: Shares fell 4.82%. An order backlog of approximately US$20 billion and data centers’ need for rapid power deployment provide support, but short sellers have questioned the volume and sourcing of scandium oxide and the cost risks embedded in fixed-price contracts. The company says supply is sufficient to support 25GW of annual production, while external estimates put capacity below 2.5GW. Disclosure transparency will determine the valuation debate.
Vertiv: Data-center power and thermal management have become hard constraints on compute deployment. Incremental North American capacity is expected to increase from 8.9GW in 2025 to 10.3GW in 2026 and 12.1GW in 2027, with cooling becoming the primary bottleneck after 2028. Order conversion will depend on cooling-equipment manufacturing, EPC labor availability, grid interconnection, and equipment lead times.
Internet/Platforms
Meta: Up 5.94% on the day, 14.77% over five days, and 17.28% over 20 days. The platform’s rerating reflects a combination of improving model capabilities, advertising cash flow, and a potential cloud business. However, its enterprise software sales experience remains limited, the Muse model requires validation through sustained releases and customer migrations, and returns on capital expenditure must be confirmed by API revenue rather than the share price alone.
“enterprises aren't going to switch overnight”
“Meta has the clearest path among hyperscalers to close on OpenAI/Anthropic”
Google: Down 0.48% on the day. The market is simultaneously pricing in Gemini delays, model compliance, and TPU infrastructure advantages. If Meta closes the gap at the model layer, Google’s search cash cow will also face direct disruption from changing AI entry points. Google’s defense rests on coordination across TPUs, cloud, networking, and power; the key question is whether Cloud and Search can sustain growth above 20%.
Amazon: Down 0.69% on the day. AWS capital expenditure remains strong, but the company unexpectedly issued $25 billion of bonds, with 2.5x subscription and an additional concession of 18–21 basis points on longer-dated debt. AI buildout is beginning to consume bond-market capacity. Cloud revenue acceleration must offset higher financing costs, depreciation, and power expenses; RPO conversion is the next key indicator.
Microsoft: Up 0.19% on the day. If internal models can replace some third-party models within Copilot, Microsoft could reduce its dependence on OpenAI and Anthropic while strengthening usage-based pricing. Conversely, Xbox will eliminate 3,200 positions over the next 12 months, approximately 20% of its workforce, showing that platform subscriptions cannot be separated from content costs and retention.
Oracle: Down 2.46% on the day and 30.10% over 20 days. Together with Microsoft, Amazon, Meta, and Google, the company has issued $194 billion of bonds year to date, representing approximately 9% of investment-grade issuance. AI cloud orders and financing pressure are rising in tandem. Revenue recognition and capital-expenditure payback matter more than backlog alone, while project financing costs will also affect earnings.
Tencent: Hy3 is competing through low inference pricing and an open license, while the company is also in talks to become Manus’s largest shareholder while retaining a minority stake. The platform opportunity lies in synergies across models, social networks, and enterprise services. Cross-border investment remains subject to regulatory constraints; closing the transaction and preserving Manus’s operational independence are key validation points, while model usage and paid conversion will determine commercial value.
Alibaba: Its Singapore subsidiary reportedly has access to advanced overseas models, but OpenAI has suspended some affiliated API users over unauthorized use and suspected distillation. Cloud demand remains intact, but compliance boundaries will directly affect model access, R&D; costs, and the pace of international expansion. Access should not be equated with stable long-term supply; progress on proprietary alternatives is more important.
Baidu: Like Alibaba and Tencent, Baidu operates at the intersection of overseas model access and domestic model development. Available information does not disclose procurement amounts or usage volumes. For the platform, the key question is whether proprietary models can reduce external dependence and convert data from search, cloud, and enterprise customers into monetizable applications. Key indicators include usage growth, customer retention, inference costs, and margins.
Shopify: Stifel upgraded the stock to Buy and raised its price target from $110 to $150, seeing a path to revenue growth of 30% or more in 2026. Agentic commerce remains at an early stage; platform migration, B2B, international operations, and payments are more tangible growth drivers, while incremental AI value must be validated through merchant conversion.
“agentic commerce still in its infancy”
Letterboxd: The platform is seeking a sale and testing a valuation of $250 million. Membership exceeded 30 million as of June 2026. Its user base provides a foundation for a transaction, but the real value depends on engagement, advertising or subscription monetization, and whether a buyer can convert film and television interest data into recurring revenue. The transaction price still awaits confirmation.
Fox: Rothschild Redburn upgraded the stock from Neutral to Buy and raised its price target from $48 to $71; it forecasts an EPS CAGR of 23% from 2026 to 2030. Platform value derives from merger synergies and rapid deleveraging. Risks include extrapolating a low tax rate indefinitely, NFL renewal costs, and post-merger execution.
Cloud Platform Financing: Cash capital expenditure by the 11 largest cloud providers is expected to reach $632 billion in 2026, 4% above consensus. Hyperscalers have strong buildout intentions, but power, cooling, EPC capacity, and equipment constrain delivery. Platform revenue growth, free cash flow, and debt costs will become the next valuation divide, while also determining financing capacity and valuations.
“Cloud capex…100% to 115%+ of operating cash flow”
Cross-Border Model Access: Overseas model providers granting access to offshore subsidiaries of Chinese companies indicates that commercial demand and regulatory boundaries still leave some room. The suspension of affiliated API users also shows that distillation, customer identity, and end use can affect service continuity. Platforms need to budget for compliance, alternative models, and data migration while preparing contingency plans for service interruptions.
AI Advertising: Click-through rates for ads native to AI conversations are said to be four to five times the display-ad benchmark, suggesting that advertising could subsidize inference costs. This figure is based on application-level observations and still lacks validation through revenue and retention. Whether platforms can embed ads without impairing answer quality will determine inference monetization margins; advertiser repeat spending, user retention, and conversion rates also matter.
Local Model Platforms: Local and open-source models are narrowing the gap with proprietary cloud models, while sensitive data, low-latency requirements, and governance needs are driving enterprise deployment. Platforms will not converge on either cloud-only or edge-only architectures. The cloud will provide peak capabilities and scale, local models will address privacy, and routing layers will optimize costs. Enterprise procurement will compare maintenance complexity, security, and total cost of ownership.
“Many models are good enough for most work”
Software/SaaS
OpenAI Codex: In Q2 2026, LLM-based evaluation estimated that 8% of contributor-days completed more than 24 hours of human engineering work. The result shows that a small share of highly productive workdays has surpassed conventional time constraints, but it is not a rigorously controlled experiment. Software value still needs to be assessed through average team productivity gains, code quality, and paid conversion.
“In Q2 2026, 8% of contributor-days involved more than 24 hours worth of human engineering work”
Anthropic Claude: Claude’s coding experience has received strong retention feedback, but claims that “ARR will surge” still lack a disclosed base and paid conversion rate. On the product side, additional compute has improved usage allowances; commercially, usage volume, customer retention, inference costs, and gross margin all require validation. High-frequency use becomes SaaS revenue only when converted into recurring payments, while enterprise contract duration also warrants attention.
Twilio: Stifel upgraded the stock from Hold to Buy and raised its price target from $175 to $260. Its Conversations, Communications, and Data products are positioned to capture demand from voice agents. No breakdown of AI revenue or orders is currently available; key indicators include customer budgets, usage volumes, and post-restructuring margins.
“As voice agents proliferate…strengthening Twilio’s position as a critical infrastructure provider for agentic customer engagement.”
MongoDB: Needham maintained its Buy rating and raised its price target from $400 to $430. The company’s AI monetization has lagged Snowflake and Datadog because externally facing applications face a higher threshold for production deployment. Whether database usage accelerates as AI applications enter production is key to validating the higher price target.
Snowflake: Down 2.05% on the day but up 9.21% over 20 days. The market groups the company with Datadog and MongoDB as usage-based infrastructure software. Its relative strength suggests that AI data demand is already reflected in expectations, but confirmation still requires consumption revenue, customer expansion, unit economics, and net retention rather than share-price performance alone.
Datadog: Down 4.23% on the day but still up 13.17% over 20 days. Observability benefits from increasing complexity across models, agents, and data pipelines, but higher usage also raises customer bills. Whether vendors can make cost monitoring mission-critical while preserving net retention is a prerequisite for further valuation expansion; customer budgets remain a countervailing constraint.
Cloudflare: Down 2.47% on the day, up 10.97% over five days, and up 22.46% over 20 days. The edge cloud and AI network provide both inference distribution and a developer entry point, but available information contains no new orders. The share price reflects elevated growth expectations; key indicators include AI inference revenue, developer adoption, network costs, gross margin, and customer concentration.
CrowdStrike: Down 5.59% on the day but up 15.66% over 20 days. Agents, plugins, and MCP servers are expanding the attack surface, while enterprise deployment may outpace security reviews. The direction of security demand is clear, but the investment thesis still depends on platform consolidation, customer retention, incremental module revenue, and sales efficiency, with renewals as a key indicator.
“the attack surface is exploding”
Palo Alto Networks: Down 3.55% on the day but up 23.96% over 20 days. AI vulnerabilities and automated attacks increase the value of security platforms, while software consolidation may reduce budgets for point solutions. Whether the company can translate multi-product bundling into higher customer lifetime value is central to margins and valuation; renewal discounts also warrant attention.
Fable: After rewriting its Windows battery benchmark from Python and its dependencies in Swift, efficiency improved by 20–40x across most workloads. The case shows that AI coding can deliver runtime efficiency, not merely faster code generation. However, the benefits of reworking the language stack must still be separated from the model’s contribution, while code maintenance costs and migration complexity require validation.
WEKA: Discussion centers on AI memory, storage, and future architectures, indicating that software-defined storage is becoming a system-level issue for large-scale inference. The company has not yet disclosed customer, order, or performance data. Key indicators include whether bandwidth, latency, cost, and GPU utilization create measurable advantages, followed by the revenue opportunity, customer stickiness, renewal capacity, and profitability.
Manus: Tencent is in talks to become its largest shareholder while retaining a minority stake and allowing the company to operate independently in Singapore. Meta’s previous $2 billion acquisition plan was ordered to be unwound, showing that the technological value of agent assets and cross-border regulatory scrutiny are rising simultaneously. The transaction structure, independence, and approval conditions will determine closing probability, while product retention and revenue also require monitoring.
Inference Routing: New models are released every 41 days on average, and pricing differences widen rapidly when capabilities are comparable. Enterprises will route workloads among frontier, near-frontier, local, and open-source models based on the task. Routing software derives value from cost, latency, governance, and reliability, rather than a one-off benchmark ranking. Key indicators include retained usage, paid conversion, gross margin, customer expansion, and renewals.
“Inference emerged as the dominant market in AI”
Enterprise AI Adoption: Enterprise AI spending is highly polarized: the top 1% of monthly spenders invest $7,449 per employee, versus a median of just $11, a gap of approximately 650x. Software demand is not diffusing evenly, so sales strategies should first target high-value workflows. The cycle should be assessed through seat expansion, retention, and revenue per customer—not trials alone—while inference expenses also matter.
Video Generation Software: Content featuring people is subject to stricter filtering because of copyright, likeness, and deepfake risks, potentially reducing the product’s value proposition to scenic or graphical assets. Improving technical capabilities does not mean monetizable use cases will expand in parallel. Training-data licenses, permissions for depicting people, content provenance, and false positives in filtering will directly affect the revenue ceiling, customer renewals, enterprise adoption, and gross margin.
“As soon as a ‘human face’ appears in the video, the entire output is blocked.”
Consumer Electronics / Smart Vehicles
Apple
1) The bill of materials for the 12GB/1TB iPhone 18 Pro Max is expected to rise by nearly $300 versus the prior generation, with memory accounting for the largest increase; even with a $200 average price increase, gross margin could still be slightly lower.
2) The company has sued OpenAI, alleging that two former employees took trade secrets for a competing hardware venture; Jony Ive was not named as a defendant.
“Memory is the largest driver of the cost increase, followed by the latest 2nm SoC using advanced packaging.”
“OpenAI’s nascent hardware business…unlawfully relies on misappropriated trade secrets.”
“Even with a $200 increase in average retail price…gross margin is still expected to be slightly below that of the 2025 iPhone 17 Pro Max.”
Tesla
1) The company has begun dismantling the Model S and Model X production lines in Fremont to make room for Optimus, with planned capacity of 1 million units annually at full ramp, but no timeline for reaching that level.
2) In South Korea, FSD costs KRW 9.04 million as a one-time purchase or KRW 150,000 per month by subscription; the roughly 60-month static payback period highlights the company’s trade-off between upfront cash collection and adoption.
Samsung Electronics: The company is developing GAIA, a 4nm AI PC chip, with mass production possible as early as 2027. If the project proceeds, Samsung would be both a foundry and an AI PC chip competitor. Technology, customer trust, and resource allocation are the three key hurdles. No performance data, orders, or customers have been disclosed; watch for samples, mass-production yields, customer adoption, and power consumption.
Qualcomm: AI200 is scheduled to ship this year and AI250 in 2027. The company guides for data-center revenue to rise from $5 billion in FY2027 to more than $15 billion in FY2029. The handset business remains affected by rising memory prices; whether data-center products can become a second growth engine will depend on the software ecosystem, customer deployments, and revenue recognition.
Microsoft Xbox: The company plans to cut 3,200 jobs over the next 12 months, representing approximately 20% of its workforce. Game Pass subscriptions have fallen short of expectations, and bundling cannot eliminate the high investment, long development cycles, and uncertainty inherent in content production. Key metrics include user retention, revenue per user, content amortization, and studio restructuring; subscription pricing and content supply also require validation.
“The complete failure of the Game Pass strategy.”
Mitsubishi Motors: The company plans to work with Highlanders to deploy humanoid robotic workers by 2027. The timeline suggests automotive factories are moving from trials toward planned deployments. Current disclosures provide no data on robot numbers, order value, or workstations. Safety certification, continuous operating time, unit cost, and procurement scale should be assessed before concluding that mass production has begun.
Agility Robotics: Its commercialization strategy centers on partnerships with large manufacturing groups such as Foxconn and Toyota. Deep collaboration facilitates iteration around specific workstations, at the cost of customer concentration and slower replication. Key validation metrics include deployment numbers, labor hours replaced, continuous operating time, and expansion across factories; revenue, gross margin, and maintenance costs remain undisclosed.
Apptronik: Partnerships with Jabil and Mercedes-Benz show how robotics companies can leverage contract manufacturing and automotive plants for mass-production and use-case support. No revenue or delivery figures are currently available. Value depends on whether the robots can operate across multiple workstations and whether partnerships progress from testing to procurement. Supply-chain costs, maintenance frequency, delivery lead times, and safety also require validation.
Figure AI: Its partnership with BMW follows a deep-integration strategy with a single large automotive group. This model can accelerate use-case definition and the data feedback loop but may lengthen customer certification. The speed of progression from demonstration to scale will depend on whether the company can build a repeatable software stack and secure a stable hardware supply. Watch actual workstation deployments, procurement volumes, continuous operation, and replication across factories.
Boston Dynamics: Hyundai Motor’s industrial resources support robot mass production and internal deployment. Compared with an open supply model and replication across multiple customers, intragroup adoption offers easier access to use cases but may slow external commercialization. Key indicators include deployment in actual factories, continuous operation, maintenance costs, and external customer expansion, with purchase orders, delivery cadence, and gross margin the most important metrics.
Rainbow Robotics: Its group-level collaboration with Samsung Electronics reflects the broader trend of overseas robotics companies partnering with large manufacturing customers. No order or revenue data are currently available. The investment case depends on whether actuators, controllers, software, and after-sales service can form a repeatable product. Investors should also track customers outside the group, mass-production costs, deployment cadence, and after-sales capabilities.
Smartphone Supply Chain: Rising DRAM and NAND prices are being passed through to end devices. Supply-chain reports suggest iPhone production could be cut by as much as 30%, while prices for some key components have risen by more than 230%. These figures still require validation through company deliveries. Whether brands raise prices, reduce specifications, or adjust product mix will determine who absorbs the cost, with implications for device gross margins, product mix, and end demand.
“Data flows through the training pipeline in the sequence of SSD/storage → CPU (preprocessing) → GPU.”
On-Device AI: Qwen 3.6 can be compressed from 54GB to 4GB and run on an iPhone 17 Pro, indicating that edge inference can offload part of the cloud workload while expanding privacy-sensitive use cases. The value of on-device AI will depend on post-compression model accuracy, power consumption, memory footprint, the developer ecosystem, and users’ willingness to pay, as well as hardware replacement cycles.
Rocket Lab and Satellite Internet: After Rocket Lab shares fell from $140 to $80, some observers expect a rebound from the 200-day moving average, but technical analysis is no substitute for order validation. A separate satellite network received $30 million in US funding to connect remote communities in Papua New Guinea; watch launch frequency, terminal deployments, and recognized revenue.
Heavy-Lift Rocket Ground Systems: The new flame diverter at Starship Launch Pad 2 can discharge 650,000 gallons of water per minute, demonstrating that high-frequency heavy-lift launches also require sustained investment in ground infrastructure. The figure validates the engineering intensity but does not directly translate into orders or profit. Launch frequency, turnaround time, infrastructure reliability, and maintenance investment should be monitored before assessing engineering returns and cash burn.
Investment Bank Target Price Changes Over the Past 12 Hours
Huang’s Select Portfolio
Related Reading
404K SEMI-AI Morning Brief 2026-07-02 — Meta Compute Monetization, Strong Memory Pricing, Software Catches the Rotation404K SEMI-AI Morning Brief — July 11, 2026 — Meta Leads Gains, Memory Pricing Power Strengthens, AI Bottlenecks Spread to Interconnects and Power
目录
Post-Close Summary
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundries, Equipment, and Advanced Packaging
Optical Communications, High-Speed Interconnects, and Power
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Investment Bank Target Price Changes Over the Past 12 Hours
Huang’s Select Portfolio
U.S. equities edged higher, led by Meta and Nvidia, while software and cybersecurity remained under pressure. Industry developments were more concentrated: SK Hynix’s U.S. listing highlighted memory scarcity, Cerebras shifted the manufacturing bottleneck toward system assembly, and optical interconnects and power are beginning to determine whether incremental compute capacity can be delivered on schedule.
Post-Close Summary
As of the July 10 close, the S&P; 500 rose 0.45%, the Nasdaq 100 gained 0.37%, the Dow advanced 0.30%, and the Russell 2000 fell 0.42%. Technology rose 0.35% and communication services gained 1.02%; the semiconductor ETF advanced 0.54%, while the software ETF declined 1.65% and the cybersecurity ETF fell 2.52%. Capital continued to favor large AI platforms and hardware leaders.
Dispersion among individual stocks was more pronounced than at the index level. Meta rose 5.94%, Nvidia gained 4.04%, and AMD advanced 2.04%; Oracle fell 2.46%, Marvell Technology declined 2.90%, MongoDB dropped 5.73%, and CrowdStrike lost 5.59%. The storage supply chain continued to outperform most software names, with Seagate Technology, Western Digital, and Sandisk up 11.64%, 18.71%, and 16.84%, respectively, over the past 20 days.
The day’s most important marginal change came from supply constraints. After pricing its ADR at $149, SK Hynix opened at approximately $170, while customer requests for memory supply reached five to six times existing plans. Compute demand is not stopping at GPUs: storage, advanced packaging, testing, optical interconnects, system assembly, cooling, and power are jointly determining project delivery timelines.
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
OpenAI
1) After integrating ChatGPT Work and Codex, traffic reached roughly twice its previous peak. The team scheduled two quota resets that day, with a larger fix planned for next week.
2) Apple has filed a lawsuit alleging that two former employees misappropriated trade secrets while helping OpenAI develop competing hardware. The case remains undecided; near-term focus should be on the product roadmap and talent-compliance costs.
“bringing ChatGPT and Codex together into a workspace where people and agents can collaborate”
Anthropic: Additional compute is translating into more generous usage quotas, with users reporting that the platform has become “noticeably more generous after gaining access to additional compute.” Demand still exceeds supply, but publicly cited ARR figures vary widely. More reliable near-term indicators are quotas, stability, paid-user retention, and inference cost per unit; revenue assessments should await standardized disclosure.
Tencent Hy3: The 295-billion-parameter MoE model activates 21 billion parameters per inference and supports a 256K context window. Pricing is US$0.14 per million input tokens and US$0.58 per million output tokens. Low pricing, sparse activation, and an open license shift competition away from parameter counts toward the capabilities, cost, and deployment convenience that customers actually value. Developer adoption and real-world task quality are the next key indicators.
“Cost-effectiveness is China’s true moat.”
CSP/Cloud Capital Expenditure
Meta: Shares rose 5.94%. Bank of America estimates approximately US$22 billion per GW based on US$145 billion of capital expenditure and 6.5GW of incremental capacity, maintaining its Buy rating and US$835 price target. Citizens lowered its target from US$825 to US$800 as investment continues to rise. The disagreement centers on unit capacity costs and the pace at which AI returns materialize.
“Meta views the API as a real business, not merely a learning exercise.”
Google: Google is moving the TPUv9 scale-up network toward 2.4T coherent-Lumentum, with Innolight supplying modules and Marvell providing custom DSPs. The solution covers distances of 2–20 kilometers, filling the gap between conventional IM-DD’s sub-2-kilometer reach and still-immature CPO. Watch for adoption at scale and optical costs.
Microsoft: FY25 electricity consumption increased 24% year over year to approximately 37TWh. The company reclaimed 690MW of stranded data-center power and extended low-power states to nearly four million unallocated servers. Compute expansion has entered a “secure power first, install equipment second” phase. Server utilization and PUE are more indicative of effective capacity than nominal GPU counts and will determine the payback period on incremental investment.
AI Cloud/Data-Center Operators
IREN: Horizon 1 is approaching handover to Microsoft, with the market citing a nine-day countdown. Reports indicate that 260MW of contracted capacity represents approximately US$14 billion in revenue, alongside a 5,500MW power pipeline. The latter is only developable resource potential and should not be treated as contracted orders. First monitor whether Microsoft’s acceptance and revenue guidance are updated concurrently, then assess project funding.
CoreWeave: After signing its first agreement with Meta in 2025, CoreWeave has expanded the relationship as capacity ramped. Meta also plans to double its compute capacity next year. Further expansion of the agreement is directionally plausible, but no incremental contract value has been disclosed. Assessment should focus on customer commitments, GPU deliveries, power access, financing costs, and utilization once capacity comes online.
WhiteFiber: First-quarter revenue was US$21.92 million, up 31% year over year, while colocation revenue rose 190.2% to US$4.77 million. The long-term target is 1.5GW. Current high growth is being driven by colocation, while the longer-term US$4 billion ARR figure remains an estimate. Key variables are NC-1 construction, financing, and the ability to deliver targeted revenue per MW.
“100% of our compute is allocated today”
GPU/CPU/ASIC
Nvidia: Shares rose 4.04%. Management said growth continued to accelerate even as quarterly revenue approached US$100 billion, with AI labs accounting for approximately 20% of total demand. Rubin Ultra remains scheduled to ship next year, while 800-volt architecture and inter-rack optical scale-up are progressing as planned. Changes to the Kyber form factor will continue to affect production scheduling for rack and interconnect suppliers.
“The memory shortage looks to last for several years”
AMD: Shares rose 2.04%. Stifel raised its price target from US$450 to US$635 and maintained its Buy rating, forecasting that the server CPU market will exceed US$120 billion by 2030, representing a CAGR of more than 35%. MI450, Helios, and a combined 6GW of commitments from OpenAI and Meta are catalysts; execution hinges on delivery and the software ecosystem.
Cerebras: The company signed a multiyear inference contract with OpenAI worth more than US$20 billion and covering 750MW. Its latest quarterly revenue reached US$193.4 million, up 94% year over year, while Flex plans to increase CS-3 capacity by approximately sevenfold. WSE-3 bypasses HBM and CoWoS but shifts the bottleneck to assembly of 23kW systems, with core gross-margin guidance reduced to 36%–38%.
HBM/DRAM/NAND/SSD/HDD
SK Hynix
1) The company issued 177.9 million ADRs at US$149 each, raising approximately US$26.51 billion. The offering was more than seven times subscribed, and the shares opened at approximately US$170.
2) Customers are requesting five to six times more supply, and management believes capacity would remain insufficient even if doubled over the next five years. Proceeds will fund the Yongin fab, P&T7; advanced packaging, and HBM expansion.
3) The risk is that high margins will ultimately induce additional supply. From 2027 to 2028, investors must assess capacity expansion alongside cloud capital expenditure.
“Demand is growing far faster than our ability to add supply.”
Nanya Technology: Second-quarter revenue was US$2.61 billion, up 68% sequentially and 684% year over year. Gross margin reached 79.5%, and ASP increased by more than 60% quarter over quarter, while bit shipments were flat sequentially. DDR4 and LPDDR4 contributed 60%–70% of revenue, indicating that traditional DRAM is also benefiting from pricing leverage as HBM crowds out leading-edge capacity.
Micron: TD Cowen reiterated its Buy rating and US$1,600 price target. Long-term strategic customer agreements are expected to cover nearly 50% of revenue, while tight supply and demand could persist beyond 2027. The company raised its US manufacturing investment target to US$250 billion. Order visibility is improving, but capital-expenditure payback, customer concentration, and a reversal in the memory cycle remain key risks to monitor.
Sandisk: Shares rose 3.32%, with trading value of US$21.08 billion. Enterprise SSD prices are expected to rise 18%–23% in the third quarter, supported by tight NAND supply. The relative-value trade remains short Sandisk and long SK Hynix, indicating that the market prefers HBM exposure and tighter supply control. Watch whether SSD pricing translates into realized earnings.
Foundries, Equipment, and Advanced Packaging
TSMC: The company plans to invest an additional US$20 billion in Arizona. AI/HPC demand is driving both advanced-node and CoWoS capacity. Constraints on capacity expansion have shifted from funding to equipment lead times, yields, power supply, and customer qualification. Whether the US fabs can achieve stable high-volume production will determine whether capital expenditure converts into revenue and will also affect localization costs and gross margins.
Samsung Electronics: The company is advancing a glass-interposer prototype, seeking to reduce silicon-interposer costs through improved flatness, lower warpage, and large-area processing. Multilayer RDL, TGV, and copper filling remain process challenges. Separately, the 4nm GAIA AI PC chip is scheduled for mass production as early as 2027. Foundry-customer trust, mass-production yields, and internal competition require monitoring; customer adoption will determine revenue.
Applied Materials: The price target was raised from US$530 to US$650. Memory expansion, advanced nodes, and packaging are jointly extending the WFE cycle, while equipment vendors benefit from procurement across multiple fabs. Risks include cleanroom expectations running ahead of demand, delayed order allocation, and customer pressure on pricing as equipment lead times lengthen. Monitor orders, revenue recognition, delivery cycles, and gross margin.
Cohu: The price target was raised from US$50 to US$70, based on the combined impact of AI-compute testing revenue and a semiconductor-cycle recovery. KYEC separately plans to invest up to US$1.4 billion in US testing facilities, although the location, timeline, and customers have not been confirmed. Monitor equipment orders, project commencement, testing revenue, and capacity utilization before assessing earnings leverage.
Optical Communications, High-Speed Interconnects, and Power
Marvell Technology: FY26 revenue was US$8.195 billion, up 42% year over year, with data centers accounting for 76% of sales. More than 50 custom AI ASIC projects are scheduled to enter production in FY2028–FY2029. The company spans copper interconnects, custom ASICs, and optics; the real risks are project-production timelines and long-dated assumptions for network TAM.
“If SerDes does not work, nothing else matters.”
Credo: Shares fell 3.03% but remained up 6.48% over five days. The company is developing both microLED and silicon photonics, while high-speed interconnect demand is supported by growth in XPU deployments. The number of transceivers per XPU could decline by 40%–50%. The key question is whether total XPU growth can offset lower content per unit and translate into orders and revenue.
Coherent: Communications revenue increased 55% year over year. Both long-haul DCI and CPO require capabilities in InP, lasers, detectors, and modules. Industry data indicate that relevant capacity remains tight, but meaningful CPO volumes may not emerge until 2029. Near-term growth depends more on pluggable coherent modules, conventional optical components, and inter-campus connectivity, while profitability hinges on InP supply.
Bloom Energy: Shares fell 4.82%. An order backlog of approximately US$20 billion and data centers’ need for rapid power deployment provide support, but short sellers have questioned the volume and sourcing of scandium oxide and the cost risks embedded in fixed-price contracts. The company says supply is sufficient to support 25GW of annual production, while external estimates put capacity below 2.5GW. Disclosure transparency will determine the valuation debate.
Vertiv: Data-center power and thermal management have become hard constraints on compute deployment. Incremental North American capacity is expected to increase from 8.9GW in 2025 to 10.3GW in 2026 and 12.1GW in 2027, with cooling becoming the primary bottleneck after 2028. Order conversion will depend on cooling-equipment manufacturing, EPC labor availability, grid interconnection, and equipment lead times.
Internet/Platforms
Meta: Up 5.94% on the day, 14.77% over five days, and 17.28% over 20 days. The platform’s rerating reflects a combination of improving model capabilities, advertising cash flow, and a potential cloud business. However, its enterprise software sales experience remains limited, the Muse model requires validation through sustained releases and customer migrations, and returns on capital expenditure must be confirmed by API revenue rather than the share price alone.
“enterprises aren’t going to switch overnight”
“Meta has the clearest path among hyperscalers to close on OpenAI/Anthropic”
Google: Down 0.48% on the day. The market is simultaneously pricing in Gemini delays, model compliance, and TPU infrastructure advantages. If Meta closes the gap at the model layer, Google’s search cash cow will also face direct disruption from changing AI entry points. Google’s defense rests on coordination across TPUs, cloud, networking, and power; the key question is whether Cloud and Search can sustain growth above 20%.
Amazon: Down 0.69% on the day. AWS capital expenditure remains strong, but the company unexpectedly issued $25 billion of bonds, with 2.5x subscription and an additional concession of 18–21 basis points on longer-dated debt. AI buildout is beginning to consume bond-market capacity. Cloud revenue acceleration must offset higher financing costs, depreciation, and power expenses; RPO conversion is the next key indicator.
Microsoft: Up 0.19% on the day. If internal models can replace some third-party models within Copilot, Microsoft could reduce its dependence on OpenAI and Anthropic while strengthening usage-based pricing. Conversely, Xbox will eliminate 3,200 positions over the next 12 months, approximately 20% of its workforce, showing that platform subscriptions cannot be separated from content costs and retention.
Oracle: Down 2.46% on the day and 30.10% over 20 days. Together with Microsoft, Amazon, Meta, and Google, the company has issued $194 billion of bonds year to date, representing approximately 9% of investment-grade issuance. AI cloud orders and financing pressure are rising in tandem. Revenue recognition and capital-expenditure payback matter more than backlog alone, while project financing costs will also affect earnings.
Tencent: Hy3 is competing through low inference pricing and an open license, while the company is also in talks to become Manus’s largest shareholder while retaining a minority stake. The platform opportunity lies in synergies across models, social networks, and enterprise services. Cross-border investment remains subject to regulatory constraints; closing the transaction and preserving Manus’s operational independence are key validation points, while model usage and paid conversion will determine commercial value.
Alibaba: Its Singapore subsidiary reportedly has access to advanced overseas models, but OpenAI has suspended some affiliated API users over unauthorized use and suspected distillation. Cloud demand remains intact, but compliance boundaries will directly affect model access, R&D; costs, and the pace of international expansion. Access should not be equated with stable long-term supply; progress on proprietary alternatives is more important.
Baidu: Like Alibaba and Tencent, Baidu operates at the intersection of overseas model access and domestic model development. Available information does not disclose procurement amounts or usage volumes. For the platform, the key question is whether proprietary models can reduce external dependence and convert data from search, cloud, and enterprise customers into monetizable applications. Key indicators include usage growth, customer retention, inference costs, and margins.
Shopify: Stifel upgraded the stock to Buy and raised its price target from $110 to $150, seeing a path to revenue growth of 30% or more in 2026. Agentic commerce remains at an early stage; platform migration, B2B, international operations, and payments are more tangible growth drivers, while incremental AI value must be validated through merchant conversion.
“agentic commerce still in its infancy”
Letterboxd: The platform is seeking a sale and testing a valuation of $250 million. Membership exceeded 30 million as of June 2026. Its user base provides a foundation for a transaction, but the real value depends on engagement, advertising or subscription monetization, and whether a buyer can convert film and television interest data into recurring revenue. The transaction price still awaits confirmation.
Fox: Rothschild Redburn upgraded the stock from Neutral to Buy and raised its price target from $48 to $71; it forecasts an EPS CAGR of 23% from 2026 to 2030. Platform value derives from merger synergies and rapid deleveraging. Risks include extrapolating a low tax rate indefinitely, NFL renewal costs, and post-merger execution.
Cloud Platform Financing: Cash capital expenditure by the 11 largest cloud providers is expected to reach $632 billion in 2026, 4% above consensus. Hyperscalers have strong buildout intentions, but power, cooling, EPC capacity, and equipment constrain delivery. Platform revenue growth, free cash flow, and debt costs will become the next valuation divide, while also determining financing capacity and valuations.
“Cloud capex…100% to 115%+ of operating cash flow”
Cross-Border Model Access: Overseas model providers granting access to offshore subsidiaries of Chinese companies indicates that commercial demand and regulatory boundaries still leave some room. The suspension of affiliated API users also shows that distillation, customer identity, and end use can affect service continuity. Platforms need to budget for compliance, alternative models, and data migration while preparing contingency plans for service interruptions.
AI Advertising: Click-through rates for ads native to AI conversations are said to be four to five times the display-ad benchmark, suggesting that advertising could subsidize inference costs. This figure is based on application-level observations and still lacks validation through revenue and retention. Whether platforms can embed ads without impairing answer quality will determine inference monetization margins; advertiser repeat spending, user retention, and conversion rates also matter.
Local Model Platforms: Local and open-source models are narrowing the gap with proprietary cloud models, while sensitive data, low-latency requirements, and governance needs are driving enterprise deployment. Platforms will not converge on either cloud-only or edge-only architectures. The cloud will provide peak capabilities and scale, local models will address privacy, and routing layers will optimize costs. Enterprise procurement will compare maintenance complexity, security, and total cost of ownership.
“Many models are good enough for most work”
Software/SaaS
OpenAI Codex: In Q2 2026, LLM-based evaluation estimated that 8% of contributor-days completed more than 24 hours of human engineering work. The result shows that a small share of highly productive workdays has surpassed conventional time constraints, but it is not a rigorously controlled experiment. Software value still needs to be assessed through average team productivity gains, code quality, and paid conversion.
“In Q2 2026, 8% of contributor-days involved more than 24 hours worth of human engineering work”
Anthropic Claude: Claude’s coding experience has received strong retention feedback, but claims that “ARR will surge” still lack a disclosed base and paid conversion rate. On the product side, additional compute has improved usage allowances; commercially, usage volume, customer retention, inference costs, and gross margin all require validation. High-frequency use becomes SaaS revenue only when converted into recurring payments, while enterprise contract duration also warrants attention.
Twilio: Stifel upgraded the stock from Hold to Buy and raised its price target from $175 to $260. Its Conversations, Communications, and Data products are positioned to capture demand from voice agents. No breakdown of AI revenue or orders is currently available; key indicators include customer budgets, usage volumes, and post-restructuring margins.
“As voice agents proliferate…strengthening Twilio’s position as a critical infrastructure provider for agentic customer engagement.”
MongoDB: Needham maintained its Buy rating and raised its price target from $400 to $430. The company’s AI monetization has lagged Snowflake and Datadog because externally facing applications face a higher threshold for production deployment. Whether database usage accelerates as AI applications enter production is key to validating the higher price target.
Snowflake: Down 2.05% on the day but up 9.21% over 20 days. The market groups the company with Datadog and MongoDB as usage-based infrastructure software. Its relative strength suggests that AI data demand is already reflected in expectations, but confirmation still requires consumption revenue, customer expansion, unit economics, and net retention rather than share-price performance alone.
Datadog: Down 4.23% on the day but still up 13.17% over 20 days. Observability benefits from increasing complexity across models, agents, and data pipelines, but higher usage also raises customer bills. Whether vendors can make cost monitoring mission-critical while preserving net retention is a prerequisite for further valuation expansion; customer budgets remain a countervailing constraint.
Cloudflare: Down 2.47% on the day, up 10.97% over five days, and up 22.46% over 20 days. The edge cloud and AI network provide both inference distribution and a developer entry point, but available information contains no new orders. The share price reflects elevated growth expectations; key indicators include AI inference revenue, developer adoption, network costs, gross margin, and customer concentration.
CrowdStrike: Down 5.59% on the day but up 15.66% over 20 days. Agents, plugins, and MCP servers are expanding the attack surface, while enterprise deployment may outpace security reviews. The direction of security demand is clear, but the investment thesis still depends on platform consolidation, customer retention, incremental module revenue, and sales efficiency, with renewals as a key indicator.
“the attack surface is exploding”
Palo Alto Networks: Down 3.55% on the day but up 23.96% over 20 days. AI vulnerabilities and automated attacks increase the value of security platforms, while software consolidation may reduce budgets for point solutions. Whether the company can translate multi-product bundling into higher customer lifetime value is central to margins and valuation; renewal discounts also warrant attention.
Fable: After rewriting its Windows battery benchmark from Python and its dependencies in Swift, efficiency improved by 20–40x across most workloads. The case shows that AI coding can deliver runtime efficiency, not merely faster code generation. However, the benefits of reworking the language stack must still be separated from the model’s contribution, while code maintenance costs and migration complexity require validation.
WEKA: Discussion centers on AI memory, storage, and future architectures, indicating that software-defined storage is becoming a system-level issue for large-scale inference. The company has not yet disclosed customer, order, or performance data. Key indicators include whether bandwidth, latency, cost, and GPU utilization create measurable advantages, followed by the revenue opportunity, customer stickiness, renewal capacity, and profitability.
Manus: Tencent is in talks to become its largest shareholder while retaining a minority stake and allowing the company to operate independently in Singapore. Meta’s previous $2 billion acquisition plan was ordered to be unwound, showing that the technological value of agent assets and cross-border regulatory scrutiny are rising simultaneously. The transaction structure, independence, and approval conditions will determine closing probability, while product retention and revenue also require monitoring.
Inference Routing: New models are released every 41 days on average, and pricing differences widen rapidly when capabilities are comparable. Enterprises will route workloads among frontier, near-frontier, local, and open-source models based on the task. Routing software derives value from cost, latency, governance, and reliability, rather than a one-off benchmark ranking. Key indicators include retained usage, paid conversion, gross margin, customer expansion, and renewals.
“Inference emerged as the dominant market in AI”
Enterprise AI Adoption: Enterprise AI spending is highly polarized: the top 1% of monthly spenders invest $7,449 per employee, versus a median of just $11, a gap of approximately 650x. Software demand is not diffusing evenly, so sales strategies should first target high-value workflows. The cycle should be assessed through seat expansion, retention, and revenue per customer—not trials alone—while inference expenses also matter.
Video Generation Software: Content featuring people is subject to stricter filtering because of copyright, likeness, and deepfake risks, potentially reducing the product’s value proposition to scenic or graphical assets. Improving technical capabilities does not mean monetizable use cases will expand in parallel. Training-data licenses, permissions for depicting people, content provenance, and false positives in filtering will directly affect the revenue ceiling, customer renewals, enterprise adoption, and gross margin.
“As soon as a ‘human face’ appears in the video, the entire output is blocked.”
Consumer Electronics / Smart Vehicles
Apple
1) The bill of materials for the 12GB/1TB iPhone 18 Pro Max is expected to rise by nearly $300 versus the prior generation, with memory accounting for the largest increase; even with a $200 average price increase, gross margin could still be slightly lower.
2) The company has sued OpenAI, alleging that two former employees took trade secrets for a competing hardware venture; Jony Ive was not named as a defendant.
“Memory is the largest driver of the cost increase, followed by the latest 2nm SoC using advanced packaging.”
“OpenAI’s nascent hardware business…unlawfully relies on misappropriated trade secrets.”
“Even with a $200 increase in average retail price…gross margin is still expected to be slightly below that of the 2025 iPhone 17 Pro Max.”
Tesla
1) The company has begun dismantling the Model S and Model X production lines in Fremont to make room for Optimus, with planned capacity of 1 million units annually at full ramp, but no timeline for reaching that level.
2) In South Korea, FSD costs KRW 9.04 million as a one-time purchase or KRW 150,000 per month by subscription; the roughly 60-month static payback period highlights the company’s trade-off between upfront cash collection and adoption.
Samsung Electronics: The company is developing GAIA, a 4nm AI PC chip, with mass production possible as early as 2027. If the project proceeds, Samsung would be both a foundry and an AI PC chip competitor. Technology, customer trust, and resource allocation are the three key hurdles. No performance data, orders, or customers have been disclosed; watch for samples, mass-production yields, customer adoption, and power consumption.
Qualcomm: AI200 is scheduled to ship this year and AI250 in 2027. The company guides for data-center revenue to rise from $5 billion in FY2027 to more than $15 billion in FY2029. The handset business remains affected by rising memory prices; whether data-center products can become a second growth engine will depend on the software ecosystem, customer deployments, and revenue recognition.
Microsoft Xbox: The company plans to cut 3,200 jobs over the next 12 months, representing approximately 20% of its workforce. Game Pass subscriptions have fallen short of expectations, and bundling cannot eliminate the high investment, long development cycles, and uncertainty inherent in content production. Key metrics include user retention, revenue per user, content amortization, and studio restructuring; subscription pricing and content supply also require validation.
“The complete failure of the Game Pass strategy.”
Mitsubishi Motors: The company plans to work with Highlanders to deploy humanoid robotic workers by 2027. The timeline suggests automotive factories are moving from trials toward planned deployments. Current disclosures provide no data on robot numbers, order value, or workstations. Safety certification, continuous operating time, unit cost, and procurement scale should be assessed before concluding that mass production has begun.
Agility Robotics: Its commercialization strategy centers on partnerships with large manufacturing groups such as Foxconn and Toyota. Deep collaboration facilitates iteration around specific workstations, at the cost of customer concentration and slower replication. Key validation metrics include deployment numbers, labor hours replaced, continuous operating time, and expansion across factories; revenue, gross margin, and maintenance costs remain undisclosed.
Apptronik: Partnerships with Jabil and Mercedes-Benz show how robotics companies can leverage contract manufacturing and automotive plants for mass-production and use-case support. No revenue or delivery figures are currently available. Value depends on whether the robots can operate across multiple workstations and whether partnerships progress from testing to procurement. Supply-chain costs, maintenance frequency, delivery lead times, and safety also require validation.
Figure AI: Its partnership with BMW follows a deep-integration strategy with a single large automotive group. This model can accelerate use-case definition and the data feedback loop but may lengthen customer certification. The speed of progression from demonstration to scale will depend on whether the company can build a repeatable software stack and secure a stable hardware supply. Watch actual workstation deployments, procurement volumes, continuous operation, and replication across factories.
Boston Dynamics: Hyundai Motor’s industrial resources support robot mass production and internal deployment. Compared with an open supply model and replication across multiple customers, intragroup adoption offers easier access to use cases but may slow external commercialization. Key indicators include deployment in actual factories, continuous operation, maintenance costs, and external customer expansion, with purchase orders, delivery cadence, and gross margin the most important metrics.
Rainbow Robotics: Its group-level collaboration with Samsung Electronics reflects the broader trend of overseas robotics companies partnering with large manufacturing customers. No order or revenue data are currently available. The investment case depends on whether actuators, controllers, software, and after-sales service can form a repeatable product. Investors should also track customers outside the group, mass-production costs, deployment cadence, and after-sales capabilities.
Smartphone Supply Chain: Rising DRAM and NAND prices are being passed through to end devices. Supply-chain reports suggest iPhone production could be cut by as much as 30%, while prices for some key components have risen by more than 230%. These figures still require validation through company deliveries. Whether brands raise prices, reduce specifications, or adjust product mix will determine who absorbs the cost, with implications for device gross margins, product mix, and end demand.
“Data flows through the training pipeline in the sequence of SSD/storage → CPU (preprocessing) → GPU.”
On-Device AI: Qwen 3.6 can be compressed from 54GB to 4GB and run on an iPhone 17 Pro, indicating that edge inference can offload part of the cloud workload while expanding privacy-sensitive use cases. The value of on-device AI will depend on post-compression model accuracy, power consumption, memory footprint, the developer ecosystem, and users’ willingness to pay, as well as hardware replacement cycles.
Rocket Lab and Satellite Internet: After Rocket Lab shares fell from $140 to $80, some observers expect a rebound from the 200-day moving average, but technical analysis is no substitute for order validation. A separate satellite network received $30 million in US funding to connect remote communities in Papua New Guinea; watch launch frequency, terminal deployments, and recognized revenue.
Heavy-Lift Rocket Ground Systems: The new flame diverter at Starship Launch Pad 2 can discharge 650,000 gallons of water per minute, demonstrating that high-frequency heavy-lift launches also require sustained investment in ground infrastructure. The figure validates the engineering intensity but does not directly translate into orders or profit. Launch frequency, turnaround time, infrastructure reliability, and maintenance investment should be monitored before assessing engineering returns and cash burn.
Investment Bank Target Price Changes Over the Past 12 Hours
Huang’s Select Portfolio