
目录
Post-Market Wrap
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
AI Cloud and Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry, Advanced Packaging, and Equipment
Optical Communications, Networking, and Servers
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Jensen Huang Select Portfolio
Memory Index Performance
Memory Stocks’ Share of US Equity Turnover
Overview
404K | 2026-08-14
Post-Market Wrap
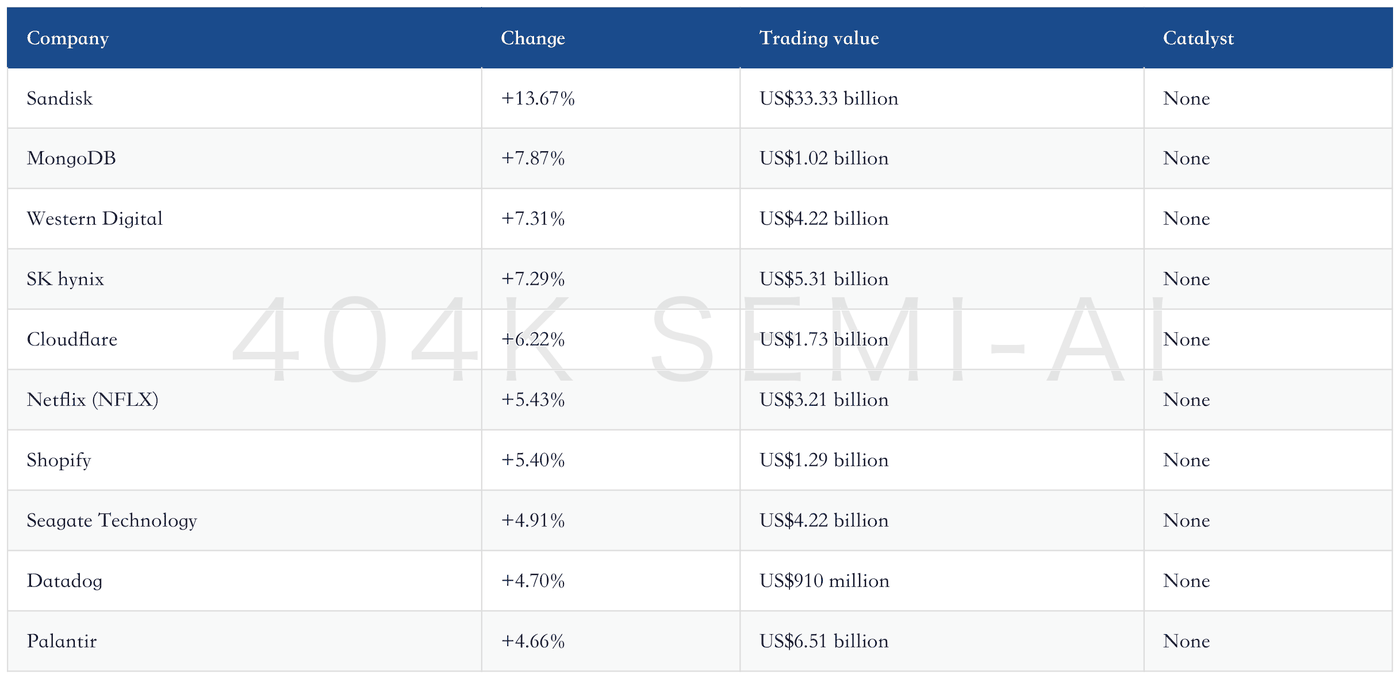
U.S. risk appetite improved on August 13. The S&P; 500 rose 0.73%, the Nasdaq 100 gained 1.19%, the equal-weighted S&P; 500 advanced 0.82%, and the Russell 2000 added 0.30%. Communication services climbed 1.80% and technology rose 1.06%, indicating that flows were not confined to a handful of mega-cap stocks.
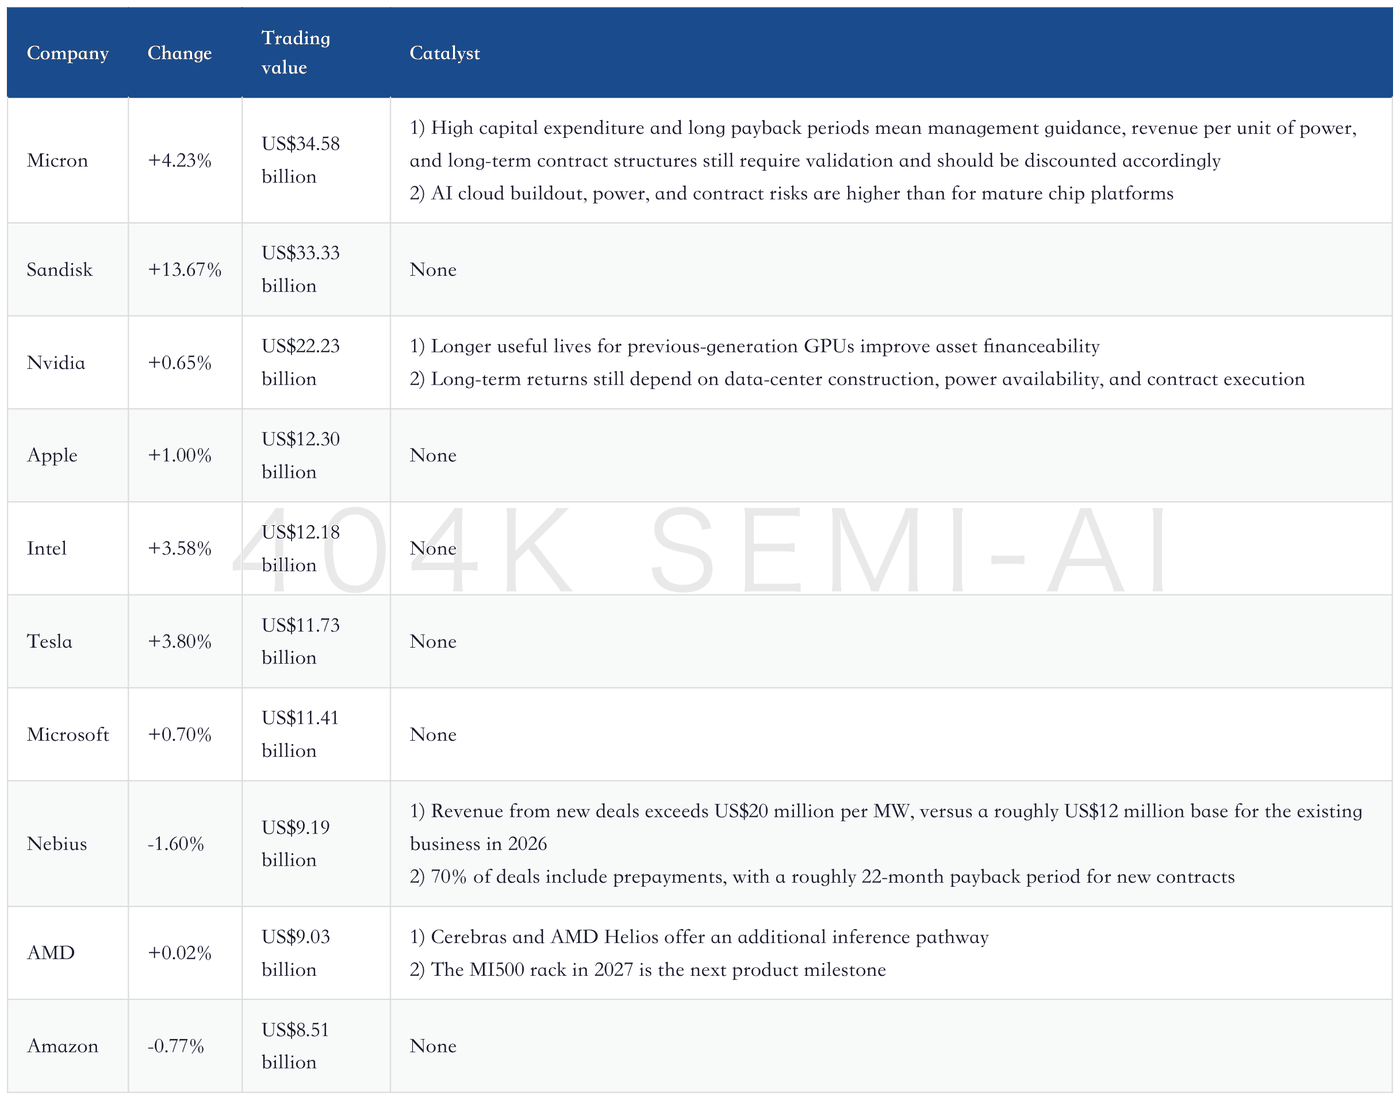
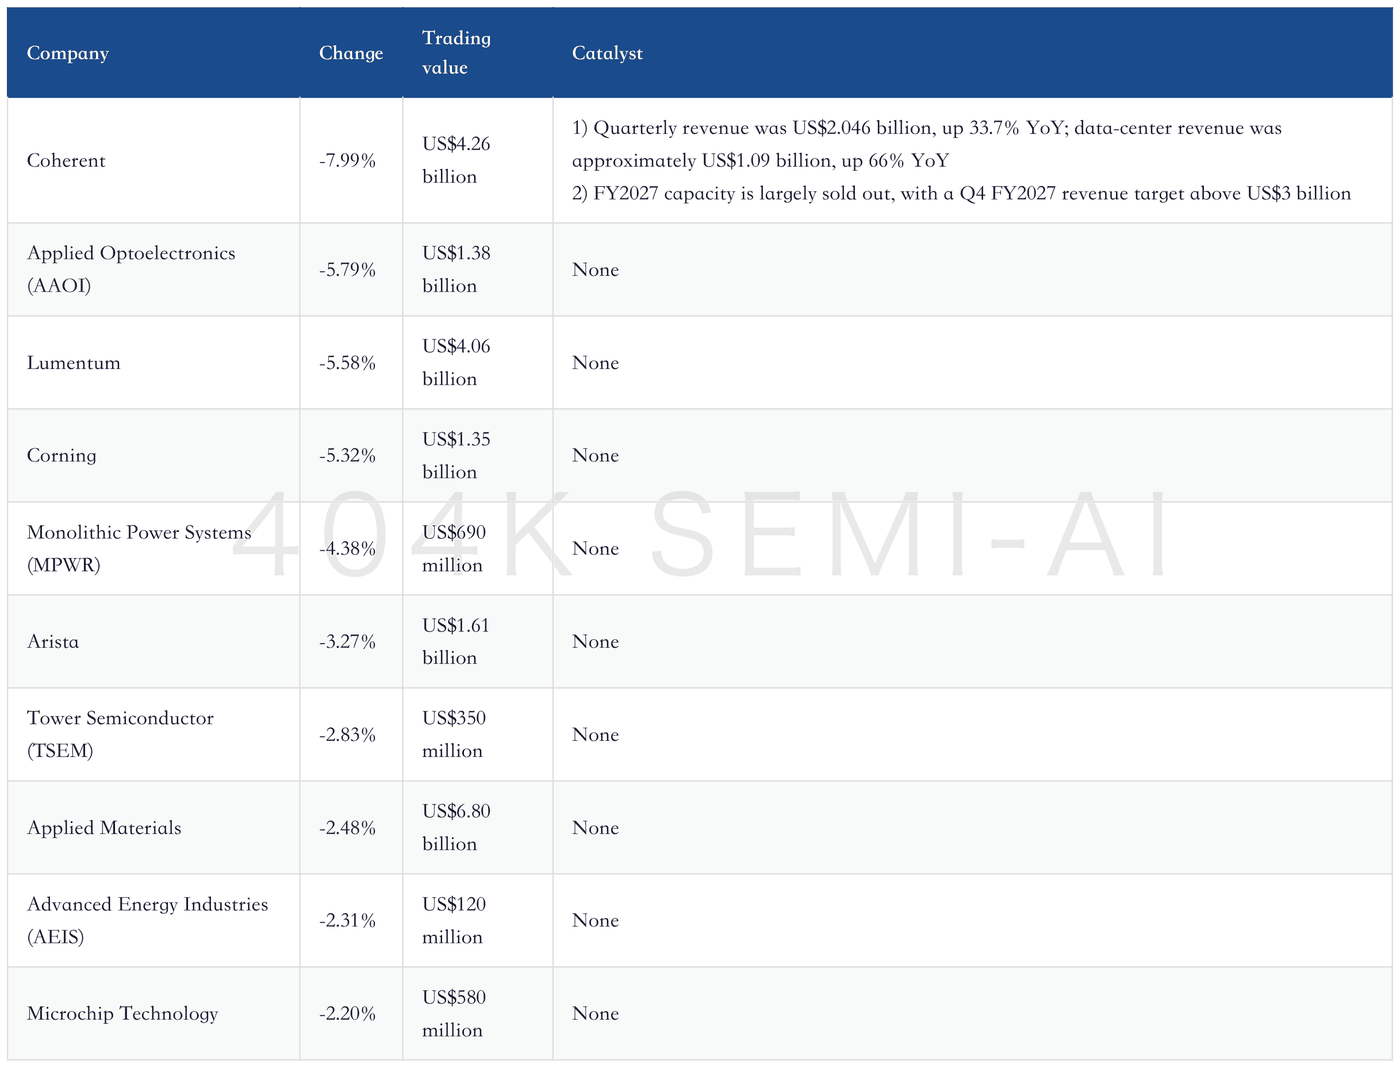
The semiconductor ETF gained 0.99%, but stock-level performance remained divergent: Sandisk rose 13.67%, Western Digital 7.31%, and Micron 4.23%, while Coherent fell 7.99% and Applied Materials declined 2.48%. The market’s focus has shifted from whether AI demand exists to whether orders can be delivered on schedule, gross margins can hold, and capital expenditure can convert into cash flow.
The most important incremental change is in AI infrastructure financing and unit economics. CoreWeave, Nebius, and IREN all provided stronger evidence on contracts, pricing, or delivery, while Anthropic’s large-scale project financing shows that capital remains willing to fund long-term compute leases. Risks are rising in parallel: power, construction, customer concentration, and vendor backstops are replacing chip procurement as the primary constraints on expansion.
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
Anthropic
1) When annualized revenue was below US$9 billion in November 2025, the company announced a US$50 billion investment in U.S. compute infrastructure. Nearly US$50 billion of related debt financing has now been identified. More than 1GW of Google TPU systems is tied to US$34.5 billion of debt, including US$30 billion backed by Broadcom.
2) Five data centers have secured another approximately US$15.2 billion of loans, supporting 1.43GW of critical IT capacity. Financing is not yet a constraint; the next tests are lease performance, collateral recovery value, and whether vendor backstops continue.
“At least in the near term, financing is unlikely to become the binding constraint on frontier-compute growth.”
OpenAI: The Ultrafast real-time preview is powered by Cerebras chips and delivers up to 750 output tokens per second. The speed improvement has moved beyond benchmarks into products and workflows; the real test is whether the preview can scale to stable commercial workloads and drive Cerebras cloud-services revenue.
“Powered by Cerebras, Ultrafast generates up to 750 output tokens per second, bringing our most intelligent models into products and workflows where every second matters.”
Google Gemini: Gemini 3.7 Flash achieved 65.5% on DeepSWE for the first time, 18.8 percentage points above 3.6 Flash, at less than half the cost per task. Simultaneous capability gains and cost reductions make it easier for applications to scale usage; accuracy, latency, and total cost in real-world workflows still require monitoring.
AI Cloud and Data-Center Operators
CoreWeave
1) Backlog stands at US$104.2 billion, with more than 50% already in delivery and over two-thirds expected to be in delivery by year-end. Contracted power totals 4.2GW, with more than 300MW activated in June alone.
2) Pricing across SKUs rose by approximately 25% in July, while new contracts carry contribution margins 5 to 10 percentage points above recent deals. Managed-inference ARR increased from approximately US$1 million to more than US$100 million, while storage, CPU, networking, and software ARR exceeded US$400 million.
3) The weighted-average cost of debt fell by approximately 300 basis points YoY, generating roughly US$1.1 billion in annualized interest savings. Construction, power, and long-term contract execution remain the principal risks.
“Revenue per GW can vary significantly by AI cloud provider and contract duration.”
Nebius
1) Q2 revenue was US$582 million, up 454% YoY. AI cloud margins rose from 24% to 45%, and then to 50%. Revenue from new deals exceeds US$20 million per MW, with near-term capacity reaching US$40 million to US$50 million.
2) 70% of deals include customer prepayments covering 50% to 60% of capital expenditure, shortening the payback period to approximately 22 months. The company believes it could immediately sell out its 2027 capacity but is reserving some supply for higher-value demand.
3) The Wales project adds high-density AI capacity, but the 300MW New Jersey project reportedly received a stop-work order following site-plan revisions. Strong pricing does not eliminate power and construction constraints.
“If we wanted to, we could sell all of our 2027 capacity today on these terms. We have chosen not to.”
IREN: Horizon 1 has been accepted by Microsoft and provides 50MW of liquid-cooled AI cloud capacity. It is the first of four 50MW facilities planned for 2026 and supports a five-year, US$9.7 billion cloud contract. GB300 NVL72 has also received Nvidia certification. The company targets 480MW in 2026 and 1.2GW in 2027; the next test is whether Horizons 2 through 4 are delivered on schedule.
“Delivering Horizon 1 demonstrates the strength of our vertically integrated model and our ability to execute complex AI infrastructure projects rapidly and at scale.”
GPU/CPU/ASIC
Nvidia
1) Goldman Sachs estimates approximately 50,000 AI rack shipments in 2026, versus roughly 5,000 for AMD. By 2028, the shipment gap is expected to widen to approximately 133,000 racks. CUDA, full-stack systems, and cloud-customer relationships remain key platform advantages.
2) A100 contracts have been signed through 2029, preserving lease value for older-generation GPUs. Nvidia aims to attract more than US$500 billion of third-party infrastructure capital and may provide backstops for transactions worth up to US$125 billion. Financing can amplify revenue, but it also brings long-term oversupply risk back onto the balance sheet.
Broadcom: The XPV program aims to support more than 20GW of deployments by 2028, with an initial approximately US$35 billion financing package backing more than 1GW of Anthropic compute capacity. Wolfe estimates that the program could represent US$140 billion to US$200 billion of revenue, but vendor support for equipment residual values would turn customer defaults and industry oversupply into financial risks.
Intel
1) Management said agentic inference is shifting the CPU-to-GPU ratio from approximately 1:8 in training toward 1:4 or even 1:1. Bank of America expects the server CPU market to grow from US$34.983 billion in 2025 to US$210.637 billion in 2030, with AI server CPUs rising from 53% to 86% of the market.
2) Server CPU shipment share declined in Q2 while revenue share increased, suggesting a better product mix or pricing. CXL also provides open connectivity across CPUs, accelerators, and pooled memory, although demand realization still depends on server-platform deployments.
AMD
1) The company plans to raise up to US$5 billion through a bond offering. Proceeds may be used for general corporate purposes and to repay US$875 million of bonds due next month.
2) Goldman Sachs estimates AMD’s 2026 AI rack shipments at approximately one-tenth of Nvidia’s. Growing revenue from approximately US$41 billion over the past 12 months to more than US$200 billion by 2030 would require sustained compound growth of 35% to 40% and market-share gains; product execution and financing-led expansion must progress in parallel.
Cerebras: Core revenue was US$209.9 million, up 103.1% YoY, while cloud and other services revenue reached US$127.7 million, up 286.7% YoY. Contracted capacity exceeds 600MW, with remaining performance obligations of US$25.4 billion. UBS raised its price target from US$320 to US$330, while Citi cut its target from US$340 to US$320. The debate centers on system leasing’s drag on gross margin and the pace at which power capacity becomes operational.
