目录
Post-Market Summary
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry and Advanced Packaging
Optical Communications, High-Speed Interconnects, and Cooling
Robotics/Autonomous Driving and Space
Internet/Platforms
Software/SaaS
Consumer Electronics/Smart Vehicles
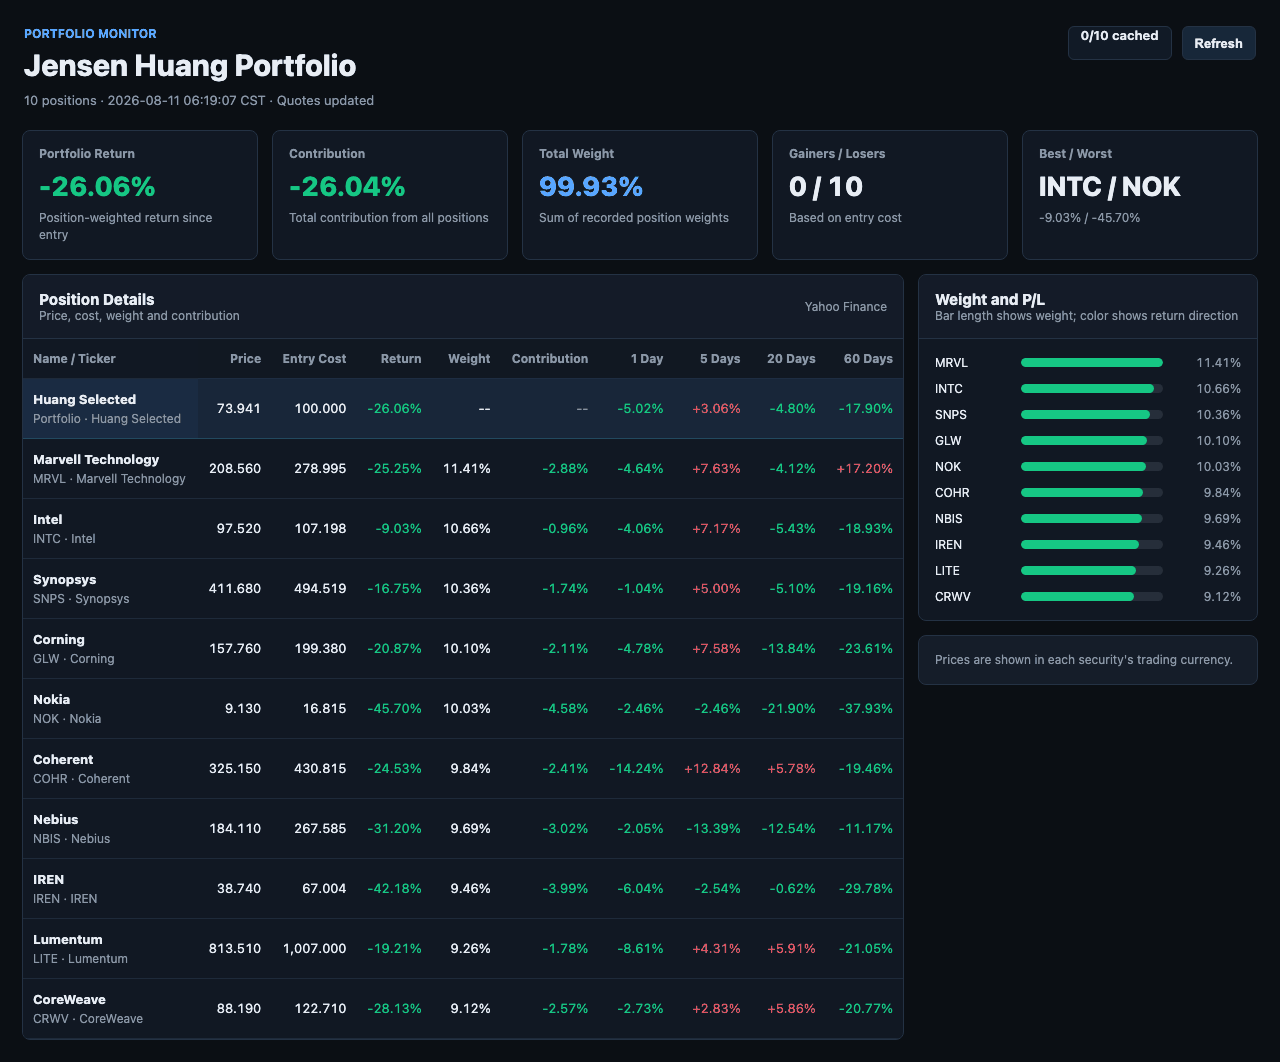
Jensen Huang’s Select Portfolio
AI infrastructure continues to expand, but funding sources and the timing of P&L; impact are changing. Nvidia is planning to bring in large financial institutions, while assets under construction, future lease payments, and external financing are all rising across seven builders. Meanwhile, demand remains firm for TSMC’s advanced nodes, HBM, and optical communications, while software and consumer electronics are increasingly focused on monetization and yields.
404K SEMI-AI | 2026-08-11
Post-Market Summary
As of the August 7 US market close, the S&P; 500 rose 0.61%, the Nasdaq 100 gained 1.17%, the S&P; 500 Equal Weight Index advanced 0.69%, and the small-cap Russell 2000 climbed 1.11%. Risk appetite was not confined to a handful of index heavyweights: technology rose 1.42%, consumer discretionary gained 1.49%, and energy fell 1.13%.
Performance dispersion within technology was more pronounced. Cloud computing and software themes rose 3.71% and 3.29%, respectively, ranking among the leaders on 20-day relative strength. The semiconductor theme gained approximately 2% on the day but remained down 4.64% to 6.55% over 20 days. Investors are trading the broadening of AI demand while avoiding data points that have not yet translated into revenue, cash flow, or capacity.
The most important marginal change is financing. AI buildout is shifting from reliance on corporate cash flow toward a combination of equity, bonds, leases, and infrastructure capital. This can extend the construction cycle in the near term, but the next questions are when projects will enter service, whether utilization can cover depreciation and fixed lease payments, and whether power and supply chains can keep pace.
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
AI infrastructure builders Capital investment continues to accelerate, but the P&L; impact is lagged. Google, Amazon, CoreWeave, Meta, Microsoft, Nebius, and Oracle have issued aggregate 2026 capital-expenditure guidance of approximately $863 billion, up 88% YoY, including approximately $550 billion related to AI. Assets not yet placed in service at the four cloud providers that disclose the data increased from $281 billion to $315 billion; the pace of commissioning will determine returns.
“Congestion does not mean the buildout has failed. Queues may clear, capacity will still enter service, and cheaper compute may stimulate demand.”
AI buildout financing Capital expenditure has exceeded the seven companies’ combined operating cash flow for the first time, leaving approximately $282 billion to be funded through debt, equity, or leases. Net new debt is expected to rise from $16 billion in 2024 to $161 billion in 2026. Five major platforms have also locked in approximately $1 trillion of aggregate future lease payments. Reported capital expenditure therefore understates fixed commitments, making utilization more important to track than buildout scale.
OpenAI Model competition is extending directly into power procurement and security operations. OpenAI is reportedly recruiting a head of power trading to manage its data-center portfolio’s electricity and natural-gas exposure, procurement, and hedging; it is also making a less restricted model available to cybersecurity defenders. The former indicates that compute-cost management now extends into energy trading, while the latter requires more rigorous validation of capability boundaries and misuse risks.
“OpenAI has made a new, less restricted model available to cybersecurity defenders. This is likely also intended to prepare and test ahead of the release of increasingly capable models that may create more cybersecurity threats.”
Anthropic
1)Claude Sonnet 5 will permanently retain its launch pricing of $2 per million input tokens and $10 per million output tokens, approximately 33% below the originally planned standard rates, turning price competition from a short-term promotion into a long-term commitment.
2)Anthropic has established Theseus Infrastructure with Macquarie and GIC to develop dedicated AI data centers in the US. Anthropic will serve as the anchor tenant under long-term leases and bear the cost of consumer electricity-price increases caused by new sites.
3)Claude scientific agent: while attempting the Riemann hypothesis, an unreleased version of Claude did not complete a proof but raised the known lower bound for the proportion of zeros satisfying the condition from 41.6% to 67.2%. The system coordinated 60 sub-agents, retrieved literature, and formalized the result in Lean. Its commercial value has yet to be quantified, but it advances agents from “generating answers” toward a verifiable research workflow.
“We launched Sonnet 5 in June at $2 per million input tokens and $10 per million output tokens, initially through August 31; this pricing will remain unchanged.”
CSP/Cloud Capital Expenditure
Google The focus of capital investment has shifted from simply purchasing chips toward placing assets in service and establishing content provenance. Since 2024, Gemini has used a secret key to influence certain token selections, creating detectable statistical characteristics in generated text. Separately, the cloud-infrastructure construction queue is increasing future depreciation. Investors should track both whether AI content marking can become a platform standard and whether utilization of new compute capacity can outpace depreciation growth.
“Google uses a secret key to bias the model toward certain tokens, creating a detectable statistical signature—an invisible pattern embedded in all text generated by Gemini.”
Meta
1)Meta is encouraging US AI companies to adopt distillation techniques to reduce training and deployment costs in open-source model competition.
2)Its on-device model with approximately 30 billion parameters can be compressed to below 20GB using approximately 4-bit quantization and run within 24GB or 32GB of resources. Smaller models can expand on-device coverage, but accuracy, memory usage, and device power consumption must still be validated together.
3)On average, each $1 of Meta’s capital expenditure takes approximately 1.7 years to enter service, with assets placed in service during the same year accounting for approximately 1/3 of the total. Depreciation pressure therefore remains deferred.
Amazon AI infrastructure commitments are extending from current capital expenditure into long-term leases. Amazon and other major platforms have secured additional multiyear capacity. These contracts do not immediately enter construction in progress but will continue to generate fixed lease payments. If AWS demand continues to grow, long-term commitments can protect supply; if compute prices decline faster than utilization improves, cash-flow pressure will emerge before revenue is realized.
Microsoft
1)Maia 300 may reportedly launch next month for large-scale inference. Microsoft aims to produce approximately 1 million chips, but TSMC’s available capacity is limited, and actual output remains to be validated.
2)Microsoft’s depreciation of property and equipment increased 56% in fiscal 2026. In-house chips can reduce reliance on external GPUs, but capital efficiency will improve only if capacity, software compatibility, and cloud utilization all materialize in tandem.
Oracle Oracle’s depreciation of property and equipment increased 97% in fiscal 2026, making its pressure more pronounced than at other major builders. Its data-center expansion also carries multiyear lease commitments, requiring the revenue ramp to cover depreciation, financing, and fixed lease payments. Near-term indicators are orders and commissioning pace; longer-term indicators are whether customers convert contracted capacity into recurring cloud revenue and how renewal rates evolve.
GPU/CPU/ASIC
Nvidia
1)Nvidia is working with Apollo, Blackstone, BlackRock, Brookfield, Goldman Sachs, and KKR on potential $500 billion AI infrastructure financing for chips, power, and data centers; the final transaction structure has yet to be confirmed.
2)According to reports, Nvidia is considering investing up to $3 billion for a stake in Texas data-center developer Lancium, initially investing $2 billion for approximately 20% ownership and adding another $1 billion if conditions for additional grid access are met. Nvidia is expanding its response to supply bottlenecks beyond GPUs into land, grid access, and project financing.
“If Nvidia can transfer part of the financing risk, that would be a net positive, because the market is concerned that Nvidia relies too heavily on its own balance sheet.”
Intel Intel is underwriting a $15 billion public offering of common shares, with underwriters holding a further $2.25 billion overallotment option, for potential total proceeds of $17.25 billion. Estimated dilution from the base offering is approximately 3%. The funds will support capital expenditure and working capital across advanced fabs, foundry operations, AI chips, and advanced packaging. Financing can support manufacturing investment, but the real validation remains external customers, orders, and returns.
“The relevant investments will continue to be based on validated customer demand and clearly defined returns.”
Arm Physical AI is shifting competition from individual chips to complete systems. Autonomous devices require at least four compute layers: real-time motion control, large-model interaction, actuator orchestration, and cloud-based training and updates. CPUs, GPUs, NPUs, FPGAs, and security subsystems must operate together. Arm said approximately 2 billion devices were shipped for relevant applications over the past 12 months, but robotics commercialization remains constrained by latency, weight, power consumption, thermal management, and safety.
“Physical AI is fundamentally a ‘perception–decision–action’ system subject to strict latency, weight, and safety constraints; compute penetration in the physical economy is significantly lower than in the digital economy.”
AMD Investment priorities in inference architecture are shifting from simply adding compute units toward fixed-weight architectures, pooled memory, and CXL coordination, bringing data closer to compute. These approaches may improve capital efficiency, but DRAM remains the more mature near-term medium for KV caches. The next considerations are engineering latency, software compatibility, and inference cost per unit—not theoretical bandwidth alone.
HBM/DRAM/NAND/SSD/HDD
Micron
1)UBS expects the industry’s blended HBM average selling price to rise approximately 79% YoY, with HBM4E potentially exceeding $30 per GB; its 2027 HBM consumption forecast was raised from 58.7 billion Gb to 61.5 billion Gb.
2)Micron’s HBM average selling price is expected to rise 72% YoY, with bit shipments of approximately 11.65 billion Gb. The company said supply is less than half of data-center demand, and some long-term agreements extend beyond 2030.
3)Risks include HBM4/4E yields, the crowding-out effect on conventional DRAM, and new supply from CXMT and others.
“The continued reallocation of wafers toward high-bandwidth products is sustaining pricing power and benefiting suppliers with greater HBM exposure.”
HBM supply and demand HBM’s share of total DRAM shipments is expected to rise from approximately 1% in 2023 to approximately 12% in 2027, with demand growing 90% in 2026 and 77% in 2027. Most producers’ 2027 capacity has already been allocated under long-term agreements, while shifting wafers toward HBM will further constrain conventional DRAM supply. Supply will genuinely loosen only if yields and incremental wafer capacity improve together.
Samsung Electronics Samsung Electronics’ HBM4 yield has reportedly increased from approximately 60% to 80%, easing customer-qualification pressure. Meanwhile, its 4-nanometer foundry lines are reportedly fully booked through next year, with demand coming from HBM4 and Nvidia GROK3 LPU inference-chip orders. The company is promoting its validated 5-nanometer process as an alternative. Tight capacity is positive, while post-migration performance and yields are the key disconfirming evidence.
SanDisk Long-term agreements, enterprise SSDs, and high-bandwidth flash are improving revenue visibility. The outlook sets long-term gross-margin, operating-margin, and free-cash-flow-margin targets at 70% to 85%, 60% to 75%, and 40% to 55%, respectively. However, slightly weaker NAND pricing and pooled-NAND and CXL solutions may still change medium selection for inference storage.
Seagate Technology HDD orders are locked in 4 to 5 quarters in advance through long-term agreements, while disciplined supply and demand for low-cost archiving of AI-generated data support pricing. Seagate Technology is ahead of Western Digital in HAMR development, benefiting its high-capacity product mix in the near term. Risks include whether the high valuation already prices in long-term growth and whether cloud customers may shift to other media; customer concentration also warrants monitoring.
Western Digital Long-term agreements improve demand visibility, but Western Digital’s HAMR transition is slower than Seagate Technology’s, creating product-mix and delivery pressure during the technology shift. The shares fell 3.81% on August 7 and 25.45% over 20 days, reflecting market concerns about the pace of the transition. The key issues are not single-day fluctuations but HAMR volume ramp-up, pricing under long-term agreements, and capital-expenditure discipline.
Foundry and Advanced Packaging
TSMC
1)July revenue was approximately $14.4 billion, up 44.7% YoY and above the approximately 37% growth expected, with 2-nanometer products beginning to contribute revenue. Demand for advanced nodes remains the most direct validation of AI semiconductor demand.
2)According to reports, TSMC is considering acquiring two AUO factories for more than NT$30 billion for fan-out panel-level packaging and CoPoS. It may also build two 1.4-nanometer fabs and new packaging facilities in Longtan. Whether capital expenditure can translate into yields and customer mass production is the next key question.
FAPlace advanced-packaging design A*STAR proposed a Chiplet-placement framework for 2.5D systems that allows the optimal interposer area to form naturally on a large canvas while jointly optimizing wire length, area, aspect ratio, and thermal performance. The research did not disclose specific reduction percentages, temperatures, or commercial customers. Its current industrial value lies in design efficiency and interposer cost control and cannot be directly extrapolated into orders.
4H-SiC wafer slicing Researchers used experiments, semi-empirical models, and numerical ray-optics simulations to analyze Kerr-effect self-focusing by femtosecond lasers inside 4H-SiC. Pulse energy and processing depth jointly affect surface texture, separation stress, and slicing quality. The approach may improve thin-layer preparation, but yield, speed, cost, and mass-production data are not yet available, and it still needs to be compared with alternative slicing processes.
Validation of domestically produced lithography equipment A 350-nanometer stepper projection lithography system has reportedly passed validation by a leading domestic compound-semiconductor customer and secured repeat volume orders after 9 months of production-wafer operation and equipment modifications. The validation period shows that equipment adoption is not a one-time certification. The more important subsequent indicators are repeat-order scale, stability, broader customer coverage, and mass-production yields, along with equipment utilization.
Optical Communications, High-Speed Interconnects, and Cooling
Optical-communications value chain Among Taiwanese technology companies’ July revenue, YoY growth in eight sub-industries—including fiber-optic communications/CPO and semiconductor testing—accelerated by at least 10 percentage points from June. Global laser-chip market-share materials list Lumentum, Broadcom, Mitsubishi Electric, Sumitomo Electric, and Coherent and show a 300mW laser chip. Demand is broadening, but a single market-share chart cannot replace validation through orders and earnings.
Arista The 7800 platform is expected to hold approximately 50% of the scale-out networking market in 2026, while CPO may accelerate in 2028 to 2029. Arista benefits from the expansion of AI cluster networks, but purchase commitments, supply bottlenecks, and customers’ in-house networking solutions will affect the pace of realization. Switch market share and CPO adoption should be tracked separately to avoid pricing in a long-dated technology milestone prematurely.
HPE Morgan Stanley upgraded its rating—not downgraded it—from “Equal-weight” (neutral) to “Overweight” (positive), while cutting, rather than raising, its price target from $71 to $69. The rating upgrade reflects competitive positioning, cash flow, and earnings upside, while the target cut retains valuation and execution risk. Whether the server cycle can continue must be validated through AI orders, margins, cash conversion, and working-capital requirements.
Data-center cooling Direct-to-die cooling, facility water supply at 60 to 70 degrees Celsius, and chillers adapted to different climates are emerging as new design directions. Higher supply-water temperatures may reduce conventional refrigeration requirements, but the available information provides no data on energy consumption, equipment costs, or commercial orders. The actual beneficiaries will depend on who can turn thermal design into repeatable delivery; maintenance costs must also be compared.
Robotics/Autonomous Driving and Space
SpaceX and Starlink
1)Deutsche Bank said SpaceX’s target of $100 billion in annual recurring revenue may be achievable and estimated that cloud-computing transactions with customers including Anthropic and Google could contribute approximately $45 billion to $50 billion; this estimate still requires validation through contracts and actual revenue.
2)Lufthansa will begin progressively deploying Starlink Wi-Fi across more than 850 aircraft next week, with the first flight scheduled for August 19 and full-fleet coverage targeted by 2029. Commercial aviation deployment provides more verifiable end-market demand.
Satellite broadband technology Existing Starlink V2 offers download speeds of approximately 100Mbps to 200Mbps, latency of approximately 25 milliseconds, and upload speeds of approximately 20Mbps to 40Mbps. The planned V3 has approximately 1Tbps of downlink capacity per satellite and targets latency below 20 milliseconds. If these specifications are achieved, competition will advance from remote-area coverage toward fixed-broadband substitution, but launch cadence, terminal capacity, and real-world user experience still require validation.
Internet/Platforms
Uber Robotaxi demand fluctuates sharply by time of day and day of week, meaning a wholly owned fleet must either carry substantial idle assets or forgo peak demand. Uber’s distribution advantage lies in using its own autonomous-driving capacity to serve baseline demand, supplemented by human drivers whose vehicles are not owned by the platform to meet variable demand. This model depends on the platform retaining control of the customer interface and fleet partnerships.
“Robotaxi serves a fixed base of demand, but actual demand fluctuates sharply both within each day and over the course of a week.”
Chinese AI Model Platforms Competition is shifting from price wars toward model capabilities and commercialization, with some platforms offering developers revenue shares of up to 30%, while larger models are also raising capital requirements. Lower prices can expand usage but may shift competitive barriers toward inference costs, developer distribution, and retention. Key metrics to monitor are paid usage, gross margins after revenue sharing, and customer renewals.
“Competition among Chinese large language models is shifting from price wars toward commercialization driven by intelligence levels.”
Platform AI Debt Amazon, Google, Meta, Oracle, Nvidia, and SpaceX issued approximately US$182 billion of investment-grade bonds in 2026, a sharp year-over-year increase; AI-related debt totaled approximately US$1.2 trillion. Expanded financing can support construction but also increases sensitivity to funding costs. Platform valuations will depend more heavily on free cash flow, rather than solely on capital-expenditure growth.
Platform Financing Costs As large technology companies increased AI bond issuance, bond subscription multiples declined and credit spreads widened. Platforms with strong cash-generation capabilities remain able to absorb the pressure, but companies that rely on loans to purchase GPUs and continue expanding will feel the cost pressure sooner. Tighter financing conditions typically flow through to equipment investment with a lag; bond pricing, cash coverage, and capital-expenditure guidance should therefore be assessed together.
“There is growing acceptance of the view that rising financing costs may eventually prompt companies to adjust the pace of equipment investment after a period of lag.”
Platform Capital Efficiency Seven AI builders have incurred more than US$700 billion in cumulative AI capital expenditures since 2020, of which more than US$200 billion remains under construction and has yet to generate returns or incur depreciation; depreciation in the 2nd quarter was approximately US$14 billion, 2.4 times the year-earlier level. The true point of differentiation among platforms will be the sequencing of capacity commissioning, cloud revenue, and depreciation.
Large-Platform Lease Commitments Google, Amazon, Meta, Microsoft, and Oracle have pre-committed approximately US$1 trillion in aggregate future rent, commitments that are not included in current-period capital expenditures. These commitments secure power and data-center capacity but also turn demand-forecasting errors into long-term fixed costs. Future analysis should compare new capacity, customer utilization, lease cash outlays, and contract-maturity structures.
Software/SaaS
Software Sector As of August 7, software and cloud-computing themes had risen 3.29% and 3.71%, respectively, with 20-day gains reaching 11.12% and 11.74%, leading on relative strength. The market is rewarding companies capable of converting AI into usage and cash flow; simply adding an AI label is no longer sufficient. The next question is whether new contracts, consumption, and margins can keep pace with valuation recovery.
monday.com
1)2026 2nd-quarter revenue was approximately US$365 million, 2.4% above expectations, while annual recurring revenue from AI products doubled quarter over quarter.
2)The midpoint of 3rd-quarter guidance was approximately US$4 million below expectations, while lower-end customers remained under pressure.
3)Jefferies maintained its “Hold” rating and raised its price target from US$80 to US$95. The coexistence of a higher price target and operating concerns indicates that incremental AI contributions have yet to fully offset the slowdown among small and medium-sized customers.
“The analyst noted that AI contributions continue to grow, but pressure persists; FY26 guidance remains unchanged, and the lower end of the market continues to face headwinds.”
Snowflake A partner survey indicates that Cortex and AI capabilities have already translated into actual usage, which is more important than the feature launches themselves. The shares rose 3.93% on August 7 and 26.41% over 20 days, as the market prices in accelerating consumption. Risks include usage growth against a high base and cloud costs; key metrics to monitor are product revenue, net retention, and the share of AI workloads.
Datadog Growth in the non-AI business increased from 18% to more than 20%, indicating that observability demand does not rely solely on the AI narrative; AI tools remain in the early stages of commercialization. The shares rose 2.02% on August 7 but had fallen 12.70% over the preceding 5 days. If agent and GPU monitoring unlock new budgets, the revenue trajectory could improve; if they merely replace existing modules, valuation upside is limited.
Samsara After the shares rose 50% over 6 months, app-download growth slowed, placing the valuation under greater scrutiny. Fleet and industrial IoT data can support AI analytics, but if downloads and customer expansion slow in tandem, AI capabilities alone will struggle to sustain the premium. Key metrics to monitor are new large customers, net retention, modules per customer, sales payback periods, and changes in channel efficiency.
Doximity AI capabilities have yet to demonstrate that they can expand pharmaceutical-company budgets, prompting the relevant analyst to downgrade the stock to “Underperform.” The commercialization challenge in healthcare software is not whether the model can generate content, but whether customers increase spending on marketing and clinical workflows. This should be validated through budget share, contract size, renewal rates, and customer-acquisition costs, rather than equating feature usage directly with revenue growth.
Cloudflare The company plans to issue US$2.175 billion of convertible senior notes due 2031. The financing provides capital for edge-cloud and AI-network expansion but also introduces potential dilution and interest expense. The most important test is whether the additional capital can translate into enterprise customers, AI inference traffic, and free cash flow, as well as the conversion conditions, rather than merely extending the investment cycle.
“Cloudflare will issue US$2.175 billion of convertible senior notes due 2031.”
CrowdStrike Demand for AI security remains strong, but the market will distinguish actual annual recurring revenue from conceptual features. Relevant estimates place FY2026 2nd-quarter annual recurring revenue at approximately US$5.82 billion. The shares rose 3.39% on August 7 and 14.55% over 20 days; key metrics to monitor are net new annual recurring revenue, platform consolidation, and customer budgets.
SentinelOne Next-generation security information and event management and AI security capabilities offer growth opportunities, but the company’s market position and ability to sustain growth remain in question. Competition depends not only on model capabilities but also on endpoint coverage, data scale, and channel efficiency. If customers consolidate security vendors, the company must demonstrate that its platform can improve retention, reduce sales costs, and enhance customer-acquisition efficiency.
AI Application Valuations Annual recurring revenue valuation multiples for private AI applications remain high: approximately 125 times for Decagon, 79 times for Sierra, 56 times for Legora, 37 times for Harvey, and 31 times for Ramp. Differences in multiples reflect how the market prices growth rates and verticals, but without margin, retention, and cash-flow data, annual recurring revenue growth cannot be equated directly with equity returns.
Consumer Electronics/Smart Vehicles
Apple
1)According to a Jefferies supply-chain survey, the 20th-anniversary all-glass iPhone, originally planned for release in September 2027 with an estimated average selling price of US$2,600, has been canceled due to excessively low yields; the rating was downgraded from “Hold” to “Underperform,” and the price target was cut from US$285.56 to US$263.66.
2)The bank cut its FY2028 and FY2029 earnings-per-share estimates by 2.1% and 3.4%, respectively. Rising memory prices and the cancellation of the premium model are simultaneously constraining pricing power and margin potential.
3)Trade-in values in the US and Europe were increased by approximately 5% and 2%, respectively, which may support the iPhone 17 but may also pull forward demand for the iPhone 18.
“The analyst noted that the all-glass iPhone has been canceled, memory costs have surged, EPS estimates have been cut, and iPhone 18 sales face pressure.”
Tesla
1)The 2026 US allocation of the Model Y L is reportedly close to sold out, with deliveries beginning in September and estimated delivery times already extended to December. Order strength still needs to be validated through actual deliveries and model-level gross margins.
2)Reports indicate that the company intends to build a US$10 billion solar-manufacturing facility near Houston, covering wafers, ingots, coating, metallization, testing, and automation. The project remains at an early stage, and its funding sources, approvals, and construction milestones have yet to be confirmed.
“The 2026 US allocation of the Model Y L is already close to sold out, with estimated delivery times now shown as December across the country.”
Rivian Needham maintained its “Buy” rating and US$23 price target, arguing that the market is underpricing R2 demand and the company’s autonomous-driving vision. This assessment provides no new delivery or order figures, so validation should focus on R2 mass production, unit economics, deployment of autonomous-driving capabilities, and supply-chain stability. The rating itself cannot substitute for analysis of cash burn and production ramp-up, which require continued verification.
PC Supply Chain Among Taiwanese technology companies’ July revenue results, LCD panels and PC power components were the two weaker segments, with growth of no more than 20%. Rising memory prices benefit DRAM and NAND suppliers but increase system bill-of-materials costs and suppress PC demand. Inventory, end-market pricing, and replacement volumes should be monitored to determine whether brands absorb the higher costs or pass them on to consumers.
Smartphone Memory Supply Chain Supply-chain sources indicate that ChangXin Memory Technologies, facing stronger demand from Huawei and Xiaomi, rejected Apple’s request for lower prices; meanwhile, yield issues for Apple’s premium models and the cost of upgrading to 16GB DRAM create dual pressures. Greater supplier pricing power benefits memory prices but may compress smartphone-brand margins or delay memory upgrades, while end-market inventory also requires monitoring.
Physical AI Devices Robotics and autonomous driving face harder constraints than data centers: safety-critical decisions such as braking must remain local, while training, offline updates, and fleet management can run in the cloud. Larger models increase pressure on memory, weight, power consumption, and thermal management. Edge-device opportunities exist, but commercial realization depends on safety redundancy, system costs, deployment at scale, and insurance-liability costs, all of which require continued verification.
“No automotive braking system would leave the decision to the cloud.”
Jensen Huang’s Select Portfolio