
目录
Post-Market Summary
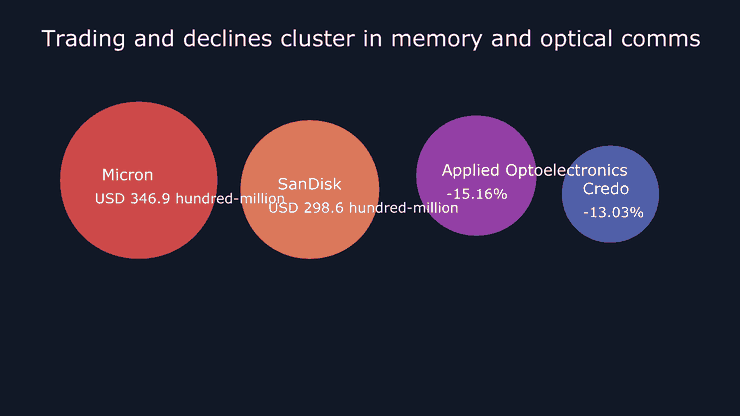
Top 10 US Stocks by Trading Value
Top US Stock Gainers
Top US Stock Decliners
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
CSP/Cloud Capital Expenditure and AI Clouds
GPUs, CPUs, ASICs, and Server Networking
HBM, DRAM, NAND, SSDs, and HDDs
Foundry, Advanced Packaging, Equipment, and Testing
Optical Communications, Passive Components, and Data-Center Infrastructure
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Huang’s Selected Portfolio
Memory Index Performance
Memory Stocks’ Share of U.S. Equity Trading Turnover
Overview
404K SEMI-AI | 2026-08-19
The investment-bank reports cited in this article and the full original text are available on Knowledge Planet.
Post-Market Summary
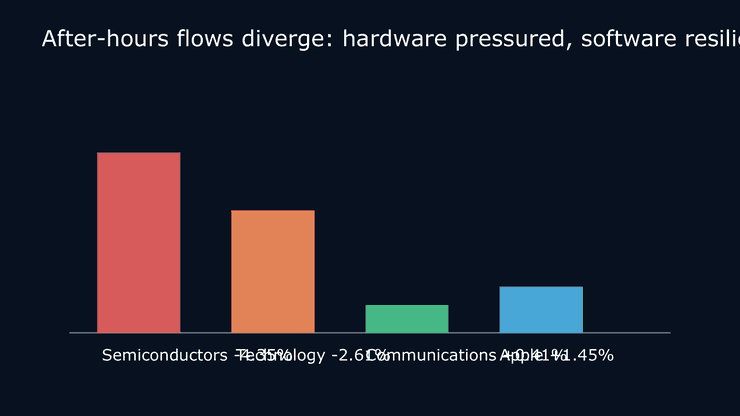
US risk appetite weakened: the S&P; 500 ETF fell 0.70%, the Nasdaq 100 ETF dropped 1.73%, and the equal-weighted S&P; 500 ETF declined 0.41%. Technology lost 2.61%, while communication services gained 0.41%, indicating that pressure was concentrated in richly valued hardware and AI infrastructure rather than spread across all technology assets.
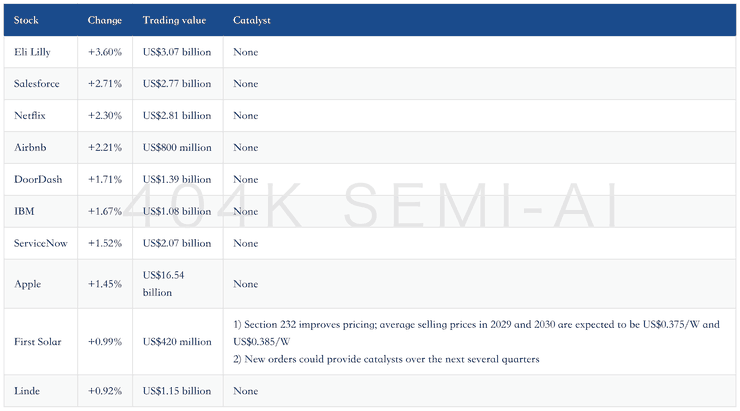
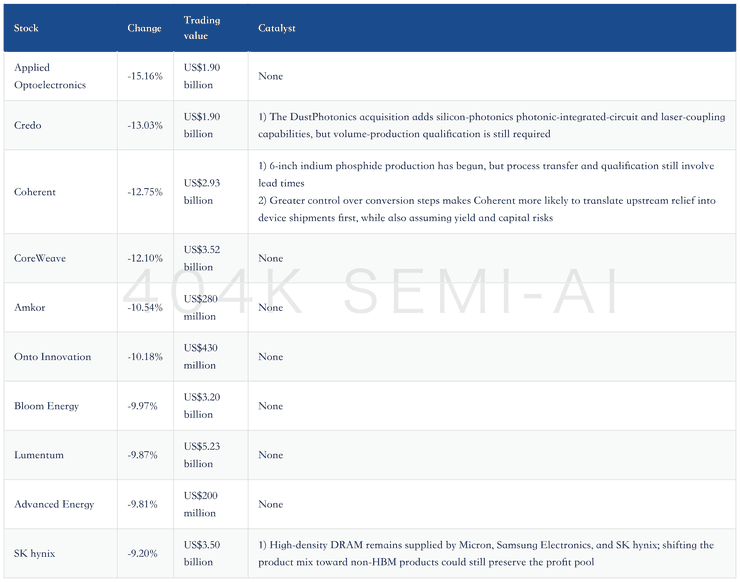
The semiconductor ETF fell 4.35%, with even steeper declines across memory, optical communications, test equipment, and data-center power. Meanwhile, Salesforce, ServiceNow, Netflix, and Apple gained. Investors are increasingly distinguishing between “demand remains strong” and “how much growth is already priced in.” The next test is whether orders can translate into shipments through capacity, yield, and customer-qualification constraints.
Top 10 US Stocks by Trading Value
Top US Stock Gainers
Top US Stock Decliners
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
Anthropic
1) Annualized recurring revenue reportedly exceeded US$65 billion at the end of July, up 15% over 4 weeks and still more than 100% year over year; more than 40% of ARR was generated through third-party cloud channels including AWS Bedrock, Microsoft Foundry, and Google Gemini Agent Enterprise.
2) Monthly growth slowed from 64% in March to 12% in July; both channel contribution and the growth trajectory now require monitoring.
OpenAI
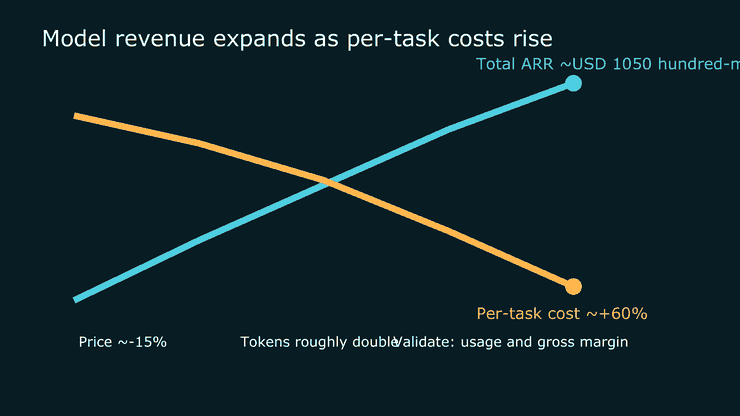
1) Annualized recurring revenue reportedly exceeded US$40 billion at the end of July, with July growth above 20%; combined ARR for OpenAI and Anthropic was approximately US$105 billion, an increase of roughly US$76 billion over the past 7 months.
2) Some frontier reinforcement-learning training was paused over model-alignment issues, so revenue expansion and training stability should be assessed separately.
“Anthropic and OpenAI both added more ARR per day in July than in June.”
Model revenue efficiency: The 2 companies generated a combined US$380 million to US$415 million of annualized revenue per day in July, even as model prices fell approximately 25% over the same period. Revenue is still rising while unit pricing declines; the key questions are whether usage can continue to outpace price cuts and whether costs can keep pace with task complexity.
“The debate now centers on the second derivative.”
CSP/Cloud Capital Expenditure and AI Clouds
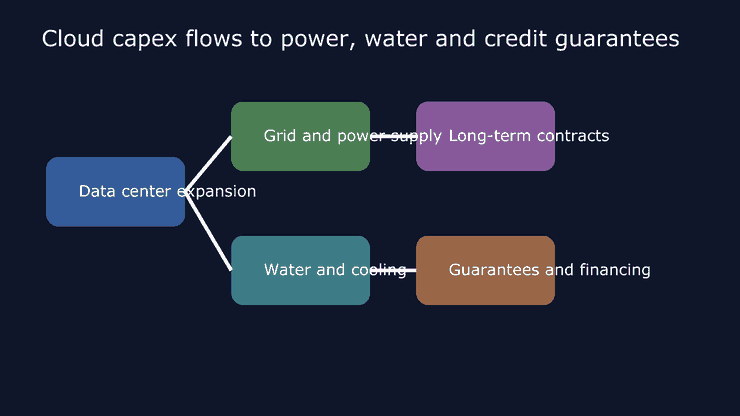
Amazon: Planned investment in its Louisiana data centers has increased from US$12 billion to US$18 billion, with a 3rd campus added. Amazon will fully fund the energy infrastructure and grid upgrades, while also planning to invest up to US$400 million in public water systems and add up to 200 MW of carbon-free energy. Capacity expansion is becoming directly tied to grid and water-infrastructure development.
Meta
1) Meta plans to increase its owned power capacity from approximately 2.5 GW to 15 GW by 2030, making electricity a prerequisite for capital expenditure rather than an ancillary consideration.
2) Oklo has entered the physical-construction phase in Idaho, with long-term plans that include supporting a 1.2 GW Ohio project for Meta’s data centers; timely grid connection still depends on regulation and construction execution.
Nebius
1) In addition to approximately 75 MW of existing US capacity, Nebius plans to add roughly 70 MW by 2027.
2) Phase 2 of the Vineland expansion exceeds 600,000 square feet, with an initial capacity of 300 MW and a US$17.4 billion Microsoft contract anchoring demand; the stock fell 7.60% as the market repriced construction speed and financing requirements.
Nvidia-backed project: Nvidia is providing approximately US$105 billion of guarantees for an Ohio AI campus planned to include 9 buildings, with construction extending through 2028 to 2030. Its AA credit rating is unchanged, indicating relatively strong contractual visibility; the risk lies in the timing mismatch between the guarantee size, construction milestones, and end-customer performance.
GPUs, CPUs, ASICs, and Server Networking
Nvidia
1) The market expects next-quarter revenue of approximately US$94.5 billion, above the US$91.8 billion consensus; the following quarter is projected at roughly US$108 billion, while demand discussions center on US$110 billion to US$111 billion.
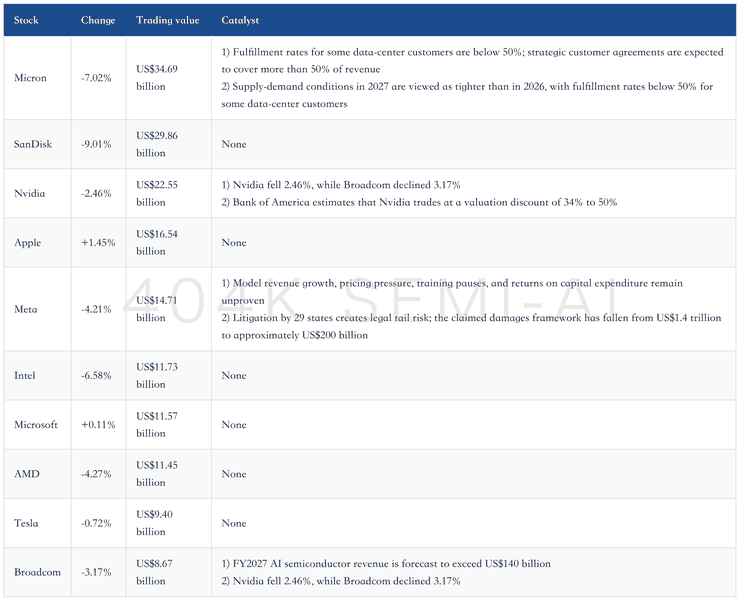
2) Rubin shipment discussions point to approximately 500,000 systems, while the stock fell 2.46%. Demand remains strong, but the near-term debate has shifted to supply execution and the valuation discount.
Broadcom: FY2027 AI semiconductor revenue is forecast to exceed US$140 billion, rising to approximately US$205 billion in FY2028. This implies deployment of roughly 10 GW at US$13 billion to US$14 billion per GW. Whether custom silicon can sustain this trajectory depends on customers’ internal-development cadence, networking-chip share, and system delivery—not the price of an individual chip.
Qualcomm
1) High-bandwidth cache will not feature in AI200 and is expected to debut with AI250 in 2027; the AI300 and server-CPU roadmaps point to 2028.
2) Qualcomm raised its FY2029 non-handset revenue target from US$22 billion to US$40 billion, including more than US$15 billion from data centers; named customers and measured system performance are still needed for validation.
“HBC will debut with AI250 in 2027.”
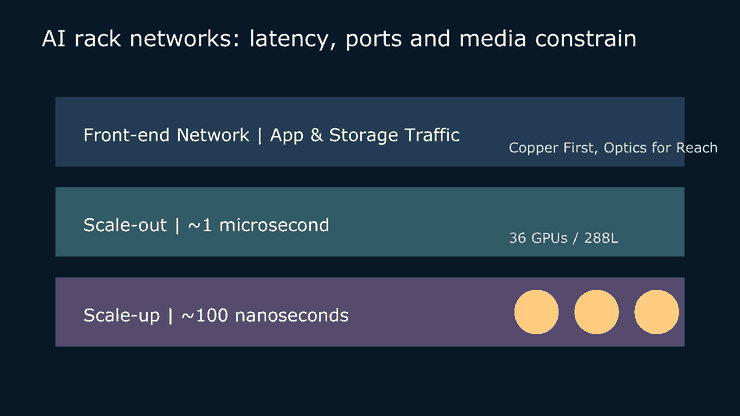
AI rack networking: Scale-out network latency is approximately 1 μs, versus roughly 100 ns for scale-up interconnects. The 288L topology connects 36 GPUs, with 8 lanes per link; each GPU can connect to 9 switch chips through as many as 72 lanes. The bottlenecks are switch topology, copper-cable reach, and fault domains—not merely the total number of ports.
“Use copper wherever possible and optics only where necessary.”
HBM, DRAM, NAND, SSDs, and HDDs
Micron
1) Fulfillment rates for some data-center customers are below 50%; strategic customer agreements are expected to cover more than 50% of revenue, with approximately 10% subject to take-or-pay terms.
2) The industry view is that supply-demand conditions could be tighter in 2027 than in 2026, with HBM average selling prices expected to rise 79%; the stock fell 7.02%, reflecting both crowded positioning and tight supply.
“Memory supply and demand in CY27 will be even tighter than in CY26.”
NAND industry: Revenue for the top 5 vendors rose 77% quarter over quarter to US$68.87 billion in Q2 2026. Samsung Electronics generated US$23.06 billion for a 29.3% share, the SK hynix group generated US$14.27 billion, and Micron generated US$11.85 billion, up 99.2% quarter over quarter. Enterprise SSDs drove revenue, while smartphones and PCs faced cost pressure.
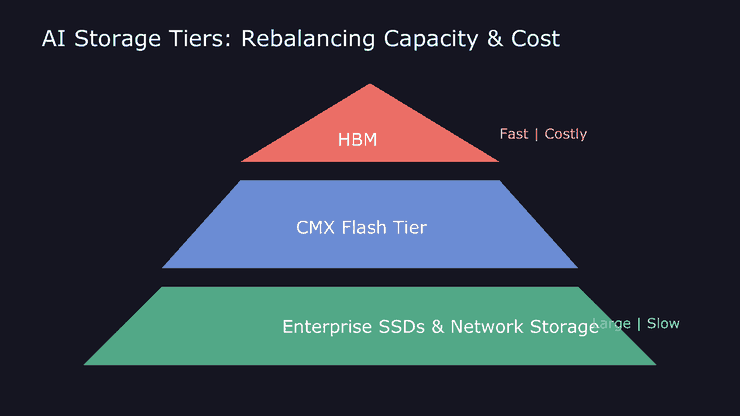
Samsung Electronics: Samsung Electronics and Micron are already supplying Vera Rubin enterprise SSDs in volume production, with Samsung Electronics the primary supplier. NAND spot prices rose approximately 5% over 1 week and a cumulative 11.6% over 3 weeks; the key questions are whether spot-price gains can flow through to long-term contracts and when incremental supply will reach the market.
SanDisk
1) 8 long-term agreements reportedly cover approximately US$94 billion of minimum revenue, with margin discussions ranging from the high-70% range to above 80%.
2) The stock fell 9.01%. Pure-play NAND exposure magnifies upside sensitivity to rising prices, but also amplifies profit risk when the cycle turns.
Foundry, Advanced Packaging, Equipment, and Testing
TSMC
1) Compared with N2P, the A16 backside-power-delivery solution can deliver 8% to 10% higher performance at the same power, or 15% to 20% lower power at the same speed, while increasing density by 8% to 10%; volume production is planned for Q4 2026.
2) Capital expenditure is approximately US$62 billion in 2026, with discussions rising to US$80 billion to US$85 billion in 2027; spending is increasingly concentrated on front-end capacity expansion and advanced packaging.
