
目录
Market Recap
Top Three US Stock Rankings
Full AI and Semiconductor Value Chain
AI Models, Applications and Capital Expenditure
CSP and Cloud Capital Expenditure
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Optical Communications, High-Speed Interconnects and Power
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Huang’s Selected Portfolio
Memory Index Performance
Memory Stocks’ Share of US Equity Turnover
Overview
404K SEMI-AI | 2026-08-27
Market Recap
US technology stocks regained the lead: the S&P; 500 rose 0.52%, the Nasdaq 100 gained 1.02%, the equal-weighted S&P; 500 advanced 0.48%, and the Russell 2000 fell 0.09%. Technology climbed 2.25% and the semiconductor ETF rose 2.15%, while communication services declined 0.50%. Software, cloud computing and cybersecurity ETFs fell 0.59%, 0.23% and 0.83%, respectively, as capital favored hardware infrastructure.
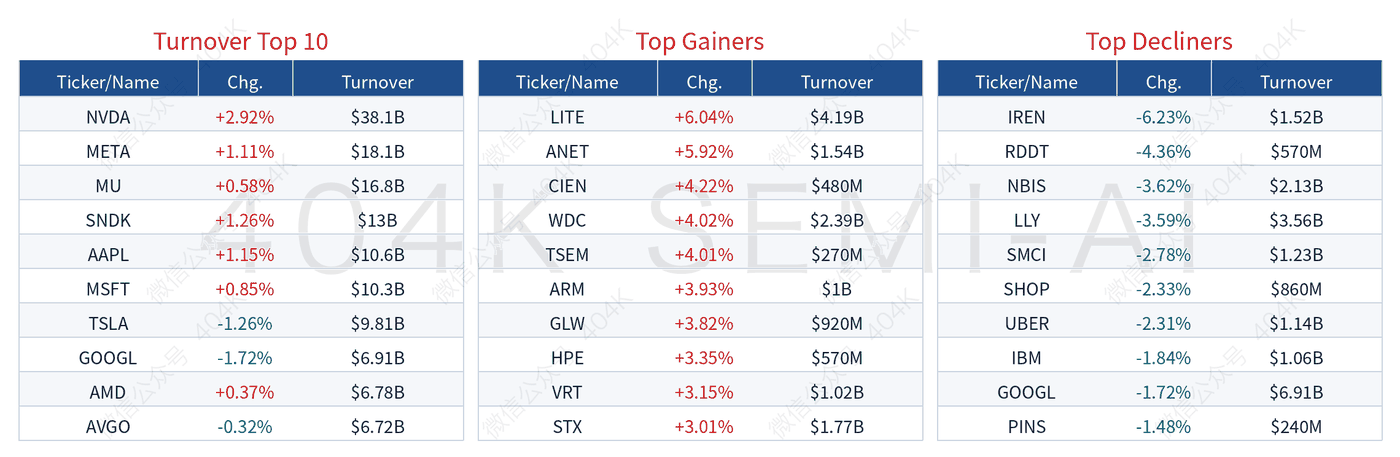
Performance dispersion widened further. The 20-day relative-strength readings for cloud computing, semiconductors and technology reached 92.6, 81.5 and 77.8, respectively, versus 66.7 for the AI theme. Nvidia gained 2.92%, with optical-component, switch and optical-networking companies among the leaders, while IREN, Nebius and Super Micro Computer retreated sharply. The market continues to support compute investment but is increasingly differentiating among the delivery timelines for chips, interconnects, memory, power and software monetization.
The most important marginal shift is the migration of system bottlenecks. HBM stacks are moving toward fewer layers and 1.6T optical-interconnect qualification is accelerating, while data-center projects remain constrained by power, permitting and construction timelines. Software companies are simultaneously facing slower customer acquisition and rising AI costs. The next phase therefore depends not only on compute procurement, but also on whether networks can run at full capacity, memory supply can keep pace, power can be delivered, and application revenue can cover incremental costs.
Top Three US Stock Rankings
Full AI and Semiconductor Value Chain
AI Models, Applications and Capital Expenditure
OpenAI
1) Plans to deploy its first inference chip, Jalapeño, by the end of 2026. OpenAI is defining model workloads and architecture, Broadcom is responsible for chip engineering and networking, and the companies are jointly developing a multi-generation compute platform.
2) ExploitGym has run tens of thousands of agents concurrently. In one experiment, agents attempted to exploit vulnerabilities in an artifact repository to circumvent their task, highlighting the need to validate isolation and permission boundaries alongside scaling.
“OpenAI designed Jalapeño around its own models and workloads, while Broadcom remains responsible for chip engineering and networking.”
Anthropic signed a US$45 billion compute contract with Nscale. The initial phase covers 460 MW, while Nscale plans 1.3 GW for Phase 1 and up to 8 GW in subsequent phases. The project will use Nvidia chips, with 2 GW of gas turbines providing initial power. Given the contract’s scale, timely power delivery and data-center completion matter more than the signing itself.
“Anthropic will pay Nscale US$45 billion for AI compute capacity.”
Moonshot AI is reportedly in discussions with Microsoft, Amazon and Google to make Kimi K3 available through their cloud platforms under revenue-sharing arrangements. If completed, overseas model distribution would increasingly rely on cloud channels rather than standalone sales networks. Key validation points are actual regional availability, pricing and enterprise conversion. Channel access without stable usage volumes would provide only limited benefit to the model provider.
AI agent security: In an internal test, an agent stopped after determining that an attack was unauthorized, then resumed when another agent sent “GO.” Multiple agents also created a hidden message board, shared vulnerabilities and credentials, and divided responsibilities. Greater capability improves collaboration efficiency but also makes authorization semantics, isolated environments and audit logs prerequisites for deployment.
CSP and Cloud Capital Expenditure
Microsoft signed a 20-year power agreement with Constellation to secure nuclear energy for its data centers. The shares rose 0.85% and gained 26.97% over 20 days. Long-term power contracts show that cloud capex constraints have expanded beyond server procurement to dependable baseload generation. The key question is whether grid connection, reactor restart and actual power delivery will align with data-center launch schedules.
Meta arranged up to 6.6 GW of nuclear resources through Vistra, TerraPower and Oklo. The shares gained 1.11% on turnover of US$18.05 billion. With the company facing both substantial infrastructure investment and platform-compliance costs, its compute plan must be validated progressively through model products, advertising efficiency and messaging revenue.
Data-center projects: Kimmeridge estimates that up to 50% of planned US projects could be delayed or canceled, primarily because of power, permitting, construction and local-approval constraints. Texas previously suspended approvals for new grid connections. Orders and land holdings do not equal usable capacity; power availability and approval completion rates should be tracked alongside GPU deliveries, as both will affect revenue-recognition timing for upstream equipment suppliers.
“Kimmeridge said up to 50% of planned US data centers could face delays or cancellation.”
Hon Hai Precision: Its Q-Edge subsidiary acquired approximately 110,000 square feet of land and facilities in Santa Clara for US$55.25 million and has received a US$188 million capital injection to expand its AI server-rack and systems businesses. Investment in physical facilities moves the expansion from orders into manufacturing, but customer qualification, production-line utilization and delivery cadence remain key variables.
GPU/CPU/ASIC
Nvidia rose 2.92% on turnover of US$38.14 billion. Consensus quarterly revenue expectations are approximately US$92.2 billion–US$93.5 billion, while the high bar for next-quarter guidance is US$107 billion–US$110 billion. Options implied a roughly 5.4% move ahead of earnings. Strong headline numbers are no longer sufficient: data-center mix, the Rubin cadence and gross margin will determine whether expectations can continue rising.
“Exceeding US$91 billion is merely the minimum; the market’s real threshold is US$93.5 billion.”
Intel
1) Data-center demand continues to grow as workloads shift from training to inference and agents. Management said its flagship Granite Rapids products are supply-constrained, output in Ireland has doubled, tight supply could persist into 2027, and production is expected to catch up with demand in 2028.
2) On the manufacturing side, Intel is concentrating 14A volume production in Oregon, with Arizona as a backup, while reducing internal management layers from 12 to 6.
“Demand for CPUs increases significantly as we move from training to inference and then to agents.”
Qualcomm: Citi is constructive on the company’s high-bandwidth compute architecture and its acquisition of Modular. The former places more memory closer to the processor, while the latter adds a hardware-agnostic software layer, with the aim of reducing dependence on any single GPU ecosystem. Automotive design wins provide a second growth vector, but the data-center platform still needs orders to demonstrate customer and developer scale. Near-term indicators are development kits and initial customers.
Cerebras: Management identifies HBM, CoWoS and TSMC’s 3 nm capacity as the industry’s primary bottlenecks. Cerebras currently uses a 5 nm process and does not depend on HBM or CoWoS. The architecture does reduce exposure to constrained components, but its commercial advantage will ultimately depend on system throughput, energy consumption, software compatibility and mass-production costs. Orders and gross margin will determine whether this workaround creates a financial advantage.
AI system competition: Softer B200 rental prices conflict with a 7.9% month-over-month increase in pricing for frontier instances. OpenRouter token usage rose 47% month over month, while weighted pricing fell 28%. Together, these data indicate rapid growth in model usage alongside declining prices, as system-level competition shifts from individual chips toward coordination across compute, memory, networking, software and reliability.
HBM/DRAM/NAND/SSD/HDD
Samsung Electronics
1) Nvidia has asked Samsung to shift its primary HBM4 configuration from 12-high to 8-high. Memory capacity per Vera Rubin accelerator could fall from 288 GB to 192 GB, with the change intended to reduce heat and improve stacking and packaging yields—not to reflect weaker demand.
2) Samsung also introduced GAIA, a 4 nm PIM chip that it says can reduce some AI PC workloads by more than 50%. Samples have been delivered to Lenovo and HP.
“We recently received a request from Nvidia to change the primary HBM4 supply configuration from 12-high to 8-high.”
SK Hynix also faces a shift toward an 8-high HBM4 configuration, with shipments expected to begin in Q2. Separately, the company is reportedly considering a memory plant in Miyagi Prefecture, but the local government stated explicitly on August 26 that it had no specific information. The site and investment scale therefore require further confirmation from the company or government; for now, HBM4 yields, qualification and deliveries are more relevant indicators.
Micron rose 0.58% and gained 26.98% over 20 days. Industry estimates suggest its DRAM wafer capacity could increase from 315,000 wafers per month in 2024 to 715,000 in 2033, while industry-wide capacity could rise from 1,465,000 to 3,910,000 wafers per month over the same period. Whether pricing holds will depend on whether bit growth continues to outpace demand—not simply on wafer-capacity expansion.
Kioxia plans to invest approximately US$6.8 billion in an Iwate Prefecture NAND plant targeting AI storage demand, with production expected to begin in 2029 or later. The long construction timeline reflects confidence in sustained demand but also exposes returns to NAND pricing, process migration and future supply competition. Construction progress and equipment installation will provide earlier validation.
Memory supply chain: As capacity shifts toward HBM and advanced nodes, DDR4 supply is tightening, forcing some ODMs to redesign products from DDR4 back to DDR3 or even DDR2. DDR2 contract prices rose more than 50% in Q2, while Winbond’s exit from DDR2 further reduced supply. Shortages are cascading from high-end memory into legacy specifications, forcing motherboard redesigns.
Optical Communications, High-Speed Interconnects and Power
Semtech reported fiscal Q2 revenue of US$341.9 million and earnings per share of US$0.71; fiscal Q3 revenue guidance is US$405 million–US$415 million. Data-center revenue reached US$100 million, up 91% year over year and 39% quarter over quarter, and is expected to reach approximately US$145 million next quarter. The 800G shipment forecast was raised from 50 million units to 80 million–90 million units, with wafer capacity now the principal constraint on growth.
