目录
Post-Close Summary
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Semiconductor Equipment/Testing and Power Semiconductors
Optical Communications/Optical Value Chain and Space
Internet/Platforms
Software/SaaS
Consumer Electronics/Smart Vehicles
Jensen Huang's Select Portfolio
Overview
404K | 2026-08-10
Post-Close Summary
The latest trading session closed on August 7. The S&P; 500 rose 0.61%, the Nasdaq 100 gained 1.17%, the equal-weighted S&P; 500 advanced 0.69%, and the Russell 2000 climbed 1.11%. Both heavyweight and small-cap stocks strengthened, indicating that the market was not being lifted solely by a handful of giants, although performance dispersion within technology remained substantial.
Cloud computing rose 3.71% and software gained 3.29%, ranking first and second, respectively, in 20-day relative strength among thematic ETFs; semiconductors rose 1.96% but remained down 4.64% over 20 days. Capital is covering underweight chip positions in the short term, while the more durable trend remains in cloud and software. The key validation point is whether semiconductors can break out of their 20-day weakness.
Industry developments are clearer: agents are broadening demand beyond HBM to DRAM, NAND, enterprise SSDs, and HDDs, while optical interconnects are benefiting from cluster expansion across racks. SoftBank’s data-center financing timeline, Micron’s assumptions for slowing price increases, and the ramp-up in optical-communications capacity constitute the three most important sets of evidence to track today.
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
AI storage hierarchy: Training relies most heavily on HBM; advanced inference pushes demand for NAND flash and enterprise SSDs to “extremely high”; and the agentic stage simultaneously lifts demand for conventional DRAM and NAND to “extremely high” and HDD demand to “high.” Demand no longer accrues only to the fastest chips but is spreading to working memory, persistent storage, and data retrieval.
SoftBank Group
1) Bernstein said NAV increased from ¥40.1 trillion to ¥72.3 trillion and loan-to-value declined to 13%; it maintained “Outperform” with a ¥11,100 price target.
2) Nomura cut its price target from ¥10,220 to ¥9,040 while maintaining “Buy,” with a focus on the proprietary AI accelerator expected by end-2026. Both firms are positive on the AI assets but differ over financing and execution risks.
"Reported leverage is conservative, but the funding calendar is now the central investor issue."
OpenAI: SoftBank completed follow-on investments of $10 billion in both April and July and plans to pay another $10 billion in October; once all investments are completed, cumulative investment is expected to reach $64.6 billion for a stake of approximately 13%. As of end-June, cumulative investment was $44.6 billion with a fair value of $89.6 billion, increasing both the valuation uplift and concentration in a single unlisted asset.
SB Energy: The company has secured approximately $19 billion in cumulative project financing, with about 5GW of generation and energy-storage capacity operating or under construction. The first phase of the French project targets 3.1GW by 2031 with an investment of €45 billion; the 10GW Ohio project is still negotiating with long-term offtakers, while the Texas project has already signed a long-term lease with OpenAI, indicating diverging execution timelines.
Volex: FY2026 revenue reached $1.243 billion, up 14% year over year; the Complex Industrial Technology division delivered 56% organic growth, implying data-center revenue of approximately $240 million, close to 20% of group revenue. Gross margin increased from 21.4% to 23.2%, but inventory rose by nearly $68 million and free cash flow was broadly flat; a second cloud customer and cash conversion will determine whether this growth can be replicated.
"Volex already has approximately $240 million in data-center revenue, genuine validation from major customers, and the ability to deliver at scale."
GPU/CPU/ASIC
NVIDIA: Shares rose 2.27% on August 7 and 11.56% over five days. Reports suggest that per-chip HBM capacity in Rubin Ultra may be reduced from 288GB to 192GB, while NVL 576 would distribute 576 GPUs across eight racks; if true, stronger cross-rack optical connectivity would use network aggregation to compensate for lower per-chip memory, shifting HBM and networking from a substitution relationship to a system-level trade-off.
Broadcom: Shares rose 1.71% on August 7, 9.88% over five days, and 6.95% over 20 days. Industry estimates suggest that even if MediaTek gains share, Broadcom may still account for 76% of ASIC shipments in 2029; whether this high share materializes will depend on the pace of custom-chip customer expansion and networking-chip content, rather than merely quarter-to-quarter valuation changes.
AMD: Shares fell 1.21% on August 7 and 13.36% over 20 days but remained up 116.30% year to date. The Taalas acquisition appears more focused on acquiring custom EDA workflows, FPGA capabilities, and embedded AI expertise: its approach requires changing only a small number of upper-layer masks among 14 to 18 metal layers, potentially shortening the model-to-chip cycle to approximately two to three months, although frequent model updates limit its applicability to general-purpose data-center inference.
Cerebras: WSE4 will reportedly increase power delivery and double clock speed, but appears closer to a generation 3.5 update. Engineering analysis maintains an estimated final yield of approximately 20% and identifies parametric yield, power-supply ripple, and voltage domains as the actual bottlenecks; the next step is to cross-check relative yield, gross margin, cost of goods sold, and average selling price rather than focusing solely on peak performance.
"The author maintains a model estimating final yield at approximately 20%, distinguishing three stages—defect, packaging, and parametric yield—and believes functional yield may reach very high levels through the NoC and spare cores."
Arm: Shares fell 1.43% on August 7, rose 17.89% over five days, and fell 12.62% over 20 days. SoftBank views data-center CPU penetration, expansion into chip products, and agentic AI as structural opportunities for Arm; the company’s long-term guidance points to $15 billion in AGI CPU sales in FY2031, a serviceable market exceeding $100 billion, and an adjusted operating margin above 30%, making supply capability the next validation threshold.
HBM/DRAM/NAND/SSD/HDD
Micron
1) Citi cut its price target from $1,400 to $1,150 while maintaining “Buy,” lowering its valuation benchmark from 10 times to 8 times FY2027 earnings per share.
2) Its sequential DRAM pricing assumptions for the next four quarters are 23%, 9%, 2%, and 0%, while its NAND assumptions are 29%, 7%, 0%, and -1%; approximately 40% of DRAM bits are already priced under long-term agreements. Price increases are slowing, but contract coverage reduces the risk of a sharp margin decline.
"Tweaking DRAM/NAND Pricing Assumptions — We adjust Aug/Nov/Feb/May Q/Q"
Samsung Electronics: Second-quarter DRAM average selling prices rose by approximately the mid-40% range quarter over quarter, while NAND increased by approximately the high-60% range; the company plans to allocate 60% to 70% of planned capacity to long-term agreements. Industry reports also indicate that HBM4 production yield reached 80% six months after mass production began and that third-quarter HBM4 sales may more than triple quarter over quarter, making yield and customer qualification more important than capacity expansion alone.
SK hynix: The company plans to invest KRW54 trillion through 2031, including KRW35.2 trillion in the second fab at Yongin and KRW19.1 trillion in Cheongju M17, covering HBM, DRAM, and NAND. Its existing 10 long-term agreements typically have five-year terms; large-scale capacity expansion addresses long-term supply but also turns equipment readiness, yield, and demand durability into new risk factors.
SanDisk: September-quarter revenue guidance was pressured by weaker pricing, but the company has signed eight agreements covering data-center and OEM customers, with a weighted-average term of four years, and expects them to cover approximately 50% and 66% of bits in FY2027 and FY2028, respectively. Spot-price elasticity is weak, while contract visibility is stronger; the next question is whether agreement pricing can protect cash flow.
HBF: The specification retains an 8G UCIe option, while 64G UCIe is expected to require another approximately six to nine months to complete qualification and stabilize, suggesting that the NAND PHY or clocking system may be the bottleneck. Sixteen UCIe groups with 64 channels each should help mitigate crosstalk, but REFCLK, jitter, EMI, and reliability requirements are complex; technical operability does not equate to optimal stacking efficiency.
"On HBF, the author has shifted from outright opposition to acknowledging that it ‘may work,’ but still believes the interface, clocking, reliability, and stacking efficiency are suboptimal."
Semiconductor Equipment/Testing and Power Semiconductors
Lam Research: Shares rose 1.82% on August 7 and 6.26% over five days but remained down 11.13% over 20 days. Management said cleanrooms would progressively come online over the next 12 months and potentially longer, allowing wafer-fabrication equipment demand to continue through 2027; whether the near-term share-price recovery becomes a medium-term trend depends on whether new cleanroom commissioning translates into equipment revenue.
"Frankly, looking ahead—I don't know—over the next 12 months and potentially longer, cleanrooms will progressively come online."
Applied Materials: Shares rose 2.21% on August 7 and 6.20% over five days but remained down 10.52% over 20 days, while gaining 100.52% year to date. The trading pattern resembles Lam Research: a strong short-term recovery but a still-weak 20-day trend; fundamental validation should come from deposition, etch, and materials-engineering orders for new fabs, rather than extrapolating solely from a broad equipment-sector rally.
KLA: Shares rose 2.53% on August 7 and 8.36% over five days but fell 14.43% over 20 days. Competition over advanced-node and HBM yields increases the value of process control and metrology, but the shares have yet to recover from the 20-day drawdown; the next questions are whether customer capacity expansion also raises inspection intensity and whether order growth can outpace total wafer-fabrication equipment spending.
Wolfspeed: Shares rose 19.14% on August 7 and 39.16% over five days but remained down 6.86% over 20 days. The company sued Navitas Semiconductor over six patents, but engineering analysis suggests that one GaN patent will expire in approximately four months and that Wolfspeed no longer has GaN products; the litigation catalyst and product competitiveness should be assessed separately.
Navitas Semiconductor: Shares rose 12.02% on August 7, 27.90% over five days, and 3.12% over 20 days. The patent dispute has introduced event-driven volatility, but the evidence also calls the competitiveness of its existing SiC products into question; the variables that truly affect revenue remain mass production, customer qualification, and gross margins for GaN and SiC products, rather than the litigation headline itself.
Optical Communications/Optical Value Chain and Space
Applied Optoelectronics: Shares rose 9.19% on August 7, 43.80% over five days, and 13.10% over 20 days. Expansion of 800G-and-above optical-module capacity at the Texas facility is the principal incremental driver, but phase-noise, line-shape, and effective-linewidth data for the 300mW DWDM laser have not yet been disclosed; engineering analysis estimates that the relevant capability may still require two to three years, making mass-production yield more important than the concept.
Lumentum: Shares rose 6.22% on August 7, 24.68% over five days, and 10.99% over 20 days. The company has demonstrated a 0.5MHz linewidth, providing verifiable data for its high-power laser capability; tight InP supply and demand from CPO and NPO jointly support product value, but after the sector’s rapid rally, investors should continue monitoring orders and capacity rather than relying solely on a shift in narrative.
Coherent: Shares rose 13.44% on August 7, 44.22% over five days, and 16.84% over 20 days, with a 20-day stock-level relative-strength score of 93.2. Even if the CPO timeline is delayed, demand for 800G and 1.6T pluggable optical modules may persist longer; current strength reflects tight supply and renewed capital inflows, but subsequent earnings reports must validate revenue, yield, and capacity utilization.
Aeva: Industry reports suggest that its semiconductor optical amplifiers may be used in high-power lasers for NPO and CPO, with InnoLight identified as the potential customer, although the end cloud customer remains speculative. This signal reinforces the high-power laser shortage thesis but is insufficient to infer revenue directly; confirmation of order size, delivery timing, and the ultimate customer is required for actionable evidence.
Rocket Lab: Shares rose 9.46% on August 7 and 27.53% over five days. Disclosures indicate that the company has more than 70 contracted missions, an order backlog exceeding $2.2 billion, and $680 million in revenue over the past 12 months; share-price momentum is very strong, but subsequent validation centers on mission execution, backlog conversion into revenue, and launch cadence, rather than treating long-term space demand as current-period profit.
Internet/Platforms
Platforms: Communication services rose just 0.06% on August 7 and fell 0.35% over 20 days, significantly underperforming cloud computing’s 11.74% 20-day gain. Platform value is diverging along two paths: agents become the new user gateway, or AI is embedded in existing products and distribution channels; whoever owns the customer is more likely to retain pricing power and profits.
"How much value remains at the model/lab layer rather than flowing to the platforms, operating systems, and applications above it?"
Google: Fell 0.96% on August 7, 0.51% over 5 days, and 0.81% over 20 days. Gmail, operating systems, and existing user gateways support embedding AI into current bundles, but may also depress the price of standalone intelligence; the stock has underperformed platform peers, and the next test is whether cloud growth and AI monetization can demonstrate that its distribution advantage is converting into revenue.
Meta: Rose 0.37% on August 7 and 6.36% over 5 days, but fell 11.52% over 20 days. The short-term rebound has not yet reversed the medium-term weakness, and the market is still assessing whether recommendation systems and agents can improve advertising monetization and whether capex can translate into visible revenue; 20-day relative strength is 28.0, indicating limited investor conviction.
Microsoft: Rose 0.03% on August 7 and 29.83% over 20 days, with 20-day stock relative strength of 98.5. Office and enterprise customer channels make it easier to bring AI into existing paid relationships, while offering greater control over the tradeoff between price and usage; the current trend is leading, but its strength means further gains depend increasingly on sustained delivery from Azure and enterprise AI revenue.
"Another scenario is that intelligence is distributed through products people already use: Gmail, Office, iPhone, operating systems, devices, and enterprise software."
Amazon: Rose 0.82% on August 7 and 11.88% over 20 days. The company is building a data center on 56 acres in Gilroy, California, and has committed to a wastewater recycling system and pipeline, but has not disclosed who will bear construction and operating costs over the next 30 years; the project demonstrates continued deployment of cloud capex while bringing water usage and infrastructure costs to the forefront.
"Amazon committed to building a wastewater recycling system and a pipeline, but declined to say who would bear the construction and operating costs over the next 30 years."
Uber: Rose 6.46% on August 7, with gross bookings up 22%, non-GAAP EPS up 35%, and trailing-12-month free cash flow exceeding $10 billion for the first time. Simultaneous improvement in growth, profitability, and cash flow matters more than order growth alone; the next question is whether cash conversion can be sustained and cover investment in platform incentives.
"We continue to convert strong revenue growth into faster profit growth and substantial cash generation."
Netflix: Rose 0.61% on August 7 and 1.05% over 20 days, but fell 18.52% YTD. Streaming already has direct customer relationships, so AI is more likely to improve recommendations, content production, and advertising efficiency than rebuild the user gateway; the stock lacks a strong trend, and the key test is whether improved usage efficiency can translate into subscription or advertising revenue.
Airbnb: Rose 17.43% on August 7, 17.52% over 5 days, and 19.82% over 20 days, with 20-day stock relative strength of 95.5. Supply-demand matching and direct traffic remain moats amid the reshuffling of AI distribution, but following the one-day surge, bookings, stays, and margins must provide further support to avoid mistaking an event-driven rerating for sustained growth.
Shopify: Rose 2.80% on August 7, 29.38% over 5 days, and 23.69% over 20 days, with 20-day stock relative strength of 97.0. Its aggregation of merchant tools, payments, and distribution positions it to embed AI into existing workflows; the current price trend is very strong, and the next question is whether merchant adoption can generate higher subscription or transaction revenue.
Reddit: Rose 7.18% on August 7 and 14.95% over 5 days, but fell 17.22% over 20 days. Community content both attracts users and has value for AI data licensing, but the short-term recovery has not yet reversed the medium-term weakness; the next test is whether licensing revenue and advertising growth can improve simultaneously, rather than the valuation relying solely on data scarcity.
DoorDash: Rose 1.41% on August 7 and 12.74% over 20 days, with 20-day stock relative strength of 87.9. The local-services platform controls the transaction gateway and fulfillment network, while AI can improve matching and delivery efficiency; whether the strength persists depends on order density, fulfillment costs, and merchant monetization, rather than the automation narrative alone.
Pinterest: Rose 1.50% on August 7 and 5.15% over 20 days, with 20-day stock relative strength of 75.0. Visual search and shopping discovery are well suited to generative AI, but the platform still needs to convert better recommendations into clicks and advertising pricing; the current trend is moderate, and revenue validation matters more than the release of user-facing features.
Snap: Rose 2.11% on August 7, 13.65% over 5 days, and 13.89% over 20 days, with 20-day stock relative strength of 90.2. AR and social content provide gateways for AI applications, but the stock remains down 34.44% YTD; the short-term recovery and long-term monetization have not yet converged, with advertising efficiency and cash flow the next areas to watch.
The Trade Desk: Fell 21.90% on August 7, 29.34% over 20 days, and 63.38% YTD, with 20-day stock relative strength of 3.8. The programmatic advertising platform has undergone a sharp derating as the market reassesses open-internet traffic and AI-driven advertising efficiency; stabilization requires evidence from revenue, customer retention, and margins.
AppLovin: Rose 3.32% on August 7, but fell 31.59% over 20 days and 43.91% YTD. SaaS valuation comparisons place the company on the relatively undervalued side, but the price trend remains weak; a valuation recovery requires simultaneous delivery on advertising monetization, revenue growth, and margins, as a low multiple is not itself a catalyst.
"Another scenario may generate far broader usage, but as intelligence is bundled into products that already have users, it will place greater pressure on the price of intelligence."
Software/SaaS
Software: The software ETF rose 3.29% on August 7, 8.57% over 5 days, and 11.12% over 20 days, with 20-day relative strength of 96.3. Investor preference is shifting from software that merely touts AI features toward companies that can demonstrate growth, profitability, and customer expansion simultaneously; the higher the valuation, the greater the need for sustained delivery through contracts and cash flow.
"One limitation of ChatGPT Work and Claude Cowork is that they assume non-programmers cannot understand how to approach problems like programmers, so they hide all of this away."
Palantir: Rose 10.32% on August 7, 39.78% over 5 days, and 35.67% over 20 days. Q2 net dollar retention rose to 157%, while total contract value in the U.S. commercial business reached $2.1 billion; the company signed 220 deals worth more than $1 million, including 73 worth more than $10 million, as AIP moved from pilots toward enterprise-wide standardization.
"Q2 showed this transition accelerating: NDR rose to 157%, while TCV in the U.S. commercial business reached $2.1 billion"
Salesforce: Rose 3.20% on August 7 and 18.01% over 20 days, with 20-day stock relative strength of 94.7. The acquisition of Fin is viewed as an example of using a new product to reshape growth; if agents can be embedded into sales and service workflows, revenue upside will exceed that from simply charging more for features. The risk is that AI may also directly replace contact-center operations.
ServiceNow: Rose 6.42% on August 7, 15.94% over 20 days, and 40.31% over 60 days. Workflow and IT service management are among the earlier areas of enterprise AI deployment, and the strong trend reflects high budget priority; the next test is whether agents expand contract value rather than merely increase seat utilization.
Snowflake: Rose 3.93% on August 7, 26.41% over 20 days, and 117.46% over 60 days, with 20-day stock relative strength of 97.7. Data governance is a prerequisite for enterprise agent deployment, but valuation comparisons indicate a substantial premium; product revenue growth and consumption by large customers are critical to absorbing that premium.
MongoDB: Rose 7.78% on August 7, 18.17% over 5 days, and 16.58% over 20 days, with 20-day stock relative strength of 92.4. Databases are foundational infrastructure for AI applications and benefit from data growth generated by new applications; the price already reflects strong expectations, and the next question is whether cloud consumption, customer expansion, and margins improve simultaneously.
Cloudflare: Rose 5.57% on August 7, 11.87% over 20 days, and 60.75% over 60 days. The edge network can support AI inference and security traffic, but valuation comparisons place the company at a premium; if revenue growth cannot keep pace with network usage, valuation sensitivity will emerge before the business weakens.
"Growth companies at earlier stages of development often appear overvalued when measured on forward P/E."
CrowdStrike: Rose 3.39% on August 7, 14.55% over 20 days, and 57.03% over 60 days, with 20-day stock relative strength of 90.9. Cybersecurity is a prerequisite investment for enterprise AI deployment, with higher budget priority than high-risk ERP replacement; the key test is whether platform consolidation can increase customer spending while preserving margins.
Datadog: Rose 2.02% on August 7, but fell 12.70% over 5 days and 9.17% over 20 days. Observability benefits from the growing complexity of AI workloads, but the share price indicates expectations are cooling; a recovery in new customers, cloud consumption, and large contracts would be needed to show that the pullback merely reflects changes in budget timing.
GitLab: Rose 9.22% on August 7, 20.20% over 20 days, and 68.85% over 60 days, with 20-day stock relative strength of 96.2. AI coding directly improves development efficiency while also expanding demand for code security and collaboration; whether the strength continues depends on paid seats, revenue per customer, and conversion of AI features.
SAP: ERP replacement carries high risk and typically will not be among the first areas where enterprises deploy agents; if agents can eventually handle payroll and financial close, a clear return on investment may reaccelerate budgets. For now, this looks more like deferred budget sequencing than a confirmed structural decline.
"Changing ERP is higher risk, so it will not be the first area where you adopt entirely new agent capabilities."
Intuit: Tax, accounting, and payroll use cases have clearly defined processes and measurable returns on investment, making them suitable for agent adoption once data and security conditions are mature. The opportunity is to convert automation into higher retention and revenue per customer; the risk is slower customer adoption in high-risk financial workflows.
Freshworks: The company has both customer experience and IT service management businesses; the former may be displaced by AI, while the latter may benefit from enterprise automation. The two businesses are moving in opposite directions, so the assessment cannot rely solely on consolidated growth; segment-level customer retention and margins will determine the direction of the rerating.
HubSpot: Distribution channels driven primarily by search traffic may be rewritten by AI gateways, with the risk initially affecting customer acquisition rather than necessarily the product itself. If the company can embed agents across the marketing, sales, and service loop, budget pressure may ease; the key metrics are organic traffic, customer acquisition costs, and customer expansion.
Block: The company said code changes per engineer have increased 150% since the beginning of the year, while Square launched 130 features in H1 2026, more than 3 times the year-earlier number. AI productivity is already translating into delivery speed, but the investment implications still depend on whether new features can generate revenue and reduce unit R&D; costs.
"Since the beginning of the year, code changes per engineer have increased 150%. For reference, Square launched 130 features in H1 2026."
Consumer Electronics/Smart Vehicles
Consumer Electronics and Smart Vehicles: Performance diverged across consumer electronics, automotive chips, and robotics. Apple rose 0.29% on August 7, Tesla rose 2.83%, and most automotive-grade and power chips rebounded; however, Tesla fell 19.42% over 20 days, indicating that short-term covering has yet to alter the medium-term pressure on the smart-vehicle supply chain.
Apple
1) The stock rose 0.29% on August 7 and fell 0.63% over 20 days; reportedly, the company is exploring Apple Watch devices without displays, with different screen types, and in multiple sizes.
2) The company is also testing CXMT memory chips for certain iPhones and MacBooks; CXMT's 2026 capacity is reportedly fully booked, with prices close to or above those of leading memory manufacturers, while supplier diversification remains constrained by capacity and regulation.
"Apple is considering launching new devices without displays, as well as devices featuring different screen types and multiple sizes"
Tesla: The stock rose 2.83% on August 7 and 5.58% over 5 days, but fell 19.42% over 20 days and 24.99% year to date. Autonomous driving and robotics remain pillars of the long-term valuation, but price trends indicate that the market requires nearer-term product and financial validation; deliveries, gross margin, and tangible autonomous-driving progress are all indispensable.
Qualcomm: The stock rose 4.66% on August 7 and 13.72% over 5 days, but fell 11.26% over 20 days. Mobile SoCs and edge AI provided rebound catalysts, but the stock fell 20.18% over 60 days; if on-device models cannot drive replacement demand and chip content, the near-term recovery will struggle to translate into a revenue trend.
Skyworks: The stock rose 5.66% on August 7 and 16.96% over 20 days, with a 20-day stock relative strength reading of 93.9. RF front-end products have led the recovery in the smartphone supply chain; the next question is whether replacement demand and content per device can sustain the momentum. If end-market unit sales do not improve, the strength will largely reflect an inventory-cycle recovery.
Mobileye: The stock rose 3.68% on August 7 and 9.95% over 5 days, but fell 8.59% over 20 days and 22.26% year to date. Advanced-driving solutions continue to recover, but the medium-term trend remains weak; order visibility, vehicle-model production ramps, and content per vehicle explain revenue better than short-term industry sentiment.
Aurora: The stock rose 4.13% on August 7, 10.66% over 20 days, and 82.43% year to date. The autonomous-trucking roadmap has received strong price confirmation, but commercialization still depends on safe-driving mileage, fleet scale, and unit economics; the substantial year-to-date gain magnifies the risk of execution slippage.
Aptiv: The stock rose 7.02% on August 7, but fell 12.25% over 5 days and 18.19% over 20 days. The rebound in automotive electronics has not reversed the weakness, as the market remains concerned about automotive demand and the product mix; orders, margins, and free cash flow must collectively confirm a bottom rather than relying solely on a single-day gain.
Symbotic: The stock rose 1.46% on August 7, but fell 6.67% over 5 days and 7.93% over 20 days. Warehouse robotics could benefit from physical AI, but the stock fell 21.71% over 60 days; project delivery, customer concentration, and post-installation service revenue will determine whether the business model can escape engineering-driven volatility.
Intuitive Surgical: The stock rose 1.36% on August 7 and 7.21% over 5 days, but fell 6.88% over 20 days. Surgical robotics already has an installed-base and consumables model, with AI primarily improving clinical efficiency rather than rebuilding the business model; the key question is whether procedure volumes, system installations, and consumables revenue can improve in tandem.
Rockwell Automation: The stock fell 0.17% on August 7, 8.13% over 5 days, and 6.58% over 20 days. Industrial automation has yet to receive price confirmation from the physical-AI narrative, while customer capital expenditure and order cycles remain the dominant variables; robotics capabilities have financial significance only if they translate into project orders.
onsemi: The stock rose 3.63% on August 7, but fell 15.41% over 20 days and 22.03% over 60 days. Automotive and power semiconductors are experiencing a short-term rebound while remaining under medium-term pressure; inventory digestion, automotive production, and data-center power revenue are the 3 variables for assessing whether margins can stabilize.
NXP: The stock rose 3.42% on August 7, but fell 17.98% over 20 days and 18.53% over 60 days. Demand for automotive-grade and industrial chips remains weaker than the market recovery, and the share price has not confirmed a cyclical reversal; the next question is whether automotive orders, channel inventories, and industrial demand can improve simultaneously.
STMicroelectronics: The stock rose 5.29% on August 7 and 7.08% over 5 days, but fell 21.49% over 20 days. The rebound in power and microcontroller businesses reflects a recovery from depressed levels and has not yet escaped medium-term pressure; the pace of inventory digestion among automotive and industrial customers will determine the revenue trajectory.
Microchip Technology: The stock rose 13.89% on August 7 and 14.00% over 5 days, but remained down 4.40% over 20 days. Microcontrollers and analog chips staged a strong rebound, but the stock fell 13.32% over 60 days; if orders and channel inventories do not improve in tandem, the single-day gain can only be viewed as an expectations reset.
Micro-LED Roadmap: In a public demonstration, Avicina operated at only 4G NRZ, with a best bit-error rate of 7e-9, a worst rate of 7e-5, and a typical rate of approximately 1e-7, versus a minimum threshold of 1e-12 without forward error correction. Phase noise, dispersion, jitter, and dense TIA packaging remain system constraints, while the mass-production roadmaps for consumer displays and short-reach interconnects require more full-array data.
"Avicina's micro-LED operated at only 4G NRZ, with a best group BER of 7e-9, a worst rate of 7e-5, and a typical rate of approximately 1e-7"
"The author attributes the fundamental limitations to phase noise, dispersion, and jitter caused by incoherent light, as well as dense TIA packaging and electrical crosstalk resulting from low per-channel data rates"
"Supplier diversification may strengthen Apple's bargaining power in conventional memory procurement and intensify competition among leading memory manufacturers."
"CXMT's 2026 capacity is already fully booked, while its prices are currently close to or above those of Micron, SK hynix, and Samsung Electronics."
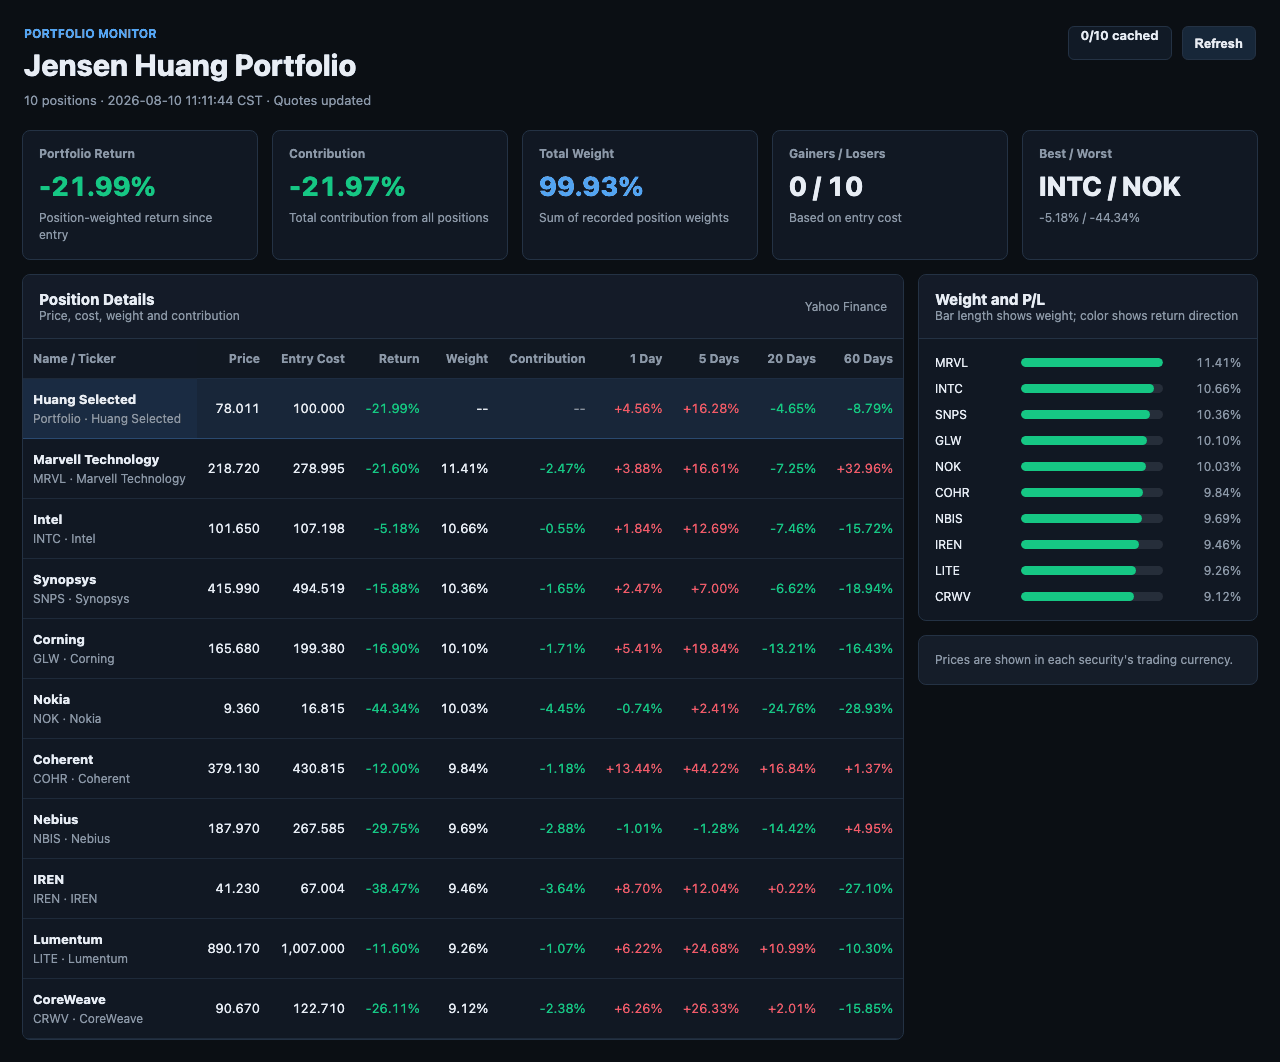
Jensen Huang's Select Portfolio