目录
Post-Close Summary
Full AI/Semiconductor Value Chain
AI Models and Applications, Capital Expenditure, and AI Cloud
GPU/CPU/ASIC
Memory, Wafer Fabrication, and Semiconductor Equipment/Testing
Optical Communications/High-Speed Interconnects/Servers
Internet / Platforms
Software / SaaS
Consumer Electronics / Smart Vehicles
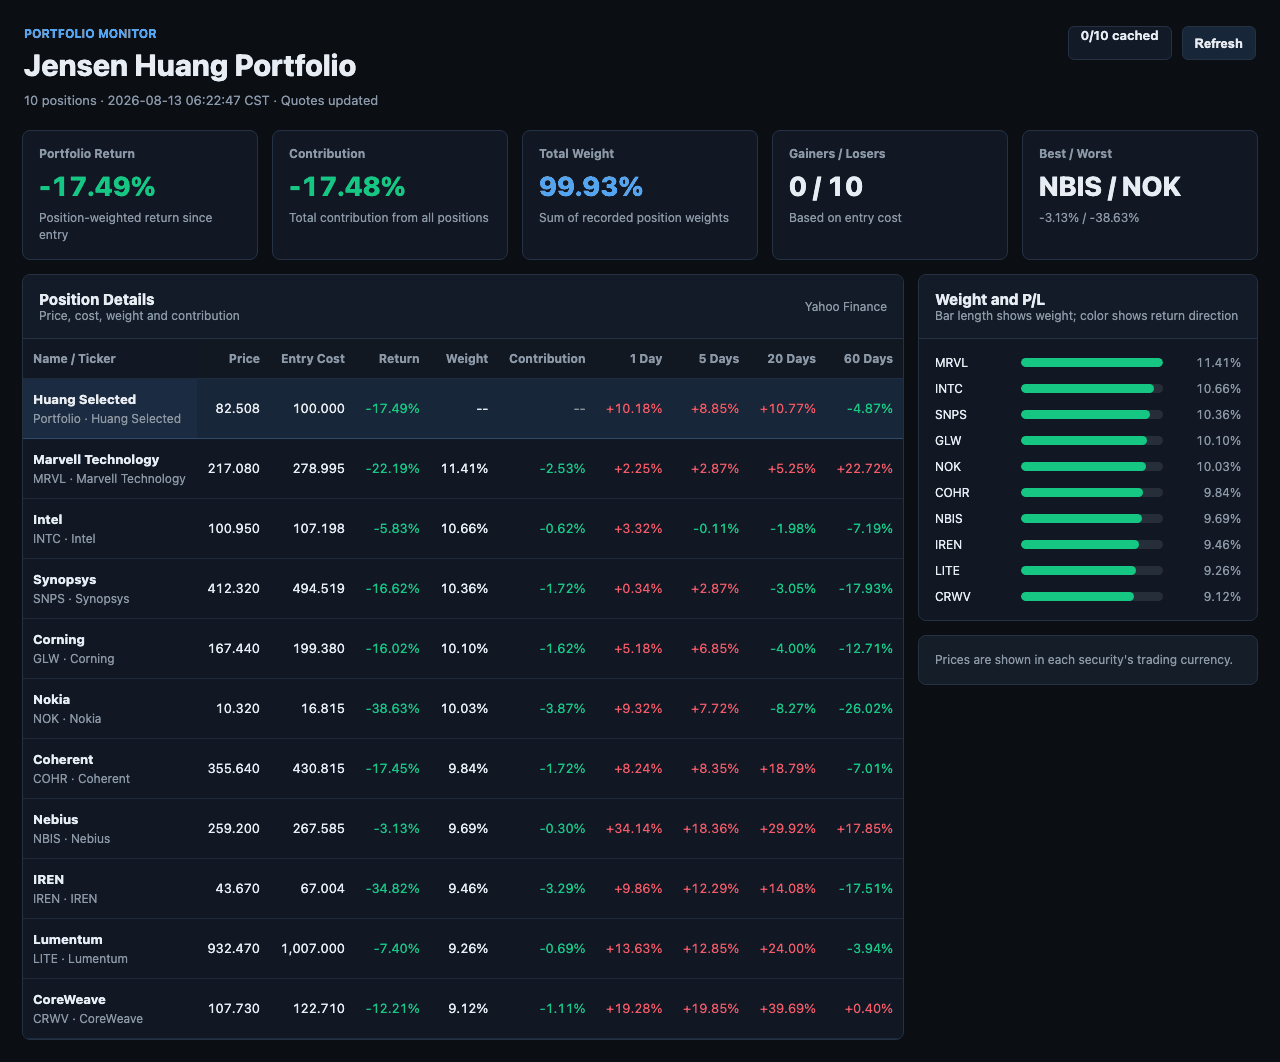
Jensen Huang’s Select Portfolio
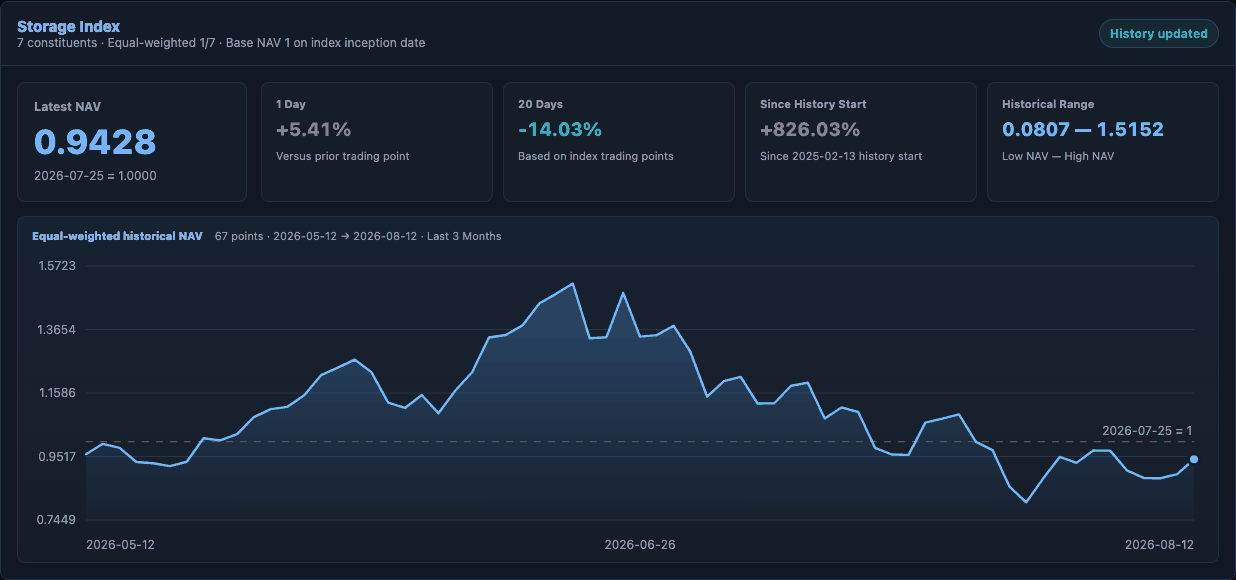
Memory Index Performance
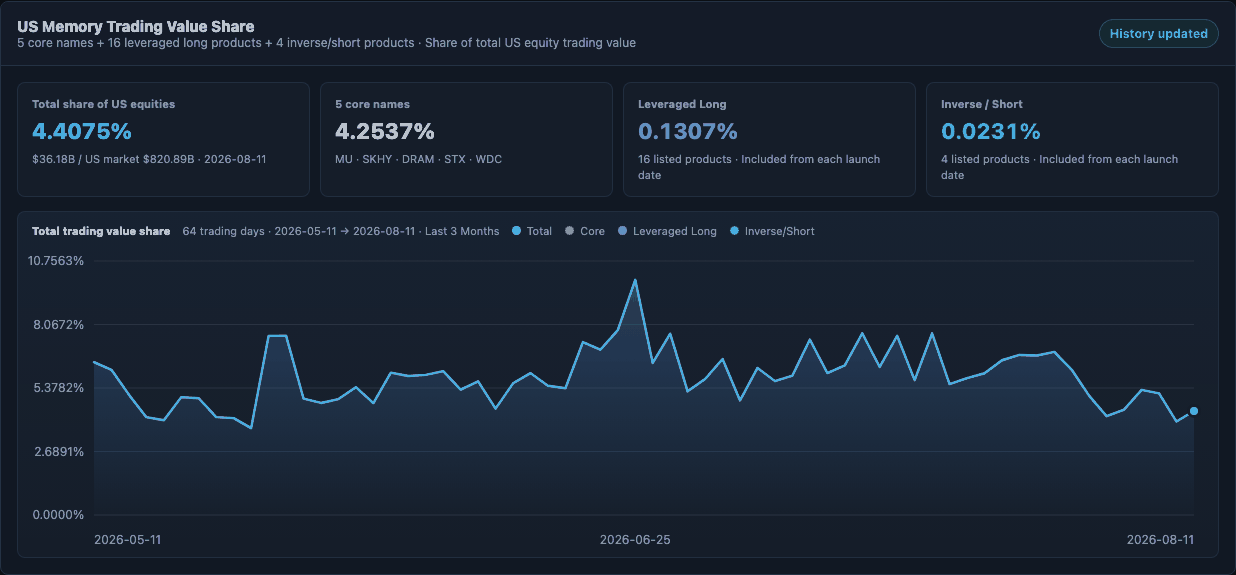
Memory Stocks’ Share of U.S. Equity Trading Turnover
Overview
404K | 2026-08-13
Post-Close Summary
At the latest available close on August 11, major U.S. indices edged lower, with the S&P; 500, Nasdaq 100, and Dow Jones all down approximately 0.3%. The equal-weighted S&P; 500 and Russell 2000 gained 0.21% and 0.34%, respectively. Market breadth was stronger than the headline indices suggested: capital did not exit technology indiscriminately, but continued rotating among mega-caps, software, and hardware.
Semiconductors rebounded on the day but remained weak over the medium term. Semiconductor ETFs gained 0.62% to 0.91%, while their 20-day declines remained 4.56% to 5.94%. Cloud computing and software continued to outperform, with their respective ETFs up 15.63% and 10.99% over the past 20 days, indicating that investors still favor order visibility and application revenue over upstream cyclical trades.
Industry developments reinforced two themes: large AI-cloud contracts are beginning to convert into revenue, driving concurrent growth in optical components, switches, and server orders; meanwhile, rising memory and component prices are beginning to pressure end markets. The next tests are whether cloud providers can turn elevated capital expenditure into sustainable profits and whether smartphone vendors can defend low- and mid-range demand.
Full AI/Semiconductor Value Chain
AI Models and Applications, Capital Expenditure, and AI Cloud
Enterprise AI applications: The economics of enterprise AI continue to improve. A typical use case can save approximately $55 per task against model-inference costs of approximately $2 to $5, implying a return on capital of 25% to 50%. Token usage has increased approximately 5× over the past 6 months and approximately 30× over 18 months, as demand shifts from experimentation to production. However, high concurrency is also transferring pressure to CPU orchestration, storage, and networking.
Qwen: Qwen3.8 uses a mixture-of-experts architecture with 2.4 trillion parameters and 95 billion activated per inference. On Nvidia’s GB300 NVL72, FP8 inference throughput exceeds 4,000 tokens per second per GPU, while single-user performance exceeds 350 tokens per second. Total parameter count is no longer a direct proxy for inference cost; activated parameters and deployment efficiency now determine commercial viability.
“This is a 2.4T-parameter model with 95 billion activated parameters, designed for demanding reasoning and agentic workloads.”
AI-agent infrastructure: Agentic workloads shift gateways, retrieval-augmented generation, tool calls, sandboxing, validation, and retries onto CPUs. In common server configurations, CPU and GPU power consumption is approximately 1:1, although some systems allocate only 20% to 30% to CPUs. As agent concurrency increases, CPU core counts, memory bandwidth, and threads per megawatt will become new data-center constraints.
“Most agentic workloads of this kind tend to be somewhat decoupled from the large-language-model inference call itself.”
Model-inference economics: Model capabilities are improving as per-call pricing declines, shifting enterprise procurement decisions from whether a model can be used to how much each completed task saves. The risk is that production deployments must also account for retrieval, permissions, human review, and failed-task retries; token pricing alone understates the true cost. Investors should therefore track end-to-end task success rates and gross profit per task.
CoreWeave
1) Second-quarter revenue was $2.575 billion, up 112.3% year over year; adjusted operating profit was $128 million, for a margin of only 5%. The midpoint of third-quarter revenue guidance is $3.525 billion, while the midpoint of 2026 revenue guidance is $12.8 billion.
2) Backlog reached $104.2 billion, with more than $25 billion of additional contracts signed after the quarter. Active power capacity was 1.5 GW, and full-year capital expenditure is expected to reach $37 billion. Contract margins are expected to improve by 5 to 10 percentage points, but customer concentration, financing costs, and residual GPU values remain the principal risks.
Nebius
1) Second-quarter revenue was $582.3 million, up 454% year over year. AI-cloud revenue rose 514% to $575 million, adjusted EBITDA was $236.2 million, and annualized recurring revenue reached $3 billion.
2) Contracted power capacity increased from more than 4 GW to 5 GW, and each of 4 contracts exceeds $1 billion. Customers prepay 50% to 60% of capital expenditure on approximately 70% of projects, reducing financing pressure, although the durability of spot pricing and premiums for older GPUs remains unproven.
Bloom Energy: Nebius’s data center in Vineland, New Jersey, is shifting to onsite fuel-cell generation. The system achieves fuel efficiency of up to approximately 60%, with energy efficiency delivered to the chip in the mid-50% range—approximately one-third higher than the conventional gas-turbine pathway. As AI data halls transition to 800-volt power, power-equipment efficiency, delivery lead times, and grid-connection constraints will directly affect sellable compute capacity.
GPU/CPU/ASIC
Nvidia: The shares fell 0.02% as of August 11 but gained 2.69% over the past 20 days. Networking revenue reached $31.3 billion, up 142% year over year, demonstrating that switch and interconnect revenue is scaling alongside GPUs. Rack-scale systems bundle compute, networking, and power into a single sale, providing turnkey delivery; the risk is that customers’ proprietary ASICs and open-network architectures divert some demand.
Broadcom: The shares fell 1.50% as of August 11 but gained 6.93% over the past 20 days. Quarterly AI revenue was $10.8 billion, up 143% year over year. Tomahawk 6 uses 200G SerDes, the third-generation co-packaged-optics platform supports 200G per lane, and a fourth-generation 400G solution is under development. The expansion of customer-designed chips benefits ASIC and networking revenue, although project concentration remains high.
Marvell Technology: The shares gained 1.80% as of August 11. Through its $9.9 billion acquisition of Inphi, $1 billion acquisition of Innovium, and integration of Celestial AI, the company has expanded into optical interconnects, switching, and optical computing. The ramp of 224G SerDes into volume production is a current advantage; the next question is whether cloud-customer orders and higher content per system can offset integration costs.
AMD
1) The shares gained 1.01% as of August 11 but fell 13.47% over the past 20 days. Turin scales to 192 cores at 500 W, while Venice scales to 256 cores at 600 W. A 256-core version optimized for agentic workloads consumes approximately 400 W, with a 128-core configuration available based on customer requirements.
2) Memory support is advancing from DDR5-6400 to DDR5-8000 and MRDIMM-12800. MI350P targets a 40% reduction in token costs for local inference, although cloud-based routing to frontier models could erode the cost advantage of local deployment.
Cerebras
1) Second-quarter GAAP revenue was $180.1 million, up 74% year over year, while core revenue rose 103% to $209.9 million. Core cloud revenue increased 287% to $127.7 million, and core gross margin was 41%, but GAAP gross margin was only 14%.
2) Remaining performance obligations reached $25.4 billion, and the company has secured more than 600 MW of data-center resources. It plans to scale 2026 capacity by more than 10×. GPT-5.6 Sol achieves 750 tokens per second; the key challenge is converting this high throughput into sustainable gross profit and cash flow.
Credo: The shares gained 3.23% as of August 11 and 4.87% over the past 20 days. Active electrical cables generated more than 99% of incremental fiscal 2026 revenue, while total revenue expanded 6.9× over two years; however, the top 2 customers accounted for 81%. The company has sampled a 224G optical digital signal processor and acquired DustPhotonics. Its next phase of growth depends on whether it can extend from intra-rack copper connectivity into optical interconnects.
Memory, Wafer Fabrication, and Semiconductor Equipment/Testing
Memory industry: JPMorgan lowered its forecast DRAM shortfall for 2026 from 10% to 3% and for 2027 from 13% to 7%. It reduced its NAND shortfall forecast from 3% to 0 for 2026 and from 8% to 5% for 2027. Supply and demand remain tight, but the deficit is narrowing; further pricing upside will depend on capacity expansion, inventories, and end-market demand.
SK hynix
1) The company will hold a groundbreaking ceremony on August 27 for its advanced-packaging plant in Indiana, U.S. The $3.87 billion facility is scheduled to begin production in the second half of 2028 and is intended to establish domestic U.S. back-end capacity for HBM.
2) New equipment must incorporate AI agents, with validation planned this year on back-end production lines in Cheongju and yield improvement included as a key metric. Automation should increase equipment content, but closed networks and edge-GPU deployments raise initial costs.
SanDisk: The shares gained 2.68% as of August 11 but fell 27.69% over the past 20 days. If persistent key-value caching follows the current trajectory of inference growth, it could approach 1 zettabyte by 2030—equivalent to more than 70% of projected NAND bit supply in 2027. This estimate is highly sensitive to cache-retention policies and inference volumes and should not be treated as confirmed orders.
TSMC: The supply chain expects GPU wafer demand to grow approximately 10% and ASIC wafer demand approximately 12%. ASICs could increase from approximately 10% of advanced-computing wafers today to 15% by 2028. Incremental demand benefits both advanced nodes and packaging, but more fragmented customer-designed chips could alter product mix, average selling prices, and capacity allocation.
imec: For the A2 node, both 2D-channel gate-all-around devices and silicon-based solutions achieve a minimum contacted gate pitch of 36 nanometers and a gate length of 10 nanometers. Contact formation, rather than the channel material alone, remains the bottleneck. Before 2D devices can enter commercial designs, further work is required on quantum transport, compact models, integration, parasitics, and circuit-level power, performance, and area validation.
“The framework encompasses quantum-transport simulation, compact-model generation, process-flow definition for A2-targeted 2D CFET gate-all-around integration, parasitic extraction, and circuit-level benchmarking.”
Advanced lithography: Stochastic defects in extreme-ultraviolet lithography arise from limited photon counts, photoresist chemistry, and 3D mask effects, while nanoimprint lithography is affected by filling, residual layers, template deformation, and release. Combining physics-based models with machine learning can reduce the sample requirements for defect prediction, but generalization across equipment and materials remains unproven.
“Defect prediction is shifting from contour correction toward physics-based, data-efficient, and uncertainty-aware approaches.”
Optical Communications/High-Speed Interconnects/Servers
Lumentum
1) Fourth-quarter revenue was $1.006 billion, up 109.3% year over year. Adjusted earnings per share were $3.23, gross margin was 50.4%, and operating margin was 36.6%. Next-quarter revenue guidance is $1.225 billion to $1.275 billion, with an earnings-per-share midpoint of $4.20.
2) Demand for electro-absorption-modulated lasers exceeds supply by approximately 30%, pump lasers are sold out, and 1.6T products have begun shipping. Quarterly optical-circuit-switch revenue exceeded $100 million. Near-packaged-optics orders total several hundred million dollars, with delivery planned for the first half of 2027.
Coherent
1) Fourth-quarter revenue was $2.05 billion, up 34% year over year. Adjusted earnings per share were $1.74, gross margin was 40.2%, and operating margin was 21.8%. Data-center and communications revenue rose 58.6% to $1.62 billion.
2) Next-quarter revenue guidance is $2.2 billion to $2.4 billion. Indium-phosphide capacity is planned to increase by more than 1× by year-end and by more than 1× again in 2027. Orders extend into 2028, but full-year operating cash flow was only $79.5 million; cash conversion will determine the quality of the capacity expansion.
“We expect growth to accelerate significantly in fiscal 2027. Having achieved our first $2 billion revenue quarter, we now expect our first quarter above $3 billion before the end of fiscal 2027.”
Cisco
1) Fourth-quarter revenue was $17.3 billion, up 18% year over year. Adjusted earnings per share were $1.22, and operating margin was 35.9%. Networking revenue rose 28% to $9.79 billion, while security revenue increased 14% to $2.23 billion.
2) Quarterly AI-infrastructure orders reached $4 billion and full-year orders totaled $9.3 billion, with remaining performance obligations of $46.7 billion. Fiscal 2027 revenue guidance is $72.2 billion to $73.4 billion. Order conversion and gross margin will determine whether this high growth is sustainable.
“In fiscal 2026, Cisco achieved its highest productivity metrics in 30 years, as measured by revenue, non-GAAP operating margin, and profit per employee.”
Hon Hai Precision: Vera Rubin racks are scheduled to enter volume production in the third quarter. AI-rack revenue is growing sequentially, and full-year rack shipments are expected to increase by more than 1×. The company expects shipment growth to remain above 10%, with demand staying strong in 2027. As server assembly shifts from individual systems to complete racks, delivery speed and integrated power and thermal capabilities are becoming more important than manufacturing scale alone.
Super Micro Computer: Fourth-quarter gross margin was 17.6%. Fiscal 2027 revenue guidance is $65 billion to $72 billion, backlog stands at $60 billion, and more than 9 customers have each placed orders exceeding $1 billion. The company expects long-term gross margin to remain above 10% and says it does not require further equity dilution. Key risks remain customer concentration, working capital, and the pace of rack deliveries.
Internet / Platforms
Platform stocks: As of August 11, the Communication Services ETF fell 0.50% and was down 0.16% over the past 20 days, significantly underperforming cloud computing and software. Performance is increasingly diverging across platforms: cloud infrastructure and enterprise AI are generating incremental revenue, while advertising, traffic-distribution, and content platforms face shifts in search entry points and pressure on customer-acquisition costs.
Google
1) As of August 11, the shares fell 3.84% and were down 8.96% over five days. The flagship Gemini model was delayed by approximately 2 months after its coding capabilities fell short of internal targets, with constrained chip allocations and organizational coordination issues also slowing the release.
2) DeepMind has adjusted its management structure, while co-founder Sergey Brin has pressed the team to accelerate investment. The model-release cadence directly affects cloud-inference demand and developer retention; coding benchmarks and real-world usability are the key metrics to watch.
“Google is restructuring DeepMind to accelerate Gemini development and regain leadership in frontier AI models.”
Amazon: As of August 11, the shares fell 2.09% but remained up 10.01% over the past 20 days. AWS expects available compute capacity to grow by more than 40% in Q3, indicating that prior investment in equipment, power, and data-center construction is beginning to translate into marketable capacity. Rapid supply growth will improve profitability only if customer utilization rises in tandem; inference workloads and depreciation pressure warrant close monitoring.
“AWS Q3 capacity growth is reportedly 40%+, with Azure and GCP also exceeding expectations—a positive signal for CSP/cloud capital expenditure.”
Meta: As of August 11, the shares rose 0.71% but were down 9.37% over the past 20 days. Adoption of the company’s models and advertising tools continues to expand. Growth in AI users can improve recommendation efficiency and advertising conversion, but returns on capital expenditure still depend on revenue per impression. Medium-term share-price weakness indicates that investors want clearer evidence of monetization, not merely user growth.
Microsoft: As of August 11, the shares fell 0.44% but were up 30.88% over the past 20 days, the strongest relative performance in the sample. The company is working with Google and the Open Compute Project to advance an 800-volt direct-current power standard designed to make high-density AI data centers safer and more scalable. A standardized power interface should shorten deployment timelines, although equipment certification and retrofit cycles will constrain near-term volume growth.
“We are proud to work with Google, Microsoft, and the Open Compute Project ecosystem to make high-density AI deployments practical, safe, and scalable for everyone.”
Oracle: As of August 11, the shares fell 3.69% but were up 13.71% over the past 20 days. Cloud revenue growth reached 77%, but annual AI data-center investment increased from approximately US$21 billion to US$55.7 billion, widening the funding gap. The company is raising cash through debt and equity financing; the key valuation question is whether order growth can cover interest, depreciation, and restructuring costs.
“To bridge the funding gap, the company borrowed US$43 billion, sold US$5 billion of stock, and plans to raise approximately another US$40 billion. Oracle has publicly stated that some layoffs are AI-related.”
Reddit: As of August 11, the shares fell 1.59% and were down 23.16% over the past 20 days. The platform is strengthening login prompts to convert search visitors into registered users. AI search summaries can generate referral traffic but may also allow users to consume content directly on the search page. The key question is whether login conversion and in-app engagement can offset traffic captured by external search interfaces.
“AI Overviews can help drive referral traffic, but they may also shift content consumption toward summaries rather than in-app engagement.”
Netflix: As of August 11, the shares fell 1.97% but were up 1.71% over the past 20 days. Near-term performance was broadly in line with the market, indicating that streaming has not participated in the strength of enterprise software and cloud computing. Subscriber growth, ad-supported plans, and content amortization remain the principal variables. AI is improving recommendation and production efficiency but has yet to establish an independent revenue driver.
Uber: As of August 11, the shares rose 0.65%, gaining 9.10% over five days and 8.96% over 20 days. The stock has been relatively strong among platform companies, reflecting continued investor confidence in mobility demand and operating leverage. Expansion of autonomous-driving partnerships could reduce driver-supply constraints, but vehicle utilization, insurance costs, and revenue-sharing arrangements will determine the ultimate profit opportunity.
DoorDash: As of August 11, the shares rose 1.02% and were up 12.89% over the past 20 days. The delivery platform continues to outperform the communication-services sector, as investors place greater weight on order density and unit economics. The key test is whether average order value, delivery subsidies, and advertising revenue can hold up if consumer spending slows; a single day’s gain is insufficient to confirm an acceleration in the trend.
Airbnb: As of August 11, the shares rose 0.15%, gaining 23.39% over five days and 26.23% over 20 days, making Airbnb one of the stronger internet platforms. The rally reflects a re-rating of travel demand and platform profitability, but its durability still depends on booked nights, average daily rates, and marketing expenditure. Growth could decelerate against a high comparison base.
Shopify: As of August 11, the shares fell 1.66% but were up 23.77% over five days and 21.43% over 20 days. Medium-term momentum in e-commerce software remains strong, supported by merchant transaction volume and payments penetration. The near-term pullback appears consistent with consolidation after a strong run. If consumer demand weakens, payment losses, marketing investment, and merchant churn would be the first pressures on profitability.
Pinterest: As of August 11, the shares fell 2.54% and were down 7.15% over five days, but remained up 5.04% over the past 20 days. The advertising platform faces changes in search traffic and intensifying competition for budget allocation. Growth depends on converting visual discovery into shopping transactions. Active users, revenue per user, and retail-advertising demand matter more than short-term share-price movements.
Snap: As of August 11, the shares rose 2.99% and were up 17.74% over the past 20 days, despite falling 4.84% over five days. The stock is experiencing both a near-term rebound and medium-term strength, but improvements in advertising products must be validated through conversion rates and pricing. Snap has a large user base but limited profit buffers; infrastructure costs and engagement among teenage users remain the principal risks.
The Trade Desk: As of August 11, the shares rose 1.27% but were down 29.89% over five days and 28.41% over 20 days, making it the weakest stock in the platform-advertising value chain. Programmatic-advertising budgets have not disappeared, but growth expectations and valuation have both been reset lower. The next indicators to watch are open-internet advertising share, customer retention, and stabilization in the platform take rate.
Software / SaaS
Software-sector performance: As of August 11, the Software ETF fell 1.04% but was up 10.99% over the past 20 days, with relative strength reaching 96.3. Investors are increasingly willing to pay for recurring revenue, AI-driven expansion, and cash flow, while rapidly penalizing companies with slowing growth or excessive investment. Differences in earnings quality within software are widening.
Wix: AI website-building platform Lovable holds approximately 55% of the vibe-coding market and is roughly 2.5 times the size of Wix-owned BASE44. Lovable’s latest funding round valued it at US$13.3 billion, approximately 4.8 times Wix’s US$2.8 billion market capitalization. The valuation gap shows that investors will pay higher multiples for AI-native workflows; Wix must demonstrate that its acquisition can convert into paying users and revenue.
“Lovable holds approximately 55% of the vibe-coding market, roughly 2.5 times the share of Wix-owned BASE44.”
Anthropic
1) Claude sessions in Chrome can now continue across desktop, web, and mobile, with conversations, skills, and connectors synchronized. The product is evolving from a standalone chat interface into a continuous work environment.
2) Cross-device continuity should increase usage frequency, but enterprise adoption still depends on permissions, data isolation, and connector security. Actual retention for Team and Pro plans will be the key metric.
“Your Claude session in Chrome can now continue across desktop, web, and mobile. Conversations are saved, and your skills and connectors are also available in the browser.”
xAI
1) Grok 4.6 input and output pricing is US$2 and US$6, respectively, while its AA-Briefcase cost per task is US$4.42, below Claude Fable 5 at US$22.30.
2) In a blind test containing 105 hidden vulnerabilities, the model identified 27 planted vulnerabilities and 15 additional vulnerabilities. A single benchmark does not establish production reliability; reproducibility across different codebases, false positives, and task-completion costs still need to be assessed.
“Grok 4.6 is on par with Claude Fable 5, with overlapping confidence intervals. On this benchmark, it is also far cheaper than other leading models, at US$4.42 per task.”
“Grok 4.6 identified 27 planted vulnerabilities and 15 additional vulnerabilities, up from Grok 4.5’s 17 planted vulnerabilities and 10 additional vulnerabilities, and close to Fable 5’s 29 planted vulnerabilities.”
“xAI trained Grok 4.6 to perform long-running agentic tasks in software engineering, research, web development, CAD, and kernel optimization.”
Okta: AI agents and machine identities are increasing both the number of permissions and the complexity of access management, transforming the identity layer from an employee-login tool into core AI security infrastructure. Growth depends on agent identity, privileged access, and cross-selling. The risk is that large cloud providers bundle identity capabilities into existing suites, depressing standalone-product pricing.
AppLovin: As of August 11, the shares fell 5.99% and were down 24.07% over five days and 29.02% over 20 days. The market has yet to establish a stable valuation for the commerce business, while advertising-technology growth and multiple compression are occurring simultaneously. Advertising returns, platform policies, and new-business revenue are the key metrics, rather than extrapolation from historically high growth.
Salesforce: As of August 11, the shares fell 0.02% but were up 17.85% over the past 20 days. AI products are contributing to new transactions, but usage has yet to reach a clear inflection point, indicating a gap between contract signings and actual consumption. Revenue recognition, agent-seat utilization, and customer renewals are the key tests of AI monetization; product-launch volume alone is insufficient.
MongoDB: As of August 11, the shares rose 5.40%, gaining 15.56% over five days and 27.41% over 20 days. Customers are moving more AI workloads into production, while a narrowing functionality gap for Atlas and vector search are supporting adoption. The strong performance must be validated through cloud revenue and net retention. If development projects remain in the pilot stage, usage growth will lag order signals.
Accenture: Enterprise AI adoption remains at an early stage, with consulting and systems-integration demand gradually shifting from proofs of concept toward process redesign. The opportunity lies in data governance, model integration, and organizational implementation, while longer customer budget-approval cycles are the key risk. Generative-AI bookings, revenue conversion, and billable-employee utilization are the principal metrics to watch.
Palantir: As of August 11, the shares fell 0.17% but were up 7.55% over five days and 30.83% over 20 days, with relative strength of 99.2. Strong momentum reflects expansion in enterprise and government AI projects, but the valuation is highly sensitive to slowing growth. Contract size, customer count, and remaining performance obligations should confirm the share-price performance.
ServiceNow: As of August 11, the shares rose 0.08%, gaining 7.96% over five days and 21.64% over 20 days. Workflow software benefits as enterprises embed AI into customer-service and operational processes, with monetization driven by expansion purchases rather than one-off trials. Remaining performance obligations, renewal rates, and large contracts are the key metrics, while seat consolidation could reduce volumes.
Snowflake: As of August 11, the shares fell 0.17% but were up 5.48% over five days and 21.09% over 20 days. Data platforms provide the foundation for enterprise model training, retrieval, and governance, and usage should rise as production deployments expand. Cloud costs and pricing competition remain risks; product-revenue growth and gross margin need to improve in tandem.
Datadog: As of August 11, the shares fell 5.37% and were down 14.36% over five days and 8.85% over 20 days. Demand for observability is increasing alongside distributed AI applications, but the share price indicates concerns about growth or valuation. Cross-selling across logs, application performance, and security products, together with usage by large customers, will determine whether the decline can stabilize.
Cloudflare: As of August 11, the shares fell 1.17% but were up 8.95% over the past 20 days. Its edge network can support inference, security, and developer workloads, creating revenue opportunities tied to traffic and compute consumption. Competition comes from cloud-native services; large-customer growth, developer adoption, and capital-expenditure efficiency are the key indicators.
Palo Alto Networks: As of August 11, the shares fell 0.32% but were up 8.76% over the past 20 days. Security-platform consolidation continues to attract budget, while AI agents expand machine identities and the access surface, increasing demand for protection. If platform consolidation relies on discounts to gain share, near-term billings growth may suffer; remaining performance obligations and margins should be assessed alongside it.
CrowdStrike: As of August 11, the shares fell 1.45% but were up 5.30% over the past 20 days. Endpoint security continues to benefit from cloud adoption and increasingly complex threats, but customers are more sensitive to product reliability and vendor concentration. New-module penetration, net retention, and the number of large customers are the principal indicators of the pace of recovery.
GitLab: As of August 11, the shares rose 3.39%, gaining 15.43% over five days and 27.68% over 20 days. Development workflows are incorporating code generation, review, and security functions, allowing an integrated platform to increase revenue per customer. Competition centers on AI-coding effectiveness and seat pricing; net retention and expansion purchases by enterprise customers are the key metrics.
IBM: As of August 11, the shares rose 0.89% and were up 9.84% over the past 20 days. The company has an established customer base across hybrid cloud, data governance, and consulting delivery, while AI revenue is generated primarily through a combination of software and services. Growth durability depends on converting bookings into revenue, consulting utilization, and recurring software revenue—not the capabilities of any single model.
Consumer Electronics / Smart Vehicles
U.S. smartphone market: Shipments fell 5% YoY in Q2 2026. Premium brands were relatively resilient, while sub-$100 shipments plunged 64%. Demand is shifting toward the $200–299 segment, where sales nearly tripled YoY and market share expanded by roughly 3x. Rising component prices are squeezing low-end handset margins first, making carrier subsidies critical to replacement demand.
“Sub-$100 smartphone sales fell 64% YoY as OEMs either discontinued supply or raised prices to pass through higher memory costs.”
Apple: U.S. shipments declined 4% YoY in Q2, still significantly outperforming low-cost white-label brands. Apple typically accounts for more than 50% of U.S. smartphone sales in Q3, and the iPhone 18 is expected to carry a higher price. Premium users and carrier subsidies provide a buffer, but if memory costs continue to rise, product mix and the replacement cycle will determine gross margins.
“Sales momentum will depend on the level of carrier subsidies; Apple could enter a strong replacement cycle as users upgrade from the iPhone 15 series.”
Samsung Electronics: U.S. shipments fell 4% YoY in Q2. A $50 price increase for the Galaxy A17 in July indicates that component inflation is beginning to pass through to lower- and mid-range devices. Higher pricing can protect per-unit margins but may weaken prepaid demand. Product mix, channel subsidies, and internal memory supply are the key variables to watch.
“The introduction states that sales in the $200–299 segment increased nearly 200% YoY, while the main text says the $200–300 segment’s market share rose to 3x the year-earlier level.”
Motorola: U.S. shipments declined 4% YoY in Q2, broadly in line with leading vendors and well ahead of the combined 45% decline among other brands. Carrier distribution and mid-range models helped stabilize share, but rising component costs will erode its pricing advantage. The key question is whether the $200–299 segment can continue delivering incremental growth.
Google: U.S. Pixel shipments fell 4% YoY in Q2, and the Pixel 11 is expected to be priced higher. AI features can strengthen differentiation at the premium end, but Google’s limited hardware scale leaves profitability more exposed to carrier subsidies and supply-chain costs. Whether on-device model performance can stimulate replacement demand will determine the market’s acceptance of higher pricing.
HMD: The sub-$100 handset market contracted 64% YoY, placing greater pressure on brands such as HMD that rely on prepaid and low-cost channels. Rising costs are forcing vendors to reduce their model lineups or raise prices, even as their customers remain highly price-sensitive. Without greater carrier subsidies, sales and channel inventories may deteriorate further.
“Total U.S. prepaid smartphone sales fell 11% YoY, but Samsung Electronics and Motorola gained share as other low-end OEMs weakened or exited.”
Carrier channels: U.S. prepaid smartphone sales declined 11% YoY, while carrier subsidies steered users toward $200–299 models. Subsidies can cushion price increases but also raise customer-acquisition costs for carriers. Demand stabilization will depend on subsidy levels, contract duration, and inventory turnover for mid-range devices.
“Samsung Electronics raised the Galaxy A17’s price by $50 in July, rapidly expanding the previously underrepresented $200–300 segment.”
Tesla: Shares rose 0.58% as of August 11 but fell 16.00% over the past 20 days. Estimated delivery for custom U.S. orders of the rear-wheel-drive Model 3 is now scheduled for Q1 2027, indicating that demand remains strong for certain configurations, although this is not a proxy for overall sales. Key indicators include order wait times, capacity allocation, and actual deliveries.
Lyft: The company plans to allow users to match directly with Waymo vehicles in the Lyft app by year-end. Integrating autonomous vehicles could expand supply and reduce driver constraints, but Lyft will still bear dispatch, customer-service, and partner revenue-sharing costs. The critical tests are city availability, completed ride volume, and contribution profit per trip.
Mobileye: Shares rose 1.37% as of August 11 and 2.66% over five days but fell 12.09% over the past 20 days. The recent rebound has yet to reverse the medium-term weakness. Automotive customer destocking and the pace of advanced driver-assistance system adoption remain the principal variables. Design wins, content per vehicle, and the number of models entering mass production are the key metrics to watch.
Aurora: Shares fell 0.43% as of August 11 and 3.87% over five days but gained 13.38% over the past 20 days. Commercialization of autonomous trucking remains at an early stage of expansion, while the medium-term performance reflects expectations for growth in driverless freight mileage. Safety incidents, remote-support costs, and fleet utilization will determine unit economics.
Aptiv: Shares fell 0.38% as of August 11 and 14.54% over the past 20 days. Demand for automotive electronics and advanced driver-assistance systems continues to grow, but vehicle production, customer pricing negotiations, and business restructuring are weighing on near-term performance. Order conversion, as well as margins in wiring harnesses and computing platforms, will be critical indicators of recovery.
Symbotic: Shares rose 3.94% as of August 11 but fell 12.16% over five days and 4.51% over the past 20 days. Warehouse robotics has a compelling long-term demand outlook, but project-recognition timing creates revenue volatility. Deployment speed, customer concentration, and implementation costs will determine whether orders convert consistently into profit.
Intuitive Surgical: Shares rose 2.00% as of August 11, 8.95% over five days, and 5.73% over the past 20 days. Surgical robotics benefits from an expanding installed base and recurring consumables revenue, supporting stronger near-term performance than most automation names. Surgical procedure volumes, system pricing, and the cost of rolling out new platforms are the key variables.
Rockwell Automation: Shares rose 2.71% as of August 11 but fell 4.85% over the past 20 days. Industrial automation demand remains tied to the capital-expenditure cycle. AI and robotics can improve factory efficiency, but customers’ appetite for capacity expansion ultimately drives orders. Backlog, discrete-manufacturing demand, and margins will signal whether a recovery is taking hold.
Jensen Huang’s Select Portfolio
Memory Index Performance
Memory Stocks’ Share of U.S. Equity Trading Turnover