
404K SEMI-AI Morning Brief 2026-07-14 — Semiconductor De-Risking, Tight Memory Supply, and a Counter-Trend Rotation into Software
目录
Post-Market Summary
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
AI/Semiconductor Value Chain
CSP/Cloud Capex
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundries and Semiconductor Equipment/Testing
Optical Communications/Optical Chain and Data-Center Power
Robotics/Autonomous Driving and Space/Satellites
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
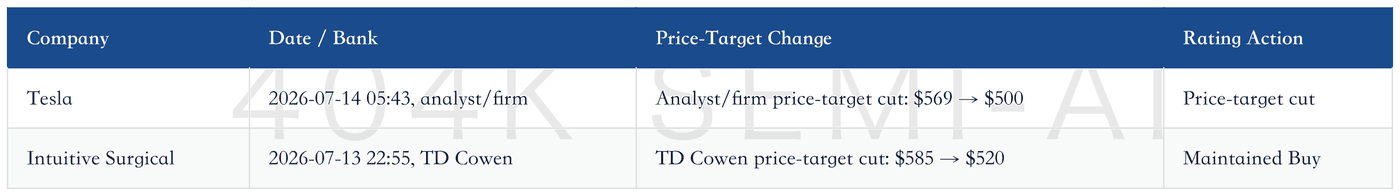
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio
Huang’s Selected Portfolio
Energy shocks and interest-rate concerns weighed on technology risk appetite, with semiconductors at the center of the sell-off. TSMC revenue, cloud capex, and long-term memory contracts continue to support medium-term demand, but end-market price increases and financing costs are beginning to provide counterevidence. Software and cloud stocks proved relatively resilient as capital rotated from high-beta hardware into cash flow and the application layer.
404K SEMI-AI | 2026-07-14
Post-Market Summary
U.S. equity risk appetite cooled markedly on July 13: the S&P; 500 fell 0.81% and the Nasdaq 100 declined 1.92%, while the equal-weighted S&P; 500 rose 0.23%. Technology fell 2.46%, while energy gained 3.30%. The crude oil ETF rose 9.42% and the VIX climbed 13.84%, as investors first moved to price energy, inflation, and interest-rate risks.
Semiconductors were at the center of the sell-off, with semiconductor ETFs falling 4.10% and 4.77%, respectively, and the AI and big data ETF declining 3.37%. The software ETF slipped only 0.03%, while the cloud computing ETF gained 0.16%, indicating that the market was not indiscriminately selling technology but reducing crowded positions in memory, interconnects, equipment, and capex-intensive names.
Fundamentals have not yet weakened in line with share prices. TSMC’s June revenue rose 67.9% year over year, forward capex estimates for cloud providers continue to move higher, and memory supply constraints still extend into 2027. However, smartphone shipments fell 11% year over year, while data-center financing and power constraints are increasing. The key question is whether demand can absorb higher prices, depreciation, and financing costs.
Top 10 U.S. Stocks by Trading Value
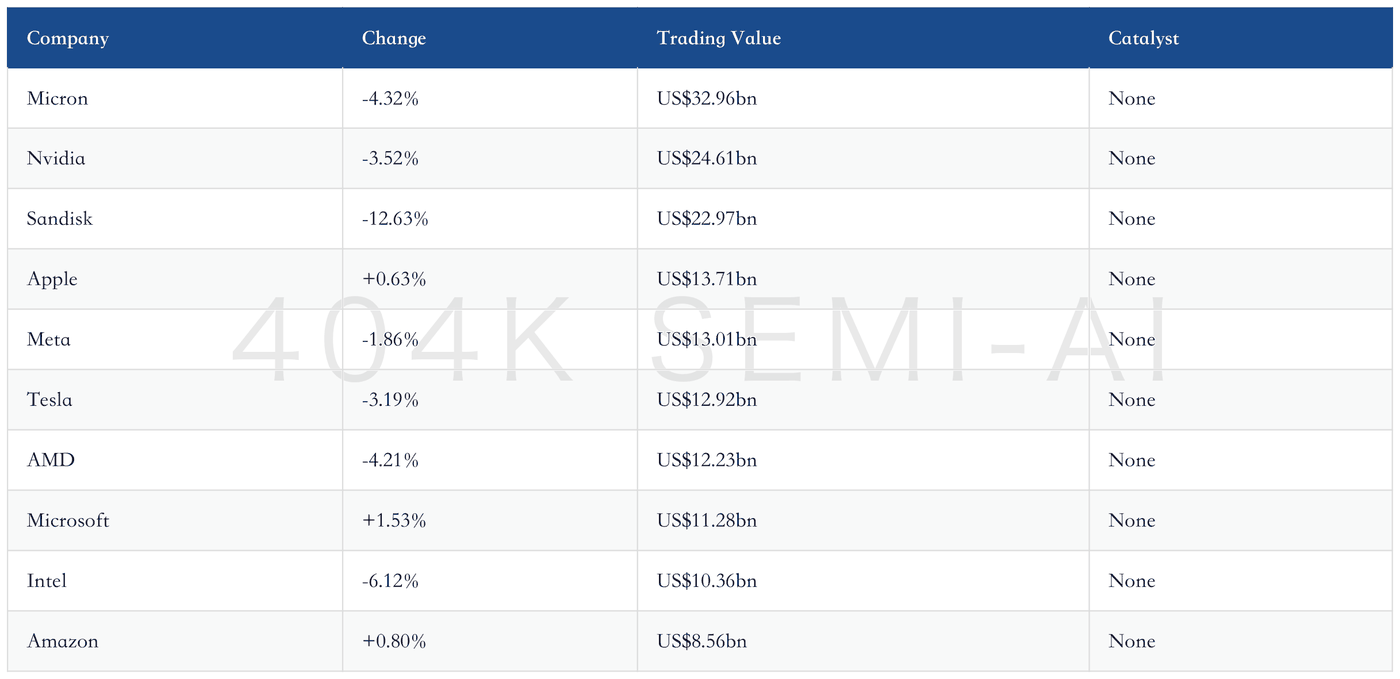
Top U.S. Stock Gainers
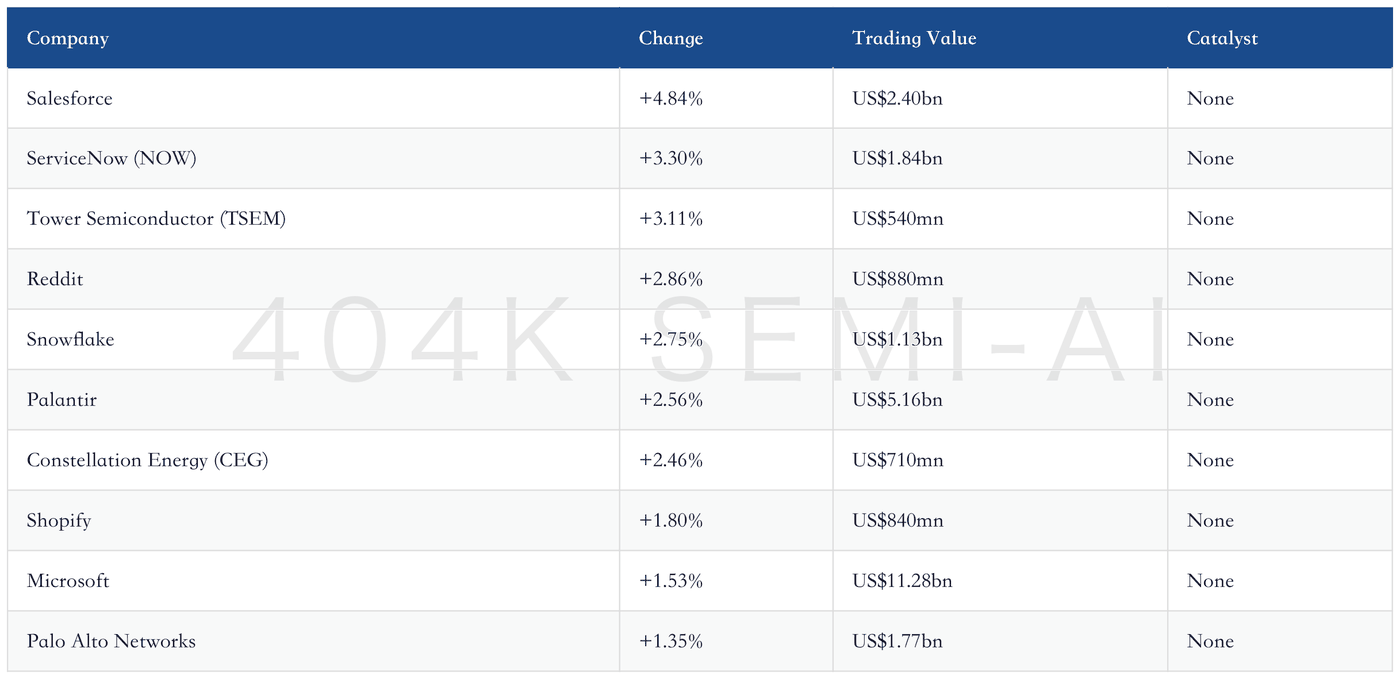
Top U.S. Stock Decliners
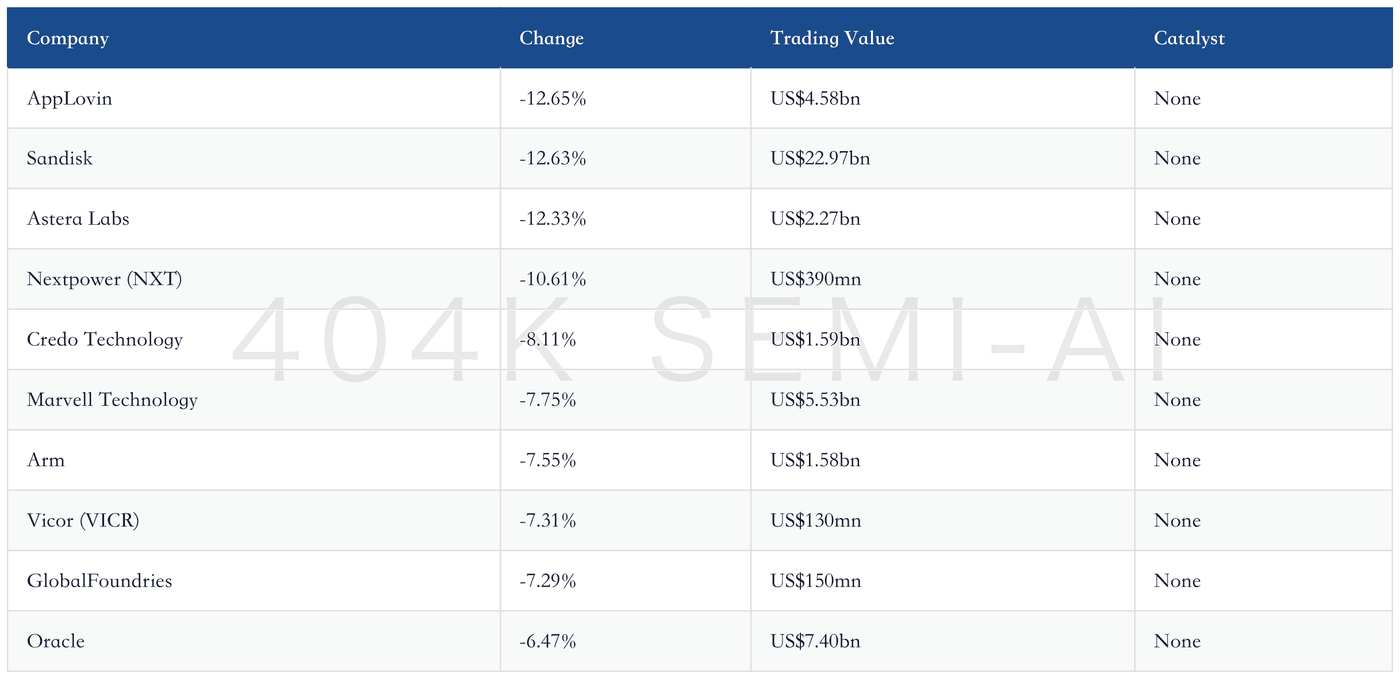
AI/Semiconductor Value Chain
CSP/Cloud Capex
Google
Morgan Stanley raised its 2027 and 2028 hyperscaler capex forecasts by 9% and 10%, respectively. Google’s 2028 spending is projected at US$375bn, the highest among the four companies. The capital will ultimately flow into TPUs, networking, and data centers, but whether this investment can translate into cloud revenue remains the key valuation test. If orders fail to convert into revenue, this thesis will be the first to break down.
Meta
The planned Louisiana data center has expanded from 2GW to 5GW, while disclosed investment has increased from US$27bn to more than US$50bn; market estimates suggest an even higher total cost when chips are included. The project validates AI infrastructure demand, but power requirements, construction timelines, and depreciation will pressure cash flow first. If utilization declines, the additional investment will become a drag on earnings.
Amazon
Morgan Stanley expects Amazon’s capex to reach US$318bn in 2028, primarily directed toward Trainium and AWS compute expansion. The risk is that cloud-provider capex has already reached the US$1tn scale. If AI service revenue growth slows, upstream equipment and server orders will be affected first. The next earnings report must validate the thesis through both revenue growth and cash flow.
Microsoft
Microsoft’s 2028 capex is projected at US$344bn. Azure’s annualized revenue is approximately US$75bn, up 40% year over year, while annualized AI revenue is approximately US$37bn, up 123%. The market is more focused on whether free cash flow can remain above US$50bn over the next 12 months, demonstrating that investment has not consumed the company’s cash-generation capacity.
"Memory accounts for 52% of CSP capex in 2026 and more than 70% the following year; quarterly DRAM ASP forecasts are +53%, +21%, and +7%."
AI Cloud/Data-Center Operators
Oracle
Shares fell 6.29% on July 13 and are down 28.16% over 20 days, continuing to underperform even as the cloud computing ETF rose 0.16%. Oracle’s AI infrastructure positioning remains intact, but the stock is being pressured by both the pullback in emerging cloud providers and the rotation into software. The next test is whether contracted revenue, financing costs, and power delivery can materialize in tandem. If customers delay deployment, the current valuation will require further digestion.
Nebius
First-quarter 2026 revenue reached US$399mn, up 684% year over year, while AI cloud revenue rose 841%. The company has US$3.7bn in cash, a US$20bn backlog, and a Meta contract worth up to US$27bn. Nebius aims to secure 3GW of power by the end of 2026; construction speed and financing capacity will determine whether the backlog converts into revenue.
IREN
IREN’s Spanish data-center site benefits from 90% fiber penetration, 35 subsea cable landing points, and ample energy capacity, but the stock has fallen 31.49% over 20 days. Resource availability addresses only site selection; the real tests remain customer contracts, time to energization, and the capex payback period. The validation point is whether pricing, volume, and gross margin can all hold.
GPU/CPU/ASIC
Nvidia
Shares fell 3.63% on July 13, with trading value of US$24.61bn. Lightmatter joined the NVLink Fusion ecosystem, and its bidirectional optical-link solution aims to reduce fiber and connector requirements by as much as 50%. Density advantages continue to expand, but software, supply security, and cost per FLOP will determine whether ASICs can gain share.
Intel
Shares fell 6.31% and are down 15.79% over five days. Intel has reportedly invested several billion euros to expand advanced manufacturing in Ireland. MediaTek’s EMIB-T project is scheduled for tape-out in 4Q26 and mass production in 4Q27. TD Cowen maintained its Buy rating and raised its price target from US$75 to US$115. Process competitiveness, customer confidence, and utilization matter more than investment headlines.
Broadcom
Shares fell 3.62%. The scale-up networking market is projected to exceed US$70bn by 2030, with Broadcom exposed to both switching platforms and custom ASICs. The opportunity stems from rising GPU counts and rack interconnect density, while uncertainty remains over open interconnect protocols and the timing of CPO adoption. The real evidence will come from customer adoption, paid conversion, and retention.
AMD
Shares fell 4.44% but remain up 9.14% over 20 days. Industry assessments suggest AMD still needs to catch Nvidia on performance in certain vLLM models, requiring both MI500 and software investment to deliver. Chip specifications alone are insufficient; customers ultimately purchase usable throughput, development efficiency, and total cost of ownership. If lower costs do not generate more inference calls, demand expectations will decline.
"The number of intra-rack connections is 10 times that of inter-rack connections; switch bandwidth is 100Tbps; Matt Murphy presented the product at COMPUTEX 2026."
HBM/DRAM/NAND/SSD/HDD
Micron
Shares fell 5.44%, with trading value of US$32.96bn. Forecast sequential growth in global DRAM ASPs slows from 53% in the second quarter to 21% in the third quarter and 7% in the fourth quarter. Prices are still rising, but the rate of increase is moderating. Whether high margins can hold depends on the simultaneous evolution of AI demand, long-term agreements, and specification reductions in consumer electronics. The next test is whether orders, deliveries, and collections improve in the same direction.
Samsung Electronics
Samsung held a 24% share of the global smartphone market in the second quarter, but its memory and handset businesses face opposing forces: AI is driving DRAM and NAND prices higher, while higher component costs are depressing end-market volumes. The next tests are HBM qualification, commodity DRAM pricing, and the ability to raise smartphone prices. Higher memory prices should not be treated as automatically translating into one-way improvement in group earnings. If supply improves faster than demand, pricing and margins will come under pressure first.
SK Hynix
Following sharp deleveraging in the Korean market, investors continue to weigh two competing interpretations: long-term agreements and HBM supply support earnings visibility, while lower blended pricing forecasts and delays in the HBM4 ramp weigh on expectations. Supply-chain sources suggest actual incremental capacity in 2028 could be only one-sixth of the original plan, making supply delivery the key variable. The next focus should be contract execution, capex, and free cash flow.
Sandisk
Shares fell 14.10%, with trading value of US$22.97bn. Five long-term NAND contracts are estimated to represent at least US$62bn in committed revenue, and Evercore raised its price target to US$3,100. The market is trading the tension between contract quality and the unwinding of crowded positions; prepayments, gross margins, and the fulfillment schedule require close monitoring.
Western Digital
Shares fell 5.10% but remain up 4.46% over 20 days, showing greater resilience than Sandisk. Enterprise storage demand and HDD capacity growth remain supportive. The risk is that combining NAND, SSD, and HDD metrics can obscure business differences; shipment capacity, pricing, and data-center customer procurement should be assessed separately. If user growth cannot be monetized, traffic advantages will not automatically translate into profit.
"TSMC’s June revenue reached a record NT$442.7bn, up 6.2% month over month and 67.9% year over year."
Foundries and Semiconductor Equipment/Testing
TSMC
Shares fell 2.67%, but June revenue reached NT$442.68bn, up 67.9% year over year, while second-quarter revenue was approximately NT$1.27tn. Prices for 2nm, 3nm, and 5nm are expected to increase by 5%–10%. Commentary on gross margin and mature-node pricing on July 16 will test the company’s pricing power. The risk is that intensifying competition causes prices to fall faster than usage grows.
UMC
Phase 3 expansion of Singapore Fab 12i was completed in 2025, with 22nm and 28nm capacity ramping from 2H26 through 2027 and increasing total company capacity by approximately 1.2% annually. Whether the additional capacity converts into revenue depends on customer qualification and utilization, not the completion of the facility itself. If channel inventories continue to rise, new product launches will struggle to improve sales.
AMEC
Reports suggest the company may deliver its first 90:1 cryogenic etching system, although the original wording included the qualifier “appears,” indicating uncertainty. Confirmation from the company or a customer would indicate that the product has progressed from R&D; validation to delivery. Without a disclosed equipment model, acceptance, and repeat orders, no revenue contribution can yet be extrapolated. The next test is unit economics, not merely scale expansion.
"UMC completed Phase 3 expansion of Fab 12i in 2025; capacity will ramp from 2H26 through 2027; total company capacity will increase by approximately 1.2% annually."
Optical Communications/Optical Chain and Data-Center Power
Marvell Technology
Shares fell 8.19% and are down 22.86% over 20 days. The company demonstrated its 100Tbps Teralynx switch and next-generation CPO switch, directly targeting higher intra-rack connection density. The risks are that mass production, customer adoption, yields, and orders have not been disclosed; a technology demonstration does not equal revenue realization. Delays in regulatory or security validation would also push back commercialization.
Lumentum
Supply-chain sources indicate that 1.6T demand has not weakened, while 800G demand has been revised significantly higher, with emerging cloud and model companies adding new customers. Supply of certain components is expected to improve from 2H26 through 1H27. Demand expansion and easing supply constraints are occurring simultaneously, so pricing and market share must be assessed separately. If any of orders, capacity, or customer qualification is missing, revenue could arrive later than expected.
Lite-On Technology
The company plans to invest US$919mn in a Texas manufacturing base, while its existing Plano facility produces battery backup units for AI servers. Capex in 2026 is expected to exceed the current NT$13bn level. U.S. manufacturing brings production closer to customers, but the commissioning schedule, orders, and returns remain unconfirmed. Gross margin and the pace of cash recovery will provide the market’s next answer.
onsemi
Shares fell 5.79% and are down 22.04% over 20 days. Demand from AI data centers and 800V DC electric vehicles is driving a recovery in silicon-carbide wafer prices, with incremental procurement requiring premium pricing. However, the industry has endured a two-year downturn and still has low-priced capacity, so a price rebound may not immediately translate into profits for overseas suppliers. If demand stems only from a short-term shortage, falling prices will quickly expose the risk.
"1.6T demand has not contracted; 800G demand has increased significantly versus prior expectations; supply of certain components is expected to improve gradually from 2H26 through 1H27."
Robotics/Autonomous Driving and Space/Satellites
Intuitive Surgical
On July 13, TD Cowen maintained its Buy rating and lowered its price target from US$585 to US$520. The analyst believes the second quarter could mark a trough for the share price and that earnings guidance may still be raised. The lower target indicates reduced expectations for near-term execution; the next tests are procedure volumes, system placements, and guidance. The next phase requires operating data to keep pace with the product narrative.
Internet/Platforms
Shopify
Rose 1.80% on July 13. Third-party data point to approximately 32% year-over-year GMV growth in Q2, above the market expectation of roughly 27%. Price increases for non-Plus plans could add 3%–4% to 2027 revenue, although partner incentives will raise near-term expenses first. If orders fail to convert into revenue, this thesis will be the first to be invalidated.
Reddit
Shares rose 2.86% and are up 15.49% over 20 days. The Google data-licensing agreement is worth approximately $60 million annually, while the OpenAI agreement is reportedly worth roughly $70 million annually, bringing the total value of related agreements above $200 million. Whether the next renewal adopts a fixed-fee-plus-usage model will be critical to monetizing the data’s value. If utilization declines, incremental investment will instead weigh on profits.
Uber
The expansion of the robotaxi fleet introduces a new supply-side variable for the platform, with approximately 10,000 vehicles operating globally. Uber’s ability to benefit depends on partnerships with operators such as Waymo, vehicle utilization, and revenue-sharing arrangements—not the total number of autonomous vehicles itself. Regulation and safety will continue to affect rollout speed. The next earnings report must validate the thesis through both revenue growth and cash flow.
DoorDash
Up 22.63% over 20 days, with the strongest relative performance in the coverage universe, indicating that local-services platforms have not yet been dragged down by hardware-related risk reduction. With no new order or profit data available, the focus should shift to average order value, fulfillment costs, and advertising monetization rather than treating relative strength as a direct fundamental upgrade. If customers delay deployment, the current valuation will still need to be reassessed.
Airbnb
Up 11.81% over 20 days, although tensions in the Middle East and higher oil prices will raise the cost of international travel. The platform’s asset-light model reduces capital-expenditure pressure but cannot insulate it from demand volatility. Validation should come from booked nights, average daily rates, and cancellation rates—not sector rotation alone. The key test is whether pricing, volume, and gross margins can all hold.
"Shopify’s Q2 GMV grew approximately 32% year over year versus a market expectation of roughly 27%; potential price increases could add approximately 3%–4% to 2027 revenue."
Netflix
Shares rose 0.34% but are down 9.41% over 20 days. The market remains concerned about user engagement, and streaming stocks did not participate in the pronounced software rally. The next indicators to watch are viewing hours, the ad-supported tier, and returns on content investment; resilience on a single day is insufficient to confirm a trend reversal. If renewals and average revenue per customer weaken, AI features will not support the valuation.
PayPal
Market commentary suggests Venmo’s growth could partly offset pressure on PayPal’s branded business. The key metrics for a payments platform are not account numbers but whether transaction frequency, payment volume, and take rates can hold. If the core brand remains under pressure, Venmo’s growth may amount only to internal substitution. The real evidence will be customer adoption, conversion to paid services, and retention.
Pinterest
The platform sits at the intersection of advertising and social commerce. AI recommendations can improve ad relevance, but no new verifiable operating figures were available today. The focus should be on monthly active users, ad pricing, and shopping conversion rather than equating AI feature launches directly with accelerating revenue. If lower costs do not drive higher usage, demand expectations will fall. This will determine the pace of earnings delivery.
Snap
The social-media and augmented-reality advertising businesses are sensitive to brand budgets, while macro risk reduction will lower near-term valuation tolerance. In the absence of new user and revenue data, the focus should be on daily active users, revenue per user, and whether compute investment improves ad conversion. Watch whether orders, delivery, and cash collection improve in the same direction. This will determine the pace of earnings delivery.
The Trade Desk
The programmatic advertising platform benefits from the migration of digital advertising budgets but also faces competition from large platforms’ proprietary data and closed ecosystems. The key indicators are customer retention, CTV spending, and customer-acquisition costs. Without new financial data, it is inappropriate to extrapolate performance solely from the software-sector rally. If supply improves faster than demand, pricing and profits will come under pressure first.
"The total value of the related agreements exceeds $200 million; negotiations began in late 2022, when OpenAI’s revenue was approximately $25 million."
WhatsApp
ChatGPT has returned to WhatsApp in the European Economic Area, supporting text, images, voice messages, image generation, and multilingual communication. This distribution channel is closer to everyday use cases, but whether the platform can capture commercial value will still depend on engagement, paid conversion, and revenue-sharing arrangements. The next indicators to watch are contract execution, capital expenditure, and free cash flow.
Kakao
ChatGPT is now available on Kakao in South Korea, indicating that AI assistants are moving from standalone applications to communications platforms. Channel expansion can lower customer-acquisition barriers, but user numbers, retention, and monetization models have not been disclosed. The platform’s value must be validated through usage frequency and revenue contribution. If user growth cannot be monetized, traffic advantages will not automatically translate into profits.
Viber
ChatGPT has also entered selected Viber markets, establishing communications-channel distribution across regions. Broader feature coverage does not equal successful commercialization. Supported countries, feature consistency, regulatory constraints, and platform revenue sharing have not been disclosed, so only channel expansion can currently be confirmed. The risk is that intensifying competition drives prices down faster than usage grows. This will determine the pace of earnings delivery.
"Users can message the verified 1-800-CHATGPT contact to ask text-based questions, upload images, send voice messages, create images, and communicate in multiple languages."
Similarweb
AI website traffic grew 45.57% year over year in the first half of 2026, significantly faster than the 3.64% growth for social-media websites and 2.90% for websites across all industries. The data confirm a shift in user attention, but without absolute base figures or monetization metrics, they cannot be used to infer revenue for specific platforms directly. If channel inventory continues to rise, new product launches will also struggle to improve sales.
Palantir
Shares rose 2.56% but are down 1.20% over 20 days. Enterprise AI platforms have been more resilient than semiconductors, indicating that the market is placing greater emphasis on real-world deployment. The next indicators are government and commercial contracts, customer expansion, and profits, rather than interpreting a single day’s rotation as a long-term valuation upgrade. Unit economics must be assessed next; scale expansion alone is insufficient.
"AI website traffic grew 45.57% year over year in the first half; social-media website traffic grew 3.64%; traffic across all industries grew 2.90%."
"The average model lead lasted 41 days; fifth-month retention ranged from the high single digits to approximately 40%."
Software/SaaS
CrowdStrike
ARR stands at $5.51 billion, with Falcon Flex ARR exceeding $1.9 billion. The platform has expanded beyond endpoints into identity, cloud workloads, and threat intelligence. AI is expanding the attack surface, keeping the spending thesis intact; the risk is whether platform consolidation can offset competition and customer budget scrutiny. If regulatory or security validation is delayed, commercialization will also be pushed back.
Palo Alto Networks
Shares rose 1.15% and are up 17.94% over 20 days. Cortex, Prisma, and CyberArk cover endpoint, network, cloud, and identity security, while the platform strategy aligns with customers’ desire to reduce vendor counts. Watch cross-selling, billings growth, and integration costs.
Cloudflare
Shares rose 0.42% and are up 18.51% over 20 days, ranking near the top in relative strength. Its global edge network supports both zero-trust security and AI inference traffic. The market expects approximately 30% revenue growth, but whether high growth can translate into free cash flow remains to be validated. If any of orders, capacity, or customer validation is missing, revenue could arrive later than expected.
Zscaler
Zero trust and SASE allow users to connect directly to applications, replacing traditional perimeter security. AI agents increase the complexity of identity and access control, supporting security budgets. The counterargument is that bundled integrated platforms could compress pricing and renewal headroom for point-solution vendors. Gross margins and cash-conversion speed will provide the market’s next answer. This will determine the pace of earnings delivery.
Fortinet
FortiOS and custom ASICs integrate firewalls, SD-WAN, SASE, endpoint, and cloud security, giving the hardware-plus-software model a cost advantage. If customers shift toward pure-cloud platforms, hardware cycles and inventory will continue to weigh on growth; the revenue mix between subscriptions and products must be monitored. If demand reflects only temporary shortages, falling prices will quickly expose the risk.
"CrowdStrike ARR stands at $5.51 billion; Falcon Flex ARR exceeds $1.9 billion; Cisco acquired Splunk for $28 billion."
Cisco
The company acquired Splunk for $28 billion, strengthening the correlation and analysis of network telemetry, SIEM, and XDR data. The transaction expands its security-data access but also creates integration and cross-selling pressure. Success should be judged by renewal rates, synergy revenue, and costs—not the size of the acquisition. The next stage is to determine whether operating data can match the product narrative. This will determine the pace of earnings delivery.
Okta
AI workflows are increasing the number of machine identities and non-human accounts, raising the importance of identity governance. Okta’s opportunity lies in permissions management and access control, while the risks are Microsoft bundling and platform consolidation. Watch customer expansion, net retention, and large-account renewals. If orders fail to convert into revenue, this thesis will be the first to be invalidated. This will determine the pace of earnings delivery.
Rubrik
Cyber resilience and post-breach recovery are becoming the final line of defense for data security in the AI era. The demand direction is clear, but whether the company can expand from backup into platform-level budgets must be assessed through subscription growth, recovery success rates, and customer concentration—not merely the frequency of security incidents. If utilization declines, incremental investment will instead weigh on profits. This will determine the pace of earnings delivery.
Qualys
Vulnerability prioritization and exposure management help customers direct limited security budgets toward the highest-risk attack paths. AI can improve detection efficiency but may also increase false positives. Watch platform integration, customer retention, and pricing rather than simply counting vulnerabilities. The next earnings report must validate the thesis through both revenue growth and cash flow. This will determine the pace of earnings delivery. This will determine the pace of earnings delivery.
Tenable
The company operates in vulnerability management and attack-path analysis, benefiting from the expansion of cloud assets and AI workflows. Competition is shifting from problem discovery toward remediation coordination. If it cannot become part of a broader security platform, the point solution may face pressure as budgets consolidate. If customers delay deployment, the current valuation will still need to be reassessed. This will determine the pace of earnings delivery.
"Developers subjectively estimated that completion times fell 20%, while measured completion times increased 19%."
Salesforce
Shares rose 4.62% on $2.4 billion in trading volume, ranking among the stronger performers in the software rotation. The market is trading enterprise-software cash flow and real-world AI adoption, but whether agent products can increase average revenue per customer, renewals, and seat expansion must still be validated through billings and remaining performance obligations. The key test is whether pricing, volume, and gross margins can all hold. This will determine the pace of earnings delivery.
ServiceNow
Shares rose 3.01% and are up 7.64% over 20 days. Workflow AI is closer to enterprise budgets than general-purpose chat tools, but deployment complexity and customer data quality determine returns. Watch large deals, renewals, and incremental revenue from AI products. If renewals and average revenue per customer weaken, AI features will not support the valuation. This will determine the pace of earnings delivery.
Snowflake
Shares rose 1.91% and are up 10.83% over 20 days. The data cloud is foundational infrastructure for enterprises to train, govern, and use AI, while consumption-based pricing can benefit from higher usage. The counterargument is that model caching and efficiency gains may reduce consumption per task. The real evidence will be customer adoption, conversion to paid services, and retention. This will determine the pace of earnings delivery.
Datadog
Shares rose 0.40% and are up 10.39% over 20 days. AI applications increase demand for monitoring logs, models, and infrastructure, expanding observability requirements as complexity rises. The risk is that cloud customers optimize spending; watch usage, customer expansion, and gross margins. If lower costs do not drive higher usage, demand expectations will fall. This will determine the pace of earnings delivery.
AppLovin
Shares fell 12.65%, with e-commerce advertising showing no clear improvement following a weak June. The AI advertising thesis requires merchant growth, adoption, and conversion to provide support. If new pixel installations remain slow following the June 22 opening, the valuation will continue to compress toward realized revenue. Watch whether orders, delivery, and cash collection improve in the same direction. This will determine the pace of earnings delivery.
"Software stocks instead outperformed the semiconductor ‘AI winners’: Figma rose 10%, TEAM 8%, Intuit 6%, and MNDY, HUBS, and CRM each gained 5%."
"Cache hits accounted for 95% of total token consumption and reduced token costs by 84%."
"Learning speed on tasks using new models was approximately twice that of models from three months earlier; the proportion of CEOs expecting AI to cause large-scale layoffs fell from 46% in January 2025 to 20% in May 2026."
Consumer Electronics / Smart Vehicles
Apple
Shares rose 0.63% and are trading near 52-week and all-time highs; global shipments grew 3% YoY in Q2, with market share reaching 20% for the first time. Premium demand is more resilient than the broader industry, but the stock trades at an approximately 65% valuation premium to the S&P; 500, requiring fall product launches and AI features to meet elevated expectations. If supply improves faster than demand, pricing and margins will come under pressure first.
Samsung Electronics
Samsung regained the top position with a 24% share of global smartphone shipments in Q2. The company is benefiting from rising memory prices while facing higher handset bill-of-materials costs; regional pricing power is temporarily cushioning the pressure. The key question is whether mid- and low-end volumes and end-market price increases can preserve market share. The next factors to watch are contract fulfillment, capital expenditure, and free cash flow. These will determine the pace of earnings delivery.
Xiaomi
Global smartphone shipments fell 11% YoY, with memory shortages having a greater impact on mid- and low-end models. Xiaomi faces dual pressure from rising DRAM and NAND prices and weakening demand. Investors should focus on per-device memory configurations, average selling prices, and shipments rather than market share alone. If user growth cannot be monetized, its traffic advantage will not automatically translate into profits.
OPPO
Memory-chip shortages are driving up handset prices, making demand destruction more likely in OPPO’s mid- and low-end markets. Industry shipments have fallen to their lowest level for the corresponding period since 2013; if supply constraints persist, specification cuts and promotional intensity will determine volume elasticity. The risk is that prices fall faster than usage grows as competition intensifies. This will determine the pace of earnings delivery.
vivo
The company is likewise under pressure to pass higher memory costs through to consumers. AI servers are competing for DRAM and NAND supply, forcing handset makers to balance specifications, pricing, and gross margins. The key question is whether channel inventories and new-product pricing trigger further demand contraction. If channel inventories continue to rise, new-product launches will struggle to improve sales. This will determine the pace of earnings delivery.
"Apple’s Q2 shipments grew 3% YoY, with market share reaching 20% for the first time, primarily supported by strong demand for its premium iPhone lineup."
Google Pixel
Google’s smartphone shipments grew 16% YoY in Q2, gaining ground even as the industry declined 11%. The growth indicates gains in product and channel share, but absolute scale, profitability, and memory costs were not disclosed; the key question is whether these share gains can be sustained across quarters. Investors need to assess unit economics, not merely scale expansion. This will determine the pace of earnings delivery.
MediaTek
Supply-chain sources indicate that the company has again lowered its full-year smartphone shipment outlook, while its ASIC business is constrained by TSMC wafer allocations. Traditional handset demand and AI-chip opportunities are moving in opposite directions; the ability to shift the revenue mix depends on wafer supply, customer projects, and the pace of mass production. If regulatory or security validation is delayed, commercialization will also be pushed back. This will determine the pace of earnings delivery.
Qualcomm
Shares fell 2.74% and are down 9.35% over 20 days. The handset SoC business faces declining shipments and rising memory prices, while data-center and edge AI offer new growth avenues. Investors should assess whether non-handset revenue growth can sufficiently offset pressure on end-market demand. Any shortfall in orders, capacity, or customer validation could delay revenue beyond expectations. This will determine the pace of earnings delivery.
"MediaTek again lowered its full-year smartphone shipment outlook; its ASIC business is constrained by TSMC wafer allocations."
Tesla
Shares fell 3.45%. Reportedly, 100 Cybercabs are being tested in Houston; Jefferies raised its price target from $375 to $400 after Q2 deliveries exceeded expectations, while another firm lowered its year-end target from $569 to $500. The divergence shows that the market is simultaneously pricing in improved deliveries and the commercialization timelines for Robotaxi and Optimus.
Waymo
The global Robotaxi fleet totals approximately 10,000 vehicles, with Waymo currently the leading participant. Future growth depends on cities opening up, vehicle utilization, and safety performance. Industry fleet expansion does not establish per-vehicle economics; investors need to assess cost per mile and regulatory approvals. If demand merely reflects a temporary shortage, falling prices will quickly expose the risk.
Zoox
Amazon-owned Zoox is positioned in the expanding Robotaxi market, supported by its parent company’s funding and cloud capabilities. Commercialization still requires progress in vehicle mass production, operating permits, and safety validation. Without clear fleet and order data, long-term industry projections should not be used as a substitute for company-specific execution. The next phase will test whether operating data can support the product narrative. This will determine the pace of earnings delivery.
"The humanoid-robot market could reach $5 trillion by 2050; manufacturing scale is not expected to begin ramping until around 2030."
Rivian
California’s new subsidy is more favorable to automakers headquartered in the state, offering $3,500 per new vehicle with a $50,000 price cap; Rivian could gain a relative policy advantage. Whether the subsidy translates into sales will also depend on vehicle pricing, production capacity, and per-unit losses. If orders fail to convert into revenue, this thesis will be invalidated first. This will determine the pace of earnings delivery.
Lucid
Lucid could likewise benefit from California’s headquarters exemption, but the subsidy budget is limited to $270 million, restricting its reach. Policy support can only ease demand-side pressure; it cannot substitute for evidence of higher capacity utilization, delivery growth, and controlled cash burn. If utilization declines, incremental investment will instead weigh on profits. This will determine the pace of earnings delivery. This will determine the pace of earnings delivery.
Volkswagen
The company may cut approximately 50,000 additional jobs, potentially bringing total layoffs to 100,000, reflecting the cost and electrification-transition pressures facing European automakers. PowerCo’s battery plant is scheduled to begin production in 2027; execution will hinge on construction progress, utilization, and whether EV sales can absorb the capacity. The next earnings report must validate the thesis through both revenue growth and cash flow. This will determine the pace of earnings delivery.
PowerCo
The plant represents a $7 billion investment, will create approximately 3,000 jobs, and is designed to supply up to one million vehicles annually, with licensed capacity of up to 85 GWh. The scale targets are clear, but the 2027 production start, commercialization of QuantumScape technology, and royalty revenue remain subject to execution risk. If customers delay deployment, the current valuation will require reassessment.
"The subsidy budget is $270 million; Volkswagen may cut approximately 50,000 additional jobs, potentially bringing total layoffs to 100,000, while its shares are at a 16-year low."
"PowerCo’s plant represents a $7 billion investment, will create approximately 3,000 jobs, can supply up to one million vehicles annually, and has licensed capacity of up to 85 GWh."
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio
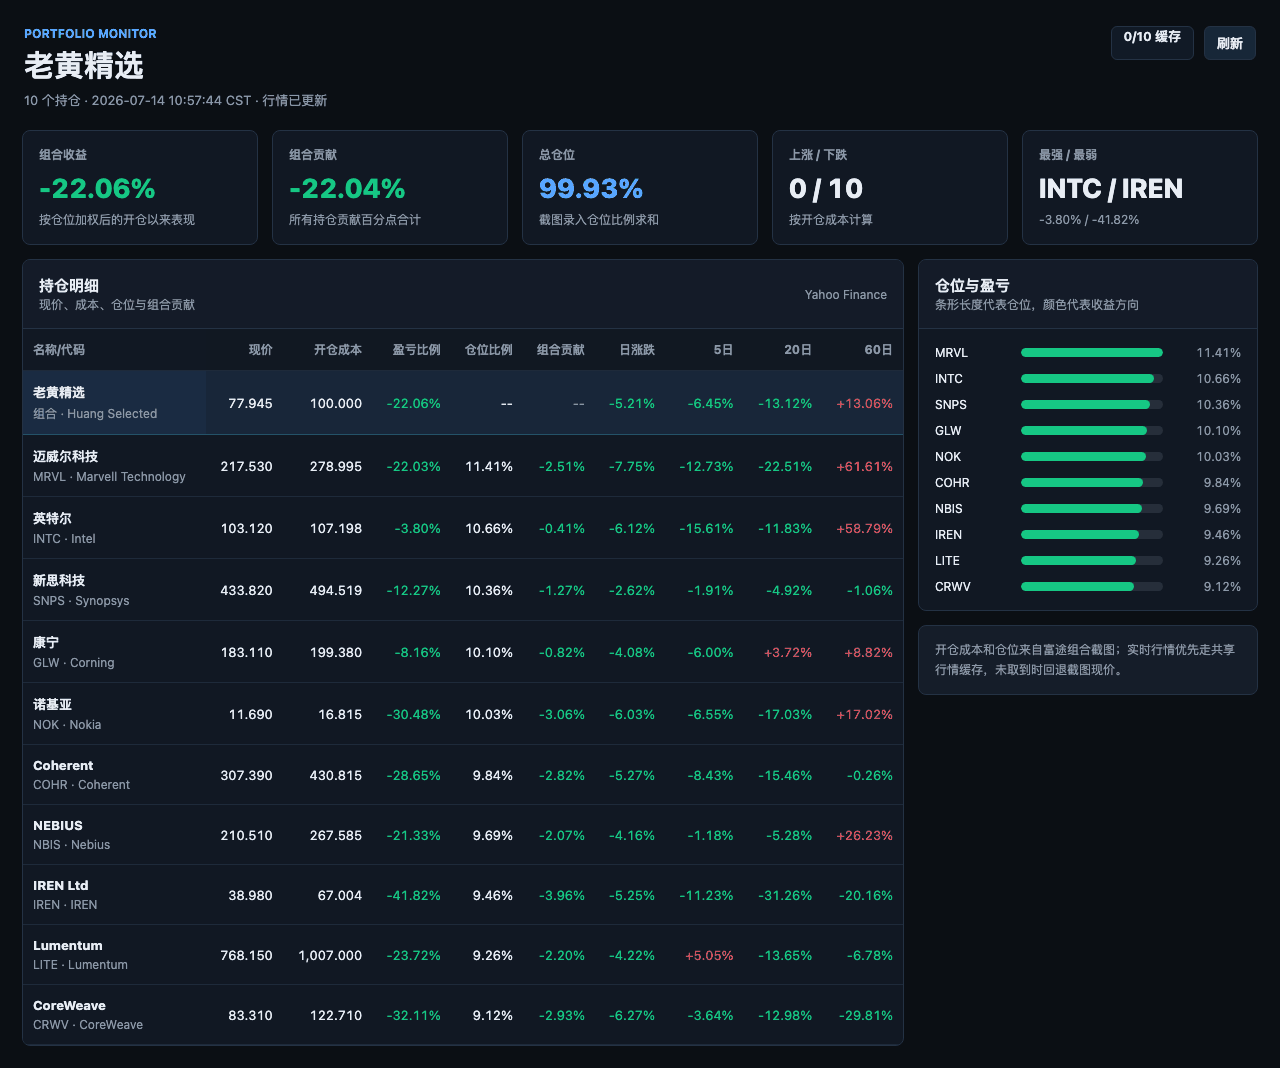
Huang’s Selected Portfolio
Related Reading
404K SEMI-AI Semiconductor Equipment Weekly — July 12, 2026 — WFE Upgrades, High-NA Adoption Divergence, and Testing and Cleaning Expansion404K SEMI-AI Morning Brief 2026-07-14 — Semiconductor De-Risking, Tight Memory Supply, and a Counter-Trend Rotation into Software
目录
Post-Market Summary
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
AI/Semiconductor Value Chain
CSP/Cloud Capex
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundries and Semiconductor Equipment/Testing
Optical Communications/Optical Chain and Data-Center Power
Robotics/Autonomous Driving and Space/Satellites
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio
Huang’s Selected Portfolio
Energy shocks and interest-rate concerns weighed on technology risk appetite, with semiconductors at the center of the sell-off. TSMC revenue, cloud capex, and long-term memory contracts continue to support medium-term demand, but end-market price increases and financing costs are beginning to provide counterevidence. Software and cloud stocks proved relatively resilient as capital rotated from high-beta hardware into cash flow and the application layer.
404K SEMI-AI | 2026-07-14
Post-Market Summary
U.S. equity risk appetite cooled markedly on July 13: the S&P; 500 fell 0.81% and the Nasdaq 100 declined 1.92%, while the equal-weighted S&P; 500 rose 0.23%. Technology fell 2.46%, while energy gained 3.30%. The crude oil ETF rose 9.42% and the VIX climbed 13.84%, as investors first moved to price energy, inflation, and interest-rate risks.
Semiconductors were at the center of the sell-off, with semiconductor ETFs falling 4.10% and 4.77%, respectively, and the AI and big data ETF declining 3.37%. The software ETF slipped only 0.03%, while the cloud computing ETF gained 0.16%, indicating that the market was not indiscriminately selling technology but reducing crowded positions in memory, interconnects, equipment, and capex-intensive names.
Fundamentals have not yet weakened in line with share prices. TSMC’s June revenue rose 67.9% year over year, forward capex estimates for cloud providers continue to move higher, and memory supply constraints still extend into 2027. However, smartphone shipments fell 11% year over year, while data-center financing and power constraints are increasing. The key question is whether demand can absorb higher prices, depreciation, and financing costs.
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
AI/Semiconductor Value Chain
CSP/Cloud Capex
Google
Morgan Stanley raised its 2027 and 2028 hyperscaler capex forecasts by 9% and 10%, respectively. Google’s 2028 spending is projected at US$375bn, the highest among the four companies. The capital will ultimately flow into TPUs, networking, and data centers, but whether this investment can translate into cloud revenue remains the key valuation test. If orders fail to convert into revenue, this thesis will be the first to break down.
Meta
The planned Louisiana data center has expanded from 2GW to 5GW, while disclosed investment has increased from US$27bn to more than US$50bn; market estimates suggest an even higher total cost when chips are included. The project validates AI infrastructure demand, but power requirements, construction timelines, and depreciation will pressure cash flow first. If utilization declines, the additional investment will become a drag on earnings.
Amazon
Morgan Stanley expects Amazon’s capex to reach US$318bn in 2028, primarily directed toward Trainium and AWS compute expansion. The risk is that cloud-provider capex has already reached the US$1tn scale. If AI service revenue growth slows, upstream equipment and server orders will be affected first. The next earnings report must validate the thesis through both revenue growth and cash flow.
Microsoft
Microsoft’s 2028 capex is projected at US$344bn. Azure’s annualized revenue is approximately US$75bn, up 40% year over year, while annualized AI revenue is approximately US$37bn, up 123%. The market is more focused on whether free cash flow can remain above US$50bn over the next 12 months, demonstrating that investment has not consumed the company’s cash-generation capacity.
“Memory accounts for 52% of CSP capex in 2026 and more than 70% the following year; quarterly DRAM ASP forecasts are +53%, +21%, and +7%.”
AI Cloud/Data-Center Operators
Oracle
Shares fell 6.29% on July 13 and are down 28.16% over 20 days, continuing to underperform even as the cloud computing ETF rose 0.16%. Oracle’s AI infrastructure positioning remains intact, but the stock is being pressured by both the pullback in emerging cloud providers and the rotation into software. The next test is whether contracted revenue, financing costs, and power delivery can materialize in tandem. If customers delay deployment, the current valuation will require further digestion.
Nebius
First-quarter 2026 revenue reached US$399mn, up 684% year over year, while AI cloud revenue rose 841%. The company has US$3.7bn in cash, a US$20bn backlog, and a Meta contract worth up to US$27bn. Nebius aims to secure 3GW of power by the end of 2026; construction speed and financing capacity will determine whether the backlog converts into revenue.
IREN
IREN’s Spanish data-center site benefits from 90% fiber penetration, 35 subsea cable landing points, and ample energy capacity, but the stock has fallen 31.49% over 20 days. Resource availability addresses only site selection; the real tests remain customer contracts, time to energization, and the capex payback period. The validation point is whether pricing, volume, and gross margin can all hold.
GPU/CPU/ASIC
Nvidia
Shares fell 3.63% on July 13, with trading value of US$24.61bn. Lightmatter joined the NVLink Fusion ecosystem, and its bidirectional optical-link solution aims to reduce fiber and connector requirements by as much as 50%. Density advantages continue to expand, but software, supply security, and cost per FLOP will determine whether ASICs can gain share.
Intel
Shares fell 6.31% and are down 15.79% over five days. Intel has reportedly invested several billion euros to expand advanced manufacturing in Ireland. MediaTek’s EMIB-T project is scheduled for tape-out in 4Q26 and mass production in 4Q27. TD Cowen maintained its Buy rating and raised its price target from US$75 to US$115. Process competitiveness, customer confidence, and utilization matter more than investment headlines.
Broadcom
Shares fell 3.62%. The scale-up networking market is projected to exceed US$70bn by 2030, with Broadcom exposed to both switching platforms and custom ASICs. The opportunity stems from rising GPU counts and rack interconnect density, while uncertainty remains over open interconnect protocols and the timing of CPO adoption. The real evidence will come from customer adoption, paid conversion, and retention.
AMD
Shares fell 4.44% but remain up 9.14% over 20 days. Industry assessments suggest AMD still needs to catch Nvidia on performance in certain vLLM models, requiring both MI500 and software investment to deliver. Chip specifications alone are insufficient; customers ultimately purchase usable throughput, development efficiency, and total cost of ownership. If lower costs do not generate more inference calls, demand expectations will decline.
“The number of intra-rack connections is 10 times that of inter-rack connections; switch bandwidth is 100Tbps; Matt Murphy presented the product at COMPUTEX 2026.”
HBM/DRAM/NAND/SSD/HDD
Micron
Shares fell 5.44%, with trading value of US$32.96bn. Forecast sequential growth in global DRAM ASPs slows from 53% in the second quarter to 21% in the third quarter and 7% in the fourth quarter. Prices are still rising, but the rate of increase is moderating. Whether high margins can hold depends on the simultaneous evolution of AI demand, long-term agreements, and specification reductions in consumer electronics. The next test is whether orders, deliveries, and collections improve in the same direction.
Samsung Electronics
Samsung held a 24% share of the global smartphone market in the second quarter, but its memory and handset businesses face opposing forces: AI is driving DRAM and NAND prices higher, while higher component costs are depressing end-market volumes. The next tests are HBM qualification, commodity DRAM pricing, and the ability to raise smartphone prices. Higher memory prices should not be treated as automatically translating into one-way improvement in group earnings. If supply improves faster than demand, pricing and margins will come under pressure first.
SK Hynix
Following sharp deleveraging in the Korean market, investors continue to weigh two competing interpretations: long-term agreements and HBM supply support earnings visibility, while lower blended pricing forecasts and delays in the HBM4 ramp weigh on expectations. Supply-chain sources suggest actual incremental capacity in 2028 could be only one-sixth of the original plan, making supply delivery the key variable. The next focus should be contract execution, capex, and free cash flow.
Sandisk
Shares fell 14.10%, with trading value of US$22.97bn. Five long-term NAND contracts are estimated to represent at least US$62bn in committed revenue, and Evercore raised its price target to US$3,100. The market is trading the tension between contract quality and the unwinding of crowded positions; prepayments, gross margins, and the fulfillment schedule require close monitoring.
Western Digital
Shares fell 5.10% but remain up 4.46% over 20 days, showing greater resilience than Sandisk. Enterprise storage demand and HDD capacity growth remain supportive. The risk is that combining NAND, SSD, and HDD metrics can obscure business differences; shipment capacity, pricing, and data-center customer procurement should be assessed separately. If user growth cannot be monetized, traffic advantages will not automatically translate into profit.
“TSMC’s June revenue reached a record NT$442.7bn, up 6.2% month over month and 67.9% year over year.”
Foundries and Semiconductor Equipment/Testing
TSMC
Shares fell 2.67%, but June revenue reached NT$442.68bn, up 67.9% year over year, while second-quarter revenue was approximately NT$1.27tn. Prices for 2nm, 3nm, and 5nm are expected to increase by 5%–10%. Commentary on gross margin and mature-node pricing on July 16 will test the company’s pricing power. The risk is that intensifying competition causes prices to fall faster than usage grows.
UMC
Phase 3 expansion of Singapore Fab 12i was completed in 2025, with 22nm and 28nm capacity ramping from 2H26 through 2027 and increasing total company capacity by approximately 1.2% annually. Whether the additional capacity converts into revenue depends on customer qualification and utilization, not the completion of the facility itself. If channel inventories continue to rise, new product launches will struggle to improve sales.
AMEC
Reports suggest the company may deliver its first 90:1 cryogenic etching system, although the original wording included the qualifier “appears,” indicating uncertainty. Confirmation from the company or a customer would indicate that the product has progressed from R&D; validation to delivery. Without a disclosed equipment model, acceptance, and repeat orders, no revenue contribution can yet be extrapolated. The next test is unit economics, not merely scale expansion.
“UMC completed Phase 3 expansion of Fab 12i in 2025; capacity will ramp from 2H26 through 2027; total company capacity will increase by approximately 1.2% annually.”
Optical Communications/Optical Chain and Data-Center Power
Marvell Technology
Shares fell 8.19% and are down 22.86% over 20 days. The company demonstrated its 100Tbps Teralynx switch and next-generation CPO switch, directly targeting higher intra-rack connection density. The risks are that mass production, customer adoption, yields, and orders have not been disclosed; a technology demonstration does not equal revenue realization. Delays in regulatory or security validation would also push back commercialization.
Lumentum
Supply-chain sources indicate that 1.6T demand has not weakened, while 800G demand has been revised significantly higher, with emerging cloud and model companies adding new customers. Supply of certain components is expected to improve from 2H26 through 1H27. Demand expansion and easing supply constraints are occurring simultaneously, so pricing and market share must be assessed separately. If any of orders, capacity, or customer qualification is missing, revenue could arrive later than expected.
Lite-On Technology
The company plans to invest US$919mn in a Texas manufacturing base, while its existing Plano facility produces battery backup units for AI servers. Capex in 2026 is expected to exceed the current NT$13bn level. U.S. manufacturing brings production closer to customers, but the commissioning schedule, orders, and returns remain unconfirmed. Gross margin and the pace of cash recovery will provide the market’s next answer.
onsemi
Shares fell 5.79% and are down 22.04% over 20 days. Demand from AI data centers and 800V DC electric vehicles is driving a recovery in silicon-carbide wafer prices, with incremental procurement requiring premium pricing. However, the industry has endured a two-year downturn and still has low-priced capacity, so a price rebound may not immediately translate into profits for overseas suppliers. If demand stems only from a short-term shortage, falling prices will quickly expose the risk.
“1.6T demand has not contracted; 800G demand has increased significantly versus prior expectations; supply of certain components is expected to improve gradually from 2H26 through 1H27.”
Robotics/Autonomous Driving and Space/Satellites
Intuitive Surgical
On July 13, TD Cowen maintained its Buy rating and lowered its price target from US$585 to US$520. The analyst believes the second quarter could mark a trough for the share price and that earnings guidance may still be raised. The lower target indicates reduced expectations for near-term execution; the next tests are procedure volumes, system placements, and guidance. The next phase requires operating data to keep pace with the product narrative.
Internet/Platforms
Shopify
Rose 1.80% on July 13. Third-party data point to approximately 32% year-over-year GMV growth in Q2, above the market expectation of roughly 27%. Price increases for non-Plus plans could add 3%–4% to 2027 revenue, although partner incentives will raise near-term expenses first. If orders fail to convert into revenue, this thesis will be the first to be invalidated.
Reddit
Shares rose 2.86% and are up 15.49% over 20 days. The Google data-licensing agreement is worth approximately $60 million annually, while the OpenAI agreement is reportedly worth roughly $70 million annually, bringing the total value of related agreements above $200 million. Whether the next renewal adopts a fixed-fee-plus-usage model will be critical to monetizing the data’s value. If utilization declines, incremental investment will instead weigh on profits.
Uber
The expansion of the robotaxi fleet introduces a new supply-side variable for the platform, with approximately 10,000 vehicles operating globally. Uber’s ability to benefit depends on partnerships with operators such as Waymo, vehicle utilization, and revenue-sharing arrangements—not the total number of autonomous vehicles itself. Regulation and safety will continue to affect rollout speed. The next earnings report must validate the thesis through both revenue growth and cash flow.
DoorDash
Up 22.63% over 20 days, with the strongest relative performance in the coverage universe, indicating that local-services platforms have not yet been dragged down by hardware-related risk reduction. With no new order or profit data available, the focus should shift to average order value, fulfillment costs, and advertising monetization rather than treating relative strength as a direct fundamental upgrade. If customers delay deployment, the current valuation will still need to be reassessed.
Airbnb
Up 11.81% over 20 days, although tensions in the Middle East and higher oil prices will raise the cost of international travel. The platform’s asset-light model reduces capital-expenditure pressure but cannot insulate it from demand volatility. Validation should come from booked nights, average daily rates, and cancellation rates—not sector rotation alone. The key test is whether pricing, volume, and gross margins can all hold.
“Shopify’s Q2 GMV grew approximately 32% year over year versus a market expectation of roughly 27%; potential price increases could add approximately 3%–4% to 2027 revenue.”
Netflix
Shares rose 0.34% but are down 9.41% over 20 days. The market remains concerned about user engagement, and streaming stocks did not participate in the pronounced software rally. The next indicators to watch are viewing hours, the ad-supported tier, and returns on content investment; resilience on a single day is insufficient to confirm a trend reversal. If renewals and average revenue per customer weaken, AI features will not support the valuation.
PayPal
Market commentary suggests Venmo’s growth could partly offset pressure on PayPal’s branded business. The key metrics for a payments platform are not account numbers but whether transaction frequency, payment volume, and take rates can hold. If the core brand remains under pressure, Venmo’s growth may amount only to internal substitution. The real evidence will be customer adoption, conversion to paid services, and retention.
Pinterest
The platform sits at the intersection of advertising and social commerce. AI recommendations can improve ad relevance, but no new verifiable operating figures were available today. The focus should be on monthly active users, ad pricing, and shopping conversion rather than equating AI feature launches directly with accelerating revenue. If lower costs do not drive higher usage, demand expectations will fall. This will determine the pace of earnings delivery.
Snap
The social-media and augmented-reality advertising businesses are sensitive to brand budgets, while macro risk reduction will lower near-term valuation tolerance. In the absence of new user and revenue data, the focus should be on daily active users, revenue per user, and whether compute investment improves ad conversion. Watch whether orders, delivery, and cash collection improve in the same direction. This will determine the pace of earnings delivery.
The Trade Desk
The programmatic advertising platform benefits from the migration of digital advertising budgets but also faces competition from large platforms’ proprietary data and closed ecosystems. The key indicators are customer retention, CTV spending, and customer-acquisition costs. Without new financial data, it is inappropriate to extrapolate performance solely from the software-sector rally. If supply improves faster than demand, pricing and profits will come under pressure first.
“The total value of the related agreements exceeds $200 million; negotiations began in late 2022, when OpenAI’s revenue was approximately $25 million.”
WhatsApp
ChatGPT has returned to WhatsApp in the European Economic Area, supporting text, images, voice messages, image generation, and multilingual communication. This distribution channel is closer to everyday use cases, but whether the platform can capture commercial value will still depend on engagement, paid conversion, and revenue-sharing arrangements. The next indicators to watch are contract execution, capital expenditure, and free cash flow.
Kakao
ChatGPT is now available on Kakao in South Korea, indicating that AI assistants are moving from standalone applications to communications platforms. Channel expansion can lower customer-acquisition barriers, but user numbers, retention, and monetization models have not been disclosed. The platform’s value must be validated through usage frequency and revenue contribution. If user growth cannot be monetized, traffic advantages will not automatically translate into profits.
Viber
ChatGPT has also entered selected Viber markets, establishing communications-channel distribution across regions. Broader feature coverage does not equal successful commercialization. Supported countries, feature consistency, regulatory constraints, and platform revenue sharing have not been disclosed, so only channel expansion can currently be confirmed. The risk is that intensifying competition drives prices down faster than usage grows. This will determine the pace of earnings delivery.
“Users can message the verified 1-800-CHATGPT contact to ask text-based questions, upload images, send voice messages, create images, and communicate in multiple languages.”
Similarweb
AI website traffic grew 45.57% year over year in the first half of 2026, significantly faster than the 3.64% growth for social-media websites and 2.90% for websites across all industries. The data confirm a shift in user attention, but without absolute base figures or monetization metrics, they cannot be used to infer revenue for specific platforms directly. If channel inventory continues to rise, new product launches will also struggle to improve sales.
Palantir
Shares rose 2.56% but are down 1.20% over 20 days. Enterprise AI platforms have been more resilient than semiconductors, indicating that the market is placing greater emphasis on real-world deployment. The next indicators are government and commercial contracts, customer expansion, and profits, rather than interpreting a single day’s rotation as a long-term valuation upgrade. Unit economics must be assessed next; scale expansion alone is insufficient.
“AI website traffic grew 45.57% year over year in the first half; social-media website traffic grew 3.64%; traffic across all industries grew 2.90%.”
“The average model lead lasted 41 days; fifth-month retention ranged from the high single digits to approximately 40%.”
Software/SaaS
CrowdStrike
ARR stands at $5.51 billion, with Falcon Flex ARR exceeding $1.9 billion. The platform has expanded beyond endpoints into identity, cloud workloads, and threat intelligence. AI is expanding the attack surface, keeping the spending thesis intact; the risk is whether platform consolidation can offset competition and customer budget scrutiny. If regulatory or security validation is delayed, commercialization will also be pushed back.
Palo Alto Networks
Shares rose 1.15% and are up 17.94% over 20 days. Cortex, Prisma, and CyberArk cover endpoint, network, cloud, and identity security, while the platform strategy aligns with customers’ desire to reduce vendor counts. Watch cross-selling, billings growth, and integration costs.
Cloudflare
Shares rose 0.42% and are up 18.51% over 20 days, ranking near the top in relative strength. Its global edge network supports both zero-trust security and AI inference traffic. The market expects approximately 30% revenue growth, but whether high growth can translate into free cash flow remains to be validated. If any of orders, capacity, or customer validation is missing, revenue could arrive later than expected.
Zscaler
Zero trust and SASE allow users to connect directly to applications, replacing traditional perimeter security. AI agents increase the complexity of identity and access control, supporting security budgets. The counterargument is that bundled integrated platforms could compress pricing and renewal headroom for point-solution vendors. Gross margins and cash-conversion speed will provide the market’s next answer. This will determine the pace of earnings delivery.
Fortinet
FortiOS and custom ASICs integrate firewalls, SD-WAN, SASE, endpoint, and cloud security, giving the hardware-plus-software model a cost advantage. If customers shift toward pure-cloud platforms, hardware cycles and inventory will continue to weigh on growth; the revenue mix between subscriptions and products must be monitored. If demand reflects only temporary shortages, falling prices will quickly expose the risk.
“CrowdStrike ARR stands at $5.51 billion; Falcon Flex ARR exceeds $1.9 billion; Cisco acquired Splunk for $28 billion.”
Cisco
The company acquired Splunk for $28 billion, strengthening the correlation and analysis of network telemetry, SIEM, and XDR data. The transaction expands its security-data access but also creates integration and cross-selling pressure. Success should be judged by renewal rates, synergy revenue, and costs—not the size of the acquisition. The next stage is to determine whether operating data can match the product narrative. This will determine the pace of earnings delivery.
Okta
AI workflows are increasing the number of machine identities and non-human accounts, raising the importance of identity governance. Okta’s opportunity lies in permissions management and access control, while the risks are Microsoft bundling and platform consolidation. Watch customer expansion, net retention, and large-account renewals. If orders fail to convert into revenue, this thesis will be the first to be invalidated. This will determine the pace of earnings delivery.
Rubrik
Cyber resilience and post-breach recovery are becoming the final line of defense for data security in the AI era. The demand direction is clear, but whether the company can expand from backup into platform-level budgets must be assessed through subscription growth, recovery success rates, and customer concentration—not merely the frequency of security incidents. If utilization declines, incremental investment will instead weigh on profits. This will determine the pace of earnings delivery.
Qualys
Vulnerability prioritization and exposure management help customers direct limited security budgets toward the highest-risk attack paths. AI can improve detection efficiency but may also increase false positives. Watch platform integration, customer retention, and pricing rather than simply counting vulnerabilities. The next earnings report must validate the thesis through both revenue growth and cash flow. This will determine the pace of earnings delivery. This will determine the pace of earnings delivery.
Tenable
The company operates in vulnerability management and attack-path analysis, benefiting from the expansion of cloud assets and AI workflows. Competition is shifting from problem discovery toward remediation coordination. If it cannot become part of a broader security platform, the point solution may face pressure as budgets consolidate. If customers delay deployment, the current valuation will still need to be reassessed. This will determine the pace of earnings delivery.
“Developers subjectively estimated that completion times fell 20%, while measured completion times increased 19%.”
Salesforce
Shares rose 4.62% on $2.4 billion in trading volume, ranking among the stronger performers in the software rotation. The market is trading enterprise-software cash flow and real-world AI adoption, but whether agent products can increase average revenue per customer, renewals, and seat expansion must still be validated through billings and remaining performance obligations. The key test is whether pricing, volume, and gross margins can all hold. This will determine the pace of earnings delivery.
ServiceNow
Shares rose 3.01% and are up 7.64% over 20 days. Workflow AI is closer to enterprise budgets than general-purpose chat tools, but deployment complexity and customer data quality determine returns. Watch large deals, renewals, and incremental revenue from AI products. If renewals and average revenue per customer weaken, AI features will not support the valuation. This will determine the pace of earnings delivery.
Snowflake
Shares rose 1.91% and are up 10.83% over 20 days. The data cloud is foundational infrastructure for enterprises to train, govern, and use AI, while consumption-based pricing can benefit from higher usage. The counterargument is that model caching and efficiency gains may reduce consumption per task. The real evidence will be customer adoption, conversion to paid services, and retention. This will determine the pace of earnings delivery.
Datadog
Shares rose 0.40% and are up 10.39% over 20 days. AI applications increase demand for monitoring logs, models, and infrastructure, expanding observability requirements as complexity rises. The risk is that cloud customers optimize spending; watch usage, customer expansion, and gross margins. If lower costs do not drive higher usage, demand expectations will fall. This will determine the pace of earnings delivery.
AppLovin
Shares fell 12.65%, with e-commerce advertising showing no clear improvement following a weak June. The AI advertising thesis requires merchant growth, adoption, and conversion to provide support. If new pixel installations remain slow following the June 22 opening, the valuation will continue to compress toward realized revenue. Watch whether orders, delivery, and cash collection improve in the same direction. This will determine the pace of earnings delivery.
“Software stocks instead outperformed the semiconductor ‘AI winners’: Figma rose 10%, TEAM 8%, Intuit 6%, and MNDY, HUBS, and CRM each gained 5%.”
“Cache hits accounted for 95% of total token consumption and reduced token costs by 84%.”
“Learning speed on tasks using new models was approximately twice that of models from three months earlier; the proportion of CEOs expecting AI to cause large-scale layoffs fell from 46% in January 2025 to 20% in May 2026.”
Consumer Electronics / Smart Vehicles
Apple
Shares rose 0.63% and are trading near 52-week and all-time highs; global shipments grew 3% YoY in Q2, with market share reaching 20% for the first time. Premium demand is more resilient than the broader industry, but the stock trades at an approximately 65% valuation premium to the S&P; 500, requiring fall product launches and AI features to meet elevated expectations. If supply improves faster than demand, pricing and margins will come under pressure first.
Samsung Electronics
Samsung regained the top position with a 24% share of global smartphone shipments in Q2. The company is benefiting from rising memory prices while facing higher handset bill-of-materials costs; regional pricing power is temporarily cushioning the pressure. The key question is whether mid- and low-end volumes and end-market price increases can preserve market share. The next factors to watch are contract fulfillment, capital expenditure, and free cash flow. These will determine the pace of earnings delivery.
Xiaomi
Global smartphone shipments fell 11% YoY, with memory shortages having a greater impact on mid- and low-end models. Xiaomi faces dual pressure from rising DRAM and NAND prices and weakening demand. Investors should focus on per-device memory configurations, average selling prices, and shipments rather than market share alone. If user growth cannot be monetized, its traffic advantage will not automatically translate into profits.
OPPO
Memory-chip shortages are driving up handset prices, making demand destruction more likely in OPPO’s mid- and low-end markets. Industry shipments have fallen to their lowest level for the corresponding period since 2013; if supply constraints persist, specification cuts and promotional intensity will determine volume elasticity. The risk is that prices fall faster than usage grows as competition intensifies. This will determine the pace of earnings delivery.
vivo
The company is likewise under pressure to pass higher memory costs through to consumers. AI servers are competing for DRAM and NAND supply, forcing handset makers to balance specifications, pricing, and gross margins. The key question is whether channel inventories and new-product pricing trigger further demand contraction. If channel inventories continue to rise, new-product launches will struggle to improve sales. This will determine the pace of earnings delivery.
“Apple’s Q2 shipments grew 3% YoY, with market share reaching 20% for the first time, primarily supported by strong demand for its premium iPhone lineup.”
Google Pixel
Google’s smartphone shipments grew 16% YoY in Q2, gaining ground even as the industry declined 11%. The growth indicates gains in product and channel share, but absolute scale, profitability, and memory costs were not disclosed; the key question is whether these share gains can be sustained across quarters. Investors need to assess unit economics, not merely scale expansion. This will determine the pace of earnings delivery.
MediaTek
Supply-chain sources indicate that the company has again lowered its full-year smartphone shipment outlook, while its ASIC business is constrained by TSMC wafer allocations. Traditional handset demand and AI-chip opportunities are moving in opposite directions; the ability to shift the revenue mix depends on wafer supply, customer projects, and the pace of mass production. If regulatory or security validation is delayed, commercialization will also be pushed back. This will determine the pace of earnings delivery.
Qualcomm
Shares fell 2.74% and are down 9.35% over 20 days. The handset SoC business faces declining shipments and rising memory prices, while data-center and edge AI offer new growth avenues. Investors should assess whether non-handset revenue growth can sufficiently offset pressure on end-market demand. Any shortfall in orders, capacity, or customer validation could delay revenue beyond expectations. This will determine the pace of earnings delivery.
“MediaTek again lowered its full-year smartphone shipment outlook; its ASIC business is constrained by TSMC wafer allocations.”
Tesla
Shares fell 3.45%. Reportedly, 100 Cybercabs are being tested in Houston; Jefferies raised its price target from $375 to $400 after Q2 deliveries exceeded expectations, while another firm lowered its year-end target from $569 to $500. The divergence shows that the market is simultaneously pricing in improved deliveries and the commercialization timelines for Robotaxi and Optimus.
Waymo
The global Robotaxi fleet totals approximately 10,000 vehicles, with Waymo currently the leading participant. Future growth depends on cities opening up, vehicle utilization, and safety performance. Industry fleet expansion does not establish per-vehicle economics; investors need to assess cost per mile and regulatory approvals. If demand merely reflects a temporary shortage, falling prices will quickly expose the risk.
Zoox
Amazon-owned Zoox is positioned in the expanding Robotaxi market, supported by its parent company’s funding and cloud capabilities. Commercialization still requires progress in vehicle mass production, operating permits, and safety validation. Without clear fleet and order data, long-term industry projections should not be used as a substitute for company-specific execution. The next phase will test whether operating data can support the product narrative. This will determine the pace of earnings delivery.
“The humanoid-robot market could reach $5 trillion by 2050; manufacturing scale is not expected to begin ramping until around 2030.”
Rivian
California’s new subsidy is more favorable to automakers headquartered in the state, offering $3,500 per new vehicle with a $50,000 price cap; Rivian could gain a relative policy advantage. Whether the subsidy translates into sales will also depend on vehicle pricing, production capacity, and per-unit losses. If orders fail to convert into revenue, this thesis will be invalidated first. This will determine the pace of earnings delivery.
Lucid
Lucid could likewise benefit from California’s headquarters exemption, but the subsidy budget is limited to $270 million, restricting its reach. Policy support can only ease demand-side pressure; it cannot substitute for evidence of higher capacity utilization, delivery growth, and controlled cash burn. If utilization declines, incremental investment will instead weigh on profits. This will determine the pace of earnings delivery. This will determine the pace of earnings delivery.
Volkswagen
The company may cut approximately 50,000 additional jobs, potentially bringing total layoffs to 100,000, reflecting the cost and electrification-transition pressures facing European automakers. PowerCo’s battery plant is scheduled to begin production in 2027; execution will hinge on construction progress, utilization, and whether EV sales can absorb the capacity. The next earnings report must validate the thesis through both revenue growth and cash flow. This will determine the pace of earnings delivery.
PowerCo
The plant represents a $7 billion investment, will create approximately 3,000 jobs, and is designed to supply up to one million vehicles annually, with licensed capacity of up to 85 GWh. The scale targets are clear, but the 2027 production start, commercialization of QuantumScape technology, and royalty revenue remain subject to execution risk. If customers delay deployment, the current valuation will require reassessment.
“The subsidy budget is $270 million; Volkswagen may cut approximately 50,000 additional jobs, potentially bringing total layoffs to 100,000, while its shares are at a 16-year low.”
“PowerCo’s plant represents a $7 billion investment, will create approximately 3,000 jobs, can supply up to one million vehicles annually, and has licensed capacity of up to 85 GWh.”
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio
Huang’s Selected Portfolio