404K SEMI-AI Morning Brief 2026-07-21 — Memory Shortages Persist, AI Cloud Contracts Ramp, Software Performance Diverges
目录
Post-Market Summary
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
AI Cloud/Data Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Semiconductor Equipment/Testing
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Sell-Side Price-Target Changes Over the Past 12 Hours
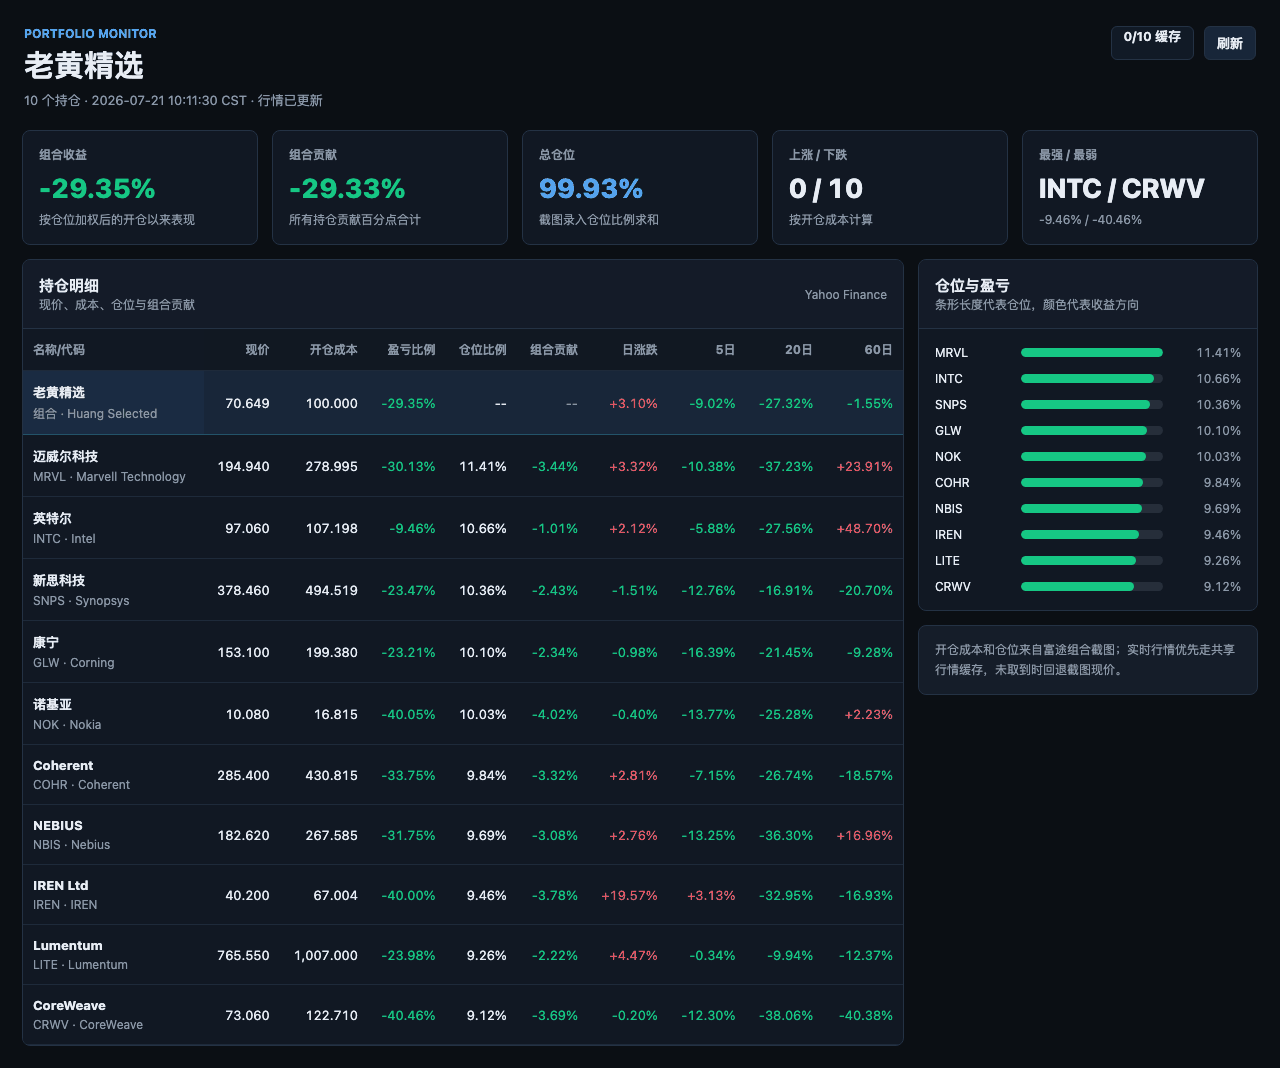
Jensen Huang’s Selected Portfolio
U.S. technology stocks stabilized, but medium-term semiconductor momentum remains weak. Incremental upside is concentrated in three areas: AI cloud contracts are beginning to generate customer prepayments and revenue visibility; Kimi K3 is bringing long-context storage demand to the forefront; and software capital continues to concentrate in infrastructure and security.
404K SEMI-AI | 2026-07-21
Post-Market Summary
U.S. equities traded in a narrow, mixed range on July 20. The S&P; 500 fell 0.13%, the Nasdaq 100 rose 0.10%, and the Dow declined 0.54%. The equal-weighted S&P; 500 fell 0.45%, while the Russell 2000 lost 0.59%, indicating that gains remained concentrated in a small number of large-cap technology stocks, without a corresponding improvement in market breadth.
The technology ETF rose 0.18%, the semiconductor ETF gained 0.41%, the AI and big data ETF advanced 0.75%, and the software ETF increased 0.19%. However, the semiconductor ETF remains down 15.31% over the past 20 days, while the software ETF has gained 4.37%, suggesting that capital preferences have shifted from high-volatility hardware toward software and security segments with greater revenue visibility.
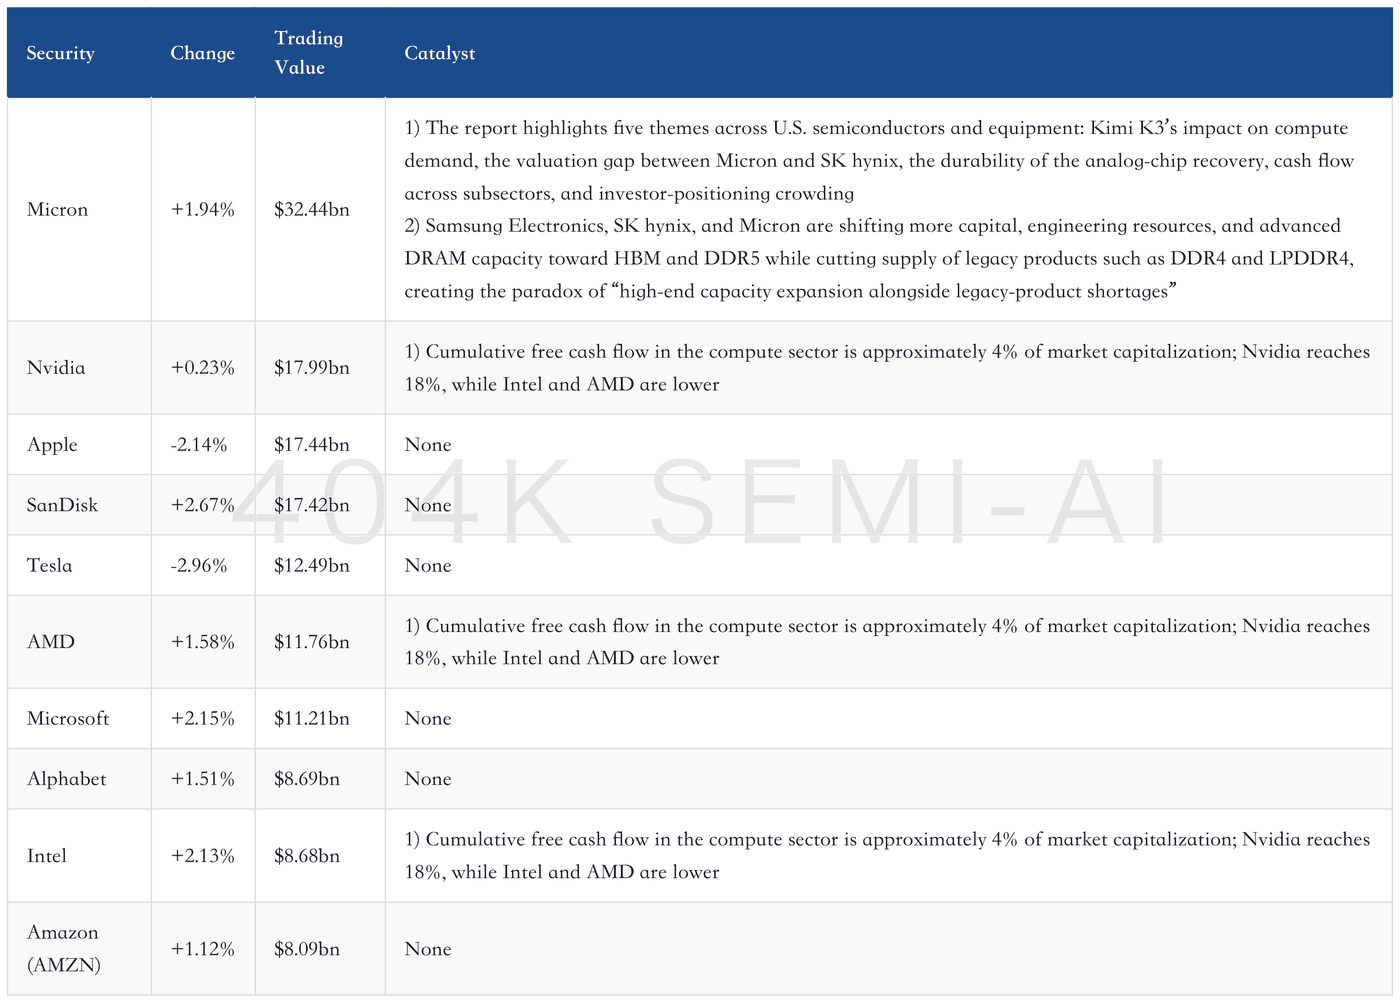
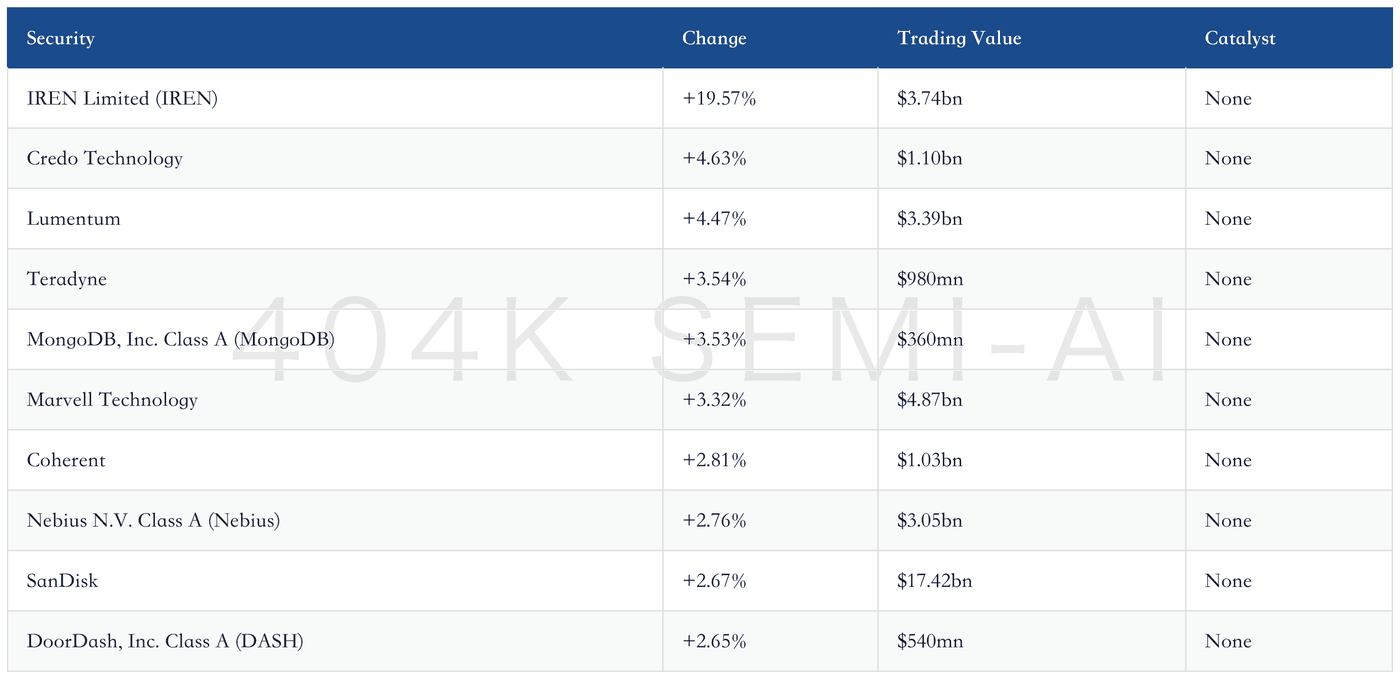
At the stock level, IREN surged 19.57% as a new AI cloud contract strengthened revenue visibility. Micron, SanDisk, Intel, and Arm rebounded, although memory and chip-IP stocks remain deeply below their levels from 20 days ago. The key question is whether this oversold recovery can continue to be validated by orders, pricing, and cash flow.
Top 10 U.S. Stocks by Trading Value
Top U.S. Stock Gainers
Top U.S. Stock Decliners
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
Kimi K3
1) The model has 2.8 trillion parameters, a 1 million-token context window, and an always-on inference mode. Long contexts increase absolute KV-cache requirements even after quantization.
2) It ranks No. 1 on the front-end coding arena. If low-cost open-source models drive more usage, GPUs, HBM, and storage should still benefit; compute demand does not disappear.
“The author believes its launch may trigger a semiconductor-stock correction similar to DeepSeek R1, but the core implication is not that low-cost models replace compute demand. Rather, lower unit costs drive higher usage.”
DeepSeek: Annualized revenue is approaching $500mn, while the V4 model has achieved a gross margin of 70%–80%, indicating that model demand has begun translating into revenue. Whether these high margins are sustainable depends on inference pricing, usage, and compute costs. Investors should track both revenue growth and unit inference costs rather than benchmark rankings alone; commercialization quality must ultimately be validated by cash collection.
“DeepSeek’s annualized revenue is approaching $500mn, while the V4 model has achieved a gross margin of 70%–80%.”
AI Content Generation: Enterprise adoption is shifting from experimentation to budget substitution. One television-advertising project originally budgeted at more than $5mn saw AI production costs fall to $3,000–$4,000; another $800,000 visual project fell to less than $10,000. Production cycles compressed from two to three months to three hours, with the initial value proposition centered on cost and delivery speed.
AI Cloud/Data Center Operators
IREN
1) The company signed a $2.8bn AI cloud contract and raised its year-end 2026 annualized run-rate revenue target from $3.7bn to more than $4.0bn, approximately 85% of which is contractually secured.
2) Customers will prepay approximately 45% of the related GPU capital expenditure. Goldman Sachs estimates approximately $1bn of incremental contracted revenue, with an average term of roughly three years. The revenue target, contract value, and recognition schedule should still be assessed separately.
“Approximately 85% of the current target is contractually secured, and customers will also prepay roughly 45% of the related GPU capital expenditure.”
CoreWeave: Bank of America maintained its Buy rating and $140 price target, raising its FY2026 capital-expenditure forecast from $29bn to $34bn. It expects operating margin to rise from 1.0% in 1Q26 to 14.6% in 4Q26, although the 2Q forecast of 2.4% is below the 2.8% consensus. The pace of capacity expansion and financing costs remain near-term pressures.
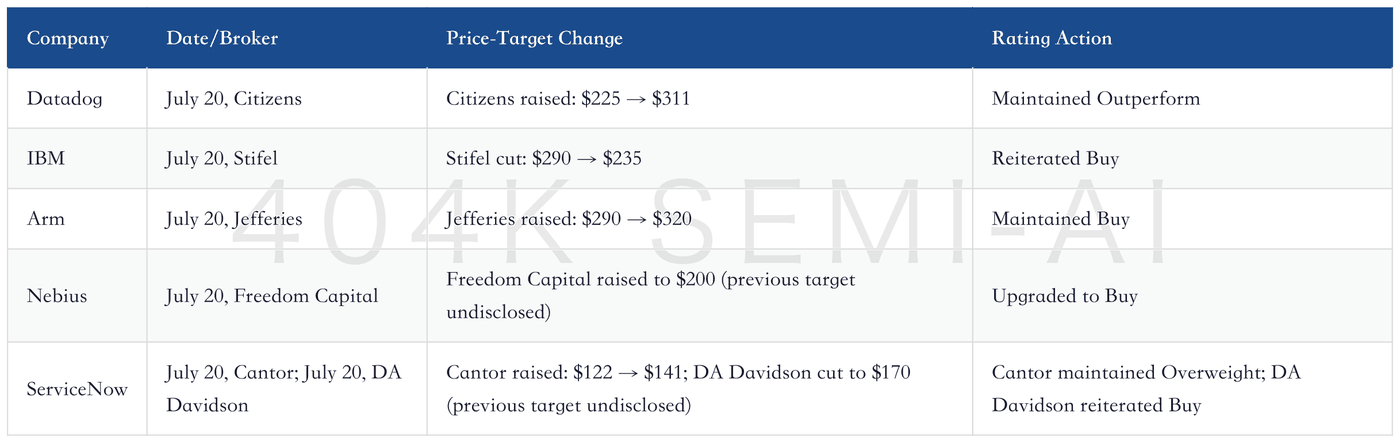
Nebius: Freedom Capital upgraded the stock to Buy and raised its price target to $200; the previous target was not disclosed. The valuation applies a 4–6x 2028 EV/EBITDA multiple, based on a 2028 revenue forecast 41 times the current level. The valuation is highly dependent on long-term revenue delivery, making orders and capital-efficiency metrics more important than near-term share-price movements.
Hut 8: The second AI data center lease at Beacon Point, Texas, is valued at $9.8bn over 15 years, increasing contracted capacity with the same tenant from 352 MW to 704 MW. The 1,000 MW campus is now fully commercialized, with total base-term contract value of $19.6bn and expected average annual net operating income of $1.31bn. Phase-two construction and tenant performance will determine cash-flow realization.
“In just a matter of months, we advanced this greenfield site from its first lease to full commercialization.”
GPU/CPU/ASIC
Nvidia: The stock rose 0.19% on July 20 but is down 3.55% over the past 20 days. UBS estimates cumulative free cash flow through 2028 at approximately 18% of current market capitalization, well above the compute sector average of roughly 4%. Morgan Stanley continues to view Nvidia as one of the more compelling companies in the compute value chain, with support from both cash flow and open-source-model demand.
Intel
1) Jefferies forecasts second-quarter revenue of $14.35bn and Data Center and AI revenue of $5.64bn, with the latter rising 12% sequentially. It forecasts third-quarter Data Center and AI revenue of $6.25bn.
2) Market reports suggest the company may raise capital after the second or third quarter to address $2.5bn and $3.8bn of maturing debt. Capital expenditure on advanced process nodes remains constrained by customer orders.
“Revenue is expected to grow approximately 8%, driven by stronger server/AI demand and improved pricing, versus the Street’s +5% estimate.”
Broadcom: UBS forecasts cumulative free cash flow of $278bn through 2028, equivalent to 16% of current market capitalization and the largest absolute cash-generation figure in its networking and infrastructure coverage. Morgan Stanley identifies Broadcom and Nvidia as offering superior risk-reward in the compute value chain, although crowded positioning means even modest fundamental misses could amplify volatility.
AMD: The stock rose 1.58% on July 20 but is down 6.28% over the past 20 days. UBS notes that AMD remains significantly crowded on the long side, while average cumulative free cash flow for the compute sector through 2028 is only around 4% of market capitalization and AMD’s free-cash-flow level is relatively low. The market is pricing product growth; subsequent validation must come from free-cash-flow conversion rather than revenue scale alone.
Arm: Jefferies maintained its Buy rating and raised its price target from $290 to $320, citing increased AGI CPU orders from new customers and the possibility that SoftBank may launch a GPU. The stock rose 0.81% on the day but is down 38.71% over the past 20 days. Expectations for long-term orders coexist with near-term valuation compression; the key variables to monitor are contributions from new customers and the pace of licensing revenue.
HBM/DRAM/NAND/SSD/HDD
Micron
1) UBS forecasts more than $40bn in cumulative free cash flow through 2028, equivalent to 47% of current market capitalization. Once repurchase restrictions expire on December 9, 2026, the company could potentially repurchase more than 40% of its shares at current prices.
2) Micron still trades at an approximately 0.3x discount to SK hynix on next-12-month EV/sales, despite historically commanding a premium. The risk is that the cash-flow outlook depends on persistent memory shortages.
“MU has historically traded at a premium to SKHY”
Samsung Electronics: Capital and engineering resources continue to shift toward HBM and DDR5, while supply of legacy products such as DDR4 and LPDDR4 is being reduced. Consumer DRAM contract prices are expected to rise 45%–50% sequentially in the second quarter, indicating that high-end capacity expansion is crowding out legacy-product supply. If mature-product capacity is subsequently expanded rapidly, shortages could also turn into inventory pressure.
SK hynix: Strong memory-industry conditions coexist with crowded positioning. UBS estimates cumulative free cash flow for the memory sector through 2028 at approximately 30% of market capitalization, but Morgan Stanley cautions that this cycle is driven almost entirely by data centers. Signals from consumer electronics, PCs, and smartphones could repeatedly disrupt spot prices. Not every price increase should be treated as evidence of long-term structural scarcity; pricing and inventories must be monitored together.
SanDisk: The stock rose 3.41% on July 20, with trading value of $17.42bn, but remains down 35.87% over the past 20 days. Morgan Stanley expects like-for-like memory pricing to rise at least 25% from the second to the third quarter and believes shortages will intensify through 2027 and 2028. Whether improved pricing translates into NAND profits will still depend on supply discipline and data center demand.
Seagate Technology and Western Digital: Seagate and Micron are the most crowded long-positioned memory stocks in UBS’s coverage, followed closely by Western Digital. On July 20, the two companies rose 2.22% and 2.35%, respectively, but remain down 24.71% and 34.55% over the past 20 days. Data center HDD demand remains strong, although crowded positioning will amplify volatility around inventory-related reports.
“Memory supply is insufficient relative to AI demand, and we see absolutely no indication that this situation will change…”
Semiconductor Equipment/Testing
ASML: The company expects shipments of low-NA EUV systems to grow 30% in both 2027 and 2028, while effective industry wafer capacity could increase by more than 45%. The difference reflects a higher mix of high-throughput systems and upgrade packages for the installed base. System volumes are not the only variable: per-tool capacity and upgrade revenue also determine revenue quality and represent incremental growth beyond equipment pricing.
“Capacity growth is higher because of the increasing mix of systems with greater wafer throughput. Upgrade packages for the installed base will also provide incremental capacity.”
Teradyne: The stock rose 3.54% on July 20 but is down 23.79% over the past 20 days. SEMI expects test-equipment sales to grow 31% to $15.3bn in 2026 and reach $20.8bn in 2028. AI systems raise requirements for known-good-die screening, thermal validation, and high-speed interface testing, turning testing from a back-end cost item into a critical yield and reliability function.
Applied Materials: The stock fell 0.85% on July 20 and is down 14.90% over the past 20 days. UBS notes that long-side crowding has recently eased slightly. Meanwhile, wafer-fab-equipment sales are expected to grow 23.1% to $143.9bn in 2026. Rising industry capital expenditure does not mean that all equipment vendors will benefit equally; product mix and customer expansion schedules determine the order-growth trajectory.
Lam Research and KLA: The two companies fell 2.62% and 2.77%, respectively, on July 20 and are down 21.58% and 20.31% over the past 20 days. UBS notes that Lam Research remains one of the most crowded semiconductor stocks, while long-side crowding in KLA has increased. Within the same equipment cycle, positioning can amplify deviations from order expectations, but order delivery remains the ultimate anchor.
Advanced Packaging and Test Equipment: Assembly and packaging equipment sales are expected to grow 9.6% to $6.7bn in 2026 and reach $8.6bn in 2028; test-equipment sales are expected to rise from $15.3bn to $20.8bn over the same period. Incremental demand is driven by chiplets, HBM integration, thermal management, and system reliability. The risk is that duplicated regional capacity ultimately leads to lower utilization.
Internet/Platforms
Google: Reports second-quarter results after the close on July 22. The market will focus on cloud growth, margins, AI capex, Gemini monetization, and search advertising. Shares rose 1.54% on July 20 but fell 4.32% over the past 20 days; the stock needs evidence that AI investment is beginning to translate into revenue, rather than merely continued capex expansion.
“Google will report earnings after the close on July 22. The focus is not only revenue, but also AI execution.”
Microsoft: Shares rose 2.19% on July 20 and 6.08% over the past 20 days. Deutsche Bank reiterated its Buy rating and $550 price target, arguing that concerns over capex, AI returns, and OpenAI-related risks are fully reflected in the valuation. Grok’s new Excel add-in also shows that productivity entry points continue to attract external models; the platform’s value lies in distribution and connectivity to enterprise data.
“Market concerns over capex, AI returns, and OpenAI risk exposure are overstated.”
Meta: Shares rose 0.08% on July 20 and 12.00% over the past 20 days, with a stock-level RPS20 of 94.1. Bank of America maintained its Buy rating and $835 price target, expecting solid second-quarter advertising growth and potential EPS upside from workforce reductions, while incorporating future AI revenue into its valuation. Near-term validation still rests on advertising and cost control, while AI revenue remains a longer-dated option.
“Second-quarter advertising growth is solid, while recent workforce reductions could provide upside to earnings per share (EPS).”
Amazon: Shares rose 1.20% on July 20 and 2.38% over the past 20 days, with a stock-level RPS20 of 87.6. Compared with the cloud-computing ETF’s 3.62% gain over the same period, Amazon performed broadly in line with the sector. The key questions remain AWS revenue, margins, and whether demand growth can keep pace with depreciation from AI infrastructure; rising depreciation will directly test cash returns.
Netflix: Phillip Securities upgraded the stock to Buy and maintained its $110 price target, citing subscriber scale, pricing power, and advertising monetization. Shares fell 2.03% on the day and 12.70% over the past 20 days. The improved rating and weaker share price coexist; further upside requires validation from advertising revenue and retention following price increases, rather than valuation recovery alone. Advertising revenue per user is the key metric to track.
“Recent share-price performance has created an attractive entry point, supported by solid subscriber scale, strong pricing power, and growing advertising monetization.”
DoorDash: Shares rose 2.53% on July 20 and 8.84% over the past 20 days, with a stock-level RPS20 of 92.2, placing it among the stronger platform stocks. The price signal indicates that investor preference remains favorable, but durability must be validated by order frequency, fulfillment costs, and advertising monetization rather than a single day’s trading-volume ranking. These factors will determine whether profit leverage and earnings quality can be sustained.
Shopify: Shares rose 14.69% over the past 20 days, with a stock-level RPS20 of 96.1, trailing only a handful of software names among internet platforms. The market is pricing in the revenue resilience of e-commerce infrastructure. Further strength should be confirmed through merchant growth, payments penetration, and free cash flow, particularly whether larger merchants are contributing more without weakening cash conversion.
Reddit: Shares rose 1.00% on July 20 and 4.60% over the past 20 days, with a stock-level RPS20 of 88.9. The platform’s AI data-licensing narrative remains supported. Advertising growth, user engagement, and the share of revenue from data licensing will determine whether the valuation can shift from thematic appeal to auditable cash flow. The pace of license renewals is equally important, and contract durations also need to extend.
Pinterest: Shares rose 12.53% over the past 20 days, materially outperforming the communication-services ETF’s 1.50% gain over the same period, with a stock-level RPS20 of 94.8. Investor preference points to social commerce and advertising efficiency. The next metrics to watch are ad pricing, shopping conversion, and international-user monetization. Overseas monetization is the primary source of upside, while user retention must also remain stable.
Uber: Shares fell 0.44% on July 20 but rose 0.70% over the past 20 days, with a stock-level RPS20 of 85.0. Medium-term performance among platform stocks remains solid but offers limited upside leverage. Further validation requires simultaneous strength in mobility bookings, delivery frequency, and margins. If incentives or insurance costs rise, revenue growth may not translate proportionately into free cash flow; platform scale is no substitute for cash returns.
Airbnb: Shares fell 1.01% on July 20 but rose 1.47% over the past 20 days, with a stock-level RPS20 of 86.3. Relative strength remains near the top of the travel-accommodation platform group, but price performance shows no clear acceleration. Key metrics are booked nights, average daily rates, and marketing efficiency, particularly whether peak-season demand can offset supply expansion. Supply-demand balance determines the quality of the platform’s take rate.
AppLovin: Shares rose 0.23% on July 20 but fell 9.41% over the past 20 days, with a stock-level RPS20 of 64.7. Advertising and AI-application monetization remain the central themes, but medium-term share performance has lagged Pinterest and DoorDash. Advertiser returns, platform retention, and margins must validate algorithmic efficiency; the AI label alone is insufficient.
Snap: Shares rose 0.66% on July 20 but fell 2.15% over the past 20 days and 43.91% year to date, with a stock-level RPS20 of 81.0. Improving relative strength has yet to reverse the full-year drawdown. Commercial validation still depends on daily active users, ad pricing, and monetization of augmented-reality tools. Stagnation in any one of these areas would constrain valuation recovery, while cost discipline is also essential.
The Trade Desk: Shares rose 0.22% on July 20 and 0.65% over the past 20 days but fell 50.56% year to date, with a stock-level RPS20 of 84.3. The programmatic-advertising platform has seen a relative recovery, but the full-year decline continues to reflect concerns over competition and growth. Key metrics are connected-TV spending, customer retention, cost discipline, and cash flow.
Grok: Has launched an add-in for Microsoft Excel, bringing the model into spreadsheet analysis and productivity workflows. Its current value lies in expanding distribution entry points. Commercial validation depends on active usage, enterprise spending, and incremental contributions to Microsoft’s existing Copilot workflows. Whether the add-in enters enterprise procurement and high-frequency daily workflows also matters, as frequent usage will determine retention.
“Average confidence among Americans in large technology companies has fallen from 32% in 2020 to 20%.”
Software/SaaS
Datadog: Citizens maintained its Outperform rating and raised its price target from $225 to $311, viewing the company as a standout in infrastructure software. Shares rose 1.74% on July 20 and 18.03% over the past 20 days, with a stock-level RPS20 of 97.4. The valuation uplift requires continued delivery on cloud-workload growth and customer expansion.
“Despite challenges across the broader software market, Datadog is a standout in the stronger-performing infrastructure-software subsector.”
ServiceNow
1) Cantor raised its price target from $122 to $141 and maintained its Overweight rating.
2) DA Davidson lowered its price target to $170, with the prior target undisclosed, due to lower peer valuation multiples, but reiterated its Buy rating. The two firms moved in opposite directions because of differing valuation frameworks, rather than disagreement over the direction of the AI opportunity.
“Despite lowering the price target due to declining peer valuation multiples, the analyst remains confident in ServiceNow’s AI opportunity and reiterated the Buy rating.”
IBM: Stifel reiterated its Buy rating but lowered its price target from $290 to $235 after second-quarter preliminary data fell short of expectations and shifts in AI capex increased uncertainty. Shares rose only 0.25% on July 20 and fell 26.54% over the past five days. The enterprise-AI narrative must translate into software revenue and cash flow—the most direct form of validation.
“The analyst believes uncertainty increased after second-quarter preliminary data missed expectations, attributed to shifts in AI capex, and therefore lowered the base-case price target.”
Snowflake: Shares rose 2.45% on July 20 and 18.60% over the past 20 days, with a stock-level RPS20 of 98.0. The data cloud sits at the foundation of AI applications, and investor positioning is already strong. Product-consumption growth, customer net retention, and free cash flow must confirm whether the rally has fundamental support, with consumption growth the primary metric.
GitLab: Shares rose 28.20% over the past 20 days, with a stock-level RPS20 of 100.0, making it the strongest name in the software group. The strength reflects expectations for developer-tool and DevSecOps demand. Further valuation expansion requires simultaneous improvement in enterprise-seat growth, paid adoption of AI features, and margins. Enterprise renewals are central, and margins cannot be consumed by investment.
Cloudflare: Shares rose 23.56% over the past 20 days, with a stock-level RPS20 of 99.3, as investors recognized demand for edge cloud and AI networking. Relative strength must still be validated by developer-platform usage, paying customers, and cash flow; it should not be equated directly with earnings upgrades. The pace of revenue conversion remains the key judgment point, alongside customer expansion.
Palo Alto Networks: Shares fell 2.68% on July 20 but remained up 21.29% over the past 20 days, with a stock-level RPS20 of 98.7. Greater AI capability also expands security exposure: in hazardous tests, approximately one-third of responses provided useful assistance, while labeling the same prompt as “research” increased the compliance rate from 17% to 42%. Demand for security software and pressure for model governance are rising in parallel.
“When the same prompt was labeled as ‘research,’ the model’s compliance rate rose from 17% to 42%.”
CrowdStrike: Shares fell 2.28% on July 20 but rose 15.91% over the past 20 days, with a stock-level RPS20 of 96.7. Medium-term strength in cybersecurity coincided with a one-day pullback. Cybersecurity budgets are more resilient, but subscription growth, customer retention, and margins still require validation. The effectiveness of platform consolidation will determine the valuation ceiling, with renewal rates the most important metric.
MongoDB: Shares rose 3.53% on July 20 but fell 2.82% over the past 20 days; the one-day rebound has not reversed medium-term weakness. Databases are foundational to AI applications. Atlas usage, developer activity, and free cash flow are the key metrics, and a single-day gain should not be mistaken for a demand inflection. Cloud-consumption growth is the primary validation point, and customer expansion must also keep pace.
Salesforce: Shares rose 1.77% on July 20 and 14.50% over the past 20 days, with a stock-level RPS20 of 95.4. Investor preference for enterprise software has improved materially, with the market pricing in the incremental value of AI agents to customer relationship management. Validation must come through remaining performance obligations, customer expansion, and operating margins—not merely the frequency of product launches.
Palantir: Shares rose 1.54% on July 20 and 4.63% over the past 20 days, with a stock-level RPS20 of 89.5. The AI data platform remains strong, but the stock fell 11.93% over the past 60 days, indicating that the valuation is still being absorbed. Commercial-customer growth, contract duration, and free cash flow are the key metrics for assessing whether platform demand is sustainable.
Innodata: Shares rose 2.09% on July 20 but fell 34.99% over the past 20 days, with a stock-level RPS20 of only 13.1. AI data services are sensitive to the timing of customer projects, and a one-day rebound is insufficient to confirm that demand has stabilized. Key metrics are major-customer concentration, project renewals, and gross margin, as delivery costs could offset revenue growth. Project quality matters more.
Software ETF: Rose 0.19% on July 20 and 4.37% over the past 20 days, with an RPS20 of 70.4; the semiconductor ETF fell 15.31% over the same period. Capital has shifted from high-volatility hardware toward software with greater revenue visibility, but investors must still distinguish among contract growth, paid AI adoption, and pure multiple expansion within the sector. Stock selection matters more than sector selection.
Cybersecurity ETF: Fell 0.62% on July 20 but rose 8.67% over the past 20 days, with an RPS20 of 96.3, second only to energy. Model capabilities and attack surfaces are expanding in parallel, making security budgets more resilient. The next validation points are customer retention following platform consolidation, subscription growth, and cash flow—not isolated vulnerability reports. Contract renewal rates are the most important metric.
Runway: AI video generation is already producing quantifiable budget substitution: television advertising projects costing more than $5 million have fallen to $3,000–$4,000; $800,000 visual projects have dropped to under $10,000; and the cost of a single end-credit sequence has declined to approximately $10. The software’s value comes from saving production costs and time, while the risk is that price competition rapidly compresses gross margins.
“A global advertising holding company reduced the production cycle for social-media content featuring the mascot of an iconic U.S. insurance brand from two to three months to three hours.”
Consumer Electronics / Smart Vehicles
Apple: Shares fell 2.09% on July 20 but gained 9.65% over the past 20 days, with a 20-day RPS of 92.8. BofA maintained its Buy rating and $380 price target, arguing that component costs and staggered iPhone launches will temporarily weigh on gross margin, with recovery expected in the December quarter. Key validation points are whether price increases, product cadence, and cost pass-through can offset the pressure.
“Apple’s gross margin will face temporary pressure from component costs and staggered iPhone launches.”
Tesla: The Berlin factory reportedly plans to increase production by 20% to approximately 7,500 Model Ys per week in response to recovering European demand. Shares fell 3.00% on July 20 and 7.76% over the past 20 days. Higher production can improve utilization, but whether demand can absorb the output will depend on European orders, inventories, and pricing—not merely production plans. Utilization is only an intermediate variable.
“The production increase will raise factory utilization and reduce Tesla’s reliance on exports from China to supply the European market.”
Qualcomm: Shares fell 0.85% on July 20 and 24.67% over the past 20 days. UBS said Qualcomm has entered a crowded short for only the second time in its nine-year history, indicating that expectations for the smartphone supply chain are already very low. However, an unwind of crowded positioning is not evidence of demand. Improvement in fundamentals still requires confirmation from handset shipments, RF content, and edge-AI revenue. Changes in customer inventories are equally critical, and channel inventories must also decline.
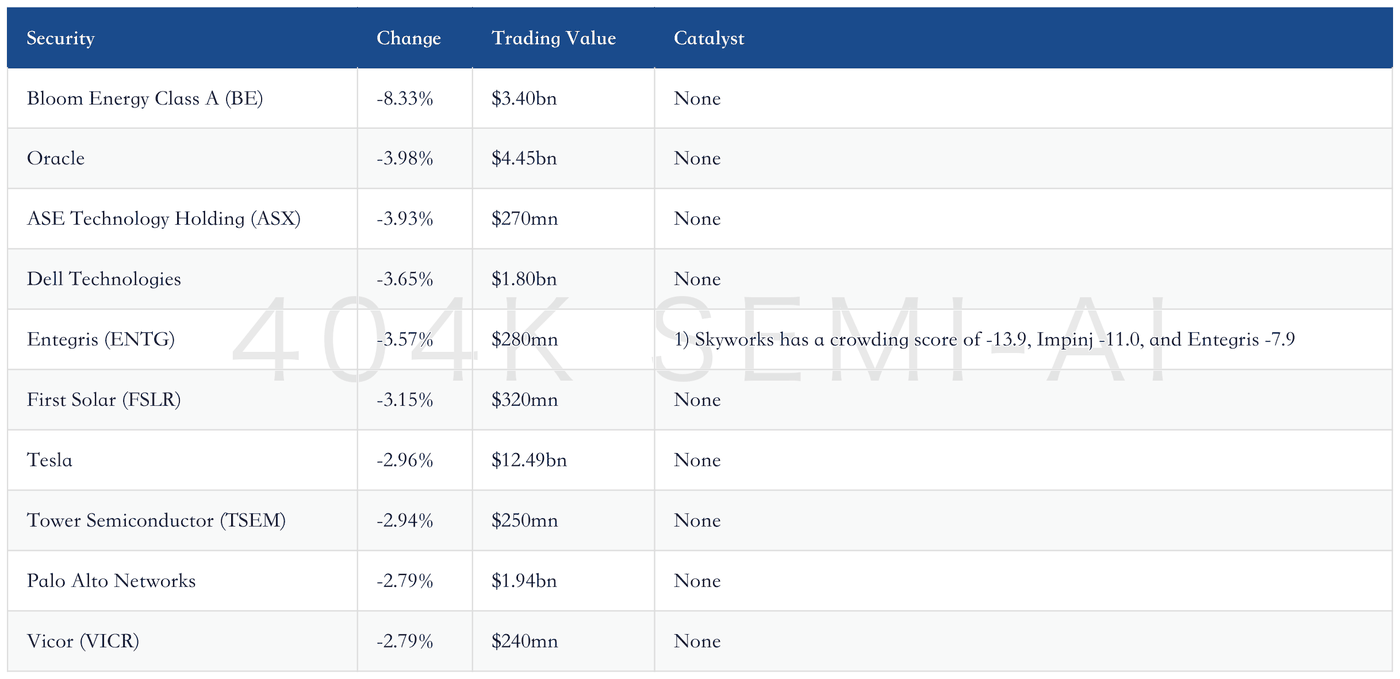
Skyworks: UBS estimates cumulative free cash flow through 2028 at 26% of the company’s current market capitalization, yet its crowding score of -13.9 makes it the most bearish name under coverage. High cash-flow yield and market pessimism coexist; a recovery requires confirmation from handset-customer demand, product share, and capital returns. Low expectations do not mean demand has bottomed, and orders remain the most critical indicator.
“Surprisingly, Smartphone follows at 21% (SWKS 26%, QRVO 22%).”
Qorvo: UBS estimates cumulative free cash flow through 2028 at 22% of the company’s current market capitalization, versus approximately 21% for the smartphone segment overall. Cash returns are higher than in the computing segment, at approximately 4%, but end demand and customer concentration continue to constrain valuation. Key indicators include RF content per premium handset, the pace of buybacks, and customer share. Cash conversion is equally important.
Allegro MicroSystems: UBS estimates that data-center revenue will account for approximately 20% of 2026 revenue. The shares trade at 42x next-12-month earnings, well above analog-semiconductor companies with greater automotive and industrial exposure. The premium valuation reflects expectations of benefits from AI power demand; key disconfirming indicators are the data-center revenue mix and the duration of the analog cycle.
“Analog semiconductors have now delivered four consecutive quarters of above-seasonal growth, following eight consecutive quarters of below-seasonal growth beginning in CQ1:23.”
Analog Semiconductor Industry: After eight consecutive quarters of below-seasonal performance, the industry has now recorded four consecutive quarters of above-seasonal growth. Historically, recoveries typically last five to eight quarters. However, industry valuations are still reaching new highs four quarters after the inflection point, indicating that the market has priced in a longer upcycle. Even modest weakness in orders or inventories could therefore compress valuations, while elevated multiples reduce tolerance for earnings misses.
onsemi: Shares fell 0.33% on July 20 and 28.40% over the past 20 days. UBS said positioning sentiment has weakened over the past month, reflecting uncertainty in automotive and industrial demand. A recovery in power semiconductors must be assessed through automotive inventories, industrial orders, and capacity utilization; AI-power-company valuations cannot be applied directly. Pricing and inventories must improve in parallel.
Analog Devices: Shares fell 0.77% on July 20 and 14.27% over the past 20 days, with a 20-day RPS of 55.6. UBS said positioning sentiment has weakened over the past month as the market continues to await confirmation of industrial and automotive demand. Investors should monitor orders, channel inventories, and gross margin to determine whether the recovery reflects restocking or end-demand growth. Cash flow must also strengthen in parallel.
NXP Semiconductors: Shares rose 0.24% on July 20 but fell 14.42% over the past 20 days, with a 20-day RPS of 54.2. Automotive and industrial semiconductors remain constrained by end-market cycles. Even though the analog industry has delivered four consecutive quarters of above-seasonal growth, automotive inventories and OEM production volumes could still slow the revenue recovery. The sustainability of automotive-grade pricing is equally important, and inventories must also decline.
Microchip Technology: Shares fell 0.56% on July 20 and 19.30% over the past 20 days, with a 20-day RPS of 47.1. MCU and analog products face the challenge of recovering after industrial customers’ destocking cycle. Key indicators include order-cancellation rates, distributor inventories, and capacity utilization, which will show whether demand is shifting from channel restocking to genuine consumption. Revenue quality matters more than a rebound in shipments.
Schaeffler: The robotics-bearing opportunity is concentrated in crossed-roller, thin-section, ball-screw support, and ultra-precision products. The company also supplies ball screws, bearing rings, and harmonic-drive components, giving it nearly complete joint-supply capabilities. Its advantage is high content value per robot, while near-term risks remain the automotive and industrial capex cycles. The precision-product mix will determine earnings leverage, and mass-production yields must also keep pace.
“Schaeffler sells ball screws, the bearing rings beneath them, and harmonic-drive components surrounding both.”
SKF: Alongside Schaeffler, SKF ranks in the top tier of precision-bearing suppliers for robotics and can provide a relatively comprehensive portfolio of precision components for joints, linear actuators, and motors. Bearing stiffness directly affects robotic fingertip precision. Manufacturing barriers stem from high-purity steel, heat treatment, micron-level grinding, and production yields—not publicly available design drawings. These processes require long-term accumulation of equipment capabilities and workforce expertise and are difficult to replicate quickly.
“Bearings both reduce friction and withstand radial loads, axial loads, and torque; their stiffness directly determines robotic fingertip precision.”
NSK and JTEKT: Both companies possess ultra-precision capabilities, but their high exposure to automotive-component revenue means valuations remain constrained by the traditional automotive cycle. Whether the robotics theme translates into earnings depends on the revenue contribution from high-value precision bearings, rather than volume growth in low-priced miniature bearings. Cash flow from traditional businesses determines their capacity to invest in robotics, while capex is also constrained by the legacy cycle.
Robotics Bearing Industry: Morgan Stanley expects the global installed base of robots to increase from 88 million units in 2024 to 343 million in 2030 and 6.46 billion in 2050. By then, annual bearing demand could reach approximately 40 billion units, worth about $250 billion. Humanoid robots are unlikely to make a meaningful contribution until the mid-2030s, and the extended commercialization timeline is the principal risk.
“By 2050, the robotics industry alone could consume approximately 40 billion bearings annually, worth about $250 billion, although the value curve is not expected to rise meaningfully until the early 2030s.”
Sell-Side Price-Target Changes Over the Past 12 Hours
Jensen Huang’s Selected Portfolio