
404K SEMI-AI Morning Brief 2026-07-15 — Semiconductors Lead, AI Costs Spill Over, Software Divergence Intensifies
目录
Post-Market Summary
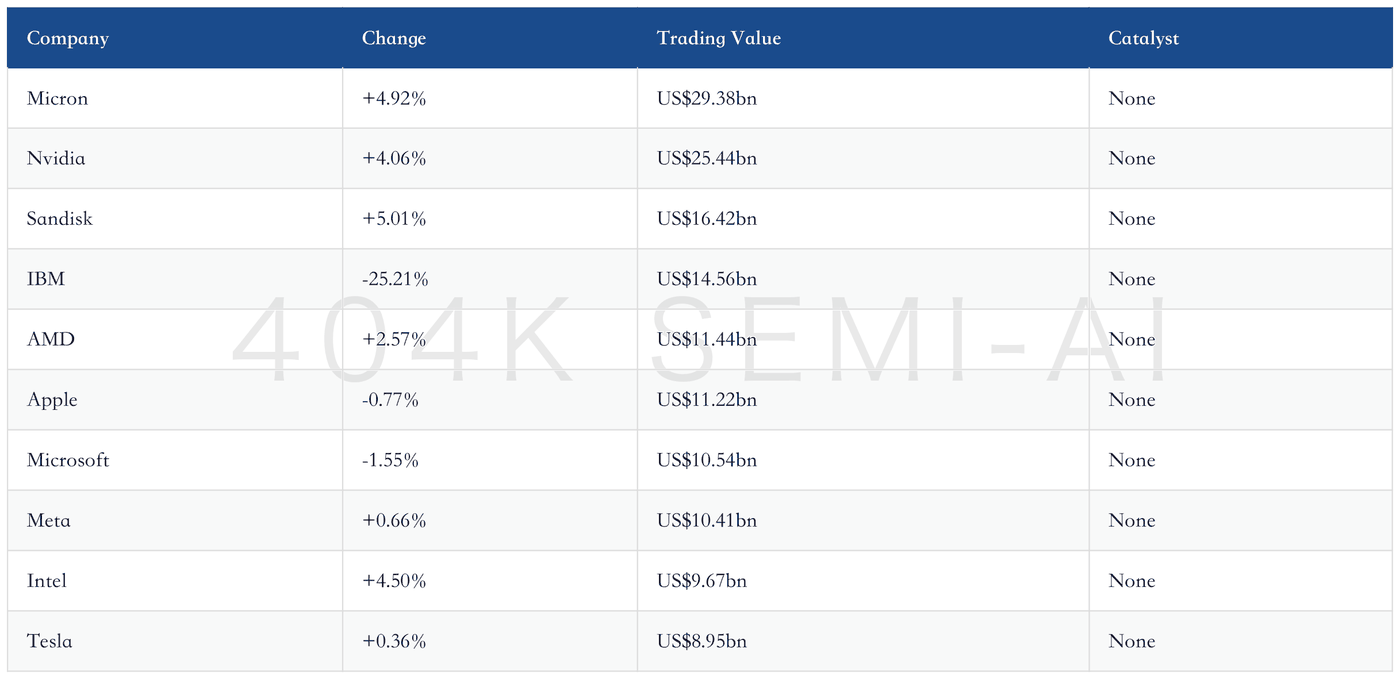
Top 10 US Stocks by Trading Value
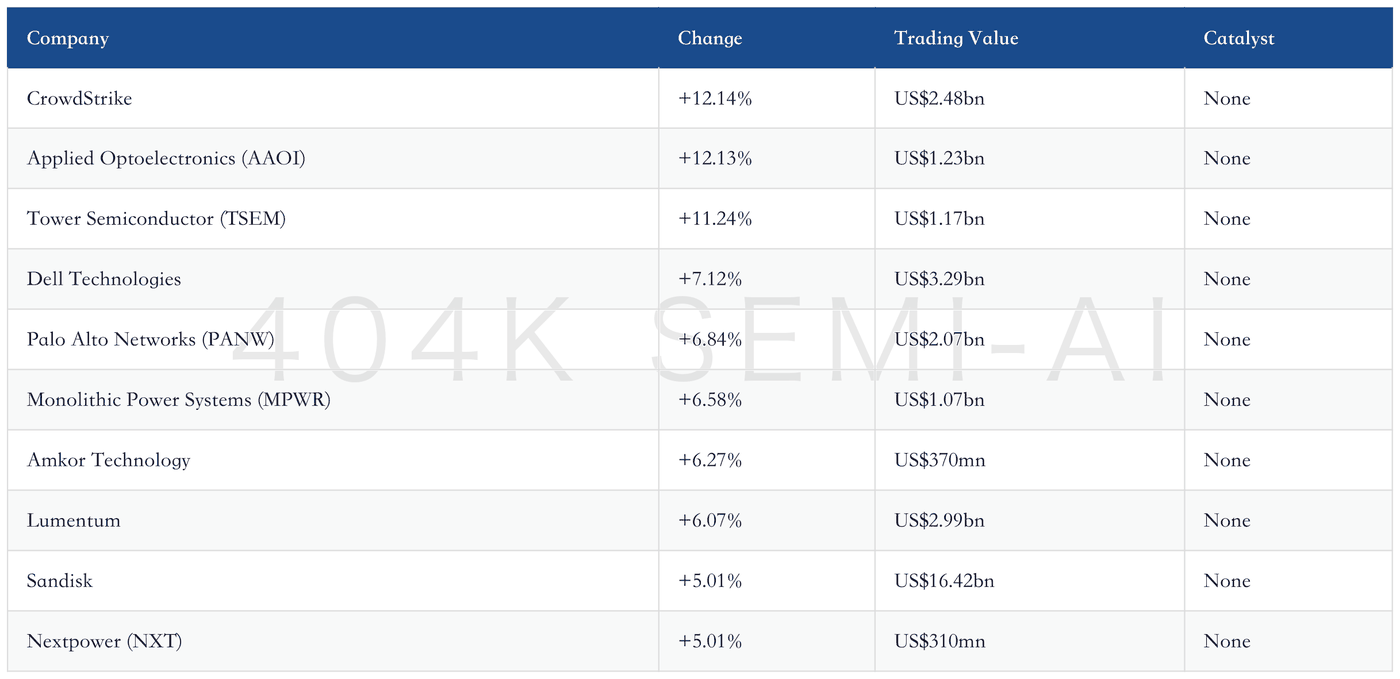
Top US Stock Gainers
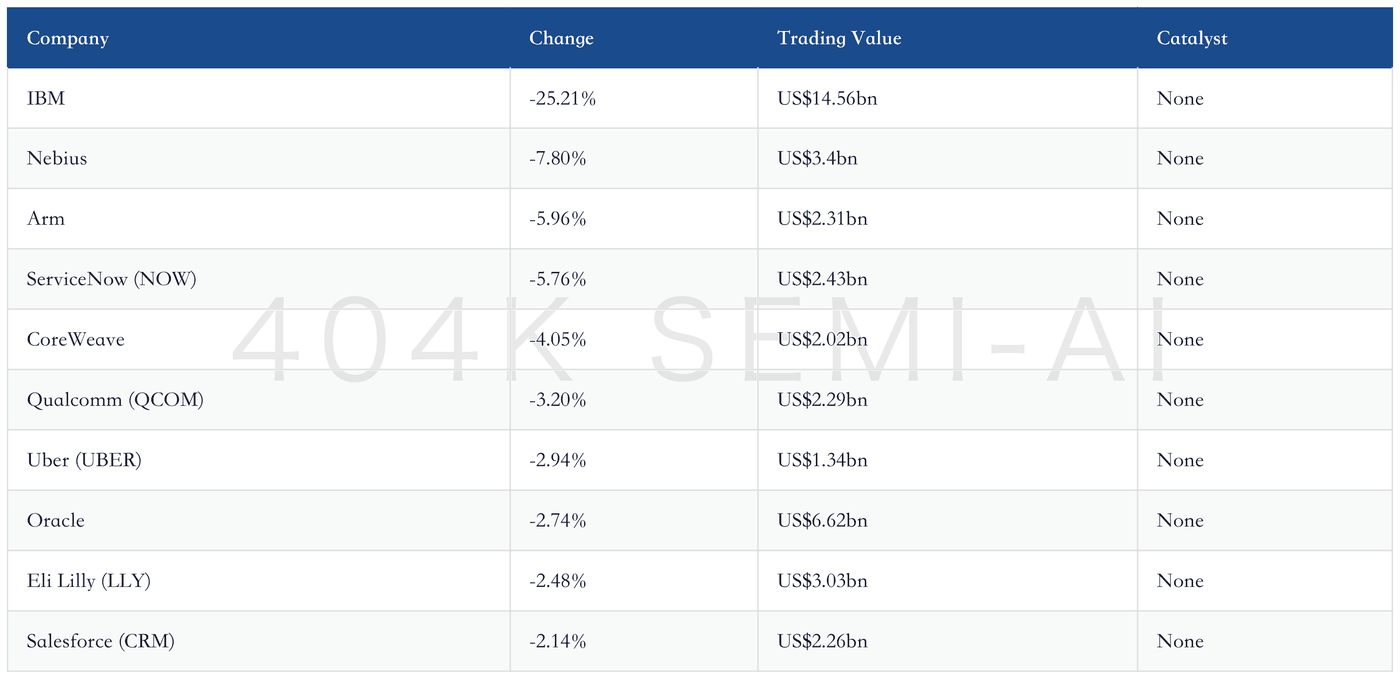
Top US Stock Decliners
Full AI/Semiconductor Supply Chain
AI Models, Applications, and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundries, Equipment, and Testing
Optical Communications, Networking, and Power
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
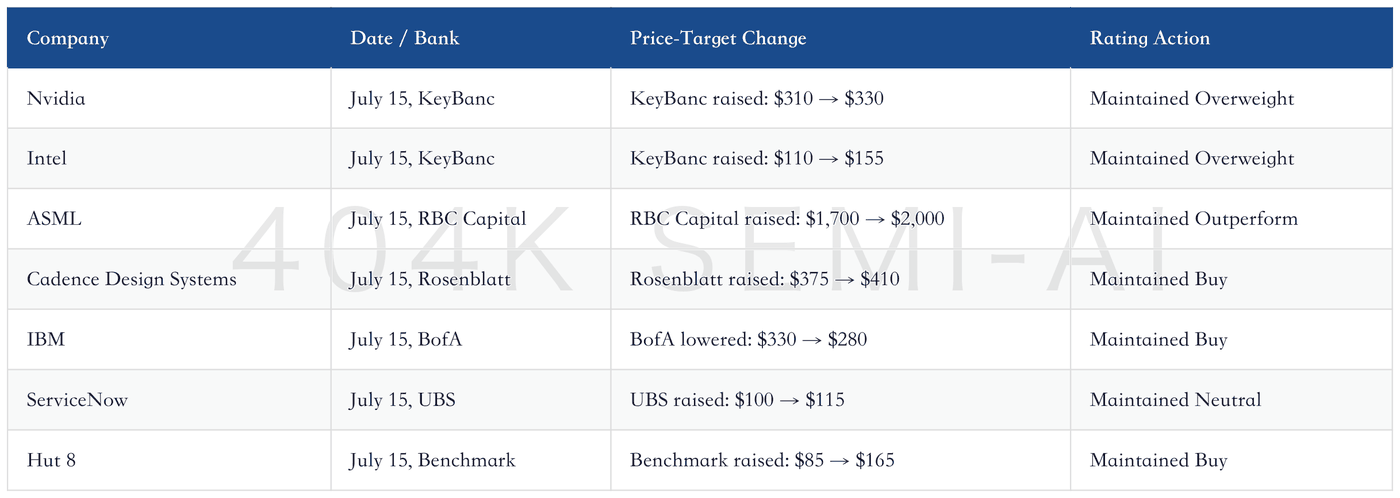
Investment-Bank Price-Target Changes Over the Past 12 Hours
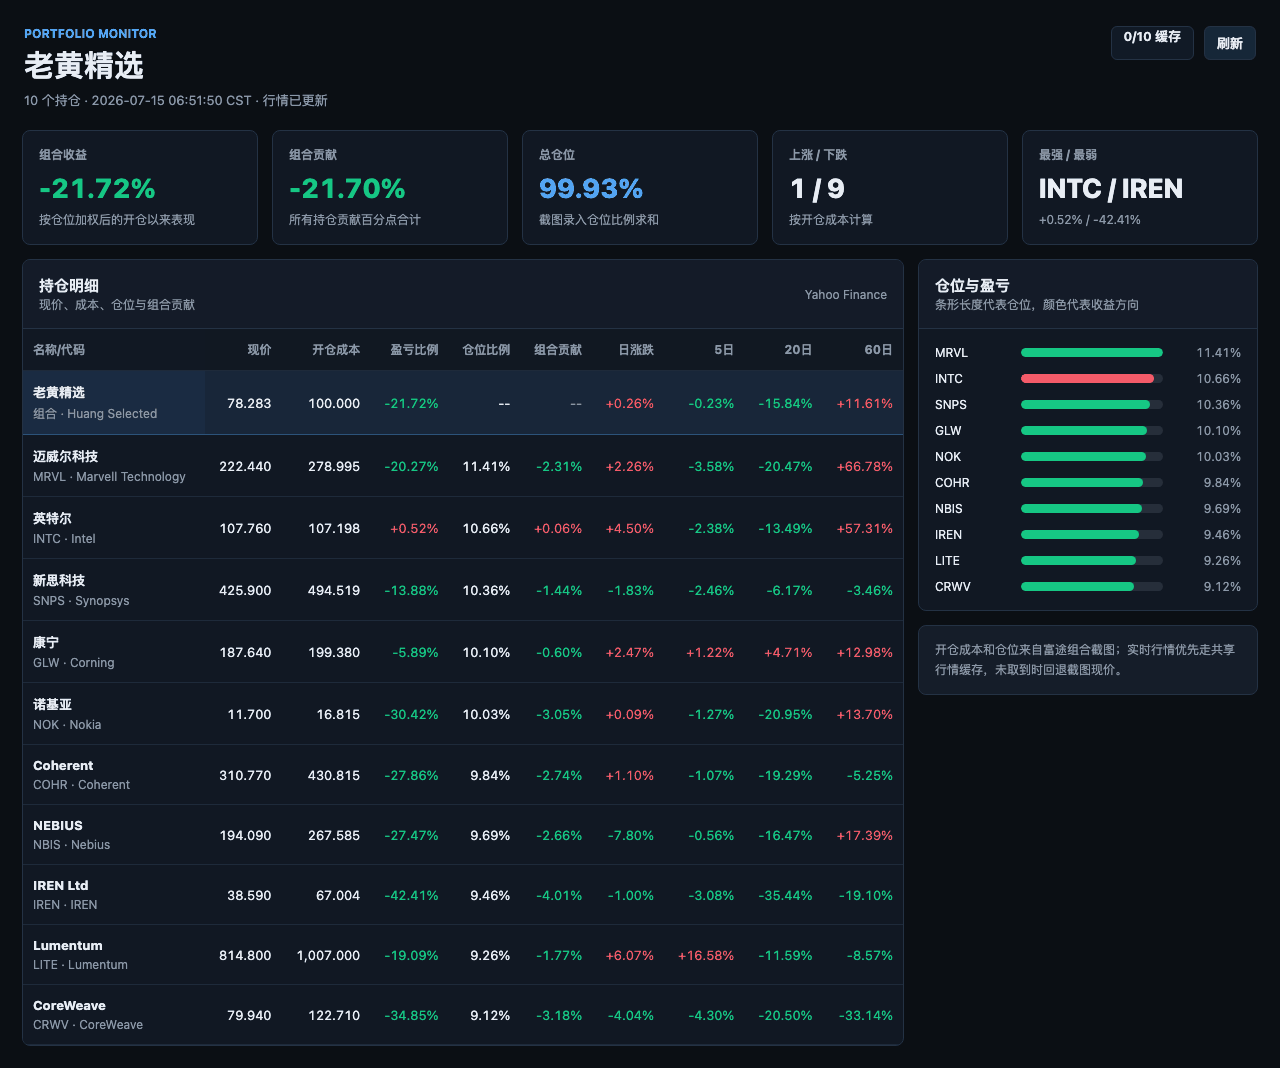
Huang’s Selected Portfolio
The Nasdaq and semiconductors rebounded, but the equal-weight index weakened, with capital still concentrated in memory, semiconductor equipment, optical communications, and cybersecurity. AI demand remains robust, but bottlenecks are spreading from GPUs to memory, power, liquid cooling, and delivery capacity. IBM’s earnings miss also serves as a reminder that the reallocation of enterprise budgets will drive pronounced divergence across software companies.
404K SEMI-AI | 2026-07-15
Post-Market Summary
US equities closed modestly higher in another technology-led session: the S&P; 500 rose 0.39%, the Nasdaq 100 gained 1.13%, and the S&P; 500 Equal Weight Index fell 0.26%. Technology advanced 1.19% and the semiconductor ETF gained 2.48%, indicating that the market’s incremental upside came primarily from heavyweight technology and the semiconductor supply chain rather than a broad-based rally.
Semiconductors and cybersecurity were the strongest segments. The equal-weight semiconductor benchmark rose 2.60% and the cybersecurity ETF gained 3.63%, while the software ETF advanced only 0.81% and the cloud-computing ETF fell 0.49%. Nvidia rose 4.08% and Micron gained 4.79%, while IBM plunged 25.21%, further amplifying the hardware-software divergence.
Industry signals were clearer than the indices: AI compute orders continue to grow, but per-gigawatt cluster costs, HBM prices, off-rack power infrastructure, and cooling costs are rising in tandem. Enterprise buyers are beginning to prioritize servers, storage, and memory. The next questions are whether orders convert into revenue, whether capacity expansion is delivered on schedule, and whether software budgets remain under pressure.
Top 10 US Stocks by Trading Value
Top US Stock Gainers
Top US Stock Decliners
Full AI/Semiconductor Supply Chain
AI Models, Applications, and Capital Expenditure
OpenAI
Inference demand grew rapidly following the launch of GPT-5.6 Sol. Codex and ChatGPT Work now have a combined 8 million active users, while usage of agent products increased 2.5x over the past week, prompting the platform to reset usage limits again. The immediate issues to validate following this usage surge are the pace of capacity expansion and service stability under heavy loads.
“We will reset everyone’s usage limits again and continue without a five-hour rate limit, allowing everyone to explore the boundaries of GPT-5.6 Sol and see just how ambitious their goals can be.”
Anthropic
1) The company launched Claude for Teachers, offering advanced features free of charge to certified US K–12 teachers and linking its teaching-skills library to academic standards across all 50 states.
2) Its annualized recurring revenue was reported at more than US$44 billion, while inference gross margin rose from 38% to over 70%. Whether growth can cover sustained training and inference investment will still depend on actual cash costs.
Moonshot AI
Kimi Open Platform displayed a “K3 launch” promotion effective July 15, prompting the market to await an official release. Its predecessor, K2.6, supports a 256K context window, up to 300 sub-agents, a 96.6% tool-call success rate, and continuous coding tasks lasting 12–13 hours. K3’s reported 2.5 trillion parameters and 1 million-token context window remain subject to official confirmation.
CSP/Cloud Capital Expenditure
Amazon
The company disclosed its elastic network graph topology and introduced the Spraypoint routing protocol, which splits packets across multiple paths to reduce congestion. Fewer network layers and random-graph deployment could improve large-cluster efficiency, but software-stack migration complexity, failure domains, and actual unit costs still require validation in production environments.
Microsoft
Cloud-market contracts are shifting in favor of vendors: three-year renewals are being shortened to one year, while long-term capacity reservations require larger minimum clusters and annual spending commitments. Microsoft benefits from cloud-capacity pricing and utilization, but also faces internal customer-budget reallocations away from general software and toward GPUs, servers, and security products.
“Customers attempting to renew three-year agreements are being told they can renew for only one year, implying smaller discounts and higher prices.”
AI Cloud/Data Center Operators
Nebius
1) The company signed a GB300 compute agreement with Reflection AI worth more than US$1 billion and extending through 2029. Third-party customers should help reduce its concentration in Microsoft and Meta.
2) First-quarter revenue reached US$399 million, up 684% year over year, while AI cloud annualized recurring revenue totaled US$1.92 billion, with a year-end 2026 target of US$7–9 billion. The real constraints are data-center construction and delivery speed.
“Nebius signs GB300 compute agreement with Reflection worth more than US$1 billion and running through 2029.”
IREN
Horizon 1 is only five days from delivery, but the company also faces controversy over repeated financing, management incentives, and governance. The shares have fallen 35.02% over 20 days, indicating that the market is no longer focused solely on power and data-center capacity; it now requires new capital to be matched with clearly defined contracts, commissioning milestones, and per-share value creation.
Hut 8
Benchmark maintained its Buy rating and raised its price target from US$85 to US$165, citing a new contract worth US$16.8 billion and operating momentum. Given the scale of the target increase, subsequent validation should focus on the contractual counterparty, delivery milestones, capital expenditure, and revenue recognition, rather than treating total contract value as current-period earnings.
GPU/CPU/ASIC
Nvidia
1) Small volumes of H200 shipments have begun to mainland China and Hong Kong, but US officials described the quantities as “very limited,” with licensing, inspections, and customs processing still handled case by case.
2) KeyBanc maintained its Overweight rating and raised its price target from US$310 to US$330. Its 2027 CoWoS supply forecast increased to 1.1 million units, representing 69% growth. Vera Rubin’s volume ramp has been slightly delayed, but training demand and packaging supply continue to support earnings.
“There is currently no indication that its dominance in training is weakening. Training workloads will continue to grow, albeit more slowly than inference workloads.”
Intel
1) KeyBanc said 18A yields improved from 65% to over 85% and raised its price target from US$110 to US$155. Stifel lifted its target to US$120 but maintained a Hold rating, with the divergence reflecting uncertainty over volume-production execution and long-term valuation.
2) EMIB-T has secured positions in the AWS Trainium 3 and Google TPU programs, but material revenue opportunities are not expected to begin scaling until 2029–2030.
“18A yields continue to improve significantly, rising from 65% last quarter to more than 85%.”
AMD
Helios launch partners have secured publicly disclosed customer adoption, with double-wide racks, liquid cooling, and PCIe Gen 6 storage positioned as system-level selling points. KeyBanc raised its general-purpose server shipment-growth forecast from 18.5% to 30%, while AMD also secured additional N4 wafers following reductions in smartphone orders. Its target of more than 50% server CPU shipment growth in 2027 remains constrained by capacity and customer deployment.
Broadcom
Morgan Stanley believes MediaTek’s involvement in TPU supply is real, but Broadcom’s long-term share should remain near 80%, making the bear-case assumption of a decline to 50% premature. The company’s AI semiconductor revenue reached US$10.8 billion, with networking accounting for approximately 40%. Its ability to defend its custom-ASIC share will depend on Google’s internal development pace, MediaTek’s production ramp, and Broadcom’s delivery capabilities.
HBM/DRAM/NAND/SSD/HDD
Micron
All 2026 HBM output has been booked under multiyear premium-priced contracts, while new fabs will not contribute meaningful production until the second half of 2027 or later. The company plans to increase DRAM and NAND bit shipments by more than 20% in 2026. Whether pricing holds will depend on both demand destruction in end markets and the ramp-up of new capacity.
“All 2026 HBM output has been booked, providing exceptionally high visibility and reducing cyclical risk.”
SK Hynix
Barclays expects DRAM bit demand to grow 35% in 2027 against only 20% supply growth, potentially extending the shortage into 2028. It initiated coverage of the ADR with an Overweight rating and a US$330 price target. The company’s operating margin was reported at 72%, but the ADR has traded at a 51% premium to the South Korean-listed shares, making cross-market mispricing and high volatility difficult to ignore.
Sandisk
Morgan Stanley said first-quarter cloud revenue grew 233% sequentially, while more than one-third of FY27 bit output has been secured under three- to five-year contracts. Disclosed penalties for customer cancellations total approximately US$11 billion. HBF samples are planned for the first half of 2027. Long-term contracts provide downside protection, but the 86.7% FY27 non-GAAP gross-margin assumption requires both elevated NAND pricing and supply discipline.
Samsung Electronics
Semiconductors contributed more than 93% of group profit, with the Device Solutions division generating KRW53.7 trillion in operating profit. HBM, server DRAM, and advanced NAND were the primary drivers. The company denied plans to issue American depositary receipts. The memory upcycle still needs to be assessed through HBM qualification, server contract pricing, and capacity utilization rather than speculation over trading structures.
JEDEC
The SPHBM4 standard uses an interface base die to mount DRAM stacks on an organic substrate, adopting 4:1 serialization to reduce data-signal pairs from 2,048 to 512 while widening bump pitch. This could reduce dependence on silicon interposers and allow more stacks around processors, but there remains a considerable gap between publication of the standard and maturity across controllers, substrates, and the mass-production ecosystem.
“The standard uses a new interface base die that allows DRAM stacks to be mounted on standard organic substrates rather than expensive silicon interposers.”
Foundries, Equipment, and Testing
TSMC
High-performance computing accounted for 61% of revenue, with 3nm, 5nm, and 7nm leading wafer revenue, while operating margin reached 58.1%. AI workloads continue to migrate toward advanced nodes and packaging, but sustaining high margins will depend on advanced-node utilization, CoWoS capacity expansion, customers’ custom-chip development cycles, and capital-expenditure depreciation.
ASML
Pre-earnings-call models project second-quarter revenue of €8.9 billion, close to the €9.0 billion consensus. Support comes from Micron’s multiyear EUV agreement and higher capital expenditure at SK Hynix and Intel. RBC Capital raised its price target from US$1,700 to US$2,000. Risks include China revenue falling below 20%, weakening DUV demand, and reduced order visibility.
Tower Semiconductor
Japan’s Ministry of Economy, Trade and Industry plans to provide up to ¥159 billion in subsidies for mass production of optical-communications semiconductors, while the company plans to invest approximately ¥600 billion to expand its Niigata and Toyama plants. The project covers 300mm silicon photonics, silicon-germanium, and advanced packaging, targeting full mass-production readiness by the fourth quarter of 2027. Subsidies do not equate to customer orders; equipment installation and yields remain key validation points.
Powerchip Semiconductor Manufacturing
DRAM foundry prices were raised another 45% in July, logic-process bookings reached 1.4x available capacity, and second-quarter gross margin was 28%. Supply and demand for mature nodes have improved, but the forecast for industry gross margins exceeding 40% in 2027 remains long-dated. If customer inventories rise or capacity expands too quickly, the sustainability of price increases will be tested first.
Aehr Test Systems
Quarterly revenue was US$18.8 million, with earnings per share of US$0.11, orders of US$61 million, and a backlog of approximately US$101 million. FY2027 revenue guidance was US$130–150 million, alongside more than US$8 million in new silicon-carbide test orders. Test demand spans AI processors, silicon photonics, and power devices; the key variables are customer qualification, delivery, and collections.
Optical Communications, Networking, and Power
Applied Optoelectronics
Construction began on a nearly 400,000-square-foot expansion project in Texas. Monthly production targets for 800G and 1.6T optical transceivers exceed 650,000 units by year-end and 930,000 by the end of 2027. First-quarter revenue reached US$151.1 million, up 51% year over year, and the company has more than US$200 million in 1.6T component orders. The expansion case is compelling, but construction, ramp-up, and CPO substitution risks all require monitoring.
Arista Networks and Cisco
1) Bank of America data show that first-quarter data-center switch revenue grew 50% year over year, with AI back-end switching up 121%. Arista led with a 21.1% share of the overall data-center market and a 32.0% share of front-end switching among Tier 2 cloud providers.
2) Cisco’s AI back-end share rose from zero to 7.9%, while its hyperscale cloud back-end share reached 13.2%, benefiting from its entry into Meta’s 800G leaf-switch layer. Whether these share gains persist will depend on customer expansion and product gross margins.
Eaton
Morgan Stanley estimates that next-generation off-rack power infrastructure, liquid cooling, transformers, and substations will cost US$16–19 million per megawatt, representing 41%–49% of the total cost of a GB300 cluster. Power-related content has increased materially, but project revenue remains constrained by substation construction, grid-connection approvals, and customers’ data-center delivery schedules.
“Next-generation off-rack infrastructure costs US$16–19 million per megawatt, accounting for 41%–49% of the total cost of a GB300 cluster.”
Internet/Platforms
Meta
1) Q1 advertising revenue grew 33%, impressions rose 19%, and price per ad increased 12%; AI returns still depend on improved advertising efficiency.
2) In June, average cost per 1,000 impressions accelerated from 12% to 26%, with ad spending 120 basis points above expectations.
3) The company was sued over allegations that its layoff system failed to account for approved medical leave, making algorithmic governance a direct legal risk.
“The lawsuit alleges that Meta used AI-powered software to target employees with medical conditions for layoffs.”
Google
1) Its US search share returned to growth for the first time since April 2025, while Gemini’s share rose to 26.9%, second only to ChatGPT’s 57.2%.
2) Google Images is being redesigned into a Pinterest-like personalized discovery feed, with AI image generation integrated directly into Search.
3) The company signed a fixed-price virtual power purchase agreement securing 100% of the Steel River project’s initial generation, adding long-term power supply for its cloud and AI infrastructure.
“Google will also integrate AI image generation directly into Search, keeping users within its ecosystem rather than directing them to external tools.”
Reddit
Total users grew 2% month over month in June, but were roughly flat versus May after excluding anomalies in the May data. Piper’s survey still ranked Reddit among the standout performers in Q2 ad spending; the quality of growth depends on genuine engagement, ad load, and data-licensing revenue rather than fluctuations in a single month’s reporting.
Netflix
Piper’s advertising-buyer survey ranked Netflix among the standout internet platforms in Q2, while separate reports indicated that Lionsgate was exploring a sale. Incremental advertising revenue and acquisitions of content assets represent two distinct paths: the former depends on user monetization, while the latter increases capital commitments and integration risk. Transaction rumors alone are insufficient.
The Trade Desk
It delivered the weakest performance relative to expectations in the Q2 advertising survey. Shares fell 4.35% that day and 1.82% over 20 days. Open-internet advertising remains under pressure from retail media and platforms’ proprietary tools; key validation points are customer retention, share of CTV budgets, and the platform’s take rate on each dollar of ad spending.
“Overall, the advertising-buyer survey was strong, with Q2 ad spending up 7.7% year over year, approximately 80 basis points above expectations. Standout performers included Reddit, Netflix, and YouTube.”
Airbnb
Management faced criticism and quickly deleted AI-generated content about asset tokenization, highlighting the reputational risks of generative AI in highly sensitive financial topics. The incident does not directly affect the accommodation business, but it reminds platform companies that while content generation can improve efficiency, review responsibilities and executive communications discipline cannot be delegated to models.
Uber
Market reports indicated that the company was seeking to reach a potential acquisition agreement as early as that week, while its shares fell 2.94% that day. Whether an acquisition would improve its mobility or delivery network depends on the target, price, and synergies; revenue implications cannot currently be inferred from rumors. The platform must also manage autonomous-driving partnerships, driver supply, and regulatory costs.
Similarweb
The company launched a free AI Visibility tool that ranks brand visibility on ChatGPT across multiple categories, initially covering US news and media brands in June 2026. The free entry point offers customer-acquisition value, but monetization will depend on methodological transparency, update frequency, and the ability to convert users into paying analytics customers.
Pinterest
Google Images’ shift toward a personalized discovery feed means that Pinterest’s visual-discovery gateway faces more direct platform competition. Pinterest rose 1.39% that day and 11.88% over 20 days; the key metrics are changes in search referrals, shopping-ad conversion, and user time spent—not one-day relative performance.
“Google is redesigning Google Images into a Pinterest-like discovery feed featuring personalized galleries and saved collections.”
Starlink
More than 7,500 commercial aircraft have installed or contracted to install its products, spanning 46 airlines or operators. The next-generation V5 terminal offers speeds above 375 Mbps, averages 35–50 W of power consumption, and is 50% more energy-efficient than V4. In-flight connectivity is entering a phase of scaled deployment, with revenue realization dependent on installation progress and service fees per aircraft.
Southwest Airlines
The company has announced that it will adopt Starlink Wi-Fi, joining the industry-wide upgrade in airline connectivity. The announcement does not itself imply fleet-wide deployment; key follow-up indicators include the number of retrofits, launch timing, whether service will be free or paid, and whether satellite bandwidth can maintain service quality on high-density routes.
United Airlines
The company is likewise among the major US airlines that have announced the adoption of Starlink. Satellite internet can improve the passenger experience and loyalty-program engagement, but airlines must bear terminal retrofit, certification, and aircraft downtime costs. The investment implications are more relevant to Starlink’s installed-base expansion than to any immediate uplift in airline margins.
American Airlines
The company has announced that it will adopt Starlink Wi-Fi, indicating growing acceptance of low-Earth-orbit satellite connectivity among large network carriers. Contracting, installation, and commercial launch are three distinct stages; the contract’s scale cannot be assessed until fleet coverage, activation rates, and customer usage are disclosed.
Frontier Airlines
The company plans to equip its fleet with Starlink internet service beginning in 2027, providing a clearer timeline than a simple adoption announcement. Whether the low-cost carrier offers high-speed connectivity for free will affect ancillary revenue and customer experience; installation progress is also a measurable indicator for Starlink’s aviation business.
“Frontier Airlines plans to launch its first Starlink-equipped aircraft in early 2027 and will become the first US airline to provide passengers with Starlink high-speed internet access through a new system managed directly by Starlink.”
Delta Air Lines and JetBlue Airways
Neither company has announced the adoption of Starlink, but the absence of an announcement does not imply rejection. Their choices will test whether the in-flight connectivity market further consolidates around low-Earth-orbit satellite solutions and will also affect renewals and pricing for incumbent in-flight connectivity providers.
Software/SaaS
IBM
1) Preliminary Q2 revenue was $17.2 billion, up 1% year over year but below the $17.86 billion consensus; software grew 5%, infrastructure declined 7%, and adjusted EPS was $2.93.
2) Management said customers were redirecting capital expenditure toward servers, storage, and memory, delaying some large deals. Bank of America cut its price target from $330 to $280, while HSBC downgraded the stock to Reduce and lowered its target to $191.
“...we did not anticipate the magnitude of the shift in capex priorities. In addition, customers were disrupted this quarter by rapidly evolving industry-wide cybersecurity issues.”
ServiceNow
UBS maintained its Neutral rating and raised its price target from $100 to $115. Analysts view demand as stable but not improving, with only modest upside to guidance. Shares fell 5.76% that day; the key question is whether AI products can increase contract value and renewals, rather than merely generating greater demo interest.
Salesforce
Evercore ISI maintained its Outperform rating but cut its price target to $250, without disclosing the prior target. Agentforce and Data Cloud are growth drivers, while Tableau remains under pressure. Customer data readiness and return on investment remain bottlenecks to scaled deployment; the lower price target indicates that the market is beginning to demand tangible AI revenue.
“Analysts see a tug-of-war between growth drivers such as Agentforce and Data Cloud and headwinds such as Tableau, with data readiness and clarity on return on investment remaining the bottlenecks.”
Datadog
Its advantage in the agentic era comes from real-world user, enterprise, and operational databases rather than the general-purpose model itself. Shares rose 17.76% over 20 days, with a relative-strength score of 95.4. Whether the valuation can be sustained depends on converting observability data into AI operations revenue and whether cloud-cost optimization suppresses usage.
CrowdStrike
Falcon has expanded from endpoint security into identity threat protection, cloud workloads, and AI threat intelligence. Shares rose 12.14% that day on turnover of $2.48 billion. AI expands the attack surface across non-human identities and automated threats, strengthening the demand thesis. The risk is that high-growth expectations are already substantially reflected in the valuation, while platform consolidation must continue converting into net new contracts.
“More software is operating autonomously. More access permissions require governance. More sensitive data is flowing across cloud, SaaS, and AI systems.”
Palo Alto Networks
Cortex, Prisma SASE, Cortex Cloud, SIEM, and identity security span endpoint, network, cloud, and privileged-access protection. Shares rose 6.84% that day. Enterprises want to reduce the number of tools they use, favoring platform consolidation and large vendors; however, sustained margins depend on whether cross-selling can preserve pricing and renewal rates.
Cloudflare
Zero trust, edge security, DDoS protection, and application security all benefit from growing AI-application traffic. Shares rose 23.31% over 20 days, reached an all-time high, and posted a relative-strength score of 97.4. Growth must be validated through large-customer revenue, edge-inference usage, and gross margin, avoiding the assumption that traffic growth directly translates into profit growth.
Okta
Authentication, access control, and privileged access are becoming foundational security layers in multi-cloud and SaaS environments. AI agents increase the number of machine identities while amplifying permission-configuration errors. Okta’s opportunity lies in the neutrality of its independent identity platform; the risk is that suite vendors such as Microsoft compete through bundled pricing.
“AI adoption increases the value of authentication, access control, and privileged access in multi-cloud and SaaS-intensive environments.”
Tenable
AI infrastructure increases vulnerabilities, identity risks, cloud misconfigurations, and attack paths, driving demand for exposure management. The company must demonstrate that its products can convert more alerts into actionable priorities while maintaining large-customer renewals; otherwise, higher security budgets may flow first to integrated platforms.
Varonis
When enterprise file permissions are overly broad, AI assistants may expose sensitive information to unauthorized users, increasing the importance of data-access governance. The company benefits from the expansion of Copilot-style workflows, but deployments typically require scanning, permission remediation, and organizational coordination, meaning sales cycles and customer execution speed will constrain the revenue ramp.
Rubrik
The company has expanded its positioning from backup to cyber resilience, spanning immutable backups, data-security posture, and identity recovery. AI increases data volumes and the attack surface, making recovery capabilities more valuable. Revenue quality should be assessed through subscription growth, customer expansion, and actual adoption of recovery products—not merely the number of security incidents.
Commvault
Its product focus has shifted from traditional backup toward clean data and identity recovery after an intrusion, while reducing the risk of reinfection during recovery. The platform strategy aligns with customer demand to reduce tool counts, but clear advantages in pricing and recovery speed are essential when competing with Rubrik and cloud-native services.
SentinelOne
Autonomous endpoint protection and extended detection and response use AI-driven behavioral analysis to accelerate detection and remediation, appealing to customers seeking to reduce manual security operations center workloads. The opportunity comes from machine-speed attacks; the counterpoint is that similar capabilities have become industry standard. Key indicators are net retention among large customers and customer-acquisition cost per unit.
F5
Hybrid, distributed, and AI-driven applications increase demand for API protection, bot defense, web application firewalls, and traffic management. Positioned at the intersection of application delivery and security, the company benefits from rising complexity. The risk is that customers consolidate these functions into cloud platforms or edge networks, compressing budgets for standalone products.
Cadence Design Systems
Rosenblatt maintained its Buy rating and raised its price target from $375 to $410. AI-chip complexity and advanced packaging increase demand for EDA tools, but shares fell 0.30% that day and 2.12% over 20 days. Key indicators are design activity among major customers, AI-related orders, and regulatory constraints.
“I genuinely believe that the broad SaaS doomsday narrative has blinded investors to the enormous opportunities emerging across software.”
Consumer Electronics / Smart Vehicles
Apple
1) The company is evaluating PrismML, which claims it can compress the 27-billion-parameter Qwen model from approximately 54GB to under 4GB for operation on the iPhone 15 and newer models, reducing memory usage by 10–15x and increasing speed by 6–8x.
2) Morgan Stanley expects the iPhone 18 Pro to raise prices by $200 for equivalent configurations to preserve an approximately 40% gross margin; KeyBanc downgraded the stock to Underweight with a $250 price target.
“Compressing the 27-billion-parameter Bonsai model to 3.9GB or 5.9GB while retaining approximately 90%–95% of full-precision capability suggests that the shift of inference to edge devices could reshape AI application costs and drive demand for unified memory, bandwidth, NPUs, and low-power inference.”
PrismML
Its on-device compression technology fits large models into smartphone memory. The commercial value lies in reducing cloud inference costs while improving privacy and latency. Performance is partially degraded, and all claimed improvements in speed, power consumption, and memory usage are company-reported. Whether Apple will invest, partner, or adopt the technology remains uncertain.
Global Smartphones
China’s smartphone shipments were approximately 66 million units in the second quarter, down 4.3% year over year. Global full-year shipments are projected to fall 13.9% to 1.09 billion units, with models priced below $400 expected to decline by more than 20%. Rising memory prices are squeezing specifications and demand in lower-priced devices; memory vendors’ pricing power also represents a cost risk for device brands.
“The contraction in unit sales does not mean demand has disappeared; memory has become the constraining variable across the electronics supply chain.”
Sonos
Sonos fell 6.5% after hours following OpenAI’s announcement of plans for a home speaker, as the market initially priced in potential competition for the user interface. OpenAI’s device emphasizes a screenless, mobile, and context-aware design, while Sonos’ moat remains its audio quality, home-device ecosystem, and distribution. The actual impact will depend on pricing, launch timing, and user adoption.
Lucid
Shares fell as much as 48% to an all-time low, leaving the company with a market capitalization of approximately $1.17 billion, following reports of a potential take-private transaction or bankruptcy-protection filing. The company had not responded at the time. With quarterly cash burn of approximately $1 billion, financing, restructuring, and deliveries ahead of the Cosmos launch are existential variables; rumors should not be treated as a finalized course of action.
Tesla
Shares rose 0.36% on the day but declined 2.67% over 20 days, while autonomous driving and robotics still lack incremental hard data. The company’s in-house semiconductor development and physical-AI strategy remain frequent discussion topics, but investment validation should focus on autonomous-driving mileage, accident rates, robot mass production, and deployment of proprietary chips—not thematic momentum.
Ferrari
Management believes the controversy surrounding the Luce EV could generate free publicity, as the initial backlash against the Purosangue ultimately did. Brand visibility has indeed increased, but negative reactions may also reflect resistance to electrification among core customers. Orders, pricing, mass production, and deliveries will determine whether publicity converts into revenue.
“Ferrari’s chairman said he was ‘pleased’ with the backlash generated by the Luce EV.”
T-Mobile
The T-Life app can use the updated Siri to check or pay bills, showing that system-level assistants are beginning to enter carrier service workflows. One individual experience does not demonstrate adoption at scale. Permission transparency, payment confirmation, error handling, and user retention are critical for voice agents to progress from demonstrations to transaction interfaces.
Eero
Following a software update, Mesh nodes experienced weaker connections and packet loss, while other networks did not exhibit the same issue. Home networking is the underlying infrastructure for edge AI and smart homes, making stability more important than incremental features. Key follow-ups include whether Amazon provides a fix, the scope of affected devices, and authorization to access diagnostic data.
BlackBerry QNX
Nvidia Halo uses QNX as its certified safety layer. The general embedded market outside automotive accounts for approximately 20% of revenue, or around $53.6 million in FY2026. Its core serviceable addressable market is projected to expand from $1.7 billion to $2.9 billion, with the total addressable market reaching $5.9 billion by 2028. The opportunity is expanding from automotive into robotics, healthcare, and industrial applications, but order conversion remains to be validated.
“Demand for physical AI is expanding rapidly, yet 91% of robotics developers still use general-purpose operating systems, and 66% of projects are delayed by failures to obtain safety certification.”
FANUC
The company has successively partnered with Google and AWS, while the value of physical AI lies in hardware precision, control systems, and factory data. The strategic direction is clear, but there is no disclosure yet on order scale, deployment timing, or revenue contribution. Key areas to monitor are how robotic controls, vision models, and cloud-based training enter actual production lines.
Auto Insurance Technology
AI can help users exaggerate accidents and alter claims documents, while also helping insurers detect fraud. The net effect depends on data quality, model audits, and human review. These dual-use applications will increase demand for anti-fraud software while creating risks related to false positives, privacy, and regulatory liability.
OpenAI Home Device
The proposed device would use cameras and sensors to understand its surroundings, move between rooms on battery power, and control appliances, media, and messaging. Its functionality overlaps with smartphones, speakers, and smart-home hubs. It must demonstrate that the convenience of continuous sensing is sufficient to offset the privacy cost and additional hardware expenditure.
“OpenAI reportedly plans to unveil a home speaker this year as its first hardware product, with sales scheduled to begin in 2027.”
Edge-AI Platforms
The 27-billion-parameter Bonsai model can be compressed to 3.9GB or 5.9GB while retaining approximately 90%–95% of full-precision capability; the iPhone 17 Pro Max delivers approximately 11 tokens per second. If the performance proves stable, inference costs will shift to user devices and drive upgrades in memory and NPUs. The largest frontier models will remain dependent on data centers.
Starlink V5 Terminal
The new terminal delivers peak speeds above 375Mbps with average power consumption of 35–50W. Its antenna dish is 35% smaller than the V4, weighs 2.4 pounds, is 14% lighter, and retains a 110-degree field of view. The smaller size and lower power consumption support residential and mobile deployments, but actual competitiveness will depend on pricing, service plans, coverage, and peak-hour bandwidth.
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio
Related Reading
404K SEMI-AI Morning Brief 2026-07-02 — Meta Compute Monetization, Strong Memory Pricing, Software Catches the Rotation404K SEMI-AI Morning Brief 2026-07-15 — Semiconductors Lead, AI Costs Spill Over, Software Divergence Intensifies
目录
Post-Market Summary
Top 10 US Stocks by Trading Value
Top US Stock Gainers
Top US Stock Decliners
Full AI/Semiconductor Supply Chain
AI Models, Applications, and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundries, Equipment, and Testing
Optical Communications, Networking, and Power
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio
The Nasdaq and semiconductors rebounded, but the equal-weight index weakened, with capital still concentrated in memory, semiconductor equipment, optical communications, and cybersecurity. AI demand remains robust, but bottlenecks are spreading from GPUs to memory, power, liquid cooling, and delivery capacity. IBM’s earnings miss also serves as a reminder that the reallocation of enterprise budgets will drive pronounced divergence across software companies.
404K SEMI-AI | 2026-07-15
Post-Market Summary
US equities closed modestly higher in another technology-led session: the S&P; 500 rose 0.39%, the Nasdaq 100 gained 1.13%, and the S&P; 500 Equal Weight Index fell 0.26%. Technology advanced 1.19% and the semiconductor ETF gained 2.48%, indicating that the market’s incremental upside came primarily from heavyweight technology and the semiconductor supply chain rather than a broad-based rally.
Semiconductors and cybersecurity were the strongest segments. The equal-weight semiconductor benchmark rose 2.60% and the cybersecurity ETF gained 3.63%, while the software ETF advanced only 0.81% and the cloud-computing ETF fell 0.49%. Nvidia rose 4.08% and Micron gained 4.79%, while IBM plunged 25.21%, further amplifying the hardware-software divergence.
Industry signals were clearer than the indices: AI compute orders continue to grow, but per-gigawatt cluster costs, HBM prices, off-rack power infrastructure, and cooling costs are rising in tandem. Enterprise buyers are beginning to prioritize servers, storage, and memory. The next questions are whether orders convert into revenue, whether capacity expansion is delivered on schedule, and whether software budgets remain under pressure.
Top 10 US Stocks by Trading Value
Top US Stock Gainers
Top US Stock Decliners
Full AI/Semiconductor Supply Chain
AI Models, Applications, and Capital Expenditure
OpenAI
Inference demand grew rapidly following the launch of GPT-5.6 Sol. Codex and ChatGPT Work now have a combined 8 million active users, while usage of agent products increased 2.5x over the past week, prompting the platform to reset usage limits again. The immediate issues to validate following this usage surge are the pace of capacity expansion and service stability under heavy loads.
“We will reset everyone’s usage limits again and continue without a five-hour rate limit, allowing everyone to explore the boundaries of GPT-5.6 Sol and see just how ambitious their goals can be.”
Anthropic
1) The company launched Claude for Teachers, offering advanced features free of charge to certified US K–12 teachers and linking its teaching-skills library to academic standards across all 50 states.
2) Its annualized recurring revenue was reported at more than US$44 billion, while inference gross margin rose from 38% to over 70%. Whether growth can cover sustained training and inference investment will still depend on actual cash costs.
Moonshot AI
Kimi Open Platform displayed a “K3 launch” promotion effective July 15, prompting the market to await an official release. Its predecessor, K2.6, supports a 256K context window, up to 300 sub-agents, a 96.6% tool-call success rate, and continuous coding tasks lasting 12–13 hours. K3’s reported 2.5 trillion parameters and 1 million-token context window remain subject to official confirmation.
CSP/Cloud Capital Expenditure
Amazon
The company disclosed its elastic network graph topology and introduced the Spraypoint routing protocol, which splits packets across multiple paths to reduce congestion. Fewer network layers and random-graph deployment could improve large-cluster efficiency, but software-stack migration complexity, failure domains, and actual unit costs still require validation in production environments.
Microsoft
Cloud-market contracts are shifting in favor of vendors: three-year renewals are being shortened to one year, while long-term capacity reservations require larger minimum clusters and annual spending commitments. Microsoft benefits from cloud-capacity pricing and utilization, but also faces internal customer-budget reallocations away from general software and toward GPUs, servers, and security products.
“Customers attempting to renew three-year agreements are being told they can renew for only one year, implying smaller discounts and higher prices.”
AI Cloud/Data Center Operators
Nebius
1) The company signed a GB300 compute agreement with Reflection AI worth more than US$1 billion and extending through 2029. Third-party customers should help reduce its concentration in Microsoft and Meta.
2) First-quarter revenue reached US$399 million, up 684% year over year, while AI cloud annualized recurring revenue totaled US$1.92 billion, with a year-end 2026 target of US$7–9 billion. The real constraints are data-center construction and delivery speed.
“Nebius signs GB300 compute agreement with Reflection worth more than US$1 billion and running through 2029.”
IREN
Horizon 1 is only five days from delivery, but the company also faces controversy over repeated financing, management incentives, and governance. The shares have fallen 35.02% over 20 days, indicating that the market is no longer focused solely on power and data-center capacity; it now requires new capital to be matched with clearly defined contracts, commissioning milestones, and per-share value creation.
Hut 8
Benchmark maintained its Buy rating and raised its price target from US$85 to US$165, citing a new contract worth US$16.8 billion and operating momentum. Given the scale of the target increase, subsequent validation should focus on the contractual counterparty, delivery milestones, capital expenditure, and revenue recognition, rather than treating total contract value as current-period earnings.
GPU/CPU/ASIC
Nvidia
1) Small volumes of H200 shipments have begun to mainland China and Hong Kong, but US officials described the quantities as “very limited,” with licensing, inspections, and customs processing still handled case by case.
2) KeyBanc maintained its Overweight rating and raised its price target from US$310 to US$330. Its 2027 CoWoS supply forecast increased to 1.1 million units, representing 69% growth. Vera Rubin’s volume ramp has been slightly delayed, but training demand and packaging supply continue to support earnings.
“There is currently no indication that its dominance in training is weakening. Training workloads will continue to grow, albeit more slowly than inference workloads.”
Intel
1) KeyBanc said 18A yields improved from 65% to over 85% and raised its price target from US$110 to US$155. Stifel lifted its target to US$120 but maintained a Hold rating, with the divergence reflecting uncertainty over volume-production execution and long-term valuation.
2) EMIB-T has secured positions in the AWS Trainium 3 and Google TPU programs, but material revenue opportunities are not expected to begin scaling until 2029–2030.
“18A yields continue to improve significantly, rising from 65% last quarter to more than 85%.”
AMD
Helios launch partners have secured publicly disclosed customer adoption, with double-wide racks, liquid cooling, and PCIe Gen 6 storage positioned as system-level selling points. KeyBanc raised its general-purpose server shipment-growth forecast from 18.5% to 30%, while AMD also secured additional N4 wafers following reductions in smartphone orders. Its target of more than 50% server CPU shipment growth in 2027 remains constrained by capacity and customer deployment.
Broadcom
Morgan Stanley believes MediaTek’s involvement in TPU supply is real, but Broadcom’s long-term share should remain near 80%, making the bear-case assumption of a decline to 50% premature. The company’s AI semiconductor revenue reached US$10.8 billion, with networking accounting for approximately 40%. Its ability to defend its custom-ASIC share will depend on Google’s internal development pace, MediaTek’s production ramp, and Broadcom’s delivery capabilities.
HBM/DRAM/NAND/SSD/HDD
Micron
All 2026 HBM output has been booked under multiyear premium-priced contracts, while new fabs will not contribute meaningful production until the second half of 2027 or later. The company plans to increase DRAM and NAND bit shipments by more than 20% in 2026. Whether pricing holds will depend on both demand destruction in end markets and the ramp-up of new capacity.
“All 2026 HBM output has been booked, providing exceptionally high visibility and reducing cyclical risk.”
SK Hynix
Barclays expects DRAM bit demand to grow 35% in 2027 against only 20% supply growth, potentially extending the shortage into 2028. It initiated coverage of the ADR with an Overweight rating and a US$330 price target. The company’s operating margin was reported at 72%, but the ADR has traded at a 51% premium to the South Korean-listed shares, making cross-market mispricing and high volatility difficult to ignore.
Sandisk
Morgan Stanley said first-quarter cloud revenue grew 233% sequentially, while more than one-third of FY27 bit output has been secured under three- to five-year contracts. Disclosed penalties for customer cancellations total approximately US$11 billion. HBF samples are planned for the first half of 2027. Long-term contracts provide downside protection, but the 86.7% FY27 non-GAAP gross-margin assumption requires both elevated NAND pricing and supply discipline.
Samsung Electronics
Semiconductors contributed more than 93% of group profit, with the Device Solutions division generating KRW53.7 trillion in operating profit. HBM, server DRAM, and advanced NAND were the primary drivers. The company denied plans to issue American depositary receipts. The memory upcycle still needs to be assessed through HBM qualification, server contract pricing, and capacity utilization rather than speculation over trading structures.
JEDEC
The SPHBM4 standard uses an interface base die to mount DRAM stacks on an organic substrate, adopting 4:1 serialization to reduce data-signal pairs from 2,048 to 512 while widening bump pitch. This could reduce dependence on silicon interposers and allow more stacks around processors, but there remains a considerable gap between publication of the standard and maturity across controllers, substrates, and the mass-production ecosystem.
“The standard uses a new interface base die that allows DRAM stacks to be mounted on standard organic substrates rather than expensive silicon interposers.”
Foundries, Equipment, and Testing
TSMC
High-performance computing accounted for 61% of revenue, with 3nm, 5nm, and 7nm leading wafer revenue, while operating margin reached 58.1%. AI workloads continue to migrate toward advanced nodes and packaging, but sustaining high margins will depend on advanced-node utilization, CoWoS capacity expansion, customers’ custom-chip development cycles, and capital-expenditure depreciation.
ASML
Pre-earnings-call models project second-quarter revenue of €8.9 billion, close to the €9.0 billion consensus. Support comes from Micron’s multiyear EUV agreement and higher capital expenditure at SK Hynix and Intel. RBC Capital raised its price target from US$1,700 to US$2,000. Risks include China revenue falling below 20%, weakening DUV demand, and reduced order visibility.
Tower Semiconductor
Japan’s Ministry of Economy, Trade and Industry plans to provide up to ¥159 billion in subsidies for mass production of optical-communications semiconductors, while the company plans to invest approximately ¥600 billion to expand its Niigata and Toyama plants. The project covers 300mm silicon photonics, silicon-germanium, and advanced packaging, targeting full mass-production readiness by the fourth quarter of 2027. Subsidies do not equate to customer orders; equipment installation and yields remain key validation points.
Powerchip Semiconductor Manufacturing
DRAM foundry prices were raised another 45% in July, logic-process bookings reached 1.4x available capacity, and second-quarter gross margin was 28%. Supply and demand for mature nodes have improved, but the forecast for industry gross margins exceeding 40% in 2027 remains long-dated. If customer inventories rise or capacity expands too quickly, the sustainability of price increases will be tested first.
Aehr Test Systems
Quarterly revenue was US$18.8 million, with earnings per share of US$0.11, orders of US$61 million, and a backlog of approximately US$101 million. FY2027 revenue guidance was US$130–150 million, alongside more than US$8 million in new silicon-carbide test orders. Test demand spans AI processors, silicon photonics, and power devices; the key variables are customer qualification, delivery, and collections.
Optical Communications, Networking, and Power
Applied Optoelectronics
Construction began on a nearly 400,000-square-foot expansion project in Texas. Monthly production targets for 800G and 1.6T optical transceivers exceed 650,000 units by year-end and 930,000 by the end of 2027. First-quarter revenue reached US$151.1 million, up 51% year over year, and the company has more than US$200 million in 1.6T component orders. The expansion case is compelling, but construction, ramp-up, and CPO substitution risks all require monitoring.
Arista Networks and Cisco
1) Bank of America data show that first-quarter data-center switch revenue grew 50% year over year, with AI back-end switching up 121%. Arista led with a 21.1% share of the overall data-center market and a 32.0% share of front-end switching among Tier 2 cloud providers.
2) Cisco’s AI back-end share rose from zero to 7.9%, while its hyperscale cloud back-end share reached 13.2%, benefiting from its entry into Meta’s 800G leaf-switch layer. Whether these share gains persist will depend on customer expansion and product gross margins.
Eaton
Morgan Stanley estimates that next-generation off-rack power infrastructure, liquid cooling, transformers, and substations will cost US$16–19 million per megawatt, representing 41%–49% of the total cost of a GB300 cluster. Power-related content has increased materially, but project revenue remains constrained by substation construction, grid-connection approvals, and customers’ data-center delivery schedules.
“Next-generation off-rack infrastructure costs US$16–19 million per megawatt, accounting for 41%–49% of the total cost of a GB300 cluster.”
Internet/Platforms
Meta
1) Q1 advertising revenue grew 33%, impressions rose 19%, and price per ad increased 12%; AI returns still depend on improved advertising efficiency.
2) In June, average cost per 1,000 impressions accelerated from 12% to 26%, with ad spending 120 basis points above expectations.
3) The company was sued over allegations that its layoff system failed to account for approved medical leave, making algorithmic governance a direct legal risk.
“The lawsuit alleges that Meta used AI-powered software to target employees with medical conditions for layoffs.”
Google
1) Its US search share returned to growth for the first time since April 2025, while Gemini’s share rose to 26.9%, second only to ChatGPT’s 57.2%.
2) Google Images is being redesigned into a Pinterest-like personalized discovery feed, with AI image generation integrated directly into Search.
3) The company signed a fixed-price virtual power purchase agreement securing 100% of the Steel River project’s initial generation, adding long-term power supply for its cloud and AI infrastructure.
“Google will also integrate AI image generation directly into Search, keeping users within its ecosystem rather than directing them to external tools.”
Reddit
Total users grew 2% month over month in June, but were roughly flat versus May after excluding anomalies in the May data. Piper’s survey still ranked Reddit among the standout performers in Q2 ad spending; the quality of growth depends on genuine engagement, ad load, and data-licensing revenue rather than fluctuations in a single month’s reporting.
Netflix
Piper’s advertising-buyer survey ranked Netflix among the standout internet platforms in Q2, while separate reports indicated that Lionsgate was exploring a sale. Incremental advertising revenue and acquisitions of content assets represent two distinct paths: the former depends on user monetization, while the latter increases capital commitments and integration risk. Transaction rumors alone are insufficient.
The Trade Desk
It delivered the weakest performance relative to expectations in the Q2 advertising survey. Shares fell 4.35% that day and 1.82% over 20 days. Open-internet advertising remains under pressure from retail media and platforms’ proprietary tools; key validation points are customer retention, share of CTV budgets, and the platform’s take rate on each dollar of ad spending.
“Overall, the advertising-buyer survey was strong, with Q2 ad spending up 7.7% year over year, approximately 80 basis points above expectations. Standout performers included Reddit, Netflix, and YouTube.”
Airbnb
Management faced criticism and quickly deleted AI-generated content about asset tokenization, highlighting the reputational risks of generative AI in highly sensitive financial topics. The incident does not directly affect the accommodation business, but it reminds platform companies that while content generation can improve efficiency, review responsibilities and executive communications discipline cannot be delegated to models.
Uber
Market reports indicated that the company was seeking to reach a potential acquisition agreement as early as that week, while its shares fell 2.94% that day. Whether an acquisition would improve its mobility or delivery network depends on the target, price, and synergies; revenue implications cannot currently be inferred from rumors. The platform must also manage autonomous-driving partnerships, driver supply, and regulatory costs.
Similarweb
The company launched a free AI Visibility tool that ranks brand visibility on ChatGPT across multiple categories, initially covering US news and media brands in June 2026. The free entry point offers customer-acquisition value, but monetization will depend on methodological transparency, update frequency, and the ability to convert users into paying analytics customers.
Pinterest
Google Images’ shift toward a personalized discovery feed means that Pinterest’s visual-discovery gateway faces more direct platform competition. Pinterest rose 1.39% that day and 11.88% over 20 days; the key metrics are changes in search referrals, shopping-ad conversion, and user time spent—not one-day relative performance.
“Google is redesigning Google Images into a Pinterest-like discovery feed featuring personalized galleries and saved collections.”
Starlink
More than 7,500 commercial aircraft have installed or contracted to install its products, spanning 46 airlines or operators. The next-generation V5 terminal offers speeds above 375 Mbps, averages 35–50 W of power consumption, and is 50% more energy-efficient than V4. In-flight connectivity is entering a phase of scaled deployment, with revenue realization dependent on installation progress and service fees per aircraft.
Southwest Airlines
The company has announced that it will adopt Starlink Wi-Fi, joining the industry-wide upgrade in airline connectivity. The announcement does not itself imply fleet-wide deployment; key follow-up indicators include the number of retrofits, launch timing, whether service will be free or paid, and whether satellite bandwidth can maintain service quality on high-density routes.
United Airlines
The company is likewise among the major US airlines that have announced the adoption of Starlink. Satellite internet can improve the passenger experience and loyalty-program engagement, but airlines must bear terminal retrofit, certification, and aircraft downtime costs. The investment implications are more relevant to Starlink’s installed-base expansion than to any immediate uplift in airline margins.
American Airlines
The company has announced that it will adopt Starlink Wi-Fi, indicating growing acceptance of low-Earth-orbit satellite connectivity among large network carriers. Contracting, installation, and commercial launch are three distinct stages; the contract’s scale cannot be assessed until fleet coverage, activation rates, and customer usage are disclosed.
Frontier Airlines
The company plans to equip its fleet with Starlink internet service beginning in 2027, providing a clearer timeline than a simple adoption announcement. Whether the low-cost carrier offers high-speed connectivity for free will affect ancillary revenue and customer experience; installation progress is also a measurable indicator for Starlink’s aviation business.
“Frontier Airlines plans to launch its first Starlink-equipped aircraft in early 2027 and will become the first US airline to provide passengers with Starlink high-speed internet access through a new system managed directly by Starlink.”
Delta Air Lines and JetBlue Airways
Neither company has announced the adoption of Starlink, but the absence of an announcement does not imply rejection. Their choices will test whether the in-flight connectivity market further consolidates around low-Earth-orbit satellite solutions and will also affect renewals and pricing for incumbent in-flight connectivity providers.
Software/SaaS
IBM
1) Preliminary Q2 revenue was $17.2 billion, up 1% year over year but below the $17.86 billion consensus; software grew 5%, infrastructure declined 7%, and adjusted EPS was $2.93.
2) Management said customers were redirecting capital expenditure toward servers, storage, and memory, delaying some large deals. Bank of America cut its price target from $330 to $280, while HSBC downgraded the stock to Reduce and lowered its target to $191.
“...we did not anticipate the magnitude of the shift in capex priorities. In addition, customers were disrupted this quarter by rapidly evolving industry-wide cybersecurity issues.”
ServiceNow
UBS maintained its Neutral rating and raised its price target from $100 to $115. Analysts view demand as stable but not improving, with only modest upside to guidance. Shares fell 5.76% that day; the key question is whether AI products can increase contract value and renewals, rather than merely generating greater demo interest.
Salesforce
Evercore ISI maintained its Outperform rating but cut its price target to $250, without disclosing the prior target. Agentforce and Data Cloud are growth drivers, while Tableau remains under pressure. Customer data readiness and return on investment remain bottlenecks to scaled deployment; the lower price target indicates that the market is beginning to demand tangible AI revenue.
“Analysts see a tug-of-war between growth drivers such as Agentforce and Data Cloud and headwinds such as Tableau, with data readiness and clarity on return on investment remaining the bottlenecks.”
Datadog
Its advantage in the agentic era comes from real-world user, enterprise, and operational databases rather than the general-purpose model itself. Shares rose 17.76% over 20 days, with a relative-strength score of 95.4. Whether the valuation can be sustained depends on converting observability data into AI operations revenue and whether cloud-cost optimization suppresses usage.
CrowdStrike
Falcon has expanded from endpoint security into identity threat protection, cloud workloads, and AI threat intelligence. Shares rose 12.14% that day on turnover of $2.48 billion. AI expands the attack surface across non-human identities and automated threats, strengthening the demand thesis. The risk is that high-growth expectations are already substantially reflected in the valuation, while platform consolidation must continue converting into net new contracts.
“More software is operating autonomously. More access permissions require governance. More sensitive data is flowing across cloud, SaaS, and AI systems.”
Palo Alto Networks
Cortex, Prisma SASE, Cortex Cloud, SIEM, and identity security span endpoint, network, cloud, and privileged-access protection. Shares rose 6.84% that day. Enterprises want to reduce the number of tools they use, favoring platform consolidation and large vendors; however, sustained margins depend on whether cross-selling can preserve pricing and renewal rates.
Cloudflare
Zero trust, edge security, DDoS protection, and application security all benefit from growing AI-application traffic. Shares rose 23.31% over 20 days, reached an all-time high, and posted a relative-strength score of 97.4. Growth must be validated through large-customer revenue, edge-inference usage, and gross margin, avoiding the assumption that traffic growth directly translates into profit growth.
Okta
Authentication, access control, and privileged access are becoming foundational security layers in multi-cloud and SaaS environments. AI agents increase the number of machine identities while amplifying permission-configuration errors. Okta’s opportunity lies in the neutrality of its independent identity platform; the risk is that suite vendors such as Microsoft compete through bundled pricing.
“AI adoption increases the value of authentication, access control, and privileged access in multi-cloud and SaaS-intensive environments.”
Tenable
AI infrastructure increases vulnerabilities, identity risks, cloud misconfigurations, and attack paths, driving demand for exposure management. The company must demonstrate that its products can convert more alerts into actionable priorities while maintaining large-customer renewals; otherwise, higher security budgets may flow first to integrated platforms.
Varonis
When enterprise file permissions are overly broad, AI assistants may expose sensitive information to unauthorized users, increasing the importance of data-access governance. The company benefits from the expansion of Copilot-style workflows, but deployments typically require scanning, permission remediation, and organizational coordination, meaning sales cycles and customer execution speed will constrain the revenue ramp.
Rubrik
The company has expanded its positioning from backup to cyber resilience, spanning immutable backups, data-security posture, and identity recovery. AI increases data volumes and the attack surface, making recovery capabilities more valuable. Revenue quality should be assessed through subscription growth, customer expansion, and actual adoption of recovery products—not merely the number of security incidents.
Commvault
Its product focus has shifted from traditional backup toward clean data and identity recovery after an intrusion, while reducing the risk of reinfection during recovery. The platform strategy aligns with customer demand to reduce tool counts, but clear advantages in pricing and recovery speed are essential when competing with Rubrik and cloud-native services.
SentinelOne
Autonomous endpoint protection and extended detection and response use AI-driven behavioral analysis to accelerate detection and remediation, appealing to customers seeking to reduce manual security operations center workloads. The opportunity comes from machine-speed attacks; the counterpoint is that similar capabilities have become industry standard. Key indicators are net retention among large customers and customer-acquisition cost per unit.
F5
Hybrid, distributed, and AI-driven applications increase demand for API protection, bot defense, web application firewalls, and traffic management. Positioned at the intersection of application delivery and security, the company benefits from rising complexity. The risk is that customers consolidate these functions into cloud platforms or edge networks, compressing budgets for standalone products.
Cadence Design Systems
Rosenblatt maintained its Buy rating and raised its price target from $375 to $410. AI-chip complexity and advanced packaging increase demand for EDA tools, but shares fell 0.30% that day and 2.12% over 20 days. Key indicators are design activity among major customers, AI-related orders, and regulatory constraints.
“I genuinely believe that the broad SaaS doomsday narrative has blinded investors to the enormous opportunities emerging across software.”
Consumer Electronics / Smart Vehicles
Apple
1) The company is evaluating PrismML, which claims it can compress the 27-billion-parameter Qwen model from approximately 54GB to under 4GB for operation on the iPhone 15 and newer models, reducing memory usage by 10–15x and increasing speed by 6–8x.
2) Morgan Stanley expects the iPhone 18 Pro to raise prices by $200 for equivalent configurations to preserve an approximately 40% gross margin; KeyBanc downgraded the stock to Underweight with a $250 price target.
“Compressing the 27-billion-parameter Bonsai model to 3.9GB or 5.9GB while retaining approximately 90%–95% of full-precision capability suggests that the shift of inference to edge devices could reshape AI application costs and drive demand for unified memory, bandwidth, NPUs, and low-power inference.”
PrismML
Its on-device compression technology fits large models into smartphone memory. The commercial value lies in reducing cloud inference costs while improving privacy and latency. Performance is partially degraded, and all claimed improvements in speed, power consumption, and memory usage are company-reported. Whether Apple will invest, partner, or adopt the technology remains uncertain.
Global Smartphones
China’s smartphone shipments were approximately 66 million units in the second quarter, down 4.3% year over year. Global full-year shipments are projected to fall 13.9% to 1.09 billion units, with models priced below $400 expected to decline by more than 20%. Rising memory prices are squeezing specifications and demand in lower-priced devices; memory vendors’ pricing power also represents a cost risk for device brands.
“The contraction in unit sales does not mean demand has disappeared; memory has become the constraining variable across the electronics supply chain.”
Sonos
Sonos fell 6.5% after hours following OpenAI’s announcement of plans for a home speaker, as the market initially priced in potential competition for the user interface. OpenAI’s device emphasizes a screenless, mobile, and context-aware design, while Sonos’ moat remains its audio quality, home-device ecosystem, and distribution. The actual impact will depend on pricing, launch timing, and user adoption.
Lucid
Shares fell as much as 48% to an all-time low, leaving the company with a market capitalization of approximately $1.17 billion, following reports of a potential take-private transaction or bankruptcy-protection filing. The company had not responded at the time. With quarterly cash burn of approximately $1 billion, financing, restructuring, and deliveries ahead of the Cosmos launch are existential variables; rumors should not be treated as a finalized course of action.
Tesla
Shares rose 0.36% on the day but declined 2.67% over 20 days, while autonomous driving and robotics still lack incremental hard data. The company’s in-house semiconductor development and physical-AI strategy remain frequent discussion topics, but investment validation should focus on autonomous-driving mileage, accident rates, robot mass production, and deployment of proprietary chips—not thematic momentum.
Ferrari
Management believes the controversy surrounding the Luce EV could generate free publicity, as the initial backlash against the Purosangue ultimately did. Brand visibility has indeed increased, but negative reactions may also reflect resistance to electrification among core customers. Orders, pricing, mass production, and deliveries will determine whether publicity converts into revenue.
“Ferrari’s chairman said he was ‘pleased’ with the backlash generated by the Luce EV.”
T-Mobile
The T-Life app can use the updated Siri to check or pay bills, showing that system-level assistants are beginning to enter carrier service workflows. One individual experience does not demonstrate adoption at scale. Permission transparency, payment confirmation, error handling, and user retention are critical for voice agents to progress from demonstrations to transaction interfaces.
Eero
Following a software update, Mesh nodes experienced weaker connections and packet loss, while other networks did not exhibit the same issue. Home networking is the underlying infrastructure for edge AI and smart homes, making stability more important than incremental features. Key follow-ups include whether Amazon provides a fix, the scope of affected devices, and authorization to access diagnostic data.
BlackBerry QNX
Nvidia Halo uses QNX as its certified safety layer. The general embedded market outside automotive accounts for approximately 20% of revenue, or around $53.6 million in FY2026. Its core serviceable addressable market is projected to expand from $1.7 billion to $2.9 billion, with the total addressable market reaching $5.9 billion by 2028. The opportunity is expanding from automotive into robotics, healthcare, and industrial applications, but order conversion remains to be validated.
“Demand for physical AI is expanding rapidly, yet 91% of robotics developers still use general-purpose operating systems, and 66% of projects are delayed by failures to obtain safety certification.”
FANUC
The company has successively partnered with Google and AWS, while the value of physical AI lies in hardware precision, control systems, and factory data. The strategic direction is clear, but there is no disclosure yet on order scale, deployment timing, or revenue contribution. Key areas to monitor are how robotic controls, vision models, and cloud-based training enter actual production lines.
Auto Insurance Technology
AI can help users exaggerate accidents and alter claims documents, while also helping insurers detect fraud. The net effect depends on data quality, model audits, and human review. These dual-use applications will increase demand for anti-fraud software while creating risks related to false positives, privacy, and regulatory liability.
OpenAI Home Device
The proposed device would use cameras and sensors to understand its surroundings, move between rooms on battery power, and control appliances, media, and messaging. Its functionality overlaps with smartphones, speakers, and smart-home hubs. It must demonstrate that the convenience of continuous sensing is sufficient to offset the privacy cost and additional hardware expenditure.
“OpenAI reportedly plans to unveil a home speaker this year as its first hardware product, with sales scheduled to begin in 2027.”
Edge-AI Platforms
The 27-billion-parameter Bonsai model can be compressed to 3.9GB or 5.9GB while retaining approximately 90%–95% of full-precision capability; the iPhone 17 Pro Max delivers approximately 11 tokens per second. If the performance proves stable, inference costs will shift to user devices and drive upgrades in memory and NPUs. The largest frontier models will remain dependent on data centers.
Starlink V5 Terminal
The new terminal delivers peak speeds above 375Mbps with average power consumption of 35–50W. Its antenna dish is 35% smaller than the V4, weighs 2.4 pounds, is 14% lighter, and retains a 110-degree field of view. The smaller size and lower power consumption support residential and mobile deployments, but actual competitiveness will depend on pricing, service plans, coverage, and peak-hour bandwidth.
Investment-Bank Price-Target Changes Over the Past 12 Hours
Huang’s Selected Portfolio