
404K SEMI-AI Morning Brief, 2026-07-30 — Hardware Under Pressure: Cloud Software Relatively Strong, Memory Long-Term Contracts and Silicon Photonics Expansion Continue
目录
Post-Market Summary
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry and Advanced Packaging
Semiconductor Equipment/Testing
Optical Communications/High-Speed Interconnects/Power
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Jensen Huang's Selected Portfolio
Overview
404K SEMI-AI | 2026-07-30
Post-Market Summary
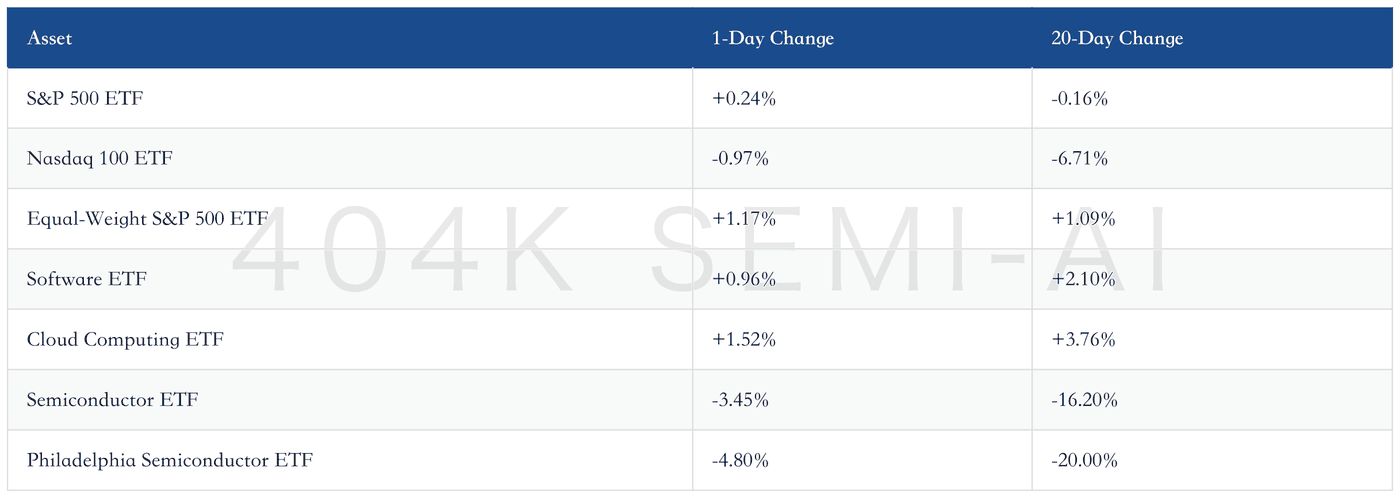
As of the latest available close on July 28, performance within technology stocks remained divergent. The S&P; 500 ETF rose 0.24%, the equal-weight S&P; 500 ETF rose 1.17%, and the Nasdaq 100 ETF fell 0.97%; software and cloud computing gained 0.96% and 1.52%, respectively, while semiconductor ETFs declined 3.45% to 4.80%. Capital remains more willing to pay for cloud revenue and software orders that have already materialized, while elevated hardware expectations are still being digested.
Over the past 20 trading days, software and cloud computing rose 2.10% and 3.76%, respectively, while semiconductor ETFs fell 16.20% to 20.00%. The latest earnings reports did not provide evidence of a broad weakening in AI demand: Microsoft Azure, Seagate Technology nearline HDDs, Lam Research’s equipment guidance, and Flex’s data-center orders all remained strong. Pressure primarily stems from the pace at which capital expenditure translates into results, supply-chain execution, and excessively high earnings hurdles.
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
OpenAI
1) ChatGPT is approaching 1 billion weekly active users, with its user base continuing to expand, although it reached this milestone approximately 7 months later than originally targeted.
2) The company launched a program for researchers, providing 10,000 researchers with free access to frontier models, and plans to expand it to 100,000 researchers by 2027. User growth remains strong; the next question is whether frequent usage can translate into enterprise seats and inference revenue.
Anthropic
The Max and High configurations of Claude Opus 5 ranked No. 2 and No. 3, respectively, in Agent Arena, based on more than 7,000 real-world agent sessions; the two configurations delivered net improvements of 11.88 and 11.73, respectively, versus the arena baseline. Model capabilities continue to improve, but whether leaderboard performance can translate into enterprise spending will still depend on task success rates, inference cost per unit, and customer retention.
"Models can use web search, file-system, and terminal tools to complete complex workflows. The leaderboard uses causal tracking to measure model performance based on task outcomes relative to the average model."
AI Capital-Expenditure Risk
Bank of America believes that spending by OpenAI and Anthropic has already entered suppliers’ backlogs and financial data and therefore cannot simply be equated with disappearing demand in the near term; the real variable is whether usage growth can outpace declining unit prices after open-weight models drive down token prices. Positive hardware developments have lost their ability to propel share prices, indicating that investors are beginning to require orders, revenue, and free cash flow to materialize simultaneously.
"Spending by OpenAI and Anthropic has already been reflected in suppliers’ backlogs and financial data. Open-weight models may ultimately increase compute demand, but the transition is unlikely to be smooth."
CSP/Cloud Capital Expenditure
Microsoft
1) Quarterly revenue was $90.0 billion and EPS was $4.74, while Azure grew 43% in constant currency, above the prior guidance of 39% to 40%. Copilot seats reached 30 million, also above the expected 25 million.
2) Future lease commitments increased from $197.0 billion to $329.0 billion, as compute and data-center resources continued to be secured in advance. The key questions are whether Azure can sustain the 43% growth threshold and when lease commitments will translate into revenue and cash returns.
Meta
Quarterly revenue was $60.8 billion, slightly above consensus of approximately $60.2 billion; revenue guidance for the next quarter is $61.0 billion to $64.0 billion. The lower bound of 2026 expense guidance was raised from $162.0 billion to $165.0 billion, while the capital-expenditure range was adjusted from $125.0 billion–$145.0 billion to $130.0 billion–$145.0 billion, lifting the midpoint by only approximately 2%. Ad impressions declined from the previous quarter, meaning that accelerating AI investment and advertising efficiency still need to be validated in tandem.
Amazon
Channel expectations call for AWS revenue growth of more than 40% next quarter, and cloud demand remains a critical pillar of the e-commerce platform’s valuation. Meanwhile, industry research indicates that AI-infrastructure capital expenditure may continue to increase in 2027. If revenue growth cannot cover depreciation, leasing, and financing costs, cloud-business margins will become a more important validation metric than the absolute amount of capital expenditure alone.
AI Cloud/Data-Center Operators
Flex
1) Quarterly revenue from data-center power, cooling, and rack businesses was $2.2 billion, up 35% year over year, with adjusted operating profit of $214 million and a margin of 9.7%.
2) More than 90% of expected revenue over the next 3 quarters is already covered by orders, and fiscal 2026 growth guidance is 65% to 75%. Group quarterly revenue was $7.9 billion, but free cash flow was only $41 million, indicating that orders are not the issue; capital expenditure and cash conversion are the constraints ahead of the separation.
Vertiv
Quarterly revenue was $3.27 billion, up 24% year over year but below the market expectation of $3.38 billion; adjusted EPS of $1.52 and an operating margin of 22.6% were above expectations. Full-year revenue guidance is $13.8 billion to $14.2 billion, and free-cash-flow guidance is $2.4 billion to $2.6 billion. Demand from AI and general-purpose computing remains strong; the weak points are supply-chain congestion in the Americas and the pace of backlog conversion.
Nebius
The company scheduled the release of its Q2 2026 results for before the market opens on August 12, with the conference call set for 8:00 a.m. Eastern Time. For new cloud providers, the market needs to see alignment among GPU-capacity deployment, customer utilization, lease duration, and capital-expenditure financing; simply increasing the scale of data centers and equipment cannot address questions about revenue quality and cash burn.
New Era Energy & Brookfield
According to reports, the two parties are advancing a data-center project valued at more than $100.0 billion, with plans to convert a retired industrial facility in Kentucky into a data-center campus with supporting power-generation capacity. The project brings power and land commitments forward ahead of compute construction; key validation points are whether customers, phased investment, grid-connection timing, and financing arrangements can materialize.
GPU/CPU/ASIC
Arm
Quarterly revenue was $1.289 billion, up 22% year over year; royalty revenue was $715 million, up 22%, and licensing revenue was $574 million, up 23%. Data-center royalty revenue more than doubled, indicating that ARMV9, compute subsystems, and server deployments are increasing value per chip. Risks include volatility in the timing of licensing revenue and the time still required for downstream customers to convert design adoption into mass production.
"Market demand for Arm AGI CPUs continues to exceed our initial expectations, and our ongoing work with partners to expand manufacturing capacity gives us greater confidence that we can achieve the delivery scale required by customers."
Qualcomm
Quarterly revenue was $9.95 billion, with handset, automotive, and IoT revenue all exceeding expectations, but EPS of $2.21 was below the $2.24 expectation; next-quarter EPS guidance of $2.15 was also below the $2.38 expectation. Handset and automotive revenue are growing, but profit delivery remains weak, while the data-center opportunity and pressure on the RF business have not yet gained market recognition.
Hewlett Packard Enterprise
The company launched the AMD EPYC-powered GX5000 AI supercomputing system, claiming a 40% increase in compute density. Higher density can reduce the number of racks required for an equivalent amount of compute, but it also concentrates power, cooling, and networking pressure within each rack. Key issues to monitor are the number of customer deployments, system delivery cycles, and whether the density improvement can translate into gross margin for the complete system rather than remaining merely a specification advantage.
HBM/DRAM/NAND/SSD/HDD
Seagate Technology
1) Quarterly revenue was $3.629 billion, up 48.5% year over year, with a non-GAAP gross margin of 52.7%, EPS of $5.71, and free cash flow of $1.118 billion; next-quarter guidance calls for revenue of $4.1 billion and EPS of $7.30.
2) Most capacity has already been allocated through 2027, demand is already visible for 2028, and customers have begun planning for 2029; HAMR is expected to account for more than 50% of nearline shipment capacity by the end of 2026. Risks include a slowdown in cloud capital expenditure, yield ramp-up, and NAND price declines improving SSD economics.
SK Hynix
1) Enterprise SSD revenue doubled sequentially, while products above 30TB increased to more than 3 times their previous level; HBM4 has entered mass production, with a full ramp planned for the second half of the year.
2) The company said approximately 10 customers are signing multiyear supply agreements, while it sold its remaining Kioxia stake in June 2026. Long-term agreements improve production-scheduling visibility, but elevated capital expenditure will also push the risk of supply normalization into 2027 to 2029.
"However, on the supply side, the supply-demand balance appears unlikely to improve materially in the near term. This is because the advanced processes used for HBM and AI-server memory are becoming increasingly complex, while new production facilities also require a certain lead time."
DRAM Spot Market
Inquiries for DDR3, DDR4, and DDR5 increased broadly, while the average spot price of DDR4 1G×8 3200 rose from $41.50 to $42.08, an increase of 1.39%. However, transactions at elevated prices remained limited, indicating that higher quotations have not yet fully translated into volume transactions. Contract prices, server orders, and channel inventories all need to be monitored to avoid treating a short-term increase in inquiries as a definitive cyclical inflection point.
Foundry and Advanced Packaging
UMC
1) Q2 revenue was NT$68.7 billion, up 12.6% sequentially, with a gross margin of 32.5%; capacity utilization increased from 79% to 85%. For the next quarter, wafer shipments are expected to grow by a high-single-digit percentage, with utilization moving into the low-90% range.
2) 2026 capital expenditure was raised from $1.5 billion to $2.0 billion, while AI revenue is expected to approach $300 million and exceed $1.0 billion within 3 years. The first 12-inch silicon-photonics product has already taped out, and a more comprehensive platform is expected to launch in 2027.
Intel Foundry
External foundry revenue was $293 million, while the business posted an operating loss of $2.1 billion, narrowing sequentially by $348 million. The improvement indicates that costs and capacity utilization are being adjusted, but external revenue remains insufficient to cover the fixed costs of advanced process nodes. Assessing foundry value requires more than looking at narrowing losses; external-customer tape-outs, mass-production yields, and long-term capacity commitments must also be considered.
