404K SEMI-AI Morning Brief 2026-07-06 — Memory Price Hikes, AI Power Constraints, Passive Components Catch-Up
目录
After-Market Summary
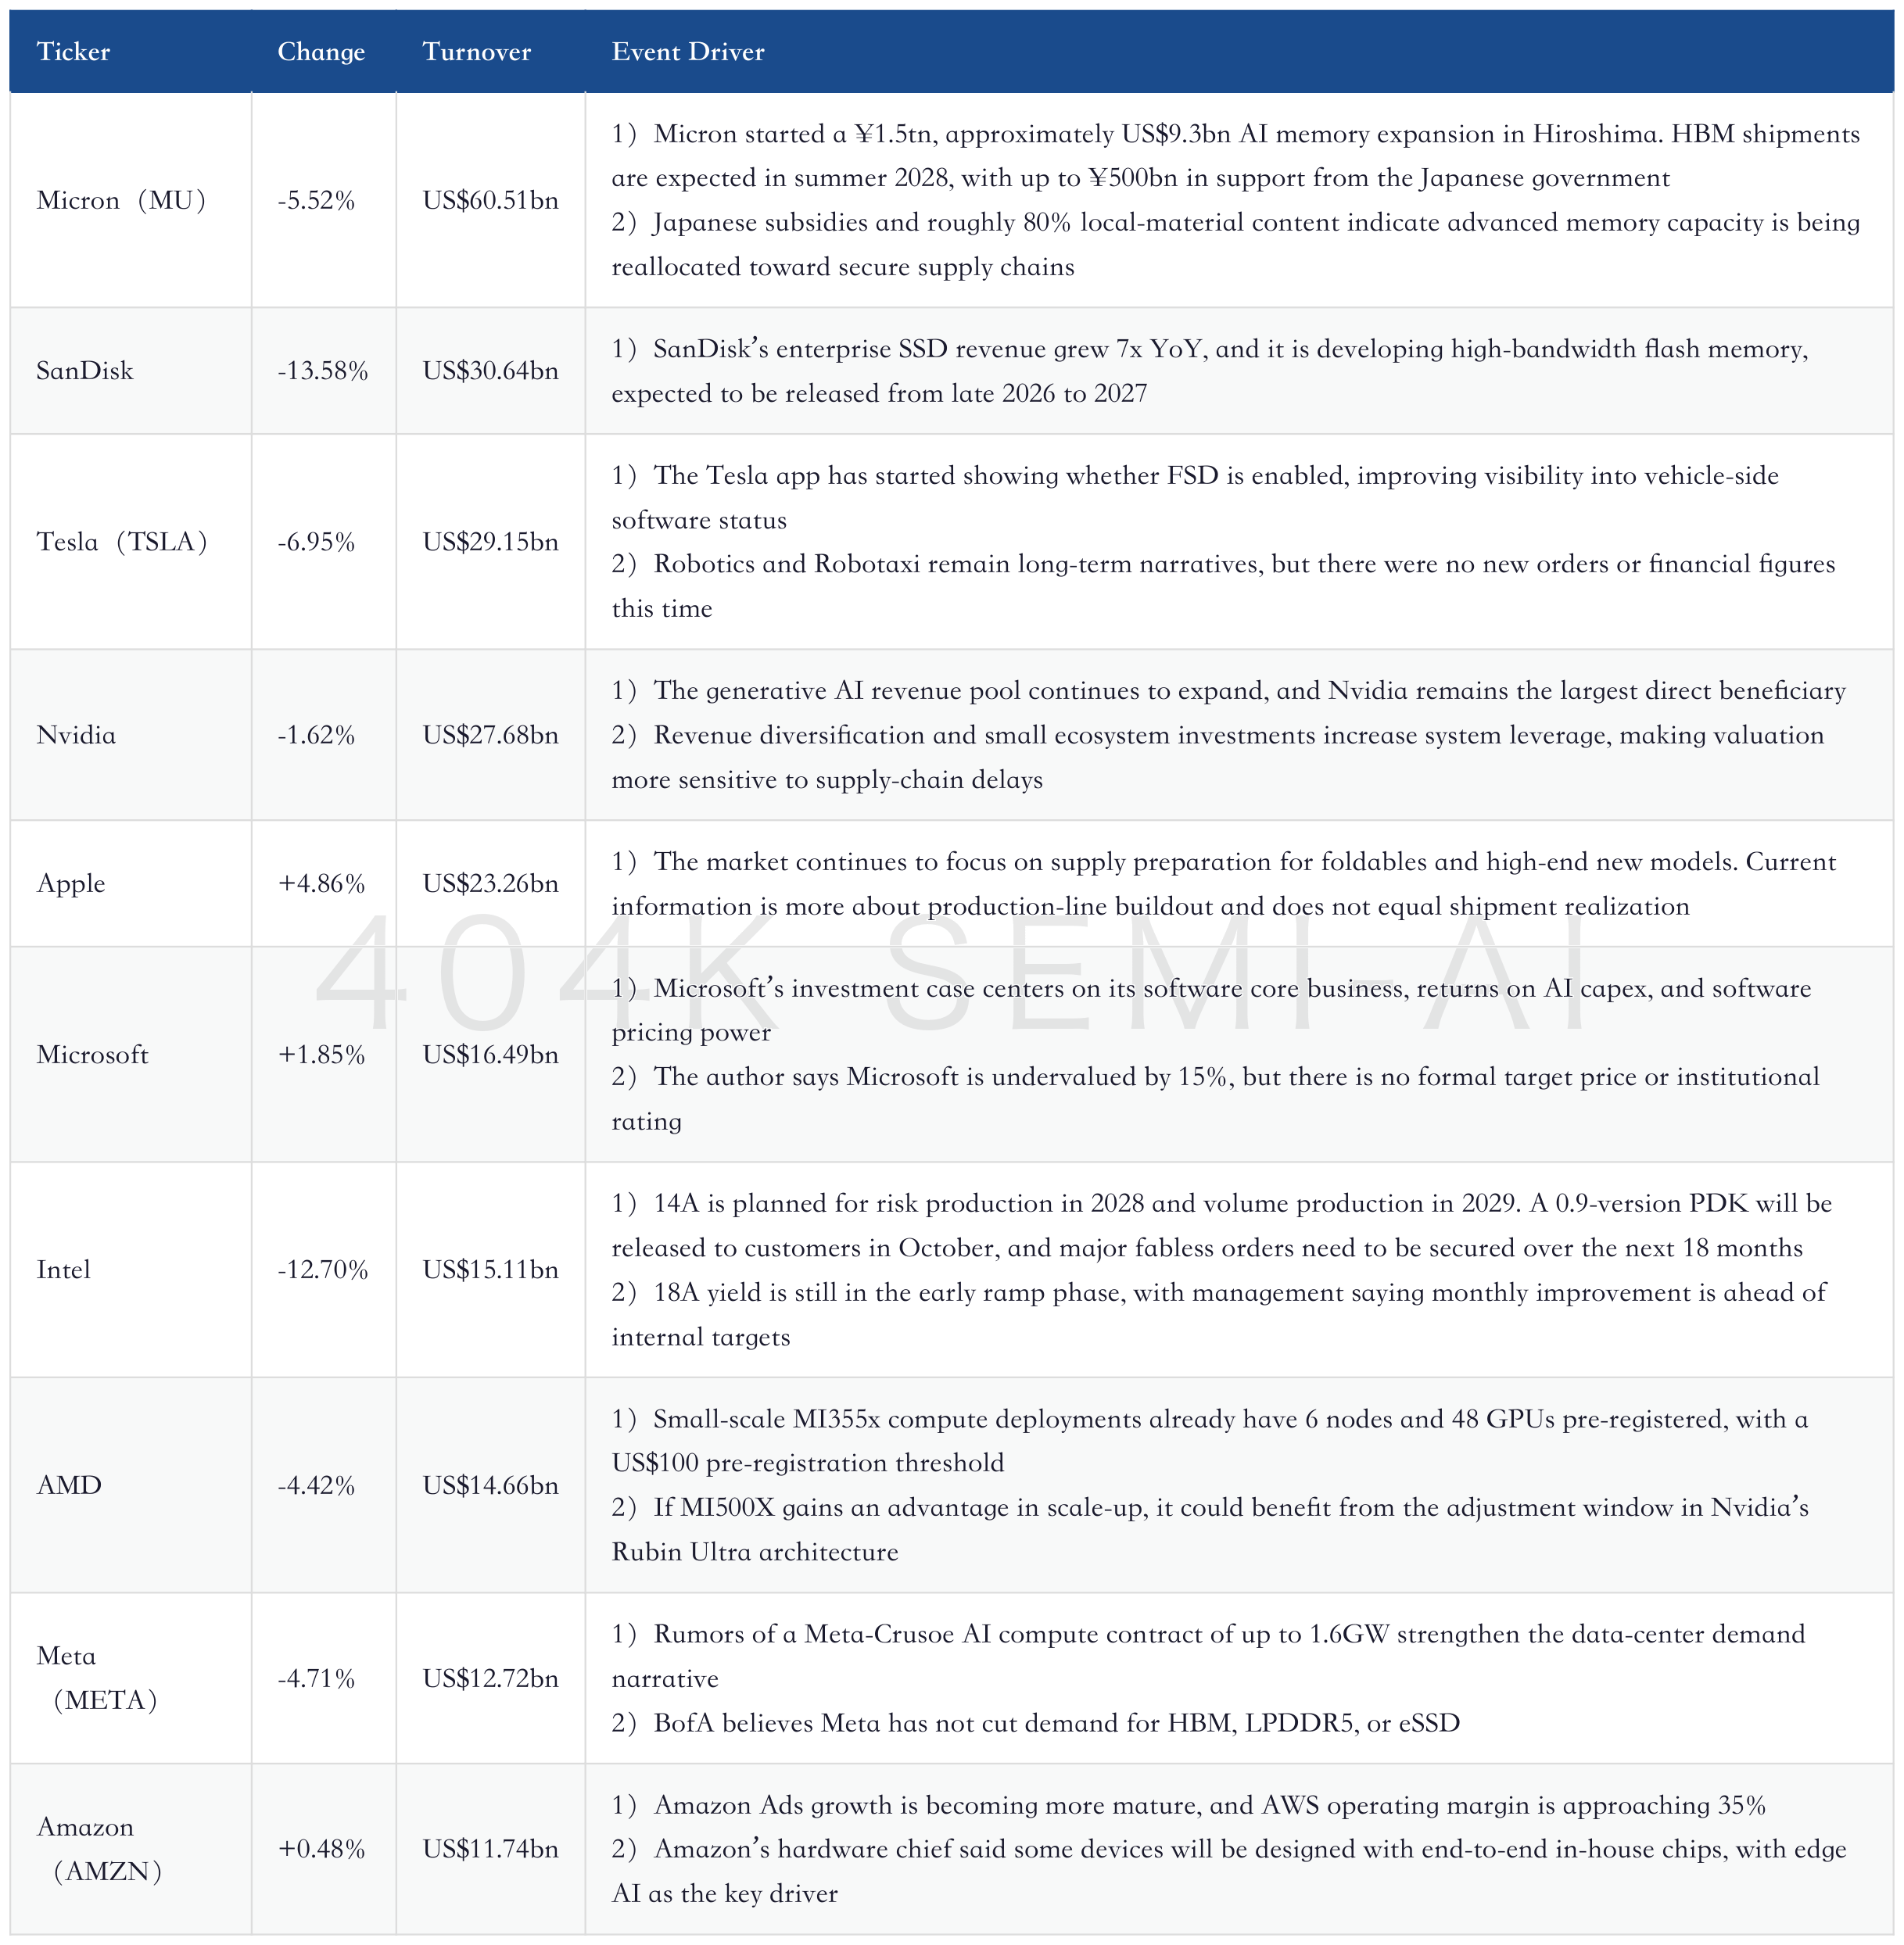
Top 10 U.S. Stocks by Turnover
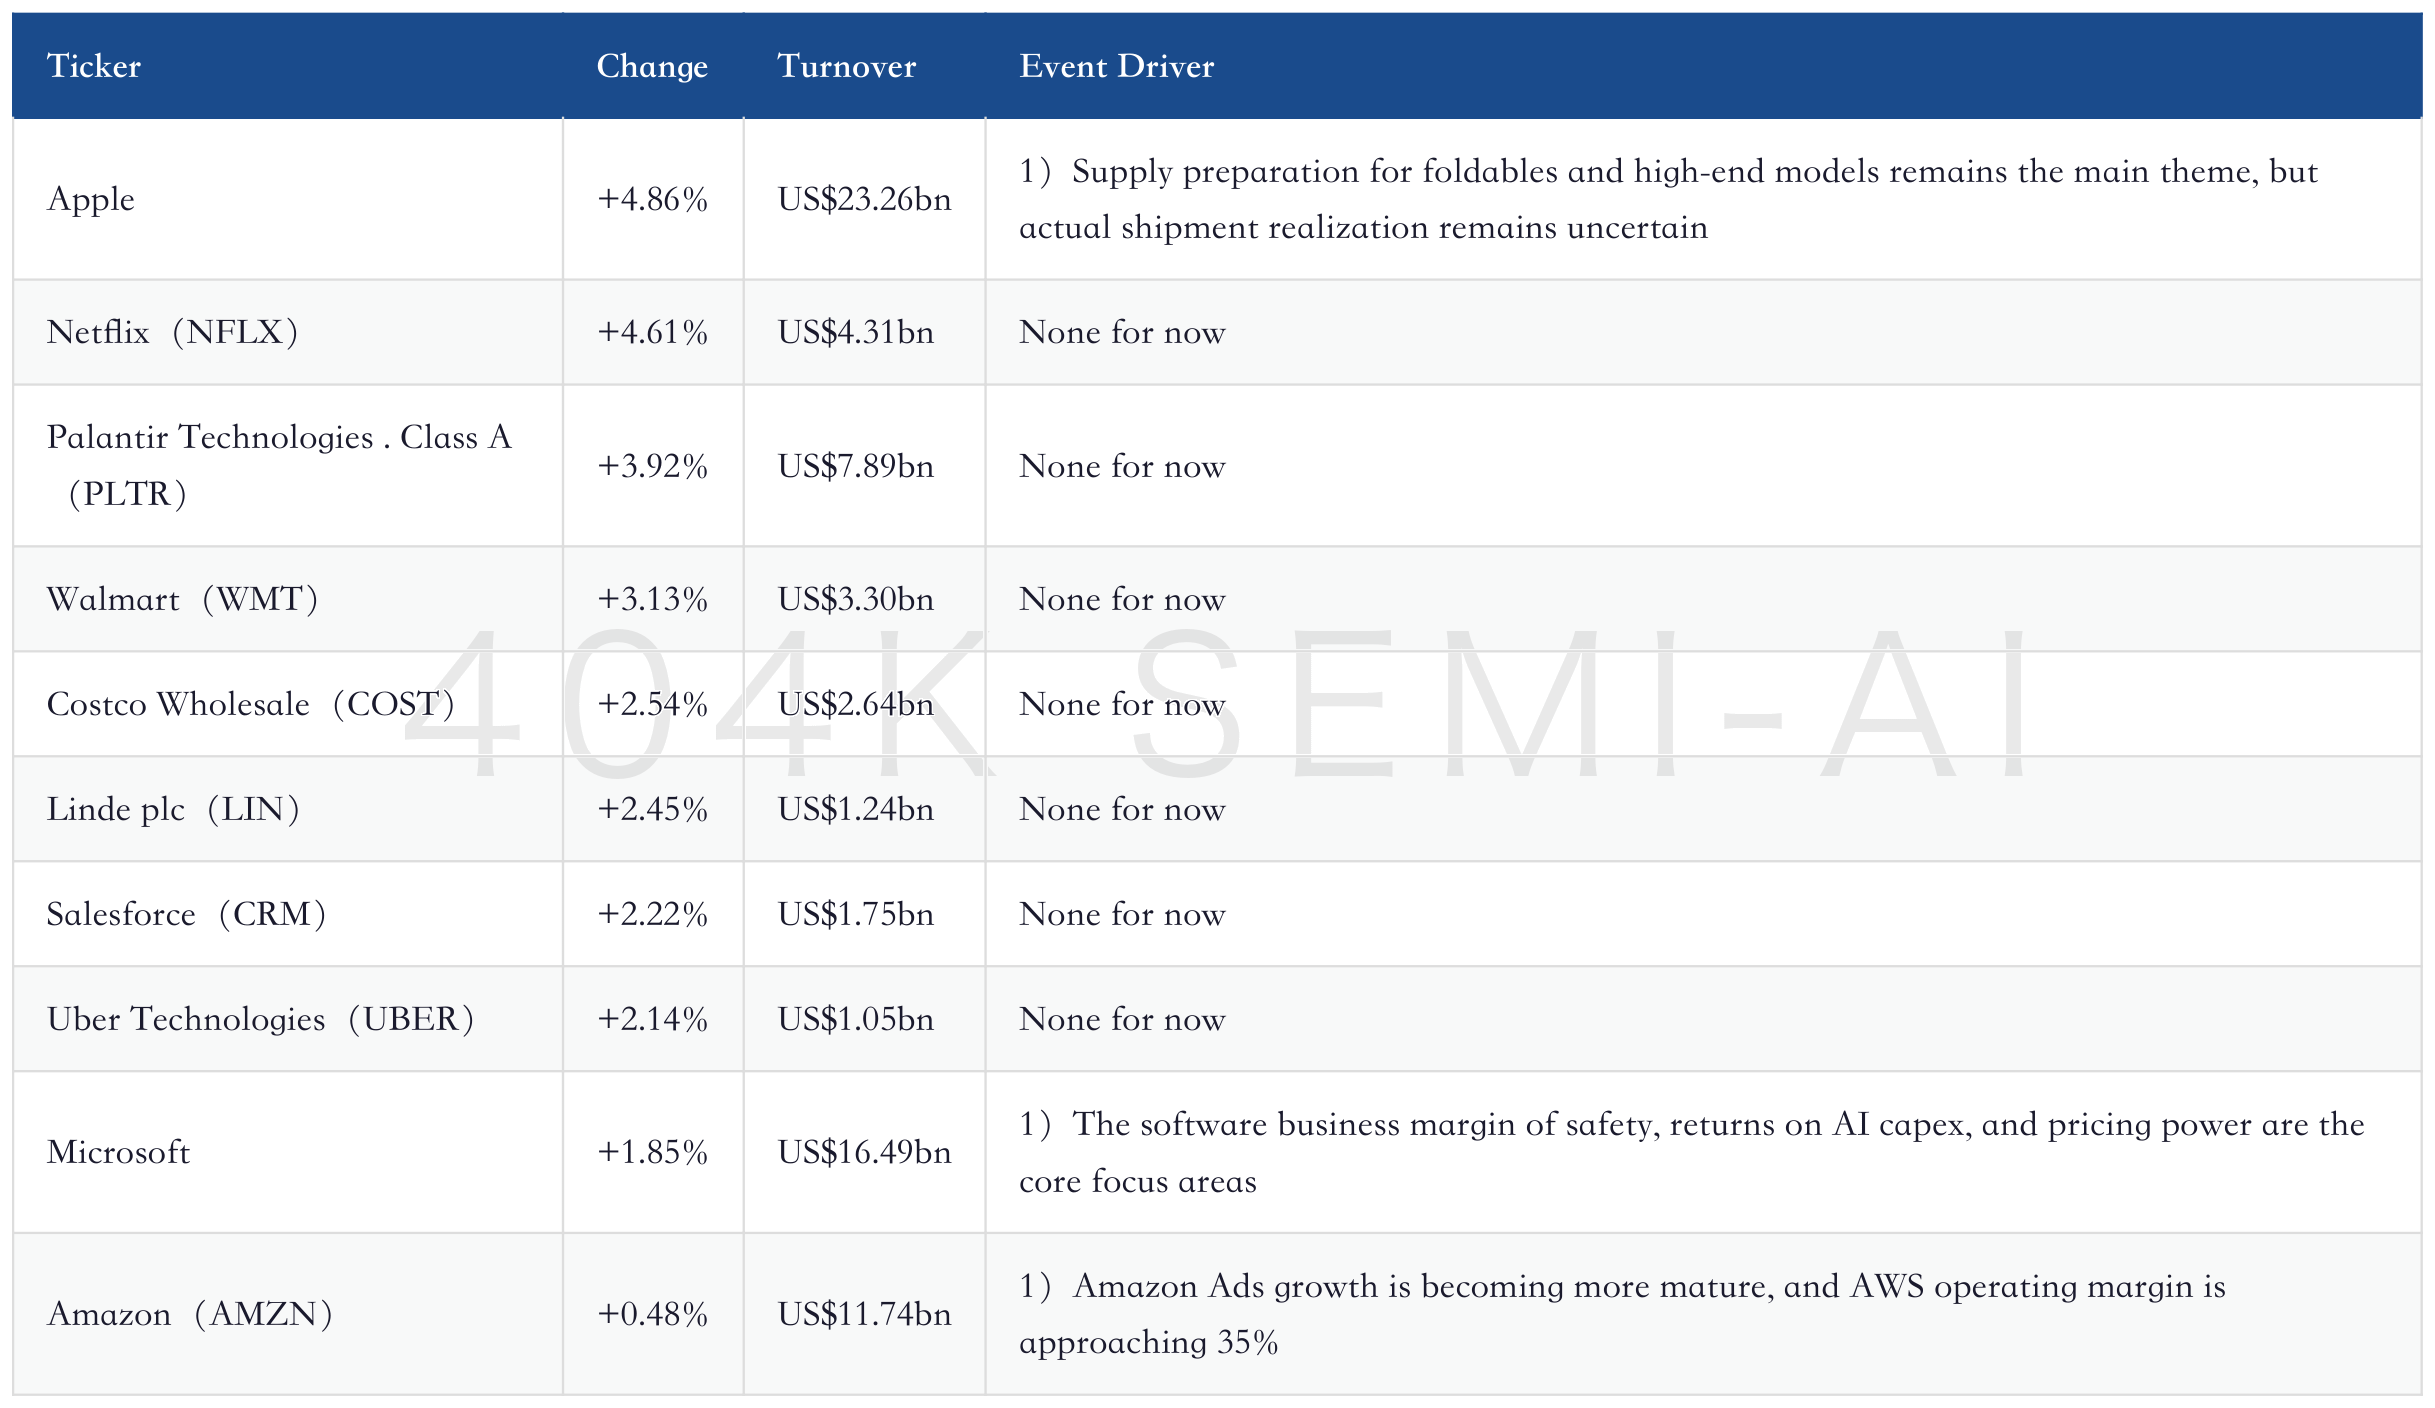
U.S. Stock Gainers
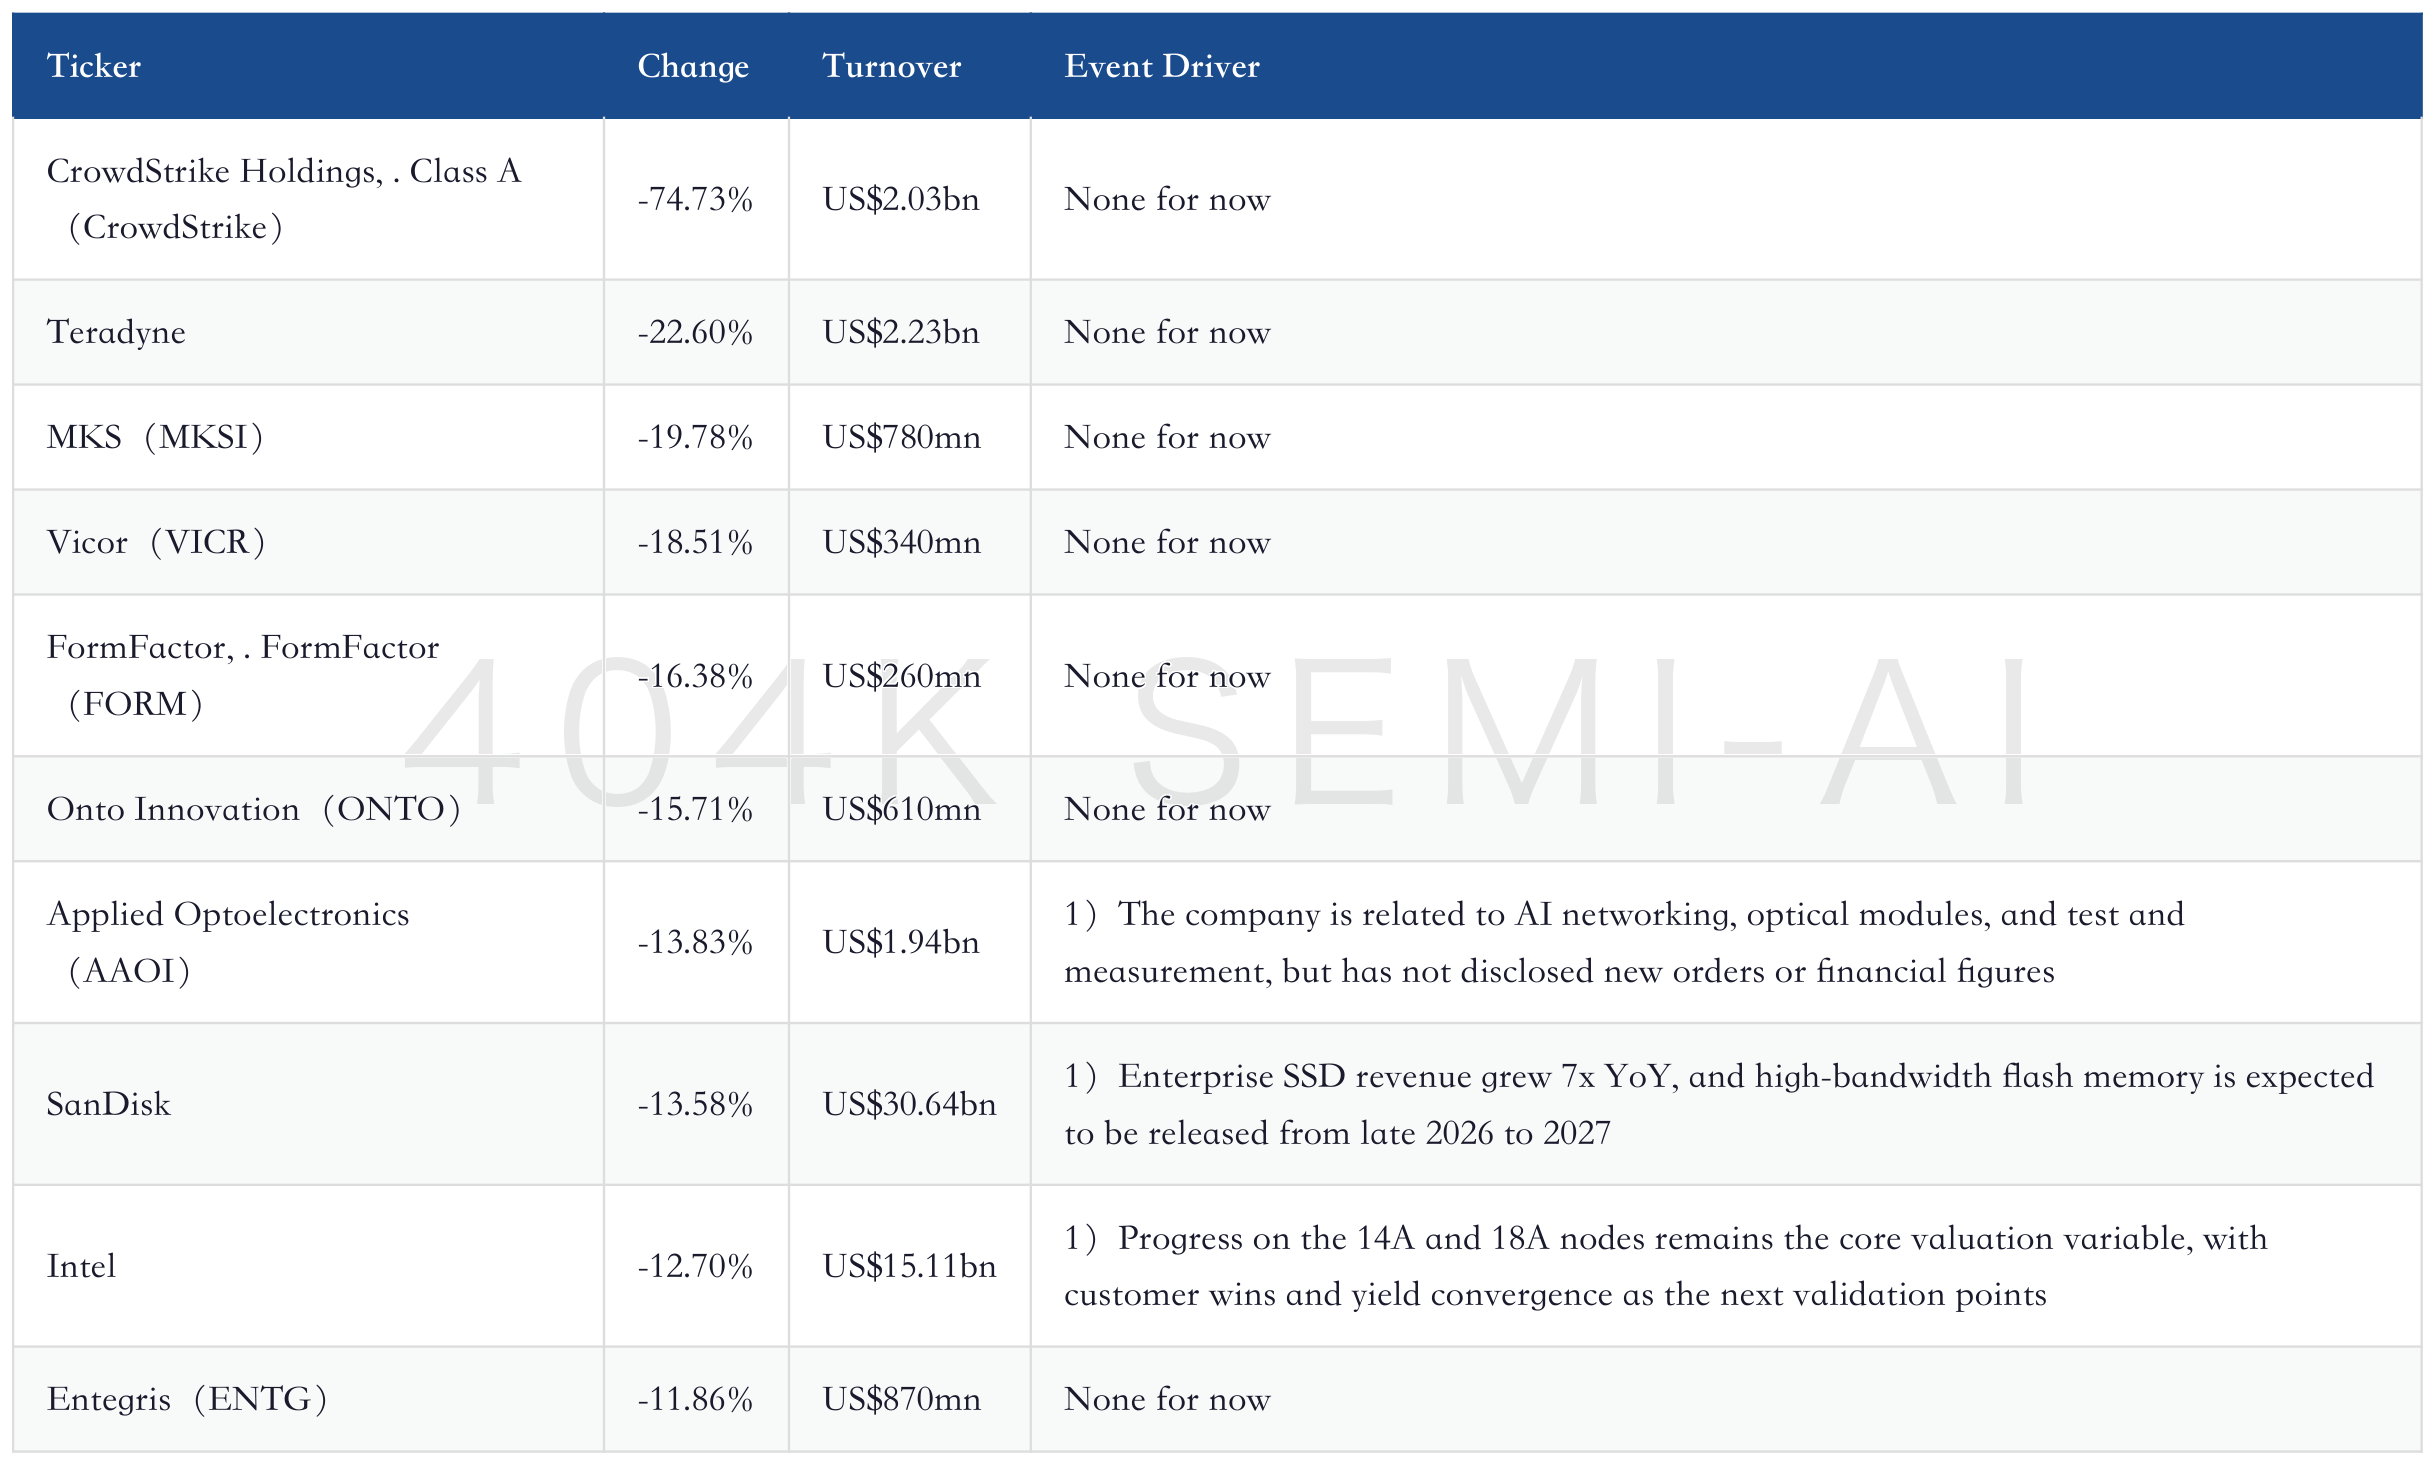
U.S. Stock Decliners
AI/Semiconductor Full Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Wafer Foundry
Semiconductor Equipment/Testing
MLCC/Passive Components and ABF
Power Semiconductors/Thermal and Power
Optical Communications / Optics Chain
Robotics / Intelligent Driving and Space Satellites
Internet / Platforms
Software / SaaS
Consumer Electronics / Smart Vehicles
Investment Bank Target Price Changes in the Past 12 Hours
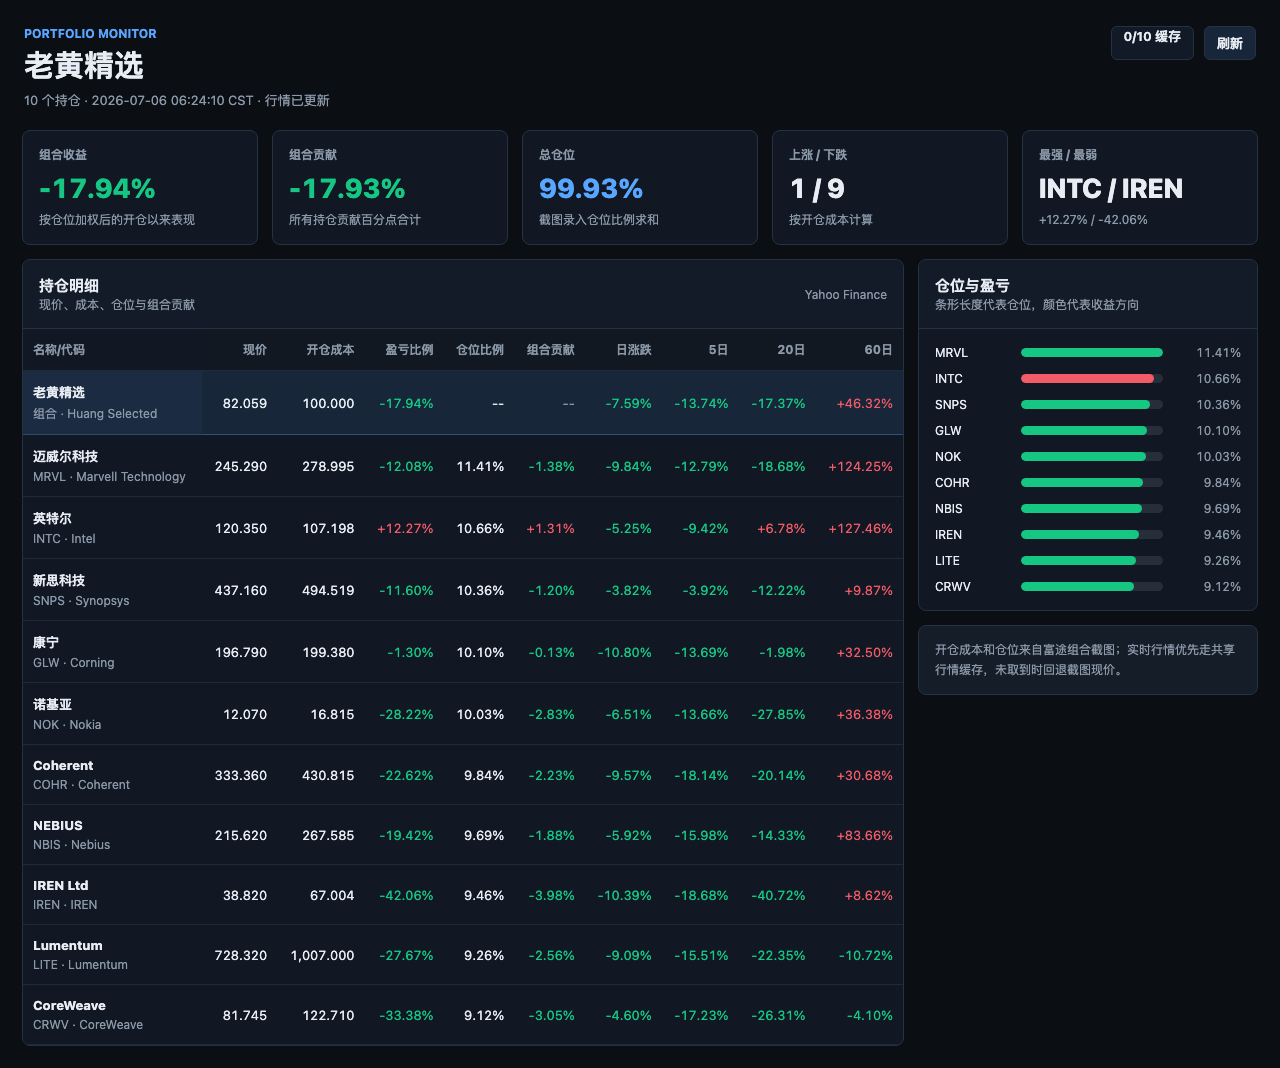
Jensen Huang Portfolio
The AI infrastructure trade has entered the supply-chain gap-filling phase. U.S. tech and semiconductors pulled back in the latest session, but capital has not left the AI theme. Instead, it is spreading from GPUs into memory, MLCCs, ABF substrates, power, electricity, silicon photonics, and data-center operators.
After-Market Summary
The latest U.S. trading session was 2026-07-02, with the tech complex selling off first. The Nasdaq 100 fell 1.73%, the technology ETF fell 2.71%, the semiconductor ETF fell 4.54%, and the equal-weight semiconductor reference fell 5.57%. The equal-weight S&P; 500 rose 0.70%, while the Dow rose 1.05%, indicating that the pullback was concentrated in mega-cap tech and the semiconductor chain.
By style, software was more resilient than hardware. The software ETF rose 0.25%, cloud computing fell 1.06%, cybersecurity fell 0.48%, while AI and big data fell 2.80%. On 20-day relative strength, software and cloud remain below prior highs, but 5-day relative strength has started to repair. Semiconductors ranked near the back on 5-day relative strength, as crowded short-term positioning was amplified by profit-taking in memory and equipment chains.
At the single-stock level, Apple rose 4.86% and Microsoft rose 1.85%, while Nvidia fell 1.62%, AMD fell 4.42%, Intel fell 12.70%, Micron fell 5.52%, and SanDisk fell 13.58%. The market’s signal is direct: the AI demand narrative remains intact, but investors are first cutting valuation and crowded exposure, then rotating back into segments that can genuinely raise prices, secure power, and deliver.
Top 10 U.S. Stocks by Turnover
U.S. Stock Gainers
U.S. Stock Decliners
AI/Semiconductor Full Value Chain
AI Models/Applications and Capital Expenditure
AI Application Deployment
1) Enterprise AI value validation is starting to shift from consumer-facing chat tools to mission-critical workflows. The material notes that the top 20% of early AI-adopting enterprises can already quantify value at the organizational level, especially in security, internal processes, and dedicated model services.
2) The investment implication is that frontier model labs’ revenue is not limited to general-purpose APIs. Enterprise security and private models may form a more stable budget pool, but renewal rates and actual procurement scale remain unproven.
"top 20% of early adopting enterprises;value is quantified at scale across the organization;mission critical functions"
Anthropic
1) Anthropic is seeking 1.4 GW of data-center capacity in Australia. Reported build-out scale varies between US$15 billion and US$21.6 billion, with around 1 GW targeted to come online by end-2027 and potentially split into 4-5 contracts.
2) This shows that model companies are not competing for a single GPU, but for power, sites, and delivery timelines. The differentiation among CDC, AirTrunk, NextDC, IREN, and other providers is who can deliver power on schedule.
OpenAI/Anthropic Duopoly
1) Concentration at the model layer continues to rise. The material says OpenAI and Anthropic together control 88% of enterprise LLM spending. Anthropic’s ARR exceeded US$45 billion in May 2026, while OpenAI’s ARR over the same period was around US$24 billion-US$33 billion.
2) The risk is that application companies hand their workflows and product roadmaps to the same group of frontier models, giving the upstream model layer pricing power while weakening downstream product differentiation.
"Anthropic and OpenAI now control 88% of enterprise LLM spend"
CSP/Cloud Capital Expenditure
Google
1) Google’s AI logic is to run Gemini on in-house TPUs and reduce cost per token. The material says profit could rise from about US$170 billion to US$247 billion by 2028. The key question is who can control unit inference cost when compute is scarce.
2) This line benefits TPUs, HBM, advanced packaging, and the data-center supply chain, but the risk is that cloud revenue growth and advertising monetization must keep pace with capital expenditure.
Meta
1) Meta is repeatedly used as counterevidence that AI demand has not disappeared. On one hand, the market worries that it may sell excess compute capacity; on the other, there are claims of up to 1.6 GW of AI compute contracts and stronger long-term demand for HBM, LPDDR5, and eSSD.
2) For memory and data-center companies, Meta’s actual orders matter more than headlines. The next points to watch are capex guidance and long-term supplier agreements.
Microsoft
1) Microsoft’s latest trading logic centers on its software core, returns on AI capital expenditure, and pricing mechanisms. The material says Microsoft’s “software business is safe,” AI capex will turn ROI-positive, and the company is 15% undervalued.
2) This is not a formal rating or target price, but it shows the market is shifting from “Microsoft is spending too much” to “Can Copilot, Azure, and software bundling raise revenue per customer?”
"Its software business is safe. AI capex will turn ROI positive. Changes in software pricing will drive growth."
Amazon
1) Amazon benefits from AWS while also designing in-house chips at the device end. Its hardware chief said some devices will move toward end-to-end chip design, while the company will continue sourcing from external suppliers such as Qualcomm.
2) If edge AI enters hardware such as Echo and Fire TV, Amazon’s chip agenda will expand from cost control to model experience and local inference.
Total Cloud Capital Expenditure
1) AI capital expenditure by Google, Amazon, Meta, Microsoft, and Oracle is expected to exceed US$800 billion in 2026 and rise to US$1.1 trillion in 2027, equivalent to about 3.2% of U.S. GDP.
2) The investment implication is direct: GPUs are only the first layer. Memory, servers, power, lease commitments, cooling, and interconnect are all consuming this budget.
AI Cloud/Data-Center Operators
Nebius
1) Nebius is viewed as one of the few neocloud companies with power, customers, and a software layer at the same time. The material shows Q1 2026 revenue of US$399 million, up 684% YoY, year-end annualized revenue guidance of US$7 billion-US$9 billion, contracted power of 3.5 GW, and a year-end target of more than 4 GW.
2) The company’s contracts with Meta and Microsoft exceed US$46 billion and run through 2031. The risk is that a capital-intensive model turns financing capacity and delivery cadence into the core of valuation.
"Most neoclouds have none of those three things simultaneously but Nebius has all of them"
CoreWeave
1) CoreWeave has pulled back more than 50% from its high, but backlog remains close to US$100 billion and revenue is still growing more than 100% YoY.
2) The company represents the neocloud debate: contracts and revenue are very strong, but debt, losses, and hyperscalers’ self-built clouds suppress valuation tolerance.
IREN
1) The debate around IREN is “MW assets” versus “platform capability.” The material says it will approach 1 GW of operating or completed capacity by end-2026, including 160 MW in Canada and 750 MW at Childress, while the 1.4 GW Sweetwater 1 standalone site was energized on May 28, 2026.
2) Nvidia has announced an initial 60 MW deployment, but a partnership with Anthropic remains unconfirmed speculation. What the share price needs to validate is whether power assets can convert into contracted AI cloud revenue.
TeraWulf, Cipher Mining, Applied Digital, Galaxy Digital
1) These companies are all on the list of AI data-center operators, but the strength of hard evidence varies in this round. The main line that can be included is data centers, power capacity, AI compute hosting, financing, and customer contracts; a stock should not be included merely because it appeared.
2) Follow-up tracking should focus on power interconnection, customer credit quality, GPU financing, and take-or-pay contracts, not one-day share-price moves.
GPU/CPU/ASIC
Nvidia
1) Nvidia remains the largest beneficiary of AI factory budgets. The material says a 1 GW AI factory based on Nvidia architecture could cost close to US$100 billion, with roughly half flowing to Nvidia chips, systems, and software.
2) The risk is also beginning to shift from demand to architecture execution: Kyber NVL144 has been delayed by more than 12 months to 2028, the NVL72x2 back-to-back solution has been canceled, and Rubin Ultra’s scale-up world size is constrained.
"1GW AI factory... could now cost nearly 100 billion dollars"
Intel
1) Intel 18A yield is still in the early ramp phase, but company commentary indicates improvement is faster than internal targets. Management has cited monthly yield improvements of 7% or 8%. 14A is planned for risk production in 2028 and mass production in 2029, with the 0.9 PDK to be released in October.
2) The business question for this line is whether Intel can lock in major fabless customers over the next 18 months. If not, the advanced foundry story will continue to be overshadowed by TSMC A14 and Samsung SF2Z.
Broadcom
1) Broadcom’s latest quarterly AI revenue grew 106% YoY to US$8.4 billion, driven by custom accelerators and AI networking chips for Google, Meta, and Anthropic.
2) At the same time, the market questions whether the company is “chips only” and lacks the narrative of full AI system integration. Future valuation depends on ASIC customer expansion and networking-chip volume growth.
AMD
1) AMD’s opportunity comes from early feedback on small-scale MI355x deployments and MI500X’s potential competition in the Rubin Ultra scale-up window. The material shows MI355x pre-registration has reached 6 nodes and 48 GPUs, with a US$100 threshold for each pre-registration.
2) This is not a formal order, but it shows independent compute deployers are starting to queue for AMD GPUs. The next validation points are MI450/MI500 mass production, customer financing, and software-stack stability.
HBM/DRAM/NAND/SSD/HDD
Micron
1) Micron has started a JPY1.5 trillion, or roughly US$9.3 billion, AI memory expansion in Hiroshima to produce HBM, with shipments expected in summer 2028. The Japanese government will provide up to JPY500 billion in support, with total support of about JPY775 billion.
2) The near-term supply impact is limited, but this reinforces Micron’s medium- to long-term capacity position in HBM. The recent share-price pullback is more about crowding and profit-taking after memory stocks reached elevated levels.
"The new facility will produce high-bandwidth memory for AI processors"
Samsung Electronics, SK Hynix
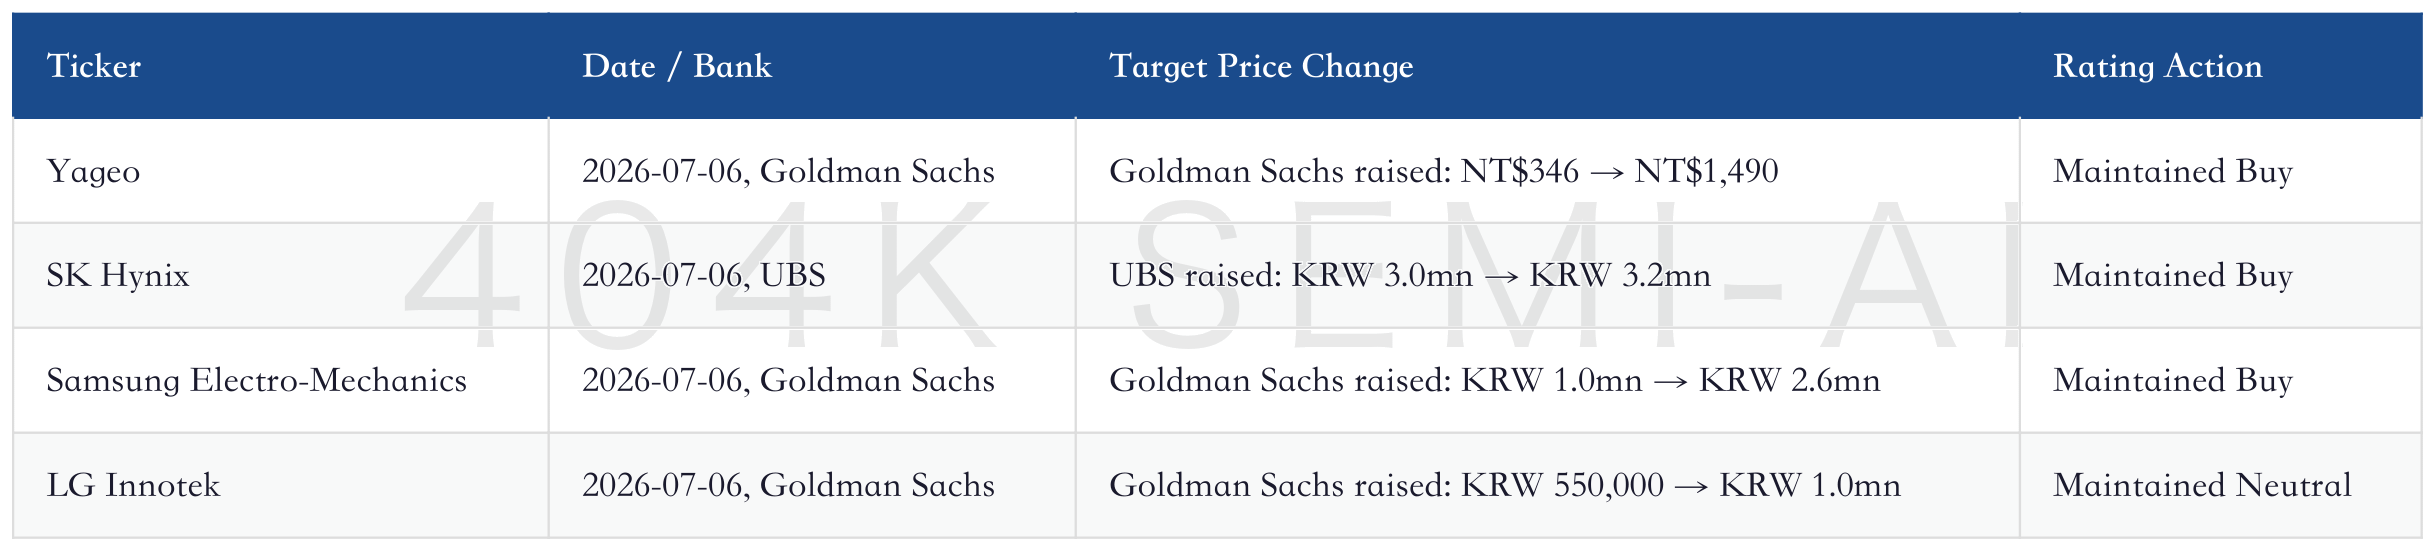
1) UBS raised its DDR contract price forecasts to +32% QoQ in Q3 2026 and +18% QoQ in Q4, and NAND to +30% QoQ in Q3 and +12% QoQ in Q4. The report judges that DRAM will remain in shortage at least until Q2 2028.
2) SK Hynix is also rumored to be planning a Nasdaq listing, with the logic of using the U.S. equity market to reprice HBM, DRAM, and flash demand. But single-stock leveraged ETFs in Korea amplify volatility, so short-term prices cannot all be treated as fundamentals.
SanDisk, Kioxia
1) BofA believes South Korea’s KRW800 trillion memory cluster will not generate effective capacity quickly, while NAND shortages and enterprise SSD demand remain strong. SanDisk’s enterprise SSD revenue grew 7x YoY, and the company is developing high-bandwidth flash, expected to launch later in 2026 to 2027.
2) The core for Kioxia and SanDisk is the NAND pricing cycle and eSSD supply-demand, not traditional consumer flash. The risk is whether downstream procurement can continue to absorb compounded price increases.
China Memory Chain
1) Lenovo’s global configuration of the ThinkBook 14 G9 has started using Yangtze Memory SSDs, while ChangXin Memory is testing a bonded DRAM pilot line in Hefei, attempting to use DUV multi-patterning to bypass EUV.
2) Neither line has yet reached large-scale mass production or order delivery, but they show China’s memory substitution progressing simultaneously from PC SSDs and DRAM process routes.
Wafer Foundry
TSMC
1) TSMC has about 70% share of global advanced wafer foundry, and Nvidia and Apple alone contribute roughly 40% of revenue. At 2025 IEEE ECTC, the company introduced SoW-X, pointing to wafer-level system integration to address reticle-size, I/O bandwidth, and thermal-management bottlenecks.
2) Advanced process nodes and advanced packaging are merging into a system capability. TSMC’s risk is not demand, but geopolitics, energy, and customer concentration.
"SoW-X redefines how logic and memory interact at scale"
Semiconductor Equipment/Testing
Equipment Chain
1) Samsung and SK Hynix are evaluating alternatives to Mattson for PR strip and RTP equipment. Supply-chain diversification benefits Applied Materials, ASML, Lam Research, Tokyo Electron, KLA, and Korean equipment vendors.
2) SEAJ raised its FY2026 Japan semiconductor equipment sales outlook to JPY6.55 trillion, with FY2027 at JPY7.4 trillion and FY2028 at JPY7.77 trillion. The equipment cycle is supported by advanced logic and DRAM capacity expansion.
FormFactor, Teradyne, Advantest
1) FormFactor’s Q1 2026 revenue was US$226 million, up 32% YoY, with non-GAAP EPS of US$0.56, above expectations of US$0.44. Through Keystone Photonics, it is partnering with Advantest to enter silicon photonics wafer-level testing.
2) As CPO, silicon photonics, and high-speed electro-optical testing become more complex, equipment value will expand from traditional electrical testing to coordinated optical-electrical validation.
MLCC/Passive Components and ABF
Yageo
1) Goldman Sachs maintained a Buy rating and raised its 12-month target price from NT$346 to NT$1,490. The report argues that migration of AI-grade MLCC capacity will squeeze general-purpose MLCC supply, with global non-AI MLCC utilization returning to 97%/100% in 2027/2028.
2) Yageo’s general-purpose MLCC prices are expected to rise 29%/93%/84% YoY in 2026/2027/2028, a typical case of AI infrastructure spilling over into ordinary passive components.
"more and more MLCC capacity is being transferred into the AI grade MLCC supply chain"
Samsung Electro-Mechanics, LG Innotek
1) Goldman Sachs raised its target price for Samsung Electro-Mechanics from KRW1.0 million to KRW2.6 million and maintained a Buy rating. AI MLCC revenue is expected to grow 6.4x from 2025 to 2028 and account for 28% of MLCC revenue in 2028.
2) LG Innotek’s target price was raised from KRW550,000 to KRW1.0 million, with a Neutral rating maintained. ABF revenue is expected to rise from KRW50 billion in 2025 to KRW700 billion in 2028, but still account for only 2.5% of total revenue.
ABF/Fiberglass Materials
1) Industrywide new capacity for high-end ABF substrates will remain limited before 2H 2027. Higher power consumption, larger packages, and faster interconnects in AI servers are raising layer counts and material requirements.
2) Nittobo has about 90% global share in low-CTE T-glass and 60%-70% share in low-Dk NER-glass. China’s Guangyuan New Materials is investing US$1 billion to challenge this position, but certification cycles remain the moat.
Power Semiconductors/Thermal and Power
Texas Instruments, Infineon, STMicroelectronics
1) Power semiconductors have already started raising prices before the arrival of 1 MW racks. Infineon has raised prices by 10%-25%, Texas Instruments raised prices again on PMICs and MOSFETs on July 1, and STMicroelectronics has implemented a second round of price increases for some products.
2) The reason is that Vera Rubin is about 225 kW per rack, while Rubin Ultra is about 600 kW or more. VRM phases, MOSFETs, drivers, controllers, capacitors, and inductors all need to scale up.
onsemi and the OSAT Supply Chain
1. Greatek plans to acquire equity in a Philippine assembly and test services company from onsemi Japan Holdings for no more than US$45 million; after closing, the company is expected to be renamed Greatek Electronics Philippines Corporation.
2. This is not a positive signal for onsemi orders. It reflects OSAT supply-chain diversification into Southeast Asia in response to customer requirements for Taiwan PCB and substrate +1 sourcing and global delivery resilience.
Thermal Components
1. MinebeaMitsumi plans to invest JPY58 billion to expand precision bearing capacity, lifting monthly capacity to more than 500 million units; the company has more than 60% global share in miniature bearings below 22mm.
2. As AI server power consumption rises, liquid cooling will not eliminate air-side components. Fan motors, bearings, and rear-door heat-exchange systems should still benefit.
Optical Communications / Optics Chain
CPO / Silicon Photonics Chain
1. Broadcom covers PIC design, laser sources, photodiodes, and EICs; Marvell Technology is the DSP engine for optical modules; MACOM is positioned in 1.6T/3.2T optical transceivers; Keysight, FormFactor, Teradyne, and EXFO benefit from rising test complexity.
2. Foxconn Industrial Internet reported Q1 2026 revenue of US$66.6 billion, up 29.7% YoY; AI servers accounted for more than 50% of server revenue. CPO switches are expected to enter mass production in Q3 2026, with full-year shipments forecast at 10,000 units.
"Every AI data center being built depends on what's in that chart"
Fiber Cables and Materials
1. Optical interconnects are not only about optical modules. Fiber, optical materials, testing, and server assembly are all benefiting. Cable and fiber-material companies such as Furukawa Electric, Fujikura, and Sumitomo Electric should be included in the optical communications chain, rather than viewed separately as a Japan materials theme.
2. The near-term items to verify are the order cadence for 1.6T/3.2T optical modules, CPO switches, DSPs, and silicon-photonics test equipment.
Robotics / Intelligent Driving and Space Satellites
Robotics Components
1. VPG Q1 revenue was US$84.35 million, up 17.6% YoY; orders were US$102.08 million, with a book-to-bill of 1.21. However, humanoid robot orders were only US$1 million, slightly above 1% of the total.
2. This line shows that tactile sensors and safety certification are real bottlenecks, but the stock once traded near 270x P/E. The long-term robotics TAM cannot be capitalized all at once as current-period earnings.
Agility / Robotics Commercialization
1. Agility plans to list via SPAC, with roughly US$640 million in private financing. About 100 Digit units have already been deployed, unfilled orders exceed US$300 million, and the annual capacity target is above 10,000 units.
2. Deployments by Amazon, GXO, Schaeffler, Toyota, MELI, and other customers show that logistics is moving first, but safety certification, real payback periods, and full-system cost remain key.
Tesla and Starlink
1. The Tesla app has started to show whether FSD is enabled, improving vehicle-side software visibility. Future Robotaxi services may require similar remote status monitoring.
2. Starlink antennas are testing emergency Wi-Fi in Japan, with 120,000 fire-hydrant markers nationwide. LEO communications are expanding from home broadband into public safety and disaster-recovery networks.
Internet / Platforms
Amazon
1. Amazon is simultaneously carrying three lines: platform, advertising, and cloud capex. The advertising business is more mature, while AWS continues to support group investment with an operating margin near 35%; in-house chips for edge hardware move the device ecosystem into the AI cost-control phase.
2. The risk is that in-house chips do not mean a full exit from external suppliers such as Qualcomm. In the near term, the key is whether products such as Alexa, Echo, and Fire TV can convert local inference into experiences users are willing to pay for.
Meta
1. The market debate around Meta comes from the intensity of AI investment, not the disappearance of the advertising core. Materials suggest it may still increase AI infrastructure spending and continue locking in HBM, LPDDR5, and eSSD.
2. If a self-built AI cloud delivers cost advantages, external clouds such as CoreWeave will come under pressure. If self-build is insufficient to cover demand, neoclouds and data-center landlords will still have contract opportunities.
Reddit, AppLovin, Unity Software
1. AI ad optimization continues to spread across internet platforms. After restructuring, Unity Software revenue grew 17% YoY, with its Grow advertising business up about 50% YoY; AppLovin revenue grew 59% YoY; Reddit advertising revenue grew 74% YoY.
2. The key in this line is not the two letters “AI,” but whether ad-conversion rates, store count, data assets, and model distribution capabilities can continue to raise the revenue slope.
Netflix, Uber, DoorDash, Airbnb
1. These platforms appear in the opening ranking mainly as market facts, with limited new hard evidence tied to AI or the semiconductor core theme.
2. The focus here is marginal change in platform business models: streaming, local services, and travel platforms remain gauges of consumer-internet risk appetite, but they do not drive this issue of the tech morning note.
Software / SaaS
Microsoft
1. The software base and AI pricing power are Microsoft’s clearest main lines. Materials state that the “software business is safe” and argue that AI capex will turn toward positive ROI.
2. For investors, the follow-through should be Copilot penetration, Azure AI revenue, enterprise contract renewals, and bundled price increases, rather than only the absolute level of capex.
Palantir
1. The SaaS valuation comparison shows Palantir with expected NTM revenue growth of 63.5% and EV/gross profit of 67.8x, placing it in the most expensive tier of the software group.
2. Its premium comes from AI data platforms and deployment into government and enterprise workflows, but the risk is also clear: high growth must be accompanied by delivery on gross margin, operating margin, retention, and free cash flow.
"SaaS valuation: growth alone is not enough"
Snowflake, Datadog, Cloudflare
1. The software-budget discussion is shifting from pure revenue growth to growth quality. Snowflake, Datadog, and Cloudflare all benefit from data, observability, and edge cloud, but valuations need to be assessed together with gross margin, operating margin, renewal rates, and retention.
2. The software group’s relative resilience versus semiconductors shows that capital is willing in the near term to look for AI applications and infrastructure software with lighter cash-flow demands, but there were no new hard target-price actions.
Figma and Model-Application Competition
1. The timing of Anthropic’s Claude Design launch has been used to discuss competition with Figma’s core product. Materials state that Figma’s share price fell 7% on launch day, was down about 80% from its historical high, and erased nearly US$50 billion in market value.
2. The core risk is that once frontier models enter vertical applications, the product moats of incumbent SaaS vendors will be compressed. But model companies themselves also need to prove they can turn features into high-retention paid products.
Generative AI Website Traffic
1. The traffic data only provides YoY growth by marketing channel for the top five generative AI websites as of May 2026 and Fable 5 search trends over the past 28 days; it does not disclose specific growth rates.
2. This type of data is useful for tracking application momentum, but it cannot be directly extrapolated to revenue and valuation.
Consumer Electronics / Smart Vehicles
Apple
1. Apple rose 4.86% on the latest close, outperforming most large-cap technology stocks. Supply-chain information points to “looks okay” completion progress for foldable-screen and high-end new-device buildout, but actual shipments may be below external expectations.
2. Memory price increases will pressure iPhone, Mac, and iPad costs; the materials also note that memory accounts for about 40% of the BOM in high-end smartphones, which will test Apple’s pricing power.
Consumer Electronics Memory Costs
1. After AI data centers absorbed HBM, server DRAM, and eSSD supply, smartphones and PCs are beginning to come under pressure. IDC expects global smartphone shipments to decline nearly 13%, with ASP rising to USD 523; higher memory prices are being transmitted to end hardware.
2. This benefits memory vendors, but creates dual pressure on consumer electronics brands through gross margins and volumes.
Tesla
1. Tesla fell 6.95% in the short term, but the useful information in this material concerns FSD status display and the longer-term Robotaxi scenario.
2. Prices for Chinese humanoid robots are also moving lower: Unitree R1 is priced at RMB 26,900, Booster K1 at RMB 29,900, and Noetix Bumi at RMB 9,998; lower costs will accelerate application pilots while compressing finished-system premiums.
Robotics Supply Chain
1. China shipped 14,400 humanoid robots in 2025, with 2026 shipments expected at 100,000-200,000 units. Unitree’s average selling price declined from about RMB 593,000 in 2023 to RMB 167,000 by end-2025, while production cost fell from RMB 73,200 to RMB 62,200.
2. The U.S. is strong in foundation models, autonomous driving, and action scaling laws; China is strong in shipments and the cost curve. Supply-chain opportunities are more concentrated in reducers, actuators, sensors, and batteries.
"The United States leads the world in where robotics is heading... while losing the race on where robotics is shipping today."
LG Innotek and Satellite Substrates
1. LG Innotek is seeking to enter the LEO satellite substrate supply chain, but there is no order value or mass-production timeline.
2. This line is suitable for inclusion in space/satellite supply-chain tracking: satellite communications hardware may drive demand for substrates, antennas, optical communications, and LEO ground infrastructure.
Investment Bank Target Price Changes in the Past 12 Hours
Jensen Huang Portfolio
404K SEMI-AI Morning Brief 2026-07-06 — Memory Price Hikes, AI Power Constraints, Passive Components Catch-Up
目录
After-Market Summary
Top 10 U.S. Stocks by Turnover
U.S. Stock Gainers
U.S. Stock Decliners
AI/Semiconductor Full Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Wafer Foundry
Semiconductor Equipment/Testing
MLCC/Passive Components and ABF
Power Semiconductors/Thermal and Power
Optical Communications / Optics Chain
Robotics / Intelligent Driving and Space Satellites
Internet / Platforms
Software / SaaS
Consumer Electronics / Smart Vehicles
Investment Bank Target Price Changes in the Past 12 Hours
Jensen Huang Portfolio
The AI infrastructure trade has entered the supply-chain gap-filling phase. U.S. tech and semiconductors pulled back in the latest session, but capital has not left the AI theme. Instead, it is spreading from GPUs into memory, MLCCs, ABF substrates, power, electricity, silicon photonics, and data-center operators.
After-Market Summary
The latest U.S. trading session was 2026-07-02, with the tech complex selling off first. The Nasdaq 100 fell 1.73%, the technology ETF fell 2.71%, the semiconductor ETF fell 4.54%, and the equal-weight semiconductor reference fell 5.57%. The equal-weight S&P; 500 rose 0.70%, while the Dow rose 1.05%, indicating that the pullback was concentrated in mega-cap tech and the semiconductor chain.
By style, software was more resilient than hardware. The software ETF rose 0.25%, cloud computing fell 1.06%, cybersecurity fell 0.48%, while AI and big data fell 2.80%. On 20-day relative strength, software and cloud remain below prior highs, but 5-day relative strength has started to repair. Semiconductors ranked near the back on 5-day relative strength, as crowded short-term positioning was amplified by profit-taking in memory and equipment chains.
At the single-stock level, Apple rose 4.86% and Microsoft rose 1.85%, while Nvidia fell 1.62%, AMD fell 4.42%, Intel fell 12.70%, Micron fell 5.52%, and SanDisk fell 13.58%. The market’s signal is direct: the AI demand narrative remains intact, but investors are first cutting valuation and crowded exposure, then rotating back into segments that can genuinely raise prices, secure power, and deliver.
Top 10 U.S. Stocks by Turnover
U.S. Stock Gainers
U.S. Stock Decliners
AI/Semiconductor Full Value Chain
AI Models/Applications and Capital Expenditure
AI Application Deployment
1) Enterprise AI value validation is starting to shift from consumer-facing chat tools to mission-critical workflows. The material notes that the top 20% of early AI-adopting enterprises can already quantify value at the organizational level, especially in security, internal processes, and dedicated model services.
2) The investment implication is that frontier model labs’ revenue is not limited to general-purpose APIs. Enterprise security and private models may form a more stable budget pool, but renewal rates and actual procurement scale remain unproven.
“top 20% of early adopting enterprises;value is quantified at scale across the organization;mission critical functions”
Anthropic
1) Anthropic is seeking 1.4 GW of data-center capacity in Australia. Reported build-out scale varies between US$15 billion and US$21.6 billion, with around 1 GW targeted to come online by end-2027 and potentially split into 4-5 contracts.
2) This shows that model companies are not competing for a single GPU, but for power, sites, and delivery timelines. The differentiation among CDC, AirTrunk, NextDC, IREN, and other providers is who can deliver power on schedule.
OpenAI/Anthropic Duopoly
1) Concentration at the model layer continues to rise. The material says OpenAI and Anthropic together control 88% of enterprise LLM spending. Anthropic’s ARR exceeded US$45 billion in May 2026, while OpenAI’s ARR over the same period was around US$24 billion-US$33 billion.
2) The risk is that application companies hand their workflows and product roadmaps to the same group of frontier models, giving the upstream model layer pricing power while weakening downstream product differentiation.
“Anthropic and OpenAI now control 88% of enterprise LLM spend”
CSP/Cloud Capital Expenditure
Google
1) Google’s AI logic is to run Gemini on in-house TPUs and reduce cost per token. The material says profit could rise from about US$170 billion to US$247 billion by 2028. The key question is who can control unit inference cost when compute is scarce.
2) This line benefits TPUs, HBM, advanced packaging, and the data-center supply chain, but the risk is that cloud revenue growth and advertising monetization must keep pace with capital expenditure.
Meta
1) Meta is repeatedly used as counterevidence that AI demand has not disappeared. On one hand, the market worries that it may sell excess compute capacity; on the other, there are claims of up to 1.6 GW of AI compute contracts and stronger long-term demand for HBM, LPDDR5, and eSSD.
2) For memory and data-center companies, Meta’s actual orders matter more than headlines. The next points to watch are capex guidance and long-term supplier agreements.
Microsoft
1) Microsoft’s latest trading logic centers on its software core, returns on AI capital expenditure, and pricing mechanisms. The material says Microsoft’s “software business is safe,” AI capex will turn ROI-positive, and the company is 15% undervalued.
2) This is not a formal rating or target price, but it shows the market is shifting from “Microsoft is spending too much” to “Can Copilot, Azure, and software bundling raise revenue per customer?”
“Its software business is safe. AI capex will turn ROI positive. Changes in software pricing will drive growth.”
Amazon
1) Amazon benefits from AWS while also designing in-house chips at the device end. Its hardware chief said some devices will move toward end-to-end chip design, while the company will continue sourcing from external suppliers such as Qualcomm.
2) If edge AI enters hardware such as Echo and Fire TV, Amazon’s chip agenda will expand from cost control to model experience and local inference.
Total Cloud Capital Expenditure
1) AI capital expenditure by Google, Amazon, Meta, Microsoft, and Oracle is expected to exceed US$800 billion in 2026 and rise to US$1.1 trillion in 2027, equivalent to about 3.2% of U.S. GDP.
2) The investment implication is direct: GPUs are only the first layer. Memory, servers, power, lease commitments, cooling, and interconnect are all consuming this budget.
AI Cloud/Data-Center Operators
Nebius
1) Nebius is viewed as one of the few neocloud companies with power, customers, and a software layer at the same time. The material shows Q1 2026 revenue of US$399 million, up 684% YoY, year-end annualized revenue guidance of US$7 billion-US$9 billion, contracted power of 3.5 GW, and a year-end target of more than 4 GW.
2) The company’s contracts with Meta and Microsoft exceed US$46 billion and run through 2031. The risk is that a capital-intensive model turns financing capacity and delivery cadence into the core of valuation.
“Most neoclouds have none of those three things simultaneously but Nebius has all of them”
CoreWeave
1) CoreWeave has pulled back more than 50% from its high, but backlog remains close to US$100 billion and revenue is still growing more than 100% YoY.
2) The company represents the neocloud debate: contracts and revenue are very strong, but debt, losses, and hyperscalers’ self-built clouds suppress valuation tolerance.
IREN
1) The debate around IREN is “MW assets” versus “platform capability.” The material says it will approach 1 GW of operating or completed capacity by end-2026, including 160 MW in Canada and 750 MW at Childress, while the 1.4 GW Sweetwater 1 standalone site was energized on May 28, 2026.
2) Nvidia has announced an initial 60 MW deployment, but a partnership with Anthropic remains unconfirmed speculation. What the share price needs to validate is whether power assets can convert into contracted AI cloud revenue.
TeraWulf, Cipher Mining, Applied Digital, Galaxy Digital
1) These companies are all on the list of AI data-center operators, but the strength of hard evidence varies in this round. The main line that can be included is data centers, power capacity, AI compute hosting, financing, and customer contracts; a stock should not be included merely because it appeared.
2) Follow-up tracking should focus on power interconnection, customer credit quality, GPU financing, and take-or-pay contracts, not one-day share-price moves.
GPU/CPU/ASIC
Nvidia
1) Nvidia remains the largest beneficiary of AI factory budgets. The material says a 1 GW AI factory based on Nvidia architecture could cost close to US$100 billion, with roughly half flowing to Nvidia chips, systems, and software.
2) The risk is also beginning to shift from demand to architecture execution: Kyber NVL144 has been delayed by more than 12 months to 2028, the NVL72x2 back-to-back solution has been canceled, and Rubin Ultra’s scale-up world size is constrained.
“1GW AI factory... could now cost nearly 100 billion dollars”
Intel
1) Intel 18A yield is still in the early ramp phase, but company commentary indicates improvement is faster than internal targets. Management has cited monthly yield improvements of 7% or 8%. 14A is planned for risk production in 2028 and mass production in 2029, with the 0.9 PDK to be released in October.
2) The business question for this line is whether Intel can lock in major fabless customers over the next 18 months. If not, the advanced foundry story will continue to be overshadowed by TSMC A14 and Samsung SF2Z.
Broadcom
1) Broadcom’s latest quarterly AI revenue grew 106% YoY to US$8.4 billion, driven by custom accelerators and AI networking chips for Google, Meta, and Anthropic.
2) At the same time, the market questions whether the company is “chips only” and lacks the narrative of full AI system integration. Future valuation depends on ASIC customer expansion and networking-chip volume growth.
AMD
1) AMD’s opportunity comes from early feedback on small-scale MI355x deployments and MI500X’s potential competition in the Rubin Ultra scale-up window. The material shows MI355x pre-registration has reached 6 nodes and 48 GPUs, with a US$100 threshold for each pre-registration.
2) This is not a formal order, but it shows independent compute deployers are starting to queue for AMD GPUs. The next validation points are MI450/MI500 mass production, customer financing, and software-stack stability.
HBM/DRAM/NAND/SSD/HDD
Micron
1) Micron has started a JPY1.5 trillion, or roughly US$9.3 billion, AI memory expansion in Hiroshima to produce HBM, with shipments expected in summer 2028. The Japanese government will provide up to JPY500 billion in support, with total support of about JPY775 billion.
2) The near-term supply impact is limited, but this reinforces Micron’s medium- to long-term capacity position in HBM. The recent share-price pullback is more about crowding and profit-taking after memory stocks reached elevated levels.
“The new facility will produce high-bandwidth memory for AI processors”
Samsung Electronics, SK Hynix
1) UBS raised its DDR contract price forecasts to +32% QoQ in Q3 2026 and +18% QoQ in Q4, and NAND to +30% QoQ in Q3 and +12% QoQ in Q4. The report judges that DRAM will remain in shortage at least until Q2 2028.
2) SK Hynix is also rumored to be planning a Nasdaq listing, with the logic of using the U.S. equity market to reprice HBM, DRAM, and flash demand. But single-stock leveraged ETFs in Korea amplify volatility, so short-term prices cannot all be treated as fundamentals.
SanDisk, Kioxia
1) BofA believes South Korea’s KRW800 trillion memory cluster will not generate effective capacity quickly, while NAND shortages and enterprise SSD demand remain strong. SanDisk’s enterprise SSD revenue grew 7x YoY, and the company is developing high-bandwidth flash, expected to launch later in 2026 to 2027.
2) The core for Kioxia and SanDisk is the NAND pricing cycle and eSSD supply-demand, not traditional consumer flash. The risk is whether downstream procurement can continue to absorb compounded price increases.
China Memory Chain
1) Lenovo’s global configuration of the ThinkBook 14 G9 has started using Yangtze Memory SSDs, while ChangXin Memory is testing a bonded DRAM pilot line in Hefei, attempting to use DUV multi-patterning to bypass EUV.
2) Neither line has yet reached large-scale mass production or order delivery, but they show China’s memory substitution progressing simultaneously from PC SSDs and DRAM process routes.
Wafer Foundry
TSMC
1) TSMC has about 70% share of global advanced wafer foundry, and Nvidia and Apple alone contribute roughly 40% of revenue. At 2025 IEEE ECTC, the company introduced SoW-X, pointing to wafer-level system integration to address reticle-size, I/O bandwidth, and thermal-management bottlenecks.
2) Advanced process nodes and advanced packaging are merging into a system capability. TSMC’s risk is not demand, but geopolitics, energy, and customer concentration.
“SoW-X redefines how logic and memory interact at scale”
Semiconductor Equipment/Testing
Equipment Chain
1) Samsung and SK Hynix are evaluating alternatives to Mattson for PR strip and RTP equipment. Supply-chain diversification benefits Applied Materials, ASML, Lam Research, Tokyo Electron, KLA, and Korean equipment vendors.
2) SEAJ raised its FY2026 Japan semiconductor equipment sales outlook to JPY6.55 trillion, with FY2027 at JPY7.4 trillion and FY2028 at JPY7.77 trillion. The equipment cycle is supported by advanced logic and DRAM capacity expansion.
FormFactor, Teradyne, Advantest
1) FormFactor’s Q1 2026 revenue was US$226 million, up 32% YoY, with non-GAAP EPS of US$0.56, above expectations of US$0.44. Through Keystone Photonics, it is partnering with Advantest to enter silicon photonics wafer-level testing.
2) As CPO, silicon photonics, and high-speed electro-optical testing become more complex, equipment value will expand from traditional electrical testing to coordinated optical-electrical validation.
MLCC/Passive Components and ABF
Yageo
1) Goldman Sachs maintained a Buy rating and raised its 12-month target price from NT$346 to NT$1,490. The report argues that migration of AI-grade MLCC capacity will squeeze general-purpose MLCC supply, with global non-AI MLCC utilization returning to 97%/100% in 2027/2028.
2) Yageo’s general-purpose MLCC prices are expected to rise 29%/93%/84% YoY in 2026/2027/2028, a typical case of AI infrastructure spilling over into ordinary passive components.
“more and more MLCC capacity is being transferred into the AI grade MLCC supply chain”
Samsung Electro-Mechanics, LG Innotek
1) Goldman Sachs raised its target price for Samsung Electro-Mechanics from KRW1.0 million to KRW2.6 million and maintained a Buy rating. AI MLCC revenue is expected to grow 6.4x from 2025 to 2028 and account for 28% of MLCC revenue in 2028.
2) LG Innotek’s target price was raised from KRW550,000 to KRW1.0 million, with a Neutral rating maintained. ABF revenue is expected to rise from KRW50 billion in 2025 to KRW700 billion in 2028, but still account for only 2.5% of total revenue.
ABF/Fiberglass Materials
1) Industrywide new capacity for high-end ABF substrates will remain limited before 2H 2027. Higher power consumption, larger packages, and faster interconnects in AI servers are raising layer counts and material requirements.
2) Nittobo has about 90% global share in low-CTE T-glass and 60%-70% share in low-Dk NER-glass. China’s Guangyuan New Materials is investing US$1 billion to challenge this position, but certification cycles remain the moat.
Power Semiconductors/Thermal and Power
Texas Instruments, Infineon, STMicroelectronics
1) Power semiconductors have already started raising prices before the arrival of 1 MW racks. Infineon has raised prices by 10%-25%, Texas Instruments raised prices again on PMICs and MOSFETs on July 1, and STMicroelectronics has implemented a second round of price increases for some products.
2) The reason is that Vera Rubin is about 225 kW per rack, while Rubin Ultra is about 600 kW or more. VRM phases, MOSFETs, drivers, controllers, capacitors, and inductors all need to scale up.
onsemi and the OSAT Supply Chain
1. Greatek plans to acquire equity in a Philippine assembly and test services company from onsemi Japan Holdings for no more than US$45 million; after closing, the company is expected to be renamed Greatek Electronics Philippines Corporation.
2. This is not a positive signal for onsemi orders. It reflects OSAT supply-chain diversification into Southeast Asia in response to customer requirements for Taiwan PCB and substrate +1 sourcing and global delivery resilience.
Thermal Components
1. MinebeaMitsumi plans to invest JPY58 billion to expand precision bearing capacity, lifting monthly capacity to more than 500 million units; the company has more than 60% global share in miniature bearings below 22mm.
2. As AI server power consumption rises, liquid cooling will not eliminate air-side components. Fan motors, bearings, and rear-door heat-exchange systems should still benefit.
Optical Communications / Optics Chain
CPO / Silicon Photonics Chain
1. Broadcom covers PIC design, laser sources, photodiodes, and EICs; Marvell Technology is the DSP engine for optical modules; MACOM is positioned in 1.6T/3.2T optical transceivers; Keysight, FormFactor, Teradyne, and EXFO benefit from rising test complexity.
2. Foxconn Industrial Internet reported Q1 2026 revenue of US$66.6 billion, up 29.7% YoY; AI servers accounted for more than 50% of server revenue. CPO switches are expected to enter mass production in Q3 2026, with full-year shipments forecast at 10,000 units.
“Every AI data center being built depends on what’s in that chart”
Fiber Cables and Materials
1. Optical interconnects are not only about optical modules. Fiber, optical materials, testing, and server assembly are all benefiting. Cable and fiber-material companies such as Furukawa Electric, Fujikura, and Sumitomo Electric should be included in the optical communications chain, rather than viewed separately as a Japan materials theme.
2. The near-term items to verify are the order cadence for 1.6T/3.2T optical modules, CPO switches, DSPs, and silicon-photonics test equipment.
Robotics / Intelligent Driving and Space Satellites
Robotics Components
1. VPG Q1 revenue was US$84.35 million, up 17.6% YoY; orders were US$102.08 million, with a book-to-bill of 1.21. However, humanoid robot orders were only US$1 million, slightly above 1% of the total.
2. This line shows that tactile sensors and safety certification are real bottlenecks, but the stock once traded near 270x P/E. The long-term robotics TAM cannot be capitalized all at once as current-period earnings.
Agility / Robotics Commercialization
1. Agility plans to list via SPAC, with roughly US$640 million in private financing. About 100 Digit units have already been deployed, unfilled orders exceed US$300 million, and the annual capacity target is above 10,000 units.
2. Deployments by Amazon, GXO, Schaeffler, Toyota, MELI, and other customers show that logistics is moving first, but safety certification, real payback periods, and full-system cost remain key.
Tesla and Starlink
1. The Tesla app has started to show whether FSD is enabled, improving vehicle-side software visibility. Future Robotaxi services may require similar remote status monitoring.
2. Starlink antennas are testing emergency Wi-Fi in Japan, with 120,000 fire-hydrant markers nationwide. LEO communications are expanding from home broadband into public safety and disaster-recovery networks.
Internet / Platforms
Amazon
1. Amazon is simultaneously carrying three lines: platform, advertising, and cloud capex. The advertising business is more mature, while AWS continues to support group investment with an operating margin near 35%; in-house chips for edge hardware move the device ecosystem into the AI cost-control phase.
2. The risk is that in-house chips do not mean a full exit from external suppliers such as Qualcomm. In the near term, the key is whether products such as Alexa, Echo, and Fire TV can convert local inference into experiences users are willing to pay for.
Meta
1. The market debate around Meta comes from the intensity of AI investment, not the disappearance of the advertising core. Materials suggest it may still increase AI infrastructure spending and continue locking in HBM, LPDDR5, and eSSD.
2. If a self-built AI cloud delivers cost advantages, external clouds such as CoreWeave will come under pressure. If self-build is insufficient to cover demand, neoclouds and data-center landlords will still have contract opportunities.
Reddit, AppLovin, Unity Software
1. AI ad optimization continues to spread across internet platforms. After restructuring, Unity Software revenue grew 17% YoY, with its Grow advertising business up about 50% YoY; AppLovin revenue grew 59% YoY; Reddit advertising revenue grew 74% YoY.
2. The key in this line is not the two letters “AI,” but whether ad-conversion rates, store count, data assets, and model distribution capabilities can continue to raise the revenue slope.
Netflix, Uber, DoorDash, Airbnb
1. These platforms appear in the opening ranking mainly as market facts, with limited new hard evidence tied to AI or the semiconductor core theme.
2. The focus here is marginal change in platform business models: streaming, local services, and travel platforms remain gauges of consumer-internet risk appetite, but they do not drive this issue of the tech morning note.
Software / SaaS
Microsoft
1. The software base and AI pricing power are Microsoft’s clearest main lines. Materials state that the “software business is safe” and argue that AI capex will turn toward positive ROI.
2. For investors, the follow-through should be Copilot penetration, Azure AI revenue, enterprise contract renewals, and bundled price increases, rather than only the absolute level of capex.
Palantir
1. The SaaS valuation comparison shows Palantir with expected NTM revenue growth of 63.5% and EV/gross profit of 67.8x, placing it in the most expensive tier of the software group.
2. Its premium comes from AI data platforms and deployment into government and enterprise workflows, but the risk is also clear: high growth must be accompanied by delivery on gross margin, operating margin, retention, and free cash flow.
“SaaS valuation: growth alone is not enough”
Snowflake, Datadog, Cloudflare
1. The software-budget discussion is shifting from pure revenue growth to growth quality. Snowflake, Datadog, and Cloudflare all benefit from data, observability, and edge cloud, but valuations need to be assessed together with gross margin, operating margin, renewal rates, and retention.
2. The software group’s relative resilience versus semiconductors shows that capital is willing in the near term to look for AI applications and infrastructure software with lighter cash-flow demands, but there were no new hard target-price actions.
Figma and Model-Application Competition
1. The timing of Anthropic’s Claude Design launch has been used to discuss competition with Figma’s core product. Materials state that Figma’s share price fell 7% on launch day, was down about 80% from its historical high, and erased nearly US$50 billion in market value.
2. The core risk is that once frontier models enter vertical applications, the product moats of incumbent SaaS vendors will be compressed. But model companies themselves also need to prove they can turn features into high-retention paid products.
Generative AI Website Traffic
1. The traffic data only provides YoY growth by marketing channel for the top five generative AI websites as of May 2026 and Fable 5 search trends over the past 28 days; it does not disclose specific growth rates.
2. This type of data is useful for tracking application momentum, but it cannot be directly extrapolated to revenue and valuation.
Consumer Electronics / Smart Vehicles
Apple
1. Apple rose 4.86% on the latest close, outperforming most large-cap technology stocks. Supply-chain information points to “looks okay” completion progress for foldable-screen and high-end new-device buildout, but actual shipments may be below external expectations.
2. Memory price increases will pressure iPhone, Mac, and iPad costs; the materials also note that memory accounts for about 40% of the BOM in high-end smartphones, which will test Apple’s pricing power.
Consumer Electronics Memory Costs
1. After AI data centers absorbed HBM, server DRAM, and eSSD supply, smartphones and PCs are beginning to come under pressure. IDC expects global smartphone shipments to decline nearly 13%, with ASP rising to USD 523; higher memory prices are being transmitted to end hardware.
2. This benefits memory vendors, but creates dual pressure on consumer electronics brands through gross margins and volumes.
Tesla
1. Tesla fell 6.95% in the short term, but the useful information in this material concerns FSD status display and the longer-term Robotaxi scenario.
2. Prices for Chinese humanoid robots are also moving lower: Unitree R1 is priced at RMB 26,900, Booster K1 at RMB 29,900, and Noetix Bumi at RMB 9,998; lower costs will accelerate application pilots while compressing finished-system premiums.
Robotics Supply Chain
1. China shipped 14,400 humanoid robots in 2025, with 2026 shipments expected at 100,000-200,000 units. Unitree’s average selling price declined from about RMB 593,000 in 2023 to RMB 167,000 by end-2025, while production cost fell from RMB 73,200 to RMB 62,200.
2. The U.S. is strong in foundation models, autonomous driving, and action scaling laws; China is strong in shipments and the cost curve. Supply-chain opportunities are more concentrated in reducers, actuators, sensors, and batteries.
“The United States leads the world in where robotics is heading... while losing the race on where robotics is shipping today.”
LG Innotek and Satellite Substrates
1. LG Innotek is seeking to enter the LEO satellite substrate supply chain, but there is no order value or mass-production timeline.
2. This line is suitable for inclusion in space/satellite supply-chain tracking: satellite communications hardware may drive demand for substrates, antennas, optical communications, and LEO ground infrastructure.
Investment Bank Target Price Changes in the Past 12 Hours
Jensen Huang Portfolio