404K SEMI-AI Morning Brief 2026-07-20 — Memory Shortages Widen, Open Models Consume All Available Compute, Software Performance Diverges
目录
Post-Close Summary
Full AI/Semiconductor Supply Chain
AI Models/Applications, CSPs, and AI Cloud Capital Expenditure
GPUs, Memory, Wafers, and Equipment
Optical Communications, Networking, and Power Infrastructure
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Investment-Bank Target Price Changes Over the Past 12 Hours
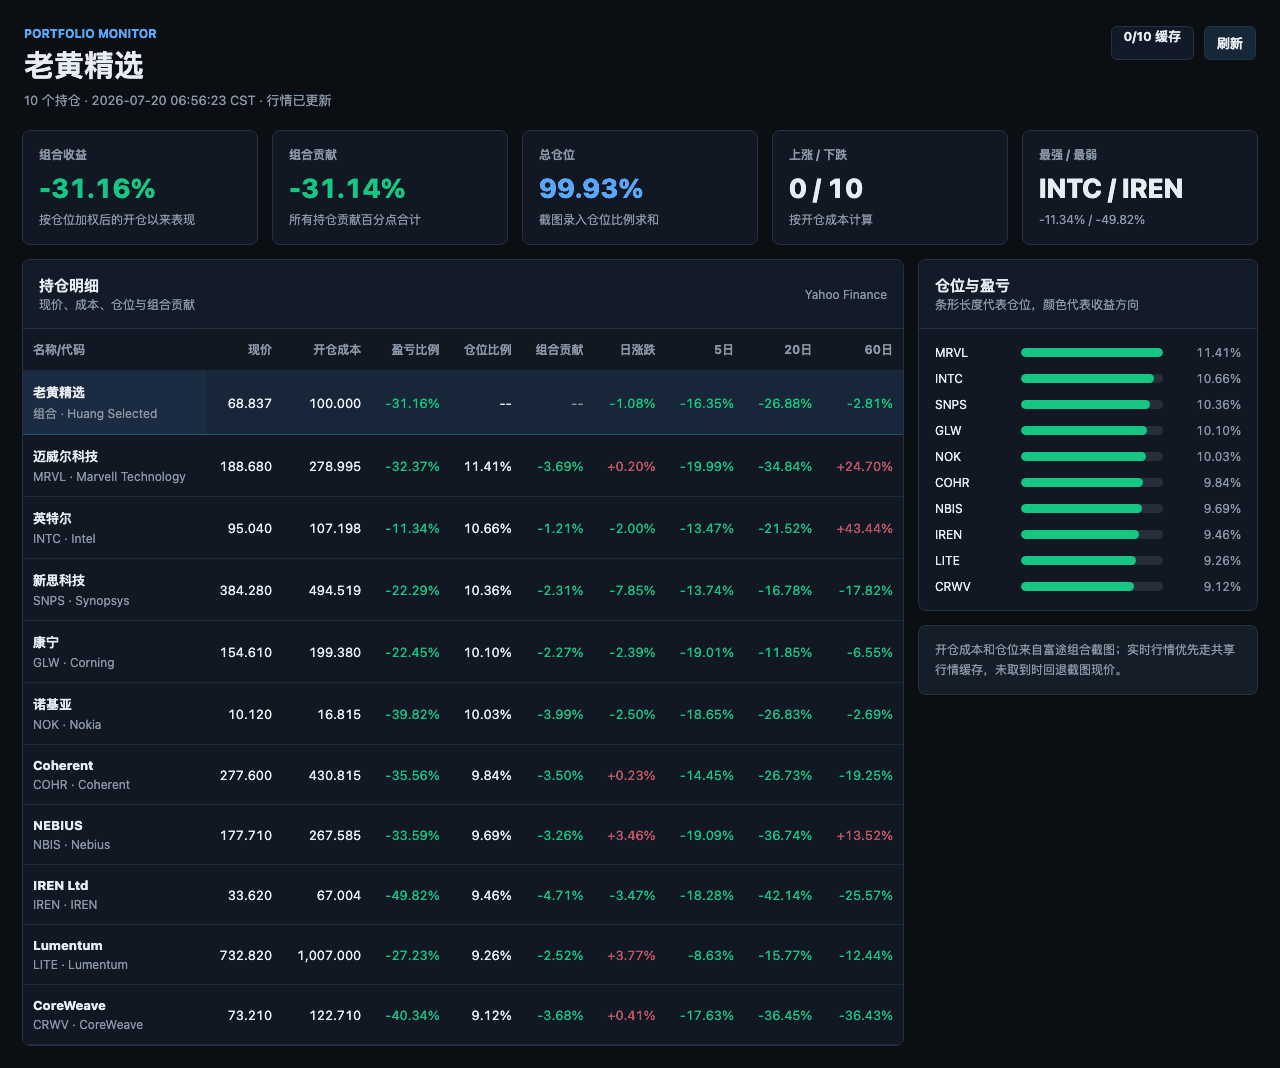
Huang’s Selected Portfolio
Risk appetite continued to cool in the latest session, while near-term pricing pressure in semiconductors diverged from supply-demand signals in memory, equipment, and optical interconnects. Open models are lowering unit usage costs without freeing up idle compute capacity; the real test is whether cloud providers can convert capital expenditure into revenue and cash flow.
404K SEMI-AI | 2026-07-20
Post-Close Summary
The latest trading session closed on July 17. The S&P; 500, Nasdaq 100, and Dow Jones fell 0.99%, 1.50%, and 0.74%, respectively, while the equal-weighted S&P; 500 declined 0.79%, indicating that pressure was not confined to a handful of index heavyweights. The VIX rose 12.19% to 18.77, and crude oil gained 3.91%, signaling greater willingness to pay for near-term risk protection.
Technology fell 1.09%, while the semiconductor theme declined 2.18%. Semiconductors have fallen 10.81% over the past 20 days, with RPS20 at just 7.4. Software declined 0.96% on the day but remained up 4.08% over the past 20 days; cybersecurity gained 0.51%, with RPS20 reaching 96.3. Capital is rotating away from high-volatility hardware trades toward application and security companies with more resilient revenue.
Semiconductor trading remains weak, but industry fundamentals have not deteriorated in parallel. Server-memory spot prices, HBM long-term contracts, wafer-equipment price increases, and model-capacity constraints all indicate that physical supply remains tight. The most important validation points ahead are cloud-provider capital expenditure, memory contract prices, advanced-packaging production schedules, and data-center power delivery—not simply whether share prices rebound.
Full AI/Semiconductor Supply Chain
AI Models/Applications, CSPs, and AI Cloud Capital Expenditure
Moonshot AI
1) Demand approached the limit of available GPU capacity within 48 hours of the Kimi K3 launch, prompting the company to suspend new subscriptions and expand capacity. This indicates that low-cost open models initially amplify usage rather than free up compute.
2) The model has 2.8 trillion total parameters, and even its 4-bit weights require approximately 1.4TB, necessitating rack-scale interconnected GPUs. Savings from a smaller KV cache are being reabsorbed by larger models and longer context windows.
“Within 48 hours of Kimi K3’s launch, demand approached the limit of available GPU capacity. The company therefore suspended new subscriptions, prioritized service for existing members, and began adding capacity and restructuring membership plans.”
Anthropic: Frontier-model revenue remains highly dependent on flagship products, while lower-priced alternatives reduce revenue per megawatt of compute. As model capabilities converge, competition will shift toward the cost of completing tasks. If pricing declines faster than training and inference costs, laboratories’ high revenue growth may not translate into sustainable cash flow.
DeepSeek: Its technical differentiation lies in actively exploring NAND-based KV Cache, which would move part of the inference cache from expensive memory to a cheaper storage tier. Deployment scale and cost reductions remain unclear, while GLM’s approximately 15%–20% gross margin suggests that model-layer profitability should not simply be extrapolated from high-margin software.
Amazon
1) First-quarter AI annualized run-rate revenue was approximately $15 billion, with Bedrock estimated at roughly $5 billion, or about one-third of the total. Bedrock sells inference services and uses Trainium to reduce costs, with estimated revenue per unit of power at $18 billion–$20 billion per gigawatt.
2) The high-margin thesis depends on model demand, pricing, and utilization of proprietary chips; it cannot be valued solely as compute-capacity leasing.
“Inference platforms control customer relationships and infrastructure while participating in model-service revenue sharing. Their revenue quality and potential margins may therefore exceed those of renting GPUs to frontier laboratories.”
Nebius
1) First-quarter revenue reached $399 million, up 684% year over year, while AI cloud revenue rose 841% to $390 million. Adjusted EBITDA margin for the AI cloud business exceeded 45%.
2) 2026 revenue guidance is $3.0 billion–$3.4 billion, with capital expenditure of $20 billion–$25 billion and a backlog of approximately $46 billion. High growth depends on customer prepayments but also carries financing and dilution risks.
CoreWeave: Approximately 50% of compute is already being used for inference. A cluster of 100,000 Grace Blackwell GPUs consumes roughly 250MW and contains approximately 16 million connection points. Losing 10% of compute cycles raises the effective cost per token by approximately 10%, meaning competitiveness depends on effective throughput, networking, and operations—not individual-chip benchmark scores.
“Losing 10% of compute cycles because of failures, retries, or poor orchestration raises the effective cost per token by approximately 10%.”
GPUs, Memory, Wafers, and Equipment
NVIDIA
1) South Korea plans to invest approximately KRW 4 trillion to purchase 10,000 Vera Rubin systems, offering up to 6x and 8x improvements in training and inference performance, respectively, versus the previous generation. The budget and site have yet to be finalized.
2) Morgan Stanley estimates that 2.5 million Vera CPUs could drive 10% growth in DRAM bit demand, while 4 million units would imply 16% growth. Demand for AI accelerators is simultaneously expanding host-memory requirements.
AMD: Deutsche Bank expects leading-edge logic supply coverage to bottom at just 72%–75% in 2027, with advanced-node coverage at 71%–82%. Whether AMD can fulfill CPU and GPU demand depends not only on its products but also on timely availability of advanced wafers, packaging, and HBM. The shares fell 1.03% in the latest session and 3.26% over the past 20 days.
Micron
1) Spot prices for 64GB DDR5 server modules have risen to $3,100–$3,400, approximately 146% above the late-June fixed transaction price of roughly $1,380.
2) HBM requires approximately 3–4x as many wafers per GB as conventional DRAM, while customer requests are 5–6x available supply. Whether higher prices enter long-term contracts matters more than the spike in spot prices.
“Spot prices for 64GB DDR5 server DRAM have risen to $3,100–$3,400, 146% above the fixed price of approximately $1,380 at the end of June.”
SK hynix: The company expects overall memory demand to grow by more than 50%–60% next year, with AI-related demand increasing 60%–100%. Its HBM market share is approximately 58%. Management also wants prices to decline, indicating that excessively high prices would damage PC and smartphone demand. Disclosures on long-term agreements and contract pricing on July 29 will be key validation points.
SanDisk
1) Data-center revenue increased from $197 million to $1.467 billion, up 645% year over year, while a 128TB enterprise SSD is scheduled to launch in the fourth quarter.
2) Multiyear agreements with five hyperscale customers represent $42 billion in minimum contracted revenue. However, at a current forward P/E of 32.3x, the valuation cushion would narrow quickly if margins retreat from 78.4%.
“The company already has more than $300 million in multiyear orders for Digit v5, but this figure is primarily attributable to approximately 1,000 units from a single core customer.”
TSMC: Second-quarter revenue reached $40.2 billion, up 33.7% year over year, with a gross margin of 67.7%. The company raised its 2026 capital-expenditure outlook from $52 billion–$56 billion to $60 billion–$64 billion. Third-quarter revenue guidance of $44.6 billion–$45.8 billion exceeded the consensus estimate of $43.11 billion, with advanced-node and CoWoS production schedules remaining strong.
ASML: A single EUV lithography system costs approximately $284 million. Average pricing has increased at a roughly 13% CAGR over the past decade, followed by another 45% rise in the latest year without order cancellations. The 3600D cannot be upgraded with a 500W light source, and all current 3800E systems are new installations, indicating that upgrade demand will translate into incremental equipment purchases rather than straightforward retrofits.
“Average pricing increased at a roughly 13% CAGR, followed by a 45% rise in a single year without order cancellations, indicating that advanced AI compute spending is strengthening pricing power through its dependence on advanced-process lithography equipment.”
Applied Materials: TSMC explicitly cited equipment price increases as a factor behind its higher capital-expenditure outlook, while Applied Materials continues to emphasize value-based pricing. Needham raised its 2027 wafer-fab equipment spending forecast from $149.6 billion to $201.0 billion. Equipment suppliers benefit from the increase in spending, but the 2028 forecast declines to $191.6 billion, indicating that growth will not be linear.
Lam Research: Morgan Stanley estimates that Lam holds approximately 43% of the dry-etch market and roughly 50% of the conductor-etch segment. Its 2027 DRAM equipment-spending forecast was raised from $49.0 billion to $84.1 billion, an increase of 72%. If memory capacity expansion continues, order visibility for etch and deposition equipment will be stronger than a pure pricing trade.
Optical Communications, Networking, and Power Infrastructure
Applied Optoelectronics: Revenue was $456 million in 2025, with 2026 guidance above $1.1 billion. First-quarter data-center optical-module revenue grew 154% year over year and accounted for 54% of total revenue. 800G entered mass production in the first quarter and accelerated in the second, but customer concentration remains high and the share count has increased from 53 million to 79 million; growth and dilution must be assessed together.
Corning: First-quarter 2026 optical-communications revenue was approximately $1.85 billion, up 36% year over year, and the company signed a multiyear agreement with Meta worth up to $6 billion. The 777 large data-center projects announced globally represent approximately 190GW, but of the 16GW scheduled to come online in 2026, only about 5GW is under construction. The pace of contract execution matters more than project headlines.
Lumentum and Coherent: NPO places optical engines on the same substrate as the switch ASIC while preserving replaceability, making it a practical transition path from pluggable optics to CPO. Whether the architecture uses pluggable optics, NPO, or CPO, demand increases for InP lasers, optical engines, and silicon photonics. The risks lie in manufacturing yields and the pace of architectural transitions.
“By balancing performance improvements, manufacturability, and serviceability, NPO could enable hyperscale cloud providers to deploy high-performance optical networks sooner and become an important bridge technology as AI clusters continue to expand over the next several years.”
Ciena: Revenue in the latest quarter reached $1.57 billion, up 40% year over year, while earnings per share increased 290%. Full-year revenue guidance is $6.3 billion, with a backlog of $7.7 billion. AI network expansion is already reaching optical-transport equipment, but customer deployments, component supply, and order recognition will determine the pace of revenue realization.
Vertiv: Rising AI rack density is increasing the value of power systems, UPS equipment, and cooling solutions sold per megawatt, while the company’s orders, revenue, margins, and cash flow are improving simultaneously. Lead times for large transformers have extended to 24–48 months, pushing data-center bottlenecks beyond GPUs into power distribution, liquid cooling, and skilled labor.
STMicroelectronics: AI and data-center revenue is expected to increase from $1 billion in 2026 to $2 billion in 2027. Products include photonic ICs for optical modules, microcontrollers, and SiC and GaN power semiconductors. A forward 12-month P/E of approximately 35x requires delivery of projected revenue, while customer exposure and penetration rates still need to be verified.
Internet/Platforms
Google: The market is focused not on the absolute level of capital expenditure, but on whether higher investment can continue to drive cloud and search revenue. Sell-side models put 2027 capex at approximately $350 billion, based on highly aggressive assumptions. If cloud orders and inference revenue fail to keep pace with depreciation, continued capex growth could still dilute earnings quality.
Microsoft: 2026 capex is approximately $190 billion, while remaining performance obligations increased 99% year over year to $627 billion, indicating a substantial demand backlog. Rising component prices added another approximately $25 billion in spending. The three key metrics for determining whether growth genuinely covers costs are order-to-revenue conversion, the pace of data-center commissioning, and depreciation.
Meta: Capex guidance is $125 billion to $145 billion, while contractual commitments increased by $107 billion in a single quarter. However, the market remains concerned about depreciation and surplus compute capacity. If Meta Compute can monetize idle capacity as high-margin revenue, oversupply could become a new business. If external demand is insufficient, the intensity of investment will directly compress EPS.
Alibaba: Qwen3.8 is a 2.4-trillion-parameter open-weight model that the company says ranks second only to Fable 5 and can compete with other frontier models. Continued parameter scaling will shift competition away from model leaderboards and back toward inference costs, memory usage, and enterprise deployment. Key follow-ups are the official release, inference pricing, and actual adoption.
OpenAI: ChatGPT Work runs agent tasks in the cloud, allowing users to continue via mobile even after closing their laptops. The product proposition is shifting from one-off answers to continuous execution, extending inference time and background-task duration. Whether costs can decline relative to task-completion rates will determine whether cloud agents can evolve from a compelling experience into a viable business.
“One of ChatGPT Work’s best features is that it runs in the cloud, meaning it remains accessible from a phone even when the laptop is closed.”
Netflix: Shares fell 7.26% in the latest session and 10.41% over the past 20 sessions, making Netflix the most pressured large-cap platform stock. The company guides to full-year revenue growth of 13% to 14%, or approximately 12% on an FX-neutral basis, versus 12% reported growth in the third quarter. Membership, price increases, and advertising remain the three revenue drivers, while the market is more concerned about valuation digestion once that growth is delivered.
“Full-year revenue growth of 13% to 14%. On an FX-neutral basis, approximately 12%, representing roughly $6 billion in incremental year-over-year revenue.”
Shopify: Shares fell 1.20% in the latest session but rose 14.31% over the past 20 sessions, with an RPS20 of 96.7, indicating sustained capital support for e-commerce infrastructure. Expected revenue growth over the next 12 months is approximately 23.2%. If growth is accompanied by margin improvement, Shopify should outperform platforms that generate traffic but lack monetization efficiency.
Reddit: Shares fell 2.20% in the latest session but rose 9.18% over the past 20 sessions, with an RPS20 of 92.2. Incremental growth for the social platform comes from advertising and AI data licensing. Whether the latter becomes recurring revenue depends on customer renewals, the boundaries of content licensing, and user engagement. Aggressive data monetization could also increase regulatory and community-governance costs.
AppLovin: Shares fell 2.29% in the latest session and 11.46% over the past 20 sessions, with an RPS20 of 54.9. Expected revenue growth over the next 12 months is approximately 43.1%, and the forward P/E is approximately 25x. Its growth-to-valuation profile is more attractive than that of many premium software stocks, but recent momentum has weakened as the market awaits further validation of advertising efficiency and margins.
“AppLovin is expected to grow approximately 43% and trades at nearly 25x forward earnings, significantly below the trend line; Oracle is expected to deliver revenue growth above 30% and trades at approximately 20x forward earnings.”
Pinterest: Shares rose 0.48% in the latest session and 13.95% over the past 20 sessions, with an RPS20 of 95.4. Positive returns in a weak market indicate relative strength in social commerce and advertising. The next test is whether user growth, shopping conversion, and ad pricing can improve simultaneously, avoiding a share price driven solely by short-term factor rotation.
Snap: Shares fell 3.41% in the latest session, 4.43% over the past 20 sessions, and 44.28% year to date. The platform lacks a scale buffer in the advertising market, while its AR narrative has yet to compensate for weak revenue and cash flow. If macro advertising budgets soften, user growth will not directly offset pressure on pricing and monetization efficiency.
Uber: Shares fell 2.13% in the latest session but rose 2.19% over the past 20 sessions, with an RPS20 of 83.7. Its two-sided mobility and local-services network remains resilient, but autonomous-driving partnerships will affect both costs and the platform’s bargaining power. Key metrics are order growth, take rate, and unit economics after autonomous-vehicle capacity is integrated.
DoorDash: Shares fell 1.19% in the latest session but rose 11.16% over the past 20 sessions, with an RPS20 of 93.5. Food-delivery platforms are reshaping customer acquisition and delivery relationships for offline merchants, and strong momentum suggests the market recognizes continued penetration of local services. Risks include subsidies, courier costs, and merchant commission constraints limiting margin expansion.
“By 2030, the four hyperscale cloud providers’ free cash flow is expected to exceed its 2024 peak.”
Airbnb: Shares fell 1.23% in the latest session but rose 3.87% over the past 20 sessions, with an RPS20 of 87.6. The accommodation platform retains its network effects, but supply quality, regulation, and travel demand determine the growth trajectory. Amid widening dispersion among platform stocks, bookings and average daily rates should be assessed alongside marketing investment, refunds, and host retention.
The Trade Desk: Shares fell 2.77% in the latest session but rose 2.37% over the past 20 sessions, with an RPS20 of 85.0. Programmatic advertising continues to benefit from the digitization of budgets, but the platform must demonstrate that its independence and data capabilities can withstand competition from large walled gardens. Key validation metrics are customer retention, ad-spend growth, and monetization per 1,000 impressions.
“This revenue is higher quality than renting GPUs to laboratories because cloud providers control the customer relationship and infrastructure.”
“One market disconnect is that sentiment around frontier laboratories is driven by near-real-time leaked ARR figures, defined aggressively, while hyperscale cloud providers are priced on their disclosed GAAP financials.”
Software/SaaS
Palantir: Expected revenue growth over the next 12 months is approximately 63.5%, the highest among the software growth cohort. Shares fell 1.53% in the latest session but rose 1.34% over the past 20 sessions, with an RPS20 of 82.4. The market already prices Palantir as a leader in AI commercialization, requiring contract growth, customer concentration, and margins to continue exceeding expectations.
ServiceNow: Expected revenue growth over the next 12 months is approximately 26%. Shares fell 0.74% in the latest session but rose 8.13% over the past 20 sessions, with an RPS20 of 91.5. Earnings must clarify whether AI is expanding the workflow platform’s total value or merely relabeling existing revenue. Net new subscriptions and renewal rates provide the clearest signals.
“Can AI expand the total value of the ServiceNow platform, or does it merely alter the composition of existing revenue?”
Snowflake: Expected revenue growth over the next 12 months is approximately 28.3%. Shares fell 0.41% in the latest session but rose 14.66% over the past 20 sessions, with an RPS20 of 97.4. The data cloud remains strong within software. Continued valuation expansion depends on whether AI workloads can drive consumption revenue, net revenue retention, and product gross margin.
Cloudflare: Expected revenue growth over the next 12 months is approximately 28.4%. Shares rose 1.91% in the latest session and 22.39% over the past 20 sessions, with an RPS20 of 98.7. The edge network is capturing demand across security, inference, and developer platforms. Revenue growth must be driven by developer adoption and enterprise contracts, rather than traffic growth alone.
CrowdStrike: Expected revenue growth over the next 12 months is approximately 22.6%. Shares fell 0.33% in the latest session but rose 18.94% over the past 20 sessions, with an RPS20 of 98.0. Security spending remains defensive in a weak market, but competitive intensity, platform consolidation, and sales efficiency will determine whether revenue converts into free cash flow.
“The best opportunities typically combine sustainable growth, improving profitability, and valuations supported by future cash-flow generation.”
Palo Alto Networks: Shares rose 1.32% in the latest session and 27.13% over the past 20 sessions, with an RPS20 of 100, ranking first in relative strength among software and platform stocks. The market has endorsed platform-based security spending. Remaining performance obligations, billings growth, and next-generation security revenue now need to validate the momentum.
Datadog: Expected revenue growth over the next 12 months is approximately 24%. Shares fell 1.38% in the latest session but rose 14.15% over the past 20 sessions, with an RPS20 of 96.1. AI applications increase observability data volumes, while cloud optimization can reduce consumption. Customer expansion, product count, and large-customer growth determine net retention.
Salesforce: Shares fell 1.11% in the latest session but rose 10.16% over the past 20 sessions, with an RPS20 of 92.8. The value of AI in enterprise software must translate into seat pricing, automated workloads, and renewal rates. If agents merely replace existing functionality, revenue upside will fall short of the market’s expectations for new products.
“As model capabilities converge, competition will shift from absolute intelligence to the ‘cost per completed task’; the discussion around Kimi and GPT serves as a case study.”
“Inference computing, reinforcement learning, and distributed key-value caching increasingly require training-grade networking.”
GitLab: Shares rose 23.61% over the past 20 sessions, with an RPS20 of 99.3, trailing only the cybersecurity leader. Developer tools directly benefit from AI coding adoption but also face competition from open-source models and tools bundled with cloud platforms. Paid seats, enterprise net retention, and inference costs are key.
MongoDB: Shares fell 4.95% in the latest session and 6.68% over the past 20 sessions, with an RPS20 of 62.7. Databases are foundational to AI applications, but consumption-based models amplify customer optimization behavior. If new workloads fail to outpace cost reductions by existing customers, revenue growth and sales efficiency will come under pressure.
Figma: Expected revenue growth over the next 12 months is approximately 30.4%, placing it among the fastest-growing software companies. Generative design can broaden use cases but may also erode differentiation in basic functionality. Enterprise-customer expansion, collaborative seats, and monetization of new products will determine growth quality.
DigitalOcean: Expected revenue growth over the next 12 months is approximately 32%, above most mature cloud-software companies. AI deployment by small and medium-sized businesses creates opportunities, but DigitalOcean has a higher cost of capital and less procurement scale than hyperscalers. GPU utilization, customer churn, and free cash flow will determine whether growth is sustainable.
Samsara: Expected revenue growth over the next 12 months is approximately 21.4%. Connected devices and operational data create a real-world entry point for software, while AI can improve fleet and asset-management efficiency. Hardware subsidies, sales investment, and large-customer retention constrain potential margin improvement.
Cadence: Kimi K3 used open-source tools to complete the design of a functional semiconductor chip within 48 hours, after which Cadence shares fell more than 7%. The market is concerned that AI could erode the barriers around commercial EDA, but genuine replacement would need to cover verification, sign-off, and manufacturing accountability. The near-term impact resembles workflow automation more than the disappearance of the full toolchain.
“The entire workflow avoided commercial EDA software from industry leaders Cadence and Synopsys.”
Synopsys: Like Cadence, Synopsys faces challenges from AI-generated designs and open-source tools. Its commercial moat extends beyond circuit generation to IP, verification, customer qualification, and manufacturing workflows. If AI improves engineer productivity, the company may initially benefit from higher seat value; the risk is pricing pressure on lower-end design demand.
Consumer Electronics / Smart Vehicles
Apple
1) Shares rose 0.14% in the latest session and 12.77% over the past 20 trading days, with an RPS20 of 94.1, making Apple one of the few large-cap technology stocks maintaining strong momentum.
2) The M7 Ultra, rumored for launch around 2028, may support up to 1.5TB of unified memory, theoretically enabling local inference for models with approximately 1.2 trillion parameters. The specifications remain unconfirmed; on-device user experience and power consumption matter more.
“The bullish thesis assumes continued model compression and declining inference costs, with competitive moats potentially shifting from model capabilities to the endpoint hardware and privacy architecture that host the models.”
Samsung Electronics: Shares fell 8.77% in the latest Korean trading session and 29.66% over the past 20 trading days. The company is simultaneously downsizing its US consumer-electronics organization and preparing to launch new foldable devices, creating a divergence between end-market pressure and the memory upcycle. Whether the new products drive replacement demand will depend on weight, durability, pricing, and panel yields.
Tesla: Shares fell 2.61% in the latest session, 3.92% over the past 20 trading days, and 13.06% year to date. The market continues to assign a valuation premium for Robotaxi and Optimus, but 2026 robot production guidance ranges from 50,000 at the low end to 150,000 at the high end—a threefold range. Actual deliveries, unit costs, and operating hours matter more than demonstrations.
Agility Robotics
1) Approximately 100 Digit robots have accumulated more than 65,000 operating hours across nine customer sites, while GXO has used them to move more than 100,000 totes.
2) RoboFab is designed for annual capacity of up to 10,000 units, and multi-year orders for Digit v5 exceed US$300 million. Orders remain heavily dependent on a single major customer, while revenue has yet to be disclosed separately.
“Agility already has paying customers, real-world operating hours, a factory, and order signals, but remains in a capital-intensive, pre-scale phase.”
Leader Harmonious Drive Systems: The company holds more than 60% of China’s harmonic-reducer market and supplies Tesla’s Mexico production line; its products are priced at approximately 40%–60% of Japanese alternatives. Domestic substitution can expand market share but may also compress supplier gross margins. The key metrics are shipments, yields, and margins, rather than customer qualification alone.
MOONS’ Electric: A 22-degree-of-freedom dexterous hand requires 16–20 coreless motors measuring 6–8 mm in diameter, with a stop-response time of less than 10 milliseconds. The company’s products are priced 40%–70% below overseas alternatives, creating an opportunity from the localization of high-value miniature drives. Micron-level assembly and consistency remain the principal mass-production challenges.
“A 22-degree-of-freedom hand requires 16–20 coreless motors, each measuring 6–8 mm in diameter.”
Zhaowei Machinery & Electronics: Drives and sensors together account for approximately 80% of a dexterous hand’s cost. The company integrates motors, reducers, and lead screws into drive modules, generating higher content per unit than individual components. In-house development by robot OEMs could constrain the addressable market for third-party suppliers; key indicators include module design wins, mass-production yields, and customer concentration.
Haozhi Mechanical & Electrical: The company covers coreless motors, harmonic reducers, six-axis force sensors, and encoders, positioning it to meet multi-component integration requirements for dexterous hands. Its advantage is a comprehensive product portfolio; the risk is that simultaneously scaling multiple critical components increases R&D; and quality-control complexity.
STMicroelectronics: Flexible circuits and driver boards in the control layer account for only approximately 3% of a dexterous hand’s cost, but the main control chip is indispensable. The company has also repositioned its sensor and microcontroller businesses around physical and edge AI. Any meaningful incremental contribution must be validated through robotics customers, semiconductor content per robot, and the pace of mass production.
“Sensors account for approximately 30% of hand cost, including tactile skin, wrist torque sensors, and joint encoders. Tactile sensing offers the greatest upside but remains an immature frontier.”
Mobileye: Shares rose 2.79% in the latest session and 5.61% over the past 20 trading days, with an RPS20 of 90.2, making Mobileye a relative outperformer within the autonomous-driving group. The market is pricing in higher ADAS penetration and the resumption of customer programs; key indicators include design wins, content per vehicle, and the production cadence of designated vehicle models.
Aurora: Shares rose 1.85% in the latest session, 0.17% over the past 20 trading days, and 17.44% over the past 60 trading days. Autonomous trucks create value by increasing vehicle utilization and alleviating driver constraints, but commercialization must still be validated through safe-driving mileage, fleet scale, and cost per mile.
Aptiv: Shares fell 3.02% in the latest session, 8.59% over the past 20 trading days, and 26.73% year to date. Automotive electronics and advanced-driving content per vehicle continue to increase, but vehicle pricing pressure will pass through to component suppliers. The pace of recovery will depend on order conversion into production, margins, and customer concentration.
Symbotic: Shares fell 1.74% in the latest session but rose 2.69% over the past 20 trading days, with an RPS20 of 85.6. Warehouse robotics has a clear labor-substitution use case, while commercial value depends on project delivery, system reliability, and customer expansion. Heavy reliance on a single major customer will continue to amplify earnings volatility.
Intuitive Surgical: Shares fell 14.15% in the latest session and 14.11% over the past 20 trading days. Surgical robotics is a mature, high-value, tightly regulated application, and the market’s tolerance for growth or margin shortfalls has declined materially. Installed systems, procedure volumes, recurring instrument and accessory revenue, and the ramp-up of the new platform are prerequisites for a recovery.
Rockwell Automation: Shares fell 1.46% in the latest session but rose 0.69% over the past 20 trading days, with an RPS20 of 81.0. Industrial automation is generating revenue earlier than humanoid robotics, with AI-related upside concentrated in controls, machine vision, and maintenance. Manufacturing capital expenditure and order cycles remain the key external variables.
“The robotic hand is not merely an accessory to humanoid robots; it is the critical bottleneck for enabling general-purpose robots to perform physical tasks and the highest-cost standalone module, accounting for more than 30% of the bill of materials.”
Investment-Bank Target Price Changes Over the Past 12 Hours
None
Huang’s Selected Portfolio