404K SEMI-AI Morning Brief 2026-07-29 — Capital Rotates Toward Applications: Semiconductor Pullback and Software Strength Reflect AI Spending Repricing
目录
After-Market Summary
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
CSP/Cloud Capital Expenditure and AI Cloud
GPUs/CPUs/ASICs and Memory
Semiconductor Equipment, EDA, Packaging, and Supporting Infrastructure
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
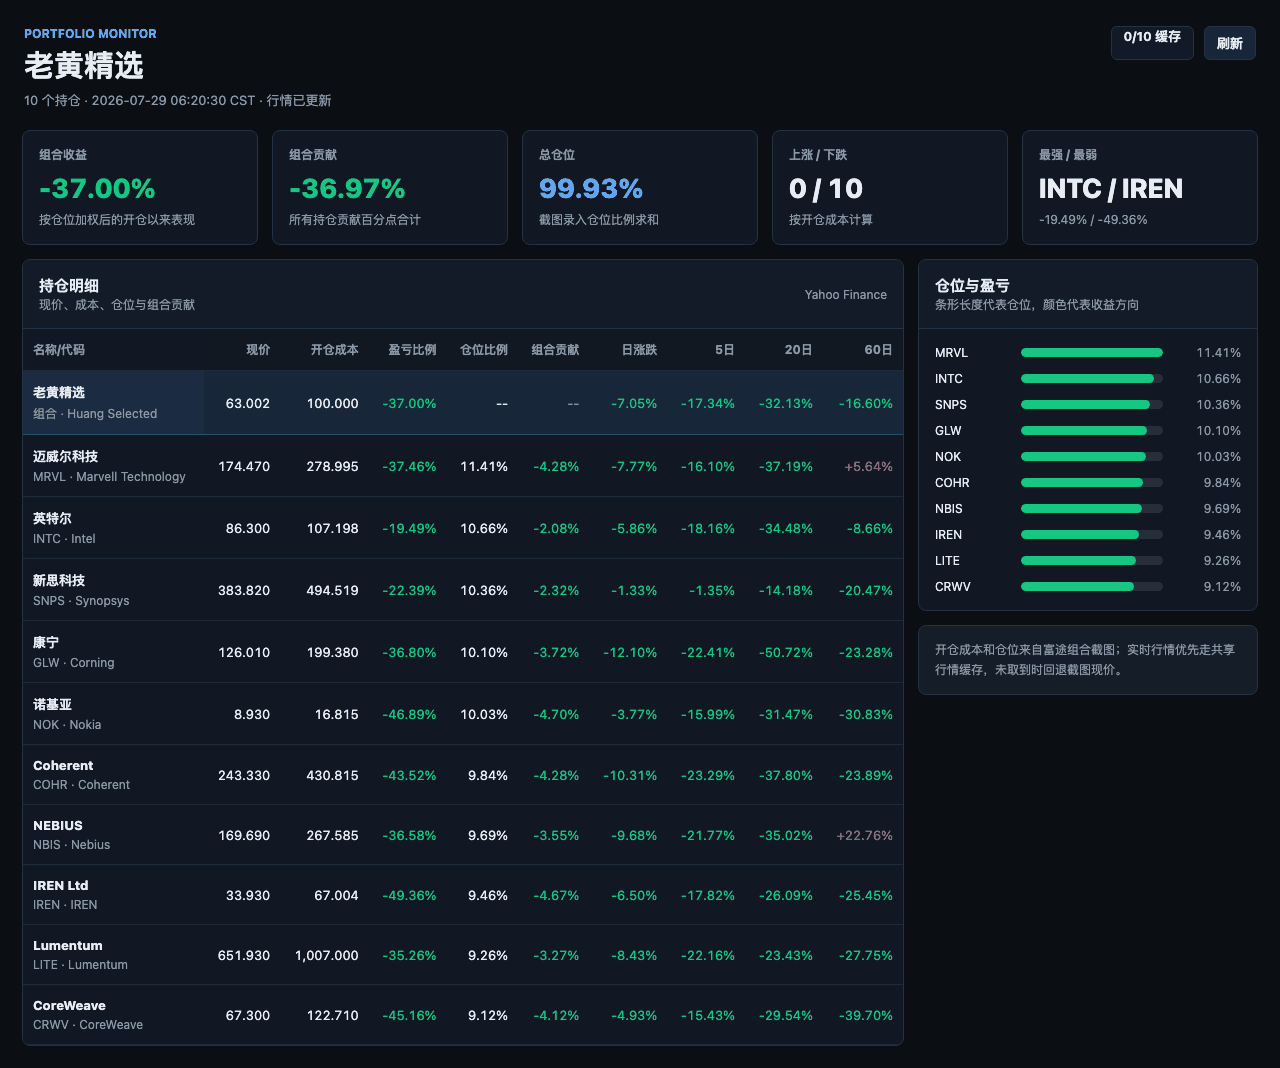
Jensen Huang Select Portfolio
AI infrastructure demand remains strong, but the market is beginning to scrutinize power, delivery, financing, and cash flow; declining model costs are simultaneously pushing capital toward software and applications.
404K SEMI-AI | 2026-07-29
After-Market Summary
The latest verifiable closing date is July 27. The S&P; 500 rose 0.02%, the Nasdaq 100 fell 0.31%, the equal-weighted S&P; 500 rose 0.75%, and the Russell 2000 rose 0.60%. The broader market has not lost momentum, but mega-cap technology underperformed equal-weighted and small-cap stocks, as capital broadened out from the crowded AI hardware trade.
The technology sector fell 0.90%, while the semiconductor ETF declined 2.25%, extending its 20-day loss to 10.31%; software and cloud-computing ETFs rose 3.33% and 2.94%, respectively. This does not mean AI demand has disappeared. Rather, the market is beginning to distinguish between “continued spending” and “when profits will materialize,” while lower model costs have expanded the perceived profit potential for software applications.
Stock-level divergence points to the same shift: NVIDIA, AMD, and SanDisk fell 4.99%, 5.17%, and 11.02%, respectively, while ServiceNow, Salesforce, and Palantir rose 6.86%, 6.07%, and 7.00%. The most important validations ahead are cloud providers’ capital expenditure, the commencement of data-center rent, and whether AI software can convert pilots into recurring revenue.
Full AI/Semiconductor Value Chain
AI Models/Applications and Capital Expenditure
Moonshot AI
1) Kimi K3 has 2.8 trillion total parameters, with activated parameters increasing from 32.6 billion to 104.2 billion, and active compute per token exceeding 3 times that of K2; the official deployment recommendation is a supernode comprising at least 64 accelerators.
2) A 1 million-token context increases the value of HBM, server DRAM, NVMe, and high-speed interconnects, but cache hits and low-precision computation will offset part of the incremental compute requirement; context length cannot be mechanically mapped to GPU count.
3) Reports indicate that inference capacity reached its limit within 48 hours of Kimi K3’s launch, and the company is seeking additional Blackwell compute for the larger Kimi K4.
“Stable LatentMoE reduces the amount of data that must be transmitted for each routing representation, but does not eliminate communication.”
OpenAI
1) The company believes inexpensive, high-quality models will remain available over the long term and continues to reduce the cost of smaller models through distillation; usage at scale means it does not need to rely on extremely high margins to fund training.
2) This implies that competition between frontier and open-source models will center on latency, price, and task quality rather than parameter count alone; key indicators to monitor include API pricing, inference utilization, and whether enterprise customers adopt tiered model usage.
“Open-source models will clearly occupy an important place in the world, and some people will want to own their own weights.”
Anthropic
Claude Opus 5 scored 74% in the DeepSWE long-horizon coding test, the highest score yet recorded on the benchmark. Improved coding capability supports enterprise-agent adoption, but annualized revenue calculated by multiplying a single month by 12 may overstate short-term growth. The metrics that truly require monitoring are customer-spending retention, whether lower-end tasks shift to cheaper models, and whether inference costs can decline concurrently.
CSP/Cloud Capital Expenditure and AI Cloud
Meta
The Louisiana data-center project is valued at $50 billion. Meta is selling an 80% interest and retaining 20%, while its partner is financing the project through $27.3 billion of bonds; the lease can be terminated every 4 years, while the associated power-generation assets are being built for a 30-year useful life. The structure reduces Meta’s upfront capital commitment but leaves financing, long-term power, and residual-asset risks with external capital. Key factors to monitor are campus delivery, lease stability, and the cost of capital.
Core Scientific
1) As of mid-July, 437 MW had begun billing, corresponding to 1.1 GW of leased capacity, approximately $635 million in annualized colocation revenue, and a disclosed gross margin of 59%.
2) The company’s initial capacity in partnership with AMD exceeds 500 MW, with expansion potential of up to 2.5 GW.
3) The primary cost constraint has shifted from chips to electrical and mechanical trades and construction labor; nominal megawatts generate revenue only after acceptance and the commencement of billing.
“Labor is now the primary driver of construction costs. Labor is currently extremely scarce across multiple markets.”
Applied Digital
Fourth-quarter revenue increased 407% year over year to $258.7 million, above the market expectation of $94.80 million, driven by AI customers’ demand for data-center capacity and long-term colocation contracts. The company also disclosed approximately 1.4 GW of critical IT load across 5 campuses and 3 take-or-pay leases with 15-year terms. The next step is not to focus on contracting rhetoric, but on power availability, customer acceptance, the commencement of rent, and the remaining construction capital requirement.
Galaxy Digital
The company acquired 500 acres of land for an AI and high-performance-computing campus in Texas, with an initial development scale of 74 MW, planned power delivery beginning in 2028, and the potential to expand to several hundred megawatts by 2030. The company will build its own private substation and water-supply infrastructure; the value of such projects depends on grid interconnection, financing, and tenants rather than nominal capacity in long-term plans.
Cipher Mining
The Black Pearl project has a direct 15-year lease with AWS, providing stronger contract credit than same-duration projects that depend on the creditworthiness of emerging cloud providers themselves. As power and data-center facilities become scarce assets, direct cloud-provider leases are easier to finance, but site control, the reliable power-delivery date, critical IT-load acceptance, and commencement of billing must still be verified individually. Mining-site power cannot be treated as directly equivalent to deployable AI capacity.
CleanSpark
The company signed a 20-year triple-net lease covering 175 MW of critical IT load, with the first delivery expected in the fourth quarter of 2027; up to another 885 MW remains at the letter-of-intent stage. The financeability of signed leases differs completely from that of indicative capacity. The most important metrics ahead are initial power delivery, construction capital, customer acceptance, and the rent-commencement date.
Nebius
Meta’s procurement of a dedicated GPU cluster under a 5-year contract shows that hyperscale cloud providers remain willing to exchange margin for delivery speed when their own capacity is insufficient. This type of hosted compute resembles bridge supply: its near-term value comes from immediate availability, while its long-term retention depends on whether cloud providers migrate workloads back after their own campuses come online and who bears the cost of GPU upgrades.
GPUs/CPUs/ASICs and Memory
AMD
1) On July 28, Citi maintained its Buy rating and $575 price target, forecasting second-quarter 2026 revenue of $11.3 billion and EPS of $1.66, and third-quarter revenue of $14.0 billion and EPS of $2.28.
2) MI455X is configured with 432GB of HBM, and the first Helios shipments are planned for September; the company says its tokens-per-dollar performance can be up to 30% higher than Vera Rubin NVL72.
3) Beginning in 2027, the company will secure more than 500 MW of data-center capacity, expandable to 2.5 GW, using infrastructure to lower the barrier for emerging cloud providers to deploy Instinct and Helios.
4) Risks include the GPU ramp, memory and wafer supply, customer concentration, and volatility associated with a high valuation.
“The first Helios shipments are planned for September, and Sanmina disclosed that its ramp is progressing as expected.”
NVIDIA
1) The stock fell 4.99% as of July 27 but remained up 2.07% over 20 days, indicating that short-term deleveraging has not yet fully disrupted its medium-term relative strength.
2) Supply-chain reports indicate that HBM4 costs may rise from $17–18 per GB to $31–32 per GB, while Vera CPU SOCAMM capacity may be reduced from 192GB to 96GB; otherwise, memory costs could account for nearly 29% of VR200 system bill-of-materials costs.
3) The company reportedly signed a lease worth up to $50 billion for Hut 8’s planned 1 GW campus; the tenant, subleasing arrangements, and final delivery still need to be verified, and the project cannot be valued solely on its nominal contract value.
“Rising memory costs are reportedly forcing NVIDIA to adjust Vera Rubin. The SOCAMM capacity of each Vera CPU may be reduced from 192GB to 96GB.”
Cerebras
The company plans to combine AMD CPUs, Helios, and its wafer-scale engine later in 2026 for ultra-low-latency inference. The partnership extends competition from individual GPUs to CPUs, rack-scale systems, and inference workflows; whether it generates revenue depends on customer deployment, software adaptation, and end-to-end latency rather than the peak performance of a single chip.
Seagate Technology
Fourth-quarter revenue was $3.63 billion, gross margin was 52.7%, and EPS was $5.71; guidance for the next quarter calls for revenue of $4.1 billion and EPS of $7.30, implying a gross margin of approximately 57%. Fiscal 2026 free cash flow reached $3.1 billion. Mozaic and HAMR are addressing cloud data-center capacity demand, but the sustainability of high gross margins, shipment cadence, and positive post-earnings momentum still needs to be validated.
Samsung Electronics
1) The company has approximately 39% DRAM market share and, together with SK hynix and Micron, controls approximately 90% of the market; high-value HBM remains the priority for profits and capital allocation.
2) The company is advancing a production line of approximately 50 D2W hybrid-bonding machines at Pyeongtaek P5 for next-generation HBM and 3D packaging of logic chips; equipment is expected to move in by year-end, but each machine costs approximately KRW6.0 billion and specifications remain under negotiation, so orders and the mass-production timeline have yet to be confirmed.
ChangXin Memory Technologies
The company rose 466% from its RMB8.66 offer price to RMB49 on its first trading day, raising RMB57.92 billion and closing with a market capitalization of approximately RMB3.3 trillion, with a free float of only 6.73%. Potential monthly wafer capacity may exceed 600,000 wafers, but expansion in standard DRAM does not equate to an HBM breakthrough. Key indicators ahead include shipments and average selling prices, HBM sample certification, mass-production yields, and the performance of equipment and materials in actual production.
SK hynix
The company has approximately 29% DRAM market share. SK Telecom plans to transfer its entire $200 million strategic equity interest in PENG to an SK hynix subsidiary for $380.3 million, corresponding to approximately 6.1 million shares, or 10.3%; this more directly links memory-supply cooperation with equity governance. Key factors to monitor are board rights, memory-supply arrangements, and customer expansion rather than the equity transfer alone.
Semiconductor Equipment, EDA, Packaging, and Supporting Infrastructure
KLA
Fiscal fourth-quarter 2026 revenue was $3.66 billion, up 15% year over year, with adjusted EPS of $1.05; semiconductor process-control revenue was $3.26 billion, up 13% year over year. Next-quarter revenue guidance is $4.0 billion, plus or minus $200 million. Demand is driven by advanced processes, increasing memory complexity, and advanced packaging, but free cash flow fell 23% year over year to $817.1 million, meaning profit conversion still depends on cash flow.
“The increasing number and complexity of advanced-node foundry/logic designs, together with rising complexity and performance requirements in memory.”
SCREEN Holdings
The company raised its net-profit forecast for the fiscal year ending March 2027 by JPY5.0 billion to JPY115.0 billion, representing 25% year-over-year growth; it raised its sales forecast to JPY743.0 billion and its operating-profit forecast to JPY156.5 billion. Demand for logic and memory equipment is strong, but the view that conditions will remain “strong for the next 2 to 3 years” still requires validation through orders, shipments, and gross margins.
Cadence Design Systems
Second-quarter revenue was $1.58 billion, up 24% year over year, with an adjusted operating margin of 45.5% and a record backlog of $8.1 billion; core EDA grew 18%, IP grew more than 40%, and System Design and Analysis grew 37%. AI agents could increase license demand and usage of underlying simulation tools, but 2026 guidance does not include large-scale agent-related revenue. The current valuation of approximately 43 times adjusted 2026 earnings requires sustained delivery of high growth.
“More design iterations may mean increased usage of the underlying tools.”
Corning
Core sales increased 17%, EPS increased 30%, Optical Communications grew 32%, and Enterprise Networks grew 65%; the company still expects approximately 16% sales growth and approximately 28% EPS growth in the third quarter, but the stock-price reaction was a decline of approximately 16% to 17%. Demand has not stopped; the issue is that the market now has higher requirements for guidance and valuation. Key indicators ahead are Enterprise Networks orders and free cash flow.
Applied Optoelectronics
The company’s differentiator is its in-house coverage of processes including InP laser epitaxial growth, giving it a more complete optical-component manufacturing chain. Vertical integration supports delivery and cost control, but performance must be validated through customer qualification, yields, shipments, and gross margins; revenue cannot be inferred directly from the technology chain. Capacity utilization must also improve concurrently.
ROHM
Citi noted that the company discussed AI data-center power architecture with Delta Electronics Japan: if the number of motherboards per rack increases 4 times, power-semiconductor and analog-semiconductor content could increase by up to 36 times and 56 times, respectively. The company covers SiC, GaN, silicon power devices, and analog-control chips, but the demand mapping still requires confirmation through orders and revenue; otherwise, the multiples remain component-content assumptions only.
Navitas Semiconductor
Baird maintained its Outperform rating and $20 price target, arguing that Wave 1 adoption of AI data-center power architecture was stronger than expected and that Wave 2 will drive future revenue. The thesis centers on high-voltage direct current and higher power density, but the price target was unchanged, while revenue conversion still requires validation through customer mass production, shipment cadence, and gross margins. Valuation upside is also constrained by the pace of production ramps.
Amkor Technology
Automotive and industrial revenue increased 17% quarter over quarter, driven by rising semiconductor content in advanced driver-assistance systems and advanced packaging. The data show that advanced-packaging demand has expanded from AI accelerators into automotive applications, but a single quarter’s sequential growth cannot represent the long-term trajectory. Key indicators ahead are automotive-customer inventories, packaging mix, capacity utilization, and gross margins, with particular attention to distinguishing inventory restocking from end demand.
Internet/Platforms
Amazon
1) The company said usage of its AI shopping assistant more than doubled in 2025, and more than 50% of shoppers are willing to let AI handle the entire purchasing process; its proprietary agent can reduce the risk of external assistants bypassing search and sponsored products, protecting its $72 billion advertising business.
2) The company is reportedly scaling back most Nova models and concentrating engineers and compute resources on fewer frontier models.
3) On July 28, UBS maintained its Buy rating and lowered its price target from $333 to $305 due to changes in the timing of AWS revenue recognition, but expects 2027 operating profit to be approximately 49% above market consensus.
“Making its proprietary agent the default option for Amazon and Alexa would help protect its $72 billion advertising business.”
Google
AI Overviews continue to account for a rising share of search, while visits to AI Mode are growing faster, indicating that the company is directing users toward conversational search. The shares rose 2.13% on July 27 but fell 7.22% over 5 days; product adoption and near-term trading performance are not aligned. The next key question is whether AI search increases query volumes, ad clicks, and cloud inference demand while keeping per-query costs under control.
“AI Overviews’ share of search is rising steadily and is becoming a core component of how people search.”
Uber
The company already has more than 20 autonomous-driving partnerships. The platform’s value lies in aggregating different fleets and sources of supply rather than betting on a single technology pathway. The shares were up 3.40% as of July 27 but down 10.52% over 20 days; the market is still assessing whether autonomous-driving orders can translate into lower driver costs and a higher platform take rate. Key indicators include the cities where services are actually operating, paid miles, and unit economics.
PDD Holdings
Following changes to the U.S. de minimis parcel policy, Temu’s revenue growth slowed from 8% in 2025 to 1% in Q1 2026. This directly compresses the logistics and customer-acquisition headroom of its low-price cross-border model. Key indicators include the share of local warehousing, fulfillment costs, return on advertising spend, and platform subsidies; beyond order volumes, margins and cash flow are more important.
“After the U.S. eliminated the de minimis exemption for parcels, its revenue growth slowed from 8% in 2025 to 1% in Q1 2026.”
Duolingo
The company faces a trade-off between user growth and monetization efficiency: AI can reduce content-production costs and improve personalization, but new features create value only if they translate into subscriptions, retention, and higher paid conversion. Key indicators include daily active users, subscription conversion, paid penetration of AI features, inference costs, gross margin, and cash flow; download volumes should not be used as a substitute for revenue quality.
Wayfair
The company is seeking to gain share in home-furnishings e-commerce, but household spending on durable goods remains a key external variable. Business validation depends on whether traffic converts into orders, fulfillment expenses decline, advertising and promotions erode profits, and adjusted EBITDA improvement comes from genuine gross-profit gains rather than reduced investment; cash flow must improve concurrently for the progress to be credible.
Shopify
The shares were up 11.54% as of July 27 and 8.57% over 20 days, placing the stock among the platform sector’s relative-strength leaders; however, they were still down 19.29% year to date, indicating that the valuation has not yet fully recovered. The rally demonstrates only that capital is returning, not that merchant growth or payments monetization has improved. Key indicators remain gross merchandise volume, payments penetration, and operating margin.
“Capital is flowing from AI infrastructure toward AI applications, triggered by the open-source wave. Kimi K3 and similar models continue to provide frontier-level capabilities for free.”
DoorDash
The shares were up 6.63% as of July 27, 0.70% over 20 days, and 8.88% over 60 days, outperforming most platform stocks in the near term. Investor preference for local services does not automatically imply improved order quality. Key validation points are total orders, advertising and membership revenue, courier and fulfillment costs, and whether the international business can reduce its drag on profits.
“Cheaper tokens mean lower costs to build better products, which in turn means broader adoption and entirely new use cases.”
Reddit
The shares were up 6.22% as of July 27 and 7.36% over 20 days but remained down 25.90% year to date. The relative strength may reflect improving expectations for advertising and data licensing. Key indicators include ad pricing, daily active users, search traffic, AI data-licensing revenue, and margins, rather than treating a one-day gain as a fundamental conclusion.
Pinterest
The shares were up 6.19% as of July 27 and 12.87% over 20 days, placing the stock among the platform sector’s relative-strength leaders, but they remained down 11.52% year to date. The market is betting on a recovery in social commerce and advertising efficiency. What must actually be validated is shopping-ad conversion, revenue per user, international monetization, and retention driven by content recommendations.
Netflix
The shares were up 0.44% as of July 27 and 4.14% over 5 days but down 4.62% over 20 days and 22.63% year to date. Near-term defensiveness has been stronger than that of AI hardware. Key indicators remain the ad-supported plan, paid-user engagement, content-spending efficiency, free cash flow, and the trend in churn following price increases.
AppLovin
The shares were up 5.29% as of July 27 but down 13.49% over 20 days and 33.25% year to date, indicating that the rebound in application monetization remains highly volatile. AI-optimized advertising has earnings significance only if advertiser retention, conversion rates, and the platform take rate remain stable; a one-day rebound is insufficient to demonstrate renewed growth acceleration.
Airbnb
The shares were up 4.08% as of July 27, 1.32% over 5 days, and 0.89% over 20 days, representing relatively resilient performance among platform stocks. Key indicators include nights booked, average daily rates, marketing investment, and expansion of the experiences business, which must also be validated against margins and free cash flow. Near-term trading performance indicates only investor preference and is no substitute for operating data.
Snap
The shares were up 3.91% as of July 27 and 2.49% over 20 days but down 24.41% over 60 days and 44.40% year to date. Near-term inflows have not yet reversed the longer-term weakness. Advertising demand, user engagement, augmented-reality investment, revenue per user, margins, and free cash flow will determine whether the recovery can be sustained.
The Trade Desk
The shares were up 3.41% as of July 27 but down 2.67% over 20 days, 26.63% over 60 days, and 52.55% year to date. Programmatic advertising remains affected by budgets and competition. Key indicators include customer retention, connected-TV share, platform spending, and operating margin, as well as confirmation of whether advertiser budgets are recovering.
Software/SaaS
F5
Q2 revenue was $865.1 million, up 10.9% year over year, systems revenue grew 32%, and gross margin was 84.2%; full-year revenue-growth guidance was raised to 9%–10%, while EPS guidance was raised to $17.21–$17.33. Direct AI customers increased 50% quarter over quarter and AI security customers doubled, but software growth slowed from 17% to 7%. The key question is whether the hardware refresh cycle can transition smoothly into software growth.
Datadog
BTIG maintained its Buy rating and raised its price target from $255 to $289; its fieldwork indicates that AI is driving observability spending and market-share gains. The shares were up 2.03% as of July 27 and 5.04% over 20 days. The price-target increase provides a sentiment catalyst, but the true operating validation remains AI-customer usage, net retention, and integrated penetration across logs, metrics, and traces.
“Analyst fieldwork indicates that AI is driving an inflection in observability spending, with Datadog among the primary beneficiaries and gaining market share from competitors.”
Dynatrace
Channel checks link AI inference, GPU monitoring, logging, and security requirements to observability spending, indicating that as the number of agents increases, fault diagnosis and cost control become more important. Key indicators include customer expansion, platform contract value, margins, and competitive share versus Datadog; industry demand should not be equated directly with company revenue.
Varonis
The company raised its full-year outlook, but SaaS net-new annual recurring revenue excluding the impact of contract conversions was only $31.50 million, below the approximately $37.00 million buy-side target, and the shares fell approximately 8% in response. Security demand remains intact; the issue is the quality of new-customer and conversion revenue. Key indicators include net-new ARR, renewals, sales efficiency, and cash flow.
“SaaS net-new ARR excluding conversions was only $31.50 million, below the approximately $37.00 million buy-side target.”
Commvault
Fiscal Q1 2027 results were driven by subscription revenue and SaaS growth. Management said AI benefits data-protection and resilience services, while the company is also facing hardware supply-chain constraints and expanding cloud partnerships. Key indicators include subscription ARR, the SaaS revenue mix, cloud-channel contributions, free-cash-flow quality, and whether hardware constraints weigh on delivery.
EPAM
The company joined the OpenAI partner network and plans to certify more than 5,000 consultants in the first year and more than 10,000 cumulatively worldwide; the platform of more than 20 AI agents that it deployed for 1&1 entered its first production environment in less than 3 months. Certifications are not revenue. The next indicators are project count, contract size, production deployments, and consultant utilization.
“The next era of enterprise AI is not about deploying models, but about applying strategic intelligence and the right talent.”
Cognizant
The company embedded Claude into its delivery platform and established a Claude-certified team of more than 30,000 employees. Training at scale indicates that enterprise service providers are converting model capabilities into implementation capacity, but the value depends on customer projects, delivery efficiency, and pricing rather than the number of certifications. Key indicators include generative-AI contracts, project gross margin, and whether automation dilutes the existing outsourcing business.
“By embedding Claude into its delivery platform and establishing a Claude-certified team of more than 30,000 employees.”
Twilio
The market is focused on organic growth, gross margin, and the Signal ’26 product roadmap. AI communications products have financial value only if they translate into higher usage of messaging, verification, and customer data. Key indicators are organic revenue growth, dollar-based net expansion, gross margin, large-customer retention, and whether the contribution from AI products can be identified separately.
Intuit
The risk of institutional investors lowering their target expectations stems from growth and valuation rather than a single product launch. Generative AI can improve tax preparation, accounting, and small-business services but may also increase competition and customer-acquisition costs. The revenue trajectory must continue to be validated by online-ecosystem revenue, paying customers, service costs, margins, long-term customer retention, and free cash flow.
ServiceNow
The shares were up 6.86% as of July 27, 7.34% over 20 days, and 18.75% over 60 days, maintaining strong relative strength within application software. Open-source models and lower token costs benefit workflow-AI gross margins, but the rally is running ahead of operating data. Key indicators include Now Assist net-new contracts, customer expansion, remaining performance obligations, and inference costs.
“Cheap tokens are turning agents from demos into deployable products, and that is where value will flow in the next phase.”
Salesforce
The shares were up 6.07% as of July 27 and 9.62% over 20 days but remained down 31.55% year to date, indicating a recovery from depressed levels rather than a complete trend reversal. Lower model costs can improve Agentforce unit economics, but the true validation remains the number of paid agents, Data Cloud adoption, contract value, and operating margin.
Snowflake
The shares were up 1.81% as of July 27, 9.62% over 20 days, and 93.26% over 60 days, placing the stock among the software sector’s relative-strength leaders. The market is betting that the data cloud will become the data foundation for enterprise agents; the strong rally has also raised expectations. Key indicators include product revenue, net revenue retention, customer compute consumption, and whether inference workloads can be sustained.
Palantir
The shares were up 7.00% as of July 27 and 16.47% over 20 days, making them one of the strongest software stocks, but they remained down 21.64% year to date. Renewed capital inflows indicate that the market is willing to pay for deployable AI applications. Fundamental validation still depends on the number of commercial customers, remaining deal value, U.S. commercial revenue, and margins, rather than a one-day gain.
GitLab
The shares were up 5.12% as of July 27 and 13.11% over 20 days, with relative strength near the top of the sector. AI coding capabilities will increase code generation while also raising demand for review, security, and DevSecOps. Key indicators include paid penetration of Duo, enterprise seats, net retention, and R&D; efficiency; growth in code volume should not be equated directly with revenue.
Cloudflare
The shares were up 1.32% as of July 27, 11.96% over 20 days, and 35.50% year to date. The edge network supports AI inference traffic while also providing security and cost control. Key indicators include Workers AI usage, large-customer contracts, gross margin, and capital expenditure, confirming whether traffic growth translates into high-quality revenue.
CrowdStrike
The shares were down 1.73% as of July 27 and 9.26% over 5 days but remained up 2.76% over 20 days. Microsoft’s launch of a vulnerability-discovery platform has increased competitive pressure on independent security vendors. To defend its valuation, the company must demonstrate that incremental modules, customer retention, and free cash flow generated by platform consolidation are sufficient to offset bundled sales by large platforms.
Consumer Electronics / Smart Vehicles
Apple
1) The company’s market capitalization briefly reached $5 trillion in Tuesday trading, making it the 2nd company to cross that threshold; as of July 27, the shares were up 1.17%, and up 18.72% over 20 days.
2) The company launched device leasing in the U.S. through Klarna, with iPhone leases starting at $17.99 per month and Apple Watch leases at $11.99 per month. Lease terms range from 12 to 24 months for these devices and from 24 to 36 months for Mac and iPad. Leasing could lower the barrier to device upgrades, but credit losses, residual values, and service revenue remain key variables.
“Nvidia’s market capitalization previously peaked at nearly $5.7 trillion, but has since declined amid market concerns about slowing AI spending.”
“The program offers lease terms of 12 to 24 months for iPhone and Apple Watch, and 24 to 36 months for Mac and iPad.”
Tesla
1) Delivery times for all Model Y variants in Canada have been pushed out to late 2026 or early 2027, indicating that the local annual allocation is nearly sold out, but this cannot be extrapolated to global demand.
2) The company signed a long-term agreement to purchase 90% of the Sterling project’s electricity. The project is scheduled to begin operations in 2028 and will include 509 MW of solar capacity and 360 MW of 4-hour energy storage.
3) As of July 27, the shares were down 1.22%, and down 18.56% over 20 days; key factors ahead include global deliveries, automotive gross margin, execution of energy-storage projects, and autonomous-driving commercialization.
“All versions of the Model Y in Canada currently show delivery dates in the final months of 2026, with some extending into early 2027.”
“The Arizona solar and energy-storage project is owned by KKR-backed ContourGlobal.”
NXP Semiconductors
2nd-quarter revenue was $3.5 billion, up 19% year over year and 10% sequentially, with EPS of $3.61; 3rd-quarter revenue guidance was $3.75 billion, with the midpoint only about 1% above consensus, and the shares fell approximately 5% in response. The industrial business drove the beat, while the automotive business made an insufficient contribution; the physical-AI thesis still requires delivery from software-defined vehicles, edge processing, and automotive-grade orders.
Skyworks
Quarterly revenue was $935 million, gross margin was 44.9%, and EPS was $1.08. Revenue and earnings were modestly above expectations, but free cash flow was weak and guidance offered limited upside, prompting an approximately 10% share-price decline. Demand exists across mobile devices, automotive, and data centers, but the market is more focused on cash-flow quality and incremental growth next quarter.
Qualcomm
As of July 27, the shares were up 1.84%, but down 10.22% over 20 days and down 1.70% year to date. On-device AI and automotive provide new growth avenues; key factors ahead include the handset-chip mix, licensing revenue, conversion of automotive orders into revenue, AI PC adoption, gross margin, and changes in free cash flow. A one-day rebound should not substitute for an assessment of operating fundamentals.
SpaceX
1) One bridge compute contract covers approximately 110,000 Nvidia GPUs and may be terminated on 90 days’ prior notice after December 31, 2026, reflecting a willingness to pay for delivery speed in the short term.
2) Commercial launch approval rules are proposed to be revised, with annual launches and reentries expected to increase from 214 this fiscal year to more than 500 within 10 years, although the proposal remains subject to public comment. The development is positive for launch cadence, but the final rules and execution remain decisive.
“The SpaceX contract covers approximately 110,000 Nvidia GPUs and may be terminated on 90 days’ prior notice after December 31, 2026.”
AST SpaceMobile
The company plans to launch BlueBird 11, 12, and 13 on a Falcon 9 on August 5, which is expected to nearly double Block 1 peak download speeds; BlueBird 14, 15, and 16 are also being prepared for the next launch. The catalysts are clear, but commercial validation still depends on successful orbital insertion, network testing, regulatory approvals, and paid connections—not the number of satellites itself.
Rocket Lab
As of July 27, the shares were up 4.74%, and up 1.83% over 5 days, but down 20.82% over 20 days. If commercial launch approvals accelerate, industry launch frequency could increase; the proposal has not yet been finalized and therefore cannot be factored into orders in advance. Key factors ahead include Neutron progress, Electron’s launch success rate, backlog, and space-systems revenue.
Intuitive Surgical
As of July 27, the shares were up 5.73%, but down 11.83% over 20 days and down 36.50% year to date. UBS initiated coverage with a Buy rating and a $500 price target; whether this valuation is sustainable still depends on procedure volumes, system installations, consumables and service revenue, capital-spending requirements, margins, and free cash flow.
Mobileye
As of July 27, the shares were down 0.50%, and down 10.50% over 5 days, but up 2.56% over 20 days. For autonomous-driving chips and solutions, the key factors are not demonstration capabilities, but automaker design wins, mass-production timing, and content value per vehicle; factors to monitor include design wins, inventory, vehicle models entering mass production, automotive-customer capital spending, and revenue recognition.
Aurora
As of July 27, the shares were up 4.37%, up 22.00% over 60 days, and up 60.47% year to date. The valuation of autonomous trucks depends on commercial mileage and safety redundancy, not one day’s trading; key factors ahead include driverless operating routes, fleet size, revenue per mile, remote-support costs, accident data, and regulatory approvals.
Aptiv
As of July 27, the shares were up 1.59%, but down 4.76% over 20 days and down 15.46% year to date. Demand for in-vehicle electronics and intelligent driving remains constrained by vehicle production volumes and platform design wins; key factors ahead include high-voltage architectures, active-safety content value, conversion of orders into revenue, and margins. Industry penetration rates should not be mapped directly onto company growth.
Symbotic
As of July 27, the shares were up 3.34%, and up 0.61% over 20 days, but down 27.65% over 60 days. The value of warehouse robotics must translate into customer capacity, system acceptance, and long-term service revenue; key factors ahead include deployment progress, backlog conversion into revenue, project gross margins, and customer concentration. A one-day rebound is insufficient to confirm an inflection point.
Rockwell Automation
As of July 27, the shares were up 0.83%, up 16.44% over 60 days, and up 16.92% year to date. Industrial automation benefits from manufacturers’ demand for greater efficiency through software, controls, and robotics, but the order cycle still depends on customer capital spending; key factors ahead include organic sales, orders, software ARR, margins, and free cash flow.
Blue Origin
If the proposed commercial launch approval rules are implemented, annual launches and reentries are expected to increase from 214 this fiscal year to more than 500 within 10 years, with Blue Origin among the potential beneficiaries. The proposal remains subject to public comment; key factors ahead include the final rules, New Glenn’s launch cadence, mission success rate, and order execution.
Jensen Huang Select Portfolio