404K SEMI-AI Morning Brief 2026-07-02 — Meta Compute Monetization, Strong Memory Pricing, Software Catches the Rotation
目录
After-Market Summary
Full AI/Semiconductor Value Chain
AI Models/Applications and Capex
CSP/Cloud Capex
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry, Equipment, and Advanced Packaging
MLCCs, PCBs, Optical Communications, and Power Infrastructure
Internet/Platforms
Software/SaaS
Consumer Electronics/Smart Vehicles
Investment Bank Target Price Changes Over the Past 12 Hours
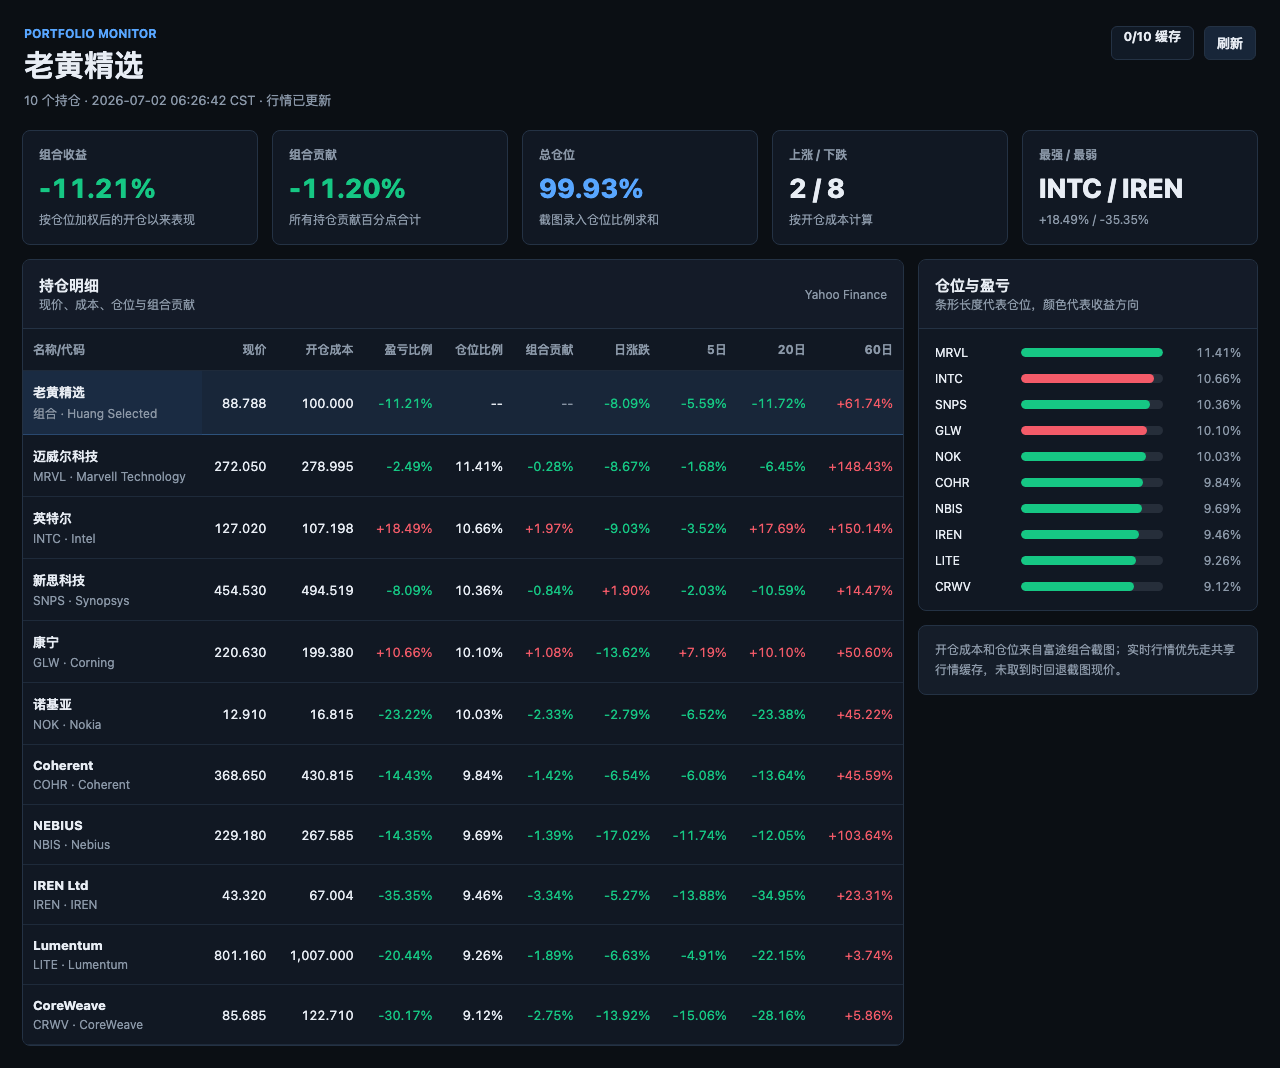
Huang’s Selected Portfolio
Meta Compute pushes the AI infrastructure trade from “keep buying GPUs” to “how do these assets earn money”; semis and memory are under short-term pressure, but DRAM/NAND, advanced packaging, MLCCs, power, and optical interconnects still have hard data support; software, security, and platform stocks absorbed capital after hardware momentum pulled back.
After-Market Summary
U.S. equities showed clear divergence at the 2026-07-01 close: the S&P; 500 fell 0.28%, Nasdaq 100 fell 1.69%, equal-weight S&P; rose 0.30%, and Russell 2000 fell 0.52%. The technology ETF fell 2.57%, the semiconductor ETF fell 5.32%, and the equal-weight semiconductor reference fell 6.42%; by contrast, the software ETF rose 3.02%, cloud computing rose 1.29%, and cybersecurity rose 1.40%. The market was not simply de-risking. It was rotating out of semiconductor momentum into software, platforms, and defensive cash-flow names.
The marginal change in the AI theme came from Meta: the market interpreted its plan to sell AI compute externally as a revenue outlet for capex, sending Meta up 8.84% on the day. But the same logic pressured independent AI cloud and semiconductor chains: Oracle fell 2.63%, Broadcom fell 2.31%, TSMC ADR fell 6.95%, Micron fell 10.99%, and SanDisk fell 11.67%. This shows investors are starting to ask: who is merely a recipient of capex, and who can turn compute assets into revenue?
There is still counterevidence within sectors. DRAM, NAND, enterprise SSDs, advanced packaging, MLCCs, and data-center power have not seen demand invalidation; this looks more like a cooling of crowded trades. The rebound in software and security was not purely defensive either: Microsoft rose 2.81%, Palantir rose 7.63%, Salesforce rose 4.19%, ServiceNow rose 6.16%, Snowflake rose 2.63%, and CrowdStrike rose 10.22%, indicating capital is searching for later-cycle monetization paths in AI applications and operations.
Full AI/Semiconductor Value Chain
AI Models/Applications and Capex
OpenAI/SoftBank
On 2026-07-01, SoftBank executed its second $10 billion follow-on investment in OpenAI Group PBC through Vision Fund 2, part of the $30 billion plan announced on 2026-02-27. The first tranche was executed on 2026-04-01, and the remaining $10 billion is expected to be completed on 2026-10-01. Capital continues to flow into frontier models, but the report did not provide confirmed figures showing order pass-through to Oracle, CoreWeave, Nvidia, or AMD.
"Executed a second follow-on investment of $10 billion in OpenAI Group PBC"
AI Token Usage
JPMorgan tracking shows that in June 2026, OpenRouter token volume rose 70% MoM and 20x YoY, while token spending rose 70% MoM and 16x YoY. U.S. models’ volume share fell to 35%, but their spending share remained above 85%. These figures support continued expansion in inference demand and help explain why GPU rental prices are still rising.
Claude/Sonnet
Sonnet 5 token usage was cited at 1x to 1.35x the comparison baseline, theoretically positive for ARR, but the materials did not provide adoption rates, customer counts, call volumes, or cloud resource consumption. This data point is suitable for monitoring usage elasticity in AI applications, but cannot be directly extrapolated into semiconductor orders.
Sovereign AI
Enterprise model selection is shifting from “who is the strongest” to “how should access rights and policy risk be managed.” The materials explicitly discuss whether enterprises may shift from OpenAI and Claude to Chinese models, and note the rising importance of sovereign AI. The investment implication is that regional cloud, data residency, and local models will become procurement constraints, but there are currently no verifiable revenue figures.
Enterprise AI Applications
Palantir is described as the enterprise AI data sovereignty layer. 1Q26 revenue was $1.63 billion, up 85% YoY; U.S. commercial revenue rose 133% YoY; U.S. government revenue rose 104% YoY; the company signed 47 deals above $10 million in the quarter; and full-year guidance is $7.65 billion. The business question for AI applications is whether sensitive data can remain inside the customer environment, not just how model parameters compare.
"1Q26 revenue was $1.63 billion, up 85% year over year"
CSP/Cloud Capex
Meta
1. Meta is commercializing surplus AI compute and hosted model access, and the market first traded it as capex converting into revenue: the stock rose 8.84%, with multiple data points indicating it was up close to 10% intraday. But this also pressured semiconductors and AI cloud, as investors began questioning whether hyperscaler capex will continue to be revised upward.
2. Counterevidence on Meta: interpreting Meta Compute directly as compute oversupply is not robust. The materials also mention Meta’s AI compute agreement with CoreWeave, extending to 2032 and worth about $21 billion, its agreement with Nebius worth up to about $27 billion, and its lease of roughly 1.6GW of data-center capacity from Crusoe. A more reasonable point to watch is the start of tiered pricing across older GPUs, frontier clusters, and inference capacity.
"Meta is building a cloud business, selling surplus compute from its overinvested data-center clusters"
Google
Several materials frame Google as counterevidence to Meta’s compute constraint: Meta’s access to Gemini compute was limited due to capacity constraints. This does not provide Google Cloud revenue or a price target, but it shows frontier-model compute resources remain bottlenecked, so AI infrastructure demand should not be judged as peaking simply because Meta is selling some compute externally.
Microsoft
Microsoft rose 2.81% in the market data. The report notes a new round of layoffs affecting less than 2.5% of employees and also places Maia, its in-house chip, within the framework of accelerating CSP-designed inference chips. Microsoft’s core question is whether Copilot/cloud AI can deliver revenue while in-house chips reduce inference costs.
Amazon
Amazon rose 1.22%. The materials place Trainium 3 alongside Microsoft Maia, Meta MTIA, and Google TPU as parallel demand engines over the next several years. This indicates cloud vendors are not only buying Nvidia for inference cost management; they are also competing for TSMC advanced nodes, advanced packaging, and OSAT capacity.
AI Cloud/Data-Center Operators
CoreWeave
CoreWeave was hit by the Meta Compute news, with data points showing a roughly 12%-14% decline. Rosenblatt still reiterated Buy and a $250 price target, saying GPU shortages remain the industry norm and that Meta may not necessarily have the right to resell capacity leased from CoreWeave through 2032. The core debate is resale rights under lease contracts and the price curves of old versus new GPUs, not one day’s share price.
"Meta recently signed a new $21 billion AI compute agreement with CoreWeave"
Nebius
Nebius is under pressure from the narrative that a customer has become a competitor. The materials show Meta’s five-year agreement of up to about $27 billion includes $12 billion of Vera Rubin dedicated capacity for delivery in early 2027 and up to $15 billion of flexible capacity, with backlog of roughly $50 billion. If this capacity has already been allocated to other customers, Meta Compute is more of a valuation shock for Nebius and not necessarily a signal of contract cancellations.
Applied Digital
Applied Digital delivered 75MW of AI capacity at Polaris Forge 1, with Phase 1 of Building 2 reaching Ready for Service and total live capacity rising to 175MW. Long-term leases cover 400MW, and the campus is fully leased. This signal matters more than pure share-price moves: valuations for AI cloud operators depend on whether power, delivery, and customer leases can convert into usable capacity on schedule.
"Polaris Forge 1 has increased to 175 MW"
IREN/TeraWulf/Cipher Mining
IREN, TeraWulf, and Cipher Mining were placed in the neocloud pullback basket. The materials showed moves such as IREN -4% and TeraWulf -5%, but lacked new customer, capacity, financing, or contract figures. We only retain the sentiment transmission here: the market is starting to worry that Meta’s entry into cloud could pressure GPU cloud rental prices. The next thing to watch is whether power advantages can become long-term cost barriers.
Bloom Energy/Power
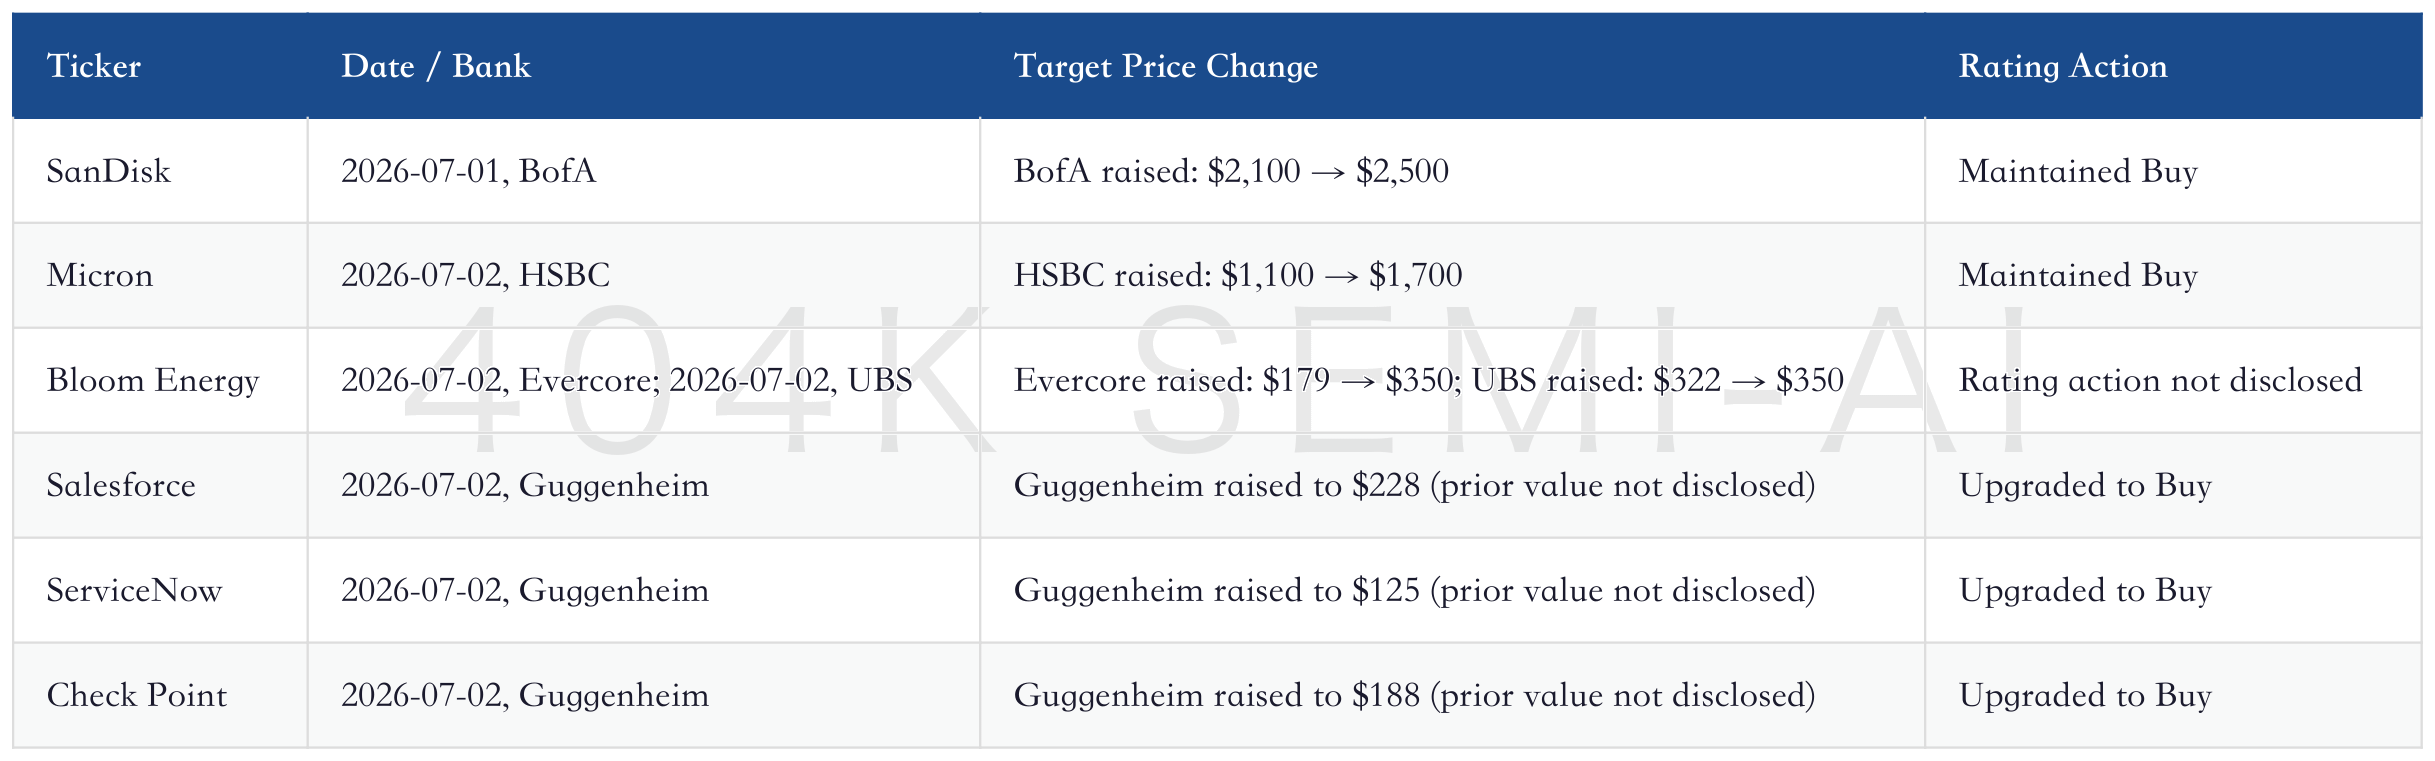
Bloom Energy’s AI infrastructure power partnership with Brookfield expanded from $5 billion to $25 billion, supported by Brookfield’s planned $100 billion AI Infrastructure Fund. Separately, Evercore raised its Bloom Energy price target from $179 to $350, and UBS raised its target from $322 to $350. The power bottleneck is shifting from total generation to grid-connection speed and on-site power delivery.
GPU/CPU/ASIC
GPU Rental Prices
JPMorgan data shows the A100’s average June price was $1.63/GPU-hour, up 6.3% MoM, marking the fifth consecutive month of growth; H100 was $2.72/GPU-hour, up 3.7% MoM, marking the seventh consecutive month of growth; and B200 was $5.33/GPU-hour, up 2.7% MoM. Absolute rental prices are still rising, indicating demand has not disappeared. The narrowing B200/H100 premium shows incremental high-end supply is starting to change the pricing structure.
"The A100’s average June price was $1.63/GPU-hour"
Nvidia
Nvidia fell 1.48%. The materials include both semiconductor momentum pullback and counterevidence that Blackwell/Rubin capacity and delivery cycles remain tight. UBS data indicates Vera CPU shipment forecasts were raised from 1.6 million units in 2026 to 5.5 million in 2027, while Rubin GPU sees a slight delay in 2Q26 but rebounds in the second half. The company is under short-term pressure mainly because valuations of capex recipients are being reassessed.
AMD
AMD fell 6.98%, but several materials still place server CPU and CoWoS demand on an incremental growth track. UBS data shows AMD Venice shipments rising from 1.3 million units in 2026 to 4 million in 2027, while AMD CoWoS demand may grow 232% in 2027. Trading pressure comes from deleveraging in AI chip stocks. The fundamental checkpoints remain EPYC, the MI series, and the Helios roadmap.
Intel
Intel fell 9.05%. The real new items worth noting are not PCs, but process and foundry-related developments: Intel is expanding its Santa Clara campus to increase EUV photomask output, involving 18A and 14A. Separately, Oxmiq’s founding team has Intel and AMD backgrounds and raised $35 million to build licensable IP combining CPU, GPU, and tensor engines. Intel needs foundry customers and yield to prove a turnaround.
Broadcom/Marvell Technology
Broadcom fell 2.31%, and Marvell Technology fell 8.59%. The materials place both in the AI ASIC and networking chip basket, which was clearly hit by the Meta Compute narrative. But the true AI bottlenecks still cover custom silicon, networking, HBM, and advanced packaging. The short-term issue is valuation and customer capex cadence; the long-term question is whether ASIC projects move from a single customer to multiple hyperscalers in parallel.
Qualcomm
Qualcomm fell 1.68%. The materials show an early AI device prototype is expected to use a Snapdragon chipset, but the project is still early, the design may change, and mass production is uncertain. This clue can only indicate that edge AI entry points may again raise the strategic value of mobile SoCs. It cannot be treated as order or revenue confirmation.
MediaTek
Goldman Sachs raised MediaTek’s price target to 6,800 in local currency, citing a major upward revision to AI ASIC forecasts: 2027 AI ASIC revenue forecast was raised from $12.3 billion to $20.3 billion, and 2028 from $28.4 billion to $52.5 billion, with AI ASIC potentially reaching 49%/69% of revenue. The market is repricing MediaTek from a mobile-chip vendor into a custom AI chip platform.
HBM/DRAM/NAND/SSD/HDD
Micron
Micron fell 10.99%, but the fundamental anchors remain strong: HSBC raised its price target from $1,100 to $1,700 and maintained Buy. The materials show Q3 revenue of $41.46 billion, data-center revenue above $25 billion, and 16 strategic customer agreements. On pricing, conventional DRAM is expected to rise 13%-18% QoQ in 3Q26, PC DRAM 15%-20%, server DRAM 13%-18%, NAND 10%-15%, and enterprise SSDs 18%-23%. The trade is punishing crowding; memory supply-demand has not yet been invalidated.
"memory demand continues to outpace supply"
SanDisk
SanDisk fell 11.67%, but BofA raised its price target from $2,100 to $2,500 and maintained Buy, citing expectations that the NAND market supply-demand imbalance will persist through all of 2027 and that pricing will remain “strong for longer” into mid-2027. The price-target hike and share-price plunge happened on the same day, showing the market was selling the AI capex narrative and momentum positioning, not the NAND pricing logic itself.
"supply/demand imbalance in the NAND market to remain through C27"
Samsung Electronics
Samsung Electronics fell 5.84% on an ADR basis. The materials show HBM4E reliability test yield above 70%, while a mature state is usually above roughly 80%; HBM4 shipments began in February 2026, 12-layer HBM4E samples were delivered in late May, and the D1d DRAM process targets PRA in November 2026. The investment question for Samsung is whether HBM4E can shift from catch-up mode to stable share.
SK Hynix
SK Hynix fell 3.40%, but the materials show it effectively monopolizes HBM3E, has more than 60% share in HBM4, and is discussing an ADR plan. Korean technology export data is also strong: June semiconductor exports were $44.8 billion, up 199.5% YoY; DRAM including modules was $21.846 billion, up 385% YoY; MCP/HBM was $12.681 billion, up 171% YoY. This remains hard evidence of a strong memory upcycle.
Seagate/Western Digital
Seagate fell 5.58%, and Western Digital fell 6.69%. The electronic components report shows nearline HDD and enterprise/data-center SSD capacity continued to grow in May 2026, and data-center storage demand did not disappear because of Meta news. Both companies were dragged down short term by the memory basket pullback. Follow-up checkpoints are enterprise drive capacity, SSD pricing, and cloud customer inventory.
Apple/China Memory Supply Chain
Apple is reportedly in talks to procure memory chips from CXMT and YMTC for devices sold in China, as AI-driven memory shortages push up component costs. This data point is a dual price and policy variable for Micron, Samsung, and the domestic memory supply chain: customers want lower costs, but compliance and supply stability will determine actual share.
Foundry, Equipment, and Advanced Packaging
TSMC
TSMC ADR fell 6.95%, but advanced packaging expansion signals remain strong. Nomura data says TSMC’s 2027 CoWoS capacity forecast has been raised to 2,000kpcs, up from 1,100kpcs in 2026; Google TPU’s CoWoS share rises to 26% in 2027, while Nvidia is about 55%. TSMC’s bottleneck is extending from wafer manufacturing to CoWoS, WoS, substrates, and materials.
"TSMC… From 1,100kpcs in 2026 to 2,000kpcs by 2027"
ASML/Applied Materials/Lam Research/KLA
Semiconductor equipment stocks pulled back together in the market data: ASML fell 7.31%, Applied Materials fell 9.96%, Lam Research fell 9.66%, and KLA fell 11.75%. Susquehanna added that it raised ASML’s price target from EUR1,475 to EUR2,350, Lam Research from $385 to $475, and Applied Materials from $575 to $900, and said wafer fab equipment spending could peak at $300 billion. The short-term selloff comes from semiconductor deleveraging, while order expectations are still driven by advanced nodes and packaging.
Selective Etch
The Tessara report places the key rent in GAA and advanced nodes on selective etch, noting that leading-edge processes are mainly covered by Lam Research, Applied Materials, and Tokyo Electron, with slow qualification and delivery cycles of more than one year. The investment implication is that N2/N2P/A16, GAA, and AI accelerator ramps will increase etch steps. But equipment stocks already reflect a meaningful amount of expectation; the next things to watch are customer cleanrooms, yield, and installation pace.
ASE/Amkor/OSAT
The materials show ASE raising advanced packaging prices by more than 20%, 2026 packaging and testing unit prices rising 5%-20%, and memory OSAT possibly rising up to 30%. Capex rose from about $2 billion to $5.3 billion in 2025 and $8.5 billion this year. Back-end engineering is no longer cheap outsourcing; it has become a pricing link in AI chip delivery.
Semiconductor Inventory
Semiconductor inventory tracking shows total supply-chain DOI increased by 9 days QoQ, below the seasonal increase of 19 days, but still 33 days above the historical median. Distributors continue to destock, while producer builds are relatively stable. The investment implication is that the sector has not entered a broad restocking cycle. Priority should remain on memory, advanced packaging, equipment, and AI networking, where supply-demand tightening is clearer.
MLCCs, PCBs, Optical Communications, and Power Infrastructure
Yageo/MLCC
Yageo raised prices across its capacitor product portfolio from 2026-07-01, covering tantalum capacitors, MLCCs, aluminum electrolytics, conductive polymer aluminum capacitors, film capacitors, and supercapacitors. These categories account for about 50% of total company revenue, while tantalum capacitors and MLCCs account for about 43%. The materials also say overall utilization is above 80%, and premium MLCC utilization is above 90%. Passive components are moving from inventory repair into demand driven by AI servers and automotive-grade applications.
"Yageo… utilization is over 80% overall, with premium MLCCs above 90%"
Samsung Electro-Mechanics
Samsung Electro-Mechanics is placed in the AI data-center MLCC supply-contract line, with a contract size of about KRW450 billion. Meritz raised its price target to KRW3 million and lifted its 2027 MLCC ASP increase assumption to 37.0%. The MLCC logic is not just price hikes; high-end server power density and reliability requirements are lifting ASP.
PCB/Substrates
Materials frame Korean substrate makers’ price-cut requests as background noise. The real constraints are BT capacity, T-Glass, CCL, ABF, and advanced packaging substrates. A report related to Victory Giant Technology says momentum should recover from Q3 with more new customers, while AI server PCBs and high-layer-count boards remain the core tracking points. This segment needs validation through mass production by new customers, not just pricing rumors.
Optical Communications/AAOI
The optical communications roadmap continues to migrate from 400G to 800G, 1.6T, and 3.2T: 800G/100G lane drives shipments in 2024-26; 1.6T/200G lane is the next wave in 2026-28; and 3.2T may enter the CPO era. For names such as Applied Optoelectronics, the key is not only current-quarter gross margin, but whether they can sit on the latest speed tier.
Nokia/Optical Networks
Nokia is included in the line that optical networks and IP networks are supported by AI infrastructure, with the report title directly pointing to “AI infrastructure buildout supports an upgraded outlook for optical networks and IP networks.” No new order figures were seen, so we only place it on the watchlist for data-center interconnect and transmission equipment, avoiding turning ordinary communications equipment news into an earnings conclusion.
Vertiv/Liquid Cooling and Power Modules
Vertiv opened a manufacturing facility in Johor, Malaysia, covering liquid cooling, power modules, Power Skid, and SmartRun. It is expected to create hundreds of technical jobs once fully operational in 2027. Power Skid/Power Module can reduce deployment time by up to 50%, and SmartRun can improve on-site deployment speed by up to 85%. The data-center supply bottleneck is shifting from GPUs to deployment speed, power modules, and liquid-cooling delivery.
Korean Power Equipment
Citi says high-voltage transformers and GIS exports to the U.S. remain strong on a half-year horizon. LS Electric’s 2Q26 new orders are expected to reach KRW2 trillion, doubling from KRW1 trillion in 1Q26; by order source, 20%-30% comes from renewable energy and 20%-30% from hyperscalers. AI data centers are pulling grid equipment from cyclicals into visible orders.
Internet/Platforms
Meta
Meta rose 8.84%. The platform-stock narrative shifted from “AI capex pressures profits” to “can compute assets be externally monetized?” Wells Fargo-related views noted that 10GW of excess capacity could potentially generate $200 billion in revenue and $55 in EPS by 2028, but this remains scenario analysis. What really needs tracking is whether Meta Compute has customers, pricing, utilization, and gross margin, not just slogans.
Google
Google rose 1.06%. In the thread, it is both the counterexample to Meta being constrained by Gemini compute and a source of demand for self-developed TPU chips. Google’s investment implications split into two questions: whether models and search advertising can continue to commercialize, and whether TPUs and cloud infrastructure can achieve higher returns on assets within AI capex.
Amazon
Amazon rose 1.22% and became a potential competitive reference point under the Meta Compute narrative. If Meta sells hosted model access, the format would resemble AWS Bedrock; if it sells raw compute, it would be closer to GPU cloud. The validation points for Amazon are AWS AI backlog, Trainium adoption, and cloud gross margin, not the Meta news itself.
Microsoft
Microsoft rose 2.81%. Investors linked layoffs to AI productivity, but the materials did not provide new financial figures. The core question remains whether Copilot, Azure AI, and the Maia in-house chip can simultaneously lower inference costs, improve customer retention, and convert AI investment into recurring revenue.
Apple
Apple rose 1.50%, but the truly relevant clue today was storage procurement: Apple is reportedly considering sourcing memory chips from CXMT and YMTC for devices sold in China. Rising AI-device costs are pushing Apple to seek more supply-chain options, but compliance, political risk, and product pricing power will determine whether this can be implemented.
Netflix
Netflix rose 3.59%. In market terms, it was part of the platform-stock rebound, but these materials contained no new content, advertising, or subscriber data. Here it is kept only as an observation point for capital returning to internet platforms, not expanded into a fundamental theme.
Reddit
Reddit was listed in the thread as one of the overlooked platform stocks, regaining attention alongside AI applications and data-licensing deals. The materials did not disclose new contracts, revenue, or target prices, so the focus is the optionality of platform data assets in AI training, search distribution, and advertising monetization.
Shopify
Shopify was included in the platform-stock rotation list. The report noted that among overlooked stocks, Shopify was up roughly 7% on the day. This looks more like capital rotating from hardware momentum into applications and platforms than a sudden change in company fundamentals; follow-up indicators are merchant GMV, AI-tool usage, and advertising/payment attach rates.
Airbnb
Airbnb appeared on the 52-week-high list in the new-high scan, with a one-day gain of 3.80%, but the mandatory new-high table at the start of the morning note was empty, indicating there was no qualifying stock-specific event anchor to support a standalone table. Here it is treated only as a marginal clue in recovering platform-stock risk appetite, not as a core catalyst today.
Uber/DoorDash
Uber and DoorDash appeared in the internet-platform list, with no orders, revenue, regulatory developments, or formal investment-bank actions observed. Their shared question is whether AI dispatching, local services, and advertising can improve unit economics, but they do not constitute the main thread today.
Circle/Stablecoin Infrastructure
The stablecoin thread showed USDC supply of roughly $74 billion and expected stablecoin scale of up to $3 trillion by 2030, versus about $310 billion currently. This is more fintech infrastructure than internet/platform and is not included in the target-price table at the end. Within internet/platforms, it is only a reminder that payment APIs and agentic transactions could become part of the AI application stack.
Platform-Stock Rotation
The thread showed capital flowing into platforms, advertising, and software after profit-taking in semiconductors: Meta, Reddit, Coinbase, AppLovin, Palantir, Shopify, ServiceNow, and others were included in the rebound list. The investment implication of this rotation is that the AI trade is beginning to spread from capex recipients to platform companies with users, data, and cash flow.
Risks
The risk for internet platforms is not that “AI is useless,” but that profit distribution across compute, models, data, and advertising revenue has not yet stabilized. If Meta Compute pushes down GPU cloud rental prices, it will hurt independent clouds; if it merely improves Meta’s asset turnover, it could instead reinforce the valuation advantage of large platforms.
Software/SaaS
Software ETF
The software ETF rose 3.02% on the day, the cloud computing ETF rose 1.29%, and the cybersecurity ETF rose 1.40%; meanwhile, the semiconductor ETF fell 5.32%. One thread showed IGV up roughly 11%-12% over five trading days, with software up 7.5% since June 23 and SOX down 7.5%, a relative spread of about 15 percentage points. Software is absorbing capital after the AI hardware pullback.
"Performance since June 23: Software +7.5%, SOX -7.5%"
Salesforce
Salesforce rose 4.19%. Guggenheim upgraded it to Buy with a $228 target price. The rationale was not immediate AI-driven upside, but that 3.7x recurring revenue and 11x EV/NTM FCF already embed excessive pessimism, implying about 46% upside. This logic is closer to valuation repair: after AI risk has been fully priced in, the stock has elasticity as long as core customer retention remains stable.
ServiceNow
ServiceNow rose 6.16%. Guggenheim upgraded it to Buy with a $125 target price, emphasizing that insufficient evidence of AI monetization is not a “death knell.” ServiceNow’s business question is clear: whether enterprise workflow software can use agentic AI to increase workflow value while preserving subscription renewal rates and seat expansion.
Check Point
Check Point was upgraded to Buy with a $188 target price. The thread showed it currently at 4.3x EV/NTM recurring revenue and 8.0x EV/NTM FCF, discounted versus security peers at 11.6x and 35x. The core logic for security software is that as the AI attack surface expands, enterprise budgets may not necessarily be cut; instead, investors may place more value on stable cash flow and low valuation.
CrowdStrike
CrowdStrike rose 10.22%. The thread showed cybersecurity and cloud observability companies being repriced by the market because the more complex inference and agentic AI become, the more enterprises need monitoring, compliance, security, and operational reliability. This is not merely an “AI concept”; the more AI is deployed, the higher the cost of failures and attack surfaces.
"market starts pricing in software companies which truly benefit from inference and agentic ai"
Palo Alto Networks
Palo Alto Networks rose 3.23% and appeared in both the all-time-high and 52-week-high lists in the new-high scan, with a one-day gain of 3.37% and a one-week gain of 24.28%. The thread also noted that its valuation is already high, at 24x sales, 68x EBITDA, and 90x PE. Both fundamentals and valuation are strong; the near-term risk is crowded momentum chasing.
Datadog
Datadog rose 1.58%. The thread grouped it with CrowdStrike and Palo Alto Networks as beneficiaries in cloud observability/cybersecurity. The more complex AI inference, agent workflows, and multi-cloud architectures become, the more enterprises need visibility into operating costs, latency, failures, and security incidents. Datadog’s validation points are large-customer expansion and net retention.
Snowflake
Snowflake rose 2.63%. Market data showed a five-day gain of 15.60% and roughly flat performance over 20 days. It is the foundation for data cloud and AI applications, and after the hardware pullback, capital is again looking for elasticity in data assets and the application layer. Follow-up indicators are whether Cortex, data sharing, and compute costs can translate into revenue growth.
MongoDB
MongoDB rose 6.99%, with a five-day gain of 18.83%. The materials did not provide new earnings, but databases, as the foundation for AI applications, benefit from the application-layer rotation. The investment question is whether generative AI applications can drive Atlas consumption and whether enterprise IT budgets are moving from experimentation to production deployment.
Cloudflare
Cloudflare rose 0.46%. The materials did not provide new official data, but the company sits at the intersection of edge cloud, AI networking, and security. As AI application traffic rises, demand for edge inference, secure access, and API protection should increase; the risk is that valuation already implies high growth, so revenue delivery needs to keep pace.
Rubrik
Rubrik entered the AI security and agent-governance thread: Project Glasswing received Mythos Research Preview access, using frontier AI to identify, validate, and remediate software risks in enterprise platforms. The materials did not provide financial figures, but the direction is clear: AI makes data recovery, permission governance, and autonomous defense more important.
GitLab/Developer Tools
GitLab appeared in the software and AI application list, with no new earnings or target price observed. It represents DevSecOps and the governance problem after code generation: the more code AI writes, the more enterprises need audit, permissions, testing, and deployment pipelines. Follow-up indicators are paid seats and penetration of advanced features.
Software Risks
The software rebound does not mean fundamentals have improved across the board. Multiple reports emphasized that today’s move came more from buybacks, valuation repair, option squeezes, and rotation out of AI hardware positions. Companies that can sustain the move need to prove that AI features drive renewals, usage, gross margin, or customer expansion, not simply rely on “semiconductors fell, so software rose.”
Consumer Electronics/Smart Vehicles
Apple On-Device AI
Apple rose 1.50%. The core of on-device AI is not a new model release, but memory costs and supply-chain choices. The thread showed Apple considering procurement of memory chips from CXMT and YMTC for devices sold in China, because AI-driven memory shortages are pushing up component costs. If procurement is implemented, Apple can lower BOM; if constrained by compliance, cost pressure will still pass through to product pricing.
Qualcomm/On-Device Chips
Qualcomm fell 1.68%, but clues that early AI device prototypes use Snapdragon suggest that competition for on-device AI entry points may again raise the importance of mobile SoCs, connectivity, and low-power inference. There are currently no shipment targets, pricing, or mass-production timelines, so this can only be viewed as long-term optionality.
Tesla
1. Tesla rose 0.94%. The thread showed that it will release Q2 production and delivery results before 09:30 ET on 2026-07-02. Wall Street expects 406,000 deliveries and 466,000 production units, along with Q2 energy-storage deployment data. On the robotics side, Tesla disclosed that the Fremont Optimus production line is modular and can be quickly adjusted as designs iterate.
2. Tesla Europe sales: Tesla registrations in France, Sweden, Denmark, and Spain rose in June, indicating signs of recovering European demand ahead of Q2 deliveries; Norway was the exception, with registrations down 43% YoY. A European recovery can cushion delivery expectations, but actual Q2 deliveries, ASPs, and inventory still need verification.
"consensus among analysts sit at 406k… estimates 466k"
General Motors/Micron
Micron and General Motors signed a long-term automotive memory supply agreement covering LPDRAM, NOR, and UFS NAND for software-defined vehicles, ADAS, and AI cabins, supported by a $2 billion investment in Manassas, Virginia. This shows that the storage bottleneck is not only in data centers, but is also entering smart-vehicle cabins and assisted driving.
Robotics Industry
The robotics materials used the large number of U.S. automakers before 1929 as an analogy for today’s robotics industry, judging that the near term will feature brand display and product segmentation, while the long term will likely see consolidation. There are no orders, shipments, revenue, or valuation data here, so the investment implication can only fall on manufacturing costs, supply chains, software iteration, and real-world scenario implementation.
Humanoid Robot Supply Chain
Additional clues showed Morgan Stanley raising its 2026 China humanoid robot shipment forecast to 50,000 units, versus earlier estimates of 14,000 and 28,000 units; UBTech’s U1 is priced at about $145,717.90, and orders were updated from more than 11,000 units to more than 13,361 units. This is a secondary clue, indicating demand elasticity in physical AI, but mapping it to overseas-listed companies requires caution.
Audi Cabin
Audi acknowledged that its interiors have underperformed in recent years. Next-generation models/EVs will use better materials, more physical buttons, and thinner screens. Smart-vehicle competition is shifting from batteries, motors, and software back toward cabin quality and interaction usability, benefiting interior materials, displays, buttons, and cabin electronics, but no orders or supplier shares were observed.
Innoviz/Sensors
Innoviz LiDAR’s counter-drone validation was placed in adjacent scenarios for optical materials, lenses, sensors, and intelligent driving. The materials did not provide customer or revenue figures, but they show that automotive LiDAR technology may expand into security, defense, and robotic perception. Follow-up indicators are mass-production customers and project scale.
PC and Memory Costs
The thread showed memory and storage prices squeezing PC purchases, with new PC purchases seeing their largest decline in nearly three years, shipments down 7%, and analysts forecasting a 14% contraction; meanwhile, gaming is beginning to recommend 64GB RAM. The contradiction in end consumer electronics is that the capacity-upgrade trend is clear, but cost pass-through will suppress low-end demand.
Sony Gaming Hardware
The thread showed that Sony will stop producing physical PlayStation game discs in January 2028, and that the PS Vita and PS3 stores will go offline in August 2026. This clue has limited impact on semiconductor demand and is more about changes in content distribution and hardware lifecycles, so it does not enter the AI main thread.
Investment Bank Target Price Changes Over the Past 12 Hours
Huang’s Selected Portfolio
404K SEMI-AI Morning Brief 2026-07-02 — Meta Compute Monetization, Strong Memory Pricing, Software Catches the Rotation
目录
After-Market Summary
Full AI/Semiconductor Value Chain
AI Models/Applications and Capex
CSP/Cloud Capex
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry, Equipment, and Advanced Packaging
MLCCs, PCBs, Optical Communications, and Power Infrastructure
Internet/Platforms
Software/SaaS
Consumer Electronics/Smart Vehicles
Investment Bank Target Price Changes Over the Past 12 Hours
Huang’s Selected Portfolio
Meta Compute pushes the AI infrastructure trade from “keep buying GPUs” to “how do these assets earn money”; semis and memory are under short-term pressure, but DRAM/NAND, advanced packaging, MLCCs, power, and optical interconnects still have hard data support; software, security, and platform stocks absorbed capital after hardware momentum pulled back.
After-Market Summary
U.S. equities showed clear divergence at the 2026-07-01 close: the S&P; 500 fell 0.28%, Nasdaq 100 fell 1.69%, equal-weight S&P; rose 0.30%, and Russell 2000 fell 0.52%. The technology ETF fell 2.57%, the semiconductor ETF fell 5.32%, and the equal-weight semiconductor reference fell 6.42%; by contrast, the software ETF rose 3.02%, cloud computing rose 1.29%, and cybersecurity rose 1.40%. The market was not simply de-risking. It was rotating out of semiconductor momentum into software, platforms, and defensive cash-flow names.
The marginal change in the AI theme came from Meta: the market interpreted its plan to sell AI compute externally as a revenue outlet for capex, sending Meta up 8.84% on the day. But the same logic pressured independent AI cloud and semiconductor chains: Oracle fell 2.63%, Broadcom fell 2.31%, TSMC ADR fell 6.95%, Micron fell 10.99%, and SanDisk fell 11.67%. This shows investors are starting to ask: who is merely a recipient of capex, and who can turn compute assets into revenue?
There is still counterevidence within sectors. DRAM, NAND, enterprise SSDs, advanced packaging, MLCCs, and data-center power have not seen demand invalidation; this looks more like a cooling of crowded trades. The rebound in software and security was not purely defensive either: Microsoft rose 2.81%, Palantir rose 7.63%, Salesforce rose 4.19%, ServiceNow rose 6.16%, Snowflake rose 2.63%, and CrowdStrike rose 10.22%, indicating capital is searching for later-cycle monetization paths in AI applications and operations.
Full AI/Semiconductor Value Chain
AI Models/Applications and Capex
OpenAI/SoftBank
On 2026-07-01, SoftBank executed its second $10 billion follow-on investment in OpenAI Group PBC through Vision Fund 2, part of the $30 billion plan announced on 2026-02-27. The first tranche was executed on 2026-04-01, and the remaining $10 billion is expected to be completed on 2026-10-01. Capital continues to flow into frontier models, but the report did not provide confirmed figures showing order pass-through to Oracle, CoreWeave, Nvidia, or AMD.
“Executed a second follow-on investment of $10 billion in OpenAI Group PBC”
AI Token Usage
JPMorgan tracking shows that in June 2026, OpenRouter token volume rose 70% MoM and 20x YoY, while token spending rose 70% MoM and 16x YoY. U.S. models’ volume share fell to 35%, but their spending share remained above 85%. These figures support continued expansion in inference demand and help explain why GPU rental prices are still rising.
Claude/Sonnet
Sonnet 5 token usage was cited at 1x to 1.35x the comparison baseline, theoretically positive for ARR, but the materials did not provide adoption rates, customer counts, call volumes, or cloud resource consumption. This data point is suitable for monitoring usage elasticity in AI applications, but cannot be directly extrapolated into semiconductor orders.
Sovereign AI
Enterprise model selection is shifting from “who is the strongest” to “how should access rights and policy risk be managed.” The materials explicitly discuss whether enterprises may shift from OpenAI and Claude to Chinese models, and note the rising importance of sovereign AI. The investment implication is that regional cloud, data residency, and local models will become procurement constraints, but there are currently no verifiable revenue figures.
Enterprise AI Applications
Palantir is described as the enterprise AI data sovereignty layer. 1Q26 revenue was $1.63 billion, up 85% YoY; U.S. commercial revenue rose 133% YoY; U.S. government revenue rose 104% YoY; the company signed 47 deals above $10 million in the quarter; and full-year guidance is $7.65 billion. The business question for AI applications is whether sensitive data can remain inside the customer environment, not just how model parameters compare.
“1Q26 revenue was $1.63 billion, up 85% year over year”
CSP/Cloud Capex
Meta
1. Meta is commercializing surplus AI compute and hosted model access, and the market first traded it as capex converting into revenue: the stock rose 8.84%, with multiple data points indicating it was up close to 10% intraday. But this also pressured semiconductors and AI cloud, as investors began questioning whether hyperscaler capex will continue to be revised upward.
2. Counterevidence on Meta: interpreting Meta Compute directly as compute oversupply is not robust. The materials also mention Meta’s AI compute agreement with CoreWeave, extending to 2032 and worth about $21 billion, its agreement with Nebius worth up to about $27 billion, and its lease of roughly 1.6GW of data-center capacity from Crusoe. A more reasonable point to watch is the start of tiered pricing across older GPUs, frontier clusters, and inference capacity.
“Meta is building a cloud business, selling surplus compute from its overinvested data-center clusters”
Google
Several materials frame Google as counterevidence to Meta’s compute constraint: Meta’s access to Gemini compute was limited due to capacity constraints. This does not provide Google Cloud revenue or a price target, but it shows frontier-model compute resources remain bottlenecked, so AI infrastructure demand should not be judged as peaking simply because Meta is selling some compute externally.
Microsoft
Microsoft rose 2.81% in the market data. The report notes a new round of layoffs affecting less than 2.5% of employees and also places Maia, its in-house chip, within the framework of accelerating CSP-designed inference chips. Microsoft’s core question is whether Copilot/cloud AI can deliver revenue while in-house chips reduce inference costs.
Amazon
Amazon rose 1.22%. The materials place Trainium 3 alongside Microsoft Maia, Meta MTIA, and Google TPU as parallel demand engines over the next several years. This indicates cloud vendors are not only buying Nvidia for inference cost management; they are also competing for TSMC advanced nodes, advanced packaging, and OSAT capacity.
AI Cloud/Data-Center Operators
CoreWeave
CoreWeave was hit by the Meta Compute news, with data points showing a roughly 12%-14% decline. Rosenblatt still reiterated Buy and a $250 price target, saying GPU shortages remain the industry norm and that Meta may not necessarily have the right to resell capacity leased from CoreWeave through 2032. The core debate is resale rights under lease contracts and the price curves of old versus new GPUs, not one day’s share price.
“Meta recently signed a new $21 billion AI compute agreement with CoreWeave”
Nebius
Nebius is under pressure from the narrative that a customer has become a competitor. The materials show Meta’s five-year agreement of up to about $27 billion includes $12 billion of Vera Rubin dedicated capacity for delivery in early 2027 and up to $15 billion of flexible capacity, with backlog of roughly $50 billion. If this capacity has already been allocated to other customers, Meta Compute is more of a valuation shock for Nebius and not necessarily a signal of contract cancellations.
Applied Digital
Applied Digital delivered 75MW of AI capacity at Polaris Forge 1, with Phase 1 of Building 2 reaching Ready for Service and total live capacity rising to 175MW. Long-term leases cover 400MW, and the campus is fully leased. This signal matters more than pure share-price moves: valuations for AI cloud operators depend on whether power, delivery, and customer leases can convert into usable capacity on schedule.
“Polaris Forge 1 has increased to 175 MW”
IREN/TeraWulf/Cipher Mining
IREN, TeraWulf, and Cipher Mining were placed in the neocloud pullback basket. The materials showed moves such as IREN -4% and TeraWulf -5%, but lacked new customer, capacity, financing, or contract figures. We only retain the sentiment transmission here: the market is starting to worry that Meta’s entry into cloud could pressure GPU cloud rental prices. The next thing to watch is whether power advantages can become long-term cost barriers.
Bloom Energy/Power
Bloom Energy’s AI infrastructure power partnership with Brookfield expanded from $5 billion to $25 billion, supported by Brookfield’s planned $100 billion AI Infrastructure Fund. Separately, Evercore raised its Bloom Energy price target from $179 to $350, and UBS raised its target from $322 to $350. The power bottleneck is shifting from total generation to grid-connection speed and on-site power delivery.
GPU/CPU/ASIC
GPU Rental Prices
JPMorgan data shows the A100’s average June price was $1.63/GPU-hour, up 6.3% MoM, marking the fifth consecutive month of growth; H100 was $2.72/GPU-hour, up 3.7% MoM, marking the seventh consecutive month of growth; and B200 was $5.33/GPU-hour, up 2.7% MoM. Absolute rental prices are still rising, indicating demand has not disappeared. The narrowing B200/H100 premium shows incremental high-end supply is starting to change the pricing structure.
“The A100’s average June price was $1.63/GPU-hour”
Nvidia
Nvidia fell 1.48%. The materials include both semiconductor momentum pullback and counterevidence that Blackwell/Rubin capacity and delivery cycles remain tight. UBS data indicates Vera CPU shipment forecasts were raised from 1.6 million units in 2026 to 5.5 million in 2027, while Rubin GPU sees a slight delay in 2Q26 but rebounds in the second half. The company is under short-term pressure mainly because valuations of capex recipients are being reassessed.
AMD
AMD fell 6.98%, but several materials still place server CPU and CoWoS demand on an incremental growth track. UBS data shows AMD Venice shipments rising from 1.3 million units in 2026 to 4 million in 2027, while AMD CoWoS demand may grow 232% in 2027. Trading pressure comes from deleveraging in AI chip stocks. The fundamental checkpoints remain EPYC, the MI series, and the Helios roadmap.
Intel
Intel fell 9.05%. The real new items worth noting are not PCs, but process and foundry-related developments: Intel is expanding its Santa Clara campus to increase EUV photomask output, involving 18A and 14A. Separately, Oxmiq’s founding team has Intel and AMD backgrounds and raised $35 million to build licensable IP combining CPU, GPU, and tensor engines. Intel needs foundry customers and yield to prove a turnaround.
Broadcom/Marvell Technology
Broadcom fell 2.31%, and Marvell Technology fell 8.59%. The materials place both in the AI ASIC and networking chip basket, which was clearly hit by the Meta Compute narrative. But the true AI bottlenecks still cover custom silicon, networking, HBM, and advanced packaging. The short-term issue is valuation and customer capex cadence; the long-term question is whether ASIC projects move from a single customer to multiple hyperscalers in parallel.
Qualcomm
Qualcomm fell 1.68%. The materials show an early AI device prototype is expected to use a Snapdragon chipset, but the project is still early, the design may change, and mass production is uncertain. This clue can only indicate that edge AI entry points may again raise the strategic value of mobile SoCs. It cannot be treated as order or revenue confirmation.
MediaTek
Goldman Sachs raised MediaTek’s price target to 6,800 in local currency, citing a major upward revision to AI ASIC forecasts: 2027 AI ASIC revenue forecast was raised from $12.3 billion to $20.3 billion, and 2028 from $28.4 billion to $52.5 billion, with AI ASIC potentially reaching 49%/69% of revenue. The market is repricing MediaTek from a mobile-chip vendor into a custom AI chip platform.
HBM/DRAM/NAND/SSD/HDD
Micron
Micron fell 10.99%, but the fundamental anchors remain strong: HSBC raised its price target from $1,100 to $1,700 and maintained Buy. The materials show Q3 revenue of $41.46 billion, data-center revenue above $25 billion, and 16 strategic customer agreements. On pricing, conventional DRAM is expected to rise 13%-18% QoQ in 3Q26, PC DRAM 15%-20%, server DRAM 13%-18%, NAND 10%-15%, and enterprise SSDs 18%-23%. The trade is punishing crowding; memory supply-demand has not yet been invalidated.
“memory demand continues to outpace supply”
SanDisk
SanDisk fell 11.67%, but BofA raised its price target from $2,100 to $2,500 and maintained Buy, citing expectations that the NAND market supply-demand imbalance will persist through all of 2027 and that pricing will remain “strong for longer” into mid-2027. The price-target hike and share-price plunge happened on the same day, showing the market was selling the AI capex narrative and momentum positioning, not the NAND pricing logic itself.
“supply/demand imbalance in the NAND market to remain through C27”
Samsung Electronics
Samsung Electronics fell 5.84% on an ADR basis. The materials show HBM4E reliability test yield above 70%, while a mature state is usually above roughly 80%; HBM4 shipments began in February 2026, 12-layer HBM4E samples were delivered in late May, and the D1d DRAM process targets PRA in November 2026. The investment question for Samsung is whether HBM4E can shift from catch-up mode to stable share.
SK Hynix
SK Hynix fell 3.40%, but the materials show it effectively monopolizes HBM3E, has more than 60% share in HBM4, and is discussing an ADR plan. Korean technology export data is also strong: June semiconductor exports were $44.8 billion, up 199.5% YoY; DRAM including modules was $21.846 billion, up 385% YoY; MCP/HBM was $12.681 billion, up 171% YoY. This remains hard evidence of a strong memory upcycle.
Seagate/Western Digital
Seagate fell 5.58%, and Western Digital fell 6.69%. The electronic components report shows nearline HDD and enterprise/data-center SSD capacity continued to grow in May 2026, and data-center storage demand did not disappear because of Meta news. Both companies were dragged down short term by the memory basket pullback. Follow-up checkpoints are enterprise drive capacity, SSD pricing, and cloud customer inventory.
Apple/China Memory Supply Chain
Apple is reportedly in talks to procure memory chips from CXMT and YMTC for devices sold in China, as AI-driven memory shortages push up component costs. This data point is a dual price and policy variable for Micron, Samsung, and the domestic memory supply chain: customers want lower costs, but compliance and supply stability will determine actual share.
Foundry, Equipment, and Advanced Packaging
TSMC
TSMC ADR fell 6.95%, but advanced packaging expansion signals remain strong. Nomura data says TSMC’s 2027 CoWoS capacity forecast has been raised to 2,000kpcs, up from 1,100kpcs in 2026; Google TPU’s CoWoS share rises to 26% in 2027, while Nvidia is about 55%. TSMC’s bottleneck is extending from wafer manufacturing to CoWoS, WoS, substrates, and materials.
“TSMC… From 1,100kpcs in 2026 to 2,000kpcs by 2027”
ASML/Applied Materials/Lam Research/KLA
Semiconductor equipment stocks pulled back together in the market data: ASML fell 7.31%, Applied Materials fell 9.96%, Lam Research fell 9.66%, and KLA fell 11.75%. Susquehanna added that it raised ASML’s price target from EUR1,475 to EUR2,350, Lam Research from $385 to $475, and Applied Materials from $575 to $900, and said wafer fab equipment spending could peak at $300 billion. The short-term selloff comes from semiconductor deleveraging, while order expectations are still driven by advanced nodes and packaging.
Selective Etch
The Tessara report places the key rent in GAA and advanced nodes on selective etch, noting that leading-edge processes are mainly covered by Lam Research, Applied Materials, and Tokyo Electron, with slow qualification and delivery cycles of more than one year. The investment implication is that N2/N2P/A16, GAA, and AI accelerator ramps will increase etch steps. But equipment stocks already reflect a meaningful amount of expectation; the next things to watch are customer cleanrooms, yield, and installation pace.
ASE/Amkor/OSAT
The materials show ASE raising advanced packaging prices by more than 20%, 2026 packaging and testing unit prices rising 5%-20%, and memory OSAT possibly rising up to 30%. Capex rose from about $2 billion to $5.3 billion in 2025 and $8.5 billion this year. Back-end engineering is no longer cheap outsourcing; it has become a pricing link in AI chip delivery.
Semiconductor Inventory
Semiconductor inventory tracking shows total supply-chain DOI increased by 9 days QoQ, below the seasonal increase of 19 days, but still 33 days above the historical median. Distributors continue to destock, while producer builds are relatively stable. The investment implication is that the sector has not entered a broad restocking cycle. Priority should remain on memory, advanced packaging, equipment, and AI networking, where supply-demand tightening is clearer.
MLCCs, PCBs, Optical Communications, and Power Infrastructure
Yageo/MLCC
Yageo raised prices across its capacitor product portfolio from 2026-07-01, covering tantalum capacitors, MLCCs, aluminum electrolytics, conductive polymer aluminum capacitors, film capacitors, and supercapacitors. These categories account for about 50% of total company revenue, while tantalum capacitors and MLCCs account for about 43%. The materials also say overall utilization is above 80%, and premium MLCC utilization is above 90%. Passive components are moving from inventory repair into demand driven by AI servers and automotive-grade applications.
“Yageo… utilization is over 80% overall, with premium MLCCs above 90%”
Samsung Electro-Mechanics
Samsung Electro-Mechanics is placed in the AI data-center MLCC supply-contract line, with a contract size of about KRW450 billion. Meritz raised its price target to KRW3 million and lifted its 2027 MLCC ASP increase assumption to 37.0%. The MLCC logic is not just price hikes; high-end server power density and reliability requirements are lifting ASP.
PCB/Substrates
Materials frame Korean substrate makers’ price-cut requests as background noise. The real constraints are BT capacity, T-Glass, CCL, ABF, and advanced packaging substrates. A report related to Victory Giant Technology says momentum should recover from Q3 with more new customers, while AI server PCBs and high-layer-count boards remain the core tracking points. This segment needs validation through mass production by new customers, not just pricing rumors.
Optical Communications/AAOI
The optical communications roadmap continues to migrate from 400G to 800G, 1.6T, and 3.2T: 800G/100G lane drives shipments in 2024-26; 1.6T/200G lane is the next wave in 2026-28; and 3.2T may enter the CPO era. For names such as Applied Optoelectronics, the key is not only current-quarter gross margin, but whether they can sit on the latest speed tier.
Nokia/Optical Networks
Nokia is included in the line that optical networks and IP networks are supported by AI infrastructure, with the report title directly pointing to “AI infrastructure buildout supports an upgraded outlook for optical networks and IP networks.” No new order figures were seen, so we only place it on the watchlist for data-center interconnect and transmission equipment, avoiding turning ordinary communications equipment news into an earnings conclusion.
Vertiv/Liquid Cooling and Power Modules
Vertiv opened a manufacturing facility in Johor, Malaysia, covering liquid cooling, power modules, Power Skid, and SmartRun. It is expected to create hundreds of technical jobs once fully operational in 2027. Power Skid/Power Module can reduce deployment time by up to 50%, and SmartRun can improve on-site deployment speed by up to 85%. The data-center supply bottleneck is shifting from GPUs to deployment speed, power modules, and liquid-cooling delivery.
Korean Power Equipment
Citi says high-voltage transformers and GIS exports to the U.S. remain strong on a half-year horizon. LS Electric’s 2Q26 new orders are expected to reach KRW2 trillion, doubling from KRW1 trillion in 1Q26; by order source, 20%-30% comes from renewable energy and 20%-30% from hyperscalers. AI data centers are pulling grid equipment from cyclicals into visible orders.
Internet/Platforms
Meta
Meta rose 8.84%. The platform-stock narrative shifted from “AI capex pressures profits” to “can compute assets be externally monetized?” Wells Fargo-related views noted that 10GW of excess capacity could potentially generate $200 billion in revenue and $55 in EPS by 2028, but this remains scenario analysis. What really needs tracking is whether Meta Compute has customers, pricing, utilization, and gross margin, not just slogans.
Google
Google rose 1.06%. In the thread, it is both the counterexample to Meta being constrained by Gemini compute and a source of demand for self-developed TPU chips. Google’s investment implications split into two questions: whether models and search advertising can continue to commercialize, and whether TPUs and cloud infrastructure can achieve higher returns on assets within AI capex.
Amazon
Amazon rose 1.22% and became a potential competitive reference point under the Meta Compute narrative. If Meta sells hosted model access, the format would resemble AWS Bedrock; if it sells raw compute, it would be closer to GPU cloud. The validation points for Amazon are AWS AI backlog, Trainium adoption, and cloud gross margin, not the Meta news itself.
Microsoft
Microsoft rose 2.81%. Investors linked layoffs to AI productivity, but the materials did not provide new financial figures. The core question remains whether Copilot, Azure AI, and the Maia in-house chip can simultaneously lower inference costs, improve customer retention, and convert AI investment into recurring revenue.
Apple
Apple rose 1.50%, but the truly relevant clue today was storage procurement: Apple is reportedly considering sourcing memory chips from CXMT and YMTC for devices sold in China. Rising AI-device costs are pushing Apple to seek more supply-chain options, but compliance, political risk, and product pricing power will determine whether this can be implemented.
Netflix
Netflix rose 3.59%. In market terms, it was part of the platform-stock rebound, but these materials contained no new content, advertising, or subscriber data. Here it is kept only as an observation point for capital returning to internet platforms, not expanded into a fundamental theme.
Reddit
Reddit was listed in the thread as one of the overlooked platform stocks, regaining attention alongside AI applications and data-licensing deals. The materials did not disclose new contracts, revenue, or target prices, so the focus is the optionality of platform data assets in AI training, search distribution, and advertising monetization.
Shopify
Shopify was included in the platform-stock rotation list. The report noted that among overlooked stocks, Shopify was up roughly 7% on the day. This looks more like capital rotating from hardware momentum into applications and platforms than a sudden change in company fundamentals; follow-up indicators are merchant GMV, AI-tool usage, and advertising/payment attach rates.
Airbnb
Airbnb appeared on the 52-week-high list in the new-high scan, with a one-day gain of 3.80%, but the mandatory new-high table at the start of the morning note was empty, indicating there was no qualifying stock-specific event anchor to support a standalone table. Here it is treated only as a marginal clue in recovering platform-stock risk appetite, not as a core catalyst today.
Uber/DoorDash
Uber and DoorDash appeared in the internet-platform list, with no orders, revenue, regulatory developments, or formal investment-bank actions observed. Their shared question is whether AI dispatching, local services, and advertising can improve unit economics, but they do not constitute the main thread today.
Circle/Stablecoin Infrastructure
The stablecoin thread showed USDC supply of roughly $74 billion and expected stablecoin scale of up to $3 trillion by 2030, versus about $310 billion currently. This is more fintech infrastructure than internet/platform and is not included in the target-price table at the end. Within internet/platforms, it is only a reminder that payment APIs and agentic transactions could become part of the AI application stack.
Platform-Stock Rotation
The thread showed capital flowing into platforms, advertising, and software after profit-taking in semiconductors: Meta, Reddit, Coinbase, AppLovin, Palantir, Shopify, ServiceNow, and others were included in the rebound list. The investment implication of this rotation is that the AI trade is beginning to spread from capex recipients to platform companies with users, data, and cash flow.
Risks
The risk for internet platforms is not that “AI is useless,” but that profit distribution across compute, models, data, and advertising revenue has not yet stabilized. If Meta Compute pushes down GPU cloud rental prices, it will hurt independent clouds; if it merely improves Meta’s asset turnover, it could instead reinforce the valuation advantage of large platforms.
Software/SaaS
Software ETF
The software ETF rose 3.02% on the day, the cloud computing ETF rose 1.29%, and the cybersecurity ETF rose 1.40%; meanwhile, the semiconductor ETF fell 5.32%. One thread showed IGV up roughly 11%-12% over five trading days, with software up 7.5% since June 23 and SOX down 7.5%, a relative spread of about 15 percentage points. Software is absorbing capital after the AI hardware pullback.
“Performance since June 23: Software +7.5%, SOX -7.5%”
Salesforce
Salesforce rose 4.19%. Guggenheim upgraded it to Buy with a $228 target price. The rationale was not immediate AI-driven upside, but that 3.7x recurring revenue and 11x EV/NTM FCF already embed excessive pessimism, implying about 46% upside. This logic is closer to valuation repair: after AI risk has been fully priced in, the stock has elasticity as long as core customer retention remains stable.
ServiceNow
ServiceNow rose 6.16%. Guggenheim upgraded it to Buy with a $125 target price, emphasizing that insufficient evidence of AI monetization is not a “death knell.” ServiceNow’s business question is clear: whether enterprise workflow software can use agentic AI to increase workflow value while preserving subscription renewal rates and seat expansion.
Check Point
Check Point was upgraded to Buy with a $188 target price. The thread showed it currently at 4.3x EV/NTM recurring revenue and 8.0x EV/NTM FCF, discounted versus security peers at 11.6x and 35x. The core logic for security software is that as the AI attack surface expands, enterprise budgets may not necessarily be cut; instead, investors may place more value on stable cash flow and low valuation.
CrowdStrike
CrowdStrike rose 10.22%. The thread showed cybersecurity and cloud observability companies being repriced by the market because the more complex inference and agentic AI become, the more enterprises need monitoring, compliance, security, and operational reliability. This is not merely an “AI concept”; the more AI is deployed, the higher the cost of failures and attack surfaces.
“market starts pricing in software companies which truly benefit from inference and agentic ai”
Palo Alto Networks
Palo Alto Networks rose 3.23% and appeared in both the all-time-high and 52-week-high lists in the new-high scan, with a one-day gain of 3.37% and a one-week gain of 24.28%. The thread also noted that its valuation is already high, at 24x sales, 68x EBITDA, and 90x PE. Both fundamentals and valuation are strong; the near-term risk is crowded momentum chasing.
Datadog
Datadog rose 1.58%. The thread grouped it with CrowdStrike and Palo Alto Networks as beneficiaries in cloud observability/cybersecurity. The more complex AI inference, agent workflows, and multi-cloud architectures become, the more enterprises need visibility into operating costs, latency, failures, and security incidents. Datadog’s validation points are large-customer expansion and net retention.
Snowflake
Snowflake rose 2.63%. Market data showed a five-day gain of 15.60% and roughly flat performance over 20 days. It is the foundation for data cloud and AI applications, and after the hardware pullback, capital is again looking for elasticity in data assets and the application layer. Follow-up indicators are whether Cortex, data sharing, and compute costs can translate into revenue growth.
MongoDB
MongoDB rose 6.99%, with a five-day gain of 18.83%. The materials did not provide new earnings, but databases, as the foundation for AI applications, benefit from the application-layer rotation. The investment question is whether generative AI applications can drive Atlas consumption and whether enterprise IT budgets are moving from experimentation to production deployment.
Cloudflare
Cloudflare rose 0.46%. The materials did not provide new official data, but the company sits at the intersection of edge cloud, AI networking, and security. As AI application traffic rises, demand for edge inference, secure access, and API protection should increase; the risk is that valuation already implies high growth, so revenue delivery needs to keep pace.
Rubrik
Rubrik entered the AI security and agent-governance thread: Project Glasswing received Mythos Research Preview access, using frontier AI to identify, validate, and remediate software risks in enterprise platforms. The materials did not provide financial figures, but the direction is clear: AI makes data recovery, permission governance, and autonomous defense more important.
GitLab/Developer Tools
GitLab appeared in the software and AI application list, with no new earnings or target price observed. It represents DevSecOps and the governance problem after code generation: the more code AI writes, the more enterprises need audit, permissions, testing, and deployment pipelines. Follow-up indicators are paid seats and penetration of advanced features.
Software Risks
The software rebound does not mean fundamentals have improved across the board. Multiple reports emphasized that today’s move came more from buybacks, valuation repair, option squeezes, and rotation out of AI hardware positions. Companies that can sustain the move need to prove that AI features drive renewals, usage, gross margin, or customer expansion, not simply rely on “semiconductors fell, so software rose.”
Consumer Electronics/Smart Vehicles
Apple On-Device AI
Apple rose 1.50%. The core of on-device AI is not a new model release, but memory costs and supply-chain choices. The thread showed Apple considering procurement of memory chips from CXMT and YMTC for devices sold in China, because AI-driven memory shortages are pushing up component costs. If procurement is implemented, Apple can lower BOM; if constrained by compliance, cost pressure will still pass through to product pricing.
Qualcomm/On-Device Chips
Qualcomm fell 1.68%, but clues that early AI device prototypes use Snapdragon suggest that competition for on-device AI entry points may again raise the importance of mobile SoCs, connectivity, and low-power inference. There are currently no shipment targets, pricing, or mass-production timelines, so this can only be viewed as long-term optionality.
Tesla
1. Tesla rose 0.94%. The thread showed that it will release Q2 production and delivery results before 09:30 ET on 2026-07-02. Wall Street expects 406,000 deliveries and 466,000 production units, along with Q2 energy-storage deployment data. On the robotics side, Tesla disclosed that the Fremont Optimus production line is modular and can be quickly adjusted as designs iterate.
2. Tesla Europe sales: Tesla registrations in France, Sweden, Denmark, and Spain rose in June, indicating signs of recovering European demand ahead of Q2 deliveries; Norway was the exception, with registrations down 43% YoY. A European recovery can cushion delivery expectations, but actual Q2 deliveries, ASPs, and inventory still need verification.
“consensus among analysts sit at 406k… estimates 466k”
General Motors/Micron
Micron and General Motors signed a long-term automotive memory supply agreement covering LPDRAM, NOR, and UFS NAND for software-defined vehicles, ADAS, and AI cabins, supported by a $2 billion investment in Manassas, Virginia. This shows that the storage bottleneck is not only in data centers, but is also entering smart-vehicle cabins and assisted driving.
Robotics Industry
The robotics materials used the large number of U.S. automakers before 1929 as an analogy for today’s robotics industry, judging that the near term will feature brand display and product segmentation, while the long term will likely see consolidation. There are no orders, shipments, revenue, or valuation data here, so the investment implication can only fall on manufacturing costs, supply chains, software iteration, and real-world scenario implementation.
Humanoid Robot Supply Chain
Additional clues showed Morgan Stanley raising its 2026 China humanoid robot shipment forecast to 50,000 units, versus earlier estimates of 14,000 and 28,000 units; UBTech’s U1 is priced at about $145,717.90, and orders were updated from more than 11,000 units to more than 13,361 units. This is a secondary clue, indicating demand elasticity in physical AI, but mapping it to overseas-listed companies requires caution.
Audi Cabin
Audi acknowledged that its interiors have underperformed in recent years. Next-generation models/EVs will use better materials, more physical buttons, and thinner screens. Smart-vehicle competition is shifting from batteries, motors, and software back toward cabin quality and interaction usability, benefiting interior materials, displays, buttons, and cabin electronics, but no orders or supplier shares were observed.
Innoviz/Sensors
Innoviz LiDAR’s counter-drone validation was placed in adjacent scenarios for optical materials, lenses, sensors, and intelligent driving. The materials did not provide customer or revenue figures, but they show that automotive LiDAR technology may expand into security, defense, and robotic perception. Follow-up indicators are mass-production customers and project scale.
PC and Memory Costs
The thread showed memory and storage prices squeezing PC purchases, with new PC purchases seeing their largest decline in nearly three years, shipments down 7%, and analysts forecasting a 14% contraction; meanwhile, gaming is beginning to recommend 64GB RAM. The contradiction in end consumer electronics is that the capacity-upgrade trend is clear, but cost pass-through will suppress low-end demand.
Sony Gaming Hardware
The thread showed that Sony will stop producing physical PlayStation game discs in January 2028, and that the PS Vita and PS3 stores will go offline in August 2026. This clue has limited impact on semiconductor demand and is more about changes in content distribution and hardware lifecycles, so it does not enter the AI main thread.
Investment Bank Target Price Changes Over the Past 12 Hours
Huang’s Selected Portfolio