
404K SEMI-AI Memory Weekly — July 17, 2026: Long-Term Contracts Reshape Profits, Inference Lifts NAND, and Costs Bite Back at End Markets
目录
TL;DR
Overall View This Week
How the Thesis Evolved This Week
Weekly Performance of Memory-Related Securities
Required Table: Performance of Covered Securities Over the Past Week
DRAM/HBM: Supply Control, Long-Term Agreements, and Customer Qualification
LPDDR/SoCAMM: Spillover into AI CPUs and Rack-Level Memory
NAND/eSSD/SSD: Inference, RAG, and Enterprise SSD Leverage
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
Equipment, Testing, and Materials: Second-Order Beneficiaries of Storage Capex
Downstream Costs and Demand Destruction: Servers, Networking Equipment, Smartphones, PCs, and EVs
Investment Ranking, Risks, and Falsification
What to Watch Next Week
Memory supply remains tight, but stocks underwent sharp deleveraging first. The key distinctions this week are earnings visibility from long-term contracts, demand elasticity from inference, and the drag of high prices on end demand.
TL;DR
This week was not about a sudden deterioration in fundamentals, but rather valuation compression in high-expectation assets. US-listed memory names broadly sold off, with declines far exceeding the change in industry evidence this week. However, crowded positioning, disputes over fixed pricing in long-term contracts, and customer resistance to price increases have moved from peripheral risks to core valuation variables.
DRAM/HBM remains the highest-conviction segment, but the upside thesis is shifting from “unlimited price increases” to “volume locked in through long-term contracts, earnings floors, and customer qualification.” Institutions estimate that more than 50% of contracted volume could ultimately enter long-term supply agreements with terms of three to five years. This would reduce downside risk at the bottom of the cycle, but also gradually moderate the pace of quarterly price increases.
NAND/eSSD offers greater upside elasticity. As inference workloads grow longer, tens-of-terabytes-scale KV caches cannot feasibly reside entirely in DRAM and HBM. Enterprise SSDs are beginning to serve as a contextual-memory tier. However, controllers, firmware, write amplification, endurance, and GPU-direct access granularity will determine whether demand progresses from a concept to sustainable procurement.
Evidence for the equipment supply chain is more robust than for consumer electronics. CoWoS, HBM stacking, and fluxless thermocompression bonding are expanding the addressable market for TCB tools, while DRAM front-end equipment investment is also stronger than NAND. However, two versions of ASMPT research from the same institution count as one evidence cluster, not independent corroboration.
The cost backlash has already begun. Memory is expected to account for more than 25% of Rubin’s bill of materials. PC manufacturers face demand and margin pressure in the second half, while smartphone brands may respond by raising prices, reducing storage capacity, or cutting other specifications. The mid- to low-end Android supply chain faces greater risk than Apple’s premium segment.
In portfolio allocation, buy visibility first, elasticity second, and wait for cash-flow confirmation last. For high-end DRAM/HBM, focus on contract quality and qualification; for NAND/eSSD, enterprise shipments and average selling prices; and for equipment, actual orders. HDD lacked new operating data this week, so stock-price declines alone cannot support the conclusion that nearline demand, shipment volumes, or free cash flow have improved.
Overall View This Week
The memory cycle remains on an upswing, but asset pricing has entered a second phase: from “shortages drive gains” to “how long can shortages persist, how much profit can be locked in, and how much can downstream customers still absorb?” There is no evidence of a sudden inventory build or large-scale, unconstrained supply expansion. Servers and AI systems continue to absorb high-density DRAM, HBM, and enterprise SSDs. At the same time, sharp pullbacks in thematic ETFs and leading stocks show that the market is demanding more rigorous evidence of execution.
Returns in this cycle should be divided into three categories. The first is visibility: HBM and high-end DRAM depend on customer qualification, capacity allocation, and long-term supply agreements. Earnings may not continue accelerating every quarter, but contracted volumes, price floors, and take-or-pay provisions can raise the cycle trough. The second is elasticity: NAND/eSSD benefits from ASP recovery and KV-cache offloading. Incremental demand could grow faster, but supply constraints are weaker than in DRAM, and pricing is more vulnerable to new capacity and technological substitution. The third is cash flow: for HDD, the key questions are whether the duopoly maintains discipline through build-to-order production, whether nearline shipments translate into exabyte growth, and whether free cash flow genuinely materializes. This week brought new evidence for the first two, while the third had only share-price movements without sufficient operating validation.
The most important disconfirming evidence would not be one week of share-price declines, but downstream customers actively reducing memory content. PC and smartphone manufacturers are raising prices and adjusting product mixes, while Android brands may also cut battery or storage specifications. If server manufacturers begin reducing memory content per system, or customers choose to defer system deployments rather than accept higher prices, tight supply would correct itself through demand destruction. Current evidence indicates that this feedback is emerging first in consumer electronics and has not yet broadened into a reversal in AI-server procurement.
Accordingly, this week’s conclusion is not to buy the dip indiscriminately, but to distinguish between a share-price correction and an industry inflection point. For DRAM/HBM, verify contract structures and qualification; for NAND/eSSD, enterprise shipments and controller capabilities; for equipment, orders rather than total addressable market alone; and for HDD, nearline exabytes and cash flow. Only if these operating indicators deteriorate in tandem should this week’s pullback be interpreted as the cycle peaking.
How the Thesis Evolved This Week
On July 14, the market advanced the question from “is there demand?” to “can demand support current pricing?” An Asian investor survey showed that discussions centered on long-term supply agreements and HBM pricing. Most investors acknowledged that supply-demand fundamentals remain favorable over the next 12–24 months, but were concerned about crowded positioning, amplified volatility, and the mismatch between cloud providers’ hardware capital expenditure and expectations for the size of the memory market. Research on SK hynix released around the same time lowered near-term expectations, but its title merely suggested “slightly lowering the line of sight,” implying an adjustment to the earnings trajectory rather than a cycle reversal. The principal conclusion that day was that fundamentals remained strong, while valuations were demanding a higher density of evidence.
On July 15, the evidence expanded from memory-chip pricing to equipment and downstream costs. ASMPT research argued that CoWoS and HBM capacity expansion, the longer persistence of 12-layer HBM stacking, and rising penetration of fluxless TCB are jointly expanding the addressable market for thermocompression-bonding equipment. Chinese semiconductor assembly and test expansion and Intel’s EMIB-T represent medium-term incremental opportunities. The two versions were highly consistent and should be treated as one evidence cluster from the same institution. Another hardware report highlighted the opposing constraint: rising memory prices are eroding server, PC, and smartphone bills of materials, and consumer end markets will face pressure on volumes, specifications, and margins in the second half.
On July 16, the thesis diverged further into “resistance to DRAM price increases” and “stronger inference-driven NAND demand.” Information from conference calls showed clear customer resistance to DRAM price increases approaching 30%, prompting institutions to trim their third-quarter pricing expectations slightly. Meanwhile, KV-cache offloading and the substitution of NAND for expensive DRAM were progressing better than expected. Penguin Solutions plans to launch a KV-cache server in Japan in the fourth quarter, indicating that inference storage is moving from architectural discussion to product validation. Samsung’s first-quarter materials provided background cross-validation: DRAM and NAND profitability improved significantly, but end-product businesses were already absorbing pressure from higher memory input costs.
Weekly Performance of Memory-Related Securities
Report date: 2026-07-17
US stocks/ETFs weekly market-data period: 2026-07-10 to 2026-07-16
South Korean/Japanese stocks weekly market-data period: unavailable (latest local market data is through 2026-06-12, 35 days before the report date and beyond the 10-day freshness threshold)
US stocks/ETFs show weekly returns and cumulative trading value; South Korean/Japanese stocks show only weekly returns, with “—” in the cumulative trading value column.
Required Table: Performance of Covered Securities Over the Past Week
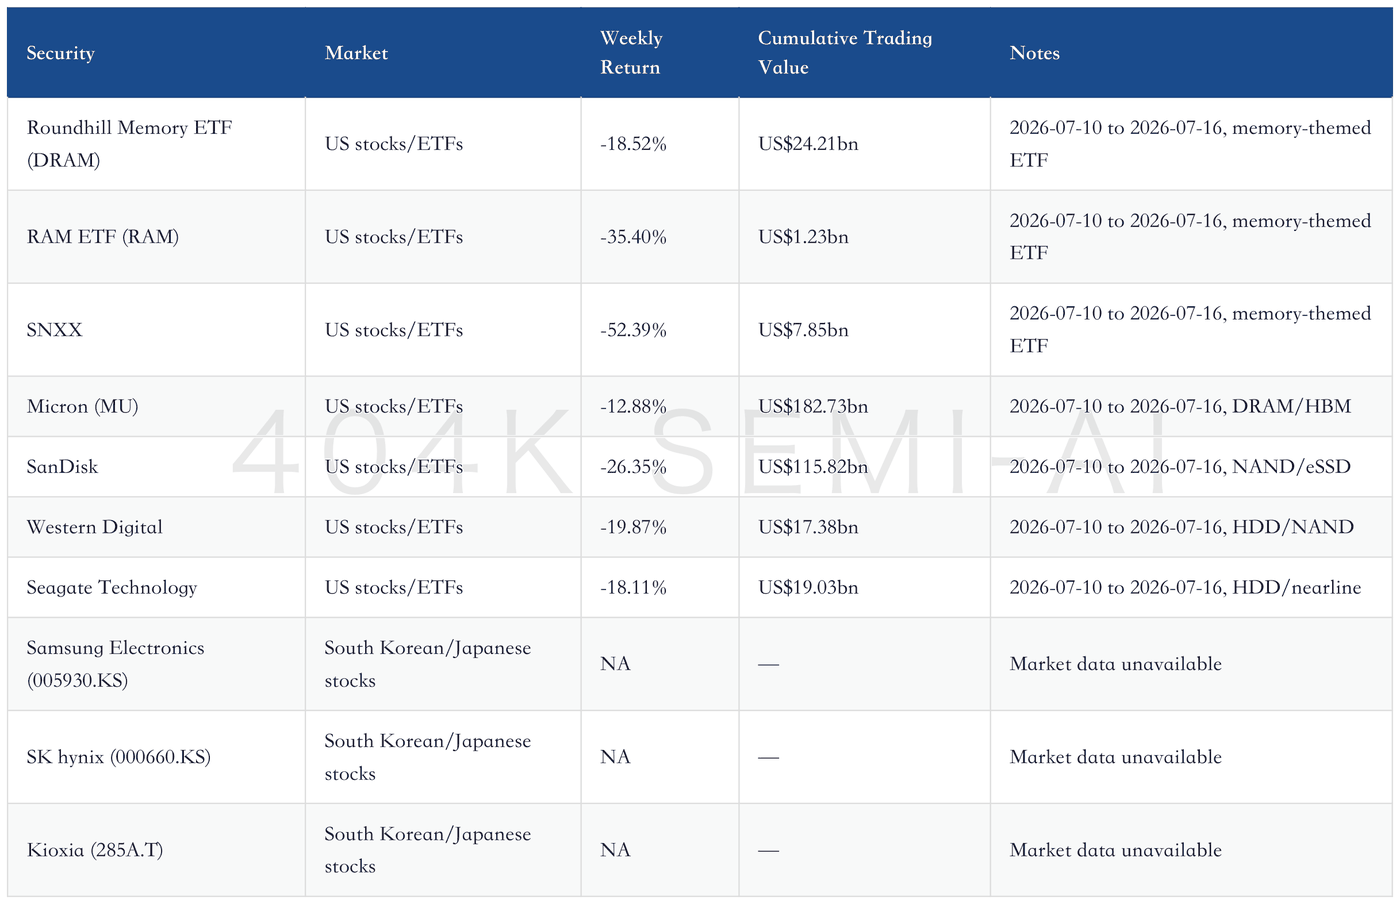
This table reflects only this week’s contraction in risk appetite and positioning; it cannot independently establish a reversal in the industry cycle. Thematic ETFs fell more sharply than individual market leaders, while NAND and HDD names also came under pressure, indicating that investors were reducing exposure across the entire memory basket. South Korean and Japanese stock data are left blank because the available figures are stale. Old prices should not be used to fill the gaps or compare relative performance across markets.
DRAM/HBM: Supply Control, Long-Term Agreements, and Customer Qualification
DRAM’s core advantage remains its deeper supply deficit. Asia technology research estimates that DRAM supply meets only approximately 50%–60% of orders, versus 70%–80% for NAND; shortages may persist even as DRAM wafer capacity continues to increase. More importantly, major customers’ memory inventories are still declining, with no sign of the simultaneous channel and customer balance-sheet inventory build typically seen at the start of a downcycle. As long as procurement, installation, and actual consumption continue to outpace supply growth, any price pullback is more likely to represent slower gains than an immediate reversal in supply and demand.
Long-term supply agreements are reshaping the distribution of earnings. Institutions estimate that more than half of contracted volume could ultimately move under long-term agreements, typically lasting three to five years. These contracts are not merely price caps; more importantly, they lock in volume, price floors, target margins, and take-or-pay provisions. For suppliers, this sacrifices some upside during extreme spot-market rallies but reduces the severity of profit declines in a downcycle. For customers, it secures deliverability in a high-price environment. The key issues are not simply whether an agreement has been signed, but whether it is non-cancellable, requires a deposit, how price floors and ceilings are structured, and whether high-value-added products are priced separately.
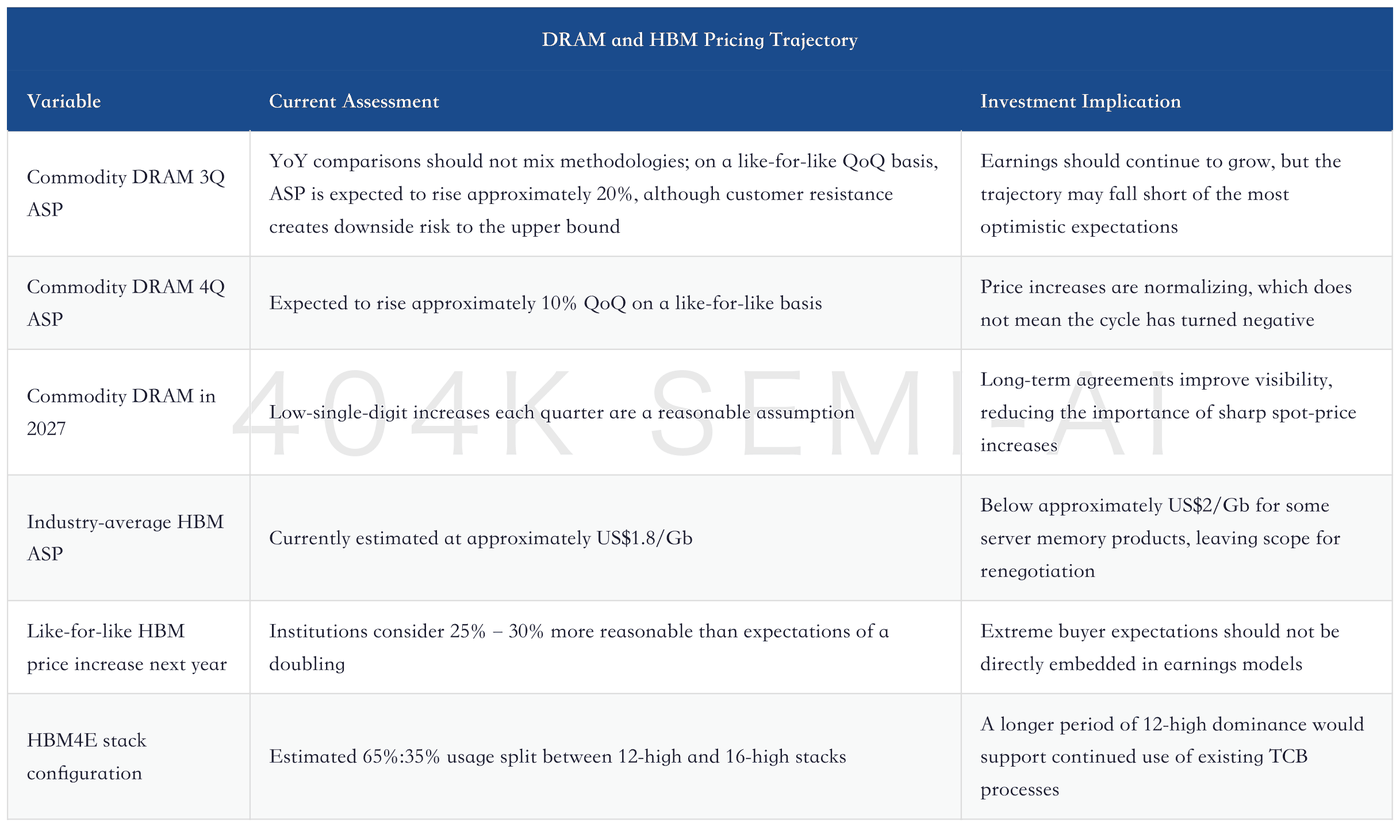
The HBM investment case should focus on customer qualification and annual repricing, not merely a single quarter’s price increase. HBM pricing is typically negotiated annually and tied to GPU and accelerator platforms, while customer qualification, yield, and packaging architecture determine saleable volume. Vera Rubin rack delays and HBM4 procurement adjustments have been discussed by the market, but demand from custom chips such as Google TPUs and AWS Trainium provides a broader customer base. If 12-high HBM4E remains mainstream, hybrid bonding may replace TCB more slowly than previously expected. If 16-high solutions become mainstream sooner, the duration of benefits for existing equipment will need to be revised downward.
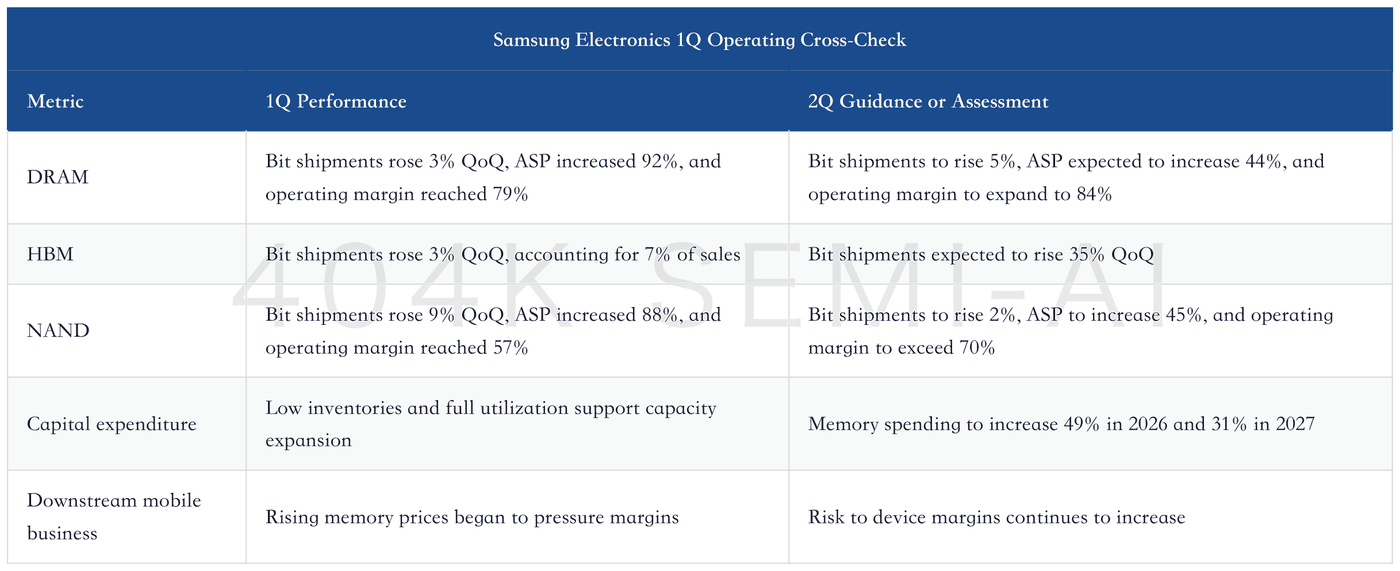
Samsung Electronics’ historical quarterly data can only validate industry strength; it cannot substitute for current weekly pricing. Its first-quarter materials showed significant improvements in margins, ASPs, and inventories for commodity DRAM and NAND, with further price increases expected in the second quarter. At the same time, higher memory costs pressured mobile-business margins. This confirms that upstream price increases and downstream cost pressure are occurring simultaneously, but it does not directly imply that July prices are still rising at the same pace.
SK hynix’s intraweek revision provides a note of restraint. The research title called for expectations to be “trimmed slightly,” indicating that near-term earnings estimates need to be revised downward, although the report maintained its positive rating and target-price framework. Together with investor surveys, it points to the same conclusion: profits remain elevated, while the market debate centers on the earnings trajectory, allocation under long-term agreements, and crowded positioning—not a sudden disappearance of orders.
LPDDR/SoCAMM: Spillover into AI CPUs and Rack-Level Memory
AI-system memory demand is expanding beyond HBM adjacent to GPUs into CPUs, racks, and modules. Server-grade memory commands a higher per-GB price than mobile LPDDR, making product mix a significant driver of blended ASPs. Asia technology research indicates that the per-GB price gap between server- and mobile-grade products can reach 30%–40%. Consequently, even with unchanged total bit shipments, a memory vendor can improve its revenue and profit mix by increasing the proportion of server products.
SoCAMM’s investment significance lies in high capacity, modularity, and closer integration with AI CPUs—not in replicating the HBM narrative. This week’s developments positioned SoCAMM alongside HBM4 as a driver of high-end demand, but independent validation of orders, customers, and the mass-production timeline is lacking. The direction can therefore be confirmed, but market-size forecasts should not yet be embedded directly into earnings estimates. Key variables to monitor include CPU-platform support, adoption by server vendors, capacity per system, power consumption, and module-supplier qualification.
The disconfirming scenarios are also clear. First, incremental AI CPU demand could be offset by delays in GPU platforms. Second, server vendors may reduce general-purpose memory configurations to control total system costs. Third, CXL memory pooling and software compression could improve utilization efficiency. LPDDR/SoCAMM spillover will move from expectations into earnings only when platform shipments, capacity per system, and module prices rise simultaneously.
NAND/eSSD/SSD: Inference, RAG, and Enterprise SSD Leverage
The weekly catalyst for NAND is not consumer electronics, but AI inference. Asia technology research reports a significant upward revision to enterprise SSD demand associated with KV-cache offloading. Vendors now project 2027 demand at approximately 500 EB, representing nearly 50% YoY growth, while some cloud customers are willing to pay higher prices for enterprise SSDs. Compared with DRAM, NAND faces weaker supply constraints and more pronounced consumer-electronics estimate cuts. Its outlook is therefore not more certain, but its earnings leverage is greater.
Inference is shifting SSDs from “storing results” to “participating in computation.” As agentic tasks extend from minutes to hours or even days, context and KV caches may expand to tens of terabytes. Keeping all of this in DRAM or HBM would create capacity, power, and cost challenges. Offloading colder context to SSDs can improve utilization of expensive GPUs. Penguin Solutions plans to launch a KV-cache server in Japan in the fourth quarter, and says its per-GB cost could be only one-seventh to one-third that of adding GPU memory capacity, providing a verifiable product milestone.
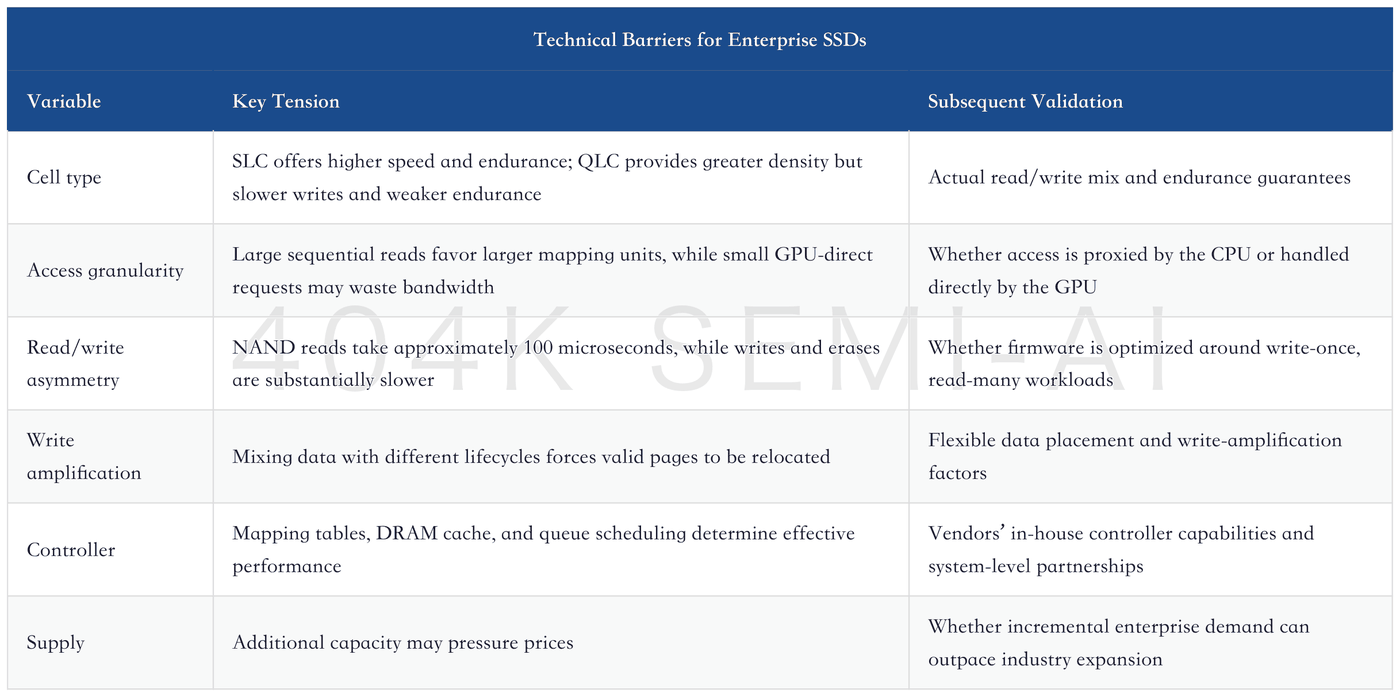
NAND’s greatest risk is that the demand thesis proves correct, but supply ramps even faster. Market-share gains by vendors such as YMTC and further capacity additions could pressure industry ASPs, while QLC endurance, small-block GPU access, and write amplification may constrain the product’s addressable applications. Other disconfirming factors include KV-cache compression, improved cache-hit rates, and CXL-pooled DRAM. If software can deliver the same inference output using fewer bytes, incremental SSD demand will fall short of projections based on linear extrapolation from raw context size.
Long-term agreements could also become a customer risk. CoreWeave is exploring put options and other instruments to hedge against declines in memory and storage prices because its long-term agreements with suppliers including Micron and SanDisk establish price floors. If future market prices fall below contracted prices, buyers will bear procurement costs above spot levels. The hedge has not yet been implemented, but the initiative shows that cloud customers already view storage pricing as a commodity exposure requiring active management.
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
This week, HDDs offered only share-price evidence, with no new operating evidence. Seagate Technology fell 18.11% for the week and Western Digital declined 19.87%, but the available materials provided no updates on nearline shipments, exabyte deliveries, capacity per platter, build-to-order execution, or free cash flow. The price pullback therefore cannot be directly interpreted as weakening AI data-lake demand, nor can the lower valuations be treated as confirmation of an operational turnaround.
The HDD investment thesis differs from that of NAND. NAND exposure is a play on average selling prices and enterprise SSD upside; HDD exposure is a play on duopoly supply discipline, build-to-order production, nearline exabyte growth, and cash-flow delivery. AI training and inference generate substantial volumes of infrequently accessed, long-lived data, theoretically supporting data-lake capacity. Whether that data ultimately resides on HDDs, however, depends on cloud customers’ hot/cold data-tiering strategies, object-storage architectures, and total cost per unit of capacity—not merely model parameters or token growth.
