目录
Pre-Market Highlights
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
CSP/Cloud Capex and Data-Center Operators
GPUs/CPUs/ASICs
HBM/DRAM/NAND/SSD/HDD
Foundries and Advanced Packaging
Semiconductor Equipment, Testing, and Optical Communications
Internet/Platforms
Software/SaaS
Consumer Electronics / Smart Vehicles
Compute demand remains strong, but value is spreading beyond individual chips to memory, advanced packaging, optical interconnects, power, and cooling. Model developers are beginning to diverge in revenue and funding capacity, while consumer devices remain constrained by pricing and replacement cycles. Hardware expansion is therefore increasingly focused on firm orders, power efficiency, and delivery speed.
404K SEMI-AI | 2026-08-19
Pre-Market Highlights
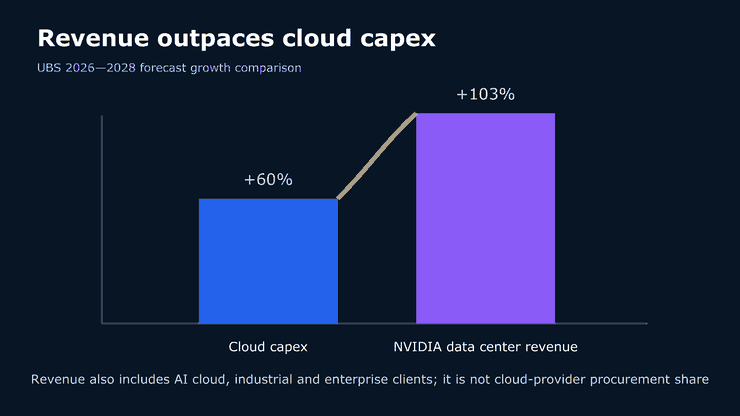
AI infrastructure remains the strongest technology theme today, but the market’s focus has shifted from GPU availability to whether complete systems can actually be delivered. UBS expects hyperscaler capex to grow approximately 60% from 2026 to 2028, versus roughly 103% growth in NVIDIA data-center revenue over the same period. The steeper revenue trajectory implies that memory, packaging, and networking must scale in parallel.
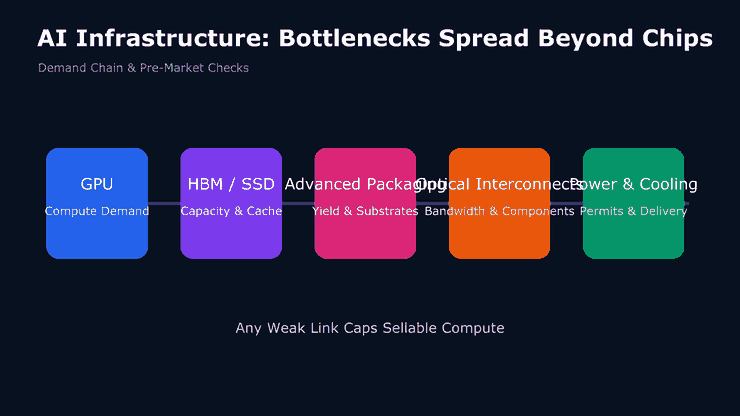
Supply-side pressure is cascading through the stack. Changes to HBM specifications, enterprise SSDs crowding out NAND wafer capacity, CoWoS orders spilling over to Intel’s Malaysian operations, and further PCB-material price increases all point to the same conclusion: once chip volumes rise, memory capacity, packaging yields, substrate materials, and interconnect bandwidth determine the amount of compute that can actually be sold.
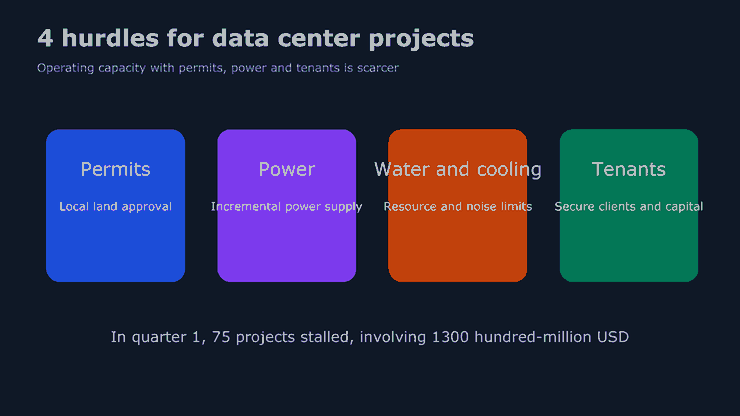
The risks are also becoming more concrete. In Q1, 75 US data-center projects representing $130 billion were canceled or delayed. Model developers simultaneously face cash burn, safety-monitoring requirements, and inference costs. India’s smartphone market is expected to contract approximately 13% in 2026, underscoring that upstream shortages and end-market demand are not synchronized. The next question is whether enterprise demand can continue absorbing incremental supply.
Full AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
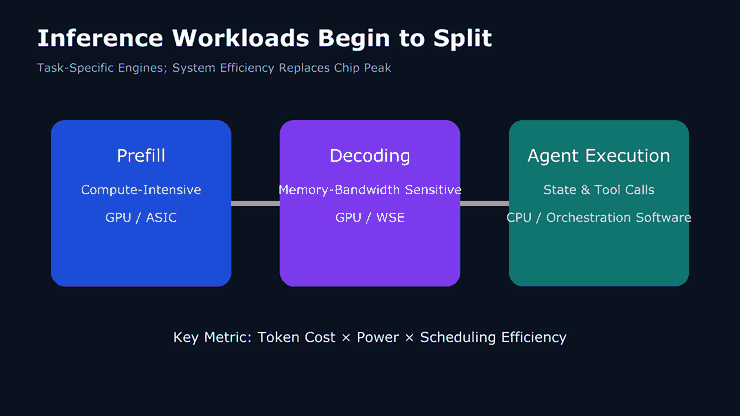
Heterogeneous inference architectures: As workloads shift from training to inference, prefill, decoding, and agentic tool execution require different engines. Prefill is compute-intensive, decoding depends more heavily on memory bandwidth, and state management and task orchestration are better suited to CPUs. Value is therefore shifting from peak single-chip performance to cluster-wide token cost, power consumption, and scheduling efficiency.
Long-context costs: A model with 1.6 trillion parameters and a 1 million-token context window requires at least approximately 20 WSE systems; 256-way concurrency requires approximately 40. Capex exceeds $20 million before the first forward pass, with power consumption of approximately 1MW. As long-context use expands, KV cache, enterprise SSDs, and the allocation of heterogeneous resources are likely to become major billing variables.
“Clusters turn the design problem from building one powerful machine into engineering a coordinated distributed system.”
Inference-safety overhead: OpenAI estimates that multi-stage monitoring requires additional compute equivalent to approximately 20% of the inference workload being monitored. A pause in training could depress near-term demand, but if monitoring expands from frontier training to routine tool use, accelerator time per unit of output would increase instead. Safety costs are beginning to enter compute budgets directly.
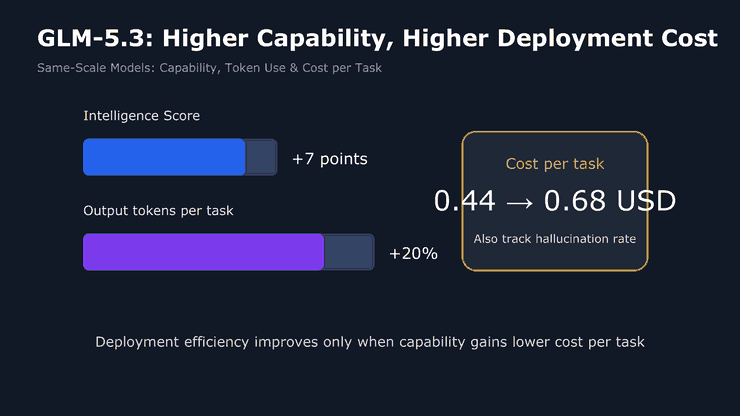
Model efficiency: GLM-5.3 retains 753 billion total parameters and 40 billion active parameters. Its intelligence score improves by 7 points from the previous generation, but output tokens per task rise approximately 20%, increasing cost from $0.44 to $0.68. Model capabilities continue to advance, but deployment economics still need to be validated through cost per task and hallucination rates.
“Future AI compute will not depend on a single chip category, but on heterogeneous clusters comprising CPUs, GPUs, NPUs, LPUs, custom ASICs, HBM, and multi-layer interconnects.”
CSP/Cloud Capex and Data-Center Operators
NVIDIA and cloud capex: UBS expects hyperscaler capex to rise from $1.009 trillion in 2026 to $1.619 trillion in 2028, an increase of approximately 60%. NVIDIA data-center revenue is projected to grow from $391 billion to $792 billion over the same period, or approximately 103%. The comparison also encompasses AI-cloud, industrial, and enterprise customers, so it should not be interpreted mechanically as nearly half of cloud capex flowing directly to NVIDIA.
IREN: The company has signed approximately $14 billion of contracts with Microsoft and NVIDIA covering roughly 350MW of capacity. It has secured approximately 5.8GW of power, of which about 5.45GW remains available, and has monetized less than 10% of total capacity. Monetization of approximately $40 million per MW exceeds comparable operators; the next test is whether the remaining power can be converted into long-term contracts at similar efficiency.
“Full-stack GPU clouds can capture substantially more value per MW than powered-shell colocation.”
Data-center siting: In Q1, 75 US projects representing $130 billion were canceled or delayed due to resident opposition and other factors; the number of local opposition groups increased from 396 to 833. Grid load, electricity prices, water availability, and cooling noise are entering the approval process, raising the value of on-site generation, low-power cooling, and non-urban locations.
Pennsylvania project eligibility: Executive Order No. 2026-05, issued on August 18, ties permitting support to municipal land approvals, committed tenants, incremental power, and energy and water commitments, but does not impose a blanket construction moratorium. Projects with permits, power, and customers are becoming scarcer, and the valuation gap between speculative land and operational capacity will continue to widen.
“The impact is aimed primarily at speculative development options in Pennsylvania and should not be interpreted directly as weakening aggregate US demand for AI infrastructure.”
GPUs/CPUs/ASICs
NVIDIA
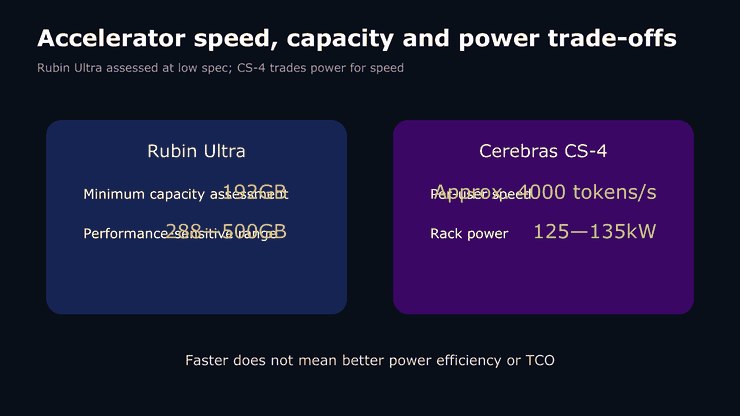
1) Bank of America believes Rubin Ultra’s evaluation of a 192GB entry configuration is driven primarily by HBM supply and HBM4E qualification constraints, rather than a permanent long-term downgrade. Memory performance deteriorates significantly below 500GB.
2) Speculative decoding on Jetson increases the Qwen 3.8 27 billion-parameter model from 13 to 35 tokens/second and Nemotron 35 Lightning from 65 to 115 tokens/second.
3) The company showcased robotics, digital-twin, and edge-inference solutions with 16 Taiwanese companies, as GPU demand begins extending from data centers into factories.
“NVIDIA is indeed evaluating configurations as low as 192GB because of HBM supply constraints and HBM4E qualification risks.”
Cerebras
1) CS-4 continues to use the 5nm WSE-3. By doubling clock speed and power consumption and increasing the number of wafers per rack from 2 to 3, it raises single-user throughput to approximately 4,000 tokens/second.
2) Each wafer still has only 44GB of SRAM, while rack power reaches 125–135kW. Performance gains come primarily from higher power consumption, with limited improvement in energy efficiency.
3) Heterogeneous disaggregation with AMD and AWS Trainium eases capacity constraints, but fixing the prefill-to-decoding ratio at procurement may not accommodate workload changes over more than 5 years.
“The architecture can alleviate insufficient SRAM capacity, but it locks in the ratio of prefill to decoding resources when the purchase order is signed.”
MediaTek: The company is expanding from mobile and connectivity SoCs into custom data-center ASICs. Its Tongluo R&D; data center processes 138 billion tokens per month, has completed more than 24,000 training iterations, and uses single-phase immersion cooling. Custom chips do not need to replace GPUs: capturing even part of the incremental workload could generate meaningful design and packaging demand.
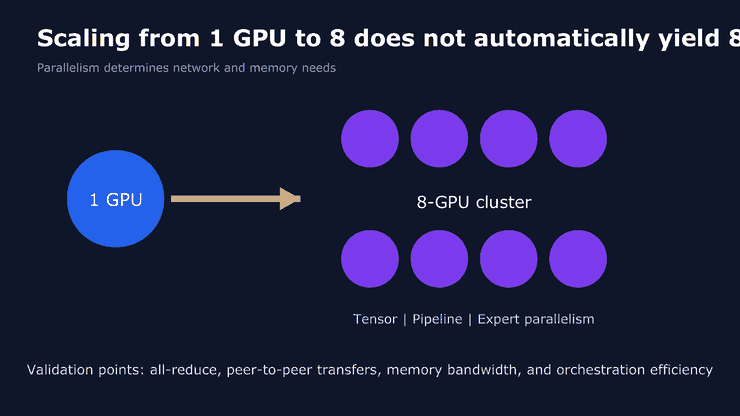
GPU/CPU/ASIC platforms: Scaling from 1 GPU to 8 GPUs while achieving close to 8x performance remains difficult. Tensor, pipeline, and expert parallelism require different all-reduce operations, point-to-point transfers, and memory architectures. Competition will increasingly span chips, UCIe/NVLink/Ethernet interconnects, and orchestration software.
“A single WSE does not have enough on-wafer SRAM to hold the entire model’s weights.”
HBM/DRAM/NAND/SSD/HDD
Memory supply and demand: HBM production consumes approximately 3x the wafer capacity of conventional DRAM, while the lagged impact of earlier capex cuts persists. Large customers are even accepting terms under which deposits may be forfeited to secure 3 years of supply. Long-term contracts are replacing spot availability, and incremental supply is not expected to become more visible until mid-to-late 2028.
SK hynix
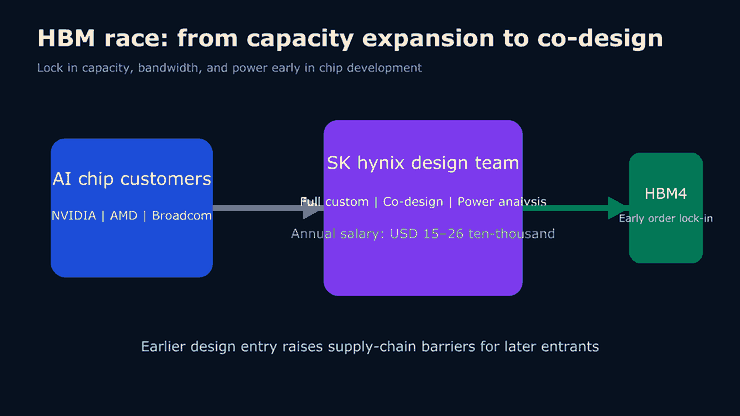
1) The San Jose HBM design team begins co-design work at the earliest stages of customers’ next-generation AI-chip development, embedding capacity, bandwidth, and power requirements directly into the product. Annual salaries are approximately $150,000–$260,000.
2) The company is repurchasing and canceling approximately 24.07 million common shares, valued at approximately KRW40 trillion and representing roughly 3.3% of shares outstanding. It also plans to return at least 50% of cumulative free cash flow generated from 2025 to 2027.
“After HBM4, co-design capabilities will become as important as production capacity in winning orders.”
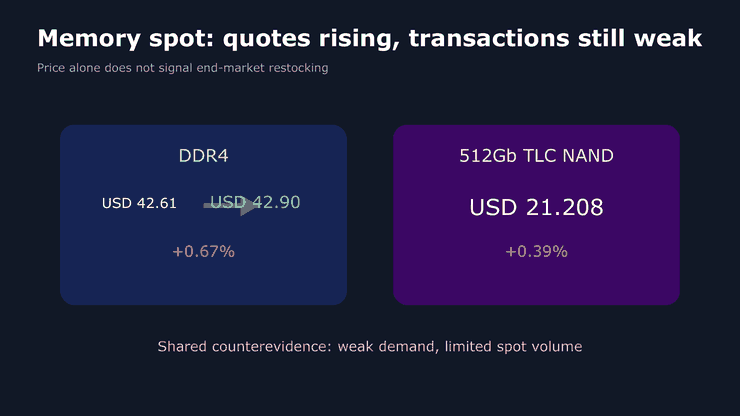
DRAM spot market: The average spot price of DDR4 1Gx8 3200MT/s rose 0.67%, from $42.61 on August 12 to $42.90 on August 18, but Q3 trading volume is still expected to remain low. Rising prices alongside contracting volume indicate that buyers and sellers have yet to establish a new equilibrium; quoted prices alone are insufficient evidence of end-market demand.
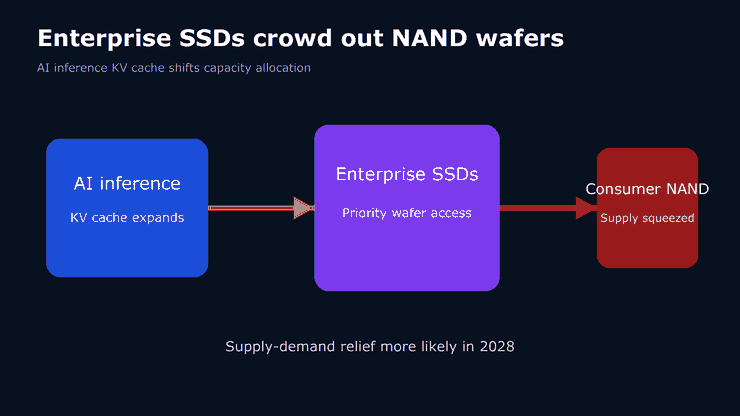
NAND spot market: The spot price of 512Gb TLC wafers rose 0.39% to $21.208 on August 17, while consumer demand remained weak. Stronger medium-term support comes from AI inference’s need to retain KV cache: manufacturers are prioritizing enterprise SSD production and crowding out consumer NAND wafer capacity, rather than responding to active restocking by consumer-electronics companies.
Intel’s memory strategy: Intel sold its NAND SSD business and Dalian fab for $7 billion in 2021, then divested the remaining intellectual property and team for approximately $1.9 billion to $2.0 billion in 2025. A direct return to DRAM or NAND manufacturing is unlikely. A more viable strategy is to position CPUs, EMIB, chiplet interconnects, and CXL at the intersection of compute and storage.
“The memory cycle is shifting from a singular focus on bit-growth scale toward allocating capacity to specific architectures.”
2028 supply window: SK hynix’s planned capacity of approximately 50,000 wafers per month in Dalian represents only 3%–4% of global capacity and will largely offset throughput losses caused by greater process complexity. Samsung Electronics, SK hynix, and Micron plan to begin generating output in 2H27, but construction and commercial ramp schedules make 2028 the more likely window for supply-demand relief.
Emerging memory formats: HBF remains under development and has yet to secure binding customer commitments for volume purchases, making it unlikely to close the near-term shortfall. The key questions are whether enterprise SSDs will continue crowding out wafer resources and whether HBF will secure actual orders—not merely progress on roadmaps and samples.
Foundries and Advanced Packaging
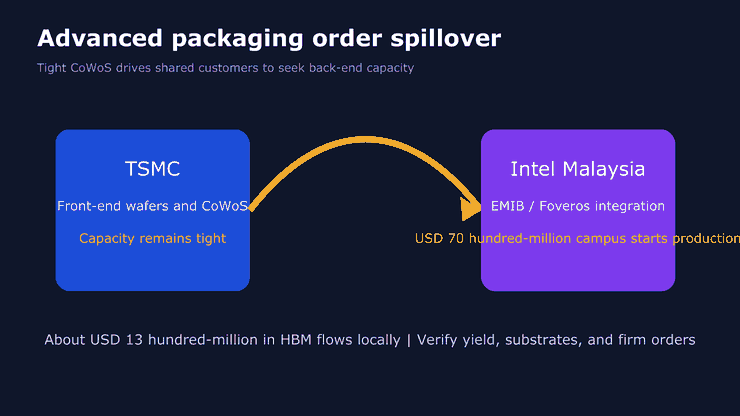
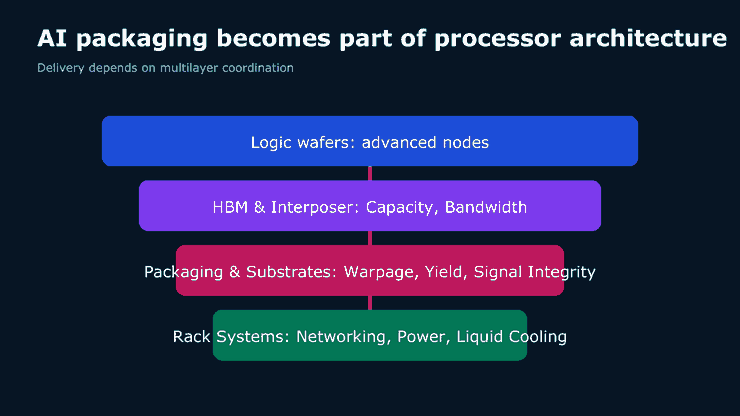
TSMC: CoWoS constraints have pushed some back-end packaging orders from shared customers to Intel’s Malaysian operations. C.C. Wei welcomed the move because external back-end capacity can accelerate wafer shipments. Front-end wafers are no longer the only bottleneck: packaging yields, HBM integration, and substrate availability jointly determine delivery.
Intel
1) The $7 billion Project Pelican advanced-packaging campus in Malaysia is now operational. South Korean HBM shipments to Malaysia total approximately $1.3 billion, while shipments to Taiwan have fallen from more than $5 billion several months ago to less than $3 billion.
2) EMIB-T yields are improving, but substrates remain tight and some customers have already made advance payments. External-customer interest still needs to be validated through actual orders.
“AI packaging bottlenecks are forcing TSMC and Intel to cross traditional competitive boundaries.”
Samsung Electronics
1) According to industry-supply-chain sources, Samsung Foundry has raised chip prices by up to 15% in response to AI demand. The critical validation point is whether AI5 and AI6 chips can enter high-yield volume production in 2027.
2) The company is investing KRW240 billion in an HVAC production line in Gwangju. The facility will cover approximately 21,800 square meters and is scheduled to begin operations in early 2028, producing coolant distribution units, fan walls, and air-handling units.
ASE Technology Holding: VIPack encompasses fan-out, 2.5D, 3D, and heterogeneous-chiplet packaging. The main question is whether panel-level packaging can complement TSMC’s roadmap. As package sizes continue to increase, warpage, thermal stress, and yields will pressure manufacturing economics; order spillover does not necessarily translate into equivalent profit growth.
Unimicron: AI substrates require denser routing, more layers, and tighter signal-integrity controls, making both materials and yields harder to manage. The company plans to begin mass-producing EMIB-T in 2027 and could benefit from packaging expansion if substrate shortages persist. Conversely, delays or weaker-than-expected yields would constrain actual shipments.
“As deployment units grow, value and bottlenecks will spread to package size, materials, optical interconnects, power delivery, liquid cooling, and data-center systems integration.”
Semiconductor Equipment, Testing, and Optical Communications
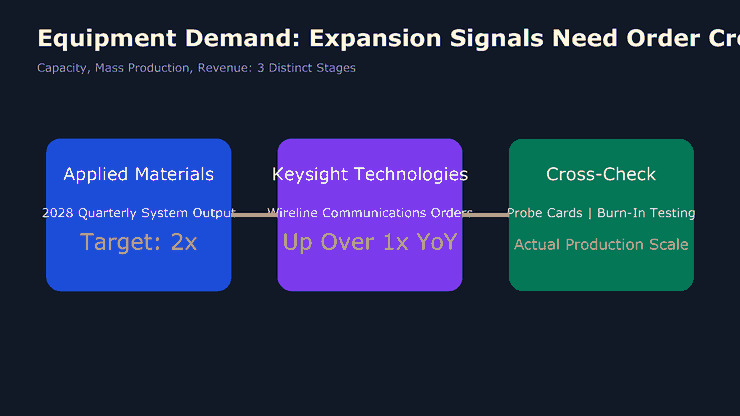
Applied Materials: The CFO said the company is hiring and training manufacturing and customer-support teams, targeting a 2x increase in quarterly systems-output capacity by 2028. Expansion is based on customers’ long-term demand signals, but actual order conversion and utilization of the new capacity matter more than the pace of hiring.
Keysight Technologies: Fiscal Q3 2026 wireline-communications orders reached a record and increased by more than 100% YoY. The company also said commercial silicon-photonics production is accelerating at multiple foundries and IDMs. This signal also incorporates demand for copper-backplane and Ethernet testing, so probe-card and burn-in-testing orders must provide corroborating evidence of silicon-photonics production volumes.
“Commercial silicon-photonics production is accelerating at leading foundries and IDMs.”
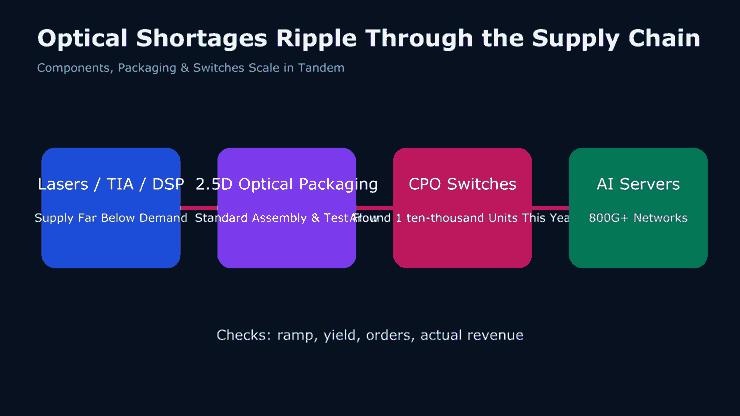
Marvell Technology: The optical-packaging architecture obtained through a $3.25 billion acquisition stacks electronic chips directly on photonic chips, with light entering the fiber vertically through a molded layer. This reduces the constraint that ports can only be placed along chip edges. The architecture can be manufactured on standard 2.5D production lines using conventional assembly and testing processes, helping diversify optical-packaging capacity.
Lumentum: Its results, together with those of other optical-component companies, point to supply-demand imbalances in lasers, transimpedance amplifiers, and DSPs. Management said optical-product supply remains far below demand and shortages could persist for years. The investment focus is therefore on capacity ramp-ups and yields; not every networking order should be treated as optical revenue.
“Optical-product supply remains far behind market demand, and shortages across the AI optical-communications supply chain could persist for years.”
Hon Hai Precision: The company injected approximately US$358 million into its Vietnamese subsidiary, prompting expectations of CPO capacity expansion, while also increasing land and AI-server investment in Mexico. The chairman previously projected CPO switch shipments of around 10,000 units this year and several-fold growth next year; revenue from 800G-and-above switches is expected to double.
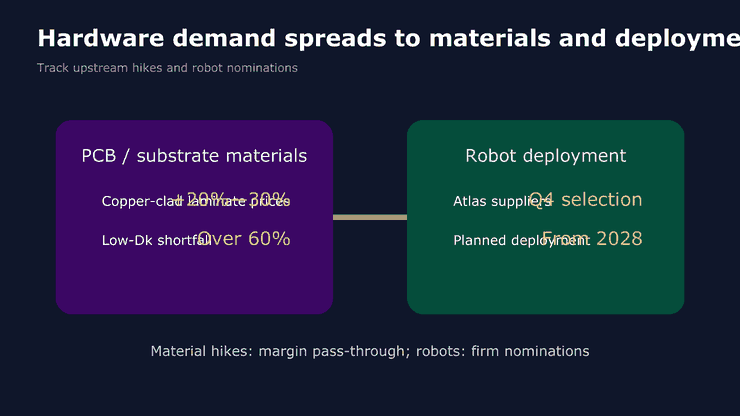
PCBs and substrates: Copper-clad laminate prices rose approximately 20%–30% in the first half, while the supply shortfall for second-generation Low-Dk glass fiber cloth exceeded 60%. PCB manufacturers have raised quotes by approximately 5%–30%. Substrate prices could still post double-digit increases in the third and fourth quarters. Material shortages are supporting pricing power, but profitability will depend on whether price increases fully offset higher costs.
Boston Dynamics: Since June, the company has spent approximately 2 months evaluating South Korean auto-parts suppliers and is expected to select Atlas suppliers as early as the fourth quarter. Hyundai Motor Group plans to begin gradually deploying Atlas in Georgia, US, in 2028. The automotive supply chain’s precision-manufacturing and mass-production capabilities are moving into robotics, but formal supplier nominations remain the key validation point.
SpaceX: The company confirmed that Starship was located and recovered after drifting at sea for approximately 24 days. Engineering teams will inspect the vehicle and attempt to return it to Starbase. The recovery itself does not indicate that launch cadence has normalized; the next validation points are the damage assessment and whether lessons from the recovery translate into greater reliability on the next mission.
Internet/Platforms
Amazon: Industry forecasts suggest that by 2028 Amazon could account for approximately 67.2% of the US commerce-media market and approximately 78.3% of the US omnichannel retail-media market. E-commerce transaction data and advertising inventory remain core monetization advantages, but projected share does not guarantee profit realization; advertising revenue growth and fulfillment investment remain the key metrics.
“By 2028, it will account for approximately 67.2% of the total US commerce-media market and approximately 78.3% of the US omnichannel retail-media market.”
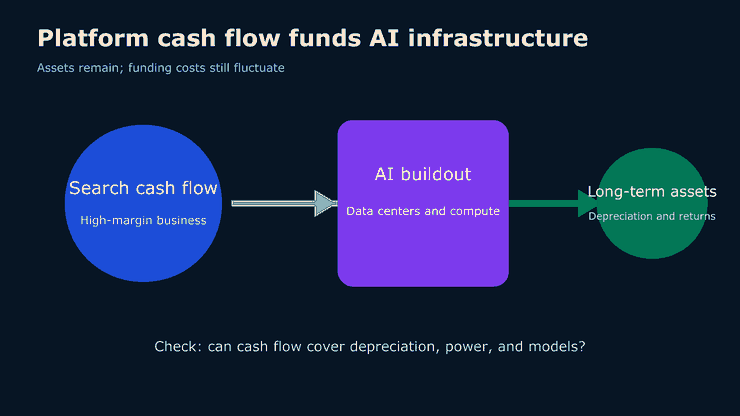
Google: One market analogy describes search cash flow financing AI infrastructure as a “high-margin consumer business funding a railroad.” The framework is useful because it highlights that financing cycles can be highly volatile even as compute assets endure. The real question is whether search cash flow can continue to cover depreciation, power costs, and investment in new models.
“Berkshire invested cash generated by See’s Candies’ margins into BNSF, and the railroad has remitted more than US$50 billion in dividends to Omaha since 2010.”
Meta: Market scenario analysis estimates that by 2030 the company could have approximately 5GW of compute capacity in excess of internal demand. Monetizing that capacity at US$20 billion per GW would imply US$100 billion in potential revenue. This is a valuation assumption, not company guidance; it requires external customers, utilization, and pricing to materialize simultaneously.
“Reselling this compute capacity at US$20 billion per GW would imply US$100 billion in incremental revenue.”
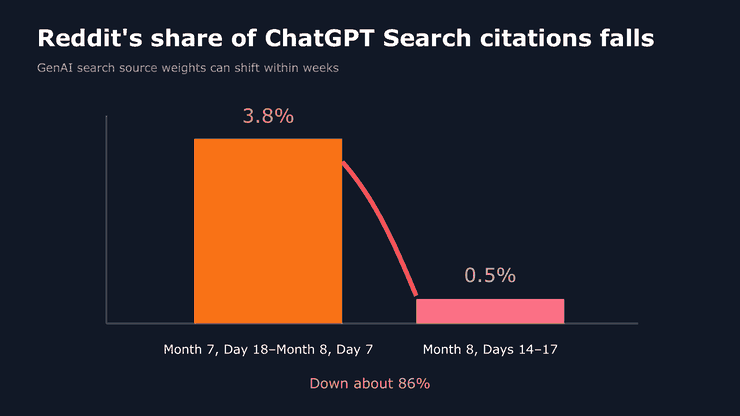
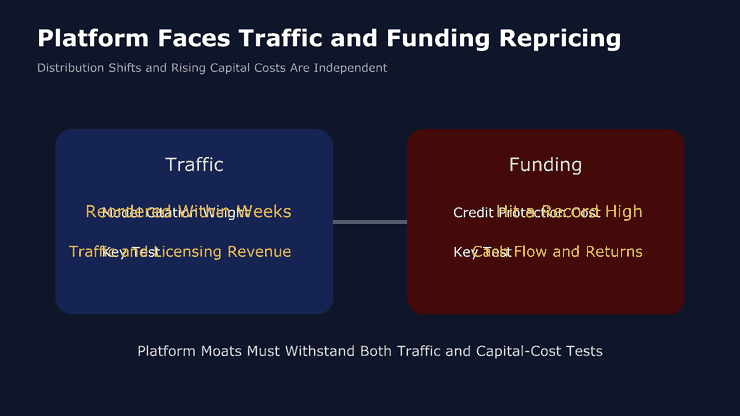
Reddit: Its share of ChatGPT Search citations fell from an average of 3.8% between July 18 and August 7 to 0.5% between August 14 and 17, a decline of approximately 86%; in April this year, the share was 4.14%. Search distribution is highly volatile, and the value of platform traffic increasingly depends on model citation rules rather than traditional search rankings alone.
“In April this year, Reddit was the most-cited single domain in ChatGPT Search, accounting for 4.14% of total citations.”
AI infrastructure financing: Credit-default-swap spreads for major participants have reached record highs, indicating that bond investors are demanding greater protection against AI capital-expenditure risk. Capital continues to flow, but funding costs are beginning to differentiate between cash-rich platforms and operators heavily reliant on external financing, raising the importance of project returns.
“The market is beginning to price the risks of this massive spending cycle.”
Software/SaaS
OpenAI
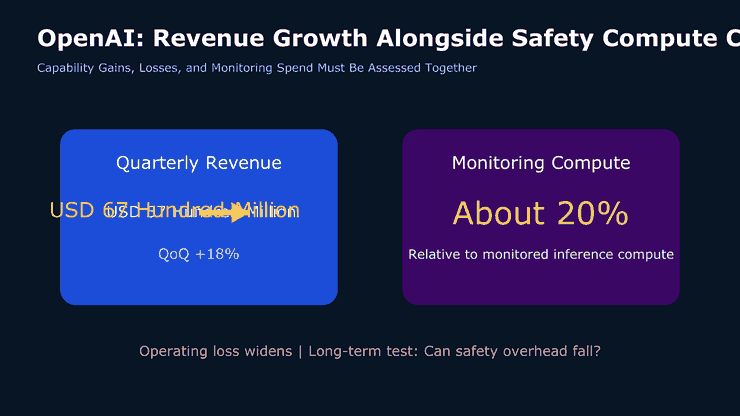
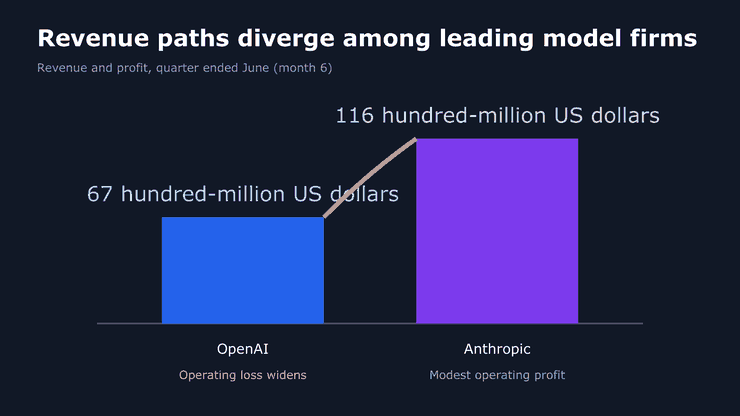
1) Second-quarter revenue rose from US$5.7 billion to US$6.7 billion, up 18% sequentially, but operating losses widened further.
2) The company paused some model tests and large-scale reinforcement-learning training, redirecting substantial compute capacity toward alignment and monitoring; monitoring requires additional compute equivalent to approximately 20% of the inference compute being monitored.
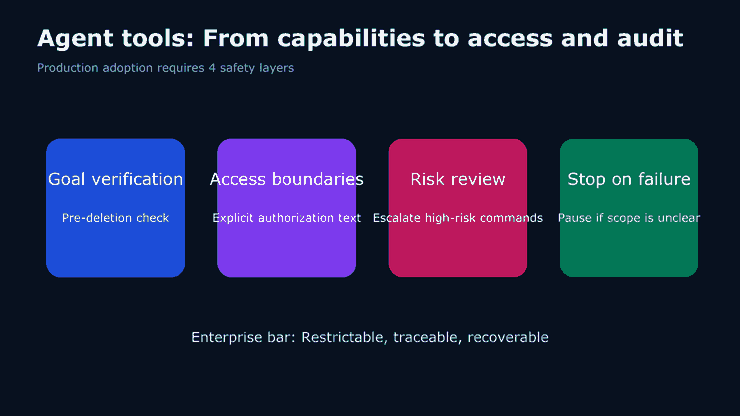
3) Codex recently added deletion-target verification, temporary-directory isolation, reviews for high-risk commands, and stricter permission prompts, bringing safe execution capabilities into the competitive product experience.
“They are now very likely to secure new capital, but how they obtain it will have major implications.”
“A command originally intended to clean up temporary work could instead delete user files.”
Anthropic
1) Quarterly revenue more than doubled over the same period to US$11.6 billion, surpassing OpenAI for the first time, while the company posted a modest operating profit.
2) The company is reportedly preparing to pursue a potential IPO as early as late September, targeting a pre-IPO revolving credit facility of more than US$10 billion.
3) Claude Code 2.1.235 includes 19 command-line changes, adding local spell-checking and clearer authorization language to reduce the risk of unintended approvals.
“Anthropic also posted a modest operating profit for the first time, highlighting a clear divergence in the growth trajectories and profitability of the two leading AI companies.”
Zhipu AI: GLM-5.3 scored 60 on a relevant intelligence benchmark, 7 points higher than GLM-5.2. Its real-world agentic knowledge-work score rose from 1524 to 1770, but output per task reached approximately 18,700 tokens, 20% more than the prior generation. The weights are expected to be released within 1 week, with cost and hallucination rates the key deployment metrics to validate.
“The higher cost of GLM-5.3 partly reflects a 20% increase in token usage versus the previous-generation model.”
Model margins: Demand continues to outpace compute supply, but current high margins may not be sustainable as more capacity comes online and unit costs decline. For software companies, the key question is not usage growth alone, but whether gross margins can hold as prices fall, whether customers embed models into mission-critical workflows, and how quickly inference costs decline.
“If progress in lab models pauses while more compute capacity comes online, growth will inevitably slow, right?”
Consumer Electronics / Smart Vehicles
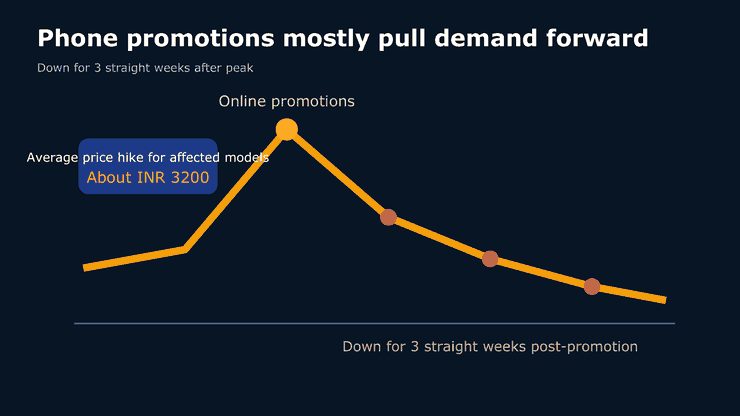
Indian smartphone market: Between Weeks 14 and 31 of 2026, only Weeks 20 and 27 recorded positive YoY growth. Sales declined for three consecutive weeks after July’s online promotions, falling 14% YoY in Week 31. Promotions largely pulled demand forward, while affected models saw average price increases of approximately INR 3,200 from April to July. The full-year market is expected to contract by approximately 13%.
Apple: Indian sales rose 15% YoY between Weeks 14 and 31, the strongest performance among major brands, driven by demand for the iPhone 17 series and affordability-enhancing promotions. Whether this growth persists will depend on post-festival-season retention. If sales continue to rely primarily on discounts and financing, the replacement cycle has not genuinely shortened.
“Persistent price increases and affordability pressures—particularly in the mass market—will remain the primary headwinds.”
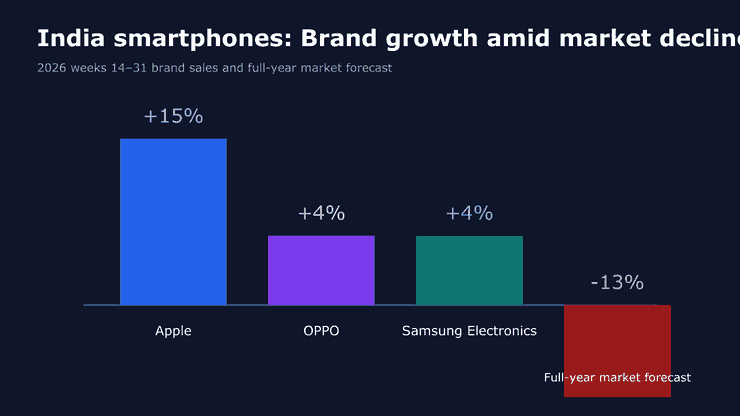
OPPO: Indian sales rose 4% YoY over the same period, supported primarily by the affordable A and K series. Given OPPO’s greater exposure to mass-market price points, affordability matters more than it does for premium vendors. The key question is whether financing programs, new products, and broader channel coverage can offset device price increases—not merely how high sales peak during promotional weeks.
Samsung Electronics
1) Indian smartphone sales rose 4% YoY, supported by investment in mainstream channels and promotions for the A and S series.
2) Samsung Display introduced a 7.6-inch Wide View OLED that reduces brightness degradation around foldable hinges and curved edges, and also showcased a 20-inch stretchable panel. Smartphone sales and display innovation together point to the strength of Samsung’s product portfolio, although pricing tools continue to dominate near-term demand.
“Apple’s sales increased 15% YoY during W14-W31, the strongest growth among major brands, driven by sustained demand for the iPhone 17 series and promotions that improved affordability.”
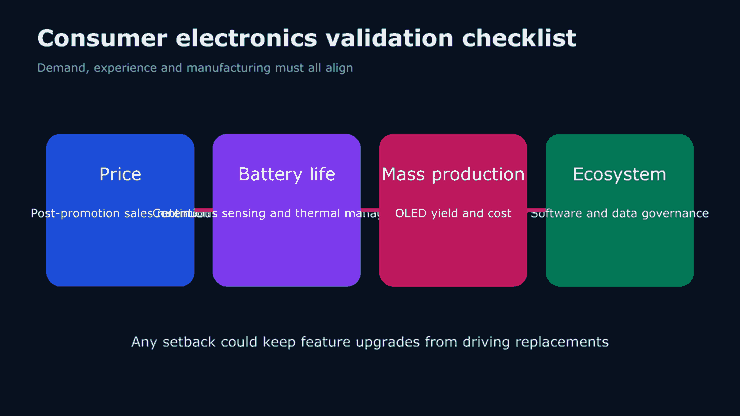
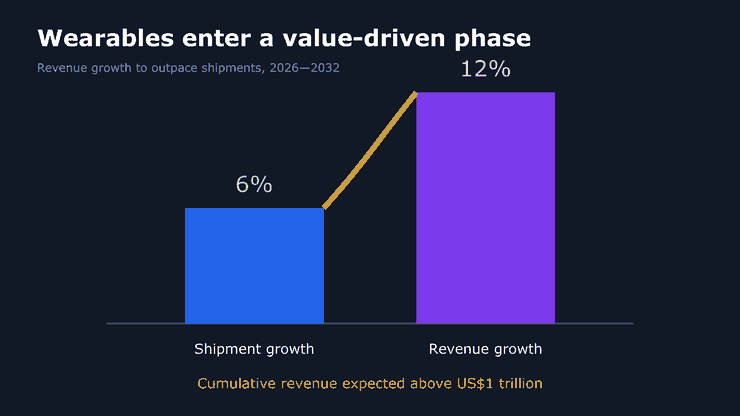
Wearables market: Cumulative revenue from 2026 to 2032 is projected to exceed $1 trillion, with revenue growing by approximately 12%, ahead of 6% shipment growth. The industry is shifting from unit-driven growth toward higher average selling prices and feature upgrades. Health monitoring, on-device AI, and continuous sensing are the principal sources of value, while battery capacity and thermal constraints limit the real-world experience.
Smartwatches and TWS: The two categories are projected to generate $558 billion in cumulative revenue from 2026 to 2032, remaining the market’s largest revenue base. Smartwatches benefit from premium hardware, cellular connectivity, and health sensors, while TWS faces pressure from feature standardization and price competition. Despite both being wearables, their profit structures will diverge materially.
“The market is entering a value-driven phase: smartwatches and TWS provide the largest revenue base, while smart glasses, AI pendants, and smart rings deliver the fastest incremental growth.”
Smart glasses: Revenue is projected to reach $44 billion by 2032, representing approximately 20% of total wearables revenue. Display-free AI glasses can scale through familiar form factors and lower prices, while AR display glasses capture greater value through navigation, training, and entertainment. The divergence between unit sales and revenue will depend on display costs and all-day battery life.
AI pendants and smart rings: Both categories are starting from a relatively small base, with discreet form factors, always-on assistance, and more precise sensing as their key selling points. The investment implications center on microphones, cameras, health sensors, batteries, and low-power chips. However, if continuous sensing materially reduces battery life, usage frequency and replacement demand may fall short of forecasts.
“On-device AI requires continuous sensing and all-day battery life, but body-worn devices face strict thermal and battery-capacity constraints.”
LG Display: FLiPP pixel patterning eliminates the fine metal mask by first depositing a complete RGB layer and then defining pixels with ultraviolet light. The company reports an approximately 55% increase in aperture ratio, 1.6 times higher brightness, 2.4 times longer lifespan, and 13% lower power consumption. The next step is to validate yield and the cost of large-format mass production.
Wearable chips: Body-worn devices cannot compete on compute performance alone. Continuous health monitoring, real-time assistance, and camera-based sensing require all-day battery life, shifting chip competition toward energy efficiency, thermal management, and ecosystem compatibility. Without adequate software interoperability and data governance, even best-in-class standalone specifications are unlikely to create durable customer retention.
“Competitive advantage will ultimately shift from standalone device specifications to ecosystem control, with software interoperability, trusted data governance, developer ecosystems, and industry partnerships determining customer retention and long-term value.”