
目录
Pre-Market Takeaways
AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
CSP/Cloud Capital Expenditure
AI Cloud/Data-Center Operators
GPU/CPU/ASIC
HBM/DRAM/NAND/SSD/HDD
Foundry and Advanced Packaging
Power Semiconductors, Passive Components, and Optical Communications
Internet/Platforms
Software/SaaS
Consumer Electronics/Smart Vehicles
Overview
404K | 2026-08-18
Pre-Market Takeaways
Technology trading is shifting further toward hardware. QQQ fell 0.16%, while semiconductors gained 1.6% and internet and software stocks declined about 3%. This looks more like rotation in thin trading than a definitive style reversal based on a single session. More durable signals will come from memory spot prices, long-term procurement contracts, and advanced-packaging capacity.
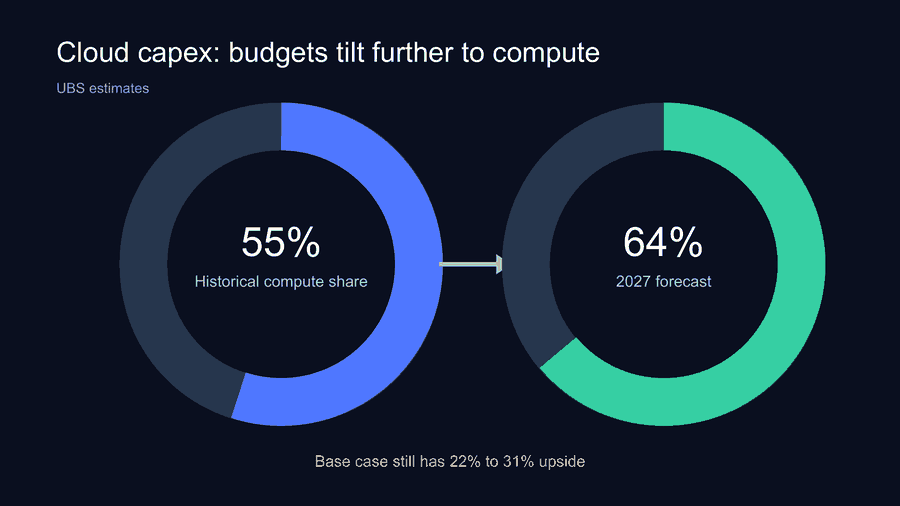
Cloud demand is not cooling, but the spending mix is changing. UBS expects compute to rise from a historical share of about 55% to about 64% of cloud providers’ capital expenditure in 2027, directing more budget toward servers, chips, memory, and networking. At the same time, greater reliance on leases, bonds, and structured financing means interest rates and credit metrics are becoming as important as orders.
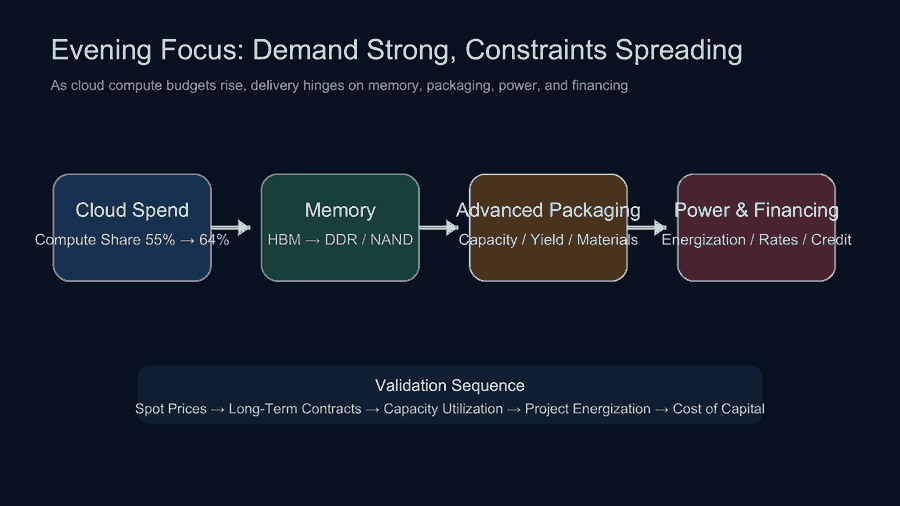
Risks are spreading as well. Memory shortages could raise server costs, packaging expansion remains constrained by yields and materials, and data-center power infrastructure is developing more slowly than chip demand. The most important pre-market check is not the one-day price move, but whether pricing, contracts, capacity utilization, capital costs, and project energization schedules corroborate one another.
AI/Semiconductor Value Chain
AI Models, Applications, and Capital Expenditure
Anthropic/Claude
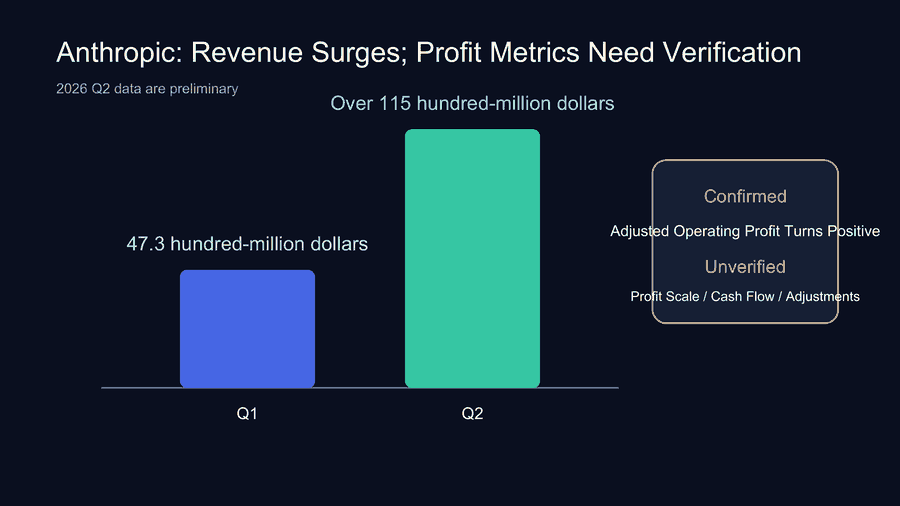
1) Anthropic reportedly generated more than $11.5 billion in preliminary revenue in Q2 2026, at least 14 times the year-earlier level and above Q1’s $4.73 billion.
2) Adjusted operating profit has turned positive, but the company disclosed neither the scale of profitability nor adjustment items, cash flow, or GAAP results. Compute costs, customer concentration, and contract durability remain the key measures of growth quality.
“Anthropic generated more than $11.5 billion in preliminary revenue in Q2 2026, at least 14 times the year-earlier level.”
OpenAI
1) At the end of 2025, OpenAI and Anthropic projected combined annualized 2026 revenue of about $45 billion. Their combined annualized revenue has now exceeded twice that forecast, reducing demand risk around existing compute-purchase commitments.
2) GPT 5.6 Sol pricing has been cut by 50% on some model gateways. The next test is whether usage grows by more than 2 times, demonstrating that the lower price improves market share rather than merely reducing revenue per unit.
AI Capital-Expenditure Financing: Buildout intensity remains high, but funding is expanding beyond operating cash flow to bonds, leases, and structured financing. Higher capital expenditure supports demand for chip and memory vendors; if financing costs rise, however, both project timelines and growth-stock discount rates will come under pressure. Cloud-provider capital expenditure should therefore be assessed alongside credit metrics, with actual demand ultimately confirmed by energized capacity and utilization.
CSP/Cloud Capital Expenditure
Google
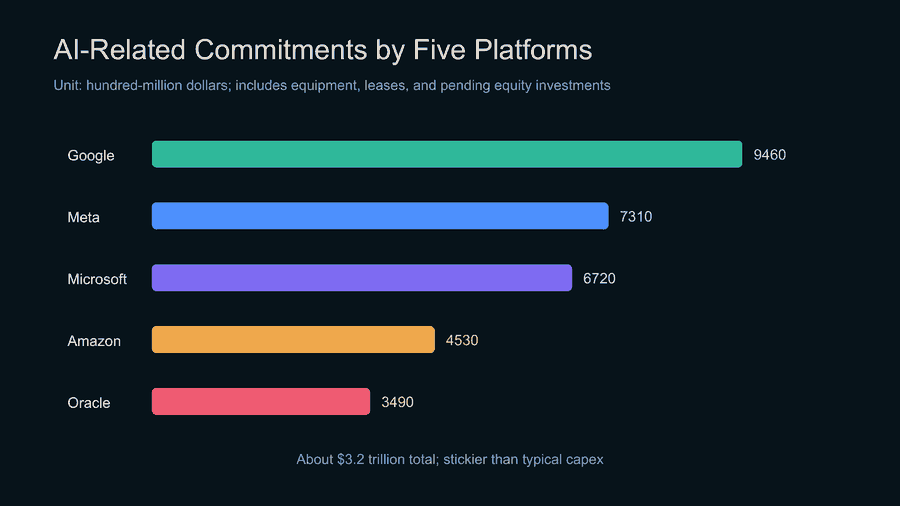
1) Google’s total AI-related commitments reached $946 billion, up 116% quarter over quarter. Equipment-purchase commitments rose 144% to $811 billion, indicating that a substantial volume of hardware orders has already been locked in.
2) The company plans to pay $10 million for de-identified internal business data from an airline for product development and AI-model training. The transaction still requires bankruptcy-court approval.
3) TPU interconnects continue to expand beyond 3D Torus. In a 4,096-chip cluster, a 6D Torus architecture can reduce the worst-case hop count from 24 to 12, but requires significantly more optical components and optical circuit-switching capacity.
“Multiyear leases and signed equipment-purchase orders are different because they represent contractual obligations the company must fulfill.”
Meta
1) Total AI-related commitments reached $731 billion, up 59% quarter over quarter; future lease commitments rose 90% to $347 billion.
2) The shares fell 3.5%. Beyond the rotation into hardware, the market is reassessing off-balance-sheet obligations and litigation over harm to teenagers. Future leases increase buildout stickiness while bringing financing costs and legal risks forward into valuation.
Amazon
1) Total AI-related commitments reached $453 billion, up 13% quarter over quarter.
2) Under a long-term scenario in which AWS adds about 8 GW annually and monetization rises from about $8 per watt to $12–$15 per watt, annual revenue could reach about $1 trillion as early as 2034–2035, implying about $300 billion in EBIT. The critical variables are power commissioning and revenue per watt, not headline capital expenditure alone.
Microsoft
1) Total AI-related commitments reached $672 billion, up 50% quarter over quarter; future lease commitments rose 67% to $329 billion.
2) The shares fell about 3% without a clear company-specific catalyst, suggesting broad de-risking across software and large-cap internet stocks. Contractual obligations improve visibility into infrastructure demand but also reduce capital-expenditure flexibility if demand weakens.
Oracle: Total AI-related commitments reached $349 billion, up 16% quarter over quarter, while future lease obligations rose to $260 billion, more than double their initial level. Oracle’s key variables now extend beyond cloud orders to lease duration, financing costs, and delivery schedules. Commitments will translate into cash returns only if leased capacity comes online on schedule and generates revenue.
Cloud-Provider Spending Mix: UBS expects compute to account for about 64% of total cloud-provider capital expenditure in 2027, up from a historical level of about 55%, with 22%–31% upside to its base forecast. The shift toward servers and chips benefits GPUs, memory, and interconnects, but also requires synchronized expansion of power, data-center space, and networking. Delays in any component would depress equipment utilization.
AI Cloud/Data-Center Operators
Nebius: Phase 2 of the Vineland data center has been approved and will add 600,000 square feet, potentially bringing the project’s ultimate footprint to 2.6 million square feet; Phase 1 remains under construction. Approval removes one preliminary constraint, but the next tests are construction, energization, and customer onboarding. Planned floor space should not be equated with immediately marketable compute capacity or revenue.
CoreWeave and IREN: One institution purchased Nebius, IREN, and CoreWeave around the July interest-rate decision, arguing that cloud giants capable of monetizing a full technology stack are better positioned than pure-play AI laboratories. This indicates investor preference but does not substitute for operating data. Customer concentration, debt maturities, and energized capacity remain the critical metrics for emerging cloud providers.
“Planning-commission members who voted to approve Phase 2 said Data One, the company behind the data center, had been responsive to residents’ complaints and that they would continue monitoring the project.”
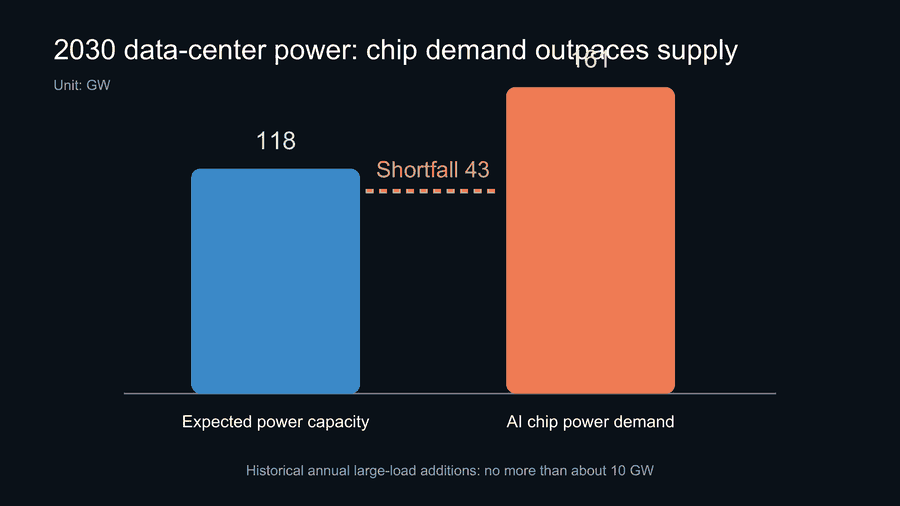
Data-Center Power: U.S. data-center power capacity is projected to reach 118 GW by 2030, 52% above the previous forecast. AI-chip shipments over the same period could imply 161 GW of power demand, leaving a 43 GW shortfall. Historically, the grid has connected no more than about 10 GW of large loads in a single year, suggesting that energization timelines could constrain revenue recognition before chip supply does.
GPU/CPU/ASIC
NVIDIA
1) BofA maintained its Buy rating and $350 price target, arguing that NVIDIA’s control of chip, land, power, and construction resources can reduce dependence on public-cloud giants. Enterprise value/free-cash-flow multiples are 18 times and 15 times for calendar 2027 and 2028, respectively.
2) Vera Rubin deployment could exceed 50,000 racks, with production expected to ramp in late 2026 and xAI and Meta leading initial adoption.
3) Supply-chain sources indicate rack-scale AI-compute plans of about 24–30 GW in 2027, potentially securing 35%–40% of global HBM supply. Neither NVIDIA nor memory vendors have confirmed this share, which must be verified against contracts and actual shipments.
“The main risk is that slower AI demand could pressure both NVIDIA’s growth rate and balance sheet.”
Cerebras
1) Cerebras has reportedly become the exclusive compute backbone for OpenAI GPT 5.6 Sol Ultrafast mode, delivering inference speeds of up to 750 tokens per second. The partnership includes 750 MW of compute capacity through 2028.
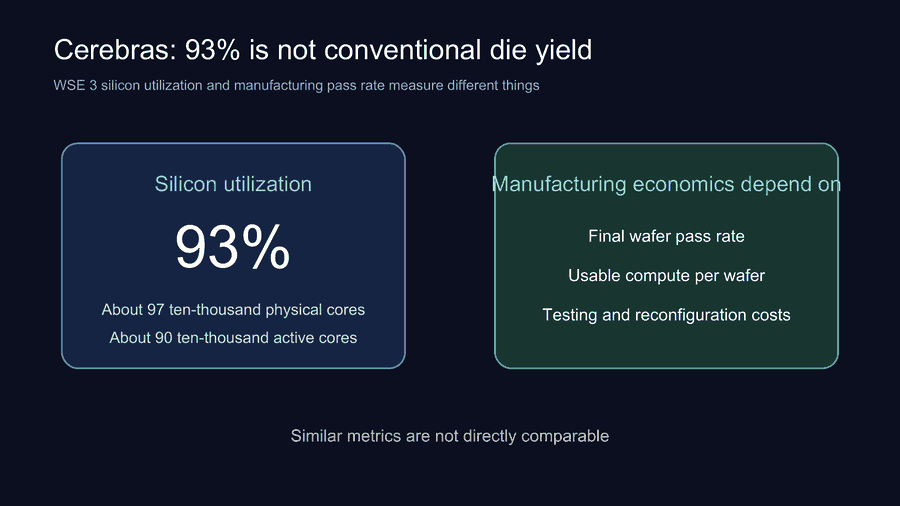
2) WSE 3’s 93% figure refers to silicon utilization, not conventional die yield: 900,000 of approximately 970,000 physical cores are active. The relevant comparisons are final wafer pass rates, usable compute per wafer, and testing and reconfiguration costs.
Broadcom: Planned HBM demand for 2028 is about 35–40 billion Gb, the highest among major customers surveyed through channel checks. Separate field pricing indicates HBM4 at about $36 per GB. Whether these demand plans become binding multiyear contracts will determine whether Broadcom’s custom-ASIC expansion secures supply or merely raises system costs.
AMD: Planned HBM demand for 2028 is about 10 billion Gb, while field checks indicate HBM4 pricing of about $40 per GB. AMD is also among TSMC’s expanding N2 customer base, with timing around 2026–2027. Scaling shipments will require adequate HBM allocation, advanced-packaging capacity, and new-process yields; GPU demand alone does not establish deliverable revenue.
HBM/DRAM/NAND/SSD/HDD
Memory Industry: UBS expects investment in HBM for AI servers to rise from $23.9 billion in 2025 to $173.3 billion in 2027, while server DDR investment increases from $10.3 billion to $305.4 billion over the same period. Server SSD NAND investment is projected to rise from $13.5 billion to $178.3 billion, and storage SSD NAND from $5.2 billion to $59.5 billion. Demand is broadening from HBM into system memory and storage.
“DDR benefits not only from AI-server investment but also from conventional-server spending, making it a growth engine for the broader memory cycle.”
Micron
1) UBS said demand strengthened further after the earnings report. Micron currently satisfies less than 50% of data-center customer demand, expects supply-demand conditions to be tighter in 2027 than in 2026, and sees the industry’s blended HBM average selling price potentially rising 79% year over year.
2) The company plans to derive more than 50% of revenue from strategic customer agreements, with about 10% of volume under take-or-pay arrangements.
3) BofA maintained its Buy rating and $1,550 price target and expects EPS could exceed $230. The risk is that early HBM contract pricing lags increases in DDR prices, delaying gross-margin improvement until repricing occurs.
SK hynix
1) Pricing obtained by Cantor at an industry event indicates that HBM4 sells for about $32–$40 per GB depending on the customer, including about $32 for NVIDIA.
2) The company said HBM4E contains 380 billion transistors and expects customer-specific designs to become a priority beginning with HBM5. Memory shortages could be most severe in 2027.
3) Headcount increased by 1,601 in the first half, 5 times Samsung Electronics’ increase. The pace of expansion must still be aligned with employee relocation to Yongin, the U.S. packaging plant, and actual yields.
