目录
Pre-Market Highlights
Full AI/Semiconductor Supply Chain
GPUs/CPUs and Rack Systems
HBM/DRAM/NAND/SSD
Foundry, Packaging, and Testing
Optical Communications, Power, and Thermal Management
Internet / Platforms
Software / SaaS
Consumer Electronics / Smart Vehicles
Value capture across AI infrastructure continues to spread into racks, power, liquid cooling, optical interconnects, and testing, while memory and passive components are also showing signs of tightening supply. Demand remains strong, but capital commitments, grid connections, and realized returns are becoming equally important constraints.
404K SEMI-AI | 2026-08-17
Pre-Market Highlights
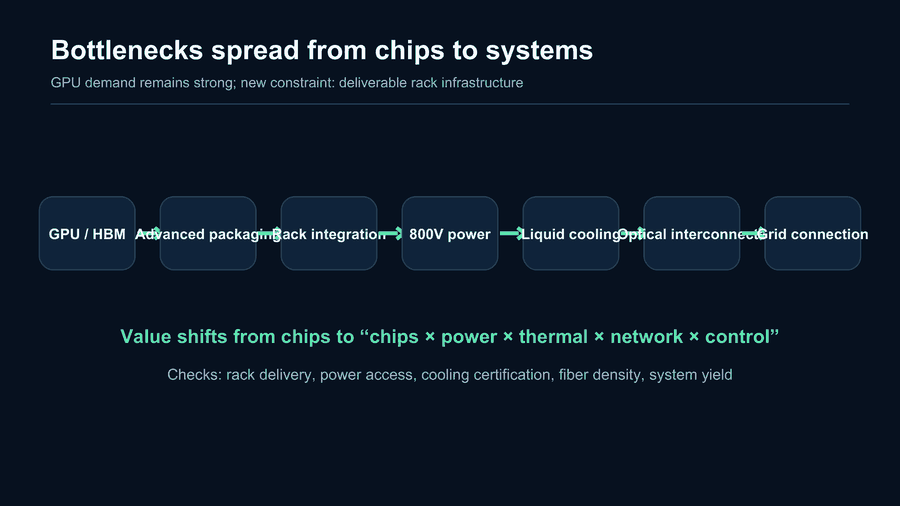
The focus of the AI trade is shifting from individual GPUs to the entire “AI factory.” As rack power rises from tens of kW to hundreds of kW and 1 MW, power delivery, liquid cooling, fiber density, packaging, and testing are no longer ancillary systems—they are hard constraints on timely delivery.
Demand remains well supported. The combined remaining performance obligations and backlogs of Microsoft, Amazon, Google, and Oracle’s cloud businesses have reached USD 2.3 trillion, while memory vendors expect supply-demand conditions to be tighter in 2027 than in 2026. The risks are also clearer: off-balance-sheet commitments, debt financing, access to power, and actual investment returns must each be delivered.
Consumer-facing trends are more mixed. Apple and Foxconn are accelerating preparations for AI-server and device manufacturing, while Tesla’s energy-storage projects are moving forward. However, U.S. retail sales, non-store retail sales, and motor-vehicle dealer sales all declined in July, indicating that end demand has yet to strengthen in step with AI-infrastructure investment.
Full AI/Semiconductor Supply Chain
GPUs/CPUs and Rack Systems
NVIDIA
1) The competitive perimeter is expanding from GPUs to complete servers, CPUs, DPUs, networking, and cooling. Through its DSX-certified partners, NVIDIA is seeking to define the standards for the entire AI factory.
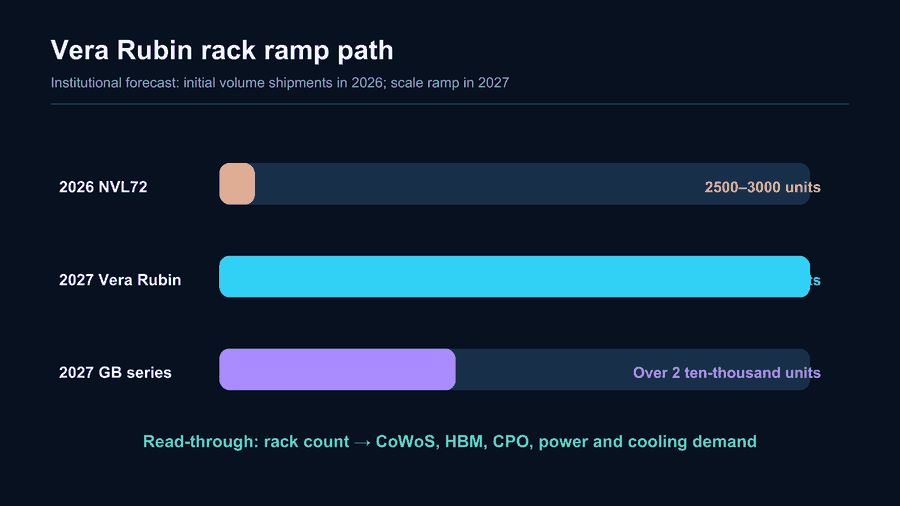
2) Mizuho expects mass shipments of VR200 NVL72 to begin in Q4 2026, with rack volumes exceeding 50,000 in 2027. If the rack ramp falls short of expectations, demand for packaging, optical interconnects, and HBM will be pushed out in tandem.
“The AI investment thesis of the past 3 years—centered on GPUs, HBM, advanced-node wafers, and advanced packaging—remains intact. As deployment scales, however, bottlenecks are spreading into power distribution, liquid cooling, fiber density, systems management, packaging, and validation testing.”
Arm: CEO Rene Haas said that although vendors are taking different approaches to building AI infrastructure, all are evolving in the same direction, with Arm-based CPUs becoming central to next-generation systems. The investment implication lies in CPU share and rack-level integration, rather than accelerator counts alone. Mass production, yields, customer qualification, and delivery cadence remain the key validation points.
Hon Hai Precision
1) AI servers accounted for 51% of Q2 revenue, ahead of smart consumer electronics at 29%; net profit rose 35% year over year to NT$59.97 billion.
2) The company aims to begin mass production of NVIDIA Vera Rubin server racks in Q4 2026 and increase equipment investment at its U.S., Mexican, and Indian manufacturing sites by 30%. The next test is whether CoWoS supply can keep pace with assembly expansion.
MiTAC: The unit of AI deployment has shifted from the server to the rack. Traditional ODMs integrate CPUs, DRAM, storage, network interface cards, and power supplies; AI racks must additionally integrate GPUs, HBM, power shelves, busbars, backup batteries, coolant distribution units, firmware, and management systems. MiTAC’s value capture will depend on how much of the rack-level bill of materials and systems integration it can control.
“The first architectural change is that the server is no longer the relevant unit of deployment—the rack is. Deployment is evolving further along the server–rack–cluster–AI factory continuum.”
HBM/DRAM/NAND/SSD
Micron
1) Management said customer-demand signals have strengthened further since the earnings release and expects supply-demand conditions to be tighter in 2027 than in 2026. It remains unclear when supply will catch up with demand.
2) Long-term supply agreements are beginning to influence allocation. Each HBM stack consumes roughly 3 to 4 times the wafer area of conventional DRAM, while new capacity takes several years to come online, leaving supply elasticity low.
“Some customers historically treated memory procurement very tactically. In today’s tight supply environment, those customers are now finding it considerably harder to secure allocations.”
Samsung Electronics
1) Combined chip-facility investment by Samsung Electronics and SK hynix increased 35% year over year to KRW43.2 trillion in the first half of 2026.
2) Semiconductor revenue was KRW209.2 trillion, representing 68.5% of total company revenue and contributing 97.4% of operating profit; DRAM share rose from 34.0% in 2025 to 39.4%.
3) The company has sold HBM4 for the Vera Rubin platform; the next question is whether it can further diversify its customer base.
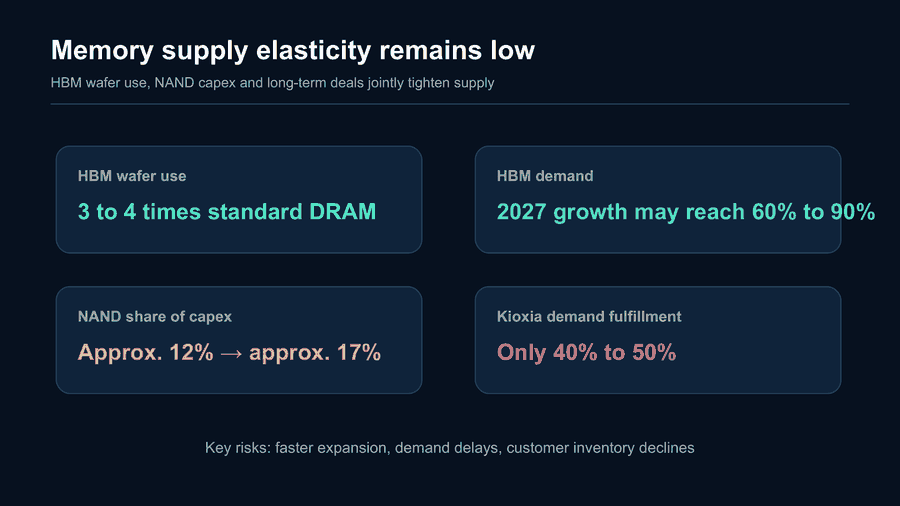
SK hynix: Facility investment and the M15X ramp support HBM capacity expansion, but NVIDIA’s share of revenue has declined to 13.35%, indicating a shift in customer concentration. Industry estimates suggest HBM demand could grow 60% to 90% by 2027, with shortages potentially lasting until close to 2030. Wafer starts, yields, and execution on long-term agreements remain the key variables.
SanDisk: UBS estimates that NAND currently represents approximately 12% of hyperscaler capital expenditure and could rise to approximately 17% by 2027. At its investor day, the company outlined HBF, NBM, shareholder returns, and an 80% gross-margin forecast. Whether the valuation uplift extends across the industry will depend on actual cloud NAND procurement and long-term contract execution. Key indicators are pricing, utilization, order durability, and cash returns.
Kioxia: Supply-chain sources said the company disclosed at the Flash Memory Summit that it can currently meet only 40% to 50% of demand, with the balance deferred into the following year. This aligns with Phison’s assessment that capacity constraints will be more severe in 2027. Near-term pricing strength still needs to be cross-checked against incremental wafer supply and deferred customer orders. The key risk is capacity expansion lagging demand and customer qualification.
“Analysts believe 2,500 to 3,000 NVL72 racks could be deployed in 2026. By 2027, Vera Rubin racks are expected to scale beyond 50,000 units, alongside more than 20,000 GB-series systems.”
Foundry, Packaging, and Testing
TSMC
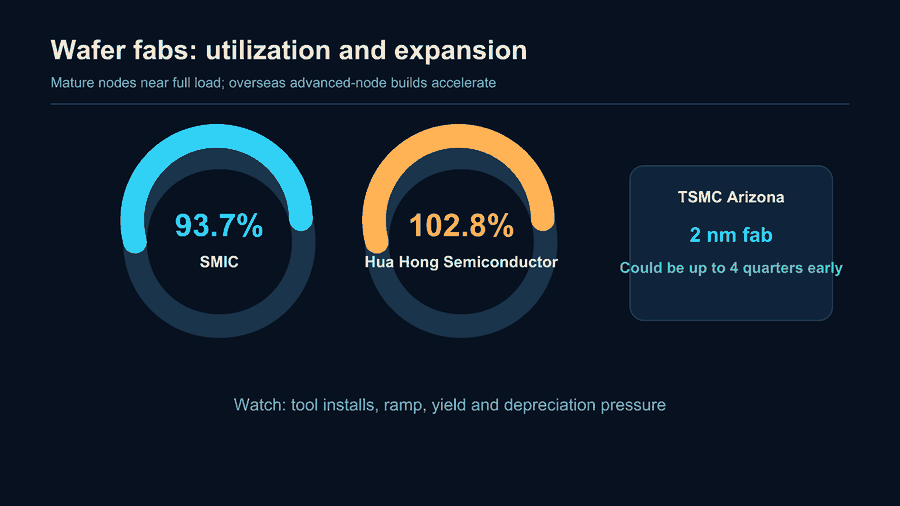
1) TSMC is reportedly accelerating construction of its third Arizona fab, with the 2 nm facility potentially completed as much as 4 quarters ahead of expectations. Equipment installation at the second fab is scheduled for the second half of 2026, with mass production beginning in the second half of 2027.
2) Profit at the local operations rose 663% year over year in the first half of 2026, but Q2 profit declined 8.2% sequentially as depreciation pressure entered the validation phase.
SMIC: Q2 capacity utilization rose to 93.7%, leaving less available headroom. High utilization supports pricing and margins, but it also means incremental AI and mature-node demand will depend more heavily on capacity-expansion progress. If equipment installation or yield ramp-up lags demand, lead times could lengthen further. The next indicators are product ramp-up, supply constraints, and the efficiency of profit conversion.
Hua Hong Semiconductor: Q2 capacity utilization reached 102.8%, above SMIC’s 93.7%. Full loading indicates strong mature-node demand, but utilization above 100% does not represent sustainable capacity. Investors should therefore focus on new-line capacity releases, product mix, and whether customer restocking continues. Mass production, yields, customer qualification, and delivery cadence remain the key validation points.
Lam Research: South Korean imports of dry and plasma-etch equipment have risen to more than USD 300 million, while wet-etch imports remain within the USD 20 million to USD 40 million range. SK hynix’s M15X, Samsung Electronics’ P4, and HBM capacity expansions are advancing in parallel. Because HBM through-silicon vias require one additional dry-etch step versus conventional DRAM, equipment intensity per wafer is increasing.
Chroma ATE: When system power reaches 100 kW, the test platform must also source or absorb 100 kW; at 1 MW, validation itself becomes an infrastructure project. Regenerative testing reduces the waste from converting all electrical energy into heat, shifting order value from unit counts toward power ratings, reliability, and energy-recovery capability. Key indicators are pricing, utilization, order durability, and cash returns.
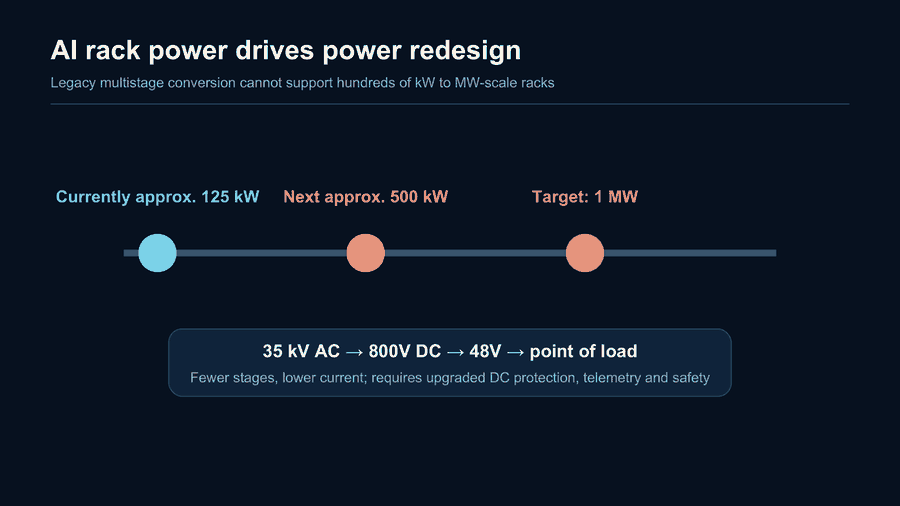
“A 100 kW system requires the test platform to source or absorb the same 100 kW. At 1 MW, testing becomes an infrastructure-level challenge, increasing the importance of regenerative testing.”
Nordson: High-density packaging is shifting bond testing from mechanical inspection toward process control. BT4800 INTEGRA Plus combines intelligent analytics with fault-mode grading and classification. When bump or copper-pillar diameters fall below 12 µm with approximately 25 µm pitch, three-axis accuracy, low-force measurement, and dynamic sampling determine whether the data is usable. The key risk is capacity expansion lagging demand and customer qualification.
“Advanced devices contain thousands or even millions of bumps on a single wafer, with interconnect dimensions of only a few µm. Minor variations in materials, deposition, and process conditions can therefore create differences in bonding.”
ASE Technology Holding: The increasing heterogeneity of AI accelerators means packaging is gradually taking on motherboard-like functions, with 2.5D, hybrid bonding, fan-out, silicon bridges, and panel-level packaging likely to coexist over the long term. Opportunities arise from multiplier demand for equipment, materials, substrates, inspection, and thermal-interface materials. The risk is that panel-level solutions will not simply replace CoWoS; yields and customer qualification will continue to determine the pace of volume ramp-up.
Optical Communications, Power, and Thermal Management
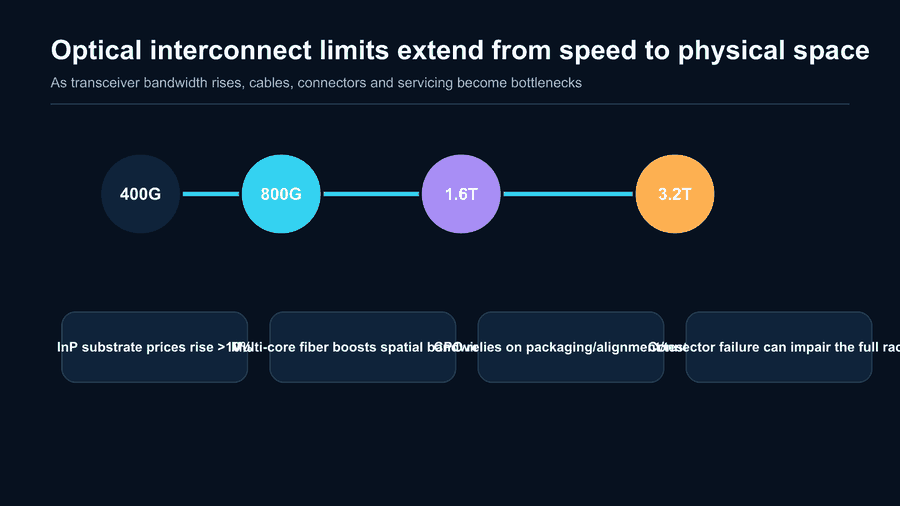
AXT: Supply-chain sources indicate that indium phosphide substrates have undergone 3 consecutive price increases since Q4 last year, with a fourth increase of more than 10% possible in Q4 2026. Epitaxial wafers may also see a third consecutive increase. Demand is being driven by high-speed optical communications, but if material shortages constrain downstream shipments, price increases may not translate fully into profit. The next indicators are product ramp-up, supply constraints, and the efficiency of profit conversion.
Corning: As network speeds progress from 400G, 800G, and 1.6T to 3.2T, constraints are expanding beyond individual transceivers to cable trays, connectors, weight, bend radius, and rack volume. Multicore fiber increases bandwidth per unit of physical space; the next question is whether connector standards, installation complexity, and maintenance costs can decline in parallel. Mass production, yields, customer qualification, and delivery cadence remain the key validation points.