
目录
Executive Summary
Overall View This Week
How the Thesis Evolved This Week
Weekly Performance of Memory-Related Securities
DRAM/HBM: Supply Control, Long-Term Agreements, and Customer Qualification
LPDDR/SoCAMM: Spillover Demand from AI CPUs and Rack-Scale Memory
NAND/eSSD/SSD: Inference, RAG, and Enterprise SSD Upside
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
Equipment, Testing, and Materials: Second-Order Beneficiaries of Storage Capex
Downstream Costs and Demand Destruction: Servers, Networking Equipment, Smartphones, PCs, and EVs
Investment Ranking, Risks, and Falsification Criteria
What to Watch Next Week
This week, the memory and storage narrative shifted from price increases to volume commitments, but the segments are moving at different speeds. DRAM/HBM offers the strongest visibility, while NAND/eSSD has the greatest upside sensitivity. Whether earnings can genuinely withstand the cycle will depend on SoCAMM configuration cuts, lower consumer-device specifications, and the renegotiation of long-term agreements.
Executive Summary
Samsung Electronics, Micron, SanDisk, and other suppliers are combining multiyear contracts with price floors, prepayments, and take-or-pay provisions. Suppliers are securing not merely orders, but also minimum volumes, cash flow, and earnings for several years. SK hynix’s terms require further disclosure, while earlier HBM3E contracts may suppress current pricing. Long-term agreements therefore improve visibility but do not guarantee permanently higher margins.
AI inference is pushing demand beyond HBM. AI server research published on August 3 indicated that agentic workloads are increasing demand for HBM, conventional DRAM, and NAND simultaneously. Expansion across TPU, Trainium, and GPU racks is also broadening the HBM customer base from individual GPU supply chains to custom silicon. HBF, CXL, GPU-direct storage, and enterprise SSDs are consequently emerging as a new tier between HBM and conventional storage, although commercialization still depends on customer qualification and the pace of volume production.
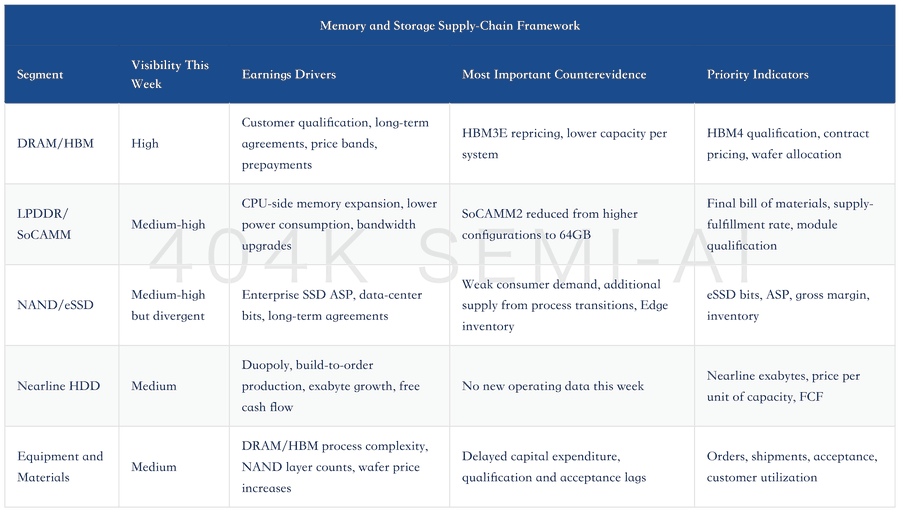
NVIDIA’s reductions in SoCAMM2 and selected HBM capacities are this week’s most important counterevidence. The cautious interpretation is that memory content per system is falling; another set of materials suggests suppliers can meet only 60%–70% of the original configuration’s requirements. These explanations imply entirely different earnings outcomes. Next week, investors should focus on final bills of materials, customer allocations, and qualification status—not a single specification number.
NAND has split into two distinct businesses. Enterprise SSDs are benefiting from AI inference, retrieval-augmented generation (RAG), and KV cache spillover, with both the export product mix and multiyear contracts improving. Consumer NAND remains constrained by smartphone and PC demand and additional bit supply from process-node transitions. SanDisk’s more moderate outlook, Edge inventory, and lower-margin long-term agreements show that high prices do not automatically translate into high-quality growth.
Second-order beneficiaries are expanding to equipment, wafers, and memory-module PCBs. ASML has greater immersion-lithography intensity in DRAM than in logic production lines. Lam Research’s incremental opportunities come from TSV etching, the transition from HBM3 to HBM4, ALD share gains, and NAND capital expenditure. Equipment orders, however, still depend on customer capital expenditure, qualification, tool installation, and acceptance, so revenue recognition materially lags memory and storage pricing.
Market performance has already begun to price in these divergences. Over the past 1 week, Micron rose 7.10%, SK hynix fell 9.25%, and Western Digital declined 17.13%, while most memory and storage thematic ETFs advanced. The current ranking should separate visibility, upside sensitivity, and cash flow: prioritize DRAM/HBM volume commitments, then NAND/eSSD pricing leverage, while awaiting renewed confirmation of nearline exabyte growth, build-to-order discipline, and free cash flow in HDDs.
Overall View This Week
Memory and storage suppliers’ pricing power is extending from spot prices into contract structures. Previous upcycles primarily relied on rising prices to lift earnings, which reversed quickly when prices fell. This cycle adds five-year contracts, price bands, purchase-volume commitments, deposits, and prepayments. To secure supply, customers are beginning to assume part of the demand and pricing risk, raising the earnings floor.
Volume commitments do not yet mean that “the cycle has disappeared.” Weaker HBM3E pricing after renegotiations shows that long-term agreements may still be adjusted as product generations, customer specifications, and competitive conditions change. Some of SanDisk’s long-term contracts also carry lower gross margins than transactional business, showing that broader coverage can sacrifice some upside. The genuine rerating case is lower cash-flow volatility—not treating every LTA as a fixed, high-price contract.
Long-term agreements should be assessed through three questions. First, are purchase volumes non-cancellable? Second, is the price floor sufficient to cover returns on reinvestment? Third, can deposits genuinely compensate suppliers if customers default? Only when all three conditions are met does a contract become an earnings floor rather than an expression of purchasing intent. If an agreement provides coverage but lacks deposits and take-or-pay provisions, customers can still renegotiate when demand weakens.
This also explains why long-term agreements from the same cycle may produce different valuations. Micron has disclosed the number of agreements, coverage ratios, minimum contract revenue, and deposits, allowing investors to translate orders into a cash-flow range. SK hynix emphasizes customer-specific arrangements but provides no standardized coverage or pricing information, leaving the market concerned that earlier contracts may have locked in low prices. Samsung Electronics has higher rolling-contract coverage, but investors still need to verify prepayment receipts, price floors, and actual shipments.
AI demand is spreading along three paths. First, training and high-end inference continue to increase HBM requirements. Second, agentic workloads are pushing KV cache and orchestration needs toward CPU-side DRAM, SoCAMM2, and CXL. Third, long-context applications, RAG, and cold/warm data tiering are shifting some demand toward enterprise SSDs, HBF, and GPU-direct storage. The boundary between memory and storage devices is narrowing, but speed, capacity, and cost continue to define their respective roles.
This week’s structural evidence and market performance were not fully aligned. Server research continued to raise memory- and storage-related earnings expectations, even as Asian leaders corrected sharply; Micron gained, while Western Digital sold off. The market is no longer debating whether AI demand exists. It is pricing whether memory content per system will be reduced, whether contract margins are sufficiently high, whether consumers can absorb price increases, and whether capital expenditure will ultimately trigger a subsequent supply backlash.
How the Thesis Evolved This Week
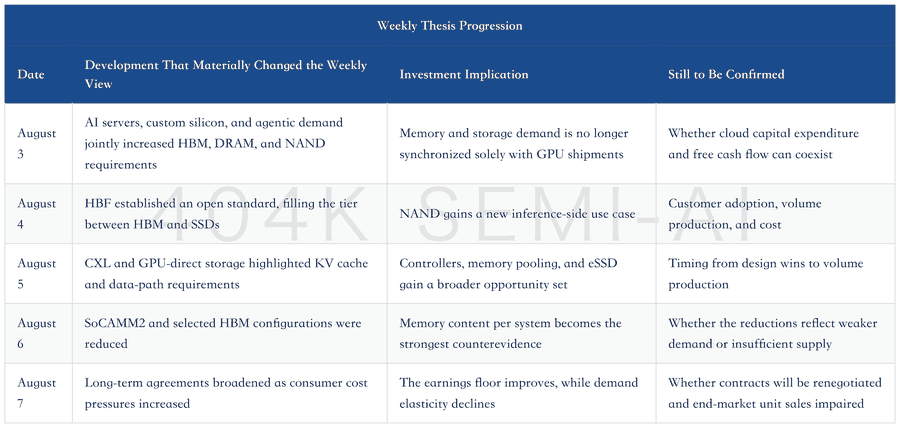
August 3 first confirmed that the underlying demand base was still being revised upward.
AI server research raised combined 2027 capital expenditure estimates for major hyperscalers, neoclouds, and Oracle to approximately US$1.11 trillion, while forecasting that the global server market will exceed US$1 trillion in 2028.
More importantly, the research explicitly indicated that conventional DRAM and NAND, beyond HBM, are also becoming meaningful cost burdens in AI systems. Memory and storage demand has expanded from training chips into inference and agentic workloads.
On August 4, the “middle tier” progressed from concept to standardization. SK hynix and SanDisk announced the first open standard for high-bandwidth flash (HBF), offering capacities of up to 512GB, bandwidth ranging from 0.4TB/s to 3.0TB/s, and UCIe connectivity to processors. HBF is not intended to replace HBM; it aims to accommodate data that cannot fit in HBM but requires more speed than conventional SSDs can provide.
On August 5, industry attention shifted from capacity to data paths. A cluster of developments involving CXL, GPU-direct storage, context storage, and PCIe Gen 6 controllers showed that enterprise customers are beginning to treat KV cache, compression, encryption, and data swapping as system-level issues. The beneficiary set has therefore expanded from memory and storage chips to controllers, DPUs, networking, and software.
On August 6, the week’s most valuable counterevidence emerged: NVIDIA reduced SoCAMM2 and HBM configurations on selected platforms. Lower memory content per system would reduce demand estimates, but another set of information indicated that suppliers could meet only 60%–70% of the original high-end configuration’s requirements. Determining whether the downgrade reflects weaker demand or insufficient supply requires confirmation from final bills of materials and supplier allocations.
On August 7, the central theme returned to contract quality and cost pass-through. Coverage ratios, price floors, and deposits continued to expand across long-term agreements. Meanwhile, smartphones, PCs, and some edge devices began absorbing higher costs through price increases, specification reductions, or deferred procurement. Memory and storage suppliers retain supply-side control, but demand destruction has reached a stage that requires monitoring.
Weekly Performance of Memory-Related Securities
Market performance shows how investors are pricing the sector, but it is no substitute for fundamentals. Broad gains in thematic ETFs alongside divergent performance among industry leaders suggest that investors still endorse the memory thesis, while increasingly differentiating among contract quality, product mix, and near-term guidance.
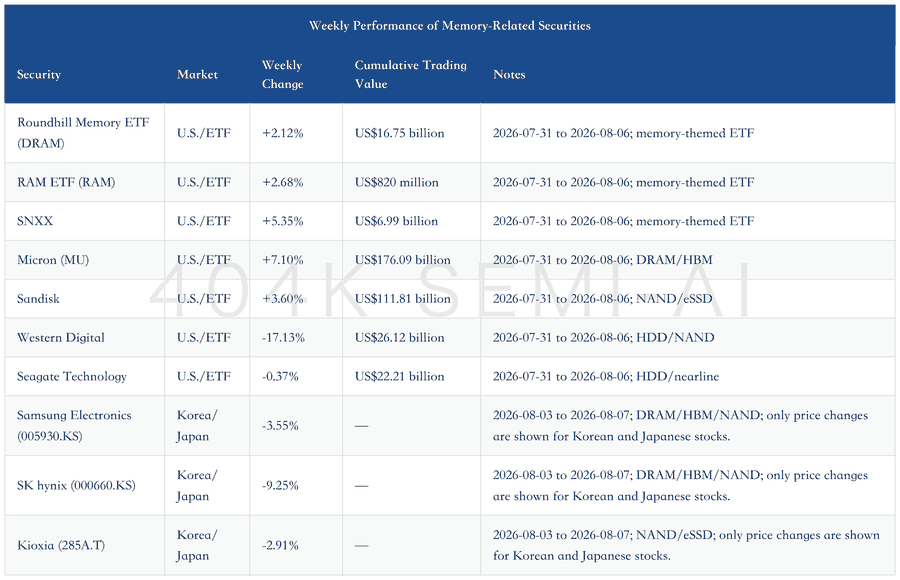
Micron’s outperformance and SK hynix’s sharp pullback should not be interpreted simply as a divergence in HBM fundamentals. SK hynix faces concerns over pricing in earlier long-term agreements, HBM3E bargaining power, and capital allocation. Micron, by contrast, provided more specific contract disclosures, making cash-flow visibility easier for the market to price. The competitive picture still needs to be validated through actual contract pricing and HBM4 market share; one week of share-price performance is not a substitute for competitive analysis.
