目录
Overall View This Week
Front-End Wafer-Fabrication Equipment
Metrology, Inspection and Test
Advanced Packaging Equipment and Critical Materials
Company, Order, and Capex Validation
Debates, Disconfirming Evidence, and Next Week’s Watchlist
Support for the equipment cycle is broadening from advanced logic and front-end memory into packaging, metrology, and testing. Order visibility is improving, but hybrid-bonding costs, packaging and testing capacity execution, and customer capital expenditure remain the key validation points for next week.
Overall View This Week
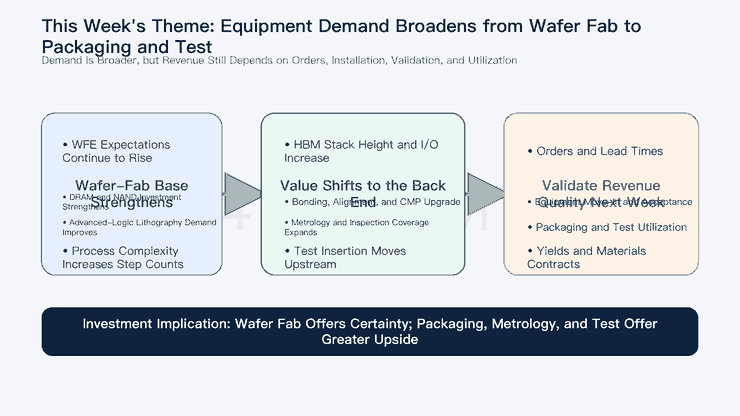
Semiconductor-equipment demand forecasts continue to rise. The broadening scope of spending is this week’s most important development, outweighing improvements in any single equipment category. Wafer-fabrication equipment (WFE) expectations continue to move higher, supported simultaneously by DRAM, NAND, and advanced logic. In the back end, HBM stacking, advanced packaging, and high-value chiplet systems are increasing investment intensity across bonding, alignment, metrology, inspection, and testing. Equipment vendors now have two growth drivers: more wafers and more process steps per wafer and per package.
Three sets of evidence now support this thesis. First, baseline WFE forecasts for 2026–2028 have risen across all 3 years, with the largest increase in 2027. Second, revenue or shipment plans are improving simultaneously across lithography, deposition, and memory equipment, indicating that demand is not confined to a single process. Third, OSAT capital expenditure, HBM stacking complexity, and the migration of testing upstream are all increasing, showing that equipment value is extending from front-end fabrication into packaging and yield protection.
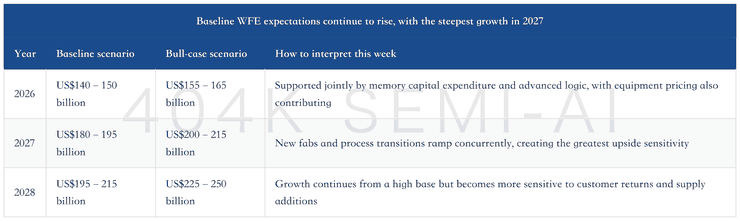
Higher forecasts do not mean that all orders have already materialized. Some market expectations are approaching or even exceeding the bull-case scenario, reducing valuation tolerance for positive surprises. Investors must distinguish among the 5 stages of customer capital-expenditure announcements, equipment orders, installation and acceptance, production ramp, and revenue recognition. Focusing only on capex announcements can overstate near-term revenue, while focusing only on quarterly revenue can understate the medium-term visibility of long-lead-time equipment.
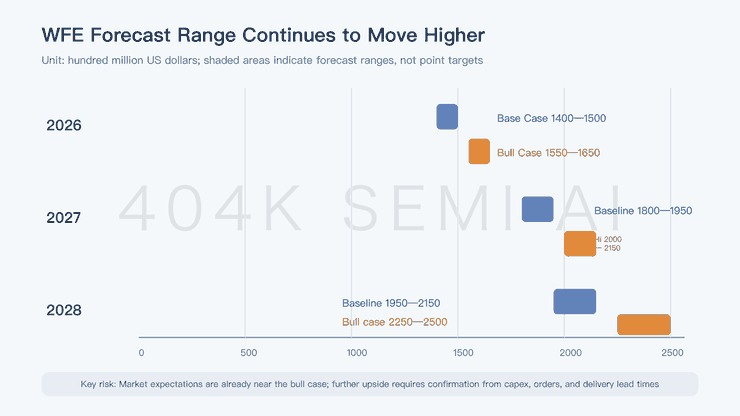
By earnings driver, 2026 equipment revenue reflects customer capacity additions, supply availability, and equipment price increases. Growth in 2027 depends more heavily on new fabs, memory-process transitions, and the concentrated ramp of advanced-logic capacity. The quality of growth therefore differs between the 2 years. If vendors raise prices without a corresponding increase in system shipments, revenue will still improve, but the resulting service and consumables stream will be less durable than one supported by genuine installed-base expansion.
Investors should focus on 2 types of companies. The first possesses scarce process capabilities that customers cannot readily bypass when expanding capacity, including advanced lithography, critical deposition and etch, and process control. The second operates in segments where equipment value is accelerating, including hybrid bonding, precision alignment, metrology and inspection, probes, and automated testing. The former offers order certainty; the latter provides upside from higher equipment value and testing intensity. The primary risk is the pace of adoption: before a technology roadmap is finalized, equipment qualification may lead revenue by several quarters.
Front-End Wafer-Fabrication Equipment
Front-end demand combines early strength in memory, catch-up growth in logic, and easing lithography supply. In the June quarter, Lam Research’s DRAM systems revenue doubled year over year, while Tokyo Electron’s DRAM sales increased 66% year over year. As NAND manufacturers transition to higher layer counts, WFE demand associated with new NAND fab space is projected to increase to 3x its prior level during 2026–2028. Higher foundry capital expenditure is also extending incremental demand from memory into advanced logic.
The implications for equipment vendors are straightforward. Lam Research and Tokyo Electron both benefit from the increasing number of memory-process steps; Applied Materials benefits from deposition, materials engineering, and advanced-packaging processes; and ASML is seeing simultaneous improvement in lithography demand from advanced logic and DRAM. Process-transition-driven equipment demand is generally more durable than demand from capacity expansion alone because changes in layer counts, materials, and structures increase the number of repeated process steps.
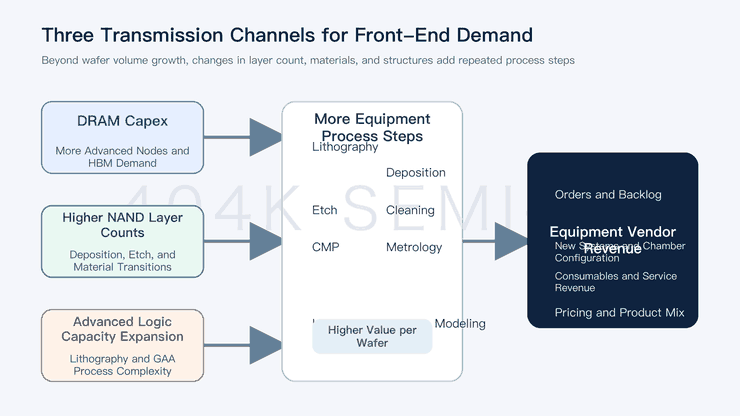
Front-end equipment exposure cannot be ranked solely by customers’ aggregate capital expenditure. For the same investment amount, high-layer-count NAND, advanced DRAM, and gate-all-around (GAA) logic require substantially more deposition, etch, cleaning, and metrology steps than straightforward mature-node capacity expansion. Investors should continue examining vendors’ system revenue by application and the respective contributions from new tools, chamber upgrades, and services to determine whether growth is being driven by unit volume, process intensity, or pricing.
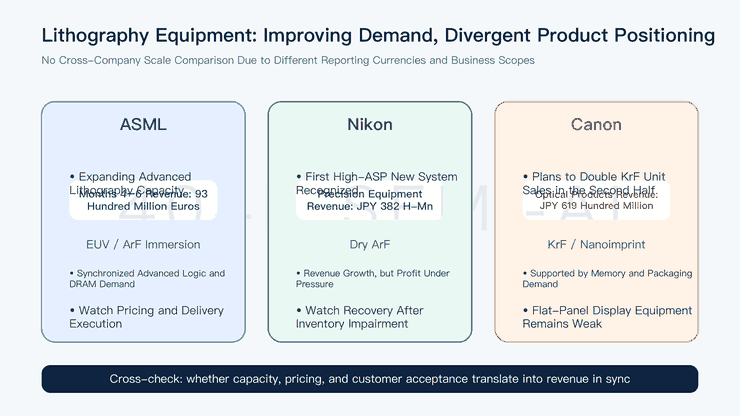
Lithography demand is broadening, but the 3 companies occupy different product and profit positions
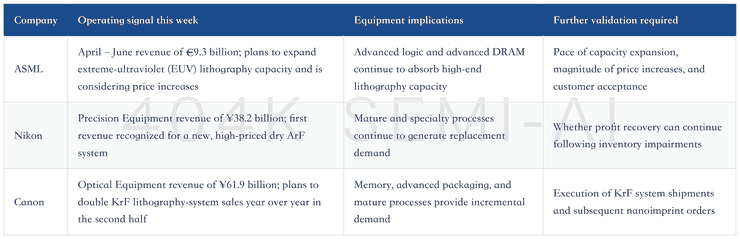
The table uses different currencies, so revenue scale is not directly comparable as a measure of competitiveness. ASML’s core advantages are scarcity and pricing power in advanced lithography, while Nikon and Canon have greater exposure to ArF, KrF, and specialty-process demand. An improving lithography cycle does not imply synchronized recovery across every product line: Canon’s flat-panel-display lithography business remains notably weak, indicating that semiconductor processes—not a broad recovery in optical equipment—are driving the upturn.
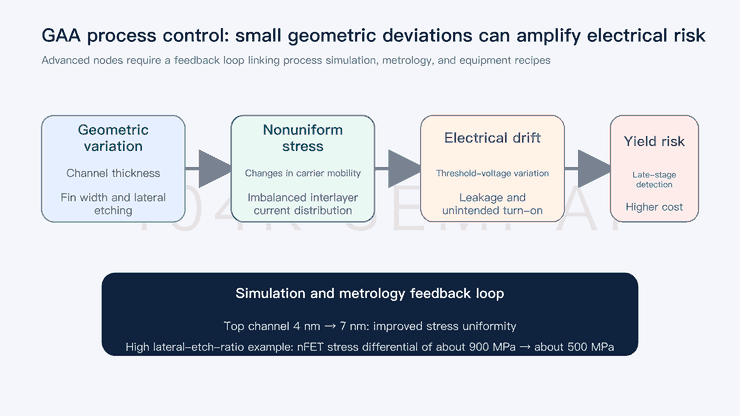
The challenge in advanced logic is shifting from whether a structure can be fabricated to whether it can be controlled consistently. In gate-all-around (GAA) nanosheets, geometric differences among stacked channels alter mechanical stress, affecting mobility, threshold voltage, and leakage. Process simulations show that increasing top-channel thickness from 4 nm to 7 nm can significantly narrow the stress differential between layers; under high lateral-etch-ratio conditions, the nFET stress differential can decline from approximately 900 MPa to approximately 500 MPa.
These challenges increase the value of computational process modeling, 3D metrology, and process control. As advanced nodes become more complex, customers can no longer wait until final electrical testing to identify systemic deviations. Equipment demand is therefore expanding beyond the core etch and deposition tools into process modeling, film-thickness and morphology metrology, defect inspection, and feedback control. Tool throughput remains important, but the ability to shorten customers’ process-learning cycles increasingly influences purchasing decisions.