
目录
Executive Summary
Weekly View
Front-End Wafer Fabrication Equipment
Metrology, Inspection, and Test
Advanced-Packaging Equipment and Critical Materials
Company, Order and Capex Validation
Debates, Disconfirming Evidence and Next Week’s Watchlist
This week, equipment momentum continued to spread upstream into manufacturing capacity and downstream into assembly and testing. Orders, imports, and capacity expansions corroborate one another, but qualification and volume production remain hard prerequisites for revenue conversion. Next week, the key question is whether customer orders keep pace with equipment vendors’ capacity expansion.
Executive Summary
Semiconductor equipment demand has broadened beyond fab expansions to equipment vendors’ own capacity planning and supply-chain procurement. Lead times for some deposition, etch, and test tools have stretched to 24 months. Applied Materials plans to have the capacity by 2028 to double quarterly systems output from current levels, while Lam Research’s FY2026 purchase obligations grew 43%, outpacing its 26% revenue growth. Demand is strong, but as suppliers expand capacity, the durability of lead times will determine how long pricing and margins can hold.
Dry etch was the clearest incremental driver in front-end equipment this week. South Korean imports of dry and plasma etch equipment rose above $300 million, while wet etch remained at $20 million–$40 million. The additional through-silicon-via steps required for HBM are increasing deep-etch and copper-fill intensity per wafer. Lam Research has clear exposure to this trend, with memory expansion timing and equipment delivery capacity as the main risks.
China’s equipment imports are recovering, with back-end demand stronger than front-end demand. Semiconductor equipment imports increased 9% YoY in July, including 7% growth in lithography equipment, 15% in chemical vapor deposition equipment, 35% in back-end equipment, and 61% in wire bonders. These figures indicate that demand is spreading from logic front-end manufacturing into packaging and testing, but one month of import growth cannot be directly equated with orders for domestic equipment or full-year capital expenditure.
Metrology and testing are moving from R&D; validation into production control. Keysight Technologies’ orders reached $2.09 billion, up 56% YoY, while revenue in its Electronic Industrial Solutions Group increased 21% YoY. Silicon photonics has entered commercial production at multiple foundries and integrated device manufacturers (IDMs). Feed-forward control simulations also show that wafer-by-wafer critical-dimension metrology combined with three etch recipes can raise yield from 60.82% to 96.77%, although throughput and cost have yet to be validated on a real production line.
The advanced-packaging opportunity has progressed from capacity shortages to equipment qualification. TSMC’s CoWoS monthly capacity is approximately 90,000–120,000 wafers, while ASE Technology Holding increased equipment investment to $10.5 billion, up 98% YoY. Some inspection tools have passed trial validation, and HBM inspection-equipment orders in the KRW 10 billion range have emerged. The critical milestones are formal procurement, acceptance, and revenue recognition; outsourcing intentions should not be treated as equipment-company earnings.
Weekly View
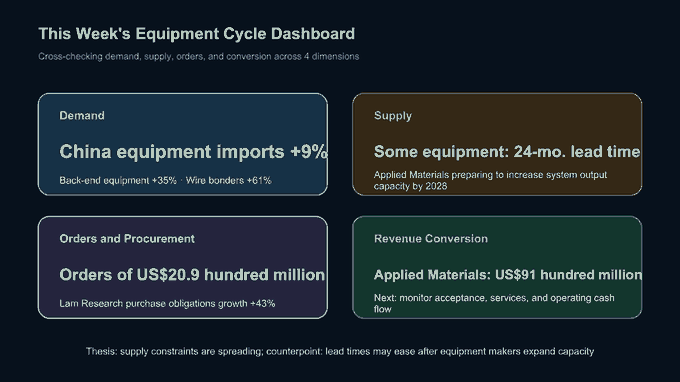
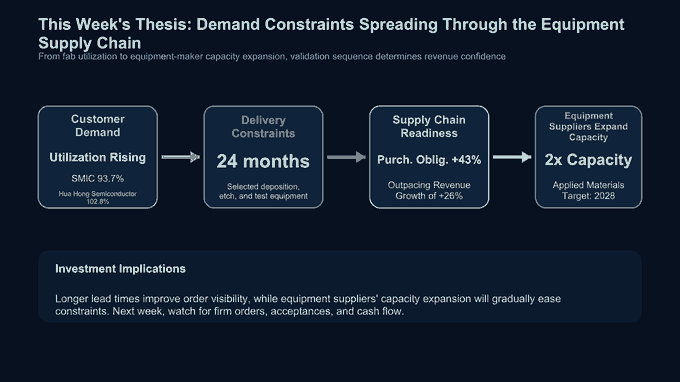
The week’s most important development was the propagation of equipment tightness along the chain from rising fab utilization to longer equipment lead times, vendor capacity expansion, and follow-on demand for components and materials. SMIC and Hua Hong Semiconductor reported Q2 utilization rates of 93.7% and 102.8%, respectively. Meanwhile, lead times for some deposition, etch, and test equipment in Europe, the United States, Japan, and South Korea stretched to 24 months. The former explains why customers are ordering; the latter explains why equipment vendors are securing labor and supply chains in advance.
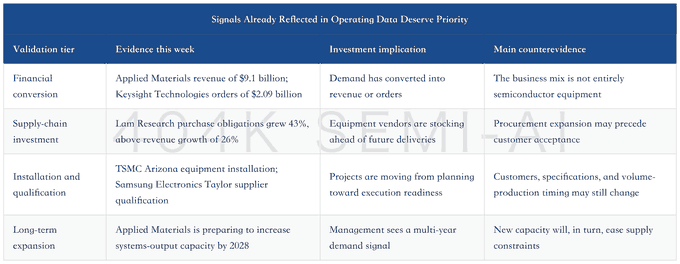
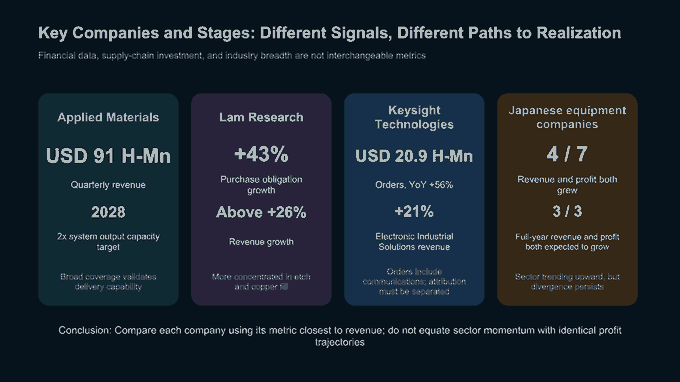
This chain now has two points of operational validation. Applied Materials reported quarterly revenue of $9.1 billion, up 15% QoQ and 25% YoY, and said it is recruiting and training manufacturing and customer-support personnel, targeting the capacity by 2028 to double quarterly systems output from current levels.
Lam Research’s FY2026 purchase obligations grew 43%, above its 26% revenue growth. Equipment companies are responding to long-term demand with actual procurement and manufacturing investment, moving beyond verbal guidance.
The same level of capital expenditure does not translate equally into equipment revenue. Greenfield fabs require full toolsets, while output increases at existing lines favor bottleneck tools and services. HBM and advanced packaging add deep-etch, electroplating, metrology, and inspection steps. Even if customers maintain total capital expenditure, they may reallocate budgets from buildings and general-purpose tools toward process bottlenecks. Assessing company upside therefore requires identifying exposure to incremental process steps, not merely tracking customers’ aggregate capital expenditure.
This also explains the divergence among companies this week. Lam Research has more concentrated exposure to dry etch and copper fill, Applied Materials covers a broader range of processes, and Keysight Technologies benefits primarily from higher test density as complexity increases. When industry volumes rise, process intensity often grows faster than wafer capacity; when industry growth slows, genuinely hard-to-replace steps are better positioned to retain orders.
Investors should distinguish between supply-demand tightness and secured revenue. Long equipment lead times indicate that customers must order earlier and may improve vendors’ pricing leverage, but vendor capacity expansion will gradually ease the same constraint. If capacity expands faster than actual customer installations, current lead-time and prepayment advantages will recede. Next week’s most valuable incremental signals will be formal orders, non-cancelable purchase obligations, equipment acceptance, and service personnel arriving on-site; long-dated capacity targets deserve less weight.
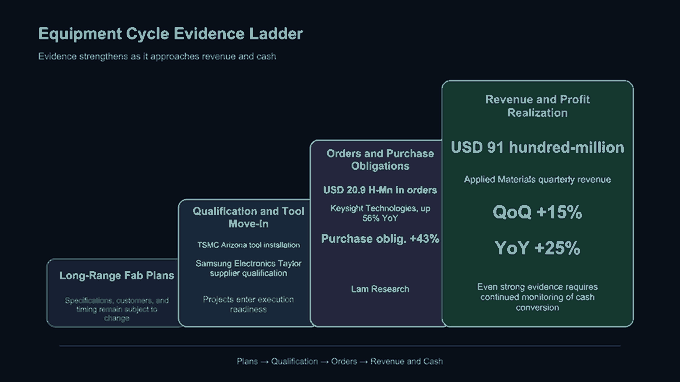
This week’s evidence falls into three tiers. Orders and revenue already reflected in financial statements are the strongest; equipment qualification, installation, and trial validation rank in the middle; media reports of long-range fab plans are the weakest. TSMC plans to install equipment at its second Arizona fab in 2H2026 and begin volume production in 2H2027, while Samsung Electronics has asked suppliers for its second Taylor fab to obtain qualification in advance. Both support front-loaded demand, but confirmation still depends on equipment move-in, customer volume production, and payment milestones.
Corroboration of the equipment upcycle is not limited to U.S. companies. Among eight major Japanese equipment companies, seven disclosed YoY changes in quarterly revenue and operating profit, and four reported growth in both. Three provided full-year guidance, all forecasting growth in both revenue and profit. This indicates that the upturn is not simply a market-share shift at one company, but the fact that only four achieved dual growth also shows that the industry is not moving in lockstep; product exposure and customer mix still determine the earnings trajectory.
Front-End Wafer Fabrication Equipment
The clearest structural shift in front-end demand is in dry etching. South Korea’s imports of dry and plasma etching equipment have risen above $300 million, while wet etching equipment imports remain within the $20 million–$40 million range. The divergence suggests that the current increase reflects additional process steps rather than a broad-based rise across all fab equipment.
HBM explains this divergence. Beyond conventional DRAM fabrication, through-silicon vias require deep, narrow holes to be etched into silicon, followed by dielectric deposition, seed-layer deposition, and copper filling. As stack height increases, so do requirements for via depth, verticality, and within-wafer uniformity. Lam Research’s deep reactive-ion etching and copper electroplating systems address the “via formation” and “via filling” steps, respectively. The company therefore benefits not only from higher memory wafer starts but also from greater process intensity per wafer.
