
目录
Executive Summary
Overall Weekly View
How the Thesis Evolved This Week
Weekly Performance of Storage-Related Names
DRAM/HBM: Supply Leverage, Long-Term Agreements, and Customer Qualification
LPDDR/SoCAMM: Spillover into AI CPUs and Rack-Level Memory
NAND/eSSD/SSD: Upside from Inference, RAG, and Enterprise SSDs
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
Equipment, Testing, and Materials: Second-Order Beneficiaries of Memory Capex
Downstream Costs and Demand Destruction: Servers, Networking Equipment, Smartphones, PCs, and EVs
Investment Ranking, Risks, and Disconfirming Evidence
What to Watch Next Week
This week’s shortages spread from HBM to server DDR, SoCAMM, and enterprise SSDs. High-end DRAM and long-term contracts offer the greatest visibility, while NAND/eSSD provides more upside torque. The key risk is that elevated prices suppress PC and smartphone demand.
Executive Summary
DRAM/HBM suppliers continue to gain pricing and allocation power, but spot prices have diverged from actual transaction volumes. DDR4 and DDR5 spot prices rose another 2% early in the week, extending their advance to an 18th consecutive week. Micron also said it can currently fulfill less than 50% of data-center customer demand and that the forward supply-demand balance could be tighter than this year. The counter-signal is persistently low DDR4 spot volume, as high prices are already deterring buyers. Investors should focus more on long-term agreements, customer qualifications, and gross margins than on spot quotes alone.
AI memory demand is expanding beyond the GPU to the entire server and rack. Vera Rubin-related configurations divide storage in one rack into 20.7TB of HBM4 for hot data, 54TB of SoCAMM for warm cache, and 9.6PB of CMX enterprise SSD capacity. Marvell Technology has also integrated CXL, PCIe 6.0 SSD controllers, and optically interconnected shared memory into a single product portfolio. HBM remains the clearest bottleneck, but incremental byte demand is spilling over into LPDDR5X, DDR5, CXL, and NAND.
NAND/eSSD offered the clearest upside torque this week—and remains the most contested segment. Combined revenue at the top 5 NAND vendors rose 77% quarter over quarter. Korean NAND and SSD exports strengthened in tandem during the first 20 days of August, while enterprise SSDs increased their share of bit shipments to 48%. However, consumer TLC wafer prices rose only marginally and transaction activity remained weak, indicating that enterprise and consumer products are not in the same cycle.
Equipment and materials will benefit only when memory manufacturers convert cleanroom capacity into actual tool orders. Korean imports of dry-etch and plasma-etch equipment have risen above $300 million, while wet-etch imports remain at $20 million to $40 million. HBM adds through-silicon-via etching, copper fill, bonding, inspection, and cleaning steps, giving Lam Research the most direct etch and deposition exposure. Chemicals, photoresists, CMP slurries, and cleaners for HBM adhesives are second-order consumables beneficiaries.
Downstream cost pass-through has evolved from a margin issue into a volume issue. Xiaomi is absorbing higher costs through product mix, launch timing, and higher average selling prices. Acer expects PC shipments could decline by more than 20% in the second half of 2026, while Asus also expects memory costs to weigh on subsequent PC demand. If smartphone and PC vendors continue reducing capacity specifications or delaying purchases, conventional DRAM and client NAND will come under pressure first, while high-end server memory and storage may continue to outperform.
This week’s investment ranking is “visibility first, upside torque second, and cash flow assessed separately.” For high-end DRAM/HBM, watch customer commitments and qualifications at Micron, SK hynix, and Samsung Electronics. For NAND/eSSD, watch SanDisk, Kioxia, and enterprise SSD ASPs. For HDDs, the focus remains Seagate Technology and Western Digital’s nearline EB shipments, BTO, and free cash flow, although this week brought no new data sufficient to change the operating outlook. Next week’s key disconfirmation tests are HBM specifications, the enforceability of long-term agreements, end-market volume cuts, and the NAND supply response.
Overall Weekly View
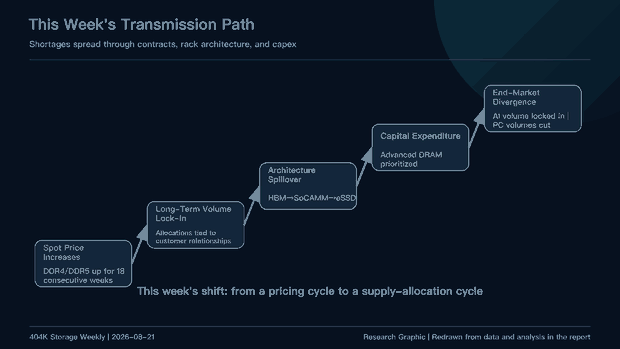
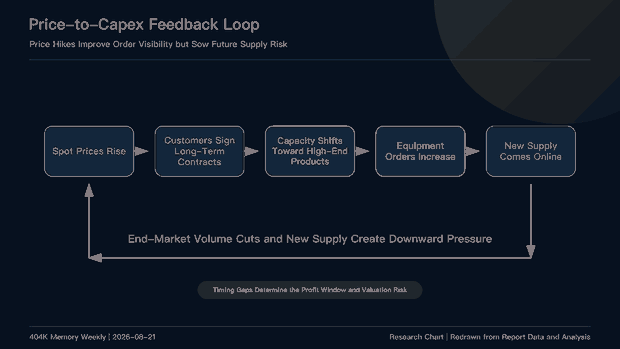
The memory industry is moving from a “pricing cycle” into a “supply-allocation cycle.” Price increases still matter, but 3 variables now determine the durability of earnings: whether customers can secure multiyear agreements, whether suppliers can allocate scarce capacity to high-value products, and whether downstream customers can absorb higher costs without cutting volumes.
Quotes were strong early in the week, but low transaction volumes and weak consumer demand emerged as counter-evidence by midweek. Prices are still rising, but buyers have begun to resist.
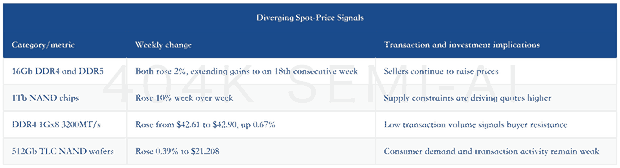
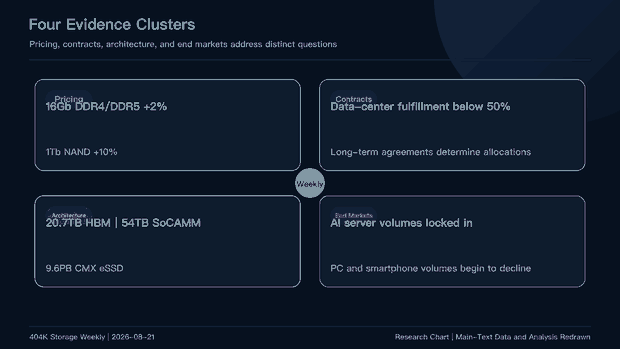
Structural signals in the second half of the week were more important. Preliminary Korean exports for August 1–20 showed sharp growth in DRAM-, NAND-, SSD-, and MCP-related products, with NAND, SSD, and MCP export unit prices reaching interim highs. Compared with weak spot-market transactions, exports and enterprise SSD demand look more like evidence of actual shipments. This was not a synchronized rally across all memory categories: AI-server buyers received priority access, while high prices pushed traditional consumer buyers to the back of the queue.
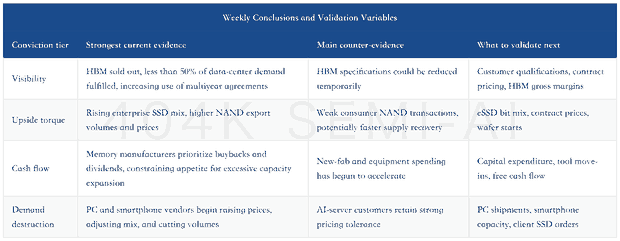
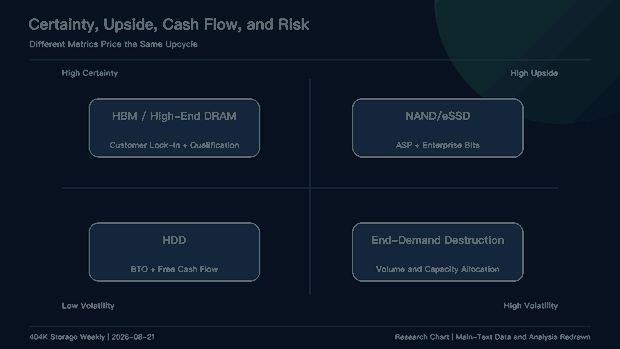
The weekly thesis is supported only when all 4 evidence categories are considered together. Spot quotes show that sellers are still raising prices; company commentary indicates that scarce capacity is increasingly allocated through contracts and quotas; Korean exports confirm that some higher prices are translating into shipments; and the Vera Rubin, HBF, and CXL roadmaps show demand broadening into new applications. These are not repetitive accounts of the same event: they separately address pricing, transactions, supplier leverage, and incremental use cases. Counter-evidence also comes from different points in the chain—low spot volumes, limited gains in consumer wafer prices, possible PC volume cuts, and continued scope to adjust HBM specifications. The conclusion is tightness at the high end and weakness in consumer markets, not an indiscriminate price increase across all memory products.
How the Thesis Evolved This Week
August 17: Prices and allocations provided the first signals. DDR4 and DDR5 spot prices rose for an 18th consecutive week, while NAND 1Tb chip prices increased 10% week over week. On the same day, Micron management explicitly linked long-term agreements to future allocations: customers that previously relied on short-term procurement strategies may find it harder to secure supply in the next shortage. This made “price increases” more clearly a question of customer relationships and supply access.
August 18: Demand broadened from HBM to the entire rack. SK hynix and SanDisk unveiled an open High Bandwidth Flash (HBF) specification covering multilayer NAND stacking, UCIe interfaces, and multiple capacity and bandwidth tiers. Vera Rubin-related configurations also divide HBM, SoCAMM, and enterprise SSDs into hot-, warm-, and cold-data layers. The market is beginning to recalculate memory and storage bytes per server and per rack, rather than focusing only on HBM capacity per GPU.
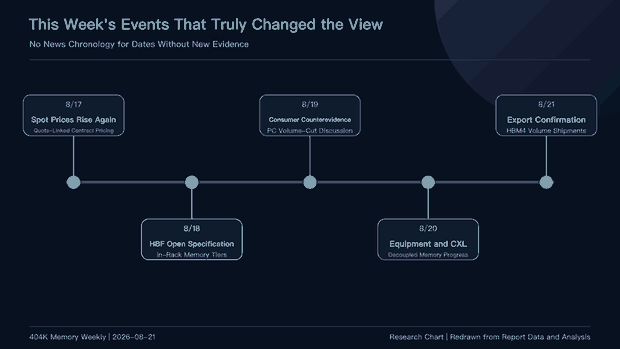
August 19: Counter-evidence began to emerge. DRAM spot transaction volumes remained low, while consumer NAND prices rose only marginally. Acer expects second-half PC shipments could decline by more than 20%, while Xiaomi is absorbing higher memory and storage costs by adjusting its product mix and average selling prices. Meanwhile, debate intensified over whether Rubin Ultra could be temporarily reduced from 288GB to 192GB. Demand has not disappeared, but high prices are forcing customers to reallocate budgets and reconfigure systems.
August 20: Equipment and disaggregated memory emerged as second-order themes. Lead times lengthened globally for deposition, etch, and test equipment, while memory manufacturers began converting cleanroom space into actual tool deployments. Marvell Technology placed PCIe 6.0 SSD controllers, CXL memory pools, and optically interconnected shared memory on a common product roadmap, showing that solutions to the “memory wall” are expanding beyond adding more HBM to include pooling, compression, and data movement.
August 21: Exports and capital expenditure confirmed the divergence. Korean NAND exports during the first 20 days rose 81% sequentially, while SSD exports increased 345% year over year. Micron confirmed that its 2026 HBM output is sold out and that HBM4 has entered volume shipments. Meanwhile, memory manufacturers’ equipment spending is shifting from fab and cleanroom construction to tool installation. DRAM capital expenditure is accelerating, while NAND investment remains more restrained. Supply will increase, but near-term additions remain skewed toward high-end DRAM and HBM.
Weekly Performance of Storage-Related Names
Share-price performance did not simply track fundamentals this week. SK hynix and Samsung Electronics advanced, while most HDD- and NAND-related names declined. The sell-offs in Seagate Technology, Kioxia, and Western Digital show that the market is pricing strong industry conditions alongside interest rates, crowded positioning, and profit-taking.
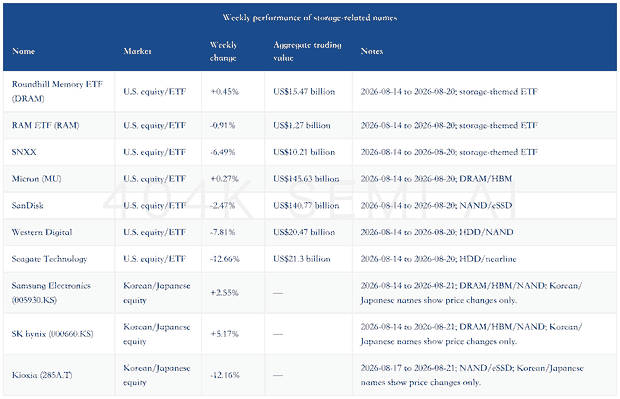
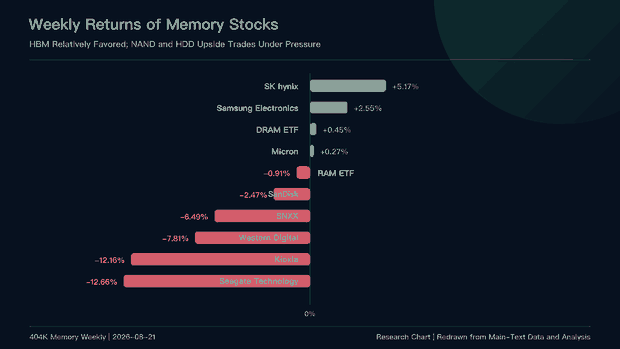
The market is sending two signals. First, HBM’s greater visibility still commands a relative premium, with SK hynix leading gains. Second, positioning in NAND and HDD recovery trades is substantially more crowded: even strong industry signals can be overwhelmed by macro interest rates and position unwinding. Investment rankings therefore need to incorporate valuation and positioning alongside demand strength.
Weekly prices also highlight the distinction between company quality and segment beta. Micron’s modest gain shows that sold-out HBM supply does not automatically translate into a steeper near-term share-price trajectory. Likewise, declines in SanDisk and Kioxia do not negate improving enterprise SSD demand. The market is simultaneously pricing contract visibility, capital expenditure, interest rates, and prior gains; industry momentum is only one variable. Share prices are better treated as signals of crowding and risk budgets, with contracts, shipments, and cash flow used to validate fundamentals—rather than extrapolating long-term supply and demand from one week’s performance.
DRAM/HBM: Supply Leverage, Long-Term Agreements, and Customer Qualification
High-end DRAM and HBM remain the segments with the greatest visibility. At an investor meeting in Singapore, Micron said demand had strengthened further since its earnings release, that it was currently meeting less than 50% of data-center customer demand, and that it expected supply-demand conditions to be tighter in 2027 than in 2026. The company aims to generate more than 50% of revenue from strategic customer agreements: approximately 10% from take-or-pay agreements without fixed pricing and the remaining approximately 40% from fixed-price or price-band contracts.
Long-term agreements do more than lock in volumes; they shift customer relationships from quarterly price negotiations toward multi-year partnerships. Micron’s chief commercial officer stated plainly that customers with a history of tactical, short-term procurement would find it harder to secure allocations during shortages. The investment implication is straightforward: future earnings differentiation among Micron, SK hynix, and Samsung Electronics will increasingly reflect contract structures, customer qualifications, and product mix—not simply DRAM bit shipments.
