目录
Executive Summary
Overall Assessment This Week
Cloud Revenue and AI Capex
Data Centers, Compute Procurement, and Custom Silicon
Models, Software, and Application Monetization
Divergence Between M7 and Neocloud Providers
Debate, Disconfirming Evidence, and What to Watch Next Week
The most important development this week was the shift in AI buildout from an annual capex race toward multiyear contracts and infrastructure commitments. Demand shows no clear signs of cooling, but how efficiently capital translates into usable compute, cloud revenue, and cash flow now matters more than the headline investment amount.
Executive Summary
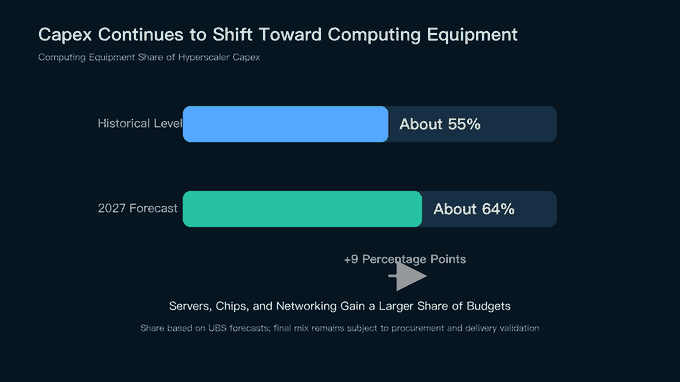
Estimated 2026 AI capex at Amazon, Microsoft, Google, Meta, and Oracle is approaching $800 billion, while compute equipment is projected to rise from a historical share of approximately 55% of hyperscaler capex to approximately 64% in 2027. Spending estimates continue to move higher, with incremental dollars increasingly concentrated in servers and chips. The next test is whether equipment purchases translate into energized capacity on schedule—not whether budgets keep expanding.
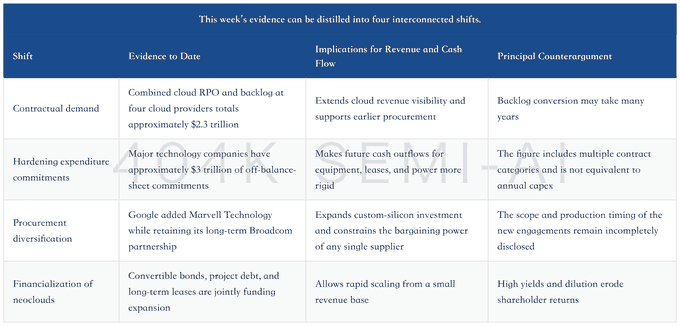
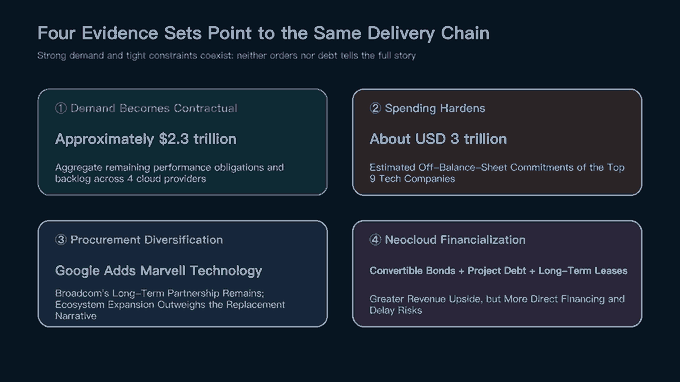
Cloud demand visibility continues to extend. The combined cloud RPO and backlog of Microsoft, Amazon, Google, and Oracle stands at approximately $2.3 trillion. Meanwhile, major technology companies’ off-balance-sheet commitments have reached approximately $3 trillion. The former supports future revenue, while the latter locks in future cash outflows. Both are expanding together, increasing revenue certainty and financial rigidity at the same time.
Google is moving its custom-silicon procurement from a single-supplier relationship to a multi-vendor model. Broadcom’s long-term TPU partnership remains in place through 2031, while Marvell Technology has added inference, networking, storage, and memory-interface engagements. The $120 billion implied by full warrant vesting is a ceiling on qualifying revenue, not a purchase commitment. The key variables are tranche-based vesting for every $500 million of revenue, production ramps, and contra-revenue effects.
Three application monetization paths are emerging: Google is turning search into longer conversational queries, Amazon is integrating payments into agent infrastructure, and Microsoft is selling third-party models to major customers such as Meta through Azure Foundry. Demand remains strong, but customer concentration in Microsoft’s AI revenue, the pause in OpenAI training, and additional compute allocated to monitoring underscore the need to distinguish usage growth from earnings quality.
Neoclouds are growing faster than traditional cloud platforms did at a comparable early stage, but they rely more heavily on convertible bonds, project debt, and long-term leases. Nebius plans to issue $4.5 billion of convertible bonds, while financing for CoreWeave-related data centers still requires high-yield capital. The critical validation next week is not another new-order headline, but whether customer prepayments, financing costs, site energization, and revenue recognition can keep pace with expansion.
Overall Assessment This Week
Evidence of AI infrastructure demand remains strong, but this week’s marginal development was the accelerating shift toward locked-in commitments. Cloud providers and model labs are securing chips, power, land, buildings, and long-term leases in advance. Order visibility now extends beyond 2027, making capex less responsive to short-term swings in quarterly sentiment.
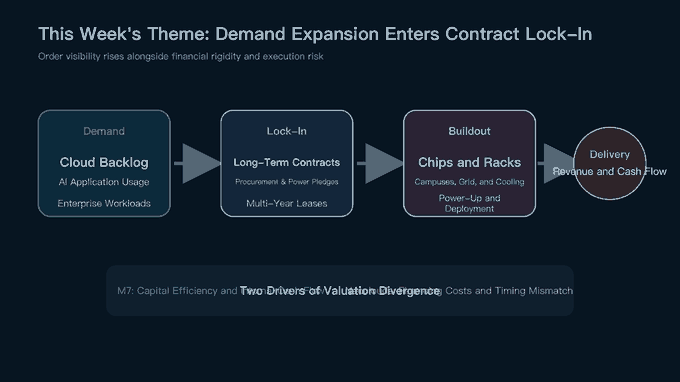
Lock-in also reduces financial flexibility. Equipment enters the balance sheet only upon delivery, while commitments for data-center leases, procurement, and power may remain off balance sheet until the facilities enter service. Reported capex therefore does not fully capture future cash requirements, and current-period free cash flow understates the rigidity of this buildout cycle.
From an investment perspective, the companies fall into two groups. Google, Microsoft, Amazon, and Meta have mature cash flows, internal demand, and software distribution channels, allowing them to absorb longer payback periods. Nebius and CoreWeave are gaining share through concentrated high-performance capabilities, rapid delivery, and customer contracts. Their revenue upside is greater, but financing costs, customer concentration, and project delays also flow through to equity value more quickly.
The order of analysis must also change. First assess whether contracts are executable, then whether capacity can be energized on schedule, and finally utilization and cash recovery. Capex announcements show only whether a company is willing to spend; energized capacity and cloud revenue show whether that spending has created a saleable product. If these three variables remain disconnected, valuations should converge toward cash-flow fundamentals rather than continue rising with order headlines.
This week was therefore about more than another increase in capex. More precisely, demand, contracts, and financing are forming a longer chain of execution. The front end remains strong, while constraints are emerging at the back end. The most informative metrics from here are energized capacity, equipment deliveries, cloud revenue growth, financing costs, and customer concentration.
Cloud Revenue and AI Capex
Capex continues to accelerate, and its composition matters more than the total. Estimates covering Amazon, Microsoft, Google, Meta, and Oracle put 2026 AI capex at nearly $800 billion. UBS projects that compute equipment will account for approximately 64% of hyperscaler capex in 2027, up from a historical level of approximately 55%. This indicates that incremental budgets are increasingly directed toward servers, chips, and networking rather than conventional campus construction.
Demand provides the rationale for continued investment. The combined cloud RPO and backlog of Microsoft, Amazon, Google, and Oracle stands at approximately $2.3 trillion. This cannot be treated as revenue for the next year because contract durations, cancellation provisions, and recognition schedules differ across companies. It nevertheless shows that major customers are reserving cloud capacity through multiyear contracts.
The spending side now casts an even larger off-balance-sheet shadow. One review of disclosures estimates that the nine largest US technology companies have approximately $3 trillion of off-balance-sheet commitments—approximately 3 times their combined reported lease liabilities and long-term debt. Disclosed capex over the past year was approximately $600 billion. These off-balance-sheet commitments include data-center and power leases as well as equipment and service procurement. They cannot be added to capex, but they show that future cash outflows have already been locked in.
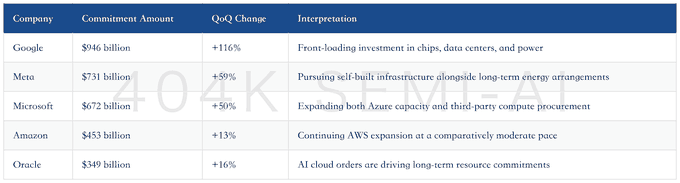
Commitment levels at five companies show the steepest increases at Google and Meta.