
目录
TL;DR
Overall View This Week
AI Chips, Advanced Packaging, and Servers
Optical Communications, CPO, PCBs, and High-Speed Interconnects
Data-Center Cooling, Power Supplies, and Electricity
Robotics, Edge AI, and Hardware Applications
Space, Quantum Computing, and AI Software Applications
Divergent Views, Counterevidence, and Next Week’s Watchlist
AI buildout accelerated again this week, but the investment opportunity has broadened beyond simply buying more GPUs to server delivery, advanced packaging, optical interconnects, power systems, and liquid cooling. Demand remains strong, while capacity, engineering progress, and financing costs have become the key determinants of earnings conversion.
TL;DR
AI infrastructure demand continues to deepen. One set of market estimates puts the combined 2026 AI capital expenditure of Amazon, Microsoft, Google, Meta, and Oracle at nearly $800 billion. AI servers already accounted for 51% of Hon Hai Precision’s Q2 revenue, versus 29% for smart consumer electronics. Demand has moved from budgets into server revenue, but the next test is whether Vera Rubin racks enter mass production as scheduled in Q4 2026.
GPUs remain the starting point of the value chain, but incremental profits are flowing more rapidly toward system bottlenecks. Initial low-volume shipments of VR200 NVL72 are expected in Q4 2026, followed by a ramp in 2027. CoWoS, HBM, switch chips, high-speed connectivity, power, and cooling must all expand in parallel; a shortfall in any one component would delay recognition of complete-system revenue.
The near-term tension in optical communications is clear upgrade direction but slow supply growth. The industry roadmap is shifting from 200G-per-lane near-packaged optics (NPO) to 400G-per-lane co-packaged optics (CPO), yet another industry assessment suggests large-scale CPO supply will remain difficult to achieve in 2027—2028. Indium phosphide and 200G EML chips are more likely to face pricing and lead-time pressure first.
Data-center power is evolving from a supporting component into a core system-design consideration. Rack power is rising from approximately 125 kW toward 500 kW and 1 MW. 800VDC can reduce conversion stages and copper usage, but requires simultaneous upgrades in DC protection, silicon carbide, power management, telemetry, and liquid cooling. Vertiv’s Q2 sales increased 24% and adjusted earnings rose 60%, demonstrating that demand can translate into results, although order visibility still requires further validation.
The application layer is beginning to assess compute returns through task output. The full report evaluates model competition through pricing power, cost advantages, and financial strength, and finds that enterprises are shifting from a narrow focus on token consumption toward cost per task, active agents, and actual output. Next week, investors should watch whether enterprise AI projects expand into production environments and whether off-balance-sheet commitments, debt financing, and interest rates begin to constrain the pace of construction.
Overall View This Week
The most important change this week is that AI capital expenditure is shifting from discrete chip purchases toward integrated delivery of entire “AI factories.” NVIDIA aims to package GPUs, CPUs, data processing units (DPUs), networking, servers, and cooling under a unified standard. Amazon, Microsoft, and Google are more inclined to retain control over data-center design and introduce alternatives such as AMD. Competition has expanded beyond chip share to control over the specifications for racks, networking, power, and software interfaces.
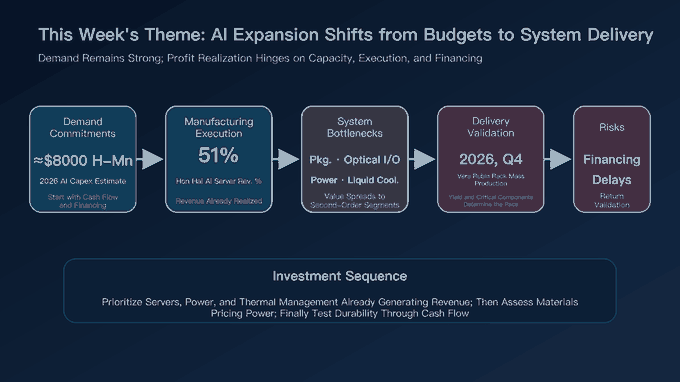
This shift directly affects stock selection. Suppliers closest to customer budgets offer greater order elasticity but also face higher financing and project-delay risks. Companies closer to delivered equipment have more readily verifiable revenue, but must contend with customer pricing pressure and component costs. At this stage, priority should go to segments where orders are already secured, supply remains constrained, and price increases can be passed through to customers.
Demand strength is supported by two layers of evidence. The first is budgets and contractual commitments: major cloud service providers’ combined 2026 AI capital expenditure is estimated at nearly $800 billion, while cloud backlogs and long-term commitments continue to expand. The second is manufacturing revenue: AI servers have become Hon Hai Precision’s largest revenue segment. The former explains why capacity is being built; the latter shows whether orders are beginning to materialize. Both must hold to support the thesis that demand is spreading from GPUs into upstream materials and downstream infrastructure.
This week’s key signals have diverged from expectations into distinct stages of execution.
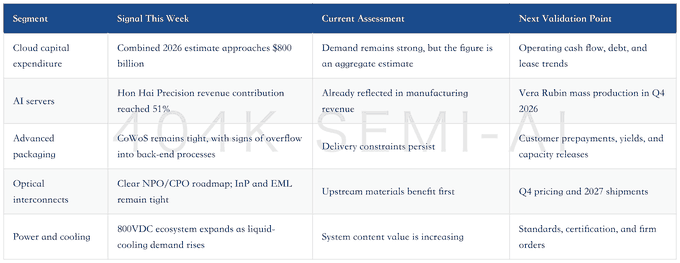
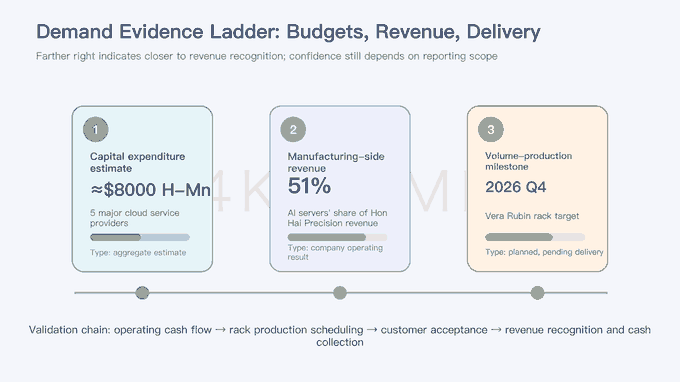
The rising manufacturing-revenue contribution has another easily overlooked implication: customers are purchasing complete systems and racks rather than individual components. This increases system integrators’ revenue scale but also concentrates component-shortage and rework risks at the delivery stage. Whether server manufacturers can protect margins will depend on their ability to lock in critical-component costs and on who bears responsibility for delayed deliveries.
Investors should distinguish between “large demand” and “immediate revenue recognition.” Capital commitments can support equipment purchases for years, yet may initially remain embedded in leases for facilities under construction, purchase commitments, or energy contracts. Figures cited in reports indicate that some hyperscalers’ off-balance-sheet commitments are approximately 4 times their recognized liabilities. The larger the order, the more sensitive it becomes to financing costs, construction permits, and equipment delivery.
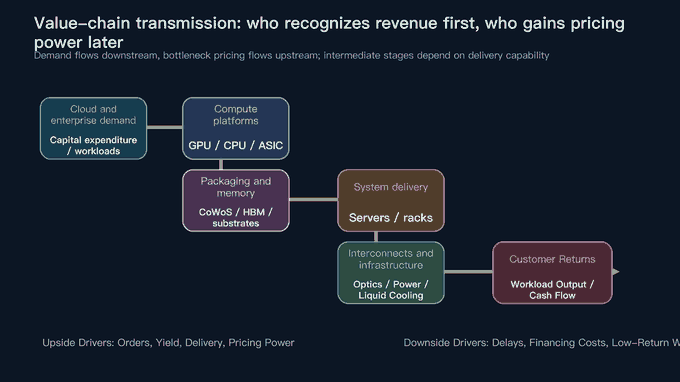
Value capture is not evenly distributed. GPUs and advanced packaging secure high content value first, followed by revenue recognition in servers and networking. Power, cooling, and maintenance services generate recurring demand as racks come online. Application software sits at the end of the chain but ultimately determines whether all preceding capital expenditure earns a return. If task output disappoints, the first casualty is typically the next expansion cycle rather than equipment already contracted for the current cycle.
AI Chips, Advanced Packaging, and Servers
GPU platforms remain the starting point of this expansion, but individual chips are no longer the tightest unit of delivery. Initial volume shipments of VR200 NVL72 are expected to begin in Q4 2026, with early demand driven by xAI and Meta, followed by a strong ramp in 2027. Institutions estimate that 2500—3000 NVL72 racks could be deployed in 2026. This remains a forecast; the critical point is that rack delivery requires HBM, CoWoS, switch chips, optical interconnects, and liquid cooling to arrive simultaneously.
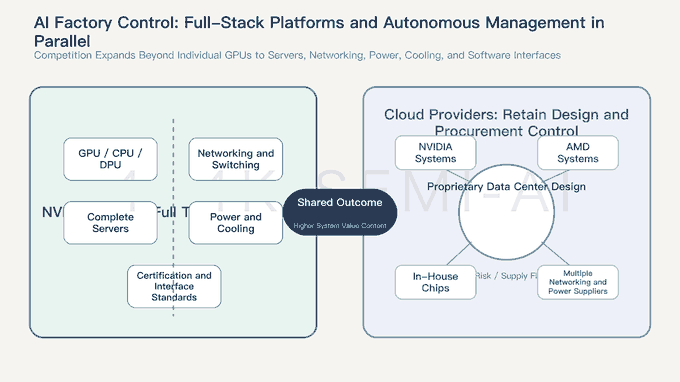
The two platform approaches will produce different supply-chain outcomes. An integrated solution supports standardized interfaces and shorter deployment cycles, but may concentrate more value within the NVIDIA ecosystem. Self-managed cloud architectures can incorporate a broader range of chip, switch, and power suppliers, but increase validation and integration costs. The next issue to watch is how customers balance efficiency against supply flexibility.
The value of advanced packaging reflects system complexity, not merely wafer volumes. VR200 is expected to retain 288GB of HBM4, while Vera Rubin Ultra could shift to 256GB of HBM4E and use near-packaged or co-packaged optical interconnects to improve system performance. Institutions expect HBM4E to command a 70%—100% price premium over HBM4 and forecast more than 75% year-over-year growth in CoWoS capacity in 2027. These figures depend on final product configurations and customer production schedules and should not be treated as confirmed revenue.
Industry information also indicates that back-end packaging for some shared customers is spilling over to Intel’s Malaysia facilities, while substrate customers have shown a willingness to make prepayments. This is creating a collaborative chain involving TSMC’s front-end packaging, Intel’s EMIB-T, ASE Technology Holding’s back-end services, and substrate suppliers. The investment implication is straightforward: after wafers are produced, revenue accrues to suppliers capable of delivering HBM, substrates, and packaging yields together.
