
目录
Executive Summary
Weekly View
Wafer-Fabrication Equipment
Metrology, Inspection, and Testing
Advanced Packaging Equipment and Critical Materials
Company, Order, and Capital-Expenditure Validation
Divergences, Counterevidence, and Next Week’s Watchlist
Equipment demand is beginning to move from expectations into production schedules: customers are freeing up cleanroom space and providing eight-quarter forecasts, while Chinese vendors’ orders are pushing the revenue peak toward 2027—2028. High valuations and execution timing remain the key risks.
Executive Summary
Applied Materials’ results and guidance have moved the global equipment cycle beyond “strong AI demand” to customers actively scheduling equipment installations. FY2026 Q3 revenue was $9.12 billion, including $7.04 billion from Semiconductor Systems; Q4 revenue guidance has a midpoint of $10.25 billion, above the $9.62 billion consensus compiled by J.P. Morgan. More importantly, major customers are now providing rolling eight-quarter forecasts, some roadmap discussions extend through 2030, and the cleanroom-space constraints that had limited equipment deliveries are easing.
China’s wafer fabrication equipment (WFE) growth peak has shifted further out. Bernstein revised its 2026—2028 China WFE forecasts to $57 billion, $73 billion, and $101 billion, while projecting domestic vendors’ revenue at $16 billion, $27 billion, and $52 billion over the same period, raising localization from 28% to 52%. Domestic equipment typically takes around 1 year to move from order to revenue recognition, meaning 2026 order strength will primarily affect 2027—2028 revenue. Current-period imports alone are therefore an inadequate cycle indicator.
Spending is flowing into advanced logic, DRAM, and advanced packaging rather than benefiting all equipment categories equally. Applied Materials expects advanced-packaging sales to grow by more than 70% in 2026, with DRAM demand accelerating materially in 2H26. The company estimates that around 80% of incremental WFE spending in 2027 will be tied to advanced foundry/logic, DRAM, and advanced packaging. Thin-film deposition, etch, materials engineering, yield improvement, and high-value services should see orders first.
China’s localization drive still faces two hurdles: performance and cash conversion. The report estimates that some domestic tools may be priced around 20% below competing products and could gain 5%—10% of mature-logic market share annually over the next several years, while acknowledging persistent gaps in yield and uptime. Long order-conversion cycles mean inventory, customer acceptance, and collection pressures will emerge before profits. Strong revenue growth should not be equated with a concurrent improvement in free cash flow.
Elevated expectations have reduced the margin for error. Domestic equipment stocks covered by Bernstein have already risen 60%—110% year to date, while Applied Materials fell around 5% after hours despite beating expectations on both results and guidance. Four data points matter next week: Applied Materials’ Q4 Semiconductor Systems production schedule, the slope of DRAM deliveries in 2H26, domestic vendors’ 2027 order guidance, and whether advanced-packaging revenue growth can remain above 70%.
Weekly View
Semiconductor equipment is entering a phase in which two upcycles overlap but convert into earnings on different timelines. Global leaders are already seeing cleanroom capacity ease, customer forecasting horizons extend, and next-quarter revenue accelerate. Chinese domestic vendors remain more order-led, with incremental orders booked in 2026 unlikely to be recognized as revenue until 2027—2028. The most common investment mistake will be treating these two curves as if they translate into profit in the same quarter.
Applied Materials provided the strongest evidence this week for the global equipment cycle. FY2026 Q3 revenue increased 25% year over year, while Semiconductor Systems revenue rose 18% sequentially; the midpoint of Q4 revenue guidance implies another 12% quarter-over-quarter increase. Customers are no longer merely signaling purchase intentions: they are allocating equipment space, setting delivery windows, and extending forecasts. For equipment vendors, secured cleanroom space is often a more immediate revenue indicator than verbal capex guidance.
The evidence from China’s equipment supply chain is more medium-term. Bernstein lowered its 2026 import assumption but materially raised its forecasts for total WFE spending and domestic vendor revenue in 2027—2028. Both can be true: overseas leaders’ China revenue can flatten while domestic equipment orders accelerate and total industry demand continues to grow. Interpreting lower imports as weaker aggregate equipment demand would overlook both localization and the lag between orders and revenue recognition.
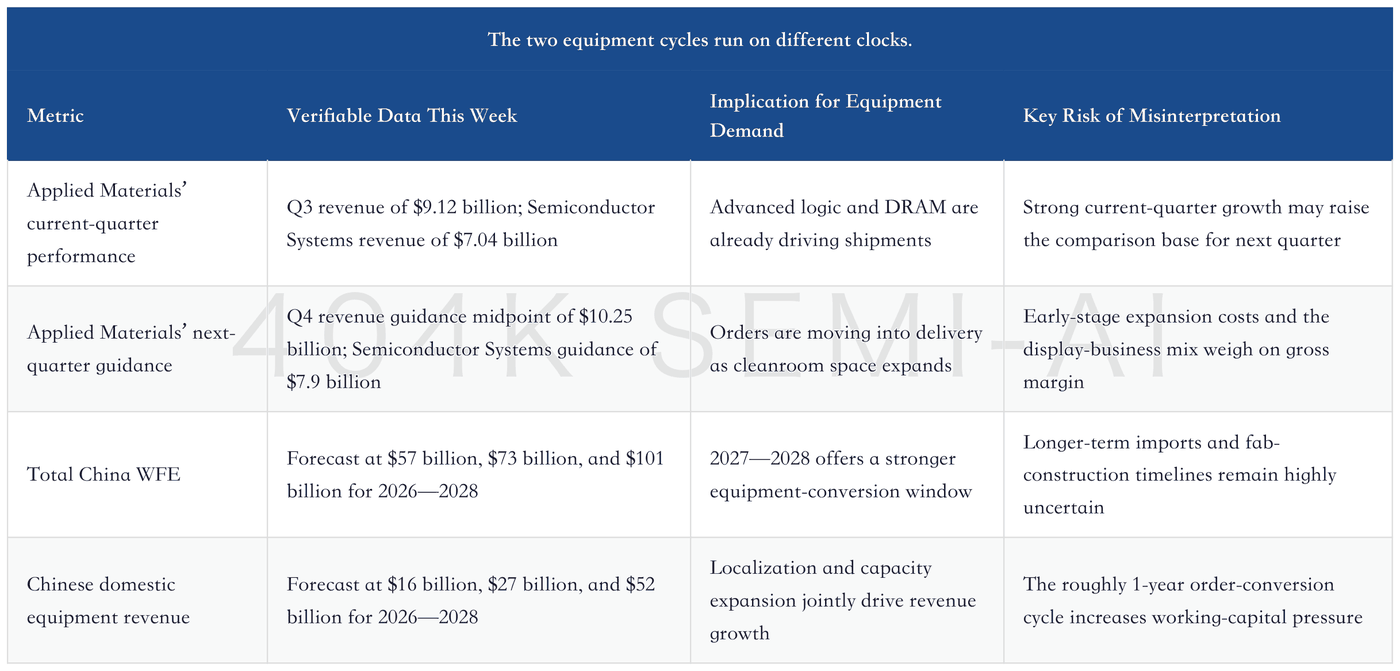
Revenue growth alone is insufficient to assess this cycle; revenue quality also matters. Applied Materials has delivered year-over-year gross-margin expansion for 13 consecutive quarters through product mix and value-based pricing. Domestic vendors must still demonstrate that equipment performance, acceptance efficiency, and collections can keep pace with orders. For the former, the test is pricing resilience; for the latter, it is whether orders convert into cash.
Wafer-Fabrication Equipment
The first major front-end theme is the gradual easing of cleanroom constraints. Applied Materials said customer demand accelerated further over the past approximately 90 days, with major customers seeking additional space to receive equipment. Q4 Semiconductor Systems revenue guidance is $7.9 billion, up 62% year over year. Customers are also providing rolling eight-quarter demand forecasts, with some roadmap discussions extending through 2030. This visibility enables equipment vendors to schedule components, manufacturing, and field services earlier, while reducing the risk of last-minute delivery cancellations.
Advanced foundry and logic remain the primary drivers of current shipments. Applied Materials’ Q3 Semiconductor Systems growth was led by gate-all-around (GAA), FinFET capacity expansion, and DRAM. By end market, foundry, logic, and other applications accounted for 67% of Semiconductor Systems revenue, DRAM for 26%, and flash for 7%. This mix shows that front-end growth is not dependent on a single memory category: advanced logic provides current strength, while DRAM supplies the acceleration in 2H26.
