
目录
Executive Summary
Overall View This Week
How the Week Evolved
Weekly Performance of Memory-Related Securities
DRAM/HBM: Supply Control, Long-Term Contracts, and Customer Qualification
LPDDR/SOCAMM: Spillover from AI CPUs and Rack-Level Memory
NAND/eSSD/SSD: Inference, RAG, and Enterprise SSD Upside
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
Equipment, Testing, and Materials: Second-Order Beneficiaries of Memory Capex
Downstream Costs and Demand Destruction: Servers, Networking Equipment, Smartphones, PCs, and EVs
Investment Ranking, Risks, and Falsification Criteria
What to Watch Next Week
The memory shortage persists, but this week’s real shift is that customers are trading longer contracts and stronger guarantees for supply. Visibility is highest in DRAM/HBM, while NAND/eSSD offers greater earnings upside. The key risk is shifting from insufficient supply to demand destruction, as elevated prices threaten server configurations and low-end devices.
Executive Summary
Micron described data-center DRAM as a tighter constraint than power, land, or logic wafers, with some customers receiving only about 50% of required supply. More importantly, strategic-customer agreements have evolved from relatively nonbinding arrangements of about 12 months into multiyear contracts extending through 2030, featuring take-or-pay commitments and advance payments or credit support. The DRAM/HBM investment case is shifting from spot-price increases toward secured supply, price floors, and customer qualification.
Sandisk is applying the same commercial model to NAND. The company disclosed long-term partnerships with 8 customers, with a weighted-average contract term exceeding 4 years. Aggregate contract value at floor prices is $93.9 billion, with $91.1 billion of remaining performance obligations. By FY2028, about 2/3 of planned bit supply will be covered by multiyear partnerships. However, whether these contracts can hold through the cycle—and whether their price floors genuinely protect profitability—must still be validated through subsequent collections, contract performance, and non-NBM pricing.
AI inference is shifting storage demand from simply “more capacity” toward a more complex hierarchy. HBM provides bandwidth, system DRAM supplies working memory, enterprise SSDs support persistent KV cache, RAG data, and fast data lakes, while HDDs retain the archival tier. Sandisk is advancing TLC performance drives, QLC capacity drives, and HBF in parallel, signaling NAND vendors’ ambition to move from capacity suppliers to participants in inference architecture. HBF, however, remains a technology option ahead of sampling in 2027.
Cost pass-through is beginning to produce 2 distinct outcomes. Server DDR5 contract prices rose 15% to 23% this month. Large customers continue to secure supply but are becoming more cost-sensitive. In the U.S., smartphone sales below $100 fell 64% in the second quarter, while shipments from brands outside the top 4 declined 45%. Higher prices have not yet disrupted AI-server procurement, but they are already materially squeezing low-end handsets and smaller brands.
Equipment, testing, and materials are second-order beneficiaries. The latest forecasts raise 2027 DRAM and NAND equipment-spending growth to 53% and 58%, respectively, while Applied Materials also expects DRAM-related growth to accelerate in the second half. Probe cards benefit from the proliferation of DRAM SKUs, while advanced packaging, yield requirements, and additional test insertions increase equipment content per high-end memory device. The risk is that strong profitability prompts memory manufacturers to expand too quickly, ultimately turning the post-2028 shortage into oversupply.
Overall View This Week
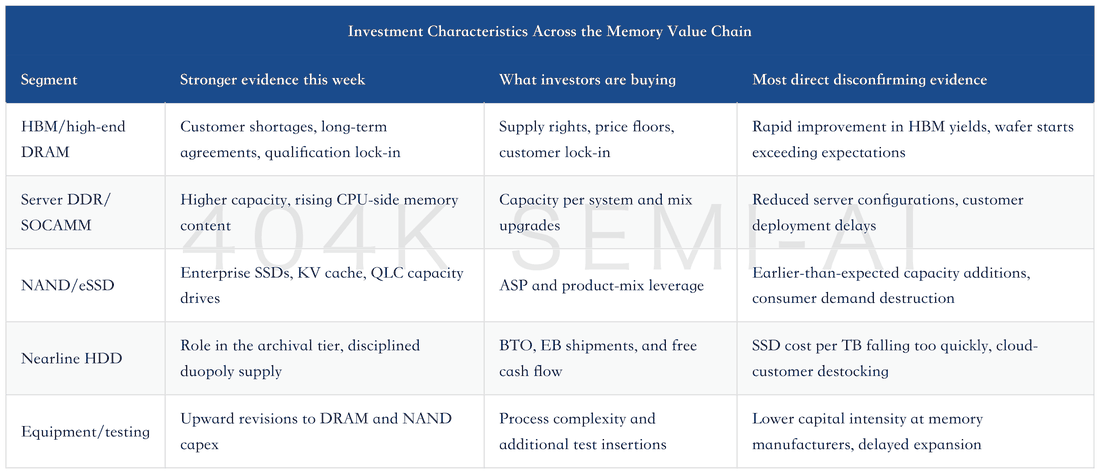
The central theme across the memory value chain this week is not simply continued price increases, but the contractualization of “supply rights.” Historically, memory cycles were assessed primarily through spot prices, inventory days, and production cuts. This cycle also requires tracking how much customers are willing to prepay, how many years contracts can lock in supply, whether price floors are enforceable, and whether a given memory product has already been jointly qualified with a GPU, CPU, or ASIC.
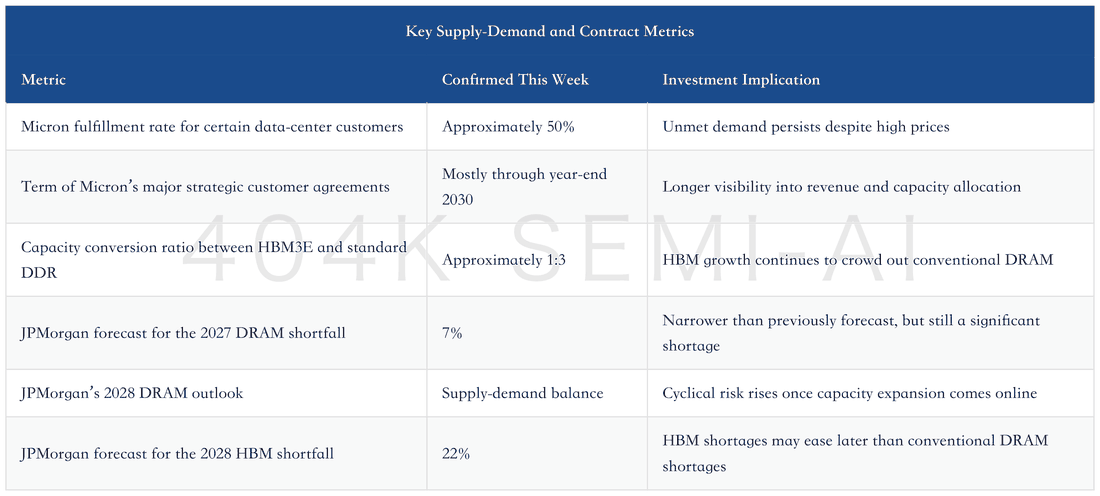
High-end DRAM and HBM still offer the greatest visibility. Micron said demand growth may continue to outpace supply growth in 2027, with some data-center customers receiving only about half their required DRAM. HBM expansion also crowds out conventional DRAM capacity. Micron estimates that producing every 100 bits of HBM3E requires sacrificing about 300 bits of conventional DDR capacity, with the ratio potentially worsening further during the transition to HBM4E. As long as customers cannot readily reduce memory capacity per system, high-end DRAM and server DDR should retain pricing support.
NAND offers somewhat lower visibility but greater earnings leverage. JPMorgan’s latest forecast revised the 2026 NAND market from a 3% shortage to balanced supply and demand, while still projecting a 5% shortage in 2027 and a return to balance in 2028.
Demand is also shifting toward enterprise SSDs. Kioxia-related research estimates that the enterprise SSD market opportunity will exceed 820EB next year, up about 55% year over year. Sandisk identifies persistent KV cache, fast data lakes, and data preparation as the principal NAND workloads in AI data centers. The NAND valuation case should be based on ASP and enterprise product-mix upside; long-term agreements should not be treated as a guarantee of permanently elevated margins.
The HDD thesis has not been displaced by SSDs. Within the inference hierarchy, SSDs sit closer to compute, while HDDs continue to provide low-cost archival and cold-data storage. Seagate Technology and Western Digital rose 19.86% and 13.12%, respectively, this week, indicating that investors are also trading the expansion of AI data lakes. However, no new company-level guidance on nearline EB shipments, build-to-order (BTO), or free cash flow emerged this week. Share-price performance alone therefore does not justify upgrading HDD fundamentals. The next datapoints remain nearline HDD EB growth, order lead times, and free cash flow—not capacity narratives alone.
How the Week Evolved
On August 10, the market first received a strong signal from DRAM. Micron said supply was meeting less than half of data-center customer demand, with some customers signing long-term agreements extending beyond 2030.
The same day, another bill-of-materials estimate placed memory at 62% of the cost of a core Vera Rubin unit and indicated that CPU-side SOCAMM2 carries a greater cost weighting than GPU-side HBM4. The supply shortage and rising content per system were therefore confirmed on the same day.
On August 11, the thesis advanced from “shortage” to “changing contract structures.” Micron further explained that strategic-customer agreements are primarily multiyear, take-or-pay arrangements, with some supported by advance payments and letters of credit. UBS simultaneously raised its HBM demand and pricing estimates, arguing that wafer reallocation toward HBM would continue to constrain conventional DRAM. Enterprise IT hardware analysts also revised their earlier view that higher prices would immediately suppress corporate procurement: demand for AI compute and storage is encouraging enterprises to buy earlier rather than wait for prices to fall.
On August 12, pricing pressure became quantifiable for the first time.
Server DDR5 contract prices broadly rose 15% to 23% this month. A substantial gap between contract and spot pricing remains, although the spread for 96GB products has begun to narrow.
Equipment forecasts were revised upward in parallel, with the 2027 wafer-fabrication-equipment spending outlook rising materially and memory providing the main incremental contribution. The memory conference also placed CXL, HBF, and persistent KV storage on the same roadmap, showing that the industry is moving beyond simply adding DIMMs toward memory pooling, tiering, and new media.
On August 13, NAND took center stage. Sandisk disclosed its multiyear partnership coverage, contract value, pricing safeguards, and financial guarantees, while breaking inference workloads into KV cache, data preparation, and fast data lakes. At the same time, demand destruction became evident in low-end smartphones: U.S. sales of handsets below $100 fell sharply, with smaller brands under greater pressure than market leaders. AI servers can still absorb higher memory prices, but at the bottom of consumer electronics, those increases are already triggering configuration cuts and brand consolidation.
On August 14, the value chain began pricing in capacity expansion and technology execution. Applied Materials expects DRAM-related growth to accelerate in the second half and raised its advanced-packaging sales-growth outlook. Phison management cautioned that new NAND capacity may require about 4 years from initial investment to volume production. Sandisk outlined BICS10, HBF, and its long-term financial targets, prompting the market to place near-term price increases, long-term contracts, and next-generation architectures within a single valuation framework. The principal risk is now clearer as well: both the contracts and technology roadmaps are aggressive, so any delay in performance, qualification, or volume production could amplify the downside.
Weekly Performance of Memory-Related Securities
Capital did not concentrate in a single category this week. All three memory-themed ETFs, Micron, SanDisk, the HDD duopoly, and leading South Korean and Japanese memory manufacturers advanced, with trading value rising sharply in SanDisk and Micron. The rally reflects a rerating across the memory value chain, although the underlying earnings drivers differ by security.
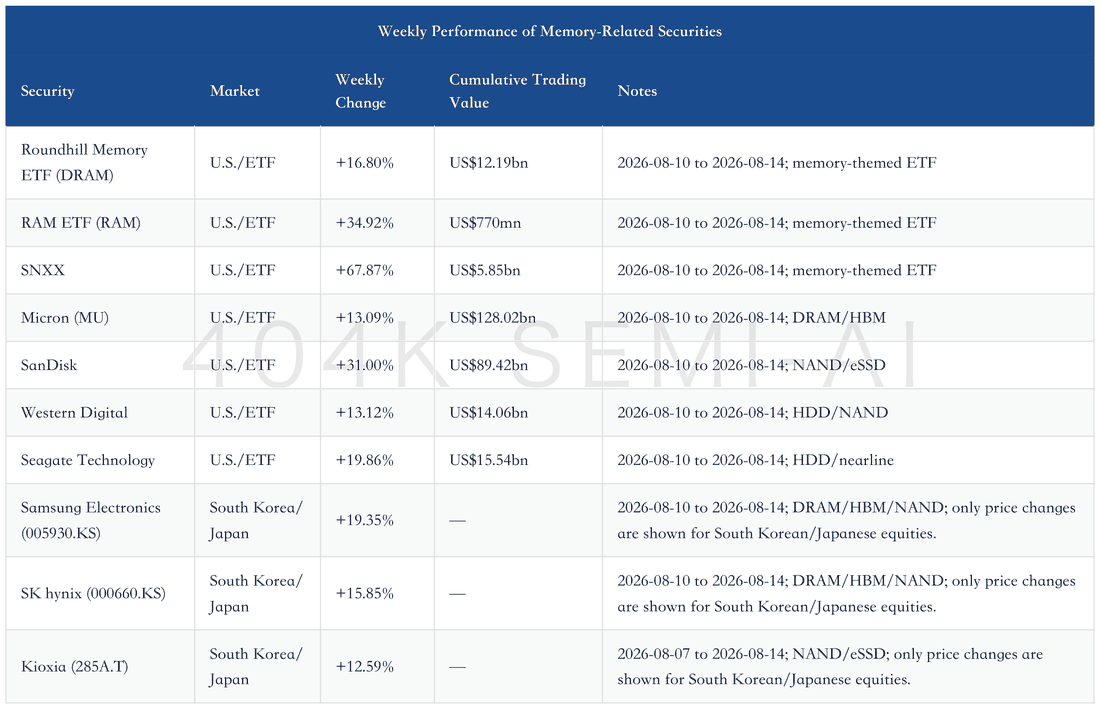
The key is not to treat share-price performance as a ranking of fundamentals. SNXX rose 67.87% and SanDisk gained 31.00%, but the former cannot substitute for company-specific analysis of contracts, products, and cash flow. Cumulative trading value reached US$128.02bn for Micron and US$89.42bn for SanDisk, indicating that positioning is also becoming increasingly crowded. High turnover will amplify the trend if fundamentals continue to deliver, but any downgrade to supply-demand forecasts or rise in interest rates would likewise magnify valuation compression.
DRAM/HBM: Supply Control, Long-Term Contracts, and Customer Qualification
The most important development in DRAM/HBM this week was customers shifting from price inquiries to using their balance sheets to secure supply. Micron’s strategic customer agreements are not conventional annual handshake arrangements; they are multi-year contracts incorporating annual purchase volumes, take-or-pay obligations, price bands, and prepayments or credit support. At its earnings release, the company disclosed 16 agreements with US$22bn in cash and cash-equivalent commitments, including approximately US$18bn in cash. The number of agreements has continued to increase since then.
These contracts affect earnings and cash flow through three distinct channels. Prepayments first strengthen cash resources and capital-spending capacity; annual offtake commitments then improve capacity utilization; and price floors ultimately protect gross margins during a cyclical downturn. None of these layers can substitute for another. Prepayments without strict purchase obligations still leave revenue volatile; committed volumes without pricing safeguards may force suppliers to trade discounts for stability; and high price floors coupled with deteriorating customer credit merely convert operating risk into contract-enforcement risk. In coming quarters, contract liabilities, cash flow, shipments, and gross margin should be assessed together.
Differences among Samsung Electronics, SK hynix, and Micron should be assessed through their products and customer qualifications. SK hynix has a leading HBM customer base, with its earnings visibility supported by market share and qualification status. Samsung Electronics offers greater upside leverage through HBM4 yields, foundry and packaging integration, and subsequent customer adoption. Micron benefits from rising prices in both HBM and conventional DRAM, and this week’s meetings also indicated that conventional DRAM may be more important than the market previously expected. The critical issue is not simply which company generates more revenue, but which can embed high prices in long-term contracts without sacrificing profit through discounts—ultimately determining cash-flow quality.
