
目录
Executive Summary
Overall Assessment This Week
AI Chips, Advanced Packaging, and Servers
Optical Communications, CPO, PCBs, and High-Speed Interconnects
Data-Center Cooling, Power Supplies, and Electricity
Robotics, Edge AI, and Hardware Applications
Space, Quantum Computing, and AI Software Applications
Divergences, Counterevidence, and Next Week’s Watchlist
Demand remains the strongest signal this week: TSMC’s July revenue reached a record high, while Quanta Computer’s order visibility now extends through 2028. Yet constraints are spreading beyond chips to DRAM, indium phosphide (InP), printed circuit board (PCB) materials, and manufacturers’ cash flow. Next week’s key question is whether capacity expansion, deliveries, and cash collection can keep pace with one another.
Executive Summary
AI infrastructure demand continues to rise, and the debate has shifted from whether orders exist to who can deliver on time and convert them into cash. TSMC’s July revenue reached NT$467.58 billion, up 44.7% year over year. Quanta Computer’s AI server order visibility reportedly extends through 2028, prompting it to raise capital expenditure from NT$30 billion to NT$40 billion. Demand shows no clear signs of weakening, but as server content value rises, inventories, receivables, and working-capital requirements will expand more rapidly. Manufacturing and financing capacity must therefore be assessed together.
DRAM is becoming a hard constraint on server shipments. Micron Technology said it can meet only about 50% of demand from some data-center customers and expects demand growth could continue to outpace supply growth in 2027. HBM capacity expansion will also consume more conventional DRAM wafer output, potentially benefiting HBM, server DRAM, and NAND simultaneously. The risk is that the price floors, purchase obligations, and customer termination provisions in long-term agreements have not been fully disclosed; multiyear demand should not be equated directly with multiyear profits.
Optical interconnects are moving from concept to the capacity and cash-flow stage. NVIDIA said Spectrum-X Ethernet Photonics has entered full-scale production, while results from Lumentum and Coherent point to strong demand for 800G, 1.6T, lasers, and optical switching. The current bottleneck appears to be InP wafers and laser capacity rather than module assembly. With the 2 companies undertaking substantial capacity expansions, the next tests are 6-inch InP yields, returns on capital expenditure, and operating cash flow—not order visibility alone.
Content value continues to spread into PCBs, electronic materials, power, and cooling, but price increases will transmit pressure downstream. Nan Ya Plastics plans to raise prices for copper-clad laminates and prepregs by 20%–25% from September 1, citing shortages of electronic-grade glass cloth and higher raw-material costs. The OCP M+ Diablo architecture is beginning to introduce ±400-volt DC sidecar power. While suppliers gain pricing and order elasticity, server OEMs will face greater pressure on costs, delivery, and cash collection.
Edge AI and application software are beginning to generate measurable revenue, although commercialization remains highly uneven. One year after entering mass production, DeepX has secured more than US$13 million in commercial orders, with its products deployed in robotics, drones, and smart factories. OpenAI’s annualized revenue has reportedly surpassed US$40 billion. Robotics and quantum computing remain focused largely on validation, partnerships, and prototypes; near-term assessment should center on orders, deployment dates, and customer payments rather than treating technical partnerships as revenue.
Overall Assessment This Week
The AI supply chain showed no demand reversal this week. Instead, 3 more concrete forms of confirmation emerged. First, TSMC revenue and AI server orders indicate that compute infrastructure investment is still accelerating. Second, revenue and earnings from Lumentum, Coherent, and PCB equipment vendors show that spending is flowing from GPUs into optical components, substrates, and manufacturing equipment. Third, long-term contracts, financing platforms, and localized power solutions indicate that projects have become large enough to require redesigned financing structures and data-center infrastructure.
What has changed is the location of the bottlenecks. The market initially focused only on GPUs and advanced packaging; now DRAM, InP lasers, electronic-grade glass cloth, power equipment, cooling systems, and working capital can all determine when a rack is delivered. For upstream suppliers, bottlenecks improve order visibility, pricing, and prepayments. For server manufacturers and data-center operators, the same constraints mean higher inventories, construction delays, and more cash tied up.
Demand, profits, and cash flow move at different speeds. Coherent’s data-center and communications business is growing rapidly, but capital expenditure, inventories, and operating cash flow are all under pressure. AI server original design manufacturers (ODMs) must also fund PCB, memory, networking, power, cooling, and logistics costs in advance. The larger the orders, the more likely the balance sheet becomes a competitive advantage. Analysis should therefore progress from “how many orders were secured” to “how much was delivered, how quickly cash was collected, and how much additional funding was required.”
This week’s supply-chain developments can be distilled into the following 4 steps.
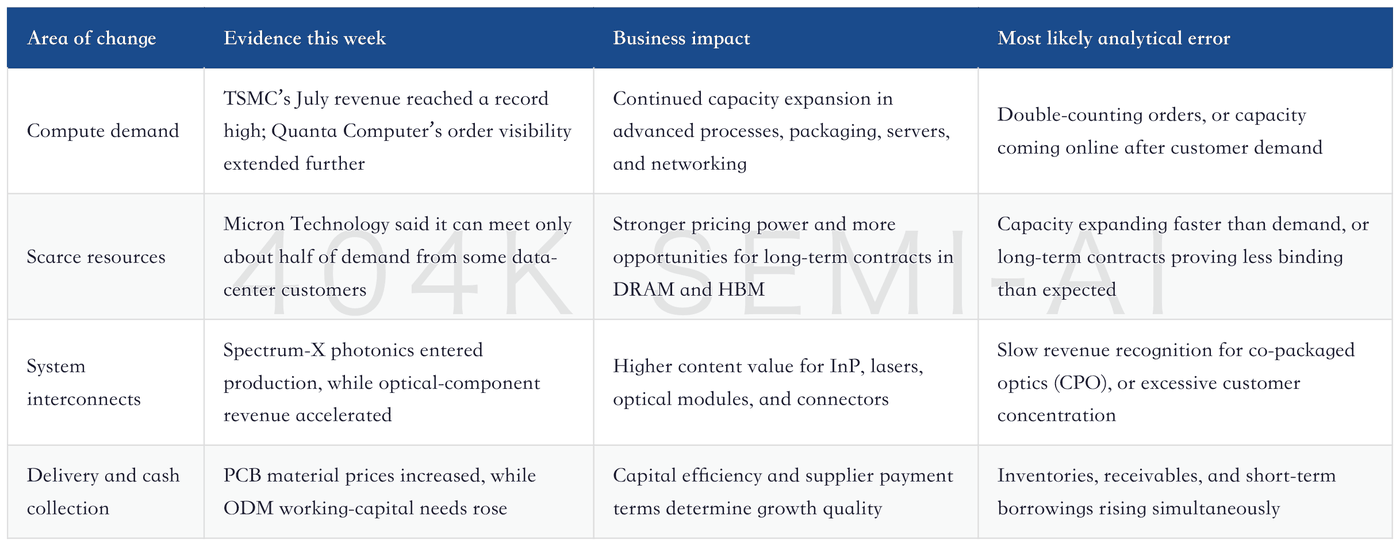
The most important investment question is which scarcity points can generate sustained pricing, binding orders, and cash returns. DRAM and InP already show relatively clear supply-demand signals; PCB materials are beginning to see price increases; and power and cooling are evolving into engineering standards. Demand for server manufacturing and emerging AI clouds is equally strong, but returns depend more heavily on financing costs, utilization, and the pace of cash collection.
AI Chips, Advanced Packaging, and Servers
TSMC remains the clearest demand barometer this week. July revenue reached NT$467.58 billion, up 44.7% year over year and 5.6% month over month. The result corroborates strong demand for AI and high-performance computing, advanced processes, and CoWoS capacity expansion. It indicates that wafer starts and packaging demand from leading chip customers remain robust, but does not by itself prove that all downstream servers will come online on schedule. Between wafer shipment and data-center revenue generation lie multiple stages, including packaging, boards, racks, power, and networking.
Advanced-packaging supply relationships are also becoming more long-term. Amkor Technology announced a multiyear collaboration with NVIDIA under which NVIDIA will provide US$1.5 billion, including prepayments. The companies will jointly develop packaging and testing technologies for AI infrastructure and support Amkor Technology’s capacity expansion. Prepayments carry more weight than ordinary purchase indications because they allow suppliers to build capacity. However, the annual allocation, delivery conditions, and minimum purchase volumes remain to be monitored; the total contract value should not be recognized as revenue upfront.
DRAM is this week’s clearest physical bottleneck. Micron Technology said it can meet only about half of the supply required by some data-center customers, while demand growth could continue to exceed supply growth in 2027. Producing HBM displaces more conventional DDR output, and the crowding-out effect could intensify with the transition to HBM4E. As a result, increased GPU deliveries will raise demand for both HBM and server DRAM.
