
目录
Executive Summary
Overall Assessment
AI Chips, Advanced Packaging, and Servers
Optical Communications, CPO, PCBs, and High-Speed Interconnects
Data-Center Cooling, Power Systems, and Electricity
Robotics, Edge AI, and Hardware Applications
Space, Quantum Computing, and AI Software Applications
Divergences, Disconfirming Evidence, and Next Week’s Watchlist
The key development this week is that total AI investment continues to be revised upward, but orders, profits, and valuations no longer move in lockstep. ASICs, optical interconnects, and enterprise software are beginning to generate clearer revenue, while power availability, advanced packaging, and investment returns will determine the pace of the next phase of monetization.
Executive Summary
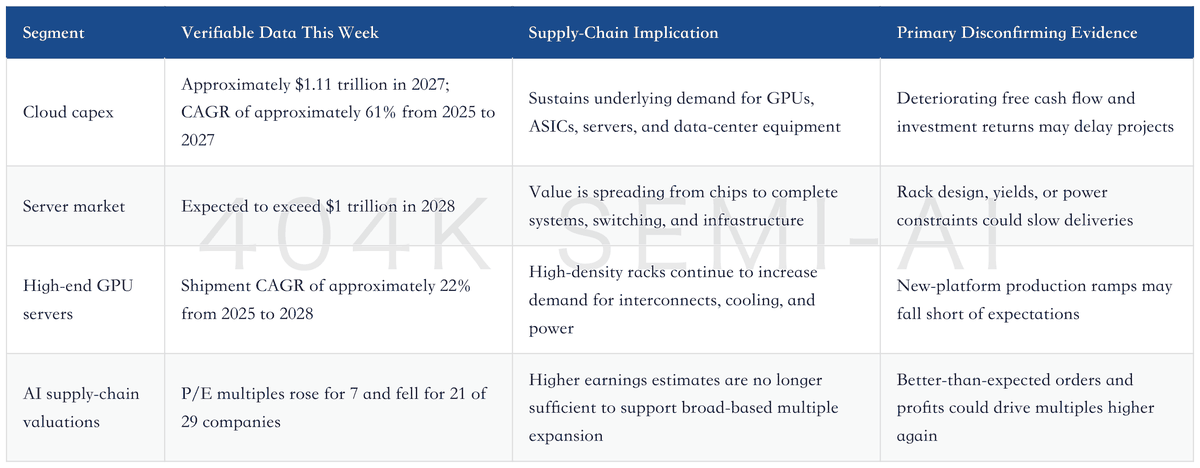
AI infrastructure demand continues to expand, but the supply chain has shifted from trading aggregate growth to trading execution. Combined 2027 capex forecasts for a group of cloud service providers, neoclouds, and Oracle stand at approximately $1.11 trillion, implying a CAGR of approximately 61% from 2025 to 2027. Meanwhile, P/E multiples have declined for most of 29 tracked AI supply-chain companies even as earnings estimates have generally risen. Share-price performance will no longer be determined solely by total capex, but by whether orders convert into revenue, earnings, and free cash flow.
GPUs remain the primary compute engine, while ASICs are capturing a more visible share of incremental demand. The XPU market is projected to reach approximately $500 billion in 2027, with ASICs accounting for approximately 20%; Google TPU shipments are expected to grow more than 90% YoY in 2026. MediaTek is seeing strong demand for AI ASICs, but a mix shift toward lower-margin products will weigh on its overall gross margin, underscoring that order growth does not translate directly into profit growth.
Optical communications and high-speed interconnects offer the strongest visibility this week. Nokia’s optical-network backlog reached €2.8 billion in Q2, nearly 3 times its Q1 level, while optical-component supply remains tight at Lumentum and Coherent. Near-packaged optics (NPO) are more likely to scale before co-packaged optics (CPO), as they shorten electrical connections while retaining better serviceability. The long-term direction of CPO remains intact, but the timing of volume adoption has yet to be validated through orders and production yields.
Server demand continues to migrate toward high-density racks, broadening bottlenecks from individual chips to PCB backplanes, connectors, switching silicon, power delivery, and cooling. The global server market is expected to exceed $1 trillion in 2028, while high-end GPU server shipments are projected to grow at a CAGR of approximately 22% from 2025 to 2028. Design and yield adjustments to Nvidia’s Kyber backplane are a reminder that system-level delivery depends on coordination across the entire rack: even 1 low-value component can delay revenue recognition for high-value equipment.
AI software is beginning to show evidence of monetization, but business-model outcomes vary widely. Microsoft now has more than 30 million paid Copilot seats, while 87% of respondents in an SAP channel survey expect AI to generate incremental spending over the next 12 months. Simplex Holdings’ AI features improved gross profit by approximately ¥300 million, but model-usage fees were also approximately ¥300 million, leaving the net contribution close to zero. The critical questions for software are whether paid seats, migration velocity, and inference costs can improve simultaneously.
Next week, investors should monitor 4 groups of potential disconfirming evidence: whether higher cloud-service-provider capex continues to pressure free cash flow; whether ASIC and HBM procurement costs erode gross margins; whether CPO production announcements convert into customer acceptance and revenue; and whether power, liquid-cooling, and quantum-computing projects progress from technology demonstrations to commercial contracts with defined values, delivery schedules, and margins.
Overall Assessment
Demand across the AI supply chain remains intact, but profits are being redistributed among segments. Upstream capex continues to expand, with GPU, ASIC, optical-component, and server shipments all expected to grow. Midstream constraints are emerging in yields, memory costs, power delivery, and interconnects. Downstream software is, for the first time, producing more trackable data on paid seats and migrations. The investment question should shift from “Will AI spending continue to grow?” to “Who can retain the economics of that growth?”
Demand remains sufficiently deep. Combined 2027 capex forecasts for a group of global cloud service providers, neoclouds, and Oracle total approximately $1.11 trillion, implying a CAGR of approximately 61% from the corresponding 2025 base.
The 2026 capex forecast has also been raised by approximately 15% since March. Separately, planned and under-construction AI data-center projects represent approximately $1.2 trillion of investment. These 2 datasets cannot be added directly, but together they indicate that aggregate AI infrastructure spending has not yet entered contraction.
Aggregate growth has not produced broad-based valuation expansion. Among 29 tracked server, component, and infrastructure suppliers, P/E multiples rose for 7 and fell for 21, while EPS estimates increased for most companies over the same period. The market is compressing forward multiples while demanding more immediate revenue and profit delivery. This combination generally favors companies with strong order visibility and customer-backed capacity expansion, while penalizing segments still reliant on long-dated total-addressable-market narratives.
This week’s core thesis can be summarized in 3 steps. First, continued cloud capex supports demand for GPUs, ASICs, and servers. Second, value is spreading into optical interconnects, switching, PCB backplanes, power supplies, and cooling because larger clusters require more complex system coordination. Third, enterprise-software vendors are embedding AI into migration, collaboration, and data products, producing more evidence of paid adoption, although inference costs will determine whether gross margins improve in parallel.
The most common analytical pitfalls are equally clear. Capex forecasts are demand signals, not supplier revenue; backlogs are leading indicators of revenue, not current-period profit; and higher technical specifications raise per-system content while potentially amplifying yield and delivery risks. Orders, shipments, gross margins, and cash flow should therefore be assessed together rather than selecting only the strongest metric.
Aggregate growth alongside valuation compression shows that the market is rewarding execution.
AI Chips, Advanced Packaging, and Servers
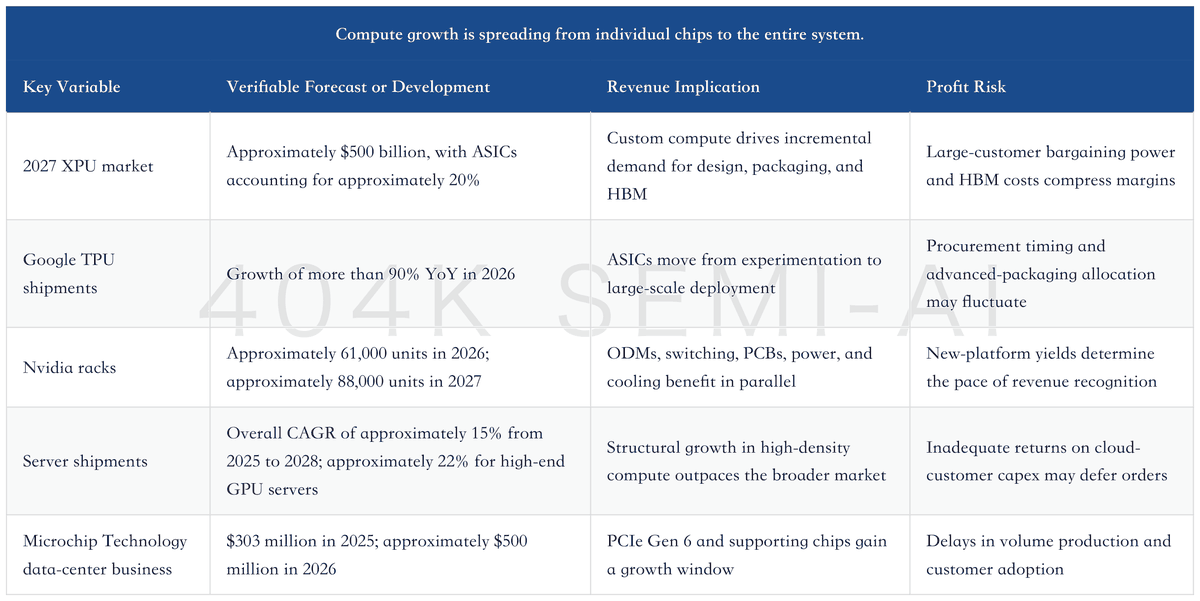
GPUs remain the primary compute engine, but ASICs are growing faster at the margin. The XPU market is projected to reach approximately $500 billion in 2027, with ASICs accounting for approximately 20%; Google TPU shipments are expected to grow more than 90% YoY in 2026. This does not imply that GPUs are being replaced. Rather, cloud service providers are assigning stable, sufficiently large workloads to custom silicon to reduce unit inference costs and gain greater control over their supply chains.
ASIC economics cannot be assessed solely through chip selling prices. The AI data-center ASIC market is expected to reach $140 billion–$160 billion by 2028, with HBM accounting for approximately half of the total value. Market-size estimates vary materially depending on how HBM pricing and procurement arrangements are treated. MediaTek is seeing strong demand for its AI ASIC projects, which is expected to offset some pressure from its smartphone business. However, as the mix shifts toward lower-margin products, overall gross margin may still decline in 2026 and 2027. Even with rapid order growth, suppliers may not retain a commensurate share of the economics.
Advanced-packaging constraints remain, but the issue has shifted from whether capacity exists to how it is allocated. GPUs, TPUs, and other ASICs are competing for HBM, advanced-packaging, and testing resources. Applied Materials expects semiconductor-equipment spending intensity to continue rising in 2027, with advanced logic, DRAM, and advanced packaging jointly driving deposition and etching demand; more than 65% of the company’s revenue is exposed to these 2 process categories. The benefit to equipment vendors is relatively clear, but the key validation point is whether customer capacity expansions convert into equipment revenue on schedule—not merely the scale of foundries’ long-term plans.
The server-demand trajectory remains steep. The global server market is expected to exceed $1 trillion in 2028, while high-end GPU server shipments are projected to grow at a CAGR of approximately 22% from 2025 to 2028. The Rubin platform and AMD’s Helios platform are expected to enter volume shipments in Q4 2026. These platform transitions will generate incremental revenue but will also concentrate validation pressures across backplanes, switching, cooling, and power systems within the same time window.
Server manufacturers’ inventories have yet to show signs of stalling. Inventory days at major server ODMs and OEMs remain normal, while 2026 consensus revenue estimates for Wiwynn and Accton have been raised by approximately 36% and 54%, respectively. This indicates that current orders are being driven by actual deliveries rather than broad-based restocking. The key risk is excessive exposure to a single large customer, rack architecture, or new platform, which would make quarterly revenue unusually sensitive to certification and yield issues.
Agentic AI will also increase the importance of CPUs again. More complex task orchestration requires CPUs for system control, data movement, and coordination across multiple models; growth in GPU counts will not eliminate CPU demand. Microchip Technology expects data-center solutions revenue to increase from $303 million in 2025 to approximately $500 million in 2026. Its PCIe Gen 6 products will enter volume production later this fiscal year and accelerate in 2027. Semiconductor investment opportunities therefore extend beyond compute cores to supporting components such as high-speed connectivity, timing, power management, and security controllers.
Optical Communications, CPO, PCBs, and High-Speed Interconnects
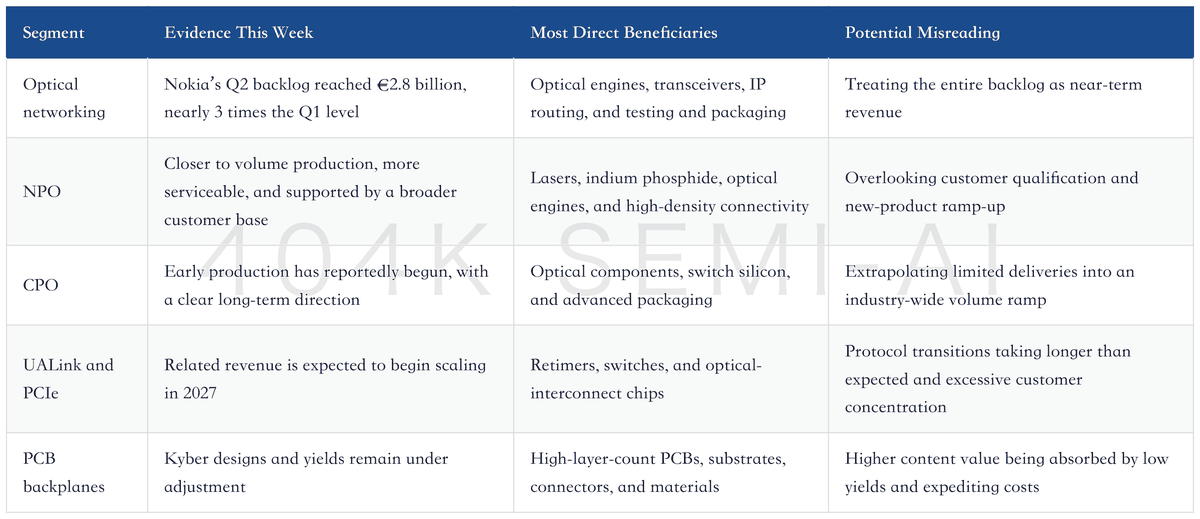
Optical communications offered the strongest order visibility this week. Nokia’s Q2 optical-network backlog reached €2.8 billion, nearly 3 times the Q1 level. Its second San Jose wafer fab is expected to begin ramping in late 2026 and continue adding capacity through 2027, while its Pennsylvania testing and packaging capacity is scheduled to increase to 10 times its current level by the end of Q3. The simultaneous expansion of orders and capacity indicates that demand from AI clusters for optical networking and IP routing has entered suppliers’ delivery plans.
Supply and demand for optical components at Lumentum and Coherent are similarly tight. Attention has recently shifted from whether demand exists to new-product ramps, internal indium phosphide capacity, and gross margins. Near-packaged optics, or NPO, is emerging as a practical bridge from pluggable optical modules to CPO. By moving optics closer to the XPU, NPO shortens electrical connections while retaining better serviceability and a broader customer base. CPO requires deeper integration of optics, switch silicon, and advanced packaging, offering higher long-term content value but also a higher near-term adoption threshold.
Supply-chain sources indicate that CPO switching systems for next-generation AI platforms have entered production and begun shipping to key customers. Industry researchers nevertheless disagree on the timing of broad adoption, with some forecasts pointing to 2028–2029. These signals are not contradictory: limited production can initially validate designs and customer processes, while large-scale revenue will still depend on laser longevity, thermal management, packaging yields, and field serviceability. Investors should prioritize orders, shipments, and gross margins rather than equating “production has begun” with an industry-wide volume ramp.
Content value in high-speed interconnects is also rising. Astera Labs expects revenue related to UALink and optical interconnects to begin scaling in 2027 and estimates the addressable market for UALink and PCIe connectivity at approximately $10 billion. Its interconnect content per XPU already exceeds $1,000, with a target of $10,000 over the next 3–5 years. That target implies substantial revenue upside but also exposes risks around customer concentration, product transitions, and gross margins. The higher content value can be realized only if the new protocols enter volume-production racks.
PCB backplanes are one of the practical bottlenecks in current system deliveries. Supply-chain timing for NVIDIA’s Kyber racks has been affected by PCB backplane design and yield adjustments, illustrating how greater compute-platform complexity amplifies the impact of a single interconnect component on full-rack shipments. Board manufacturers and suppliers of connectors and substrates will benefit only if three conditions are met: designs are finalized, yields reach target levels, and customers accept the higher costs. Technical upgrades alone do not guarantee margin expansion.
Traditional electronic components provide modest cross-validation. Japan’s electronic-component shipments rose 15% year over year in May, while connectors maintained a moderate recovery; however, high-frequency components and electrode materials for multilayer ceramic capacitors were weaker sequentially. These data cannot be attributed entirely to AI, but they show that demand for connectivity, passive components, and materials is not rising in lockstep. Performance should remain sharply differentiated between suppliers with strong AI orders and those with greater consumer-electronics exposure.
Optical-interconnect orders are strong, but technology pathways should still be ranked by time to commercialization.
Data-Center Cooling, Power Systems, and Electricity
Power supply is shifting from a supporting requirement for data centers to a prerequisite for project execution. Compute chips, servers, and optical networks all have explicit shipment forecasts, but capital expenditure can remain stuck at the planning stage unless grid interconnection, backup power, rack-level distribution, and cooling scale in parallel. Analysis of the power value chain must focus on deliverable capacity, commissioning dates, and contractual responsibilities—not merely total data-center investment.
High-density racks link power and cooling constraints. Rubin, Helios, and larger ASIC clusters will increase power per rack, driving demand for power modules, busbars, liquid cooling, pumps, valves, and heat-exchange equipment. Server supply-chain tracking already identifies power racks, liquid cooling, and electrical equipment as major themes for the next 12 months. However, valuation multiples for relevant companies have recently compressed, as the market demands evidence that incremental orders can cover capacity expansion, certification, and after-sales service costs.
Supply-chain sources report that Bloom Energy and server manufacturer MiTAC are deploying a fuel-cell microgrid at an AI-server manufacturing campus in California. Bloom Energy has disclosed nearly 20 AI-infrastructure customers representing a project portfolio of approximately 250 MW. This suggests that on-site generation is beginning to move beyond backup power toward serving as a primary power source for some AI facilities, although the current stage is better viewed as validation of the business model. Key follow-up indicators include the share of projects commissioned, fuel costs, long-term service revenue, and whether customers continue adding capacity.
Europe is also using public funding to support AI infrastructure. The Spanish government has approved a €719 million investment through SETT in an AI gigafactory initiative, targeting approximately €5 billion in total project investment. Such projects can create demand for servers, power systems, and networking equipment, but their timelines depend on project selection, approvals, and construction progress. Suppliers should incorporate policy funding into revenue expectations only after receiving firm orders with defined delivery milestones.
Cooling requires the clearest distinction between design wins and profit realization. Inclusion of liquid cooling in a server design indicates only that a supplier has secured a qualification opportunity. Revenue and gross profit will emerge only after racks ship at scale, yields stabilize, and field-service costs become manageable. If a new platform is delayed by PCB or optical-interconnect issues, revenue recognition for liquid-cooling equipment may also be deferred. Key metrics for next week are rack power, liquid-cooling penetration, project megawatts, and initial commissioning dates.
Robotics, Edge AI, and Hardware Applications
The edge-AI opportunity is expanding beyond standalone chips into sensing, connectivity, and system-level certification, but commercialization is more difficult than in the cloud. Ambarella has strong edge-AI capabilities, and both automotive and consumer devices require low-power vision inference. The challenge is that large customers can develop solutions internally, while chip suppliers must bear long-term software-adaptation and certification costs. Unless technical leadership translates into stable design wins, it will remain difficult to support premium valuations.
Following its acquisition of Hailo, Microchip Technology has combined edge-AI capabilities with its connectivity, control, and data-center portfolio. The value proposition is that customers can purchase an integrated suite of compute, connectivity, and control solutions rather than a single AI chip. The relevant validation metrics are cross-selling revenue, the pace of new-customer adoption, and gross margins—not merely a more complete product portfolio.
Demand for robotics hardware is also constrained by market access. New US device-certification rules have limited impact on robot-vacuum models that have already been approved, which may continue to be imported, sold, and used. However, the authorization, launch, and sales timelines for new models remain uncertain. Manufacturers including Roborock and Ecovacs already have overseas production capacity, so the near-term sales impact may be limited, but new-product certification, channel inventory, and regional revenue trends still warrant monitoring over the medium term.
These developments show that risks in the robotics supply chain extend beyond algorithms and components. Access to major markets, the ability to adjust supply chains quickly, and whether certification costs can be recovered through pricing also determine commercialization speed. For suppliers of sensors, connectors, batteries, and motors, delays to OEM product launches will propagate upstream, while dependence on a single fast-growing customer may itself become a concentration risk.
Japanese electronic-component data provide a broadly neutral backdrop for hardware demand. May shipments totaled ¥353.3 billion, up 15% year over year but down 6% sequentially; connectors rose 15% year over year, while high-frequency components declined 7%. This points to a structural recovery rather than synchronized strength across all hardware categories. Edge-AI companies must demonstrate that the incremental per-device content from new AI capabilities can outweigh volatility in the traditional consumer-electronics cycle.
Space, Quantum Computing, and AI Software Applications
Space and quantum computing remain in a phase of rapid technological progress but limited revenue validation. Satellite networks continue to expand coverage and connectivity, but this week produced no major contracts directly tied to AI workloads, ground-station orders, or service revenue. For the AI value chain, space is better viewed for now as a long-term indicator of expanding network and compute boundaries, rather than placed at the same commercialization stage as optical communications and servers with established order backlogs.
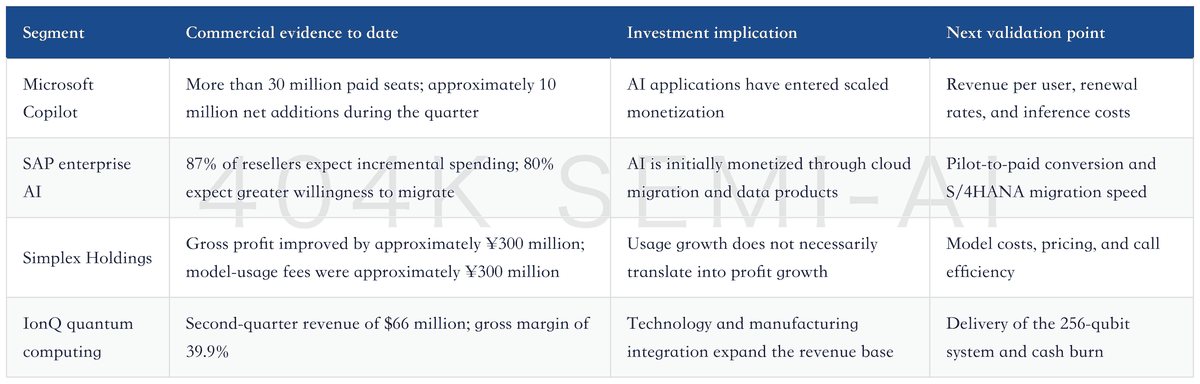
Quantum-computing milestones are increasing, but so are the financial costs. IonQ generated $66 million in second-quarter revenue. Following the SkyWater combination, 2027 pro forma revenue would be approximately $952 million, while the operating loss would remain approximately $517 million. The company plans to demonstrate a 256-qubit system by year-end and deliver it in the first half of the following year. Higher revenue does not by itself establish a clear path to profitability; integration costs, R&D; spending, and system delivery all require further validation.
D-Wave reportedly demonstrated approximately 99.9% fidelity for a two-qubit entangling gate in quantum-error-correction research, with a gate-operation time of approximately 500 nanoseconds, and outlined a roadmap to achieve 100 logical qubits by 2032. This is an important technical signal, but it remains far removed from repeatable commercial revenue. Investors should track peer-reviewed results, usable system deliveries, paying customers, and cash burn separately.
Enterprise software is already showing more direct evidence of monetization. Microsoft had more than 30 million paid Copilot seats at the end of the June quarter, adding approximately 10 million during the quarter—approximately 2 times the prior-quarter increase. AI applications typically offer better unit economics than underlying cloud compute because software can monetize existing customers and workflows. The next test is whether seat growth translates into revenue per user while covering inference and sales costs.
For SAP, AI is initially creating value by accelerating migrations rather than through sales of a standalone AI product. In channel surveys, 33% of resellers had already seen customers pay to adopt AI, while 53% remained in pilot programs.
87% of resellers expect AI to increase customer spending over the next 12 months, while 80% believe AI migration tools will increase customers’ willingness to move to S/4HANA. SAP says these tools can reduce migration costs by up to 30%. If AI shortens implementation cycles, its initial benefits will be faster cloud migration, lower service costs, and stronger renewal stickiness; standalone AI revenue may emerge later.
Simplex Holdings provides a counterexample to the software-profit thesis. AI features improved gross profit by approximately 2.3 percentage points, equivalent to approximately ¥300 million, but model-usage fees were also approximately ¥300 million over the same period, leaving the net contribution close to zero. The company can retain the product’s value only through model switching, call optimization, and cost controls. This is a common challenge across the application layer: customers’ willingness to use a product does not mean the vendor has found a high-margin monetization model.
Monetization has begun at the application layer, but profitability depends on inference costs and workflow stickiness.
Divergences, Disconfirming Evidence, and Next Week’s Watchlist
The first divergence concerns capital expenditure and investment returns. US equity strategy tracking suggests the AI capital-expenditure cycle still has substantial room to run, with AI adopters’ relative net margin improving by approximately 50 basis points over the past 3 months and standing approximately 400 basis points above the broader market. This supports continued demand expansion but also raises the market’s expectations: cloud providers must demonstrate that incremental depreciation, power, and equipment spending can drive faster revenue growth. If free cash flow continues to deteriorate without an acceleration in AI revenue, supplier orders will begin cooling at the forward-planning stage.
The second divergence concerns value allocation between GPUs and ASICs. A rising ASIC share helps cloud providers control costs and creates additional revenue opportunities for MediaTek, interconnect chips, HBM, and advanced packaging. However, GPUs still account for most of the compute market and retain advantages in software ecosystems, general-purpose capabilities, and iteration speed. Next week, investors should track ASIC shipments, HBM procurement metrics, advanced-packaging allocations, and supplier gross margins rather than focusing solely on chip volumes.
The third divergence concerns the timing of CPO adoption. Early production and customer deliveries demonstrate that the technology roadmap is advancing, but NPO’s maintainability and lower complexity make it more likely to generate broad-based revenue first. The signals that would materially change earnings forecasts are customer acceptance, sustained volume shipments, and higher gross margins for optical suppliers. If progress remains limited to prototypes and small-volume deliveries, CPO should still be valued as a long-term opportunity.
The fourth divergence is whether power constraints can translate into profits for equipment vendors. A portfolio of 250 MW-scale projects and investment in AI superfactories demonstrate underlying demand, but commissioning schedules, fuel prices, interconnection responsibilities, and operating and maintenance costs will determine profitability. Power-supply, liquid-cooling, and on-site generation companies need to disclose contracted capacity, capacity under construction, commissioned capacity, and service revenue; a standalone megawatt target is insufficient evidence of profitability.
The fifth divergence concerns software adoption versus software gross margins. Microsoft and SAP have provided data on seats, reseller activity, and migration intent, while Simplex Holdings shows that model-inference fees can absorb the entire improvement in gross profit. Next week, the most important metrics for application companies are not the number of new features, but paid conversion, revenue per user, inference costs, and renewal rates.
Next week’s monitoring should focus on indicators capable of disproving this week’s conclusions.
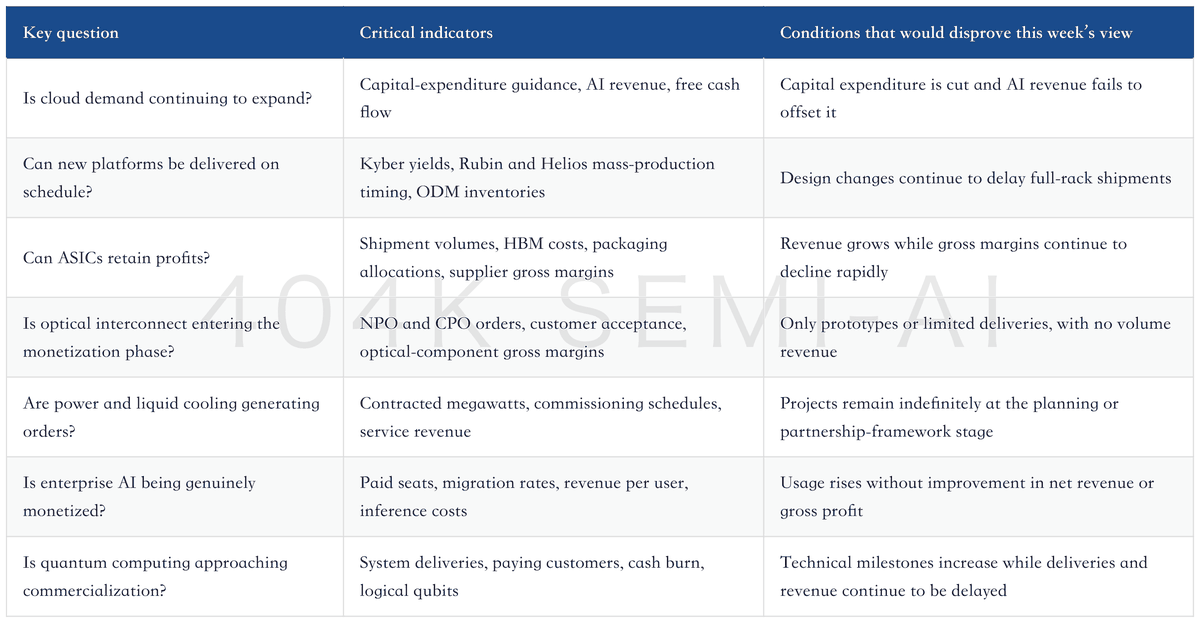
The constructive view on aggregate AI infrastructure demand can be maintained, but the same growth multiple should no longer be applied across the entire value chain. Optical interconnect, high-speed connectivity, and selected enterprise-software companies have provided more concrete order or payment data. ASICs, advanced packaging, power, and quantum computing still need to demonstrate that growth can overcome cost, yield, and delivery constraints. The next phase of excess returns is more likely to come from differences in monetization timing than from a broad-based thematic rally.