
404K SEMI-AI 2026-07-31 Semiconductor Equipment Weekly — Order Broadening: WFE Upgrades Flow Through to Process Control and Test; Deliveries and Gross Margins in Focus Next Week
目录
TL;DR
Overall View This Week
Front-End Wafer Fabrication Equipment
WFE Upgrades Continue, While Process-Control Intensity Rises Further
AMEC: Memory Capacity Expansion and Portfolio Expansion Jointly Determine the Revenue Trajectory
Subsystems and Consumables Begin to Follow Equipment-OEM Capacity Expansion
Metrology, Inspection and Test
KLA Demonstrates That Metrology and Inspection Are Outgrowing WFE
ATE Is Shifting From Cyclical Recovery to Growth in Test Content
Advantest Is Expanding Capacity Ahead of Demand, but Share Shifts Will Still Take Time
Advanced Packaging Equipment and Critical Materials
ASMPT’s Orders Are More Convincing Than Industry Rhetoric
Back-End Capital Expenditure Is Flowing Through to Bonding, Test and Optical Assembly
Company, Order and Capital-Expenditure Validation
Debates, Counterevidence, and What to Watch Next Week
Debate 1: Can the WFE Upgrade Translate Smoothly into Revenue?
Debate 2: Has the Process-Control Premium Already Been Fully Priced In?
Debate 3: Is ATE Growth Driven by Market Expansion or Share Redistribution?
Debate 4: When Will Advanced-Packaging Orders Reach the Income Statement?
The Six Numbers Most Worth Watching Next Week
This week, the equipment supply chain moved from aggregate upgrades to broader order growth, with front-end process control, automated test, and advanced packaging equipment strengthening in tandem. The market has already priced in growth; the next questions are whether backlogs can be delivered on schedule and whether gross margins can hold.
TL;DR
The wafer fabrication equipment (WFE) outlook continues to be revised upward, but the shift in spending mix is the most important development to track. KLA raised its 2026 WFE estimate from approximately $140 billion to approximately $150 billion and provided a reference baseline of approximately $190 billion for 2027. Its advanced-packaging process-control revenue is expected to increase from $635 million in 2025 to approximately $1.1 billion in 2026. More complex processes and additional packaging layers will both drive inspection and metrology equipment value to grow faster than wafer investment itself.
Order strength is already showing up in company financials. KLA’s backlog stood at approximately $12.5 billion at the end of June, up 60% YoY, with a book-to-bill ratio of 1.4x. Ultra Clean Holdings expects its existing capacity to approach full utilization by 1H27. ASMPT secured volume orders in July for more than 50 chip-to-substrate thermocompression bonding systems. The equipment supply chain’s main issue is shifting from “whether demand exists” to “whether capacity, lead times, and customer acceptance can keep pace.”
Automated test equipment (ATE) is entering a structural expansion. Teradyne believes ATE spending as a percentage of WFE could stabilize at 7%—9%, as chiplets, high-bandwidth memory, and AI processors increase test time and the number of test insertions. Advantest is accelerating V93K capacity expansion, while customer-demand visibility has extended from approximately 6 months historically to 18 months for many projects. Test demand is growing, but shifts in Teradyne’s and Advantest’s market shares still depend on customer qualification and validation through 2027 volume production.
Advanced-packaging equipment has progressed from a concept to actual orders. ASMPT’s Q2 gross margin and Q3 sales guidance both exceeded consensus expectations. Revenue from its photonics business was approximately $75 million in 1H26, rising to 3x the year-earlier level. The company expects co-packaged optics (CPO) equipment orders to become more meaningful in 2027—2028. Market reports also indicate that ASE Technology Holding has raised capital expenditure and increased ATE procurement, with back-end equipment demand broadening into bonding, optical assembly, and testing.
Risks have not disappeared. KLA shares still fell as much as approximately 8% after earnings, indicating that a high valuation requires continued upward revisions to absorb. Memory-related costs have already reduced its gross margin by more than 100 basis points. Ultra Clean Holdings’ supplier position may cause its earnings to peak before those of equipment OEMs, lead times for some ASMPT materials have lengthened, and Teradyne also faces new-product ramp and product-mix pressure in Q4. Next week, investors should prioritize order-to-revenue conversion, delivery cycles, gross margins, and customer qualification, rather than focusing only on capital-expenditure headlines.
Overall View This Week
The clearest change in semiconductor equipment this week is that demand is no longer confined to the aggregate level of fab capital expenditure. Advanced logic, DRAM/HBM, NAND, advanced packaging, and testing are all increasing equipment content, and orders are beginning to broaden into process control, subsystems, consumables, and back-end testing.
KLA provided the most representative industry benchmark. The company raised its 2026 WFE estimate to approximately $150 billion from approximately $140 billion previously; for 2027, it provided a reference baseline of approximately $190 billion, representing approximately 25% YoY growth. This assessment is not supported solely by long-range plans. The company’s backlog stood at approximately $12.5 billion—$12.6 billion at the end of June, up 60% YoY, with a book-to-bill ratio of 1.4x, average lead times of approximately 12 months, and lead times of 18—24 months for some products.
Upstream demand has not weakened either. Google raised its 2026 capital-expenditure guidance to $195 billion—$205 billion and said spending would increase significantly again in 2027. Related estimates raised industry-wide capital expenditure to $1.34 trillion in 2027 and $1.48 trillion in 2028. Cloud-provider spending will not translate one-for-one into equipment revenue, but it continues to drive custom chips, advanced-process, memory, and packaging capacity, providing the underlying demand base for longer equipment-order visibility.
This week’s signals strengthened progressively along the chain of “fab investment—equipment OEMs—subsystems and consumables—packaging and testing.”
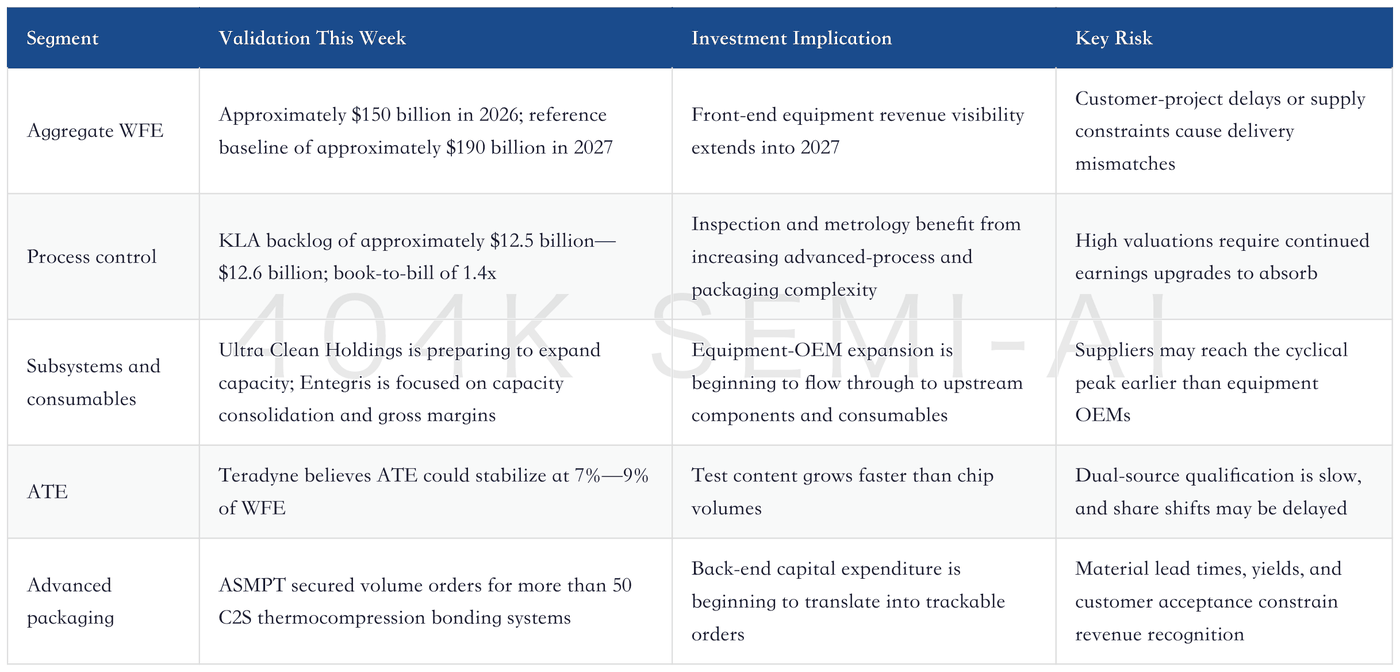
Accordingly, the best way to track the sector now is not to treat every equipment company as part of the same aggregate-volume trade. Process control offers stronger content growth, test equipment benefits from longer test times and more insertions, while advanced-packaging equipment depends on customer capacity expansion, orders, and acceptance. Subsystem and consumables companies offer greater operating leverage, but their cyclical and gross-margin risks also emerge earlier.
Front-End Wafer Fabrication Equipment
WFE Upgrades Continue, While Process-Control Intensity Rises Further
KLA’s June-quarter revenue was $3.66 billion, up 15% YoY and 7% QoQ. Non-GAAP gross margin was 62.4%, and EPS was $1.05, both above prior guidance or market expectations. The midpoint of September-quarter revenue guidance is $4.0 billion, implying approximately 9% QoQ growth. The company also expects 2H26 revenue to grow approximately 20% versus 1H26.
More important is the revenue mix. Advanced-logic investment is moving from 3-nanometer capacity expansion into an accelerated 2-nanometer ramp, DRAM/HBM and NAND investment are increasing simultaneously, and 2.5D packaging is progressing toward higher levels of integration. The higher the wafer value and the greater the number of process steps, the more customers are willing to pay for defect inspection and process stability. KLA expects advanced-packaging process-control revenue to increase from approximately $635 million in 2025 to approximately $1.1 billion in 2026, representing growth of more than 70%.
