
404K SEMI-AI 2026-07-31 Memory Weekly — Locked Volumes Spread: HBM Long-Term Contracts Spill Over into SSDs and HDDs, While Cost Pass-Through Awaits Demand Validation
目录
Too Long; Didn't Read
Overall Assessment This Week
Developments This Week
Weekly Performance of Memory-Related Stocks
DRAM/HBM: Supply Control, Long-Term Agreements, and Customer Qualification
LPDDR/SoCAMM: Spillover from AI CPUs and Rack-Level Memory
NAND/eSSD/SSD: Inference, RAG, and Enterprise SSD Upside
HDD: AI Data Lakes, Nearline Exabytes, and Cash Flow
Equipment, Testing, and Materials: Second-Order Beneficiaries of Memory Capex
Downstream Costs and Demand Destruction: Servers, Networking Equipment, Smartphones, PCs, and EVs
Investment Ranking, Risks, and Falsification
What to Watch Next Week
The dominant development this week was memory vendors further embedding price increases into long-term contracts, capacity allocation, and customer qualification. HBM offers the highest certainty, eSSD the greatest upside, and HDD the strongest cash flow; the real risks have shifted to whether end demand can absorb the costs and when incremental supply will materialize.
Too Long; Didn't Read
The key battleground in DRAM/HBM has shifted from quarterly price increases to volume lock-ins and qualification. The multi-year partnership between Samsung Electronics and Broadcom links HBM, foundry, and AI-chip revenue into a longer contractual chain; SK hynix has signed approximately 10 long-term agreements and introduced performance mechanisms such as deposits. Investors should prioritize vendors that can convert HBM4 yields, customer qualification, and long-term supply volumes into stable cash flow, rather than focusing only on how much further spot prices can rise.
AI inference is extending memory demand beyond HBM into DDR5, LPDDR5, SoCAMM, CXL, and enterprise SSDs. KV cache requires capacity, bandwidth, and low latency, but does not need to reside entirely in the most expensive HBM. Frequently accessed data remains in HBM and DRAM, while colder data moves down into CXL memory pools and SSDs. This means inference-efficiency gains may not reduce memory demand and could instead expand the economically viable scale of retained context and data.
NAND/eSSD offered the greatest upside this week, but also generated the widest divergence of views. SK hynix identified AI servers and eSSD as sources of structural demand; Kioxia’s enterprise SSD mix, ASP, and margins continued to strengthen. The counterevidence is equally clear: if new capacity comes online faster than enterprise demand while smartphone and PC vendors continue cutting configurations, NAND will return to oversupply before DRAM.
HDD has simultaneously delivered demand visibility, pricing, and free cash flow. Most of Seagate Technology’s nearline capacity has been allocated through 2028, while customer planning extends beyond 2029; HAMR increases capacity per drive and lowers unit costs. The HDD investment case therefore rests on disciplined duopoly supply, build-to-order production, nearline EB growth, and buybacks—not on treating HDD simply as a lower-cost substitute for NAND.
Equipment, testing, and materials are second-order beneficiaries of the spread in volume lock-ins. Order visibility is extending for HBM testing, advanced packaging, ABF substrates, and high-layer-count PCBs, but revenue recognition depends on equipment delivery, customer qualification, yields, and utilization. Unimicron Technology’s capacity expansion and margin improvement already have operating evidence; for test equipment, delivery schedules and second-source qualification still require verification, and capacity-expansion plans should not be treated directly as revenue.
Downstream cost pass-through is beginning to determine the slope of demand. Apple can still absorb part of the increase in memory costs through its brand, product mix, and price increases, while mainstream PC and smartphone brands face greater demand elasticity. If brands broadly begin cutting memory and storage configurations and delaying procurement, memory prices may continue to rise, but volumes and end-market shipments will be hit first; this will be the primary thesis-invalidating signal from next week onward.
Overall Assessment This Week
The memory cycle is moving from “price increases” into “allocation of supply priority.” Vendors that secure advanced process capacity, packaging, testing, and customer qualification first can prioritize scarce wafers for HBM, server DRAM, and enterprise SSDs; those able to lock in pricing, configurations, and deposits through long-term agreements will experience lower earnings volatility. This shift simultaneously constrains available supply of commodity DRAM, client NAND, and low-end products, while pushing cost pressure downstream into smartphones, PCs, and consumer electronics.
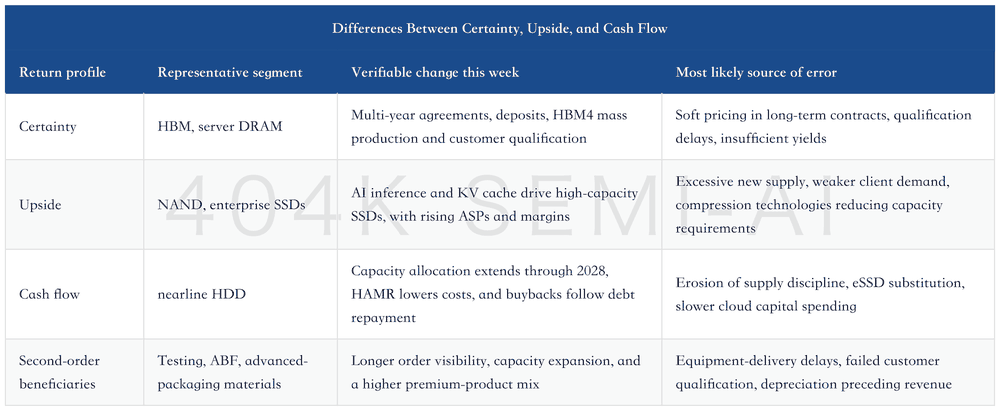
The value chain can be divided into three return profiles this week. HBM and high-end DRAM offer customer lock-in and long-term agreements; NAND and enterprise SSDs offer leverage to ASP and product mix; HDD offers a duopoly, build-to-order production, and free cash flow. Equipment, testing, and materials are second-order beneficiaries: they do not directly capture memory pricing, but receive more orders when memory vendors expand capacity, upgrade nodes, and increase testing intensity.
These three return profiles correspond to different sequences in financial reporting. For HBM, assess customer qualification and product mix first, followed by pricing and gross margin; for enterprise SSDs, examine bit shipments and pricing together to distinguish genuine demand from simple shortages; for HDD, infer supply discipline from the combination of pricing, inventory, and free cash flow. Looking only at current-period earnings would mistakenly treat all three theses as the same cyclical trade.
Investment priorities should also move with the evidence. Qualification, deposits, and firm purchase volumes support certainty; pricing and premium-product mix support upside; build-to-order production and shareholder returns support cash flow. If these indicators do not improve in the same direction, share-price appreciation is more likely driven by positioning and valuation changes and should not be directly elevated into an industry call.
When the three categories of signals conflict, priority should be given to collectible orders, completed customer qualifications, and free cash flow already generated. Quotations, capacity targets, and long-range customer plans remain informative, but they are further removed from the income statement and more susceptible to revision when demand or qualification changes.
Valuations should not simply follow upward earnings revisions. The divergence over Seagate Technology is the clearest example: multiple institutions have raised forward earnings estimates, but their target P/E multiples range from 8x to 24x. The real market debate is whether supply discipline and long-term contracts in this cycle can support a more durable valuation for cyclical stocks, or whether multiples should compress as earnings approach their peak.
The counterevidence this week was also more specific than before. First, SK hynix’s long-term agreements improve visibility but may restrain near-term ASP increases. Second, Apple has already identified memory costs as a pressure on gross margin, while mainstream brands have less capacity to absorb them. Third, NAND faces a scenario in which incremental supply in 2027 outpaces consumer demand. Fourth, CXL memory pools, KV cache compression, and more efficient models will change the share captured by each storage tier rather than guarantee synchronized growth across all categories.
Developments This Week
July 27: Supply access began to be quantified through multi-year contracts. The partnership between Samsung Electronics and Broadcom covers memory and advanced foundry services. JPMorgan estimates that Samsung Electronics may supply approximately 75%—85% of Broadcom’s future HBM requirements, with purchases of Samsung products associated with the partnership exceeding US$200 billion.
Based on the estimated purchasing structure, 90%—95% may come from HBM. The partnership ties together AI-chip revenue, HBM procurement, and foundry capacity, indicating that leading customers are locking in multi-year supply in advance.
On the same day, a clear contrast also emerged in downstream cost pressure. Goldman Sachs observed that Apple continued gaining share even as the broader industry raised prices in response to memory-cost inflation, while protecting gross margin through its premium product mix, in-house component development, and selective price increases. This shows that higher memory prices do not affect all brands equally: the stronger the brand loyalty and the higher the product ASP, the greater the ability to pass costs on to customers.
July 28: HDD moved from supply-demand tightness to realized earnings and capital returns. Seagate Technology’s quarterly revenue, gross margin, and EPS all exceeded market expectations, while pricing per EB rose approximately 11% year over year. The company expects the pricing trend to continue through fiscal 2027 and plans to redirect capital allocation toward buybacks after repaying high-yield debt. HAMR is no longer merely a technology narrative, but a shared driver of unit costs, incremental margins, and free cash flow.
July 29: DRAM/HBM, HDD, and ABF simultaneously delivered operating validation. SK hynix generated KRW79.32 trillion in revenue and KRW60.54 trillion in operating profit, with its operating margin reaching 76%. HBM4 shipments have begun, while approximately 10 long-term agreements now incorporate pricing and deposit mechanisms.
Seagate Technology extended the allocation of most nearline capacity through 2028, with customer planning extending further. Unimicron Technology validated improvements in ABF pricing, utilization, and product mix through a quarterly gross margin of 24.8%.
July 30: Second-order beneficiaries shifted from narrative to orders and capacity. Asian technology-sector tracking indicates that memory TCB revenue is expected to reaccelerate following HBM4 delays, while AI inference is simultaneously driving ASIC, CPU, and DRAM testing demand; Advantest plans to expand tester capacity more rapidly. KLA’s expected revenue from process control for advanced packaging also continues to rise. For the equipment chain, the confirmation sequence should be orders, delivery, qualification, utilization, and only then profit.
Weekly Performance of Memory-Related Stocks
Share-price performance this week did not fully align with fundamentals. Memory-themed ETFs and NAND names posted larger declines, Western Digital edged higher, and Seagate Technology was nearly flat. Among Korean and Japanese stocks, Samsung Electronics rose, while SK hynix and Kioxia declined. This reflects positioning, expectations, and the pace of earnings realization, and should not be used as a direct substitute for industry analysis.
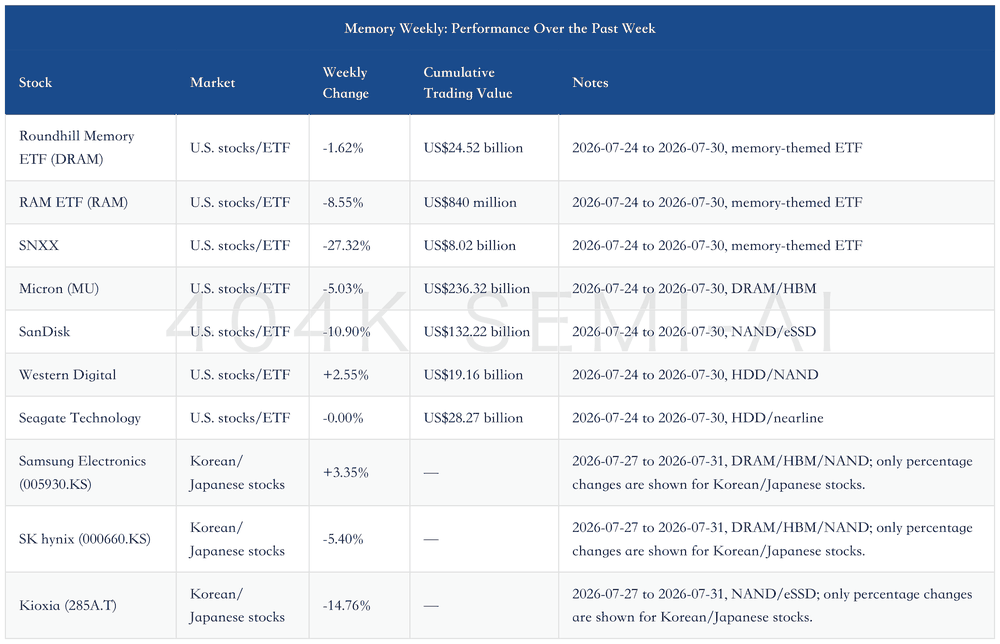
The categories with the largest declines also happen to offer the greatest earnings leverage. Kioxia, SanDisk, and NAND-themed names faced concerns over pricing peaks and incremental supply; DRAM/HBM names were repriced amid high profitability, capital expenditure, and competitive market-share dynamics. For investors, near-term price pullbacks only improve the risk-reward; they cannot replace verification of contract quality, supply discipline, and end demand.
DRAM/HBM: Supply Control, Long-Term Agreements, and Customer Qualification
HBM’s visibility comes from simultaneous tightening across three areas: advanced DRAM wafers, base dies, and advanced packaging. Samsung Electronics’ multi-year partnership with Broadcom shows that major customers are securing not only finished HBM products but also foundry capacity.
