
404K SEMI-AI 2026-07-31 M7 and CSP Weekly — Financing Shifts Gears: Cloud Revenue Accelerates, Capex Guidance Rises, and Cash Flow and Debt Issuance Face Scrutiny
目录
TL;DR
Overall View This Week
Cloud Revenue and AI Capex
Data Centers, Compute Procurement, and Custom Chips
Model, Software, and Application Monetization
Divergence Between M7 and Neocloud Providers
Points of Debate, Disconfirming Evidence, and Next Week’s Watchlist
The clearest change this week is that AI cloud demand remains strong, but capex funding is shifting from “covered by cash flow” toward “supported by debt, leasing, and project financing.” The slower revenue materializes, the sooner financing costs and depreciation hit the income statement.
TL;DR
Demand signals from Google, Amazon, and Microsoft remain strong. Google’s quarterly capex doubled year over year to $44.9 billion, and the company raised its 2026 guidance to $195 billion–$205 billion; AWS grew 36.7% in Q2, yet Amazon still said capacity was insufficient despite planning approximately $220 billion in cash capex. Demand for AI infrastructure is not contracting; what the market is reassessing is the pace of investment payback.
Meta best illustrates how “revenue realization” and “cash-flow pressure” can occur simultaneously. Q2 revenue was $60.801 billion, up 28% year over year; the company narrowed its 2026 capex range to $130 billion–$145 billion. Free cash flow during the period was only $784 million, while infrastructure, depreciation, data-center operations, and third-party AI token costs all increased. Advertising AI has already proven it can generate revenue, while consumer AI and external compute-capacity rentals still require more evidence.
The financing model for five hyperscale cloud providers is shifting gears. Goldman Sachs estimates that direct debt financing as a share of capex will rise from 33% in 2026 to 35% in 2027. The five companies have also disclosed $1.2 trillion in lease obligations, of which $725 billion has not yet commenced. Debt capacity remains substantial, but credit ratings, spreads, and project-financing pricing will increasingly have a direct impact on equity valuations.
Custom silicon has evolved from a cost-reduction tool into a capacity and financing tool. Google is using TPUs to fulfill its $514 billion Google Cloud backlog while securing long-term supply; Amazon is using Trainium to obtain multiyear, multi-gigawatt commitments from Anthropic and OpenAI; partnerships between NVIDIA and SK Group, and between Broadcom and Samsung Electronics, show that leading chip companies are securing HBM, foundry capacity, and advanced packaging in advance. The aggregate value of these partnerships does not equal confirmed revenue; the next variables to watch are purchase orders, capacity ramp-up, and revenue recognition.
Three monetization paths have emerged at the application layer. Microsoft is embedding AI into Azure, Microsoft 365, and security products; Meta is seeking incremental revenue through advertising recommendations, business agents, subscriptions, APIs, and rentals of surplus compute capacity; Apple is using iCloud+, AppleCare+, and device upgrades to monetize AI features. Cloudflare is gaining share in edge inference, but surveys indicate that scaled adoption will still occur mainly in 2027, and is not yet sufficient in the near term to overturn hyperscalers’ distribution and funding advantages.
The most important validation next week is not “whether capex will rise again,” but whether three sets of metrics can improve simultaneously: cloud revenue and backlog conversion, free cash flow and depreciation pressure, and the cost of debt issuance and project financing. If revenue growth continues to accelerate while financing costs remain stable, the AI cloud investment cycle can continue; if capex guidance rises, free cash flow turns negative, and credit spreads widen simultaneously, valuations will decline before demand estimates are revised downward.
Overall View This Week
AI cloud investment has entered a phase in which “demand is abundant, but money is becoming more expensive.” Previously, the market debate focused primarily on whether there were enough GPUs, sufficient power, and whether data centers could be delivered on schedule. This week added a new question: when capex grows faster than operating cash flow, who will provide the next tranche of funding, who will bear leasing and project risk, and when will returns flow through the income statement?
This is not evidence that demand has peaked. Growth in Google Cloud backlog, AWS acceleration, Microsoft cloud revenue, and Meta advertising all indicate that customers are still purchasing compute capacity and AI services. The real divergence lies in funding structures. Microsoft has a relatively ample cash-flow buffer; Google, Amazon, and Meta continue to expand investment; Oracle and neocloud providers are more dependent on external financing, leasing, and anchor customers. The same revenue growth may ultimately correspond to entirely different free-cash-flow profiles and valuation multiples.
This week’s operating signals from five representative companies can be summarized in one table.
Cloud revenue is accelerating, while capex and income-statement pressure are also rising
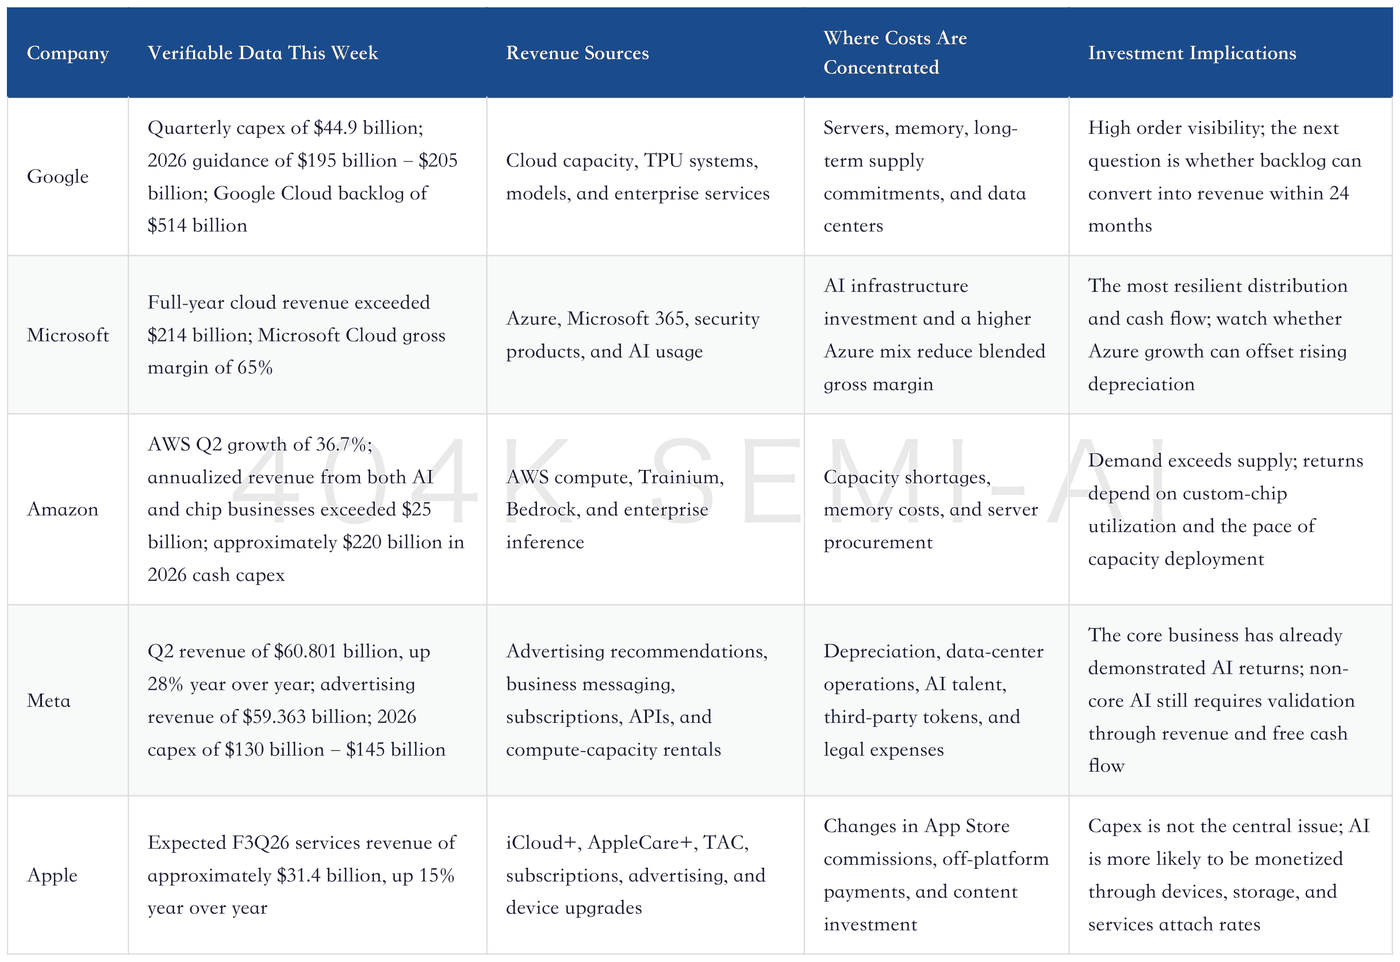
The timing mismatch is the easiest factor to overlook in the table. Capex is incurred when equipment is delivered; depreciation and operating expenses subsequently enter the income statement; cloud revenue must wait for capacity to come online, customer migrations, and usage ramp-up. Goldman Sachs’ summary of cloud-provider management commentary indicates that the lag from investment to monetization may range from 3 months to 2 years. As long as revenue recognition lags spending, free cash flow will come under pressure first.
Cloud Revenue and AI Capex
Google has taken demand visibility to a new scale. Quarterly capex doubled year over year to $44.9 billion, while 2026 guidance was raised by $15 billion to $195 billion–$205 billion. Management also expects investment to increase significantly in 2027.
Based on this, UBS raised its estimates for Google’s 2026 and 2027 capex growth to approximately 125% and 72%, respectively. More importantly, Google Cloud backlog reached $514 billion, up 385% year over year, and is expected to convert gradually into revenue within 24 months.
Google’s risk does not lie in order volume, but in delivery and tied-up capital. The company disclosed $707 billion in future guaranteed purchase commitments, most extending through 2030. UBS believes a substantial portion may be used to secure memory and TPU supply. Purchase commitments can ensure capacity, but they also commit future cash flow in advance. If TPU deliveries slow, customer deployments are delayed, or project-financing costs rise, backlog quality will matter more than its aggregate value.
Amazon’s signal is more direct: AWS grew 36.7% year over year in Q2, its fastest growth in 18 quarters. Annualized revenue from both the AI business and the chip business exceeded $25 billion; Trainium secured multiyear, multi-gigawatt commitments from Anthropic and OpenAI; and Amazon Bedrock already has hundreds of thousands of customers. At the same time, Amazon raised its 2026 cash capex to approximately $220 billion and said that even with this level of investment, it would still be unable to meet all demand in 2026 and 2027.
