
404K SEMI-AI 2026-07-31 AI Supply Chain Weekly — Compute Broadens Out: Cloud Spending Flows into Optical Interconnects, Packaging, and Power; Deliveries and Financing Costs in Focus Next Week
目录
Executive Summary
Overall View This Week
AI Chips, Advanced Packaging, and Servers
Optical Communications, CPO, PCBs, and High-Speed Interconnects
Data-Center Cooling, Power Equipment, and Electricity
Robotics, Edge AI, and Hardware Applications
Space, Quantum Computing, and AI Software Applications
Divergences, Counterevidence, and Next Week’s Watchlist
Cloud providers continue to raise capital spending, and demand has not receded, but investment is beginning to spread from GPUs into servers, optical interconnects, advanced packaging, and power and cooling infrastructure. The real risks are deferred deliveries and rising financing costs; next week, the focus will first be on Advanced Micro Devices (AMD) volume ramp-up, supply-chain deliveries, and project-debt spreads.
Executive Summary
AI infrastructure demand is still accelerating, but the beneficiary set has shifted. According to supply-chain sources, aggregate 2026 capital spending by major U.S. cloud providers is expected to rise to approximately $750 billion, up 79% year over year in the June quarter. More importantly, results from Celestica, Corning, Amphenol, Unimicron, and Teradyne show that incremental spending is flowing into server systems, 800G/1.6T networking, connectors, ABF substrates, and test equipment. Chips remain the starting point, but supporting systems are beginning to determine the pace of revenue realization.
Server and GPU demand is strong, but delivery capacity deserves closer monitoring than orders. Celestica reported second-quarter revenue of $4.699 billion, approximately 8% above institutional forecasts, with communications and enterprise revenue growing approximately 62% and 167% year over year, respectively. Sell-side analysts expect initial AMD Helios shipments in September, with customer volume ramp-up potentially extending from the second half of 2026 through 2027. If deliveries of servers, HBM, wafers, or racks become misaligned, orders will not disappear, but revenue will be pushed into subsequent quarters.
Cross-rack connectivity is rapidly shifting toward optics, while copper is not exiting immediately. Short-distance electrical connectivity within a single rack retains cost and maintenance advantages. Once deployment expands across multiple racks, however, signal loss, power consumption, and distance begin to increase the value of optical engines, lasers, and fiber. Corning’s enterprise network revenue grew 65% year over year, while generative-AI-related sales nearly doubled; Amphenol is benefiting from both copper connectivity and fiber. Over the next 1–2 quarters, investors should first monitor 800G supply and the 1.6T ramp rather than prematurely treating CPO’s long-term opportunity as current-period revenue.
Advanced packaging, substrates, and testing are entering a phase in which customers are locking in capacity, while 2028 supply risks are also accumulating. Unimicron’s second-quarter ABF revenue grew 22% quarter over quarter, gross margin rose to 24.8%, and capital spending was raised to NT$53.7 billion; in July, ASMPT secured a volume order for more than 50 chip-to-substrate thermocompression bonding systems. Demand strength is already visible, but EMIB-T still needs yield improvements, CoPoS still needs to address warpage and equipment uniformity, and Unimicron’s capacity expansion could also lead to temporary oversupply in 2028.
Power and cooling have the strongest orders but are also the segments where revenue realization is most easily deferred. Vertiv reported second-quarter revenue of $3.274 billion, below market expectations, primarily because of supply-chain congestion and the delivery cadence of complete solutions; profit and full-year guidance remained strong. Liquid cooling is shifting from low-temperature refrigeration toward higher-temperature cooling water and cold-plate designs closer to the chip, increasing equipment content, but supplier revenue still depends on complete component availability, acceptance, and commissioning.
Financing risk is beginning to diverge from industry fundamentals. AI-related high-yield bonds accounted for approximately 25% of primary issuance in the second quarter, and some 2027 projects may be delayed by constraints in power, equipment, and labor. Financing markets have not closed, but higher coupons and wider spreads will first compress returns for highly leveraged data-center projects. Industry momentum can continue to improve, while equity and credit assets may diverge because of differences in cash-flow duration.
Robotics, quantum computing, and AI software are all commercializing, but the strength of the evidence varies considerably. Industrial robots already have sales and market-share data, while surgical robots are also generating overseas orders, installations, and procedure volumes; humanoid robots still need to demonstrate unit economics through productive operating hours, human-intervention rates, and repeat purchases. Quantum network optimization has produced early enterprise use cases, while AI software is moving from usage growth into monetization validation. Next week, priority should be given to actual revenue, gross margin, and customer renewals—not demonstration counts or long-term market-size projections.
Overall View This Week
The most important development this week is that AI capital spending has not stopped because of rising financing costs. Instead, it continues to flow from cloud providers’ balance sheets into a longer physical supply chain. Demand-side signals are broadly consistent: cloud usage and remaining performance obligations remain strong, revenue growth is accelerating at server, networking, and connector companies, and advanced-packaging and substrate manufacturers are beginning to secure capacity through prepayments, long-term agreements, and joint investments.
Supply, however, is not expanding in sync. GPUs, HBM, server systems, optical modules, substrates, connectors, cooling, and power infrastructure must all be available together within the same project. If any link is delayed, end-customer demand remains intact, but supplier revenue may be deferred. Vertiv’s “revenue miss, profit beat” this quarter is a typical example: demand and backlog were not weak, but project stages and component completeness constrained current-period deliveries.
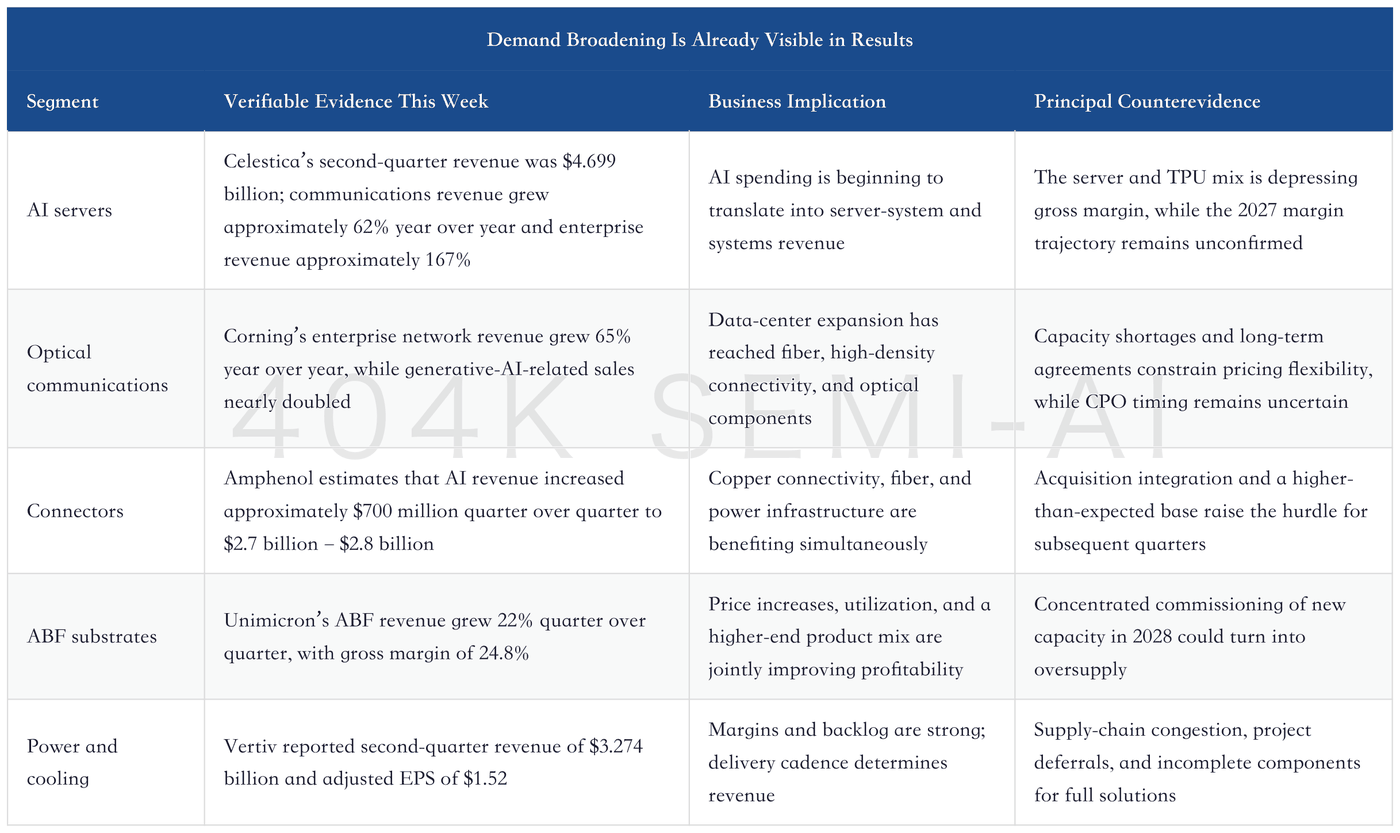
From an investment perspective, it is no longer sufficient to ask whether AI capital spending is rising. More useful questions are: which segment receives the money first, who can deliver on time, who must expand capacity first, and who bears customer-financing or project-delay risks. Servers, optical communications, connectors, advanced-packaging equipment, and power and cooling are currently closer to orders and capacity bottlenecks, giving them higher revenue visibility; long-term technology pathways and highly leveraged projects offer greater valuation sensitivity but also carry higher execution risk.
AI Chips, Advanced Packaging, and Servers
GPU demand remains strong, but competition is shifting from individual-chip specifications toward full racks and supernodes. Pre-earnings forecasts for AMD show that sell-side analysts expect AI GPU revenue of $14.5 billion in 2026, rising to $33.0 billion in 2027. Initial Helios shipments are scheduled to begin in September, and MI455X uses 2-nanometer and 3-nanometer processes with 432GB of HBM. The key issues to validate are not roadmap specifications, but whether initial racks can be delivered on schedule, whether customers can continue expanding from 1GW-scale deployments, and whether the GPU mix will depress gross margin.
Celestica has already provided validation through systems-level results. Second-quarter revenue was approximately 8% above institutional forecasts, with communications, enterprise, and ATS all exceeding expectations; adjusted EPS of $2.54 also beat forecasts. The server and TPU revenue mix left gross margin slightly below institutional expectations, but volume leverage lifted operating margin to 8.22%. This shows that the revenue growth trajectory for AI servers is strong, while margins depend on product mix, customer bargaining power, and manufacturing efficiency.
Broadcom’s long-term view is more aggressive. Based on the memorandum of understanding between Samsung Electronics and Broadcom, JPMorgan estimates that Broadcom’s cumulative AI revenue from 2026–2030 could exceed $1 trillion. This figure is a scenario estimate based on HBM procurement share, foundry procurement mix, and market share, and should not be treated as an order. Its useful implication is that demand for HBM and advanced foundry capacity from ASICs and switching and routing chips may remain structurally linked over the long term; the actual validation points are customer-project progress, Samsung Electronics’ realized supply share, and revenue growth after 2028.
Technology competition in advanced packaging is also shifting from “whether capacity exists” to “who can produce larger packages at acceptable yields.” Research reports estimate that the advanced-packaging market could grow from $19 billion in 2026 to $122 billion in 2030. Intel’s EMIB-T has a simpler structure, lower costs, and better scalability for very large packages, while TSMC’s CoPoS is stronger in interconnect density, signal integrity, 3D stacking, and future CPO integration. Both pathways can grow; the difference is whether customers prioritize cost and a second source, or performance and high-volume manufacturing reliability.
Packaging expansion will continue to channel spending into substrates, bonding, and testing. Unimicron’s second-quarter ABF revenue grew 22% quarter over quarter, while capital spending was raised from NT$34.0 billion to NT$53.7 billion; in July, ASMPT secured orders for more than 50 chip-to-substrate thermocompression bonding systems, while first-half photonics revenue was approximately $75 million, increasing to 3 times the prior-year level. Teradyne, meanwhile, believes automated test equipment spending may stabilize at 7%–9% of wafer-fabrication equipment spending because test intensity is increasing for chiplets, AI processors, and memory.
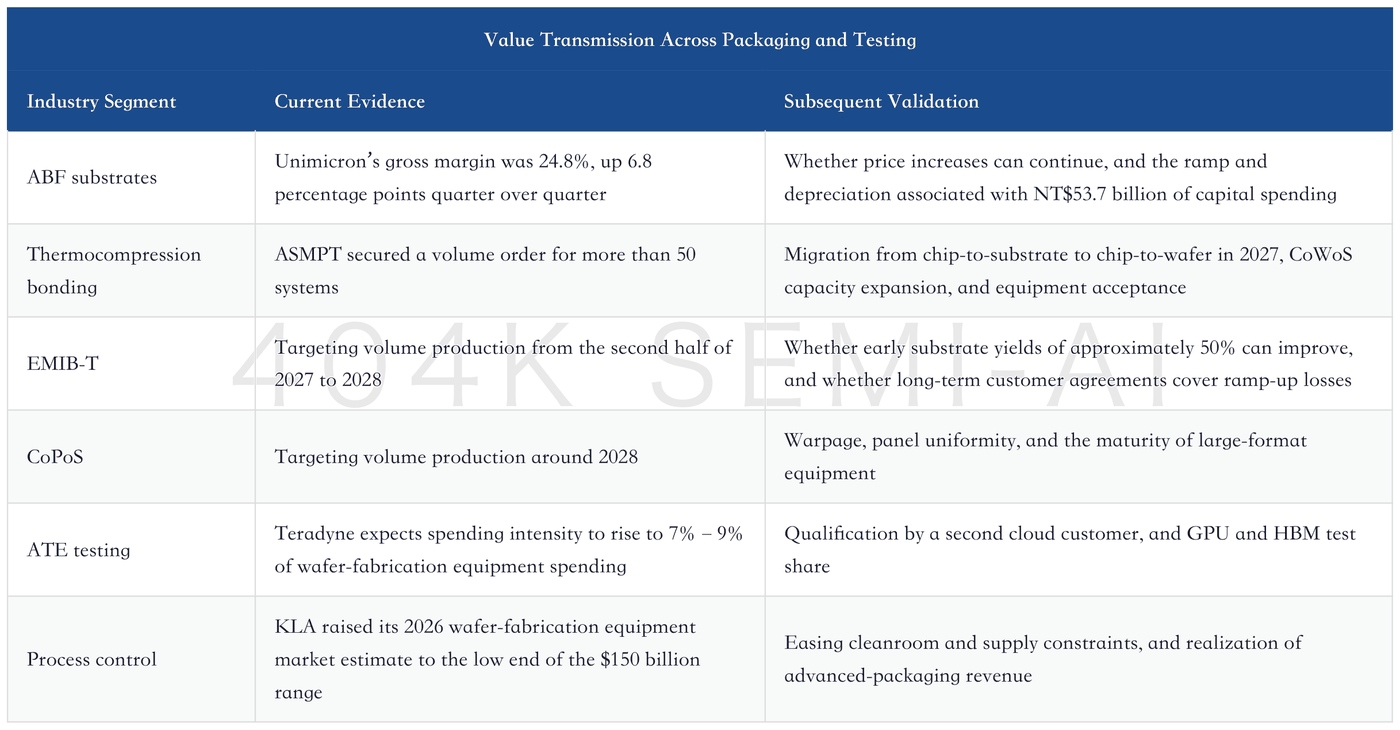
Risks also need to be incorporated into models in advance. Unimicron expects to continue expanding capacity at the end of 2026 and through 2027, while new industry capacity could create oversupply in 2028. EMIB-T, CoPoS, and glass-core substrates all face technology and reliability issues. Current customer prepayments and long-term agreements reduce suppliers’ near-term risks, but may concentrate more capacity additions within a similar timeframe. By the second half of 2027, pricing, utilization, and depreciation will matter more than capacity-expansion announcements.
Optical Communications, CPO, PCBs, and High-Speed Interconnects
This week, expectations for optical communications translated into actual results. Corning’s Optical Communications revenue increased 32% year over year, Enterprise Networks revenue grew 65%, sales of generative AI-related products nearly doubled, and segment net income was approximately 1.8 times the prior-year level. Management also said demand exceeded available capacity. For now, the most direct beneficiaries remain data-center scale-out, high-density connectors, and pluggable optical modules; CPO has yet to become a major contributor to current-period revenue.
Supernode architectures explain why copper and optics can grow simultaneously. Short-distance electrical connections within a single rack are low-cost and easy to integrate, and remain the preferred choice for most systems. When nodes scale across racks, the reach, signal loss, and power consumption of copper connections become constraints, increasing the value of optical interconnects. Morgan Stanley’s system comparison shows that multiple platforms have already incorporated 64—1024 accelerators into a single scale-up domain, with some architectures expanding further. The larger the scale, the greater the aggregate content of PCIe retimers, switch chips, optical engines, and high-speed cables.
Amphenol’s results show that this is not an either-or architectural choice. The company reported second-quarter revenue of $8.758 billion and earnings per share of $1.31 excluding one-off effects, both above market expectations. Goldman Sachs estimates that its AI revenue increased by approximately $700 million quarter over quarter to $2.7 billion—$2.8 billion; both copper connectivity and fiber-optic products grew. Customers choose different solutions depending on distance, power consumption, and maintenance requirements, and suppliers capable of providing copper, optical, and power connectivity are better positioned to capture architectural transitions.
CPO carries high content value, but commercialization will still unfold in stages. Supply-chain teardowns indicate that one CPO switch assembly has a total value of approximately $83,200, with 1.6T optical engines accounting for 43% and external laser-source modules for 22%. This is a market teardown, and the specific procurement volumes have not been cross-verified or confirmed by the research reports reviewed in this round; it can only be used to understand the BOM structure and cannot be used to directly infer company revenue. In 2026, investors should focus more on 800G and 1.6T pluggable products, before turning to CPO equipment orders and heterogeneous-integration yields in 2027—2028.
Demand for PCBs and substrates is also upgrading. AI accelerators, server CPUs, optical modules, and switches are simultaneously raising requirements for layer counts, size, and materials, causing ABF, HDI, mSAP, and low-loss materials to consume more capacity. Unimicron’s data-center revenue contribution increased from 47% in the prior-year period to 61%, and the company expects AI’s contribution to rise further in the second half of 2026. Price increases for high-end products and long-term customer agreements support profitability, but certification of materials such as T-glass fiber, yields at new plants, and supply in 2028 are three variables that must be tracked simultaneously.
Data-Center Cooling, Power Equipment, and Electricity
Data-center demand is strong, but revenue from power and cooling is particularly vulnerable to project-delivery delays. Vertiv reported second-quarter revenue of $3.274 billion, approximately 3% below market expectations; adjusted earnings per share were $1.52, approximately 7% above market expectations. Revenue in the Americas fell short of expectations, while Asia-Pacific and Europe, the Middle East, and Africa performed better. The company attributed the issue to supply-chain congestion, project phasing, and the availability of all components required for complete solutions, and raised the midpoint of its full-year revenue guidance to $14 billion.
These figures show that backlog cannot be directly equated with current-period revenue. Power distribution, cooling, racks, busways, and control systems must arrive together, and projects must also complete construction, commissioning, and acceptance. If Vertiv can resolve the congestion in the second half, margins and backlog can continue to convert; if the issues persist, revenue will continue to be deferred, and customers may also split procurement or seek a second supplier.
The direction of liquid-cooling technology is changing the equipment mix. According to supply-chain sources, next-generation Rubin infrastructure may operate with inlet water at approximately 45°C and outlet water at approximately 55°C. After adopting the relevant liquid-cooling architecture, a 50 MW data center may save more than $4 million annually in cooling electricity and water costs. This estimate has not yet been cross-confirmed by this report, but the business implications are clear: cold plates, pumps, heat exchangers, dry coolers, control systems, and precision machining are all becoming more important, while the configuration of conventional chillers may change.
High-voltage direct-current architectures are also shifting demand from data-hall equipment toward power semiconductors and analog control. Market rumors suggest that certain suppliers are securing silicon-carbide capacity for 800V DC data centers, but the contracts and deployment pace remain unverified. At this stage, the more prudent approach is to track orders for 800V products, customer qualification, power-conversion efficiency, and mass-production revenue, rather than elevating a single supply-chain rumor into industry certainty.
Another route for power supply is to shorten grid-connection waiting times. On-site fuel cells, energy storage, and captive power generation can enable projects to commence operations earlier, and orders for solid-oxide fuel-cell equipment, modules, and ceramic substrates were disclosed this week. Order value does not equal profit: equipment depends on delivery and acceptance, modules on actual production volumes, and ceramic substrates on customer qualification and yield. The tighter data-center power availability becomes, the more valuable the optionality of these solutions, but capital costs, fuel costs, and utilization determine the ultimate returns.
Robotics, Edge AI, and Hardware Applications
The robotics value chain has begun to show improving sales, but commercialization strength falls into three tiers. Industrial automation has quarterly sales volumes and market-share data; surgical robots have orders, installations, and procedure volumes; humanoid robots remain primarily driven by pilots, capacity planning, and financing. Viewed together, these three categories suggest that investors should shift from asking “can it be built?” to asking “do customers reorder, does the equipment operate consistently, and is cash collected?”
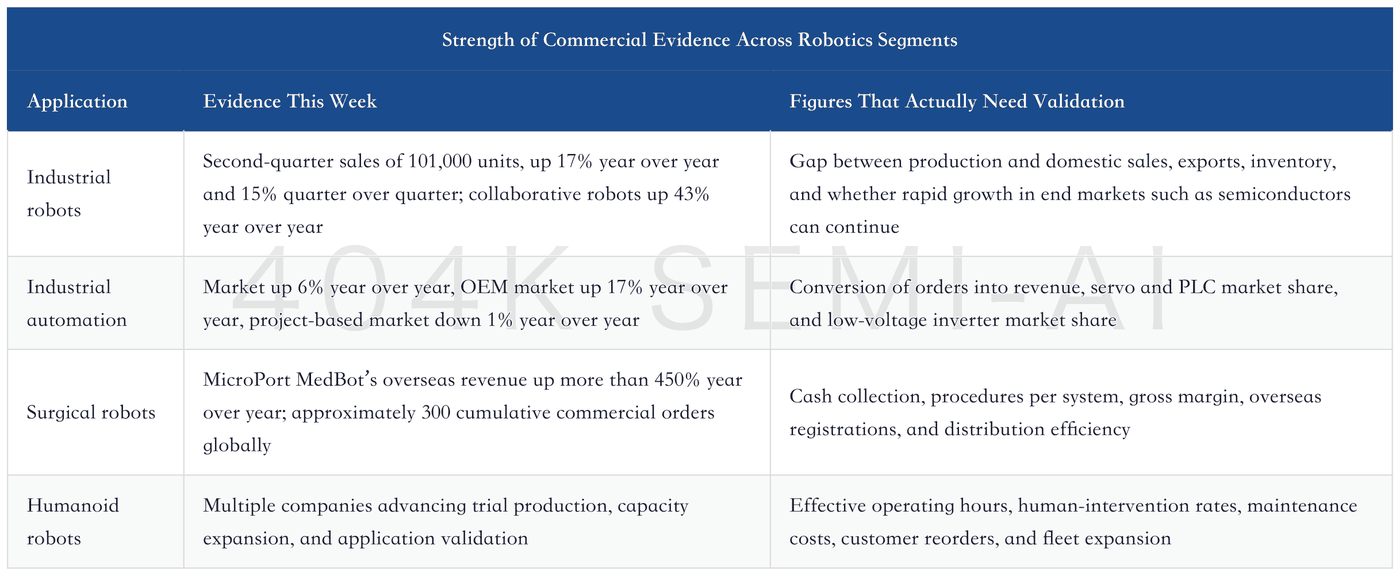
Industrial robot demand is primarily coming from high-tech manufacturing sectors such as semiconductors, automotive electronics, and lithium batteries, with semiconductor-related sales increasing 65% year over year. The relevance of this value chain to the AI industry is that capacity expansion in wafers, packaging, servers, and optical modules will all increase demand for factory automation. The counterevidence is that robot production growth exceeded domestic sales growth, with exports and inventory absorption accounting for part of the gap. If subsequent orders do not convert smoothly into revenue, equipment manufacturers’ revenue trajectory will be weaker than industry production growth.
Surgical robots are closer to auditable revenue than humanoid robots. MicroPort MedBot’s first-half revenue increased approximately 200%—230% year over year, with overseas revenue rising more than 450% year over year. As of June, cumulative commercial orders totaled approximately 300 systems, including more than 240 overseas. Edge Medical Robotics had completed more than 20,000 cumulative procedures as of May. The next metrics to watch are accounts receivable, utilization per system, distributor quality, and gross margin; installation numbers alone cannot substitute for commercial returns.
Edge AI did not generate a sufficiently strong new cluster of evidence this week. PC and smartphone demand remains affected by memory costs, product cycles, and consumer demand, while the clearer incremental growth in the available materials came from data centers, networking, and industrial applications. It is preferable to leave this area temporarily unfilled rather than package ordinary new consumer-device launches as AI supply-chain orders.
Space, Quantum Computing, and AI Software Applications
The verifiable incremental growth in the space value chain is concentrated in low-Earth-orbit satellite communications. WIN Semiconductors’ second-quarter capacity utilization increased to 65%, and the company expects growth to continue in the third quarter, driven by photodiode and low-Earth-orbit satellite shipments. The report estimates that low-Earth-orbit satellite revenue has reached a double-digit share and may exceed 15% in 2027; optical communications revenue may also reach a double-digit share in 2027. For compound-semiconductor suppliers, the real variables are the pace of launches and terminal deployments, customer share, project capital expenditure, and utilization—not satellite-count targets.
Amazon Leo has reportedly completed multiple launches and has nearly 400 satellites in orbit. Such developments can demonstrate that deployment is continuing, but cannot yet be used to directly infer supplier revenue. The next stage is to monitor orders for user terminals, ground stations, RF chips, and optical communications, as well as whether capital expenditure per user can decline with scale.
Quantum computing has produced enterprise operating cases, but remains at an early validation stage. Market reports indicate that AT&T; has expanded its collaboration with D-Wave, with early network-optimization tests reducing processing time from 1 hour to less than 15 seconds, and plans to apply the technology to outage response and network planning. The case demonstrates that quantum annealing can address specific optimization problems, but no contract value, revenue contribution, or large-scale deployment cost has been disclosed. Any upgrade to the investment view on quantum computing requires, at minimum, repeat customers, paid contract values, and a total-cost advantage over classical computing.
Commercialization is more differentiated in AI software than in infrastructure. SAP’s second-quarter current cloud backlog grew approximately 26% year over year at constant currency, ahead of the trajectory implied by its full-year guidance. However, customer feedback and revenue contributions from AI products such as Joule remain insufficiently clear, while investment intensity may continue to pressure margins. This reminds the market that possessing customers and workflows does not mean AI functionality has already generated incremental monetization.
The evidence from Cadence is stronger. The company’s backlog reached $8.1 billion, the midpoint of its 2026 revenue growth guidance is approximately 19%, and management positions agentic EDA as an accelerator of usage within existing workflows, with early paid deployments already underway. Cloudflare channel checks also indicate growing usage of edge inference and developer platforms, although scaled enterprise adoption is expected to occur more extensively in 2027. The next metrics to watch in software applications are AI attach rates, usage-based revenue, renewals, and gross margin—not the number of feature launches.
Divergences, Counterevidence, and Next Week’s Watchlist
The biggest divergence this week is that “strong demand” and “pressure on asset returns” can coexist. Cloud providers can continue investing, while server, optical communications, and connector companies can continue growing, but returns on data-center project bonds may deteriorate because of construction delays and rising financing costs. High-yield bond research shows that AI-related issuance accounted for approximately 25% of the primary high-yield market in the second quarter, while some projects scheduled to begin operations in 2027 face power, equipment, and labor constraints. Funding has not dried up; it has become more expensive.
The second divergence is that the faster capacity expands, the greater the longer-term cycle risk. ABF, advanced packaging, testing, optical modules, and power equipment are all currently undergoing capacity expansion, while customer prepayments and long-term agreements have increased near-term visibility. If multiple new plants begin production simultaneously in 2027—2028, while GPU platform transitions, customers’ in-house chips, or the CPO roadmap progress later than expected, utilization and pricing will weaken before aggregate revenue does.
The third divergence is that the order logic applied to hardware cannot be extended to software and robotics. Hardware orders typically specify volume, unit price, and delivery schedules; software and robotics must additionally demonstrate usage frequency, customer retention, labor savings, service costs, and cash collection. Without these data, even a large long-term addressable market cannot substitute for cash flow.
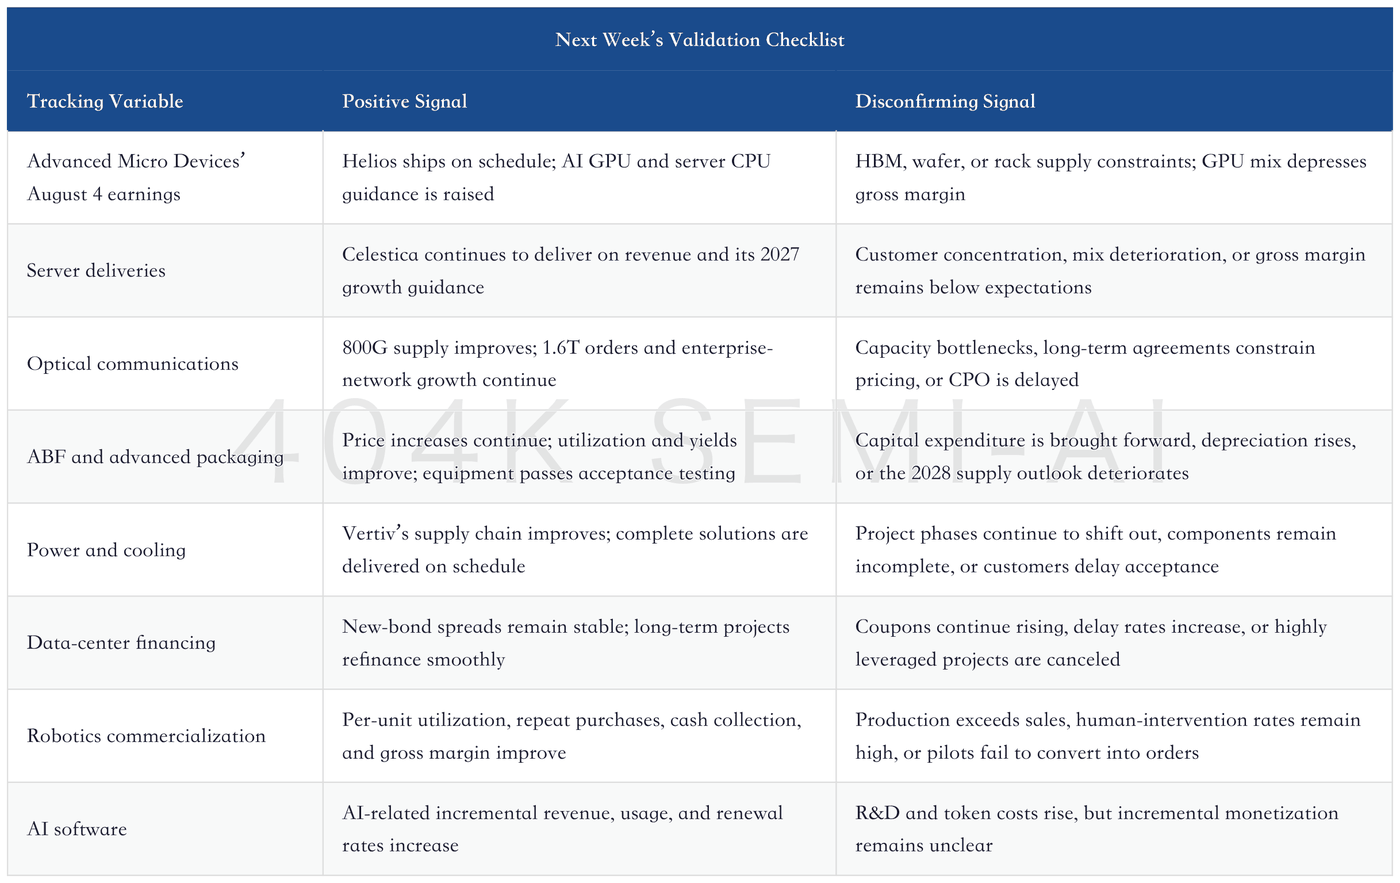
If Advanced Micro Devices’ GPU and server CPU guidance, Celestica’s systems deliveries, connector demand at Corning and Amphenol, pricing and utilization at Unimicron, and Vertiv’s delivery of complete projects all remain strong next week, the “compute diffusion” thesis can continue. If financing spreads continue widening, deliveries are pushed back again, or companies expanding capacity begin lowering utilization expectations, the market will shift from rewarding orders to penalizing cash-flow duration.