
404K SEMI-AI 2026-07-24 Semiconductor Equipment Weekly — WFE Upgrades, Advanced Packaging Delivery, and Diverging Test Orders
目录
TL;DR
Overall View This Week
Front-End Wafer-Fabrication Equipment
Metrology, Inspection, and Testing
Advanced Packaging Equipment and Key Materials
Company, Order, and Capital-Expenditure Validation
Divergences, Counterevidence, and What to Track Next Week
Equipment demand continued to broaden into advanced nodes, hybrid bonding, and testing this week, but China imports, the pace of HBM bonding adoption, and crowded positioning remain the key counterarguments.
TL;DR
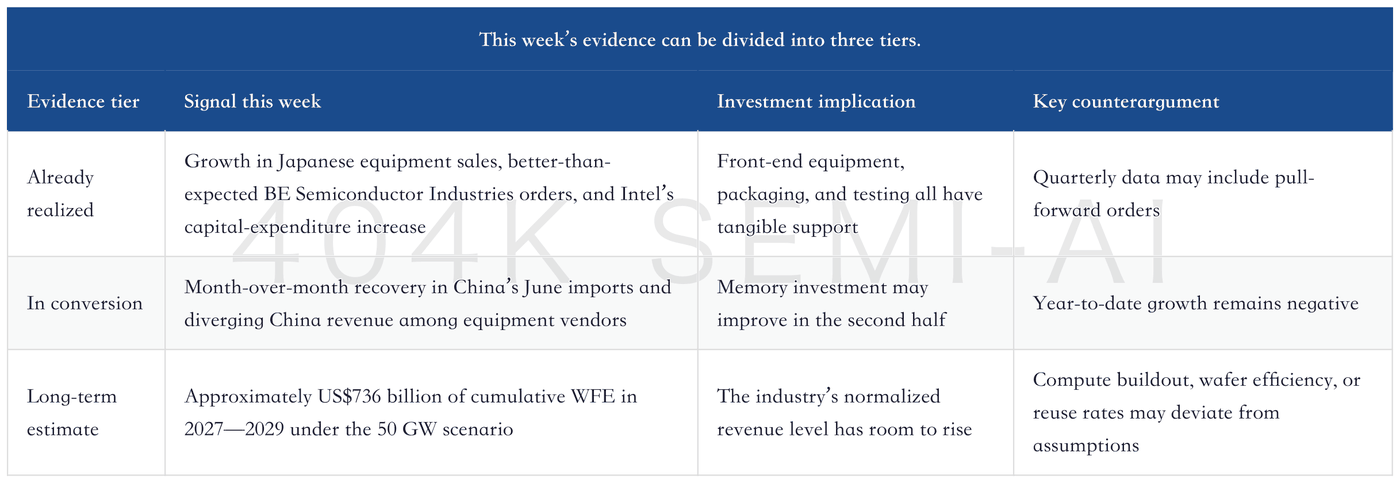
AI infrastructure continues to raise the ceiling for wafer-fab equipment spending (WFE). The base case assumes an additional 50 GW of annualized compute capacity in 2030 versus 2026, corresponding to cumulative WFE of approximately US$736 billion in 2027—2029, or roughly US$245 billion annually. This suggests equipment demand may surpass traditional cyclical peaks, but it is a scenario estimate based on compute capacity, wafer consumption, and equipment intensity—not secured orders.
Front-end equipment data are also improving. Japan’s monthly semiconductor production equipment sales averaged JPY 513.6 billion in April—June, up 27% year over year and 7% quarter over quarter, led by front-end equipment. Intel also raised its 2026 capital expenditure to more than US$20 billion and said spending would increase significantly again in 2027, with investment covering equipment, cleanrooms, and advanced packaging.
Chinese demand showed a monthly recovery, but it is too early to conclude that the cycle has fully reversed. June WFE imports were US$3.4 billion, up 57% month over month and 1% year over year, but remained down 10% year to date; another three-month moving-average dataset showed a 7% year-over-year decline. Import classifications do not map perfectly to vendor revenue, so the next key question is whether memory-customer investment translates into sustained equipment deliveries.
BE Semiconductor Industries’ second-quarter orders reached €293 million, above the prior expectation of approximately €274 million and the €249 million market consensus. Its customer count rose from 15 in 2025 to 21, with logic, memory, co-packaged optics, and consumer electronics all contributing to orders. Order conversion supports the advanced-packaging equipment upcycle, but the timing of hybrid-bonding adoption in high-bandwidth memory remains unclear.
Test equipment has entered a phase of “broadening demand and diverging company performance.” Teradyne is benefiting from testing demand for networking, memory, and custom-compute chips, although the medium-term market opportunity in co-packaged optics is smaller than some expectations. Meanwhile, Techwing secured a test-handler order from Micron, while Aehr Test Systems reported record orders and backlog. The next question is whether orders convert into revenue, rather than merely whether end-market compute demand remains strong.
Overall View This Week
The most important change in semiconductor equipment this week is that demand evidence is shifting from long-term compute projections toward actual orders and capital spending. Japanese equipment sales, Intel’s capital expenditure, BE Semiconductor Industries’ orders, and test-equipment contracts provide validation across front-end equipment, advanced packaging, and back-end testing, respectively. The industry upcycle is no longer dependent on a single segment.
However, the strength of the evidence varies. Reported sales, order values, and capital expenditure are actual data; WFE market size in 2027—2029, hybrid-bonding penetration, and equipment-vendor earnings leverage still depend on model assumptions. Investors should distinguish between “the direction of demand is correct” and “profits have already been realized.”
The long-term ceiling for AI-equipment demand is primarily determined by wafer consumption. In the base case, each additional 1 GW of annualized compute capacity requires approximately 46,000 12-inch wafers per month of capacity, comprising 53% standard dynamic random-access memory (DRAM), 16% high-bandwidth memory (HBM), 11% advanced logic, and 20% NAND flash. Even for the same compute-capacity expansion, memory and logic have different wafer intensities, so equipment revenue will not be distributed evenly.
Equipment intensity further widens the gap between categories. Each additional 10,000 wafers per month of capacity requires approximately US$3.4 billion of equipment investment for advanced logic, approximately US$1.4 billion for DRAM and HBM, and approximately US$1.3 billion for NAND. Advanced logic has the highest investment per unit of capacity, while memory contributes to aggregate demand through greater wafer volumes.
Under the 50 GW base case, incremental monthly capacity is approximately 264,000 wafers for advanced logic, 365,000 for HBM, 1.22 million for standard DRAM, and 458,000 for NAND. The revenue captured by an equipment company depends on which capacity category its products serve, not merely on total WFE. Logic equipment depends on value per unit of capacity; memory equipment depends on wafer volume; metrology and testing must also account for process steps and yield requirements.
Equipment-stock valuations are already pricing in this change. Research materials indicate that crowded positioning in equipment and electronic design automation is being tracked separately, while expectations for several industry leaders have already been raised substantially. There are insufficient data here to assess the precise level of crowding, but it is a clear counterargument: orders may continue to grow while share prices correct first because positioning is excessive.
Revenue allocation will also be affected by delivery capacity. Lithography, etch, deposition, and process-control equipment rely on different critical components and face different capacity bottlenecks. Even after customers approve budgets, revenue recognition may still be delayed if facilities, components, or engineers are not available on schedule. The best combination for equipment vendors is simultaneous order growth, stable lead times, and higher gross margins; the absence of any one factor could weaken earnings upgrades.
Front-End Wafer-Fabrication Equipment
The front-end equipment upcycle is broadening from back-end hotspots into wider fab investment. Japan’s monthly semiconductor production equipment sales averaged JPY 513.6 billion in April—June, up 27% year over year and 7% quarter over quarter. Back-end inspection equipment had previously posted faster growth, but the current increase is being driven more by front-end equipment, indicating that investment in advanced logic, HBM-related DRAM, and some general-purpose memory is beginning to drive equipment demand simultaneously.
Industry forecasts have consequently been revised upward. The relevant model projects Japanese semiconductor production equipment sales of JPY 6.55 trillion in the fiscal year ending March 2027, up 26% year over year, followed by JPY 7.4 trillion in the next fiscal year, up 13%. The model also observes that some customers are asking equipment vendors to deliver existing orders early, suggesting demand is stronger than indicated by new orders alone.
Accelerated deliveries are both positive and a risk. They can lift near-term revenue for equipment vendors but may pull forward revenue from subsequent quarters. The validation method is straightforward: monitor orders, backlog, and lead times together. If sales rise while orders stop growing, the slope of the upcycle may subsequently decline.
ASML’s delivery outlook supports continued advanced-node capacity expansion. Research materials project shipments of 92 and 104 extreme-ultraviolet lithography (EUV) systems in 2027 and 2028, respectively. The company also plans to increase deep-ultraviolet lithography capacity by 30% over the next 2 years, reflecting equipment demand in both mature and advanced nodes.
