
404K SEMI-AI 2026-07-24 M7 and CSP Weekly — Google Cloud Validates AI Returns, Capex Steps Up Again, Neocloud Financing Diverges
目录
TL;DR
Overall View This Week
Cloud Revenue and AI Capex
Data Centers, Compute Procurement, and Custom Chips
Model, Software, and Application Monetization
Divergence Across the M7 and Emerging Cloud Providers
Disagreements, Counterevidence, and What to Track Next Week
The strongest signal this week came from Google Cloud: revenue, margins, and backlog all accelerated. The cost is also becoming clearer, with rising capex, externally leased compute capacity, and financing needs. The next question is whether cash flow can keep pace.
TL;DR
Google Cloud delivered the first threefold validation across revenue growth, margins, and orders. Q2 2026 revenue reached $24.77 billion, up 82% year over year; operating profit was $8.81 billion, with a margin of approximately 36%; and backlog rose to $514 billion. AI investment is already generating revenue and profit, but has not yet improved free cash flow.
Google raised its 2026 capex guidance to $195 billion–$205 billion and expects a significant increase in 2027. Forecasts from 4 institutions for 2027 range from $325 billion to $378 billion, with differences driven mainly by construction cost per gigawatt (GW), backlog conversion, and the pace of exiting third-party compute capacity. High spending remains positive for the compute supply chain, while Google itself must absorb depreciation and financing pressure.
Compute shortages are changing procurement models. Google is using third-party capacity to serve large customers while waiting for its own data centers to come online; TPUs are beginning to be sold externally. Apple’s Baltra is expected to enter small-volume production in 1H 2027, while its second-generation AI ASIC is expected to enter mass production in 2028. The objective of custom silicon has shifted from “cost reduction” to “controlling delivery, costs, and product cadence.”
Neocloud providers have secured stronger contractual validation but lack hyperscaler balance sheets. IREN added $2.8 billion of contracts, providing approximately 85% contracted coverage of its target for more than $4 billion in annualized run-rate revenue by year-end 2026, while customers are prepaying approximately 45% of the associated GPU capex. CoreWeave’s high-yield bond disclosures, however, show high leverage, negative free cash flow, and financing costs above 10%; contract growth does not equate to cash-flow security.
Quantifiable monetization channels are beginning to emerge for AI applications. Google AI Mode has more than 1 billion monthly active users, while the Gemini app has reached 950 million monthly active users; Meta One places advanced AI features behind a subscription, while AI glasses also create a hardware-revenue scenario. Going forward, user numbers alone are insufficient; investors must track payment rates, advertising conversion, unit inference costs, and retention.
Overall View This Week
This week advanced the market debate by one step: returns on AI capex are now visible in cloud revenue and segment profit, but enormous construction-in-progress balances, third-party compute expenses, and depreciation still separate those returns from cash flow.
Google Cloud is the clearest example. Revenue grew 82% year over year, 10 percentage points above Goldman Sachs’ pre-earnings forecast; its operating margin was approximately 36%, and backlog increased by $52 billion during the quarter. Simultaneous improvements in customer demand, contracts, and profit show that prior investments in servers, data centers, and custom silicon were not merely a long-term narrative.
The pressure points also became concentrated and visible. Google’s Q2 2026 capex was $44.9 billion, while free cash flow was negative $5.9 billion. The company raised its full-year capex guidance to $195 billion–$205 billion and explicitly stated that spending would increase significantly again in 2027. Some of the incremental expenditure reflects earlier delivery of equipment and capacity and should not simply be interpreted as a sudden $15 billion increase in demand; however, the cash has already been paid, while depreciation and externally leased compute costs will also hit the income statement first.
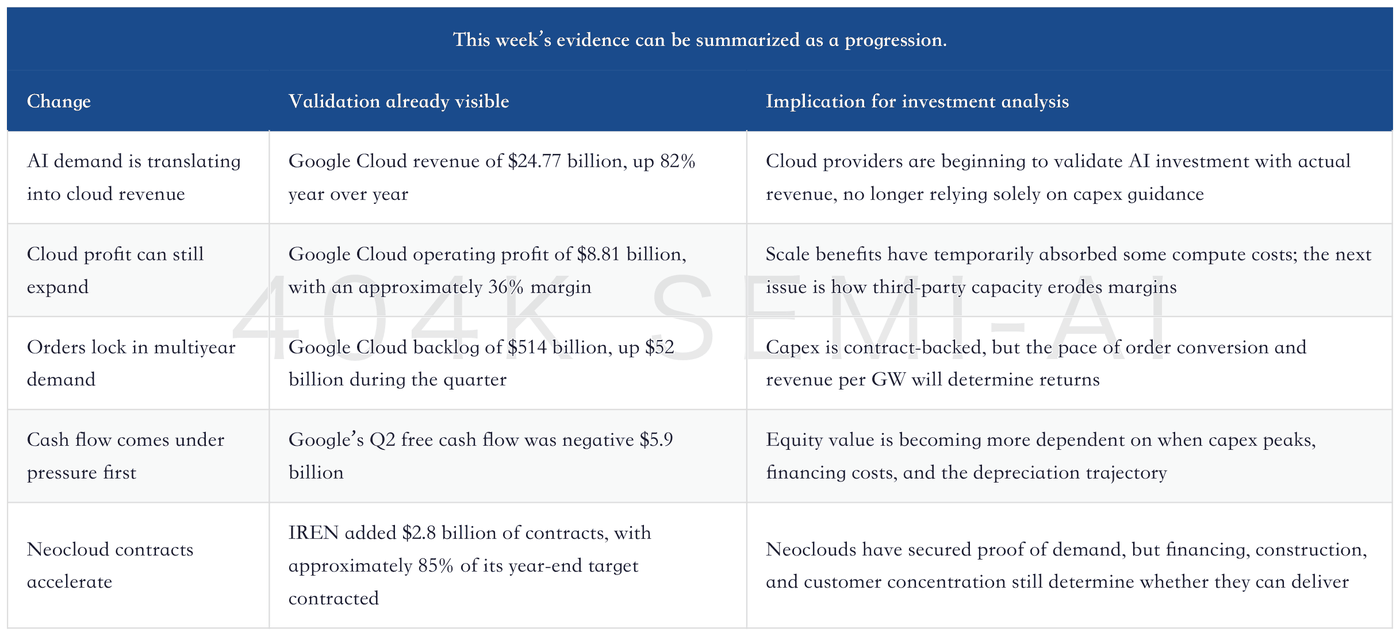
Accordingly, M7 companies and neocloud providers are better viewed as two distinct asset classes this week. Hyperscalers benefit from customer access, custom silicon, software monetization, and low-cost financing that can offset one another; neoclouds offer faster growth and greater contractual upside but face simultaneous expansion in equipment, debt, and cash-flow requirements. Both groups benefit from compute demand, but their valuations cannot be explained using the same revenue curve alone.
Cloud Revenue and AI Capex
The quality of Google Cloud’s growth matters more than the headline growth rate alone. Within its $24.77 billion of revenue, the core Google Cloud Platform business continued to accelerate; cloud customers’ usage exceeded contractual commitments by more than 50%, while the pace of new customer acquisition doubled year over year. Model application programming interfaces process approximately 22 billion tokens per minute, up 37.5% from the previous quarter. Demand comes from enterprise applications, model training, inference, and TPU sales, with multiple revenue streams growing simultaneously.
Backlog provides longer-term visibility. Google Cloud’s backlog reached $514 billion, with slightly more than half expected to convert into revenue over the next 24 months. If conversion proceeds smoothly, existing contracts are sufficient to support further capacity construction; if customers delay deployments, model efficiency improves significantly, or contract scope contracts, capex will first become idle assets and depreciation pressure.
The capex debate has shifted from “whether to invest” to “how high spending will go and when it will peak.” Google’s 2026 guidance is $195 billion–$205 billion, while its 2027 guidance is only qualitative, indicating a significant increase. Sell-side models vary widely because each uses different assumptions for unit capacity costs, the mix of tensor processing units (TPUs) and graphics processing units (GPUs), the duration of externally leased compute capacity, and order conversion.
Google’s 2027 capex forecasts continue to be revised upward broadly, but there is no consensus on the upper bound.
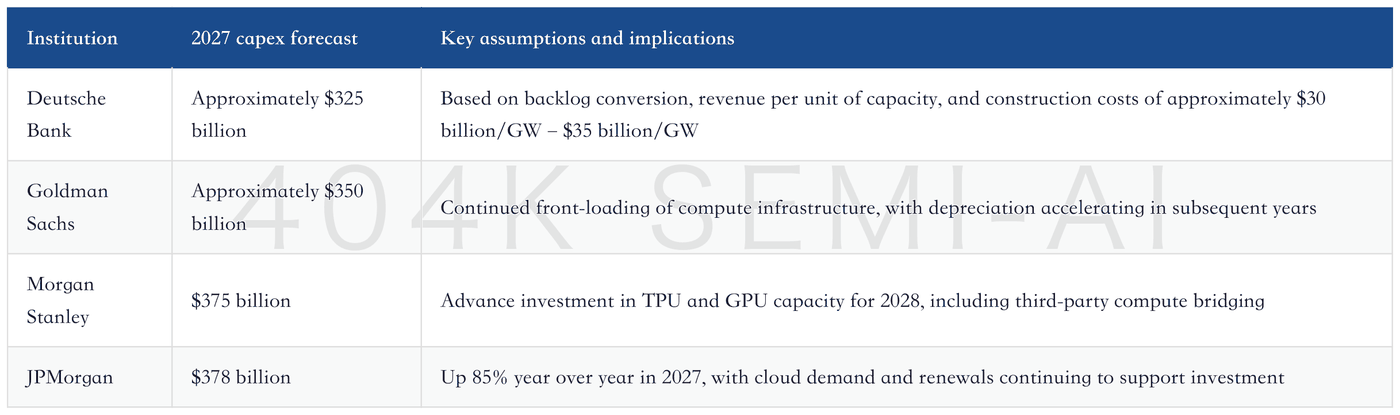
This table is bullish for the supply chain but not unambiguously positive for Google’s equity. If capex rises from around $200 billion to more than $300 billion, orders for servers, custom silicon, storage, networking, power, and data centers will strengthen; Google’s earnings per share and free cash flow, however, will depend on whether cloud revenue can grow faster than depreciation, leasing, and financing costs.
